



PW Consulting: Plastic Bearings Market to Reach $15.78 Billion by 2032 at 4% CAGR
By PW Consulting, 2026-09-07

The Strategic Pivot: Why the Plastic Bearings Market Demands Attention in 2026
Introduction: The Quiet Revolution in Motion Control
In the complex machinery of global industry, few components work as quietly yet as critically as plastic bearings. Once relegated to low-load, low-cost applications, engineered polymer bearings have evolved into high-performance solutions capable of replacing metals in some of the most demanding environments known to manufacturing. From the sterile precision of medical devices to the high-load cycles of automotive automation, the shift toward maintenance-free, corrosion-resistant, and lightweight bearing solutions is no longer a trend—it is a structural transformation of the supply chain.
Worldwide KLT BOX Market
As we navigate the mid-2020s, the market for plastic bearings stands at a pivotal inflection point. The convergence of material science advancements, shifting regulatory landscapes, and the relentless drive for industrial efficiency has created a landscape where legacy assumptions no longer hold true. For strategic decision-makers, this environment demands more than cursory market scanning; it requires a deep, forensic understanding of where value is being created, where margins are under pressure, and which competitors are positioning themselves for the next decade.
Worldwide VCSEL Lidar Chip Market
This article serves as an executive preview of our latest comprehensive study: the Plastic Bearings Market Research Report. Designed for C-suite executives, procurement leaders, and strategic planners, this piece outlines the macro foundations of the industry, highlights the competitive architecture, and underscores the immediate strategic value of the full intelligence contained within our research.
Worldwide Ketoprofen Lysine Salt Market
Macro Foundations: Tracking the Trajectory of Growth
Understanding the scale and velocity of the plastic bearings market is the first step in calibrating strategic response. The data tells a story of consistent, resilient expansion, even amid broader economic volatility. Based on historical analysis from 2020 through 2025, the market has demonstrated a steady compound annual growth trajectory that underscores the durability of demand for polymer-based motion solutions.
The overall market revenue, measured in millions of USD, has grown from approximately 9.8 billion in 2020 to a projected valuation reaching beyond 15.7 billion by the end of the forecast window in 2032. This growth is not merely a reflection of inflation or currency shifts; it represents a genuine expansion in the addressable market as industries replace legacy metal components with advanced polymers. The base year analysis for 2025 sets a robust platform, with revenues stabilizing at a level that supports aggressive R&D and capacity expansion initiatives among key players.
Central to this outlook is the compound annual growth rate (CAGR), which our analysis pegs at approximately 4.0 percent over the forecast period extending from 2026 through 2032. While this growth rate might appear moderate in isolation, it is significant given the maturity of certain segments within the bearing industry. A 4.0 percent CAGR in a specialized component market signals sustained adoption curves, particularly in sectors where plastic bearings are still displacing traditional solutions. This steady pace allows for calculated investment rather than speculative gambling, provided decision-makers have access to the granular trend lines that our full report provides.
However, macro aggregates only tell part of the story. The real strategic insights lie in the subtle shifts within type segmentation, application uptake, and regional performance. Without diving into the specific percentages that could compromise the exclusivity of our data, it is sufficient to note that the market is not monolithic. Certain polymer types are seeing accelerated adoption due to performance breakthroughs, while specific application verticals are driving the bulk of incremental revenue. The divergence between high-growth niches and stable legacy segments creates both opportunity and risk, necessitating a nuanced go-to-market strategy that our research unpacks in detail.
Currents Shaping the Landscape: Raw Materials and Regulation
No market strategy can be formulated in a vacuum. The plastic bearings industry is deeply sensitive to upstream commodity dynamics and downstream regulatory frameworks. Two emerging themes in the first half of 2026 illustrate the complexity that manufacturers and buyers must navigate.
On the supply side, the cost and availability of polymer resins remain critical variables. Recent data from the US Bureau of Labor Statistics indicates that plastic resins and materials saw increases in the index for processed goods as of April 2026. This uptick contributes to broader upward pressure on polymer availability and costs. For producers of plastic bearings, this translates into margin management challenges and potential pricing power negotiations with downstream customers. For buyers, it signals the need for long-term supply agreements or strategic inventory positioning to mitigate cost volatility. Our report dissects how these raw material fluctuations are being absorbed by different tiers of the supply chain and which regions are most exposed.
On the regulatory front, compliance requirements are tightening in key manufacturing hubs. In a notable development, the Indian government notified the Bearing (Quality Control) Order, 2025, mandating BIS certification and compliance for bearings, including plastic types. This regulation, highlighted in industry updates from May 2026, introduces new barriers to entry and compliance costs for companies looking to serve the Indian market. Such regulatory shifts often serve as precursors to similar quality control mandates in other emerging economies. Navigating these requirements requires not just legal diligence but also an understanding of how certification timelines and standards will affect market access and competitive positioning. Our research provides a regulatory mapping that goes beyond headlines, offering actionable insights for market entry and compliance strategy.
Strategic Segmentation: Beyond the Aggregates
While the headline numbers provide the scope of the opportunity, the true strategic leverage comes from understanding the architecture of the market. The plastic bearings sector is defined by distinct segmentation dimensions—by type, by application, and by region—each of which carries its own driver set, competitive intensity, and growth profile.
When examining the market by type, the landscape is dominated by a hierarchy of polymer technologies. Acetal and Nylon variants continue to hold substantial share, reflecting their established performance profiles and cost-effectiveness in standard industrial applications. However, the dynamics are shifting. Teflon and UHMWPE-based bearings are carving out specialized roles in environments where chemical resistance, low friction, or extreme wear tolerance are non-negotiable. The interplay between these material types is not static; it is influenced by resin pricing, processing technology maturity, and the specific technical requirements of end-use industries. Strategic planners must understand which material segments are commoditizing and which are moving up the value chain to command premium positioning.
The application segmentation reveals where the demand pressure is originating. Automotive represents a massive anchor for plastic bearing consumption, driven by the need for lightweighting, corrosion resistance, and maintenance-free operation in under-hood and chassis applications. Yet, the automotive sector is not a monolith; it spans passenger vehicles, heavy-duty commercial transport, and the rapidly evolving electric vehicle landscape, each with distinct bearing requirements. Equally important are sectors such as packaging, medical, food processing, and industrial machinery. The medical and food processing verticals, while smaller in aggregate volume compared to automotive, often present higher margin opportunities and stricter regulatory hurdles, creating a different risk-reward calculus for suppliers. Packaging and industrial machinery provide volume stability and broad application breadth. Our report provides a deep dive into how these application verticals are evolving, including sub-segment trends that are not visible in top-line data.
Regionally, the market exhibits distinct maturity curves and growth drivers. North America and Europe remain strongholds with established manufacturing bases and high adoption rates of advanced polymer solutions. Asia Pacific, however, continues to be a focal point for volume growth, driven by industrial expansion and increasing localization of supply chains. Latin America and the Middle East and Africa represent emerging opportunity zones where infrastructure development and industrial modernization are creating new demand pockets. Understanding the relative attractiveness of each region, including trade dynamics, local content requirements, and competitive intensity, is essential for allocating resources effectively.
Competitive Architecture: Navigating a Consolidated Field
The competitive landscape of the plastic bearings market is characterized by a blend of specialized innovators and diversified industrial players. Market concentration metrics indicate that a significant portion of revenue is captured by a core group of leading firms. With a CR3 of approximately 55 percent and a CR5 extending to 68 percent, the top-tier competitors wield substantial influence over pricing norms, technology standards, and supply chain expectations. This concentration suggests that new entrants face high barriers to scale, while existing players must constantly innovate to defend share and margin.
Among the key companies shaping this landscape, Igus, headquartered in Köln, Germany, stands out as a specialist in motion plastics. The company focuses on injection-molded iglidur polymer bearings designed for high-load, maintenance-free industrial applications, particularly in automation and robotics. Their strategy emphasizes material innovation and direct-to-engineer engagement, allowing them to capture value in high-performance niches where reliability is paramount.
GGB, based in Torrington, Connecticut, USA, is another major force, specializing in metal-polymer and thermoplastic composite plain bearings. Their portfolio addresses automotive, industrial, and heavy-duty environments, leveraging a hybrid approach that combines the strength of metals with the benefits of polymers. GGB's positioning highlights the ongoing relevance of composite solutions in applications where pure polymer bearings may face load or thermal limitations.
Trelleborg AB, a producer based in Trelleborg, Sweden, brings a broad polymer and composite expertise to the bearing space, with products serving extreme environments in aerospace, marine, and industrial sectors. Their ability to operate in harsh conditions underscores the expanding envelope of where plastic bearings can be deployed, particularly as industries push for components that withstand corrosive, high-temperature, or high-vibration settings.
In the North American market, players such as BNL and Hartford Technologies demonstrate the diverse strategies within the sector. BNL is an active supplier of advanced plastic bearing solutions, maintaining visibility through trade show participation and industry engagement. Their recent showcase of advanced plastic bearing solutions at The Bearing Show North America in Detroit in March 2026 illustrates the importance of customer engagement and technology demonstration in a market where application-specific fit is critical. Hartford Technologies, on the other hand, focuses on custom manufacturing of plastic bearings and assemblies, serving niches such as pool and spa, recreational equipment, and industrial drop-in replacements. Their model highlights the value of customization and rapid prototyping in serving fragmented application markets where standard catalog parts may not suffice.
The competitive dynamics are not static. As raw material costs fluctuate and regulatory requirements tighten, competitive advantages will shift toward companies that can secure stable resin supply, navigate certification landscapes efficiently, and offer differentiated technical value rather than competing solely on price. Our report includes detailed competitor profiling, evaluating capabilities, market footprints, and strategic moves that are reshaping the hierarchy.
Contents of the Full Study: A Toolkit for Decision-Making
This article has outlined the macro contours and the competitive stakes. But for a strategy to be executable, it must be built on granular intelligence. Our full Plastic Bearings Market Research Report is designed as a practical toolkit for the demands of 2026 and beyond. It goes far beyond the aggregates and themes discussed here, providing a structured, data-rich foundation for planning.
Core Deliverables Include:
- Historical and Forecast Revenue Analysis: Detailed time-series data covering the historical period from 2020 through 2025, with a comprehensive forecast extending through 2032. This includes base year calibration and segment-level projections that allow for scenario modeling.
- Segmentation Deep Dives: Complete breakdowns by bearing type, application vertical, and geographic region. These splits reveal the relative contribution of each segment, growth rates, and shifting share dynamics that are critical for portfolio prioritization.
- Competitive Benchmarking: In-depth profiles of leading companies, including Igus, GGB, Trelleborg AB, BNL, Hartford Technologies, and other key market participants. The analysis covers product portfolios, technological focus, market presence, and recent strategic moves.
- Supply Chain and Cost Dynamics: Examination of raw material influences, including resin pricing trends and availability pressures, with implications for manufacturing economics and pricing strategies.
- Regulatory and Standards Mapping: Tracking of quality control orders, certification mandates, and compliance requirements across major markets, helping companies anticipate barriers and plan market access.
- Strategic Recommendations: Actionable guidance for manufacturers, suppliers, and buyers on positioning, investment, risk mitigation, and opportunity capture in a market defined by both steady growth and structural change.
The report is structured to serve multiple functions within an organization. For product development teams, it provides market pull insights that can guide material selection and feature prioritization. For sales and marketing, it offers segmentation clarity to target high-value applications and geographies. For finance and strategy, it supplies the quantitative backbone for CAPEX planning, M&A screening, and market entry decisions. For procurement, it illuminates supply chain vulnerabilities and pricing trends that affect cost management.
Why 2026 Is the Critical Year for Strategic Clarity
The year 2026 represents more than a midpoint in a forecast period; it is a moment of convergence. The market has absorbed years of incremental growth and technological maturation, reaching a size and complexity where legacy planning tools are insufficient. The 4.0 percent CAGR signals that growth is real and sustained, but it also means that the market is large enough that small percentage shifts translate into significant absolute value movements. Companies that continue to operate with broad-brush assumptions risk misallocating resources, missing high-margin niches, or underestimating competitive threats from specialized players.
Furthermore, the external environment is adding layers of complexity. Raw material cost pressures are testing the resilience of pricing models. Regulatory initiatives, such as the BIS certification mandates in India, are signaling a global trend toward tighter quality control that could reshape market access in emerging economies. Trade show activity and industry engagement, exemplified by recent events like The Bearing Show North America, highlight the importance of staying connected to the application community and tracking technological showcases that signal where innovation is heading.
For leaders, the question is no longer whether plastic bearings are relevant—they are indispensable in an increasing array of applications—but how to position for the next phase of the market's evolution. Do you have visibility into which type segments are gaining momentum? Do you understand the regional risk-reward profiles for expansion? Are you aware of the competitive moves that could alter your share position? These are the questions that our research is built to answer.
Conclusion: Accessing the Full Intelligence
The plastic bearings market is undergoing a period of sustained transformation, driven by material innovation, application expansion, and a competitive landscape that rewards technical differentiation. The macro data confirms the scale and trajectory of the opportunity, but the real value for strategic decision-making lies in the details—the segmentation nuances, the competitive profiles, the supply chain sensitivities, and the regulatory horizon.
This article has provided a strategic preview, highlighting the market's growth path, the forces shaping its dynamics, and the structure of the competitive field. It has intentionally avoided the granular splits and specific figures that form the core of our analytical depth. To access the complete segmentation data, detailed competitor assessments, regulatory mappings, and forecast models that will enable precise decision-making in 2026, we invite you to consult the full Plastic Bearings Market Research Report.
In a market where a 4.0 percent CAGR compounds into significant value over the forecast horizon, and where raw material and regulatory shifts can rapidly alter the economics of supply and demand, information is not just an asset—it is a strategic imperative. Equip your organization with the intelligence needed to navigate the complexities of the plastic bearings market with confidence and precision.
For detailed analysis of this topic, please visit the official page: Plastic Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Lubrication Systems Market to Hit $1.34B by 2032, 4.95% CAGR Forecast
By PW Consulting, 2026-09-07

Strategic Intelligence for the Automatic Lubrication Systems Market: Navigating Growth Trajectories Through 2032
In an industrial landscape where uptime directly dictates profitability, the automatic lubrication systems sector has transitioned from a supporting operational function to a strategic investment priority. PW Consulting’s comprehensive market research for this domain delivers a granular, data-backed assessment of the sector’s performance, competitive architecture, and forward-looking drivers. This analytical introduction outlines the structural forces shaping the market, the competitive dynamics that define investment and procurement decisions, and the specific analytical dimensions our report unpacks. The objective is not to replicate the full intelligence deliverable, but to demonstrate how decision makers can extract executable advantage from the complete dataset as they position for the 2026–2032 horizon.
Modular Temperature Control Systems Market
Establishing the Macro Trajectory: Why the Numbers Matter Strategically
The market has demonstrated consistent, compounding expansion over the past half-decade, reflecting a structural shift rather than a cyclical rebound. From a baseline of approximately 751.62 million USD in 2020, revenue advanced to 952.32 million USD by 2025, underscoring a practical recovery and growth inflection after the volatility of earlier years. The forward trajectory projects the sector to surpass the 1 billion USD threshold in 2026, reaching 1,008.16 million USD, before stepping to 1,132.41 million USD by 2028 and 1,173.72 million USD by 2029. The terminal forecast stands at 1,335.61 million USD in 2032, a magnitude that signals sustained capital allocation, OEM engineering focus, and end-user procurement confidence.
Metal Water Truck Pumps Market
Underlying this progression is a compound annual growth rate of 4.95 percent across the 2026–2032 forecast window. For senior leadership, that rate is not merely a statistical projection; it is a calibration benchmark for capacity planning, supply chain hedging, and R&D prioritization. A sub-5 percent CAGR in a mature industrial hardware category indicates steady, predictable demand rather than speculative hype. It suggests that growth is being driven by operational necessities—reduced unplanned downtime, labor optimization, and regulatory pressures—rather than discretionary capex. Consequently, organizations that treat this category as a steady-state procurement line risk missing the embedded strategic levers: deployment standardization, total cost of ownership reduction, and integration into broader predictive maintenance architectures.
Nano Sponge Market
Another strategic layer emerges from market concentration. The combined share of the top three participants reaches 58.0 percent, while the top five account for 72.5 percent. This tiered concentration reveals a market with recognizable incumbents and defensible technical positioning, yet still open enough to reward focused innovators and regional specialists who can differentiate on reliability, digital connectivity, or application-specific engineering. Understanding where concentration is high and where fragmentation persists directly informs partnership strategies, channel design, and competitive response planning.
Structural Segmentation: Reading the Demand Architecture Without Losing Sight of the Whole
Segmentation analysis in this domain rarely exists for its own sake. It functions as a diagnostic framework for identifying value pools, deployment roadblocks, and technology adoption cycles. The market bifurcates fundamentally between oil-based and grease-based lubrication systems. The oil-based segment holds a clear volume advantage, reflecting its broader compatibility with continuous-flow industrial machinery, centralized distribution architectures, and applications demanding higher thermal stability or longer service intervals. Grease-based systems, while smaller in aggregate value, address distinct operational requirements—sealed bearings, high-load points, and environments where viscosity retention and contamination resistance are paramount. The coexistence of these two technology families means that procurement strategies cannot be generic; they must align with machine OEM specifications, environmental exposure profiles, and maintenance cadence objectives.
Application-side segmentation further illustrates how demand is distributed across industrial verticals. Steel, manufacturing, cement, paper and printing, transportation, and construction each present different lubrication pain points and adoption thresholds. High-speed manufacturing environments prioritize precision dosing and minimal intervention windows, whereas heavy industrial sectors such as steel and cement demand systems engineered for thermal extremes, particulate contamination, and structural vibration. Transportation and construction applications introduce additional complexity: mobile deployment, variable operating cycles, and the need for modular, ruggedized architectures. Rather than viewing these application splits as isolated revenue buckets, strategic planners should read them as proxies for implementation readiness. Verticals with higher automation maturity and tighter maintenance budgets tend to adopt centralized and digitally monitored systems more rapidly, while operations still reliant on manual or semi-automated workflows represent the near-term conversion opportunity.
Regional demand concentration tells a complementary story. Industrial activity, capital expenditure cycles, and supply chain localization all shape where deployments scale fastest. The geography of demand influences not only end-user sourcing patterns but also manufacturer footprint decisions, service network density, and pricing architectures. Companies evaluating expansion, localization, or distributor partnerships need a clear view of regional readiness, not a narrow snapshot of nominal size. That is why the complete report prioritizes regional dynamics in conjunction with industrial base indicators and procurement seasonality, rather than presenting static regional splits in isolation.
Competitive Architecture: Incumbent Strength, Differentiation Vectors, and Recent Moves
The competitive field is anchored by manufacturers with established engineering heritage, global distribution reach, and deep application-specific portfolios. Groeneveld-BEKA, headquartered in Gorinchem, Netherlands, operates as the second-largest manufacturer globally, extending across transportation, construction, mining, agriculture, and industrial applications. Its breadth signals a strategy rooted in cross-sector applicability and fluid management integration. SKF Lincoln, based in Decatur, Illinois, provides a complete portfolio of automatic lubrication systems and components for industrial and mobile equipment, spanning oil- and grease-based centralized architectures. Its positioning within a larger bearing and reliability ecosystem reinforces the market’s trend toward integrated maintenance solutions rather than isolated component sales.
perma, located in Euerdorf, Germany, distinguishes itself as a global leader in single-point and multi-point automatic lubrication systems, increasingly paired with connected digital solutions designed to improve industrial reliability and reduce maintenance burden. This pivot toward connectivity is a defining competitive vector: lubrication delivery is becoming a data-generating node within broader asset management platforms. Bijur Delimon International, headquartered in Morrisville, North Carolina, maintains a global leadership stance in the design and manufacturing of automatic lubrication systems, pumps, and lubrication equipment for industrial machinery, emphasizing precision engineering and broad equipment compatibility. Dropsa, based in Italy, manufactures centralized automatic lubrication systems encompassing single-line, dual-line, progressive, oil, grease, and air/oil configurations, reflecting deep expertise in diversified delivery architectures for industrial production.
Graco, headquartered in Minneapolis, Minnesota, provides automatic lubrication systems for in-plant and mobile applications, complemented by pumps, meters, controllers, and accessories aimed at equipment optimization. A.T.S. Electro-Lube, based in Canada, manufactures self-contained automatic lubrication systems, including single-point, multi-point, and refillable units engineered for demanding industrial environments. Oil-Rite Corporation, located in Manitowoc, Wisconsin, specializes in designing and manufacturing high-quality lubrication systems and components focused on industrial machinery efficiency and longevity. LSP Industries, Inc., headquartered in South Windsor, Connecticut, delivers comprehensive lubrication system solutions tailored to modern industries, combining design, manufacturing, and support capabilities. Together, these firms form an ecosystem where scale, specialization, and service integration determine market positioning.
Recent corporate activity reinforces the strategic themes visible across the sector. In January 2026, A.T.S. Electro-Lube prepared to exhibit at POWERGEN 2026 in San Antonio, Texas, showcasing next-generation automatic lubrication systems for industrial equipment performance and reliability. This trade presence reflects the ongoing importance of face-to-face demonstration, application engineering dialogue, and live reliability proofing in a category where equipment downtime carries tangible financial consequences. In October 2025, perma held a groundbreaking ceremony for a new production and dispatch facility aimed at supporting expanded manufacturing capacity. That move signals confidence in demand sustainability and a willingness to invest in throughput, lead-time performance, and regional fulfillment capability. Around the same period, Lubecore participated in TKD Technical Contact Days in the Netherlands with automated greasing systems for earthmoving and recycling equipment, while Applied Lubrication Technology Inc. exhibited automatic lubricators and lubrication solutions for heavy-duty applications at the Lubricant Expo & The Bearing Show North America in Detroit. These events collectively indicate that innovation showcases, capacity expansion, and application-specific demonstrations are compounding as competitive levers.
Market Dynamics and Structural Forces Shaping Deployment
Regulatory and safety imperatives are increasingly re 아키텍팅 the economics of manual lubrication. Growing regulatory pressure concerning workplace safety and environmental protection is compelling industries to adopt automated lubrication solutions. When compliance burdens rise, organizations look for repeatable, controlled application methods that reduce operator exposure, minimize spill risk, and standardize maintenance procedures. Automated delivery systems answer that need by reducing variability in quantity, frequency, and point coverage. At the same time, stricter regulations related to worker safety and machine performance support adoption while influencing material and labor cost structures. The result is a dual compression: end users seek reliability and safety, while suppliers must manage input cost volatility and labor intensity across design, assembly, and service delivery.
A broader macro trend reinforces this direction. The global trajectory toward automation is accelerating demand for automatic lubrication systems in industrial machinery. As plants and fleets integrate more sensors, controllers, and programmable logic into their operations, lubrication delivery is increasingly viewed as a process that should be synchronized with equipment state rather than treated as a standalone maintenance task. This mindset shift expands the addressable use case beyond traditional heavy equipment into continuous-process environments and high-cycle production lines where precision and repeatability yield measurable efficiency gains.
Cost and geopolitical variables add further complexity. United States tariffs implemented in 2025 are influencing the cost structure for single-line centralized lubrication equipment. Tariff exposure alters sourcing decisions, prompts supply chain reevaluation, and can shift competitive advantage toward manufacturers with localized assembly, diversified component sourcing, or flexible distribution models. For procurement teams and channel partners, this means that quotation framing, inventory positioning, and contract timing are no longer administrative details; they are strategic variables that affect landed cost and service continuity. Organizations that map tariff exposure against regional demand and product architecture can better anticipate pricing shifts and negotiate with a clearer understanding of structural cost drivers.
What the Full Research Deliverable Supplies: Operational Intelligence, Not Just Forecasts
A market research report is only as valuable as its ability to translate macro direction into actionable planning parameters. The complete PW Consulting study is structured to support budget justification, technology roadmapping, competitive benchmarking, and market-entry evaluation. It opens with an executive synthesis that connects historical performance, forecast direction, and the strategic implications for capital allocation and procurement planning. The methodology and scope section clarifies data construction, analytical boundaries, and modeling assumptions so that readers can assess forecast reliability and apply the findings appropriately to their own scenarios.
The core market analysis quantifies revenue progression, forecast inflection points, and concentration dynamics while framing the market in terms of what is driving adoption and what may constrain it. Industry dynamics are mapped across regulatory pressure, automation momentum, cost-structure influences, and tariff-related cost effects, giving planners a multi-variable lens rather than a single-line growth narrative. Segmentation is examined by type and application with attention to technical fit, deployment requirements, and demand timing, allowing readers to identify which product families and verticals align with their capabilities or procurement priorities. Regional dynamics are discussed in the context of industrial activity, supply chain considerations, and competitive density, helping stakeholders evaluate where to prioritize sales effort, service investment, or sourcing adjustments.
Competitive profiling forms a central pillar of the report. Each key participant is assessed for positioning, portfolio coverage, geographic footprint, and strategic direction. Beyond descriptive profiles, the analysis links corporate moves—facility expansion, trade show demonstrations, product emphasis, and capacity investments—to broader market implications. This enables readers to interpret competitor behavior as signals about capacity confidence, segment focus, and technology priorities. Recent developments are incorporated as real-time indicators of where attention and resources are flowing, giving decision makers a forward-looking pulse on the competitive field.
The deliverable is also designed for practical application by multiple internal audiences. Finance and procurement teams can use the revenue framework and concentration patterns to benchmark pricing expectations, evaluate supplier concentration risk, and plan contract timing. Engineering and maintenance leaders can use segmentation and dynamics insights to justify standardization, compare technology families, and align lubrication strategy with reliability programs. Commercial and strategy teams can use the competitive architecture and regional context to assess positioning, identify underserved application pockets, and shape channel or partnership decisions. By presenting these layers in an integrated format, the report supports cross-functional alignment rather than siloed reading.
Guidance for Decision Makers Entering 2026
As organizations set their plans for 2026, the strategic question is not whether automatic lubrication systems matter, but how to allocate attention and capital in a market that is consolidating around reliable incumbents while still rewarding targeted innovation and application-focused execution. Several priorities emerge from the structural evidence. First, treat lubrication delivery as a reliability and compliance investment rather than a commodity line item. Where automated systems reduce variability, limit operator exposure, and extend service intervals, the value case extends beyond the unit price into maintenance cost avoidance and operational continuity.
Second, align technology selection with application reality. Oil-based and grease-based systems serve different operating conditions and maintenance philosophies, while centralized architectures vary in complexity, routing requirements, and controllability. Procurement specifications should be built around machine profiles, environmental exposure, maintenance staffing models, and the organization’s appetite for monitoring and integration. In practice, that means evaluating not only the delivery mechanism but also the surrounding controls, refill logistics, and serviceability.
Third, factor supply-side cost dynamics into sourcing strategy. Tariff exposure, material cost sensitivity, and regional fulfillment capability can materially affect landed cost and lead time. Where possible, buyers should compare total cost of ownership across suppliers with different manufacturing footprints and distributor networks, and suppliers should assess where localized capacity or diversified sourcing can protect margin and service reliability. Fourth, watch competitor capacity and showcase behavior as leading indicators. Facility expansions and trade show demonstrations are not cosmetic; they communicate where manufacturers expect demand to concentrate and which applications they believe represent the highest value opportunities.
Finally, integrate lubrication systems into the broader automation and data strategy wherever feasible. As connected monitoring and digital service tools mature, lubrication points can become part of a more responsive maintenance ecosystem. Organizations that plan for this integration early—by specifying compatible architectures, training maintenance teams, and defining data usage protocols—will be better positioned to convert equipment reliability into measurable operational advantage.
Proceeding with Full-Market Intelligence
The automatic lubrication systems market is expanding along a measured, structurally supported trajectory, with a forecast CAGR of 4.95 percent carrying the sector past 1.3 billion USD by 2032. Concentration patterns, technology bifurcation, application diversity, and cost-dynamic pressures all point to a market where informed positioning matters more than blanket exposure. PW Consulting’s full report provides the detailed segmentation breakdowns, regional evaluation, competitive mapping, and scenario-ready analysis required to move from awareness to execution.
For executives and commercial leaders who need to justify investment timing, evaluate supplier landscapes, or identify the highest-value deployment opportunities, the complete deliverable supplies the granularity and context necessary to make confident decisions. The macro direction is clear; the strategic edge lies in understanding where value concentrates, which competitive signals to watch, and how to align product, sourcing, and service choices with operational reality. Access to the full intelligence package converts the market’s broad trajectory into a usable roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automatic Lubrication Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ceramic Ferrule Market Reaches $237M in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-07

Navigating the Next Wave: Why the 2026 Ceramic Ferrule Market Intelligence Report Is a Strategic Imperative
The global ceramic ferrule market stands at a critical inflection point in 2026. As optical networks expand to support exponential data traffic, and as precision ceramic components penetrate new industrial and medical applications, decision-makers require more than generic forecasts. They require granular, scenario-tested intelligence that maps technological shifts, competitive maneuvering, and demand-side signals to actionable growth strategies. This newly released market research delivers precisely that. Built on a rigorous multi-year historical foundation and extended through a forward-looking forecast horizon, the study equips executives, investors, and supply chain leaders with the clarity needed to allocate capital, position product portfolios, and anticipate capacity constraints before they become industry-wide bottlenecks.
Attenuated Vaccine Market
The market has demonstrated steady, compounding expansion over the past half-decade. Between 2020 and 2025, aggregate revenue climbed from approximately 176.5 million USD to 237.0 million USD, reflecting a sector that has consistently outpaced cyclical volatility. The forward trajectory remains equally compelling. Our base year normalization and subsequent projection modeling indicate that the global market will reach roughly 259.45 million USD in 2026, accelerating through 2032 to approach 363.08 million USD. At the core of this expansion sits a forecast compound annual growth rate of 6.5 percent across the 2026-2032 period. These are not abstract figures; they represent structural demand signals driven by high-density interconnect deployments, data center fiber ribbon scaling, and the gradual migration of ceramic ferrule technology into adjacent active and passive device ecosystems. Understanding the mechanics behind these numbers, rather than merely acknowledging them, is where strategic advantage is forged.
Wear Resistant Steel Plates for Construction Machinery Market
Historical Resilience and the Forward Curve: Translating Macro Trends into Decision-First Intelligence
Market sizing alone rarely translates into boardroom confidence. What executives truly need is a diagnostic lens that explains why growth is occurring, where marginal returns will concentrate, and which operational variables will determine execution success. This report begins by reconstructing the historical revenue path from 2020 through 2025, treating each year as a data point in a broader behavioral narrative rather than a static line item. The recovery and expansion observed across this window coincide with several converging forces: improving manufacturing yield on precision-machined zirconia bodies, tighter tolerances demanded by next-generation connector polishing standards, and a supply chain environment that is slowly rebalancing after years of disruption.
High Voltage Shore Power Supply Market
Looking ahead, the 6.5 percent CAGR is anchored in a disciplined bottom-up build that accounts for volume growth, pricing dynamics, and mix shifts across product categories and end-use domains. Rather than relying on top-down extrapolations, the analysis decomposes the revenue trajectory into drivers that matter to operational planning: capacity ramp timing, regional demand elasticity, and the pace at which high-performance ceramic components displace legacy alternatives in specific use cases. The result is a forecast architecture that can be stress-tested against internal assumptions, enabling teams to evaluate upside scenarios, downside risks, and the strategic timing of investments in tooling, labor, and vertical integration.
What the Report Delivers: Operational Content Designed for Execution
This study is structured to move beyond descriptive market mapping and into the territory of decision enablement. Readers will encounter a comprehensive set of analytical modules that connect market structure to enterprise action. The report unpacks the core segmentation architecture, examining how different ferrule configurations align with distinct manufacturing requirements, performance tolerances, and customer adoption curves. Through detailed type-based evaluation, the research clarifies which form factors are experiencing the strongest volume momentum, where premiumization is compressing margins versus expanding value, and how design-led differentiation is reshaping competitive expectations.
Application-side analysis forms another critical pillar. The study dissects demand concentration across fiber optic connector deployments while also tracing the growing relevance of ceramic ferrules in other active and passive device segments. By mapping usage intensity, replacement cycle dynamics, and specification migration patterns, the report helps organizations identify where demand is structural versus cyclical, and where cross-selling or portfolio extension opportunities may be underappreciated. Regional dynamics are explored with equal depth, not as static share tables, but as living ecosystems shaped by local manufacturing footprints, import/export flows, infrastructure investment cycles, and evolving procurement preferences.
Beyond segmentation, the report integrates production economics, raw material sensitivity, and supply chain resilience into a unified framework. Readers gain visibility into how input cost behavior, processing complexity, and quality-control intensity influence cost structures across different manufacturing approaches. The study also evaluates the pace of technology maturation, including advances in grinding, polishing, and inspection workflows that are redefining what constitutes competitive yield and throughput. Taken together, these sections provide a practical operating manual for teams responsible for capacity planning, vendor selection, pricing strategy, and long-range business case development.
Competitive Landscape: Positioning, Moves, and the Concentration Reality
A market of this scale and growth profile does not evolve in a vacuum. Competitive positioning is already being reshaped by companies that are investing in material science expertise, application-specific customization, and regional manufacturing presence. The research profiles a set of organizations that embody the current market's strategic center of gravity, offering a window into how leading players are translating technical capability into commercial advantage.
Kyocera Corporation continues to anchor its reputation as a global leader in fine ceramics, leveraging deep expertise in zirconia-based components for optical applications. Its scale, process discipline, and broad industrial reach give it a distinctive vantage point when serving demanding connector and device specifications. Orbray Co., Ltd. has carved out a specialized position through a focus on zirconia and custom ceramic ferrules designed for fiber optic connectors and devices, with an organizational footprint that reflects both technical precision and strategic realignment. In 2026, Orbray relocated its headquarters to Yuzawa, Akita, Japan, a move that signals more than administrative change; it reflects a deliberate consolidation of engineering, production coordination, and regional talent strategy aimed at reinforcing its high-precision component capabilities.
On the manufacturing and export-intensive side, T&S Communication Co., Ltd. has built a recognized presence in zirconia ceramic ferrules for SC, LC, and MPO fiber optic connectors. Its participation in industry exhibitions, including the showcase of a high-density optical interconnect portfolio at APE 2026, illustrates how leading suppliers are aligning product roadmaps with the broader industry push toward density, bandwidth efficiency, and integration readiness. ChaoZhou Three-circle (Group) Co., Ltd. represents another important node in the landscape, producing fiber optic ceramic ferrules that have earned recognition as a national manufacturing champion product. This status underscores not only scale and consistency, but also the strategic weight that domestic champion enterprises carry in shaping supply reliability and cost competitiveness.
Market structure analysis within the report also examines concentration dynamics, revealing how a relatively small group of prominent players commands a meaningful share of total revenue while leaving substantial room for specialized entrants, regional specialists, and application-focused innovators. A concentrated core often translates into stable pricing benchmarks and rigorous quality expectations, but it can also create pockets of supply dependency if procurement strategies are not diversified. Understanding where concentration exerts pressure, and where fragmentation still offers negotiation leverage, is essential for procurement leaders, partnership strategists, and companies evaluating entry or expansion pathways.
Market Dynamics: Materials, Policy Signals, and the Supply-Side Context
The strategic usefulness of market intelligence depends heavily on its ability to connect demand forecasts with the operational realities that shape execution. In the ceramic ferrule sector, material inputs and policy environments are two of the most influential external variables. Zirconium-based ceramics remain foundational to high-performance ferrule production, and their cost behavior ripples through manufacturing economics, margin planning, and supplier negotiations. In the first quarter of 2025, global zirconium dioxide prices held broadly stable with a slight uptick, supported by recovering demand from automotive and electronics end markets. While this signal may appear narrow, it carries broader implications for producers who must calibrate inventory strategy, contract structures, and cost-pass-through mechanics in a market where raw material stability can quickly become a competitive differentiator.
Regulatory and policy developments add another layer of strategic context. The 2026 U.S. Geological Survey Mineral Commodity Summaries highlight ongoing critical mineral policies that continue to support domestic zirconium production investments. For companies operating in or dependent on transatlantic supply chains, such policy trajectories matter because they influence source diversification, lead-time risk, and the long-term economics of regionalized manufacturing. The report weaves these dynamics into its market analysis, ensuring that readers can interpret demand forecasts through the lens of material availability, policy-driven investment incentives, and the practical consequences for production planning and supplier selection.
These dynamics also intersect with broader technology and infrastructure trends. As optical interconnect requirements intensify and precision assembly tolerances tighten, the value of consistent ceramic quality, surface finish reliability, and dimensional repeatability becomes more pronounced. Markets that once treated ferrules as commoditized connector components are increasingly recognizing them as performance-critical elements whose specifications can influence insertion loss, alignment stability, and overall system reliability. That shift changes the bargaining position of manufacturers who can demonstrate process control and certification rigor, and it creates a more demanding environment for those competing primarily on price alone.
Why This Report Matters for 2026 Decision-Making
For executive teams, the strategic question is no longer whether ceramic ferrule demand will grow, but how to position an organization to capture the right portion of that growth with acceptable risk. This report is designed to answer that question through a decision-oriented lens. It helps strategy teams evaluate where to commit resources by clarifying which segments exhibit the strongest momentum and which applications offer the most durable demand profiles. It supports supply chain and procurement leaders by mapping the competitive field, concentration patterns, and material-market signals that shape sourcing resilience. It assists product and engineering organizations by highlighting the performance expectations and manufacturing discipline required to compete in a space where tolerance, consistency, and customization increasingly define commercial outcomes.
The research also serves investors and business development teams who need a reliable framework for assessing market attractiveness, competitive moats, and regional opportunity. Because the analysis bridges historical behavior, forward projections, and the active moves of key companies, it provides a practical vantage point for scenario planning. Whether the objective is to evaluate capacity expansion, assess partnership or acquisition targets, refine pricing strategy, or anticipate demand shifts tied to network build-outs and device adoption, the report offers a structured basis for judgment rather than a static snapshot.
Looking Ahead: The Value of Getting Ahead of the Curve
Markets rarely reward those who wait for full clarity before acting. In the ceramic ferrule sector, the convergence of precision manufacturing, optical network growth, and evolving material and policy conditions means that the most successful organizations will be those who interpret early signals accurately and convert them into disciplined strategy. The 2026 market research report is built to support exactly that posture. It provides a detailed, analytically rigorous view of where the market has been, how it is structured today, and what forces will shape its trajectory through the end of the decade.
The full study contains the deeper segmentation breakdowns, company-level profiles, demand-side mappings, and competitive analysis required to turn high-level direction into operational execution. It is organized to give decision-makers the specificity they need to validate assumptions, benchmark positioning, and identify the opportunities most relevant to their strategic objectives. For teams that require complete market sizing detail, segment-level interpretation, regional demand context, and an integrated competitive landscape assessment, the comprehensive report remains the definitive source for proceeding with confidence.
For detailed analysis of this topic, please visit the official page: Ceramic Ferrule Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Marketing Automation Software Market to Hit $7B in 2025, Projected 11.5% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the Marketing Automation Software Market: A 2026 Decision Framework
The landscape of customer engagement is undergoing a seismic shift. As organizations strive to balance personalization with privacy, scale with efficiency, and automation with human insight, the Marketing Automation Software Market has emerged as a critical infrastructure layer for enterprise growth. At PW Consulting, we recognize that navigating this complex ecosystem requires more than surface-level trend analysis. It demands a rigorous examination of historical trajectory, competitive dynamics, and emerging technological vectors. Our latest market research publication, the Marketing Automation Software Market Study 2026-2032, is designed specifically to equip senior executives, product leaders, and investment strategists with the actionable intelligence needed to make high-stakes decisions in 2026 and beyond.
Wireless Micrometer Heads Market
This introductory insight serves as a strategic primer. It outlines the macro environment, highlights the structural forces reshaping demand, and previews the depth of analysis contained within the full report. We will not obscure the magnitude of opportunity; however, to preserve the analytical integrity and commercial value of our comprehensive dataset, we deliberately withhold granular regional, application, and type-specific monetary breakdowns. The complete segmentation intelligence, coupled with proprietary company benchmarking and scenario modeling, is available exclusively through the full report. The following overview establishes the context and strategic framework that decision-makers must grasp before deploying capital or restructuring marketing technology stacks.
Far Infrared Panel Heaters Market
The Trajectory of Market Expansion and the 2026 Inflection Point
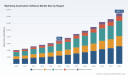
Establishing a reliable baseline is the first step in any strategic planning exercise. Over the historical review period from 2020 through 2025, the marketing automation software sector has demonstrated robust, compounding growth. Beginning at a foundational valuation of approximately 4.1 billion USD in 2020, the market advanced through successive years of acceleration, reaching an estimated valuation of 7.0 billion USD by the base year of 2025. This progression reflects not merely the adoption of digital tools but the structural embedding of automation into the core operational fabric of marketing organizations across industries.
Worldwide Bromine Tablet Market
Looking forward to the forecast period spanning 2026 to 2032, the appetite for scalable, intelligent automation continues to strengthen. Our projections indicate that the market will surpass the 7.6 billion USD threshold in 2026, setting the stage for a sustained expansion phase. Driven by an anticipated compound annual growth rate of 11.5 percent, the sector is on a trajectory to approach 15.0 billion USD by 2032. This growth corridor is not uniform; it is being shaped by divergent adoption curves, evolving procurement models, and a rapidly evolving technology landscape where artificial intelligence transitions from a value-add feature to an existential requirement.
For the 2026 strategic planner, these figures represent more than a growth narrative. They signal a market in transition from early-maturity consolidation to a phase where differentiation is determined by integration depth, AI capability, and compliance readiness. The 2026 horizon demands that leaders evaluate their automation investments against a backdrop of rising platform expectations, heightened data governance requirements, and intensifying vendor competition.
Key Structural Drivers Reshaping Market Dynamics
Several interconnected forces are propelling the market forward, yet each carries nuanced implications that require careful strategic interpretation. Understanding these dynamics is essential for framing the questions that our full research report answers in detail.
- Artificial Intelligence and Workflow Intelligence: The integration of AI-powered workflow orchestration, predictive segmentation, and intelligent prompt optimization is redefining what marketing automation platforms can achieve. Vendors are racing to embed generative and agentic capabilities that reduce manual configuration, accelerate campaign deployment, and improve personalization at scale. This shift is altering procurement criteria, with buyers increasingly prioritizing platforms that demonstrate tangible AI utility across the customer lifecycle rather than isolated machine learning features.
- Omnichannel Orchestration and Real-Time Engagement: Customer expectations have cemented the need for seamless, cross-channel engagement. Platforms that can synchronize messaging across email, social, web, mobile, and paid channels while maintaining contextual continuity are gaining traction. Real-time analytics, predictive behavioral scoring, and dynamic content adaptation are moving from premium capabilities to baseline expectations, particularly for organizations seeking to maximize lifetime value.
- Data Governance, Privacy Regulation, and On-Premise Resilience: The regulatory environment is imposing new constraints on data handling, consent management, and cross-border data flows. Recent adjustments to privacy frameworks have introduced stricter monetary thresholds and expanded deletion mechanisms, compelling organizations to reassess their data architecture. Concurrently, deployment preferences continue to reflect a strong preference for on-premise and hybrid models in segments where data control, sovereignty, and compliance assurance are paramount. This dynamic is creating a bifurcated market in which platform flexibility and governance tooling are decisive competitive differentiators.
- Talent Scarcity and Operational Efficiency: The demand for sophisticated marketing automation is outpacing the supply of specialized talent. Shortages in qualified marketing automation specialists are exerting measurable pressure on implementation timelines and optimization velocity, introducing a modest but persistent drag on growth trajectories. Organizations are responding by prioritizing platforms with intuitive configuration, low-code workflow design, and embedded guidance that reduce reliance on scarce technical resources while preserving operational rigor.
Competitive Landscape: Leadership, Differentiation, and Strategic Positioning
The vendor ecosystem in this market is characterized by a mix of broad-platform incumbents, specialized challengers, and enterprise-grade solution providers. Our analysis indicates a moderately concentrated market structure, with the top three players capturing a meaningful share of total revenue and the top five collectively accounting for a majority of market activity. This concentration does not imply stagnation; rather, it reflects a competitive arena where differentiation is increasingly articulated through product philosophy, ecosystem integration, and the ability to address distinct customer archetypes.
Several established leaders continue to set the pace. HubSpot, headquartered in Cambridge, Massachusetts, has reinforced its position through a comprehensive Marketing Automation Hub that tightly couples CRM integration, AI-powered workflows, and end-to-end funnel management. Its recent Spring 2026 Spotlight release introduced over 100 updates, including HubSpot AEO for AI-driven prompt suggestions and brand visibility analytics, signaling a strategic emphasis on search-augmented engagement and measurable brand impact. ActiveCampaign, based in Madison, Wisconsin, has pursued a focused strategy centered on sales and marketing alignment, deploying AI agents and omnichannel capabilities to unify customer communication. Its November 2025 product expansion, which integrated Active Intelligence Personalized Cards and Knowledge Base functionality, also established an official Claude Connector, reflecting a broader industry movement toward interoperable AI ecosystems.
Specialized strengths define other prominent players. Klaviyo, from Boston, has carved a distinct niche in customer lifecycle marketing automation, particularly for e-commerce, leveraging real-time segmentation and AI agents to drive commerce-oriented engagement. Braze, headquartered in New York, delivers real-time customer engagement automation across channels, using predictive analytics and its Sage AI framework to power moment-based interactions. On the enterprise side, Salesforce Marketing Cloud and Adobe Marketo Engage continue to anchor large-scale deployments. Salesforce’s San Francisco-based platform emphasizes multi-channel orchestration within a broader CRM ecosystem, while Adobe’s Marketo Engage, based in San Jose, remains a focal point for B2B demand generation and lead nurturing in complex enterprise environments.
Oracle Eloqua, from Austin, provides enterprise demand generation automation with deep integration into Oracle CX and sophisticated workflow capabilities, appealing to organizations already invested in the Oracle technology estate. Microsoft Dynamics 365 Marketing, rooted in Redmond, integrates marketing automation directly within the Dynamics 365 environment, aligning marketing execution closely with CRM and sales workflows. Meanwhile, Mailchimp, based in Atlanta, continues to serve a broad user base with accessible email and multi-channel automation, automation sequences, and CRM ties that lower the barrier to entry for smaller teams and scaling organizations.
This competitive mosaic illustrates a market where platform philosophy, target customer profile, and AI integration strategy are as consequential as raw feature counts. Our report provides a structured comparative analysis of these vendors, examining product roadmaps, deployment models, ecosystem alliances, pricing dynamics, and positioning relative to key customer segments. It also explores how recent product releases and partnership moves are reshaping buyer expectations and influencing vendor selection criteria in 2026.
Research Coverage and Operational Utility
A market study earns its place on a leadership team’s desk only if it translates data into decision-ready insight. Our Marketing Automation Software Market research is constructed to support a wide range of strategic applications, from technology investment planning and vendor evaluation to competitive benchmarking and market entry strategy. The report is organized to provide both macroeconomic clarity and granular, actionable detail, while maintaining the analytical discipline necessary to avoid oversimplified conclusions.
- Historical Baseline and Forecast Architecture: The research establishes a robust historical foundation spanning 2020 through 2025 and extends a forward-looking forecast through 2032. This dual-horizon approach enables executives to validate assumptions against observed performance and to model multiple growth scenarios based on different adoption and technology maturation pathways.
- Segmentation Frameworks: The study decomposes market activity across multiple dimensions, including functional type, application, and regional distribution. By mapping how value accrues across campaign management, email marketing, lead nurturing and scoring, social media marketing, analytics and reporting, content management, and other functional categories, the report helps organizations identify where investment intensity and platform maturity are most pronounced. Application-level analysis differentiates between large enterprise deployments and SME adoption patterns, providing context for procurement behavior, integration complexity, and scaling requirements.
- Competitive Company Profiles and Benchmarking: The report delivers in-depth profiles of leading vendors, including headquarters location, platform capabilities, product philosophy, and recent strategic moves. It evaluates how each player addresses core buyer needs, where they position themselves relative to competitors, and how their recent releases and integrations reshape the value proposition. This competitive mapping supports vendor shortlisting, partnership evaluation, and strategic positioning analysis.
- Regulatory, Compliance, and Deployment Considerations: Given the increasing importance of data governance and privacy compliance, the research examines how regulatory developments influence platform selection, deployment preferences, and operational processes. It addresses the continued relevance of on-premise and hybrid deployment models in segments where data control and regulatory assurance are decisive, and it contextualizes how compliance requirements are being operationalized within marketing technology stacks.
- Strategic Implications and Decision Frameworks: Beyond descriptive analysis, the report provides structured guidance for evaluating automation investments. It outlines criteria for assessing platform fit, integration depth, AI readiness, scalability, and total cost of ownership, helping leaders translate market intelligence into actionable plans for procurement, development, and organizational alignment.
What the Full Report Delivers
The excerpt presented here establishes the strategic terrain and highlights the critical forces that will shape decision-making in 2026. Yet the full complexity of the market, including the precise allocation of revenue across regions, functional types, and application segments, as well as the detailed vendor benchmarking and scenario modeling, resides within the complete research publication. Accessing the full report unlocks a comprehensive dataset and a structured analytical framework that enables executive teams to move beyond general market awareness to precise, evidence-based strategy formulation.
The complete study provides explicit segmentation values across all major geographic regions, granular breakdowns by functional type and application profile, and quantified concentration metrics that illuminate the competitive structure of the market. It also supplies a detailed catalog of recent product releases, partnership developments, and regulatory updates that are actively reshaping buyer expectations and implementation roadmaps. By consolidating these elements into a single, rigorously validated research asset, the report empowers leaders to benchmark their current position, evaluate alternative investment pathways, and anticipate the competitive moves that will define the next phase of market evolution.
Strategic Outlook for 2026 and the Path Forward
The Marketing Automation Software Market in 2026 is defined by a confluence of accelerating AI adoption, intensifying omnichannel expectations, tightening data governance, and a competitive vendor landscape that rewards differentiation through integration and usability. Organizations that treat automation as a strategic enabler rather than a tactical utility will be best positioned to capture the value embedded in this growth corridor. The window for decisive action is open, but it requires clarity about where to invest, which capabilities to prioritize, and which vendors align with an organization’s operational and compliance realities.
PW Consulting’s Marketing Automation Software Market research is built to provide that clarity. By combining a rigorous historical-to-forecast architecture with in-depth competitive analysis, segmentation insight, and actionable decision frameworks, the study offers a reliable foundation for executive strategy in a market that is both dynamic and consequential. The macro trajectory is promising, the competitive stakes are high, and the margin for strategic misjudgment is narrowing. Leaders who ground their 2026 decisions in comprehensive, current intelligence will be better equipped to navigate complexity, optimize investment outcomes, and build marketing automation capabilities that scale with their ambitions.
The complete intelligence, including detailed segmentation data, vendor benchmarking, regulatory impact assessment, and forecast scenarios, is available through the full report. Access the complete research to equip your leadership team with the depth of analysis required to make confident, forward-looking decisions in the Marketing Automation Software Market.
For detailed analysis of this topic, please visit the official page: Marketing Automation Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 10-Deacetylbaccatin III Market Hits $161.5M in 2025, Poised for 5.5% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the 10-Deacetylbaccatin III Market: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global landscape for oncology-supporting pharmaceutical intermediates is undergoing a structural transformation, driven by sustained demand for taxane-based therapeutics, expanding regional manufacturing capabilities, and an increasingly rigorous regulatory environment. As therapeutic pipelines continue to rely on semi-synthetic routes for paclitaxel and docetaxel production, the upstream supply of 10-Deacetylbaccatin III has evolved from a niche botanical input into a strategically critical node within the broader pharmaceutical value chain. Our latest market research delivers a comprehensive, forward-looking assessment of this segment, positioning corporate strategists, procurement leaders, and investment professionals with the analytical clarity required to make informed decisions across the forecast horizon.
Worldwide Aged Home Care Market
Designed to anchor executive planning for the 2026 strategic cycle and beyond, this study bridges historical performance tracking with multi-year projection modeling. Rather than offering static snapshots, the analysis maps the momentum of market expansion, dissects the structural forces shaping supply and demand, and evaluates how key enterprise players are positioning themselves amid shifting regulatory expectations, botanical sourcing constraints, and evolving purity specifications. The following exposition outlines the strategic rationale behind this research, previews the analytical architecture of the full report, and demonstrates how the intelligence contained within it can be operationalized to strengthen market entry strategies, optimize procurement frameworks, and refine competitive positioning.
Escape Hoods Market
Market Trajectory: Translating Historical Momentum into Forward-Looking Strategy
Market sizing and growth modeling form the quantitative backbone of any credible strategic assessment. Over the historical window spanning 2020 through 2025, the global 10-Deacetylbaccatin III market has demonstrated a consistent upward trajectory, moving from an initial revenue base into progressively higher valuation tiers as pharmaceutical manufacturers scaled production capacity and secured long-term supply agreements for taxane intermediates. The baseline year of 2025 establishes a clear inflection point, after which the forecast period extending to 2032 illustrates a steady compound annual growth rate that reflects both underlying demand expansion and incremental capacity rationalization across key producing regions.
Worldwide Food Foil Market
For corporate planners, this trajectory is not merely a numerical projection; it is a structural signal. A sustained mid-single-digit CAGR across the forecast window indicates a market that is maturing but far from saturated, with growth increasingly dependent on alignment between intermediate availability, downstream API scheduling, and regional regulatory clearance cycles. The projection framework incorporated in our study captures this dynamic by modeling demand propagation through manufacturing pipelines, accounting for capacity ramp-up timelines, and stress-testing scenarios against potential supply interruptions, botanical harvest variability, and shifts in procurement preference toward higher-purity grades.
Decision-makers leveraging this intelligence can translate the growth curve into actionable planning parameters. Procurement teams can map contract renewal cycles against projected supply tightness, manufacturing strategists can evaluate whether to expand in-house extraction or secure multi-source agreements with specialized botanical intermediate suppliers, and investors can distinguish between cyclical demand spikes and structural growth drivers when assessing exposure to taxane-related segments. By anchoring forecasts to scenario frameworks rather than single-point estimates, the research enables organizations to build flexible operating models that withstand market volatility while capturing upside from capacity expansions and regional demand acceleration.
The research deliberately withholds granular segment-level revenue breakdowns in this introductory preview, reserving those precise allocations for the full analytical suite. This approach ensures that prospective clients experience the methodological rigor of the study while recognizing the necessity of accessing the complete dataset to unlock region-specific sourcing strategies, application-driven demand mapping, and formulation-grade commercial prioritization.
Value Chain Architecture and Procurement Implications
The commercial ecosystem surrounding 10-Deacetylbaccatin III is defined by a complex intersection of botanical sourcing, semi-synthetic processing, regulatory documentation, and downstream pharmaceutical demand. Unlike commodity chemical intermediates, this compound requires specialized extraction and purification pathways originating from Taxus species, which introduces inherent volatility related to harvest cycles, geographic sourcing constraints, environmental regulations, and the operational maturity of extraction facilities. Simultaneously, downstream manufacturers depend on consistent intermediate quality and documented compliance frameworks to maintain uninterrupted production of anti-cancer APIs, making supply reliability as critical as cost competitiveness.
Our study maps this value chain in operational detail, providing procurement and supply chain leaders with a structured view of where value is created, where bottlenecks typically emerge, and how supplier capabilities differ across regions and processing standards. The analysis differentiates between standard formulation pathways and enhanced purity grade outputs, recognizing that while standard formulations address broad commercial manufacturing needs, enhanced purity specifications increasingly influence procurement decisions in markets where regulatory scrutiny, downstream process sensitivity, and quality documentation requirements have intensified.
Chemical synthesis and research and development applications further complicate the procurement landscape. While the majority of intermediate demand flows toward pharmaceutical manufacturing, a meaningful share of consumption originates from synthesis programs and R&D initiatives that prioritize availability, documentation, and formulation flexibility over bulk cost optimization. This dual-channel demand structure requires buyers to maintain differentiated sourcing strategies: long-term, volume-oriented agreements for manufacturing-scale requirements, and responsive, specification-sensitive procurement channels for development-stage consumption. The research outlines how leading suppliers structure their commercial offerings to serve both channels, and where structural gaps persist that forward-looking organizations can exploit through targeted supplier partnerships or vertical integration.
For strategic planners, the value chain analysis serves as a diagnostic tool for assessing exposure to supply concentration, evaluating the credibility of supplier certifications, and determining whether existing procurement architectures are aligned with anticipated demand quality and volume trajectories. Understanding how botanical extraction capacity, purification throughput, and documentation readiness interact enables organizations to anticipate lead-time variability, negotiate more effectively, and construct contingency plans that reduce vulnerability to regional disruptions or regulatory hold-ups.
Competitive Landscape: Strategic Positioning of Key Market Participants
The competitive environment for 10-Deacetylbaccatin III is characterized by a fragmented yet increasingly differentiated supplier base, with participants competing across dimensions such as botanical sourcing expertise, regulatory documentation breadth, processing infrastructure, geographic reach, and commercial specialization. Market concentration metrics indicate that while no single enterprise dominates the segment, a cluster of established players has secured meaningful positions through combinations of extraction capability, compliance readiness, and regional distribution networks. The strategic relevance of this landscape lies not in simple market share rankings, but in understanding how each participant’s operational profile shapes their ability to capture demand growth, withstand supply shocks, and expand into adjacent formulation or purity segments.
Indena S.p.A. exemplifies a Europe-based specialist with deep botanical intermediate expertise, leveraging established regulatory documentation and commercial readiness as a pure molecule precursor pathway for docetaxel-related applications. Its positioning reflects a broader strategic archetype: specialized extraction capability paired with compliance-oriented commercial deployment, enabling access to procurement programs that prioritize documented supply continuity and formulation traceability. Phyton Biotech LLC operates from a similar philosophy but with a stronger emphasis on plant-derived pharmaceutical intermediates for semi-synthetic taxane production, reinforcing its role as a globally oriented supplier that bridges extraction capability with downstream manufacturing requirements.
Within the Asia-Pacific region, several producers have built commercial footprints that combine regional manufacturing density with export-oriented distribution. Samyang Biopharmaceuticals Corporation maintains an active supply posture supported by Asia-Pacific manufacturing and distribution infrastructure, making it a relevant reference point for organizations evaluating regional sourcing diversification. ScinoPharm Taiwan, Ltd. brings advanced process control infrastructure to its intermediate production, an attribute that increasingly matters for buyers seeking consistent specification performance and scalable purification capacity. In China, a cluster of producers including Hainan Yew Pharmaceutical Co., Ltd., Fujian South Pharmaceutical Co., Ltd., Chengdu Biopurify Phytochemicals Ltd., Wuxi Taxus Pharmaceutical, and Ningbo Green-Health Pharmaceutical illustrate the breadth of domestic manufacturing capability, ranging from large-scale domestic and export-focused production to GMP-aligned facilities serving pharmaceutical-grade intermediate requirements. Each organization brings a distinct commercial emphasis, whether oriented toward volume leadership, cost optimization for export markets, or compliance and certification readiness.
India-based Alchem International Pvt. Ltd. adds another strategic dimension by combining botanical API manufacturing with a robust certification portfolio, reinforcing its relevance for buyers seeking internationally recognized documentation alongside export capability. Meanwhile, Germany-based PhytoLab GmbH occupies a specialized niche as a reference substance specialist, offering high-purity standards that support research and pharmaceutical benchmarking rather than bulk manufacturing supply. This diversity of strategic archetypes underscores the importance of matching supplier selection to procurement objectives: bulk manufacturing continuity, enhanced purity assurance, regulatory documentation strength, regional proximity, or research-grade standardization.
Our competitive analysis extends beyond individual company profiles to examine how these participants interact within the broader market structure. The study assesses where capacity expansion is likely to alter supply balance, where certification and compliance advantages translate into commercial preference, and where regional manufacturing networks may tighten or loosen depending on export policy, environmental constraints, and downstream demand distribution. For corporate strategists, this competitive mapping provides a framework for evaluating partnership candidates, assessing substitution risk, and identifying which supplier attributes will carry the most weight as regulatory expectations and purity requirements continue to evolve.
Structural Drivers, Regulatory Context, and Emerging Industry Dynamics
The medium-term trajectory of the 10-Deacetylbaccatin III market is shaped by a set of interlocking structural drivers that extend beyond simple demand growth. One of the most significant is the continuing reliance of taxane-based oncology therapies on semi-synthetic pathways that depend on dependable intermediate supply. As downstream pharmaceutical programs scale or sustain production to meet therapeutic demand, the upstream requirement for high-quality 10-Deacetylbaccatin III becomes increasingly embedded in operational planning, contract manufacturing schedules, and API continuity strategies. This structural dependency reinforces the market’s resilience even as pricing, sourcing conditions, and regional production dynamics fluctuate.
Regulatory and quality assurance expectations represent another central force. Buyers in pharmaceutical manufacturing environments are placing greater emphasis on documented GMP alignment, certification breadth, and consistent specification control, particularly when intermediates feed into regulated drug production pathways. In this context, suppliers that can demonstrate robust process control, traceability, and internationally recognized documentation gain a structural advantage, while those competing primarily on price without equivalent compliance readiness face increasing scrutiny. The research captures how these expectations are reshaping procurement criteria and influencing commercial negotiations across regions.
Botanical sourcing dynamics introduce additional complexity. Because the feedstock originates from biologically derived sources, supply planning must account for harvest timing, extraction yield variability, and the operational capacity of specialized processing facilities. Organizations that depend on single-source arrangements or geographically concentrated supply chains face elevated exposure to disruptions, making diversification, buffer inventory planning, and supplier qualification rigor more important than ever. At the same time, suppliers with mature extraction infrastructure, established regrowth or sustainable sourcing practices, and multi-regional distribution capability are better positioned to stabilize availability and support long-term contractual commitments.
In addition to these structural forces, the market is being shaped by evolving procurement preferences around formulation type and purity grade. As manufacturing processes become more sensitive to impurity profiles and downstream yields, demand for enhanced purity grades is gaining strategic relevance, particularly for applications where specification consistency directly influences processing efficiency or regulatory readiness. Simultaneously, standard formulations continue to serve a broad manufacturing base where cost-efficiency and reliable availability remain paramount. The interplay between these demand segments influences pricing behavior, supplier capacity allocation, and the strategic emphasis of intermediate producers as they decide whether to broaden standard-grade output or invest in higher-purity processing pathways.
This preview does not enumerate specific development announcements or transient market events; instead, it frames the analytical lens through which such dynamics are evaluated in the full report. The complete study assesses how operational developments, certification milestones, capacity adjustments, and regional supply shifts alter competitive positioning and procurement strategy, allowing decision-makers to distinguish signal from noise when planning for the 2026 horizon and beyond.
How the Full Research Converts Intelligence into Action
A market research report delivers value only when it converts analytical depth into operational decision support. Our 10-Deacetylbaccatin III study is structured to serve multiple strategic functions simultaneously: as a source of macro-level growth intelligence, as a diagnostic framework for supplier evaluation, as a reference for regional demand distribution, and as a planning tool for procurement, manufacturing, and investment teams. The report integrates historical performance tracking, forecast modeling, segmentation analysis, competitive profiling, and supply chain assessment into a unified analytical system that can be adapted to different organizational use cases.
For procurement and supply chain leaders, the study provides the context needed to design sourcing architectures that balance cost, quality, and continuity. By examining how intermediate supply flows through manufacturing pipelines, where specification sensitivity is highest, and which supplier profiles offer the strongest documentation or capacity advantages, procurement teams can construct more resilient contracts, evaluate multi-source strategies, and prioritize supplier qualification criteria that align with both near-term operational needs and longer-term regulatory expectations.
For business development and market entry strategists, the report offers a structured view of where demand is expanding, which formulation and purity segments present the strongest commercial opportunity, and how competitive intensity varies across sourcing regions. This intelligence supports decisions about partnership selection, distribution channel design, and capacity investment, helping organizations avoid overconcentration in saturated supply pathways while identifying underserved demand pockets that may warrant dedicated commercial engagement.
For investor and corporate strategy teams, the study provides a framework for assessing market maturity, growth sustainability, and competitive differentiation without relying on isolated data points. By linking growth projections to structural drivers, supply constraints, and supplier capability profiles, the analysis enables more disciplined evaluation of opportunities tied to taxane intermediate supply, botanical extraction capacity, and pharmaceutical intermediate manufacturing.
The full report contains the detailed segmentation architecture, regional demand distribution, formulation-grade commercial splits, and company-level capability assessments necessary to execute these strategies with precision. Those core segmentation figures and detailed allocations are intentionally reserved for the complete intelligence package, ensuring that the full depth of the analysis is accessible only to clients who obtain the complete research. This approach preserves the strategic value of the dataset while allowing the preview to demonstrate the rigor, structure, and decision orientation of the study.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle presents a pivotal moment for organizations engaged with pharmaceutical intermediates, botanical extraction supply chains, and taxane-related manufacturing pathways. Demand is not entering a speculative phase; it is continuing along a documented growth path that requires deliberate strategic alignment rather than reactive procurement adjustments. Supplier capabilities are diversifying, regulatory expectations are tightening, and the distinction between standard and enhanced-purity supply is becoming increasingly material to downstream operational outcomes. In this environment, decisions made with incomplete intelligence carry disproportionate risk, while organizations that ground their planning in structured, forward-looking analysis are better positioned to secure supply continuity, optimize cost-quality trade-offs, and build defensible competitive positioning.
This research is designed to support that discipline. It translates historical momentum into forecast orientation, maps competitive capability into procurement and partnership implications, and frames structural drivers in terms that can be directly applied to sourcing strategy, capacity planning, and market development decisions. By engaging with the full study, decision-makers gain access to the segmentation detail, regional demand architecture, company-level capability assessment, and scenario-based planning context needed to move from broad market awareness to executable strategy.
The 10-Deacetylbaccatin III market is not defined solely by its growth rate; it is defined by the strategic choices organizations make in response to supply complexity, regulatory evolution, and competitive differentiation. Our analysis provides the intelligence foundation for those choices. For executives seeking to align 2026 planning with a clear, evidence-based view of market direction and supplier landscape, the complete research offers the depth required to act with confidence and precision.
For detailed analysis of this topic, please visit the official page: 10-Deacetylbaccatin III Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Watermelon Seeds Market Hits $752.25M in 2025, Forecasts 6.8% CAGR to 2032
By PW Consulting, 2026-09-07
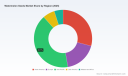
Strategic Horizons: Navigating the Watermelon Seeds Market in 2026 and Beyond
The global agriculture sector stands at a critical inflection point, where biological innovation meets complex supply chain dynamics. For stakeholders in the watermelon seeds market, the period from 2026 through 2032 represents more than just a forecast window; it is a decisive era for capital allocation, breeding strategy, and supply chain resilience. As we release the latest edition of our Watermelon Seeds Market research, our objective is to provide the strategic scaffolding necessary for enterprises to navigate this growth trajectory with precision.
Tea Cutting Machine Market
This report is designed not merely as a repository of statistics, but as a decision-support tool for executives, investors, and agricultural strategists. The following analysis outlines the macroeconomic landscape, competitive pressures, and regulatory vectors that will define market performance over the next seven years. By synthesizing historical performance with forward-looking indicators, we uncover the latent opportunities within a sector that is evolving faster than traditional agricultural models predict.
Business Valuation Software Market
Market Trajectory and Revenue Architecture
Understanding the current valuation and future potential of the watermelon seeds market requires a clear view of the revenue architecture established over the past half-decade. Our analysis covers a robust historical period from 2020 to 2025, establishing a baseline of stability before projecting growth into the 2026-2032 forecast period. The data indicates a consistent upward trend in market valuation, reflecting heightened demand across both commercial agriculture and specialized nutraceutical applications.
Worldwide Finger Expansion Joint Market
In 2020, the market established a foundational revenue base that has since compounded annually. By 2025, the overall market size had expanded significantly, signaling strong adoption rates and expanded cultivation areas globally. Looking toward the forecast horizon, the momentum continues unabated. The market is projected to reach substantial revenue milestones by 2032, driven by consistent compound annual growth. This growth is not linear but is influenced by technological adoption in seed breeding and shifting consumer preferences toward seedless and specialty varieties.
The Compound Annual Growth Rate (CAGR) observed during the forecast period underscores the resilience of this sector. Even amidst global supply chain perturbations, the demand for high-quality planting material remains inelastic relative to price fluctuations in many regions. For strategic planners, this implies that revenue models based on volume expansion must account for yield improvements rather than solely relying on acreage increases. The revenue unit measured in millions USD provides a standardized framework for comparing investment returns against the cost of research and development in seed genetics.
Competitive Dynamics and Strategic Positioning
The competitive landscape of the watermelon seeds market is characterized by a mix of global agrochemical giants, specialized seed breeders, and regional exporters. Our analysis identifies key companies that are shaping the market through variety launches, licensing agreements, and geographic expansion. Understanding the positioning of these entities is crucial for identifying partnership opportunities or assessing competitive threats.
Leading the charge in innovation are entities such as Syngenta Vegetable Seeds and Sakata Seed America. These organizations are not merely maintaining existing portfolios; they are actively expanding them to capture premium market segments. For instance, recent updates in early 2026 highlight the introduction of new triploid varieties designed for specific rind patterns and sugar content profiles. These launches are strategic moves to differentiate products in a crowded marketplace where visual appeal and taste consistency drive retailer and consumer choice.
In the Asia-Pacific region, companies like Safal Seeds and Seamons Seeds Pvt. Ltd. are focusing on high-yield hybrid varieties tailored for export and commercial production. Their strategies reflect the region's dual role as both a major producer and a growing consumer market. Similarly, Chinese enterprises such as Rizhao Spring Trading Co., Ltd. and Gansu Dunhuang Seed Co., Ltd. are leveraging manufacturing scale to serve international demand, emphasizing export capabilities for kernels and seeds alike.
The presence of firms like East-West Seed, utilizing AI-powered quality inspection systems, signals a broader industry trend toward technology integration in seed production. This shift aims to reduce variability and ensure genetic purity, which is a critical quality metric for commercial growers. Meanwhile, companies like High Mowing Organic Seeds and Johnny's Selected Seeds cater to the niche but growing demand for organic and open-pollinated varieties, addressing the needs of small-scale growers and specific consumer demographics that prioritize non-GMO attributes.
Strategic consolidation is also evident. Recent movements include licensing agreements that grant exclusive access to germplasm and breeding pipelines. These agreements accelerate the development cycle for new varieties, allowing larger entities to secure intellectual property advantages over competitors. For market entrants, this suggests that barriers to entry are rising, particularly in the segment of proprietary hybrid seeds.
Technological Innovation and Breeding Pipelines
The core of value creation in this market lies in breeding technology. The shift from traditional open-pollinated varieties to advanced hybrids, particularly triploid seedless varieties, is a primary driver of market differentiation. Industry data suggests that hybrid diploid seeds held a significant share in recent years, yet the forecast indicates that hybrid triploid seeds are expected to grow at a faster rate through the end of the decade.
This divergence creates distinct strategic pathways for seed companies. Those focused on diploid varieties must compete on cost efficiency and reliability for standard farming operations. Conversely, players in the triploid segment are commanding premiums based on consumer preference for convenience and eating quality. The development of varieties like the El Capitan triploid or the Midnight Jewels portfolio illustrates how breeders are targeting specific aesthetic and sensory traits to capture value-added market segments.
However, technological advancement brings complexity. Seedless varieties cannot be established by direct seeding in certain contexts, requiring specific transplanting protocols that increase operational complexity for growers. Furthermore, the biological requirements for producing triploid seeds involve specific pollinator ratios and handling procedures. Companies that can provide not just the seeds but also the technical support and agronomic guidance around these varieties gain a competitive moat.
Innovation is also responding to regulatory and environmental pressures. New launches are increasingly designed for export markets and fresh-cut applications, where shelf life and uniformity are paramount. The integration of digital tools in quality inspection, as seen with some leading breeders, ensures that the genetic potential of these new varieties is realized in the field without degradation during processing.
Regulatory Frameworks and Supply Chain Constraints
The operational environment for the watermelon seeds market is heavily influenced by regulatory frameworks and physical constraints. Phytosanitary regulations are becoming increasingly stringent, particularly regarding international trade. These regulations increase the demand for seed treatments to enhance germination rates and facilitate cross-border movement of planting material. Compliance is no longer optional; it is a prerequisite for market access in key regions.
Changes in seed handling and testing protocols have also impacted cost structures. Recent industry profiles indicate that changes in handling have led to significant increases in the price of watermelon seeds for growers. This cost pressure is compounded by the requirement for soil incorporation for certain seed treatments, such as those involving neonicotinoids, to ensure control and efficacy. These operational requirements add layers of complexity to the supply chain, affecting logistics and inventory management.
Labor conditions and input costs are shaping operational planning for seed production and field activities in 2026. Tight labor conditions in key agricultural regions are driving up the cost of harvesting and processing seeds, particularly for varieties that require manual sorting or delicate handling. Rising input costs for fertilizers and field maintenance further squeeze margins unless offset by higher yields or premium pricing strategies.
For strategic planners, these dynamics suggest that supply chain resilience must be prioritized. Dependence on single-source regions for raw materials or processing could expose companies to significant risk if regulatory or labor disruptions occur. Diversification of sourcing and investment in automated processing technologies may be necessary to mitigate these cost pressures.
Strategic Imperatives for 2026 Decision-Makers
Based on the comprehensive analysis contained in our report, several strategic imperatives emerge for stakeholders planning their moves in 2026. The market is no longer a commodity play; it is a technology and service play. Success will depend on the ability to navigate the intersection of biological innovation, regulatory compliance, and market demand.
- Invest in Breeding R&D: With triploid varieties forecast to grow faster than diploid segments, allocating resources to develop unique, proprietary hybrids is essential. Licensing agreements and germplasm access will become critical assets for maintaining competitive advantage.
- Optimize Supply Chain Compliance: Navigating phytosanitary regulations and seed treatment requirements is vital for international expansion. Companies must ensure their handling and testing protocols meet the highest standards to avoid trade barriers and ensure germination reliability.
- Diversify Application Focus: While the food industry remains the dominant application segment, the nutraceutical sector offers high-margin opportunities. Seeds and kernels rich in nutrients are increasingly valued for health applications, providing an avenue for premium pricing.
- Monitor Regional Shifts: Growth is not uniform across all geographies. Market concentration data suggests that a significant portion of revenue is generated by a few key regions. Understanding the specific demand drivers in North America, Europe, and Asia Pacific is necessary for targeted expansion.
- Address Cost Pressures: With rising labor and input costs, operational efficiency is key. Automation in seed processing and strategic sourcing of raw materials can help protect margins amidst inflationary pressures.
Conclusion: The Value of Comprehensive Intelligence
The watermelon seeds market offers substantial opportunities for growth, but realizing this potential requires more than surface-level analysis. The interplay between breeding technology, regulatory environments, and competitive strategies creates a complex web that demands deep insight. Our structured research provides the granularity needed to make informed decisions, from assessing specific variety performance to understanding the financial health of key market participants.
For organizations looking to secure their position in this evolving landscape, access to detailed segmentation data, regional breakdowns, and competitor profiling is indispensable. The macro trends outlined here provide the direction, but the tactical execution relies on precise data. We invite industry leaders to explore the full scope of our findings to refine their strategies for the 2026-2032 period.
By leveraging this intelligence, stakeholders can move beyond reactive planning and toward proactive market shaping. The future of the watermelon seeds market belongs to those who can balance biological innovation with operational excellence and strategic foresight.
For detailed analysis of this topic, please visit the official page: Watermelon Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dicing Blade Market to Reach USD 371M by 2032 with 4.87% CAGR
By PW Consulting, 2026-09-07
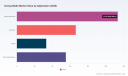
Strategic Intelligence in a Precision-Driven Era: Unlocking the Dicing Blade Market Opportunity for 2026 Decision-Makers
The precision manufacturing landscape is undergoing a structural recalibration, and few components illustrate this shift as clearly as the dicing blade. As semiconductor architectures shrink, ceramic substrates multiply, and glass-based solutions redefine optical and display supply chains, the tools that cut these materials with micron-level accuracy have moved from routine consumables to strategic procurement categories. For executives navigating 2026 capital allocation, supplier negotiations, and capacity planning, this transition demands a sharper analytical lens. Our latest market research publication on the Dicing Blade Market has been designed precisely for that moment of decision.
Papermaking Suction Rolls Market
This introductory overview outlines why the study matters now, what it contains, and how its findings translate into actionable strategy. It is not a data sheet. It is a framing device built to surface the questions that matter most to operations leaders, procurement directors, and R&D strategists, while preserving the granular intelligence that deserves dedicated exploration.
Worldwide Hydraulic Swing Beam Shear Market
Why 2026 Is a Pivot Year for Dicing Blade Strategy
The global market measured in our study has demonstrated a clear upward trajectory across the historical window from 2020 through 2025, and the momentum carries decisively into the forecast period extending through 2032. In baseline terms, the industry recorded a valuation of approximately 230.15 million USD in 2020 and has since progressed through successive growth phases, reaching an estimated 268.15 million USD by 2025. That progression reflects more than cyclical demand. It reflects a compounding effect of material innovation, tighter tolerance requirements, and a broader manufacturing ecosystem that is increasingly dependent on precision singulation and substrate preparation.
Product Data Management Software Market
Looking ahead, the forecast trajectory projects the market to exceed 283.04 million USD in 2026, with sustained expansion through the rest of the decade and a projected valuation approaching 371.0 million USD by 2032. The study attributes this expansion to a compound annual growth rate of 4.87 percent over the forecast horizon, a figure that may appear measured on the surface but carries strategic implications when viewed through the lens of segment competition, raw material transitions, and regional capacity shifts. In other words, the growth rate is not the whole story. The composition of that growth, the players driving it, and the operational constraints shaping it are where real decision advantage emerges.
For leadership teams planning 2026 investments, that means the question is no longer whether the dicing blade market is expanding. The question is whether an organization’s sourcing strategy, product roadmap, and geographic exposure are aligned with the segments and dynamics that will define the next cycle of value creation.
What the Study Delivers: Operational Intelligence, Not Just Market Size
A robust market research report should do more than describe what happened. It should equip teams to act on what comes next. Our Dicing Blade Market study is structured around that principle, with content developed for direct application in commercial planning, supplier evaluation, and technology assessment.
At its core, the report maps the market across multiple structural dimensions, giving readers a complete operational picture rather than a single aggregate number. The segmentation framework examines how demand disperses across blade type categories, application environments, and regional markets. It also provides historical context that helps distinguish temporary fluctuations from durable demand shifts. The forecast section translates that structure into forward-looking projections, allowing stakeholders to test scenarios against a consistent analytical baseline.
Beyond sizing and segmentation, the study integrates the forces that shape purchasing behavior and product development priorities. This includes the role of raw material characteristics in blade selection, with particular attention to how diamond grit continues to anchor market leadership due to its hardness profile and longevity in demanding dicing applications. It also addresses the regulatory and standards environment that increasingly governs production and deployment, including quality management expectations, safety considerations for dicing system implementations, and equipment automation guidelines that influence operational parameters. These are not peripheral details. They define what is commercially viable, what is auditable, and what can scale reliably across global supply chains.
The report also devotes substantial attention to the competitive landscape, evaluating how major manufacturers position themselves by bond type, application focus, and precision requirements. Rather than treating competition as a static ranking, the analysis emphasizes differentiation logic: where incumbents reinforce scale and process consistency, where specialized suppliers compete on low-chipping performance and ultra-thin geometries, and where regional manufacturers expand their footprint through materials-tailored solutions. This framing helps buyers and investors understand not only who operates in the market, but how value is created and defended within it.
How the Competitive Landscape Shapes 2026 Procurement and Partnership Decisions
The dicing blade market is characterized by a concentrated group of manufacturers whose capabilities span multiple blade families and end-use requirements. That concentration has implications for pricing discipline, supply reliability, and innovation cadence. The study examines several of the most influential participants, highlighting the specific roles they play in shaping demand pathways across semiconductor and adjacent precision material markets.
DISCO Corporation stands out as a manufacturer of precision diamond dicing blades offering resin, metal, and electroformed bond types for semiconductor wafer scribing and singulation. Their breadth across bond technologies gives them a strong position in applications where process flexibility and cut quality must be balanced against throughput requirements. Kulicke & Soffa Industries, Inc. operates as a supplier of hub dicing blades and specialized precision blades for wafer and package singulation in semiconductor assembly, reinforcing the importance of hub-based tooling in assembly-stage processing. Advanced Dicing Technologies Ltd. contributes a developer and global supplier profile that spans resin, nickel, and metal-bond families for high-precision semiconductor applications, emphasizing breadth and application adaptation.
UKAM Industrial Superhard Tools focuses on low-chipping, ultra-thin diamond dicing blades and precision tools for silicon wafers, sapphire, and ceramics, a positioning that matters in applications where edge quality and material integrity are non-negotiable. Ceiba Technologies provides specialized dicing blades, edge grind wheels, and precision consumables for semiconductor and hard drive applications, reflecting a broader consumable ecosystem approach rather than blade-only competition. Asahi Diamond Industrial Co., Ltd. is covered as a leading producer of diamond and CBN dicing blades and tools for semiconductor wafer processing and precision cutting, underscoring the continued importance of diamond and superhard material expertise. Tokyo Seimitsu Co., Ltd. enters the competitive picture as a supplier of precision ACCRETECH blades across resin, nickel, metal-bond, and hub types for wafer dicing, illustrating the role of established precision equipment ecosystems in blade demand. Shanghai Sinyang Semiconductor Materials Co., Ltd. represents a manufacturer of diamond dicing blades and solutions tailored for semiconductor wafer cutting and scribing, highlighting the growing influence of region-specific production capabilities and materials-oriented service models.
Read together, these profiles show that competition is not defined solely by blade pricing. It is defined by bond architecture, application fit, quality consistency, and the ability to support increasingly strict process standards. In 2026, procurement teams benefit from evaluating suppliers through that multidimensional lens rather than through headline specifications alone.
Forces Reshaping Demand, Cost, and Capability
Several industry dynamics are now influencing how dicing blade demand forms and how suppliers must respond. One of the most persistent is the continued dominance of diamond grit blades, which retain market leadership because of superior hardness and longevity in dicing applications. That advantage is not abstract. It translates into fewer blade changes, better edge control, and more predictable tool life in high-value processing steps. As a result, material performance remains a central variable in both product design and purchasing strategy.
At the same time, the regulatory and standards environment is tightening the operating perimeter for dicing-related production. Automotive-oriented quality expectations have introduced stricter requirements for semiconductor components used in dicing parameters, raising the bar for traceability, repeatability, and validation. Safety standards applicable to dicing system implementations impose operational constraints that affect layout, handling, and integration choices. Quality management frameworks require documented procedures for process control in dicing blade production, making consistency and procedural discipline part of the competitive baseline. Equipment automation guidelines also impose constraints on dicing saw operations, influencing how blade performance is evaluated in automated lines.
These forces matter because they interact with cost structures and supplier selection. A blade that delivers excellent cut quality but complicates compliance or integration may lose ground to a slightly less exotic alternative that performs reliably within a governed process. Conversely, in applications where chipping, surface integrity, or wafer yield dominate the value equation, premium tooling can justify its place in the process. The study provides the analytical scaffolding to assess those tradeoffs without reducing them to a single specification sheet.
Where Strategy Meets Market Reality
For organizations operating in or adjacent to semiconductor manufacturing, ceramics processing, glass cutting, and related precision material markets, the dicing blade segment offers a concrete example of how midstream tooling decisions shape upstream competitiveness. Blade selection influences yield, throughput, consumable costs, and downstream cleanliness. Supplier relationships influence lead-time stability, technical support depth, and the ability to adapt to changing substrate requirements. Regional exposure influences logistics, tariffs, and proximity to end-demand clusters.
The forecast period through 2032 suggests that these considerations will become more important, not less. Demand is projected to expand steadily, but the composition of that expansion will reward organizations that can align procurement with application needs, manage material and regulatory pressures intelligently, and select partners whose capabilities match the precision requirements of their specific production environment. In that context, the value of a detailed research study lies in its ability to convert aggregate growth into segment-level clarity.
Because the real strategic advantage often comes from the details, this overview intentionally focuses on the structure of the market and the logic behind the analysis rather than reproducing the full segmentation breakdown. The complete report reserves its deepest granularity for the audiences that need it: precise regional comparisons, application-level breakdowns, type-based demand splits, and the competitive profiles that connect those segments to real supplier behavior. That is where the numbers become operational.
How to Use This Research in 2026 Planning Cycles
The study is built to support several recurring planning needs. Procurement teams can use it to benchmark supplier positioning, evaluate whether current sourcing strategies align with the fastest-moving application and region combinations, and identify where bond-type and material preferences are shifting. Strategy and business development teams can use it to assess market entry feasibility, partnership logic, and the relative attractiveness of different precision material pathways. R&D and process engineering teams can use it to understand how tool performance expectations are evolving under tighter quality, safety, and automation requirements.
Executives can also use the report to test assumptions. If internal forecasts assume that one application vertical will carry most of the growth, the segmentation structure in the study provides a reference point for stress-testing that belief. If leadership expects regional demand to concentrate in familiar markets, the regional breakdown offers context for whether that exposure remains optimal. If the prevailing view is that tool purchasing is primarily a cost exercise, the competitive and regulatory analysis reframes it as a capability and compliance exercise as well.
Conclusion: Precision Is the New Strategic Currency
The dicing blade market may be specialized, but its implications are broad. It sits at the intersection of material science, process control, automation, and supply chain discipline. In 2026, organizations that treat dicing blades as mere consumables risk missing the larger signal: precision tooling is increasingly a determinant of yield, consistency, and downstream competitiveness.
Our Dicing Blade Market research was developed to help leaders read that signal clearly. It combines historical context, forward-looking projections, competitive profiles, and regulatory and material dynamics into a single analytical framework. The headline growth figures tell part of the story. The segment composition, supplier differentiation, and operating constraints tell the rest.
For decision-makers who need the full detail set, the complete report provides the regional, application, and type-level intelligence behind the narrative presented here. That is where the analysis moves from orientation to execution, and where strategy becomes measurable.
For detailed analysis of this topic, please visit the official page: Dicing Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PC System Utilities Market Hits $17.125 Billion in 2025, Expands at 4.11% CAGR Through 2032
By PW Consulting, 2026-09-07
Navigating the PC System Utilities Software Market: Strategic Imperatives for 2026 and Beyond
The PC System Utilities Software Market has entered a phase of structured evolution. Over the historical period from 2020 to 2025, the sector demonstrated consistent upward momentum, with global revenue climbing from approximately 13,682 million USD to around 17,125 million USD. As organizations plan their technology roadmaps for 2026, the strategic value of this market lies not merely in incremental growth, but in the convergence of operational efficiency demands, heightened data-security expectations, and an increasingly fragmented competitive landscape. This research provides executive decision-makers with a rigorous, forward-looking framework to navigate market entry, portfolio expansion, and partnership strategies through the 2032 horizon.
Worldwide Drawer Air Fryer Market
Market Architecture and the Trajectory to 2032
Understanding the macroeconomic footprint of the market is the first step toward informed capital allocation. The baseline year of 2025 established a clear inflection, and the forecast window from 2026 to 2032 reveals a compound annual growth rate of 4.11 percent. While the headline figure signals stability, the underlying trajectory exposes a more nuanced reality: growth is not linear, and it is punctuated by structural shifts in how users and organizations interact with system maintenance tools. By 2032, the market is projected to reach approximately 22,739 million USD, representing a meaningful expansion from the 2025 baseline. This progression is shaped by several interlocking forces. First, the maturation of operating-system ecosystems has increased the baseline demand for third-party optimization and maintenance utilities, even as native OS capabilities have improved. Second, the proliferation of digital workflows across both individual and commercial environments has elevated the cost of downtime, driving users toward tools that promise faster system responsiveness and cleaner resource allocation. Third, infrastructure modernization has made it possible for software providers to scale update delivery, telemetry, and secure data-handling pipelines more efficiently, though not without introducing new cost dimensions that must be managed carefully.
CTC and CTB Batteries for EV Market
Strategic readers will note that the forecast period is not a straight extrapolation. The growth path reflects recalibrations tied to product innovation cycles, competitive repositioning, and macroeconomic conditions that influence consumer and enterprise spending on maintenance software. A measured CAGR in this environment does not imply stagnation; it indicates a market that rewards disciplined execution, differentiated feature sets, and clear value propositions. Organizations that approach the market with a clear sense of where growth concentrates, what constitutes defensible differentiation, and how regulatory expectations are reshaping product design will be better positioned to capture share without overextending resources.
Refrigerated Container Adhesive Market
The Strategic Value of This Research for 2026 Decision-Making
Market intelligence becomes actionable only when it connects data to decision. This report is designed to do exactly that: it translates a broad market trajectory into operational guidance for executives, product leaders, and investment teams evaluating the PC system utilities space in 2026. The analysis is structured around the questions that matter most in this stage of the market lifecycle. Where is demand most resilient? Which product categories are gaining or losing momentum relative to user expectations? How do competitors structure their market presence, and where do gaps remain for new entrants or incumbents seeking to pivot? What external pressures—regulatory, infrastructural, and labor-related—are reshaping cost structures and speed-to-market? The answers are not superficial. They are embedded in a research architecture that ties historical performance to forward-looking scenarios, allowing decision-makers to test assumptions rather than rely on static narratives.
For companies planning product roadmaps, the research provides a lens on where utility features intersect with user behavior. For investors and strategic partners, it clarifies the boundaries of market concentration and the practical implications of operating in a space where a small group of players commands a substantial portion of total revenue. For organizations evaluating expansion into adjacent maintenance, optimization, or data-protection segments, the report frames the operational realities that define margin potential and execution risk. The report is not intended as a retrospective summary. It is a decision-support instrument built to help leadership teams convert market signals into prioritized actions, whether those actions involve feature prioritization, channel strategy, pricing architecture, or geographic sequencing.
Inside the Report: Frameworks, Dimensions, and Actionable Intelligence
The research is organized to support both high-level strategy and granular execution. It opens with a comprehensive market sizing exercise that anchors the narrative in verified historical data and extends into forecast modeling for the 2026 to 2032 window. From there, the analysis decomposes the market along multiple dimensions so that leadership can evaluate where value is created and how it flows through the ecosystem. Rather than presenting a single aggregated number and stopping, the report examines how different product categories, user segments, and regional dynamics interact to produce the overall trajectory. This layered approach matters because aggregate growth can obscure divergent sub-trends, and executives need to see beneath the surface to allocate resources intelligently.
A core feature of the research is its focus on product-category dynamics. System optimization remains a central pillar of the market, reflecting sustained demand for tools that improve responsiveness, clear unnecessary files, and streamline routine maintenance. Disk cleanup and data recovery also represent significant components of the landscape, while file management and other utility functions occupy more specialized but still relevant positions. The report evaluates how these categories differ in terms of user adoption patterns, feature expectations, and competitive intensity. It also addresses application-level segmentation, distinguishing between individual users, small and medium enterprises, and large enterprises. Each of these user groups presents distinct purchasing drivers, sensitivity to pricing, and requirements for integration and support. Individual users often prioritize ease of use and immediate perceived performance gains, while smaller enterprises look for cost-effective bundles and manageable deployment. Large enterprises, by contrast, tend to emphasize reliability, compliance alignment, and centralized management considerations. The report maps these differences without reducing them to oversimplified generalizations, enabling readers to identify which segments align with their strategic objectives.
Geographic coverage is equally deliberate. The market is analyzed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with attention to how regional conditions influence adoption, pricing tolerance, and competitive presence. Each region carries its own mix of user behavior, infrastructure maturity, and regulatory environment, and the report uses these distinctions to inform market-access strategies. Rather than treating geography as a static backdrop, the research examines how regional demand patterns evolve in response to product updates, ecosystem changes, and broader technology adoption trends. Executives can use this framing to evaluate where to prioritize go-to-market efforts, where localization matters most, and where the balance between opportunity and operational complexity tilts one way or the other.
Beyond segmentation, the report incorporates operational and structural considerations that directly affect competitiveness. It addresses the cost environment that software providers face, including the labor intensity of specialized development and ongoing maintenance work, as well as the infrastructure burden associated with cloud hosting for update servers and secure data storage. These factors are not peripheral; they shape margin envelopes, product-update cadence, and the ability to scale without compromising reliability. The research also discusses the evolving impact of data privacy and compliance expectations on product design and operational practice. As utilities increasingly interact with system files, user data, and scanning routines, the standards for secure handling and regulatory alignment become central to both reputation and market access. ISO 27001 and related data-protection frameworks are treated as practical reference points that influence how providers structure their workflows and customer commitments. The report weaves these elements into the broader market narrative so that decision-makers can evaluate opportunity in the context of the operational realities that determine long-term viability.
Competitive Dynamics and the Shifting Battleground
No market assessment is complete without a rigorous competitive read. The PC system utilities space is characterized by a concentration of players that have built recognizable brands around system cleaning, optimization, and maintenance. The analysis profiles the firms that define much of the current competitive tension, including iolo Technologies with System Mechanic, Glarysoft Ltd with Glary Utilities, IObit with Advanced SystemCare, Ashampoo GmbH with WinOptimizer Pro, WiseCleaner Technology Co., Ltd. with Wise Disk Cleaner and Wise Care 365, Piriform Software Ltd with CCleaner, and Avanquest Software with its PC tune-up and optimization offerings. These companies do not occupy identical positions in the market. Their product philosophies, feature scopes, and positioning strategies differ in ways that matter for both incumbents and new entrants. Some emphasize comprehensive optimization suites, while others lean into cleaner-focused experiences or integrate security-minded functions alongside maintenance tasks. The report examines these distinctions as strategic signals, showing how each player’s approach shapes customer perception, feature competition, and the boundaries of market share.
The Microsoft trajectory adds an important layer to the competitive picture. Recent update activity underscores how a platform-level player can influence expectations across the broader utilities ecosystem. In late 2025, a new version of Microsoft PC Manager was released with enhancements to storage cleanup and PC performance monitoring. A subsequent update in mid-2026 continued the rollout with improvements aimed at broader global deployment. This cadence matters because it signals renewed attention to native or platform-adjacent maintenance tools, which can shift user baselines and raise the bar for third-party offerings. The presence of an established platform player in this space does not automatically compress the market for independent utilities, but it does change the competitive context. Third-party providers must articulate clear and credible reasons for users to adopt their solutions beyond what is already available through default system tools. The research addresses this dynamic directly, focusing on how differentiation, trust, and functional depth become more important when baseline expectations rise.
Market concentration further sharpens the competitive read. The sector is not evenly distributed across all participants. A meaningful share of total revenue is accounted for by a small group of leading firms, and the cumulative footprint of the top players remains substantial. This concentration has strategic implications. It suggests that established positions are not easily displaced, that brand trust and installed-base momentum carry weight, and that differentiation must be both credible and sustained. At the same time, concentration does not imply stagnation. It often signals where innovation pressure is highest, because leaders must continuously defend their positions while challengers search for underserved needs or alternative bundling strategies. The report helps executives interpret these concentration patterns not as barriers alone, but as indicators of where value capture is occurring and where competitive openings may still exist for focused execution.
Structural Forces Reshaping the Market
Beyond competition and segmentation, the market is being shaped by operational realities that influence how utilities are built, delivered, and trusted. Data privacy and compliance requirements have become embedded in product design considerations rather than treated as afterthoughts. Utilities that perform system scans, handle user files, or interact with sensitive system areas must navigate expectations around secure handling and transparent data practices. This dynamic raises the stakes for product architecture and customer communication. Providers that treat compliance as integral to their offering can turn it into a trust advantage, while those that underestimate it may face friction in adoption or reputational exposure.
The labor dimension is equally important. Specialized software development and maintenance represent a core operational expense, and the talent required to build and sustain reliable optimization tools is not commoditized. This cost pressure influences release cycles, feature ambition, and the pace at which providers can respond to user feedback. In a market where perceived performance improvements and stability are central purchase drivers, development discipline matters as much as marketing reach. Infrastructure cost has a parallel effect. Cloud hosting for update servers and secure storage for user data adds another layer to the expense profile, particularly as providers scale and seek to maintain consistent delivery across regions. The report integrates these cost drivers into the analysis so that growth estimates are evaluated alongside the operational commitments required to support them. This makes the forecast more than a projection of revenue movement; it becomes a practical assessment of what it takes to sustain position in a competitive environment.
How to Use This Research in 2026 Planning
The most valuable research is the kind that changes how a team thinks before it changes what the team does. In 2026, leadership teams can use this report to test several strategic hypotheses at once. It can support decisions about whether to enter the market, deepen an existing presence, or reposition an existing offering against evolving user expectations. It can help product leaders identify which categories and user segments offer the best alignment with current capabilities and where the opportunity cost of broadening too quickly may be highest. It can guide commercial teams in evaluating pricing, bundling, and channel strategies against a competitive backdrop in which trust, clarity, and reliability are increasingly important purchase drivers. It can also support investor and partnership conversations by providing a structured view of market size, trajectory, concentration, and the operational pressures that influence margin and execution speed.
Crucially, the report is built to be referenced, not just read. Its segmentation detail, competitive profiles, and structural analysis are designed to feed directly into planning cycles, scenario testing, and investment prioritization. Executives do not need every underlying data point presented as a static table to benefit from the analysis. What matters is that the research preserves enough depth to support real decisions while remaining clear about where additional intelligence is needed. That is why this overview is deliberately framed as an entry point rather than a full disclosure. The complete dataset, scenario pathways, and granular segment readings are available in the full report, where teams can examine the numbers that matter most to their specific strategies.
What the Full Report Unlocks
This introduction provides the strategic context, the competitive logic, and the structural forces that define the PC System Utilities Software Market in 2026 and beyond. It establishes that the market is growing with discipline, that concentration shapes the competitive battleground, and that operational realities around compliance, development labor, and infrastructure are central to sustainable positioning. It also makes clear that the deeper the decision stakes, the more valuable the underlying detail becomes. The full research release goes further by offering target-segment readings, detailed category-level assessments, regional deployment considerations, and the specific competitive intelligence needed to move from directional confidence to precise execution. For organizations that intend to act on this market with seriousness, the complete report is where the analysis converts into operational advantage.
The PC system utilities market is no longer a space where generic features or broad promises are sufficient. It rewards clarity of purpose, credible differentiation, and disciplined execution. For decision-makers in 2026, the strategic task is to understand not only how large the market is or how fast it is likely to grow, but where value concentrates, how competitors defend their positions, and what operational commitments are required to compete effectively. This research is designed to help leaders answer those questions with confidence, and to lay the groundwork for decisions that are grounded in evidence rather than assumption.
For detailed analysis of this topic, please visit the official page: PC System Utilities Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


