



PW Consulting: Titanium Dental Implants to Top USD 750.3M by 2032 at 6.1% CAGR
By PW Consulting, 2026-07-23
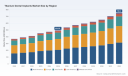
Titanium Dental Implants Market 2026 Briefing: Strategic Imperatives for Competitive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our Titanium Dental Implants Market study — a practitioner‑focused synthesis designed to inform capital allocation, product strategy, and commercial execution as companies plan for 2026. This briefing highlights the market’s directional dynamics, competitive architecture, and the operational levers that will determine winners over the next planning cycle. It intentionally demonstrates methodological depth while withholding the granular segment tables and region/application allocations — those detailed splits are available in the full report on our site for clients who require the raw inputs behind each recommendation.
Titanium Dental Implants Market
Why 2026 is a Pivotal Year
The titanium dental implants market entered 2026 with clear momentum. Between 2020 and 2025 the market expanded from roughly USD 370 million to just under USD 495 million, reflecting steady demand driven by demographic trends, greater adoption of immediate‑loading protocols, and wider penetration of digital workflows in restorative dentistry. Our base/focus year is 2025, and our forecast horizon spans 2026–2032. Over that forecast interval the market is projected to grow at a compound annual growth rate of 6.1% and reach approximately USD 750 million by 2032.
Titanium Dental Implants Market
For executives, these numbers matter because they frame three concurrent strategic imperatives: (1) scale and differentiation are both required — mid‑market players can win by adjacent specialization while larger players consolidate platform advantages; (2) technology and evidence are decisive — incremental improvements in surface treatments, connections, and immediate‑loading protocols translate into measurable commercial advantage; and (3) regulatory and reimbursement constraints remain a gating factor for adoption and route‑to‑market timing.
Titanium Dental Implants Market
What This Report Delivers — Practical, Transactional, and Tactical
- Market sizing and validated growth scenarios: an audit trail from historicals (2020–2025) to three upside/downside forecast cases (2026–2032) that support investment memos and board deliberations.
- Competitive playbooks: capability matrices for system providers, comparative product positioning, and customer decision criteria mapped to surgeon, prosthodontist and clinic procurement workflows.
- Regulatory and reimbursement checklists: pragmatic 510(k) submission pathways, ISO 13485/FDA 21 CFR 820 alignment items, and reimbursement sensitivity models tailored to major payer contexts (note: Original Medicare does not cover dental implants).
- Go‑to‑market blueprints: distribution channel economics, digital sales enablement, dentist training program templates, and KPIs to monitor clinical adoption and case conversion.
- Commercial modeling tools: price elasticity scenarios (including prevailing implant price ranges), margin waterfall analyses, and supplier concentration risk assessments for titanium feedstock and precision manufacturing.
- M&A and strategic partnership filters: target scores and integration considerations for bolt‑on technologies (surface treatments, digital abutments, guided surgery kits) that accelerate time to market.
- Operational execution guides: sterilization/packaging validation requirements (including accepted sterility assurance levels), manufacturing scale‑up checklists, and quality management system milestones for ISO/FDA compliance.
Competitive Landscape — Who’s Shaping the Market
The competitive architecture is a hybrid of global platform leaders and regionally strong specialists. Market concentration metrics indicate a meaningful degree of aggregation: the top three firms capture a substantial portion of revenue, and the top five approach two‑thirds of the market—conditions that favor differentiated clinical value or scale‑driven cost leadership for late entrants.
- Straumann Group (Switzerland): A platform player with a strong product portfolio — including titanium implants, TiZr alloys, and advanced surface treatments — that prioritizes clinical evidence, premium positioning, and integrated prosthetic solutions. Straumann’s investment in accelerated osseointegration technologies continues to create differentiation in tissue‑level and bone‑level use cases.
- Nobel Biocare (Switzerland): Known for TiUnite surfaces and system‑level solutions like All‑on‑4, Nobel’s emphasis on full‑arch restorations and high‑precision surgical workflows makes it a go‑to partner for clinics pursuing high‑value procedural mixes.
- ZimVie (United States): Focused on modularity and clinical versatility through portfolios like T3, TSX and short implant lines. Recent launches around modular surgical kits reflect a strategy to simplify clinical logistics and reduce procedural time, which aligns with immediate‑loading trends.
- Dentsply Sirona (United States): Combines implant platforms with strong digital integration across CAD/CAM workflows. Recent product catalog initiatives on digital channels signal an increasing emphasis on e‑commerce and clinician self‑service for product selection.
- BioHorizons (United States), MegaGen and Osstem (South Korea): These players compete effectively on thread design, connection geometry, and surface engineering. BioHorizons’ Laser‑Lok and conical connections emphasize aesthetic and immediate‑loading outcomes; MegaGen and Osstem capture share through innovation in primary stability and cost‑competitive execution.
- Hiossen, Surcam Dental, Acrotec Medtech: These firms either target immediate‑loading niches, supply OEM components, or focus on regulatory/compliance strengths (e.g., FDA 510(k), ISO 13485). Their strategic value is often unlocked via partnerships, white‑label supply, or regional distribution agreements.
Recent product developments underline the velocity of incremental innovation: catalogue and digital platform updates from Dentsply Sirona (2025), modular surgical kit introductions from ZimVie (early 2026), and scannable healing abutments from BioHorizons (mid‑2026). Each signals a push toward simplifying clinical workflows, enhancing digital connectivity, and shortening the evidence‑to‑adoption timeline.
Regulatory, Reimbursement and Operational Constraints
- Regulatory: Titanium dental implants remain subject to 510(k) clearance for U.S. marketing; manufacturers must maintain ISO 13485 quality systems and comply with FDA 21 CFR 820. These requirements create a predictable (but non‑trivial) compliance runway for new entrants and product modifications.
- Reimbursement: Public payer coverage is generally limited — for example, Original Medicare excludes dental implants — which preserves out‑of‑pocket and private payer dynamics as the primary pricing levers. This reality necessitates clinic‑level economics and patient financing strategies to unlock broader uptake.
- Materials and cost: Implant-level prices vary widely in the market, with typical ranges used as planning benchmarks. Titanium feedstock, manufacturing precision, and validated sterilization/packaging all materially affect unit economics, and supply chain disruptions can compress margins quickly.
- Sterilization & quality: The industry employs validated sterility assurance protocols aligned with ISO standards (e.g., ISO 11135) and expects sterile packaging at accepted SAL levels. These operational controls should be built into time‑to‑market assumptions and manufacturing CAPEX plans.
Strategic Recommendations for 2026 Planning
- Prioritize clinical pathway economics: Invest in solutions that demonstrably reduce chair time and conversion friction (guided surgery kits, scannable components, modular kits). Our scenarios show that improving case throughput by even single‑digit percentages materially increases surgeon adoption and lifts ASPs.
- Build evidence early and continuously: Allocate budget to multi‑center clinician studies that quantify healing time improvements and long‑term survival; these data accelerate premium positioning in private clinic networks.
- Lock in supply and scale selectively: Secure titanium and precision‑manufacturing capacity through multi‑year contracts or strategic JV models to avoid margin erosion from raw‑material volatility.
- Design channel models for patient financing: Given limited public reimbursement, commercial success will hinge on clinic‑level financing solutions and bundled pricing that make higher‑value procedures accessible.
- Consider M&A for capability gaps: Acquire or partner with firms that provide digital prosthetic workflows, surface‑treatment IP, or validated OEM supply to accelerate time to a differentiated system offering.
- Operationalize compliance: Make ISO 13485 and FDA quality artifacts first‑class deliverables within product development timelines to avoid launch delays; validate sterilization and packaging early in prototype phases.
How to Use This Briefing
This article is a strategic prelude. The full PW Consulting Titanium Dental Implants Market report provides the underlying datasets, segmented forecasts, and decision tools that procurement, product, and M&A teams will need during 2026 planning cycles. We intentionally kept region/application tables and granular share numbers out of this public briefing to preserve the analytical value of the complete dataset and drive targeted client engagement. If your 2026 capital plan, product roadmap, or market entry thesis depends on precise regional sizing, application mixes, or competitive unit economics, the full report supplies the verified inputs and downloadable models.
Contact PW Consulting to request a demonstration of the dataset, to run a custom scenario for your portfolio, or to commission a tailored due‑diligence package aligned to your strategic timetable. Our advisory team combines market modeling, regulatory navigation, and clinical adoption playbooks to convert the market momentum described here into measurable commercial outcomes.
— PW Consulting, Titanium Dental Implants Market Team
For detailed analysis of this topic, please visit the official page: Titanium Dental Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

Digital Printed Wallpaper Market — Strategic Briefing for 2026 Decision-Makers
As companies recalibrate portfolios for a post-pandemic, sustainability-driven interiors market, the digital printed wallpaper sector presents both a high-growth opportunity and a strategic puzzle. PW Consulting’s latest market study (base year 2025; forecast 2026–2032) synthesizes macro trajectories, technology inflection points, regulatory pressures, and supplier dynamics to help executives make commensurately bold, yet pragmatic, choices in 2026.
Digital Printed Wallpaper Market
Why this study matters in 2026
The digital printed wallpaper market is evolving from a niche designer segment into a mainstream channel bridging residential renovation, commercial fit-outs, and large-scale architectural projects. Our topline model shows the market expanding rapidly — from USD 9.1 Billion in 2025 to an anticipated USD 29.35 Billion by 2032 — driven by an 18.2% CAGR across the forecast period. That growth is not uniform: it is underpinned by distinct demand vectors (sustainability-focused procurement, on-demand production economics, and contract-grade specifications) and by discrete technology shifts that change unit economics and capital intensity for manufacturers and converters.
Digital Printed Wallpaper Market
For 2026, the strategic value of this report is twofold:
Digital Printed Wallpaper Market
- It provides board-level evidence to justify capital allocation to manufacturing modernization, strategic M&A, or channel reorientation.
- It supplies operational guidance (supply-chain design, SKU rationalization, pricing frameworks) that aligns short-run digital capability with long-horizon growth expectations.
What the research delivers — practical content overview
Beyond market forecasts and scenario analysis, the full PW Consulting report contains a suite of actionable modules crafted for decision-makers:
- Market sizing and demand-driver decompositions that link macro trends (remodeling cycles, green building mandates, hospitality reopening) to addressable revenue pools.
- Technology and unit-cost roadmaps comparing dry toner, aqueous pigment, and dye-sublimation processes — with capital cost, throughput, and substrate compatibility trade-offs.
- Go-to-market playbooks for three archetypes: legacy wallpaper manufacturers, digital-native on‑demand providers, and contract/interiors suppliers.
- Channel economics and margin models for retail, contract, and direct-to-consumer (D2C) routes, including pricing sensitivity analysis for textured and peel-and-stick formats.
- Supply‑chain resilience frameworks, with decision trees for reshoring, regionalization, and supplier partnerships to manage raw-material volatility and regulatory compliance.
- M&A and partnership targets mapped by capability (print capacity, substrate innovation, design platforms, AR/visualization tools), prioritized by strategic fit and integration risk.
- Scenario-based financial models and KPI dashboards executives can deploy immediately to stress-test investment cases under different demand and cost assumptions.
Note: The full report contains detailed segment-level tables, regional and application splits, and granular unit economics. This briefing intentionally omits those segment tables to protect strategic insights — access to the full dataset and Excel models is via the PW Consulting report portal.
Competitive landscape — who shapes the market and why it matters
The sector blends heritage décor brands, contract specialists, digital-native disruptors, and specialist printers. Market concentration remains relatively low: the top three firms account for roughly one-quarter of market sales, and the top five do not dominate to the extent seen in many industrial segments. That fragmentation creates opportunities for scale consolidation but also for differentiated niche plays.
- A.S. Création Tapeten AG (Germany) — A.S. Création’s emphasis on high-volume seasonal collections and non-woven substrates signals a hybrid strategy: retain cost advantages of scale while adopting digital runs for speed-to-market. Their seasonal releases are an early indicator that large-format digital production is being used to accelerate assortment refreshes rather than replace traditional print entirely.
- York Wallcoverings & Brewster Home Fashions (United States) — Both brands highlight the coexistence of heritage design and commercial-grade specifications. York’s contract certifications and Brewster’s textured/peel-and-stick offerings demonstrate how legacy players protect margins by entering higher-specification, higher-value segments.
- Graham & Brown, Vescom, Grandeco, Muraspec (UK/Belgium/Netherlands) — These firms illustrate two strategic threads: sustainability credentials and contract-grade customization. Partnerships with sustainability organizations and the integration of recycled substrates are evolving from marketing themes into procurement prerequisites for many institutional buyers.
- Spoonflower (United States) — Spoonflower’s print-on-demand model is a case study in platform economics, unlocking thousands of micro-designs from independent creators. It is particularly instructive for D2C strategies and long-tail SKU management.
- Luxury and design-led players (Sanderson Design Group, Osborne & Little) — These suppliers monetize brand and design scarcity, focusing on high-margin, low-volume business that is less price-sensitive but requires impeccable color fidelity and substrate quality.
Recent technology and deal activity — signals executives must decode
We’ve tracked several market-moving developments in 2025 that will materially impact 2026 decisions:
- New production technologies (e.g., dry toner systems) improve cost economics for short-to-medium runs, lowering break-even volumes for digital relative to analog production.
- Regional capacity expansions and acquisitions are accelerating, as firms secure scale and sustainability-compliant substrates through M&A.
- Cross-industry partnerships between printers and substrate manufacturers are reducing technical barriers to entry for peel-and-stick and recycled-content wallpapers.
- AR and visualization tools are proliferating among contract suppliers, shortening sales cycles and increasing conversion in specification-driven procurement.
These developments collectively lower operational barriers to on-demand production, increase the value of design platforms, and make sustainability integration a practical, not just reputational, requirement.
Regulatory and material dynamics — constraints that shape strategy
Three practical regulatory/material realities inform near-term choices:
- Regulatory pressure (e.g., chemical restrictions in major markets) is accelerating the adoption of water-based pigment inks — manufacturers that defer this transition risk market access and reformulation costs.
- Non-woven substrates are emerging as the pragmatic default for many applications due to dimensional stability and installation advantages; substrate partnerships therefore carry strategic importance.
- Sustainability mandates — and green-building influence over procurement — are turning recycled-content sourcing from a brand differentiator into a baseline capability for many contract bids.
What to do in 2026 — prioritized strategic actions
For leadership teams evaluating the space, we recommend a three-horizon action plan aligned to the 2026 decision calendar:
Immediate (0–90 days)
- Run an internal coste-to-serve and SKU profitability review focused on peel-and-stick, textured, and contract-grade SKUs to identify candidates for digital conversion.
- Audit chemical and substrate compliance against key markets’ regulatory regimes; prioritize conversion roadmaps for water-based pigment inks where exposure exists.
- Begin technical vendor due diligence for dry-toner and high-speed aqueous pigment equipment if intent on shortening lead times and reducing inventory.
Near term (3–12 months)
- Implement pilot on-demand product lines with integrated AR visualization to test customer willingness-to-pay and to de-risk platform investments.
- Pursue targeted partnerships or tuck-in acquisitions to secure recycled-content substrates and complementary digital print capacity.
- Redesign commercial contracts with major trade customers to reflect new lead-time and replenishment economics enabled by digital production.
Medium term (12–36 months)
- Decide on manufacturing footprint adjustments: selectively regionalize production to reduce logistics risk and meet sustainability criteria for large commercial accounts.
- Scale design platform and creator economy integrations (print-on-demand APIs, licensing deals) to broaden SKUs without inflating working capital.
- Formalize an M&A pipeline focused on substrate innovation, visualization technology, and production scale in target regions.
Conclusion — the strategic payoff
By 2032 the market size and growth trajectory make clear that digital printing will be central to wallpaper industry economics: it enables assortment agility, supports sustainability commitments, and unlocks new customer segments via customization and visualization. For 2026, the question is not whether to engage with digital printing, but how — and at what pace. Executives who combine selective capital investment in new printing technologies, strategic partnerships for substrate and sustainability compliance, and customer-facing digital tools (AR, D2C platforms) will convert today's market momentum into sustainable competitive advantage.
PW Consulting’s full Digital Printed Wallpaper Market report contains the underlying segment models, regional and application splits, and the financial templates required to run your organization’s decision scenarios. For access to the detailed datasets and an executive briefing tailored to your organization’s strategic priorities, please visit the PW Consulting report page or contact your engagement lead.
For detailed analysis of this topic, please visit the official page: Digital Printed Wallpaper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

Pyrometers Market 2026: Strategic Imperatives and Actionable Insights — A Preview from PW Consulting
As industrial operators, OEMs, and investors plan capital allocation for 2026, temperature sensing technology is quietly moving from a commodity instrument to a strategic asset. PW Consulting’s upcoming Pyrometers Market research (base year 2025, forecast period 2026–2032) synthesizes historical momentum, vendor dynamics, regulatory change, and technology pathways into an operational playbook for decision-makers. This preview demonstrates the report’s analytical depth while intentionally omitting detailed sub‑segment tables and granular regional splits — a deliberate “trailer” designed to validate our method and invite practitioners to the full study for proprietary segmentation and downloadable models.
Pyrometers Market
Market snapshot: scale, trend and outlook
The global pyrometers market stood at USD 1,735.0 Million in 2025, following a steady expansion from USD 1,350.0 Million in 2020. Our consolidated view anticipates market growth at a compound annual growth rate (CAGR) of approximately 5.16% across the 2026–2032 forecast window, with the total market approaching the mid‑segment of USD 2.4–2.5 Billion by the end of the period. That trajectory reflects a mix of steady replacement demand, incremental adoption of imaging and fiber‑optic solutions, and increasing service revenues tied to calibration and compliance.
Pyrometers Market
Why this research matters for 2026 decision cycles
- Capital allocation with confidence: Procurement and capex teams often face competing demands for limited budgets. Our report translates market growth and vendor economics into time‑phased replacement and upgrade scenarios, enabling CFOs to justify investments that optimize uptime and reduce lifecycle cost.
- Technology selection aligned with use cases: Advances in SWIR imaging, fiber optic pyrometry and Ethernet‑native sensors change the value equation for applications from metal heat treatment to continuous manufacturing lines. The report helps technical leaders match spectral, field‑of‑view and dynamic range choices to process risk profiles.
- Regulatory and compliance preparedness: SAE AMS 2750H (2024) and the rollout of updated training (e.g., Pyrometry II course releases) elevate both the technical and administrative requirements for thermal processing. Our compliance roadmap turns standards into procurement and maintenance actions that firms can implement before audits.
- Supply‑chain and cost risk mitigation: Raw‑material price volatility for thermocouple alloys and specialist optical components materially affects BOM economics. We model supplier risk scenarios and provide hedging and sourcing strategies customized for buyers and OEMs.
- Aftermarket and services as margin engines: Calibration, certification, and predictive maintenance derived from sensor telemetry are high‑value opportunities. The study quantifies potential service upsides and outlines go‑to‑market models.
What the PW Consulting report contains — practical outputs for 2026
This study is designed as a decision support toolkit as much as a market map. Key deliverables include:
Pyrometers Market
- Transparent market sizing and methodology (base year 2025) with historical performance (2020–2025) and scenario‑based forecasts for 2026–2032.
- Demand‑driver analysis that dissects industrial end uses, replacement cycles, and the impact of Industry 4.0 integration on sensor penetration.
- Comprehensive vendor landscaping and competitive scorecards covering capability, channel reach, innovation pipeline, warranty and aftermarket services.
- Procurement playbooks and RFP templates focused on spectral selection, environmental hardening, calibration expectations, and total cost of ownership models.
- Regulatory translation guides converting SAE and aerospace pyrometry requirements into practical test, inspection and calibration schedules.
- Scenario stress tests simulating raw material shocks, regulatory tightening, and accelerated imaging adoption — with quantified P&L impact for operators and OEM suppliers.
- Actionable M&A and partnership heatmaps identifying targets and capabilities that de‑risk market entry or accelerate product breadth.
- Downloadable Excel models: TCO calculators, replacement timing simulators, and supplier scorecards that can be adapted to buyer data.
Note: this preview highlights deliverables at a functional level. The full report contains granular regional and application splits, vendor share tables, and confidential appendices intended for licensed access.
Competitive landscape: who matters and why
The pyrometers market exhibits moderate concentration: the top three vendors account for roughly one‑third of global share, and the top five approach the mid‑50s percentile of market control. That structure creates a market in which global leaders set technical expectations and a strong group of specialist vendors compete on niche performance, integration and service.
- AMETEK Land (UK) — A global heavyweight in metal and foundry temperature measurement. The firm’s depth in high‑temperature process instrumentation and strong trade‑show presence signal an ongoing focus on scale and channel penetration into heavy industry.
- Fluke Process Instruments (US) — Known for rugged spot pyrometers and hardening‑grade solutions that address extreme temperatures. Their product set appeals to heavy industry customers who prioritize reliability in the harshest environments.
- DIAS International (Germany) — A technology‑driven player expanding its PYROSPOT portfolio into fiber‑optic devices and shortwave thermal imaging. Recent catalog releases demonstrate a clear push into higher value imaging and fiber‑delivered sensing.
- Sensortherm & Optris (Germany) — Both firms compete on digital integration, compact platforms and modular spectral options. Optris’ Ethernet‑ready designs and Sensortherm’s calibration offerings speak to automation customers and recurring revenue models.
- Advanced Energy & Williamson IR (US) — High‑temperature specialists whose products address demanding metallurgy and ceramic processes; Advanced Energy’s radiation pyrometers and Williamson’s dual‑wavelength capabilities are differentiators for precision control.
- Specialists: Himmelwerk, Keller Pyrometer Systems, Micro‑Epsilon — These vendors focus on inductive heating integration, precision optical measurement and automation‑grade sensors respectively. They are well‑positioned for niche use‑cases and OEM partnerships.
Recent competitive moves corroborate the innovation trend: DIAS released fiber optic and SWIR‑capable devices in 2025 and rolled out new thermal imaging platforms earlier the same year; AMETEK Land increased its international visibility through major industry events in 2025. These product and marketing actions are early signals of an industry shifting toward sensor fusion and imaging‑based process control.
Industry context and headwinds
- Regulation and training: SAE AMS 2750H (2024) raises the technical bar for thermal processing equipment. Organizations that fail to align calibration procedures and documentation risk audit exposure. The updated Pyrometry II training for 2025 means competency requirements will rise in tandem with equipment sophistication.
- Raw‑material volatility: Thermocouple alloys and specialty optical coatings expose manufacturers to input price swings. Optical pyrometers typically command significantly higher average selling prices than simple thermocouples, amplifying margin sensitivity to COGS pressure.
- Technology acceleration: The migration from spot pyrometers to imaging and fiber‑optic platforms unlocks new process control strategies but increases supplier lock‑in and integration complexity.
Strategic plays for executives in 2026
- For industrial buyers: Prioritize integrated proof‑of‑concept deployments that combine calibrated pyrometry, analytics, and maintenance contracts. Use our TCO models to compare ASP against lifetime calibration and downtime costs.
- For OEMs and system integrators: Secure strategic partnerships with imaging and fiber‑optic specialists to broaden solution portfolios without long product development cycles. Embed calibration and traceability services into base contracts to capture aftermarket margins.
- For component suppliers: Focus R&D on spectral flexibility and compact Ethernet interfaces that lower system integration friction. Establish multi‑tier sourcing strategies for critical alloys to mitigate price spikes.
- For investors and M&A teams: Target bolt‑ons that extend spectral coverage, add calibration lab footprints, or provide access to underserved verticals (e.g., aerospace thermal processing tied to AMS2750H compliance).
How PW Consulting’s report accelerates execution
Our full study is built to be operational from week one. Licensed clients receive: the full market model with regional and application detail, vendor scorecards with capability matrices, downloadable procurement templates and calibration schedules, and scenario simulators that quantify regulatory and commodity shocks. In short, we translate market intelligence into executable actions for procurement cycles, product roadmaps and M&A diligence.
This preview demonstrates the report’s analytical depth and strategic orientation. For the detailed segmentation tables, vendor financial proxies, and the downloadable TCO and RFP tools that enable direct application to your 2026 planning, access the full Pyrometers Market report through PW Consulting’s client portal.
Next steps
- Contact PW Consulting for a briefing that aligns the report’s scenarios to your plant portfolios and procurement timelines.
- Request a tailored calibration roadmap that maps AMS2750H requirements to your current sensor estate and replacement schedule.
- Engage our M&A desk for a confidential heatmap of adjacency targets prioritized by time‑to‑integration and aftermarket margin accretion.
Temperature measurement is no longer an ancillary input; it is a measurable driver of throughput, quality and regulatory compliance. In 2026, leaders will separate themselves by choosing sensing strategies that convert thermal visibility into competitive advantage. PW Consulting’s Pyrometers Market report provides the data, the scenarios, and the practical templates to do exactly that.
For detailed analysis of this topic, please visit the official page: Pyrometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Time Delay Relays Market to Reach USD 1,036.08M by 2032 at 5.78% CAGR
By PW Consulting, 2026-07-23

Time Delay Relays Market — Strategic Imperatives for 2026
Executive snapshot
As industrial ecosystems accelerate automation and reliability requirements, the Time Delay Relays market is evolving from a niche electromechanical component marketplace into a strategic supply chain and product-architecture frontier. Our PW Consulting market model — built on a 2025 base-year data set and a 2020–2025 historical series — places global revenue at approximately USD 699.14 Million in 2025. Under our central forecast, the market expands at a compounded annual growth rate (CAGR) of 5.78% through the 2026–2032 horizon, reaching in excess of USD 1,036 Million by 2032. Market concentration is meaningful: the three largest players account for a majority share (CR3 ~55%), and the top five together hold roughly two-thirds of the market (CR5 ~68%).
Time Delay Relays Market
This briefing is a “trailer” for our full Time Delay Relays Market study: it synthesizes the strategic implications you need to act in 2026 while intentionally withholding granular segment tables, region-by-region percentages, and line-item financials — data that are available in the full report and supporting workbooks on our source page.
Time Delay Relays Market
Why this matters for 2026 decision-makers
- Procurement & sourcing: With steady mid-single-digit CAGR and clustered supplier power, procurement levers and dual-sourcing strategies become decisive to managing price and lead-time volatility.
- Product strategy: The shift from traditional electromechanical timers toward solid‑state and digitally controlled timing functions is changing product lifecycles, warranty economics, and service models.
- Supply chain resilience: Regional manufacturing footprints and local qualification cycles (including military and nuclear standards) are now part of go/no-go supplier evaluations.
- Aftermarket & services: Reliability improvements in solid‑state units lengthen replacement cycles but create premium aftermarket services and retrofit markets for mixed-technology installed bases.
- Regulatory & standards compliance: Military, industrial-safety, and nuclear qualifiers create premium niches that demand specialized manufacturing and certification roadmaps.
Market dynamics you need to internalize
Three structural dynamics underpin the growth and strategic choices in 2026:
Time Delay Relays Market
- Technology substitution and reliability economics — Solid‑state and microcontroller-enabled relays are reducing failure modes associated with shock, vibration, and humidity, and in some supplier claims can extend operational life by orders of magnitude compared to mechanical counterparts. This trend forces OEMs and systems integrators to reassess total cost of ownership and spares stocking logic.
- Standards-driven premium niches — Certifications (for example, military series qualifications and hermetic sealing for high-assurance sectors) create differentiated value pools. Suppliers that invest in these credentials command higher margins and longer sales cycles tied to capital projects and regulated procures.
- Geopolitics and manufacturing footprint — Recent capacity expansions in Asia by major suppliers reflect a pragmatic response to supply-chain risk and regional demand growth. Firms that lock in regional manufacturing and redundancy will be advantaged in lead-time-sensitive verticals.
What our report delivers (practical, executable content)
The full PW Consulting Time Delay Relays Market report is designed to be a working tool for commercial, product, and supply‑chain teams. Key deliverables include:
- Market sizing and validated forecast model (2020–2032) with scenario toggles for demand shocks, technology adoption curves, and regional growth elasticities.
- Vendor benchmarking templates and scorecards (technical breadth, certifications, lead time, price banding, product roadmaps) for the major OEMs and emerging players.
- Supply‑chain heatmaps and sourcing playbooks that translate risk into tactical actions (dual‑sourcing, consignment, strategic inventory, co‑located assembly).
- Go‑to‑market playbooks for product managers (modularity, firmware upgrade paths, retrofit kits, aftermarket subscriptions) and an ROI calculator for capex choices.
- M&A and partnership pipeline analysis, including candidate profiles for bolt‑on acquisitions in geographically strategic markets or technology niches.
- Regulatory readiness checklists (military, nuclear, sector-specific) and a certification timeline planner to de‑risk bids on regulated projects.
Note: this synopsis intentionally omits the segment-level tables and split-by-region/application/type matrices that appear in the gated dataset available on our site.
Competitive landscape — focused implications for 2026
The market structure features a small set of global leaders and a diverse tier of regional specialists. Each archetype offers a different strategic pathway:
- TE Connectivity (Schaffhausen, Switzerland) — TE positions itself across mid- and high-assurance segments with both commercial mid‑range and hermetically sealed military-qualified relays. Its recent capacity expansion in Asia (mid‑2025 and early‑2026 updates) signals a deliberate push to shorten lead times and capture regional project flows. Strategic implication: partnering or qualifying TE as a preferred supplier is attractive where certified, high‑reliability products or hermetic variants are required.
- Littelfuse (Chicago, USA) — Known for solid‑state and microcontroller-based single‑function timers, Littelfuse emphasizes repeat accuracy and long lifecycle components. Their product profile suits customers seeking lower maintenance and longer MTBF. Strategic implication: assess lifecycle-cost tradeoffs and warranty exposures when substituting mechanical with solid‑state devices.
- Omron (Kyoto, Japan) — Omron’s analog and digital H3 series remain standard-fit in many automation stacks. Their strength is integration with broader control ecosystems. Strategic implication: Omron is a natural partner for systems integration strategies tied to PLC-driven automation roadmaps.
- Finder (Milan, Italy) — Modular European designs and strong channel relationships make Finder relevant for panel builders and distribution-led channels. Strategic implication: leverage Finder for standardized industrial panels in EMEA where design conformity is important.
- Eaton (Dublin, Ireland) — Eaton offers NEMA-standard relays and positions in power-control applications. Strategic implication: consider Eaton for power-system-integrated timing solutions where compliance to electrical codes and ruggedness is prioritized.
- Siemens (Munich, Germany) — Siemens integrates timer relays into high-end automation solutions; the value is system-level integration and lifecycle service. Strategic implication: Siemens should be evaluated when timing functions are part of a broader automation buy and when long-term service packages matter.
- Macromatic, GEYA, CHINT, Shenler (regional specialists) — These firms supply flexible form factors, cost-competitive units, and localized support in their respective geographies. Strategic implication: regional players are attractive for cost-sensitive builds or when local certification and fast replacement are priorities.
Actionable strategic moves for 2026
Based on our data and supplier analysis, we recommend a prioritized set of moves for any industrial OEM, system integrator, or distributor engaging the time‑delay relay market in 2026:
- Implement a dual-sourcing strategy that pairs a certified global vendor (for regulated/high‑assurance projects) with a qualified regional supplier (for volume and service agility).
- Invest in a modular relay architecture roadmap that allows swap-in of solid‑state timing modules to capture reliability and digitalization benefits while protecting installed-base revenue from mechanical-to-solid transitions.
- Qualify suppliers’ certification credentials early in project cycles — MIL and hermetic qualifications materially extend lead times and require upfront R&D and testing budgets.
- Negotiate long‑lead contracts that include capacity commitments or priority allocation clauses with leading suppliers that have expanded regional manufacturing (notably in Asia), converting supply-chain risk into negotiated service levels.
- Monetize aftermarket services: develop retrofit kits, predictive maintenance offerings, and extended warranty options that convert extended MTBF into annuity revenue despite slower replacement cycles.
- Model M&A or minority investments into regional specialists to secure local production and fast-track entry into crowded verticals without incurring full capex of greenfield sites.
How to use the full PW Consulting dataset
Our full report and downloadable models are designed to be used directly in procurement negotiations, product roadmap planning, and M&A diligence. They include dynamic scenario models, supplier scorecards, and an annotated supplier map showing capacity, certification scope, and recent investments.
For readers of this briefing: we intentionally withheld the granular regional, application, and type-level revenue splits, and we have redacted underlying tables that show pricing tiers and contract terms. These elements are available in the gated deliverable and are essential if you are planning sourcing commitments, production footprint changes, or acquisition screening in 2026.
Final thought
The Time Delay Relays market in 2026 is no longer just a component market; it is a battleground for supply-chain resilience, certification-led premium positioning, and technology-enabled lifecycle economics. The numbers — from roughly USD 528 Million in 2020 to about USD 699 Million in 2025, and a projected run to above USD 1,036 Million by 2032 at a 5.78% CAGR — underscore a steady, investible growth path. What distinguishes winners will be their ability to pair technical qualification with nimble sourcing and a services-led aftermarket strategy. For the full, exportable datasets, scenario models, and vendor scorecards you need to operationalize these insights, access the complete PW Consulting Time Delay Relays Market report on our source page.
For detailed analysis of this topic, please visit the official page: Time Delay Relays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hexamethylene Diisocyanate Market to Reach USD 277.5 Million by 2032 (5.2% CAGR)
By PW Consulting, 2026-07-23
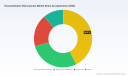
Hexamethylene Diisocyanate (HDI) Market: Strategic Insights for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused briefing that translates complex market signals into actionable strategy for executives making critical decisions in 2026. This preview synthesizes our comprehensive Hexamethylene Diisocyanate (HDI) Market study (base year 2025) to highlight the strategic inflection points, competitive moves, and operational risks that will determine winners and laggards through the 2026–2032 forecast window.
Hexamethylene Diisocyanate Market
Market trajectory at a glance
HDI has demonstrated steady expansion through the 2020–2025 period, rising from an estimated USD 153.2 Million in 2020 to USD 194.8 Million in 2025. Our forecast projects the market to continue growing at a compound annual growth rate (CAGR) of 5.2% for the 2026–2032 period, reaching approximately USD 277.5 Million by 2032. This trajectory is not uniform: growth is being driven by differentiated demand pockets (high-performance coatings, specialty adhesives and select elastomer blends) while simultaneously being constrained by feedstock availability, regulation, and episodic logistics disruptions.
Hexamethylene Diisocyanate Market
Why this matters for 2026 decision-makers
- Investment timing: A mid-single-digit CAGR signals a durable market, but the next wave of returns will accrue to companies that align capacity, feedstock procurement, and product differentiation before 2028.
- Risk calibration: Supply-side volatility and regulatory tightening mean conventional volume plays will face margin compression unless offset by supply integration or premium product slating.
- M&A and partnership opportunities: Market concentration is high—top-tier players control the majority of available supply—so selective acquisitions or JV structures can be a fast route to strategic scale, but diligence must integrate feedstock and regulatory scenarios.
Key market dynamics reshaping strategy
The HDI ecosystem in 2025–2026 is evolving under several interlocking dynamics. Understanding these forces is essential for supply chain, commercial, and capital-allocation decisions.
Hexamethylene Diisocyanate Market
- Feedstock volatility: Hexamethylene diamine (HMD) availability is the single-largest upstream risk driver. In early 2026, Chinese domestic quotes tightened materially, and European markets experienced shortages tied to broader energy and logistics constraints. These swings feed directly into production economics and price pass-through timelines for HDI producers.
- Regulatory pressure: REACH enforcement in Europe and upgraded workplace safety standards have raised manufacturing cost baselines and restricted certain processes. Producers without compliance-ready assets face higher barrier-to-exit costs; conversely, compliant producers can command premium positioning for regulated end-markets.
- Logistics fragility: Port congestion and transport delays in H1 2025 resulted in transient price dislocations and highlighted the risks of single-origin procurement strategies. Companies that have diversified transit routes or localized buffer inventories navigated the period with fewer margin shocks.
- Demand-side pull: Automotive refinish, durable industrial and architectural coatings continue to favor HDI’s aliphatic, non-yellowing attributes. When automotive OEM cycles accelerate, HDI prices can respond sharply in short windows—illustrated by pronounced price upticks in North America during strong automotive demand periods.
Competitive landscape — consolidation, capability and strategic positioning
The current market is characterized by a tightly concentrated supply base. The implication is straightforward: moves by a leading producer (capacity additions, acquisitions, or pricing) materially shift market balance and commercial bargaining power.
- Covestro AG (Leverkusen, Germany) — A technology-forward producer with gas-phase HDI capability. Recent strategic actions include capacity expansion at Leverkusen and the acquisition of two independent HDI facilities from a competitor, which materially increases their adaptable supply footprint across Europe, North America, and Asia. For buyers, Covestro’s moves translate into a stronger ability to influence contract terms and lead-time expectations.
- Vencorex Holding SAS (Cognac, France) — Historically significant supplier and derivative innovator. The divestment of certain assets reduced direct production exposure while enabling a sharper focus on higher-margin derivatives. This reshapes the competitive map and creates acquisition opportunities for players seeking rapid scale.
- BASF SE (Ludwigshafen, Germany) — A diversified chemical player with integration advantages. BASF’s presence ensures continuity for large, multi-national customers seeking integrated supply chains and global service footprints.
- Asahi Kasei Performance Chemicals & Tosoh Corporation (Tokyo, Japan) — Japanese manufacturers remain important suppliers to high-performance coatings markets, particularly where non-yellowing characteristics are valued. Recent commercial actions by one supplier (a material price increase announced in 2026) signal a willingness to recalibrate pricing to reflect tighter upstream economics.
- Wanhua Chemical (Yantai, China) — Aggressive capacity expansion in China highlights a strategic play to capture growing local automotive and construction coatings demand and to export into regional markets. The timing of these projects matters for margin cycles and regional competitiveness.
- Evonik Industries & Huntsman Corporation — Both maintain specialty portfolios that serve niche coatings and adhesives requirements; their product engineering capabilities are attractive for OEMs with demanding performance specs.
Collectively, the supplier moves of 2024–2026 (capacity builds, asset acquisitions, and targeted price adjustments) have shifted the balance toward a more integrated and concentrated producer set. For buyers, this means counterparty risk needs to be modeled explicitly; for producers, it means the path to premiumisation is via regulatory-proof production and downstream technical partnerships.
What our full report delivers (practical, decision-ready content)
PW Consulting’s full HDI Market study is structured to convert insight into action. Highlights of the deliverables include:
- Granular market sizing and a validated 2020–2032 time series with scenario overlays for feedstock and regulatory shocks.
- Risk-adjusted NPV and IRR models for greenfield and brownfield HDI projects, including sensitivity to HMD price, utilities, and capex phasing.
- Supplier scorecards and procurement negotiation playbooks that incorporate supply concentration, lead-time variability, and regulatory-compliance credentials.
- Commercial playbooks for premium product launches (formulation targeting, channel segmentation, and OEM qualification timelines).
- M&A and JV due-diligence templates focused on feedstock security, environmental liabilities, and integration synergies.
- Operational readiness checklists: REACH compliance mapping, workplace safety upgrades, and contingency logistics planning.
- Tailored scenario planning: rapid-demand ramp, prolonged feedstock squeeze, and high-regulation pathways — each layered with recommended tactical responses for producers and buyers.
We intentionally present analytical frameworks and executable templates rather than raw segment-by-segment revenue breakdowns in this briefing. The full report contains the detailed segmentation, supplier benchmarking matrices, and numerical sensitivity tables that underpin the strategic recommendations summarized here.
Concrete strategic actions for 2026
For senior leaders seeking priority actions this year, our analysis recommends the following focused moves:
- Producers with growth ambitions — Prioritize feedstock integration (long-term HMD offtakes or upstream partnerships) and accelerate regulatory-compliance investments. Consider bolt-on acquisitions only where they deliver immediate feedstock or geographic arbitrage.
- Procurement and downstream consumers — Rebuild multi-source supply strategies, introduce contract flexibility clauses for regulatory or feedstock-driven price shifts, and qualify alternate chemistries for non-critical applications to reduce exposure.
- Private equity and corporate development — Target targets with compliant assets in legal jurisdictions that reduce regulatory drag, and price in the operational cost of tightened REACH-like regimes when modeling returns.
- R&D and product teams — Invest in formulations that maximize HDI’s performance advantage (non-yellowing, weather resistance) and accelerate co-development agreements with coating OEMs to secure adoption pipelines.
- Supply chain and operations — Build tactical inventory buffers at nodal distribution points and diversify shipping corridors to mitigate episodic port congestion impacts.
Closing — strategic framing for 2026 and beyond
The HDI market is entering a phase where structural growth is real, but prize capture will depend on strategic clarity. The market’s mid-single-digit CAGR masks important asymmetries: producers who solve feedstock and compliance constraints will compound margins, while buyers that secure diversified, compliant supply and convert HDI attributes into differentiated end-product value will protect margins in a tighter environment.
This brief conveys the directional intelligence PW Consulting uses to inform client decisions. For executives preparing capex approvals, procurement renegotiations, or M&A plays in 2026, the detailed segmentation data, supplier-level financials, and scenario-specific valuation models in our full report are essential. Access to those datasets and the tailored strategy templates is available through the PW Consulting report page — the full study includes the numerical breakouts and actionable appendices referenced in this preview.
For detailed analysis of this topic, please visit the official page: Hexamethylene Diisocyanate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Salon Software Market to Reach USD 468.4M by 2032, Growing at 10.5% CAGR - PW Consulting
By PW Consulting, 2026-07-23
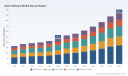
Salon Software Market 2026: Strategic Signals for Leaders — A PW Consulting Preview
Executive snapshot
As salons and wellness providers accelerate digital adoption, the global salon software market has moved from early adoption into a phase of steady commercialisation and consolidation. Using 2025 as the base year, PW Consulting’s market model places global industry revenue at USD 233.5 Million in 2025 and projects a compound annual growth rate (CAGR) of 10.5% through the 2026–2032 forecast window. By 2032 the market is expected to nearly double relative to 2025 levels, reflecting persistent demand for appointment management, payments, client lifecycle tools and embedded marketplace discovery.
Salon Software Market
Historic performance underpins the outlook: between 2020 and 2025 the market expanded from the low‑hundreds to today’s base, demonstrating both resilient demand among independent providers and growing spend by multi‑location operators. That trajectory — faster SaaS adoption, richer platform capabilities, and renewed M&A activity — shapes a strategic agenda for 2026 decisions.
Salon Software Market
Why this research matters for 2026 decision cycles
-
Investment prioritisation: The market’s mid‑teens structural growth dynamics mean limited capital should be directed to features and channels that accelerate stickiness (client retention, automated rebooking, recurring revenue) rather than one‑off acquisition incentives.
Salon Software Market -
M&A and partnership timing: Consolidation is both a risk and an opportunity. Players looking to scale quickly should decide between organic product investment and targeted tuck‑ins that unlock marketplace demand or geographic distribution.
-
Product roadmaps: The fastest path to ROI in 2026 will be modular platform strategies — core booking + payments + client CRM — augmented by optional AI and analytics components sold as premium layers.
-
Regulatory compliance as market entry barrier: Changes in EU/UK data regimes will reshape product design and cross‑border expansion playbooks; compliance is a commercial advantage for platforms that can guarantee simple, auditable controls for SMB customers.
Market dynamics and key themes
-
Cloud first, but nuance matters: Cloud‑based SaaS remains the dominant architectural choice for new deployments, offering faster onboarding and centralized updates. However, product differentiation now comes from integration depth (POS, inventory, payroll) and vertical tailoring for multi‑unit vs. solo operators.
-
Marketplace and discovery economics: Platforms that combine booking with discovery and marketplace features capture higher lifetime value by reducing client acquisition costs for salons. Operators should assess the trade‑off between taking marketplace fees and driving organic bookings through salon marketing.
-
AI and automation adoption: Early deployments (concierge assistants, automated client outreach, dynamic scheduling) improve utilization and client retention, but they require robust training data and privacy‑first design to earn salon trust.
-
Fragmented competitive landscape: The market remains moderately fragmented; the largest vendors account for roughly a quarter to a third of global vendor revenues, with a long tail of regionally focused specialists and point solutions. That structure favors both vertical consolidation and continued niche innovation.
-
Regulatory and privacy headwinds: Recent regulatory shifts — notably EU proposals that introduce SMB exemptions and the UK Data (Use and Access) Act adjustments — lower some compliance friction for basic scheduling use‑cases but increase scrutiny on transparency and cross‑border data disclosures. Platforms must balance simplified compliance flows for low‑risk SMBs with the transparency required under evolving EU/UK enforcement practices.
Competitive landscape — strategic positions and implications
The vendor universe ranges from single‑practitioner solutions to enterprise suites. Understanding each player’s strategic move helps buyers and investors prioritise partnerships and targets.
-
Vagaro (United States, https://www.vagaro.com) — A cloud‑first player focused on beauty and wellness professionals. Recent M&A and partnership activity (notably an acquisition in early 2025 and a major partnership in 2026) signals an aggressive scale strategy combining product breadth with distribution via salon networks. Strategic implication: attractive partner for channel expansion but expect integration complexity post‑deal.
-
Booksy (Poland, https://biz.booksy.com) — Strong in appointment management with integrated payments and CRM. Booksy’s core strength lies in mobile‑first workflows and a broad SMB footprint; it remains an acquisition target or regional consolidator.
-
Fresha (United Kingdom, https://www.fresha.com) — Emphasises a marketplace model with discovery at its core. Fresha is a bellwether for platforms that monetise through client leads rather than pure subscription fees.
-
Phorest (Ireland, https://www.phorest.com) — Differentiates through inventory, payroll and retention tools for both independent and multi‑location salons. Its positioning is compelling for operators seeking an integrated back‑office experience.
-
Mindbody (United States, https://www.mindbodyonline.com) — Historically a wellness heavyweight. The sector’s recent aggregation into larger wellness operating systems (notably a March 2026 merger activity) redefines competitive dynamics for traditional full‑suite providers and creates new scale economies for marketing and distribution.
-
GlossGenius (United States, https://glossgenius.com) — Targets solo stylists with an elegant UX and simple monetisation. Its success highlights the premium clients place on ease of use for micro‑businesses.
-
Mangomint (United States, https://www.mangomint.com) — Focuses on multi‑location operations; recent product launches enhance omnichannel client communication. Tactical implication: feature parity with enterprise suites but with lower total cost to small chains.
-
Boulevard (United States, https://www.boulevard.co) — Positions itself as a premium client experience platform, attractive to higher‑end salons and medical‑aesthetic operators requiring enterprise‑grade controls.
-
Zenoti (United States, https://www.zenoti.com) — Enterprise‑oriented with AI concierge and advanced marketing automation. Zenoti represents the upper bound of capability for multi‑unit operators willing to pay for deeper analytics and automation.
-
Acuity Scheduling (United States, https://www.acuityscheduling.com) — Favoured by small to medium salons for scheduling simplicity and payment integration; its lightweight model underscores opportunities for channel integrations and white‑label partnerships.
Recent moves to watch (signal map)
-
Consolidation acceleration: A notable merger in early 2026 combined several wellness brands into a larger operating system, shifting distribution and marketing dynamics across the market.
-
Buy‑side playbooks: Larger vendors continue to acquire point solutions (scheduling, payments, discovery engines) to accelerate cross‑sell — a pattern that will drive valuation premia for targeted tuck‑ins.
-
Feature competition: New communication and AI features launched across vendors prioritise client engagement and automation, raising the bar for product roadmaps in 2026.
What the PW Consulting report delivers (practical, decision‑ready content)
Our full report is structured to convert insight into action. Highlights include:
-
A transparent market model (base year 2025) with historical calibration and scenario forecasts to 2032, including high/central/low cases that quantify revenue sensitivity to adoption rates, pricing changes and consolidation.
-
Buyer and use‑case segmentation that maps willingness to pay, feature elasticity, and churn risk for solo practitioners, multi‑location chains and enterprise wellness operators — presented as decision matrices and actionable personas.
-
Vendor benchmark and capability matrix: feature, pricing, integration maturity and partner ecosystems — scored against PW Consulting’s GTM readiness framework.
-
M&A heatmap and target shortlist methodology: identification criteria, valuation multiples observed in the market, and playbooks for integration that preserve retention and accelerate cross‑sell.
-
Compliance & privacy checklist tailored for EU/UK/US cross‑border operations, with pragmatic controls that reduce implementation friction for SMB customers while meeting higher‑risk enterprise needs.
-
Product and monetisation blueprints: suggested bundles, premium feature ladders, and channel incentive structures designed to lift average revenue per customer without increasing churn.
-
An 18–24 month roadmap for executives: prioritised investments, quick wins, and a test‑and‑learn plan for AI pilots and marketplace rollouts.
Action recommendations for 2026
-
Prioritise modular SaaS investments that derive revenue from recurring services (retention tools, loyalty, automated marketing) rather than one‑off integrations.
-
Use M&A to fill distribution gaps or acquire discovery channels, not just product parity. The best targets accelerate customer acquisition or deliver high margins on cross‑sell.
-
Design privacy‑first AI pilots: start with opt‑in concierge features that demonstrably increase bookings; measure lift before full roll‑out and document consent flows to preempt regulatory scrutiny.
-
Lock in channel partners (salon groups, franchise systems, payment providers) early — strategic distribution wins in 2026 translate to durable market share by 2028.
-
Request vendor scorecards and scenario outputs from advisors. Key inputs you should demand: granular segmentation by deployment type, detailed vendor capability scores and the underlying assumptions driving the 2032 upside case.
Next steps — why access the full report
This preview highlights the strategic contours and the most consequential moves shaping the salon software market in 2026. The full PW Consulting report contains the granular modelling, vendor scorecards and playbooks executives need to translate growth forecasts into executable plans. If you are allocating product, partnership or M&A capital in 2026, the detailed scenarios and acquisition readiness checklists in our report will materially shorten your decision cycle and reduce execution risk.
For access to the complete dataset, vendor scorecards and our full set of recommendations — including downloadable models and an interactive decision matrix — please consult the full Salon Software Market report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Salon Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coastal Surveillance Market to Reach USD 1,200 Million by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-23

Coastal Surveillance Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our forthcoming Coastal Surveillance Market study. This briefing synthesizes the structural forces, competitive dynamics, technology inflection points, and procurement signals that will shape coastal surveillance strategy in 2026 and beyond. It deliberately demonstrates analytical depth while withholding the granular segmentation tables and proprietary models reserved for the full report—consider this a high-fidelity trailer designed to orient senior leaders, procurement leads, and investors toward the critical decisions they must make in the year ahead.
Coastal Surveillance Market
Market at a Glance: Macro Trajectory and What It Means
The coastal surveillance market has recorded steady expansion through the first half of the decade, growing from roughly USD 580 million in 2020 to an estimated USD 780 million by the 2025 base year. With a compound annual growth rate (CAGR) of approximately 6.8% over our forecast horizon, our model projects the market will approach roughly USD 1.2 billion by 2032. This trajectory reflects a combination of technology refresh cycles, expanded maritime domain awareness (MDA) requirements, and a steady replacement/modernization demand across naval, coast guard, and civil maritime operators.
Coastal Surveillance Market
For decision-makers, that macro outlook carries three implications:
Coastal Surveillance Market
- Scale of Opportunity: Growth is consistent and broad-based enough to justify multi-year capital allocations and strategic partnerships, but not so concentrated as to guarantee quick market domination for new entrants.
- Timing of Spend: The middle of this decade is dominated by refresh and integration projects—meaning procurement windows are being defined now for installations and upgrades in 2026–2028.
- Value Capture: With market concentration relatively low at the top (our concentration metrics indicate a fragmented landscape), opportunities exist for differentiated offerings—especially those that lower life‑cycle costs or accelerate operational integration.
Structural Drivers and Strategic Risks
Multiple forces are reshaping coastal surveillance procurement and capability design:
- Technology Integration: Buyers increasingly demand sensor-agnostic, AI-enabled command-and-control stacks that fuse radar, electro-optical/infrared (EO/IR), and non-traditional sources (e.g., AIS, satellite) into an operational picture usable at sea and ashore.
- Spectrum and Sensing Evolution: National plans and spectrum strategies continue to signal investments in wide-area HF surface-wave radars and complementary shore-based coherent systems to extend detection envelopes beyond traditional line-of-sight gaps.
- Regulatory and Security Constraints: Tightening national security controls over critical communications and surveillance supply chains—most notably restrictions on specific foreign equipment classes—are increasing supplier due diligence and reshoring incentives in procurement specifications.
- Infrastructure Burdens: Many coastal operators face aging shore infrastructure. Modern sensor deployments are conditional on port, pier, and station upgrades, which often require parallel capital programs and influence total cost of ownership and deployment timelines.
Where Value Will Aggregate
Not all capabilities are equal in terms of strategic value. PW Consulting’s scenario work suggests three domains where buyers and suppliers can capture disproportionate value:
- AI-Driven Analytics & Automation: Systems that materially reduce operator cognitive load and false-alarm rates accelerate operational adoption and reduce manpower costs—key levers for budget-constrained maritime agencies.
- Modular, Open Architectures: Platforms enabling incremental sensor upgrades and third-party app integration extend platform lifespans and create recurring revenue opportunities through software and services.
- Integrated Procurement Solutions: Suppliers that bundle hardware, system integration, training, and lifecycle support—especially those able to manage shore infrastructure complexity—are more likely to win long-term frameworks.
Competitive Landscape: Who’s Leading the Conversations
The market remains fragmented with a mix of global prime contractors, specialist radar manufacturers, and niche integrators. The top-tier participants bring complementary strengths:
- Thales Group (France) — Market-leading systems integrator recognized for modular AI-powered coastal solutions that combine radar, EO/IR, and command systems to provide extended monitoring from shore to open sea. Their recent product rollout underscores a strategic push into integrated AI-enabled offers.
- Raytheon Technologies (United States) — Emphasizing maritime domain awareness suites with AI analytics targeted at naval and coast guard customers. Their product suite evolution points to stronger analytics and platform integration capabilities.
- Lockheed Martin (United States) — Focused on sensor integration platforms and defense-grade system architectures, with an emphasis on scale and interoperability with naval assets.
- L3Harris Technologies (United States) — Concentrated on coastal radar solutions and deployments optimized for port, harbor, and maritime security missions, with recent government acquisition activity reinforcing their market role.
- HENSOLDT (Germany) — Noted for coherent shore-based radar technologies and national-scale monitoring solutions; their product line is tailored toward high-performance shore installations.
- Terma (Denmark) — Specialist radar supplier with a strong record in national coastal projects and recent contract wins that reflect demand for sovereign-capable solutions.
- Forward Slope, Inc. (United States) — Turnkey integrator focusing on ruggedized coastal deployments and complete command-center projects for border and coastal security.
- IEC Infrared Systems (United States) — Niche provider of multispectral integrated surveillance systems combining thermal, visual, and radar technologies for harbor and offshore monitoring.
Our competitive mapping indicates a clear bifurcation: primes and large integrators compete on scale, systems interoperability, and lifecycle support; mid-sized and specialist firms compete on niche sensing performance, rapid deployability, and cost-effectiveness. The top-three market share concentration remains modest—indicating a healthy competitive environment for differentiated entrants.
Recent Market Signals (Highlights)
- Several suppliers have announced product suites or capability upgrades in the past 12–18 months that accelerate AI/automation, sensor fusion, and shore-to-sea monitoring.
- Contract awards and national procurements emphasize modularity and sovereign supply chain assurances—favoring vendors capable of local integration or partnership models.
- Policy and spectrum guidance from national authorities continues to prioritize wide-area sensing approaches, reinforcing multi-sensor architectures rather than single-technology strategies.
What the Report Contains: Operational Intelligence You Can Use
Our full Coastal Surveillance Market report is structured to be immediately operational for procurement and strategy teams. Key deliverables include:
- Market sizing and a validated growth model from 2020 through 2032, with scenario sensitivities and pivot points mapped to procurement cycles.
- A technology roadmap describing radar families, EO/IR developments, AI analytics, and networked command-and-control architectures—highlighting upgrade paths and obsolescence windows.
- Practical procurement playbooks and decision trees for system selection, including integration risk matrices and life‑cycle cost assumptions.
- Supplier dossiers and competitive scorecards—evaluating technical fit, delivery risk, supply-chain exposure, and post‑sales support capability.
- Case studies and deployment blueprints illustrating common implementation traps and mitigation measures for shore infrastructure dependencies.
- Contract and pricing archetypes, procurement timelines, and negotiation levers commonly observed across recent national and commercial tenders.
Strategic Recommendations for 2026 Decision-Makers
For public agencies and private operators setting 2026 priorities, PW Consulting recommends a three-track approach:
- Adopt a modular procurement posture. Prioritize open standards, modular sensor bays, and plug-and-play analytics to preserve competitive upgrade options.
- Invest in analytics-first capability. Funding that shifts a modest portion from hardware to software and integration yields outsized operational returns through reduced false alarms and improved detection timelines.
- Mitigate supply‑chain and infrastructure risk. Insist on transparent supplier provenance, local integration pathways, and concurrent shore-infrastructure planning to avoid deployment schedule slippage.
Why This Matters Now
Three concurrent trends compress decision timelines in 2026: the consolidation of AI analytics into operational C2 centers; national security-driven procurement constraints that reshape supplier eligibility; and a wave of mid-decade modernization programs tied to shore-infrastructure upgrades. Taken together, these forces create a narrow window where procurement design choices—architecture, supplier selection, and contract structure—will determine operational capability and cost profiles for a decade.
Next Steps & How to Access the Full Study
This preview outlines the strategic contours of a market that is growing predictably yet evolving in complexity. For program managers, investors, and C-suite strategists who require the detailed segmentation, supplier scorecards, procurement templates, and full scenario model that underpin these findings, the complete Coastal Surveillance Market report provides the actionable intelligence needed to finalize budgets and supplier strategies for 2026 and beyond.
Contact PW Consulting to schedule a briefing and obtain access to the full report, including downloadable datasets, supplier risk matrices, and a customizable procurement playbook.
For detailed analysis of this topic, please visit the official page: Coastal Surveillance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gel Permeation Chromatography (GPC) Market to grow at 7.32% CAGR
By PW Consulting, 2026-07-23

Gel Permeation Chromatography (GPC) Market — Strategic Preview for 2026 Decisions
Introduction: why this preview matters
As companies position for growth and resilience in 2026, understanding the trajectory and structural dynamics of the Gel Permeation Chromatography (GPC) market is a strategic imperative. This preview synthesizes the high‑value, decision‑relevant signals from our full PW Consulting study to help executive teams prioritize investments, calibrate risk, and shape go‑to‑market plays. Consistent with our “trailer” approach, we demonstrate methodological rigor and directional insight while intentionally withholding granular sub‑segment figures to encourage access to the full report for transactional and tactical execution.
Gel Permeation Chromatography (GPC) Market
Market snapshot: headline metrics and trend drivers
GPC has moved from a specialized analytical technique to an essential enabler across polymers, biopharmaceuticals, and advanced materials. On a macro basis, the market shows steady expansion: using 2025 as the base year, PW Consulting models a multi‑year upward trajectory through 2032, with a compound annual growth rate (CAGR) of approximately 7.32% across the 2026–2032 forecast window. In absolute terms, the market size rose meaningfully through the first half of the decade and is forecast to surpass key milestones by the end of the outlook period—reflecting continued end‑market demand, instrument upgrades, and higher recurring consumables and services spend.
Gel Permeation Chromatography (GPC) Market
Market concentration is material but not insurmountable: the top three vendors account for a majority share of industry revenue, and the top five widen that control meaningfully. This structure creates both stability and tactical space for specialist vendors and new entrants to carve profitable niches via innovation, service differentiation, and targeted channel plays.
Gel Permeation Chromatography (GPC) Market
Why PW Consulting’s 2026 intelligence changes decisions
- Capital allocation with horizon clarity. The forecast and scenario modules allow CFOs and business unit leaders to phase capital investments—instrument upgrades, factory capacity, and R&D—aligned to expected adoption cycles rather than one‑off competitive pressure.
- Product portfolio strategy. Our analysis prioritizes which instrument characteristics (e.g., high‑temperature capability, multi‑detector integration, automation and QC workflows) will drive purchasing decisions in the near term, helping product teams prioritize roadmaps and resource allocation.
- Supply‑chain risk mitigation. The dynamics model quantifies exposure to sensitive inputs and offers hedging and procurement strategies to absorb raw‑material inflation shocks without eroding margins.
- Go‑to‑market and channel optimization. Sales and marketing leaders can use the buyer journey mapping and personas to refine segmentation and to size serviceable opportunities for consumables, maintenance, and software subscriptions.
- M&A and partnership playbook. With mid‑market consolidators and specialist technology providers active, the report outlines value creation levers for bolt‑on acquisitions and OEM supply agreements.
Report contents: what the full study delivers
The full PW Consulting GPC study is structured to be immediately operational for strategy teams. Key components include:
- Methodology and data provenance: transparent modelling approach, primary interview matrix, and reconciled historical series (base year 2025).
- Market sizing and forecast (2026–2032): a base case with upside/downside scenarios and sensitivity to raw material and regulatory shocks.
- Technology and product taxonomy: detailed coverage of system architectures, detector suites, columns, software, and consumables, with adoption curves for emerging variants (e.g., high‑temperature GPC, integrated GPC‑IR solutions).
- Pricing and cost stacks: ASP dynamics, recurring revenue streams (consumables, service), and margin archetypes for OEMs vs. aftermarket specialists.
- Commercial playbooks: buyer personas, tender dynamics in large labs, channel economics, and service bundle templates for faster payback.
- Competitive intelligence: vendor profiles, portfolio comparisons, capability heatmaps, and a transaction pipeline tracking recent launches, acquisitions, and product roadmaps.
- Risk register and regulatory watch: scenario planning for solvent availability/pricing and compliance drivers influencing instrument adoption.
- Practical appendices: RFP templates, model inputs for bespoke forecast runs, and interview excerpts from leading end‑users and OEMs.
Competitive landscape: strategic positions and watch‑items
The GPC vendor ecosystem combines global instrument majors with specialized technology houses. Our review concentrates on the strategic posture of the core players covered in the study and what their moves mean for partners and competitors in 2026.
- Agilent Technologies (Santa Clara, CA): Offers integrated GPC/SEC systems, detectors, columns, and analytics software—strengthened by prior acquisitions that broadened polymer standards and column portfolios. Strategic play: leverage broad installed base to cross‑sell software and consumables; watch for software‑as‑service monetization and deeper vertical integration into lab workflows.
- Waters Corporation (Milford, MA): Focused on high‑resolution polymer chromatography and advanced APC systems. Strategic play: differentiate on analytical performance and instrument reliability for high‑value polymer and pharmaceutical customers; monitor pricing discipline in high‑end segments.
- Tosoh Corporation (Tokyo): Known for robust EcoSEC systems, including high‑temperature options. Strategic play: compete on ruggedness and throughput for industrial polymer labs; tactical partnerships with regional service providers can expand aftermarket capture.
- Polymer Char (Valencia): Specialist in high‑temperature GPC and targeted polyolefin solutions; recent launches (full automation and a dedicated dRI detector) reflect a strategy to own niche polyolefin workflows. Strategic play: incumbents should assess technology licensing, while potential partners should evaluate complementary automation and IR capabilities.
- Testa Analytical Solutions (Epsom): Focused on high‑performance detectors and viscometers, with OEM supply relationships. Strategic play: detector specialization creates opportunities for co‑development with system integrators and for premium aftermarket revenues.
- Shimadzu Corporation (Kyoto): Provides Nexera series instruments and dedicated columns; strength in instrument reliability and channel support. Strategic play: leverage strong service networks in APAC and instrument reliability narratives to defend and expand share.
- Malvern Panalytical (Malvern): Offers multi‑detector GPC/SEC packages with a reputation in polymer metrology. Strategic play: continue bundling measurement services and software analytics to capture longer‑tail services revenue.
Implication: incumbents with comprehensive portfolios can monetize multiple revenue streams (instruments, consumables, service, software), but the market remains fertile for focused players that bring technological differentiation—especially in high‑temperature, automation, and detector innovation.
Market dynamics and near‑term shocks to monitor
Three interlocking dynamics are shaping supplier economics and buyer behavior into 2026:
- Raw material volatility (mobile phase solvents). Tetrahydrofuran (THF) price movements have been notable: producers announced step‑up price actions in 2025 and early 2026, even as market stabilization later in 2025 led to regional price declines. For instrument makers and labs, solvent cost variability impacts operating margins and total cost of ownership assessments; it also incentivizes solvent‑efficient methods and supplier consolidation for procurement leverage.
- Regulatory tightening and method standardization. Updates to pharmacopeial monographs are increasing the importance of validated GPC methods for specific excipients and products. Buyers in regulated industries will prioritize vendors that can provide validated workflows, documentation, and support for method transfer—driving demand for end‑to‑end solutions.
- Product innovation and aftermarket monetization. Recent product launches—automated QC‑focused systems and novel detectors—underscore a shift toward workflow automation and higher‑value instrument bundles. The resulting aftermarket potential (consumables, columns, service contracts, calibration standards) will account for an increasing portion of vendor revenue over the next three to five years.
Actionable strategies for 2026
Executives should translate the forecast and dynamics into concrete moves now:
- Hedge and diversify solvent sourcing. Procurement teams should build multi‑source contracts, index clauses, and forward coverage for critical solvents to protect lab operating margins.
- Prioritize validated workflows for regulated customers. R&D and quality teams must invest in method validation templates and documentation packages that reduce customer adoption friction—this is a fast path to share gains in regulated segments.
- Invest selectively in automation and detector partnerships. Product leaders should accelerate integration with high‑value detectors (IR, viscometry, triple‑detector arrays) and consider OEM alliances or co‑development to expand addressable use cases.
- Design service and consumable bundles. Commercial teams should test subscription‑style offers (instrument + consumables + calibration + remote diagnostics) to increase customer lifetime value and smooth revenue volatility.
- Prepare M&A and alliance playbooks. With a concentrated vendor landscape, identify complementary targets (detectors, software analytics, automation) and prepare standardized diligence templates to move quickly on opportunistic acquisitions.
How to use the full PW Consulting study
Consider this preview a concise strategic map: it identifies the high‑leverage decisions and the risks that will matter in 2026. The full study supplies the empirical backbone—granular segmentations, regional and application splits, vendor benchmarking matrices, and downloadable models—to operationalize the recommendations above. Those granular data elements (including detailed sub‑segment revenue and share breakdowns) are deliberately reserved for the full report so that pricing, channel and M&A execution are informed by validated, proprietary inputs.
Closing: preparing to act with confidence
The GPC market in 2026 will reward companies that combine technical differentiation, disciplined commercial execution, and proactive supply‑chain and regulatory risk management. PW Consulting’s full study equips leaders with the data, scenarios, and playbooks necessary to convert market growth into sustained, profitable share. To unlock the detailed segment maps, vendor scorecards, and customizable forecast model that power tactical execution, request the full report or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Gel Permeation Chromatography (GPC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


