



Crude Heparin Market: How 7.47% CAGR and Surgical Demand Reshape Industry Profits
By PW Consulting, 2026-09-21
Navigating the Crude Heparin Market: Strategic Trends and Commercial Opportunities (2026–2032)
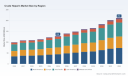
The global crude heparin market has entered a period of measured but steady expansion, with revenue projected to climb from 128.0 million USD in 2025 to 212.0 million USD by 2032, sustained by a compound annual growth rate of 7.47 percent. This trajectory reflects a market that is simultaneously maturing and reconfiguring. Demand anchored in cardiovascular applications and surgical procedures continues to provide a reliable base, while supply-side dynamics, regulatory scrutiny, and geographic rebalancing introduce new layers of complexity. For executives, investors, and procurement leaders, the central question is no longer whether the market will grow, but how participants can position themselves to capture value amid shifting competitive and compliance landscapes.
Market Snapshot and Structural Realities
The current market size of 128.0 million USD in 2025 represents more than incremental growth; it signals a market that has absorbed years of consolidation, quality standardization, and regional capacity adjustments. Over the historical window from 2020 through 2025, revenue moved from 100.0 million USD to its present level, reflecting resilience despite periodic supply interruptions and evolving regulatory expectations. Looking ahead, the forecast window from 2026 through 2032 points toward a consistent upward path, with annual figures crossing 140.32 million USD in 2026 and reaching 212.0 million USD in 2032.
A defining structural feature of this market is its fragmentation. The top three players account for roughly 24.5 percent of revenue, and the top five capture approximately 29.8 percent. Such concentration levels indicate that no single entity dominates the value chain outright, leaving room for regional specialists, vertically integrated producers, and downstream consumers to exert meaningful influence. This fragmented structure also means that differentiation tends to emerge through operational reliability, traceability credentials, and the ability to meet stringent quality requirements rather than through sheer scale alone.
Beyond the headline numbers, the market is navigating a series of inflection points. First, geographic demand is increasingly dispersed, with multiple regions contributing materially to overall volume and revenue. This dispersion complicates supply planning but also creates opportunities for producers with flexible sourcing and multi-region distribution capabilities. Second, the raw material base remains heavily tied to porcine intestinal mucosa, which continues to dominate global crude heparin output because of its high yield and comparatively lower disease transmission risk. That dependence creates efficiency advantages but also exposes the market to animal health disruptions that can ripple through supply availability. Third, the interplay between volume growth and regulatory stringency is tightening. Compliance is no longer a back-office function; it has become a commercial differentiator that influences procurement decisions, partnership formation, and market access.
For decision-makers, these structural realities translate into a simple imperative: growth will accrue to participants who can align capacity, quality assurance, and geographic agility while maintaining cost discipline. Operators and buyers alike need to treat crude heparin not as a commodity input but as a strategically managed resource with compliance, continuity, and traceability as core value drivers.
Key Drivers Shaping the Market
Several interlocking forces are propelling the crude heparin market forward while simultaneously reshaping how participants compete.
- Technological innovation and manufacturing precision are raising the bar for quality and consistency. Advances in extraction, purification, and analytical verification are helping producers standardize output across batches, reduce variability, and support downstream conversion into active pharmaceutical ingredients and low molecular weight heparin. These improvements matter because reproducibility directly affects supplier qualification, regulatory confidence, and ultimately commercial reliability.
- Regulatory and policy dynamics are redefining acceptable sourcing and documentation practices. Recent updates to heparin importation rules require specific analytical data, including species origin and contaminant testing for every shipment of crude heparin. Alongside this, active guidance on monitoring crude heparin for oversulfated chondroitin sulfate and ruminant material contaminants has reinforced the need for mandatory supplier qualification and lot testing. The practical effect is clear: documentation, traceability, and analytical rigor now function as market entry requirements rather than supplementary best practices.
- Demand-side behavior is becoming more risk-aware and procurement-disciplined. Cardiovascular applications remain a substantial and steady anchor for consumption, while surgical procedures provide additional procedural demand. At the same time, procurement teams are increasingly prioritizing supply continuity, validated quality records, and multi-source resilience over spot pricing alone. This shift is encouraging longer-term supplier relationships and more rigorous qualification processes.
- Supply chain and cost structures are being tested by animal health dynamics and regional capacity conditions. Industry reporting has highlighted ongoing outbreaks affecting a significant share of the global crude heparin supply associated with Chinese production, underscoring how animal disease can create bottlenecks and prompt buyers to diversify sourcing. At the same time, producers with vertically coordinated operations and established traceability are better positioned to absorb volatility and maintain reliable delivery.
These drivers are not operating in isolation. Innovation improves the ability to meet regulatory expectations; regulation raises the value of traceable sourcing; demand-side caution rewards continuity; and supply-side risks make diversification and integrated operations more commercially attractive. The net result is a market in which reliability and transparency are becoming as important as volume and price.
Competitive Landscape and Leading Strategies
The competitive field is defined by players with distinct strategic stances, each aligning capabilities to different parts of the value chain. Understanding these positions makes it easier to anticipate where partnerships, capacity investments, and procurement decisions are likely to flow.
Strategic Positioning of Key Players
Bioiberica has built a reputation around heparin molecule production, commercialization, and research, with an international footprint spanning multiple production sites. Its emphasis on pharmaceutical-grade crude porcine heparin for active pharmaceutical ingredients and low molecular weight heparin reflects a strategy oriented toward quality consistency and lifecycle engagement with the molecule. Participation in major industry events to mark corporate milestones and unveil refreshed branding suggests an ongoing effort to reinforce visibility and credibility within the pharmaceutical supply community.
Darling Ingredients, through its heparin operations, has focused on fully traceable crude porcine heparin extracted from hydrolyzed mucosa for pharmaceutical use as starting material for active pharmaceutical ingredients and low molecular weight heparin. Traceability is not merely a compliance checkbox here; it functions as a strategic asset that supports qualification, risk management, and buyer confidence. The company’s emphasis on profitable growth through strategic planning, including discussions of its heparin operations at investor events, signals an intent to treat heparin as a value-creating segment within a broader ingredients portfolio rather than a standalone volume play.
Shenzhen Hepalink operates as a multinational pharmaceutical company with a clear focus on heparin sodium active pharmaceutical ingredient and enoxaparin sodium active pharmaceutical ingredient production from crude sources. Its continued emphasis on these product lines through interim reporting indicates a strategy anchored in downstream conversion and product-level execution. By concentrating on active pharmaceutical ingredients, the company aligns itself with the value-added stages of the chain, where differentiation often depends on process control, regulatory standing, and consistent supply to formulation and finished-product markets.
Heparin Market
Hebei Changshan Biochemical Pharmaceutical specializes in research, development, production, and sales of heparin sodium active pharmaceutical ingredient and low molecular weight heparin, with a complete industrial chain extending from crude heparin products. Vertical integration across the chain can provide advantages in cost management, quality oversight, and responsiveness to demand fluctuations. Inclusion in recognized stock exchange indices has also drawn attention to the company, illustrating how market recognition and financial visibility can complement operational strategy in a fragmented competitive field.
Sanofi represents a different role in the landscape as a major consumer of crude heparin for low molecular weight heparin production, notably within its Clexane franchise and broader anticoagulant portfolio. For large downstream users, the crude heparin market is less about producing the molecule and more about securing dependable inputs that support branded and portfolio-level commercial commitments. This consumer-side perspective matters because major buyers can influence supplier qualification standards, specification expectations, and long-term supply commitments.
How the Landscape Is Evolving
The market is undergoing a nuanced evolution rather than a simple consolidation wave. On one hand, traceability, documentation maturity, and quality assurance are raising barriers for suppliers that cannot meet increasingly rigorous expectations. On the other hand, the relatively modest concentration levels leave space for regional specialists and integrated players to compete on operational excellence rather than market dominance alone. This environment favors strategies that combine reliable capacity, regulatory readiness, and transparent sourcing. It also creates openings for partnership models in which producers and downstream users align on qualification, continuity, and product-specific requirements.
PW Consulting
For investors and executives, the practical takeaway is that competitive advantage in this market is increasingly multidimensional. Scale matters, but so do traceability systems, animal-health risk management, analytical compliance, and the ability to serve downstream conversion with consistency. Companies that can demonstrate these attributes are better positioned to secure long-term relationships and withstand disruption.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape how value is created and captured in the crude heparin market.
- Regulatory and quality requirements will continue to deepen as standard practice. Importation rules requiring species-origin and contaminant data, together with ongoing guidance on oversulfated chondroitin sulfate and ruminant contaminant monitoring, point toward a future in which analytical documentation is integrated into commercial workflows rather than treated as a periodic checkpoint. Producers and suppliers that can deliver standardized, verifiable data with each shipment will strengthen their qualification standing and reduce friction in procurement cycles.
- Geographic diversification and supply resilience will become more prominent in sourcing strategies. Animal health disruptions affecting a large share of supply associated with Chinese production have reinforced the importance of not concentrating sourcing too narrowly. Over the forecast period, buyers and producers alike are likely to place greater value on multi-region capability, flexible logistics, and contingency planning. This trend favors operators with diversified sourcing, transparent traceability, and the ability to maintain continuity when regional conditions shift.
- Downstream alignment and product-focused value creation will gain importance. Because cardiovascular applications and surgical procedures provide a durable demand base, participants that connect crude heparin supply more tightly to downstream active pharmaceutical ingredient and low molecular weight heparin production can capture more stable demand relationships. Vertical integration, long-term supply agreements, and product-specific quality alignment are likely to be rewarded as buyers seek to reduce variability and protect continuity for essential anticoagulants.
These trends create commercial opportunities for operators that can combine reliable production with compliance maturity and geographic flexibility. There is also opportunity in supplier qualification services, documentation systems, and analytical capabilities that help market participants demonstrate species origin, contaminant controls, and lot-level consistency. For downstream consumers, the opportunity lies in building qualified multi-source networks that reduce concentration risk without sacrificing quality or cost efficiency.
Risks and Uncertainties to Monitor
Despite the constructive growth path, several uncertainties warrant attention. Animal health events remain a persistent risk factor because of the market’s reliance on porcine intestinal mucosa. Regulatory expectations can evolve further, increasing documentation and testing burdens or adjusting qualification requirements. Concentration risk persists where sourcing is overly narrow, while over-diversification without strong quality assurance can introduce new variability. Currency and cost dynamics, regional capacity adjustments, and the pace of downstream demand growth can also influence margins and availability. Participants should treat these factors as variables to manage actively rather than external conditions to simply accept.
Strategic Actions for Decision-Makers
The current market environment rewards deliberate, differentiated action rather than passive participation. The right moves depend on a company’s position in the value chain, but several priorities apply broadly.
- For manufacturers and producers, investment in traceability, analytical documentation, and multi-region sourcing flexibility should be treated as core commercial capabilities. Aligning production with verifiable species-origin data, contaminant testing, and lot-level quality records can strengthen supplier qualification outcomes and improve resilience during regulatory or supply disruptions. Where feasible, vertical coordination or strategic partnerships that link crude heparin output to downstream active pharmaceutical ingredient and low molecular weight heparin needs can create more stable demand relationships and reduce exposure to spot-market volatility.
- For investors, the market’s fragmented structure and moderately concentrated leadership field suggest that value can be created through operational differentiation, compliance maturity, and disciplined growth planning rather than through scale alone. Emphasis on companies with transparent traceability, validated quality systems, and credible strategies for managing animal-health and supply continuity risks may align with the market’s evolving requirements. At the same time, monitoring how major downstream consumers structure sourcing and qualification can provide early signals about where supply relationships are heading.
- For procurement and supply chain leaders, the priority is to balance cost, continuity, and compliance in a way that reflects the market’s risk profile. Qualifying multiple suppliers, verifying documentation standards, and building contingency plans around animal-health and regulatory developments can reduce exposure to disruption. It is also important to treat supplier qualification as an ongoing process, given that importation rules and guidance on contaminants continue to shape acceptable sourcing practices. Long-term partnerships with suppliers that can demonstrate consistent analytical data and reliable delivery may offer more commercial stability than short-term price optimization alone.
Across these roles, the common thread is that crude heparin is increasingly evaluated through a lens that combines quality assurance, traceability, and continuity with traditional commercial considerations. Companies that internalize this lens are better positioned to navigate the forecast growth path from 128.0 million USD in 2025 toward 212.0 million USD by 2032 while managing the operational and regulatory risks that accompany it.
For decision-makers seeking a more detailed view of regional and application-level dynamics, sourcing patterns, and company-specific strategic paths, the full PW Consulting research report provides deeper segment data and tailored recommendations. It is designed to support scenario planning, supplier evaluation, and investment prioritization with the granularity required for operational and strategic decisions.
Heparin Sodium Market
For detailed analysis of this topic, please visit the official page: Crude Heparin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flat Glass Market 2026: Why the 6.5% CAGR Trajectory Changes Everything
By PW Consulting, 2026-09-21
The Flat Glass Market: Strategic Trends and Commercial Opportunities Through 2032
The global flat glass market approaches a defining decade. From a base near 143 billion USD in 2020, the sector expanded steadily to approximately 187 billion USD by 2025, reflecting a trajectory shaped by architectural modernisation, vehicle lightweighting, and the rapid scaling of solar deployments. Forward projections indicate continued growth through the late 2020s, with the market anticipated to reach around 292 billion USD by 2032, supported by a compound annual growth rate of roughly 6.5 percent. This trajectory is not uniform across segments or geographies, nor is it insulated from supply-side volatility and regulatory pressure. For executives planning capacity, sourcing, or capital allocation, the flat glass sector demands a nuanced reading of where structural demand is concentrating, where cost and compliance pressures are intensifying, and which competitive moves are likely to separate durable players from cyclical participants.
Market Snapshots and the Core Tensions Defining the Next Cycle
The headline growth figures mask a more complex reality. Revenue expansion is being driven disproportionately by building envelope upgrades, transportation performance standards, and photovoltaic panel build-outs, yet these same applications intersect with raw material cost variability, energy input exposure, and evolving quality expectations. The market sits at an inflection point where volume growth and value creation are increasingly decoupled: producers that deploy higher-performing, lower-carbon, or application-specific products are capturing margins that commodity-grade lines cannot easily replicate. At the same time, regional demand patterns remain uneven, with some mature markets prioritising replacement and efficiency retrofits while emerging regions accelerate first-build construction and infrastructure.
Three tensions deserve executive attention. First, energy and input cost volatility continues to complicate planning for soda-ash, natural gas, and specialty silica variants, creating margin risk for producers reliant on energy-intensive float lines and for fabricators balancing throughput against unit economics. Second, regulatory and certification frameworks are tightening around optical quality, dimensional tolerances, and safety glazing requirements, raising the bar for thin glass adoption in multi-pane insulated units and for new product claims in building envelopes. Third, the sector’s competitive fabric is undergoing subtle re-sorting, as leading groups reposition around low-carbon production, high-performance coatings, and integrated application portfolios, while regional players and new entrants test niches where volume scale is less decisive than specification capability. Collectively, these dynamics mean that growth alone is no longer a reliable proxy for strategic success; the composition of that growth matters just as much.
The Drivers Reshaping Demand, Cost, and Competitive Value
Technology and Product Differentiation as Margin Engines
Innovation in flat glass is increasingly oriented toward performance attributes that translate directly into end-use value: thermal efficiency, optical clarity, strength-to-weight ratios, and compatibility with advanced building or vehicle assemblies. Float glass remains the volume backbone, but the commercial premium is migrating toward processed and coated variants that meet stricter insulation, daylighting, and safety expectations. Thin and ultra-thin formats are expanding the design envelope for architects and automotive engineers, though their adoption paths are tempered by tempering constraints and certification hurdles in certain multi-pane configurations. For specialty segments, high-transmission and precision-controlled products are opening doors in solar and high-performance construction applications where incremental efficiency gains translate into measurable lifecycle benefits. The strategic implication is clear: differentiation is shifting from pure volume production to specification-driven offerings that can be validated against application-specific standards.
Regulatory and Standards Pressure as a Filter and a Tailwind
Policy and standardisation activity is functioning as both a constraint and an accelerant. Building energy efficiency mandates and sustainability reporting expectations are pushing developers and manufacturers toward lower-embodied-carbon materials and verifiable performance claims. At the same time, technical standards are codifying expectations for dimensional consistency, optical quality, and visual uniformity in building-applied float glass, raising the baseline for acceptable supply. In North America, safety glazing certification continues to influence product choices in insulated glazing units, particularly where thinner configurations encounter tempering or structural acceptance limits. On the low-carbon side, several producers are advancing lines and declarations that reduce embodied carbon intensity, which aligns with procurement requirements in highly regulated markets and supports premium positioning where green credentials are scrutinised. The net effect is a market where compliance capacity and transparent performance data are becoming prerequisites for accessing the most demanding segments.
Float Glass Market
Demand-Side Shifts Toward Efficiency, Durability, and Application-Specific Formats
Demand is being reshaped by decisions at the building, vehicle, and energy-system levels. In construction, the emphasis is moving beyond basic transparency toward envelopes that manage heat transfer, solar gain, and acoustic performance while meeting aesthetic and structural goals. Thisfavors coated, insulating, and laminated configurations that can be integrated into modern facade and fenestration systems. In automotive applications, the push for lighter, stronger, and safer glazing supports continued demand for tempered and laminated formats, with additional interest in specialised optical or structural properties where vehicle architectures allow. In solar, growth in generation capacity is feeding demand for glass that balances transmission, durability, and cost, with low-iron specialty feedstocks gaining attention where performance thresholds are higher. For commercial buyers, the throughline is a preference for solutions that reduce operational risk and operating cost over the asset lifecycle, rather than lowest first-cost alone.
Supply Chain Realities and Cost Structure Sensitivity
The cost architecture of flat glass remains sensitive to energy inputs, soda-ash pricing, and specialty silica availability. Float production lines in Europe and North America have faced mixed price trends and cost volatility in early 2026, underscoring how tightly throughput economics are linked to commodity and energy markets. At the same time, demand from solar applications has influenced pricing for specialised low-iron silica variants, illustrating how cross-sector demand can propagate into raw material markets and alter sourcing strategies for precision grades. For manufacturers, this environment favours procurement flexibility, line efficiency, and process control that can buffer margin compression. For fabricators and system integrators, it elevates the importance of supplier resilience, inventory strategy, and specification discipline to avoid cost shocks being passed unpredictably into end projects.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field spans global producers with broad application portfolios and specialty or regional players that compete on precision, local market access, or specific processing capabilities. Several large groups anchor their positioning in low-carbon production and high-performance architectural, automotive, and solar offerings. Saint-Gobain emphasises float flat glass across architectural, automotive, and solar uses with a clear focus on lower-carbon production pathways, a stance that aligns with regulated building markets and buyers seeking verifiable sustainability attributes. AGC positions around float and processed flat glass, including ultra-thin insulating and low-emissivity products, appealing to markets where thermal performance and design flexibility are priorities. NSG Group’s Pilkington-branded portfolio targets construction, automotive, and high-performance uses, leveraging brand recognition and application breadth.
In North America, Guardian Industries supplies coated and insulated flat glass for architectural and automotive markets, while Cardinal Glass Industries and Pittsburgh Glass Works serve construction and specialty applications with regionally anchored capability. Vitro operates as a major producer with emphasis on energy-efficient and architectural glass, and its disclosed carbon intensity indicators support engagement with efficiency-driven procurement programmes. In Europe and adjacent markets, Şişecam combines broad regional reach with energy-efficient architectural offerings, while Central Glass specialises in high-performance and specialty flat glass, illustrating how niche expertise can coexist with larger-scale players. In Asia, Fuyao Glass and CSG Holding hold strong positions across automotive, construction, and solar segments, supported by large-scale production and global supply chains; Taiwan Glass and Xinyi Glass add further capacity for construction, industrial, solar, and automotive applications. Schott AG remains notable for specialty flat glass, including ultra-thin and high-transmission variants, where precision and performance matter more than volume.
Strategic Patterns Among Leaders
Across these participants, several strategic patterns emerge. The first is application integration: leading producers are increasingly organised around serving construction, automotive, and solar with product lines that are not merely commoditised float, but engineered to meet specific performance, safety, and carbon expectations. The second is the low-carbon differentiator: several groups are advancing production lines and declarations that reduce embodied carbon, using these attributes to align with regulation and procurement preferences in efficiency-sensitive markets. The third is geographic and capability balancing: global scale is paired with regional service depth, processing capability, and certification readiness, which matters because end-use acceptance often depends on local standards and fabricator relationships. Together, these patterns suggest that leadership is being rebuilt around a combination of volume, specification depth, and verifiable sustainability performance rather than capacity alone.
How the Landscape Is Evolving
Market structure is likely to evolve along three directions. Consolidation pressure will persist where scale efficiencies, energy cost management, and R&D amortisation favour larger, multi-application groups, particularly in mature markets where margins reward differentiation. At the same time, segmentation will deepen: specialty producers and regional experts will retain relevance where precision formats, certification complexity, or local service networks create barriers for generalist volume players. New entry and expansion will be selective, concentrated in regions where demand growth and cost positions are favourable, or in niches where thin, coated, or high-transmission products meet emerging architectural, automotive, or solar requirements. Participation in industry events and supply chain gatherings also reflects the importance of channel relationships and specification influence; major trade shows and conferences continuing through 2026 provide forums where manufacturers, fabricators, and dealers align on product roadmaps, supply expectations, and application trends.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next half-decade is likely to be defined by the interaction of performance demands, carbon expectations, and cost discipline. The first trend is rising performance specification as a baseline. As building codes, automotive requirements, and solar efficiency targets continue to advance, coated, insulating, laminated, and thin-format products are expected to command a growing share of value even where float glass remains the volume core. This rewards producers and fabricators that can document optical quality, thermal behaviour, and safety compliance with confidence, and it raises the stakes for suppliers that depend on undifferentiated commodity supply.
The second trend is carbon intensity as a commercial variable. Decisions in procurement and project approval are increasingly influenced by embodied carbon considerations and energy efficiency mandates. Producers that can deliver lower-carbon lines, transparent carbon disclosures, and consistent quality are better positioned to participate in regulated or preference-driven segments. This does not eliminate price competition, but it changes the criteria on which bids are won and retained, especially where multiple technically acceptable options exist.
The third trend is cost and supply resilience becoming a core competitive capability. With input cost volatility affecting soda-ash, natural gas, and specialty silica, the ability to manage procurement risk, maintain line efficiency, and ensure dependable delivery will separate stable operators from those exposed to repeated margin compression. For solar-related feedstocks, continued demand growth can tighten availability for low-iron specialty variants, making long-term sourcing strategies and grade discipline increasingly important. These trends point toward opportunities in product portfolios that blend specification value with cost control, in regional supply arrangements that reduce exposure to energy and commodity swings, and in service models that help fabricators and developers navigate certification and performance requirements without sacrificing project timelines.
Uncertainty remains. Energy price paths, raw material availability, certification evolution for thinner glass in multi-pane insulated units, and the pace of policy implementation can all alter the timing and distribution of demand. In construction, rate cycles and renovation activity can shift replacement demand relative to new builds. In automotive, platform architectures and lightweighting roadmaps influence glazing specifications. In solar, generation capacity additions interact with glass demand in ways that depend on technology mix, local content expectations, and feedstock availability. Navigating these variables requires continuous monitoring rather than one-time planning assumptions.
PW Consulting Chemical & Energy Research Center
What Decision-Makers Should Do Now
For Manufacturers and Producers
Prioritise differentiation that is measurable and certifiable. Invest where it strengthens optical, thermal, or structural performance claims and where low-carbon production can be demonstrated with credible disclosures. Balance volume lines with application-specific processing that meets the expectations of construction, automotive, and solar buyers. Strengthen procurement and energy strategies to reduce sensitivity to soda-ash, natural gas, and specialty silica volatility, and ensure that quality systems align with evolving dimensional and optical standards. Use trade and technical gatherings as channels to test specifications, align with fabricators, and signal product roadmaps, but base commercial commitments on resilient cost structures and verified performance rather than short-term demand noise.
For Investors and Capital Allocators
Evaluate exposure by segment composition rather than headline market size. Business models tied to higher-value coated, insulating, laminated, and specialty formats are likely to capture more durable value than undifferentiated volume plays, especially where regulation and procurement preferences reward efficiency and lower embodied carbon. Assess supply chain resilience, energy intensity, and certification readiness as part of operational risk, since these factors increasingly determine margin stability. When evaluating regional expansion or consolidation, consider the interaction of demand growth, input cost environments, and the ability to serve specification-driven applications with local acceptance and support.
For Procurement, Specification, and Supply Chain Leaders
Shift evaluation criteria toward lifecycle performance and supply reliability. Where multiple technically acceptable options exist, weigh embodied carbon, optical and dimensional consistency, and safety compliance alongside first cost. Build sourcing strategies that account for specialty feedstock availability, especially for low-iron and precision grades used in solar and high-performance building applications, and secure relationships that provide visibility into production and certification status. Require clear documentation for performance claims and certification alignment, particularly for thin glass in multi-pane insulated units where tempering and safety acceptance can constrain adoption. Treat trade and standards activity as early signals that can affect specification feasibility and project timelines.
For decision-makers who need segment-level sizing, regional detail, application splits, cost sensitivity analysis, and tailored recommendations aligned to specific products or markets, the full PW Consulting report provides the underlying structure and supporting data to move from directional insight to executable planning.
Optical Glass Market
For detailed analysis of this topic, please visit the official page: Flat Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Engine-Driven Welders Market
Market Landscape and Core Challenges
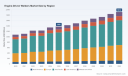
The global market for engine-driven welders has demonstrated steady expansion over the past five years, with total revenue climbing from approximately USD 1.08 billion in 2020 to a projected USD 1.38 billion in 2025. Growth is expected to continue along a 4.91 percent CAGR through 2032, pushing the market toward roughly USD 1.91 billion by the end of the forecast period. This trajectory reflects a mature but resilient equipment category that sits at the intersection of construction, energy infrastructure, and industrial maintenance. Rather than experiencing volatile boom-and-bust cycles, the segment has grown in a measured fashion, supported by replacement demand, expanding project pipelines, and the ongoing need for mobile power and welding capability in remote or off-grid environments.
The current landscape is defined by a concentration of demand among a handful of large players. The top three manufacturers account for roughly 68.5 percent of revenue, while the top five hold about 82.2 percent. Such concentration indicates that scale advantages in distribution, service networks, and engine sourcing remain decisive. At the same time, the market is not monolithic: demand patterns differ significantly by region, fuel type, and end-use application, creating pockets of opportunity that are less visible in headline figures. For decision makers, understanding where growth is actually coming from—and where friction is building—is more valuable than relying on aggregate market size alone.
Key Challenges and Inflection Points
Three interconnected challenges are shaping the near-term direction of the engine-driven welders market. First, the product category is caught between the need for rugged, high-output equipment and tightening emissions expectations. Many models rely on small internal combustion engines that must meet increasingly strict regulatory standards, particularly in North American and European markets. Compliance requirements affect engine selection, aftertreatment systems, and ultimately total cost of ownership, forcing manufacturers to balance performance, footprint, and certification burdens.
PW Consulting Automotive & Machinery Research Center
Second, input cost volatility remains a persistent pressure point. Engine-driven welders integrate gasoline, diesel, or LPG engines alongside alternators, control systems, and heavy-duty structural components. Fluctuations in raw material and component pricing can compress margins or ripple through end-user pricing, especially when manufacturers cannot pass costs through quickly enough. Since these machines are often purchased for demanding field conditions, buyers are sensitive to both upfront price and long-term reliability, making cost management a strategic rather than purely tactical issue.
Third, the market is facing a subtle but important shift in how jobsite labor is valued. Equipment that combines welding and auxiliary power generation can reduce the number of separate units and personnel required on site, lowering overall operational complexity. This labor-saving logic is increasingly attractive in environments where skilled trades are scarce or where project schedules are compressed. However, it also raises the bar for what buyers expect from a single machine: they want multi-functionality without sacrificing duty cycle, fuel efficiency, or serviceability. Manufacturers that fail to deliver integrated, dependable solutions risk losing share to alternatives that better match evolving field economics.
Key Drivers of Market Change
Technology Innovation and Performance Gains
Performance improvement remains one of the most direct catalysts for demand. Recent product introductions show a clear push toward higher welding output, better duty cycle characteristics, and more compact mechanical footprints. For example, ESAB’s introduction of the Ruffian EMP 270G engine-driven welder/generator highlighted a 270-amp welding output at 100 percent duty cycle, paired with 11 kW of generator power and a 23.5-HP Kohler Command Pro engine. The unit is assembled in Texas and positioned for harsh construction environments, with a smaller footprint designed to fit service trucks. Similarly, The Lincoln Electric Company’s launch of the Frontier 500X emphasized advanced arc performance and technology aimed at challenging construction and industrial settings.
These launches point to a broader engineering theme: buyers increasingly value machines that can sustain output under continuous use while remaining portable enough for mobile crews. Improved arc performance, better voltage stability, and more efficient engine-generator integration reduce downtime and expand the range of applications a single unit can handle. For manufacturers, the opportunity lies not just in adding features, but in optimizing the entire system so that welding quality, generator reliability, and fuel consumption work together in the field.
Policy and Regulatory Environment
Regulatory pressure on engine emissions continues to influence product design and market access. Engine-driven welder platforms that rely on diesel, gasoline, or LPG must navigate compliance requirements that differ across jurisdictions and customer segments. In the United States, certain engine-driven welder models are subject to EPA engine standards, which shapes engine sourcing decisions and can affect time-to-market for new configurations. This does not eliminate growth, but it does raise the importance of proactive compliance planning. Manufacturers that integrate emissions considerations early—rather than treating them as a retrofit problem—can reduce redesign risk and maintain smoother product rollout schedules.
Regulation also indirectly affects buyer behavior. Contractors and fleet managers increasingly factor compliance into procurement decisions because non-conforming equipment can create operational risk on regulated sites. As a result, certification and documented compliance are becoming part of the commercial value proposition, especially in public works, utilities, and oil and gas-adjacent projects where audit trails and environmental requirements carry real weight.
Demand-Side Shifts in Construction, Pipeline, and Mining
Demand is being shaped by how end users organize work on site. Construction, pipeline, mining, and broader infrastructure activities remain central to consumption, but the competitive edge is shifting toward equipment that can reduce mobilization costs and simplify field logistics. In remote or temporary work zones, the ability to carry both welding capability and auxiliary power in one unit can lower the burden on support equipment and crew coordination. This is especially relevant where fuel availability, transport weight, and service access are constraints.
A related demand-side change is the growing preference for application-tuned configurations rather than generic multi-purpose machines. Pipeline work, for instance, may prioritize stable arc conditions and continuous operation, while construction crews may value quick deployment, compact storage, and rugged serviceability. Mining environments can impose additional demands for durability and dust-related durability. Buyers are increasingly looking for evidence that a machine has been engineered for their specific operating conditions, which rewards manufacturers that can align product claims with real-world use cases.
Supply Chain and Cost Structure Evolution
Cost structures in this market are sensitive to engine availability, electrical component pricing, and the broader logistics of building heavy equipment. Because engine-driven welders depend on engines, alternators, and control systems, suppliers must manage exposure to component cost swings and lead-time variability. In practice, this means that successful players often secure dependable engine sourcing and maintain buffer strategies for critical subsystems. The commercial impact is significant: even a well-designed machine can struggle if production planning cannot keep pace with demand or if margin erosion forces price increases that slow customer adoption.
At the same time, the economics of ownership are tilting the discussion toward total cost rather than sticker price. Fuel consumption, maintenance intervals, and downtime all influence whether a machine is profitable over its service life. This encourages buying decisions that favor durability and service network coverage, particularly in regions where equipment downtime can stall an entire project sequence. For manufacturers, this environment rewards consistent quality and predictable support more than short-term promotional pricing.
Competitive Landscape and Leading Strategies
Core Players and Strategic Positioning
The competitive set spans established welding specialists, diversified equipment suppliers, and regional manufacturers with distinct operational strengths. The Lincoln Electric Company remains a prominent U.S. manufacturer of engine-driven welders and generators, with product families such as the Ranger, Frontier, and Vantage lines commonly associated with Kohler and Kubota engines. Miller Electric Mfg. LLC is another strong U.S. presence, offering engine-driven welder platforms including the Bobcat and Trailblazer series as well as all-in-one EnPak models, frequently paired with Kohler engines. ESAB Corporation continues to compete with welder-generator platforms such as the Ruffian EMP 270G series, assembled in Texas and aimed at construction and oil/gas demand. Hobart Brothers Company also participates as a supplier and manufacturer of engine-driven welders, including Champion series models, reinforcing the importance of strong brand recognition in the North American market.
Beyond these leaders, several additional players contribute to a diverse supply base. Tomahawk Power LLC produces portable engine-driven welders and generators, including series models built around 15-HP engines, appealing to users who prioritize mobility and straightforward field operation. Multiquip Inc. supplies engine-driven welders and generators for construction and industrial applications, while Denyo Co. Ltd. from Japan emphasizes compact units with a focus on fuel efficiency and overseas TIG welding shipments. MOSA S.p.A. in Italy markets engine-driven welders and generators under the CANAWELD brand for professional and industrial use, and Shindaiwa Co. Ltd. offers portable and rugged units for field and agricultural applications. In the broader export and industrial space, Cruxweld Industrial Equipment Ltd in China manufactures engine-driven welders and generators for industrial welding and power generation, and Welding Industries of Australia supplies and manufactures for domestic and export markets.
Differentiation and Competitive Advantages
Differentiation in this market tends to cluster around three dimensions: engine and power integration, application-specific engineering, and service ecosystem strength. Product examples show that pairing proven engines with welding and generator outputs that match field demands can create a credible performance narrative. The recent ESAB and Lincoln Electric introductions illustrate a pattern where manufacturers highlight duty cycle, output stability, and environmental suitability together rather than treating them as separate selling points.
Another differentiator is build-and-source strategy. Units assembled in specific locations for regional demand can help manufacturers align with local compliance expectations, service expectations, and customer preferences. Along similar lines, brands that maintain strong recognition among contractors and fleet buyers benefit from lower sales friction and repeat demand in replacement cycles. In a concentrated market, reputation and reliability often matter as much as technical specifications because procurement decisions are frequently made by teams that prioritize uptime and predictable support.
Market Structure Evolution
The competitive structure appears to be moving along two parallel paths: consolidation among scaled players and continued niche activity around specialized use cases. High concentration at the top suggests that large manufacturers have advantages in engine partnerships, distribution reach, and brand equity. That said, the presence of multiple regional and application-focused suppliers indicates that smaller or more specialized players can still compete by serving specific customer segments, fuel preferences, or export markets.
New entrants and smaller producers are likely to find the most traction where they can respond faster to local requirements or offer configurations that larger brands do not prioritize. Conversely, incumbents are likely to continue strengthening their positions through product line depth, service coverage, and adherence to compliance-driven engineering. The result may be a market where the leaders protect broad demand while specialized manufacturers capture targeted niches, creating a layered competitive environment rather than a simple winner-takes-all outcome.
Worldwide TIG Welder Market
Forward-Looking Trends and Commercial Opportunities
Integration of Welding and Power as a Standard Expectation
Over the next three to five years, the combination of welding output and auxiliary generation is likely to become less of a bonus feature and more of a baseline expectation in many field applications. Buyers in construction, pipeline, and industrial maintenance are increasingly motivated by equipment that reduces equipment count and simplifies crew deployment. Commercial opportunity lies in designing machines that make this integration seamless, with stable power delivery, intuitive controls, and configurations that match actual jobsite usage. Manufacturers that can demonstrate dependable multi-function performance will be better positioned to capture replacement cycles and fleet standardization decisions.
Fuel-Type and Compliance-Driven Product Segmentation
Fuel choice and emissions compliance will continue to shape demand segmentation. Diesel, gasoline, and LPG options each carry different advantages in terms of fuel availability, runtime economics, and regional acceptance. As regulatory expectations evolve, product portfolios may become more clearly segmented by market and application, with some platforms optimized for strict compliance environments and others positioned where portability or fuel logistics matter more. For suppliers, the strategic opportunity is to plan engine and emissions strategies proactively, so that product families can serve multiple regulatory contexts without excessive rework.
Regional Demand Maturation and Export Dynamics
Demand growth will not be uniform across regions. Some markets will be driven by ongoing infrastructure and energy-related activity, while others will depend more on equipment replacement and fleet modernization. Export-oriented manufacturers may find chances to expand where local production capacity is limited or where regional service models are still developing. The commercial implication is that market expansion will increasingly depend on aligning product offerings with regional operating conditions, support networks, and fuel preferences, rather than assuming that a single global configuration fits all markets.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Regulatory changes may accelerate or restructure engine compliance requirements in ways that affect product timing and cost. Input cost volatility can compress margins and slow adoption if pricing becomes less predictable. In addition, competition from alternative power solutions or hybrid equipment concepts could pressure the role of traditional engine-driven platforms in certain applications. Economic slowdowns in construction or industrial activity may also affect procurement cycles, especially for discretionary fleet upgrades. Manufacturers and buyers alike should monitor these factors as part of capacity planning and investment decisions.
Actionable Recommendations for Decision Makers
For Manufacturers
Invest in integrated product engineering that treats welding performance, generator output, and engine compliance as a combined system rather than separate components. Prioritize engine partnerships and sourcing resilience to reduce exposure to component cost swings and lead-time disruption. Build product narratives around real field conditions—duty cycle, footprint, serviceability, and fuel efficiency—so that buyer decisions are supported by practical operating value rather than specification sheets alone. Where possible, differentiate through application-tuned variants that match the needs of construction, pipeline, mining, and infrastructure users.
For Investors
Evaluate companies based on their ability to manage compliance-driven engineering, maintain dependable engine and component sourcing, and sustain service network strength. In a concentrated market, scale advantages matter, but niche positioning can still create attractive returns where a company serves a specific fuel type, application, or regional export channel. Pay attention to product launch cadence and whether new introductions reflect genuine field requirements, since sustained relevance in this category depends on aligning engineering with customer operating economics.
Welding Equipment Market
For Procurement and End-User Buyers
Evaluate total cost of ownership with a focus on downtime, fuel efficiency, service access, and compliance status rather than purchase price alone. Consider whether a single welder-generator platform can reduce equipment mobilization and simplify field staffing for the applications you run most often. Request configuration details that reflect actual jobsite conditions, including intended duty cycle, engine type, and service support coverage, so that purchasing decisions align with operational risk and maintenance planning.
For decision makers who need a more detailed view of segmentation splits, regional demand patterns, and company-level positioning, the full research report provides deeper context beyond the strategic overview presented here. A more granular reading of the market can help translate these trends into procurement timing, product investment choices, and competitive planning with greater precision.
For detailed analysis of this topic, please visit the official page: Engine-Driven Welders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Graphite Electrodes Market: Why APAC & UHP Power the 4.8% CAGR Through 2032
By PW Consulting, 2026-09-21
The Graphite Electrodes Market: Strategic Shifts and Commercial Opportunities Through 2032
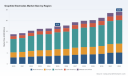
The global graphite electrodes market is entering a phase of structural recalibration, where growth trajectories intersect with trade realignments, raw material volatility, and technological differentiation. Valued at approximately USD 17.3 billion in 2025, the market has expanded from a base of USD 13.68 billion in 2020, reflecting a compound annual growth rate of 4.8 percent through the 2026–2032 forecast horizon. By 2032, revenue is projected to reach USD 24.02 billion, driven by sustained demand from electric arc furnace steelmaking, ladle furnace operations, and ancillary industrial applications. The geographic distribution of value reflects Asia Pacific’s dominant share, followed by North America and Europe, while product segmentation shows ultra-high power electrodes capturing the largest portion of market revenue, with high power and regular power grades representing the remainder. This macro framework masks deeper competitive and supply chain dynamics that will define where value is created and captured over the next several years.
Graphite Electrode Rod Market
Market Snapshot and the Current Inflection Point
The market’s recent growth pattern has not been linear. Post-pandemic recovery phases, shifting steel production economics, and incremental capacity expansions created a rhythm of expansion that is now giving way to more pronounced structural adjustments. Three interconnected challenges stand out as defining inflection points. First, raw material cost volatility has re-emerged as a critical pressure point, with petroleum needle coke prices experiencing significant upward movement in late 2025 tied to tight feedstock availability and broader crude oil dynamics. Second, trade policy is actively reshaping regional price formation and competitive positioning, as demonstrated by recent tariff and duty actions targeting large-diameter imports from China and India into key Western markets. Third, the industry is navigating a sustainability and performance threshold, where ultra-high power grades are increasingly expected to deliver both operational efficiency and documented environmental credentials, raising the bar for product differentiation beyond conventional specifications.
Core Drivers Reshaping the Market
A set of interdependent forces is accelerating the market’s evolution. Understanding how these drivers interact is essential for anticipating where demand will concentrate and where margin opportunities will emerge.
Technological Innovation and Performance Thresholds
The push toward larger-diameter ultra-high power electrodes is one of the most visible technology shifts in the sector. Larger electrodes enable fewer assembly joints, higher thermal efficiency, and improved arc stability in electric arc furnaces, directly translating into productivity gains for steel producers. Recent product validations for 800mm-class electrodes have expanded the addressable furnace base for operators seeking to modernize or optimize batch efficiency. At the same time, environmental product declaration achievements for graphite electrodes have established an official sustainability benchmark, signaling that performance is no longer measured solely by electrical conductivity, mechanical strength, and thermal resistance. The combination of technical performance and verifiable lifecycle data is becoming a competitive differentiator, particularly in markets where procurement teams are under increasing pressure to document Scope 3 impacts and material transparency.
Policy and Regulatory Environment
Trade defense measures and regional regulatory actions are introducing structural shifts in pricing and supply routing. In the United States, petitions for antidumping and countervailing duty investigations filed in early 2026 targeted large-diameter graphite electrode imports from China and India, reflecting concerns about material injury to domestic producers. Subsequent determinations by the U.S. International Trade Commission reinforced the view that these imports are materially affecting the U.S. industry, while also indicating reasonable indication of less-than-fair-value and subsidized imports. In parallel, Japan imposed a provisional anti-dumping duty rate of 95.2 percent on graphite electrodes imported from China effective in early 2025. These actions are not isolated regulatory events; they are reshaping competitive geography by influencing where supply is routed, how pricing is negotiated, and which producers gain or lose access to specific demand pools.
Coal Tar Pitch For Graphite Electrodes Market
Demand-Side Shifts in Steel and Industrial Production
The dominant application segment continues to anchor market growth, with electric arc furnace steelmaking absorbing the largest share of electrode consumption. This reflects broader structural trends in steel production, including the ongoing preference for scrap-based melting in many regions, capacity modernization, and efforts to reduce energy intensity per ton of output. Ladle furnace operations and other industrial applications contribute additional demand, but the strategic weight of the market is closely tied to electric arc furnace deployment and optimization. As steelmakers upgrade furnace configurations, pursue larger electrode diameters, and seek to lower lifecycle operating costs, demand patterns increasingly favor higher-performance grades and suppliers capable of supporting qualification, logistics, and technical service requirements at scale.
Supply Chain and Cost Structure Dynamics
Graphite electrodes are fundamentally linked to petroleum needle coke as the primary upstream feedstock, which means that margin dynamics and pricing strategy are sensitive to coke availability, refining capacity, and crude oil price movements. In late 2025, prices for petroleum coke and needle coke surged amid tight supply conditions and international crude oil fluctuations, adding pressure to input costs across the value chain. This raw material sensitivity has strategic implications. Vertically integrated producers with direct access to needle coke production can better manage cost volatility and protect gross margins, while non-integrated players face greater exposure to spot market swings and supplier negotiations. The resulting cost structure divergence is likely to reinforce competitive advantages for firms that control key upstream inputs and for those that can pass through cost changes with disciplined pricing frameworks.
Competitive Landscape and Strategic Positioning
The market does not exhibit extreme concentration, with the three largest players accounting for roughly one-quarter of revenue and the five largest reaching just over a quarter. This relatively fragmented structure creates room for differentiation through scale, vertical integration, technical service, and regional market access rather than purely through price competition. Several leading companies illustrate how distinct strategic positions are being built.
- GrafTech International Ltd. operates as a major producer and supplier of ultra-high-power graphite electrodes, including super-sized 800mm-diameter electrodes for electric arc furnace steelmaking. Its vertical integration into petroleum needle coke production, with facilities spanning France, Spain, Mexico, and Pennsylvania, supports cost control and supply reliability. Recent actions include an announced price increase on uncommitted volumes, anchored at a minimum of USD 600 to USD 1,200 per metric ton depending on region, alongside the successful launch of 800mm electrodes with completed customer qualifications. This combination of upstream control, large-diameter product capability, and disciplined pricing signals a strategy centered on margin restoration and performance leadership.
- HEG Limited is a leading Indian manufacturer of high-power and ultra-high-power electrodes, anchored by the world’s largest single-site integrated plant. Its focus on large-diameter electrodes for electric arc furnace steel production positions it as a scale-oriented supplier within a region that plays an important role in both domestic demand and export dynamics.
- Tokai Carbon Co., Ltd. maintains a global electrode production footprint across Japan, Europe, and North America, supplying ultra-high-power electrodes for electric arc furnace steelmaking. Capacity adjustments in Japan and Europe illustrate a pragmatic approach to regional competitiveness and asset optimization in response to shifting market conditions.
- Resonac Graphite America Inc. supplies high-quality graphite electrodes for electric arc furnaces, ladle furnaces, and non-ferrous applications, with manufacturing presence across the Americas, EMEA, and Asia. As part of the Resonac Group, it is involved in large-diameter electrode supply and has pursued trade investigations alongside Tokai Carbon GE LLC to address import competition in the United States.
- Tokai Carbon GE LLC, based in North Carolina, produces graphite electrodes and connecting pins up to 32 inches for electric arc furnace steelmaking, reinforcing regional manufacturing capability and direct market access in the United States.
- Graphite India Limited is a major producer of ultra-high-power electrodes for steelmaking with operations in India and Europe, and it is recognized as part of the five largest global producers outside China. Its geographic diversification and grade specialization reflect a strategy aimed at balancing regional demand with export-oriented positioning.
Market Evolution: Consolidation, Differentiation, and Trade-Induced Shifts
The competitive landscape is evolving along three trajectories. First, scale and integration are becoming more valuable as raw material volatility and large-diameter qualification requirements raise barriers to efficient participation. Producers with needle coke access, large-diameter capability, and broad furnace qualification networks are better positioned to capture premium demand. Second, regional realignment is intensifying as trade measures alter import economics and domestic industry protection becomes a more prominent policy theme in key markets. This does not eliminate global trade, but it increasingly conditions it on pricing discipline, duty exposure, and supply chain routing. Third, product differentiation is moving beyond electrical and mechanical performance to include sustainability verification and technical service intensity. Suppliers that can standardize qualification processes, reduce furnace downtime risk, and provide documented environmental data are building an advantage that is harder to replicate through capacity alone.
Strategic Outlook: Trends Shaping 2026–2032
Looking forward, three trends are likely to define the market’s next phase.
PW Consulting Chemical & Energy Research Center
Trend 1: Premiumization toward larger-diameter ultra-high power electrodes. As electric arc furnace operators seek throughput, energy efficiency, and operational stability, demand for larger-diameter and ultra-high power grades is expected to strengthen. This trend favors suppliers with proven qualification records, robust logistics for oversized product handling, and the ability to support furnace-specific configurations. Commercial opportunity lies not just in selling volume, but in bundling technical support, replacement planning, and performance documentation.
Trend 2: Trade policy as a permanent variable in pricing and sourcing. The recent U.S. trade investigation outcomes and Japan’s provisional duty actions indicate that tariff and duty frameworks will remain a meaningful factor in regional price formation. Sourcing strategies will increasingly need to account for duty exposure, alternative routing, domestic supply options, and negotiation leverage tied to local production capability. The commercial implication is a more complex procurement environment where cost optimization depends on legal, logistical, and regional supply considerations in addition to raw material pricing.
Trend 3: Sustainability and data transparency becoming procurement criteria. Environmental product declarations and lifecycle documentation are moving from optional differentiators to expected elements of supplier evaluation in certain customer segments. As downstream buyers face greater scrutiny over material sourcing and embodied impacts, electrode suppliers with verified environmental data and consistent reporting frameworks may gain preference in qualification processes. This opens opportunity for early movers to institutionalize sustainability credentials as part of their commercial value proposition.
These trends carry uncertainty. Raw material price swings can compress margins faster than pricing actions can be implemented. Trade determinations and policy adjustments may shift again, altering competitive access across regions. Demand growth may also be tempered by steel production cycles, scrap availability, and macroeconomic conditions that influence capital spending and furnace modernization timing. The market’s direction is clear enough to plan against, but the pace and intensity of change will depend on how these variables interact.
Implications for Decision Makers
Different stakeholders face distinct strategic priorities, but all share a need to act on more granular intelligence than headline market size can provide.
For Manufacturers and Suppliers
- Prioritize vertical integration or secure needle coke supply arrangements to reduce exposure to feedstock volatility and protect pricing flexibility.
- Invest in large-diameter qualification coverage and technical service capability, since furnace-specific validation and reliable delivery increasingly influence supplier selection for ultra-high power demand.
- Build disciplined regional pricing frameworks that can respond to raw material cost spikes while maintaining customer relationships, using uncommitted volume adjustments and contract structures strategically.
For Investors
- Focus on business models that combine scale, upstream input access, and differentiated product capability, since these traits are better positioned to capture premium demand and manage margin pressure.
- Monitor trade policy outcomes and regional duty exposure as factors that can alter revenue accessibility, competitive intensity, and the relative attractiveness of domestic versus export-oriented production.
- Evaluate sustainability readiness as a longer-term valuation consideration, especially where procurement trends are shifting toward documented environmental performance and supply chain transparency.
For Procurement and Procurement-Led Organizations
- Diversify sourcing with explicit attention to duty exposure, regional supply reliability, and qualification status for larger-diameter electrodes to reduce disruption risk.
- Incorporate total cost of ownership and furnace performance considerations into supplier evaluation, rather than relying solely on spot price comparisons, given the operational impact of electrode quality and service support.
- Track environmental documentation and product transparency as emerging procurement criteria, particularly where internal sustainability commitments or customer requirements are tightening.
Closing Perspective
The graphite electrodes market is expanding, but the more important story is how value is being redistributed across grades, regions, and business models. Ultra-high power electrodes, larger-diameter product capability, needle coke integration, trade policy dynamics, and sustainability verification are collectively reshaping where competitive advantage lies. Organizations that understand these forces at a granular level will be better positioned to price strategically, source resiliently, and capture demand from furnace modernization and performance-driven procurement. For decision makers seeking detailed segmentation data, regional demand breakdowns, competitive benchmarking, and tailored scenario analysis, the full research report provides the depth required to translate these market trends into operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Graphite Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steam Turbine Market: Asia Pacific’s Growth Drivers and the 2.8% CAGR Trajectory to 2032
By PW Consulting, 2026-09-21
The Steam Turbine Market at an Inflection Point: Strategy, Scale, and the Next Decade of Power Generation
The global steam turbine market is entering a phase of measured but decisive evolution. Valued at approximately 26.2 billion USD in 2025, the market has grown steadily from 22.82 billion USD in 2020, reflecting an average trajectory of 2.8% compound annual growth through 2032. While the headline numbers point to gradual expansion rather than explosive disruption, the underlying dynamics tell a more strategic story. Revenue concentration remains notable, with the top three firms capturing 48% of the market and the top five holding 50%, signaling that scale, technology access, and long-cycle project execution still reward incumbency. Yet the operational context is shifting fast: policy frameworks are tightening efficiency thresholds, data center demand is reshaping project pipelines, and material costs are pressuring margins across the value chain. For executives, investors, and procurement teams, the central question is no longer whether the market will grow, but where the growth will concentrate and how to position for it.
Market Snapshot: Steady Growth, Concentrated Structure, and a Changing Demand Base
Over the 2020 to 2025 period, the market expanded from the low 20-billion range to the mid-20s, with forward estimates reaching 31.79 billion USD by 2032. The compound annual growth rate of 2.8% captures a market that is expanding in line with infrastructure cycles rather than speculative demand. This baseline matters because it frames the strategic logic of the industry: steam turbines remain embedded in long-lived power assets, where efficiency, reliability, and compliance determine asset economics over decades.
Regionally, the market reflects a global but uneven footprint. Asia Pacific accounts for the largest share of revenue, followed by Europe and North America, with Latin America and the Middle East and Africa forming smaller but strategically important segments tied to utility expansion and industrial cogeneration. By application, power generation dominates the demand base, with oil and gas and other industrial uses representing smaller but commercially relevant niches. By type, both impulse and reaction turbines continue to serve distinct operating envelopes, with selection driven by pressure regimes, thermal profiles, and plant architecture rather than a single universal design.
What matters for strategy is not the spreadsheet of splits but the direction of travel. Demand is increasingly shaped by large-scale power projects that couple high-efficiency turbines with grid reliability mandates and, in several regions, by new load centers that require dedicated generation capacity. At the same time, the market’s concentration suggests that competitive wins are often won through differentiated technology packages, service relationships, and the ability to move quickly on project bookings in a capital-intensive environment.
Key Challenges and Inflection Points
Three challenges define the current turn in the market. First, efficiency and emissions regulations are rewriting the economics of existing assets. Updated performance standards for stationary combustion turbines now impose efficiency subcategorization thresholds, with large low-utilization units facing design efficiency expectations around 38%. For operators and OEMs, this creates a compliance calculus that affects turbine selection, cycle design, and retrofit strategies.
Second, the material and cost environment is becoming more volatile. Trade dynamics have elevated prices for nickel and chromium-based alloys that are central to turbine component performance. In a market where uptime and thermal resilience are valued, input cost pressure can compress margins and alter the attractiveness of certain design choices, particularly for long-lead components and high-stress rotor and blade assemblies.
Third, demand is bifurcating. Traditional thermal and cogeneration applications continue to matter, but a new demand vector is emerging from power-intensive digital infrastructure. AI data center power demand is accelerating combined-cycle projects that incorporate steam turbines, with several projects targeting online operation around 2028. This creates a fast-moving opportunity set, but also raises execution risk around timeline compression, site readiness, and the coordination of turbine supply with broader generation and grid integration plans.
Key Drivers Reshaping the Steam Turbine Market
Technology Innovation and the Efficiency Mandate
Efficiency remains the central technical battleground. Steam turbine value is increasingly derived from design refinements that extract more work from the same thermal input, reduce losses in moisture and staging, and improve part-load performance for plants that cycle more frequently. The push is not only about peak efficiency but about flexibility: operators want turbines that can respond to variable load profiles, integrate with different heat sources, and maintain reliability under changing operating regimes.
Recent commercial activity underscores this direction. Siemens Energy has booked significant steam turbine orders that contributed to a record backlog of 138 billion EUR, indicating strong demand for large-scale turbine-generator sets in complex power projects. The company’s selection to supply steam turbine generator sets for a 1 GW AI data center power project illustrates how turbine technology is being embedded into new demand centers where reliability and scale matter. Equally telling is the binding contract signed for a condensing steam turbine destined for an advanced reactor power plant, signaling that turbine applications are expanding beyond conventional thermal cycles into next-generation nuclear infrastructure.
These developments matter because they show how innovation is being validated through orders, not just laboratory benchmarks. For manufacturers, the strategic prize is to align efficiency gains with real project economics: fuel savings, emissions compliance, maintenance intervals, and the ability to operate across a wider load range. For buyers, the question is whether a turbine package can support both today’s operational needs and tomorrow’s regulatory and demand scenarios.
Policy and Regulatory Pressure as a Market Organizer
Policy is no longer a background condition; it is shaping project pipelines and asset decisions. The U.S. Department of Energy allocated 475 million USD in mid-2025 to enhance steam turbine efficiency in clean energy infrastructure, a signal that public funding is being directed toward performance improvements that can bridge conventional and low-carbon generation pathways. This kind of targeted support can accelerate adoption of higher-efficiency designs, especially where operators seek to extend asset life or improve economics before a wider transition.
On the compliance side, updated standards for coal-fired steam generating units require conversion to natural gas or carbon capture retrofit across a 2030 to 2039 window. Combined with efficiency thresholds for stationary combustion turbines, these rules create a structured timeline of decision points. Some plants will retrofit, some will repower, and some will be replaced entirely. For the steam turbine sector, this means demand will be redistributed across retrofit packages, new combined-cycle builds, and specialized configurations tied to evolving fuel and emissions pathways.
The practical implication is that policy is acting as an organizer of demand. Projects are being sequenced around compliance deadlines, and turbine selection is increasingly tied to the chosen compliance route. This favors suppliers that can offer flexible, documentation-ready solutions and that can support operators through the engineering and approval processes that accompany regulatory change.
Demand-Side Shifts: Data Centers, Grid Reliability, and New Load Centers
The most visible demand-side disruption is coming from power-intensive digital infrastructure. AI data center power demand is accelerating combined-cycle projects that incorporate steam turbines, with several initiatives targeting online operation around 2028. For turbine suppliers, this represents a shift from traditional utility-led procurement to a more diversified set of developers and offtakers that may prioritize speed, reliability, and dedicated supply for critical facilities.
This trend is not simply about adding load. It is about how that load is served. Data center power projects often require firm capacity, predictable availability, and tight integration with balance-of-plant systems. Steam turbines in combined-cycle configurations can offer the efficiency and scale needed to serve large continuous loads, while also supporting grid reliability when deployed in regions where new generation must come online quickly. The strategic opportunity lies in the convergence of industrial-scale turbine capability with fast-track project execution and service readiness.
A second demand shift is the continued relevance of industrial cogeneration and oil and gas applications. While smaller in revenue terms than power generation, these uses depend on turbines that can operate efficiently in tailored thermal environments and support process heat as well as electricity. Demand here is less about headline growth and more about reliability, lifecycle support, and the ability to adapt to site-specific constraints.
Supply Chain and Cost Structure: Materials, Lead Times, and Margin Discipline
Cost structure is becoming a strategic variable rather than a static input. Tariff-driven increases in nickel and chromium-based alloy prices are affecting components that are both performance-critical and long-lead. For manufacturers, this creates a balancing act between design integrity, sourcing strategies, and pricing discipline. For buyers, it can translate into more variable procurement costs and longer planning horizons as supply chains adjust.
The response is likely to differentiate winners. Suppliers that secure resilient sourcing, standardize high-value components where possible, and integrate service and lifecycle support can protect margins and reduce exposure to spot volatility. Buyers that engage early on specification, long-lead item planning, and service agreements can reduce execution risk and avoid late-stage cost surprises. In this environment, the steam turbine market behaves less like a commodity transaction and more like a structured engineering partnership, where risk allocation and planning horizon matter as much as unit pricing.
PW Consulting
Competitive Landscape and Leading Strategies
Incumbents with Scale, Technology, and Backlog Advantage
The market is led by large, globally integrated OEMs with strong positions in utility and industrial steam turbines. Siemens Energy brings a broad portfolio spanning conventional, combined-cycle, and nuclear applications, with an emphasis on efficiency and sector integration. Its recent order activity, including the record backlog and assignments tied to large data center and advanced reactor projects, highlights a strategy centered on winning complex, high-value projects where turbine performance is closely tied to overall plant economics.
GE Vernova remains a dominant force in installed capacity, with a long track record in steam turbine families for power plant solutions and advanced combined-cycle reheat designs. Its scale in global installed base creates a durable service and upgrade opportunity, while continued product development in high-efficiency configurations supports new project competitiveness. For the market, GE’s position illustrates how installed-base breadth can complement new-equipment leadership through lifecycle revenue and retrofit potential.
Mitsubishi Heavy Industries is notable for high-efficiency steam turbines in gas turbine combined-cycle plants, including components with hydrogen co-firing capabilities. This positions the firm at the intersection of efficiency and fuel flexibility, an increasingly relevant pairing as operators evaluate lower-carbon pathways without sacrificing thermal performance. The strategic value is in offering turbines that can operate across evolving fuel mixes while maintaining plant output and reliability.
Regional Players and Specialized Strengths
Alongside the global incumbents, several regional and specialized players hold meaningful positions. Dongfang Electric and Shanghai Electric are leading Chinese suppliers of large-scale turbines for power generation and utility-scale combined-cycle systems, with strong domestic demand and growing export activity. Harbin Electric similarly manufactures steam turbines with substantial domestic and export capability, reinforcing the importance of China’s manufacturing base in the global supply picture.
Doosan Enerbility has built a profile around combined-cycle and data center power projects, including recent North American orders, showing how a mid-tier global player can win by aligning turbine supply with fast-growing demand segments and executing on international project pipelines. Bharat Heavy Electricals Limited continues to serve Indian power generation and cogeneration applications, where domestic utility demand and cogeneration needs support a steady commercial base. Toshiba Energy Systems & Solutions and Ansaldo Energia add further depth in combined-cycle, cogeneration, and industrial power applications, reflecting the value of specialized engineering capabilities and regional project relationships.
Strategic Positioning and Differentiation
Across these firms, differentiation is emerging along several axes. Technology leadership in efficiency and cycle design remains foundational, but it is increasingly paired with fuel flexibility, service integration, and the ability to support complex compliance requirements. Backlog strength and project execution capacity are becoming competitive assets, especially where demand is concentrated in large, long-cycle projects that reward organizational reliability.
Another axis is application breadth. Players that can move across conventional thermal, combined-cycle, cogeneration, and emerging nuclear or advanced reactor applications are better positioned to capture demand that shifts as policies and load centers evolve. This breadth is not merely a portfolio feature; it is a hedge against demand volatility and a way to maintain utilization across different project types and geographies.
Service and lifecycle capability also matter. In a market where installed assets operate for decades, the ability to provide upgrades, maintenance, and performance restoration can stabilize revenue and deepen customer relationships. The competitive logic is straightforward: the turbine sale is often the entry point, but the long-term value is shaped by how well the supplier supports availability, efficiency retention, and compliance over the asset life.
Worldwide Steam Turbine for Power Station Market
Market Structure Trends: Integration, Differentiation, and New Entry Points
The market’s concentration suggests a tendency toward consolidation of advantage among scaled players, but it does not imply stagnation. Instead, the structure appears to be evolving through differentiation rather than pure consolidation. Global incumbents compete on technology, installed base, and complex project delivery, while regional players compete on cost, domestic relationships, and export execution. At the same time, new demand centers such as data center generation and advanced nuclear create entry points for specialized partnerships and project-driven wins, even if the core manufacturing barrier remains high.
This means the landscape is likely to remain layered. Leaders will continue to defend their positions through efficiency, scale, and service, while challengers and specialists will seek niches where project timeliness, regional proximity, or application-specific engineering provides an edge. For buyers, this layered structure creates options but also requires careful evaluation of technology fit, delivery risk, and long-term support.
Forward Outlook: Three Trends to Watch Over the Next 3 to 5 Years
Trend 1: Efficiency as the Default Purchase Criterion
Efficiency is likely to become an even more explicit purchase criterion as compliance windows tighten and fuel and emissions costs remain relevant. Projects will increasingly be evaluated on how turbine selection supports both immediate economics and future regulatory readiness. This favors designs that offer strong part-load performance, integration with higher-efficiency cycles, and clear documentation for compliance and permitting processes.
The commercial opportunity is in packages that link turbine performance to plant-level outcomes: reduced fuel intensity, lower exposure to emissions-related retrofit costs, and improved flexibility for cycling or dedicated load service. The risk is that efficiency gains can be undermined if material costs or lead times disrupt execution, or if operators underinvest in balance-of-plant and service planning that protects performance over time.
Trend 2: Demand Reallocation Toward Large Combined-Cycle and Dedicated Generation
The next few years are likely to see continued reallocation of demand toward large combined-cycle projects and dedicated generation for new load centers. AI data center power demand is already accelerating combined-cycle projects that incorporate steam turbines, and this pipeline is expected to shape order flow as projects move toward commissioning around 2028 and beyond. At the same time, retrofit and repower activity tied to coal-to-gas conversion and emissions compliance will redistribute demand across different project types.
For suppliers, the opportunity lies in aligning turbine offerings with the pacing of these projects and in demonstrating the ability to deliver under compressed timelines without compromising reliability. For developers and operators, the opportunity is in securing firm capacity with efficient, scalable generation assets that can support continuous loads and contribute to grid stability. The uncertainty is execution: timeline compression can stress supply chains, site readiness, and integration planning, especially when multiple large projects compete for the same materials and engineering resources.
Trend 3: Fuel Flexibility and Lifecycle Value as Competitive Differentiators
As operators evaluate lower-carbon pathways, fuel flexibility and lifecycle support will likely become more prominent differentiators. Hydrogen co-firing readiness, compatibility with changing fuel mixes, and upgrade paths that preserve efficiency and availability will matter for assets expected to operate through transition periods. Equally important will be service models that help operators manage performance, compliance, and maintenance across the asset life.
The strategic opportunity is in offering turbines and support structures that reduce the risk of stranded assets and extend useful life under evolving operating conditions. The risk is that fuel-flexibility claims must be matched by operational reality and that service promises must be delivered consistently, especially in markets where skilled labor and parts availability are constrained.
Actionable Guidance for Decision Makers
For Manufacturers and Suppliers
Position around efficiency, fuel flexibility, and delivery credibility. The market rewards technology that can be demonstrated in real projects, not only in specifications. Prioritize long-lead planning, resilient sourcing for critical alloys, and service integration that protects margins against input cost volatility. Where possible, build project-ready packages that simplify compliance documentation and reduce engineering friction for operators facing regulatory deadlines. Differentiate through application breadth where it can be supported by genuine engineering depth, especially in combined-cycle, cogeneration, and emerging nuclear-related applications.
For Investors
Evaluate exposure by project pipeline quality, backlog durability, and the ability to serve high-growth demand vectors without overconcentrating on any single cycle. The market’s 2.8% growth trajectory is steady, but the returns are likely to be uneven across players depending on their execution, technology positioning, and service mix. Watch for signs of margin resilience in the face of alloy cost pressure, and assess whether firms have credible pathways to capture data center-linked generation and retrofit-driven demand without compromising delivery reliability. Concentration in the market means scale matters, but differentiation in efficiency, fuel flexibility, and lifecycle support can determine who captures the higher-value segments of demand.
For Procurement and Operators
Treat turbine selection as a multi-decade decision shaped by compliance timelines, load profiles, and service realities. Engage early on specifications, long-lead items, and balance-of-plant coordination to reduce execution risk, especially for large combined-cycle or dedicated generation projects with ambitious commissioning targets. Evaluate suppliers not only on unit economics but on documentation support, upgrade paths, and the ability to sustain performance through regulatory transitions. In a market where material costs and lead times can shift, early planning and clear risk allocation are often as valuable as negotiating price.
Closing Perspective
The steam turbine market is not defined by rapid disruption but by a set of converging pressures that reward disciplined strategy. Efficiency, compliance, new demand centers, and cost discipline are reshaping where growth concentrates and how value is captured. The firms that navigate this environment well will be those that combine technical credibility with project execution, fuel flexibility with lifecycle support, and global scale with the ability to serve emerging demand channels. For executives and investors, the practical task is to map these trends to specific pipelines, asset strategies, and sourcing decisions before the next wave of project awards and compliance deadlines settles the market’s direction.
For a detailed breakdown of market size by region, type, and application, along with company-level profiles, recent order and contract developments, and regulatory and material cost dynamics, the full research report provides the segmented data and customized recommendations needed to support planning at the project and portfolio level.
Gas Turbine Market
For detailed analysis of this topic, please visit the official page: Steam Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Center Construction Market 2026: Why Hyperscale Demand Drives 6.4% Growth Through 2032
By PW Consulting, 2026-09-21
Data Center Construction Market: Strategic Trends and Commercial Opportunities in the AI Infrastructure Era
Market Snapshot: Scale, Growth Trajectory, and Structural Friction
The data center construction market has entered a decisive growth phase, driven by the compounding effects of cloud migration, enterprise digitalization, and the rapid deployment of artificial intelligence workloads. From a base of approximately 150 billion USD in 2020, the sector expanded to an estimated 288.34 billion USD in 2025, with a projected compound annual growth rate of 6.4 percent through 2032. By the close of the forecast period, cumulative revenue is expected to approach 442.64 billion USD, reflecting sustained capital allocation toward mission-critical infrastructure. This trajectory is not merely a continuation of historical IT spending patterns; it signals a structural reallocation of construction resources toward facilities designed for higher power densities, advanced thermal management, and resilient electrical architectures.
Despite the upward momentum, the industry faces two pivotal challenges that will define competitive positioning over the next several years. The first is the tension between accelerated deployment timelines and the physical limitations of power and supply chain capacity. Hyperscale and AI-oriented facilities demand faster commissioning cycles, yet electrical grid interconnections, specialized equipment lead times, and skilled labor availability constrain the pace at which projects can move from blueprint to operation. The second challenge lies in the shifting cost and compliance environment. Rising material input costs, evolving energy efficiency mandates, and the growing expectation that developers internalize the cost of new generation and transmission capacity are compressing margins and forcing earlier-stage design decisions to carry heavier financial weight. These friction points do not diminish the market's growth potential; rather, they elevate the value of differentiated execution capability, early stakeholder alignment, and cost-structured procurement strategies.
Key Drivers Reshaping the Construction Landscape
Technology Innovation and the AI Density Shift
The most consequential driver is the architectural shift required to support high-density computing. Traditional data center designs optimized for general-purpose server racks are being recalibrated for AI training and inference clusters that demand substantially higher power per square foot, more sophisticated cooling approaches, and tighter integration between mechanical and electrical systems. This shift is changing the construction value chain from a volume-driven model to a precision-driven model. Contractors and engineering firms that can deliver AI-ready infrastructure at scale—while managing thermal performance, redundancy requirements, and rapid mobilization—are gaining strategic relevance. Emerging construction approaches, including modular enclosure strategies and prefabricated mechanical and electrical assemblies, are increasingly attractive because they compress schedule risk and reduce on-site integration complexity. The practical implication for operators is that design flexibility and construction sequencing now matter as much as site selection.
Policy and Permitting Dynamics
Policy developments are actively reshaping the speed and economics of project delivery. Recent federal action has emphasized accelerated permitting for data center infrastructure, including streamlined environmental review processes and financial incentives for qualifying projects. At the same time, a growing number of states have advanced legislation requiring developers to cover the full cost of new energy infrastructure needed to support their facilities. This regulatory momentum creates a dual effect: it shortens certain federal approval timelines while simultaneously increasing the importance of state-level engagement, local grid coordination, and early cost modeling. Combined with energy efficiency standards that impose stricter compliance requirements for cooling and electrical systems, developers face a more layered approval environment. The winners in this context are organizations that treat permitting and utility coordination as core project pillars rather than peripheral administrative steps.
Demand-Side Evolution Across Hyperscale, Colocation, and Enterprise Segments
Demand is expanding across the spectrum of deployment models, but the composition of that demand is changing. Hyperscale facilities continue to anchor large-scale construction activity as major operators scale capacity to meet cloud and AI consumption growth. Colocation providers remain critical for organizations seeking flexible, professionally managed space with robust interconnection ecosystems. Enterprise demand, while smaller in aggregate scale than the largest provider categories, is becoming more sophisticated as companies pursue hybrid architectures, edge-enabled operations, and compliance-driven resilience requirements. The broader trend is a move away from one-size-fits-all facility design toward segmented construction strategies that reflect workload profiles, power availability, and long-term scalability needs. For construction and engineering participants, this means revenue opportunities are increasingly tied to the ability to customize specifications without sacrificing repeatability or cost control.
Data Center Rack Market
Supply Chain Pressure and Cost Structure Realignment
Cost dynamics are being reshaped by input price volatility, trade-related material exposure, and labor market constraints. Recent cost indexing from the construction sector points to elevated material and labor expenses tied to surging AI-related demand. Alongside that, upstream producer price movements for industrial chemicals and broad tariff exposure on steel, aluminum, and copper have increased cost sensitivity for structural and electrical components. Power market signals reinforce the cost narrative: capacity pricing in key regions has risen sharply as hyperscale demand competes for limited interconnection and generation resources. These pressures are not uniform across geographies or project types, but they are pushing the industry toward earlier procurement commitments, stronger supplier partnerships, and more disciplined contingency planning. The commercial opportunity here lies in cost-transparent project delivery models that allow operators to forecast total cost of ownership more reliably rather than reacting to mid-project escalation.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive environment is populated by firms with distinct service models, geographic reach, and technical specializations. Several companies have built recognizable positions by aligning their capabilities with the demands of mission-critical construction and high-density AI infrastructure. Fluor Corporation operates across multiple continents with full-scale data center construction services, including hyperscale facilities and mission-critical infrastructure. AECOM delivers end-to-end engineering, design, and construction for hyperscale and enterprise projects worldwide, positioning itself at the intersection of technical design and execution. Turner Construction Company has a track record of executing large-scale build-outs for hyperscale operators and colocation providers, giving it exposure to some of the highest-volume project pipelines in the market.
The landscape also includes firms with narrower but increasingly valuable specializations. DPR Construction focuses on mission-critical construction and preconstruction services for AI-ready facilities, an emphasis that aligns directly with the market's shift toward higher power density and faster delivery cycles. Holder Construction emphasizes efficiency and advanced mechanical and electrical systems, a profile that supports operators seeking tighter performance control in energy-intensive environments. HITT Contracting provides construction and general contracting services tailored to high-density AI infrastructure, while Clayco brings expertise in modular and sustainable design approaches that can help reduce schedule risk and improve environmental performance. Mortenson constructs hyperscale campuses with integrated sustainability and power solutions, and Brasfield & Gorrie delivers construction and commissioning for enterprise and cloud providers. Equans adds an international dimension with data center construction and facility management services, reflecting the globalization of operator demand.
Data Center Consulting Services Market
What distinguishes the leading participants is not simply scale, but the integration of design insight, procurement discipline, and execution reliability. Differentiated advantages increasingly come from the ability to manage power-intensive designs, coordinate complex mechanical and electrical installations, and maintain schedule certainty under cost volatility. Market concentration remains meaningful, with a significant share of activity tied to a relatively concentrated set of large players, yet the demand environment is broad enough to support specialized entrants and regional leaders who can deliver technical reliability and localized permitting expertise. The trend is one of selective consolidation among firms that can absorb complexity at scale, alongside continued fragmentation at the project level where customization, speed, and compliance knowledge determine success. New entrants and expanding contractors are likely to find opportunity not by competing on generic construction capacity, but by demonstrating proven delivery of AI-ready mechanical and electrical configurations, stronger utility engagement models, and cost-structured project planning.
Forward View: Three Trends Shaping the Next 3–5 Years
The first trend is the normalization of power availability as the primary project constraint. As facility designs become more energy-intensive, early coordination with utilities, explicit modeling of interconnection risk, and contractual frameworks that reflect capacity costs will become standard practice. This creates commercial opportunity for firms that can integrate power planning into the construction process and for operators that secure long-term energy alignments before breaking ground. The associated risk is that projects without robust power strategies will face schedule slippage, escalated costs, or reduced site optionality.
The second trend is the continued shift toward repeatable yet adaptable construction models. Modular elements, prefabricated subsystems, and standardized design modules are likely to gain share because they reduce on-site integration risk and improve schedule predictability. At the same time, workload diversity will preserve demand for customized engineering in high-performance environments. The opportunity lies in offering platform-based construction approaches that allow operators to scale efficiently while still accommodating segment-specific requirements. The uncertainty is that standardization can collide with local code variations, site constraints, and evolving efficiency mandates, requiring constant reconciliation between speed and compliance.
The third trend is a more explicit alignment between sustainability, regulatory compliance, and operational economics. Stricter energy efficiency standards and state-level cost-coverage expectations are pushing developers to treat efficiency and long-term operating cost as design inputs rather than downstream considerations. This opens opportunities for construction partners that can deliver compliant systems with lower lifecycle energy intensity and for operators that can communicate credible sustainability and cost-protection strategies to regulators, communities, and investors. The risk is that compliance-driven design changes, if addressed late in the project cycle, can raise costs and erode schedule confidence.
Strategic Actions for Decision Makers
For construction and engineering leaders, the priority is to build repeatable capabilities around high-density designs, power integration, and schedule certainty. Organizations should strengthen preconstruction planning, lock in early procurement pathways for critical materials, and develop partnerships that reduce exposure to volatile input costs. Differentiated positioning will come from proving that complex systems can be delivered efficiently without sacrificing performance or compliance.
For investors and capital allocators, the opportunity is to assess project pipelines based on power readiness, permitting alignment, and cost-structure resilience rather than headline capacity alone. Due diligence should emphasize utility coordination status, local regulatory exposure, and the contractor's demonstrated ability to manage mechanical and electrical complexity. Projects that have secured realistic energy arrangements and built-in cost controls are better positioned to convert capacity plans into operating assets on schedule.
For operators and procurement teams, the strategic imperative is to treat data center construction as a multi-variable optimization problem. Site selection, design standardization, supplier engagement, and regulatory planning should be integrated early to reduce late-stage rework and cost inflation. Procurement strategies that favor transparency, staged commitments, and verifiable performance criteria will increasingly protect margins in a volatile cost environment. More detailed segmentation data, project-level scenarios, and customized positioning guidance are available in PW Consulting's full market research report for teams that need deeper operational and regional insight to supportplanning decisions.
PW Consulting Chemical & Energy Research Center
For detailed analysis of this topic, please visit the official page: Data Center Construction Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Home Appliances Market: How 6.98% CAGR and Regional Shifts Redefine Growth Through 2032
By PW Consulting, 2026-09-21
Navigating the Home Appliances Market: Strategic Trends and Commercial Opportunities Through 2032
The global home appliances market has entered a phase of sustained expansion, reflecting deep structural shifts in how households and commercial enterprises consume, manage, and upgrade essential equipment. From 2020 through the base year of 2025, the sector demonstrated consistent upward momentum, with revenues climbing steadily as consumption patterns evolved and product categories matured. Current market size figures sit at 938.5 million USD, and forward projections indicate the base year will be followed by continued compound annual growth averaging 6.98 percent through the 2026 to 2032 forecast horizon. By the close of that period, revenues are expected to reach 1,495.2 million USD. This trajectory is not merely a function of population growth or replacement cycles. It reflects a convergence of technological advancement, regulatory recalibration, supply chain repositioning, and shifting consumer expectations that together reshape competitive dynamics and redefine where value is created.
For executives, strategists, and investors evaluating the home appliances sector, the headline growth rates tell only part of the story. The more consequential questions revolve around which segments will capture disproportionate share, how regulatory and trade environments will alter cost structures and sourcing strategies, and what operational or partnership models will separate resilient operators from those exposed to margin compression. Understanding these dynamics requires moving beyond aggregate figures and examining the forces that are actively redirecting capital, innovation, and market positioning across the industry.
Market Snapshot and Core Challenges
The home appliances market has grown from 743.2 million USD in 2020 to a base year valuation of 938.5 million USD, with the pathway from 2021 through 2024 showing steady annual increases that reflect both recovering post-pandemic demand and gradual upgrades in product portfolios. The forecast period from 2026 onward projects a market expanding to 979.21 million USD, then accelerating through subsequent years to reach 1,495.2 million USD by 2032. This growth cadence suggests that demand is broadening rather than merely rebounding, with new product categories, connectivity features, and commercial applications contributing incremental revenue streams alongside traditional residential replacements.
Beneath these aggregate trends, several structural challenges and inflection points are reshaping how companies plan for the coming years. The first is the intensifying friction between trade policy and manufacturing economics. Recent tariff adjustments on steel and aluminum imports, along with derivative duties affecting certain non-electric domestic cooking appliances, stoves, ranges, and washing machines, have introduced new cost volatility. Import volumes face downward pressure while domestic production costs rise, forcing manufacturers to weigh localized assembly against margin preservation. The second challenge lies in product safety and compliance risk. Regulatory warnings and recalls across categories such as small room tower heaters, steam cleaners, and hair dryers underscore the scrutiny facing manufacturers as appliance functionality becomes more electrified and digitally integrated. Failure to anticipate compliance requirements or to maintain rigorous quality controls can disrupt product pipelines and erode consumer confidence. The third inflection point is the widening divergence between traditional mechanical appliance performance and the expectations set by connected, AI-assisted, and energy-responsive products. Companies that treat smart features as additive accessories rather than core design parameters risk ceding premium positioning to competitors who embed intelligence into user workflows and service ecosystems from the outset.
Key Growth Drivers
Technological innovation continues to be the most visible engine of differentiation. Advances in kitchen automation, personalized guidance features, and cordless cleaning technologies illustrate how manufacturers are translating computational capability into tangible user benefits. Recent product introductions have showcased AI-driven cooking assistance integrated into connected home ecosystems, alongside premium cordless stick vacuums leveraging advanced filtration and micro-cleaning mechanisms. These launches signal a broader shift from standalone appliance functionality toward integrated experiences that reduce friction in daily routines and provide actionable feedback on usage patterns. The commercial implication is clear: differentiation increasingly depends on software architecture, sensor integration, and post-purchase service models as much as on mechanical durability or energy efficiency ratings.
Policy and regulatory environments are simultaneously reshaping cost structures and competitive boundaries. Tariff frameworks targeting steel, aluminum, and derivative articles have introduced meaningful uncertainty into sourcing strategies. The expansion of tariff inclusions to cover additional derivative appliances, portable non-electric cooking devices, and related components means that import-dependent supply chains face both direct duty exposure and indirect cost pass-through effects. At the same time, regulatory bodies are heightening safety expectations across multiple categories, reinforcing the need for proactive compliance management. For manufacturers with significant cross-border component flows, the strategic response involves mapping exposure across the bill of materials, evaluating domestic or near-shore production alternatives, and aligning product design with evolving tariff classifications to avoid unintended duty escalation.
On the demand side, consumer and commercial behavior alike are shifting toward efficiency, convenience, and resilience. Households are prioritizing appliances that reduce energy consumption, simplify maintenance, and integrate smoothly with broader smart home environments. The appetite for connected functionality is no longer confined to premium niches; it is expanding as users become more comfortable with app-based controls and automated scheduling. Commercial buyers, meanwhile, are evaluating appliances through the lens of operational continuity, compliance, and total cost of ownership rather than sticker price alone. This dual pressure pushes manufacturers to design products that perform reliably under varied usage patterns while providing data that supports predictive maintenance, service optimization, and energy management.
Supply chain and cost structure dynamics complete the driver set. Component availability, freight volatility, and regional manufacturing capacity all influence how quickly companies can scale new models or adjust to regulatory shifts. Investments in U.S. manufacturing expansion, including commitments exceeding 3 billion USD over a five-year horizon, highlight the strategic priority of domestic capability for certain product lines, including vertical zoneline air conditioners and demand-response electric water heaters. Such capital deployment does more than mitigate tariff risk; it positions companies to respond faster to localized demand, adapt product specifications to market-specific requirements, and reduce dependency on long, multi-tier logistics networks. The broader implication is that supply chain resilience is increasingly a competitive attribute rather than a back-office operational concern.
Worldwide Energy-efficient Household Appliance Market
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of large incumbents commanding a substantial share of revenues. This concentration creates a landscape where scale advantages in procurement, distribution, and brand recognition coexist with intense competition on product innovation and regional positioning. Leading players span major appliance specialists, diversified consumer electronics groups, and premium brand portfolios, each pursuing a distinct strategic emphasis. Some companies lean on broad brand families and deep installed bases in core categories such as refrigerators, washers, dryers, and ranges. Others differentiate through premium engineering, ecosystem integration, and brand equity in high-end segments. Chinese manufacturers continue to expand their global footprints, combining scale production with increasingly sophisticated feature sets and aggressive geographic diversification.
Recent developments illustrate how these companies are attempting to tilt the competitive balance. A premium appliance group launched an AI-driven kitchen guidance feature within a connected home application and introduced new cordless stick vacuums with advanced cleaning technology for the North American market. These moves reflect a focus on post-purchase engagement and differentiated cleaning performance, areas where incremental improvements can strengthen brand loyalty and support premium pricing. Another major domestic manufacturer announced a collaboration centered on specialty baking equipment, signaling a willingness to target niche usage patterns with tailored solutions and co-branded partnerships that elevate category relevance. The same company also disclosed a large multi-year investment program to expand U.S. manufacturing capacity, explicitly tied to air conditioning and demand-response water heater models that align with energy and grid-interaction trends. A separate strategic partnership between a European appliance group and a large Chinese manufacturer aims to accelerate growth and innovation in North America, illustrating how cross-border alliances are being used to combine engineering capabilities, scale, and regional market access.
These actions point to several evolving dynamics. Consolidation and partnership activity are increasing as companies seek to pool technology, share development costs, and access distribution pathways that would be slower to build organically. At the same time, segmentation is sharpening: premium brands are doubling down on connected experiences and specialized performance, while scale manufacturers are optimizing cost structures and expanding into adjacent categories. New entrants and niche innovators are finding opportunities not by challenging incumbents across the entire product spectrum, but by targeting specific workflows, unmet consumer preferences, or commercial applications where incumbent portfolios are less dense. The strategic question for incumbents is whether they can sustain differentiation as feature sets converge and as tariffs and compliance costs reshape the economics of global sourcing.
Forward-Looking Trends and Commercial Implications
One of the most consequential trends over the next three to five years is the deepening integration of intelligence and connectivity into mainstream appliance portfolios. AI-assisted guidance, usage personalization, and ecosystem interoperability are moving from premium differentiators to expected baseline features in key categories. The commercial opportunity lies in designing products where software and sensors create measurable improvements in cooking precision, laundry efficiency, cleaning performance, or energy management, and in building service models that leverage device data for predictive maintenance and customer retention. The risk is that intelligence becomes a commodity if multiple competitors adopt similar platforms without meaningful differentiation in user experience or service reliability.
Worldwide Domestic Appliances Market
A second trend is the reconfiguration of trade, sourcing, and manufacturing footprints in response to tariff and compliance pressures. As duties on steel, aluminum, and derivative articles affect cost structures, companies will continue to evaluate localized production, supplier diversification, and design adjustments that reduce exposure to tariff classifications. This creates opportunities for manufacturers with flexible production networks and for suppliers positioned in regions that benefit from trade realignment. The uncertainty to monitor is the pace and scope of future policy adjustments; abrupt changes can disrupt sourcing plans, alter margin assumptions, and shift the relative attractiveness of import-based versus domestic assembly models.
A third trend is the expansion of commercial and specialty applications as growth contributors. Demand-response electric water heaters, vertical zoneline air conditioners, and niche baking or cleaning solutions indicate that appliances are increasingly evaluated for their role in broader energy systems, operational efficiency, and targeted consumer experiences. Companies that can align product design with grid-interactive capabilities, commercial compliance requirements, or specific user workflows stand to capture value beyond traditional replacement cycles. The counter-risk is execution complexity: commercial specifications, certification demands, and service expectations can differ sharply from residential models, and misjudging these requirements can lead to costly market-entry setbacks.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to treat connectivity, compliance, and sourcing strategy as integrated design constraints rather than separate workstreams. Product roadmaps should account for tariff exposure across derivative components, embed intelligence that delivers measurable user value, and align manufacturing footprints with the markets where demand and policy dynamics are most volatile. Building post-purchase engagement through data-driven service, personalized guidance, and ecosystem interoperability can strengthen retention and support premium positioning. At the same time, quality and safety controls must be calibrated to heightened regulatory scrutiny, particularly in categories with elevated recall or hazard risk.
For investors, the focus should be on identifying companies with durable differentiation in a market where concentration is high and feature convergence is accelerating. Favor operators that demonstrate credible pathways to margin resilience under shifting tariff regimes, that invest in domestic or near-shore capacity where it aligns with demand and policy trends, and that can translate smart features into service-based revenue or stronger brand loyalty. Pay close attention to partnership structures and cross-border alliances, as these can accelerate access to technology and regional markets but also introduce integration and execution risk. Monitor recall patterns and safety compliance as leading indicators of operational discipline and reputational exposure.
For procurement and commercial buyers, the emphasis should shift from unit cost to total cost of ownership, energy performance, compliance assurance, and service responsiveness. Appliances that support demand-response capabilities, reduce maintenance downtime, and integrate cleanly into existing operational or smart home environments can deliver value that outweighs initial price premiums. Vendor evaluation should include assessments of manufacturing resilience, sourcing transparency, and readiness to adapt to evolving regulatory requirements, particularly where procurement volumes make tariff exposure and recall risk material.
PW Consulting Health Care Research Center
The home appliances market is evolving along multiple fronts simultaneously: technology is reshaping user expectations, policy and trade frameworks are altering cost and sourcing logic, and demand is broadening across residential, commercial, and specialty applications. Navigating this environment requires granular insight into segment dynamics, regional exposures, competitive moves, and the operational implications of regulatory change. Detailed breakdowns of segmentation, regional trajectories, competitive benchmarking, and scenario analysis are available through the full market research report, where deeper data and tailored recommendations can support planning for specific categories, geographies, and strategic objectives.
For detailed analysis of this topic, please visit the official page: Home Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Binders for Lithium Ion Batteries: Why the 15.8% CAGR Changes Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Lithium Ion Battery Binders Market
The lithium-ion battery binders market has evolved from a supporting materials segment into a critical enabler of next-generation energy storage performance. As electrode architectures grow more demanding and manufacturing processes shift toward sustainability and localization, binder formulations now influence battery cycle life, production economics, and regulatory compliance. Over the historical period from 2020 to 2025, the market expanded steadily, reaching an estimated global revenue of USD 5.63 billion in 2025. Forward projections indicate continued momentum through the 2026-2032 forecast horizon, with the market expected to reach USD 15.72 billion by 2032. This trajectory reflects a compound annual growth rate of 15.8 percent, signaling that demand for specialized binder solutions is accelerating rather than plateauing.
Such expansion is not merely a byproduct of broader battery production growth. It reflects a structural shift in how binders are engineered, sourced, and validated. The market concentration remains relatively fragmented at the top, with the top three participants accounting for approximately 29.4 percent of revenue and the top five reaching 36.2 percent. This distribution suggests room for both specialized challengers and integrated suppliers, while also indicating that scale advantages in formulation consistency and supply reliability are becoming increasingly decisive in securing long-term contracts.
Polyvinylpyrrolidone (PVP) for Lithium Ion Battery Market
Structural Challenges and Inflection Points
Despite the favorable growth backdrop, the industry is navigating several interconnected challenges that will shape competitive outcomes over the coming years. Raw material volatility stands out as a persistent pressure point. PVDF binder feedstock pricing has exhibited fluctuations in the 15-25 percent range, directly affecting cathode binder production costs. At the same time, CMC and SBR feedstock inputs, tied to cellulose and styrene pricing, have driven material cost increases of 10-20 percent in 2025. These swings are not isolated margin issues; they force formulators to rethink co-binder ratios, adjust supply strategies, and invest in formulation flexibility to maintain performance without overreliance on any single input stream.
A second inflection point lies in the regulatory and environmental transition away from solvent-based electrode processing. Water-based binder processes are being actively promoted under environmental mandates, with the potential to reduce NMP usage by up to 90 percent in electrode manufacturing. This shift is not simply a compliance exercise. It changes drying profiles, slurry rheology requirements, and equipment specifications, which means binder suppliers must deliver formulations that perform reliably in water-based systems without sacrificing adhesion, conductivity, or cycle stability. Companies that can support manufacturers through this transition are gaining structural relevance beyond traditional product specifications.
Foundry Binder Market
A third challenge is the tightening of qualification standards for automotive and high-reliability applications. New ISO certifications for lithium-ion binder formulations have become required for EV OEM qualification, and 2025 updates mandate enhanced electrolyte compatibility testing. These requirements raise the barrier to entry for new suppliers and reward incumbents with established testing infrastructure, long-term validation data, and close engagement with cell makers during the development cycle. The practical effect is that binder selection is increasingly tied to risk management and certification readiness, not just price or basic performance metrics.
Key Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
The pace of binder innovation is closely tied to changes in anode and cathode design. For graphite-based anodes, SBR and CMC combinations continue to serve as the performance baseline, but the emergence of higher-silicon anodes is pushing formulators toward PAA and advanced co-binder architectures. Silicon-rich designs promise higher capacity, yet they introduce volume expansion challenges that require binders with stronger mechanical resilience and better interfacial stability. On the cathode side, binder selection increasingly intersects with cathode chemistry and cell architecture. PVDF remains widely used for its electrochemical stability and adhesive strength, but modified formulations are being optimized for longevity, energy density, and tolerance to high-voltage operation. The broader trend is toward tailored binder portfolios, where a single product line is no longer sufficient across multiple cell chemistries and manufacturing routes.
Policy, Regulation, and Supply Chain Nationalization
Policy dynamics are reinforcing the push toward localized and more sustainable binder supply chains. Government-backed supply chain initiatives have supported domestic PVDF and SBR binder production expansions, including substantial capacity additions in North America. These efforts reflect a broader strategic priority: reducing dependence on concentrated foreign supply for critical battery materials and improving resilience against logistics disruptions. At the same time, regulatory mandates favoring water-based processes are reshaping procurement priorities. Manufacturers are increasingly evaluating binders not only on technical performance, but also on how well they enable lower-solvent processing, reduce environmental footprint, and align with plant-level sustainability targets. The outcome is a dual incentive structure: cost and reliability remain important, but environmental process compatibility is becoming a procurement gate.
Demand-Side Shifts Across Applications
Demand is shifting in ways that reward binders designed for different performance and durability profiles. Electric vehicles remain the largest application driver, reflecting their scale, performance requirements, and the need for long calendar and cycle life. Energy storage systems represent a second major growth path, with applications that often prioritize cost efficiency, safety, and extended service life under stationary cycling conditions. Consumer electronics continue to demand binder solutions that balance thin-electrode processing, space constraints, and consistency at high volume. Industrial and marine devices, while smaller in current market share, create specialized requirements around temperature tolerance, mechanical robustness, and safety margins. As demand disperses across these segments, binder suppliers are increasingly evaluated on application-specific fit rather than generic capability.
Cost, Scale, and Manufacturing Localization
Cost structure and manufacturing geography are interacting in ways that influence both supplier strategy and buyer behavior. Expanding local production capacity reduces exposure to freight costs, import delays, and regional supply shocks, but it also requires disciplined scale-up and consistent quality control. Water-based SBR and CMC-compatible grades, for example, are being scaled to meet broader demand from graphite and silicon anodes while maintaining cycle stability and enhanced capacity performance. For buyers, localized supply can improve lead-time predictability and technical support responsiveness. For suppliers, the challenge is to balance capital deployment against uncertain demand timing while preserving formulation integrity across multiple production sites.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established polymer specialists, chemical majors, and regional-focused material suppliers. Japanese firms continue to hold strong positions in advanced binder technologies, with several companies emphasizing water-based anode binders, cathode-grade PVDF, and application-specific formulations aimed at tensile strength, cycle performance, and electrochemical stability. These companies often benefit from long development histories, close relationships with battery manufacturers, and the ability to offer formulation guidance beyond the product itself. At the same time, European and North American players are expanding capacity and broadening portfolios to serve cathode and anode requirements across multiple binder chemistries, including suspension and emulsion types, water-based SBR/CMC systems, and functional PVDF grades.
Differentiation Through Formulation Depth and Application Fit
Leaders are increasingly differentiating on formulation depth rather than volume alone. In cathode binder markets, differentiation often centers on adhesive strength, electrolyte resistance, and compatibility with high-energy or high-voltage designs. In anode markets, the emphasis shifts to slurry handling, adhesion under water-based processing, cycle stability with silicon-containing formulations, and the ability to support higher capacity without sacrificing electrode integrity. Suppliers that can present validated performance across these variables create stronger switching costs for buyers, because changing binders often requires requalification, slurry re-optimization, and cell-level testing. This dynamic favors companies that combine product breadth with application-specific engineering support and reliable qualification data.
Capacity Expansion and Localization as Strategic Moves
Recent activity shows that capacity and geographic positioning are becoming central strategic levers. In March 2025, one major supplier expanded U.S. manufacturing for water-based anode binders in Pennsylvania and Tennessee, targeting global lithium-ion battery demand with SBR and CMC-compatible grades. Around the same time, another firm began preparations for a new battery binder production line in Texas, expected to become operational in 2026 for localized supply. These moves are not merely capacity additions; they signal a deliberate alignment with regional demand, OEM localization expectations, and supply chain resilience goals. Local presence can improve technical engagement with cell manufacturers, reduce logistics risk, and support faster response to formulation tweaks required during pilot and ramp phases.
Market Structure Evolution and the Role of Specialized Entrants
The market is likely to continue evolving along two parallel tracks. On one hand, larger suppliers will seek to consolidate advantage through portfolio breadth, multi-region manufacturing, and qualification readiness across major application areas. On the other hand, specialized producers will remain relevant where niche formulations, localized feedstock advantage, or deep experience in a particular binder type create defensible positions. In practice, this creates a landscape where buyers may source standard grades from scale suppliers while relying on specialists for specific high-performance or application-tailored needs. The presence of companies focused on CMC, SBR, PAA for high-silicon anodes, and functionalized PVDF illustrates how segmentation is reinforcing itself. Over time, the most resilient players will be those that can move fluidly between commodity-scale supply and specialized formulation value.
Future Trends and Commercial Implications
Trend 1: Water-Based Processing as the Default Design Basis
The shift toward water-based binder processes is expected to deepen over the next three to five years. As environmental mandates and manufacturing sustainability goals gain traction, electrode production is likely to lean further into systems that reduce solvent dependence and the associated handling and recovery burden. The commercial implication is clear: binder portfolios built primarily around solvent-based compatibility may face growing marginalization in new production lines. Suppliers that have already adapted formulations for water-based slurry stability, drying behavior, and adhesion performance will be better positioned to participate in next-generation cell manufacturing. For buyers, this trend increases the importance of assessing supplier readiness for water-based qualification, not just current price-performance ratios.
Trend 2: Higher-Silicon and Chemically Diverse Anodes Driving Binder Complexity
Anode formulation is moving toward higher-silicon content and more diverse material blends, which places greater stress on binder performance. Binders will need to handle expansion, maintain contact integrity, and support stable cycling without compromising electrode processing. This trend creates an opportunity for suppliers offering advanced co-binder systems, PAA-based formulations, and engineered ratios that balance capacity with mechanical durability. It also raises the stakes for formulation transparency and testing support, because anode behavior is highly dependent on the interaction between active material, conductive additives, and binder architecture. Companies that can help customers optimize these interactions will capture value beyond the resin itself.
Trend 3: Qualification, Certification, and Supplier Reliability as Competitive Moats
As EV OEM qualification standards tighten and ISO-aligned testing requirements become more demanding, certification readiness will increasingly function as a competitive moat. The trend is toward more rigorous electrolyte compatibility testing, consistency verification, and documentation that supports multi-year validation cycles. This favors suppliers with established quality systems, predictable batch-to-batch performance, and the ability to support long qualification timelines. It also raises the importance of regional supply continuity, because qualification programs often prefer or require stable access to the same material source over extended periods. The practical commercial outcome is that supplier selection will place greater weight on reliability, documentation, and applied engineering support, especially in automotive and energy storage projects where downstream cost of failure is high.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market evolution. Raw material volatility may persist, particularly if feedstock pricing for PVDF, styrene, or cellulose-related inputs remains sensitive to macroeconomic and supply disruptions. A second risk is the possibility of uneven adoption of water-based processes, where some manufacturing lines or regions transition more slowly due to equipment constraints or formulation challenges. A third uncertainty lies in the speed and coordination of qualification cycles across automotive OEMs and cell makers, which can delay demand realization even when technical readiness exists. Finally, shifts in cathode and anode chemistry roadmaps could change the relative importance of specific binder types, making portfolio flexibility essential for suppliers and careful tracking essential for buyers.
Strategic Actions for Decision Makers
For Battery and Materials Manufacturers
Evaluate binder strategy as a system-level choice rather than a discrete procurement item. Map current and planned electrode chemistries against binder requirements, especially where water-based processing, silicon blending, or higher-energy cathode designs are involved. Prioritize suppliers that can demonstrate consistent performance across multiple production sites and provide formulation guidance during slurry optimization and cell qualification. Build dual-source or regional-supply options where qualification timelines and production continuity make it feasible, and align internal testing protocols with emerging certification expectations so that supplier changes do not create unnecessary delays.
For Investors and Strategic Planners
Focus on differentiation that translates into switching costs and recurring demand. In this market, sustainable advantage often comes from formulation depth, validation infrastructure, and regional manufacturing presence rather than brand alone. Track capacity expansions that align with localized demand and assess whether new entrants have the technical support capability to participate in qualification-heavy segments. Monitor feedstock sensitivity and formulation flexibility as indicators of resilience, and pay attention to how quickly suppliers can adapt to water-based processing requirements and higher-silicon anode trends. Portfolio exposure should favor companies that can serve both scale applications and specialized needs without sacrificing consistency.
For Procurement and Supply Chain Leaders
Treat binder sourcing as a risk and performance decision that should be coordinated with cell design roadmaps. Assess supplier readiness for water-based processing, electrolyte compatibility testing, and regional supply continuity, especially where OEM qualification and localization expectations are becoming more stringent. Use multi-year qualification and testing data as part of supplier evaluation, and ensure that cost negotiations do not obscure the potential downstream impact of inconsistent material performance. Where possible, align sourcing decisions with planned shifts in anode and cathode chemistry so that binder transitions are proactive rather than reactive.
The lithium-ion battery binders market is moving into a phase where technical complexity, regulatory direction, and supply chain geography jointly determine competitive outcomes. Growth is robust, but the real commercial value lies in understanding how formulation needs, processing shifts, and qualification requirements will reshape demand across EV, energy storage, consumer electronics, and specialized applications. Decision makers who track these dynamics closely will be better positioned to select suppliers, time capacity investments, and build resilient material strategies. For teams that need more granular segmentation data, regional demand patterns, and company-level benchmarking to support internal planning, the full research report provides a deeper evidence base and tailored analytical pathways.
For detailed analysis of this topic, please visit the official page: Binders for Lithium Ion Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


