



PW Consulting: Worldwide Acetylated Starch Market Reaches USD 644.0 Million in 2025, Poised for a 4.81% CAGR (2026–2032)
By PW Consulting, 2026-07-15
Worldwide Acetylated Starch Market — Strategic Preview for 2026 Decision-Making
Executive summary
Acetylated starch is a technically mature but commercially dynamic ingredient used across food, paper, pharmaceutical and industrial applications. PW Consulting’s new market study frames the space as a steady-growth, mid-consolidation market that rewards technology-led differentiation, feedstock risk management and selective capacity investment. The global market expanded from USD 508.12 Million in 2020 to USD 644.0 Million in the base year 2025, and our forecast indicates a compound annual growth rate (CAGR) of 4.81% through the 2026–2032 outlook period, reaching an estimated USD 894.16 Million by 2032. For C-suite leaders preparing 2026 plans, this research translates macro momentum into operational priorities and investment guardrails.
Worldwide Acetylated Starch Market
Why this report matters for 2026
-
Timing. The industry is entering a phase where incremental innovations (clean-label formulations, freeze-thaw stability, pharma-grade functionalization) can unlock above-market growth. Our 2026-focused tools help firms prioritize short-cycle R&D and customer trials that will yield commercially meaningful wins within 12–18 months.
Worldwide Acetylated Starch Market -
Risk-to-reward clarity. With feedstock volatility and periodic regulatory shifts, executives need quantified scenarios to balance margin protection against share-seeking investments. The report provides pass-through models and scenario outputs tailored to common commercial structures in the sector.
Worldwide Acetylated Starch Market -
M&A and partnership diagnostics. Consolidation is moderate: the top three companies control a meaningful share of the market, and the top five nearly half (our concentration metrics indicate a CR3 ~32.4% and CR5 ~46.8%). That structure creates openings for targeted bolt-ons and strategic alliances — especially for specialty or regional plays. We map realistic transaction archetypes and valuation cushions for 2026 deal pipelines.
What the report contains — practical modules you can act on in 2026
-
Market sizing and forward scenarios: a transparent base-case and two stress scenarios (high volatility and accelerated adoption) that convert the headline CAGR into revenue and margin trajectories for 2026–2028 planning.
-
Price & cost engineering toolbox: custom elasticity and raw-material pass-through models, unit-cost curves by process route, and break-even analyses for in-house vs toll-manufacturing choices.
-
Go-to-market playbooks: tailored GTM templates for enterprise suppliers, co-manufacturers and ingredient innovators, including channel economics and sample commercial terms used by leading customers.
-
Regulatory impact matrix: mapping of food- and pharma-related approvals and tolerances, with actionable checklists to expedite dossier updates and labeling changes.
-
Competitive heatmaps and supplier dossiers: strategic profiles of global and regional producers, capability assessments (R&D, co-manufacturing, regulatory support) and scenario-based partner shortlists.
-
Investment and capex playbook: NPV templates, capacity utilization thresholds and contingency triggers for greenfield, brownfield expansion and retrofitting to specialty grades.
Market dynamics shaping 2026 strategy
Several supply-side and demand-side vectors will dominate 2026 decision-making:
-
Feedstock dynamics. Corn remains a primary feedstock in many value chains; disruptions in corn markets and trade policy can quickly alter cost parity across sourcing options. For example, historical price signals and trade frictions have produced durable regional sourcing effects that should inform procurement hedges and dual-sourcing strategies.
-
Input cost idiosyncrasies. Acetic acid, a key reagent in acetylation, has shown material regional pricing dislocations — recent oversupply in parts of Asia has driven spot price declines, while European potato starch costs experienced upward pressure after acreage reductions. Firms should model localized supplier baskets rather than rely on global averages.
-
Regulatory clarity. Authoritative re-evaluations of certain acetylated starches have reinforced their safe-use profile in food applications; yet product-labeling trends (clean label, “natural” claims) and category-specific limits will continue to nudge formulations toward lower-additive and transparent ingredient statements.
-
End-market sensitivities. Demand from frozen foods, shelf-stable bakery, specialty paper and pharmaceutical excipients varies in growth rate and margin potential. Winning in 2026 means matching product development cadence to those segments that deliver the fastest payback while defending against commoditization in high-volume categories.
Competitive landscape — strategic implications
The sector blends global integrators and regionally focused specialists. Leading players include Cargill Inc., Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Avebe U.A., Emsland Group, AGRANA and KMC — each with distinct strengths:
-
Cargill: scale and formulation depth for broad food-industry penetration; advantage in supply chain integration and co-development with large food manufacturers.
-
Ingredion: strong clean-label positioning and brand-anchored product lines that appeal to consumer-facing customers seeking simple-ingredient narratives.
-
Tate & Lyle: niche strength in technical grades for stability and freeze-thaw performance, supported by deep application know-how in frozen and chilled foods.
-
Roquette: pharmaceutical-grade capabilities and regulatory depth; an attractive partner for companies seeking excipient development and regulatory transfer expertise.
-
Avebe, Emsland, KMC: potato-focused specialists with product portfolios tailored to dairy, meat analogs and extrusion processes — attractive assets for targeted acquisitions or co-development agreements.
-
AGRANA: an example of a supplier that bridges food and industrial paper applications, useful for customers with cross-category needs.
Strategic takeaway: incumbents with broad distribution and co-development capability can defend share through bundled solutions; mid-sized players achieve higher returns by specializing in technical niches or by being attractive acquisition targets for larger integrators seeking regional feedstock advantages.
Strategic recommendations for 2026 planning
-
Hedge raw material exposure actively. Build a procurement ladder that combines spot, forward and index-linked contracts for corn derivatives and acetic acid. Consider strategic tolling agreements in regions where raw material or energy cost volatility is elevated.
-
Prioritize specialty-grade investments. Allocate R&D and capital to grades that solve high-margin customer problems (e.g., freeze-thaw stability, clean-label emulsification, tablet-binding in pharma). These yield faster payback and reduce exposure to commodity price cycles.
-
Structure M&A with capability, not just capacity, in mind. Given the market’s mid-level concentration, value accretion is more likely from acquiring formulation know-how, regulatory dossiers or regional feedstock position than from acquisitive volume alone.
-
Optimize manufacturing footprints. Use short-cycle pilot lines and toll-manufacturing partnerships to test new grades before committing capex; where scale is essential, prioritize expansions in jurisdictions with stable feedstock supply and favorable trade terms.
-
Embed regulatory and labeling agility. Expect tightening of consumer-facing declarations; put cross-functional teams in place to accelerate label changes and claim substantiation without disrupting supply chains.
-
Design commercial instruments for 2026 contracting: offer performance-based contracts and technical service bundles to capture upside from formulation improvements while protecting against price erosion.
Risks and watch-items for board-level review
-
Policy and trade risks. Tariff actions and export controls affecting major feedstock flows can alter sourcing economics; scenario-planning should explicitly incorporate plausible near-term trade shifts.
-
Input-price shocks. Sudden changes in corn or potato supplies and reagent availability can compress margins; maintain liquidity buffers and access to alternative reagent markets.
-
Labeling & consumer trends. Accelerating clean-label demand can render commoditized grades less attractive; invest now in communication and reformulation capability.
How to use this report in your 2026 roadmap
For executives building 2026 budgets and three-year plans, the report functions as both a lighthouse and a workshop kit: it identifies where growth will be realized across the market and supplies the analytic templates to test investments under multiple economic and regulatory scenarios. Use the report to:
-
Prioritize R&D and plant investments with clear ROI thresholds;
-
Design procurement strategies tied to product margins and regional exposure;
-
Create M&A shortlists and transaction model assumptions aligned with realistic integration synergies;
-
Operationalize a monitoring dashboard with KPIs tied to feedstock price indices, utilization rates and new-grade adoption curves.
Next steps
PW Consulting’s Worldwide Acetylated Starch Market report gives you the frameworks, models and competitive intelligence needed to convert the industry’s steady CAGR and identified opportunities into executable 2026 strategies. This preview highlights strategic directions and practical tools while preserving the detailed segment-level and regional figures that underpin investment-grade decisions. To access the full dataset, interactive dashboards and supplier scorecards — and to book a tailored briefing with our lead analysts — please contact PW Consulting through our corporate channels.
For detailed analysis of this topic, please visit the official page: Worldwide Acetylated Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Veterinary Glucometers Market to Reach USD 926.01 Million by 2032, Expanding at a 7.85% CAGR
By PW Consulting, 2026-07-15
Worldwide Veterinary Glucometers Market — Strategic Imperatives for 2026
PW Consulting’s newest market study on the Worldwide Veterinary Glucometers Market synthesizes five years of historical performance and a seven‑year forecast to 2032, delivering a market view that is both data‑rigorous and directly actionable for executive decision‑making. The global market is projected to expand from a 2025 base of approximately USD 545.6 Million to just over USD 926.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of roughly 7.85%. Market concentration is material — the top three and five suppliers together account for a clear majority of revenue — an attribute that shapes pricing, channel, and M&A dynamics through 2026 and beyond.
Worldwide Veterinary Glucometers Market
Why this report matters to 2026 strategic planning
-
Timing: 2026 will be a pivotal year for veterinary diagnostics, as new continuous glucose monitoring (CGM) entrants complete regulatory and manufacturing validation while incumbent players consolidate channel relationships. Our forecast period (2026–2032) is therefore aligned to the window in which product relaunches, distribution changes, and reimbursement practice evolution will most strongly influence share shifts.
Worldwide Veterinary Glucometers Market -
Actionability: The study translates market movement into clear decision levers — product investment priorities, channel build vs. partnerships, pricing architecture, and M&A criteria — so that commercial and corporate development teams can convert insight into near‑term actions.
Worldwide Veterinary Glucometers Market -
Risk‑adjusted planning: The veterinary glucometer market sits at the intersection of medtech accuracy requirements, species‑specific validation needs, and an increasingly digital, clinic‑to‑home continuum of care. Our scenarios explicitly model regulatory friction, channel concentration, and adoption rates for clinic‑direct CGMs versus home testing solutions to inform contingency planning for 2026 operational budgets.
Market trajectory and structural takeaways
After a steady expansion through 2020–2025, the market enters a higher‑growth phase driven by two convergent themes: (1) the maturation and clinical acceptance of pet‑oriented CGMs and enhanced meter algorithms calibrated for species‑specific physiology; and (2) broader digitization of the veterinary patient record and remote monitoring workflows that raise demand for interoperable measurement devices. Our base‑case projects continued mid‑single‑digit to high‑single‑digit growth through 2032 — a profile that rewards timely investments in product differentiation and channel access.
Concentration indicators show the market is not a fragmented long tail: leading manufacturers capture concentrated shares that enable them to move distribution and pricing quickly. This creates both opportunities for disruptive entrants with clinically‑validated technology and challenges for smaller incumbents that lack scale in manufacturing, distribution partnerships, or post‑market clinical evidence.
Competitive landscape — what to watch in 2026
The competitive map combines traditional veterinary diagnostics specialists, medtech players extending into animal health, and dedicated pet CGM innovators. Key companies profiled in our study include established large animal health players, specialist glucometer manufacturers, and CGM‑first startups. Across the competitor set, three themes deserve attention:
-
Species‑specific calibration and clinical validation: Vendors with robust, published validation against laboratory reference methods in dog, cat (and where relevant, equine) matrices are carving out trust advantages with veterinarians.
-
Platform and data strategy: Devices that support clinic workflows — data sharing between pet owners and veterinarians, multi‑pet profile management, and clinic‑level dashboards — are gaining traction over one‑off meters that merely display a value.
-
Channel and distribution sophistication: Exclusive or preferential relationships with major animal health distributors materially accelerate market access for devices positioned as clinic‑direct CGMs or vet‑recommended home meters.
Representative vendor snapshots included in the report (each with strategic implications and suggested partner/competitive responses) are:
-
Zoetis (Parsippany, NJ): Continues to leverage brand trust and a product ecosystem calibrated for companion animals. Recent device iterations emphasize small sample volumes and integrated mobile apps to strengthen clinic‑to‑home continuity.
-
i‑SENS (Seoul): Focuses on veterinary‑calibrated meters with an emphasis on straightforward clinic and home use; competitive on unit economics and global distribution reach.
-
Nova Biomedical (Waltham, MA): Addresses both companion and herd applications by extending glucose and ketone measurement capability, positioning around multi‑use clinical value.
-
Universal Biosensors (Rowville): Emphasizes multi‑pet profile management and handheld point‑of‑care usability for clinical settings.
-
ALR Technologies / GluCurve (Singapore / USA): A CGM‑focused entrant that has announced re‑validation and relaunch plans — a development that could reshape clinic CGM adoption timelines if commercial roll‑out meets projected accuracy and distribution targets.
-
Adapet Medical, UltiMed/Advocate, MAI Animal Health, Woodley Equipment: Each brings differentiated mixes of portability, dual analyte testing (glucose + ketone), and clinical distribution footprints; collectively they form the tactical competitive field for mid‑market clinic and home segments.
Notably, recent developments — including a late‑2025 product relaunch announcement from a CGM vendor and earlier major meter upgrades by established players — signal that 2026 will be the year when product claims, clinic validation, and distribution activation converge to produce measurable share movement.
Regulation, clinical validation and technology implications
Regulatory and validation dynamics are central to commercial strategy. Veterinary glucometers are judged not only by ease of use but by species‑specific accuracy validated against laboratory reference methods. Where applicable, ISO 15197 performance benchmarks and animal‑matrix verification are increasingly referenced in procurement and clinical guideline decisions. In practice this means that new product launches without rigorous animal‑specific validation face slower adoption and greater discounting pressure.
Operational implications for suppliers include investment needs for veterinary clinical studies, documentation for distributor qualification, and engineering for small sample volumes consistent with ear or paw capillary sampling. Meanwhile, the ongoing off‑label use of certain human flash glucose monitors in veterinary practice underscores both an unmet clinical need and an addressable regulatory gap for dedicated veterinary CGMs.
What the PW Consulting report delivers (practical, non‑theoretical outputs)
We designed the study to support tactical decisions in 90–180 day planning cycles as well as to inform three‑year strategic roadmaps. Key deliverables include:
-
Comprehensive market model: historical series and scenario‑based forecasts through 2032, with modular drivers so teams can re‑run outcomes under alternative adoption, pricing, and regulatory scenarios.
-
Segment and channel playbooks: go‑to‑market blueprints for clinic‑direct CGMs, clinic‑recommended home meters, and herd/large‑animal solutions.
-
Competitive battlecards: validated strength/weakness matrices, product claims comparison, and distributor maps for each major competitor.
-
Evidence and regulatory checklist: recommended study designs, sample size guidance, and pathways for animal‑matrix validation to meet purchaser expectations.
-
M&A and commercial partnership scoring: a rational, repeatable framework to prioritize targets by technology fit, distribution access, and scale economics.
-
Financial templates and price sensitivity analysis: margin and payback models calibrated to typical veterinary channel mixes.
To honor the “trailer” principle and preserve the strategic value of the full dataset, this release intentionally omits core segment tables and granular regional or product‑level figures. The report itself contains complete segmentation by product type, animal category, end‑user channel, and region, together with downloadable models for internal use.
Recommendations for executives in 2026
-
Manufacturers with clinical validation: Shift from feature‑led marketing to evidence‑led commercial programs. Prioritize clinic key opinion leader (KOL) engagement and distributor exclusivity pilots that tie reimbursement or purchasing incentives to demonstrated accuracy in veterinary matrices.
-
SME device makers: Consider partnerships or selective licensing with larger animal health distributors to overcome channel friction. Evaluate bolt‑on acquisitions that can close gaps in clinical evidence or manufacturing scale.
-
Private equity and corporate development: Target assets that combine validated CGM algorithms, regulatory dossiers, and existing distributor agreements; avoid technology‑only assets lacking clinic validation unless a clear, well‑funded clinical program is part of the deal thesis.
-
Veterinary groups and networks: Implement standardized device evaluation criteria based on species‑specific performance and data integration capability before endorsing home monitoring kits to clients.
Next steps and how to access the full intelligence
PW Consulting’s full Worldwide Veterinary Glucometers Market report contains the complete numerical backbone — segmented market sizes, pricing ladders, and the financial model that underpins our 7.85% CAGR projection. For procurement teams, corporate strategy groups, and investor due diligence teams preparing for 2026 initiatives, the dataset and playbooks in the full report are designed to fast‑track execution while reducing clinical and commercial risk.
Contact PW Consulting to request the full report, the underlying market model (editable), and our executive briefing package. For organizations seeking a short engagement, we offer a 4‑week strategic sprint that converts the report’s insights into a tailored 90‑day action plan and a prioritized list of pilot or M&A opportunities.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary Glucometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide LARC Market Valued at $5.61B in 2025, Forecast to Reach $8.66B by 2032 at a 6.4% CAGR
By PW Consulting, 2026-07-15
Worldwide LARC Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
Executive preview — why this report matters to leadership teams planning for 2026
As healthcare payers, device manufacturers, and strategic investors set budgets and pipelines for 2026, the long‑acting reversible contraception (LARC) market presents a mix of predictable growth and accelerating structural change. PW Consulting’s latest Worldwide LARC Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market size, technology evolution, regulatory inflection points and competitive dynamics into an actionable playbook. At a macro level the global LARC market approached USD 5.6 billion in 2025 and is forecast to grow at a compound annual growth rate of 6.4% through our 2032 horizon, illustrating both steady demand and clear upside for differentiated strategies.
Worldwide Long-Acting Reversible Contraception(LARC) Market
High‑level takeaways for 2026 decision cycles
-
Moment of product lifecycle opportunity: recent regulatory wins extending the approved duration of implantable options, combined with the entrance of next‑generation, lower‑copper IUD designs, are reshaping lifetime value calculations for existing portfolios.
Worldwide Long-Acting Reversible Contraception(LARC) Market -
Consolidation and concentration: the market remains concentrated among a small group of established players, making targeted alliances, licensing and selective M&A high‑impact levers for faster scale and channel access.
Worldwide Long-Acting Reversible Contraception(LARC) Market -
Policy and reimbursement tailwinds: recognition of LARC’s superior efficacy and favorable long‑term cost profile is increasingly reflected in reimbursement frameworks — but payer uptake timelines differ by market and program structure.
-
Supply chain and raw material risks: innovations that materially reduce copper content create risk/reward tradeoffs for manufacturers reliant on traditional copper‑IUD supply models and for procurement agencies.
What’s new in the competitive landscape (select highlights)
-
Product lifecycle extensions: One incumbent obtained regulatory approval in early 2026 to extend the labeled duration of an etonogestrel subdermal implant, shifting the competitive calculus around replacement cycles and follow‑on product economics. This kind of extension raises the bar for clinical evidence packages required from rivals and generics.
-
New entrants and licensing activity: The licensing of a next‑generation hormone‑free copper IUD to a major global vendor in 2026 — following earlier regulatory authorization of that device in 2025 — is accelerating commercialization plans for “low‑copper” designs that claim comparable efficacy with smaller metal loads and preloaded inserter ergonomics.
-
Public‑sector and low‑cost manufacturing: Established WHO‑prequalified implants and domestically scaled copper IUD producers remain critical suppliers for donor‑funded and national procurement, sustaining distinct demand channels where price and supply continuity matter most.
-
Regulatory and clinician requirements: For certain implants, regulator‑mandated training and certification for insertion and removal remain binding operational constraints; these influence adoption curves and drive demand for training services and digital support tools.
Report scope — what PW Consulting delivers
This report is designed as an operationally focused, strategy‑grade tool for corporate strategy, commercial planning, R&D prioritization and investor due diligence. Key inclusions are:
-
Market sizing and seven‑year forecasts (2026–2032) at a global level, with scenario modelling that quantifies sensitivity to adoption rates, duration extensions and price erosion.
-
Multi‑angle segmentation frameworks (by device type, geography and end‑user channel) and a reproducible methodology (bottom‑up market build corroborated with primary interviews and vendor validation). Note: the press summary intentionally omits detailed segment revenue tables — full segment datasets are available in the complete report on our website.
-
Practical go‑to‑market playbooks covering pricing, reimbursement engagement, tender strategy, and product launch sequencing for both branded and lower‑cost entrants.
-
Vendor profiles and scorecards — covering regulatory status, pipeline, manufacturing footprint, pricing posture and partnership appetite — calibrated to support M&A screening and commercial partnerships.
-
Supply‑chain risk matrix and mitigation options focusing on raw material exposure, contract manufacturing dependencies and scale‑up timelines for new inserter or frame technologies.
-
Regulatory and policy tracker with likely near‑term inflection points that can compress or expand addressable markets, including training/REMS requirements and public procurement policy shifts.
-
Appendices containing primary interview transcripts, unit cost models, and a reproducible sensitivity model clients can adapt for bespoke scenarios.
Strategic implications and recommended actions for 2026
-
Prioritize evidence-generation that targets duration and non‑inferiority claims. Clinical dossiers that demonstrate extended duration of effectiveness materially change lifetime revenue and substitution dynamics; sponsors should evaluate accelerated or adaptive trial pathways now to capture label extensions.
-
Pursue selective licensing and co‑commercial deals to accelerate access in markets where in‑country regulatory or procurement barriers are high. Licensing a differentiated, lower‑copper device or a preloaded inserter can rapidly expand channel presence without capex‑intensive manufacturing investments.
-
Design tender strategies aligned to public‑sector buying cycles. Manufacturers supplying public programs should model multi‑year demand and include contingency for price compression from generic entrants post‑patent expiry.
-
Hedge raw material risk. For companies exposed to copper price and supply volatility, develop alternative sourcing, vertical inventory strategies, and R&D plans that can validate lower‑metal formulations without compromising clinical outcomes.
-
Invest in training and services. Regulatory requirements for clinician certification create a stable revenue opportunity for training programs, digital insertion aids, and remote proctoring — all of which can accelerate uptake and reduce adverse event rates.
-
Prepare for intensified competition following patent expiries. Companies should map likely generic entrants, assess applicator patent coverage windows, and develop defensive strategies including product‑differentiation, patient support services, and locked‑in procurement contracts.
Competitive watchlist — who to monitor
The market is shaped by a mix of multinational pharmaceutical/device companies and regionally focused manufacturers. A small group of incumbents holds dominant share and extensive channel reach, while agile niche players are introducing clinically differentiated designs and lower‑cost supply options. Recent public moves — including device approvals, licensing deals and duration‑extension approvals — are concentrated among both global brands and specialist women’s health manufacturers. Our full report contains scored profiles, comparative matrices and likely partner/opportunity maps for each major player.
Risk scenarios that change the 2026 playbook
-
Accelerated generic entry following patent expirations could depress prices in private markets and compress margins unless sponsors secure service differentiation or protected applicator designs.
-
Slower than expected public procurement uptake or prolonged reimbursement negotiations could shift demand from premium branded options to lower‑cost alternatives, particularly in price‑sensitive markets.
-
Regulatory requirements that tighten insertion/removal training could slow adoption in ambulatory channels but create downstream commercial opportunities for accredited training providers and bundled service offerings.
-
Raw material shocks — for example, copper supply disruption or sudden price spikes — would advantage lower‑copper technologies and manufacturers that diversified sourcing early.
Why PW Consulting’s analysis is a strategic asset for 2026
Executives tell us they need intelligence that goes beyond point estimates — they need a playbook that links clinical evidence, regulatory timing, procurement mechanics and competitor intent to concrete commercial choices. This report is built to answer “what‑if” questions that matter in boardrooms and M&A committees: what happens to unit economics if a leading implant’s label is extended; where will procurement buyers shift if a lower‑copper, preloaded system achieves broader approvals; which suppliers are most exposed to copper price swings. We combine top‑down macro scenarios with bottom‑up primary research and vendor engagement so clients can model realistic outcomes and prioritize investments in 2026.
Next steps
This press preview highlights the strategic contours of PW Consulting’s Worldwide LARC Market report. It intentionally omits granular segment allocations and detailed vendor market shares to preserve the commercial value of the full dataset. For market participants preparing budgets, pipeline decisions, or M&A screening for 2026, the complete report delivers the data tables, scored vendor profiles, downloadable models and primary research transcripts necessary to move from insight to action.
For detailed analysis of this topic, please visit the official page: Worldwide Long-Acting Reversible Contraception(LARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Reusable Food Wrap Market to Reach USD 397.3 Million by 2032, Fueled by 7.15% CAGR
By PW Consulting, 2026-07-15
Worldwide Reusable Food Wrap Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As sustainability moves from consumer preference to regulatory requirement, the reusable food wrap market has shifted from a niche lifestyle segment to a strategic category for consumer goods, retail and foodservice operators. Our new PW Consulting report (base year 2025) quantifies this transition: the worldwide market expanded from roughly USD 173 million in 2020 to USD 245 million in 2025 and is forecast to approach USD 397 million by 2032, representing a compound annual growth rate of approximately 7.15% over the 2026–2032 forecast window. That trajectory reflects a convergence of policy-driven demand, improving unit economics for reusable products, and technology-enabled distribution models.
Worldwide Reusable Food Wrap Market
Why this briefing matters for 2026 strategy
For executives preparing budgets, portfolios and M&A pipelines in 2026, reusable food wraps are no longer an optional sustainability exercise: they are a defensible growth lever and a reputational hedge against accelerating single-use bans and procurement mandates. This preview highlights the actionable insights our full report provides — including scenario-tested forecasts, supplier scorecards, and go-to-market playbooks — while preserving the proprietary, segment-level intelligence available in the full dataset.
Worldwide Reusable Food Wrap Market
Market snapshot (macro view)
The category’s recovery and growth across 2020–2025 demonstrate resilience: a post-disruption rebound in consumer spending on eco-friendly kitchenware, and expansion into commercial channels. Looking ahead, our 2026–2032 base forecast anticipates steady expansion driven by regulatory tailwinds, retail channel evolution and product innovation. The market’s compound growth profile points to sizable upside for firms that capture distribution breadth, certification-led premiumization, and manufacturing scale.
Worldwide Reusable Food Wrap Market
What the full report delivers (practical, transaction-ready content)
Organizations purchasing the full PW Consulting study will receive a toolbox designed for immediate operationalization and board-level decision support. Key deliverables include:
- Bottom-up demand models by region, channel and product type (sensitive assumptions and scenarios included).
- Price and margin benchmarking across product types and geographies, with historical trajectories and short-term elasticity estimates.
- Supplier and OEM/ODM scorecards combining capacity, certifications (e.g., LFGB, REACH, FDA compliance), lead times and quality metrics.
- Regulatory impact matrix mapping near-term policy changes to addressable demand by channel and compliance risk.
- Commercial playbooks: D2C and retail launch templates, pricing ladders, subscription and refill mechanics, and private-label considerations for grocery and foodservice accounts.
- M&A and partnership shortlist: accretive targets identified using strategic fit, manufacturing footprint and brand equity filters.
Regulatory and demand dynamics shaping 2026
Regulation is the most visible accelerant. State-level mandates in the United States and similar moves globally are creating explicit commercial incentives to shift away from single-use packaging. Notable developments that feed directly into 2026 opportunity sizing include California’s extended producer responsibility and recyclability requirements, as well as state bans and limits on single-use food service ware that are coming online regionally. These policies are prompting foodservice buyers and retail procurement teams to re-evaluate packaging specifications and to pilot reusable alternatives — a procurement channel that will be decisive for broader adoption.
Supply-side realities and raw material dynamics
Margins and procurement strategy hinge on raw material dynamics. Beeswax — a core input for many traditional reusable wraps — has shown price volatility in visible transactions, underlining a procurement risk for producers reliant on mono-commodity supply chains. Global export price benchmarks and transaction-level trades in 2024–2025 indicate material cost pressures that will alter supplier economics unless firms diversify formulations (e.g., plant-based or silicone alternatives), lock in long-term supply agreements, or pursue vertical integration. Our full study includes a procurement playbook with hedging simulations and alternative-material sensitivity analyses to inform 2026 sourcing decisions.
Competitive landscape — what incumbents and manufacturers are doing
The market combines heritage artisan brands, digitally native challengers and cost-driven manufacturers. Established brands such as Bee’s Wrap and Abeego have leveraged certification, storytelling and premium retail placement; digitally native and zero-waste labels (including several Canadian and U.S.-based players) capitalize on direct-to-consumer familiarity and subscription models. At the same time, larger-scale manufacturers in Asia have built capacity for compliant OEM/ODM production, offering cost advantages and scale for private-label initiatives.
Strategic implications we observe from competitive movements:
- Brand differentiation is migrating from aesthetics and materials claims toward verifiable sustainability credentials and supply-chain transparency; brands without certified claims risk commoditization.
- Silicone and other non-beeswax formulations are expanding the set of addressable customers (including vegan and high-temperature use cases), creating an adjacent product innovation frontier.
- OEM/ODM partners with regulatory certifications and flexible minimums are enabling retailers and CPGs to test private-label offerings rapidly — an effective route to scale for buyers seeking margin capture.
Sector risk profile for 2026
Decision-makers must weigh three principal risks:
- Input-cost risk — material price volatility can compress margin if not actively managed through supply agreements or formulation diversification.
- Quality & safety risk — inconsistent product quality or lack of regulatory compliance can trigger reputational and legal exposure, particularly for foodservice partnerships.
- Market fragmentation risk — a proliferation of low-cost imports and undifferentiated private labels can depress prices and erode brand equity unless companies secure distribution advantages or IP-based differentiation.
Playbook for 2026 — recommended actions by capability
PW Consulting recommends a calibrated set of actions depending on your role and risk appetite:
- For consumer brands: accelerate certification and third-party testing, introduce a mid-tier silicone offer to capture new use cases, and pilot subscription replenishment to increase lifetime value.
- For retailers: pursue private-label rollouts in foodservice and grocery categories with limited-risk test-and-learn assortments; prioritize suppliers with proven compliance and scalable capacity.
- For manufacturers and OEMs: invest in traceability systems and lab certifications to win B2B contracts; evaluate forward-integration to capture a greater share of value.
- For investors and M&A teams: focus on targets that combine brand equity, supply resilience and attractive unit economics — and conduct diligence on raw material contracts and certification history.
What we’re watching in 2026
Near-term inflection points include the pace at which foodservice buyers implement reusable program pilots, the emergence of standardized certification frameworks for reusable packaging, and how quickly premium retailers convert regulatory pressure into category resets. We are also monitoring supply-chain consolidations and the entry of larger, multi-category sustainability brands that can cross-sell into reusable kitchenware.
Competitive profiles — illustrative, non-exhaustive
The full report contains vendor-by-vendor analysis and scored profiles. Examples of the types of players covered include:
- Heritage artisan brands with certification-led positioning and established retail distribution.
- Digitally native zero-waste labels that focus on direct-to-consumer growth and community-driven retention.
- Large-scale Asian OEM/ODM players offering certified manufacturing and flexible private-label services, capable of supporting rapid scaling for retail and foodservice customers.
Conclusion — the strategic window for 2026
Reusable food wraps sit at the intersection of regulation, consumer preference and supply-chain economics. For companies looking to make material progress on sustainability while protecting or expanding margin pools, 2026 is a pivotal year to translate pilots into scaled programs. The macro trajectory is favorable: the market has shown sustained growth from 2020–2025 and, under our central case, continues its expansion toward a substantially larger market by 2032. However, the pace and quality of that capture will be determined by firms’ choices on certification, sourcing and channel strategy.
Next steps
PW Consulting’s full Worldwide Reusable Food Wrap Market report provides the granular market maps, supplier scorecards, and executable playbooks needed to turn strategy into results. For procurement teams, business-unit leaders and investors that need transaction-grade analysis for 2026 planning, our database and advisory services can be deployed to produce tailored models, supplier negotiations support, and acquisition diligence briefs.
Contact PW Consulting to request the full dataset, scenario models, and proprietary supplier scorecards to inform your 2026 strategy and operational plan.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Lock With Cat's Eye Market to Reach USD 3,760.99 Million by 2032 at 13.5% CAGR — Asia Pacific Leads with USD 849.6 Million
By PW Consulting, 2026-07-15
Worldwide Smart Lock With Cat's Eye Market: Strategic Outlook for 2026 — PW Consulting Release
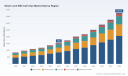
PW Consulting's latest market study, "Worldwide Smart Lock With Cat's Eye Market," equips senior leaders with the empirical context and strategic frameworks required to make high-consequence decisions in 2026. The market has moved from a nascent niche toward a scale opportunity: global revenues expanded materially through 2020–2025 and, with a modeled compound annual growth rate (CAGR) of 13.5% across our forecast horizon, are projected to roughly double again by the early 2030s. This press brief summarizes the report’s strategic value, core dynamics, competitive positioning, regulatory headwinds, and 2026-ready playbooks — while intentionally withholding granular segment-level figures to preserve our subscriber-first intelligence model.
Worldwide Smart Lock With Cat's Eye Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a pivotal inflection year. Early high-growth adoption of visual-integrated smart locks (cat's eye devices) has transitioned the segment from product innovation to commercialization and regulatory scrutiny. Executives who align product, channel, and compliance strategies now will capture asymmetric market share as mainstream adoption accelerates.
Worldwide Smart Lock With Cat's Eye Market -
Signal-to-noise optimization: The report synthesizes five years of historical market performance with a 2026–2032 forecast built on bottom-up adoption curves, device-level ASP trajectories, and platform integration economics. That allows procurement, product, and M&A teams to distinguish durable structural trends from transient hype.
Worldwide Smart Lock With Cat's Eye Market -
Operational levers: Beyond market sizing, PW Consulting provides executable playbooks — from GTM segmentation and OEM partnerships to device lifecycle cost models — enabling teams to convert market opportunity into measurable P&L outcomes.
Market trajectory: What the macro numbers reveal
Our macro analysis shows the smart lock with cat's eye market has grown substantially since 2020. Using USD-denominated revenues, the market more than doubled in the first half of the decade as early adopters embraced video-integrated access solutions. Our modeling indicates that by 2026 the market continues to expand at a double-digit pace and, under baseline assumptions, will scale meaningfully through 2032 as hardware costs decline, AI-driven features improve conversion, and retrofit cycles for multifamily and single-family housing accelerate.
Importantly, market concentration metrics indicate a moderately fragmented vendor landscape: the three largest players hold a meaningful but not dominant share, while the top five consolidate additional reach. For corporates this means attractive windows exist for scale-focused entrants with distribution advantages or for incumbents to pursue bolt-on acquisitions that improve margins and platform stickiness.
Competitive dynamics: product, platform, and channel
The competitive set is heterogeneous, spanning multinational device OEMs, platform enablers, and specialized device integrators. Leading device manufacturers increasingly embed wide-angle visual capture, AI-based human detection, night vision, and multi-modal unlocking to differentiate on convenience and perceived safety. Platform providers are moving upstream by offering standardized SDKs, cloud services, and white-label solutions that accelerate go-to-market for OEMs and installers.
-
Xiaomi and Huawei: These consumer-tech incumbents emphasize vertical integration — combining wide-angle cat's eye cameras, AI detection, and large indoor displays to deliver a unified home security experience. Rapid product cycles and ecosystem bundling (smart home hubs, cameras, and voice assistants) are their competitive strengths.
-
Global legacy brands (e.g., Yale under ASSA ABLOY): These firms blend mechanical access credibility with digital features, targeting trust-conscious buyers through channel partnerships and certified installer networks.
-
Platform and ODM players (e.g., Tuya): Platform players enable OEM scale by providing firmware, cloud connectivity, and app ecosystems across multiple manufacturers — lowering time-to-market but introducing differentiation challenges.
-
Specialists and regional OEMs: Niche manufacturers are advancing cost-efficient camera modules, local-language UX, and retrofit-friendly mechanical interfaces for diverse housing stock.
Recent product launches in 2024–2025 underscore these dynamics: several major vendors introduced new cat's eye-enabled smart locks with expanded viewing angles, enhanced indoor screens, and AI detection suites — signaling a shift from novelty features to baseline customer expectations.
Regulatory and privacy dynamics shaping commercial risk
Smart locks with integrated cameras sit at the intersection of consumer safety and data protection, and regulators are reacting at different speeds across jurisdictions. Several regulatory vectors have immediate strategic implications for 2026:
-
Data minimization and retention: Jurisdictions with robust privacy regimes treat video captured by door devices as highly sensitive. Product roadmaps must include configurable retention policies, on-device anonymization modes, and explicit consent flows to avoid non-compliance risks.
-
Positional privacy and scope: Rules that prohibit cameras from pointing at neighboring units or public thoroughfares require engineering and installation controls — both in hardware mechanical design and in commissioning processes for installers.
-
Tenant protections: Urban tenant protection laws are increasingly mandating physical-key options, data minimization, and transparent notice and consent procedures — influencing multi-dwelling unit (MDU) deployment strategies.
Notably, some national standards remain narrowly focused on mechanical safety and lag in defining consistent requirements for recording, triggering, and storage practices of visual-enabled door devices. This regulatory patchwork creates first-mover advantages for vendors that can offer compliance-by-design solutions and installer training programs for complex markets.
Report deliverables: what PW Consulting provides (high level)
Our full report is designed as an operational toolkit for corporate strategy, product, and M&A teams. Key components include:
-
Market sizing and forward-looking demand models (historical 2020–2025 and forecast 2026–2032) with scenario analysis reflecting alternative macro, component-cost, and regulatory outcomes.
-
Investment-grade competitor dossiers covering product roadmaps, channel strategies, and recent launches — enabling rapid benchmarking and opportunity mapping.
-
Commercial playbooks: pricing frameworks, installer economics, subscription vs. one-time revenue models, and partner co-investment structures that accelerate adoption in target end markets.
-
Technology and component deep dives: camera modules, edge-AI compute, battery strategies, and trade-offs for on-device versus cloud inference in latency and privacy-sensitive contexts.
-
Regulatory risk matrices by major jurisdiction and a compliance checklist for product and installation teams to operationalize privacy-by-design for 2026 deployments.
-
M&A and partnership screening templates with priority targets, integration playbooks, and a valuation sensitivity grid to expedite diligence.
To preserve the actionable value of the report for subscribers, detailed segment and regional breakdowns, channel-level unit economics, and company-specific revenue splits are reserved for report access.
Strategic recommendations for 2026
Based on our synthesis, we advise executive teams to pursue a three-track strategy in 2026: invest in product defensibility, orchestrate channel scale, and harden privacy governance.
-
Product defensibility: Prioritize edge AI and privacy-preserving features (on-device person detection, selective recording) to reduce cloud dependency while meeting privacy expectations. Differentiate through user experience touchpoints — large indoor displays, low-latency alerts, and robust onboarding for installers.
-
Channel orchestration: Build hybrid distribution strategies. Retail and e-tail channels serve mainstream consumers; certified installer networks and strategic MDU partnerships unlock higher ACV customers. Consider white-label partnerships with platforms to expedite reach in markets where brand recognition is nascent.
-
Privacy and compliance as market access: Treat regulatory compliance as a market-entry enabler rather than a cost. Invest in modular compliance stacks and installer certification to pre-empt local regulations and win procurement opportunities in privacy-sensitive segments such as MDUs and commercial real estate.
Where PW Consulting adds unique value
PW Consulting combines rigorous quantitative models with practitioner-focused deliverables. Our strength is translating device-level technical decisions into P&L and risk-exposure outcomes — enabling boards and executive teams to make rapid, defensible decisions. We also provide bespoke scenario analysis during diligence or strategic planning cycles, isolating the economic impact of feature choices (e.g., inclusion of on-device storage vs. cloud subscription) under different regulatory regimes.
Next steps and how to access the report
For leaders preparing budgets, product roadmaps, or M&A pipelines in 2026, this report functions as a decision-grade resource. PW Consulting has intentionally reserved detailed regional, application, and type-level figures within the subscriber report to maintain the report’s commercial integrity and to ensure clients receive the most relevant, tailored intelligence.
To download the complete report, including the data tables, regional and application splits, and full competitor annexes, please visit our report page. Clients can also request a tailored briefing with our analysts, who will walk through scenario models and recommend action paths aligned with your corporate priorities.
Closing observation
The smart lock with cat's eye market is no longer purely experimental. By 2026, it will be judged on how well vendors balance convenience-driven features with robust privacy controls and installer-centric economics. For companies that move early to codify compliant product architectures, scale distribution partnerships, and embed privacy-by-design, the next three years offer structural growth and consolidation opportunities. PW Consulting’s report is crafted to be the operational compass for that journey.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Lock With Cat's Eye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mosquito Repellent Water for Pregnant Women Market to Reach USD 456.24 Million by 2032 at a 7.5% CAGR; Asia Pacific Leads with USD 126.21M
By PW Consulting, 2026-07-15
Worldwide Mosquito Repellent Water For Pregnant Women Market — Strategic Outlook for 2026
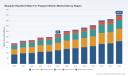
PW Consulting’s latest market study on the Worldwide Mosquito Repellent Water for Pregnant Women market (base year 2025, forecast period 2026–2032) delivers a focused, decision-ready view for executives planning 2026 strategies. The global market—estimated at USD 275.0 Million in 2025—is projected to expand to roughly USD 303.6 Million in 2026 and follow a 7.5% CAGR through the forecast window, reflecting accelerating demand driven by health guidance, product innovation and shifting channel economics. This briefing synthesizes the study’s strategic implications while reserving granular segment-level tables and proprietary model outputs for subscribers of the full report.
Worldwide Mosquito Repellent Water For Pregnant Women Market
Why this market matters to leadership teams in 2026
-
Clear regulatory tailwinds: Public health authorities (CDC, EPA, ACOG and related bodies) have continued to clarify safety guidance for pregnant women, explicitly endorsing specific EPA-registered actives when used as directed. That clarity reduces consumer hesitation and creates a stable platform for evidence-based marketing and clinical communication.
Worldwide Mosquito Repellent Water For Pregnant Women Market -
Health risk awareness and preventative healthcare: As vector-borne disease risk remains a prominent public-health concern in numerous geographies, pregnant women and caregivers are a priority buying cohort—one that values demonstrated efficacy and safety above anecdotal "natural" claims.
Worldwide Mosquito Repellent Water For Pregnant Women Market -
Product innovation is differentiating: Manufacturers combining proven repellents (picaridin, DEET, IR3535 and PMD/OLE where appropriate) with skin-care adjuncts (e.g., humectants and hyaluronic agents) are achieving higher trial and repurchase among sensitive-skin users—an important competitive lever in the maternity category.
-
Channel transformation: Evolving retail dynamics—especially omnichannel and subscription models—are reshaping how pregnant consumers discover and repurchase repellents; 2026 will be a year where digital-first pilots must demonstrate unit economics to scale.
What PW Consulting’s report delivers (practical, transaction-ready content)
-
Robust market-sizing and forward-looking forecast model calibrated to 2020–2025 historicals and stress-tested across three macro scenarios for 2026–2032.
-
Granular segmentation frameworks (product formulation, distribution channel, and use-case archetypes) and proprietary consumer-insight clusters that reveal purchase triggers, channel preferences, and messaging sensitivities for pregnant consumers and their influencers.
-
Regulatory and safety dossier mapping: a compliance playbook that translates CDC/EPA guidance into label claims, clinical support strategies, and risk-mitigation checklists for packaging and marketing.
-
Supply-chain and sourcing heat map focused on active-ingredient availability, single-supplier risks, and formulation inputs (including trends toward combining synthetic actives with skin-conditioning agents).
-
Competitive benchmarking and value-pool analysis, including CR-level concentration metrics, channel profitability matrices, and a prioritized list of white-space opportunities for SKUs, packaging and service bundling.
-
Go-to-market playbooks by distribution archetype and a tactical marketing roadmap with measurable KPIs for 6-, 12- and 24-month horizons.
-
M&A screening templates, deal-values sensitivity checks (revenue and margin accretion scenarios), and post-merger integration quick wins for bolt-on acquisitions in formulation, contract manufacturing and digital retail capability.
Competitive landscape — strategic read on core players
-
PARA'KITO (France; with notable U.S. operations): Positioned as a family-oriented brand, PARA'KITO leverages an approachable product design and claims that balance everyday usability with risk/benefit messaging for sensitive groups. Their strength lies in consumer-facing packaging and cross-border brand recognition; the primary strategic imperative is to convert awareness into repeatability via proven efficacy claims and stronger clinical positioning for pregnant users.
-
Sawyer Products (United States): Known for Picaridin and DEET portfolios, Sawyer occupies a performance-first niche with explicit safety communication targeted at pregnant women. Their technical credibility is a competitive advantage; success for Sawyer in 2026 will depend on scaling consumer messaging and building trust in mainstream retail channels beyond outdoor-enthusiast cohorts.
-
SC Johnson — OFF! brand (United States): A legacy mass-market incumbent with wide distribution, OFF! benefits from scale, EPA-registered formulations and a well-known brand name. The strategic challenge is to modernize maternal safety narratives and capture premiumization opportunities without diluting brand equity.
-
Repel (Spectrum Brands, United States): Offers high-concentration DEET products and positions safety guidance prominently. Repel’s opportunities lie in diversifying formulations toward skin-compatible actives and expanding into curated maternity bundles and clinical channels.
-
MURO (South Korea): A regional innovator combining icaridin (picaridin) with skin-care additives like sodium hyaluronic acid. MURO exemplifies the new-product archetype that fuses efficacy with dermal comfort—an increasingly important differentiator for pregnant consumers and caregivers.
Overall market concentration is moderate: the top three and top five players capture material shares, but the field remains contestable for differentiated products and channel specialists. The CR3 and CR5 metrics in the report quantify this dynamic and underpin tactical recommendations for both incumbents and new entrants.
Regulatory and safety dynamics — practical implications
-
Authoritative guidance now frames the market: EPA-registered repellents with certain actives are deemed safe and effective for pregnant women when used according to label instructions. This removes ambiguity and enables evidence-based product positioning.
-
DEET (up to commonly registered concentrations) retains a strong efficacy and safety profile in peer-reviewed literature; however, perception risks around "chemical" ingredients persist among some consumer segments—requiring clear, science-backed communication.
-
Labeling, clinical support and health-professional outreach will be decisive. Compliance teams should prioritize harmonized labeling, pregnancy-safety FAQs, and targeted clinician engagement programs to convert institutional endorsement into retail traction.
Formulation and product trends to watch in 2026
-
Hybrid formulations that pair proven repellents (picaridin, low-concentration DEET, IR3535) with humectants and gentle skin conditioners are achieving higher acceptance among pregnant consumers and those with sensitive skin.
-
Manufacturers will increasingly invest in clinical comfort studies (dermal tolerance, pregnancy-specific safety substantiation) to support premium pricing and to enable pharmacy and prenatal-clinic distribution partnerships.
-
Natural or "citronella-only" claims remain attractive for a subset of buyers but carry efficacy trade-offs; strategic players will focus on bundling education with products rather than relying on natural positioning alone.
Commercial playbook: prioritized actions for 2026
-
Product: Release a maternity-tier SKU set with clear, evidence-backed safety claims and skin-care benefits; validate with small-scale clinical or tolerability studies to support clinician endorsements.
-
Channel: Pilot subscription and prenatal-bundle offers via digital channels while deepening presence in pharmacy and obstetric clinic networks through professional education and sampling.
-
Marketing & Communication: Lead with authoritative guidance (CDC/EPA) in consumer-facing content, employ testimonial evidence, and invest in targeted educational campaigns to reduce perceived chemical risk.
-
Supply & Risk: Secure multi-source supply for key actives, prioritize contract manufacturing relationships that meet regulatory audit standards, and institute raw-material price-hedging where appropriate.
-
M&A: Look for bolt-on assets that bring formulation IP, clinical data, digital-direct-to-consumer capabilities, or regional distribution strength that accelerates market access.
How PW Consulting can help
For leadership teams evaluating product launches, portfolio prioritization or deal activity in 2026, PW Consulting offers implementation-focused advisory: tailored market-entry roadmaps, acquisition screening and diligence support, pricing-architecture models, and clinician-outreach playbooks derived from our proprietary consumer cluster data and forecast scenarios.
Next steps — where to find the full intelligence
This press summary is designed as a strategic preview. The full PW Consulting Worldwide Mosquito Repellent Water For Pregnant Women Market report contains the complete forecasting model, segmented demand curves, regional and channel tables, competitor scorecards, and downloadable Excel workbooks that underpin the conclusions summarized above. For access to the complete dataset, proprietary segmentation, and bespoke advisory engagements for 2026 planning, please consult the report landing page and contact PW Consulting for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Mosquito Repellent Water For Pregnant Women Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 6.94% CAGR as Global Child-Resistant Blister Lidding Film Market Expands Through 2032
By PW Consulting, 2026-07-15
Worldwide Child Resistant Blister Lidding Film Market — Strategic Preview for 2026 Decision-Makers
Executive summary
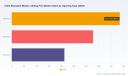
PW Consulting’s latest market study on the Worldwide Child Resistant Blister Lidding Film Market provides a forward-looking, actionable briefing for executives planning strategic moves in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecasting horizon, the report quantifies an established global market that expands at a steady compound annual growth rate (CAGR) of 6.94%. Our baseline analysis pegs the market at approximately USD 975 million in 2025 with a projected rise to roughly USD 1,559 million by 2032. Beyond headline figures, the research synthesizes regulatory shocks, raw-material dynamics, supplier concentration, and innovation vectors that will define competitive advantage over the next planning cycle.
Worldwide Child Resistant Blister Lidding Film Market
Why this matters for 2026 strategy
Child-resistant blister lidding films sit at an intersection of healthcare safety, regulatory compliance, sustainability mandates, and material science. For corporate strategists, procurement heads, R&D leaders and M&A teams, the market offers three immediate strategic inflection points in 2026:
Worldwide Child Resistant Blister Lidding Film Market
- Regulatory-driven product spec escalation — CPSC and European standards continue to tighten performance and usability constraints, forcing redesigns that affect cost, bill-of-materials and supplier qualification time.
- Supply-side cost pressure and recycling mandates — aluminum remains a critical raw input and its price dynamics, together with recycled-content rules, materially affect life-cycle cost and product architecture choices.
- Consolidation and capability concentration — the market reveals a mid-level concentration where a handful of players account for a disproportionate share of specialized capability, creating both partnership and competitive risk for new entrants.
Core market dynamics shaping 2026 decisions
Four forces will dominate boardroom conversations next year:
Worldwide Child Resistant Blister Lidding Film Market
- Regulatory compliance as a product requirement, not a checkbox. North American and European child-resistance protocols (including CPSC Protocol 1700.20 and EN 14375) collectively raise the bar for both child-test failure rates and adult usability durability. Compliance timelines and repeat-certification cycles are shortening, driving demand for pre-validated film systems and contract test services.
- Materials and cost volatility. Primary lidding constructions continue to rely on thin-gauge aluminum foil laminated to polymers. Aluminum pricing remains a material lever — our reference datasets show recent market pricing pressure that must be modeled explicitly in procurement and product-cost scenarios. Packaging tax regimes and recycled-content mandates in key jurisdictions further complicate cost-to-serve calculations.
- Sustainability and regulation converge. Extended producer responsibility (EPR) and packaging waste directives are pushing customers to request recyclable or mono-material solutions. Manufacturers that can demonstrate viable, certified recyclable constructions will gain access to procurement panels and tenders where environmental criteria are weighted heavily.
- Supplier concentration and capability clusters. The market displays moderate concentration: the top three suppliers capture a meaningful share of specialty capability while the top five increase that footprint substantially. This creates a supplier landscape where strategic partnerships, dual-sourcing and qualification speed are material competitive levers.
Competitive landscape — who matters and why
Our competitive assessment highlights several global and regional players who set technical, commercial and compliance benchmarks. PW Consulting’s report profiles each firm with a focus on capability, strategic intent, and tactical implications for customers and competitors:
- Amcor plc (Melbourne). A leader in compliant child-resistant lidding films, Amcor’s development of recyclable child-resistant solutions positions it well with sustainability-focused pharmaceutical customers. Expect them to leverage scale in commercialization and regulatory documentation to win larger tenders.
- Constantia Flexibles (Vienna). Constantia’s strength in high-barrier aluminum lidding foils and multi-layer constructions makes them a go-to for high-spec Rx blister programs. Their visibility at major trade shows signals continued investment in product portfolio and market positioning.
- Tekni-Plex (Wayne, PA). Tekni-Plex’s thermoformable solutions and documented compliance work for senior-friendly and CPSC protocols make them attractive for customers prioritizing usability alongside child safety. Continued certification updates indicate a focus on regulatory alignment as a selling point.
- Winpak Ltd. (Winnipeg) and Sonoco Products Co. (Hartsville). Both companies emphasize high puncture resistance and integrated barrier films, serving medical and pharmaceutical segments where durability and shelf life are paramount.
- Alpine Packaging, ProAmpac, Hood Packaging. These regional and specialty suppliers differentiate on customization, sustainable laminates and patented peel/reseal or peel-push mechanics, offering customers tailored solutions for OTC and Rx portfolios.
Recent corporate events — from product launches of recyclable CR lidding films to trade-show demonstrations and certification milestones — confirm that incumbents are executing both incremental innovation and market signaling strategies that materially affect procurement timelines and qualification hurdles.
What PW Consulting’s report provides — practical, not academic
This is not a product catalogue. The report is structured to be used by decision-makers on the move. Key operational deliverables include:
- Forward-looking scenario models calibrated to 2020–2025 history and stress-tested through 2032, enabling CFOs to model capex, COGS and margin impact under multiple aluminum-price and regulatory regimes.
- A supplier risk-and-opportunity matrix that scores vendors on technical capability, regulatory documentation, sustainability roadmap and commercial flexibility to inform dual-sourcing and preferred-supplier strategies.
- Practical procurement playbooks for rapid supplier qualification, including test-bench templates for verifying CPSC and EN compliance and recommended timelines for sample-to-qualification cycles.
- R&D and packaging-engineering roadmaps that prioritize material substitution, recyclability pathways and adult-usability optimization to reduce rework and reduce recall risk.
- M&A and partnership decision frameworks that identify where bolt-on acquisitions versus strategic alliances deliver the fastest route to capability ownership.
Regulatory and cost levers — what you must model now
Our analysis underscores two modeling imperatives for 2026 planning cycles:
- Simulate regulatory-compliance cost trajectories. CPSC Protocol 1700.20 and EN 14375 impose both child-safety thresholds and adult-usability durability tests; design changes to meet those thresholds often carry material cost and cycle-time implications that procurement must forecast into multi-year contracts.
- Incorporate packaging taxation and recycled-content mandates into product cost and portfolio rationalization. Regional tax instruments — for example, penalties for low recycled content in plastic packaging — and 2030 recycled-content milestones materially change the attractiveness of polymer-rich constructions. These should be embedded in TCO models rather than treated as peripheral risks.
Actionable recommendations for 2026 (short list)
- Prioritize supplier pre-qualification now. Shortlist suppliers that offer pre-validated CPSC/EN compliant constructions and request accelerated qualification programs tied to contract pricing.
- Run material-substitution pilots with explicit tax and recycling constraints. Select two test SKUs to re-engineer for recyclable mono-materials or reduced polymer content and track cost, yield and certification timelines.
- Negotiate flexible pricing clauses linked to primary raw-material indices. Given aluminum price volatility, include indexation or shared-cost mechanisms to avoid margin erosion during price spikes.
- Design procurement scorecards that value regulatory documentation speed and sustainability roadmaps. Do not chase lowest initial price at the expense of time-to-market and compliance burden.
- Assess M&A targets for complementary technical patents and test-facility ownership. Small acquisitions that reduce qualification time can produce outsized returns during product rollouts.
Methodology, data integrity and market concentration
PW Consulting’s study consolidates primary interviews with packaging engineers and procurement heads, supplier financials, trade-show intelligence, regulatory standards, and commodity-price inputs. The market exhibits measurable concentration: the top three suppliers command a meaningful portion of specialized capability, and the top five increase that footprint considerably. This concentration pattern should inform deal diligence, contingency sourcing and commercial negotiation strategies.
What we intentionally omit here — and why
In keeping with a “trailer” approach, this briefing purposefully demonstrates analytical depth while withholding certain granular segment-level figures and region-by-region application breakdowns. Those specifics are embedded in our full report and model sets to ensure licensed access control and to support confidential use by client teams. Executives who need the detailed segmentation, supplier scoring matrices, unit-cost build-ups and downloadable scenario models will find them in the complete PW Consulting report.
Next steps — how to use this intelligence in Q1 2026
For immediate action in the first quarter of 2026, we recommend three parallel tracks: (1) run a two-SKU pilot to test recyclable constructions and new supplier engagement; (2) update procurement contracts to include commodity-indexation clauses; and (3) initiate a short-list and RFP process focused on suppliers with documented CPSC and EN compliance pathways. These steps convert market insight into defensible commercial action.
Access the full analysis
PW Consulting’s full Worldwide Child Resistant Blister Lidding Film Market report contains the complete datasets, downloadable financial models, supplier profiles and compliance playbooks needed to move from insight to execution. For licensing and access details, or to commission a tailored executive briefing that maps the findings to your product portfolio, please visit our publication page or contact our industry practice team.
For detailed analysis of this topic, please visit the official page: Worldwide Child Resistant Blister Lidding Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isopropyl Biphenyl Heat Transfer Fluid Market Poised for 5.48% CAGR — From USD 238.5M in 2025 to USD 346.6M by 2032
By PW Consulting, 2026-07-15
Isopropyl Biphenyl Heat Transfer Fluid Market — Strategic Insights for 2026 Decisions
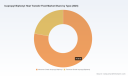
PW Consulting today releases an executive industry briefing drawn from our full Isopropyl Biphenyl Heat Transfer Fluid Market report (base year 2025, forecast 2026–2032). The market is in a steady expansion phase: from a measured industry size in 2025 the sector is forecast to grow at a compound annual growth rate (CAGR) of 5.48%, reaching materially higher valuations by the end of the forecast window. For leadership teams planning 2026 capital allocation, supplier strategies, or product roadmaps, the analysis offers targeted, actionable intelligence that bridges technical performance characteristics with commercial levers and regulatory realities.
Isopropyl Biphenyl Heat Transfer Fluid Market
Why this report matters in 2026
-
Accelerating thermal demand. Industrial electrification, concentrated solar power (CSP) projects, and expanded waste-heat-recovery initiatives are increasing demand for reliable, high-temperature heat transfer fluids (HTFs). Decision-makers need a clear view of the size, trajectory, and supplier dynamics to prioritize investments.
Isopropyl Biphenyl Heat Transfer Fluid Market -
Risk concentration and supplier selection. The market exhibits a meaningful degree of concentration among a small set of established suppliers. Choosing the right partner, or designing a robust multi-supplier procurement strategy, will materially affect uptime, warranty exposure, and TCO in 2026 and beyond.
Isopropyl Biphenyl Heat Transfer Fluid Market -
Regulatory and legacy substitution dynamics. Isopropyl biphenyl-based fluids have been adopted historically as safer alternatives to legacy polychlorinated biphenyl (PCB) solutions. Regulatory scrutiny, environmental compliance, and insurance requirements continue to shape procurement and product development choices.
-
Opportunity windows for OEMs and specialty chemical players. Firms that align product chemistry, service offerings (e.g., fluid management), and regional supply footprints can convert technical differentiation into durable commercial advantage.
What’s inside the full report
-
Comprehensive market sizing and forecast (historical series through 2025; forecast 2026–2032) with scenario variants reflecting macro and project-driven outcomes.
-
Methodology note: blended top-down and bottom-up modeling informed by plant-level capacity checks, commercial tender data, and primary interviews with procurement, R&D and project owners.
-
Competitive landscape and supplier benchmarking covering global incumbents and regional challengers, including product portfolios, stated maximum bulk temperature limits, and service coverage.
-
Supply-chain and feedstock analysis with production capacity mapping and raw-material risk matrices.
-
Technical profiles: formulation performance, thermal stability comparisons, and operating envelopes for typical industrial and CSP use cases.
-
Regulatory impact assessment and compliance playbook, including legacy risk mitigation for users transitioning from banned PCBs.
-
Commercial playbooks: procurement strategies, conditioning service models, aftermarket revenue levers and M&A target screening criteria.
-
Executive-ready dashboards, downloadable financial templates, and a prioritized action checklist for 90/180/360‑day initiatives.
Data-driven headline findings
Key macro dynamics are clear and consistent across the modelling universe. After a multi-year rise through the early 2020s, the market in our base year (2025) reflects increased adoption across industrial heat and specialty cooling segments. The forecast corridor we model projects compound growth at 5.48% annually through 2032, driven by steady expansion in industrial process heating, continued CSP deployments where applicable, retrofits for legacy fluids, and incremental adoption in electronics and dielectric cooling niches. Importantly, the projection set is not a single-line estimate but a set of plausible scenarios—baseline, upside and downside—each tied to defined assumptions on project flows, regulatory interventions, and raw-material availability.
Competitive landscape — what executives need to know
The market comprises both global specialty-chemical incumbents and regionally focused manufacturers. Several firms have established reputations and differentiated technical offerings that matter to end-users:
-
Eastman Chemical Company (Kingsport, TN) is a clear benchmark for scale and global distribution. Its Therminol brand is positioned as a high‑purity HTF with an emphasis on thermal stability and global service coverage—attributes that reduce execution risk for multinational projects.
-
Nippon Chemical Texas Inc. (NCTI) (Texas) offers formulations tuned for extended high-temperature envelopes and sub-zero operability—features attractive to projects with wide thermal cycles.
-
Dalian Richfortune Chemicals and Jiangsu Zhongneng Chemical Technology represent Chinese suppliers that combine local project experience (including CSP) with competitive pricing and regional logistics advantages.
-
Manto Chemistry (Jiangsu) has signalled meaningful upstream commitment: we validated an annual dedicated production capacity figure for isopropyl biphenyl (the principal feedstock) that supports medium-scale supply agreements—an important consideration for buyers assessing capacity security.
-
Rütgers GmbH represents European specialty fluid know‑how with product variants tuned for very high temperature service conditions.
Market concentration metrics indicate that a small number of suppliers collectively control a substantial share of the global market. This concentration has practical implications: pricing resilience, counterparty negotiation power, and the relative attractiveness of forward‑looking integration strategies (e.g., captive feedstock, tolling arrangements, or long‑term take-or-pay contracts).
Regulatory and safety dynamics
Historical regulatory action—most notably the ban on PCB manufacture and distribution decades ago—was a major catalyst for adoption of alternative synthetics such as isopropyl biphenyl mixtures. Those historical shifts are instructive for 2026 decision-makers: transitions away from legacy chemistries were driven less by immediate cost and more by regulatory certainty, long-term liability reduction and insurance access. Today, the regulatory conversation centers on lifecycle impacts, waste handling protocols, and ensuring formulations meet evolving environmental and workplace‑safety standards. Firms should incorporate regulatory scenario planning into product launches and procurement contracts to avoid stranded assets and unexpected remediation costs.
Strategic recommendations for 2026 decision-makers
-
Prioritize supplier qualification over lowest-cost procurement. Given market concentration and the role of HTF integrity in plant uptime, the short-term premium for certified, well-documented fluids and service support typically yields lower total cost of ownership.
-
Design multi-layered sourcing strategies: combine a primary supplier with a validated secondary source and mapped freight contingencies to de-risk supply interruptions.
-
Assess vertical moves selectively. For mid‑to-large industrial users, partial backward integration (e.g., long-term feedstock contracts or tolling agreements) can stabilize supply and margins. Our models show the inflection point where such investments become accretive under different demand-growth scenarios.
-
Invest in fluid‑management service capabilities. Service contracts that include monitoring, periodic analysis and end-of-life handling reduce operational risk and are a differentiator for EPCs and licensors bidding on turnkey projects.
-
Embed regulatory scenario clauses in contracts. Include change‑of‑law, phase-out and waste-disposal cost allocation to protect against asymmetric regulatory risk shifting.
-
Pursue product and application adjacencies. High‑purity formulations and fluids optimized for extreme temperature ranges can open higher-margin niches such as specialty electronics cooling or advanced thermal storage systems.
-
Use the 90/180/360 decision framework we provide: immediate supplier validations and short-term hedges, mid-term capex and product trials, and long-term strategic options (JV, M&A, or integration) mapped to quantified scenario triggers.
How PW Consulting can support your 2026 agenda
Our full report contains the proprietary datasets, supplier scorecards and scenario models referenced here and is designed to be a practical toolkit for CEOs, procurement heads, R&D leaders and project sponsors. PW Consulting offers bespoke engagements that include supplier due diligence deep dives, procurement playbook roll-outs, bespoke scenario stress tests for capex approvals, and M&A target screens customized to your strategic threshold and geographic focus.
Methodology & data integrity
The market synthesis combines public filings, vendor literature, plant-capacity verification, and in‑market interviews across the value chain. We base the report on a historical series through 2025 with a forecast window covering 2026–2032; our headline CAGR (5.48%) reflects the baseline scenario. For transparency, the report documents assumptions underlying each scenario and provides sensitivity tables so executives can adapt conclusions to their own risk tolerances and operational parameters.
In sum, the Isopropyl Biphenyl HTF market presents a measured growth opportunity with important structural considerations: supplier concentration, feedstock security, and regulatory dynamics. Executives who invest in validated supplier relationships, service capabilities, and scenario-based strategic planning in 2026 will position their organizations to capture upside while minimizing operational and regulatory exposure. For access to the complete dataset, supplier scorecards, and the downloadable decision playbook, visit the PW Consulting report landing page or contact our industry practice to schedule a bespoke briefing.
For detailed analysis of this topic, please visit the official page: Isopropyl Biphenyl Heat Transfer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


