



PW Consulting: MMA‑Triazine H2S Scavengers Market Forecast to Reach USD 271.5 Million by 2032, Expanding at a 6.19% CAGR
By PW Consulting, 2026-07-13
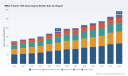
MMA Triazine H2S Scavengers Market — Strategic Intelligence for 2026 Decision‑Makers
As sour hydrocarbon streams remain a persistent operational and regulatory challenge across oil & gas production, midstream transport and downstream processing, chemical scavengers built on MMA (monomethylamine) triazine chemistries are reasserting their strategic importance. PW Consulting’s new market study — grounding historical performance (2020–2025) and delivering a forward view for 2026–2032 — equips executives with the evidence and playbooks needed to convert H2S management from a cost center into a controllable, optimizable element of asset strategy.
Mma Triazine H2S Scavengers Market
Market snapshot: a resilient growth trajectory
The MMA triazine H2S scavengers market has demonstrated steady expansion through the base year (2025) and is projected to continue on a multi‑year growth path. Our model, built on detailed shipment, pricing and application-layer demand analysis, shows a compound annual growth rate of approximately 6.19% over the forecast window. The total market value has moved markedly since 2020 and our scenario worklines indicate continued expansion through 2032 under central and upside demand scenarios.
Mma Triazine H2S Scavengers Market
For 2026 planning cycles, this translates into two simple truths: purchasing exposures will remain material to upstream and midstream operators, and supplier and formulation choices will materially affect asset operating costs, permit compliance, and long‑term remediation liabilities.
Mma Triazine H2S Scavengers Market
What this report contains — practical intelligence for operators, purchasers and investors
- Market sizing methodology and transparent assumptions — reconciled shipment data, producer revenues and downstream consumption models so you can trace every top‑line number back to inputs.
- Demand drivers by application class (upstream, midstream, downstream) and by formulation family — including operational performance comparisons between water‑based and solvent‑based MMA triazine solutions, and cost‑per‑kg of active comparisons under typical field conditions.
- End‑to‑end supply‑chain mapping — feedstock origins, synthesis routes (monomethylamine + formaldehyde condensation chemistry), manufacturing bottlenecks, and logistics constraints that influence landed costs and service levels.
- Regulatory and environmental risk matrix — granular analysis of spent scavenger by‑products (including regulatory classifications that affect disposal paths), OSHA/EPA compliance vectors for North American operators, and incremental compliance costs under revised EU frameworks.
- Competitive benchmark and capability matrix — technology positioning, on‑site blending capacity, formulation portfolios and route‑to‑market strengths for the principal suppliers active in 2025.
- Practical procurement playbooks — fixed/variable hedging options, contractual clauses for quality/acceptance testing, KPIs for supplier performance, and contingency sourcing templates.
- Strategic scenarios and sensitivity analysis — price, feedstock and regulatory stress tests across best‑, base‑ and adverse‑case pathways to 2032, with recommended action timelines for 2026 decision points.
- Executive decision toolkit — one‑page readiness checks, CAPEX/OPEX tradeoff matrices for on‑site blending vs. delivered product, and a prioritized list of pilots and quick wins.
Competitive landscape — who shapes supply and why their moves matter
The market evidences moderate concentration: the top three producers account for a substantial share of revenue‑weighted supply, and the top five further increase that share materially. This concentration creates supplier leverage in contract negotiations but also concentrates technology leadership in areas such as higher‑activity formulations, on‑site blending systems, and customized additive packages.
- Foremark Performance Chemicals (League City, Texas) — recognized for its PureMark® family and targeted formulations for mercaptan removal and liquid hydrocarbon streams. Foremark’s product breadth and US operational footprint make it a go‑to for large producers seeking field‑proven chemistries.
- Hexion Inc. (Columbus, Ohio) — a longstanding specialty chemical supplier with multi‑chemistry capabilities. Hexion’s strength lies in integrated supply and technical support for crude treatment applications and safety/compliance advisory to large operators.
- Q2 Technologies (USA) — specialist manufacturer with high‑activity MEA‑triazine lines and custom formulation services. Q2’s flexible manufacturing and additive know‑how make it attractive for operators needing bespoke solutions.
- Venus Ethoxyethers (Venus‑Goa) (Goa, India) — competitive global supplier of MMA triazine and MEA triazine intermediates; positions itself on cost and scale advantages for export markets.
- International Chemical Group (ICG) (USA) — offers multiple activity levels of MMA triazine products, enabling tiered procurement strategies for operators balancing cost with performance.
- Jay Dinesh Chemicals (India) — focuses on enhanced MMA formulations aimed at corrosion control and odour abatement; well positioned for industrial and downstream niches.
- Novamen Inc. (Canada) — supplies blend chemistries and supports large‑volume on‑site blending programs, attractive for field operators aiming to reduce transport of high‑density liquids.
- OneCor (USA) — emphasis on customizable activity levels and midstream specifications; strengths include technical field support and adherence to operator specs.
- Geocon Products (India) — supplies triazine variants into Gulf and US markets; competitive in cost and distribution reach for certain trade lanes.
Each supplier’s capabilities map to differentiated strategic options for buyers: total cost of ownership, on‑site vs delivered logistics, residue and waste management responsibility, and regulatory risk sharing. The full report contains a confidential, attachable vendor scorecard and a set of negotiation levers tailored to each supplier archetype.
Supply‑chain and regulatory dynamics that will shape 2026‑era choices
Production chemistry for MMA triazine centres on the condensation of monomethylamine with formaldehyde to form the triazine ring. As such, feedstock availability and pricing, as well as logistics to chemical‑grade intermediates, are leading near‑term cost drivers. Separate but related pressures include regional trade measures that have altered landed costs for specialty triazines; we have observed strategic responses in the form of localized production expansions and co‑located blending assets.
On the regulatory front, two vectors are particularly material. First, routine use of scavengers supports operator compliance with occupational and emissions standards, reducing immediate operational risk. Second, lifecycle concerns over scavenger reaction by‑products — notably polymeric or crystalline residues that can complicate disposal — have attracted regulatory scrutiny. Revised waste‑classification regimes in some jurisdictions are increasing the compliance premium on residue handling and requiring operators to factor remediation and disposal pathways into procurement decisions.
Strategic implications and recommended moves for 2026 decision cycles
- Embed scavenger strategy in 2026 operating budgets: centralize forecasting of consumption volumes and link to conditional hedges tied to feedstock indices or supplier indexation clauses.
- Diversify feedstock and formulation exposure: pilot water‑based alternatives where appropriate, and evaluate co‑sourcing agreements to mitigate single‑supplier service risks.
- Invest in on‑site blending capability as a modular option: our models show on‑site blending reduces delivered cost volatility and offers a lever to optimize activity levels per field conditions.
- Contract hard on residues: include clear waste‑acceptance, testing and liability language in supply contracts to avoid post‑sale surprises tied to by‑product treatment changes under evolving regulations.
- Run targeted pilots under regulatory constraints: execute 6–12 month field tests that pair operational performance KPIs (H2S removal efficiency, chemical consumption, corrosion markers) with full‑cost capture (logistics, disposal).
- Prepare for M&A and partnership opportunities: suppliers with flexible manufacturing footprints and on‑site service platforms are attractive targets for integrated operators seeking supply security.
- Quarterly review of feedstock and tariff developments: supply chain monitoring should be a board‑level KPI given the recent trade measures that have altered regional cost curves.
How PW Consulting’s report supports 2026 decisions
Our study combines a multi‑disciplinary approach: primary interviews across producers and major buyers, proprietary shipment and pricing models, laboratory condition equivalency testing, and regulatory cost overlays. The result is an actionable dataset that translates into executive‑ready recommendations — from procurement contract language and pilot designs to CAPEX/OPEX tradeoffs for on‑site blending vs. delivered supply.
We provide the analytical foundation to run company‑specific scenario models: plug your consumption, site logistics and waste‑handling cost inputs into our companion spreadsheet and generate a tailored 36‑month action plan for board and procurement committees.
Next steps
This bulletin is intended as a strategic preview. To see the detailed segment breakouts, vendor scorecards and the full sensitivity model that underpins our 6.19% CAGR projection and long‑range sizing to 2032, access the full report or contact PW Consulting’s industry desk. For procurement teams and technical operations leaders preparing 2026 budgets, we recommend scheduling a 60‑minute briefing with one of our senior consultants to run through the supplier scorecard and an operator‑specific savings roadmap.
In fast‑moving operational environments, the margin between compliant, resilient H2S management and exposure to fines, warranty claims and latent remediation costs is often smaller than procurement teams assume. Armed with the full PW Consulting MMA Triazine H2S Scavengers Market report, executives will have the scenario‑tested evidence to make confident, defensible decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Mma Triazine H2S Scavengers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Chromatography Cartridges Market to Hit USD 1,566.55 Million by 2032
By PW Consulting, 2026-07-13
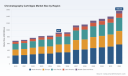
Chromatography Cartridges Market — Strategic Preview for 2026: Key Implications from PW Consulting’s New Report
PW Consulting’s latest market research on Chromatography Cartridges delivers a practice-oriented strategic playbook for companies making critical decisions in 2026. Built on a 2025 base year and a robust forecast through 2032, the study quantifies the market’s trajectory — demonstrating a disciplined recovery and expansion from roughly USD 682 million in 2020 to about USD 925 million in 2025, and projecting growth to approximately USD 1.57 billion by 2032 at a compound annual growth rate (CAGR) of 7.85% (2026–2032). For decision-makers, this represents an inflection window: volume growth is returning, but commercial advantage will accrue to firms that convert technical differentiation, supply resilience, and regulatory certainty into scalable go-to-market programs.
Chromatography Cartridges Market
Why this report matters for 2026 strategic decisions
-
Timing and resource allocation: The market’s mid-single-digit-plus CAGR through 2032 means near-term investments in capacity, quality systems and targeted R&D can still capture meaningful share — but timing matters. Firms that target the 2026–2028 window for commercialization of differentiated cartridges will face the most favorable demand and pricing dynamics.
Chromatography Cartridges Market -
Risk management: Raw material dynamics and regulatory scrutiny (especially for bioprocessing applications requiring GMP traceability) are shifting bargaining power upstream and altering the cost-of-goods profile. Procurement and supplier strategy developed now will materially affect margins and service levels in 2026 and beyond.
Chromatography Cartridges Market -
Portfolio prioritization: Not all cartridge formats and end-markets scale equally. The practical task for 2026 is to allocate R&D and commercial spend toward those modalities and value chains that amplify existing capabilities (e.g., prepacked flash cartridges, bioprocessing consumables, inert guard and specialty phases) while deferring or divesting lower-return segments.
What’s inside the PW Consulting report — practical, transaction-ready content
-
Market sizing & forward models: A validated top-down and bottom-up market model covering 2020–2032 with scenario runs (base, upside, downside) to stress-test capacity and pricing plans.
-
Demand-driver analytics: Quantitative and qualitative drivers across pharmaceutical, biotechnology, environmental and food safety applications, including addressable use-cases and adoption curves for preparative vs analytical cartridges.
-
Supply-chain & raw-material scenarios: Cost-impact models for silica and specialty media, supplier concentration mapping, and contingency playbooks for interruptions and input-price shocks.
-
Regulatory & quality playbook: Actionable checklists for GMP-compliant cartridge manufacturing, traceability templates, and audit preparation guidance for large-molecule purification customers.
-
Commercial playbooks: Channel strategy, pricing architecture, tender response frameworks, and customer segmentation with tailored value propositions for discovery, process development and manufacturing customers.
-
Competitive & M&A intelligence: Profiles and strategic positioning of leading suppliers, market concentration metrics, potential acquisition targets and a screening matrix for bolt-on vs capability acquisitions.
-
Operational improvements: Benchmarked KPIs for yield, cycle time, scrap and QC throughput; modular factory designs for scalable cartridge production; and CapEx sizing templates.
-
Decision-support deliverables: Financial model (driver-based), an executable 12–36 month roadmap, and an interactive dashboard for executive briefings.
Competitive landscape — actionable takeaways
The chromatography cartridges market sits at a moderate concentration level: the top three suppliers account for a meaningful minority of the market, while the top five enlarge that share to a majority. This structure favors both incumbents that can scale and specialist challengers that can exploit niches through product performance and superior customer service.
-
BUCHI Labortechnik (Switzerland) — Strength: prefilled flash cartridges in a wide range of sizes and bonded phases. Strategic implication: incumbency in purification-grade disposables makes BUCHI a logical partner for labs scaling up purification workflows; competitors should anticipate pressure on loading-capacity innovations and backpressure-optimized media.
-
Biotage (Sweden) — Strength: broad prepacked flash portfolio across normal and reversed phases with clear focus on drug-discovery throughput. Strategic implication: Biotage’s channel relationships in discovery labs mean pricing and service models (e.g., just-in-time supply of prepacked cartridges) will be a competing battleground.
-
Restek Corporation (USA) — Strength: guard and protection cartridges for HPLC/LC with inert options for metal-sensitive analytes. Strategic implication: Restek’s recent launches underscore demand for inert protection solutions; analytical labs and LC-MS workflows will drive adoption and upgrade cycles.
-
Sartorius AG (Germany) — Strength: process-scale and monolithic cartridges for bioprocessing. Strategic implication: For players targeting biologics and large-molecule purification, meeting GMP requirements and providing robust documentation chains are table-stakes that favor firms with bioprocess experience.
-
Agilent Technologies (USA) — Strength: HPLC columns and inert-series innovations for biotherapeutics. Strategic implication: Agilent’s investment in ultra-inert phases is a competitive signal — suppliers must respond with performance claims validated by independent data.
-
Waters Corporation (USA) — Strength: advanced protein and affinity cartridges for biopharma analysis. Strategic implication: Specialty cartridges for protein analytics represent a high-value attach opportunity for cartridge suppliers who can meet stringent purity and reproducibility targets.
-
Thermo Fisher Scientific (USA) — Strength: breadth across analytical to preparative applications. Strategic implication: Thermo Fisher’s scale and integrated offering create a benchmark for integrated consumable + instrument solutions.
-
Orochem Technologies (USA) — Strength: flexible manufacturing across flash, HPLC and preparative formats. Strategic implication: Contract-manufacturing and private-label opportunities are available for companies that can provide consistent quality at lower cost.
Recent product moves and sector dynamics to watch in 2026
-
New product introductions focused on inert performance and biotherapeutic-optimized phases (notable launches in late 2025) indicate an accelerating premiumization trend for cartridges that protect metal-sensitive analytes and support peptide/oligonucleotide workflows. Buyers should plan for validated comparison studies and incorporate upgrade paths into budget cycles.
-
Silica remains the dominant stationary phase. The industry continues to favor spherical silica for resolution and reproducibility; suppliers who can secure reliable spherical silica supply chains or novel media with comparable performance will gain a decisive cost and quality edge.
-
Regulatory tightening for bioprocessing cartridges — especially around GMP documentation and traceability — is not a distant regulatory scenario: it is already reshaping purchasing criteria. For 2026, expect larger biopharma buyers to require supplier certifications and audit readiness as preconditions for supply agreements.
Strategic recommendations for 2026 (practical, prioritized)
-
Accelerate GMP readiness for biologics-focused cartridge lines. Allocate budget in 2026 for traceability systems, validation studies and third-party audits to secure larger bioprocess contracts.
-
Lock in raw-material arrangements (spherical silica, specialty phases) with multi-year agreements or dual sourcing to reduce margin volatility and prevent supply disruption during forecasted demand upticks.
-
Invest selectively in inert-phase and protection cartridge technologies targeted at metal-sensitive and peptide/oligonucleotide workflows — these carry premium pricing and faster adoption by large labs.
-
Pursue bolt-on acquisitions or strategic partnerships to fill capability gaps (e.g., monolith production, affinity media) rather than greenfield builds where time-to-market matters.
-
Design a segmented go-to-market plan that distinguishes discovery, process development and manufacturing use-cases and ties product specifications to buyer KPIs (throughput, reproducibility, documentation).
How PW Consulting’s deliverables accelerate execution
Our report is engineered to move teams from insight to action. Beyond narrative analysis we deliver a driver-based financial model, supplier scorecards, a GMP readiness checklist, a go-to-market playbook, a shortlist of M&A targets plus scenario simulations tailored to client risk appetites. We also provide an executive workshop to convert report outputs into a 12–36 month operating plan — including prioritized investments and a measurable implementation timeline.
To preserve the strategic value of the dataset for our clients, detailed subsegment revenue splits and sensitive regional breakdowns are intentionally withheld from this press release. The full report includes those granular layerings, validation datasets and anonymized stakeholder interviews necessary for transaction diligence and commercial planning.
Next steps
For procurement leaders, R&D heads and corporate strategy teams preparing budgets and M&A pipelines for 2026, the PW Consulting Chromatography Cartridges report is a practical tool: it clarifies where to invest, where to partner, and where to hold off. Contact PW Consulting to request the full report package, arrange a briefing, or commission a tailored deep-dive that maps our models to your balance sheet and operational targets.
For detailed analysis of this topic, please visit the official page: Chromatography Cartridges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microbes Protein Hydrolysates Market Poised for 6.45% CAGR, New Insights Reveal
By PW Consulting, 2026-07-13
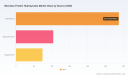
Microbial Protein Hydrolysates: Strategic Imperative for 2026 — A PW Consulting Industry Brief
As the microbial protein hydrolysates market accelerates into a phase of commercial maturation, executive teams face a narrow window in which to convert early technical advantages into durable competitive positions. PW Consulting’s latest market analysis — anchored on a 2025 base and a 2026–2032 forecast horizon — shows the market moving from an estimated USD 465.5 Million in 2025 toward a materially larger opportunity in the coming decade, growing at a compound annual growth rate (CAGR) of 6.45% through 2032 and approaching roughly USD 721.0 Million by the end of the forecast period. These macro trends are already informing investment, regulatory and go-to-market choices across verticals that include feed, food & beverage, pharma/biotech and agricultural biostimulants.
Microbes Protein Hydrolysates Market
Executive snapshot — what senior leaders must know
-
Growth trajectory. The market’s mid-single-digit CAGR masks important inflection points tied to regulatory approvals, commercial-scale plant commissioning, and feedstock availability that will determine winners and losers in 2026–2028.
Microbes Protein Hydrolysates Market -
Commercial readiness. Several technology paths — gas fermentation (methanotrophs), autotrophic CO2-based processes, and yeast fermentation — have moved from pilot to commercial output in selected applications, especially animal nutrition and selected human-food demonstrations.
Microbes Protein Hydrolysates Market -
Regulatory gating. Recent approvals and organic-system recognitions are lowering entry barriers for feed use, but full mainstreaming in human food and pharma remains contingent on regional regulatory clarity and clinical substantiation for specialized hydrolysates.
-
Market structure. The competitive landscape is characterized by dynamic specialization rather than a single dominant incumbent; top suppliers account for a meaningful share of supply, but there remains room for targeted entrants and partnerships.
Why our 2026 strategic planning must account for microbial hydrolysates
-
Timing matters more than absolute scale. While the market remains sub‑billion-dollar in near-term revenue terms, the pace of technological scale‑up and the discrete nature of approvals means first movers can lock-in valuable offtake agreements, feedstock contracts, and channel partnerships that yield outsized returns as the market expands.
-
Feedstock and energy are strategic levers. Producers using methane, CO2 + H2 (electricity-driven), or sugar feedstocks face different risk profiles: access to low‑cost methane or renewable electricity/green hydrogen and CO2 streams will materially affect unit economics and sustainability credentials.
-
Product differentiation is technical and regulatory. Suppliers who can combine consistent amino-acid profiles with functional claims (digestibility, bioavailability, peptide functionality) and validated health outcomes will secure premium placement in food, pharma and specialty feed applications.
-
Partnerships beat solo scale-ups. Joint ventures, toll manufacturing and strategic alliances with established feed and ingredient players are the fastest routes to commercial traction and risk mitigation in 2026 planning cycles.
Competitive landscape — profiles and strategic implications
-
Unibio (Denmark) — Uniprotein via gas fermentation: regulatory momentum in aquaculture and early commercial shipments position Unibio as a lead commercializer for methanotrophic single‑cell protein in feed. Strategic implication: incumbents and integrators should evaluate aquaculture pilot partnerships and regional feed trials where approvals exist.
-
Calysta Inc. (United States) — FeedKind and scaled JV output: Calysta’s recent shift from R&D pilots in the US/UK to concentrated commercial manufacturing in its China JV reflects a pragmatic move to optimize CAPEX utilisation and unit costs. Strategic implication: firms evaluating supply should prioritize assured commercial supply agreements and consider geographic production footprints when modeling supply risk.
-
Solar Foods (Finland) — Solein (CO2 + H2): its product demonstrations for next‑generation protein beverages show the attractiveness of electricity-driven production for human-food applications. Strategic implication: consumer-facing brands seeking low-land-use, decarbonized protein should open co-development dialogues now to secure formulation windows.
-
Angel Yeast (China) — Yeast-derived hydrolysates: breakthrough research on nutrient synergies (e.g., peptides + mineral absorption) indicates value-add pathways into functional foods and nutraceuticals. Strategic implication: formulators and supplement companies should evaluate trial programs to exploit differentiated health claims.
-
Kerry Group, DSM‑Firmenich, Corbion, Lallemand, Alltech — ingredient and fermentation incumbents: these firms offer scale, channel access and formulation expertise, and are natural acquirers or partners for smaller microbial protein innovators. Strategic implication: buyers and investors should map alliance and M&A strategies against these firms’ capability footprints.
Recent industry moves that shape 2026 playbooks
-
Regulatory wins for feed use and organic status in some jurisdictions are already de‑risking pilot-to-commercial transitions for methanotrophic proteins; companies should monitor approvals as triggers for expansion.
-
Operational consolidation by certain innovators toward fewer, larger manufacturing sites signals a shift to manufacturing-first playbooks — raising the importance of long-term feedstock/energy contracts and plant reliability data for offtakers.
-
Visible product showcases from CO2‑based producers into consumer-facing beverage prototypes indicate an emerging pathway for microbial proteins into mainstream human nutrition — but commercialization timelines will hinge on cost curves and consumer acceptance pilots.
What the PW Consulting report delivers — actionable components
-
Market sizing and demand scenarios: top‑down and bottom‑up forecasts from 2020 baseline through 2032, including sensitivity runs that quantify impact of regulatory approvals, feedstock pricing shocks, and CAPEX scaling.
-
Technology and cost models: CAPEX/OPEX build-ups for gas fermentation, CO2‑based autotrophy, and yeast fermentation pathways; energy and feedstock cost elasticities; break‑even curves under multiple price and scale assumptions.
-
Regulatory and standards matrix: approval timelines, labeling considerations, and organic/animal‑feed certification pathways across priority jurisdictions — with recommended engagement sequences for 2026 regulatory filings.
-
Competitive intelligence dossiers: strategic profiles of active players, recent developments, partnership maps and capability heatmaps to support target screening and JV sourcing.
-
Commercialization playbooks: pilot-to-scale roadmaps, sample offtake and tolling contract clauses, procurement scorecards, and go‑to‑market segmentation frameworks for feed, food, pharma and agri-biostimulant customers.
-
Investment and M&A guidance: red-flag risk checklist, valuation drivers for providers at different maturity stages, and prioritized target lists based on capability gaps, IP position and go-to-market synergies.
How to use this intelligence in 2026 planning cycles
-
Board & capital committees — integrate a two-track capital allocation approach: preserve optionality for rapid scale via JV/tolling while selectively funding proprietaryscale where unique feedstock or IP advantages exist.
-
Commercial teams — secure binding offtake windows for pilot volumes now and include escalation clauses tied to published regulatory milestones to hedge price risk as units scale.
-
R&D & regulatory — prioritize dossiers that unlock the largest near-term revenue pools (e.g., aquaculture/animal feed approvals) while planning parallel human‑food safety and labeling studies for medium-term expansion.
-
Procurement & operations — model feedstock scenarios (natural gas/methane, sugar streams, renewable H2 + CO2) and secure long‑dated supply or capture agreements for critical inputs to protect margins in a tightening market.
-
M&A and partnerships — use a capability-first lens: ingredient formulators and feed integrators should target microbial producers that can demonstrate repeatable scale, validated quality systems, and defensible supply contracts.
Priority next steps — a 90‑day action plan for executives
-
Run a feedstock sensitivity analysis across your portfolio and price points to identify exposure and opportunity under three energy/commodity scenarios.
-
Initiate pilots with at least two different microbial suppliers that use different process pathways (gas vs yeast vs CO2‑based) to evaluate functional equivalency and cost-to-formulation.
-
Engage regulatory counsel to map the fastest viable route for product claims and labeling in target markets; prioritize regions where approvals provide immediate commercial access.
-
Open dialogues with incumbent ingredient players for JV or tolling arrangements to accelerate market entry without absorbing full CAPEX burden.
Conclusion: The microbial protein hydrolysates market is no longer a speculative niche — it is an emergent supply domain with distinct commercial pathways and embedded strategic choices for 2026. The macro numbers point to steady expansion, but the commercial winners will be those who align technology selection, feedstock strategy and regulatory sequencing with disciplined partnership and offtake execution.
For full datasets, detailed segment-level intelligence, cost models and candidate target lists to inform 2026 decisions, access PW Consulting’s full Microbial Protein Hydrolysates Market report and supporting appendices on our web portal.
For detailed analysis of this topic, please visit the official page: Microbes Protein Hydrolysates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Consumer Electronic BMS Chip Market Set to Expand at 7.5% CAGR — From USD 2,450 Million in 2025 to USD 4,064.7 Million by 2032, Led by Asia‑Pacific (USD 1,217.1M)
By PW Consulting, 2026-07-13
Consumer Electronic BMS Chip Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s forthcoming market research on Consumer Electronic Battery Management System (BMS) chips synthesizes a unique combination of quantitative market modeling and hands‑on commercial frameworks to inform executive decisions in 2026. Our base-year analysis uses 2025 as the grounding point (market size: USD 2,450 million), with historical trend mapping across 2020–2025 and a forward-looking forecast to 2032. The market is modeled to grow at a steady 7.5% CAGR over the forecast horizon, reaching roughly USD 4,065 million by 2032 under our central scenario. This briefing outlines the strategic value of the report for product, supply‑chain and M&A choices in 2026 while deliberately withholding granular sub‑segment tables — these are available in full on the report landing page.
Consumer Electronic Battery Management System Bms Chip Market
Why this matters for 2026 planning
-
A predictable mid‑single‑digit-to‑high‑single‑digit CAGR creates a planning horizon where product investments and supply commitments can be staged over multi‑year cycles rather than requiring immediate, full‑scale reallocation. Our model shows an accelerated compound expansion from the 2025 base through 2032 that makes phased R&D and capacity contracts a viable way to balance risk and opportunity.
Consumer Electronic Battery Management System Bms Chip Market -
Macro policy and supply‑chain idiosyncrasies are creating asymmetric risk profiles. Regulatory requirements (notably new EU rules) and export control regimes are shifting where and how high‑value functionality (e.g., advanced fuel gauging, AI‑enabled estimators) can be developed and shipped — a dynamic that has direct implications for 2026 sourcing, localization and partnership choices.
Consumer Electronic Battery Management System Bms Chip Market -
Market concentration is meaningful but not insurmountable: the top three players hold a material share of market value, and the top five are well positioned across product platforms. Competitive entry by focused analog and mixed‑signal vendors continues to compress margins in commoditized nodes while premium feature sets command ASP resilience.
Report contents — what you get (practical, decision‑ready modules)
-
Market model and scenarios — a calibrated bottom‑up revenue model (2020–2032), three demand scenarios, and sensitivity dashboards that let finance and product teams stress‑test revenue by price, device penetration, and regulatory adoption curves.
-
ASP and cost curves — dynamic ASP tracking (including 2025 observations) and component cost breakouts to support negotiating positions with IDM and fab partners.
-
Product and roadmap playbook — comparative feature maps across cell protection, fuel gauging, integrated BMS+charger solutions and low‑power wearables variants; vendor capability matrices for quick vendor short‑lists.
-
Supply‑chain risk map — lead time heatmaps, single‑sourcing points, raw material exposures and mitigation levers (dual‑sourcing, design requalification pathways, buffer stock models).
-
Regulatory and compliance navigator — obligations tracking (including near‑term deadlines for state‑of‑health reporting), impact scoring and compliance roadmaps for product teams and legal/compliance functions.
-
Commercial playbooks — go‑to‑market strategies for OEMs, ODMs, and semiconductor suppliers including pricing playbooks, bundling options and co‑engineering engagement templates to accelerate adoption.
-
M&A and partnership pipeline — target screening criteria, valuation heuristics and a prioritized list of tuck‑ins and technology partners aligned to different strategic objectives (time‑to‑market, IP, customer access).
Competitive landscape — who’s shaping the market
Our competitive analysis synthesizes public product portfolios, reference designs, recent product moves and go‑to‑market posture to generate battle‑cards for each major supplier. Market concentration metrics indicate an environment where leading analog and mixed‑signal specialists retain structural advantages, but differentiated system suppliers and highly focused niche players create corridors for growth.
-
Texas Instruments (Dallas, TX) — Strengths: deep analog portfolio, broad BQ family with cell balancing, protection and fuel gauge logic. Strategic posture: platforming for OEMs and power‑bank / laptop use cases. Recent move: late‑2025 launches expanded multi‑cell monitors targeting higher‑cell‑count consumer packs.
-
Analog Devices (Wilmington, MA) — Strengths: precision monitoring and state‑of‑charge algorithms; strong presence in multi‑cell stacks. Strategic posture: positioning LTC series as the premium monitoring solution for mid‑to‑high end portables. Recent move: 2025 sampling activity to accelerate design wins in wearables and multi‑cell devices.
-
STMicroelectronics (Geneva) — Strengths: low‑power, system‑level integration for wearables and IoT. Strategic posture: reference designs and developer ecosystems to speed adoption of single‑cell BMS in mass‑market consumer earbuds and sensors. Recent move: reference design releases for TWS earbuds to lower customer integration hurdles.
-
NXP Semiconductors (Eindhoven) — Strengths: controller platforms for consumer battery packs with emphasis on pack‑level management and communications. Strategic posture: leveraging automotive‑grade qualifications to win higher‑reliability consumer segments. Recent move: product qualification wins to broaden addressable markets.
-
Renesas Electronics (Tokyo) — Strengths: high‑accuracy monitoring and strong reliability pedigree. Strategic posture: targeting notebook and professional portable segments by adapting automotive‑grade architectures to consumer reliability expectations.
-
Infineon Technologies (Neubiberg) — Strengths: ASIC and multi‑cell solutions for drones and power tools; communications architectures for daisy‑chaining cells. Strategic posture: bringing industrial robustness into premium consumer categories.
-
Maxim Integrated (Analog Devices, San Jose) — Strengths: single‑cell fuel gauge and protector products for ubiquitous devices such as earbuds and single‑cell wearables. Strategic posture: deep OEM relationships on single‑cell power management.
-
Monolithic Power Systems (Kirkland) — Strengths: integrated charging+protection controllers for portable devices with compact BOM impacts. Strategic posture: cost‑effective integration and fast time‑to‑market for consumer electronics makers.
Recent industry developments shaping 2026 tactics
-
Product cadence is accelerating: several vendors announced sampling or launches through 2024–2025, bringing higher cell counts and integrated functionality to consumer packs. These moves compress product windows and make early design wins materially more valuable.
-
Pricing and ASP behavior: the unit ASP for consumer BMS ICs rose meaningfully in 2025 (our market monitoring flagged a rise to approximately USD 1.20/unit driven by demand for AI‑enabled fuel gauging). That trend supports near‑term revenue resilience for differentiated chips while commoditized parts face margin pressure.
-
Supply‑chain and raw‑material frictions: wafer fab lead‑times spiked (20–24 weeks in Q4 2025 for automotive‑grade wafers) and palladium shortages extended qualification cycles for analog ICs — factors that increase the time and cash required to bring new designs to production.
-
Policy and geopolitical constraints: export‑control measures have real, measurable impact on the ability to transfer advanced BMS technologies across borders; our mapping estimates roughly 15% of global consumer supply is affected by recent export rules. This changes where OEMs can source advanced nodes and puts a premium on localized design capacity.
-
Regulatory mandate: the EU has set out a timeline for consumer devices to report state‑of‑health data beginning in 2027. Product and compliance roadmaps need to account for firmware, security and data‑handling obligations now to avoid late‑stage rework.
Strategic actions PW Consulting recommends for 2026
-
Lock design windows, not just capacity: given extended qualification lead times for new analog designs, secure multi‑phase commitments with preferred vendors and include requalification corridors. Shorten time‑to‑design‑win via early reference design partnerships.
-
Prioritize regulatory readiness: incorporate state‑of‑health telemetry and secure reporting into platform architectures now to meet near‑term mandates without feature trade‑offs.
-
Adopt a differentiated ASP strategy: exploit premium ASP resilience for AI‑enabled and multi‑cell solutions while aggressively cost‑optimizing single‑cell and commoditized SKUs.
-
De‑risk supply chains: build dual‑source strategies for critical analog components, evaluate localized wafer sourcing for sensitive designs and use staged buffer inventory for long‑lead items.
-
Use M&A and alliances tactically: prioritize tuck‑ins that provide IP for fuel gauging, state‑estimation algorithms, or compliance stacks rather than only capacity targets.
Methodology, confidence and where to look next
The report’s base year is 2025 with historical coverage from 2020–2025 and a forecast window through 2032. Our approach blends bottom‑up bill‑of‑materials modelling, primary interviews with OEM/ODM/power‑IC suppliers, and triangulation from semiconductor market trackers and policy databases. We present three forecast scenarios plus a comprehensive sensitivity matrix so teams can test alternative ASP and penetration assumptions. Confidence intervals are provided at the product family level; the full report contains the granular tables, segment‑level forecasts and vendor revenue splits that are intentionally not excerpted here.
Conclusion and call to action
For executives making 2026 capital allocation, product roadmap or M&A decisions, this PW Consulting report offers an operationally actionable synthesis: a proven growth trajectory from USD 1.75 billion in 2020 to USD 2.45 billion in 2025, and a modeled expansion to roughly USD 4.07 billion by 2032 at a 7.5% CAGR. The combination of evolving regulation, supply‑chain constraints and selective vendor consolidation means that well‑timed, targeted moves in 2026 can secure durable advantage. To access the full dataset, segment breakdowns, vendor financials and our prioritized short‑list of targets and suppliers, consult the report landing page for subscription access and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Consumer Electronic Battery Management System Bms Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Intelligent Fire Emergency Lighting Market to Grow from USD 3,450 Million in 2025 to USD 6,107 Million by 2032 at an 8.5% CAGR
By PW Consulting, 2026-07-13
Intelligent Fire Emergency Lighting and Evacuation Indication Systems: Strategic Imperatives for 2026 — PW Consulting Market Preview
PW Consulting today releases a strategic preview of our upcoming market research on the Intelligent Fire Emergency Lighting and Evacuation Indication System market. As organizations prepare procurement, product, and regulatory strategies for 2026, this analysis synthesizes multi-year market trajectories, regulatory inflection points, technology adoption vectors, and competitive dynamics to inform C-suite and business unit decision-making. The full report contains the confidential segment-level datasets and vendor scorecards referenced below; this preview highlights the operationally relevant insights while deliberately withholding detailed revenue splits to drive direct engagement with the source report.
Intelligent Fire Emergency Lighting And Evacuation Indication System Market
Market trajectory at a glance
The market for intelligent fire emergency lighting and evacuation indication systems has transitioned from steady recovery into structurally accelerated adoption. Our baseline shows market size rising from approximately USD 2,348 Million in 2020 to about USD 3,450 Million in 2025. Under our central forecast, the market continues to expand through the coming decade, reaching roughly USD 6,107 Million by 2032 — representing a compound annual growth rate (CAGR) in the forecast window. This growth reflects converging forces: stricter safety standards, broader adoption of adaptive escape lighting and positioning technologies, and increasing integration of emergency illumination with building management, fire alarm and communications systems.
Intelligent Fire Emergency Lighting And Evacuation Indication System Market
Why this matters for 2026 decisions
- Budgeting and CapEx prioritization: Facilities and infrastructure owners should assume elevated baseline investment in intelligent emergency lighting through 2026 as compliance cycles and retrofit programs accelerate. Early alignment of budgets with multi-year upgrade pathways reduces disruption and secures preferential procurement terms.
- Product roadmap alignment: Manufacturers and OEMs must prioritize features that regulators now explicitly recognize — adaptive lighting, automatic self-test and reporting capabilities, and personnel-positioning interfaces — to avoid product obsolescence in multiple major markets.
- Channel and partner strategy: Integration with fire detection, voice evacuation and BMS platforms is becoming table stakes. Strategic partnerships with established fire-system integrators and property-management software vendors will materially shorten sales cycles in 2026.
- M&A and investment screening: The market concentration data indicates room for consolidation and regional champions. Investors should focus on targets that combine hardware competence with software and certification capabilities.
Key trends driving the market
- Adaptive and dynamic evacuation solutions: Adaptive escape lighting that responds to incident conditions and directs occupant flow is moving from niche to normative in major jurisdictions. This creates demand for centralized control architectures and intelligence at the luminaire level.
- Integration and interoperability: Buyers increasingly demand turnkey solutions that integrate emergency lighting with fire alarms, voice alarm systems, access control and building management to enable coordinated evacuations and post-event analytics.
- Digitalization and self-testing: Automated testing, remote reporting and predictive maintenance — often cloud-enabled — are shifting service models from time-based maintenance to condition-based operations, reducing lifecycle cost and improving compliance evidence.
- Positioning and personal safety features: Bluetooth-based personnel positioning and wayfinding functions are now recognized in several regulatory and standards updates, creating new use cases for occupant-level guidance and rescue coordination.
- Energy and LED performance: Advances in LED efficiency and battery technology continue to improve lumen output, runtime and lifecycle cost, accelerating replacement of conventional emergency luminaires in retrofit cycles.
Regulatory inflection points and compliance timing
Regulatory momentum is a central near-term driver. Several recent updates materially affect product specifications, certification pathways and the timeline for compliance:
Intelligent Fire Emergency Lighting And Evacuation Indication System Market
- National certification rules in certain markets now expand the scope of mandatory certification for emergency lighting distribution equipment, and introduce explicit expectations for Bluetooth-based functions, personnel positioning, and enhanced self-test capabilities. Compliance calendars set conversion deadlines that create a finite window for suppliers and systems integrators to certify legacy product lines.
- European standards have been revised to incorporate luminous and functional requirements for adaptive escape lighting and related safety signage, with national conflicting standards scheduled for withdrawal on a defined timeline. Suppliers targeting cross-border sales must map these transitions into product design and documentation plans.
- Standards strengthening in areas such as risk assessment, documented design and periodic illuminance measurement raise the bar for professional services and testing providers. This expands serviceable revenue streams for vendors who can offer certified test and maintenance programs.
Competitive landscape: who matters and why
The space is a mix of large multinational systems integrators, specialized EU/UK innovators, and regional manufacturers. Market concentration metrics indicate a landscape where top-three vendors hold a meaningful but not dominant share, with wider opportunity for regional champions and specialized suppliers. The following firms illustrate the different strategic archetypes operators and investors should consider:
- Siemens (Munich, Germany) — Established systems integrator delivering high-performance intelligent emergency lighting and evacuation guidance integrated tightly with fire alarm ecosystems. Strength: end-to-end building systems integration and global service capability. ( https://www.siemens.com)
- Honeywell (Charlotte, NC, USA) — Offers intelligent detection and life-safety platforms with integrated emergency lighting capabilities for connected buildings. Strength: deep channel and enterprise building relationships. ( https://buildings.honeywell.com)
- Eaton (Dublin, Ireland) — Known for adaptive evacuation central battery systems and control panels enabling dynamic evacuations linked to fire and voice systems. Strength: power systems and resilient design expertise. ( https://www.eaton.com)
- Mircom (Concord, Ontario, Canada) — Integrates emergency lighting within broader fire detection and life-safety portfolios, emphasizing North American market needs. ( https://mircom.com)
- Evaclite (United Kingdom) — Specialist in dynamic exit signage and adaptive evacuation indication systems with strong product innovation in directional guidance. ( https://evaclite.com)
- Leading Chinese suppliers (examples) — Several China-based manufacturers provide complete centralized control solutions and have been active in certification and volume markets; they are increasingly relevant for global sourcing strategies.
- Technical-specialist vendors (Advanced, Orena, Sanjiang, Beijing Mingri) — These companies offer targeted products (addressable automatic test systems, rechargeable luminaires, centralized control with testing capabilities, integrated monitoring) that form the modular pieces of larger integrated solutions.
For procurement teams the implication is clear: route-to-market and installed-base service capability matter as much as unit-cost. Systems that can be integrated into existing alarm and building management layers reduce time-to-value and compliance risk.
What the PW Consulting report contains (practical, actionable deliverables)
The full PW Consulting market study is structured to enable direct operational execution across procurement, product, regulatory, and M&A decisions. Key deliverables include:
- Macro market sizing and seven-year forecast with scenario analysis and sensitivity to regulation, technology adoption, and macroeconomic variables (note: detailed segment revenue tables and geographic/application splits are available in the report appendix).
- Vendor scorecards and capability matrices that assess product breadth, integration capability, channel reach, and certification readiness.
- Compliance playbooks aligned to the latest standard updates — including technical checklists, testing regimens, and documentation templates to accelerate certification and audit readiness.
- Procurement playbooks and TCO models that compare centralized vs. decentralized architectures, retrofit vs. new build economics, and the impact of remote-monitoring service contracts.
- Go-to-market roadmaps for vendors and integrators — prioritizing segments and channel strategies to maximize 2026 growth while balancing certification investment.
- M&A and investment heatmaps identifying bolt-on capabilities, regional consolidation targets, and strategic partnership opportunities.
How to use this intelligence in 2026
- For facility owners/operators: Launch compliance gap assessments now that map existing systems to forthcoming standards; prioritize pilot deployments of adaptive evacuation solutions in high-occupancy assets to validate operations and occupant behavior assumptions.
- For OEMs and suppliers: Accelerate firmware and interoperability roadmaps to meet adaptive lighting, self-test and personnel-positioning expectations; secure certifications in priority markets ahead of the enforced conversion deadlines to protect revenue.
- For system integrators and channel partners: Expand managed-services capabilities around automated testing, reporting and predictive maintenance; these will become differentiators in long-term service contracts.
- For investors and acquirers: Prioritize targets with proven certification programs, software-enabled service revenue, and flexible manufacturing that can scale into retrofit demand waves.
Recent regulatory and standards milestones to watch
- National certification updates in major markets now require broader product scope and include new functional expectations such as Bluetooth-enabled positioning and enhanced self-test capabilities; transitional timelines impose a hard deadline for certificate conversions.
- European standard revisions now codify adaptive escape lighting performance and luminous requirements, with a defined withdrawal schedule for conflicting national standards. Parallel updates to national codes are already in process in several jurisdictions.
- Standards strengthening around design documentation and periodic illuminance verification will increase demand for third-party testing and certified maintenance programs.
Conclusion — a decision point for 2026
2026 is not simply another planning year — it is a decision point. The convergence of regulatory tightening, functional evolution toward adaptive, networked solutions, and an evolving competitive map creates both risk and optionality. Organizations that treat emergency lighting and evacuation indication as an integrated safety and digitalization initiative will capture efficiency, compliance and resilience benefits. Conversely, delayed response to certification timelines and interoperability expectations will create retrofit cost waterfalls and contractual exposure.
PW Consulting’s full report provides the granular segmentation, regional and application breakouts, vendor rankings, and financial models needed to operationalize these insights. For procurement-ready matrices, certification playbooks and the complete data tables that underpin these strategic recommendations, please refer to the full report on our website or contact PW Consulting directly for enterprise licensing and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Intelligent Fire Emergency Lighting And Evacuation Indication System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solid-State Cooling Market Set to Hit USD 2,019.32 Million by 2032, Growing at a 12.48% CAGR
By PW Consulting, 2026-07-13
Solid State Cooling Market: Strategic Imperatives for 2026 — PW Consulting Release
As organizations across electronics, healthcare, automotive and industrial verticals reassess their thermal management roadmaps for 2026, PW Consulting’s new Solid State Cooling Market report delivers the pragmatic intelligence leaders need to translate technological promise into executable strategy. Built on a rigorous historical baseline (2020–2025), scenario modelling for 2026–2032 and primary company interviews, the study synthesizes market trajectories, competitive positioning, technology inflection points and actionable go-to-market playbooks designed for boards, corporate strategy teams and investors.
Solid State Cooling Market
Why 2026 Is a Decision Point
Solid-state cooling is moving from niche to selective scale. Our market model — expressed in constant USD (millions) — shows a pronounced expansion from the 2020 baseline through 2025 and into the forecast window: the market more than doubles on the 2020 base by the end of the 2032 horizon under our central scenario, driven by an expected compound annual growth rate of 12.48% across 2026–2032. That pace reflects converging forces: tightening regulations on traditional refrigerants, accelerating demand for compact, vibration-free thermal solutions in sensitive electronics and medical applications, and fresh material-science breakthroughs that may materially alter device efficiency curves.
Solid State Cooling Market
What the Report Contains — Practical, Executable Insight
- Proprietary market sizing and scenario modelling: annualized market values and stress-tested trajectories calibrated to multiple adoption pathways through 2032.
- Technology roadmaps and performance benchmarks: comparative thermal metrics, projected efficiency gains, and sensitivity analysis tied to material innovations.
- Supply-chain and raw-material risk heatmaps: inputs, sourcing concentration and mitigation levers for critical components such as thermoelectric semiconductor materials.
- Commercial playbooks: segment-specific go-to-market strategies, pricing frameworks and channel models for OEMs, module suppliers and systems integrators.
- Competitive intelligence and M&A landscape: vendor scorecards, capability matrices and scenarios for consolidation and partnership.
- Regulatory and standards matrix: implications of refrigerant phase-downs, ASHRAE guidance and IEC compliance on product design and market access.
- Case studies and pilot evaluation templates: eight real-world deployments across data center, medical refrigeration and precision industrial control, with measurable KPIs and NPV-style investment tests.
We intentionally present high-level, actionable frameworks in this release; the report contains the granular segmentation tables, vendor-level revenue splits and unit economics required for transaction diligence and program budgeting.
Solid State Cooling Market
Competitive Landscape — Leaders, Challengers and Strategic Gaps
The solid-state cooling domain remains a mixture of specialized incumbents, system integrators and emerging materials innovators. Market concentration is moderate: the top three players capture a meaningful but not dominant share (CR3 ~38.4%), with the top five together representing just over half of the market (CR5 ~52.2%). That structure creates both competitive stability at scale and opportunities for targeted disruption.
- Ferrotec Holdings Corporation (Japan) — a major manufacturer of thermoelectric modules and assemblies. Ferrotec’s scale and vertical integration in module manufacturing give it a core advantage in industrial and medical OEM channels, particularly where supply security and custom assembly expertise are critical.
- Coherent Corp. (United States) — with legacy assets from II‑VI Marlow, Coherent brings precision thermal management expertise that aligns with high-reliability electronics and laboratory applications. Their strength is in engineered thermal solutions rather than commodity modules.
- Laird Thermal Systems (United States) — known for thermoelectric coolers and integrated systems, Laird is well positioned to capture demand where packaged solutions and speed-to-market matter most.
- Phononic, Inc. (United States) — focused on solid-state refrigeration systems for electronics, data centers and cold chain; highlights the category’s move beyond component sales to system-level solutions.
- Delta Electronics, Inc. (Taiwan) — a large power and thermal management player integrating solid-state cooling into broader systems, signaling an industrialization route for the technology.
- Specialists and regional producers — companies such as Solid State Cooling Systems, TECA, TE Technology, CUI Devices, Kryotherm, RMT and several other regional suppliers maintain important positions in recirculating chillers, lab equipment and bespoke industrial cooling. Their agility and niche focus make them preferred partners for pilot projects and customized applications.
Collectively, the competitive picture points to a two-track market: a consolidating layer of scaled module and system providers focused on data center, healthcare and automotive electrification; and a diverse field of niche vendors serving specialized laboratory, instrumentation and industrial segments. For buyers and investors, the strategic question is which track aligns with their required time-to-market, risk tolerance and margin profile.
Technology and Material Inflection — The CHESS Disruption
One of the most consequential inputs to our 2026 advisory is the emergence of nano-engineered thin-film thermoelectric materials. In mid-2025, the Johns Hopkins Applied Physics Laboratory (APL) publicized CHESS thin-film materials that, in laboratory refrigeration testing with a major industry partner, nearly doubled the efficiency of commercial solid-state cooling devices. The development was subsequently validated with a high-profile award later that year.
Strategic implications are immediate:
- Efficiency improvements accelerate use-case expansion: higher COP (coefficient of performance) can make solid-state solutions competitive in higher-capacity applications previously dominated by vapor-compression systems.
- IP and licensing become choke points: firms with early access to, or licenses for, next-generation materials will enjoy a multiyear window to capture premium segments.
- Supply-chain reorientation: thin-film processes may reduce reliance on bulk bismuth telluride for some configurations, but broader adoption still depends on scale-up, manufacturability and thermal interface engineering.
Our full report maps plausible adoption timelines for next-gen materials and quantifies the sensitivity of market size and margin expansion to these technology milestones — a critical input for R&D portfolio prioritization in 2026.
Regulatory and Standards Context
Two policy and standards themes underpin the sector’s near-term acceleration: regulatory pressure on HFC refrigerants and tightening environmental, safety and performance standards in electronics cooling. Industry norms such as ASHRAE thermal guidelines for high-density electronics, and compliance with IEC laboratory safety standards, shape allowable architectures and verification protocols for product certification. PW Consulting’s regulatory matrix aligns these rules with design constraints, providing product teams with an actionable compliance-to-market timeline.
Strategic Playbook for 2026
Executives and investors must translate the market trajectory and technology inflection into prioritized bets. Our recommended 2026 agenda, drawn from the report’s executive playbooks, includes:
- Portfolio triage: identify which product lines and markets will benefit most from incremental efficiency gains versus those that require step-change materials breakthroughs.
- Partnerships and licensing: pursue selective material-IP partnerships and early licensing to secure performance advantages without shouldering full-scale manufacturing risk.
- Hybrid system development: invest in engineering hybrid architectures that combine solid-state modules with conventional refrigeration to unlock interim use cases and lower total cost of ownership.
- Supply resilience: implement raw-material sourcing plans and dual-sourcing contracts for critical thermoelectric inputs while exploring thin-film suppliers as hedges.
- M&A scouting: target complementary module manufacturers, systems integrators and thermal interface specialists to accelerate time-to-market and capture value across the stack.
- Pilot-first commercialization: use staged pilots in high-value segments (medical, precision lab, data center) to build references, optimize thermal management software and validate total-cost models.
Decision-Quality Outputs for 2026 Planning
Boards and strategy teams will find the report particularly valuable for three planning functions: capital allocation (R&D and M&A sizing), commercial go-to-market design (pricing, channel and partner economics), and risk management (supply chain and regulatory stress-testing). We provide modular tools — including a customizable NPV template, thermal-performance sensitivity tables and a vendor negotiation checklist — to move from insight to procurement and engineering decisions within 60–90 days.
Next Steps
PW Consulting’s Solid State Cooling Market report is designed as an active decision support asset for 2026. This press release highlights the analysis framework, high-level market trajectory and strategic recommendations; the full report contains the granular segmentation, vendor scorecards and financial models required for transaction-level diligence and program execution. For teams preparing budgets, R&D roadmaps or M&A pipelines for 2026, the report is the operational intelligence you should base your first-mover, fast-follow or defensive play on.
Contact PW Consulting or visit our Solid State Cooling Market research page to request the full dataset, vendor benchmarking annex and executive briefings tailored to your organization’s role in the value chain.
For detailed analysis of this topic, please visit the official page: Solid State Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 8.75% CAGR for Networked Pulse Oximeter Market in 2026–2032
By PW Consulting, 2026-07-13
Networked Pulse Oximeter Market: Strategic Imperatives for 2026
As PW Consulting’s senior strategy advisor and chief industry analyst, I present a concise, actionable briefing drawn from our new Networked Pulse Oximeter Market report. The connected oximetry market is moving from early adoption to structural deployment across acute and home settings. Our baseline analysis places the market at USD 1,150.8 Million in 2025, with a compound annual growth rate (CAGR) of 8.75% over the 2026–2032 forecast period, driving the market toward a multi‑billion dollar opportunity by 2032. This brief outlines the strategic implications for executives preparing budgets, product roadmaps, regulatory strategies, and partnerships in 2026 — while reserving the granular segment-level intelligence for the full report.
Networked Pulse Oximeter Market
Why 2026 is an Inflection Year
-
Regulatory tightening and clearer guidance: The FDA’s January 2025 draft guidance on pulse oximeters — which elevates expectations around non‑clinical and clinical performance testing, inclusive skin pigmentation studies, and labeling — raises the bar for medical-grade connected devices. Manufacturers who align their R&D and regulatory pathways now will avoid costly rework and accelerate time-to-market in 2026.
Networked Pulse Oximeter Market -
Reimbursement tailwinds: Remote patient monitoring (RPM) coding and reimbursement updates through CMS (2025–2026), including new short‑term reading codes, materially improve the payback profile for networked oximetry programs. Health systems and device-makers that can demonstrate automated data uploads and clinical workflow integration will be first to capture payer-aligned use cases.
Networked Pulse Oximeter Market -
Technology convergence: Bluetooth, Wi‑Fi and cellular connectivity, combined with low‑power wearable form factors and cloud analytics, are enabling continuous, networked SpO2 monitoring across settings. The commercialization cadence in 2024–2025 (new product launches and clearances) signals that 2026 will shift from pilots to scaled deployments.
Market Dynamics Executives Must Prioritize
-
Clinical performance and equity: Expect buyers and regulators to demand robust clinical validation across diverse skin tones and physiologic states. Investment in controlled desaturation studies and transparent labeling is no longer optional; it is a market entry ticket.
-
Interoperability and cybersecurity: Compliance with IEC 60601‑1‑2 EMC standards plus FDA cybersecurity expectations should be baked into design and premarket dossiers. Interoperability with hospital information systems (HIS), EHRs, and RPM platforms will be a decisive procurement criterion.
-
Operational and commercial models: Vendors must present not only device performance but also deployment playbooks — logistics for device provisioning, cellular or Wi‑Fi management, clinical escalation pathways, and billing workflows to capture RPM revenues.
-
Consolidation pressure and competitive concentration: The market exhibits a moderate level of concentration among the top vendors. Strategic partnerships, selective acquisitions, and OEM/ODM arrangements will continue to shape who controls clinical workflows versus who supplies sensing components.
Competitive Landscape — How Leading Players Are Positioning
-
Masimo Corporation — Continues to leverage its clinical-grade sensor platforms and wireless PPG offerings, extending into wearable ecosystems and partnerships to broaden reach across acute and ambulatory care. Expect continued emphasis on proprietary signal processing and multi‑parameter integration as differentiators.
-
Medtronic (Nellcor) — Maintains strength in bedside and integrated monitoring, reinforcing presence in acute care networks where established clinical trust matters. Integration into central monitoring systems remains a core advantage.
-
Koninklijke Philips — Focused on modular sensor components and enterprise integrations that connect oximetry data into broader digital health platforms and hospital IT investments. Partnerships and platform playbook choices will drive adoption among health systems.
-
GE HealthCare — Pursuing wearable and wireless backbones that integrate into enterprise monitoring and EHR workflows; strategy emphasizes breadth of clinical device portfolio plus software analytics.
-
Nonin Medical — Strengthening connected consumer‑grade and clinical fingertip offerings with targeted accuracy claims and app ecosystems to serve both OTC and telehealth channels.
-
Nihon Kohden — Reinforces hospital-centric monitoring, focusing on sensor reliability and compatibility with central station monitoring architectures prevalent in Asia and regions with legacy monitoring infrastructure.
-
Contec Medical and Shenzhen Viatom — Chinese producers are scaling Bluetooth‑enabled devices and obtaining incremental regulatory clearances to expand into Western markets; their trajectory is toward cost‑competitive connected devices for telehealth and value care programs.
-
Prevounce Health and OxiWear — Emerging innovators targeting specific remote monitoring niches: cellular‑connected standalone devices and ear‑worn continuous oximetry, respectively. These form factors and connectivity models can disrupt traditional device-to-workstation paradigms.
Recent Developments Shaping 2026 Decisions
-
FDA regulatory guidance (Jan 2025) clarifying testing expectations and labeling requirements for diverse skin pigmentation — impacting device validation plans and clinical study designs.
-
Notable market entries and clearances in 2024–2025, including new cellular and ear‑worn devices and multiple FDA 510(k) clearances, that broaden form factor choices for RPM and continuous monitoring programs.
-
CMS reimbursement updates extending RPM CPT codes and introducing a short‑period readings code in 2026 — creating new revenue levers for providers deploying automated oximetry data capture.
-
Regulatory emphasis on EMC and cybersecurity conformity for wireless devices, accelerating demand for security-by-design and validated communication stacks.
Strategic Playbook — Immediate Actions for 2026
-
Manufacturers: Prioritize robust clinical validation programs aligned with FDA recommendations and ISO standards; package regulatory readiness with interoperability and cybersecurity evidence to shorten procurement cycles.
-
Health systems & IDNs: Pilot cellular and Bluetooth models in RPM pathways that map to updated CPT reimbursement; insist on turnkey operational plans (device lifecycle, patient onboarding, escalation protocols) in vendor RFPs.
-
Payers: Define evidence thresholds for reimbursement that include automated data ingestion, clinical escalation outcomes, and health equity measures. Consider coverage pilots tied to value-based contracts.
-
Investors & M&A teams: Target assets that combine validated sensing technology with software platforms enabling chronic care management and billing automation. Pay special attention to firms with cleared form factors (ear, wearable, cellular) and demonstrated clinical integrations.
-
Technology partners & integrators: Build secure, standards‑based middleware that solves data normalization (SpO2, pulse rate, device metadata), low latency alerting, and audit trails required by both clinicians and regulators.
What PW Consulting’s Report Delivers
-
Proprietary market sizing and forecast models (2020–2032) that quantify the macro opportunity and sensitivities under alternative regulatory and reimbursement scenarios.
-
Vendor scorecards and a competitive action matrix that evaluates technology, regulatory readiness, go‑to‑market capability, and strategic fit for OEM, enterprise and consumer channels.
-
Operational playbooks for scaled RPM deployments, including device provisioning, connectivity management (cellular + Bluetooth + Wi‑Fi), clinical escalation templates, and billing workflows aligned to CPT coding changes.
-
Regulatory and compliance toolkit: checklists for FDA premarket submissions, IEC/EMC and cybersecurity evidence, and labeling that addresses performance across diverse populations.
-
M&A and partnership heatmaps identifying high-value targets by capability and geography, plus scenario-based ROI models for tuck‑ins versus greenfield development.
Using the Report to Inform 2026 Budgets and Roadmaps
Executives preparing 2026 plans should use the report to: align R&D and clinical validation spend to regulatory timelines; sequence product launches that combine validated sensing with interoperability and cybersecurity credentials; design commercial pilots tied to RPM reimbursement mechanics; and prioritize partnerships that complement in‑house strengths. The report’s sensitivity runs and scenario playbooks will help CFOs and strategy leaders stress-test investment cases under conservative and accelerated adoption curves.
Final Observations
The networked pulse oximeter market is maturing into a strategically significant layer of the clinical monitoring stack. With a projected CAGR of 8.75% and the market on a trajectory to materially expand through 2032, organizations that integrate regulatory foresight, clinical validation, interoperable engineering, and pragmatic deployment models will convert technical capability into sustainable commercial advantage. Our full Networked Pulse Oximeter Market report contains the granular segmentation, regional and end‑user breakouts, and vendor-level datapoints needed to operationalize these recommendations.
For PW Consulting clients and prospective subscribers seeking the complete dataset, vendor scorecards, and tailored advisory engagements that convert this market intelligence into 2026 action plans, please visit our report page or contact our industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Networked Pulse Oximeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Lock Market to Expand at a 6.15% CAGR from 2026–2032
By PW Consulting, 2026-07-13
Lock Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive preview — why this report matters to decision-makers in 2026
PW Consulting’s Lock Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes market-scale modeling, competitive mapping, and practical go-to-market playbooks tailored for industrial, commercial, and residential security stakeholders. The global lock market reached an estimated USD 38,500 Million in 2025 and, under our central forecast, expands at a 6.15% compound annual growth rate (CAGR) to exceed USD 58,400 Million by 2032. These macro dynamics — combined with mounting input-cost pressures and a shifting competitive topology — make the report an operational tool for procurement chiefs, product heads, M&A teams, and public-sector buyers planning for 2026 and beyond.
Lock Market
Headline market signals
- Structural growth, but uneven conversion: After a recovery phase through 2024–2025, the market enters a consistent mid-single-digit CAGR period to 2032. Adoption of digital and electromechanical access systems is an important growth engine, but mechanical solutions remain resilient across many end markets.
- Fragmented supply base: Market concentration remains low—our CR3 is 18.5% and CR5 is 25.4%—indicating opportunities for consolidation as well as room for specialized niche players to capture premium pockets of demand.
- Cost and trade shocks are material: Elevated tariffs on steel and aluminum (including a U.S. Section 232 increase to 50% in mid‑2025) and new import measures affecting North American supply chains have materially raised procurement risk and compressed margins for incumbents that rely on commodity metals.
- M&A and portfolio reshaping are accelerating: Strategic bolt‑on acquisitions—especially in high‑security and electromechanical segments—are being prioritized by large OEMs seeking to broaden technology stacks and route-to-market.
What’s in the report — practical deliverables for 2026 action
The study is designed as an executive playbook, not an academic exercise. Key operational components include:
Lock Market
- Top-line market modeling (historical 2020–2025, base year 2025) and scenario forecasts (2026–2032) with sensitivity testing for raw-material shocks and policy shifts.
- Competitive heat maps and strategic profiles for the leading OEMs and challengers, with acquisition overlays and capability matrices to support partner selection and M&A screening.
- Channel and commercial playbooks: pricing levers, retrofit vs. new‑build go‑to-market strategies, and a modular partner model for system integrators and value-added resellers.
- Procurement & supply-chain checklist: sourcing alternatives, near‑shoring decision matrix, and hedging recommendations tuned to metal-price volatility and tariffs.
- Technology adoption roadmap: product and services blueprints for migrating customers from mechanical to electromechanical and connected access systems while mitigating cybersecurity and regulatory risk.
- Deal flow and valuation appendices: comparable-transactions framework, synergy templates, and an anonymized short list of targets and partners suitable for strategic buyers and private equity.
Competitive landscape — who matters and why
The market is populated by a mix of global platform players, regional champions, and specialized security houses. The report’s competitive section does not simply rank suppliers by size; it evaluates strategic moats, channel reach, product breadth, and integration risk. Highlights:
Lock Market
- Global platform leaders: Long-established multinational groups are leveraging scale to combine mechanical, electromechanical, and digital offerings into bundled enterprise solutions. These incumbents are the default choice for customers prioritizing global supply consistency and wide service networks.
- Regional and brand-centric players: Well‑known North American and APAC brands maintain strong consumer and commercial positions through retail, locksmith channels, and localized manufacturing advantage—important when tariffs and shipping costs bite.
- Specialists and high‑security houses: Niche firms focused on patented cylinders, safe locks, and government/industrial credentials are becoming prime targets for acquisitions by platform players seeking to add certified high‑security capabilities quickly.
Recent market activity underscores these dynamics. A case in point: the integration of an established high‑security lock specialist into a global group in late 2025–early 2026 has accelerated consolidation in certified security segments and creates new cross‑sell opportunities within institutional and government channels. For buyers and investors, this validates a two-track strategy: (1) scale through platform consolidation of complementary technologies; and (2) defend margins by owning premium, patented product lines that command structural price protection.
Regulatory and input-cost headwinds — operational implications
Three near-term themes require active mitigation planning in 2026:
- Tariff risk and sourcing flexibility: Tariff increases and trade measures introduced in 2025 disproportionately impact lock makers that source heavy-gauge steel or import finished locksets. The report’s procurement playbook maps practical near‑term actions: dual-sourcing, regional manufacturing pivots, and contract clauses for pass‑through pricing.
- Raw-material volatility: Steel price swings increase working capital needs and inventory risk. We outline inventory hedging strategies and just‑in‑time vs. just‑in‑case sourcing tradeoffs for different product families.
- Certification and procurement policy: Government and institutional tenders are increasingly looking for certified, traceable supply chains. Firms that can rapidly demonstrate chain-of-custody, anti-counterfeit measures, and compliance with procurement regimes will gain a procurement premium.
Technology and product strategy — seize the transition
The shift toward electromechanical and connected access is both a growth lever and an operational challenge. The report provides an action framework for 2026 that includes:
- Product roadmaps balancing legacy mechanical offerings (serviceable, price-sensitive) with higher-margin smart-lock systems (subscription and software revenue potential).
- Integration templates for cybersecurity hardening, lifecycle software updates, and cloud/on-premise hybrid deployment options demanded by enterprise and government buyers.
- Aftermarket and services monetization models: managed access services, retrofit kits, and long-term maintenance contracts that smooth cyclicality and increase customer lifetime value.
Dealmaking and capital allocation — where to place bets in 2026
Given a fragmented market and mid-single-digit CAGR tailwinds, our advisory view for boards and private investors centers on three portfolio plays:
- Buy-and-build in high-security niches: Acquire certified specialist firms to obtain IP, channel trust, and contract stickiness in government and critical infrastructure markets.
- Scale digital offerings through partnerships: Pursue strategic tie-ups with cloud and cybersecurity vendors to accelerate time-to-market for connected access platforms while preserving manufacturing independence.
- Operational resilience investments: Allocate capital to regional manufacturing and inventory flexibility to protect margins from tariff shocks and metal-price volatility.
Practical recommendations for 2026 decision-makers
- Prioritize a supply‑chain stress test in Q1 2026 that models tariff, shipping, and steel‑price scenarios; implement rapid contingency actions for single‑source components.
- Accelerate product modularization so mechanical and electromechanical components can be mixed-and-matched without long redesign cycles—this reduces time-to-revenue for retrofit opportunities.
- Formalize an M&A screening funnel focused on patented high‑security technologies, cloud‑native access management, and regional manufacturing platforms.
- Invest in service capabilities and recurring-revenue offers (managed access, software subscriptions) to soften capital spending cyclicality among OEM customers and landlords.
- Engage proactively with procurement authorities and certification bodies to shape standards that favor traceable, anti‑counterfeit manufacturing and secure update channels.
How to use the PW Consulting report
This release is a strategic preview intended to orient boards, executive teams, and investors. The full PW Consulting Lock Market report provides the granular segmentation, channel breakouts, and scenario spreadsheets necessary to execute the recommendations above. In keeping with our “trailer” approach, we intentionally reserve proprietary sub‑segment percentages and granular regional/application-level figures for the full publication—these are provided with source data, spreadsheets, and an implementation workbook to buyers of the report.
Final note — timing and next steps
2026 is a year of choices: react defensively to input-cost and tariff pressure, or act offensively to capture long-term value from digitalization and consolidation. PW Consulting’s Lock Market report equips leaders with modeled outcomes, prioritized initiatives, and executable templates to make those choices with confidence. For teams that want immediate tactical support, we offer advisory sprints to operationalize procurement resilience, product roadmaps, and M&A diligence informed by the study’s confidential annexes.
To access the full study, scenario files, and the implementation workbook, please consult PW Consulting’s Lock Market report page or contact our industry practice for a briefing and customized executive summary tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Lock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


