



PW Consulting: Commercial Ice Machine Market to Hit $332M by 2032 on 7.45% CAGR
By PW Consulting, 2026-09-16
Beyond Thermal Output: Strategic Intelligence for the 2026 Commercial Ice Machine Market
The commercial ice machine sector has quietly transitioned from a commoditized utility play to a capital-intensive, regulation-sensitive infrastructure decision. Across foodservice, healthcare, and retail environments, ice systems are no longer evaluated solely on daily production capacity. Facility managers, procurement officers, and capital equipment planners now weigh energy compliance, refrigerant transitions, sanitation certification, and total cost of ownership against volatile supply chain conditions. As we move deeper into the 2026–2032 forecast window, the organizations that will secure margin protection and operational continuity are those making their ice equipment decisions with granular, forward-looking intelligence rather than historical benchmarks.
PW Consulting’s newly released Commercial Ice Machine Market research is structured as a decision-grade intelligence asset. It moves past surface-level market commentary to deliver executable procurement roadmaps, competitive positioning frameworks, and regulatory readiness checklists. The following overview outlines what the study covers, why the 2026 decision window is structurally distinct, and how leadership teams can translate market velocity into risk-adjusted capex and opex strategy. The core segment valuations, regional breakouts, and proprietary forecasting layers are reserved for the full report, where the complete analytical architecture can be navigated without dilution.
A Market in Structural Expansion: Why 2026 Is a Pivotal Inflection Point
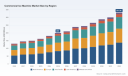
The commercial ice machine market has demonstrated consistent expansion over the past half-decade, with revenue compounding from approximately USD 130.5 million in 2020 to an estimated USD 200.0 million in 2025. The trajectory reflects more than post-pandemic normalization. It signals a durable alignment between hospitality recovery, healthcare sanitation mandates, retail cold-chain sophistication, and industrial cold processing requirements. Looking forward, the forecast period extends through 2032, with market revenue projected to surpass the USD 330 million threshold by the close of the outlook window. This expansion is supported by a CAGR of 7.45 percent, a pace that places ice equipment alongside other commercial kitchen and facility infrastructure categories experiencing sustained institutional demand.
Commercial Ice Machine Market
Ice Cream Machine Market
For enterprise planners, a double-digit compound growth trajectory carries a specific strategic implication: delay is expensive. Capacities installed in 2026 will remain in operation well into the next decade, and the operating environment those machines face will be shaped by tightening energy expectations, evolving refrigerant policy, and heightened sanitation enforcement. The report uses the full 2020–2032 timeline to frame not just where the market has been, but which cohorts of demand are structurally permanent versus which are cyclical. Decision-makers are given a calibrated view of how near-term procurement cycles interact with long-lived asset exposure, enabling more disciplined budgeting across multi-year capex programs.
Competitive Architecture: Concentration, Positioning, and the Strategic Playbook
The commercial ice equipment landscape is not a fragmented free-for-all. Market concentration metrics underscore a consolidated environment in which a relatively small group of manufacturers commands the majority of share. The report examines this structure through the lens of competitive moats, channel leverage, and innovation cadence rather than simple shipment rankings. With CR3 levels at 65.0 percent and CR5 levels at 85.0 percent, competitive dynamics are defined by brand trust in sanitation-critical environments, dealer and service network density, and the ability to deliver certified, energy-optimized platforms across multiple ice formats.
Several established players anchor this ecosystem. Hoshizaki America, headquartered in Fayetteville, Georgia, manufactures commercial ice machines across flaker, nugget, and cube configurations, with a consistent emphasis on NSF-listed models and energy-efficient options. The company’s recent 2026 product calendar reinforces this positioning: an updated commercial product brochure released in April highlighted improved energy efficiency and hygiene options across 2026 model years, followed in May by an expanded cube ice portfolio under the new IM CUBE series, which incorporates UV sanitization alongside energy and water savings. Such moves illustrate a broader industry pattern in which premium differentiation is increasingly tied to integrated sanitation and resource efficiency rather than production volume alone.
Manitowoc Ice, based in Manitowoc, Wisconsin, focuses on engineered commercial ice machines for foodservice, hospital environments, and high-volume applications, supported by dealer networks that extend service reach and installation fidelity. In May 2026, the company continued its refrigerant transition toward R290 while advancing supply chain optimizations designed to enhance commercial ice machine performance. This trajectory reflects the operational reality that after-sales reliability, parts availability, and service responsiveness often matter as much as the hardware specification itself.
Scotsman Ice Systems, operating from South Carolina, is recognized globally as a leading manufacturer of commercial ice machines, offering modular and countertop models with a clear focus on foodservice reliability. Ice-O-Matic, also U.S.-based, specializes in commercial ice machines and dispensers built around modular designs tailored to restaurants and institutions. Grant Ice Systems manufactures industrial and commercial units, including nugget and flake types designed for high-capacity requirements. Follett Ice delivers commercial ice machines and dispensers with integrated technology aimed at foodservice operations, while Maxx Ice offers self-contained and premium indoor/outdoor commercial ice machines, several with Energy Star listings. Summit Appliance produces commercial ice makers certified to NSF-12, with production ranges spanning from 55 lb to 210 lb. Outside the U.S. incumbent core, Naixer Ice, based in China, serves as a global supplier of commercial ice makers with NSF certification and product catalogs designed for international distribution. Morris Thermal rounds out the competitive field by producing custom industrial ice makers with Tube-Cube and Nugget technologies suited to food processing and high-volume use.
The report does not stop at company profiles. It maps how these players compete across product families, service architectures, and compliance readiness, and it highlights where concentration creates pricing discipline versus where niche innovation can still open addressable pockets. This structure is especially valuable for procurement teams evaluating not only unit cost but the strategic risk of vendor lock-in, parts dependency, and long-term service support across dispersed locations.
Regulatory Dynamics, Certification Realities, and the 2026 Compliance Landscape
One of the most consequential layers of the 2026 decision environment is regulatory and certification pressure. Commercial ice machines sit at the intersection of energy policy, refrigerant mandates, and food safety standards, making compliance a design constraint rather than an optional add-on. As of May 2026, commercial ice machines must meet ENERGY STAR performance specifications or equivalent performance thresholds if not labeled as such. In parallel, Florida Water Star has required these standards for appliances, tying water and energy efficiency into broader building and equipment approval frameworks. For multi-site operators with exposure to these jurisdictions, the implication is straightforward: efficiency performance is becoming a purchasing prerequisite, not merely a sustainability talking point.
Refrigerant transitions are equally influential. In November 2025, Hoshizaki transitioned 66 of its ice maker models to R-600a and R-290 refrigerants, achieving over a 99 percent reduction in global warming potential. This shift reflects a wider industry migration toward lower-GWP alternatives and demonstrates how OEMs are redesigning platforms to align with both federal direction and customer expectations around environmental footprint. The EPA SNAP rule further shapes the market by allowing specific refrigerants, including HFC-32, R-454A, R-454B, R-454C, R-455A, R-457A, and R-516A, for use in new commercial ice machines under defined conditions. Compliance with these pathways requires vendors and buyers alike to track approval conditions and equipment eligibility, especially as state-level timelines and federal requirements interact.
Certifying bodies add another layer of non-negotiable scrutiny. NSF/ANSI Standard 12 certification is mandatory for all U.S. commercial ice machines sold in foodservice to ensure sanitation and food safety compliance. This requirement creates a structural barrier to entry for unverified equipment and makes certification status a baseline procurement filter. On the regulatory timing side, the Washington Department of Ecology issued an interpretive statement in December 2024 delaying the HFC prohibition effective date for automatic commercial ice machines to align with federal 2026–2027 requirements. The interplay of federal and state regulatory calendars means that what appears to be a single compliance decision often requires multi-jurisdiction validation. The report organizes these dynamics into actionable categories so that facility and procurement leaders can map equipment selection to the specific standards that govern their locations and use cases.
What the Report Delivers: An Operational Intelligence Framework
PW Consulting’s Commercial Ice Machine Market study is designed for teams that need more than directional market commentary. The deliverable combines macroeconomic trajectory, product-form dynamics, application-driven demand behavior, regional performance context, and competitive profiling into a coherent planning tool. The research architecture is built around several practical components.
- Historical baseline and forecast modeling spanning 2020 through 2032, providing a continuous revenue view that supports budgeting, capacity planning, and trend validation across multiple forecast vintages.
- Product-form analysis across cube, flake, nugget, and other configurations, examining how production footprint, ice characteristics, and operational use cases drive adoption across foodservice, healthcare, retail, and industrial settings.
- Application-based demand mapping that distinguishes between high-volume commercial foodservice requirements, healthcare sanitation-sensitive environments, retail point-of-use needs, and broader institutional or industrial deployments.
- Regional context that situates market performance across major geographies without forcing simplistic generalizations, helping multinational operators and domestic chains calibrate rollout priorities based on infrastructure maturity, regulatory exposure, and demand density.
- Competitive profiling of leading manufacturers and emerging suppliers, including product positioning, certification posture, and recent innovation or catalog activity, enabling side-by-side evaluation of vendor options and service implications.
- Regulatory and certification tracking that consolidates ENERGY STAR expectations, SNAP-listed refrigerant pathways, state-level interpretive actions, and NSF/ANSI Standard 12 requirements into a usable compliance overview for procurement teams.
- Decision-support frameworks that translate market information into purchasing criteria, replacement-cycle logic, and vendor-selection checklists aligned to operational continuity and total cost of ownership.
This structure is intentionally practical. It is not a static market snapshot but a tool that supports recurring decisions: whether to replace aging units now or stage the transition; how to weigh efficiency-certified platforms against upfront cost; which product formats align with specific site profiles; and how to interpret competitive moves such as refrigerant migrations, UV sanitization integration, and modular design refinements. By tying these considerations to a single research baseline, the report reduces the risk of fragmented decision-making across departments that often evaluate equipment from different angles.
Why the Full Intelligence Set Matters for 2026 Procurement and Planning
Strategic procurement in a market growing at a mid-to-high single-digit CAGR is not simply a matter of identifying the cheapest compliant unit. The real decision space includes service network coverage, spare-parts availability, energy-cost exposure over the machine’s service life, regulatory drift, and the operational consequences of choosing a platform that may not align with future certification or efficiency expectations. In a market where a concentrated group of manufacturers controls a substantial share, vendor selection also carries concentration risk and dependency considerations that should be weighed explicitly rather than inferred from spec sheets alone.
The report is built to support that level of evaluation. It gives teams a structured way to interpret market momentum, segment behavior, competitive responses, and compliance shifts without relying on fragmented sources or outdated assumptions. The full study preserves the detailed segment valuations, regional performance context, application-level demand breakdowns, and forward forecasting layers that enable scenario-based planning. Those components are essential for organizations that need to justify capex against auditable market evidence, compare vendors on a consistent basis, and anticipate how regulation and technology will reshape operating economics through 2032.
Navigating the Market with Proven Strategic Intelligence
The commercial ice machine market in 2026 rewards teams that plan with precision. Growth is real, concentration is high, and the regulatory environment is actively reshaping product design and procurement criteria. In that context, the difference between reactive replacement and strategic deployment is information quality. PW Consulting’s Commercial Ice Machine Market research is intended to provide that information in a form that procurement, operations, and finance leaders can use immediately.
The complete report includes the full market sizing arc, segment-level insight, regional performance context, competitive analysis, and the compliance and certification frameworks that define viable equipment selection in the current period. For organizations preparing multi-site deployments, lifecycle replacements, or technology refresh cycles, the full intelligence set offers the depth required to make decisions with confidence rather than approximation. The core data, scenario-ready forecasts, and category-specific evaluations are available through the complete study, where the analytical detail and proprietary market architecture can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Commercial Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Shredder Market Hits $1.27B in 2025, Projected to Reach $1.77B by 2032 at 4.9% CAGR
By PW Consulting, 2026-09-16
Industrial Shredder Market Outlook 2026: Strategic Intelligence for Capital Allocation and Competitive Positioning
Executive Summary
The industrial shredder sector is entering a phase of disciplined, technology-led expansion. As organizations across recycling, waste management, and secure destruction verticals navigate tightening compliance mandates, input cost volatility, and accelerating decarbonization requirements, capital deployment decisions require more than top-line growth projections. They demand granular visibility into demand drivers, equipment segmentation, regional adoption patterns, and the competitive maneuvers shaping pricing and innovation velocity. Our latest Industrial Shredder Market study delivers that visibility, mapping the trajectory from 2020 through 2032 with a forecasting architecture calibrated to the operational realities of procurement cycles, plant retrofits, and OEM capacity planning.
For decision-makers operating on a 2026 timeline, this research functions as a strategic filter. It separates structural growth from cyclical noise, identifies where margin expansion is realistically achievable, and highlights the operational and regulatory variables that will determine whether a capital investment translates into long-term competitive advantage. Below, we outline the scope of the analysis, the market architecture it reveals, and the actionable intelligence it provides for enterprise strategy teams, equipment procurement leaders, and investment stakeholders.
Market Trajectory: A Multi-Year Expansion Built on Structural Demand
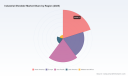
Over the historical window from 2020 to 2025, the industrial shredder market established a consistent upward arc, reflecting sustained investment in material recovery infrastructure, confidential waste processing, and volume-reduction systems across industrial and municipal environments. The base year closes at a revenue level of approximately 1,268 million USD, representing a meaningful step beyond the pre-2023 baseline. That momentum carries into 2026, with the market positioned at roughly 1,295 million USD as operational budgets normalize, replacement cycles accelerate, and new compliance-driven procurement enters the pipeline.
Looking ahead across the 2026–2032 forecast window, the trajectory compounds at a steady pace. The overall market is projected to reach close to 1,773 million USD by 2032, translating to a forecast-period CAGR of 4.9 percent. This growth profile does not suggest a speculative surge; rather, it reflects compounding demand from end-use sectors that depend on size-reduction equipment as core operational infrastructure. For strategic planners, the implication is clear: industrial shredders are no longer peripheral tools but critical assets whose selection, procurement timing, and technology configuration have direct consequences for throughput efficiency, total cost of ownership, and downstream compliance performance.
The research emphasizes that the growth curve will not be uniform across all equipment classes or end-use categories. Instead, it is being shaped by diverging requirements around material hardness, particle-size outcomes, energy intensity, and regulatory documentation standards. As a result, the strategic question for 2026 is not simply where the market is heading, but which segments are best positioned to capture disproportionate value and which operational parameters should govern capital allocation.
Strategic Segmentation: Why Configuration and Application Matter More Than Ever
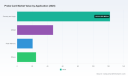
A central contribution of this study is its detailed breakdown of demand by equipment configuration and application context. These dimensions matter because they directly influence capacity selection, maintenance intensity, throughput consistency, and return-on-investment timelines. The findings show that double-shaft systems have emerged as a dominant configuration within the overall equipment base, reflecting their widespread applicability for metals, plastics, wood, tires, and mixed waste streams. Single-shaft and three-shaft designs continue to play specialized roles where controlled particle sizing, material separation, or operational flexibility is prioritized. Four-shaft configurations occupy a narrower but strategically important niche where high consistency and intensive volume reduction are required.
On the application side, the market is shaped by several core demand streams. Scrap metal recycling remains the largest end-use driver, underpinned by the ongoing need for efficient downsizing of ferrous and non-ferrous scrap prior to melting and reprocessing. WEEE recycling represents a significant and expanding application, reflecting both regulatory pressure and the materials recovery value embedded in electronic and electrical waste. Wood waste recycling, paper waste recycling, and a range of additional applications round out the demand base, each with distinct operational requirements around output grading, contamination handling, and equipment wear.
What this segmentation reveals for 2026 strategy is that purchasing decisions cannot be made on a single specification sheet. A facility prioritizing high-volume scrap processing may benefit from robust multi-shaft configurations with high wear-resistance characteristics, while an operation focused on confidential document destruction or specialized material recovery may need different installation profiles, control architectures, and documentation-capable output standards. The study quantifies these dynamics and links them to demand share, equipment value distribution, and the practical implications for capacity planning—details that procurement teams can translate directly into specification requirements and vendor evaluation criteria.
Competitive Dynamics and the Battle for Differentiation
The industrial shredder landscape is moderately concentrated, with the leading firms commanding a meaningful share of total revenue and leveraging established engineering capabilities, service networks, and regional presence. The report profiles a competitive set that includes Shred-Tech, Vecoplan, SSI Shredding Systems, Franklin Miller, UNTHA, BCA Industries, Zato North America, Williams Patent Crusher & Pulverizer Co., SatrindTech Srl, and Allegheny Shredders. These organizations are not competing on price alone; they are contesting the market through product architecture, application specialization, service responsiveness, and the ability to align equipment performance with the operational constraints of each end-use segment.
Recent developments make the competitive rhythm especially visible. In 2025, SSI Shredding Systems introduced a new SR900F shredder designed for high-volume RDF production, reinforcing the continued link between shredding capacity and alternative fuel feedstock preparation. That same year, SSI exhibited at PPRC 2025 in Chicago, underscoring the importance of trade channels in shaping buyer expectations and technology diffusion. In 2026, UNTHA showcased two new machine designs alongside the latest evolution of its XR series at IFAT Munich, signaling continued investment in design refinement and application versatility. Meanwhile, Franklin Miller completed a notable TASKMASTER TM4000 shredder installation, highlighting the operational relevance of high-capacity systems in real-world processing environments.
Industrial Shredder Market
Worldwide kitchen Waste Shredder Market
These events are more than product announcements; they are indicators of where the market is moving. OEMs are increasingly orienting development toward energy efficiency, material compatibility, throughput reliability, and ease of integration into broader recycling or destruction workflows. For enterprises evaluating suppliers, that shift changes the evaluation framework. Technical specifications still matter, but so do control-system intelligence, service accessibility, parts availability, and the vendor’s ability to support compliance documentation and long-term operating efficiency. The study examines these competitive levers in detail, connecting them to pricing posture, installed-base considerations, and the strategic positioning of each major player.
Operational Realities Shaping Demand and Procurement Decisions
Behind the headline growth figures lies a set of operational variables that directly influence equipment selection and total cost of ownership. One of the most practical considerations is cutter and blade material performance. High-wear alloy cutters used in industrial shredder blades typically cost 15–30 percent more than baseline D2 steel, but they deliver materially longer service life in impact-prone applications. For facilities running mixed loads, abrasive waste streams, or high-throughput metal processing, that upfront premium can substantially reduce downtime and maintenance frequency. The report assesses when such premium components are strategically justified and how they affect lifecycle cost modeling.
Energy performance is another increasingly decisive factor. New industrial shredder models are delivering up to 15 percent energy savings through smart control technologies, a substantial improvement for installations where power intensity and operating hours drive recurring costs. As organizations face both economic and sustainability targets, control-system intelligence, load optimization, and process automation are becoming key differentiators in vendor selection. The study analyzes how these efficiency gains influence operating economics and whether they are sufficient to alter the evaluation calculus for new installations versus retrofits.
Safety and compliance also remain critical inputs to procurement strategy. OSHA incident records underscore the operational risk environment, documenting an amputation of an employee’s hand caused by an industrial shredder. That kind of incident reinforces the importance of engineered safeguards, operator training, interlock design, and site-specific risk management protocols. At the same time, confidentiality and destruction standards are tightening in specific application areas. The UNE EN 15713 standard establishes recommendations for the management and control of confidential document destruction processes using industrial shredders, while UNE 15713 provides post-destruction information confirming the type of industrial shredder used to divide documents into portions barely containing two letters. These standards matter not only for compliance teams but also for equipment specification, because they influence output requirements, traceability expectations, and the documentation capabilities buyers demand from their shredding systems.
Taken together, these dynamics mean that the 2026 procurement process is increasingly multidisciplinary. Engineering teams must consider wear performance and energy optimization; environmental and compliance teams must factor in destruction documentation and recycling output requirements; and operations leaders must integrate safety, maintenance access, and service reliability into the final selection. The report is structured to support that cross-functional decision-making by aligning equipment analysis with the operational realities buyers face on the plant floor.
What the Study Delivers: Practical Intelligence for 2026 Decision-Making
This Industrial Shredder Market research is designed to convert macroeconomic and competitive signals into a usable decision framework. Rather than offering a single aggregate number, it builds a layered picture of demand, equipment configuration, application distribution, regional structure, and competitive performance. The analytical scope includes historical size evolution, forecast modeling through 2032, and segmentation that shows how value and volume are distributed across equipment types and end-use applications.
Key practical outputs include:
- A structured view of market size progression from 2020 through the 2026–2032 forecast horizon, enabling planners to benchmark internal expectations against the broader industry trajectory.
- Segment-level demand architecture across equipment configurations and application categories, helping procurement teams match specifications to actual operating conditions rather than generic requirements.
- Competitive profiles and recent development tracking for major OEMs, giving strategy and sourcing teams context on product evolution, installation activity, trade-show presence, and technology direction.
- Operational and regulatory context that influences equipment performance, maintenance, safety, and compliance documentation, supporting more realistic total cost of ownership models.
- Insights into efficiency trends, material-handling requirements, and the cost-performance trade-offs that affect whether a buyer should prioritize throughput, particle-size control, energy savings, or wear resistance.
Importantly, the study is built to support scenario planning. Because market growth is shaped by multiple variables—material recovery demand, regulatory tightening, energy and input cost dynamics, and technology adoption—decision-makers need the ability to test assumptions against different operational contexts. The report provides that flexibility by connecting aggregate market structure to the practical choices that determine project success, whether the priority is secure destruction, scrap preparation, WEEE processing, wood waste reduction, paper recovery, or broader mixed-waste downsizing.
How to Use This Research in 2026 Planning Cycles
For executives and analysts entering 2026 planning, this study is useful in several concrete ways. It supports capital budgeting by clarifying where demand is structurally strongest and how equipment classes align with those demand centers. It strengthens vendor evaluation by situating supplier activity within a competitive landscape defined by recent launches, installations, and application-specific development. It improves risk management by integrating safety incidents, compliance standards, wear-material economics, and energy-efficiency improvements into the equipment selection conversation. And it sharpens strategic positioning by revealing where concentration, specialization, and technology differentiation are likely to influence pricing and service competitiveness over the forecast period.
The full analysis contains the detailed segmentation structures, regional breakdowns, application-level market values, and competitive assessments needed to convert strategic objectives into procurement, investment, and sourcing decisions. Because the granular figures, subsegment allocations, and proprietary interpretations are central to the report’s value proposition, this preview intentionally highlights the analytical framework and the decision-relevant themes without reproducing the full dataset.
Whether your objective is to evaluate new equipment investment, reassess existing shredding capacity, benchmark supplier options, or align sustainability and compliance targets with operational realities, the complete study provides the depth required to move from market awareness to informed action.
Next Steps
To access the full market sizing, segmentation detail, competitive analysis, and forecast interpretation, readers are encouraged to explore the complete Industrial Shredder Market report. The complete version delivers the underlying figures, regional and application-level intelligence, and strategic context needed to support 2026–2032 planning with precision.
For detailed analysis of this topic, please visit the official page: Industrial Shredder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Probe Card Market Hits $215M in 2025, Projecting 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Probe Card Market: Strategic Intelligence for 2026 Decision-Makers
The semiconductor testing ecosystem stands at a critical inflection point. As chip architectures grow more complex and production volumes scale to meet demand from artificial intelligence, high-performance computing, and advanced memory technologies, the probe card segment has evolved from a commoditized testing accessory into a strategic bottleneck that directly influences yield, time-to-market, and overall fab economics. PW Consulting recent comprehensive analysis of the probe card market provides executives, investors, and supply chain leaders with the structured intelligence required to navigate this shifting landscape through 2032. This overview outlines the strategic value embedded in the full report and demonstrates why forward-looking organizations are already integrating these insights into their 2026 planning cycles.
The Macro Trajectory: A Market Compounding at Strategic Pace
Historical performance paints a clear picture of sustained expansion. Between 2020 and 2025, the global probe card market progressed from approximately 163.15 million USD to 215.0 million USD, reflecting consistent annual appreciation as semiconductor manufacturers ramped advanced node production and expanded test floor capacities. Looking ahead, the forecast period spanning 2026 through 2032 projects the market to reach 344.8 million USD by the terminal year, driven by a compound annual growth rate of 6.98 percent. These figures are not merely retrospective summaries. They establish the baseline against which capital allocation, capacity planning, and supplier relationship strategies must be measured.
For executives evaluating 2026 initiatives, this trajectory signals that demand will continue outstripping incremental supply in specialized segments. Organizations that treat probe card procurement as a routine operational expense risk encountering throughput constraints, elevated lead times, and compromised test reliability. Conversely, firms that align their testing infrastructure roadmaps with the documented growth curve position themselves to capture efficiency gains, negotiate from a position of informed leverage, and mitigate the operational friction that arises when test capacity becomes the pacing item for wafer output.
Report Architecture: Operational Intelligence Over Abstract Commentary
The full PW Consulting study is structured to translate market dynamics into executable strategy. Rather than offering high-level commentary, the report delivers a granular examination of the segments, players, and structural forces that define purchasing decisions and competitive positioning.
Worldwide Probe Cards Market
- Segmentation Analysis: The research dissects the market across multiple structural dimensions, mapping historical performance and forward projections to reveal where volume concentrates, where margins expand, and where technological transitions are reshaping procurement requirements. Readers gain clarity on which product architectures dominate current deployment and which emerging formats are gaining traction as chip designs push beyond conventional testing limits.
- Competitive Landscape Mapping: Profiles of leading manufacturers are synthesized to illustrate capability portfolios, geographic footprints, and strategic postures. The analysis covers how differentiated product platforms, manufacturing scale, and regional specialization influence supplier selection and long-term partnership viability.
- Market Structure and Concentration Metrics: Concentration indicators are evaluated to provide context on pricing power, negotiation dynamics, and the realistic availability of alternative suppliers. Understanding the degree of consolidation helps procurement teams assess supply risk and structure contracts that balance cost efficiency with continuity assurance.
- Forward-Looking Scenarios: The forecast framework extends through 2032, enabling planners to model capacity requirements, evaluate investment timing, and stress-test supply strategies against varying demand trajectories. This multi-year horizon supports decisions that extend beyond quarterly procurement cycles.
Competitive Dynamics: Strategic Moves Redefining the Supplier Base
The competitive environment is not static. Recent developments throughout 2025 and early 2026 reveal a pattern of partnerships, capacity investments, and supply agreements that are actively reshaping the probe card ecosystem. These moves carry direct implications for buyers evaluating supplier stability, technology access, and long-term availability.
In February 2025, Advantest Corporation announced strategic partnerships and minority investments involving FormFactor Inc. and Technoprobe S.p.A., signaling coordinated efforts to align probe card technology development with broader tester and test methodology roadmaps. Such collaborations tend to accelerate innovation cycles while also influencing which suppliers can offer integrated solutions that span testing hardware and probe card platforms.
Production capacity and supply continuity have also become focal points. In May 2025, Micronics Japan Co., Ltd. acquired a strategic stake in Hermes Testing Solutions Inc. to strengthen probe card solution presence in Taiwan, a move that reflects the growing importance of regional testing ecosystems and localized support for advanced logic and memory fabrication. Later that year, in December 2025, WinWay Technology Co., Ltd. entered a five-year supply agreement with Technoprobe for MEMS probe card production, underscoring how multi-year commitments are being used to secure access to specialized probe technologies amid rising demand.
Capacity expansion continues to define the competitive frontier. In March 2026, Technoprobe S.p.A. announced a new manufacturing facility in Italy, with operations expected to ramp by the end of the year. This investment illustrates how leading suppliers are building additional production throughput to accommodate sustained demand and reduce lead-time exposure for high-end probe card applications.
Collectively, these developments indicate that suppliers are investing aggressively in both technology collaboration and manufacturing scale. Buyers who understand the structure and intent behind these moves can better anticipate shifts in availability, negotiate more effectively, and align their own product roadmaps with suppliers whose strategic direction complements their testing requirements.
Structural Pressures: Tariffs, Export Controls, and Supply Chain Constraints
Beyond corporate strategy, the probe card market is navigating a layer of external pressures that directly affect cost structures, lead times, and regional supply availability. These forces are not peripheral. They are increasingly embedded in procurement risk assessments and capacity planning assumptions.
Tariff actions on semiconductor equipment and materials have introduced cost escalation and delivery friction into the manufacturing environment. The resulting production slowdowns and extended delivery timelines have raised the operational stakes for test floor planning, particularly for organizations that rely on just-in-time provisioning of probe cards and associated consumables.
Geopolitical and export control dynamics are compounding these challenges. Restrictions involving gallium, germanium, and rare earth magnets have constrained specialty material supply chains, with direct consequences for probe card production and component availability. At the same time, export restrictions on advanced probe card designs have encouraged domestic capacity expansion among regional manufacturers focused on mature node production. This bifurcation between advanced and mature node supply paths is creating divergent procurement realities across different fab segments and geographic markets.
Lead-time visibility has emerged as a critical operational metric. Recent industry reporting has highlighted probe card lead times extending significantly as demand for AI chip testing surges, placing additional pressure on test scheduling and production ramp coordination. In parallel, the limited global availability of ultra-low-resistance probe materials is introducing medium-term supply chain risk for advanced node production, where electrical performance requirements leave little tolerance for substitution or delay.
These structural pressures reinforce the need for intelligence that goes beyond headline market size. Organizations require a clear view of where vulnerabilities concentrate, which material and design constraints are likely to persist, and how supplier strategies are adapting to regulatory and logistical headwinds.
Why 2026 Decision-Makers Need This Analysis Now
The convergence of sustained market growth, intensifying supplier competition, and external supply chain pressures creates a decision environment where information asymmetry carries tangible cost. Enterprises that enter 2026 without a structured understanding of probe card market dynamics risk making procurement, capacity, and partnership decisions based on incomplete or outdated assumptions.
The PW Consulting study is designed to close that gap. It equips leadership teams with the context needed to evaluate supplier proposals, assess the credibility of capacity expansion claims, and determine where strategic inventory or multi-source arrangements may be warranted. For capital planners, the forecast horizon supports modeling of test infrastructure investments aligned with realistic demand trajectories. For competitive analysts, the combination of segment mapping, concentration metrics, and recent corporate developments offers a basis for anticipating where market share shifts are most likely to occur.
Equally important, the report helps organizations distinguish between short-term market noise and durable structural trends. In a sector where technology transitions, regulatory actions, and supplier consolidation can each reshape procurement conditions within a single planning cycle, separating signal from noise is a strategic necessity.
What the Full Report Delivers Beyond This Overview
This article provides a directional summary of the market environment and the strategic considerations that should inform 2026 planning. It intentionally does not enumerate detailed segment splits, regional revenue breakdowns, application-level valuations, or product-type market shares. Those granular datasets form the analytical backbone of the complete study and are essential for precise budgeting, sourcing strategy, and scenario modeling.
The full report provides the depth required to translate high-level growth signals into actionable procurement and investment decisions. It includes structured comparisons across the key segmentation axes, detailed supplier profiles that connect corporate strategy with product capability, and a comprehensive treatment of the regulatory, material, and lead-time factors currently shaping market behavior. For organizations that need to move from awareness to execution, the complete dataset and accompanying analysis offer the precision necessary to support board-level discussions, procurement negotiations, and long-range capacity planning.
Probe Card Market
Conclusion: Turning Market Intelligence into Strategic Advantage
The probe card market is expanding along a measured but consistent growth path, supported by rising test complexity, advanced packaging adoption, and sustained semiconductor output requirements. At the same time, suppliers are consolidating capabilities, extending manufacturing capacity, and entering strategic collaborations that will influence availability and technology access throughout the forecast period. External pressures from tariffs, export controls, material constraints, and lead-time volatility add further complexity to an environment where test infrastructure performance directly affects fab throughput and product ramp success.
For executives and strategy teams planning across 2026 and beyond, the value of rigorous market intelligence is not abstract. It lies in the ability to anticipate constraint points, evaluate supplier claims with evidence, and align testing strategy with the realities of a market that is both growing and structurally transforming. PW Consulting full probe card market study provides the framework, data, and competitive context needed to make those decisions with confidence. Readers seeking the complete segmentation detail, supplier analysis, and forward forecast necessary for execution are encouraged to access the full report to obtain the comprehensive intelligence required for 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Probe Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Centrifugal Chiller Market to Grow at 6.21% CAGR, Reaching $483.9M by 2032
By PW Consulting, 2026-09-16
Navigating the Next Decade: Strategic Intelligence in the Global Centrifugal Chiller Market
The commercial and industrial HVAC landscape is undergoing a structural transformation driven by stringent energy codes, the explosive growth of digital infrastructure, and a regulatory pivot toward low-global-warming-potential (GWP) refrigerants. For executives, facility owners, and engineering leaders, understanding the centrifugal chiller segment is no longer a technical afterthought—it is a capital allocation imperative. At PW Consulting, we have synthesized a multi-year historical record and a forward-looking forecast to illuminate where value will accrue between 2026 and 2032. This research is designed not as a static snapshot, but as a decision-grade instrument for portfolio planning, infrastructure investment, and competitive positioning.
Our baseline analysis anchors on a measured historical trajectory from 2020 through 2025, capturing the market's recovery and maturation phases. The global revenue base expanded from approximately 263.05 million USD in 2020 to 319.5 million USD by 2025, reflecting resilient demand across commercial campuses, heavy industrial processes, and the rapid densification of cooling requirements in technology-driven environments. Looking ahead, the forecast period to 2032 maps a sustained upward curve, with compounded annual growth projected at 6.21 percent. This trajectory signals more than incremental expansion; it indicates a market structurally re-rating around efficiency, refrigerant compliance, and application-specific engineering. Decision-makers who internalize these macro signals early will be better positioned to align procurement cycles, capacity planning, and technology roadmaps with the market's directional momentum.
The Architecture of the Study: From Macro Signals to Operational Playbooks
A credible market study must bridge the gap between aggregate forecasting and the granular realities of engineering, procurement, and operations. Our Centrifugal Chiller Market research is organized to support that translation. Rather than presenting a single headline number, the report decomposes the market along dimensions that matter to buying committees and capital planners: technology architecture, application contexts, and regional deployment patterns. These lenses allow readers to test assumptions about where capacity is being installed, which operating profiles dominate spend, and how regional regulatory climates influence product specification.
The study's operational value lies in its scaffold of decision-support content. Each section is constructed to answer a concrete planning question:
- Where does historical volatility end and structurally driven growth begin, enabling more reliable budgeting for multi-year capital programs?
- Which technology pathways—air-cooled versus water-cooled configurations—carry distinct risk-return profiles under evolving ambient conditions and efficiency mandates?
- How do application contexts such as commercial facilities, industrial operations, and data center environments shape load profiles, redundancy requirements, and lifecycle cost calculus?
- What regional dynamics influence project timing, specification preferences, and supply chain readiness across major demand centers?
By integrating these dimensions, the report gives stakeholders a structured way to compare scenarios rather than a single deterministic path. That distinction matters in a market where project lead times, refrigerant transitions, and efficiency targets can shift procurement economics within a single budget cycle.
Competitive Intensity and the Battle for Specification
The centrifugal chiller segment features a concentrated set of global manufacturers, each competing on thermodynamic performance, refrigerant readiness, and application-specific engineering. Our market concentration analysis indicates that the top three firms collectively account for roughly 60 percent of revenue, while the top five capture approximately 75 percent. This concentration reflects both the technical barriers to entry in large-capacity, high-efficiency chiller design and the importance of service networks, certification track records, and long-term operational credibility in winning institutional assignments.
Centrifugal Compressors Market
Within this landscape, several established players continue to advance product portfolios that directly address efficiency mandates and refrigerant compliance. Johnson Controls has emphasized its YK, YZ, YMC2, and YK-HT magnetic bearing centrifugal chillers, engineered for energy savings, low-GWP refrigerant compatibility, and large-capacity data center applications. Carrier has focused on the AquaEdge 19DV and AquaForce series, pairing variable-speed drives with sustainability-oriented features for commercial and industrial use. Trane Technologies offers CenTraVac and Series R magnetic bearing units positioned for high efficiency and space savings across commercial, industrial, and data center applications. Daikin Applied promotes its Magnitude WMT, WME-D, and WME series oil-free magnetic bearing chillers with two-stage compressors and low-GWP refrigerants. Mitsubishi Heavy Industries contributes efficient centrifugal platforms for energy saving and environmental protection in large commercial and industrial installations. LG Electronics brings its H Series 2-stage centrifugal chillers with inverter technology and AHRI 550/590 certified performance to the equation. In parallel, regional and specialized manufacturers extend the competitive field: Ecochillers from Guadalajara offers oil-free centrifugal chillers using low-GWP refrigerants and custom magnetic-bearing models for industrial and commercial applications, while Smardt Chiller Group from Dorval provides oil-free centrifugal units designed for laboratories, food, and pharmaceutical environments with ISO 9001 certification.
The strategic implication for buyers is that specification competition is intensifying at the edges of performance, refrigerant compliance, and application fit. For vendors, differentiation increasingly depends on demonstrating measurable lifecycle advantages under real operating conditions rather than headline capacity claims alone. Our report situates each company's positioning within the broader demand structure, helping readers interpret where competitive pressure is likely to influence pricing, service models, and technology roadmaps over the forecast period.
Latest Market Movements: Product Innovation Meets Regulatory Realities
Recent developments in the segment underscore how quickly product roadmaps and compliance requirements are converging. In February 2026, Johnson Controls previewed the high-density compact YORK YK-HT two-stage economized centrifugal chiller at the AHR Expo, highlighting a wide operating range from a single driveline, zero water consumption capability, and lift performance up to 110°F for data centers and large campuses. Announced in October 2024, Daikin Applied introduced the Magnitude WME-D magnetic bearing oil-free centrifugal chiller with a two-stage compressor and low-GWP R-515B refrigerant. These milestones are not isolated product launches; they are signals of how manufacturers are adapting to denser load profiles, water availability constraints, and refrigerant phase-down expectations.
These product movements intersect with a hardening regulatory and technical environment that shapes procurement specifications and performance validation. ASHRAE 90.1-2022 requires non-standard rating condition adjustments for water-cooled centrifugal chiller packages using the K adj equation to meet minimum full-load kW/ton and IPLV efficiencies. AHRI 550/590 certification is mandatory for all listed centrifugal chiller performance ratings, including full-load and integrated part-load values. In the United States, low-GWP refrigerants are mandated for new centrifugal chillers beginning January 2025, prompting manufacturers to expand compliant model lines; Johnson Controls, for example, extended YVAM air-cooled models to support compliance. At the technology level, magnetic bearing architectures in centrifugal chillers eliminate oil lubrication, reducing maintenance costs and enabling operation at condenser temperatures up to 30°F below chilled water setpoint.
Together, these forces create a market environment in which efficiency targets, refrigerant readiness, and certified performance documentation are becoming baseline expectations rather than premium differentiators. Organizations that anticipate these requirements in their specification language and vendor evaluation criteria will encounter fewer delays and lower residual compliance risk during project execution.
Where Decision-Makers Gain Edge: How to Use This Research
The strategic value of this study is highest when it is used to inform multi-layered decisions rather than a single purchase event. For capital planners and facility executives, the forecast structure supports capacity planning by clarifying the pace and shape of market growth across the 2026–2032 window. For engineering and specification teams, the segmentation framework provides a structured way to align chiller type and application context with operating goals, redundancy needs, and environmental constraints. For competitive strategy and sourcing functions, the company profiles and concentration metrics offer a lens into where market power resides and how vendor portfolios are evolving in response to regulatory and performance pressures.
Because the segment is moving on multiple vectors simultaneously—technology advancement, refrigerant compliance, certification rigor, and application growth—decision-makers benefit from a research asset that connects these vectors rather than treating them separately. The report is designed to support that integrative view. It helps teams frame questions such as whether a project's load profile favors a magnetic bearing platform, how regional specification norms affect product selection, and which company portfolios are most aligned with an organization's compliance timeline and operational priorities.
What Is Inside and How to Access the Full Intelligence
The complete study delivers a comprehensive map of the centrifugal chiller market across the 2020–2032 horizon, combining historical revenue context with a detailed forward forecast. It examines market size and growth trajectories, breaks down demand by technology type and application context, and reviews regional dynamics that influence deployment patterns and specification preferences. It further profiles leading manufacturers, evaluates recent product and compliance-driven developments, and integrates the regulatory and technical standards that shape performance validation. Market concentration metrics provide additional context on competitive structure and supplier power.
To preserve the analytical integrity of the forecast model and protect the proprietary structure of our segmentation work, certain detailed split values and regional or application-level breakdowns are reserved for the full report. The summary presented here is intended to demonstrate methodological rigor and strategic relevance while encouraging deeper engagement with the complete dataset. Readers who require precise segment sizing, regional distribution details, application-level revenue context, and company-level positioning data will find those capabilities fully developed in the final document.
Centrifugal Chiller Market
For teams tasked with navigating 2026 planning cycles, the Centrifugal Chiller Market research offers a structured baseline for scenario testing, procurement timing, specification alignment, and competitive benchmarking. By combining macro growth signals with practical decision frameworks, it helps organizations move from general market awareness to targeted action. To access the full report, including detailed segmentation figures, complete company profiles, and the underlying forecast methodology, please visit the source page to retrieve the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Centrifugal Chiller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind Turbine Installation Vessel Market to Hit $10.5B by 2032 at 11% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Wind Turbine Installation Vessel Market: A 2026 Outlook
The global offshore wind sector has entered a decisive phase of industrial scaling, and the capital assets required to execute this expansion—Wind Turbine Installation Vessels (WTIVs)—are at the center of a rapidly intensifying market dynamic. As policymakers, developers, and marine contractors navigate the complex intersection of technological evolution, regulatory shifts, and supply chain constraints, access to precise, forward-looking intelligence is no longer a luxury; it is a foundational requirement for strategic planning. Our latest market research on the Wind Turbine Installation Vessel Market provides a comprehensive, data-driven blueprint of the industry landscape, engineered specifically to inform high-stakes corporate decisions throughout 2026 and beyond.
Between 2020 and 2025, the market experienced a sustained trajectory of revenue growth, expanding from 3.0 billion USD to 5.06 billion USD. This historical performance reflects a sector transitioning from early-stage pilot deployments to industrialized, utility-scale installation campaigns. Moving forward, our forecast model projects that the market will continue its robust expansion, reaching approximately 5.51 billion USD in 2026 and scaling steadily toward 10.5 billion USD by 2032. This growth is underpinned by a compound annual growth rate of 11.0 percent over the forecast period, signaling a structural acceleration rather than a cyclical fluctuation. For executive teams, financial planners, and maritime asset managers, these macroeconomic signals establish a clear mandate: capacity allocation, fleet modernization, and partnership strategy must be recalibrated to capture value in a market that is fundamentally outpacing historical benchmarks.
However, aggregate figures only tell part of the story. The real strategic leverage lies in understanding how growth distributes across vessel architectures, service models, and geographic deployment corridors. Our full report deliberately segments these dimensions, revealing where capital efficiency is being maximized, which application verticals are driving sustained utilization rates, and how regional project pipelines are reshaping vessel routing and charter economics. While we reserve the granular regional and application-level breakdowns for our comprehensive publication, it is already evident that the installation of offshore wind farms remains the dominant revenue driver, while onshore deployment and specialized maintenance and repair services contribute distinct, complementary revenue streams that require differentiated operational playbooks.
Decoding the Competitive Architecture
The WTIV market is characterized by a notably concentrated competitive structure. Our analysis indicates that the top three operators collectively command approximately 58.0 percent of market revenue, while the top five players extend their combined share to roughly 65.0 percent. This concentration is not merely a statistical observation; it reflects a strategic reality where scale, vessel capability, and long-term charter commitments create formidable barriers to entry. For incumbent operators, this landscape presents an opportunity to solidify pricing power and secure preferential access to high-value project slots. For new entrants, joint ventures, asset leasing models, or niche specialization in emerging deployment zones may offer more viable pathways to market participation.
Several industry leaders have already positioned themselves at the forefront of this evolution. Cadeler, headquartered in Copenhagen, Denmark, continues to expand its operational footprint as the owner and operator of the largest fleet of jack-up offshore wind turbine installation vessels, including next-generation assets such as Wind Mover, Wind Ally, and Wind Ace. The company’s 2025 annual report, published in March 2026, confirmed the doubling of its WTIV fleet capacity through the delivery of five vessels, underscoring a deliberate strategy to capture a growing share of large-scale installation contracts. In the Netherlands, Van Oord operates specialized marine installation platforms, including Boreas and Aeolus, which are engineered for heavy-lift foundation work and turbine deployment in demanding offshore environments. Meanwhile, DEME Group, based in Beveren, Belgium, has aggressively advanced its next-generation fleet with vessels such as Norse Wind and Norse Energi, both designed to install 15+ MW turbines and handle XXL monopiles in deepwater settings. DEME Group formally named Norse Wind at the Port of Oslo in April 2026, and earlier that year announced the delivery of Norse Energi at CIMC Raffles Shipyard, with the sister vessel entering service in the first half of 2026.
Wind Turbine Installation Vessel Market
Additional players are reinforcing the industry’s operational diversity and geographic reach. A2SEA, headquartered in Fredericia, Denmark, remains a specialized provider of offshore wind turbine installation services and vessels tailored for wind farm construction. Eneti Inc., operating from Monaco, manages self-elevating platform vessels through its Seajacks fleet, delivering targeted installation capabilities for offshore wind projects. In the United Kingdom, MPI Offshore deploys the MPI Resolution and MPI Adventure specifically for turbine and foundation installation tasks. Jack-Up Barge, based in Oosterhout, Netherlands, supports the sector with jack-up barges and accommodation vessels that enable both installation and ongoing maintenance operations. Fred. Olsen Windcarrier, operating out of Oslo, Norway, focuses on global energy security and large wind farm projects through its dedicated installation fleet. On the shipbuilding and integrated delivery side, Seatrium in Singapore has emerged as a critical enabler, handing over a next-generation WTIV to Maersk Offshore Wind in February 2026 for deployment on the Empire Wind 1 project, a milestone that highlights the growing synergy between Asian shipyards and Western offshore wind developers. Swire Blue Ocean, also headquartered in Copenhagen, continues to provide fleet services for major wind farm installations, reinforcing the sector’s reliance on experienced, project-proven operators.
Operational Realities Shaping 2026 Decision-Making
The strategic calculus for any organization operating in this market is increasingly defined by capital intensity, operational expenditure dynamics, and regulatory friction. Newbuild prices for modern, large-scale WTIVs now exceed 400 million USD, and industry benchmarks suggest that five-year-old vessels will command valuations approaching 275 million USD by 2030. These asset valuations are driven by multiple reinforcing cost factors: steel procurement, specialized marine equipment, and the integration of high-capacity crane systems and dynamic positioning technologies all contribute to substantial upfront capital requirements. Equally important, daily operational expenses—encompassing fuel, crew, maintenance, and port logistics—represent a persistent pressure point on project economics. Organizations that fail to model these operational cost structures with precision risk underpricing charter engagements or overestimating net utilization returns.
At the same time, regulatory frameworks and jurisdictional requirements are introducing new variables into fleet planning. In the United States, emerging Jones Act-compliant WTIV conversion concepts are being evaluated as a cost-mitigation pathway, targeting conversion expenditures that represent roughly one-third to one-half the cost of constructing a new US-built vessel. This development is particularly relevant for stakeholders aligned with domestic offshore wind capacity goals, as it may unlock a more cost-effective route to meeting localized installation demands while navigating maritime compliance mandates. On the technology frontier, vessels capable of installing 15+ MW turbines with 180-metre hook height cranes have already been delivered to Maersk Offshore Wind in early 2026 for the Empire Wind 1 project, demonstrating that the industry’s capability threshold is rising in lockstep with turbine scale.
These operational and regulatory dynamics do not exist in isolation. They intersect with project scheduling, feed-in tariffs, monopile and foundation supply chains, port infrastructure availability, and seasonal weather windows. Our full report maps these interdependencies systematically, enabling decision-makers to stress-test scenarios, identify bottlenecks before they become capital traps, and align fleet deployment strategies with real-world execution constraints.
What the Full Report Delivers
Designed for executive leadership, corporate development teams, maritime investors, and policy-aligned strategists, our comprehensive Wind Turbine Installation Vessel Market research goes far beyond headline figures. The publication delivers an integrated analytical framework that connects market sizing with actionable operational intelligence. Key components include:
- Historical performance tracking from 2020 through 2025, establishing a verified baseline against which forward projections can be benchmarked.
- A detailed forecast architecture spanning 2026 to 2032, with scenario-sensitive modeling that accounts for vessel delivery timelines, turbine size progression, and regional project pipeline variability.
- Deep-dive segmentation that isolates growth contributions by vessel type, application vertical, and geographic deployment pattern, allowing teams to pinpoint where marginal revenue opportunities are concentrated.
- A structured competitive landscape assessment that evaluates fleet capacity, vessel specifications, strategic positioning, and recent operational milestones for leading market participants.
- Analysis of capital cost trajectories, daily operational expense drivers, and regulatory developments that directly influence charter pricing, asset valuation, and project feasibility.
- Integration of recent industry developments, including major vessel deliveries, fleet expansion announcements, and naming ceremonies that signal near-term capacity shifts and deployment priorities.
- Strategic implications for market entry, partnership structuring, vessel chartering, and capital allocation, presented with the granularity required for board-level planning.
Rather than offering generic commentary, the report synthesizes proprietary data, industry market intelligence, and verified corporate announcements into a single, decision-ready reference. The objective is to equip organizations with the clarity needed to act confidently in a market where timing, capability alignment, and cost discipline determine competitive advantage.
Why 2026 Demands a Disciplined Intelligence Advantage
The current moment represents a critical inflection point for the WTIV sector. On one side, demand is being propelled by accelerating offshore wind capacity targets, larger turbine ratings, and increasingly complex foundation designs that require more capable, more expensive vessels. On the other side, capital markets, supply chain latency, and operational cost inflation are raising the stakes for every investment decision. Organizations that approach this environment with fragmented data or reactive planning will find themselves either overcommitting to underutilized assets or missing high-probability deployment windows. Conversely, those that integrate rigorous market sizing, segmentation intelligence, and competitive benchmarking into their planning cycles will be better positioned to negotiate favorable charter terms, sequence fleet upgrades efficiently, and align strategic partnerships with verified project pipelines.
Our research is built to serve as that strategic anchor. By synthesizing historical performance, forward-looking projections, and granular breakdowns of market structure, the report enables leaders to move from intuition to evidence-based action. The concentration of revenue among a handful of major operators, the escalating cost of next-generation vessel assets, and the rapid pace of recent deliveries all point to a market where information asymmetry carries real financial consequences. Access to comprehensive, verified intelligence is the most reliable countermeasure.
Moving Forward with Confidence
The Wind Turbine Installation Vessel Market is not simply growing; it is reconfiguring around higher technical thresholds, stronger competitive moats, and more demanding operational economics. Success in 2026 and the years that follow will depend on the ability to interpret macro growth signals, navigate vessel capability requirements, and align capital deployment with realistic utilization expectations. Our full market research report provides the structural insight, segmented detail, and competitive context required to make those decisions with precision. We invite executive teams, investors, and maritime strategists to access the complete publication, where the full segmentation breakdowns, regional deployment patterns, application-level revenue distributions, and actionable strategic recommendations are presented in depth. In a market that rewards speed, accuracy, and disciplined planning, comprehensive intelligence is not an optional resource—it is the foundation of durable competitive advantage.
Offshore Wind Turbine Installation Vessel Market
For detailed analysis of this topic, please visit the official page: Wind Turbine Installation Vessel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Marine Fleet Management Market Hits $1.04B in 2025, Projects 10.8% CAGR to $2.12B by 2032
By PW Consulting, 2026-09-16
Navigating the Digital Seas: Strategic Intelligence for the Marine Fleet Management Software Market
The maritime industry stands at a critical inflection point. As vessels grow smarter and supply chains demand greater transparency, the marine fleet management software market has evolved from a back-office utility into a strategic command center for shipping operators worldwide. Our latest market research delivers a comprehensive, data-driven assessment of this landscape, offering decision-makers the clarity required to navigate investment, procurement, and competitive positioning through 2032.
This analysis is not merely a snapshot of current valuations. It is a forward-looking strategic instrument designed to help executives anticipate regulatory shifts, evaluate technological migration paths, and align fleet digitalization roadmaps with measurable operational outcomes. Below, we outline the structural forces shaping the market and demonstrate how our research framework translates complex maritime dynamics into actionable intelligence.
Market Trajectory and Structural Expansion
Over the past half-decade, the marine fleet management software sector has demonstrated consistent, compounding growth. Revenue expanded from approximately 670.0 million USD in 2020 to an estimated 1040.0 million USD by 2025, reflecting sustained enterprise adoption, rising compliance mandates, and the gradual phasing out of legacy spreadsheet-driven workflows. The trajectory forward indicates continued acceleration, with the market projected to surpass 1153.18 million USD in 2026 and approach 2118.2 million USD by 2032.
At the core of this expansion lies a compound annual growth rate of 10.8 percent across the forecast horizon. This rate is not an abstract figure; it represents the cumulative effect of cloud migration, remote vessel monitoring requirements, and the operational necessity of integrating maintenance, crewing, and compliance into unified digital platforms. Organizations that treat fleet software as a capital allocation priority rather than a discretionary upgrade will be best positioned to leverage this growth cycle.
The historical baseline from 2020 through 2025 reveals a market that has already weathered early adoption friction and emerged with clearer procurement standards. Enterprises now evaluate solutions based on interoperability, data sovereignty, and total cost of ownership across vessel lifecycles. These evaluation criteria are reshaping vendor selection and influencing the pace at which digital transformation initiatives advance across fleets of varying sizes.
Core Segmentation Drivers Shaping Investment Decisions
The market does not expand uniformly. Growth is concentrated where operational pain points intersect with regulatory pressure and technological feasibility. Enterprise buyers are increasingly prioritizing deployment models that balance scalability with control, while application-specific requirements continue to differentiate procurement strategies across shipping operations, terminal infrastructure, and freight forwarding networks.
Deployment architecture remains a defining strategic variable. Cloud-native solutions have captured the majority of recent commercial momentum, driven by the demand for real-time synchronization across dispersed fleets, reduced on-site infrastructure overhead, and continuous feature iteration. At the same time, on-premises deployment retains a meaningful footprint among operators with strict data residency mandates, legacy integration dependencies, or specialized onboard connectivity constraints. Evaluating the appropriate architecture requires a nuanced understanding of vessel connectivity profiles, cybersecurity posture, and long-term total cost of ownership rather than a one-size-fits-all preference.
Application adoption patterns further illustrate how fleet software is being deployed across the maritime value chain. Shipping operators continue to represent the largest demand pool, leveraging integrated platforms to coordinate maintenance scheduling, regulatory compliance, and voyage optimization. Ports and terminals are expanding their software footprints to improve berth coordination, asset utilization, and cross-functional data exchange. Maritime freight forwarders are adopting fleet-adjacent modules to enhance shipment visibility, carrier coordination, and operational reporting. These application-level dynamics influence not only vendor positioning but also the scope of enterprise negotiations and integration roadmaps.
Regional demand patterns also reflect divergent maturity curves and regulatory environments. Certain markets exhibit advanced digitalization baselines and strong vendor ecosystems, while others are in earlier stages of fleet standardization and cloud adoption. Understanding where demand is consolidating versus where it is emerging enables procurement leaders to calibrate rollout strategies, prioritize regional support capabilities, and anticipate competitive intensity in local market segments.
Competitive Landscape and Strategic Positioning
The vendor ecosystem reflects a mix of established classification-linked platforms, specialized maritime software providers, and broader marine technology companies extending into digital fleet operations. Strategic buyers must evaluate not only product functionality but also ecosystem reach, integration depth, and the ability to maintain continuity across vessel classes and regulatory regimes.
DNV continues to reinforce its position through ShipManager, a solution engineered to support vessels and fleets across technical, operational, and compliance dimensions. Its alignment with class and regulatory expertise gives it particular resonance among operators seeking to embed compliance workflows directly into daily fleet management routines. BASS Software Ltd competes with BASSnet, a native cloud maritime ERP platform that unifies maintenance, HSEQ, payroll, crewing, and financial functions within a single operational framework. This breadth appeals to organizations pursuing end-to-end digitization rather than point solutions.
Marine Fleet Management Software Market
SERTICA by RINA delivers fleet management capabilities centered on planned maintenance, procurement, HSQE, and operational optimization, positioning itself as a practical operational efficiency platform for fleets that require disciplined maintenance planning and procurement visibility. ABS Group of Companies Inc provides the ABS Wavesight platform, which has scaled across more than 5,000 vessels and combines fleet management with classification integration for compliance assurance. This scale and class linkage create a distinctive value proposition for operators prioritizing standardized compliance reporting and broad fleet coverage.
TIMEZERO has strengthened its relevance in navigation and fleet tracking through cloud-based AIS, real-time positioning, and chart-based operational awareness. Its April 2025 transition to a fully cloud-based product line introduced automatic software updates, community maps, extended-range online AIS, premium weather with real-time Doppler radar, text-based weather alerts, and enhanced fleet tracking. This migration signals a broader industry shift toward continuously updated cloud services and away from isolated, manually maintained navigation tools.
IoT Fleet Management Market
Additional participants such as SpecTec, Shipnet AS, PRIME Marine, and Kongsberg contribute further specialization across ship operations, fleet tracking, maintenance efficiency, and digital optimization. Their presence underscores a fragmented but increasingly integrated competitive field where differentiation is determined by workflow coverage, interoperability, and the ability to support both operational and compliance objectives simultaneously.
Market concentration remains meaningful. The top three players account for approximately 50.3 percent of market revenue, while the top five collectively represent about 68.2 percent. This concentration indicates established incumbency advantages, but it also signals room for specialized challengers that can win on deployment flexibility, regional support, or application-specific optimization. Enterprise buyers should interpret concentration not as a barrier to choice but as a framework for evaluating ecosystem reliability, negotiated value, and long-term vendor stability.
Dynamics, Risks, and Technology Migration Realities
Fleet management software adoption does not occur in a vacuum. It intersects with cybersecurity expectations, data governance requirements, connectivity limitations, and the operational realities of managing vessels across multiple jurisdictions. Decision-makers must assess platforms not only for feature depth but also for resilience, certification alignment, and the capacity to safeguard vessel tracking and fleet operations against evolving threat vectors.
Cybersecurity has become a defining procurement consideration. Maritime software platforms increasingly operate under infrastructure certifications such as SOC 2 Type 2 and ISO 27001:2022, which provide structured assurance for organizations managing sensitive operational data, crew information, and compliance reporting. These frameworks are not optional garnish; they are becoming baseline expectations for operators that rely on digital platforms for vessel tracking, remote monitoring, and fleet-wide coordination. Evaluating a vendor's security posture alongside its functional capabilities is now a necessary component of procurement due diligence.
Connectivity and data latency further complicate deployment strategy. Vessels operating in remote routes or with intermittent bandwidth face different adoption constraints than those in regions with robust maritime connectivity. Cloud migration can deliver rapid updates, centralized data, and improved cross-fleet visibility, but it must be balanced against crew training requirements, onboard hardware compatibility, and fallback operational procedures. Successful transformation programs recognize these constraints and sequence implementation in ways that preserve operational continuity while capturing digital benefits.
Regulatory complexity continues to elevate the strategic importance of fleet software. Compliance documentation, emissions-related reporting, safety management integration, and class-related workflows are increasingly expected to flow through unified digital environments rather than fragmented manual processes. Software that can standardize these workflows while maintaining auditable records offers tangible operational and risk-management value. Enterprises that delay this integration may face rising administrative overhead and greater exposure to documentation gaps as regulatory scrutiny intensifies.
What the Research Delivers
This market study translates broad industry momentum into a structured, decision-ready intelligence framework. Rather than offering surface-level descriptors, the report maps the commercial architecture of the marine fleet management software market across multiple dimensions that matter to enterprise strategy.
- Historical revenue progression and forward-looking projections that frame the scale and pace of market expansion across the forecast horizon
- Deployment-level analysis that clarifies where cloud momentum is strongest and how on-premises demand persists under specific operational and regulatory conditions
- Application-level demand characterization that distinguishes adoption patterns across shipping operations, ports and terminals, and maritime freight forwarding contexts
- Regional demand mapping that identifies where maturity, competition, and procurement dynamics differ across major commercial zones
- Competitive profiling of core vendors, including solution scope, deployment emphasis, and strategic differentiation relevant to fleet operators
- Market concentration measurement that informs vendor benchmarking, negotiation strategy, and ecosystem stability assessment
- Operational and regulatory dynamics that connect cybersecurity expectations, compliance workflows, and connectivity realities to procurement and implementation decisions
Each section is designed to support concrete corporate actions: prioritizing software investment, evaluating vendor shortlists, sequencing digital rollout across fleets, and anticipating where competitive pressure is likely to intensify. The analysis emphasizes not just what the market is doing, but why it is doing it, and what that implies for capital allocation, vendor selection, and operational planning.
Strategic Implications for 2026 Decision-Making
For executives planning 2026 initiatives, the strategic question is no longer whether fleet management software matters, but how to deploy it in a way that compounds operational resilience and commercial advantage. Organizations that align procurement with deployment reality, compliance trajectory, and cybersecurity expectations will extract more value from their digital investments than those that evaluate solutions in isolation.
Procurement teams should assess platforms against the full operational lifecycle: maintenance coordination, compliance documentation, crew and payroll integration, financial reporting, and real-time fleet visibility. Technology leaders should weigh cloud migration benefits against connectivity constraints and data governance requirements. Commercial leaders should interpret market concentration and regional demand divergence as signals for where vendor leverage, support capability, and implementation risk are likely to differ.
The market's growth rate, structural segmentation, and evolving competitive dynamics all point to a single conclusion: fleet management software is becoming a core operational asset rather than a peripheral IT purchase. Companies that approach it with the appropriate strategic rigor will be better equipped to manage compliance exposure, improve vessel and terminal utilization, and support the broader digitalization of maritime operations.
Accessing the Full Intelligence Framework
The insights summarized here represent the strategic surface of a much deeper analytical structure. The complete report contains the segmentation detail, vendor comparison framework, deployment and application demand breakdowns, regional demand mapping, and concentration analysis required to convert market awareness into procurement and investment decisions.
For executives who need to benchmark vendors, prioritize deployment paths, or evaluate regional rollout timing, the full dataset provides the granularity necessary to move from directional understanding to executable planning. We invite decision-makers to access the complete research directly through our source page, where the full segmentation logic, competitive profiles, and forecast structures are available for internal review and strategic application.
In a market expanding at a double-digit pace and increasingly defined by cloud adoption, compliance integration, and cybersecurity expectations, incomplete information is a strategic liability. The full report is designed to remove that liability and replace it with a structured basis for confident, evidence-based decision-making.
For detailed analysis of this topic, please visit the official page: Marine Fleet Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Matches Market Hits $224.3M by 2032, 1.8% CAGR Forecast to 2032
By PW Consulting, 2026-09-16
Beyond the Flame: Strategic Intelligence for the Global Matches Market in 2026 and Beyond
Introduction: The Strategic Imperative of a Maturing Category
In an era dominated by digital transformation and electrification, the global matches market might appear to be a relic of a simpler past. Yet, for strategic planners, supply chain architects, and category managers, this unassuming product category represents a fascinating case study in resilience, segmented utility, and regional economic interdependence. As organizations calibrate their portfolios for 2026, understanding the nuanced trajectories of traditional consumer goods becomes a critical differentiator. PW Consulting’s latest Matches Market research report is designed not merely as a statistical archive, but as a strategic compass. By synthesizing historical performance from 2020 through 2025 with forward-looking projections extending to 2032, this analysis equips decision-makers with the clarity needed to navigate a landscape that is simultaneously stable, quietly evolving, and deeply sensitive to macroeconomic undercurrents.
The market’s recent trajectory reveals a story of measured resilience rather than explosive growth. Following a baseline year in 2025 that stabilized near 199.0 million USD, the broader outlook points to a compound annual growth rate of 1.8 percent across the forecast period. While such a figure might initially suggest a low-priority asset, it actually underscores a market where incremental gains, margin optimization, and channel-specific shifts carry disproportionate strategic weight. In mature consumer packaged goods categories, the difference between stagnation and sustainable expansion often lies in how well leadership understands the structural forces shaping demand, distribution, and competitive positioning. This report dissects those forces with precision, offering a framework that transforms raw macroeconomic indicators into actionable intelligence.
Macro Trajectory and the 2026 Decision Horizon
The historical window from 2020 to 2025 demonstrates the market’s ability to absorb supply chain disruptions, shifting regulatory environments, and evolving consumer purchasing behaviors without undergoing fundamental structural collapse. Revenue figures across that period reflect modest volatility, with a notable rebound in 2023 and 2024 that pushed the category past the 200 million USD threshold before settling into a more normalized cadence. For corporate strategists, this pattern is highly instructive. It signals a category that has moved past the acute shock phases of recent global disruptions and is now operating within a more predictable, demand-driven equilibrium. That equilibrium, however, does not imply complacency.
Looking toward 2026, the projected revenue sits at approximately 197.13 million USD, marking a transitional year that many analysts interpret as a consolidation phase before the next growth inflection. From 2027 onward, the trajectory arcs upward, with the market expected to approach 211.35 million USD by 2027, navigate minor recalibration in subsequent years, and ultimately crest near 224.3 million USD by 2032. The 1.8 percent CAGR across this horizon may appear modest, yet it masks significant underlying dynamics. Growth is not distributed uniformly; rather, it is concentrated in specific product formats, packaging preferences, and distribution ecosystems that reward targeted investment and penalize undifferentiated positioning.
For enterprises planning capital allocation, product portfolio adjustments, or regional expansion strategies in 2026, the key takeaway is timing. The near-term stabilization offers a window to restructure operational efficiencies, renegotiate supplier contracts, and pilot new packaging or channel initiatives before the next wave of upward pressure materializes. Companies that treat 2026 as a mere continuation of historical trends risk missing the structural realignment already underway. Those that use this period to stress-test their assumptions against granular market intelligence will be better positioned to capture the incremental gains that define mature-category success.
Report Architecture: Translating Data into Operational Playbooks
A market research publication only delivers value when it bridges the gap between high-level observation and on-the-ground execution. PW Consulting’s Matches Market report is engineered to close that gap. Rather than presenting data in isolation, the analysis is structured around decision-critical dimensions that procurement leaders, product managers, and commercial directors can immediately apply to their planning cycles. The report dissects the category across multiple axes, each chosen for its direct relevance to pricing strategy, inventory planning, and go-to-market optimization.
At the foundational level, the study examines how product classification influences demand elasticity and margin profiles. By distinguishing between ordinary match formats, high-grade variants, and specialized or niche configurations, the analysis reveals how manufacturers and distributors can tailor their portfolios to specific consumer segments and industrial applications. This segmentation is not treated as a static snapshot but as a dynamic framework that responds to quality perception, safety standards, and end-use requirements. Similarly, the packaging dimension is explored as a strategic lever rather than a mere logistical detail. The report evaluates how traditional match boxes, book-style formats, and alternative packaging solutions perform across different retail environments and consumer touchpoints, highlighting the operational and branding implications of each choice.
Matches Market
Distribution channel analysis forms another critical pillar of the research. The study maps how sales flow through supermarkets and hypermarkets, convenience retail networks, digital commerce platforms, and other specialized outlets. Rather than simply ranking channels by volume, the report examines the structural characteristics that drive performance within each ecosystem: basket composition, purchase frequency, margin expectations, and consumer visibility. This approach enables clients to identify which channels offer scale, which deliver profitability, and which require reconfiguration to remain viable in a shifting retail landscape. Regional dynamics are similarly contextualized, with attention paid to how economic development levels, regulatory frameworks, and cultural consumption patterns shape market behavior across different geographies.
Beyond structural breakdowns, the report integrates actionable frameworks for scenario planning. Decision-makers are provided with templates to assess how changes in raw material pricing, fuel and logistics costs, or consumer safety preferences could ripple through their supply chains. Competitive benchmarking modules help organizations calibrate their positioning relative to established players, while risk assessment tools highlight vulnerability points that are often overlooked in conventional forecasting models. The objective is to deliver a living document that supports quarterly reviews, annual strategy sessions, and long-range capital planning alike.
Competitive Dynamics and Concentration Realities
Market structure plays an outsized role in how effectively companies can execute their strategies. In the matches category, competitive intensity is shaped by a combination of manufacturing scale, distribution reach, brand trust, and the ability to manage cost structures in a low-margin environment. Historical data and market concentration metrics indicate that the top three players collectively command approximately 42 percent of total revenue, while the top five extend their influence to roughly 50 percent. This level of concentration suggests a landscape where established incumbents hold meaningful advantages in supplier negotiations, retailer relationships, and brand recognition, yet where fragmentation below the top tier still allows agile participants to carve out defensible niches.
For organizations evaluating market entry, partnership opportunities, or acquisition targets, this concentration profile carries several implications. First, it underscores the importance of channel access. Retail shelf space and procurement contracts are often gatekept by a handful of dominant players, meaning that new or expanding competitors must either secure exclusive distribution agreements, target underserved retail formats, or leverage digital channels to bypass traditional bottlenecks. Second, it highlights the strategic value of product differentiation. In a category where price competition can quickly erode profitability, companies that invest in quality tiers, safety certifications, or specialized packaging can escape direct price wars and command more stable margins. Third, it points to the need for operational discipline. With half of the market controlled by a small group of competitors, cost efficiency in manufacturing, inventory turnover, and logistics becomes a decisive factor in sustaining long-term viability.
The competitive environment is also influenced by broader industry dynamics that extend beyond individual corporate strategies. Regulatory shifts around safety standards, environmental considerations in packaging materials, and evolving consumer expectations around convenience and reliability all shape how competitors position themselves. Companies that continuously monitor these external pressures and integrate them into their product development and compliance workflows gain a structural advantage. They are better equipped to anticipate retailer requirements, adapt to consumer sentiment shifts, and maintain consistency in a market where brand trust often hinges on reliable performance rather than flashy innovation.
For 2026 planning, competitive awareness must translate into concrete action. Procurement teams should assess supplier concentration risks and explore dual-sourcing strategies where feasible. Commercial leaders should evaluate which channels offer the strongest defensive moats and which present the highest risk of margin compression. Product managers should scrutinize whether existing offerings align with the quality and format preferences that are gaining traction, and whether packaging choices support both consumer usability and downstream logistics efficiency. The report provides the comparative lens needed to make these assessments with confidence, drawing on a comprehensive view of market structure and competitive behavior.
Market Context: Navigating Structural Shifts and Quiet Innovations
Every mature consumer goods category operates within a broader ecosystem of macroeconomic, regulatory, and behavioral forces that shape its trajectory. The matches market is no exception. While the product itself remains functionally straightforward, the environment in which it is produced, distributed, and consumed is continuously evolving. One of the most significant contextual themes is the tension between tradition and adaptation. Consumers in many regions continue to rely on match-based ignition for domestic, culinary, and ceremonial purposes, yet their expectations around safety, packaging convenience, and retail availability are shifting. Companies that recognize this duality and invest in incremental improvements rather than radical reinvention are typically better positioned to sustain relevance.
Supply chain resilience has also emerged as a defining theme for the category. Fluctuations in raw material availability, energy costs, and freight logistics have repeatedly demonstrated their ability to disrupt production schedules and pressure margins. Organizations that have diversified their supplier bases, optimized inventory buffers, and integrated more transparent forecasting mechanisms have navigated these pressures more effectively than those relying on lean, single-source models. The lesson for 2026 is clear: operational flexibility is no longer optional. It is a core competitive requirement, particularly in a category where volume growth is steady rather than dramatic, meaning that cost control and reliability often determine outperformance more than top-line expansion alone.
Retail channel evolution further complicates the landscape. While traditional brick-and-mortar outlets continue to play a dominant role, the gradual rise of digital commerce and convenience-focused retail formats is reshaping how consumers discover and purchase everyday essentials. Online channels, though still a smaller portion of total distribution, are gaining strategic attention as companies experiment with direct-to-consumer models, subscription approaches, and bundled household essentials offers. Simultaneously, convenience retail networks are adapting to local purchasing habits, often serving as high-frequency touchpoints for impulse and habitual purchases. Understanding how these channels interact, where they overlap, and where they diverge is essential for organizations designing omnichannel strategies that do not overinvest in one format at the expense of another.
Regulatory and safety considerations add another layer of context. As product standards tighten and sustainability expectations rise, manufacturers must align their production processes, packaging materials, and labeling practices with evolving compliance requirements. These adjustments often carry short-term costs but can yield long-term benefits in terms of retailer confidence, consumer trust, and market access. Companies that proactively integrate compliance into their product development cycles, rather than treating it as a retrospective fix, typically experience smoother market interactions and fewer operational disruptions. The report captures these contextual pressures and maps them against practical strategic responses, ensuring that decision-makers can anticipate rather than react to external change.
Why 2026 Demands Precision Intelligence
The strategic value of PW Consulting’s Matches Market research lies in its ability to convert broad market signals into precise, context-ready insights. In a category growing at a measured pace, the margin for error is slim. Overinvesting in channels or product formats that are already saturated can drain resources, while underinvesting in areas poised for incremental growth can cede ground to more agile competitors. The report is designed to eliminate that ambiguity. It provides a structured view of where demand is stabilizing, where it is quietly strengthening, and where operational efficiency will matter most in the coming years.
For executives preparing 2026 budgets, the analysis offers a disciplined framework for prioritization. It helps identify which product tiers warrant continued investment, which packaging configurations align with retailer and consumer preferences, and which distribution pathways promise the most sustainable returns. It also supports scenario-based planning by highlighting the variables that could accelerate or decelerate performance across the forecast horizon. Whether an organization is optimizing an existing portfolio, exploring geographic expansion, or evaluating partnership and acquisition opportunities, the research delivers the kind of grounded, data-informed perspective that reduces uncertainty and improves decision quality.
Mirrors Market
The 1.8 percent CAGR and the broader revenue path from 2026 through 2032 should not be interpreted as a signal to disengage. Instead, they should be read as an invitation to compete on precision. In mature categories, the winners are rarely those who chase volume for its own sake. They are the organizations that understand channel economics, manage cost structures intelligently, differentiate where it matters, and anticipate competitive and regulatory shifts before they become urgent. PW Consulting’s report equips leaders with the intelligence required to play that game effectively.
Accessing the Full Strategic Picture
This overview has highlighted the structural dimensions, competitive realities, and contextual forces that define the global matches market and shape its relevance for 2026 decision-making. Yet the full depth of the analysis extends well beyond the macro indicators and thematic summaries presented here. Detailed segmentation profiles, channel-specific performance dynamics, regional demand characteristics, and competitive benchmarking modules are all integrated into the complete report, offering a comprehensive reference that supports both immediate planning cycles and long-range strategic positioning.
Organizations that require granular breakdowns of product types, packaging formats, distribution pathways, and geographic performance should access the full research document to extract the precise data points relevant to their operating context. The complete report also includes interpretive frameworks, scenario models, and strategic recommendations tailored to different market participation levels, from established manufacturers and distributors to new entrants evaluating selective category exposure. By pairing high-level market intelligence with actionable, segment-level detail, PW Consulting ensures that decision-makers can move from awareness to execution with clarity and confidence.
The matches market may be defined by a simple product, but the strategic environment surrounding it is anything but simple. Navigating it successfully requires a clear view of historical resilience, a disciplined read on near-term stabilization, and a forward-looking understanding of where incremental growth will materialize. With the right intelligence in hand, 2026 can serve not as a year of cautious maintenance, but as a foundation for calculated, well-informed market participation.
For detailed analysis of this topic, please visit the official page: Matches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Potentiometer Market Hits $215M in 2025, Forecasts $317.4M by 2032 at 5.81% CAGR
By PW Consulting, 2026-09-16
Navigate the Potentiometer Market in 2026: Strategic Intelligence for Decision Makers
Executive Summary
As global industries pivot toward higher precision, greater connectivity, and tighter supply chain resilience, the potentiometer market stands at a critical inflection point. What was once a mature passive-component segment is now being reshaped by digital integration, material constraints, and application-specific engineering demands. For executives, procurement leaders, and R&D directors, understanding where this market has been and where it is heading is no longer optional. It is a prerequisite for informed capital allocation, product roadmapping, and supplier negotiation in 2026 and beyond.
This strategic overview distills the core findings of our latest Potentiometer Market research into an actionable executive briefing. It traces the market trajectory from historical momentum through the forecast horizon ending in 2032, assesses the competitive architecture, and examines the structural dynamics that will define the next phase of growth. The goal is simple: give you enough depth to build confidence in the analysis, while preserving the granular intelligence that powers precise go-to-market and sourcing decisions.
Historical Context and Growth Trajectory
The potentiometer market has demonstrated consistent expansion over the past half-decade, building on steady unit demand across industrial control, automotive electronics, and consumer device platforms. Revenue measured in United States dollars reached approximately 163.15 million in 2020, climbed to 166.6 million in 2021, and continued its upward path to 181.6 million in 2022. By 2023, the figure moved to 193.17 million, followed by 203.39 million in 2024. The most recent full-year baseline sits at 215.0 million in 2025, reflecting a market that has broadened its addressable scope as digitization and automation penetrate deeper into end-use systems.
Looking forward, the forecast window from 2026 through 2032 maps a measured but unmistakable growth arc. The market is projected to reach 232.85 million in 2026, advance to 245.1 million in 2027, and approach 246.57 million in 2028. Momentum then accelerates through 2029 at 260.5 million, moves to 289.06 million in 2030, and continues to 290.69 million in 2031 before closing the period at 317.4 million in 2032. These top-line projections are aligned with a compound annual growth rate of 5.81 percent. While the percentage may appear moderate at first glance, it reflects a mature component category that is being selectively expanded by technology transition rather than broad-based volume boom. That distinction matters. Growth in this market is not uniform across product families or customer segments; it is concentrated where engineering requirements favor precision, reliability, and integrated sensing capabilities.
Potentiometer Market
For leadership teams planning 2026 budgets and beyond, this trajectory signals three operational realities. First, demand is not disappearing from traditional industrial and automotive control loops; it is evolving. Second, differentiation is moving up the value chain as customers ask for tighter tolerances, longer service life, and compatibility with higher-level control architectures. Third, the forecast suggests that market participants who can align product roadmaps with the fastest-growing application and regional pockets will capture disproportionate share, even in a category where overall growth stays in the mid-single digits.
Why This Research Matters for 2026 Decision-Making
Market studies are only as useful as the decisions they inform. Our Potentiometer Market research is designed to turn a broad industry narrative into a structured decision framework. Rather than offering a single aggregated number and a generic growth statement, the report decomposes the landscape into the dimensions that actually move business outcomes: product architecture, end-use application behavior, geographic demand distribution, competitive positioning, and the external forces that can compress margins or accelerate substitution.
Executives evaluating 2026 planning cycles need answers to questions that surface-level summaries cannot resolve. Which product architectures are preferred in new designs versus legacy retrofits. Where demand is expanding fastest and where it is plateauing. Which suppliers are building meaningful advantages through technology, scale, or regional presence. What external constraints are likely to influence cost structures and supply continuity. The report addresses each of these areas with a methodology built for operational use: it defines the scope clearly, quantifies the addressable universe in a consistent currency and unit framework, and maps the forward path with a rigorous forecast period that extends well beyond the immediate budget year.
A central reason this research carries strategic weight in 2026 is the concentration profile of the market. With the three largest competitors accounting for approximately 24.6 percent of revenue and the five largest reaching about 26.2 percent, the category is neither fragmented nor tightly consolidated. That middle ground creates both opportunity and risk. Buyers can access a meaningful range of suppliers, yet the competitive center of gravity still rests with a handful of established players who can influence pricing norms, technology adoption, and channel expectations. Understanding who occupies that center, and how the broader field is positioning around them, is essential for sourcing strategy, partnership selection, and new product introduction timing.
The report also treats the forecast not as a single line but as a navigational tool. The years between 2026 and 2032 include moments where growth visibly changes pace. Recognizing those inflection intervals matters when organizations are deciding whether to invest in additional capacity, sign long-term supply agreements, enter new application verticals, or phase out older product lines. With historical data spanning 2020 through 2025 and a forecast extending to 2032, the research gives decision makers a continuous timeline to test assumptions against, instead of forcing them to extrapolate from a single snapshot.
Inside the Report: What You Will Find
The full study is organized to move from macro structure to actionable detail. It begins with a comprehensive market definition and scope framework, establishing the product categories, revenue conventions, and geographic boundaries used throughout the analysis. From there, the report builds a quantified historical view that supports the forecast and provides context for year-over-year shifts. Rather than leaving readers with a single composite figure, it frames the market in terms of its major structural dimensions so that strategy teams can map the data back to their own portfolio, customer base, and supply footprint.
Multi Turn Potentiometer Market
A substantial portion of the report focuses on segmentation logic that mirrors how buyers and engineers evaluate potentiometer solutions in practice. This includes a product architecture perspective covering the families that shape design choices, an application view that connects demand patterns to end-use requirements, and a regional breakdown that highlights where volume and growth are concentrated. These views are arranged to help teams answer practical questions: which product types are most relevant to your target applications, which applications are expanding most rapidly, and how regional demand differs enough to warrant distinct sourcing or go-to-market approaches.
The competitive section profiles the principal players shaping the market today. Each company profile emphasizes the capabilities and offerings most relevant to potentiometer demand, including precision trimmers, rotary and linear variants, digital variants, industrial and high-reliability grades, and integration with sensors and connector systems. The research also tracks recent commercial activity that signals where each company is placing its bets. For example, in November 2025, Bourns Inc. introduced a new high-resolution digital potentiometer series optimized for IoT and automotive applications. This launch illustrates a broader industry trend in which analog essentials are being augmented by digitally enabled variants designed for tighter control loops and connected equipment. The report places developments like this within the larger competitive context so that readers can interpret product announcements as strategic signals rather than isolated events.
How the report supports different functions
- Executive planning teams can use the forecast horizon and structural segmentation to stress-test revenue assumptions, prioritize regions, and identify where portfolio adjustment is most valuable.
- Procurement and supply chain leaders can benchmark the competitive field, evaluate concentration risk, and align contracting strategy with the reality of a market that is moderately concentrated but still supplied by a broad field of capable manufacturers.
- Product and engineering leaders can connect application-level demand patterns to design choices, particularly where digital integration, precision requirements, and reliability expectations are reshaping specification behavior.
- Strategy and M&A teams can use the competitive profiles and regional dynamics to identify adjacent capabilities, partner candidates, and segments where consolidation or capability investment may create durable advantage.
Competitive Landscape: Who Shapes the Market and How
The potentiometer market is defined by a set of established manufacturers that combine component engineering depth with broad distribution reach and application-specific development capability. The competitive picture is not dominated by a single architecture or geography. Instead, it reflects multiple centers of strength: American firms with strong precision and industrial heritage, Japanese manufacturers with deep consumer and automotive electronics experience, and globally integrated suppliers that tie potentiometers into broader sensor and connectivity ecosystems.
Bourns, Inc., based in Riverside, California, continues to stand out for its leadership in trimmers, precision potentiometers, and specialized electronic components serving industrial, automotive, and IoT applications. Its positioning is especially relevant for design teams that need repeatable precision and a product set aligned with both traditional control tasks and newer connected requirements. The company's late-2025 digital potentiometer launch underscores a focus on higher-resolution control and compatibility with automotive and IoT use cases, signaling that its roadmap is actively extending into digitally assisted sensing and adjustment functions.
Vishay Intertechnology, Inc., headquartered in Malvern, Pennsylvania, offers a strong portfolio of single-turn trimpots and precision analog potentiometers built on wire-wound and cermet technologies. Its emphasis on industrial and high-reliability segments makes it a notable reference point for applications where stability, durability, and controlled tolerance matter more than unit cost alone. In a market where some demand is moving toward digital alternatives, Vishay's analog strength remains important for end-uses that still rely on proven resistor-based adjustment and feedback elements.
Honeywell International Inc., based in Charlotte, North Carolina, brings a broader sensing and control identity to the market. Alongside potentiometer-based solutions, Honeywell provides Hall-effect and position sensors for industrial automation and aerospace. This mix matters because many engineering teams evaluate potentiometers not in isolation but as one option within a larger sensing architecture. A supplier that can address both contact-based adjustment and non-contact sensing can influence specification choices at the system level.
Nidec Copal Electronics, located in Tokyo, Japan, specializes in rotary and trimmable potentiometers for consumer electronics and automotive control systems. Its relevance reflects the continued importance of compact, application-tight components for control interfaces and adjustment functions where size, consistency, and integration ease are priorities. Alps Alpine Co., Ltd., also based in Tokyo, manufactures robust rotary and linear potentiometers for automotive and industrial control applications, reinforcing the role of Japanese manufacturers in segments where mechanical robustness and steady performance under demanding conditions are critical.
TE Connectivity, headquartered in Schaffhausen, Switzerland, supplies precision potentiometers integrated into connectors and sensors for electronics and semiconductor-adjacent systems. Its value proposition is rooted in integration and system-level compatibility, which matters as design teams increasingly look for components that reduce assembly complexity and align with broader interconnect and sensing strategies. CTS Corporation, based in Westlake Village, California, produces industrial-grade rotary potentiometers for transportation, medical, and heavy-duty equipment. Its profile highlights demand in sectors where equipment uptime, certification expectations, and long service life shape purchasing decisions more than short-term price variance.
What this competitive structure means for buyers and investors
- The field includes firms with specialty strength in analog precision, digital transition, automotive-grade robustness, and sensor integration, so procurement choices should be tied to application requirements rather than brand familiarity alone.
- Competitive advantage is increasingly defined by the ability to serve demanding end-use environments while also supporting design trends toward higher resolution and digital compatibility.
- Moderate market concentration means credible alternatives exist, but the strongest suppliers still influence expectations on technology roadmaps, qualification cycles, and channel support.
- Recent new-product activity suggests that competitive differentiation will continue to hinge on how well suppliers bridge traditional potentiometer functions with the needs of connected, automated, and high-reliability systems.
Market Dynamics: Materials, Regulation, and Strategic Pressure
Pricing, sourcing, and availability in the potentiometer market do not exist in isolation. They are shaped by material flows, regulatory actions, and the broader electronics supply environment. One of the most significant external factors currently reshaping input-cost expectations is the evolving rare earth export environment linked to China. In April 2025, China imposed expanded export controls on medium- and heavy-rare-earth materials. According to reporting attributed to the Ministry of Commerce of China, the move had the potential to reduce exports dramatically and double global prices for affected elements within weeks. That kind of shock does not remain confined to raw material markets; it filters into component manufacturing, especially where rare-earth-dependent materials contribute to magnetic, sensor-adjacent, or performance-critical subsystems.
The pressure intensified later in the year. The Chinese Ministry of Commerce announced further export controls on rare earth elements and related products effective 8 November 2025, requiring licenses for products containing 0.1 percent or more of Chinese-origin rare earths or manufactured with Chinese equipment. A related assessment from the International Energy Agency in October 2025 noted that China's export controls on heavy rare earth elements introduced in April 2025 had driven European prices up to roughly six times those in China, constraining competitiveness for rare-earth-dependent electronic components.
These developments matter for the potentiometer market because the category does not operate in a vacuum. Even when a component is not itself a rare-earth product, its manufacturing ecosystem, adjacent sensors, and the broader electronic assembly environment can be affected by material constraints and licensing complexity. For sourcing leaders and finance teams, the strategic implication is not simply that costs may rise, but that supply continuity and regional cost structures may diverge more sharply than historical norms suggest. Companies that rely on single-source dependencies or that do not model regulatory risk into their procurement assumptions may face margin compression or schedule disruption.
Operational implications for 2026 planning
- Build rare-earth exposure and material dependency into supplier evaluation criteria, especially for high-reliability and automotive-grade programs where qualification lead times make rapid switching difficult.
- Pressure-test cost models against regional price divergence, particularly if your design or manufacturing footprint depends on components or subsystems sensitive to rare-earth input constraints.
- Use the forecast window to plan flexibility into contracts and inventory strategy, recognizing that regulatory-triggered cost movements can alter the economics of long-term commitments.
- Monitor substitution and design-adaptation trends, since material constraints often accelerate engineering efforts to reduce dependency on constrained inputs or to shift specifications toward alternative technologies.
What Comes Next for Strategy and Sourcing
The potentiometer market is moving through a phase where growth is dependable but uneven, and where competitive advantage is increasingly tied to technology transition, reliability assurance, and supply resilience. The top-line forecast points to a market that will continue expanding through 2032, but the real strategic work lies in understanding where that expansion concentrates, which product approaches win new specifications, and how external constraints alter the economics of supply.
For 2026 decision makers, the highest-value questions are practical. Which applications are pulling demand upward most strongly in your portfolio. Which product architectures best match the precision and integration requirements of your customers. How exposed your sourcing strategy is to material and regulatory volatility. Which competitors are shaping expectations through product launches, integration offerings, and application-specific development. The full Potentiometer Market research is built to help answer those questions with the level of detail that planning committees, procurement teams, and engineering leaders need to act with confidence.
This briefing has outlined the trajectory, structure, competitive landscape, and external pressures that define the market today. The complete report goes further, offering the segment-level analysis, regional views, application breakdowns, and company-level insights necessary to turn strategic awareness into concrete decisions. For organizations preparing for 2026 and the forecast years that follow, that deeper intelligence is where the real advantage lies.
For detailed analysis of this topic, please visit the official page: Potentiometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


