



PW Consulting: Medical Practice Management Software Market Hits $8.95B in 2025, 9.2% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Medical Practice Management Software Market
The healthcare technology sector is entering a decisive phase. As administrative burdens grow and regulatory frameworks tighten, medical practices are no longer treating practice management software as a back-office utility. It has become the operational backbone connecting clinical care, revenue integrity, and patient experience. For executives, investors, and strategic planners, understanding where this market is heading is no longer optional. It is a prerequisite for capital allocation, vendor selection, and product roadmap planning.
PW Consulting has released a comprehensive market research study on the Medical Practice Management Software Market. This report is built to inform 2026 decision-making with granular market sizing, segmentation analysis, competitive profiling, and forward-looking scenario modeling. What follows is a preview of the market terrain, the structural forces reshaping it, and the analytical rigor you can expect from the full study. The complete dataset, detailed breakdowns, and advanced scenario models are available through the source page, where decision-makers can access the full intelligence package needed to act with confidence.
A Market in Measured but Accelerating Expansion
Over the 2020 to 2025 historical window, the market demonstrated consistent upward momentum, expanding from 6800 Million USD in 2020 to 8950 Million USD in 2025. This trajectory reflects a sector that has absorbed the shock of rapid digital transformation and evolved into a more mature, demand-driven environment. Practices are no longer purchasing software in isolation. They are consolidating administrative workflows, integrating clinical documentation, and seeking platforms that can adapt to shifting reimbursement models and patient expectations.
Looking ahead to the 2026 to 2032 forecast period, the market is projected to continue its expansion at a compound annual growth rate of 9.2 percent. By 2032, the overall market size is anticipated to reach 16559 Million USD. This growth profile signals more than incremental adoption. It points to structural adoption cycles where mid-sized and independent practices, healthcare systems, and specialty groups are reevaluating their technology stacks. The forecast reflects a market where demand is broadening beyond core scheduling and billing into integrated clinical, financial, and engagement workflows.
For 2026 strategy sessions, the most important takeaway is trajectory stability paired with segment-level divergence. While the headline growth path is clear, the drivers behind it vary significantly across practice types, deployment models, and functional priorities. Our full report unpacks these variations without flattening them into averages, giving leadership the precision needed to align investments with the segments that matter most to their portfolio.
Where Value Is Being Created: Structural Shifts in Demand
The market is not expanding uniformly. Demand is being reshaped by three interlocking forces: workflow consolidation, AI-enabled automation, and compliance pressure. These forces are influencing how practices evaluate vendors, what features they prioritize, and how quickly they move from evaluation to deployment.
Workflow Consolidation and Integrated Platforms
Practices are increasingly favoring platforms that unify scheduling, billing, clinical documentation, and patient engagement rather than stitching together point solutions. Integrated deployments reduce data silos, lower administrative handoff errors, and create a cleaner audit trail for compliance and revenue cycle management. This trend is particularly visible among independent and group practices that need to do more with smaller administrative teams. At the same time, larger healthcare systems are seeking enterprise-grade platforms that can scale across specialties while maintaining consistent revenue cycle optimization. The report examines how these preferences are influencing adoption patterns and vendor positioning across the market landscape.
AI as an Operational Inflection Point
Artificial intelligence has moved from a marketing differentiator to a practical operational lever. According to the 2026 Physician Survey on Augmented Intelligence from the American Medical Association Center for Digital Health and AI, 81 percent of physicians are using AI tools professionally, more than double the 38 percent reported in 2023. That surge is reshaping expectations for practice management software. 일선 physicians and administrators now expect AI-assisted clinical documentation, smarter scheduling optimization, and automated revenue cycle support. The market response is accelerating, with product releases and financing activity increasingly centered on AI capabilities.
Recent developments illustrate this shift clearly. AdvancedMD’s 2026 Winter Product Release introduced more than twenty updates, highlighted by the AI Clinical Assistant. Athenahealth’s Spring 2026 release added authorization expiration alerts embedded directly into scheduling and eligibility workflows. DrChrono’s January 2026 update launched a No Show Predictor AI feature that assigns risk scores to upcoming appointments. Meanwhile, Tebra secured 250 million USD in new equity and debt financing led by Hildred to accelerate AI development across clinical documentation, billing automation, and practice marketing. These moves are not isolated product tweaks. They represent a broader reorientation toward AI as a core value driver in practice management.
Compliance Pressure Reshaping Procurement Priorities
Regulatory and reimbursement dynamics are tightening the cost of inaction. The proposed HIPAA Security Rule update would eliminate the distinction between required and addressable safeguards, mandating encryption, multi-factor authentication, and 72-hour system restoration. It is also projected to add a 9 billion USD industry cost in year one. These requirements are pushing security, resilience, and audit readiness up the procurement checklist.
Enforcement intensity is rising in parallel. HHS enforcement accelerated dramatically in 2025, with 19 or more HIPAA settlements announced through August alone for risk analysis failures. For practice management software buyers, this environment changes the evaluation calculus. Functionality remains essential, but vendors that cannot demonstrate robust risk management, secure data exchange, and reliable restoration capabilities face growing scrutiny. Our report places these compliance dynamics in context, showing how they influence purchasing timelines, contract terms, and long-term vendor viability.
Competitive Landscape: Differentiation in a Consolidating Arena
The competitive field is defined by a mix of established platforms, cloud-native entrants, and specialty-focused vendors. Concentration levels indicate a market that is still broad enough for differentiated positioning while increasingly shaped by scale players. The top three competitors account for 35.5 percent of the market, while the top five reach 48.2 percent. This concentration suggests that while no single vendor dominates outright, leadership positions are beginning to consolidate around platforms that can deliver integration depth, AI-enabled workflow support, and strong revenue cycle capabilities.
Several core companies define the current battleground, each bringing a distinct strategic profile:
- Athenahealth, based in Boston, Massachusetts, provides cloud-based medical practice management software with integrated EHR, revenue cycle management, scheduling, and patient engagement tools targeted at independent and group practices.
- AdvancedMD, headquartered in South Jordan, Utah, offers cloud-based EHR, practice management, and AI-powered tools with specialty-specific workflows for front office, billing, and patient engagement.
- Veradigm LLC, formerly Allscripts Healthcare Solutions, delivers specialty-adaptable practice management software for administrative, financial, and clinical operations across multiple medical specialties.
- eClinicalWorks, located in Marlborough, Massachusetts, provides comprehensive medical practice management and EHR software focused on independent practices, including scheduling, billing, and reporting.
- CureMD, based in New York, New York, offers easy-to-use medical practice management and EHR solutions optimized for cost-effective independent practices.
- Greenway Health, headquartered in Atlanta, Georgia, supplies integrated practice management and EHR platforms with emphasis on specialty care and seamless data exchange.
- Kareo, from Salt Lake City, Utah, delivers cloud-based practice management software specifically for independent medical practices, including billing and front-office automation.
- Practice Fusion, based in San Francisco, California, offers cloud-based EHR and practice management software with certified tools for ambulatory care and billing.
- NextGen Healthcare, also in Atlanta, Georgia, provides enterprise-grade practice management and EHR solutions with a strong focus on healthcare systems and revenue cycle optimization.
- ChartLogic, based in Fort Worth, Texas, supplies practice management and EHR software including e-prescribing, revenue cycle, and patient portals for independent providers.
- OmniMD, headquartered in Overland Park, Kansas, delivers web-based practice management software with tools for scheduling, billing, and clinical documentation in ambulatory settings.
The strategic question for 2026 is not simply who leads today, but how each vendor is positioned to absorb the compliance burden, scale AI capabilities, and maintain data interoperability across diverse practice settings. Some players are leaning into specialty workflows and independent practice economics. Others are emphasizing enterprise-grade revenue cycle optimization or cloud-native automation. Our report evaluates these postures in detail, mapping capabilities to the segments where they create the most competitive advantage.
What the Report Delivers: From Market Sizing to Actionable Strategy
This study is designed to support both strategic planning and operational decision-making. It integrates historical performance, forward-looking forecasts, segmentation analysis, competitive profiling, and industry dynamics into a single decision framework. Rather than presenting high-level commentary, the report grounds each insight in structured data and practical interpretation.
The report covers the full market arc, with a base year of 2025 and a historical review spanning 2020 to 2025. The forecast period extends from 2026 to 2032, enabling leadership to test near-term commitments against longer-term adoption cycles. Market sizing is presented in Million USD, with growth trajectories evaluated through a 9.2 percent CAGR lens. This structure allows readers to understand not only where the market stands, but how momentum is likely to build across the forecast horizon.
Beyond top-line sizing, the study breaks down demand by type, application, and region. These segmentation views help identify where adoption is strongest, which functional categories are attracting the most investment, and how geographic patterns differ across maturity levels and practice structures. Importantly, the report connects segmentation to decision relevance, showing how each slice of the market relates to vendor strategy, purchasing behavior, and implementation risk.
Competitive analysis is another central pillar. The report profiles the companies shaping the market, examining their strategic focus, target segments, and recent product or financing activity. This is paired with concentration analysis to give readers a realistic picture of market structure, competitive intensity, and the room available for differentiated positioning. For organizations evaluating partnerships, procurement, or market entry, this section provides a practical map of who is competing on which dimensions.
The research also integrates industry context that directly affects market behavior. Regulation, reimbursement pressure, AI adoption trends, and enforcement activity are treated as active market drivers rather than background noise. The goal is to help leaders anticipate how these forces will alter purchasing timelines, feature priorities, and vendor requirements in 2026 and beyond.
How Decision-Makers Can Use the Study
The full report is structured to support a range of strategic use cases. Executive teams can use it to validate market entry assumptions, prioritize investment areas, and benchmark growth expectations. Procurement and IT leaders can use the segmentation and competitive sections to refine vendor shortlists and align feature requirements with market realities. Investors and financial analysts can use the forecast framework and concentration data to assess market maturity, growth durability, and the distribution of value across participants.
Because the market is expanding while becoming more complex, the most valuable insights are often the ones that connect macro trends to segment behavior. That is where the full study adds the most weight. It isolates the demand patterns that averages can obscure and highlights the operational implications that matter for planning cycles.
Why 2026 Demands a More Precise Read on This Market
This is a year when technology expectations, compliance requirements, and operational economics are converging. Practices are under pressure to reduce administrative friction, protect revenue integrity, and meet rising security expectations. Vendors are racing to embed AI, strengthen interoperability, and demonstrate tangible workflow improvements. In that environment, strategy built on broad generalizations is increasingly risky.
Medical Practice Management Software Market
Legal Practice Management Software Market
The Medical Practice Management Software Market is large enough to offer meaningful opportunity and fragmented enough to reward targeted positioning. A 9.2 percent CAGR through 2032 indicates durable expansion, but the real strategic value lies in understanding which demand pockets are accelerating, how competitive pressure is concentrating, and where regulatory and reimbursement shifts will reshape buyer behavior.
This preview has outlined the market’s direction, the forces shaping it, and the analytical depth of the full study. The complete report provides the detailed segmentation, company-level assessments, scenario-ready forecasts, and compliance-context analysis needed to move from awareness to action. For organizations preparing decisions in 2026, the source page offers the full intelligence package, including the granular breakdowns and proprietary analysis that support confident, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Medical Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micro Gas Generator Market Hits $176.58M in 2025, Projected 6.98% CAGR to 2032
By PW Consulting, 2026-09-16
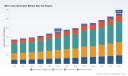
Navigating the Micro Gas Generator Market: Strategic Intelligence for 2026 and Beyond
The global energy landscape is undergoing a profound transformation, driven by the urgent need for distributed power solutions, heightened efficiency standards, and an accelerating shift toward low-emission technologies. For enterprises operating in or adjacent to the energy sector, understanding the trajectory of micro gas generators is no longer optional—it is a strategic imperative. As we release our latest comprehensive market research on the Micro Gas Generator Market, this article serves as a foundational overview, highlighting the macro-level trends and competitive dynamics that define the opportunity space through 2032 while compelling a deeper dive into the full intelligence package available for executive decision-makers.
A Market in Structural Growth Mode
The Micro Gas Generator Market has demonstrated consistent expansion over the past half-decade, evolving from a niche distributed energy solution into a critical component of modern power infrastructure. Historical data from 2020 through 2025 reveals a market that has steadily climbed in revenue terms, reflecting sustained demand across multiple verticals. This upward trajectory is not merely cyclical; it is structural, underpinned by technological maturation, regulatory tailwinds, and an increasingly volatile macroeconomic environment that favors on-site generation.
Looking ahead, our forecast model projects continued robust growth across the 2026 to 2032 horizon. The compound annual growth rate anticipated over this forecast period underscores the market's resilience and its capacity to absorb new capacity additions. Revenue projections escalate meaningfully year over year, suggesting that scale effects, cost reductions in core technologies, and expanding application breadth will compound over time. For corporate strategists, these top-line indicators signal a market that is both expanding and maturing—conditions that reward early movers with clear positioning strategies.
Drivers Shaping the Market Trajectory
Several interlocking forces are accelerating adoption of micro gas generator technologies. Understanding these dynamics is essential for any organization evaluating product roadmaps, partnership strategies, or market entry considerations.
- Distribution of power generation assets is becoming a priority for industries seeking to reduce reliance on centralized grids. Micro gas generators offer modular, scalable solutions that can be deployed close to load centers, minimizing transmission losses and enhancing energy security.
- Efficiency mandates and emissions regulations are compelling end-users to evaluate combined heat and power configurations. Technologies capable of running on natural gas, biogas, and renewable natural gas align directly with decarbonization roadmaps and qualify for incentive programs designed to reward high-efficiency, low-emission systems.
- Input cost volatility in industrial energy markets is reshaping total cost of ownership calculations. As natural gas prices fluctuate and procurement strategies adapt, organizations are weighing the economic merits of on-site generation versus grid procurement, with micro gas turbines presenting a compelling hedge against supply disruption and price spikes.
- Technological convergence—particularly in microturbine design, air-bearing systems, and hybrid configurations—is broadening the addressable use cases. From industrial facilities to commercial buildings and specialized mobile power applications, the versatility of these systems is expanding the customer base.
The Competitive Arena: Who Is Setting the Pace
The competitive landscape of the Micro Gas Generator Market is characterized by a mix of established manufacturers, specialized technology providers, and emerging players vying to capture share in a growing field. Our research profiles the key companies that are defining product standards, securing high-profile deployments, and shaping industry expectations around performance and sustainability.
At the forefront stands Capstone Green Energy Corporation, a leading manufacturer of microturbine systems that form the technological core of many micro gas generator offerings. Headquartered in Van Nuys, California, Capstone provides a broad range of combined heat and power units spanning 30 to 1000 kW, catering to distributed power generation needs across industrial and commercial applications. The company's recent strategic moves illustrate the kind of corporate agility that matters in this market. In May 2026, Capstone Energy+—formerly operating under the Capstone Green Energy brand—completed a rebranding exercise to emphasize its focus on circular, scalable, and clean energy solutions, simultaneously closing a $112.5 million strategic investment. This capital infusion reinforces the company's ability to scale operations and invest in product development.
Worldwide Wood Gas Generator Market
Operational momentum has accompanied this financial and strategic repositioning. In April 2026, Capstone powered a premier Utah hospitality destination with its microturbine energy solution for efficient on-site power generation, demonstrating the technology's appeal in high-visibility commercial settings. Toward the end of 2025, the company secured repeat orders from a leading Mexican food manufacturer for its C1000S Microturbine CHP System and was selected by a major frozen Mexican food producer for the C800S Microturbine Energy Solution. Additionally, in October 2025, Capstone was awarded a contract by Valparaiso Community Schools for high-efficiency CHP systems, highlighting the technology's relevance in institutional and public-sector applications.
Beyond the North American leader, the competitive field includes a diverse set of players with distinct technological focuses and geographic footprints. Bladon Micro Turbine, based in the United Kingdom, produces Micro Turbine Gensets featuring high-speed microturbines and air-bearing technology tailored for distributed power generation. In the Netherlands, MTT Microturbine specializes in low-cost micro gas turbine systems aimed at domestic, small, and medium-sized enterprise power generation—addressing price-sensitive segments that remain underserved in many regions. FlexEnergy Solutions, also headquartered in the United States, manufactures microturbine-based systems for both power-only and CHP applications, emphasizing high-efficiency designs that meet distributed energy requirements.
European and global coverage widens further with Ansaldo Energia SpA in Italy, which offers microturbine solutions for combined heat and power and industrial distributed generation, and Aurelia Turbine in Finland, focused on efficient power generation applications. ICR Turbine Engine Corporation, another U.S.-based developer and producer, targets distributed energy and CHP uses, while UAV Turbine supplies microturbine systems encompassing both portable and industrial power generation options. Rounding out the competitive mosaic, Brayton Energy in the United States manufactures hybrid microturbine systems designed for versatile power generation scenarios.
Micro Gas Generator Market
This array of companies illustrates a market where differentiation hinges on technology specificity, application fit, and the ability to navigate regional regulatory and economic conditions. Concentration metrics indicate that while no single entity dominates the market outright, a cluster of leading firms commands a meaningful share of revenue, creating both competitive pressure and collaboration opportunities.
What the Full Report Delivers
While this overview establishes the macro context and competitive contours, the complete Micro Gas Generator Market research study goes substantially deeper, providing the granular intelligence that strategy teams require to make actionable decisions. The report is structured to support multiple use cases, from market entry assessments and competitive benchmarking to investment prioritization and risk evaluation.
- Detailed segmentation analysis that breaks down the market by type, application, and region, offering clarity on which sub-segments are driving growth and where saturation or disruption risks may emerge.
- Company profiles and competitive positioning assessments that evaluate the strategic posture, product portfolios, and recent moves of key market participants, enabling apples-to-apples comparison across technology approaches and business models.
- Market dynamics analysis that synthesizes regulatory developments, raw material cost trends, incentive structures, and macro energy price movements into a coherent picture of the forces shaping demand and supply.
- Forecast data spanning the 2026 to 2032 period, with revenue projections and growth rate estimates that allow scenario planning under varying conditions.
- Technology and application deep dives that correlate product characteristics with end-user requirements, helping buyers and sellers align specifications with real-world performance expectations.
The report avoids superficial aggregation. Instead, it isolates the variables that matter most for decision-making—capacity deployment trends, regional demand differentials, application-specific adoption curves, and the interplay between fuel costs and system economics—presenting them in a format designed for executive consumption and strategic planning.
Market Dynamics and External Influences
No market analysis is complete without situating the industry within its broader environment. The Micro Gas Generator Market does not operate in a vacuum; it is shaped by energy prices, environmental regulations, and procurement incentive frameworks that vary by jurisdiction and evolve over time. For instance, U.S. industrial natural gas prices averaged 6.03 USD per thousand cubic feet in 2025, establishing a baseline against which on-site generation economics are measured. Yet price volatility remains a reality, as evidenced by natural gas prices falling to 3.22 USD per MMBtu in June 2026, reflecting ongoing fluctuations in industrial energy markets that complicate long-term cost forecasts and reward flexible procurement strategies.
Regulatory and incentive landscapes further influence adoption patterns. Microturbine-based CHP systems can qualify for U.S. Environmental Protection Agency Combined Heat and Power incentives due to their high efficiency and low emissions profile, improving the financial case for deployment in eligible settings. Additionally, manufacturers such as Capstone have emphasized that their microturbines operate on natural gas, biogas, and renewable natural gas, positioning their products to support low-emission distributed power applications in alignment with sustainability targets. These capabilities are particularly relevant as organizations seek to demonstrate progress on decarbonization while maintaining operational reliability. With over 9,000 global installations attributed to leading clean technology manufacturers in this space, the installed base provides both a proof point for technology maturity and a foundation for service, support, and incremental innovation.
Strategic Implications for 2026 Decision-Makers
The confluence of market growth, technological diversification, and external volatility creates a decision environment that rewards rigorous analysis. For organizations evaluating participation in or exposure to the Micro Gas Generator Market, the strategic questions are clear: Which sub-segments offer the best balance of growth and competitive defensibility? How should product portfolios be positioned to capture demand from both established industrial users and emerging application areas? What partnerships, acquisitions, or R&D investments will strengthen a firm's ability to compete as the market scales and differentiates?
Our research is designed to equip leadership teams with the answers. By combining historical context, forward-looking forecasts, and detailed competitive and dynamic analysis, the study reduces uncertainty and sharpens strategic focus. It provides the evidentiary basis for capital allocation decisions, market entry evaluations, and product strategy refinements, ensuring that executives are not operating on assumptions but on validated market intelligence.
Access the Full Strategic Intelligence
This article has illuminated the broad contours of the Micro Gas Generator Market—its growth trajectory, its key players, and the forces shaping its evolution. Yet the depth required for high-stakes strategic decisions lies within the full report. Detailed segmentation data, company-by-company competitive assessments, regional demand patterns, application-specific revenue breakdowns, and forward-looking scenario analyses are all essential components that cannot be fully captured in a summary format.
For decision-makers who need to move beyond surface-level trends and into the specifics that drive resource allocation, partnership selection, and competitive positioning, we invite you to access the complete Micro Gas Generator Market research. The full study delivers the comprehensive, data-rich intelligence necessary to navigate this dynamic market with confidence in 2026 and through the forecast horizon to 2032.
For detailed analysis of this topic, please visit the official page: Micro Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Poultry Breeding Equipment Market to Hit $609.8M by 2032 at 5.54% CAGR
By PW Consulting, 2026-09-16
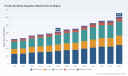
Strategic Imperatives in the Poultry Breeding Equipment Market: A 2026 Outlook
The global poultry industry stands at a critical inflection point. As protein demand scales and production systems modernize, the machinery underpinning breeding operations has evolved from a operational necessity to a strategic asset. For executives, investors, and supply chain leaders operating in animal agriculture, understanding the trajectory of poultry breeding equipment is no longer optional. It is a prerequisite for capital allocation, competitive positioning, and long-term resilience. This industry insight introduces our latest comprehensive market research, designed specifically to equip decision-makers with the analytical rigor required for 2026 planning and beyond.
Poultry Breeding Equipment Market
Why 2026 Demands a Reset in Equipment Strategy
The past half-decade has reshaped the economics of poultry breeding. Historical performance from 2020 through 2025 demonstrates a consistent upward trajectory, with total market valuation climbing from 321.5 million USD to 420.0 million USD. This growth was not merely cyclical; it reflects structural shifts in automation adoption, biosecurity prioritization, and the consolidation of breeding operations around standardized, high-throughput environments. Looking forward, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 5.54 percent. By the close of the forecast window, market revenue is expected to surpass 600 million USD.
These figures are more than macroeconomic indicators. They signal a maturing equipment ecosystem where incremental efficiency gains translate directly into margin protection. Flocks are growing larger, turnaround cycles are tightening, and regulatory scrutiny around disease control has intensified. Equipment procurement decisions made in 2026 will lock in operational characteristics for the next seven to ten years. A feeder system, climate control array, or incubation line selected today dictates throughput capacity, labor dependency, and vulnerability to biological stressors. Strategic buyers must therefore evaluate equipment not as isolated capital expenditures, but as integrated components of a long-term production architecture.
What This Research Delivers: Operational Intelligence Over Abstract Projections
Our market study is structured to bridge the gap between high-level industry narratives and floor-level execution. Rather than offering a single growth curve, the report deconstructs the market across multiple analytical dimensions, each calibrated to answer specific strategic questions. The segmentation framework examines equipment categories including incubation systems, hatching infrastructure, and breeding management platforms, allowing readers to isolate capital intensity, technology readiness, and adoption velocity within each functional area. Application-level analysis further distinguishes between broiler breeding and layer breeding operations, acknowledging that feed conversion targets, cycle lengths, and environmental control requirements diverge significantly between the two production models.
Regional dynamics are mapped with equal precision. The research captures how procurement patterns, infrastructure maturity, and policy environments differ across major geographic corridors. Readers will find contextual guidance on where equipment demand is being pulled by capacity expansion, where it is being pushed by modernization of legacy facilities, and where regulatory or logistical friction is reshaping procurement timelines. This geographic lens is essential for manufacturers evaluating market entry, distributors planning inventory positioning, and end-users benchmarking regional best practices against their own operational baselines.
Beyond segmentation, the report integrates forward-looking modeling that stress-tests growth assumptions against plausible macroeconomic and industry-specific variables. Sensitivity scenarios address fluctuations in feed input costs, shifts in labor availability, and the pace of automation penetration across different farm sizes. By presenting these scenarios side by side, the study enables leadership teams to identify which equipment investments remain robust under downside conditions and which carry elevated exposure to external shocks.
Competitive Landscape: Differentiation, Velocity, and Strategic Positioning
The poultry breeding equipment sector is characterized by a concentrated yet highly active competitive field. Our analysis tracks the strategic postures of leading manufacturers whose product portfolios and deployment footprints shape market standards. Roxell, headquartered in Belgium, has carved a specialist position through automated feeding, drinking, nesting, and climate systems tailored specifically for broiler breeder environments. Big Dutchman, based in Germany, operates as a global leader in smart poultry production equipment, offering integrated feeding, housing, and climate control solutions that emphasize data connectivity and breeder management efficiency. VAL-CO, operating from the United States, focuses on watering systems, feeding architecture, and environmental control equipment designed for the practical demands of commercial breeder farms.
The competitive field also includes Facco from Italy, which provides complete turnkey poultry equipment solutions encompassing breeding systems and integrated farm layouts. TEXHA, based in Slovakia, manufactures both cage-based and cage-free equipment configurations, reflecting the industry's ongoing navigation between conventional and alternative housing philosophies. Hightop Group, headquartered in China, has expanded its footprint as a manufacturer of fully automatic poultry farming equipment, including dedicated breeder systems that combine scale economics with automation features. Together, these players illustrate a market where differentiation emerges from engineering specialization, regional service networks, and the ability to package equipment into cohesive operational ecosystems rather than standalone machines.
Recent corporate activity underscores the pace of strategic execution. In March 2025, Big Dutchman completed the installation of comprehensive poultry production systems at a Hungarian broiler breeder farm, a deployment that highlights the industry's preference for integrated solutions capable of streamlining breeder management across multiple production variables. By March 2026, the same company showcased its newest equipment innovations at the PEAK trade show powered by the Midwest Poultry Federation, signaling continued investment in product iteration and direct engagement with North American procurement audiences. Meanwhile, Facco confirmed its attendance at VIV Europe 2026 in Utrecht, Netherlands, positioning itself to present the latest poultry equipment developments to a concentrated European buyer base. These events are not isolated press items; they are indicators of where engineering priorities are being demonstrated, where sales channels are being reinforced, and how manufacturers are aligning product roadmaps with regional demand clusters.
Regulatory Forces and Biosecurity as Equipment Design Drivers
Equipment selection in poultry breeding cannot be divorced from the regulatory and biosecurity environment. The National Poultry Improvement Plan establishes sanitation procedures for hatchery equipment, including incubators and hatchers, to ensure the integrity of disease-free breeding stock. Under these standards, hatchery equipment must be cleaned and disinfected after each set or transfer, reinforcing a operational reality that equipment design, material selection, and access geometry directly influence compliance feasibility.
For procurement teams, this translates into a practical evaluation criterion: how readily can a system be sanitized without compromising throughput, and how do design choices affect the labor and chemical costs associated with routine disinfection protocols? Equipment that integrates smooth surfaces, removable components, and clear access pathways reduces the friction of compliance, while systems that complicate sanitation routines introduce hidden operational costs and biosecurity risk. The report examines how manufacturers are responding to these requirements through engineering choices and how end-users can factor compliance burden into total cost of ownership calculations.
Beyond sanitation, the broader regulatory context influences ventilation standards, climate control precision, and environmental monitoring integration. As breeding operations face increasing expectations around traceability, animal welfare, and disease containment, equipment that supports data capture and environmental consistency gains strategic value. The research connects these regulatory dynamics to procurement timing, vendor selection criteria, and lifecycle planning, ensuring that compliance considerations are treated as design inputs rather than afterthoughts.
How to Use This Study for 2026 Decision-Making
This market research is designed for operational deployment, not passive reading. Capital planning teams can use the segmentation and forecasting framework to prioritize equipment categories that align with their production mix and growth targets. Procurement leaders can benchmark regional demand patterns against supplier coverage, identifying gaps where localized service capacity or inventory positioning may create competitive advantage. Manufacturers and distributors can leverage the competitive landscape analysis to refine product roadmaps, assess white-space opportunities, and calibrate partnership or channel strategies against the positioning of established players.
The study also supports risk governance. By mapping growth assumptions against operational sensitivities, leadership teams can distinguish between investments that are structurally aligned with industry momentum and those that depend on narrow favorable conditions. The inclusion of biosecurity and regulatory context further ensures that equipment acquisitions are evaluated through the lens of long-term operational resilience, not just upfront pricing or specification checklists.
Detailed regional breakdowns, application-level revenue distributions, company-level capability assessments, and scenario-modeling outputs are reserved for the full report. These components are built to support specific procurement timelines, investment committee reviews, and strategic planning cycles. The executive summary presented here establishes the analytical foundation and directional evidence; the complete study delivers the granular intelligence required to translate strategy into executed decisions.
Next Steps: Accessing the Full Intelligence Package
The poultry breeding equipment market is expanding with structural consistency, but the dispersion of opportunity across equipment types, applications, and regions requires precise navigation. Our full market research report provides the segmented data, competitive profiling, regulatory context, and forward-looking modeling needed to ground 2026 decisions in evidence rather than assumption. For executives seeking to allocate capital, refine vendor selection, or position operations for the next phase of industry modernization, the complete study offers the depth and structure necessary for confident action.
To access the full report, including detailed market size trajectories, segmentation intelligence, competitive benchmarks, and scenario analyses tailored for strategic planning, visit the source page to request the complete intelligence package.
Worldwide Bee Breeding Equipment Market
For detailed analysis of this topic, please visit the official page: Poultry Breeding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tungsten Hexafluoride Market to Hit USD 344.8 Million by 2032, Growing at 6.8% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence Behind the Tungsten Hexafluoride Market Outlook: Navigating the 2026–2032 Inflection Point
Executive Perspective: Why This Market Deserves Boardroom Attention
Tungsten hexafluoride has long operated as a quiet but indispensable enabler of advanced manufacturing. As a key precursor in chemical vapor deposition and a foundational feedstock for tungsten-based materials, its demand profile is tightly coupled to the cadence of semiconductor scaling, advanced packaging, and industrial tungsten carbide production. Yet the market has entered a new strategic era defined by material geopolitics, capacity realignments, and accelerating procurement complexity. For executives managing supply chains, capital allocation, and technology roadmaps, the task is no longer to track price movements in isolation, but to decode the structural forces reshaping availability, grade differentiation, and competitive positioning across the value chain.
The latest PW Consulting Tungsten Hexafluoride Market research was built to meet that challenge. It translates a multi-year historical trajectory and a forward forecast window into a decision-ready framework, giving leadership teams the clarity needed to evaluate sourcing strategies, investment timing, and competitive exposure with greater precision.
Cumulative Momentum and the Forward Growth Arc
The market’s growth narrative over the past half-decade reflects sustained expansion rather than episodic spikes. Historical revenue progression from 2020 through 2025 shows a steady upward path, building from a base above 160 million USD in 2020 to a 2025 position at 215.0 million USD. This trajectory establishes an important baseline: demand has not merely recovered, it has compounded through successive manufacturing cycles, capacity additions, and broader content gains in high-value applications.
Looking ahead, the forecast architecture extends across the 2026–2032 period and points to continued expansion at a projected CAGR of 6.8 percent. The forward numbers illustrate a market that is scaling into a materially larger revenue envelope, with the outlook positioning 2026 near 238 million USD and progressing toward a 2032 level of approximately 345 million USD. These figures are not simply statistical projections; they are a structural signal that demand creation is becoming more durable, more diversified, and increasingly sensitive to technology roadmaps, regional production strategies, and grade-specific sourcing preferences.
For decision-makers, the strategic implication is clear. Growth at this pace rewards early visibility. Companies that wait for market signals to become obvious often find themselves reacting to capacity constraints, grade availability issues, or regional supply interruptions rather than shaping their own positioning. A research framework that maps the progression from historical consolidation to the forecasted expansion window allows executives to test scenarios around procurement timing, regional exposure, and application mix well before those decisions become urgent.
Where Value Is Being Created: Segmentation Logic That Matters
A market of this scale cannot be managed through aggregate totals alone. The operational reality is that different segments behave very differently in terms of procurement cadence, specification sensitivity, pricing tolerance, and supply chain vulnerability. That is why the research framework decomposes the market along axes that matter to real purchasing and production decisions.
Regionally, the market is shaped by clusters of semiconductor manufacturing intensity, industrial material demand, and the evolving geography of gas supply chains. Some regions anchor high-volume advanced manufacturing ecosystems, while others function as growing demand centers or specialized supply nodes. Understanding these regional dynamics is essential because exposure to one geography can carry very different risk-and-opportunity profiles than exposure to another.
By application, the demand base reflects the relative weight of semiconductor manufacturing, tungsten carbide production, and a broader set of industrial and specialty uses. The semiconductor segment carries a distinct set of requirements: high-purity specifications, tight quality assurance expectations, and procurement tightly linked to fab build-outs and node transitions. Tungsten carbide demand, meanwhile, follows a different rhythm tied to tooling, industrial components, and downstream manufacturing cycles. A third application grouping captures additional specialty and industrial use cases that contribute to overall resilience and diversification.
By grade, the distinction between electronic-grade and industrial-grade material is especially important. Electronic-grade supply tends to command stricter qualification processes, more intensive quality documentation, and stronger sensitivity to continuity and traceability. Industrial-grade demand is shaped by different performance thresholds and cost structures. For buyers, the grade mix is not a detail; it is a procurement architecture decision that influences supplier qualification, inventory strategy, contract design, and risk exposure across the supply base.
The research does not flatten these distinctions into generic averages. Instead, it treats segmentation as a strategic lens: where demand is concentrated, which segments are expanding fastest in structural terms, and how grade and application choices shape competitive positioning. This approach enables a much more grounded evaluation of where opportunity and vulnerability coexist.
Competitive Structure: Concentration, Capability, and Strategic Posture
The tungsten hexafluoride supply landscape is characterized by meaningful concentration, but concentration alone does not tell the full story. Concentration ratios indicate how much of the market is controlled by a smaller group of players, yet the real competitive insight lies in what each participant brings to the market in terms of grade capability, application focus, geographic reach, and supply strategy.
The leading competitive set spans globally integrated electronic-gas specialists, major industrial gas companies with semiconductor-facing portfolios, regional distributors and suppliers, and increasingly active producers aligned with regional demand expansion. Merck KGaA operates with a semiconductor-grade offering oriented toward deposition and metals applications across logic and memory markets, with a footprint that spans major semiconductor manufacturing centers. Linde plc supplies tungsten hexafluoride as an electronic special gas tied to chemical vapor deposition, positioning the material within a broader electronic gases context. Air Liquide S.A. delivers the product through its electronics business unit, supporting semiconductor fabs and display manufacturers internationally. These players reflect the high-specification end of the market, where qualification, consistency, and global service capability often matter as much as volume.
At the same time, other participants illustrate the more diversified and regional dimensions of the supply base. Airgas USA, LLC distributes and supplies tungsten hexafluoride for industrial, synthetic, and analytical chemistry applications, emphasizing breadth of reach and application flexibility. Inhance Technologies emphasizes semiconductor CVD-grade supply with customized specifications and an American-made supply angle that aligns with onshoring considerations. This illustrates how national supply posture is becoming a procurement attribute in its own right, especially where supply security and local presence are weighted alongside price and quality.
On the production side, Chinese manufacturers are expanding to meet growing demand and to strengthen domestic and export capacity. CSSC Special Gas Co., Ltd. has announced a new project designed to add substantial annual capacity, with operations expected in 2027, signaling a deliberate response to demand growth and an intent to scale output in step with market needs. Jiangsu Kaimei Electronic Materials Co., Ltd. manufactures high-purity material for export and maintains a dedicated production capacity, reinforcing the presence of specialized export-oriented supply. Asian Isotope International supplies hexafluorotungsten for semiconductor-related CVD applications, reflecting continued participation across the semiconductor demand chain.
The strategic takeaway is that the market combines concentrated leadership with an active and sometimes divergent set of regional and application-specific players. For buyers, this means qualification strategy, dual-sourcing design, and supplier evaluation must be handled with care. For investors and competitors, it means that capacity announcements, grade capabilities, and regional supply posture can shift bargaining dynamics and availability patterns more quickly than broad market averages suggest.
Industry Dynamics: Supply Security, Material Controls, and Capacity Response
One of the most consequential features of the current market environment is the interaction between raw-material policy and production capacity. Tungsten hexafluoride does not exist in a vacuum; its supply chain is affected by the accessibility of tungsten feedstocks and by the regulatory frameworks that govern their movement. Recent developments have highlighted how quickly material controls can reshape procurement conditions for downstream producers.
Worldwide Inorganic Fluoride Market
China introduced an export licensing system for strategic minerals, including tungsten, in early 2025. This measure affected raw-material procurement pathways for tungsten hexafluoride producers in Japan and contributed to output constraints in the second half of 2026. Around the same timeframe, China’s Ministry of Commerce reinforced export controls on tungsten-related items to Japan and placed tighter oversight on the flow of tungsten products. Taken together, these measures have illustrated how policy can alter the input side of the supply chain with direct consequences for availability, cost structures, and planning confidence.
The impact of such controls is amplified by the role played by Japanese suppliers in the global supply base. With Japanese sources accounting for a meaningful share of global supply, restrictions on raw-material procurement have prompted preparation for production adjustments and have introduced a new layer of uncertainty into sourcing plans. For semiconductor and industrial buyers alike, this is a reminder that even a market with strong overall demand can experience localized disruption when upstream material access is constrained.
Capacity expansion is the market’s structural answer to that uncertainty, but capacity decisions are rarely instantaneous. The planned addition of new production capacity in 2027 reflects a medium-term response to demand growth and supply pressure. This is exactly the kind of dynamic that makes forward-looking research valuable: it helps organizations distinguish between temporary interruptions and more durable shifts in supply geography, grade availability, and competitive balance.
Moreover, these dynamics interact with broader procurement themes such as regionalization, qualification lead times, and the increasing sensitivity of advanced manufacturing to supply resilience. In that environment, the ability to anticipate where supply may tighten, which grades may become more contested, and how competitors are adjusting their sourcing strategies can create meaningful advantages in negotiation timing, inventory planning, and supplier diversification.
What the Research Delivers: Practical Intelligence for Decision-Making
A strong market study is not defined by the size of its forecast alone. It is defined by whether the findings can be used. This research is structured to serve as a practical analytical toolkit rather than a static overview. It provides a connected view of historical performance, forward projections, segmentation patterns, competitive positioning, and the external forces currently reshaping the market.
Inside the full report, readers can expect a detailed examination of market sizing and growth architecture, with context that links the historical baseline to the forecast trajectory and explains the logic behind the projected expansion path. The segmentation analysis goes beyond high-level splits to show how regional, application, and grade differences influence demand behavior, procurement complexity, and strategic exposure. This is especially useful for organizations that need to evaluate where their own exposure sits within the broader market structure and whether that exposure is concentrated, diversified, or shifting.
The competitive assessment provides a working map of the supply base. It situates major electronic-gas participants alongside industrial suppliers and regional producers, enabling a more nuanced reading of concentration, capability, and strategic intent. That matters because supplier relationships in this market are not interchangeable. Qualification requirements, grade capabilities, geographic reach, and service expectations can differ substantially, and the report framework is designed to help decision-makers evaluate those differences with greater precision.
The report also integrates the market dynamics that are shaping near-term behavior. Supply-side developments, regulatory actions, capacity expansion plans, and raw-material policy signals are analyzed not as isolated news items, but as interconnected forces that influence availability, pricing posture, and sourcing risk. By placing these dynamics inside a longer forecast horizon, the research helps users separate short-term disruption from structural realignment.
For strategy teams, this translates into a more reliable basis for scenario planning. For procurement organizations, it supports smarter supplier evaluation and sourcing architecture. For investors and corporate development teams, it offers a clearer picture of where growth is accumulating and what competitive conditions are likely to shape profitability and access. In each case, the objective is the same: to make the market legible well enough for confident action.
Why 2026 Is a Decision-Making Inflection Year
The current environment places a premium on anticipation. Demand is expanding, capacity is being added, and material-flow controls are altering procurement conditions in ways that can affect multiple quarters of planning. In a market like this, information that arrives too late can become a constraint rather than an advantage.
2026 represents an inflection point because several forces are converging at once. Forecast momentum suggests continued growth into the next phase of the cycle. Competitive dynamics reflect both concentration and regional diversification, which means sourcing strategy and supplier evaluation require careful judgment. At the same time, raw-material policy and capacity response are reshaping the practical terms of availability and continuity. Organizations that understand how these forces interact will be better positioned to make sourcing, investment, and risk-management decisions with foresight rather than hindsight.
This is the strategic value of the full research: it gives leadership a structured way to interpret a market that is growing, concentrating, and simultaneously being reshaped by policy and capacity decisions. The macro direction provides the context; the segmentation, competitor mapping, and dynamic analysis provide the operational detail needed to act on that context.
How to Use This Intelligence
The most effective use of this research begins with a clear strategic question. For procurement leaders, the relevant question may be how to structure supplier qualification, dual sourcing, and grade selection in a way that balances cost, continuity, and specification requirements. For corporate strategists, the question may be how regional demand trends and supply-side developments affect long-term sourcing geography and capacity exposure. For investors and market entrants, the question may be where growth is most durable and which competitive conditions will determine access and margin opportunity.
Whatever the starting point, the research is designed to support decision-making at the level where it matters most: the intersection of market structure, competitive behavior, and external dynamics. By combining historical grounding, a forward outlook, and a detailed breakdown of the forces shaping supply and demand, it provides a platform for more informed planning and more confident strategic choices.
Tungsten Hexafluoride Market
Next Steps
The figures, segmentation breakdowns, competitor profiles, and dynamic analyses summarized here are intended to convey the direction and analytical depth of the full study. They establish the strategic frame; the complete report provides the operational detail, contextual interpretation, and scenario-ready structure needed to put that frame to work. For organizations operating in or adjacent to the tungsten hexafluoride market, the value lies not only in understanding where the market is going, but in understanding how to position for it before the next phase of growth, constraint, and competition fully unfolds.
For detailed analysis of this topic, please visit the official page: Tungsten Hexafluoride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hazardous Location Lighting Market Hits $531.56M in 2025, Booms 4.88% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Lighting in Hostile Environments: A 2026 Decision-Making Framework
The global infrastructure landscape is undergoing a period of intense recalibration. As industries expand into more remote and hazardous operational theaters, the demand for reliable, compliant, and energy-efficient illumination has become a critical boardroom priority. Our latest research release, the Hazardous Location Lighting Market report, provides a comprehensive roadmap for navigating this complex sector between 2026 and 2032. This analysis is not merely a collection of statistics; it is a strategic instrument designed to help stakeholders align capital allocation with safety mandates and technological shifts.
Hazardous Location Lighting Market
For decision-makers operating in heavy industry, energy, or infrastructure development, understanding the trajectory of hazardous location lighting is essential. The market has demonstrated resilience and steady growth over the past five years, recovering from global supply chain disruptions to establish a robust upward trend. In 2020, the market valuation stood at approximately $418.88 million, growing to $531.56 million by 2025. This historical performance underscores the inelastic demand for specialized lighting solutions that ensure operational continuity in high-risk zones. The forecast period projects this momentum to continue, with revenue expected to reach $558.27 million in 2026 and climb toward $741.3 million by 2032. This growth trajectory, reflecting a compound annual growth rate of 4.88 percent, signals a mature yet expanding market where strategic positioning can yield significant long-term returns. However, these aggregate figures only tell part of the story. The real value lies in understanding the drivers behind these numbers and how they intersect with regulatory changes and technological advancements.
Market Dynamics and Regulatory Pressures
The hazardous location lighting sector is defined by its stringent compliance requirements. Unlike general industrial lighting, products designed for explosive atmospheres must meet rigorous safety standards to prevent ignition sources. The regulatory environment is tightening, creating both barriers to entry and opportunities for compliant innovators. A significant development shaping the 2026 landscape is the introduction of new product model certification requirements under NEC 2026. This update mandates specific model-level IIC gas group approvals for explosion-proof LED lights, moving beyond broader family ratings. For procurement managers and engineering teams, this means that legacy approvals may no longer suffice, necessitating a review of current inventory and future procurement strategies to ensure full compliance.
Furthermore, the technical benchmarks for safety and efficiency are being raised. The DesignLights Consortium finalized SSL V6.0 technical requirements for hazardous location lighting in November 2025, mandating safety testing by OSHA NRTL or equivalent bodies. This standard emphasizes the importance of verified safety testing alongside performance metrics. Companies that have already aligned their product lines with these emerging standards are better positioned to capture market share, while those lagging risk exclusion from major supply contracts. These regulatory shifts are not just compliance hurdles; they are market segmentation tools that favor established players with robust certification portfolios. Our report dives deep into how these regulations impact different regions and product categories, helping you anticipate compliance costs and timelines.
On the material side, the construction of explosion-proof lighting fixtures relies on heavy-duty materials such as stainless steel, aluminum, or glass-reinforced polyester for enclosures and components. The availability and pricing of these raw materials can influence manufacturing costs and final product pricing. As supply chains stabilize, manufacturers are optimizing material usage to balance durability with cost efficiency. Understanding the interplay between material costs and regulatory requirements is crucial for forecasting margin pressures and pricing strategies in the coming years.
Technological Shifts and Application Diversity
The transition from traditional lighting technologies to advanced LED solutions is a dominant theme in this market. While legacy technologies such as incandescent, fluorescent, and high pressure sodium fixtures still hold presence in specific niches, LED has become the primary driver of growth and innovation. LED luminaires offer superior energy efficiency, reduced maintenance requirements, and longer lifespans, which are critical advantages in hazardous environments where access for maintenance can be dangerous and costly. The shift is evident across various applications, including oil and gas, mining and steel, railway, power and energy, and military and public safety sectors.
Each application segment presents unique challenges and lighting requirements. For instance, the oil and gas sector demands robust solutions capable of withstanding explosive gases and harsh environmental conditions, often requiring Zone 1/2 or Division 1/2 certifications. Mining and steel industries require lighting that can endure dust, heat, and physical impact. Railway and power sectors have specific visibility and reliability standards. Military and public safety applications often require portability and extreme durability. Our analysis explores how different lighting types are suiting these diverse needs, highlighting where LED adoption is accelerating and where traditional technologies remain relevant due to specific operational constraints. We examine the nuances of these applications without oversimplifying, providing a clear view of where demand is concentrated and how it is evolving.
Recent industry exhibitions highlight the pace of innovation. For example, Dialight Corporation exhibited ATEX and IECEx-certified LED lighting solutions, including ProSite LED Floodlights and SafeSite high bay luminaires, at Hazardex Live 2026 in February. Such events demonstrate the industry's focus on showcasing certified, high-performance products that meet the latest safety standards. The presence of major manufacturers at these venues underscores the competitiveness of the market and the importance of continuous product development to maintain technological leadership. By analyzing these trends, our report helps you identify which technologies are gaining traction and which vendors are leading the innovation curve.
Competitive Landscape and Key Players
The market is characterized by a competitive landscape where consolidation and specialization are key strategies. The top three companies hold a combined market concentration of 45.0 percent, while the top five control 55.0 percent. This indicates a moderately concentrated market with room for niche players but dominated by large conglomerates with extensive resources and global reach. Several key companies define the current competitive dynamics, each bringing distinct strengths to the hazardous location lighting sector.
- Eaton Corporation plc , headquartered in Dublin, Ireland, is recognized as a leader in the Crouse-Hinds series LED luminaires. Their HPL and HPLN series are specifically engineered for Zone 1/2 and Zone 21/22 hazardous environments, featuring global certifications and energy-efficient designs. Eaton's strength lies in its comprehensive portfolio and global distribution network, making it a go-to partner for multinational projects requiring standardized compliance.
- Hubbell Incorporated , based in Stamford, Connecticut, USA, produces the Killark VML-X series of high and low bay LED fixtures. These products are certified for Class 1 Div 2 and Zone 2 hazardous locations, catering to industrial settings where safety and performance are paramount. Hubbell's focus on durable, high-bay solutions makes it a strong contender in heavy industrial applications.
- Dialight Corporation , located in New Jersey, USA, provides ProSite LED floodlights and SafeSite high bay luminaires with ATEX and IECEx certifications. Their recent participation in Hazardex Live 2026 highlights their commitment to showcasing advanced solutions for industrial hazardous areas. Dialight's specialization in LED technology for harsh environments positions them as an innovator in the space.
- Emerson Electric Co. , through its Appleton Group in St. Louis, Missouri, offers Areamaster Connect LED luminaires and Linmaster series for Class I Division 2 hazardous locations. Emerson emphasizes energy savings of up to 80 percent with their solutions, appealing to operators focused on reducing total cost of ownership while maintaining safety standards. Their connected lighting options also align with Industry 4.0 trends.
- Signify Holding N.V. , headquartered in Eindhoven, Netherlands, manufactures industrial and hazardous area LED lighting solutions, including long-life fixtures designed for harsh environments. Signify's strong brand presence in lighting and focus on sustainability and longevity make it a significant player, particularly in regions with strict energy efficiency mandates.
These players are not just competing on product features; they are competing on certification breadth, global service support, and technological integration. Recent developments, such as Dialight's exhibition of certified solutions, reflect the ongoing race to meet evolving standards and customer expectations. Our report provides a detailed competitive analysis, examining market share dynamics, product strategies, and the strategic moves these companies are making to solidify their positions. We analyze how their offerings map to different regulatory zones and application needs, giving you a clear picture of the competitive field.
Worldwide Helideck Explosion Proof Light Market
Strategic Implications for 2026 and Beyond
For stakeholders planning their 2026 strategies, the hazardous location lighting market presents several actionable insights. First, the tightening regulatory environment means that compliance is no longer optional; it is a competitive differentiator. Procurement teams must verify that suppliers meet the latest NEC 2026 and DesignLights Consortium requirements to avoid project delays or safety liabilities. Second, the shift toward LED technology is accelerating, driven by energy savings and operational reliability. Investment in LED infrastructure in hazardous zones can yield significant long-term savings and reduce maintenance risks. Third, the competitive landscape favors vendors with global certifications and robust service networks. Partnerships with established players like Eaton, Hubbell, Dialight, Emerson, or Signify can provide access to proven technologies and localized support.
Our full report goes beyond these high-level observations to provide granular data on regional demand patterns, type-specific growth rates, and application-level analysis. We break down the market forces driving growth in different areas and identify which segments are poised for expansion. The detailed segmentation analysis allows you to pinpoint opportunities aligned with your specific business interests, whether you are looking at regional markets, product types, or end-use applications. You will gain insights into pricing trends, technology adoption curves, and the impact of raw material costs on the supply chain. We also explore the implications of market concentration, helping you understand the balance of power among key suppliers and the potential for new entrants.
The data spans the historical period from 2020 to 2025 and provides a detailed forecast through 2032. This longitudinal view enables trend analysis and scenario planning. You can see how the market evolved from the pandemic era through recovery and into the current growth phase, and how it is projected to mature. Such context is invaluable for long-term capital planning and risk assessment. By accessing the complete intelligence, you can move from reactive compliance to proactive strategic positioning.
In conclusion, the Hazardous Location Lighting Market research report serves as an essential resource for navigating the complexities of this vital industry. With rigorous data, expert analysis, and a focus on strategic decision-making, it empowers you to make informed choices that drive safety, efficiency, and growth. To access the full depth of our analysis and secure the intelligence needed for your 2026 planning, we invite you to explore the complete report. The details that will shape your strategy are waiting to be uncovered.
For detailed analysis of this topic, please visit the official page: Hazardous Location Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vehicle Telematics Market Hits $93.61B in 2025, Driven by 8.7% CAGR to $167.85B by 2032
By PW Consulting, 2026-09-16
Unlocking the Road Ahead: Strategic Intelligence for the 2026 Vehicle Telematics Landscape
The global automotive ecosystem is undergoing a profound transformation, driven by connectivity, data ubiquity, and an escalating demand for operational efficiency. At the center of this shift lies vehicle telematics, a technology once relegated to simple tracking but now serving as the central nervous system of modern mobility, fleet management, and insurance underwriting. As enterprises navigate the complexities of 2026, understanding the trajectory of this market is not merely an advantage; it is a strategic imperative.
Our latest comprehensive market research delves into the multifaceted dynamics of the vehicle telematics industry, offering a granular view of where value is being created, how competitive forces are aligning, and what regulatory headwinds lie on the horizon. This article serves as a strategic preview of the full report, highlighting the macroscopic trends and qualitative shifts that will define decision-making for the remainder of the decade. For senior leadership teams, the insights contained within this study provide the necessary framework to allocate capital, mitigate risk, and identify high-growth vectors in a rapidly consolidating landscape.
The Trajectory of Growth: A Macro View
The momentum behind vehicle telematics is undeniable. Following a robust historical performance from 2020 through 2025, the market has demonstrated resilience against supply chain disruptions and economic volatility. The total revenue generated across the sector has climbed steadily, reflecting an increasing integration of telematics hardware and software into both legacy and next-generation vehicle platforms. This growth is not accidental; it is the result of a structural shift where connectivity is no longer a premium feature but a baseline expectation for commercial and consumer vehicles alike.
Vehicle Telematics Market
Looking forward, the forecast period from 2026 to 2032 suggests a continued expansion trajectory. Market projections indicate that the industry is expected to advance toward a valuation exceeding 167 billion USD by the end of the forecast window. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.7 percent, signaling a healthy, sustained demand curve. Such growth rates are characteristic of an industry moving past its early adopter phase and entering a period of broad-scale integration and maturation.
This macroscopic growth narrative is supported by consistent year-over-year revenue increases. The baseline established in 2025 at approximately 93.61 billion USD serves as the springboard for the estimated 101.46 billion USD mark expected in 2026. As organizations plan their strategic roadmaps, aligning internal targets with these external market signals is crucial. The data suggests that the window for capturing market share remains open, but it is narrowing as technology standards converge and barriers to entry evolve.
Navigating Segmentation and Technological Shifts
While the overall numbers tell a story of growth, the composition of that growth reveals where the strategic opportunities lie. The market is characterized by a diverse array of solution types, ranging from embedded systems directly integrated into vehicle manufacturing to tethered and integrated aftermarket solutions. The prevalence of embedded technologies suggests a transition toward seamless, factory-installed connectivity that leverages OEM partnerships. This shift reduces installation friction and enhances data reliability, aligning with the broader industry move toward software-defined vehicles.
OBD Telematics Market
Application-wise, the demand drivers are multifaceted. Safety and security remain paramount, reflecting the industry's commitment to reducing accidents and enhancing asset protection. Meanwhile, fleet and asset management applications continue to drive significant volume, as logistics and transportation companies seek to optimize routes, monitor driver behavior, and reduce total cost of ownership. Beyond these core verticals, insurance telematics is reshaping risk assessment models, allowing for more granular pricing based on actual driving data rather than demographic proxies. Information, navigation, and infotainment systems further round out the ecosystem, enhancing the user experience and creating additional touchpoints for data monetization.
It is within these segments that the real strategic nuance exists. Organizations must understand not just the size of each segment, but the velocity of adoption and the specific pain points each application addresses. Our full report dissects these areas to identify which sub-sectors are poised for acceleration and which may face saturation earlier than anticipated.
Competitive Dynamics and the Path to Consolidation
The competitive landscape of the vehicle telematics market is both crowded and intensely competitive. A select group of key players commands a significant portion of the market share, indicating a trend toward concentration among established vendors with robust technology stacks and global reach. The top three players alone account for over half of the market share, while the top five extend their influence to cover approximately seventy percent of the total market. This level of concentration suggests that scale, technological differentiation, and ecosystem partnerships are becoming increasingly critical differentiators.
Leading the charge are companies that have expanded beyond simple tracking to offer holistic platforms. Geotab, headquartered in Mississauga, Canada, continues to set the pace with its comprehensive vehicle telematics platform, integrating GO devices, OEM-embedded solutions, and AI analytics capabilities through its Geotab Ace initiative. Their focus on supporting mixed fleets and electric vehicle data positions them well for the transition to electrification. Similarly, Samsara in San Francisco has built a formidable connected telematics platform that unifies GPS, driver safety tools, and diagnostics into a cohesive workflow for fleet visibility and risk management.
The competition is further heated by innovative entrants and established players pivoting strategies. Motive, also based in San Francisco, differentiates itself by integrating video signals with vehicle data, enabling more effective driver coaching and asset monitoring. Verizon Connect and Teletrac Navman provide robust equivalents with a focus on real-time GPS, maintenance alerts, and OEM integration strategies that bridge the gap between factory-fitted hardware and cloud analytics. Meanwhile, companies like Trimble and Omnitracs emphasize diagnostics, predictive maintenance, and route optimization, catering to the operational efficiency needs of heavy and commercial fleets.
Recent developments underscore the pace of innovation. In early 2026, LG Electronics unveiled a next-generation smart telematics solution that integrates the Telematics Control Unit and antenna into a single module, marking their first participation at MWC Barcelona and signaling a push toward design efficiency and enhanced connectivity. Earlier in 2025, Teletrac Navman launched an OEM Telematics integration for their TN360 platform, allowing seamless data access from factory-fitted hardware without aftermarket installation. These moves highlight the industry's focus on hardware integration and reducing installation complexity. Furthermore, strategic alliances are reshaping the value chain; for instance, Cambridge Mobile Telematics announced a partnership with TransUnion to leverage portable consumer driving scores, reinforcing the growing synergy between telematics data and broader financial and insurance ecosystems.
Regulatory Tailwinds and Headwinds
No discussion of vehicle telematics strategy in 2026 would be complete without addressing the regulatory environment. The industry is operating within a complex web of compliance requirements that vary significantly by geography. In the United States, federal rules now require affirmative certification for information and communications technology supply chain security in connected vehicles and telematics systems. This mandate aims to enhance resilience but imposes additional due diligence requirements on manufacturers and integrators. Additionally, the US International Trade Commission has extended its investigation into certain vehicle telematics and video-based safety systems, creating a period of regulatory uncertainty that organizations must monitor closely.
Across the Atlantic, the European Union has implemented stringent mandates affecting heavy vehicles. The second-generation smart tachograph V2 became mandatory for vehicles over 3.5 tonnes, with strict timelines for adoption and migration of first-generation units. The EU General Safety Regulation further mandates commercial vehicle telematics requirements, and the Data Act, effective from 2025, grants users access to raw vehicle data. This shift empowers end-users but challenges traditional data monopolies held by OEMs and platform providers. In North America, state-level legislation is also evolving; for example, North Carolina now requires insurer notice and consent before using vehicle telematics data, signaling a broader trend toward consumer privacy and data sovereignty.
For enterprises, these regulations are not just compliance hurdles but strategic variables. They influence product design, data handling protocols, and international expansion strategies. Our report provides a detailed mapping of these regulatory landscapes to help organizations anticipate compliance costs and leverage regulatory standards as competitive moats.
Strategic Imperatives for 2026 and Beyond
As the market moves toward 2032, the organizations that will thrive are those that can synthesize these various threads into a coherent strategy. The convergence of AI, video analytics, and embedded connectivity is creating new value propositions that go beyond basic tracking. Companies like Powerfleet and Geosavi are pushing the boundaries of video-based telematics and AIoT platforms, integrating SaaS solutions that offer deeper operational insights. Teltonika and Linxup are focusing on hardware durability and AI-enabled safety features, such as dash cameras for distracted driving detection.
For strategic planners and investors, the key questions revolve around where to place bets in this ecosystem. Should the focus be on the hardware layer, the software analytics layer, or the data marketplace? How will OEM integration strategies evolve as manufacturers gain more control over vehicle data? What is the impact of insurance telematics on consumer behavior and fleet procurement? Our full market research addresses these questions with detailed segmentation analysis, competitive benchmarking, and scenario planning.
The vehicle telematics market is at an inflection point. The growth rates forecast suggest a maturing industry with significant room for innovation, while the competitive and regulatory dynamics indicate that passive participation is no longer viable. Organizations need access to precise, actionable intelligence to navigate this terrain effectively. The full report provides the depth, data, and strategic context required to turn market complexity into competitive advantage. We invite you to explore the complete study to gain the insights necessary for informed decision-making in this critical sector.
For detailed analysis of this topic, please visit the official page: Vehicle Telematics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Frozen Pizza Market Hits $21.5B in 2025, Projected to Reach $34.4B by 2032
By PW Consulting, 2026-09-16
Navigating the Frozen Pizza Landscape: A 2026 Strategic Imperative
The global frozen pizza market stands at a critical inflection point. As consumer habits shift, supply chains face volatility, and regulatory frameworks tighten, understanding the trajectory of this staple convenience food category is no longer optional for executives—it is essential. Our latest comprehensive market research report provides a detailed roadmap of the Frozen Pizza Market, offering the granular intelligence required to navigate the complexities of the 2026 economic landscape and beyond.
This article serves as a strategic overview of the key dynamics shaping the industry, highlighting the macroeconomic forces and competitive pressures identified in our full study. However, to truly capitalize on the opportunities ahead, decision-makers must engage with the complete dataset. The following insights outline the scope of our analysis and demonstrate why this report is an indispensable tool for strategic planning in 2026.
Macro Demand Curve: Validation of Growth from 2020 to 2032
The historical performance of the frozen pizza sector demonstrates remarkable resilience and steady expansion. Between 2020 and 2025, the market navigated pandemic-induced consumption spikes, subsequent normalization, and inflationary pressures. This period established a robust baseline for future forecasting. According to our analysis, the global revenue reached approximately $21.5 billion in the base year of 2025, following a consistent upward trajectory from $16.3 billion in 2020.
Looking forward, the market is projected to sustain a healthy Compound Annual Growth Rate (CAGR) of 5.5 percent through the forecast period of 2026 to 2032. By the end of this forecast window, the market valuation is expected to approach $34.5 billion. This growth is not merely a function of population increase; it is driven by evolving convenience demands and product innovation that keeps frozen pizza relevant in a crowded quick-meal landscape.
- Base Year Strength: 2025 closed with significant momentum, setting the stage for double-digit absolute growth in the immediate term.
- Forecast Stability: The 2026 to 2032 projection accommodates potential economic fluctuations while maintaining a bullish outlook on core demand drivers.
- Valuation Thresholds: Crossing key revenue milestones in the late forecast period signals maturity and opportunity for premiumization.
While these top-line figures provide a high-level health check, our full report delves into the underlying volume and value drivers that vary significantly by product configuration and geographic deployment, details of which are reserved for subscribers seeking actionable intelligence.
Consumer Preferences and Product Architecture
The architecture of the frozen pizza market is defined by critical segmentation dimensions that dictate manufacturing strategies and retail placements. Consumer preferences are no longer monolithic; they are increasingly differentiated by dietary requirements and taste profiles. Our research dissects these preferences across key axes such as crust typology and topping composition, revealing where manufacturers are gaining traction and where saturation points are approaching.
On the crust front, the market exhibits clear leaders in terms of volume adoption, with thin crust varieties commanding a significant share of consumer attention. However, thick crust and stuffed crust options maintain loyal followings, particularly in specific retail channels and regional demographics. The strategic balance between these formats influences production line configuration and ingredient sourcing. Similarly, the topping segment analysis highlights the interplay between traditional meat-based options, vegetable-forward alternatives, and cheese-focused innovations.
The rise of specific dietary needs has also reshaped the competitive landscape. Demand for plant-based, gluten-free, and organic offerings is no longer a niche consideration but a core component of product portfolios for several major players. Understanding the revenue share and growth rate of these specific sub-segments is vital for capacity planning and marketing allocation. Our report quantifies these splits precisely, allowing stakeholders to identify which product configurations offer the highest margin potential in the current cost environment.
- Crust Dynamics: Analysis of Thin, Thick, Stuffed, and Other crust types relative to price points and regional taste profiles.
- Topping Trends: Evaluation of Vegetable, Meat, Cheese, and Other topping categories against nutritional trends and cost volatility.
- Dietary Innovation: Assessment of gluten-free and plant-based lines as demi-market drivers.
Competitive Landscape and Enterprise Strategies
The frozen pizza industry is characterized by a mix of global giants, regional specialists, and agile niche players. Market concentration metrics indicate a moderately consolidated environment, with the top three entities controlling a significant portion of total revenue and the top five firms commanding an even larger share. Understanding the strategic positioning of these key companies is crucial for assessing competitive threats and partnership opportunities.
Major branded producers continue to leverage extensive distribution networks and brand equity to maintain volume leadership. For instance, large-scale manufacturers focus on expanding their SKU counts to cover various price points and dietary needs. In June 2025, one such major brand introduced over 50 new frozen food SKUs, including gluten-free and plant-based varieties, signaling a strategy of diversification to capture convenience-driven consumers.
Conversely, specialized manufacturers are carving out sustainable niches through organic, plant-based, and gluten-free offerings. Companies like Amy's Kitchen Inc. and Daiya Foods Inc. exemplify the shift toward ethical and dietary-specific production, while others like Dr. Oetker and McCain Foods Ltd. balance branded products with private-label manufacturing services, adding flexibility to their revenue streams.
However, the operational landscape is not without risk. Recent events underscore the importance of supply chain integrity and safety protocols. In mid-2026, significant recalls highlighted vulnerabilities in production oversight. Champion Foods LLC voluntarily recalled certain batches of Motor City Pizza Co. 5 Cheese Bread due to potential Salmonella contamination, while Bakkavor recalled Basil Pesto and Mozzarella frozen pizzas distributed via HelloFresh due to possible metal fragments. These incidents serve as stark reminders of the operational risks inherent in food manufacturing and the reputational stakes involved.
Our full report provides detailed profiles on all major market participants, including Nestlé S.A., General Mills Inc., and Schwan Food Company, analyzing their recent developments, strategic moves, and potential vulnerabilities. This competitor intelligence is synthesized to help you benchmark your capabilities and identify gaps in the market.
Frozen Pizza Market
Raw Material Pressures and Macroeconomic Inputs
Profitability in the frozen pizza sector is heavily influenced by input cost volatility. In 2026, manufacturers are grappling with fluctuating prices for key agricultural commodities. According to data from the USDA Economic Research Service, farm-level wheat prices increased 1.9 percent from March 2026 to April 2026 and were 7.9 percent higher in April 2026 than in April 2025. This upward trend in grain costs directly impacts dough production and overall COGS.
Dairy costs also present a critical variable. The average weighted price for mozzarella cheese in SY 2026 is recorded at $1.8444 per kilogram. As cheese is a primary value driver and ingredient in most frozen pizza formulations, this pricing structure affects both premium and value-tier products differently. Managing these input costs requires sophisticated hedging strategies and supply chain negotiations, elements that are thoroughly examined in our procurement analysis section.
Furthermore, broader macroeconomic conditions, including labor costs and logistics expenses, continue to pressure margins. Companies that can optimize their production efficiency and negotiate favorable ingredient contracts will be better positioned to absorb these costs without eroding consumer affordability. Our report models these cost pressures against revenue growth scenarios to project net margin trends for the forecast period.
Regulatory Headwinds and Compliance Standards
Regulatory environments are becoming increasingly stringent, particularly regarding nutrition labeling and food safety. In May 2025, the FDA proposed a front-of-package nutrition labeling scheme requiring simplified labels for saturated fat, sodium, and added sugars on most packaged foods. This initiative aims to empower consumers with quicker nutritional insights but may necessitate packaging redesigns and reformulations for products that exceed specific thresholds.
Cross-border considerations are equally important. Canada implemented front-of-package nutrition symbols that became fully mandatory for packaged foods exceeding saturated fat, sugars, or sodium thresholds effective January 1, 2026. Additionally, prepared frozen foods labeling rules now require specific best-before usage and nutrition facts for categories including frozen fried foods, dumplings, rice products, and noodles effective April 1, 2026.
Frozen Potatoes Market
Compliance with these evolving regulations is not just a legal necessity but a competitive differentiator. Brands that proactively adapt their labeling and formulations can mitigate regulatory risk and enhance brand trust. Our report details the impact of these regulatory changes on market dynamics, offering a compliance roadmap for manufacturers operating in North America and globally.
Strategic Outlook and Recommendations for 2026
Navigating the frozen pizza market in 2026 requires a multi-faceted approach. Success depends on balancing cost management with product innovation, ensuring regulatory compliance while maintaining brand appeal, and addressing diverse consumer needs without diluting core value propositions. The market growth outlined in our forecast suggests that the pie is expanding, but capturing a larger slice requires precise execution.
Strategically, firms should consider the following focus areas derived from our analysis:
- Portfolio Optimization: Align product mix with the highest growth sub-segments identified in the segmentation analysis, particularly where dietary trends meet established taste preferences.
- Supply Chain Resilience: Mitigate raw material volatility through diversified sourcing and long-term contracts, especially for wheat and dairy ingredients.
- Regional Penetration: Leverage the strong performance in mature markets while identifying high-potential regions for expansion, understanding local taste and cost sensitivities.
- Risk Management: Implement rigorous quality control systems to prevent recalls and protect brand equity, learning from recent industry incidents.
Our comprehensive market research study provides the data backbone for these strategies. From detailed segmentation splits to company-specific profiles and regulatory impact assessments, the full report equips stakeholders with the tools needed to make informed decisions.
To access the complete analysis, including precise regional valuations, crust and topping revenue splits, and deep-dive competitor assessments, we invite you to secure your copy of the Frozen Pizza Market Report today. Don't navigate the future on assumptions—arm your strategy with definitive intelligence.
For detailed analysis of this topic, please visit the official page: Frozen Pizza Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Functional Sugar Market Hits $2.47B in 2025, Projected 6.2% CAGR to $3.81B by 2032
By PW Consulting, 2026-09-16
The Functional Sugar Market: Navigating the 2026 Growth Curve
The global landscape for functional sugars is undergoing a structural transformation. As consumer demand shifts steadily toward clean-label, low-calorie, and gut-health-supporting ingredients, manufacturers are recalibrating their portfolios to capture value in a high-growth segment. Our latest market research positions stakeholders to make informed decisions with a clear view of the macroeconomic trajectory and the competitive forces shaping the industry. Between 2020 and 2032, the market is projected to expand from 1.85 billion USD to 3.81 billion USD, reflecting a compound annual growth rate of 6.2 percent over the forecast period. This sustained expansion signals a durable shift rather than a transient trend, driven by regulatory approvals, supply chain maturation, and a broadening base of applications across food, beverage, and dietary supplement formats.
For executives evaluating capital allocation, product development pipelines, or market entry strategies in 2026, the window to act is narrowing. The pace of innovation among leading ingredient suppliers has accelerated, and the regulatory environment continues to evolve in ways that reward early movers with validated health claims and scalable production capabilities. This report distills those dynamics into a decision-ready framework, giving you the context needed to prioritize investments where demand signals are strongest and competitive pressure is most acute.
A Market on the Rise: Key Trajectory Signals for 2026
The historical record demonstrates a consistent upward climb. From 2020 through 2025, revenue grew each year, reaching 2.47 billion USD by 2025. Looking ahead, the forecast extends through 2032 and outlines a path that carries the total toward 3.81 billion USD. The progression is not uniform; it reflects a combination of volume growth, value-added formulations, and expanding geographic reach. By 2026, the market is expected to cross the 2.69 billion USD mark, establishing a new baseline for the decade ahead.
Several underlying drivers support this trajectory. First, the post-pandemic consumer emphasis on preventive health has elevated the role of gut microbiome support and metabolic stability as key purchase drivers. Functional sugars that deliver prebiotic benefits or moderate glycemic responses are increasingly embedded in everyday products, from breakfast cereals and snack bars to ready-to-drink beverages and capsule-based supplements. Second, manufacturing innovation has reduced the cost premium historically associated with specialized sweeteners, allowing brands to integrate functional sugars without sacrificing price competitiveness. Third, ingredient sourcing strategies are adapting to supply side realities; for example, EU sugar beet prices navigated a period of increase in the early 2020s before stabilizing in 2024 and softening during the first half of 2025, while USDA forecasts projected U.S. sugar production at a record 9.42 million short tons in the 2025/26 season. These supply factors influence cost structures and regional sourcing decisions, and they are examined in detail within the report to help procurement teams anticipate volatility.
Within this context, the buildup in capacity by major players is particularly noteworthy. Tate & Lyle expanded allulose production capacity by 35 percent in March 2025 to improve supply availability for low-calorie sweeteners, and Cargill has advanced fermentation-based functional sugar solutions that improve production efficiency for dietary supplement and food manufacturers. These moves signal confidence in sustained demand, but they also raise the bar for competitors and purchasers alike: access to premium functional sugars will increasingly depend on long-term partnerships and secured supply chains.
Rising from 1.85 Billion to 3.81 Billion: What the Growth Curve Means for Strategy
A market moving from 1.85 billion USD in 2020 to a projected 3.81 billion USD in 2032, at a CAGR of 6.2 percent, invites a straightforward question: where is the greatest value-creation potential concentrated, and how should organizations align their capabilities to capture it? The growth curve is not just a number; it is a signal of demand elasticity, category readiness, and regional maturity. As the base expands, differentiation becomes essential. The strongest performers are likely to be those that combine science-backed ingredient claims with consistent supply, regulatory compliance, and formulation flexibility.
Our analysis confirms that market leadership is fragmented rather than consolidated, a structural feature that creates room for niche positioning and targeted partnerships. The top three players collectively account for 34.5 percent of revenue, while the top five hold 49.2 percent. No single entity dominates, and the spacing between leading firms allows specialized suppliers to build durable presence in distinct applications or geographies. This dynamic is reinforced by the entry of regional and specialty manufacturers that bring formulation depth, localized sourcing, and proprietary processing methods. For brands evaluating suppliers, the implication is clear: supplier selection should weigh technical capability, claim substantiation, and capacity reliability alongside price.
The report frames these market-level signals in a way that supports scenario planning. Executives can use the trajectory data to model revenue ranges under different adoption timelines, assess the timing of product launches relative to regulatory milestones, and identify segments where the margin opportunity is widening fastest. Because the forecast spans multiple years, it also exposes inflection points where capacity additions or regulatory changes could alter competitive positioning, making now an ideal moment to review your roadmap against the data.
Competitive Landscape: How Tier-1 Innovators Are Defining the Next Wave
A resilient competitive field has emerged around functional sugars, with incumbents leveraging scale and specialists competing on formulation intelligence and claim support. The companies featured in this research represent a cross-section of strategies: some focus on core sweeteners with documented metabolic benefits, others emphasize fiber-based ingredients for digestive health, and several invest in sustainability as a differentiator. The report profiles each and compares their capabilities, recent moves, and positioning.
Tate & Lyle, headquartered in London, offers functional sugars including allulose and isomaltulose for blood sugar management and prebiotic benefits in dietary supplements and beverages. Its capacity expansion in allulose underscores a bet on consumer appetite for low-calorie, glycemic-friendly sweeteners. C.argill, based in Wayzata, provides fermentation-based functional sugar solutions with improved production efficiency for dietary supplement and food manufacturers, a route that can reduce cost and improve consistency. Ingredion, located in Westchester, launched a next-generation prebiotic sugar ingredient in January 2026 that improved digestive health performance by 24 percent for premium supplement formulations, an example of how formulation advances can accelerate adoption in higher-margin categories. ADM, in Chicago, supplies natural functional sugar ingredients to global beverage and food companies for North American operations, emphasizing broad reach and operational reliability. BENEO, in Karlsruhe, specializes in chicory root-derived functional carbohydrates and fibers for blood sugar management and sugar reduction, with regulatory recognition such as the FDA GRAS Notice 1242 for short-chain fructooligosaccharides issued in June 2025, which exempted specified uses from premarket approval.
On the plant-based and fiber side, Roquette Frères, in Lestrem, develops plant-based functional sugar and fiber ingredients for food, beverage, and supplement applications, and released its 2026 sustainable actions report in June 2026 highlighting biodiversity and nature initiatives in functional ingredient production. Tereos Group, in Origny-Sainte-Benoite, produces functional sugar solutions from beet and cane sources for sweetening and health-focused food products. Cosucra Groupe Warcoing, in Warcoing, extracts chicory root fibers such as PISANE™ as functional ingredients for sustainable nutrition and sugar alternatives. Nexira, in Rouen, supplies natural acacia and botanical extracts as functional ingredients for blood sugar control in supplements. In the low-calorie sweetener space, Samyang Corporation, in Seoul, manufactures allulose as a next-generation low-calorie functional sugar sweetener for beverages and snacks, while Matsutani Chemical Industry, in Itami, develops FIBERSOL® soluble dietary fiber and allulose for prebiotic and sugar-reduction applications.
Functional Chewing Gum Market
Across these players, three themes recur: diversification of sweetness and fiber platforms, investment in processing and capacity, and a sharper focus on validated health outcomes. The report maps these strategies to the segments and applications where they are most relevant, giving buyers a comparative lens to evaluate partnerships and procurement options with greater precision.
Functional Sugar Market
Segmentation Drivers: Ingredient Types, Application Breadth, and Regional Dispersion
The functional sugar market is not monolithic; it spans multiple ingredient types, application areas, and regional ecosystems, each with its own growth logic and competitive dynamics. The analysis segment the market by type, application, and region to surface where momentum is building and which combinations are likely to outperform.
By type, the market includes oligogaccharide, inulin, sugar alcohols, and other specialty categories. Oligosaccharides and inulin anchor the prebiotic narrative, while sugar alcohols and next-generation low-calorie sweeteners address glycemic management and calorie reduction. The "others" category captures emerging botanicals and fiber blends that continue to gain traction in premium formulations. The report examines each category substantively, without disclosing segment-level revenue shares, to help formulation teams match ingredient properties to functional goals and cost constraints.
By application, the breadth is broad and expanding. Food and beverage remain the largest usage base, where functional sugars are embedded in everyday products to deliver taste, texture, and health positioning. Dietary supplements constitute a significant and growing channel, where claims around digestive health and metabolic support are increasingly central to product identity. Pharmaceuticals and other applications contribute additional demand, often governed by stricter specifications and quality standards. The research outlines the differentiators across these applications, including regulatory requirements, formulation compatibility, and the strength of consumer demand signals, to guide category strategy and packaging decisions.
By region, the dispersion reflects differences in consumer preferences, regulatory frameworks, and supply infrastructure. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The report provides qualitative context on regional momentum drivers and sourcing patterns, again withholding exact split percentages, so that readers can calibrate their geographic focus to the most relevant growth engines without pre-judging local execution challenges.
Two regulatory developments frame part of this regional picture. EFSA extended the use of isomalto-oligosaccharide as a novel food under Regulation (EU) 2015/2283, a step that broadens the application canvas for certain prebiotic ingredients in Europe. In parallel, FDA granted GRAS notice 1242 for short-chain fructooligosaccharides from BENEO for use in certain foods, exempting those specified uses from premarket approval and simplifying formulation pathways. Together, these moves illustrate how regulatory milestones can unlock new product possibilities and influence regional prioritization.
Formulation and Sourcing Realities: What Operational Teams Need to Know
Turning market opportunity into commercial reality requires attention to the mechanics of formulation and sourcing. Functional sugars must perform not only as health-forward ingredients but also as contributors to taste, mouthfeel, stability, and shelf life. Each category presents trade-offs. Oreosaccharide and inulin can deliver prebiotic functionality and fiber content, but their behavior in different matrices varies; sugar alcohols offer sweetness profiles and glycemic moderation, yet their inclusion levels must be managed carefully; allulose and related low-calorie sweeteners can replicate sugar-like taste with lower caloric impact, but supply availability and cost remain important considerations for high-volume programs.
From a sourcing standpoint, the ability to secure consistent quality and volume is increasingly tied to supplier investment in processing efficiency and capacity. Cargill's fermentation-based solutions, for instance, reflect a broader industry shift toward more efficient production routes that can support scale without sacrificing quality. Meanwhile, sustainability is moving from a narrative element to an operational one: Roquette's 2026 sustainable actions report underscores biodiversity and nature initiatives as part of functional ingredient production, a signal that procurement teams may increasingly evaluate suppliers on environmental performance alongside cost and reliability. The report details the operational considerations relevant to each major ingredient route and supplier type, helping teams weigh formulation goals against supply continuity and total cost of ownership.
Regulatory alignment is another operational thread. The EU sugar beet price trajectory, the record U.S. sugar production forecast, and the evolving status of novel food approvals all influence cost structures and formulation options. By synthesizing these variables, the research equips teams to anticipate changes and adjust sourcing strategies before they become reactive.
Turn Insights into 2026 Decisions: The Full Intelligence Awaits
The functional sugar market is positioned for a sustained run of growth, with a clear upward trajectory, an active competitive field, and a regulatory environment that continues to open new possibilities. The report translates these macro trends into actionable intelligence, covering market sizing across historical and forecast years, segmentation by type, application, and region, competitive profiling of leading and emerging players, and the latest industry developments that could affect sourcing, formulation, and go-to-market timing in 2026 and beyond. It is designed to support multiple use cases: portfolio planning, supplier selection, market entry evaluation, pricing strategy, and long-range scenario modeling.
Because the decision space is competitive and time-sensitive, partial visibility carries risk. The report delivers the full segmentation detail, including regional breakdowns, application splits, and type-level analysis, alongside company comparisons and regulatory context, so that your team can act with precision. The complete intelligence is available on the source page; accessing it will give you the granular data needed to benchmark opportunities, validate assumptions, and set priorities for the year ahead.
Now is the moment to align your strategy with the data. As the market moves toward the 2026 baseline and beyond, organizations that combine strong formulation insight with reliable supply and clear health claims will be best placed to capture value. The research provides the foundation; your next step is to secure the full intelligence and translate it into concrete actions.
For detailed analysis of this topic, please visit the official page: Functional Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


