



PW Consulting: FLIM Market Hits $332.3M in 2025, Projected to Reach $490.2M by 2032 at 5.91% CAGR
By PW Consulting, 2026-09-07
Unlocking the Future of Microscopic Imaging: Strategic Insights into the Fluorescence Lifetime Imaging Microscopy Market (2026–2032)
As the boundaries between life sciences, industrial diagnostics, and precision medicine continue to blur, Fluorescence Lifetime Imaging Microscopy (FLIM) has emerged as a pivotal technology for next-generation cellular analysis. This market intelligence report delivers a comprehensive, data-driven assessment of the global FLIM landscape, designed to empower executive leadership, R&D directors, and strategic planners with the foresight required to navigate the 2026–2032 investment cycle. Drawing on historical performance from 2020 through 2025 and leveraging forward-looking projections through 2032, the study transforms raw market metrics into actionable strategic frameworks. Readers will find not only a rigorous sizing and growth trajectory but also a deep exploration of technological inflection points, competitive positioning, regulatory tailwinds, and the practical deployment considerations that will define commercial success in the coming decade.
Water Pump Bearing Seal Ring Market
Market Trajectory and Structural Evolution
The FLIM market has demonstrated consistent, compounding growth over the past five years, establishing a robust foundation for accelerated expansion in the forecast horizon. Valued at approximately 252.5 million USD in 2020, the segment climbed steadily to 272.65 million USD in 2021 and reached 332.3 million USD by 2025. This trajectory reflects sustained adoption across research laboratories, clinical development pipelines, and specialized industrial applications. The momentum carries firmly into the initial forecast year of 2026, with projected revenues expanding to 344.01 million USD, and continues its upward curve through 2032, where the market is anticipated to surpass 490 million USD. Driving this trajectory is a forecasted compound annual growth rate of 5.91 percent, a figure that captures both organic adoption curves and the compounding effect of technological modernization across existing user bases.
Construction Building Robot Market
This growth narrative is underpinned by several converging forces. FLIM is rapidly becoming a transformative tool in neurology, enabling the visualization of molecular and metabolic information that supports surgical tumor margin detection and personalized medicine approaches. Simultaneously, regulatory frameworks are evolving to accommodate advanced imaging modalities, though reimbursement pathways and biomarker validation will remain critical gating factors for widespread clinical integration. Modifications for intraoperative use, including portability, remote fiber optic access to patients, fiber-probe sterilization, and medical safety, have already begun to reshape application boundaries, signaling that the market is transitioning from a predominantly research-focused instrument category toward a more diversified, clinically adjacent ecosystem.
Double Circuit Circulating Ball Hydraulic Steering Gear Market
Core Technology Segmentation and Application Drivers
The structural composition of the FLIM market is defined by distinct technological architectures and application verticals, each carrying unique value propositions, adoption timelines, and strategic implications. By method of signal acquisition, the market is anchored by time-domain techniques, which represent the dominant technological approach and continue to benefit from established photon-counting infrastructure and mature laser scanning integrations. Frequency-domain methodologies hold a substantial secondary presence, particularly where high-speed acquisition and specialized modulation architectures align with advanced developmental workflows. Complementary approaches and emerging system variants round out the technical landscape, catering to niche requirements where miniaturization, cost-efficiency, or hybrid operational profiles take precedence.
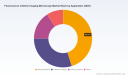
From an application perspective, the market spans a broad spectrum of end-use environments. Biology and medical research constitutes the largest demand center, reflecting the fundamental reliance of cellular imaging, metabolic tracking, and therapeutic development on lifetime-resolved fluorescence data. Academic institutes form a substantial secondary pillar, sustaining foundational research, next-generation instrumentation development, and training pipelines that feed into both commercial and clinical ecosystems. The chemical industry represents a meaningful specialized segment, leveraging FLIM for material characterization, molecular interaction studies, and quality assurance workflows. Additional application areas continue to expand the addressable opportunity, capturing demand from specialized industrial diagnostics and cross-disciplinary analytical programs. While the precise allocation of revenue across these segments requires deeper examination, the directional takeaway is clear: FLIM demand is no longer monolithic. It is bifurcating into highly specialized, application-optimized deployments that reward vendors capable of delivering tailored system architectures, robust software ecosystems, and domain-specific workflow integration.
Regional Distribution and Market Concentration
Geographically, the FLIM market exhibits a mature, internationally distributed revenue base, with significant concentration across leading industrial and research economies. North America and Europe collectively anchor the majority of global demand, reflecting deep-established research infrastructure, strong procurement capacity for advanced microscopy platforms, and sustained funding across both public and private innovation channels. Asia Pacific continues to expand its share of the market, driven by accelerating life sciences investment, growing research institution capacity, and increasing integration of FLIM-compatible workflows in regional development pipelines. Latin America and the Middle East and Africa represent developing but strategically important markets, where growth is increasingly shaped by targeted procurement programs, collaborative research initiatives, and selective adoption of cost-efficient imaging configurations.
The competitive structure of the market reflects meaningful but not absolute concentration. The top three participants command a combined share of approximately 44.5 percent, while the top five collectively account for roughly 55.8 percent of overall revenue. This concentration profile suggests a market that is accessible to specialized disruptors and niche innovation leaders, even as established multinational players retain dominant positions through portfolio breadth, global service networks, and deep technical integration with leading microscopy platforms. Strategic positioning in this environment increasingly depends on the ability to differentiate through software-driven analysis capabilities, upgrade-path flexibility, application-specific validation support, and alignment with evolving regulatory and reimbursement expectations.
Competitive Landscape: Strategic Positioning of Leading Participants
The FLIM ecosystem is defined by a cohort of technically sophisticated participants, each anchoring their commercial strategy around complementary strengths ranging from instrument manufacturing and detector technology to optical component specialization and workflow-enabling consumables. Leica Microsystems, headquartered in Wetzlar, Germany, exemplifies the high-end confocal integration strategy with its STELLARIS 8 FALCON confocal microscope system featuring integrated FLIM capabilities designed for medical device and life science applications. Teledyne Princeton Instruments, based in Acton, Massachusetts, delivers FLIM-compatible scientific imaging systems and cameras that support both research programs and medical device development, positioning its hardware at the intersection of precision detection and scalable research infrastructure. Renishaw plc, operating from Gloucestershire, United Kingdom, provides FLIM solutions integrated with advanced microscopy platforms tailored for industrial and medical applications, reinforcing the cross-sector applicability of lifetime imaging.
The market also features a strong contingent of Berlin-based innovators specializing in modular and upgrade-oriented architectures. PicoQuant offers compact FLIM and FCS upgrade kits, along with laser scanning microscope upgrade solutions that allow existing installations to adopt lifetime imaging capabilities without full system replacement. Becker & Hickl GmbH complements this modular ecosystem with DCS-120 confocal and multiphoton FLIM systems, TCSPC/FLIM cards, and upgrade kits engineered for high-resolution imaging, emphasizing signal integrity and system adaptability. HORIBA, headquartered in Kyoto, Japan, has strengthened its positioning through the launch of the new InverTau platform for confocal FLIM and related imaging systems, a product introduction that signals continued investment in integrated software-hardware workflows for confocal lifetime analysis. Bruker, based in Billerica, Massachusetts, advances multiphoton imaging depth with its ULTIMA multiphoton microscope equipped with FLIM and PLIM modules for life science and medical applications, addressing demand for deeper tissue interrogation and multimodal imaging pipelines. ibidi GmbH, operating from Gräfelfing, Germany, supports the imaging workflow from a consumables and sample preparation angle, offering μ-Slide and polymer/glass coverslips optimized for FLIM imaging applications, illustrating how downstream workflow optimization plays an increasingly strategic role in adoption decisions.
Recent industry developments reinforce the pace of innovation. In mid-2024, HORIBA introduced the new InverTau platform, a dedicated environment for confocal FLIM that reflects broader industry momentum toward integrated analysis suites, streamlined data handling, and reproducible quantification pipelines. Such launches underscore an industry trend in which competitive advantage is increasingly derived not solely from optical hardware excellence, but from the reliability, usability, and interoperability of the complete imaging and analysis chain.
Regulatory, Reimbursement, and Clinical Translation Dynamics
While technology readiness and research demand remain powerful growth drivers, the trajectory of FLIM into broader clinical and commercial deployment will be shaped by regulatory validation and reimbursement architecture. The widespread clinical integration of fluorescence lifetime imaging microscopy hinges heavily on regulatory and reimbursement structures, making policy alignment, evidence generation, and health economic demonstration essential strategic considerations. Regulatory approval will also depend on the validation of FLIM-based biomarkers and the demonstration of clinical benefit in large, multicenter trials. These requirements translate directly into market behavior: adoption curves in medical device and intraoperative contexts will accelerate only when standardized validation frameworks, clinical-grade performance data, and clear reimbursement pathways converge.
At the same time, the practical requirements of translational use are already influencing product development. Modifications for intraoperative use, including portability, remote fiber optic access to patients, fiber-probe sterilization, and medical safety, illustrate how clinical deployment constraints are reshaping hardware design and operational workflows. For strategic planners, this means that the market is no longer purely an instrument procurement discussion. It is increasingly an ecosystem evaluation, encompassing validation support, workflow integration, service and training models, and the ability to generate evidence that satisfies both regulatory reviewers and healthcare reimbursement bodies.
Strategic Implications for 2026 Decision-Making
The period beginning in 2026 represents a decisive window for strategic positioning in the FLIM market. Organizations evaluating investment, procurement, partnership, or product development opportunities must look beyond headline sizing numbers and engage with the structural forces that will differentiate winners from laggards. Several strategic imperatives stand out.
Prioritize Application-Specific Value Demonstration
Generic imaging capability is no longer sufficient. Commercial and research buyers are evaluating FLIM solutions based on domain-specific outcomes, whether that means metabolic imaging fidelity in biology and medical workflows, reproducibility in academic research pipelines, or material characterization reliability in chemical industry applications. Vendors and adopters alike must articulate clear, application-anchored value propositions that connect lifetime imaging data to decision-quality outcomes.
Design for Modularity, Upgrade Pathways, and Workflow Integration
The presence of robust upgrade-kit and modular system options in the competitive landscape signals a market where total-cost-of-ownership considerations, installation flexibility, and the ability to expand functionality over time are critical purchasing criteria. Systems that allow existing microscope infrastructure to be extended with FLIM capability, or that integrate smoothly with downstream analysis software and consumables workflows, will continue to capture meaningful share among cost-conscious and operationally pragmatic buyers.
Align Development and Procurement with Regulatory and Reimbursement Realities
As clinical and intraoperative applications expand, strategic plans must account for biomarker validation requirements, multicenter trial dynamics, and reimbursement pathway uncertainty. For instrument manufacturers, this implies investing in clinical-grade documentation, safety optimization, and evidence-generation partnerships. For procurement and investment decision-makers, it means factoring regulatory readiness and health-economic positioning into technology adoption timelines rather than treating them as downstream administrative concerns.
Monitor Concentration Trends Without Overlooking Niche Innovation
With the top three participants holding a combined share near 44.5 percent and the top five near 55.8 percent, the market is concentrated enough to reward scale advantages in service, global reach, and portfolio depth, yet open enough to allow specialized players to capture high-value niches through detector innovation, software differentiation, and targeted application support. Strategic engagement should therefore evaluate both established platform ecosystems and emerging capability leaders, particularly where upgrade flexibility, portability, or specialized analysis pipelines align with specific end-use requirements.
What the Full Report Delivers
This executive overview provides a directional foundation, but the complete market research study offers the granular intelligence required to convert strategy into execution. The full report delivers detailed sizing and growth modeling across the 2020–2025 historical window and the 2026–2032 forecast horizon, including scenario-based projections that account for technology adoption variability, regional procurement dynamics, and application-driven demand shifts. The study breaks down technology-type and application-segment structures with precision, providing revenue allocations and growth trajectories that enable targeted go-to-market planning, portfolio prioritization, and competitive benchmarking. Regional analysis is presented in depth, allowing decision-makers to assess demand maturity, procurement behavior, and strategic entry considerations across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Beyond quantitative modeling, the report includes a comprehensive competitive profiling section that examines the strategic positioning, product architectures, recent development activity, and market-facing capabilities of leading participants, with emphasis on how each player's approach shapes procurement considerations and innovation pathways across different buyer segments. The study also integrates a detailed analysis of market dynamics, covering regulatory evolution, reimbursement considerations, intraoperative deployment requirements, and the expanding role of FLIM in neurology and personalized medicine contexts. Practical guidance is provided on adoption barriers, validation expectations, workflow optimization, and the strategic implications of modular versus integrated system architectures.
For executives, commercial leaders, and research operations planners, the full report functions as both an analytical reference and a decision-support toolkit. It identifies where demand is most likely to accelerate, which technology and application intersections offer the most defensible growth positions, and how competitive intensity is likely to evolve as regulatory clarity and clinical translation pathways mature. Readers seeking segment-level revenue detail, regional demand breakdowns, and actionable competitive benchmarking will find the complete study structured to support both immediate planning cycles and multi-year strategic roadmaps.
Conclusion
The fluorescence lifetime imaging microscopy market is entering a phase of structured expansion in which technological maturity, application diversification, and translational momentum converge to reshape demand patterns. With historical growth establishing a solid base and a forecast CAGR of 5.91 percent extending through 2032, the market presents meaningful opportunities for organizations that can align product strategy, procurement planning, and evidence-generation capabilities with the realities of application specialization, regulatory validation, and reimbursement dynamics. The vendors that succeed will be those offering not only high-performance hardware but also credible workflows, upgrade flexibility, domain-specific validation support, and a clear line of sight to clinical and industrial adoption. Strategic decision-makers who engage with the full depth of this market research will be better positioned to allocate resources, prioritize partnerships, and capture sustainable advantage as the FLIM landscape continues to evolve through the end of the decade and beyond.
For detailed analysis of this topic, please visit the official page: Fluorescence Lifetime Imaging Microscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Manual Motor Starter Market to Hit $857M by 2032, 4.5% CAGR
By PW Consulting, 2026-09-07
Unlocking Market Intelligence: Inside the Manual Motor Starters Landscape for 2026 and Beyond
The global industrial landscape is undergoing a profound transformation, driven by the dual pressures of operational efficiency and stringent safety compliance. Within this intricate ecosystem, the Manual Motor Starters Market remains a critical cornerstone. These electromechanical devices are not mere components; they are the primary interface for manual isolation, control, and overcurrent protection in a vast array of electrical installations. For strategic planners, investors, and industry executives, understanding the trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and opportunity capture.
Worldwide Fiber Expansion Joints Market
PW Consulting is pleased to introduce a comprehensive market research study that dissects the current state and future potential of the global Manual Motor Starters sector. This article serves as a strategic overview, highlighting the key dynamics, competitive tensions, and growth vectors that define the landscape between 2026 and 2032. While we provide high-level context here, the full granularity of our analysis is reserved for the detailed report, available exclusively through our platform.
Worldwide Clock Chip Market
The Macro Trajectory: Growth Amidst Stability
When evaluating the historical performance of the Manual Motor Starters Market, the data reveals a story of steady resilience rather than volatile spikes. Following a trajectory that began at a substantial baseline in the early 2020s, the market has demonstrated consistent appreciations in value year over year. From a valuation in 2020, the market grew to cross significant thresholds by 2025, reflecting the underlying demand from industrial manufacturing, infrastructure development, and energy sectors.
AI Visual Intelligent Analysis Solution Market
Looking forward, our forecast models indicate a continued positive trend. The Compound Annual Growth Rate (CAGR) projected for the period through 2032 underscores a moderate but reliable expansion. This growth is not merely a function of population increase, but rather a structural shift towards modernizing aging electrical infrastructure and adhering to updated safety standards globally. The cumulative revenue value over the forecast period represents a significant opportunity for stakeholders who can position themselves correctly within the supply chain.
Strategic Value for 2026 Decision-Making
Why does this matter specifically for decisions being made in 2026? The answer lies in the timing of capital expenditure cycles. As industries plan for upgrades and expansions in the mid-decade, the procurement of motor protection and control units must align with long-term reliability goals. A reactive approach to sourcing manual motor starters can lead to procurement inefficiencies, compatibility issues, and compliance risks.
This research is designed to turn uncertainty into actionable intelligence. By analyzing the market size evolution and the drivers behind it, executives can better allocate resources. The study moves beyond simple top-line numbers to explore the structural forces reshaping the demand side. Understanding the velocity of adoption in critical sectors allows decision-makers to anticipate volume shifts before they impact supply availability or pricing power.
Core Market Dynamics and Regulatory Tailwinds
The operational environment for manual motor starters is heavily influenced by technical standards and regulatory frameworks. These devices are fundamentally defined by their ability to provide manual isolation, control, and overcurrent protection in strict accordance with IEC and UL standards. This rigorous requirement creates a high barrier to entry for non-compliant manufacturers and ensures that safety remains a primary market differentiator.
Furthermore, the technical specifications of these devices are becoming increasingly demanding. Manufacturer specifications often require compliance with short-circuit breaking capacity requirements up to 100 kA at 400 VAC. This technical ceiling dictates the engineering roadmap for vendors and influences the pricing tiers of high-performance units. On the hazardous side of operations, specific product lines, such as factory-sealed manual motor starters, are engineered for use in hazardous locations including Class I, Division 1 and 2 areas. These niche requirements carve out specialized segments within the broader market, where consistent supply and certified safety take precedence over pure cost competition.
Pricing dynamics also play a critical role in market accessibility. The average selling price for industrial-grade manual motor starters typically ranges from $150 to $450, depending largely on the current rating, which can span from 10A to 100A, and the sophistication of protection features. This pricing sensitivity means that procurement strategies must carefully balance specification requirements against budget constraints, a tension this report analyzes in depth.
Competitive Landscape: The Titans and the Challengers
The market is not a free-for-all; it is defined by a specific set of established players and regional specialists. Our analysis identifies key companies that are driving innovation and market share acquisition. The competitive structure is moderately concentrated, with the top players commanding significant influence over product roadmaps and pricing standards.
Leading the charge is ABB, headquartered in Zurich, Switzerland. ABB has long been recognized for its robust portfolio of motor protection and control. Their specific offering for the Manual Motor Starters Market includes the MS116, MS132, MS165, MO132, and MO165 series. These units are designed to provide comprehensive motor protection and control within compact units, appealing to customers who value space efficiency and integrated functionality.
Schneider Electric, based in France, continues to exert strong influence through its TeSys Deca GV2 and GV3 series. These manual starters and protectors are widely deployed in industrial applications where modularity and ease of integration are paramount. In late 2025, the company released the TeSys Catalog 2026, featuring TeSys Deca Advanced and new Motor Starter Solutions, signaling a continued commitment to product line evolution and catalog expansion.
Eaton, with its headquarters in Dublin, Ireland, offers a diverse range of solutions including the PKZM series, MS series, and Cutler-Hammer B100 manual motor starters. Their breadth of branding allows them to address different legacy system requirements across multiple geographies. Siemens, from Munich, Germany, remains a formidable presence with its 3RV2 series manual motor starters, often embedded in larger automation and machine-building contexts.
Beyond the European and American giants, the landscape includes specialized players contributing to regional stability and product diversity. NOARK Electric, based in Pomona, California, USA, recently released the Ex9S80 Manual Motor Starter as part of the Ex9S series, adding to their lineup of Ex9S series manual motor starters known for built-in fault indication. Fuji Electric, from Tokyo, Japan, provides the Duo Series and Fuji Duo MMS manual motor starters, targeting high reliability in demanding environments. Appleton Electric, located in Marion, Illinois, USA, offers the EDS series factory-sealed manual motor starters, a crucial product for specific hazardous applications. Finally, LS Electric, headquartered in Anyang, South Korea, competes with its Metasol MMS series manual motor starters, emphasizing robust performance and regional supply chain advantages.
The competitive dynamics are not static. They shift with every product release and catalog update. For instance, the sequencing of a new release by a major player in the summer, followed by a catalog expansion by another competitor in the winter, highlights the continuous innovation cycle that defines this market. Stakeholders must monitor these cadence shifts to stay ahead in procurement negotiations and technology adoption.
Segmentation Insights: Beyond the Surface
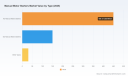
To truly navigate this market, one must understand the distinct branches of the value tree. The report provides a deep dive into segmentation that goes far beyond simple categorization. We examine the dominance of different technological types, specifically the contrast between Alternating Current and Direct Current based manual motor starters. Each type serves a distinct utility profile, and the volume split reveals much about the current state of industrial electrification.
Additionally, the application landscape is a key determinant of demand stability. Industrial manufacturing remains a primary driver, but sectors such as Oil & Gas, Water & Wastewater, and Mining exhibit unique procurement behaviors and specification requirements. The "Others" category aggregates various secondary applications that often provide early signals of emerging trends. The report analyzes how these applications interact with regional economic activity to create varying demand curves.
Geographically, the market exhibits a fragmented distribution. Demand is not uniform across the globe. Different regions demonstrate varying levels of market maturity and investment in electrical infrastructure. Our analysis breaks down the performance across major territories, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. This geographical nuance is essential for companies with global supply chains or those looking to enter new markets, as it reveals where growth pockets are forming relative to saturated zones.
The Strategic Imperative of Market Concentration
Understanding the structure of competition is vital for assessing risk. In markets with high concentration, a few players can dictate terms, whereas fragmented markets offer more procurement flexibility but potentially lower quality assurance. Our data suggests a moderate level of concentration, implying a balanced but competitive oligopoly. This structure benefits the end-user by providing multiple viable suppliers without diluting the collective R&D investment needed to meet evolving safety standards. The ratio of market share held by the top players indicates a healthy level of rivalry that drives product improvements and service enhancements.
What’s Inside the Full Report?
This overview scratches the surface of a comprehensive analytical effort. The full report, "Manual Motor Starters Market," is an exhaustive resource designed for high-level strategy and detailed operational planning. It contains actionable intelligence that cannot be gleaned from press releases or standard industry news.
Readers of the full document will find:
- Detailed historical expenditure analysis from the base year 2025, tracing back to 2020 to establish robust trend lines.
- A granular forecast extending through 2032, detailing the expected trajectory of the 2026 market valuation and its progression into the future.
- In-depth segmentation analysis that correlates specific product types with geographical demand, providing a matrix of opportunity.
- Application-specific buyer power analysis, distinguishing the procurement drivers in heavy industry versus infrastructure sectors.
- Company profiles that go beyond product lists to analyze market positioning, strategic shifts, and competitive responses.
- Regulatory impact assessments, detailing how compliance requirements are shaping the operational landscape for manufacturers and users alike.
- Supply chain and pricing sensitivity models based on current rating specifications and protection feature sets.
The report is built to serve as a reference point for boardroom discussions, R&D planning, and supply chain optimization. It connects the dots between raw regulatory facts, technical specifications, and economic reality.
Conclusion: Positioning for the Future
The Manual Motor Starters Market is at a juncture where safety, efficiency, and technological evolution converge. The projected growth trajectory suggests that demand will continue to rise, supported by the relentless need to protect and control industrial motors across diverse global sectors. For companies operating in or adjacent to this space, the ability to interpret these signals accurately is a competitive advantage.
Relying on high-level headlines is insufficient for the complex decisions of 2026 and beyond. You need the depth. You need the segmentation. You need the competitive nuance. The full scope of this intelligence is available in our detailed market research report. We invite you to explore the complete analysis to equip your organization with the insights necessary to navigate the future of electrical motor protection and control with confidence.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AFIS Market to Hit $566M by 2032 with 7.5% CAGR from 2026-2032
By PW Consulting, 2026-09-07
Navigating the Next Decade: A Strategic Preview of the Automated Fingerprint Identification Systems Market
The global security infrastructure is undergoing a fundamental transformation, driven by the escalating demand for precise identity verification and the rapid integration of biometric technologies into critical public and private sectors. As we move beyond the baseline of 2025, the Automated Fingerprint Identification Systems (AFIS) market stands at the intersection of technological evolution and regulatory necessity. PW Consulting has recently finalized a comprehensive market research study focused on the trajectory of this sector from 2026 through 2032. This article serves as a strategic executive preview, outlining the macroeconomic currents, competitive dynamics, and operational imperatives that define this landscape. For enterprise leaders, government contractors, and investment stakeholders, understanding the velocity of this market is no longer optional; it is a prerequisite for informed decision-making in an era where digital identity is the new currency of security.
Worldwide Manual Feeding System Market
The purpose of this insight piece is to delineate the strategic value embedded within our latest report. While the following narrative highlights the structural trends and key players shaping the industry, the full depth of our quantitative analysis—including specific volume projections and structural breakouts—remains exclusive to the complete research document. This approach ensures that our clients receive unfiltered, high-fidelity intelligence necessary for formulating robust strategies in the coming years. The market is not merely growing; it is evolving in complexity, requiring a nuanced understanding of regional variances, technological shifts, and the consolidating nature of the vendor landscape.
Unified Commerce Service Market
Macroeconomic Trajectory and Market Vitality
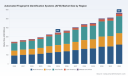
The historical performance of the AFIS sector over the past half-decade provides a robust foundation for future forecasting. Between 2020 and 2025, the market demonstrated consistent resilience and expansion, reflecting the broader adoption of biometric solutions across government and commercial verticals. Our analysis tracks the revenue progression from a baseline of 245.0 million USD in 2020, marking a steady climb to 348.0 million USD by the base year of 2025. This historical arc underscores a fundamental shift where fingerprint identification has moved from a niche forensic tool to a cornerstone of modern identity management infrastructure.
Worldwide Gasoline Lawn Mower Market
Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in valuation. The market is projected to reach 368.96 million USD in 2026, immediately following the base year, and continue its upward trajectory to culminate at 566.0 million USD by 2032. This growth path implies a Compound Annual Growth Rate (CAGR) of 7.5 percent over the forecast horizon. Such a rate indicates a healthy, maturing market that is expanding beyond initial adoption curves into widespread integration phases. For strategists, this CAGR is not just a number; it represents the pace at which capital must be allocated to R&D, partnership development, and market entry strategies to capture value before the growth curve stabilizes.
It is crucial to note that this top-line valuation aggregates diverse revenue streams ranging from hardware procurement to software licensing and maintenance services. The sheer scale of the projected 566.0 million USD endpoint suggests that the addressable market is becoming increasingly crowded. Organizations entering this space must recognize that organic growth will likely need to be supplemented by strategic consolidation or differentiation through algorithmic superiority. The transition from the 348.0 million USD mark in 2025 to the final forecast figures reflects not only volume growth but also potential price erosion due to competition, balanced against premium pricing for advanced AI-driven matching capabilities.
Technological Segmentation and Structural Drivers
The internal architecture of the AFIS market is defined by distinct operational types and application vectors, each carrying different implications for deployment complexity and customer acquisition costs. Our research distinguishes between Live Scan AFIS, Offline AFIS, and other emerging types, highlighting how the mode of capture influences downstream processing speeds and integration requirements. The industry is witnessing a pronounced tilt toward solutions that offer seamless connectivity and real-time processing capabilities. While our detailed report provides the specific revenue attribution for each type, the strategic implication is clear: solutions that bridge the gap between physical capture and digital analysis without latency are commanding the most attention from end-users.
Live scan technologies, which allow for the digital capture of fingerprints without ink and paper, continue to dominate the operational mindset of law enforcement and border control agencies. However, offline systems retain relevance in specific archival and forensic contexts where digital infrastructure may be limited or where retroactive analysis of physical latent prints is required. The balance between these types is shifting as cloud infrastructure becomes more reliable and secure. The move toward cloud-native architectures allows for scalable database management, which is essential as national and international biometric databases expand in size.
Application-wise, the market is primarily anchored by Law Enforcement and Security agencies, which remain the steadfast backbone of AFIS adoption. Criminal investigations utilize these systems for suspect identification and case resolution, while border and immigration authorities leverage them for traveler verification and identity fraud prevention. The interplay between these applications creates a complex demand signal. For instance, increased border security protocols often drive demand for higher throughput scanners, whereas criminal investigation needs prioritize accuracy and latent print matching capabilities. Our report delves into the operational requirements of each segment, helping buyers understand which solution architecture aligns with their specific use case without disclosing the precise share splits that could compromise competitive intelligence within the document.
Furthermore, the integration of multi-modal biometrics is becoming a standard expectation rather than a differentiator. Modern AFIS platforms are increasingly expected to interoperate with facial recognition and iris scanning systems to create a holistic view of identity. This convergence reduces false acceptance rates and enhances security postures. Vendors who fail to adapt their AFIS offerings to support multi-biometric environments risk obsolescence, particularly in high-security government contracts where layered verification is mandated. The strategic takeaway for 2026 and beyond is that standalone fingerprint solutions are losing ground to integrated identity platforms.
Competitive Landscape and Vendor Dynamics
The vendor ecosystem within the AFIS market is characterized by a mix of established multinational technology giants and specialized biometric firms. Our analysis identifies a market concentration that suggests a moderately consolidated environment, where a handful of key players command significant influence over pricing and technology standards. The CR3 and CR5 metrics within our full report quantify this concentration, but qualitatively, it is evident that the battle for market share is being fought on the grounds of algorithmic accuracy, scalability, and global support networks.
NEC Corporation, headquartered in Tokyo, remains a formidable presence with its Integra-ID AFIS/ABIS platform. Their focus on advanced fingerprint matching algorithms for law enforcement and border security positions them as a preferred partner for government-grade contracts. Similarly, Fujitsu Limited leverages its strong IT infrastructure background to provide cloud-based AFIS platforms. By integrating AI-enhanced matching for financial institutions and public security, Fujitsu addresses the dual need for high security and scalable cloud architecture, appealing to sectors beyond traditional policing.
IDEMIA, based in Courbevoie, France, continues to push the boundary with its STORM ABIS cloud-native system and Case AFIS for latent fingerprint identification. Their emphasis on multibiometric searches aligns with the industry trend toward comprehensive identity solutions. HID Global Corporation, operating out of Austin, Texas, takes a hardware-centric approach with modular AFIS/ABIS solutions. Their FBI-certified scanners and livescan management software are critical for government and law enforcement clients who require certified hardware interoperability. These three entities, among others, define the upper tier of the competitive hierarchy.
In the European and emerging markets, companies like DERMALOG Identification Systems GmbH in Hamburg contribute specialized high-speed matching algorithms for civil and criminal identification. Meanwhile, Papillon Systems in Moscow supplies AFPIS multibiometric AFIS with support for palmprint and fingerprint, catering specifically to forensic and law enforcement needs in specific geographic zones. The presence of diverse players such as Sonda Technologies Ltd. from the Republic of Korea and M2SYS Technology from Chennai, India, highlights the global nature of the supply chain. M2SYS, for instance, focuses on scalable cloudABIS platforms with hyper-threaded matching servers, targeting large-scale biometric databases that require heavy computational resources.
Crossmatch Technologies Inc. and SUPREMA from South Korea represent the hardware and integration stronghold. Crossmatch manufactures fingerprint scanners and AFIS integration solutions certified for FBI NGI systems, ensuring compliance with stringent US federal standards. SUPREMA provides BioMini and other fingerprint scanners alongside AFIS-compatible solutions for ID and border control, reinforcing the importance of end-to-end compatibility. Innovatrics in Bratislava adds to this mix with high-performance ABIS featuring multimodal support for enterprise biometric identification. The competitive landscape is not static; it is defined by ongoing technological upgrades and the ability of these companies to navigate local regulatory environments while maintaining global interoperability. For a buyer, selecting a partner involves weighing these specific capabilities against long-term support viability and integration costs.
Regional Dynamics and Deployment Considerations
Geography plays a critical role in the deployment and adoption rates of AFIS technologies. While global growth is positive, the drivers vary significantly by region. North America typically maintains a strong position due to established federal and state-level investment in biometric infrastructure and the presence of key industry players. Europe follows with rigorous data privacy regulations that shape how AFIS solutions are implemented, often requiring localized data handling and strict compliance frameworks. The Asia Pacific region represents a high-growth vector, driven by expanding digital identity programs, smart city initiatives, and increasing security expenditures across both public and private sectors.
Emerging regions in Latin America and the Mideast and Africa present unique opportunities and challenges. In these markets, the adoption of AFIS is often linked to international aid projects, border security enhancements, and modernization of legacy law enforcement systems. The growth potential here is significant, but it is accompanied by infrastructure constraints and varying levels of regulatory maturity. Our full report provides a detailed breakdown of revenue performance across these regions, allowing strategists to pinpoint where capital expenditure is most likely to yield returns. However, the strategic overview indicates that a one-size-fits-all approach is ineffective. Deployment strategies must be localized, considering connectivity issues, power stability, and local legal mandates regarding biometric data storage and processing.
The regional analysis also extends to supply chain considerations. With manufacturing hubs distributed across Japan, the United States, Europe, India, and South Korea, logistics and trade dynamics influence the availability and cost of hardware components. Import regulations and technology transfer restrictions can impact the ability of vendors to deploy solutions in certain jurisdictions. Understanding these geographic friction points is essential for multinational corporations planning to roll out AFIS solutions across multiple continents. The market research provides the necessary context to navigate these complexities, ensuring that deployment timelines are realistic and compliant with local trade and security laws.
Strategic Implications for 2026 and Beyond
For stakeholders formulating strategies in 2026, the AFIS market offers clear signals regarding where value is being created. The first implication is the necessity of cloud integration. As databases grow from millions to billions of records, on-premise solutions may struggle to offer the required scalability and update cadence. Vendors and buyers alike must prioritize architectures that support hybrid or full-cloud environments to ensure long-term viability. The second implication is the critical importance of AI and machine learning in matching algorithms. As the volume of data increases, manual verification becomes impossible. Automated, AI-driven matching that reduces false positives and negatives is the key performance indicator that will differentiate winning solutions from legacy systems.
Investment decisions should also account for the trend toward modal convergence. Projects that propose AFIS as a standalone silo may face scrutiny during budget approvals. Instead, positioning fingerprint identification as part of a broader biometric identity suite aligns better with current procurement trends in both the public and private sectors. This positioning also mitigates risk; if one modality faces technical limitations, others can compensate, ensuring continuous security operations.
Furthermore, compliance and certification remain non-negotiable hurdles. The FBI NGI system certifications and other regional regulatory standards act as gatekeepers to significant market segments. Companies must maintain rigorous compliance schedules to remain eligible for government contracts. For investors, this means due diligence must include an assessment of a vendor's regulatory track record and their capacity to maintain certifications amidst changing standards. The market is rewarding vendors who view compliance not as a burden but as a value proposition that guarantees trust and interoperability.
Finally, the concentration of the market suggests that partnership or acquisition strategies may be more effective than pure organic growth for new entrants. The barrier to entry regarding algorithm development and hardware certification is high. Collaborating with established players or acquiring niche technology firms can accelerate time-to-market. The detailed segmentation data in our full report will help identify which sub-segments are ripe for consolidation and where white spaces might exist for disruptive innovation.
Conclusion and Access to Complete Intelligence
The Automated Fingerprint Identification Systems market is poised for significant expansion through 2032, underpinned by robust technological adoption and enduring security needs across the globe. The journey from 348.0 million USD in 2025 to a projected 566.0 million USD in 2032 represents more than just revenue growth; it signifies a deepening integration of biometric identity into the fabric of societal security and operational efficiency. The 7.5 percent CAGR indicates that this is a sector where sustained attention and strategic positioning are required to capture value. While the macroeconomic overview and competitive landscape presented here offer a valuable starting point, they are merely the surface layer of the intelligence available.
PW Consulting's full market research report goes far beyond these high-level insights. It contains the granular data necessary to build financial models, assess specific regional risks, evaluate vendor capabilities against detailed specifications, and identify precise growth vectors within each segmentation category. The report includes comprehensive profiles of the key companies driving the market, detailed analysis of recent developments, and a breakdown of concentration metrics that inform merger and acquisition strategies. For decision-makers who need to move from observation to action, the complete document is the essential tool.
We invite industry leaders, investors, and strategic planners to access the full report to equip themselves with the exact data points needed to navigate this evolving landscape. In a market defined by precision and trust, relying on partial information is a risk that can be avoided. The complete research provides the clarity required to make informed investments, forge the right partnerships, and deploy technologies that will stand the test of time in the global security infrastructure. The strategic value of this intelligence lies in its ability to turn complex market dynamics into actionable roadmaps for 2026 and the years beyond.
For detailed analysis of this topic, please visit the official page: Automated Fingerprint Identification Systems (AFIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micromanipulators Market Hits $81.5M in 2025, Projected 9.3% CAGR to $152.8M by 2032
By PW Consulting, 2026-09-07
Precision at the Microscale: Strategic Imperatives in the 2026 Micromanipulators Market
The micromanipulation landscape is undergoing a decisive transformation. As laboratory workflows grow more complex and industrial tolerances tighten, the demand for sub-micron positioning accuracy has shifted from a niche requirement to a foundational capability. Our latest market research on the Micromanipulators Market provides a comprehensive, data-grounded lens into how this sector is evolving through 2032. For executives navigating capital allocation, R&D prioritization, and competitive positioning, this report delivers the strategic clarity required to act with confidence in 2026 and beyond.
Algae Based Plastics Market
The Macro Trajectory: Velocity, Scale, and Structural Shift
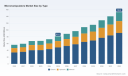
Over the past half-decade, the global micromanipulators market has demonstrated consistent, compounding growth. Revenue expanded from approximately USD 56.5 million in 2020 to an estimated USD 81.5 million in 2025, reflecting a sector that has not only recovered from pandemic-era supply chain friction but has accelerated into a new growth phase. Looking ahead, the forecast period from 2026 through 2032 projects a robust compound annual growth rate of 9.3 percent, with market revenue anticipated to cross the USD 150 million threshold by the end of the decade. These figures are not merely historical retrospectives; they are leading indicators of structural demand drivers that will shape procurement strategies, partnership decisions, and innovation roadmaps across life sciences, semiconductor fabrication, and advanced materials research.
Low Voltage LED Explosion Proof Light Market
Several converging forces explain this momentum. Sustained investment in neurology and cell biology research has intensified the need for repeatable, high-fidelity manipulation workflows. Simultaneously, the semiconductor and microelectronics sectors continue to push dimensional tolerances downward, requiring positioning subsystems that can operate with minimal drift and exceptional repeatability. The normalization of assisted reproductive technologies and the formalization of micro-operative protocols have further embedded micromanipulation into regulated clinical pipelines. Together, these dynamics create a multi-application demand base that is less vulnerable to single-sector downturns than earlier market cycles suggested.
Hydrogen Electronic Pressure Regulators Market
From Linear Growth to Compounding Value
The growth trajectory observed between 2020 and 2025 was not accidental. It was built on a foundation of iterative product refinement, expanding end-user training programs, and the gradual migration from legacy manual setups toward motorized and electric architectures. As research institutions and commercial laboratories scale their throughput, the total cost of ownership calculus has shifted. Buyers now weigh precision stability, integration compatibility, calibration drift, and service responsiveness alongside initial purchase price. This recalibration of buyer priorities is a critical insight for suppliers evaluating product roadmaps and for procurement leaders structuring multi-year equipment budgets.
Equally important is the market's increasing sensitivity to regulatory and standardization developments. Recent definitions and clinical guidance documents have formalized micro-operative techniques that rely on micromanipulation for procedures such as intracytoplasmic sperm injection and assisted hatching. While these standards do not dictate device specifications directly, they influence laboratory procurement policies, quality management expectations, and the documentation burden placed on equipment vendors. Organizations that anticipate these compliance trends will secure smoother adoption cycles and reduce time-to-deployment for new instrumentation.
Competitive Architecture: Focused Leaders, Regional Depth, and Consolidation Signals
The micromanipulators market remains characterized by a concentrated yet highly specialized competitive field. Industry data indicates that the top three participants collectively account for roughly 38.5 percent of total market revenue, while the top five expand that share to approximately 45.2 percent. This concentration pattern reflects the technical barriers inherent in precision mechanical design, sensor integration, and application-specific calibration. At the same time, the remaining market share is distributed among a long tail of capable manufacturers, regional integrators, and application-focused specialists, creating a landscape where differentiation is achieved through expertise rather than scale alone.
Several companies exemplify the strategic posture now required to compete effectively. Sensapex Oy, headquartered in Oulu, Finland, has built its reputation on patented ultraprecise micromanipulators and automated microscope workstations designed for electrophysiology and imaging, with in-house manufacturing supporting tight control over performance consistency. Sutter Instrument, based in Novato, California, continues to serve a broad electrophysiology and cell manipulation customer base through precision manual and motorized platforms that emphasize reliability and practical usability. Scientifica Ltd, operating from East Sussex, United Kingdom, has focused on the PatchStar micromanipulator line and electromechanical systems tailored for patch clamp and electrophysiology workflows, reinforcing a strategy of deep application specialization.
In the United States, Siskiyou Corporation, located in Grants Pass, Oregon, has maintained a strong reputation for high-precision micromanipulators and micropositioners used in microscopy and research applications, where customization and engineering responsiveness remain key differentiators. Narishige Group, headquartered in Tokyo, Japan, offers a distinct product philosophy through its NTX series hydraulic and motorized micromanipulators, addressing cell manipulation and microinjection requirements with a balance of mechanical robustness and fine positional control. World Precision Instruments, based in Sarasota, Florida, remains closely associated with manual micromanipulators for electrode positioning in electrophysiology and neuroscience, a segment where familiarity, service networks, and practical ergonomics continue to drive repeat purchases.
Larger systems players also shape the market's direction. Leica Microsystems, from Wetzlar, Germany, delivers integrated micromanipulator systems that align precision positioning with advanced microscopy and cell research environments, benefiting from cross-platform integration and brand trust in imaging ecosystems. Eppendorf SE, headquartered in Hamburg, Germany, contributes high-precision micromanipulation and injection systems that serve broad life science applications, reinforcing a portfolio strategy that connects sample handling, manipulation, and downstream processing in a cohesive workflow.
Recent Moves That Signal Strategic Direction
Recent corporate activity illustrates how quickly product portfolios and deployment models are evolving. In mid-2024, Sensapex released a revised manual for its uMp micromanipulation system, incorporating the uMp-TSC2 controller alongside uMp-3 and uMp-4 micromanipulators, a move that underscores a continued emphasis on usability upgrades and controller-level integration. By late 2024, New Scale Technologies completed delivery of a Modular Insertion System to the Allen Institute for Neural Dynamics, enabling order-taking for next-generation silicon probe micromanipulation and highlighting the growing importance of modular, research-grade insertion workflows in neuroscience. More recently, planning for SLAS Europe 2026 has featured sessions examining manual micromanipulation in an era of lab automation, signaling a broader industry conversation about where manual control still adds value and where automation is reshaping protocols.
These developments matter because they reveal how incumbents and innovators are responding to the same underlying pressure: laboratories want higher throughput, better repeatability, and clearer integration paths without sacrificing the fine control required for delicate procedures. Companies that can bridge that gap through modular architecture, improved controller interfaces, or application-tuned mechanical designs are likely to capture disproportionate attention from advanced research groups and commercial testing organizations.
Operational Content: What the Report Delivers for Decision-Makers
This market research is designed as an operational instrument, not a static summary of figures. The report is structured to help strategy, product, and commercial teams translate market signals into concrete actions. It provides a detailed examination of product architectures across electric, hydraulic, and manual configurations, mapping each category to the performance trade-offs, maintenance profiles, and application fit that drive adoption decisions. Rather than treating these segments as isolated statistical buckets, the analysis situates them within the purchasing logic of end users who must balance precision, throughput, training burden, and lifecycle cost.
The report also traces application-level demand patterns in a way that is actionable for go-to-market planning. Cell micromanipulation remains a dominant use environment, driven by life science research, reproductive medicine workflows, and advanced cellular engineering. Industrial micromanipulation applications form a distinct and growing demand base, shaped by micro-assembly, inspection, and precision handling requirements in manufacturing-adjacent settings. Additional use cases extend the market's reach into specialized research and imaging workflows. By examining how these application clusters interact with product type preferences, procurement cycles, and regional laboratory infrastructure, the study helps companies identify where to concentrate sales engineering resources and where to adapt messaging for different operational realities.
Regional Context Without Overgeneralization
Geographic analysis in the report is framed around deployment density, institutional demand profiles, and the practical realities of supply and support networks rather than simplistic share rankings. North America continues to reflect a mature buyer base with strong exposure to neuroscience, electrophysiology, and advanced imaging research. Europe maintains a substantial footprint shaped by established academic institutions, clinical research infrastructure, and a strong tradition of precision instrumentation. Asia Pacific's trajectory is gaining attention as research investment, semiconductor-related precision needs, and expanding laboratory capacity reinforce demand across multiple application domains. Latin America and the Middle East and Africa, while smaller in absolute scale, represent targeted opportunities where specialized support, affordability, and application training can influence adoption more than headline market size alone.
By maintaining this contextual framing, the report helps clients avoid the trap of treating all regions as homogeneous. Regional strategy requires understanding what local laboratories prioritize, how procurement cycles differ, and which service and calibration capabilities are expected as baseline requirements. The analysis provides the qualitative scaffolding needed to translate market potential into realistic entry or expansion plans.
Industry Dynamics: Cost Pressure, Standards, and Cross-Sector Pull
One of the most important dynamics shaping procurement behavior is the tension between precision expectations and total cost of ownership. Industry commentary has noted that certain low-cost electric micromanipulator assemblies can materially undercut the price of commercial hydraulic alternatives while eliminating the need for regular maintenance. This cost dynamic does not uniformly displace premium systems, but it does reshape comparison sets, especially in laboratories balancing performance requirements against budget constraints. For vendors, this environment rewards clarity about where value is created: in stability, in integration, in service responsiveness, or in application-specific calibration that lower-cost alternatives cannot easily replicate.
Regulatory and standards developments are exerting a parallel influence. Recent consensus definitions and clinical guidance have formalized the role of micromanipulation within micro-operative assisted reproductive techniques, including ICSI and assisted hatching. These references may appear clinical on the surface, but they have commercial implications. They influence laboratory purchasing criteria, documentation expectations, and the degree of procedural justification required for equipment selection. Suppliers that understand how such standards filter into procurement checklists and internal validation processes are better positioned to support customers through adoption and to avoid friction in regulated environments.
On the demand side, a broader macro trend continues to accelerate interest in high-precision micromanipulation across neurology, biology, and semiconductor-adjacent sectors. The rise in R&D activity is not simply expanding the user base; it is changing the sophistication of the user base. More laboratories now expect repeatable positioning, better integration with imaging or automation peripherals, and clearer documentation for method reproducibility. That shift increases the strategic importance of product reliability and supplier support, while also expanding the addressable market for systems that can serve multi-application labs without sacrificing specialized performance.
Why This Study Matters for 2026 Decision-Making
2026 is a planning year in which many organizations must reconcile near-term budget constraints with long-term capability needs. The micromanipulators market is at a point where historical growth, product evolution, and application expansion are aligning in ways that reward informed strategic positioning. Companies that delay analysis risk overindexing to legacy product assumptions, misallocating sales coverage, or underestimating the importance of integration and service in buyer decisions. Organizations that act early can align product development, pricing architecture, channel strategy, and customer education with the demand patterns that are already shaping procurement behavior.
The strategic value of this research lies in its ability to connect multiple layers of evidence into a single decision framework. It grounds narrative insight in verified market sizing and forecast direction, integrates competitive profiles with recent product and deployment developments, and contextualizes those findings within the practical realities of laboratory and industrial purchasing. For executives evaluating market entry, portfolio expansion, partnership opportunities, or competitive response, the report offers a disciplined starting point that reduces uncertainty without oversimplifying a technically complex sector.
What Is Reserved for the Full Report
To preserve the analytical integrity and commercial utility of the study, this preview intentionally omits the detailed segmentation breakdowns, region-specific share figures, application-level revenue distributions, and type-level quantitative splits that support the broader narrative. Those data are essential for building precise financial models, sizing submarket opportunities, and benchmarking competitive exposure. They are also the core reason the full report functions as a working intelligence asset rather than a high-level overview. Clients who rely on top-line macro signals alone risk missing the structural differences that determine where value is created and where competition is most intense.
The complete study unpacks those layers in a format designed for internal strategy discussions, product planning sessions, and commercial forecasting. It connects market size movement to segment-level dynamics, maps competitive positioning to product and application fit, and provides the granularity needed to assess which opportunities are large enough to justify investment and which require a more targeted approach. For teams planning 2026 initiatives, that level of detail is not optional; it is the difference between directional confidence and decision-grade evidence.
How to Use This Intelligence
Organizations derive the most value from this research when they treat it as a strategic framework rather than a single-use reading. Product leaders can use the analysis to pressure-test roadmap assumptions against application demand and buyer cost sensitivity. Commercial teams can align territory plans and value propositions with the segments and use cases most likely to drive near-term growth. Corporate development and partnership teams can identify where interoperability, service networks, or application expertise create more advantage than raw manufacturing scale. Executive leadership can use the forecast trajectory and market concentration context to frame investment timing and risk tolerance with a clearer view of where growth is structural rather than cyclical.
In a market defined by precision, repeatability, and increasing application complexity, the organizations that outperform will be those that understand not just that demand is growing, but why it is growing, where it is concentrating, and what buyers now expect from the equipment they trust with critical workflows. This study is built to provide exactly that understanding.
To access the full segmentation detail, competitive benchmarking, application analysis, and forecast scenarios that support planning-level decisions, we invite you to review the complete Micromanipulators Market research on the source page. The complete dataset and proprietary analysis are available there for teams that need to move from market awareness to actionable strategy.
For detailed analysis of this topic, please visit the official page: Micromanipulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Barcode Label Printer Market to Reach $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-07
Executive Brief: Navigating the Barcode Label Printer Market 2026-2032
In an era where supply chain resilience and data integrity dictate competitive advantage, the barcode label printer has evolved from a peripheral utility to a strategic asset. As enterprises across logistics, healthcare, manufacturing, and retail confront mounting regulatory pressures and volatile input costs, the need for precise, forward-looking intelligence has never been greater. The updated Barcode Label Printer Market Research offered by PW Consulting delivers exactly that: a comprehensive, data-grounded examination of where the market stands, how it is shifting, and what decision-makers must anticipate through the end of the decade. This article serves as a strategic preview of the full report, outlining the executive value proposition and highlighting the analytical frameworks embedded within our latest publication.
Food Preservative Sodium Benzoate Market
The global landscape for barcode label printers is undergoing a phase of structural redefinition. Demand is no longer driven solely by volume replacement cycles; it is being reshaped by compliance mandates, automation trends, edge computing integration, and sustainability expectations. Understanding these forces requires more than a snapshot of current sales. It demands a disciplined look at historical trajectories, near-term inflection points, and the competitive architecture that will determine market share allocation in the years ahead. PW Consulting’s assessment is built to support exactly that level of strategic foresight.
PCB Automated Visual Inspection(AVI) System Market
Market Trajectory and Strategic Context: 2020-2032
The baseline figures in our analysis trace a clear upward arc across the historical window from 2020 through 2025, establishing a foundation of consistent expansion even amid macroeconomic disruptions. That momentum carries forward into the forecast horizon extending to 2032, with a projected compound annual growth rate (CAGR) reinforcing the market’s resilience and long-term relevance. For leadership teams evaluating capital allocation, operational readiness, or vendor partnerships, the scale of this expansion is meaningful. A market that crosses multiple hundred-million-dollar thresholds over the forecast window signals sustained demand for label printing solutions across both mature and emerging use cases.
Industrial Low-Temperature Heat Pump Systems Market
More important than any single headline figure is the rhythm of growth itself. The trajectory reflects a market that is not merely recovering but recalibrating around new operational priorities: higher print reliability at the edge of the warehouse floor, compact and ruggedized devices for mobile workflows, and printer portfolios aligned with connected inventory systems. The data narrative in the full report connects these demand-side shifts to revenue growth patterns, enabling readers to align procurement planning, product roadmaps, and regional expansion strategies with realistic quantitative expectations. Because the complete breakdown of regional contributions, technology preferences, application weightings, and device-type distributions is detailed within the report itself, this preview intentionally retains the macro-level framing. That approach preserves the analytical gravity of the dataset while directing readers to the source for the precise figures required to model their own scenarios.
What the Report Delivers: Operational Intelligence Beyond the Numbers
A strong market study does more than summarize past performance; it equips stakeholders with a usable framework for action. PW Consulting’s Barcode Label Printer Market research has been constructed with that standard in mind. The publication is organized to serve a range of internal functions, from procurement and supply chain leadership to product strategy, competitive intelligence, and financial planning. Each section is designed to reduce ambiguity around market structure and to clarify where investment and procurement decisions should be prioritized.
Core Components of the Report
- Historical sizing and forecast modeling spanning the full analysis window, enabling year-by-year context for revenue evolution and growth pacing.
- Structural segmentation analysis that maps the market across device categories, printing technologies, key application environments, and geographic regions, providing the scaffolding needed to understand where value concentrates and where opportunities are emerging.
- Competitive profiling of leading participants, including positioning summaries and technology focus areas, so that buyers and competitors alike can benchmark capability sets and strategic intent.
- Documentation of recent corporate developments, such as product launches, line extensions, and trade-show activations, offering a timely view of how major players are translating strategy into market-facing moves.
- Assessment of market concentration indicators, giving readers a sense of fragmentation, consolidation risk, and bargaining dynamics within the supplier base.
- Industry context review covering regulatory updates, raw-material cost pressures, and logistics disruptions that are reshaping manufacturing economics and lead-time reliability for printer hardware.
This structure is deliberate. By combining quantitative market sizing with qualitative event tracking and external factor analysis, the report functions as a decision-support tool rather than a static reference. Readers can use it to validate assumptions, pressure-test expansion plans, and identify which operational variables merit closer monitoring. For organizations that depend on label printing as part of broader identification, traceability, or fulfillment workflows, that blend of data and context is indispensable.
Competitive Landscape: Established Leaders and Specialized Challengers
The competitive environment in barcode label printing is defined by a blend of global automation incumbents, specialized identification technology providers, and regional specialists with strong cost-performance positioning. The report profiles a broad cross-section of these companies, capturing how each is shaping its offering for distinct operational environments. This matters because procurement decisions are increasingly tied not only to unit price but to integration readiness, durability, connectivity features, and alignment with sector-specific compliance requirements.
Major Participants and Strategic Positioning
- Zebra Technologies Corporation remains deeply embedded in the high-volume identification space, with printer solutions extending across industrial, desktop, mobile, and RFID-enabled formats for logistics, retail, and healthcare environments. Recent activity underscores a continued push toward faster print speeds, hygiene-conscious device design, and advanced RFID integration for warehouse and clinical settings.
- Honeywell International Inc. emphasizes rugged desktop and portable printers with integrated scanning functionality, targeting industrial and warehouse use cases where durability and hands-free data capture matter. Its recent portable printer series highlights an interest in embedding AI-assisted data processing functions for healthcare and retail workflows.
- SATO Holdings Corporation focuses on industrial and mobile thermal label printers optimized for high-speed output in manufacturing, logistics, and healthcare, reinforcing the importance of throughput and reliability in mission-critical environments.
- TSC Auto ID Technology Co., Ltd. positions cost-effective industrial and mobile printers for demanding warehouse and logistics conditions, appealing to operators that need robust performance without premium price structures.
- Brother Industries, Ltd. serves high-volume and point-of-sale applications with industrial desktop and mobile thermal barcode label printers, reflecting a balance between commercial print density and operational simplicity.
- Seiko Epson Corporation offers label printers and dedicated barcode printing devices for retail, shipping, and industrial applications, extending its imaging heritage into operational identification workflows.
- Toshiba Tec Corporation contributes industrial desktop barcode and label printers tailored to manufacturing and logistics, aligning printer capability with material handling and production-line identification needs.
- DYMO (Newell Brands) concentrates on compact desktop and portable label printers and label makers for office, retail, and shipping use, while also expanding toward eco-friendly label materials in response to sustainability-driven demand.
- Citizen Systems Japan Co., Ltd. delivers high-performance desktop and portable printers for POS and industrial use, supporting environments that require consistent output and quick deployment.
- BIXOLON Co., Ltd. brings mobile, desktop, and industrial label and barcode printers into retail, logistics, and healthcare contexts, with recent visibility at international retail technology events signaling continued portfolio expansion.
- GoDEX International Co., Ltd. offers high-resolution desktop and mobile barcode label printers for industrial and commercial applications, targeting users that prioritize print clarity and versatility across commercial workflows.
These profiles are not mere company summaries. They are structured to help readers understand how each participant competes: through ruggedization, integrated scanning, RFID readiness, cost-efficient industrial output, compactness for office and shipping use, or sustainability features. For procurement leaders comparing vendor shortlists, or for strategists tracking possible consolidation and capability migration, this competitive mapping offers a practical lens. The full report broadens this view with additional market context and development tracking, allowing users to connect corporate moves to the broader growth pattern described earlier in the analysis.
Industry Dynamics: Regulation, Materials, and Supply Chain Pressures
Market growth does not occur in a vacuum. The current cycle is heavily influenced by external forces that affect both demand and the economics of supplying hardware. The report integrates several of these dynamics so that readers can anticipate friction points and compliance-driven opportunities rather than react to them after the fact.
Regulatory and Standards Developments
In North America, updated industry guidance for standard case code labeling has reinforced best practices for GS1-128 barcode compliance in grocery and foodservice sectors. This type of standardization typically raises the baseline expectation for print quality, label durability, and data formatting consistency, which in turn influences equipment selection and integration planning for distributors and retailers. At the same time, the U.S. Drug Supply Chain Security Act continues to drive mandatory adoption of barcode-enabled tracking systems in healthcare and pharmaceutical distribution. For printer suppliers and end users alike, these regulatory currents increase the strategic importance of reliable, traceable, compliant printing equipment.
Input Costs and Trade Constraints
Hardware economics are being pressured by a combination of material cost escalation and export-control dynamics. Rising U.S.-China technology trade tensions, including restrictions on semiconductor-related exports, have contributed to higher costs for rare earth elements used in printer hardware components. This input-cost environment is a reminder that pricing stability in the barcode printer market can be influenced as much by global trade policy and material availability as by end-market demand. Organizations planning multi-year printer deployments should factor such volatility into total cost of ownership assumptions and inventory timing.
Logistics Disruptions and Lead-Time Exposure
Supply chain conditions remain a practical concern for hardware sourcing. Prolonged transit delays in key maritime routes have extended shipping timelines and increased per-container costs, disrupting component imports for barcode printers. For buyers, this translates into longer lead times, potential deployment schedule slippage, and a stronger case for risk-buffered procurement strategies. For suppliers, it reinforces the value of regional inventory positioning and demand forecasting discipline. These dynamics are not short-term anomalies to be wished away; they are part of the operating reality that the report’s market outlook incorporates when framing the path toward 2032.
Strategic Implications for 2026 Decision-Making
What does this body of analysis mean for executives making decisions in 2026? First, it confirms that the barcode label printer market remains a growth-relevant category with broad cross-industry demand. The scale of the forecast trajectory and the underlying growth rate indicate that label printing infrastructure should be treated as a long-duration capability rather than a discretionary purchase. Second, the competitive landscape shows that no single device category or supplier profile fits every environment. Industrial throughput, mobile flexibility, desktop simplicity, integration with scanning and RFID, and sustainability-oriented materials all represent distinct value propositions that must be matched to operational requirements.
Third, external pressures—regulatory compliance, raw-material cost exposure, and logistics disruptions—make timing, sourcing strategy, and vendor reliability more important than ever. Organizations that evaluate printer portfolios with these factors in mind can reduce procurement risk, improve deployment predictability, and align hardware choices with compliance expectations in healthcare, retail, and food distribution workflows. Fourth, recent product activity from major participants signals that the market is moving toward faster, more connected, and in some cases more hygiene- or sustainability-conscious devices. Keeping pace with these developments requires ongoing monitoring, which is precisely the role the full report is designed to serve.
Leaders in finance, operations, procurement, and product strategy can use the research to address questions that often remain under-examined until a disruption forces attention: Where is demand expanding most reliably? Which device types and technologies dominate different parts of the market? How concentrated is supplier power, and what does that imply for negotiation and roadmap flexibility? What external shocks could alter cost structures or delivery timelines? The report is built to support that level of internal discussion with documented data and current event context, while leaving the detailed segment-level breakdowns available for deeper modeling within the full publication.
Final Word: Why This Research Belongs on the 2026 Planning Agenda
The barcode label printer market may appear, on the surface, to be a mature hardware category. In practice, it is a bellwether for how well organizations are adapting to traceability mandates, edge-level automation, mobile operational models, and supply chain cost pressures. PW Consulting’s updated market research offers a rigorous, current, and decision-oriented view of that landscape, bridging historical performance, forward-looking growth, competitive positioning, and external dynamics in a single structured assessment.
This article has outlined the macro framework and the report’s practical value without exposing the full segment-level intelligence that makes the study actionable for specific planning scenarios. For teams that need exact market sizing by region, device type, technology, and application, along with the accompanying competitive and industry-context detail, the complete Barcode Label Printer Market report is the appropriate next step. It is designed to convert high-level awareness into procurement confidence, portfolio strategy, and risk-informed planning. In a market where compliance, cost, and continuity all matter at once, that level of clarity is not optional—it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Barcode Label Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DDoS Protection Market Hits $2.15B in 2025, Projects 13.83% CAGR to $5.38B by 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the 2026 DDoS Protection and Mitigation Landscape
Executive Overview
The cybersecurity ecosystem in 2026 is defined by a relentless arms race between defenders and adversaries. As digital transformation accelerates across every industry sector, the surface area for attack expands in parallel. Among the most persistent and disruptive threats facing Chief Information Security Officers today is the Distributed Denial of Service (DDoS) attack. What was once considered a nuisance has evolved into a sophisticated instrument of geopolitical coercion, extortion, and competitive sabotage. PW Consulting presents this comprehensive market research to dissect the economic and technological architecture of DDoS Protection and Mitigation, offering enterprise leaders the intelligence required to navigate a high-stakes environment.
Mini LED Vehicle Display Market
This analysis serves not merely as a snapshot of current expenditures but as a strategic roadmap for the forecast period spanning 2026 through 2032. By understanding the trajectory of capital allocation, technology adoption, and competitive maneuvering, organizations can transform their security posture from reactive survival to proactive resilience. The following insights distill the core findings of our latest study, highlighting the macroeconomic drivers, the shifting competitive dynamics, and the operational considerations that will define success in this domain.
TFT Liquid Crystal Materials Market
Market Trajectory and Financial Performance
The VDDOS Protection and Mitigation market has demonstrated robust and consistent growth over the past half-decade, reflecting the essential nature of these services. Historical data from 2020 to 2025 indicates a steady upward climb in revenue, driven by increasing awareness of threat vectors and the tangible costs associated with downtime. The market has progressed from a valuation of approximately 1.61 billion USD in 2020 to an estimated 2.15 billion USD by the base year of 2025. This progression underscores a fundamental shift: security budgets are no longer discretionary but are instead foundational to business continuity.
Hollow Glass Window Market
Looking toward the forecast horizon, the momentum shows no signs of deceleration. Projections indicate the market will reach 2.42 billion USD in 2026, continuing its expansion to exceed 5 billion USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 13.83 percent through the end of the forecast period. Such a rate places DDoS mitigation among the faster-growing segments within the broader cybersecurity infrastructure landscape. For financial planners and IT strategists, this trajectory suggests that sustained investment will be necessary to keep pace with the evolving sophistication of attack mechanisms. The integration of these services into broader cloud architectures and the rising frequency of volumetric attacks ensure that demand will remain inelastic relative to economic fluctuations.
It is important to note that these figures represent the aggregate global market. The distribution of this value across different geographical zones and deployment models reveals further complexity. Organizations must look beyond the headline numbers to understand how specific regional dynamics and operational preferences influence total cost of ownership and efficacy. Detailed breakdowns of regional revenue contributions and specific deployment splits are critical for tailoring local strategies, and these granular insights are fully elaborated within the complete market research publication.
Market Dynamics: Drivers Forces and Restraints
Several interrelated factors are propelling the expansion of the DDoS protection market. The primary driver remains the escalating scale and frequency of attacks. Adversaries are leveraging larger botnets composed of compromised Internet of Things devices and cloud instances, enabling them to generate traffic volumes that threaten even well-engineered network perimeters. Furthermore, the motivation behind these attacks has diversified. Nation-state actors utilize DDoS as a tool of hybrid warfare, while criminal syndicates employ it for ransomware extortion and smokescreening during data breaches. This diversity in threat origin requires enterprises to adopt protection strategies that are equally versatile.
Infrastructure evolution is another critical driver. As enterprises migrate workloads to public and hybrid cloud environments, the traditional perimeter dissolves. This necessitates a shift from hardware-centric mitigation to scalable, software-defined protection that can span multiple environments without introducing significant latency. The requirement for always-on availability, particularly for digital-native businesses and critical service providers, mandates that mitigation capabilities be integrated directly into the content delivery and application layers. Consequently, the market is seeing a convergence of DDoS protection with broader web application firewall (WAF) and bot management services, creating bundled solutions that offer unified threat management.
However, the market does face headwinds that warrant strategic consideration. Operational costs associated with high-throughput scrubbing centers and the energy consumption of data center infrastructure are rising. Recent analysis suggests that data center electricity demand could potentially affect electricity rates if that demand leads to a meaningful change in the local utility's costs. This creates a secondary financial pressure on service providers, which may trickle down to pricing models for enterprise customers. Additionally, cybercrime-related DDoS attacks have caused unplanned data center outages, highlighting the physical realities of digital threats. These events serve as reminders that mitigation is not just about software rules but also about physical infrastructure resilience and redundancy.
Regulatory environments are also reshaping the landscape. In the European Union, the European Union Agency for Cybersecurity mandates operators in 18 critical sectors to meet resilience and 24-hour reporting requirements. Such mandates compel organizations to adopt certified mitigation capabilities and maintain rigorous incident response protocols. Compliance is no longer optional; it is a license to operate for many critical industries. To explore how these regulatory pressures vary by region and how they impact specific vertical market segmentations, stakeholders are encouraged to review the detailed sector analysis provided in the full report.
Technology Architecture Segmentation
The market is broadly categorized by how protection is deployed and the layer at which mitigation occurs. Deployment models have evolved as organizations seek to balance control, scalability, and cost. Cloud-based solutions currently represent a significant portion of the market, reflecting the industry-wide shift toward cloud-native architectures. These solutions offer the advantage of elastic scalability, allowing mitigation capacity to expand instantly in the face of massive volumetric attacks without requiring customers to procure additional hardware.
Hybrid models remain relevant for organizations with specific regulatory or latency requirements. These approaches combine the scalability of the cloud with the immediate response capabilities of on-premises appliances. On-premises deployment, while representing a smaller share of the market, persists in environments where data sovereignty or ultra-low latency is paramount. The choice between these models often depends on the specific risk profile of the organization and its architectural maturity. Detailed analysis of the revenue distribution across cloud-based, hybrid, and on-premises segments, along with the implications for procurement strategy, is available in the comprehensive segmentation chapter of the study.
Protection type segmentation further refines the market view. Network-based protection focuses on the infrastructure layer, filtering malicious traffic before it reaches application servers. This is essential for mitigating volumetric attacks that aim to saturate bandwidth. Application-based protection operates at the Layer 7 level, distinguishing between legitimate user requests and sophisticated application-layer attacks. Host-based solutions provide a final line of defense at the operating system level. As attacks become more targeted, the reliance on a single protection type is diminishing. Multi-layered strategies that integrate network, application, and host-based defenses are becoming the standard for high-security environments. The specific revenue attributable to each protection type and the growth rates associated with each layer are detailed within the full research document, providing clarity on where innovation spending is concentrated.
Competitive Landscape and Strategic Positioning
The competitive environment in the DDoS Protection and Mitigation market is characterized by a mix of established security vendors, cloud hyperscalers, and specialized network defense firms. Market concentration metrics indicate a moderately concentrated industry, where the top three companies hold a CR3 of 34.5 percent and the top five companies account for a CR5 of 42.0 percent. This structure suggests that while there are dominant players, there is still ample room for niche players and regional specialists to compete on differentiation.
Akamai Technologies continues to leverage its extensive distributed network to offer robust defense. Their Prolexic DDoS protection platform emphasizes behavioral defense and offers flexible deployment options including in-cloud, on-premise, and hybrid configurations. With dedicated infrastructure for both network and application layer attacks, Akamai positions itself as a comprehensive solution for large enterprises requiring global reach and deep expertise.
Cloudflare has carved out a strong position by integrating DDoS protection directly into its global anycast network. Their approach relies on automated L3/L4/L7 mitigation rulesets and CDN-integrated scrubbing, which allows for real-time bot and botnet defense. This integration simplifies operations for customers who already utilize Cloudflare for content delivery, creating a sticky ecosystem where security and performance are managed through a single pane of glass.
Imperva focuses on a multi-layered doctrine that covers networks, applications, APIs, and DNS. Their services emphasize automated mitigation backed by threat intelligence, appealing to organizations that need to secure complex application architectures including microservices and API gateways. Radware offers a distinct value proposition through its hybrid on-premise appliances and cloud scrubbing centers. Their adaptive real-time mitigation for L3/L4/L7 attacks and application security is supported by continuous innovation, such as the recent partnership expansion with Chief Telecom to launch the Godshield Pro DDoS protection service in Taiwan. This move highlights the industry trend toward regional partnerships to deliver high-performance, low-latency mitigation for local enterprises.
NETSCOUT Systems brings a legacy of network visibility to the table with their Arbor DDoS protection portfolio. Including Arbor Edge Defense, Arbor Cloud, and Threat Mitigation System, their suite is designed for perimeter and enterprise-scale volumetric attacks. F5 Networks contributes to the competitive field with Silverline DDoS protection and F5 Distributed Cloud Services, offering an integrated WAF and bot mitigation capabilities within a multi-cloud SaaS platform. Corero Network Security targets service providers and enterprises with their SmartWall real-time DDoS mitigation solutions, focusing on high-performance distributed defense.
Recent developments illustrate the dynamism of this competitive arena. Amazon Web Services launched a DDoS Protection feature for game developers via Amazon GameLift Servers, providing UDP-based proactive mitigation without manual byte matching and negligible latency. This demonstrates how cloud providers are embedding security into specific developer tools to capture niche markets. GTT Communications expanded global DDoS scrubbing capacity to 4 Tbps with new mitigation centers in São Paulo, Hong Kong, and Miami, signaling a race to increase capacity and reduce latency geographically. Radware also introduced Alteon Protect, an expansion of their AI-driven cloud security platform for scalable application security enforcement. These moves highlight a market where companies are constantly expanding capacity, entering new regions, and integrating AI to stay ahead of threat actors. Corero Network Security expanded real-time DDoS protection services into Pakistan and nearby regions via partnership with Beyond Technology MEA, exemplifying the push for global coverage. Stakeholders seeking a complete competitive benchmarking analysis, including detailed profiles of all key companies and their specific strategic moves, should refer to the full competition chapter of this report.
Forward Outlook 2026 to 2032
As we look toward the remainder of the decade, the DDoS Protection and Mitigation market is poised for continued evolution. The forecast period through 2032 suggests a market valuation trajectory that will likely reshape procurement strategies. The convergence of security and network functions, driven by the adoption of SASE and secure access service edge architectures, will likely blur the lines between traditional DDoS mitigation and broader network security operations.
Innovation in mitigation technology will likely focus on reducing the human burden of management. Automated response systems that can distinguish between legitimate traffic spikes and malicious floods without manual intervention will become a baseline requirement. Additionally, the integration of threat intelligence feeds that anticipate attack patterns before they materialize will add value to premium service tiers. As the threat landscape incorporates more artificial intelligence on the attacker's side, defenders will need equally sophisticated AI-driven defense mechanisms to maintain parity.
For enterprise decision-makers, the implications are clear. Continuing to rely on fragmented security tools will increase risk and operational overhead. The strategic value lies in selecting partners and platforms that offer integrated visibility and scalable mitigation capacity. Investing in education and incident response planning is equally critical, as technology alone cannot prevent all disruptions. The detailed scenario analysis and forecast models contained in our full study provide the quantitative backing needed to justify these investments and allocate resources effectively across the 2026 to 2032 timeline.
Conclusion
The DDoS Protection and Mitigation market represents a critical component of the modern cybersecurity infrastructure. With a robust growth trajectory, evolving competitive dynamics, and increasing regulatory pressures, the sector offers both challenges and opportunities for industry participants. Understanding the macro trends and the specific capabilities of market leaders is essential for crafting a resilient security strategy.
This overview provides a glimpse into the depth of analysis available in the complete PW Consulting market research report. To access granular data on regional revenue splits, detailed segmentation percentages, specific company market shares, and comprehensive sales channel analysis, we invite you to explore the full publication. The complete intelligence gathered here is designed to empower your organization with the actionable insights necessary to thrive in an increasingly hostile digital environment.
For detailed analysis of this topic, please visit the official page: DDoS Protection and Mitigation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Long-Term Care Software Market to Reach $642.7M by 2032, Growing at 8% CAGR
By PW Consulting, 2026-09-07
Strategic Horizons in Long-Term Care Software: A 2026 Market Intelligence Brief
The long-term care software market has entered a decisive phase of structural transformation. For executives navigating care delivery, technology procurement, and capital allocation, the question is no longer whether digital infrastructure will reshape post-acute and senior care operations, but how quickly the competitive landscape will consolidate around platforms that can reconcile regulatory complexity, reimbursement volatility, and clinician workflow demands. The latest PW Consulting market research on the Long-term Care Software Market is designed to answer that question with empirical rigor and actionable strategic framing.
Worldwide Non-Slip Floor Covering Market
Drawing on historical momentum through 2025 and extending our forecast horizon to 2032, the research establishes a clear trajectory of expansion. The market has consistently moved upward from 2020 through 2025, reflecting sustained institutional demand for integrated electronic health records, revenue cycle management, and ancillary operational modules. Over the forecast period, the analysis projects a compound annual growth rate of 8.0 percent, with total market size climbing from the mid-400 million range in 2026 toward a scale exceeding 640 million by the close of the decade. These figures are not merely indicators of volume; they signal a compounding shift in how care organizations digitize documentation, optimize reimbursement, and coordinate transitions of care. For leadership teams, the strategic implication is straightforward: software selection and integration roadmaps now carry enterprise-level financial and operational consequences.
Worldwide Tetrachloroethene Market
What elevates this research beyond headline metrics is the deliberate focus on decision-grade architecture. The report is built to support scenario planning, vendor evaluation, and resource allocation under conditions of regulatory uncertainty and platform competition. It provides a comprehensive map of the market’s structural layers, including type-based segmentation, application-driven demand patterns, and regional distribution of value creation. Crucially, while the executive brief you are reading highlights the scale and direction of the market, the full study preserves the granular splits, detailed segmentation values, and region-specific revenue dynamics that executives require for precise budgeting, go-to-market modeling, and competitive benchmarking. Those deeper figures are available through the complete research portal, where they can be cross-referenced with your internal forecasting assumptions.
Worldwide Scalable Clinical Chemistry Analyzers Market
Why Long-term Care Software Is a Strategic Imperative in 2026
The operational environment for long-term care providers has become significantly more demanding. Reimbursement frameworks are being recalibrated, compliance obligations are tightening, and clinical teams are under sustained pressure to reduce documentation burden while improving care continuity. Software platforms that once functioned primarily as record-keeping tools are now expected to serve as the connective tissue between clinical documentation, reimbursement accuracy, quality reporting, and operational decision-making.
Several regulatory and policy developments reinforce that expectation. CMS released an FY 2026 PDPM ICD-10 mapping tool with 34 changes effective October 1, 2025, directly affecting MDS and RAI coding as well as reimbursement calculations in long-term care settings. Alongside that, the FY 2026 Skilled Nursing Facility PPS Final Rule updated quality reporting and case-mix requirements, creating additional compliance responsibilities that long-term care software must support. At the same time, new HIPAA Security Rule amendments effective in 2026 mandate 72-hour breach reporting and biannual vulnerability scanning for in-scope systems used in long-term care EHR platforms. Together, these shifts mean that software capabilities are now tightly coupled to both financial performance and regulatory exposure.
For executives, the implication is that technology investment decisions can no longer be optimized around feature checklists alone. The market is rewarding platforms that can adapt to code changes, support accurate case-mix capture, streamline reimbursement workflows, and maintain compliance without adding friction to clinical documentation. This is precisely the environment in which detailed market research becomes a guiding instrument: it helps organizations distinguish between incremental product updates and structural competitive advantage.
What the Research Delivers: Structure, Applications, and Practical Intelligence
The PW Consulting study is organized to support multi-layered decision-making. It begins with a macro-level view of market growth and then drills into the components that drive revenue composition and adoption behavior. The research covers the principal software categories shaping the long-term care space, including electronic health records, revenue cycle management, and a broad set of supporting solutions that together form the operational backbone of care facilities and home-based services. Rather than presenting these categories as static silos, the report analyzes how demand for each segment interacts with organizational priorities, compliance needs, and reimbursement models.
The application dimension is equally important. Demand is distributed across nursing homes, assisted living facilities, and home healthcare agencies, with each setting carrying distinct workflow requirements, staffing models, and regulatory touchpoints. The study evaluates how software adoption differs across these environments and what that means for implementation complexity, integration priorities, and long-term value capture. Executives evaluating expansion, partnership, or procurement strategies can use this framing to determine where software capabilities must be most robust and where standardization can create efficiency gains.
Beyond structure, the report provides practical intelligence for vendor assessment and internal planning. It maps the capabilities that matter most in the current cycle, including MDS and RAI support, billing and reimbursement optimization, quality reporting, care transitions, and clinician productivity tools. It also examines how cloud deployment, data interoperability, and AI-assisted workflows are reshaping expectations around scalability and administrative burden. The goal is to give leadership teams a coherent framework for comparing solutions not only by feature sets, but by operational outcomes and compliance resilience.
Competitive Landscape: Platform Differentiation and Consolidation Signals
The long-term care software market is characterized by a moderately concentrated competitive field, with a limited number of leading providers accounting for a substantial share of revenue. This concentration creates both risk and opportunity. On one hand, a small group of dominant platforms can shape pricing, integration norms, and buyer expectations. On the other, it intensifies the importance of differentiation through AI-enabled workflows, reimbursement tooling, and domain-specific compliance support. The research systematically examines how the leading companies are positioning themselves within this environment.
PointClickCare, based in Chicago, has built its long-term care offering around an AI-powered EHR platform designed for skilled nursing, senior living, and post-acute care. Its emphasis on real-time data, transitions of care, and reimbursement optimization reflects the market’s growing need to connect clinical documentation with financial performance. MatrixCare, headquartered in Bloomington, focuses on EHR and home health solutions for both facility-based and home-based care organizations, with support for MDS/RAI, billing, and quality reporting. WellSky, located in Overland Park, offers a Long-Term Care EHR alongside its SkySense AI solution, targeting operational efficiency, documentation quality, and clinician productivity in skilled nursing and post-acute settings.
Netsmart Technologies, based in Cleveland, provides myUnity and GEHRIMED EHR platforms for post-acute and long-term care providers, spanning senior living, home health, and value-based care coordination. American HealthTech, headquartered in Ridgeland, has historically delivered EHR solutions for long-term care facilities with an emphasis on MDS/RAI automation, case-mix optimization, and reimbursement tools, and its acquisition by PointClickCare signals continued consolidation among major platforms. Optimus EMR contributes a cloud-based EHR system for skilled nursing and long-term care facilities, while HealthMEDX focuses on EHR solutions specifically for skilled nursing and long-term care providers. Collectively, these firms illustrate a competitive landscape in which domain specialization, reimbursement tooling, and workflow automation are becoming central to market positioning.
Recent developments reinforce that trajectory. In February 2026, WellSky expanded SkySense AI into Long-Term Care and Skilled Nursing Facilities, embedding AI capabilities within the Long-Term Care EHR to improve operational efficiency, documentation quality, and clinician productivity. In March 2026, PointClickCare launched a next-generation EHR for practice groups, integrating AI-driven workflows such as Ambient Scribe to streamline senior care documentation and reduce administrative burden. These moves are not isolated product updates; they reflect a broader industry push to use AI and automation to address documentation fatigue, compliance complexity, and reimbursement accuracy simultaneously.
For organizations evaluating the market, the strategic takeaway is that vendor selection increasingly depends on how well a platform integrates compliance support, reimbursement functionality, and clinician-facing efficiency tools into a single operating environment. The full research report profiles these competitive dynamics in greater depth, including capability comparisons and strategic implications for buyers, investors, and incumbent vendors. The detailed assessments are available through the complete study, where they can be used to support due diligence and procurement decisions.
Regulatory Pressure and the Reimburse-to-Compliance Nexus
One of the defining themes of the current market cycle is the convergence of reimbursement mechanics and compliance obligations. Long-term care software is no longer evaluated solely on usability or record-keeping fidelity; it is assessed on its capacity to support accurate case-mix capture, adapt to coding changes, and maintain audit-ready documentation under evolving regulatory expectations. This is why regulatory developments must be treated as market drivers rather than background noise.
The FY 2026 PDPM ICD-10 mapping changes are particularly significant because they alter the coding foundation used for reimbursement calculations and MDS/RAI workflows. Software platforms that can accommodate mapping updates efficiently, reduce manual rework, and preserve reimbursement accuracy gain a direct operational advantage. Similarly, the FY 2026 Skilled Nursing Facility PPS Final Rule’s updates to quality reporting and case-mix requirements raise the compliance bar for software vendors and the organizations that depend on them. In practice, this means that long-term care software must support not only day-to-day clinical workflows, but also the reporting and documentation structures that determine payment and regulatory standing.
At the same time, the HIPAA Security Rule amendments effective in 2026 add another layer of operational responsibility. The requirement for 72-hour breach reporting and biannual vulnerability scanning places greater emphasis on security governance within in-scope EHR platforms. For providers, this creates a dual mandate: systems must enable efficient care and reimbursement workflows while also meeting heightened security and monitoring expectations. The market research accounts for these pressures by analyzing how software capabilities align with compliance risk, implementation burden, and long-term total cost of ownership. Detailed regulatory impact analysis and its implications for procurement timing are included in the full study.
Strategic Takeaways for Executives and Investors
For leaders operating in or around the long-term care software market, the research supports several high-level strategic conclusions. First, the market’s growth trajectory indicates that digital transformation in post-acute and senior care is moving from adoption to maturation. Organizations that delay integration, standardization, or vendor consolidation may find themselves carrying higher administrative costs and greater compliance exposure over time. Second, reimbursement-linked functionality is becoming a primary differentiator. Platforms that strengthen MDS/RAI accuracy, case-mix optimization, and billing efficiency are well positioned because they directly affect revenue integrity and operational predictability.
Third, AI-enabled documentation and workflow tools are shifting from innovation narratives to practical expectations. Recent product launches from major vendors show that the market is beginning to reward systems that reduce administrative load, improve documentation quality, and support clinician productivity without compromising compliance. Fourth, the competitive field’s concentration suggests that strategic buyers should evaluate not only current capabilities, but also the likely direction of platform consolidation, integration ecosystems, and post-acquisition product roadmaps. These considerations have direct bearing on procurement strategy, contract negotiation, and long-term planning.
Finally, the research underscores that market intelligence in this sector must be both broad and precise. Executives need a clear view of overall momentum while still being able to interrogate the specific segmentation and regional dynamics that shape local demand and vendor positioning. The full PW Consulting report is structured to provide that balance, preserving the macro narrative while making deeper data available for detailed analysis and internal modeling.
Accessing the Full Intelligence Set
This executive brief has outlined the strategic direction of the Long-term Care Software Market, the regulatory forces shaping demand, the competitive dynamics among leading platforms, and the practical decision-making value embedded in the research. To move from directional insight to precise planning, organizations need access to the complete market study, where detailed segmentation values, regional distributions, application-level demand patterns, and vendor-level assessments are presented in full. Those deeper figures, including region-specific market sizes, type-based revenue splits, and application-driven breakdowns, are available through the full research portal and can be aligned with internal forecasting models, procurement timelines, and investment theses.
For teams preparing decisions in 2026, the market is sending a clear message: long-term care software is now central to compliance resilience, reimbursement performance, and clinician workflow sustainability. The organizations that act on that message with disciplined analysis will be best positioned to navigate the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Long-term Care Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intranasal Drug Delivery Market to Hit $3.4B by 2032 at 8.98% CAGR
By PW Consulting, 2026-09-07
The Strategic Imperative: Navigating the Intranasal Drug Delivery Devices Market in 2026
The pharmaceutical landscape is undergoing a profound transformation, driven by the need for patient-centric administration routes that balance efficacy, compliance, and speed of onset. Among these, intranasal drug delivery has emerged as a critical modality, bridging the gap between systemic treatment and direct nose-to-brain pathways. As we stand in 2026, the market for intranasal drug delivery devices is not merely growing; it is evolving in complexity, demanding strategic foresight from stakeholders across the value chain. This article serves as a precursor to PW Consulting's comprehensive market research report, designed to equip executive teams, R&D directors, and investors with the analytical framework necessary to capitalize on the opportunities defining this sector.
Preclinical Toxicology Service Market
Understanding the trajectory of this market requires more than a superficial glance at headline figures. It demands a nuanced appreciation of how technological innovation, regulatory shifts, and clinical adoption patterns converge to create value. PW Consulting's latest study offers a deep dive into these dynamics, providing the intelligence needed to make informed decisions in a competitive environment. The following analysis highlights the strategic dimensions of the market and outlines the operational insights contained within our full report.
Car First Aid Kit Market
Market Trajectory and Growth Dynamics
The financial trajectory of the intranasal drug delivery devices market reflects a robust compound annual growth rate, signaling sustained investor and developer confidence. Based on historical data spanning from 2020 through 2025, the market has demonstrated consistent expansion, moving from a baseline position of approximately 1,224.29 million USD to reach an estimated 1,882.0 million USD in 2025. This historical performance sets a strong foundation for the forecast period extending through 2032.
Power Data Loggers Market
Looking forward, the market is projected to accelerate, with the overall revenue expected to climb significantly by the end of the forecast horizon. The growth rate, quantified at a CAGR of 8.98 percent, indicates that the sector is outpacing many traditional pharmaceutical delivery segments. This expansion is fueled by the increasing prevalence of chronic conditions requiring rapid intervention, such as migraine and seizure disorders, alongside the expanding utility of nasal delivery for vaccines and opioid reversal agents.
For strategic planners, this growth rate suggests a widening total addressable market. However, raw growth figures only tell part of the story. The value creation is distributed unevenly across different device types, therapeutic applications, and geographic regions. Our report dissects these macro trends to reveal where value is being generated most efficiently, allowing companies to prioritize high-yield segments without exposing sensitive granular data prematurely. The shift from early-stage adoption to mainstream integration is evident, particularly as key regulatory milestones pave the way for broader commercial deployment of intranasal systems.
Technological Segmentation and Device Innovation
The intranasal delivery ecosystem is characterized by a diverse array of device architectures, each tailored to specific formulation requirements and clinical use cases. The market is broadly segmented into distinct system types, including multi-dose systems, unit-dose systems, and other specialized configurations. Multi-dose systems currently represent a significant portion of the market landscape, favored for their cost-efficiency and convenience in chronic management scenarios. Unit-dose systems, conversely, are gaining traction in emergency and acute care settings where precise, single-use administration is critical.
Beyond the dosing architecture, the technology landscape is defined by the mechanical and physical delivery mechanisms. Manufacturers are increasingly focusing on spray pumps, mucosal atomization devices, and dry powder inhalers. Each technology offers distinct advantages regarding drug deposition, particle size distribution, and ease of use. For instance, atomization technology has proven vital for mucosal delivery where rapid absorption is required, while dry powder systems are opening new avenues for biologic stability and nose-to-brain targeting.
PW Consulting's analysis delves into the technical specifications and performance metrics of these device categories. We evaluate the trade-offs between usability, dosing accuracy, and manufacturing complexity. This technical granularity is essential for pharmaceutical partners selecting a delivery platform for their drug candidates and for device manufacturers seeking to differentiate their portfolios. The report provides a comparative assessment of leading technologies, highlighting the innovation curves that will define competitive advantage over the next decade.
Therapeutic Applications and Clinical Drivers
The demand for intranasal drug delivery is inextricably linked to the therapeutic areas it serves. The market is segmented across a range of clinical indications, each with its own growth dynamics and adoption barriers. Allergy and nasal conditions remain a foundational segment, leveraging the established convenience of nasal sprays for local treatment. However, the most dynamic growth is occurring in systemic and central nervous system applications.
Migraine rescue represents a high-value segment, driven by the need for rapid onset of action that oral formulations often cannot match. Similarly, the use of intranasal devices for opioid overdose reversal has gained critical importance in public health strategies, necessitating reliable and accessible delivery mechanisms. Beyond these acute interventions, the market is seeing exploration in CNS and psychiatric applications, where the potential for nose-to-brain delivery offers a promising route to bypass the blood-brain barrier.
Other significant areas include seizure rescue, where speed is paramount, and the emerging field of nasal vaccines, which presents novel opportunities for immunization campaigns. The report provides a detailed mapping of these applications, analyzing the clinical evidence supporting device adoption and the commercial potential of each indication. By understanding the specific drivers and constraints within each therapeutic area, stakeholders can align their development pipelines with the segments offering the highest return on investment.
Competitive Landscape and Strategic Positioning
The competitive environment in the intranasal drug delivery devices market is defined by a mix of established device manufacturers and specialized players with deep technical expertise. Market concentration metrics indicate a moderately consolidated landscape, with the top players commanding significant market share. This concentration underscores the importance of scale, regulatory experience, and proprietary technology in securing a leading position.
Aptar Pharma stands out as a leading manufacturer with a comprehensive portfolio encompassing single-dose, two-dose, and multi-dose nasal spray pumps for both liquid and powder formulations. Their ongoing engagement in clinical trials, such as the recent utilization of their delivery system in a Phase II study for the SPONTAN nasal spray, highlights their role in advancing novel therapies. Similarly, Teleflex provides essential tools like the MAD Nasal Intranasal Mucosal Atomization Device, serving critical care and emergency settings.
European manufacturers also play a pivotal role. Bespak specializes in nasal drug-device combinations, including multi-dose aqueous sprays and unit-dose NasaDose systems. Nemera offers innovative platforms such as DryPowder and DriDose, expanding capabilities for nose-to-brain applications and forming new partnerships to broaden their portfolio. In the CDMO space, Hovione has emerged as an integrated partner offering API-to-device solutions, including single-use nasal dry powder devices, with recent announcements regarding commercial partnership availability.
Other key contributors include Silgan Dispensing, known for systems like the Gemini BE Nasal Pump and Monodose systems, and Kindeva Drug Delivery, which supports nasal MDI and spray combination products. Aero Pump continues to provide precision spray pumps for specialized applications. The landscape is further dynamic with new entrants and product launches, such as Zeteo Biomedical's introduction of ZTech-P Cygnus devices for precise metered-unit dosing of dry powder drugs and biologics.
Our report includes detailed company profiles, analyzing the strategic initiatives, recent developments, and market positioning of these key players. We examine how partnerships, platform expansions, and clinical validations are reshaping the competitive hierarchy. For instance, recent collaborations, such as the partnership between Nemera and Therakind to expand the DriDose platform, illustrate the trend toward ecosystem building and technology licensing. Understanding these moves is crucial for benchmarking and identifying potential partners or acquisition targets.
Regulatory and Reimbursement Ecosystem
Navigating the regulatory environment is a prerequisite for market entry and success. The classification and clearance pathways for intranasal devices significantly influence development timelines and costs. Devices for intranasal drug delivery are often classified under specific regulatory frameworks, with many falling under Class I categorization with 510(k) exemption in certain cases. However, the regulatory landscape is nuanced, with the FDA having approved multiple devices and systems under 510(k) clearance, including nasal spray pumps and mucosal atomizers.
Recent approvals and labeling updates further illustrate the evolving regulatory stance. Updated labeling for products such as epinephrine nasal sprays and naloxone nasal spray configurations signals increased acceptance and standardization of intranasal modalities. These regulatory milestones reduce uncertainty and encourage investment in device development. Nevertheless, manufacturers must remain vigilant about compliance requirements and classification nuances, which can vary based on device functionality and intended use.
Reimbursement policies constitute another critical pillar of market viability. In the United States, reimbursement policies for intranasal drug delivery devices are supported for approved nasal spray products and devices used in clinical settings. This support helps drive adoption in healthcare facilities and encourages prescription by clinicians. However, reimbursement dynamics can be complex, involving payer negotiations and coverage determinations that vary by indication and device type. Our analysis explores the reimbursement landscape, identifying the policy drivers that facilitate market access and the gaps that may pose challenges for new entrants.
Strategic Recommendations for 2026 Decision Makers
As we move through 2026, the strategic priorities for companies operating in this market must be aligned with the evolving realities of the sector. First, technological differentiation is paramount. With a robust growth rate and increasing competition, relying on commoditized device designs will erode margins and market position. Investment in novel delivery mechanisms, such as advanced dry powder systems or precision atomizers, offers a pathway to value creation. Companies should evaluate their R&D pipelines against the emerging needs of therapeutic areas like nose-to-brain delivery and biologic stabilization.
Second, strategic partnerships will be a key enabler of growth. The ecosystem is characterized by collaborations between device manufacturers, CDMOs, and pharmaceutical developers. Access to integrated platforms that offer API-to-device solutions can accelerate development cycles and reduce time-to-market. For device manufacturers, forming alliances with innovators in high-growth therapeutic segments can secure volume commitments and expand reach. For pharmaceutical companies, selecting a delivery partner with a proven track record and regulatory expertise is essential to mitigate development risk.
Third, market entry strategies must be informed by a detailed understanding of regional dynamics and concentration trends. While certain regions currently dominate in terms of revenue, emerging markets present untapped potential. Companies should assess the relative attractiveness of different geographies, considering factors such as regulatory maturity, reimbursement infrastructure, and local competitive intensity. The report provides the geographic intelligence needed to prioritize expansion efforts effectively.
Finally, keeping abreast of regulatory changes is non-negotiable. The FDA's ongoing approvals and labeling updates create opportunities for devices that align with current standards. Companies must proactively engage with regulatory bodies and monitor classification databases to ensure their products remain compliant and competitive. The report includes a comprehensive review of the regulatory environment, offering actionable insights for navigating approvals and maintaining market access.
Conclusion: Access the Full Intelligence
The intranasal drug delivery devices market represents a convergence of innovation, clinical need, and growth potential. The data indicates a strong upward trajectory, supported by a CAGR that outperforms many adjacent sectors and a broadening scope of therapeutic applications. However, capturing the value within this market requires more than a general understanding of growth trends. It demands precise, actionable insights into segmentation dynamics, competitive maneuvers, technological benchmarks, and regulatory pathways.
PW Consulting's full market research report offers a definitive resource for stakeholders seeking to navigate this complex landscape. The study provides detailed segmentation analysis, comprehensive company profiles, and forward-looking strategic assessments that go beyond the high-level overview presented here. By accessing the complete report, decision makers can obtain the granular intelligence necessary to formulate robust strategies, identify partnership opportunities, and optimize investment decisions for the forecast period through 2032.
To secure the competitive edge required in 2026 and beyond, we invite you to explore the full depth of our analysis. The detailed market size projections, segmentation splits, and competitive intelligence contained within the report are designed to support your strategic planning with accuracy and depth. Visit our source webpage to access the complete market intelligence and empower your organization with the insights needed to lead in the intranasal drug delivery devices market.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


