



PW Consulting: Cs Beam and Hydrogen Maser Market Hits $40M in 2025, 6.98% CAGR to 2032
By PW Consulting, 2026-09-07
The Precision Imperative: Strategic Intelligence for the Caesium Beam and Hydrogen Maser Atomic Clocks Market 2026–2032
In an era defined by satellite navigation dependency, deep-space exploration, and resilient infrastructure, atomic timing has graduated from a niche metrology concern to a boardroom-critical strategic asset. The global Caesium Beam and Hydrogen Maser Atomic Clocks market is undergoing a structural shift, driven by sovereign PNT (Positioning, Navigation, and Timing) mandates, GNSS disruption threats, and the insatiable demand for microsecond stability across telecommunications, data center synchronization, and spaceborne ensembles. This introduction to our latest market research exposition distills the strategic contours of the 2026–2032 landscape, equipping executives with the analytical framework required to navigate a market poised for sustained expansion. All macroeconomic trajectories, competitive dynamics, and operational insights referenced herein are drawn from our comprehensive study; granular regional breakdowns, application-level revenue splits, and detailed sensitivity matrices are reserved for the full report, available at the source page.
System IP Market
Market Sizing and Growth Trajectory: A Decade of Measured Expansion
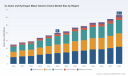
The market has demonstrated consistent, compounding growth from 2020 through the base year 2025, with revenue advancing from 25.0 million USD to 40.0 million USD. This trajectory reflects a maturing ecosystem where legacy frequency standards are being complemented—and in critical applications, superseded—by next-generation hydrogen maser and optical cesium beam architectures that deliver enhanced short-term stability, extended operational lifespans, and sovereign deployment compatibility. Looking forward, our forecast period from 2026 through 2032 projects the market to reach 63.1 million USD, anchored by a compound annual growth rate of 6.98 percent. This growth profile is not merely a function of incremental adoption; it is underpinned by structural catalysts including new manufacturing capacity, space mission deployments, standardization milestones, and the accelerating integration of primary reference clocks into defense, telecom, and utility networks that cannot tolerate GNSS outages.
Military Command and Control System Market
The growth cadence across the forecast window is particularly instructive for capital allocation and product roadmap planning. Revenue stepping from 42.06 million USD in 2026 to 46.89 million USD in 2027, then progressing through 48.89 million USD in 2028 and 53.1 million USD in 2029, signals an acceleration phase as facility expansions come online and deployment cycles mature. By 2030, the market is projected to approach 53.85 million USD, followed by 58.01 million USD in 2031 and 63.1 million USD in 2032. This arc indicates that demand is not flat or speculative; it is being pulled by concrete infrastructure modernization programs and the certification of new primary frequency references that recalibrate national metrology baselines. Decision-makers evaluating timing investments should align procurement cycles, capacity planning, and partnership strategies with this underlying momentum rather than treating atomic clocks as commoditized spare-parts purchases.
Food Chain Management Software Market
Competitive Dynamics: A Concentrated Arena with Differentiated Technology Plays
The competitive landscape is moderately concentrated, with the top three firms capturing approximately 40 percent of market revenue and the top five collectively accounting for around 50 percent. This concentration coexists with meaningful differentiation in product architecture, deployment footprint, and strategic positioning. Leading players are not competing solely on price; they are competing on frequency stability, holdover performance, lifecycle durability, certification alignment, and sovereign supply-chain resilience.
Microchip Technology Inc., headquartered in Chandler, Arizona, manufactures the 5071B cesium beam frequency standard and MHM-2020 active hydrogen maser atomic clocks, serving metrology, telecommunications, and satellite applications with accuracies as low as 5x10^-13. In April 2026, Microchip opened a new manufacturing facility in Tuscaloosa, Alabama, dedicated to the MHM-2020 active hydrogen maser, explicitly aimed at increasing production capacity and reducing lead times amid rising demand for independent timing systems. For organizations relying on resilient timing, this facility expansion signals a tangible shift toward scalable, domestically grounded maser production that can support national infrastructure protection against GNSS disruptions.
Oscilloquartz SA, based in Neuchâtel, Switzerland, produces optical cesium beam atomic clocks through the OSA 3230 series and hydrogen maser solutions with enhanced short-term stability via the ESTU module, targeting telecom, defense, and precision timing applications. Its technology footprint emphasizes stability enhancements that close the historical gap between cesium beam and hydrogen maser performance in short-term metrics—an increasingly relevant consideration for synchronization in data centers and critical infrastructure.
Safran Electronics & Defense, headquartered in Paris, France, develops and supplies the Space Hydrogen Maser (SHM) and cesium beam systems, with deployments tied to the ESA ACES mission for spaceborne atomic clock ensembles. In April 2025, the SHM powered the ESA ACES atomic clock ensemble aboard the ISS, achieving record stability for global timekeeping and deep-space applications. Later, in September 2025, an all-European Maser active hydrogen maser was deployed at the ESA New Norcia deep-space ground station in Australia, marking the first fully European ultra-precise maser operation for interplanetary missions. These milestones illustrate how space-grade maser technology is extending its reach from orbital ensembles to ground-based deep-space tracking, reinforcing sovereign timing capabilities and GNSS resilience.
Adtran Inc., headquartered in Huntsville, Alabama, provides Oscilloquartz optical cesium beam clocks with the ESTU module for enhanced stability, targeting data centers, power utilities, and defense PNT applications. In June 2025, Adtran launched the Oscilloquartz OSA 3200 SP and OSA 3250 enhanced primary reference clocks, which are cost-effective optical cesium beam solutions designed with a 10-year lifespan and improved holdover for telecom and infrastructure modernization. This product progression demonstrates how optical cesium beam architectures are being engineered to deliver hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems at a point on the value curve that broadens deployment eligibility.
- Microchip reinforces domestic maser capacity and lead-time reduction to meet independent timing demand.
- Oscilloquartz advances ESTU-enabled short-term stability across both cesium beam and maser lines.
- Safran anchors spaceborne and ground-station maser deployments for sovereign deep-space and GNSS resilience.
- Adtran accelerates optical cesium beam adoption in data centers, utilities, and defense with extended-lifespan, holdover-optimized designs.
Structural Shifts and Regulatory Catalysts
The market is being reshaped by a confluence of standardization, certification, and component-level developments that alter both the competitive baseline and the deployment economics of atomic timing. The certification of the NIST-F4 cesium fountain atomic clock as the new U.S. primary frequency standard in April 2025 represents a pivotal calibration reference for UTC traceability and metrology applications. By calibrating against hydrogen masers and replacing legacy HP 5071A models in national metrology labs, this standard elevates the performance bar and aligns metrological expectations with next-generation stability requirements. For commercial and defense buyers, such national standard shifts cascade into procurement specifications, calibration protocols, and compliance expectations.
On the component and capability side, the ESA ACES mission selection of Safran's Space Hydrogen Maser in April 2025 underscores the strategic premium placed on exceptional short-term frequency stability for spaceborne applications. Simultaneously, the September 2025 deployment of the all-European Maser at ESA New Norcia for sovereign deep-space tracking and GNSS resilience signals a policy-aligned push toward independent, ultra-precise maser operations beyond orbital missions. In parallel, Adtran's June 2025 launch of Oscilloquartz optical cesium beam clocks with the ESTU module offers hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems, broadening the palette of viable options where total cost of ownership and deployment practicality intersect with stability mandates.
These developments are not isolated events; they collectively define the market dynamics that executives must internalize. Standardization recalibrates the reference frame. Space missions and ground stations expand the application frontier. Component-level innovations narrow performance gaps between cesium beam and hydrogen maser families, enabling more flexible procurement strategies. Organizations that treat these as background noise risk misaligning their timing architectures with the evolving performance, compliance, and sovereignty criteria that now shape purchasing decisions.
Where Precision Meets Deployment: Applications and End-Market Pull
Although detailed application splits and regional magnitudes are intentionally reserved for the full report to preserve the granularity of our commercial intelligence, the directional pull across end markets is unmistakable. Telecommunications and data centers continue to anchor steady demand for primary reference clocks that sustain synchronization, reduce jitter, and support 5G and next-generation network architectures. Power utilities are integrating precision timing into grid synchronization, protection relaying, and phasor measurement under programs that prioritize resilience against timing disruptions. Defense and PNT applications are expanding as sovereign capability programs prioritize independent timing sources that can maintain operational continuity when GNSS signals are degraded or denied.
In the space domain, hydrogen maser and cesium beam systems are increasingly embedded in orbital ensembles, interplanetary tracking, and ground-station operations. The record-stability outcomes associated with recent ESA missions and the establishment of fully European maser operations at deep-space ground locations illustrate how space-grade timing is becoming integral to global timekeeping and deep-space mission architectures. These applications are not merely analytical curiosities; they represent durable demand vectors that interact with national research priorities, international partnership frameworks, and long-duration asset deployment cycles.
From a strategic standpoint, the convergence of telecom modernization, utility resilience, defense PNT mandates, and spaceborne timing creates a multi-vector demand environment. Buyers are less interested in clock instruments as standalone devices and more focused on integrated timing solutions that deliver stability, holdover, lifecycle durability, certification alignment, and supply assurance. That shift in buying logic has direct implications for product strategy, channel partnerships, and service-level definitions.
Strategic Implications for 2026 Decision-Makers
For executives steering capital allocation, R&D roadmaps, procurement strategies, and supply-chain resilience initiatives, the 2026 outlook for the Caesium Beam and Hydrogen Maser Atomic Clocks market carries several actionable implications. First, the projected 6.98 percent CAGR and the 63.1 million USD endpoint in 2032 indicate that timing is a growing, not stagnant, category. Organizations should plan for sustained procurement and integration activity rather than treating atomic clocks as static, one-time purchases.
Second, the concentration profile—approximately 40 percent for the top three and 50 percent for the top five—suggests that supplier selection has outsized impact on performance, lead times, and continuity. Given recent capacity expansions, product launches, and mission deployments, the field is evolving quickly. Strategic buyers should assess not only nominal specifications but also manufacturing readiness, calibration alignment, holdover characteristics, and the supplier's track record in mission-critical and sovereign deployments.
Third, the certification and standardization momentum—exemplified by the U.S. primary frequency standard update and ESA mission and ground-station maser deployments—means that compliance and traceability considerations are becoming more stringent and more consequential. Aligning internal specifications with evolving national and international references can reduce integration risk and improve the longevity of timing investments.
Fourth, the narrowing performance gap between optical cesium beam designs with enhanced modules and hydrogen maser architectures expands the decision space. Where short-term stability and holdover are paramount, hydrogen masers remain compelling; where cost-effectiveness, lifecycle duration, and deployment practicality are equally weighted, advanced cesium beam solutions merit serious evaluation. The strategic task is not to default to one technology family but to match architecture to application criticality, operating environment, and total cost of ownership.
Finally, sovereign infrastructure protection against GNSS disruptions is becoming a decisive demand driver. Capacity expansions dedicated to active hydrogen maser production, all-European maser deployments for deep-space tracking, and enhanced primary reference clocks tailored to defense and telecom PNT systems collectively indicate that timing independence is moving from a technical aspiration to a procurement priority. Organizations that anticipate this shift—by securing supply, validating holdover performance, and mapping timing dependencies across critical operations—will be better positioned to maintain continuity as the external timing environment becomes more contested and more regulated.
What the Full Study Delivers
This introduction is deliberately the strategic trailer: it establishes the market's growth arc, competitive concentration, technology differentiation, and regulatory catalysts, while preserving the deeper quantification and segmentation for the full research. The complete study unpacks operational intelligence that cannot be responsibly summarized without diluting its decision value. Among the elements covered in depth are demand drivers, restraints, and opportunities; segment-level dynamics across technology types, including Caesium Beam Atomic Clocks and Hydrogen Maser Atomic Clocks; regional market structures across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa; country-level demand contexts; competitive positioning, market share estimates, and company profiles; and detailed recent developments and strategic developments that map the sequence of product launches, facility expansions, space mission deployments, ground-station operations, and certifications shaping the market.
The report also integrates regulatory and standardization context, raw material and component considerations, and application-oriented demand narratives that tie timing performance to real-world operational outcomes in telecom, data centers, power utilities, defense PNT, and spaceborne ensembles. For analysts and executives, the value lies not only in the numbers but in the connective tissue: how capacity expansions interact with lead times, how certification changes cascade into procurement specs, how space missions and ground stations extend the application frontier, and how enhanced cesium beam modules alter the cost-stability trade-off landscape.
Closing Perspective
The Caesium Beam and Hydrogen Maser Atomic Clocks market is entering a phase where precision, sovereignty, and resilience converge. From 2020 through 2025, the market advanced from 25.0 million USD to 40.0 million USD; from 2026 through 2032, it is projected to reach 63.1 million USD at a 6.98 percent CAGR. These figures are more than indicators; they are signals of structural demand reinforced by facility expansions, space mission deployments, ground-station operations, and primary frequency standard certifications. The competitive arena is concentrated enough to matter and differentiated enough to reward careful architecture selection. The strategic question for 2026 is not whether atomic timing matters, but how organizations will align their timing investments with the performance, compliance, and continuity requirements now taking shape.
To access the full dataset, segmentation detail, regional and application-level intelligence, competitive estimates, and the complete chronology of strategic developments that underpin these conclusions, request the complete market research at the source page. The executive summary provided here is designed to help you evaluate the study's relevance to your planning cycle; the full report is designed to help you act on it with precision.
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: POCT Market Hits $215M in 2025, Projected 8.5% CAGR to $378M by 2032
By PW Consulting, 2026-09-07
Executive Preview: Why the 2026 POCT Market Landscape Demands a New Strategic Playbook
The global healthcare ecosystem is undergoing a structural shift. Care delivery is moving away from centralized laboratories and into decentralized environments, driven by patient demand for immediacy, the need for operational efficiency in hospital systems, and the lessons learned from recent global health crises. Point-of-Care Testing (POCT) is no longer a niche convenience; it is a foundational pillar of modern diagnostics. For industry leaders, investors, and corporate strategists, understanding the trajectory of this market is not merely about observing growth; it is about securing competitive advantage in a sector defined by rapid technological evolution and tightening regulatory frameworks.
Tech Career Accelerator Market
PW Consulting is pleased to release our latest comprehensive market research report, designed specifically to guide enterprise decision-making through the forecast period of 2026 to 2032. This document serves as an executive overview of the intelligence contained within the full study. Our goal is to demonstrate the depth of our analysis and the strategic value of this data, while highlighting why immediate access to granular insights is critical for navigating the year ahead.
Worldwide Air Transfer Fire Damper Market
The Macro Trajectory: Sustained Growth Amidst Consolidation
The overarching narrative for the POCT sector is one of resilient expansion. Based on our rigorous analysis of historical data from 2020 through 2025 and our forecasted models extending to 2032, the market demonstrates a robust compound annual growth rate (CAGR) of 8.5%. This growth trajectory signals that despite macroeconomic headwinds and supply chain complexities experienced in the early 2020s, demand for rapid diagnostic solutions remains inelastic and is accelerating.
Automatic Sealing and Packing Machine Market
Our baseline data indicates that the market has recovered from temporary fluctuations observed in 2021 and 2022, establishing a stronger foothold in 2023 and 2024. By the base year of 2025, the market has reached significant revenue milestones. Looking forward, the forecast period projects a steady climb, with revenue units expected to scale substantially by the end of the decade. This is not a linear projection; it is a curve influenced by technological adoption rates, regulatory approvals, and shifting care models. Understanding the specific inflection points where investment yields the highest return requires looking beyond the aggregate numbers. The full report details the revenue units measured in USD Millions across the entire forecast horizon, providing the financial clarity needed for budget allocation and market entry strategies.
Competitive Intelligence: The Moat Is Innovation
The competitive landscape for Point-of-Care Testing is characterized by high concentration. Our analysis of market concentration indicates that the top three players hold a significant portion of the market share, while the top five companies command an even larger majority. This suggests a mature market where scale, portfolio breadth, and regulatory mastery are critical barriers to entry. However, within this consolidated environment, individual strategies are diverging sharply.
Our report provides deep-dive profiles on the key enterprises defining this landscape. Each company is deploying distinct technological architectures to capture value across different testing verticals. To illustrate the strategic variety captured in our analysis, consider the following positioning among leading contenders:
- Abbott Laboratories continues to leverage its integrated ecosystem approach. Their strategy focuses on versatile platforms capable of handling multiple diagnostic requirements. Key offerings analyzed in the report include the i-STAT system for comprehensive blood analysis, the ID NOW rapid molecular platform for infectious diagnostics, and the Alinity i system which targets cardiac, infectious, and metabolic markers. Their strength lies in the breadth of coverage within a single infrastructure.
- F. Hoffmann-La Roche Ltd maintains a strong position through molecular innovation. Their recent focus has been on expanding the utility of the cobas liat system. This platform is designed for specific molecular tests, including sexually transmitted infections (STIs) and other panels that enable rapid, multi-target POCT directly at point-of-care sites. Their strategy emphasizes regulatory progress and clinical utility in specialized care settings.
- Siemens Healthineers AG differentiates through high-throughput and comprehensive solutioning. Their portfolio covers blood gas, cardiac, and routine testing. A key element of their competitive edge involves high-throughput analyzers that bridge the gap between traditional laboratory capabilities and rapid bedside needs, appealing to larger healthcare systems seeking efficiency without sacrificing volume capacity.
- Danaher Corporation operates through multiple enabling subsidiaries. Their exposure in the POCT market includes the Cepheid GeneXpert and Beckman Coulter platforms. These assets cover molecular and immunoassay POCT, allowing Danaher to serve diverse clinical needs ranging from complex molecular diagnostics to standard immunoassays.
- QuidelOrtho Corporation focuses on fluorescence and lateral flow technologies. Their offerings include Sofia fluorescent analyzers and QuickVue lateral flow tests, which are staples for rapid immunoassay POCT. Their recent corporate activity suggests a strategy of consolidating respiratory testing capabilities to streamline their product lines.
- Becton, Dickinson and Company (BD) provides robust diagnostic platforms including the Veritor system. Their portfolio encompasses both molecular and immunoassay tests designed for rapid point-of-care diagnostic platforms. Their recent regulatory clearances highlight a focus on maintaining compliance with evolving health authority standards while updating legacy tools.
- bioMérieux SA specializes in rapid molecular and automated solutions. Their systems, such as BIOFIRE and VITEK 2, are critical for rapid identification and antibiotic stewardship. Their value proposition centers on speed and accuracy in microbial identification, which is crucial for infection control protocols.
- Thermo Fisher Scientific Inc. rounds out the key competitive set with rapid diagnostic and molecular test solutions. They focus heavily on infectious diseases and clinical POCT, leveraging their broader life sciences infrastructure to support scaling and distribution of diagnostic tools.
These summaries represent only the surface of our competitive analysis. The full report goes further, analyzing supply chain resilience, R&D pipelines, and partnership networks that are not visible in public profile summaries. Understanding how these companies interact, compete, and potentially collaborate is essential for anyone evaluating M&A targets or benchmark comparisons.
Regulatory Dynamics and Technological Shifts
Strategy in the POCT market cannot be divorced from the regulatory environment. Our report dedicates significant attention to the policy shifts that will impact market access and reimbursement through 2032. The regulatory landscape is becoming more stringent, requiring companies to adapt their quality assurance and performance validation processes.
Recent developments provide a clear signal of this tightening environment. For instance, updated CLIA regulatory requirements for point-of-care testing went fully into effect recently, bringing enhanced proficiency testing requirements. Specifically, performance ranges for analytes like hemoglobin A1C have been tightened to within a +/-8% performance range. This change directly impacts device manufacturers and healthcare providers, necessitating re-validation of existing workflows and potentially favoring platforms with higher inherent precision.
Simultaneously, product-specific approvals are reshaping market access. In early 2025, Roche received FDA clearance with a CLIA waiver for cobas liat STI multiplex panels for point-of-care use. This marks a significant expansion of molecular testing capabilities outside of traditional lab settings. Later in the year, BD secured FDA 510(k) clearance for the BD Veritor System for SARS-CoV-2 rapid point-of-care COVID-19 testing, replacing the previous EUA version. This transition from emergency use authorization to full clearance indicates a normalization of pandemic-related diagnostics into standard care protocols.
Corporate maneuvers also reflect these dynamics. QuidelOrtho announced an intent to acquire LEX Diagnostics pending U.S. FDA clearance for its VELO respiratory POCT system, with plans to discontinue the Savanna platform. This suggests a strategic pivot toward specific respiratory assets while streamlining older technologies. Meanwhile, industry participants like SEKISUI Diagnostics launched new rapid diagnostic tools for RSV detection in professional healthcare settings, indicating broad-based innovation across smaller and mid-sized players.
Our full analysis dissectess how these regulatory and corporate events cascade through the market, affecting time-to-market for new entrants and creating windows of opportunity for incumbents with established compliance infrastructures.
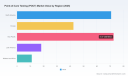
The operational application of POCT is split across distinct care settings, each with unique purchasing drivers. Our segmentation analysis identifies three primary application zones: Hospital Bedside, Physician Office, and Home Self-testing. Historical data shows that Hospital Bedside usage commands the highest volume, reflecting the need for immediate results in acute care scenarios. Physician Offices represent a stable channel driven by routine screening and chronic disease management. Home Self-testing has emerged as a transformative segment, accelerated by consumer comfort with self-administered diagnostics.
Similarly, test types are divided into critical categories. Glucose Monitoring remains a foundational pillar supporting chronic disease management. Infectious Disease Testing continues to drive volume due to ongoing surveillance needs and the permanent integration of rapid tests into respiratory care protocols. Cardiometabolic Testing is gaining traction as integrated health platforms seek to combine cardiac and metabolic markers in single rapid visits. Other specialized testing categories round out the portfolio, often serving niche high-value needs.
In terms of geographic distribution, the market is global but exhibits distinct regional maturity levels. North America, Europe, and Asia Pacific represent major revenue contributors, with specific dynamics influencing growth in each territory. Latin America and the Mideast and Africa regions present emerging opportunities where infrastructure development and public health initiatives are driving adoption.
While these segments are identifiable, the real value lies in understanding the interplay between them. For example, the growth in Home Self-testing may cannibalize Physician Office volumes for certain tests while creating new revenue streams for consumable kits. The full report provides the specific market size evolution for each segment from 2020 through the forecast period, allowing strategists to model cannibalization effects, cross-selling potential, and regional penetration strategies.
Strategic Value for 2026 Decision-Makers
Why is this report essential for your 2026 planning cycle? The POCT market in 2026 is a pivot point. The early growth phase of rapid adoption is maturing into a phase defined by efficiency, regulatory compliance, and targeted innovation. Companies that rely on outdated intelligence will find themselves misaligned with reimbursement trends and regulatory requirements. The insights within our report are designed to mitigate this risk.
Our research offers actionable intelligence for several key strategic functions. For product development teams, the segmentation analysis clarifies which technologies are gaining share and which are plateauing. For commercial leaders, the competitive profiles reveal where competitors are investing and where gaps in the market remain. For financial planners, the historical and forecast revenue data provides the basis for realistic market sizing and investment modeling.
Furthermore, the regulatory analysis included in the study is not just a summary of laws; it is a risk assessment tool. Understanding the implications of CLIA updates, FDA clearance pathways, and international regulatory harmonization helps companies anticipate compliance costs and timeline adjustments. In a market where time-to-market is a critical success factor, this intelligence serves as a strategic buffer against delays.
Unlocking the Full Intelligence
This overview has highlighted the structural trends, key competitors, and regulatory dynamics that define the Point-of-Care Testing market. However, strategic decisions require precision. General trends inform direction, but specific data drives execution. The complete report contains detailed segmentation splits, year-by-year revenue projections, market concentration metrics, and granular analysis of recent developments that are necessary to build robust business cases.
To access the full 2026-2032 forecast, detailed company profiles, and the complete segmentation data referenced in this preview, please visit the PW Consulting report page. Secure your copy of the comprehensive study today to ensure your organization is equipped with the intelligence needed to navigate the evolving POCT landscape.
For detailed analysis of this topic, please visit the official page: Point-of-Care Testing (POCT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: L-Carnitine Market to Reach $307.8M by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for the L-Carnitine Market: Navigating Growth, Compliance, and Competitive Dynamics Through 2032
Executive Overview: Why This Report Matters for 2026 Decision-Making
The global L-Carnitine market stands at a critical inflection point. As manufacturers, investors, and strategic planners prepare for the 2026–2032 forecast period, the intersection of rising consumer demand, tightening regulatory frameworks, and evolving supply chain economics demands a clear, data-grounded view of where value will be created—and where risk will accumulate. Our latest market research delivers precisely that view. Built on a rigorous historical baseline spanning 2020 to 2025 and extended through a seven-year forward projection, this report is designed not as a static snapshot but as an actionable strategic compass.
Worldwide Wedding Car Rental Market
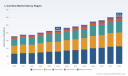
Over the past half-decade, the sector has demonstrated a measured but consistent expansion trajectory. The market closed 2025 at a valuation of 216.4 million USD, building on a compound annual growth rate of 5.2 percent across the historical window. This growth, while steady, masks underlying structural shifts: regional demand rebalancing, grade-level segmentation divergence, and the gradual consolidation of capacity among players who can sustain regulatory compliance and cost-efficient synthesis. The forward projection positions the market at 233.44 million USD in 2026, climbing to 307.8 million USD by 2032. For executives mapping capacity investments, formulation portfolios, or market entry strategies, these figures are not abstract numbers—they are the scaffolding for scenario planning, pricing architecture, and competitive positioning.
Defoamer for Water-Based Ink Market
What separates this research from conventional market summaries is its explicit focus on operational utility. Rather than stopping at top-line valuation, the report dissects the mechanics driving growth: the cost-intensity of fermentation versus chemical synthesis pathways, the pricing pressure exerted by raw material volatility across global supply chains, and the reimbursement and approval landscape that shapes pharmaceutical-grade demand. It also traces how regulatory renewals and residue-level revisions are reallocating market access among suppliers with documented safety verification infrastructure. The result is a document that can be deployed directly in boardroom discussions, product roadmap reviews, and M&A due diligence cycles.
Worldwide Simulation Program with Integrated Circuit Emphasis (SPICE) Market
Market Trajectory and Structural Shifts: What the Data Actually Reveals
Understanding the L-Carnitine market requires moving beyond aggregate figures to the underlying dynamics that will determine profitability and share allocation over the next seven years. The historical record from 2020 through 2025 shows a market that weathered short-term fluctuations while maintaining an upward bias. The 2021 surge to 188.84 million USD gave way to a modest contraction in 2022, followed by a sustained recovery that pushed valuations past the 200 million USD threshold in 2023 and continued upward through 2024 and 2025. This pattern is consistent with a category maturing through cyclical input cost pressures, formulation innovation cycles, and gradual premiumization in application segments.
The forward curve reflects a market that is neither explosive nor stagnant. A 5.2 percent CAGR across the 2026–2032 window indicates that growth will be driven less by raw demand expansion and more by value migration: upward movement in higher-grade formulations, expansion of functional delivery formats, and the gradual integration of L-Carnitine into clinical and specialty nutrition portfolios. For strategic planners, this means that volume growth alone will not guarantee margin expansion. Competitive advantage will increasingly reside in grade optimization, regulatory readiness, and the ability to bundle L-Carnitine into end-product formulations that command pricing power.
Supply-side realities further complicate the growth narrative. L-Carnitine synthesis—whether through fermentation or chemical pathways—remains cost-intensive, and raw material price fluctuations continue to create obstacles for manufacturers operating across global supply chains. These input dynamics do not merely affect unit economics; they shape which players can sustain competitive pricing while maintaining quality thresholds required by pharmaceutical and nutraceutical buyers. Our report maps these cost structures in relation to grade-level segmentation, enabling readers to identify where margin resilience is most attainable and where price competition may compress returns.
On the demand side, the regulatory and reimbursement environment is quietly reshaping application priorities. Health authorities have approved oral and intravenous L-Carnitine formulations for the treatment of primary and secondary carnitine deficiency arising from inborn errors of metabolism. While this clinical pathway represents a specialized demand stream, it signals broader acceptance of L-Carnitine as a therapeutically relevant compound, reinforcing the strategic value of pharmaceutical-grade capacity. Simultaneously, regulatory attention in key export markets has intensified. The EU Commission's enactment of Regulation (EU) 2026/140, which revises Maximum Residue Levels for carnitine derivatives, has concentrated market access among API manufacturers with documented safety verification infrastructure. This is not a marginal compliance issue; it is a structural filter that will determine which suppliers can serve regulated end markets without friction.
Competitive Landscape: Mapping the Players Shaping Market Outcomes
The L-Carnitine market is characterized by a moderately concentrated competitive field, with CR3 and CR5 metrics indicating that the largest players hold meaningful but not dominant share. This structure creates both opportunity and friction: room for differentiated positioning exists, but the barrier to sustained relevance is rising as regulatory, quality, and cost requirements tighten. The report provides detailed profiles of the companies that are actively shaping supply, formulation, and market access across pharmaceutical, nutraceutical, feed, and research channels.
Among the standout entities is Lonza Ltd., headquartered in Basel, Switzerland, which specializes in L-Carnitine production under the Carnipure® brand for pharmaceutical, nutraceutical, and animal feed applications. Lonza's recent regulatory renewal—receiving an EFSA scientific opinion for the authorisation of L-Carnitine and L-Carnitine L-tartrate as feed additives for all animal species in October 2025—illustrates how compliance victories can unlock and protect demand streams across species categories. Biosint S.p.A., based in Italy, produces L-Carnitine as an active pharmaceutical ingredient and feed additive, positioning itself at the intersection of human and animal health supply chains. Northeast Pharmaceutical Group Co., Ltd., operating from Shijiazhuang, Hebei, China, manufactures L-Carnitine and derivatives for pharma and supplement use, reflecting the growing capacity and export orientation of Chinese pharmaceutical-grade producers.
The competitive field also includes specialized suppliers whose positioning underscores the breadth of L-Carnitine applications. Cayman Chemical Co. in Ann Arbor, Michigan, supplies L-Carnitine for research, diagnostics, and nutritional products. Kaiyuan Hengtai Nutrition Co., Ltd. and ChengDa Medicines Co., Ltd., both based in China, produce L-Carnitine for animal nutrition and human health supplements, as well as pharmaceutical and veterinary applications. Huanggang Huayang Medicines Co. Ltd. supplies L-Carnitine for pharma and feed markets, while AdvaCare Pharma USA LLC, headquartered in Cheyenne, Wyoming, offers L-Carnitine in OTC supplements and formulations. On the fine chemical and research side, Tokyo Chemical Industry Co., Ltd. in Tokyo and Merck KGaA in Darmstadt, Germany, provide L-Carnitine for laboratory and industrial applications, and Sigma-Aldrich in Saint Louis, Missouri, distributes and supplies L-Carnitine for research and manufacturing. Together, these players illustrate a market that spans high-purity API supply, formulation-grade ingredients, research reagents, and feed additives—each with distinct quality, compliance, and pricing dynamics.
Recent corporate and regulatory developments reinforce the strategic importance of timing and compliance readiness. Otsuka Pharmaceutical's January 2025 launch of the ENSOLID clinical nutrition formula incorporating L-Carnitine signals how established pharmaceutical and nutrition brands are embedding the compound into differentiated clinical offerings. Combined with the EFSA renewal and the EU Commission's residue-level revision, these events point to a market where regulatory alignment and formulation innovation are becoming primary drivers of share movement. Our report analyzes these developments not as isolated headlines but as indicators of where competitive advantage will be built over the forecast period.
Inside the Report: Operational Tools for Strategy and Execution
This market research is structured to translate macro trends into executable insights. The report moves systematically through the dimensions that matter most to strategic and operational decision-makers, providing frameworks that can be applied directly to capacity planning, market entry evaluation, and competitive positioning.
- Historical and forward valuation trajectories, anchored to a 2025 baseline and extended through 2032, with analysis of the growth drivers behind each phase of the curve.
- Grade-level segmentation analysis covering food, pharmaceutical, and feed grades, with attention to quality thresholds, pricing architectures, and end-market acceptability.
- Application-level demand mapping across dietary supplements, sports nutrition, functional beverages, animal feed, and pharmaceuticals, highlighting where volume concentration and value migration are occurring.
- Regional demand structure analysis that identifies where consumption is scaling, where export flows are redirecting, and where regulatory or logistical factors are reshaping local market dynamics.
- Cost and supply chain diagnostics that examine synthesis pathways, raw material volatility, and the pricing strategies manufacturers are deploying to protect margins.
- Regulatory and compliance tracking, including feed additive authorisations, maximum residue level revisions, and clinical approval pathways that influence market access and product positioning.
- Competitive benchmarking across the companies actively supplying the market, with profiles that clarify each player's grade focus, application coverage, and recent strategic moves.
- Scenario-ready frameworks that enable readers to stress-test investment decisions against alternative growth, regulatory, and cost environments through 2032.
Each section is designed to be referenceable, not merely descriptive. The segmentation analysis, for example, does not simply allocate share; it examines why certain grades and applications are commanding premium positioning, how regulatory filters are altering demand eligibility, and where supply-side constraints are creating pricing opportunities or vulnerabilities. The regional analysis similarly avoids superficial ranking, instead tracing the structural factors—logistics, compliance capacity, formulation adoption, and buyer concentration—that determine where demand is durable versus where it is vulnerable to redistribution.
Strategic Implications for 2026 and Beyond
For executives and planners entering 2026, the L-Carnitine market presents a landscape where growth is real but conditional. The 5.2 percent CAGR and the projected climb toward 307.8 million USD by 2032 indicate a category that will continue to expand, but the distribution of that growth will favor players who can navigate grade-level differentiation, regulatory complexity, and input cost variability simultaneously. The market is not merely growing; it is sorting. Suppliers with robust safety verification infrastructure, documented compliance histories, and flexible synthesis capabilities will find expanding access to regulated and premium application segments. Those without such foundations will face narrowing channels and increasing price pressure.
Several strategic implications merit attention. First, grade-level positioning will increasingly determine margin outcomes. Pharmaceutical and high-purity grades are supported by clinical acceptance and regulatory demand, while food and feed grades depend on cost efficiency and formulation integration. The report's segmentation analysis helps identify where each grade's economics are most favorable and where cross-grade capability can create portfolio resilience. Second, regulatory readiness is becoming a competitive moat. The EU's residue-level revision and the EFSA feed additive renewal demonstrate that compliance is not a back-office function; it is a market access determinant that rewards suppliers who invest in verification infrastructure and documentation discipline. Third, formulation integration is reshaping demand. The launch of clinical nutrition formulas incorporating L-Carnitine, alongside sustained demand across dietary supplements and sports nutrition, indicates that end-product differentiation will increasingly drive ingredient value. Suppliers and formulators who can align grade selection, quality assurance, and regulatory compliance with end-market positioning will capture disproportionate share of the value created.
Finally, the competitive structure of the market—moderately concentrated, with room for differentiated players—means that strategic choices around capacity, partnerships, and geographic focus will have outsized effects on trajectory. The report's company profiles and recent development tracking provide the context needed to evaluate where capacity additions make sense, where regulatory milestones are likely to shift access, and where cost pressures may compress returns for under-prepared entrants.
Accessing the Full Intelligence: What You Will Gain
The overview presented here is intentionally designed to demonstrate the depth and operational relevance of the research while preserving the granular segmentation data, regional revenue distributions, and grade-level revenue figures that form the analytical core of the report. Those details—precise regional valuations, application-level revenue splits, and type-level breakdowns—are essential for building precise investment cases, pricing models, and market entry strategies, and they are available in full within the complete study.
Readers who engage with the full report will gain a comprehensive, decision-ready view of the L-Carnitine market across the 2026–2032 horizon. This includes the exact regional demand structure that reveals where consumption is concentrated and where export dynamics are redirecting flow; the precise type-level and application-level revenue distributions that clarify where value is accruing and where competition is intensifying; and the detailed cost, regulatory, and competitive frameworks needed to translate market direction into execution. The report is built to support capacity investment decisions, formulation portfolio planning, supplier evaluation, and competitive positioning reviews with the specificity that strategic planning requires.
For organizations preparing for 2026 and beyond, the strategic question is not whether the L-Carnitine market will grow, but how to position within its evolving structure to capture durable value. This research provides the evidence base, the analytical frameworks, and the competitive context to answer that question with confidence. The full report delivers the complete data architecture behind this overview—enabling precise, defensible decisions in a market where regulatory alignment, grade-level differentiation, and cost discipline are increasingly the determinants of success.
For detailed analysis of this topic, please visit the official page: L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Capsule Filling Machines Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Capsule Filling Machines Market: Navigating Growth Through 2032
The global pharmaceutical and nutraceutical manufacturing landscape is undergoing a profound transformation, driven by accelerating demand for precise, compliant, and high-throughput encapsulation technologies. As industry leaders confront tightening regulatory frameworks, evolving product formulations, and intensifying competitive pressures, the Capsule Filling Machines Market has emerged as a critical nexus of operational efficiency and strategic investment. This analysis draws from PW Consulting’s latest comprehensive market research to illuminate the structural forces shaping the sector, offer actionable intelligence for 2026 decision-making, and frame the strategic questions that forward-looking organizations must address to secure long-term competitive advantage.
Adhesion Prevention Gel Market
Macro Trajectory and The Architecture of Growth
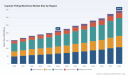
The sector’s historical performance reflects a sustained expansion trajectory. From a baseline valuation of approximately 153.44 million USD in 2020, market revenue climbed steadily through the mid-2020s, reaching 215.0 million USD by 2025. This upward momentum is projected to continue, with the market anticipated to attain 226.24 million USD in 2026 and accelerate toward 344.8 million USD by 2032. The compound annual growth rate of 6.98 percent underscores a moderate yet resilient expansion profile, one that is neither speculative nor saturated, but rather anchored in structural demand drivers across regulated manufacturing ecosystems.
Angular Contact Axial Bearing Market
This growth architecture is not uniform. It is shaped by divergent regional adoption curves, varying capital expenditure cycles, and the gradual migration of production capacity toward markets with expanding domestic pharmaceutical and supplement manufacturing bases. While specific regional revenue contributions and application-level breakdowns are detailed within the full research repository, the overarching narrative is clear: the market is consolidating around mature demand centers while simultaneously cultivating high-growth corridors that reward early-mover capital allocation and localized technical partnerships. Organizations that map their investment horizons to these geographic and application-specific inflection points will be best positioned to capture disproportionate share gains.
Piston Ring Wire Market
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The competitive environment exhibits moderate market concentration, with the top three players collectively commanding approximately 24.6 percent of global revenue and the top five holding roughly 26.2 percent. This fragmented-yet-consolidating structure creates a dynamic arena where scale, technological differentiation, and regulatory compliance capabilities determine market access and pricing power. A diverse cohort of manufacturers operates across this spectrum, each pursuing distinct value propositions tailored to specific production volumes, formulation complexities, and compliance requirements.
European engineering firms continue to anchor the high-end segment, leveraging decades of precision dosing expertise and advanced rotary or suction bowl architectures. One prominent German-based provider offers a flagship capsule filling series optimized for high-volume pharmaceutical and nutraceutical production, emphasizing precision dosing and high throughput. In Italy, multiple manufacturers have established strong footholds by delivering rotary and advanced dosing systems capable of processing up to 200,000 capsules per hour, while others focus on flexible E Series and IN-CAP platforms that accommodate powders, pellets, tablets, mini-tablets, and capsule-in-capsule configurations, all engineered to meet CE and cGMP compliance standards. A separate Italian manufacturer has expanded its automatic capsule filling portfolio with machines specifically engineered for pharmaceutical and supplement production, reinforcing the region’s reputation for high-accuracy encapsulation hardware.
Asia-Pacific and transcontinental players are increasingly shaping the mid-to-high volume segments through integrated solutions that balance operational simplicity, safety, and efficiency. An Indian-headquartered global supplier delivers integrated capsule filling systems tailored for pharmaceutical and nutraceutical applications, emphasizing reliability and streamlined operational workflows. In Japan, a Tokyo-based technology provider delivers encapsulation solutions and capsule filling equipment designed for global pharmaceutical manufacturers, reinforcing the importance of geographic proximity to advanced drug delivery research ecosystems. Meanwhile, United States-based manufacturers contribute to the domestic supply chain with USA-made capsule filling equipment and service capabilities, while a New Jersey-based firm specializes in encapsulation equipment for pharmaceutical and nutraceutical applications.
French and German packaging specialists further diversify the competitive field. A France-based entity under the Lonza Group umbrella specializes in hard capsule filling machines and encapsulation systems focused on advanced drug delivery applications. In Germany, another engineering firm develops high-efficiency capsule filling and packaging systems designed for integrated pharmaceutical production lines. Chinese and hybrid-market manufacturers also play a growing role, with several firms offering semi-automatic and industrial-grade capsule filling machines that bridge manual-automation workflows, alongside laboratory-scale and mass-production units designed for pharmaceutical and supplement manufacturing. These providers continuously refine their product portfolios, as evidenced by recent equipment upgrades aimed at improving precision and efficiency in pharmaceutical manufacturing environments.
2025–2026 Innovation Cycles and Product Lifecycle Acceleration
The past several months have witnessed a noticeable acceleration in product launches and technology showcases, signaling an industry-wide push toward human-centered design, advanced dosing combinations, and tighter weight control systems. In late 2025, one European manufacturer introduced a new platform within its E Series, featuring human-centered design principles, advanced dosing combinations, and integrated weight control systems designed to reduce batch variability and streamline operator workflows. Shortly thereafter, the same company debuted an automatic capsule filling machine at a major European trade fair, showcasing support for multiple fill types with throughput capabilities reaching 3,000 capsules per hour, alongside full CE and cGMP compliance alignment. These releases reflect a broader industry pattern: manufacturers are not merely iterating on mechanical performance but are increasingly engineering for flexibility, operator ergonomics, and real-time quality feedback.
Concurrently, other players have advanced their equipment modernization roadmaps. A notable equipment upgrade launched in mid-to-late 2025 targeted precision and efficiency improvements for a widely deployed capsule filling model, reinforcing the competitive imperative to reduce downtime, enhance dosing repeatability, and support faster changeover cycles. Such innovation cycles are particularly consequential for 2026 capital planning, as they introduce new benchmarking criteria for total cost of ownership, maintenance predictability, and integration readiness with existing packaging and inspection lines. Organizations evaluating equipment refresh cycles or capacity expansions must assess not only baseline throughput figures but also the trajectory of software-driven control systems, modular dosing adaptability, and vendor-supported compliance documentation.
Regulatory Dynamics as a Strategic Filter
Regulatory compliance has evolved from a baseline operational requirement into a strategic filter that shapes procurement decisions, vendor selection criteria, and market entry pathways. In 2026, capsule filling equipment deployed in pharmaceutical and nutraceutical production must align with stringent sanitation, reliability, calibration, inspection, and maintenance expectations codified under FDA cGMP regulations. Equipment intended for dietary supplement manufacturing must additionally satisfy compliance frameworks specific to supplement production, while pharmaceutical-grade systems must adhere to broader cGMP expectations for equipment safety, sanitation, and operator protection. These requirements do not merely influence equipment design; they dictate documentation rigor, validation protocols, and the ability to demonstrate consistent quality management across production runs.
Beyond domestic regulatory frameworks, international market access increasingly depends on standardized certification pathways. ISO 9001 and ISO 22000 certifications are expected for capsule filling machine manufacturers seeking to assure consistent quality management and food safety in regulated production environments. For pharmaceutical applications, CE marking and cGMP compliance have become de facto prerequisites for market access in regulated regions, meaning that procurement teams must evaluate not only mechanical performance but also the completeness of compliance portfolios, audit readiness, and the vendor’s capacity to support lifecycle documentation. Furthermore, equipment transactions involving domestic, import, and export flows are subject to mandatory electronic reporting requirements, adding an administrative compliance layer that procurement, legal, and logistics functions must coordinate. These regulatory dynamics collectively raise the bar for vendor qualification and reinforce the strategic value of partnering with manufacturers that maintain robust quality management systems and transparent compliance documentation.
Operational and Strategic Implications for 2026 Capital Allocation
For manufacturing executives, R&D leaders, and procurement strategists, the Capsule Filling Machines Market in 2026 presents a window of calculated investment. The combination of moderate but steady market growth, a moderately concentrated competitive field, and an accelerating product innovation cycle creates a favorable environment for strategic equipment selection, capacity planning, and vendor partnership development. Several operational implications warrant particular attention.
- Total cost of ownership extends beyond purchase price. Organizations must evaluate dosing precision, changeover flexibility, maintenance predictability, and compliance documentation as integral components of long-term value. Equipment that reduces batch variability and supports faster sanitation or reconfiguration cycles can yield measurable gains in throughput consistency and quality assurance.
- Compliance readiness is a procurement differentiator. As regulatory expectations intensify across pharmaceutical and nutraceutical production lines, vendors that provide comprehensive CE and cGMP alignment, robust quality management certifications, and transparent lifecycle support will command preferential positioning in supplier evaluations.
- Flexibility is increasingly tied to formulation complexity. The ability to handle powders, pellets, tablets, mini-tablets, and specialized fill configurations is no longer a niche requirement. Manufacturers developing multi-SKU production strategies or transitioning between dosage forms will prioritize machines that offer advanced dosing combinations and modular adaptability.
- Innovation cycles demand forward-looking refresh planning. Recent product launches and technology showcases indicate that equipment performance benchmarks are shifting toward operator-centered design, weight control precision, and higher throughput efficiency. Procurement teams should align capital planning horizons with vendor roadmaps to avoid stranded investments in rapidly evolving equipment categories.
- Regional demand divergence rewards localized strategy. While mature markets continue to drive stable demand, emerging manufacturing corridors are cultivating distinct procurement rhythms, regulatory nuances, and service expectations. Organizations that tailor their equipment sourcing, service agreements, and compliance strategies to regional operating conditions will gain agility in market expansion and supply chain resilience.
What the Full Research Delivers: A Practical Intelligence Framework
PW Consulting’s comprehensive Capsule Filling Machines Market research is structured to translate macro-level market dynamics into actionable, segment-specific intelligence. The report provides a detailed examination of revenue trajectories, segmentation architectures, competitive positioning, regulatory impact pathways, and innovation timelines, all calibrated to support 2026 strategic planning and multi-year forecasting. Rather than offering static snapshots, the analysis maps the structural relationships between equipment type adoption, application demand patterns, regional deployment trends, and vendor competitive strategies, enabling readers to model investment scenarios, assess supplier qualification criteria, and anticipate shifts in procurement prioritization.
The research framework is designed for cross-functional application. Manufacturing and operations leaders can leverage the segmentation and equipment-type analysis to benchmark capacity planning and changeover requirements. Procurement and supply chain teams can use competitive landscape and compliance data to refine vendor scoring matrices and total cost of ownership models. Executive strategists and investors can draw on the market trajectory, concentration metrics, and innovation cycle synthesis to evaluate market entry timing, partnership opportunities, and long-term sector resilience. By maintaining a disciplined focus on decision-ready intelligence—not merely descriptive market narration—the report equips stakeholders to convert market complexity into structured strategic action.
Conclusion: Positioning for Deliberate Growth
The Capsule Filling Machines Market is at an inflection point where steady expansion, regulatory rigor, and accelerating technological differentiation converge. The projected trajectory from 226.24 million USD in 2026 toward 344.8 million USD by 2032, supported by a compound annual growth rate of 6.98 percent, reflects a market that is expanding through structural demand rather than transient cycles. In this environment, the organizations that thrive will be those that treat equipment selection, compliance alignment, vendor partnership, and innovation readiness as interconnected strategic levers rather than isolated procurement tasks.
The full market research provides the granular segmentation data, competitive benchmarking, regulatory impact mapping, and scenario-based forecasting required to operationalize these decisions with precision. For executives and strategic planners seeking to align capital allocation with long-term manufacturing resilience, the report offers a comprehensive foundation for evidence-based action. We invite you to access the complete research repository to examine the detailed regional, application, and equipment-type breakdowns, competitive profiles, and forward-looking analysis that will further sharpen your 2026 strategic roadmap.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SOI Market to Reach $3.85B by 2032, 13.5% CAGR Predicted Globally
By PW Consulting, 2026-09-07
Beyond the Bulk: Why the Silicon-on-Insulator Market Is Rewiring Strategic Planning for 2026 and Beyond
The semiconductor substrate landscape is undergoing a structural recalibration. For decades, bulk CMOS dominated the architecture of integrated circuits, but the relentless pursuit of power efficiency, radio frequency performance, and isolation integrity has pushed Silicon-on-Insulator technology from a specialized niche into a mainstream strategic imperative. As device geometries shrink and application demands compound, the SOI ecosystem is no longer a passive supplier of wafers. It is becoming a decisive determinant of product roadmaps, supply chain resilience, and regional manufacturing footprints. Our latest market research on the Silicon-on-Insulator Market is designed to give executives, product planners, and capital allocators the clarity required to navigate this inflection point with confidence.
Worldwide Asthma Nebulizer Market
The trajectory is unmistakable. From 2020 through 2025, the global SOI market expanded from 0.85 billion USD to 1.6 billion USD, reflecting a compound annual growth rate that underscores sustained demand across mobility, connectivity, and high-performance computing verticals. Looking forward, the forecast period from 2026 to 2032 projects the market reaching 3.85 billion USD, driven by a CAGR of 13.5 percent. These figures are not abstract aggregates. They reflect a fundamental shift in how device manufacturers evaluate trade-offs between performance, power, and process complexity. For leadership teams planning capital deployment, capacity allocation, and partnership strategies in 2026, understanding the underlying architecture of this growth is no longer optional. It is a prerequisite for competitive positioning.
Worldwide Live Attenuated Influenza Vaccine (LAIV) Market
This report is structured to convert macroeconomic momentum into operational intelligence. Rather than stop at headline numbers, we map the forces shaping demand, the technologies redefining supply, and the competitive dynamics that will separate resilient players from vulnerable incumbents. The following sections preview the depth and practical orientation of the full study, while deliberately reserving the granular segmentation data for the complete report, where regional, type-level, and application-level breakdowns are presented with the precision required for investment committee and board-level decision-making.
18K Gold Jewelry Market
The Structural Case for SOI in a Performance-Constrained Era
The renewed emphasis on Silicon-on-Insulator reflects a convergence of electrical, thermal, and integration requirements that traditional bulk substrates struggle to satisfy simultaneously. SOI architectures introduce a buried oxide layer that decouples the active silicon film from the bulk substrate, delivering benefits that cascade across device physics. Reduced parasitic capacitance enables faster switching and lower dynamic power consumption. Enhanced isolation supports mixed-signal integration without cross-talk penalties. Radiation hardness and latch-up immunity broaden the technology's relevance to automotive, aerospace, and industrial applications where reliability is non-negotiable. For RF designs, the insulator layer provides a foundation for high linearity and low loss, which is critical as wireless standards evolve toward higher bandwidth and more complex modulation schemes.
These attributes are not incremental. They are reshaping design hierarchies. System architects are increasingly evaluating SOI not as a substitute for bulk silicon, but as a domain-specific enabler for functions where power, speed, and isolation define the performance envelope. That shift is visible across multiple end markets. Automotive electronics are demanding more robust, lower-power sensor and control architectures. Telecom infrastructure is pushing RF front-end complexity higher as 5G and next-generation Wi-Fi deployments mature. Consumer electronics continue to prioritize energy efficiency in always-on and edge-processing workloads. Each of these vectors contributes to sustained SOI adoption, but the composition of demand varies by region, application maturity, and technology generation. The full report dissects these variations in detail, allowing readers to see where the highest-value opportunities are forming and where growth is more transitional.
Market Dynamics: Capacity, Policy, and the New Geography of Risk
Capacity expansion is currently one of the most consequential forces in the SOI market. Producers are investing in larger-diameter wafers, improved bonding and separation processes, and dedicated lines for RF and power-oriented variants. Recent industry activity illustrates the pace of change. In March 2026, Soitec announced a EUR 500 million expansion of its 300 mm SOI facility in Bernin, France, lifting annual capacity by 40 percent to strengthen supply for automotive and RF applications. Earlier, in November 2025, Tower Semiconductor expanded its 300 mm wafer bonding technology across SiPho and RF-SOI platforms, targeting compact high-performance chips for wireless and automotive ICs. In December 2024, Soitec and GlobalFoundries formalized a supply arrangement for 300 mm RF-SOI substrates to support next-generation RF technologies in 5G and Wi-Fi markets. By mid-2024, GlobalWafers had increased 200 mm SOI wafer production and introduced 300 mm SOI manufacturing at its MEMC plant, signaling a broader transition toward advanced-diameter capability.
Policy and trade dynamics are equally influential. CHIPS Act funding has been enabling domestic SOI wafer capacity additions that reduce lead-time risk, with companies having announced more than 140 semiconductor projects across the United States totaling over USD 640 billion in investments since 2020. At the same time, global trade tensions and tariffs are impacting the cost of silicon substrates and related manufacturing equipment, driving regional SOI manufacturing and strategic investments. For executives, these forces create a dual imperative: secure supply continuity while managing exposure to geopolitical and input-cost volatility. The report quantifies these dynamics in a structured framework, helping organizations assess where localized capacity, long-term agreements, and multi-source strategies will deliver the greatest risk-adjusted value.
A critical element of the dynamic environment is the concentration of supply among established producers. The market displays meaningful consolidation, with the top three players accounting for 58 percent of revenue and the top five reaching 72 percent. Such concentration can support scale economics, process consistency, and customer confidence, but it also raises questions about supply flexibility, pricing power, and the pace at which new entrants or differentiated technology variants can gain traction. Understanding this concentration is essential for procurement strategy, partnership evaluation, and long-term capacity planning. The full report explores how this structure interacts with demand segmentation and technology transitions, without reducing the analysis to simplistic rankings.
Technology Segmentation and the Real Meaning of Type-Level Demand
SOI is not a single product category. It is a family of technologies, each optimized for different electrical and mechanical requirements. Thin Film SOI continues to serve a broad range of applications where a thin active layer supports low-power and high-speed operation. FD-SOI has gained attention for its ability to deliver high performance with reduced leakage and simplified biasing control, making it attractive for specific mobile, IoT, and edge-processing scenarios. RF-SOI remains central to wireless infrastructure, front-end modules, and connectivity ICs, where linearity, loss, and integration density define competitiveness. Together, these types represent a substantial share of current demand, but their relative importance is shifting as design priorities evolve and as 300 mm processing becomes more widely available.
What matters strategically is not only which type is growing, but why. Thin Film SOI demand is influenced by the balance between performance needs and cost sensitivity in high-volume electronics. FD-SOI adoption is shaped by design ecosystem maturity, tooling availability, and the degree to which designers can leverage bias-controlled performance for power-constrained devices. RF-SOI growth is tied to the expansion of wireless standards, the complexity of antenna and front-end architectures, and the push toward software-defined radio and advanced connectivity. The complete report provides a structured comparison of these types, mapping their technical value propositions to application fit, production economics, and near-term adoption catalysts. This allows decision-makers to see where each technology is positioned within the broader market and how the mix is expected to change over the forecast horizon.
Application Demand: Where the Growth Is Concentrated and Why
The SOI market's expansion is being propelled by a set of application categories that are each undergoing their own technology and volume transitions. Automotive systems continue to place heavier demands on sensor interfaces, power management, and robust electronics capable of operating in harsh environments. Telecom and 5G infrastructure are driving sustained RF-SOI requirements as base stations, small cells, and terminal devices evolve toward higher throughput and more complex signal processing. Consumer electronics remain a significant contributor, especially where low-power ICs, display drivers, and connectivity modules rely on the efficiency advantages of insulating substrates. A smaller but strategically important share of demand comes from other specialized applications that value isolation, radiation tolerance, or custom device configurations.
The strategic challenge for most organizations is not recognizing that these sectors matter, but determining how their SOI demand will behave as product cycles mature, as regional manufacturing shifts, and as alternative substrate or packaging approaches compete for share. In the full report, we break down application-level demand with enough granularity to support sourcing strategy, product positioning, and investment prioritization. We focus on the mechanisms that drive volume growth, the sensitivity of each segment to technology transitions, and the ways in which supply constraints or cost dynamics can alter adoption timing. This approach is designed to help leaders move beyond broad market narratives and into the kind of segment-level clarity that supports realistic forecasts and defensible plans.
Competitive Landscape: Leaders, Differentiators, and the Shape of the Battlefield
The SOI market is defined by a set of companies that combine wafer processing expertise, technology heritage, and increasingly, capacity scale. Soitec, headquartered in Bernin, France, is a leading designer and producer of SOI wafers through its Smart Cut technology, with strong relevance to mobile communications, automotive, and smart devices. Its recent capacity expansion underscores the strategic importance of 300 mm supply for high-volume RF and automotive demand. GlobalWafers, based in Taiwan, is a supplier of RF-SOI and Power-SOI wafers and has been expanding 300 mm manufacturing capacity, positioning itself at the intersection of connectivity and power-oriented substrate needs. Shin-Etsu Chemical, in Tokyo, Japan, is a mass producer of 300 mm SOI wafers for high-speed and low-power consumption applications, reflecting the scale and quality focus required in advanced wafer supply. SUMCO Corporation, also based in Tokyo, manufactures bonded SOI wafers for high integration, low power, high speed, and high reliability devices, emphasizing versatility across demanding device categories.
Other players add important dimensions to the competitive map. Shanghai Simgui Technology, in Shanghai, China, manufactures SOI wafers and EPI wafers using SIMOX, bonding, and Simbond technologies, illustrating the breadth of process approaches in the market. Okmetic, in Vantaa, Finland, is a pioneer in bonded SOI wafers for MEMS sensors, power devices, and RF applications, with E-SOI and C-SOI variants that target specialized performance and integration needs. Silicon Valley Microelectronics, in Santa Clara, California, operates as a distributor and provider of thin and thick film SOI wafers, cavity SOI, and custom manufacturing for low-power and high-speed devices, serving customers that require flexibility and tailored substrate configurations. Tower Semiconductor, in Migdal Haemek, Israel, provides foundry RF-SOI platforms for wireless and automotive ICs, linking substrate supply with integrated device solutions and platform-level differentiation.
These companies are not competing in a vacuum. Their strategies are increasingly shaped by capacity timing, process migration to 300 mm, customer co-development, and the ability to align substrate supply with downstream integration requirements. Recent developments show this clearly. Soitec's facility expansion directly targets automotive and RF supply scale. Tower Semiconductor's platform expansion connects bonding technology with compact high-performance chips. Soitec and GlobalFoundries' supply agreement ties substrate capability to next-generation RF technology roadmaps. GlobalWafers' production increases and 300 mm introduction reflect a broader industry push toward advanced-diameter economics. The report evaluates these moves within a competitive framework that considers technological differentiation, geographic positioning, customer relationships, and the implications for procurement and partnership strategy. Full company-level assessments, including capability mapping and strategic posture, are provided in the complete study.
How the Report Converts Intelligence into Decision Support
A market study is only valuable if it can be used. This report is built around practical decision support rather than descriptive storytelling. It combines quantitative context with qualitative analysis to address the questions that executives and technical leaders face when planning for 2026 and beyond. The structure is designed to support multiple use cases, from capacity and sourcing strategy to technology roadmapping, competitive positioning, and investment prioritization.
The report includes detailed coverage of the following areas:
- Macro market trajectory and forecast logic, anchored in historical performance and forward projections across the forecast period, with an emphasis on the drivers that explain the pace of growth rather than merely restating outcomes.
- Technology segmentation analysis that compares Thin Film SOI, FD-SOI, and RF-SOI in terms of performance fit, production economics, and adoption catalysts, helping readers anticipate where each variant will gain or lose relative importance.
- Application-level demand analysis that links automotive, telecom, consumer electronics, and other end-use categories to underlying technology requirements, volume dynamics, and regional variation, without reducing the picture to a single aggregate number.
- Competitive profiling of key producers and platform players, including their process strengths, capacity direction, and strategic moves, so that organizations can benchmark suppliers and assess partnership or procurement options.
- Market dynamics and risk framework covering capacity expansion, policy-enabled investments, trade-related cost pressures, and concentration effects, with guidance on how to interpret supply resilience and exposure.
- Strategic implications for capital allocation, sourcing architecture, technology selection, and regional planning, presented as actionable perspectives rather than abstract observations.
Throughout, the analysis is designed to be modular. Procurement teams can focus on supplier positioning and supply resilience. R&D and product leaders can concentrate on technology fit and application drivers. Strategy and finance groups can use the forecast logic, concentration data, and dynamic risk framework to inform scenario planning and capital decisions. The full report provides the underlying segmentation detail necessary to support these different lenses, while maintaining a consistent narrative about where the market is heading and why.
Why This Research Matters for 2026 Decision-Making
The key strategic question for 2026 is not whether SOI matters, but how to position within a market that is expanding quickly, consolidating selectively, and being reshaped by policy, trade, and technology migration. The headline growth rate of 13.5 percent and the projected ascent to 3.85 billion USD by 2032 indicate a market with durable momentum, but momentum alone does not tell an organization what to do. Decision-makers need to know where demand is most structurally supported, which supplier capabilities will become more valuable, how regional capacity shifts affect lead times and cost, and where competitive differentiation will be earned.
Our research addresses these questions by connecting market size to market mechanics. It examines how capacity additions change the supply environment, how policy and trade pressures influence regional manufacturing incentives, how concentration affects negotiation leverage and continuity risk, and how technology segmentation determines which applications and customers will drive the most valuable growth. This integrated view is especially important in a market where a single sourcing decision, technology choice, or capacity commitment can have multi-year consequences. The report is intended to reduce uncertainty in those decisions by replacing general assumptions with structured, evidence-based analysis.
At the same time, we recognize that the most useful intelligence is often the most specific. Regional demand composition, application-level revenue splits, and type-level market shares are essential for precise planning, but they are also the details that require careful interpretation. For that reason, the complete study presents these breakdowns in full, along with the methodology and context needed to use them responsibly. The preview above establishes the strategic frame; the full report delivers the operational detail.
Conclusion: A Market at the Intersection of Performance and Supply Chain Strategy
Silicon-on-Insulator has moved from a specialized substrate option to a central element of modern semiconductor strategy. Its value lies not only in device physics, but in the way it enables performance, power, and integration goals that are increasingly difficult to achieve with bulk alternatives alone. The market's growth trajectory reflects that value proposition, but it also reflects a broader set of forces: capacity investment, policy support, trade and cost pressures, technology migration, and a competitive field that is consolidating around scale, process maturity, and platform relevance.
For leaders planning in 2026, the most important task is to align strategy with the realities of this evolving landscape. That means understanding where growth is most durable, where supply risk is concentrated, where technology differentiation matters most, and how supplier capabilities map to future demand. Our Silicon-on-Insulator Market research is designed to provide that alignment. It offers a rigorous, decision-oriented view of the market, with enough depth to support strategic planning and enough discipline to avoid overgeneralization.
The complete report provides the full segmentation detail, competitive depth, and dynamic analysis needed to turn market insight into executable strategy. For organizations that depend on substrate supply, device performance, and supply chain resilience, that level of clarity is not a luxury. It is the foundation for smarter capital decisions, stronger partnerships, and more confident technology roadmaps in the years ahead.
For detailed analysis of this topic, please visit the official page: Silicon-on-Insulator (SOI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Biochemical Analyzer Market Hits $3.15B in 2025, Set for 5.51% CAGR Growth to 2032
By PW Consulting, 2026-09-07
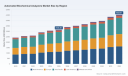
Navigating the Automated Biochemical Analyzers Market: Strategic Imperatives for 2026 and Beyond
The landscape of clinical diagnostics and biochemical testing is undergoing a profound transformation, driven by the urgent need for efficiency, accuracy, and scalability in healthcare delivery. As healthcare systems globally grapple with increasing patient volumes and the demand for rapid turnaround times, Automated Biochemical Analyzers have emerged as a critical infrastructure component. For stakeholders operating in this sector, understanding the nuances of market growth, competitive positioning, and regulatory dynamics is not merely an academic exercise but a strategic necessity. This insight serves as a precursor to our comprehensive market research report, designed to equip decision-makers with the intelligence required to navigate the complexities of the period from 2026 to 2032.
Worldwide Sensor Actuator Cable Market
Our latest study, Automated Biochemical Analyzers Market, offers a granular examination of an industry poised for steady expansion. By integrating historical performance data with forward-looking projections, we provide a roadmap that highlights where value is being created and where risks may lie. This article outlines the strategic value of this research for enterprise planning in 2026, touching upon market magnitude, competitive forces, regulatory frameworks, and operational dynamics without revealing the full depth of our proprietary data models.
Abdominal Crunch Machine Market
Market Trajectory and Historical Context
Understanding the current market position requires a clear view of the past trajectory. The Automated Biochemical Analyzers industry has demonstrated resilience and consistent growth over the last half-decade. Our analysis tracks revenue trends from 2020 through 2025, establishing a solid baseline for forecasting future performance. The market has evolved from a value of approximately 2426.75 Million USD in 2020 to an estimated 3145.49 Million USD in 2025. This historical progression illustrates a steady upward trend, reflecting the broader adoption of automation in clinical settings and the continuous replacement of legacy manual systems with integrated solutions.
Worldwide ABS Protective Helmet Market
Looking ahead, the forecast period extends from 2026 to 2032. The momentum observed in the historical years is expected to continue, albeit at a moderated pace reflective of market maturity. The projected revenue for 2026 stands at 3407.66 Million USD, indicating an immediate growth step as organizations finalize capital expenditures planned during the previous fiscal year. By the end of the forecast window in 2032, the market is anticipated to reach 4525.81 Million USD. This growth path suggests a Compound Annual Growth Rate (CAGR) of 5.51 percent over the forecast period. Such consistent expansion underscores the essential nature of these analyzers in modern healthcare infrastructure, driven by factors such as aging populations, the rise of chronic diseases, and the integration of advanced diagnostic technologies.
The significance of this trajectory lies in its implications for capacity planning and investment timing. Organizations entering the market or expanding their footprint need to understand whether they are riding a wave of rapid adoption or stabilizing in a mature environment. Our data suggests a stable, predictable growth environment, which favors long-term strategic planning over speculative short-term maneuvers. However, the aggregate numbers only tell part of the story. The distribution of this growth across different regions, product types, and application areas varies significantly, offering distinct opportunities and challenges that are detailed in the full report.
Competitive Landscape and Key Players
The market is characterized by a mix of established multinational giants and specialized regional players, creating a competitive environment that is both contested and fragmented. Our analysis identifies key companies that are shaping the industry through innovation, acquisition, and strategic positioning. Prominent among these are Roche Diagnostics, headquartered in Indianapolis, IN, USA, which offers cobas c 703, cobas ISE neo, and cobas pro integrated solutions for automated clinical chemistry and immunoassay testing. Similarly, Abbott Laboratories, based in Abbott Park, IL, USA, provides Alinity ci-series and Alinity c systems for integrated clinical chemistry and immunoassay automation, maintaining a strong presence in the integrated systems segment.
Siemens Healthineers, located in Munich, Germany, supplies the Atellica Solution and Atellica CI Analyzer for high-throughput clinical chemistry and immunoassay testing, catering to large-scale laboratory needs. In the United States, Beckman Coulter, headquartered in Brea, CA, manufactures the DxC 500i, DxC 500 AU, DxC 700 AU, and AU 5800 series for scalable automated clinical chemistry analysis. Another significant contender is QuidelOrtho, based in San Diego, CA, USA, which offers VITROS XT 7600, VITROS 5600, and VITROS 3600 integrated systems for clinical chemistry and immunoassay automation.
The landscape also includes strong players from Asia and other regions. Mindray, headquartered in Shenzhen, China, delivers BS-2800M, BS-800M, and BS-600M biochemistry analyzers for high-throughput clinical chemistry testing. YSI Life Sciences, located in Yellow Springs, OH, USA, produces YSI 2500 and 2900 biochemistry analyzers for clinical, bioprocess, and medical applications. In India, Agappe Diagnostics, based in Thiruvananthapuram, supplies the TBA-1500FR advanced clinical chemistry analyzer for routine biochemistry testing, while Meril Diagnostics, also in India, offers fully automatic biochemistry analyzers such as the SERACHEM series for clinical use. Eurolyser Diagnostica, from Austria, provides compact automated biochemistry analyzers including the CUBE series for clinical diagnostics, and YHLO Biotech, also based in Shenzhen, China, manufactures the iBC 2000 fully automated biochemistry analyzer for clinical laboratory testing.
The competitive intensity is reflected in the market concentration metrics. The CR3 percent stands at 25.6 percent, and the CR5 percent is 34.2 percent. These figures indicate that while the top players hold significant influence, the remaining market share is distributed among a diverse array of manufacturers. This structure suggests opportunities for niche players to compete on price, specific features, or regional support, while larger entities compete on integration, throughput, and global service networks. Understanding the specific capabilities and recent movements of these companies is crucial for benchmarking and strategic positioning.
Recent Developments and Strategic Moves
In the fast-moving medical technology sector, recent events often signal future market directions. Our report includes a detailed timeline of significant developments that have occurred among key market participants. For instance, Beckman Coulter achieved FDA clearance for their DxC 500i integrated clinical chemistry and immunoassay analyzer in March 2025. This regulatory milestone likely expands their addressable market in the United States and reinforces their commitment to integrated testing solutions.
QuidelOrtho launched a Certified Analyzer Program for VITROS systems in August 2025. This initiative was designed to expand access in rural and community hospitals, highlighting a strategic shift towards democratizing advanced diagnostics for underserved settings. This move could potentially increase volume in lower-tier healthcare facilities while strengthening customer loyalty through certified service programs. In terms of new hardware, YHLO Biotech launched the iBC 2000 fully automated biochemistry analyzer at the CACLP trade show in March 2025, signaling aggressive market entry and product innovation from the Chinese manufacturer segment.
More recently, in March 2026, Roche Diagnostics received FDA 510(k) clearance for cobas c 703 and ISE neo analytical units for cobas pro integrated solutions. This clearance allows them to scale their integrated solutions further, maintaining their competitive edge in the high-end automation space. These developments illustrate a market where regulatory success, product launches, and access programs are key battlegrounds. A deep dive into these events reveals patterns of innovation focus, such as the emphasis on integrated chemistry and immunoassay testing, and strategic priorities like expanding into rural healthcare markets.
Regulatory and Reimbursement Dynamics
Operating in the medical device sector requires navigating a complex web of regulations and reimbursement policies. Our research delves into the specific regulatory requirements that impact market entry and product lifecycle. Automated biochemistry analyzers are classified as Class II medical devices, requiring 510(k) premarket notification or FDA clearance for market entry. This regulatory hurdle creates a barrier to entry that protects established players but also demands significant compliance resources from new entrants. The recent FDA Class 2 Device Recall for the Beckman Coulter DxC 500 AU Clinical Chemistry Analyzer on February 26, 2025, due to software design issues, serves as a reminder of the operational risks and quality management imperatives inherent in this space.
Reimbursement policies also play a critical role in driving demand. Clinical chemistry testing utilizing instrumented chemistry analyzers is covered under CPT code 80306. Changes to fee schedules or coverage policies under the CMS CPT Fee Schedule for 2026 can directly impact the financial viability of diagnostic testing, influencing procurement decisions by hospitals and laboratories. Furthermore, procurement channels for public sector entities are defined by specific frameworks. Clinical laboratory analyzer service contracts fall under the VA Federal Supply Schedule 66 III for immunochemistry, chemistry, coagulation, hematology, microbiology, and urinalysis analyzers, according to the VA Office of Procurement, Acquisition and Logistics for 2026. Understanding these contractual frameworks is essential for vendors targeting government and Veterans Affairs health systems.
These regulatory and reimbursement factors create a dynamic environment where policy changes can shift demand overnight. Our report analyzes how these elements interact with market growth, providing stakeholders with a risk assessment framework.
Market Segmentation and Growth Drivers
The breadth of the Automated Biochemical Analyzers market is best understood through its segmentation. The report breaks down the market by region, type, and application, revealing where the primary growth engines are located. While aggregate figures provide the macro view, the segmentation splits offer insight into the preferences and needs of different customer bases. For example, the distinction between Fully Automated and Semi-Automated systems reflects varying needs for throughput, labor savings, and capital expenditure. The Fully Automated segment represents a significant portion of the market, driven by the desire for maximum efficiency and reduced human error in high-volume settings.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique dynamics regarding healthcare infrastructure development, regulatory maturity, and pricing sensitivity. The Asia Pacific region, with its expanding healthcare networks, represents a significant volume, while North America and Europe remain key markets for high-end integrated solutions. The report details the revenue contribution of these regions, allowing strategists to prioritize geographic expansion or focus efforts.
In terms of application, Clinical Diagnostics dominates the landscape, reflecting the primary use of these analyzers in routine patient testing. However, Drug Discovery and Research applications also contribute to the market, driven by the needs of pharmaceutical companies and research institutions for accurate biochemical data. The growth in these sectors is tied to broader trends in biotechnology investment and pharmaceutical development pipelines. Other applications also exist, catering to specific niche needs. The full report provides the specific valuation for these segments, enabling a precise allocation of marketing and R&D resources.
Strategic Implications for 2026 Decision Makers
For executives and strategists planning for 2026, the data presented in our comprehensive report offers several actionable insights. First, the steady CAGR of 5.51 percent suggests that organic growth is achievable, but capturing market share will require differentiation. With a CR5 percent of 34.2 percent, the market is not a monopoly, leaving ample room for competitive maneuvering. Companies must decide whether to compete on volume and integration like the major players, or on agility and specific regional needs like the specialized manufacturers.
Second, the regulatory environment demands vigilance. The classification as Class II devices and the requirement for 510(k) clearance mean that product development cycles must account for regulatory timelines. Recent recalls highlight the importance of robust quality assurance systems. Procurement through channels like the VA Federal Supply Schedule also opens specific revenue streams that require dedicated business development efforts.
Third, the evolution of reimbursement codes like CPT 80306 must be monitored. Changes in reimbursement rates can alter the cost-benefit analysis for laboratories considering new analyzers. Understanding the payer landscape is as important as understanding the technology landscape.
Fourth, the trend towards integration, evidenced by products like the cobas pro integrated solutions and Atellica Solution, indicates that laboratories are seeking multi-analyte platforms. Manufacturers offering siloed solutions may face pressure to bundle capabilities. Conversely, this trend creates opportunities for companies that can seamlessly integrate biochemistry analyzers with laboratory information systems and other diagnostic workflows.
Our research provides the detailed data needed to validate these strategic hypotheses. It allows companies to benchmark their performance against competitors, identify white spaces in the market, and assess the viability of potential mergers or partnerships. The segmentation data helps in tailoring product mixes to specific regional demands, while the competitive profiles offer intelligence on rival strategies and vulnerabilities.
Conclusion: The Value of Deep Intelligence
The Automated Biochemical Analyzers market is a vital component of the global healthcare ecosystem, characterized by steady growth, intense competition, and complex regulatory requirements. Navigating this environment successfully requires more than general industry knowledge; it demands precise, data-driven intelligence. Our report, Automated Biochemical Analyzers Market, delivers this intelligence by combining historical analysis, future projections, and deep dives into competitive and regulatory dynamics.
While this overview highlights the macro trends and key players, the full report contains the specific segmentation data, detailed company profiles, and granular forecasts that are essential for precise decision-making. The specific revenue shares by region, type, and application, as well as the detailed timelines of competitive developments, are available within the comprehensive document. For organizations looking to secure their position in this growing market, accessing this detailed intelligence is a critical step. We invite you to explore the full report to gain the complete strategic advantage needed for the 2026-2032 period.
Access the full market report to unlock detailed segmentation data, competitive profiles, and strategic recommendations tailored to your organizational goals.
For detailed analysis of this topic, please visit the official page: Automated Biochemical Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wellington Boots Market to Hit $1.84B by 2032, Growing at 4.8% CAGR: PW Consulting
By PW Consulting, 2026-09-07
The Wellington Boots Market in 2026: Strategic Imperatives for a Reshaping Industry
The global Wellington boots market is entering a decisive phase of its evolution. After a decade of steady expansion, the sector is no longer defined by simple utility or seasonal sales cycles. Today, it sits at the intersection of supply chain realignment, material innovation, regulatory shifts, and changing end-user expectations across agriculture, industrial manufacturing, household use, and outdoor recreation. For executive teams, procurement leaders, and brand strategists, the 2026 landscape demands a more granular understanding of where value is being created, where margins are being tested, and how competitive positions are being reconfigured.
Worldwide Precision Fluid Dispensing Systems Market
Our latest Wellington Boots Market research study is designed to cut through the noise and provide a structured, data-informed view of the market from 2020 through 2032. The analysis is anchored in a clear historical trajectory and a forward-looking forecast period that maps the growth path from a 2025 revenue base of approximately 1,330.0 million USD to an estimated 1,842.67 million USD by 2032. This trajectory reflects a compound annual growth rate of 4.8 percent across the forecast horizon, signaling durable demand but also underscoring the importance of execution quality as competition intensifies and input costs remain volatile. The years from 2020 to 2025 already demonstrated how resilient the category can be, with revenue progressing from 1,087.15 million USD to 1,330.0 million USD. Yet the next phase will be less forgiving for players that rely on undifferentiated product portfolios or rigid sourcing models.
Productivity Tool Market
This article serves as a strategic preview of the full report. It highlights the market structure, competitive dynamics, and operational pressures that executives should be tracking right now. At the same time, it intentionally leaves the most granular segmentations, regional comparisons, and application-level revenue splits for the complete study. Those detailed breakdowns are essential for precise portfolio planning, pricing strategy, and geographic prioritization, and they are available in the full Wellington Boots Market research release.
PVC Footwear Market
Macro Momentum: Why the Wellington Boots Market Still Has Strategic Relevance
The Wellington boots category has moved beyond its traditional image as a narrow seasonal accessory. It now functions as a cross-sector footwear segment that supports professional work environments, agricultural operations, facility management, and leisure activities. That breadth gives the market a structural advantage: demand is diversified, and downturns in one application can be offset by stability or growth in another. At the same time, the category is exposed to macroeconomic forces that are difficult to ignore, including raw material pricing, freight volatility, labor costs, and evolving tariff regimes.
The historical record supports a constructive view, but not an automatic one. From 2020 to 2025, the market expanded from 1,087.15 million USD to 1,330.0 million USD. That progression reflects consistent end-user demand, broadened product positioning, and sustained relevance across both professional and consumer settings. The forecast period from 2026 to 2032 extends that momentum, projecting revenue movement from 1,352.27 million USD in 2026 to 1,842.67 million USD in 2032. The interim years show a market that is not simply growing linearly but steadily building scale: 1,508.07 million USD in 2027, 1,564.37 million USD in 2028, 1,575.3 million USD in 2029, 1,712.65 million USD in 2030, and 1,736.61 million USD in 2031.
For strategy teams, the key insight is that a 4.8 percent CAGR is meaningful but not exceptional in a vacuum. Its real value lies in what it implies about the prioritization of investments. In a market expanding at this pace, competitive advantage is increasingly determined by product differentiation, sourcing agility, channel execution, and the ability to manage cost inflation without eroding brand equity. Companies that treat Wellington boots as a commodity line will face pressure, while those that build defensible positions around durability, weather resistance, professional-grade performance, or style-led consumer appeal can capture disproportionate value.
What the 2026 Research Delivers: A Practical Toolkit for Decision-Makers
The full Wellington Boots Market study is built for applied decision-making rather than abstract observation. It combines historical market sizing, forecast modeling, segmentation analysis, competitive profiling, and industry context into a single integrated reference. The objective is to help leadership teams answer operational and strategic questions with greater confidence, especially in an environment where cost structures and regulatory conditions are changing quickly.
The report includes the following core components:
- Market sizing and forecast for the overall Wellington boots category, with a detailed historical series and forward outlook through 2032.
- Analysis of the materials landscape, including the relative importance of rubber, polyurethane, EVA, PVC, and other constructions in shaping product performance, cost profiles, and consumer perception.
- A structured view of application demand across agriculture, household, industrial manufacturing, outdoor recreation, and other end-use segments, helping teams understand where volume and value are concentrated.
- Regional market context that situates demand, supply exposure, and channel dynamics across major geographic markets without reducing the discussion to simplistic one-dimensional rankings.
- Competitive analysis of key companies and their strategic positioning, with an emphasis on product philosophy, brand character, target users, and recent commercial moves.
- Industry context covering regulation, import duties, raw material and freight pressures, product innovation trends, and pricing behavior that directly influence margin planning and sourcing decisions.
Equally important, the study is intended to support practical outputs: product roadmap prioritization, sourcing scenario planning, pricing architecture, channel strategy, and market-entry or expansion assessment. Because the Wellington boots market is fragmented across use cases and materials, high-level totals alone are insufficient. Decision-makers need the ability to see how demand patterns differ by application, how material choices affect both performance and cost, and how competitive intensity varies by segment. Those insights are developed in depth in the full report.
Competitive Landscape: Differing Philosophies in a Consolidated-but-Fragmented Market
The Wellington boots market presents an interesting competitive paradox. On one hand, the top players collectively hold a meaningful share of total industry revenue, with the top three accounted for by approximately 28.4 percent and the top five reaching about 37.2 percent. On the other hand, the market remains diverse enough that specialized brands, regional players, and multi-material manufacturers can all compete effectively by serving distinct customer groups. That balance creates both opportunity and risk: scale matters, but positioning matters just as much.
The competitive set covers a wide spectrum of product philosophies. Le Chameau, based in Normandy, France, emphasizes iconic handcrafted rubber Wellington boots, using a Chamolux rubber upper and dual-material construction designed for durability and weather resistance. Its approach reflects a premium, heritage-oriented positioning that appeals to customers willing to pay for craftsmanship and long-term product reliability. By contrast, Grundéns, headquartered in Canada, focuses on professional-grade rubber and neoprene fishing and work boots, including the Crewman model built for commercial durability. Its market identity is rooted in performance under demanding conditions rather than lifestyle appeal.
Xtratuf, operating in the United States, delivers durable waterproof rubber work and fishing boots under Rocky Brands ownership, bringing a more industrial-commercial orientation to the category. Rubbermaid, based in Atlanta, Georgia, contributes a commercial-grade perspective with rubber boots and protective footwear intended for industrial and facility use. Bogs Footwear, from Portland, Oregon, offers waterproof rubber and seamless Wellington-style boots for farm, work, and outdoor use, combining utility with comfort-oriented design. Blundstone, headquartered in Hobart, Australia, extends the category further by integrating rugged rubber and leather Wellington boots for both work and casual use, broadening the appeal of the style beyond purely functional settings.
Aigle, from France, adds a unisex outdoor and adventure orientation with rubber Wellington boots featuring lugged soles and dual-material uppers. Dunlop Boots, in the United Kingdom, reinforces the professional side of the category with industrial and rubber boots that include chemical-resistant features. Rockland, in the United States, leans toward more accessible pricing for general consumer and work applications, while Tingley Rubber serves safety and industrial needs with durable rubber overshoes and Wellington-style footwear. Together, these companies illustrate that Wellington boots are not a single product category so much as a family of related offerings with different performance expectations, styling priorities, and price points.
Recent company-level activity reinforces how actively this landscape is being shaped. In February 2025, Grundéns launched the Crewman boot after nine months of testing across Alaska, the Canadian Maritimes, Maine, and Europe for professional fishing and work use, signaling a clear investment in field-validated product development. In March 2025, Le Chameau previewed and began stocking new Fairfax collaboration Wellington boots at major retailers, showing how brand partnerships can extend reach and refresh consumer-facing offerings. These moves matter because they demonstrate two different routes to growth: one through specialized professional performance, the other through retail presence and collaborative design.
Industry Dynamics: Regulation, Cost Pressure, and Material Innovation
The Wellington boots market in 2026 cannot be understood without accounting for the external forces reshaping costs, sourcing options, and product development priorities. Several converging dynamics are worth close attention.
First, tariff and customs actions have introduced new uncertainty into footwear supply chains. In February 2026, U.S. Customs and Border Protection applied a 37.5 percent ad valorem duty under HTS 6401.99 for waterproof rubber boots originating from China under Executive Order 14389. This kind of measure directly affects landed cost calculations and can alter the economics of sourcing strategies that previously relied on specific export markets. The broader picture is equally important: in April 2025, the U.S. imposed new tariffs on imported footwear, raising duties for Vietnamese boots by 46 percent and Indonesian boots by 32 percent, with up to 145 percent on certain Chinese imports. These changes have direct implications for Wellington boots supply chains, especially for manufacturers and retailers that must rebalance sourcing footprints, renegotiation timelines, and inventory planning.
Second, import duty structures in other major markets also shape competitive conditions. As of 2026 HTS revisions, HS Code 6401.99.00 for rubber Wellington boots carries EU import duties of 16 percent and UK duties of 16 percent. For global suppliers and multinational distribution plans, these duty levels become part of the baseline cost architecture and can influence where products are positioned, how they are priced, and which markets are most attractive for expansion or consolidation.
Third, cost pressure has become a defining operational reality. Industry-wide pressure from rising raw material and freight costs in 2025 has led manufacturers to increase Wellington boot prices by 20 percent or more in order to maintain margins. This is not an isolated pricing event; it reflects a structural squeeze that requires careful management. Companies that pass on costs without a corresponding value narrative risk volume erosion, while those that fail to adjust pricing may damage profitability. The strategic response involves more than setting a higher sticker price. It requires clarity on which product tiers can absorb cost changes, how to communicate durability or performance benefits, and where sourcing or design improvements can offset input inflation.
Fourth, material and sustainability trends are influencing product roadmaps. Eco-friendly materials have featured in approximately 50 percent of new product launches for Wellington boots since 2023, driving consumer demand in Europe and North America. At the same time, broader footwear trend data indicates that Wellington boots dominate material demand with a 32 percent share in consumer footwear, ahead of rubber at 30 percent. This suggests that the Wellington boot style itself has become a meaningful fashion-and-function platform, not merely a utility item. For brands, the implication is clear: sustainability credentials, material innovation, and styling relevance are increasingly intertwined. A boot that performs well but fails to align with evolving consumer preferences may lose ground to competitors that integrate eco-conscious construction with strong design language.
Taken together, these dynamics create a market environment where strategic agility matters more than ever. Regulatory shifts can change the attractiveness of specific sourcing corridors. Cost inflation can compress margins if product architecture is not carefully managed. Sustainability-linked innovation can open new demand angles while raising expectations for transparency and performance. Companies that monitor these forces only at a high level risk being caught off guard; those that integrate them into sourcing, pricing, and product decisions will be better positioned to protect margins and grow share.
Where the Real Strategic Value Lies in 2026
For executives, the Wellington boots market presents a set of questions that are best answered with detailed segmentation, not broad averages. The overall growth story is encouraging, but the business implications differ sharply depending on which material categories matter most to a company's portfolio, which applications drive its volume, and which regions represent the best balance of opportunity and risk. The same market can look very different to a professional work-boot supplier, a consumer lifestyle brand, an agricultural distributor, or an industrial procurement organization.
Several strategic themes recur across the full analysis and should shape planning in 2026:
- Portfolio alignment: Companies need to determine where they compete in the material and application spectrum. Rubber remains central to the category, but polyurethane, EVA, PVC, and other constructions each carry distinct performance and cost characteristics. The right mix depends on target users, durability expectations, and price positioning.
- Sourcing and tariff strategy: With duties and trade measures affecting multiple export sources, companies must evaluate not just unit cost but total landed cost, lead-time reliability, and exposure to policy changes. Sourcing flexibility is likely to be a competitive advantage.
- Margin defense and value communication: In an environment where manufacturers have raised prices by 20 percent or more, the challenge is to justify price increases through product credibility, material quality, and clear use-case benefits rather than relying on category inflation alone.
- Retail and channel execution: Partnerships, seasonal placement, and retailer relationships can accelerate adoption for consumer-oriented Wellington boots, while professional and industrial channels may prioritize durability documentation, safety attributes, and supply consistency.
- Innovation and sustainability: With eco-friendly materials appearing in roughly half of new launches since 2023, brands need to decide how seriously to integrate sustainability into product design, messaging, and sourcing, especially in Europe and North America where consumer sensitivity is strongest.
These themes are not abstract. They directly affect product development timing, inventory strategy, pricing architecture, and long-term brand positioning. The full report provides the underlying market detail needed to translate these themes into concrete actions, including the segmentation depth that helps identify where demand is strongest and where competitive intensity is most pronounced.
Why the Full Report Matters Now
Market intelligence is most valuable when it reduces uncertainty at the point of decision. The Wellington boots category is large enough to offer real growth opportunities and fragmented enough to reward focused strategies. The combination of a 4.8 percent CAGR, a revenue trajectory moving from 1,352.27 million USD in 2026 toward 1,842.67 million USD in 2032, and a competitive field that spans premium heritage brands, professional-grade manufacturers, and value-oriented suppliers creates a landscape where precision matters.
The full Wellington Boots Market research study goes further than the summary figures and trend overview presented here. It offers a detailed breakdown of market size across the historical period and forecast horizon, a structured view of material and application segmentation, competitive profiles that connect product philosophy to commercial strategy, and an integrated account of the regulatory, cost, and innovation forces that will shape profitability. The deeper segmentation data, regional context, and application-level revenue splits are especially important for teams that need to evaluate where to invest, where to defend, and where to reposition.
For organizations preparing 2026 plans, the study is intended to serve as a practical foundation: not just a description of where the market has been, but a framework for deciding where it is heading and how to participate with confidence.
Access the Full Wellington Boots Market Research
This article provides a strategic preview of the market environment and the analytical approach behind our latest study. To explore the complete segmentation, competitive detail, regional insights, and forward forecast supporting 2026 decision-making, access the full Wellington Boots Market research report. The full edition contains the deeper data and structured analysis needed to turn market momentum into actionable strategy.
For detailed analysis of this topic, please visit the official page: Wellington Boots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: School Furniture Market to Hit $4.8B in 2025, 7.2% CAGR Through 2032
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Global School Furniture Market 2026
The educational landscape is currently undergoing a significant transformation, driven by evolving pedagogical models, heightened health and safety standards, and a renewed focus on student well-being. For stakeholders in the school furniture sector, these shifts represent more than just operational adjustments; they signal a fundamental restructuring of demand dynamics. As we move into 2026, understanding the trajectory of this market is critical for procurement officers, manufacturers, and investors alike. This article serves as a strategic overview of the current environment, drawing upon comprehensive market intelligence to highlight the key forces shaping the industry and the imperative for data-driven decision-making.
PCBN Composite Sheet Market
For senior leadership, the question is no longer whether to invest in updating or expanding educational furnishings, but how to align those investments with the long-term trends that will define the next decade. The following analysis outlines the macro-economic backdrop, the evolving competitive landscape, and the regulatory currents that must be navigated to secure a sustainable position in the market.
Short-video Content Parsing Software Market
Market Trajectory and Growth Vectors
The global school furniture market has demonstrated remarkable resilience and expansion over the past several years. Following a period of stabilization post-2020, the sector has entered a robust growth phase. Trajectory data indicates a consistent upward trend in revenue, reflecting increased capital expenditure in educational infrastructure and the replacement of aging inventories with modern, functional solutions. The market momentum is expected to sustain this pace, with projections extending through the end of the decade.
Worldwide PA Filament Market
Strategic forecasts suggest that the industry will continue to expand at a compound annual growth rate (CAGR) of 7.2 percent during the forecast period. This growth is not merely a reflection of inflation or population increases; it represents a structural shift toward higher-quality educational environments that support collaborative learning, ergonomic health, and technological integration. For enterprises operating in this space, maintaining a market share requires not only capturing current demand but anticipating the volume spikes associated with this growth trajectory.
Revenue projections through 2032 indicate a substantial increase in total market value, suggesting that the peak opportunities for strategic entry or expansion lie within the immediate future. Companies that establish strong partnerships with educational institutions and government bodies now are well-positioned to benefit from the sustained capital inflow into school facilities. However, capturing this growth requires a nuanced understanding of where the value is concentrated within the broader ecosystem.
Competitive Landscape and Stakeholder Dynamics
The market structure is characterized by a moderately concentrated environment where established players hold significant influence. Industry analysis reveals that a small group of leading manufacturers controls a majority of the market share. This concentration implies that while there is room for niche players and specialized providers, the dominant strategies for market leadership involve scale, comprehensive product portfolios, and strong distribution networks. Understanding the positioning of these key players is essential for any entity seeking to benchmark its performance or identify acquisition targets.
Several core organizations define the competitive baseline. Smith System, based in Grand Haven, Michigan, has carved a distinct niche by specializing in wholesale ergonomic and flexible furniture designed for K-12 classrooms. Their focus on collaborative systems for elementary through high school levels illustrates a market preference for adaptability in younger educational settings. Similarly, Haworth, located in Holland, Michigan, provides broader institutional solutions that bridge the gap between higher education and K-12 environments, offering modular systems and seating that cater to diverse learning spaces.
International perspectives are also vital. VS Furniture, headquartered in Germany, offers school and office furniture with a strong emphasis on ergonomic systems and modular solutions. Their presence highlights the global nature of standards and design philosophies that are crossing borders. In the United States, manufacturers like Krueger International (KI) from Green Bay, Wisconsin, and Virco from Placentia, California, continue to be pivotal. KI's adherence to BIFMA standards for institutional furniture underscores the importance of compliance in building trust with institutional buyers, while Virco's focus on durable desks and modular seating solutions speaks to the longevity requirements of public sector procurement.
Smaller but significant players also contribute to the ecosystem. Insalco provides contract furniture including storage and seating systems, while Robert H. Lord offers specialized school furniture adhering to educational seating standards. PSI-New England Storage Products supplies essential storage and seating solutions as part of institutional contracts. The interplay between these large conglomerates and specialized providers creates a dynamic where differentiation is often achieved through specific product features, regional service capabilities, or adherence to emerging sustainability criteria.
Regulatory Frameworks and Industry Standards
One of the most critical aspects of operating in the school furniture market is navigating the complex web of industry standards and regulatory guidelines. Compliance is not merely a legal checkbox; it is a competitive differentiator that signals quality and safety to risk-averse educational administrators. Recent developments from the Business and Institutional Furniture Manufacturers Association (BIFMA) have reinforced the importance of staying updated with the latest protocols.
In February 2026, BIFMA published the updated Furniture Surfaces Guideline (BIFMA G8.1-2026). This document details protocols for furniture surface performance against cleaning, sanitizing, and disinfecting products. For manufacturers, this means that surface durability and resistance are no longer optional features but baseline expectations. Schools and universities are increasingly concerned with hygiene infrastructure, and furniture that can withstand rigorous cleaning regimes without degrading offers a distinct value proposition.
Furthermore, the BIFMA 360 Conference held in February 2026 featured sessions on industry leadership and standards development for institutional furniture, including education applications. These gatherings often serve as barometers for future regulatory directions. Alongside the conference, BIFMA released the Outdoor Furniture Whitepaper (OF-2025), which covers performance and sustainability criteria applicable to educational outdoor spaces. This white paper is particularly relevant as schools look to expand learning environments beyond the traditional four walls, focusing on ventilation and outdoor connectivity.
Existing standards remain foundational. The BIFMA X6.1-2018 standard for educational seating evaluates student seating in pre-school through adult education environments. Together with ANSI/BIFMA X5.1, these standards cover general-purpose seating performance and specific educational seating durability. Additionally, the BIFMA LEVEL certification program evaluates environmentally and socially responsible products for institutional and education facilities. For companies, aligning product development with these standards is a strategic necessity to access public procurement channels and satisfy the requirements of conscious institutional buyers.
Segmentation and Application Trends
While the overall market numbers tell a compelling story of growth, the strategic opportunities lie in understanding the segmentation drivers without getting lost in the aggregate. The market is divided across various dimensions, each presenting unique challenges and opportunities for product development and sales strategies.
In terms of product type, the demand is diverse. Seating remains the dominant category, reflecting the core need for student ergonomics and comfort during prolonged learning hours. However, storage furniture and lab furniture also represent significant value pools. The demand for lab furniture is particularly sensitive to STEM education initiatives and the integration of technology in science classrooms, requiring specialized durability and utility. Storage solutions are critical as schools manage increasing amounts of digital and physical learning assets, driving demand for modular and secure storage systems.
Application-wise, the classroom remains the primary locus of spending, but it is evolving. The traditional row-based seating is giving way to flexible configurations that support group work and project-based learning. However, substantial opportunities also exist in library and labs, as well as other specialized applications. Libraries are transforming into media centers, requiring furniture that accommodates technology and collaborative study. The "others" category encompasses administrative offices, cafeterias, and common areas, each with distinct aesthetic and functional requirements.
Regional dynamics also play a role in shaping demand, though specific quantitative breakdowns are proprietary to detailed market studies. Different regions face varying challenges regarding infrastructure age, funding models, and educational priorities. For instance, some regions may prioritize replacement cycles due to aging stock, while others may be focused on expansion to accommodate population growth. Understanding these regional nuances requires granular data that goes beyond the headline figures.
Strategic Implications for 2026 Decision-Makers
For executives and strategists, the data points to several actionable implications. First, the growth rate implies that the market is large enough to support new entrants and innovators, but the concentration of market share among top players suggests that differentiation is key. Competing solely on price in a commodity segment is increasingly risky. Instead, value creation through ergonomics, compliance with the latest BIFMA guidelines, and modular flexibility offers a stronger path to margin retention.
Second, the regulatory updates from early 2026 should be viewed as immediate project parameters. Any procurement cycle initiated in 2026 must account for the new surface performance guidelines and the sustainability criteria highlighted in recent white papers. Suppliers who can certify their products against these standards will reduce friction in the sales cycle and build credibility with facility managers.
Third, the distinction between K-12 and higher education needs, while sometimes overlapping, requires tailored approaches. K-12 furniture must withstand high usage rates and accommodate growing students, favoring durability and adjustability. Higher education environments may prioritize aesthetics and flexibility for adult learners. Product lines that can address these specific needs without compromising on core standards will outperform generic offerings.
Finally, the long-term forecast extending to 2032 suggests that investments made today will have a multi-year payoff. Supply chain stability, manufacturing capacity, and service networks need to be scaled in anticipation of this sustained demand. Delays in capacity expansion or supply chain resilience could result in missed opportunities as competitors secure long-term contracts with educational districts during this growth window.
Conclusion: The Value of Deep Market Intelligence
The school furniture market is at an inflection point where growth, regulation, and changing educational pedagogies converge. For organizations looking to capitalize on this environment, surface-level knowledge is insufficient. Success depends on a granular understanding of market size, segmentation splits, competitive positioning, and the specific regulatory frameworks that govern procurement.
While this overview highlights the broader trends and key players shaping the industry, the full strategic picture requires accessing detailed intelligence. Comprehensive analysis of regional revenue splits, exact segmentation values, and deep-dive competitor profiling provides the precision needed to refine go-to-market strategies. The data suggests a robust opportunity, but seizing it requires navigating the specifics with confidence.
We invite industry leaders to explore our complete market research report to unlock the full depth of these insights. By leveraging the detailed dataset and strategic analysis contained within, your organization can align its 2026 roadmap with the realities of the market, ensuring that your investments are backed by the most accurate intelligence available. The future of school furniture is being built now, and informed strategy is the blueprint for success.
For detailed analysis of this topic, please visit the official page: School Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


