



PW Consulting: Sulphur Recovery Market Exceeds $118M in 2025, Growing at 2.51% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the Sulphur Recovery Market: A 2026 Outlook
The global energy landscape is undergoing a structural transformation, driven by the dual forces of tightening environmental regulations and the continued expansion of hydrocarbon processing capacity. At the center of this shift lies the sulphur recovery market, a critical infrastructure segment that converts hazardous acid gas streams into elemental sulphur while enabling refineries and gas processing facilities to meet stringent emission standards. As enterprises navigate the 2026 planning cycle, understanding the trajectory, competitive pressures, and regulatory catalysts shaping this market has moved from an operational afterthought to a boardroom priority. Our newly released Sulphur Recovery Market research provides a rigorous, data-grounded framework for strategic decision-making across engineering procurement, technology licensing, capacity expansion, and regulatory compliance.
Worldwide AEM Rubber Market
Drawing on historical performance from 2020 through 2025 and a forward-looking forecast extending to 2032, this analysis distills macro-level market behavior into actionable intelligence. The overall market, measured in USD millions, expanded from approximately 103.53 in 2020 to 169.73 in 2024, reflecting sustained investment in desulfurization infrastructure, refinery modernization programs, and gas processing capacity additions across emerging and mature economies alike. The baseline year of 2025 records a revenue figure of 118.0, a moderation that aligns with cyclical project deferrals and the completion of several major capacity installations. From this base, the forecast period projects a compound annual growth rate of 2.51 percent, with market size anticipated to reach 117.45 in 2026, climb to 125.61 in 2027, and continue its upward trajectory toward 140.41 by 2032. These figures are not merely statistical projections; they represent the commercial footprint of capital allocation decisions, technology adoption curves, and the pace at which environmental compliance mandates translate into equipment and licensing demand.
Ultra Lightweight Bulletproof Helmet Market
Market Trajectory and Structural Drivers
The sulphur recovery market is defined by its capital intensity, technology specificity, and deep integration with upstream processing economics. Acid gas streams generated during crude oil refining and natural gas sweetening carry hydrogen sulfide concentrations that, depending on the processing configuration, can range from 5 to 30 percent, a feedstock variability that directly influences reactor sizing, catalyst selection, and tail gas treatment requirements. The dominant technological pathway remains the Claus process, which accounts for the vast majority of installed capacity globally and continues to serve as the baseline architecture against which advanced modifications and hybrid configurations are evaluated. Complementary tail gas treatment units have gained prominence as regulatory bodies and corporate sustainability frameworks demand near-complete sulfur removal, pushing operators to pair conventional thermal and catalytic stages with catalytic reduction, oxidation, or low-temperature oxidation processes that close the emission loop.
Worldwide Controllable Heating Mantle Market
Forecast models indicate that growth through 2032 will be shaped by three interlocking dynamics. First, the ongoing modernization of mature refining complexes in North America, Europe, and the Middle East is driving replacement and efficiency upgrades of existing units, often with a focus on reducing auxiliary energy consumption and improving catalyst longevity. Second, gas processing capacity expansions in Asia Pacific and Latin America are creating new sulphur recovery installations that must be engineered to handle variable sour gas compositions while maintaining operational flexibility. Third, the globalization of marine fuel sulfur restrictions and the expansion of emission control areas are indirectly reinforcing demand for high-efficiency recovery trains, particularly at facilities that supply intermediate streams to logistics corridors where compliance margins are narrow. These drivers do not operate in isolation; they interact with logistics costs, localized permitting timelines, and the availability of specialized engineering talent, all of which our research maps in granular detail.
Regulatory Catalysts and Compliance Implications
Regulatory frameworks are no longer peripheral constraints; they are primary architects of market behavior. In the United States, federal emission standards at 40 CFR establish specific sulfur dioxide emission limits for sulfuric acid manufacturing and sulphur recovery operations, creating a compliance baseline that informs equipment specification, monitoring instrumentation, and maintenance scheduling. Parallel permitting regimes, including those administered by state commissions, govern the authorization pathway for new and modified sulphur recovery units under ambient air quality standards, adding project timeline variability that must be factored into investment underwrite models. In Europe and adjacent maritime corridors, the Mediterranean Sea Emission Control Area mandates a marine fuel sulfur limit of 0.10 percent, effective from mid-2025, tightening the operational envelope for bunkering supply chains and reinforcing the value of low-sulfur output streams. On a global scale, the implementation of IMO 2020 fuel sulfur restrictions and the continued expansion of emission control areas have accelerated demand for advanced sulphur recovery tail gas treating solutions, particularly in regions where refineries and gas plants support marine fuel blending operations.
For corporate planners, the regulatory layer translates into three practical imperatives. First, technology selection must be evaluated against the most stringent likely future limit, not merely the current permitted threshold, to avoid stranded asset risk. Second, tail gas treatment capacity should be modeled as an integral component of overall recovery train economics rather than a downstream add-on, given that underinvestment in polishing steps can erode the compliance value of otherwise robust primary recovery units. Third, permitting and operational reporting workflows should be integrated into the early stages of front-end engineering to de-risk schedule exposure, particularly in jurisdictions where air quality standards trigger incremental review cycles. Our report quantifies these compliance-driven decision points and maps them against regional project pipelines, enabling clients to prioritize investments that align with both current mandates and emerging regulatory trajectories.
Competitive Landscape and Technology Positioning
The global sulphur recovery market exhibits a high degree of concentration among established technology licensors, engineering firms, and specialized service providers. The top three participants collectively command a 65 percent share of the market, while the top five hold an 85 percent concentration, signaling a landscape where incumbency, proprietary process licensing, and long-term service relationships create meaningful barriers to entry. This structure does not imply a static competitive environment; rather, it reflects a market where differentiation is achieved through process efficiency, integration capability, and the ability to deliver modular or brownfield solutions that minimize operational downtime.
Shell Catalysts & Technologies, headquartered in the Netherlands, offers a broad portfolio encompassing Claus, SCOT, sulphur degassing, and THIOPAQ oil and gas sulphur recovery technologies for refineries and gas processing facilities. This breadth allows the company to position itself across primary recovery, tail gas polishing, and sulfur handling, making it a preferred partner in integrated modernization programs. Worley, based in Australia, provides Comprimo sulphur recovery units and advanced tail gas treatment units engineered for high-efficiency recovery, with recent project activity underscoring its growing footprint in the Middle East gas processing segment. In December 2024, Worley secured a front-end engineering and design contract from ADNOC Gas for the Bab Gas Cap project, which includes dedicated sulphur recovery units, an award that highlights the value of integrated FEED capability in large-scale gas expansion programs.
Linde AG, headquartered in Germany, supplies LO-CAT sulphur recovery units built around low-temperature oxidation processes, a configuration that is particularly attractive in applications where operational simplicity, reduced thermal stress, and lower emissions footprints are prioritized. Fluor Corporation, based in the United States, delivers EconoClaus sulphur recovery units integrated with refinery operations, emphasizing footprint efficiency and retrofit compatibility for sites seeking to upgrade recovery performance without major front-end redesign. Technip Energies, operating from France, licenses SmartSulf and sulphur recovery processes for the oil and gas industries, leveraging its engineering scale to bundle recovery technology with broader front-end and detailed design services. Chiyoda Corporation, based in Japan, provides Superclaus and sulphur recovery unit technology under exclusive contracts for advanced sulphur recovery, a positioning that reinforces its role in high-specification projects where proprietary process guarantees are critical.
Sulfur Recovery Engineering, headquartered in Canada, specializes in optimization, maintenance, and services for sulphur recovery units, tail gas treatment units, and sour water stripping units, offering a service-centric model that extends asset life and improves availability in operating facilities. Air Liquide Engineering & Construction, also based in France, licenses the Lurgi Claus process for sulphur recovery from acid gas streams, combining process licensing with execution capability in projects that require gas treatment integration. KT-Kinetics Technology SpA, an Italy-based supplier, offers low-temperature oxidation and sulphur recovery units, providing an alternative pathway for applications that prioritize reduced thermal load and simplified gas cleaning. GTC Technology US, operating from the United States, delivers advanced Claus process and tail gas treating solutions, with a focus on engineered configurations that align with refinery and gas plant operating envelopes. Heurtey Petrochem, based in France, provides sulphur recovery units integrated with petrochemical refining, supporting sites where recovery infrastructure must interface with downstream conversion units. McDermott, headquartered in the United States, engages in sulphur recovery unit design and engineering for gas processing facilities, contributing execution depth in brownfield and greenfield gas infrastructure programs. Sunway Petrochemical Engineering, based in Malaysia, delivers modular sulphur recovery units for regional refineries, a model that is particularly relevant for markets seeking faster deployment timelines and reduced field construction exposure.
Recent project activity illustrates how these players are translating capability into market share. In April 2025, a major engineering and technology provider secured a contract from Saudi Aramco for the modernization of the Haradh and Hawiyah Gas Plants, upgrading sulphur recovery efficiency to 99.9 percent, a benchmark that reflects the industry’s movement toward near-complete sulfur capture in large-scale gas processing complexes. In December 2025, OMV Petrom completed a 45 million euro investment in a new sulphur recovery unit at the Petrobrazi refinery, signaling sustained capital commitment to recovery infrastructure in European refining assets. These developments are not isolated milestones; they represent the types of execution arcs that our research analyzes across technology families, geography, and project scale, enabling clients to benchmark their portfolios against comparable programs and anticipate supplier and licensor behavior.
Segmentation Context and Regional Demand Patterns
The sulphur recovery market is segmented by type, application, and region, each dimension carrying distinct implications for technology selection, supply chain design, and investment prioritization. In terms of type, the market is dominated by the Claus process, which remains the foundational architecture for the majority of installed and planned capacity. Complementary tail gas treatment represents a significant and growing share, reflecting the industry’s shift toward higher capture efficiency and the operational need to handle marginal streams that would otherwise escape primary recovery stages. Application segmentation underscores the market’s anchor in petroleum and coke processing, where desulfurization requirements are structurally embedded in crude throughput and product specification economics, alongside a substantial natural gas segment driven by sour gas processing and gas plant modernization. Additional applications contribute a smaller but strategically important portion, often tied to specialty gas streams and niche processing configurations that require customized engineering responses.
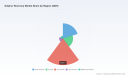
Regionally, demand patterns reflect the geography of refining capacity, gas processing growth, and regulatory intensity. The Asia Pacific segment accounts for the largest portion of market value, consistent with the concentration of refining and gas processing capacity in the region and the ongoing program of capacity additions and efficiency upgrades. North America follows as a significant segment, shaped by mature refining infrastructure, active modernization cycles, and a regulatory environment that maintains continuous pressure on sulfur emission performance. Europe, Latin America, and the Middle East and Africa collectively represent important but comparatively smaller segments in absolute terms, each characterized by distinct project rhythms, feedstock profiles, and compliance timelines. Our research examines these regional dynamics through the lens of project pipelines, technology mix, and supplier presence, but deliberately avoids presenting sub-regional or sub-application percentage breakdowns or discrete monetary figures, ensuring that the strategic narrative remains focused on decision architecture rather than point-in-time snapshots that can quickly become outdated.
What the Report Delivers for 2026 Decision-Makers
This market research is designed as an operational tool for strategy, procurement, engineering, and corporate development teams. It integrates historical market sizing from 2020 through 2025 with a forecast spanning 2026 to 2032, expressed in USD millions, and contextualized within the technological, regulatory, and competitive realities that shape capital deployment. The report provides a structured examination of the primary recovery and tail gas treatment technology families, their integration pathways, and the performance trade-offs that influence licensor selection and engineering scope. It profiles the leading companies by headquarters, technology portfolio, and recent contract and project activity, enabling readers to map supplier capabilities to specific project requirements and risk tolerances. It also details the regulatory environment across key jurisdictions, translating emission limits, permitting rules, and maritime fuel sulfur mandates into practical planning considerations for new installations and existing asset optimization.
Beyond macro and competitive description, the research delivers actionable content for near-term planning. It examines how feedstock variability, particularly hydrogen sulfide concentration ranges typical of gas processing plants, influences unit configuration and tail gas treatment necessity. It assesses the implications of industry-wide pushes toward higher recovery efficiency, including the operational and economic consequences of approaching 99.9 percent capture in large-scale gas plant modernization programs. It evaluates the strategic significance of modular delivery models, brownfield retrofit compatibility, and service-oriented optimization offerings, all of which affect timeline, cost structure, and availability outcomes. The report also provides a framework for evaluating concentration risk within the supplier base, helping procurement and engineering leaders balance incumbency advantages against the need for competitive tension in technology and execution sourcing.
How to Use This Intelligence in the 2026 Planning Cycle
For enterprises preparing investment decisions, capacity plans, or technology roadmaps for 2026 and beyond, the value of this research lies in its ability to connect market-wide behavior to firm-level action. The forecasted growth path and baseline historical trajectory provide a reference for sizing demand expectations and aligning internal capacity or procurement assumptions with market reality. The competitive and technology profiles support supplier evaluation, licensing negotiations, and partnership screening, particularly in contexts where multiple process options are technically feasible but differ in integration complexity, service support, and performance guarantees. The regulatory analysis informs risk-adjusted scheduling, compliance cost modeling, and the prioritization of tail gas treatment investments that may determine whether a facility remains comfortably within permitted limits or faces future retrofitting exposure.
Strategically, the report is intended to be used as a baseline for scenario planning rather than a single-point forecast. Teams can anchor capital allocation models to the central market trajectory while stress-testing assumptions around regional project pacing, regulatory tightening, and supplier capacity constraints. Engineering and procurement leaders can use the company and technology content to refine request-for-proposal scopes, evaluation criteria, and risk registers for upcoming front-end engineering and design phases. Corporate development and investor relations teams can draw on the market concentration and segment structure to frame discussions around competitive positioning, partnership opportunity, and exposure to high-growth demand corridors without relying on discrete sub-segment figures that may shift as project pipelines evolve.
Next Steps
The sulphur recovery market is entering a period in which the intersection of compliance pressure, technology maturity, and regional capacity growth will reward organizations that plan with precision and act with discipline. A compound annual growth rate of 2.51 percent across the forecast window, supported by historical expansion from 2020 through 2025 and a forecast trajectory extending to 2032, provides a credible baseline for strategic modeling, but the real decisions will hinge on technology fit, supplier alignment, regulatory anticipation, and project execution quality. This research is built to support those decisions at the level of detail that matters for 2026 and beyond.
For a complete view of the market structure, including the full segmentation analysis, detailed regional and technology dynamics, supplier capability mapping, and the comprehensive historical and forecast tables, we invite you to access the full report on our website. The complete intelligence package is designed to serve as the foundation for investment committees, engineering strategy reviews, procurement planning, and corporate development assessments, ensuring that your team enters the 2026 planning cycle with a clear, evidence-based understanding of where the sulphur recovery market is headed and how to position accordingly.
For detailed analysis of this topic, please visit the official page: Sulphur Recovery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Document Scanner Market Hits $4.6B in 2025, Nears $6.7B by 2032 at 5.35% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence in the Document Scanner Market: Navigating the 2026–2032 Landscape
The document scanner market has evolved from a peripheral hardware category into a critical enabler of digital transformation, regulatory compliance, and operational resilience. As organizations across government, healthcare, and enterprise sectors accelerate their shift toward paperless workflows, the strategic importance of scanning infrastructure has never been more pronounced. Our latest market research report, Document Scanner Market, delivers a comprehensive, data-driven assessment of this evolving landscape, providing executives, procurement leaders, and technology strategists with the actionable intelligence required to make informed decisions through 2032.
Fiber Optic Converters Market
This analysis is designed for decision-makers who require more than surface-level industry summaries. It maps historical performance, quantifies growth trajectories, dissects competitive positioning, and isolates the regulatory, technological, and operational forces that will reshape procurement strategies in the coming years. The following overview outlines the strategic value embedded in the full report, while preserving the granular segmentation, regional breakdowns, and company-level scoring that constitute the complete intelligence package.
High-end Ventilator Market
Market Trajectory and Structural Shifts (2020–2032)
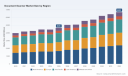
The document scanner market has demonstrated consistent expansion over the past half-decade, with historical performance (2020–2025) establishing a reliable baseline for forward-looking planning. Revenue grew from approximately USD 3,982 million in 2020 to USD 4,645 million in 2025, reflecting steady adoption across enterprise back offices, public sector digitization initiatives, and healthcare record management. A modest contraction observed in 2024 was followed by a rebound in 2025, underscoring the market's sensitivity to procurement cycles, supply chain normalization, and shifting IT budget allocations.
At-Home Spirometer Market
Looking ahead, the forecast period (2026–2032) projects a compound annual growth rate (CAGR) of 5.35 percent, with market revenue expected to reach USD 6,680 million by 2032. This trajectory signals sustained demand, but more importantly, it highlights a structural transition: growth will increasingly be driven by workflow automation, software-integrated capture solutions, and compliance-mandated digitization rather than replacement cycles alone. Organizations that treat scanning hardware as a standalone purchase risk overlooking the broader ecosystem value—integration capabilities, data security protocols, and total cost of ownership models—that will define procurement success in this forecast window.
For enterprise strategists, this growth profile carries several implications. First, the steady expansion suggests that supplier competition will intensify, particularly in price-sensitive segments, making differentiation through software bundling, service-level agreements, and compliance alignment more critical. Second, the projected acceleration in later forecast years indicates that early movers who align their scanning infrastructure with broader digitization roadmaps will secure favorable positioning before capacity constraints or regulatory tightening reshape procurement timelines.
Core Operational and Regulatory Dynamics
The market's trajectory cannot be isolated from the operational and regulatory pressures that are actively reshaping scanning workflows. Several developments in the 2025–2026 window illustrate the complexity that procurement and IT leaders must now navigate.
Regulatory scrutiny around data handling and privacy has intensified across multiple jurisdictions. In the United States, the implementation of Executive Order 14117 brought new requirements for bulk data transfers to countries of concern, effective April 2025, necessitating careful vendor selection and data routing strategies for organizations managing cross-border document flows. Simultaneously, the Connecticut Data Privacy Act (CTDPA) enforcement became fully active in 2026, with an initial fine of USD 85,000 issued in 2025 signaling that compliance is no longer advisory but financially consequential. Under GDPR, organizations processing personal data in document scanning workflows must implement appropriate technical and organizational measures, including encryption and access controls, embedding privacy-by-design principles directly into capture pipelines.
On the operational side, labor efficiency and automated workflows are becoming the primary cost drivers at high scanning volumes. As organizations scale digitization programs, the marginal cost of manual handling, quality control, and exception management can quickly erode the perceived savings of digitization initiatives. This reality is pushing procurement teams to evaluate scanners not merely on throughput speed, but on their ability to integrate with intelligent document processing, metadata extraction, and workflow orchestration layers.
Industry incidents further illustrate the risks of misaligned procurement. The U.S. Internal Revenue Service's scanning operation, which processed 58.7 million pages of historical Forms 709 between December 2023 and early July 2025, was ultimately discontinued due to low volumes and quality issues. This case underscores that volume alone does not guarantee success; process design, vendor capability, and ongoing quality oversight are equally decisive.
Competitive Landscape and Strategic Positioning
The document scanner market is characterized by a concentrated yet diverse competitive field, where established imaging and office equipment manufacturers compete alongside specialized scanning vendors. The broader market structure reflects moderate concentration, with the top three players accounting for a significant share of revenue and the top five firms commanding a dominant portion of the market. This concentration creates both opportunities and constraints for buyers: scale economies and ecosystem integration are advantages, but procurement leverage must be exercised carefully to avoid lock-in or limited negotiation flexibility.
A closer examination of the leading participants reveals distinct strategic orientations that procurement teams should align with their operational priorities:
- Fujitsu focuses on advanced high-speed sheetfed document scanners paired with PaperStream technology, positioning its offerings around enterprise workflow automation and seamless integration. Its strength lies in organizations that require high-volume capture with robust software handoff to downstream processing systems.
- Canon delivers the imageFORMULA series, emphasizing high-speed duplex and flatbed document scanners optimized for office document management and multi-page scanning. Its portfolio suits environments where versatility, image quality, and straightforward deployment are prioritized.
- HP offers portable and desktop document scanners supported by WorkScan software, targeting mobile and office capture solutions. This positioning is relevant for distributed workforces, field operations, and organizations that require flexible capture points beyond centralized scanning rooms.
- Epson provides desktop and flatbed document scanners with automatic document feeder options and TAA-compliant models tailored for government and enterprise use. Recent product activity underscores its commitment to regulated procurement channels and broad industry applicability.
- Brother markets the ADS-series of compact and high-speed desktop document scanners with auto document feeders designed for business environments. Its emphasis on space-efficient, reliable desktop capture appeals to office-dense deployments.
- Plustek specializes in wide-format and professional document scanners, incorporating AI-enhanced scanning capabilities. This positions the company for specialized use cases where format flexibility and intelligent image processing add measurable value.
- Xerox delivers the DocuMate series of duplex document scanners integrated with enterprise document management systems, aligning hardware capture with broader information management ecosystems.
- Visioneer offers the Patriot and intelligent document scanners with OneTouch software for networked and mobile capture, emphasizing streamlined user workflows and connectivity across capture points.
These profiles illustrate that competitive differentiation in the document scanner market is increasingly defined by more than optical performance or feeder capacity. Software integration, compliance readiness, deployment flexibility, and alignment with downstream document management platforms now form the core of vendor evaluation. The full report expands on these positions with detailed segment-level revenue context, capability assessments, and procurement-relevant scoring that enable side-by-side comparison.
Recent Developments Shaping Procurement Decisions
Recent product and software activity provides a concrete window into how vendors are responding to market demands. In May 2025, Epson America launched TAA-compliant desktop document scanners, including the DS-530 II, DS-730N, and DS-870, specifically targeting federal government agencies. This move reflects the growing premium on regulatory alignment within public sector procurement, where TAA compliance can be a gatekeeping requirement rather than a secondary consideration.
Later in June 2025, Epson unveiled new flatbed document scanning solutions, the DS-1730 and DS-1760WN, broadening its reach across a wide range of industries. This expansion signals a strategic emphasis on versatility and multi-industry applicability, particularly for organizations that require reliable flatbed capture for bound documents, fragile materials, or non-standard formats.
In January 2026, Scanbot released version 8.0.0 of its Linux Document Scanner SDK for headless server environments. This software update highlights a parallel trend in the market: the rising importance of server-side, automated capture pipelines that operate without direct user intervention. As organizations scale digitization, SDK-level capabilities that support headless deployment, batch processing, and integration with enterprise server infrastructure become decisive factors in total solution evaluation.
These developments are not isolated product events; they are indicators of where the market is heading. Procurement strategies that account for compliance readiness, format versatility, and software-defined capture will be better positioned to absorb the operational and regulatory shifts expected through the forecast period.
Segmentation Architecture and Strategic Selection Criteria
The document scanner market is structured around multiple segmentation dimensions that collectively determine how organizations evaluate fit, cost, and deployment complexity. While the full report provides detailed revenue breakdowns by region, type, and application, understanding the strategic logic behind these segments is essential for effective procurement planning.
By device type, the market encompasses sheet-fed, portable, and flatbed scanners, each serving distinct operational profiles. Sheet-fed systems are typically associated with high-throughput office and back-office environments where continuous feed and speed are paramount. Portable scanners address mobile, distributed, and field-based capture needs, offering flexibility at the expense of some throughput and ergonomic trade-offs. Flatbed scanners serve use cases that require careful handling of non-standard media, bound documents, or materials that cannot be fed through a roller mechanism. The strategic selection among these types often depends less on isolated performance metrics and more on the composition of the document population, the frequency of capture, and the degree to which scanning must be decentralized.
By application, document scanning demand spans office environments, government operations, and healthcare settings. Each vertical imposes different requirements on throughput, compliance, integration, and auditability. Office deployments typically emphasize ease of use, multi-page handling, and integration with everyday productivity tools. Government use cases frequently introduce TAA compliance, security certifications, and integration with public-sector document management systems as non-negotiable criteria. Healthcare environments add layers of complexity related to sensitive data handling, workflow consistency, and adherence to privacy regulations, where capture infrastructure must align with broader information governance frameworks.
By region, market revenue is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, reflecting varied adoption maturity, regulatory environments, and procurement practices. Regional differences influence not only volume but also the relative importance of compliance, service availability, and total cost of ownership. The full report maps these regional dynamics with precision, allowing organizations to benchmark their expectations against localized market conditions rather than relying on global averages that may obscure critical nuances.
Strategic Value for 2026 Enterprise Decision-Making
The strategic value of this research lies in its ability to convert market complexity into procurement clarity. For enterprise decision-makers operating in 2026, the document scanner market is no longer a simple hardware acquisition category. It is a decision point that intersects with regulatory compliance, workflow automation, data security, service continuity, and long-term digitization roadmaps. The report is structured to support these intersecting priorities through several practical components.
First, it provides a rigorous historical foundation, tracing revenue performance from 2020 through 2025 to establish a reliable baseline against which forecast assumptions can be tested. This historical context is essential for organizations that are calibrating multi-year procurement plans or evaluating whether current market pricing and availability trends are consistent with broader industry patterns.
Second, the forecast period analysis (2026–2032) equips leaders with forward-looking growth expectations, enabling capacity planning, budget forecasting, and technology roadmap alignment. By quantifying the projected CAGR and endpoint revenue, the report gives executives a reference frame for evaluating whether immediate investments, phased rollouts, or vendor diversification strategies are appropriate for their specific operational context.
Third, the competitive landscape assessment translates vendor profiles into procurement-relevant insight. Rather than presenting a static directory of manufacturers, the report contextualizes each participant's strengths, deployment orientations, and ecosystem alignment so that buying teams can match vendor characteristics to their own operational requirements, compliance constraints, and integration needs.
Fourth, the inclusion of recent developments and industry context ensures that decision-makers are working with current signals rather than outdated assumptions. Product launches, software updates, regulatory enforcement actions, and operational case studies are woven into the analysis to illustrate how market forces are actively shifting procurement criteria. This temporal relevance is critical in a market where compliance requirements and software-defined capture capabilities are evolving faster than traditional hardware refresh cycles.
Finally, the segmentation framework supports targeted decision-making by clarifying how device type, application, and regional factors influence fit and value. The full report preserves detailed revenue splits and segment-level context that allow organizations to benchmark their requirements against market structure without relying on generic guidance. This level of specificity is particularly valuable for organizations that operate across multiple regions, manage diverse document populations, or must satisfy varied compliance and integration requirements within a single procurement program.
Why the Complete Report Is Essential
The overview presented here is deliberately structured to demonstrate the depth and strategic orientation of the research while preserving the detailed figures, segment-level breakdowns, regional revenue distributions, and company-specific scoring that constitute the complete intelligence package. Market structure, competitive positioning, and procurement strategy cannot be fully optimized on the basis of macro-level trends alone. They require precise segment context, comparative assessments, and operational benchmarks that are developed through the full analytical framework.
The complete report delivers that precision. It provides the granular market size context, segmentation detail, competitive evaluation, and regulatory mapping needed to support procurement decisions, technology planning, and strategic investment timing through 2032. For organizations that are aligning scanning infrastructure with broader digitization initiatives, evaluating vendor portfolios against compliance and integration requirements, or forecasting multi-year capacity and budget needs, the full analysis offers the evidentiary foundation required to move from general awareness to actionable strategy.
To access the complete Document Scanner Market research, including detailed segmentation data, regional revenue distributions, competitive scoring, and forecast assumptions, please visit the source page for the full report.
For detailed analysis of this topic, please visit the official page: Document Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Long Glass Fiber Reinforced Polypropylene Market Hits US$7,674.32M in 2025, Projected 6.8% CAGR Through 2032
By PW Consulting, 2026-09-07
Navigating the Long Glass Fiber Reinforced Polypropylene Market: Strategic Intelligence for 2026 and Beyond
The global materials landscape is undergoing a structural shift, driven by the simultaneous demands of lightweighting, cost efficiency, and regulatory compliance. Long glass fiber reinforced polypropylene (LGF PP) has emerged as a cornerstone material in this transition, offering an unprecedented balance of mechanical performance, design flexibility, and manufacturability. As organizations map their capital allocation and product development roadmaps for the 2026–2032 horizon, access to precise, forward-looking market intelligence is no longer a luxury—it is a strategic imperative. The newly released Long Glass Fiber Reinforced Polypropylene Market study provides a rigorous, data-anchored examination of this evolving ecosystem, delivering the analytical depth executives need to navigate uncertainty and capture growth.
Battery Management System (BMS) for Energy Storage Market
This overview outlines the strategic architecture of the research, contextualizes the macro trajectory of LGF PP demand, and highlights the operational components that make this study a decision-ready asset for leadership teams, procurement directors, R&D leaders, and competitive strategy units. Rather than presenting isolated statistics, the report weaves historical performance, near-term forecasts, and structural market dynamics into a cohesive narrative designed to inform risk-adjusted planning and product positioning.
Wear Resistant Steel Plate for Mining Market
Market Trajectory and the Strategic Imperative for 2026
Over the past half-decade, the LGF PP market has demonstrated consistent, compounding growth, reflecting the material's broadening adoption across structurally demanding and weight-sensitive applications. The market's revenue baseline in the base year reached approximately 7,674 million USD, building on a historical progression that moved from roughly 5,745 million USD in the early 2020s to sustained mid-7,000 million USD levels by 2024. This upward arc underscores a durable shift in how engineers and sourcing teams evaluate thermoplastic composites versus legacy metal and short-fiber alternatives.
Food Grade L-Fucose Market
The forward outlook reinforces that momentum. Projected revenue is expected to climb past the 8,100 million USD threshold in 2026, continuing along a defined growth corridor toward the 11,000 million USD range by the end of the forecast window. The implied compound annual growth rate of 6.8 percent over the 2026–2032 period signals more than incremental expansion; it reflects a structural reallocation of material spend toward long-fiber reinforced polypropylene in applications where stiffness, impact resistance, and thermal stability must coexist with processing efficiency.
For 2026 decision-making, this trajectory carries several strategic implications. First, organizations that delay capacity planning, qualification investments, or supplier diversification risk entering a tightening supply-demand environment where premium grades and specialized formulations command stronger pricing power. Second, the growth corridor suggests that LGF PP is transitioning from a niche engineering solution into a mainstream structural material across multiple verticals, which in turn reshapes competitive benchmarks, regional sourcing strategies, and technology roadmaps. Third, the forecast window provides sufficient lead time for manufacturers to align capital projects, tooling transitions, and application-specific compound development with anticipated demand waves, provided they have granular visibility into where growth concentrates and which end-use drivers are most resilient.
The full study translates these macro movements into a structured, decision-oriented framework. It does so without overwhelming leadership with fragmented figures, instead emphasizing the relationships between historical performance, forecast assumptions, and the operational variables that can accelerate or compress realization timelines.
Report Architecture and Operational Utility
A market study only earns executive trust when it bridges high-level trends with actionable research design. The Long Glass Fiber Reinforced Polypropylene Market report is built around that principle, organizing its analysis into clearly defined sections that support practical decision-making across commercial, technical, and supply chain functions.
Scope and Analytical Framework
The research anchors its quantitative modeling in a transparent historical base, then extends into a forward-looking forecast period designed to capture the product lifecycle inflection points most relevant to corporate planning. The study evaluates the market through multiple structural lenses, including formulation and fiber architecture distinctions, application-driven demand logic, and regional pricing and volume dynamics. Each lens is cross-referenced with supply-side considerations—such as resin availability, compounding economics, and fiber cost behavior—so that readers can assess where end-market demand intersects with input cost sensitivity.
Core Analytical Modules
The report's structure is designed to support multiple use cases. Executive and strategy teams can leverage the market sizing and trajectory sections for top-down portfolio and investment planning, while engineering and procurement teams can reference the application and type-based analyses to prioritize qualification pathways and supplier engagement. The competitive assessment module adds another layer of operational relevance by mapping how leading producers position their product architectures, which technical claims differentiate their offerings, and where capacity or geographic footprint may influence future supply reliability.
- Historical baseline review with sequenced revenue progression and contextual interpretation of growth inflection points
- Forward-looking forecast modeling that connects demand drivers to revenue projections across the 2026–2032 window
- Structural segmentation analysis that isolates the key demand logic for fiber architecture types and major end-use verticals
- Regional perspective that frames volume, pricing, and adoption dynamics across key geography clusters without reducing the picture to single-factor conclusions
- Competitive landscape assessment covering leading global and regional suppliers, their product positioning, and strategic differentiation
- Market dynamics evaluation incorporating regulatory pressure, raw material cost behavior, and downstream adoption incentives
- Decision-support synthesis for capacity planning, application qualification, supplier diversification, and pricing strategy
Importantly, the report avoids treating segmentation data as a static catalog. Instead, it interprets the relative weight and interaction of categories to help decision-makers understand where demand is being created, where substitution risk is low, and where formulation or processing advantages can win share. The detailed numeric breakdowns, region-level shares, and application-specific revenue allocations are presented in the full study so that leadership teams can perform their own scenario testing and internal benchmarking without relying on second-order approximations.
Competitive Landscape: Positioning, Differentiation, and Supply Strategy
The LGF PP market is shaped by a concentrated but strategically diverse supplier base. Competitive advantage in this space is rarely a function of scale alone; it depends on the ability to deliver consistent fiber-matrix adhesion, tailored compounding architectures, and application-specific validation support. The report evaluates the leading participants through the lens of product architecture, technical positioning, and market-facing value propositions, offering a practical map for procurement, partnership, and benchmarking decisions.
SABIC stands out for its emphasis on engineering-grade LGF PP resins designed for automotive lightweighting and structural applications, signaling a strategy centered on performance validation and OEM-adjacent use cases. BASF SE reinforces its technical materials heritage through its Ultramid® portfolio, aligning long glass fiber reinforced polypropylene with demanding technical applications where mechanical consistency and process reliability matter. LyondellBasell Industries N.V. contribute a compound-focused approach built on proprietary resin platforms, targeting automotive and structural applications where resin-grade control and compound design intersect.
Japan Polypropylene Corporation brings a distinctive processing emphasis, leveraging proprietary melt impregnation technology to deliver its FUNCSTER™ and WAYMAX™ compound families. This manufacturing orientation highlights the importance of process engineering as a differentiator, especially for customers seeking repeatability and fiber length retention in complex molded components. RTP Company operates with a strong customization focus, producing long glass fiber reinforced polypropylene compounds tailored for automotive compliance across major North American OEMs, which positions the company as a solutions-oriented partner for specification-sensitive programs. Avient Corporation extends the structural replacement narrative through its OnForce™ portfolio, targeting high-stiffness applications where designers seek to replace heavier components without sacrificing load-bearing performance.
Celanese Corporation reinforces the engineered polymers angle with its Celstran® grades, connecting long glass fiber reinforced polypropylene to broader technical polymer ecosystems and automotive requirements. Mitsui Chemicals, Inc. completes the competitive picture with a multi-regional manufacturing footprint spanning Japan, the United States, and China, giving it flexibility to serve geographically dispersed demand and to adapt to regional cost and supply dynamics.
The market's competitive structure is notably concentrated, with the top three participants holding a substantial share of total market revenue and the top five collectively representing the majority of industry activity. This concentration has practical implications. For buyers, it suggests that supplier qualification, dual-sourcing strategies, and relationship-based technical support will remain critical, especially for programs that require consistent fiber performance or extended validation cycles. For producers, it underscores the need to defend share through formulation IP, customer-specific compound optimization, and regional service capability rather than relying on commodity positioning alone. The study's competitive assessment section expands on these dynamics with supplier-by-supplier context, helping readers identify where differentiation is authentic and where market claims may be overstated.
Industry Dynamics, Regulatory Tailwinds, and Cost Realities
The LGF PP market does not evolve in isolation. Its adoption curve is tightly coupled to regulation, raw material economics, and downstream engineering priorities. The report integrates these forces into a unified market dynamics view so that strategic planners can separate durable tailwinds from cyclical noise.
Regulatory pressure remains one of the most significant adoption accelerants, particularly in automotive. European CO2 frameworks have set progressively demanding fleet emission targets, including the mandate for average emissions of 93.6 grams per kilometer by 2025 and a further requirement for 55 percent CO2 reduction by 2030 relative to 2021 levels. These targets create a direct incentive for weight reduction in structural and underbody components, where long glass fiber reinforced polypropylene can deliver meaningful mass savings while maintaining stiffness and durability. In North America, EPA standards calling for average fleet CO2 reduction to 162.5 grams per mile by 2030 similarly reinforce the case for lightweight structural materials, especially in applications where metallurgy can be partially displaced without compromising functional requirements.
Regulatory momentum alone, however, does not guarantee adoption. Material substitution decisions must also clear cost, processing, and validation hurdles. That is where raw material cost behavior becomes operationally relevant. Glass fiber pricing in the United States reached 1,458 USD per metric ton in December 2025, with a downward trend emerging as domestic demand from construction eased in the fourth quarter of 2025. This sort of input cost movement can shape compound economics, margin structure, and supplier pricing negotiation dynamics, particularly for programs that are sensitive to fiber cost allocation. At the same time, broader resin economics are also in motion: industry data indicates that propylene price increases have driven compounded PP resin prices higher in the UK, with increases holding steady through the first quarter of 2025. Together, these signals show that LGF PP economics are influenced by both fiber-side and resin-side variables, requiring procurement and planning teams to monitor multiple cost channels rather than a single commodity benchmark.
The report uses these dynamics to frame a more nuanced interpretation of growth. Rather than assuming linear expansion, the analysis distinguishes between demand that is regulatory-led, demand that is performance-led, and demand that is cost- or supply-constrained. This layered view helps organizations anticipate where adoption may accelerate quickly, where qualification cycles may slow near-term uptake, and where pricing volatility could alter project economics. Readers seeking the full regional and segment-level interpretation of these cost and regulatory factors will find the detailed synthesis in the complete study.
Strategic Applications: Where Performance Meets Commercial Value
One of the most decision-relevant dimensions of the LGF PP market is the distinction between application drivers. Not all end-use categories expand for the same reason, and not all programs derive value from the material in the same way. The study isolates the principal application engines to help leaders understand where the strongest commercial logic resides and where program-specific qualification may be the key gating factor.
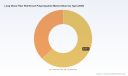
Automotive remains the most prominent demand anchor, reflecting the intersection of lightweighting mandates, structural component replacement, and the need for molding-friendly thermoplastic solutions. In this environment, LGF PP is valued not simply for weight reduction, but for the combination of stiffness, impact performance, and manufacturability that enables designers to consolidate parts and optimize assemblies. Aerospace demand reflects a different logic, where the emphasis is on technical reliability, weight efficiency, and the ability to meet rigorous application requirements in specialized structures and interior or secondary structural elements. Electrical and electronics applications, meanwhile, are driven by the material's potential to support functional performance and design flexibility in environments where thermal and mechanical behavior must coexist with tight tolerances and specific processing needs.
Construction and consumer goods extend the material's reach into additional value contexts, but with distinct adoption drivers. Construction-related demand is shaped by durability, cost-effectiveness, and the need for materials suited to structural or semi-structural uses where long-fiber reinforcement can improve performance relative to unreinforced or short-fiber alternatives. Consumer goods applications tend to be more design- and cost-led, relying on the material's ability to deliver specific aesthetic and functional qualities while maintaining processing efficiency.
The report's application analysis is built to help readers move beyond generic category labels. It frames each vertical in terms of adoption rationale, substitution potential, and the technical or commercial criteria that typically determine whether a program advances. The detailed revenue allocation and growth logic behind each application segment are presented in full within the study, allowing teams to test assumptions against their own product roadmaps and customer portfolios.
What 2026 Decision-Makers Should Take Away
The Long Glass Fiber Reinforced Polypropylene Market study is designed for organizations that need more than a directional headline. It provides the connective tissue between market sizing, competitive behavior, regulatory momentum, and cost dynamics, enabling leaders to make 2026 decisions with greater confidence and fewer assumptions.
For strategy and corporate development teams, the report offers a credible basis for investment prioritization, geographic focus, and product portfolio signaling. For procurement and supply chain leaders, it supports supplier evaluation, risk mapping, and negotiation preparation by clarifying where concentration, regional supply footprints, and input cost behavior shape buyer leverage. For R&D and application engineering groups, it provides a framework for prioritizing compound qualification, selecting fiber architecture strategies, and aligning development resources with the application categories most likely to deliver near-term commercial impact.
The macro picture is clear enough to set direction: the market is expanding along a defined growth corridor, supported by regulatory pressure in key automotive markets and by the widening recognition that long-fiber reinforced polypropylene can deliver structural performance in a processing-friendly thermoplastic format. Yet the real strategic advantage comes from the details that sit beneath that headline—the relative weight of application drivers, the competitive differentiation that will matter most in qualification-heavy programs, and the cost and regulatory variables that can compress or extend adoption timelines. Those details are developed in depth in the complete research, where region-and-segment-level data, competitive profiles, and dynamic modeling are fully accessible for internal analysis.
For organizations preparing for the 2026–2032 cycle, the most valuable move is to anchor planning in a structured, validated market view before committing capital, qualification spend, or supplier commitments. This study provides that foundation, giving teams the context they need to convert market momentum into disciplined, executable strategy.
Accessing the Full Intelligence
The overview above is intended to demonstrate the analytical framework and strategic relevance of the research while preserving the full depth of data for detailed review. The complete Long Glass Fiber Reinforced Polypropylene Market study contains the comprehensive market sizing progression, segmentation breakdowns, regional revenue context, application-level analysis, and competitive profiles necessary for scenario planning and internal benchmarking. Leadership teams that need granular figures, region-and-segment-level allocations, and the full supplier-by-supplier competitive mapping will find those resources in the full report, where the data is structured for direct use in investment committees, procurement reviews, and product strategy sessions.
For teams seeking to translate market momentum into 2026 action plans, the full study offers the specificity required to move from directional confidence to operational execution.
For detailed analysis of this topic, please visit the official page: Long Glass Fiber Reinforced Polypropylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Safety Glasses Market to Hit $225.5M in 2025, 4.05% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Eye Protection: Navigating the Safety Glasses Market Through 2032
As industrial environments grow increasingly complex and regulatory frameworks evolve, the safety glasses market has emerged as a critical intersection of compliance, innovation, and strategic procurement. PW Consulting’s latest market research report provides a comprehensive, data-driven examination of this sector, offering enterprise decision-makers the intelligence required to navigate competitive pressures, anticipate demand shifts, and align product portfolios with emerging occupational safety mandates. This overview articulates the strategic value of the report for 2026 corporate planning, outlining the macro trajectory, competitive dynamics, regulatory catalysts, and operational dimensions that define the landscape without disclosing the granular segment-level intelligence contained in the full study.
Compaction Equipment Rental Market
Market Trajectory and Revenue Context
The safety glasses industry has demonstrated consistent expansion over the past half-decade, with revenue trends reflecting steady procurement cycles across industrial, construction, and specialized application verticals. From a baseline exceeding $185 million in 2020, the market has advanced through successive growth phases, reaching approximately $225.5 million by 2025. Our forecasting framework projects this trajectory to continue through 2032, with a compound annual growth rate of 4.05 percent. By the close of the forecast horizon, total market revenue is positioned to approach the $300 million threshold, underscoring a sector characterized by mature demand foundations and moderate but reliable expansion.
Lawnmower Oil Market
It is important to recognize that historical performance and forward-looking projections are shaped by distinct structural drivers. Procurement patterns, regulatory compliance cycles, material innovation, and regional industrial activity all contribute to the revenue arc. The report dissects these drivers in detail, mapping how macroeconomic conditions, supply chain normalization, and workplace safety investments intersect to influence purchasing velocity. Rather than presenting surface-level aggregates, the analysis isolates the mechanisms behind revenue movement, enabling leaders to differentiate between cyclical noise and structural growth signals.
Power Bank Charging Station Market
Report Scope and Analytical Architecture
The study is engineered to serve multiple decision-making functions: portfolio planning, competitive benchmarking, procurement strategy refinement, and market entry assessment. Its architecture spans historical baselines, forward-looking forecasts, segmentation logic, and competitor profiling, all structured to translate raw market data into actionable strategy. The following components form the analytical backbone of the report.
Core Analytical Dimensions
- Historical performance tracking across the 2020 to 2025 evaluation window, establishing baseline momentum and identifying inflection points in demand behavior.
- Forward projection modeling covering the 2026 to 2032 horizon, with scenario-aware forecasting that accounts for regulatory timing, product lifecycle transitions, and regional procurement rhythms.
- Material and product-type analysis examining how lens composition, coating technologies, and frame engineering influence adoption patterns and pricing dynamics.
- Application vertical mapping that connects safety eyewear demand to operational environments, clarifying which sectors drive volume, which demonstrate higher margin potential, and where specialization commands procurement premiums.
- Competitive landscape profiling that evaluates market share distribution, product positioning, and strategic maneuvering among leading manufacturers.
- Regulatory and standard-development tracking that links compliance milestones to market behavior, enabling leaders to anticipate certification-driven purchasing shifts.
Each dimension is supported by data tables, analytical commentary, and contextual interpretation designed for executive review. The report avoids static listing in favor of connective analysis, demonstrating how material preferences interact with application requirements, how competitive concentration shapes pricing tolerance, and how standard revisions propagate through procurement pipelines. Decision-makers gain not just a snapshot of market size, but a working model of how the market operates and where leverage points emerge.
Competitive Landscape and Strategic Positioning
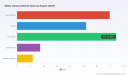
Market concentration data reveals a moderately consolidated environment. The three largest participants collectively account for a combined share just above one-third of total revenue, while the top five firms extend their footprint to slightly more than half of the market. This concentration profile indicates the presence of established players with durable distribution networks, brand recognition, and compliance-certified product lines, alongside sufficient fragmentation to allow specialized entrants and regional manufacturers to capture niche demand.
Our report profiles a cross-section of influential companies whose product strategies and certification portfolios illustrate the competitive dynamics shaping the sector.
Leading Participants and Strategic Profiles
Wiley X operates from a US base with a focus on ballistic and industrial safety eyewear engineered for high-impact resistance and chemical exposure scenarios. Its lens coating technologies and ANSI Z87.1-rated product lines reflect a positioning strategy that emphasizes protection performance in demanding operational contexts.
Bollé Safety , headquartered in France, emphasizes certified protection with anti-fog and anti-scratch performance as core differentiators. Its PLATINUM-coated offerings align with ANSI Z87.1 and OSHA standards, demonstrating how coating durability and optical clarity serve as recurring procurement drivers in environments where lens degradation accelerates replacement cycles.
uvex Safety Group brings a German engineering orientation to the market, offering safety glasses and goggles that meet ANSI/ISEA Z87.1 standards while extending into prescription and specialized models. Its portfolio breadth illustrates how manufacturers compete not only on impact performance but also on wearer comfort, optical precision, and integration with existing vision correction requirements.
MCR Safety supplies ANSI Z87.1-compliant eye protection with military-grade and UV-blocking options tailored to industrial applications. Its emphasis on performance-grade specifications positions it within segments where hazard intensity and certification rigor influence purchasing decisions.
Honeywell contributes a broad safety portfolio that spans impact, chemical, and splash protection use cases. Its certified product range reflects the advantage of scaled distribution and cross-category integration, allowing enterprise buyers to consolidate procurement across multiple personal protective equipment categories.
MSA Safety manufactures safety glasses and goggles with prescription options and ANSI Z87.1 certification for general industry and construction contexts. Its product strategy demonstrates how compliance certification paired with prescription adaptability supports sustained demand in settings where worker vision requirements intersect with hazard protection mandates.
Essilor’s prescription safety eyewear division operates through partnerships with frame manufacturers to deliver ANSI Z87.1 and OSHA-compliant prescription solutions. This collaborative model highlights the role of specialty vision correction in the broader safety glasses market, where ergonomic fit and optical performance influence adoption among workers requiring corrective lenses.
Radians Safety offers GLYF™ and ballistic-rated eyewear compliant with ANSI Z87.1, with a product emphasis on comfort and debris protection. Its recent GLYF™ and Crossfire BOLO™ introductions underscore the ongoing innovation cycle around wearer comfort, ballistic performance, and industrial usability.
Day Sun Industrial Corp. , based in Taiwan, produces ANSI Z87.1 and CE-certified safety glasses with anti-scratch and UV protection for industrial use. Its dual certification footprint illustrates how manufacturers adapt product lines to serve both regional regulatory expectations and export-oriented compliance requirements.
The report does not stop at descriptive profiling. It evaluates how these participants position themselves relative to one another, where certification alignment creates procurement lock-in, and where product differentiation enables margin expansion. It also examines how competitive concentration interacts with regional demand patterns, allowing buyers and sellers alike to understand where pricing tension exists and where substitutability is highest.
Regulatory Catalysts and Industry Dynamics
Regulatory and standards activity represents one of the most consequential forces shaping demand behavior, procurement timing, and product redesign cycles. In January 2026, The Vision Council published ANSI/ISEA Z87.1-2025, the sixth revision of the voluntary consensus standard for occupational eye and face protection devices. Developed by the Z87 Committee on Safety Standards for Eye Protection, this revision sets updated criteria for testing, marking, and use across occupational hazard scenarios. The standard emphasizes harmonization with global benchmarks and addresses performance requirements for diverse workplace hazards, including chemical exposure and radiation-related risks.
OSHA 1910.133 continues to function as a central compliance reference point. It requires safety glasses to comply with ANSI/ISEA Z87.1 editions including 2010, 2003, or 1989 with its 1998 revision, and it also accommodates the 2025 revision for hazard protection spanning impact, radiation, and liquid splash scenarios. The standard further mandates side shields for flying debris protection in general industry under ANSI Z87.1 requirements. For procurement leaders, these regulatory anchors create both continuity and transition pressure. Existing certified inventory may remain acceptable under legacy reference points, yet forward procurement increasingly aligns with the updated revision, prompting product refreshes, coating upgrades, and side-shield integration to meet evolving compliance expectations.
Recent corporate developments reinforce the significance of these regulatory and product cycles. In January 2026, MCR Safety released its 2026 Eye Protection Catalog, featuring updated styles, advanced coatings, and ANSI Z87+ impact-rated options. Radians Safety followed in February 2026 with the introduction of GLYF™ Safety Eyewear and Crossfire BOLO™ ballistic-rated eyewear, showcased at the NSC Expo. Later in the year, uvex Safety Group scheduled participation at INTERSCHUTZ 2026 in Hannover, presenting new product lines for safety glasses and goggles. These moves illustrate how manufacturers use catalog refreshes, product launches, and trade-show visibility to signal compliance alignment, technological advancement, and category leadership.
The report integrates these developments into a broader dynamics framework, mapping how standard revisions, certification references, and product innovation cycles interact to influence purchasing calendars, specification upgrades, and competitive repositioning. By contextualizing regulatory updates within procurement behavior, the analysis helps leaders anticipate when compliance-driven replacement demand may accelerate and how specification changes can alter supplier evaluation criteria.
Segmentation Logic and Strategic Intelligence Design
While the full report provides detailed segment-level revenue and share breakdowns, this overview deliberately preserves depth for the complete study. What can be outlined here is the analytical logic that underpins the segmentation framework and the strategic value it delivers to decision-makers.
Material and Product-Type Analysis
Safety glasses are commonly evaluated through the lens of material composition, with polycarbonate, glass, and other engineered materials each presenting distinct performance and cost profiles. Polycarbonate-based products typically command attention in high-impact contexts due to their ballistic tolerance and lightweight characteristics, while glass and alternative materials serve use cases where optical clarity, scratch resistance, or cost considerations shape procurement choices. The report examines how material preferences vary across application requirements, how coating technologies amplify or mitigate material limitations, and how procurement teams weigh performance trade-offs against total cost of ownership. Rather than presenting raw segment shares in isolation, the analysis connects material adoption to hazard profiles, replacement frequencies, and compliance specifications, enabling a functional understanding of why certain product types gain traction in particular environments.
Application Vertical Mapping
Demand for safety eyewear is distributed across industrial manufacturing, construction, and a broader set of application contexts. Each vertical exhibits distinct purchasing rhythms, specification priorities, and compliance drivers. Industrial manufacturing environments often emphasize impact resistance, chemical protection, and durable coatings that withstand continuous exposure. Construction settings may prioritize side-shield compliance, anti-fog performance, and ergonomic fit for workers moving across variable site conditions. Other application segments contribute additional complexity, with specialized hazard profiles that can elevate demand for prescription integration, radiation protection, or customized frame geometry.
The report maps these application dynamics without reducing them to static allocations. It examines how vertical-specific procurement criteria influence supplier selection, how replacement cycles differ by operational intensity, and where specialization creates pricing resilience. This vertical lens enables leaders to identify which environments offer steady volume, which present higher specification requirements that can support premium positioning, and how demand migration may occur as hazard exposure profiles evolve.
Regional Demand Awareness
Regional analysis forms another essential layer of the study. While specific regional revenue figures and share percentages are reserved for the complete report, the segmentation architecture acknowledges that demand patterns vary according to industrial activity, regulatory enforcement intensity, certification adoption, and distribution maturity. North American, European, Asia Pacific, Latin American, and Middle East and Africa markets each present distinct procurement ecosystems, with local standards alignment, channel structures, and competitive presence shaping how safety glasses are specified, sourced, and substituted. The report provides a comparative regional framework that helps leaders interpret where demand density concentrates, where certification harmonization influences sourcing decisions, and where growth acceleration may emerge as industrial safety investment expands.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle offers a pivotal moment for enterprises operating in or adjacent to the safety glasses market. Standard revisions are translating into specification updates, manufacturers are refreshing catalogs and launching new product lines, and procurement teams are recalibrating supplier evaluation criteria around compliance, comfort, and durability. In this environment, strategic advantage depends on the ability to distinguish trend from noise, anticipate certification-driven purchasing shifts, and align product or sourcing strategies with durable demand drivers.
The report is designed to support that effort across several decision domains.
Portfolio and Product Strategy
For manufacturers and brand owners, the study provides context on where performance differentiation commands procurement attention and where specification convergence compresses competitive differentiation. It examines how coating technologies, lens materials, side-shield compliance, and prescription integration influence buyer preference, and it identifies the product attributes most closely associated with sustained demand in high-hazard environments. This enables portfolio leaders to prioritize development investments, refine product roadmaps, and align launch timing with certification and trade-show cycles.
Procurement and Sourcing Strategy
For buyers, the report clarifies how compliance references, certification editions, and standard revisions shape acceptable product specifications over time. It helps procurement teams anticipate when legacy-compliant inventory may remain sufficient and when updated revision alignment will increasingly drive replacement demand. By mapping application requirements to material and coating preferences, the study supports more precise specification writing, supplier comparison, and total-cost evaluation. This reduces the risk of over-specifying in low-hazard contexts or under-specifying in high-exposure environments.
Market Entry and Competitive Positioning
For organizations assessing expansion opportunities, the analysis frames the competitive landscape in terms of concentration, specialization, and regional demand heterogeneity. The moderate concentration profile suggests that established players hold meaningful share, but the environment also leaves room for entrants that can differentiate through certification alignment, application specialization, or regional channel strength. The report evaluates where competitive overlap is highest, where niche demand remains underserved, and how regional certification dynamics influence entry feasibility. This allows market developers to target segments where their capabilities create the strongest fit rather than pursuing undifferentiated volume plays.
Why the Full Report Matters
An overview such as this establishes the strategic terrain, but the complete study delivers the segment-level precision required for execution-grade planning. It contains detailed revenue trajectories, segmentation breakdowns, competitive share distributions, application-specific demand dynamics, and regional performance comparisons that transform high-level insight into operational intelligence. It also integrates the most recent regulatory developments, product launches, and trade-show activity into a forward-looking framework, enabling leaders to connect near-term events with multi-year demand behavior.
The full report is intended for executives, category managers, product strategists, and procurement leaders who need to make specification, sourcing, and investment decisions with confidence. It provides the evidentiary base for portfolio prioritization, supplier negotiation, market entry assessment, and compliance-aligned procurement planning. By consolidating historical performance, forecast modeling, segmentation logic, and competitive profiling into a single analytical structure, the study reduces the time required to reach informed conclusions and increases the reliability of the resulting strategy.
Closing Perspective
The safety glasses market is defined by a balance of steady growth, compliance-driven specification shifts, and continuous product innovation. With revenue advancing from a strong 2025 baseline toward a forecast near the $300 million mark by 2032 and a CAGR of 4.05 percent, the sector offers durable expansion for participants who can align product capability with workplace hazard requirements and procurement expectations. Yet the strategic value of this market lies not in its size alone, but in the precision with which leaders can interpret certification dynamics, material preferences, application demands, and competitive positioning.
PW Consulting’s Safety Glasses Market research is built to deliver that precision. It equips decision-makers with the analytical depth required to navigate a moderately consolidated, regulation-sensitive, and technology-evolving landscape. The complete report contains the segment-level detail, regional comparisons, and competitor evaluations necessary to convert strategic intent into executable planning. For organizations preparing for 2026 and beyond, this study provides the intelligence foundation needed to act with clarity, prioritize effectively, and maintain alignment with the standards and performance expectations that shape occupational eye protection today.
For detailed analysis of this topic, please visit the official page: Safety Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Autoclave Market to Hit $399.1M by 2032 as Revenue Surpasses $309M in 2025
By PW Consulting, 2026-09-07
Strategic Intelligence for the Dental Autoclave Market: Navigating Growth and Compliance in 2026
The global dental equipment landscape is undergoing a structural shift, driven by tightening infection-control mandates, digital workflow integration, and sustained capital investment in outpatient care infrastructure. At the center of this transformation sits the dental autoclave, a foundational sterilization asset that has evolved from a simple pressure chamber into a networked, compliance-critical node within the modern dental practice. This latest market research from PW Consulting is designed to give executives, procurement leaders, and product strategists a clear, decision-ready view of where the industry stands today and how it will unfold through the end of the decade.
Rotating Shield Tunneling Machine Market
The analysis is anchored in a rigorous historical-reconstruction methodology spanning 2020 through 2025, followed by a forward-looking forecast window that carries the narrative from 2026 into 2032. Rather than presenting a static snapshot, the study treats market size as a moving indicator shaped by regulatory momentum, purchasing cycles, and technology adoption curves. In 2025, the overall dental autoclave market reached 309.0 million USD in revenue, reflecting a compound annual growth trajectory of approximately 3.69 percent over the base-to-forecast span. The outlook extends this momentum into the late 2020s and early 2030s, with projected revenue climbing toward 327.58 million USD in 2026, advancing to 337.78 million USD by 2028, and reaching 359.63 million USD in 2030 before approaching 399.1 million USD by 2032.
Portable Oil Fume Recorder Market
These figures are more than macroeconomic placeholders. They are the connective tissue between clinical compliance requirements, capital-budget planning, and competitive positioning. For organizations evaluating capacity expansion, product-line evolution, or market-entry timing, the numbers serve as a shared reference point for scenario modeling. The report does not stop at aggregate sizing; it translates the trajectory into operational implications, helping teams align equipment investment with the pace of practice modernization and the cadence of regulatory change.
Stranding Dies Market
Why This Research Matters for 2026 Decision-Making
2026 is a pivotal inflection point for the dental sterilization sector because it sits at the intersection of two converging forces: the implementation of newly effective quality-management frameworks and the maturation of digitally enabled sterilizers. For manufacturers, distributors, and practice owners alike, the strategic question is no longer whether compliance will become more demanding, but how quickly traceability, cycle validation, and automated verification will transition from desirable features to non-negotiable purchase criteria. This report frames that transition in terms that support concrete action.
A second strategic driver is the shift in purchasing behavior across end-user profiles. Dental clinics, hospitals, and a broader category of service and support users each bring distinct procurement rhythms, volume expectations, and operational priorities. Understanding how these segments interact with product classes and regional pricing environments allows teams to allocate go-to-market resources more efficiently and to calibrate product configurations for the right mix of throughput, footprint, and connectivity. Where competitors often publish broad market narratives, this research is built to support granular decision-making without drowning readers in superficial categorization.
A third consideration is the regulatory environment itself. Recent FDA recognition of ISO 17665-1 in December 2024 established a benchmark for documented cycle validation and traceability, while the Quality Management System Regulation that took effect in February 2026 introduced end-to-end sterilization traceability expectations for dental devices. These developments have real procurement implications. They raise the cost of non-compliance and materially increase the appeal of equipment that can generate reliable, auditable sterilization records with minimal manual intervention. In parallel, CDC audit findings from mid-2024 indicated that a significant share of dental practices fail routine spore tests, reinforcing demand for autoclaves with automatic verification and reducing the tolerance for manual, error-prone workflows. Meanwhile, European standards developments have extended harmonized coverage to small steam sterilizers used in dental settings, further raising the baseline for product qualification in key export markets.
Taken together, these forces make the 2026 decision environment unusually sensitive to timing. Teams that wait for the market to settle risk losing ground to rivals who already understand where value is migrating and which product attributes are becoming table stakes. This report is designed to shorten that learning curve and give readers a defensible basis for planning in the coming twelve to twenty-four months.
Report Coverage: From Market Structure to Actionable Intelligence
A high-quality industry study earns its value by converting data into operational clarity. This research is built around that principle, with coverage organized to support both strategic oversight and tactical execution. The report begins with a fully reconciled market sizing framework that links historical performance to forward projections, giving readers a consistent reference for revenue trends, volume implications, and timing of expected growth phases. The forecast architecture is deliberately structured to support sensitivity analysis rather than single-point certainty, so decision-makers can test assumptions against different adoption speeds, regulatory enforcement levels, and capital-budget constraints.
The segmentation architecture is treated as a decision lens rather than a static taxonomy. Product-oriented analysis distinguishes automatic, semi-automatic, and manual configurations and examines how each category performs against workflow complexity, staffing models, and compliance expectations. End-user analysis separates dental clinics, hospitals, and other service environments to reveal how purchasing drivers differ across settings, while regional analysis maps demand patterns to local regulatory intensity, practice density, and investment capacity. For executives who need to decide where to prioritize channel investment or product specialization, this layered structure provides a practical roadmap without exposing the full quantitative splits in isolation.
Beyond sizing and segmentation, the report delivers a competitive landscape assessment that goes beyond nameplate recognition. The analysis examines how leading manufacturers are differentiating through cycle design, chamber volume, water and energy efficiency, digital monitoring, and cloud-connected service support. The report also traces recent product activity to show how incumbents are responding to the same compliance and workflow pressures shaping buyer demand. This approach allows readers to benchmark their own positioning, identify gaps in value propositions, and anticipate where competitive intensity is likely to intensify.
Operational coverage extends into procurement and deployment considerations that often get overlooked in high-level market summaries. The report addresses how validation documentation, cycle reliability, maintenance support, and remote-service capabilities influence the total cost of ownership over the equipment lifecycle. By integrating these factors with the broader demand narrative, the study helps purchasing teams evaluate options on more than initial price and helps manufacturers understand which service and software capabilities are becoming monetizable differentiators.
Competitive Landscape: Differentiation Shaping the Next Cycle
The market’s competitive structure reflects a broad spread of regional manufacturing strengths and product philosophies, but it is increasingly defined by a few recurring battlegrounds: automation, traceability, and workflow integration. The companies profiled in this research illustrate how those battlegrounds are translating into product strategy.
Tuttnauer has emphasized tabletop and bench-top dental autoclaves built around Class B cycles, fast-cycle options, and smart sterilization tracking for clinics. Its July 2024 introduction of the Elara11 autoclave, which added front or top water-fill options and upgradeable pre/post-vacuum cycles, highlights a design philosophy centered on configuration flexibility and procedural control. MELAG Medizintechnik, based in Germany, has pushed a complementary angle with fully automated high-capacity and tabletop sterilizers that emphasize sustainable water and energy use alongside digital monitoring. This positions MELAG as a specialist in efficiency-linked compliance rather than raw throughput alone.
Dentsply Sirona brings scale and integrated workflow thinking to the category, manufacturing dental-specific autoclaves with instrument-processing workflows built into the broader clinical ecosystem. Dürr Dental contributes the Hygoclave series, targeting dental practices with high chamber volumes and cycle reliability, an approach that resonates where throughput consistency is a primary procurement concern. W&H Dentalwerk has focused on smart digital integration and cloud connectivity through its B-type Lina sterilizer series, and its September 2024 launch of the Lina sterilizer Smart Edition reinforced the industry’s movement toward digitally enhanced sterilization efficiency.
In the large-capacity segment, Flight Dental Systems specializes in high-capacity steam sterilizers such as the Clave45+, designed for large dental and lab facilities. Its October 2024 launch of the Clave45+ with closed-door drying demonstrated a continued push toward dry-load reliability and higher-volume throughput. Mocom has pursued a cloud-centric bench-top strategy, with its upgraded B Classic+ featuring full cloud integration for cycle tracking and remote service alerts, a signal that smaller-footprint equipment is increasingly being evaluated as a connected device rather than a standalone appliance.
The Asian manufacturing landscape adds important competitive variation. Tomy Seiko produces ES-series tabletop dental autoclaves certified for high-volume sterilization in dental settings, while Hirayama Manufacturing offers HV-series and HV-Ⅱ dental autoclaves with vacuum drying and color touch-panel controls, an example of how user interface and drying performance are becoming part of product differentiation. Kenz rounds out the competitive field with CS-series dental autoclaves aimed at reliable tabletop clinic use. Outside these core groups, Eschmann Technologies supplies Ses series tabletop autoclaves for dental instrument sterilization, and Biobase has built a presence around cost-effective dental autoclaves with an emphasis on basic sterilization cycles.
What connects these companies is not product similarity but a shared need to adapt to a market where compliance documentation, verification reliability, and digital service capabilities are increasingly priced into purchasing decisions. The report examines where these strategies converge and where they diverge, giving readers a structured view of competitive pressure points rather than a simple company-by-company list.
Regulatory and Compliance Dynamics Redefining Buyer Behavior
Regulatory change has moved from a background risk to a foreground purchase criterion in the dental autoclave market. FDA recognition of ISO 17665-1 created a formal expectation for documented cycle validation and traceability, and the QMSR framework that took effect in 2026 reinforced the need for end-to-end sterilization traceability for dental devices. In practical terms, these developments increase the strategic value of equipment that can produce consistent, auditable records and reduce dependence on manual documentation practices that are vulnerable to inspection failures.
The CDC audit findings published in mid-2024 sharpened this trend by highlighting how widely spore-test compliance can vary across practices. Where a substantial share of dental practices fail routine spore tests, automatic verification becomes more than a convenience feature; it becomes a risk-management investment. That reality is reshaping how buyers evaluate manufacturers. Products that can embed verification into the cycle, surface anomalies quickly, and reduce manual test burden are gaining a structural advantage in procurement discussions, especially in environments where staff time and compliance exposure are both tightly constrained.
In Europe, the updated harmonized standards list for small steam sterilizers used in dental settings has added further clarity to qualification requirements. For exporters and multinational manufacturers, this matters because it affects product acceptance, documentation expectations, and the cost of maintaining market access across regions with different compliance baselines. The report treats these regulatory developments as a dynamic rather than a static backdrop, examining how they influence purchasing cycles, product design priorities, and the competitive weight of traceability-enabled equipment.
Buyer Behavior, Workflow Integration, and Total Cost of Ownership
As sterilization equipment becomes more digitally connected, buyer evaluation is increasingly extending beyond chamber size and cycle time. Practice owners and hospital procurement teams are asking how an autoclave fits into instrument flow, how much staff effort it demands, and how reliably it supports compliance documentation. This has elevated the importance of features such as automated cycle verification, remote alerts, cloud-based tracking, and service integration. In many cases, the purchasing decision is becoming a judgment about operational resilience as much as about sterilization performance.
The report analyzes these buying dynamics across the major end-user environments to show how priorities differ. Dental clinics tend to weigh footprint, cycle speed, and ease of use heavily, especially where space and staffing are constrained. Hospitals and larger facilities place greater weight on throughput consistency, integration with broader sterilization workflows, and service reliability. Other service and support environments introduce additional variability based on usage intensity, regional procurement norms, and equipment utilization patterns. By separating these perspectives, the study helps readers avoid the common mistake of applying one purchasing logic to all customer groups.
Total cost of ownership is likewise treated as a multi-layered concept. Initial price remains relevant, but lifecycle cost now includes validation support, service access, downtime risk, energy and water consumption, and the hidden labor cost of manual documentation or failed verification cycles. In a compliance-heavy environment, those hidden costs can become material. The analysis connects product features to these cost drivers so that procurement and product teams can make more disciplined comparisons across automatic, semi-automatic, and manual configurations.
Positioning This Research for Strategic Execution
This market research is intended to function as a decision framework rather than a passive reference document. For manufacturers, it supports product-roadmap planning by clarifying where compliance-driven demand is most likely to concentrate and which feature sets are becoming differentiating rather than optional. For distributors and channel partners, it helps prioritize market segments and geographies where purchasing intensity, regulatory pressure, and equipment refresh cycles are most aligned. For practice groups and hospital procurement teams, it provides a structured basis for comparing equipment options against long-term operational risk, not just immediate cost.
The study is also built to support scenario planning. Because the forecast period extends through 2032, readers can use the framework to test alternative assumptions about adoption speed, enforcement intensity, and competitive entry. That flexibility is important in a market where regulatory interpretation, practice economics, and digital-service expectations can shift purchase timing quickly. Rather than forcing a single prediction, the report gives decision-makers a defensible structure for evaluating multiple futures.
The insights in this introduction are deliberately framed at the level of strategic direction. The full report contains the detailed segmentation structure, comparative company analysis, regional demand patterns, and product-level evaluations needed to turn those directions into specific action. The macro trajectory, the regulatory context, and the competitive dynamics outlined here establish the rationale for deeper engagement, while the complete dataset and analysis are reserved for the full study.
What to Expect When You Go Deeper
The complete version of this research translates the market narrative into a set of actionable deliverables. Readers can expect a fully developed market-sizing model that connects historical performance with forecast pathways, a segmentation framework that clarifies how product, end-user, and regional categories interact with purchasing behavior, and a competitive assessment that maps company positioning against the features and service models now shaping demand. The report also contextualizes recent product launches and regulatory milestones within the broader sales environment, allowing teams to see not just what changed, but why it matters for near-term planning.
For executives who need to make capital-allocation choices, refine product strategies, or prepare for more stringent compliance expectations, the full analysis provides the granularity necessary to move from general market awareness to specific, defensible decisions. The teaser above is designed to show the analytical discipline behind the study and the strategic relevance it brings to 2026 planning. The detailed intelligence that supports precise segmentation, competitive benchmarking, and procurement-level evaluation is available in the complete report.
For detailed analysis of this topic, please visit the official page: Dental Autoclave Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot Water Storage Tank Market to Hit $7,565M by 2032 with 4.71% CAGR
By PW Consulting, 2026-09-07
Navigating the Hot Water Storage Tank Market: Strategic Intelligence for 2026 and Beyond
The global hot water storage tank market stands at a pivotal inflection point. As infrastructure modernization, energy efficiency regulations, and evolving consumer expectations reshape the plumbing, heating, cooling, and plumbing (PHCP) landscape, industry leaders must look beyond surface-level trends to understand the structural forces driving volume, value, and competitive positioning. Our latest comprehensive market research report delivers the analytical depth required to navigate the 2026–2032 forecasting horizon with confidence. This overview outlines the strategic architecture of the study, demonstrating how granular execution data, regulatory mapping, and competitive intelligence converge to support capital allocation, product development, and market-entry decisions.
Super-Depth Digital Microscope Market
Macro Trajectory and the 2026 Decision Window
Historical performance from 2020 through 2025 reveals a market that has consistently expanded despite periodic supply chain friction and material cost volatility. The sector crossed the 4.5 billion dollar threshold in the early 2020s and has since maintained a steady upward trajectory, culminating in a 2025 baseline that exceeds 5.5 billion dollars. Looking ahead, the forecast period through 2032 projects a compound annual growth rate of approximately 4.71 percent, translating into a multi-year expansion path that pushes total market value toward the mid-seven-billion-dollar range by the close of the decade. These headline figures establish a foundational growth narrative, but the real strategic value lies in understanding the underlying drivers, regional divergence, and segment-level momentum that will determine which organizations capture disproportionate share during the forecast window.
UV Curable Marking Ink Market
For executives planning 2026 capital expenditure, inventory positioning, and channel strategy, the forecast is not merely a numbers exercise. It is a structural map of where demand will concentrate, which product architectures will gain regulatory tailwinds, and how material science innovations are reshaping warranty economics and total cost of ownership. The report isolates these variables, connecting macro growth to actionable decision nodes.
Three Point Bend Rig Market
Report Architecture: What the Study Delivers
This market research is designed as an operational intelligence toolkit rather than a static snapshot. The document is organized around several interconnected modules that translate high-level market sizing into executable strategy:
- Comprehensive market sizing and forecast modeling covering historical performance and a multi-year projection window, with explicit care taken to present top-line scale without diluting analytical rigor.
- Segment-level breakdowns that map product architectures, end-use applications, and geographic footprints, allowing leadership teams to identify high-velocity corridors and evaluate portfolio alignment.
- Competitive landscape profiling that examines established incumbents and emerging challengers, focusing on product breadth, certification footprints, manufacturing footprints, and recent commercial activity.
- Regulatory and standards mapping that tracks evolving efficiency mandates, potable water certification requirements, and plumbing code amendments influencing design specifications and compliance pathways.
- Material and construction analysis detailing how lining technologies, stainless steel formulations, and corrosion-resistant designs affect durability, warranty structures, and total cost of ownership.
- Distribution and channel dynamics that contextualize how manufacturers, wholesalers, plumbing contractors, and specification-driven commercial projects interact across the value chain.
Each section is structured to feed directly into planning workflows. Market sizing is cross-referenced with segment behavior. Competitive profiles are linked to regulatory exposure and product differentiation. The result is a report that can be used in board presentations, product roadmap reviews, and regional expansion assessments without requiring additional data synthesis.
Competitive Landscape: Incumbents, Positioning, and Recent Activity
The hot water storage tank market operates within a concentrated but differentiated competitive environment. Industry concentration metrics indicate that the top three players collectively command roughly 45.5 percent of market value, while the top five extend that footprint to approximately 65 percent. This concentration reflects the advantage of scale in manufacturing, certified production lines, and established distribution relationships, yet it also leaves meaningful room for specialized manufacturers and regional specialists to compete on customization, certification compliance, and application-specific engineering.
The competitive set spans a broad range of organizational profiles. Major manufacturers such as A.O. Smith Corporation, headquartered in Milwaukee, Wisconsin, and Rheem Manufacturing Company, based in Atlanta, Georgia, continue to anchor broad commercial and residential portfolios with durable tank solutions designed for high-demand applications. Bradford White Corporation, operating from Philadelphia, Pennsylvania, focuses on commercial storage tanks engineered to pair with large-volume water heaters, while State Water Heaters, located in Ashland City, Tennessee, targets restaurant and business environments where consistent hot water supply is a non-negotiable service requirement. Ruud Company, based in St. Louis, Missouri, extends commercial and residential coverage as part of a broader water heating portfolio.
Beyond the large-scale incumbents, a layer of specialized manufacturers competes on certification, configuration flexibility, and material performance. Hanson Tank, located in Los Angeles, California, specializes in ASME HLW certified units with horizontal and vertical configurations and NSF potable water certification. PVI Industries, operating from Piedmont, South Carolina as part of Watts Water Technologies, manufactures commercial storage tanks and related accessories. American Wheatley, based in Tulsa, Oklahoma, supplies glass-lined tanks with capacities reaching up to 5,700 gallons for commercial and industrial uses. Stiebel Eltron, headquartered in Holzminden, Germany with U.S. operations, produces indirect solar and geothermal storage tanks for residential and commercial installations. Vaughn Corporation, in Lubbock, Texas, manufactures lined and thermoplastic tanks for electric, hybrid, and solar applications. Sioux Manufacturing Corporation, from Sioux Falls, South Dakota, produces custom water tanks integrated with water heaters for industrial and commercial use.
Recent commercial activity underscores how actively this field is evolving. PVI Industries exhibited at the 2026 AHR Expo in November 2025, showcasing commercial water heaters and storage tank solutions. Stiebel Eltron followed with a product catalog release in February 2026, introducing the new SHC 6 mini tank model for domestic hot water storage, and then returned to the AHR Expo in April 2026 to highlight its range of indirect storage tanks. These moves illustrate a market where product refreshes, event-driven visibility, and application-specific introductions are central to maintaining relevance and capturing specification-driven demand.
Regulatory and Standards Dynamics: Efficiency, Certification, and Compliance
Regulatory change is no longer a peripheral concern in this market; it is a design constraint and a competitive differentiator. U.S. DOE regulations, as of October 2026, require at least 96 percent thermal efficiency for instantaneous water heaters and have tightened standby loss limits for storage units. These requirements place a direct premium on insulation performance, heat retention engineering, and system-level integration, rewarding manufacturers that can demonstrate measurable efficiency gains without compromising reliability or footprint constraints.
Certification and code compliance further shape procurement behavior. Hot water storage tanks exceeding 120 gallons operating pressure must comply with ASME HLW Section IV and NSF 61 standards for potable water, a requirement that influences manufacturing qualification, testing protocols, and downstream specification acceptance. The International Plumbing Code adds another layer, requiring third-party certification and safety devices such as dip tubes and vacuum relief valves for all hot water storage tanks. Together, these standards create a compliance environment where certification breadth, documentation rigor, and product transparency directly affect win rates in commercial and municipal projects.
For strategy teams, the regulatory landscape is best understood as a moving target that rewards early alignment. Manufacturers that proactively update product lines, secure necessary certifications, and communicate compliance advantages in sales collateral are better positioned to capture specification-led demand and reduce project-cycle friction.
Material Innovation and Construction Economics
Material selection has become a decisive factor in tank durability, warranty economics, and long-term operating cost. Stainless steel tank linings, including duplex stainless formulations such as AquaPLEX, are increasingly used in commercial hot water storage tanks to eliminate anode rods and support extended warranty periods, with 15-year warranties becoming a meaningful benchmark in certain commercial segments. This shift reflects a broader industry move toward reducing maintenance burden and improving lifecycle value, especially in applications where service interruptions or corrosion-related failures carry high operational costs.
At the same time, glass-lined or cement-lined construction remains a standard approach for ensuring corrosion resistance in potable water systems. The coexistence of advanced stainless approaches and established lining methods indicates a segmented material landscape in which the optimal choice depends on application severity, water chemistry, warranty expectations, and total cost of ownership calculations. The report examines these trade-offs in context, linking material decisions to segment suitability, certification pathways, and competitive differentiation.
Segmentation Currents: Type, Application, and Regional Momentum
The market’s structure is defined by the interplay of product type, end-use application, and regional demand patterns. Across product architectures, electric storage tanks represent a substantial share of market value, followed by gas storage tanks, with solar and heat pump storage tanks forming a smaller but strategically important portion of the mix. This distribution reflects both legacy adoption patterns and the growing relevance of hybrid and renewable-integrated systems as efficiency mandates tighten and customer expectations shift toward lower operational costs.
In application terms, residential demand forms the largest portion of market value, supported by replacement cycles, housing activity, and homeowner investment in reliability and efficiency. Commercial applications constitute a significant second tier, driven by restaurants, hospitality, healthcare, and other high-demand environments where consistent hot water supply is central to service quality. Industrial applications, while smaller in total value, remain important for specialized configurations and larger-capacity systems.
Regionally, North America represents the largest geographic concentration of market value, reflecting mature infrastructure, strong PHCP distribution networks, and ongoing retrofit and replacement activity. Europe follows as a major market, with Asia Pacific contributing a substantial additional share, and Latin America and the Middle East and Africa representing smaller but strategically relevant corridors for expanded presence and localized product strategies. The report examines these regional dynamics not as static percentages, but as operating environments with distinct specification practices, channel structures, and competitive intensity.
Strategic Implications for 2026 Planning
Translating market intelligence into 2026 action requires aligning product, compliance, and commercial strategy with where value is actually being created. Several strategic themes emerge from the study’s framework:
- Efficiency-aligned product development: With standby loss limits tightened and thermal efficiency expectations elevated, product roadmaps should prioritize insulation performance, heat retention, and system integration features that can be documented and validated for specification-sensitive buyers.
- Certification as a commercial asset: ASME HLW, NSF 61, and third-party certification requirements are not merely compliance hurdles; they are procurement enablers. Manufacturers that streamline certification pathways and communicate compliance clearly can reduce friction in commercial and municipal selling cycles.
- Material strategy and warranty positioning: The shift toward duplex stainless linings and extended warranty claims signals an opportunity to differentiate on durability and lifecycle cost. Engineering and commercial teams should evaluate how material choices affect warranty economics, service expectations, and segment fit.
- Portfolio alignment with demand concentration: Given the scale of residential and commercial applications and the distinct requirements of industrial configurations, portfolio planning should consider where to compete on breadth, where to specialize on capacity or application, and where customization creates margin advantage.
- Regional execution priorities: Concentration in North America and Europe does not imply uniform execution. Regional strategies must account for local code environments, distribution structures, and material or certification expectations that influence both product design and go-to-market approach.
These themes are not abstract. They inform inventory planning, specification marketing, channel partner selection, and capital allocation. The report provides the supporting structure to convert these themes into specific planning decisions, with enough granularity to guide team-level execution while preserving a coherent market-level narrative.
Why This Study Matters for 2026 Decisions
In a market defined by regulatory tightening, material evolution, and concentrated yet fragmented competition, broad directional awareness is insufficient. Decision-makers need a source that connects market sizing to competitive realities, compliance requirements, and application-specific demand behavior. This research is built for that purpose. It presents the overall market trajectory, outlines the segment and regional architecture, profiles the companies shaping competitive dynamics, and integrates the regulatory and material developments that will influence product viability and commercial success through 2032.
The full report extends well beyond the strategic frame presented here. It contains the detailed segmentation analysis, company-level competitive mapping, regulatory timeline, material and certification cross-references, and forecast detail that leadership teams require to set 2026 priorities with precision. The overview above is intentionally designed to demonstrate analytical rigor and contextual relevance while directing readers to the complete intelligence package for the data and breakdowns needed to execute.
For organizations planning product development, regional expansion, compliance investment, or competitive positioning in the hot water storage tank market, the strategic value of this study lies in its ability to convert complex market signals into a clear decision framework. The complete report is available through our official market research page, where the full segmentation detail, competitive profiles, and forecast architecture can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Hot Water Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Niobium Carbide Market to Grow at 5.1% CAGR, Reaching $83.69M by 2032
By PW Consulting, 2026-09-07
Navigating the Niobium Carbide Market 2026: Strategic Imperatives for Industrial Resilience
The global industrial landscape in 2026 is being reshaped by a confluence of technological advancement, supply chain reconfiguration, and heightened geopolitical scrutiny over critical materials. Among these, niobium carbide (NbC) occupies a specialized but strategically vital position, bridging advanced manufacturing, high-performance engineering, and defense-adjacent applications. As operational and capital-allocation pressures intensify, executives cannot afford to treat specialty refractory compounds as peripheral inputs. They must treat them as strategic enablers whose availability, quality consistency, and pricing architecture directly influence product roadmaps, sourcing resilience, and long-term competitiveness.
High-power Graphite Anodes Market
This new market research from PW Consulting is designed as a decision-grade intelligence instrument. It moves beyond surface-level sizing to provide a structured, forward-looking view of how the niobium carbide ecosystem is evolving across purity architectures, form-factor preferences, application pull, and regional industrial dynamics. The study is calibrated explicitly for 2026 planning cycles, offering executives a framework to align procurement, R&D, and market-entry strategies with realistic market trajectories rather than optimistic assumptions.
AlMgSc Alloy Powder for Additive Manufacturing Market
Why 2026 Decisions Require Deeper Structural Intelligence
The niobium carbide market has entered a phase where historical growth patterns no longer provide sufficient guidance. Over the 2020 to 2025 evaluation window, total market revenue expanded from approximately 46.5 million USD to 58.9 million USD, reflecting steady industrial adoption and incremental substitution in high-wear and high-temperature contexts. The forward trajectory, modeled across the 2026 to 2032 forecast period, points to a compound annual growth rate of 5.1 percent, with revenue projected to approach 62.43 million USD in 2026 and continue rising toward 83.69 million USD by 2032.
Garden LED Courtyard Light Market
These figures are not merely descriptive. They encode important signals about demand consolidation, industrial upgrading, and the increasing premium attached to material performance. A mid-single-digit CAGR in a specialty carbide market indicates that growth is being driven less by broad commodity expansion and more by targeted, value-sensitive applications where performance thresholds, certification requirements, and sourcing reliability justify higher specification materials. For strategists, that distinction matters. It implies that winning positioning in this market depends on understanding where performance specifications are hardening, which buyer segments are willing to pay for purity and consistency, and how regulatory and supply-side constraints are reshaping competitive access.
This is precisely the kind of differentiation that a general industry scan cannot provide. Executives need to know not only that the market is expanding, but which structural forces are accelerating that expansion, which segments are absorbing incremental demand, and where bottlenecks or substitution risks could undermine procurement assumptions. The PW Consulting analysis is built to answer those questions with rigor, while preserving the analytical discipline of keeping the most decision-sensitive figures within the full report environment.
What the Research Covers: A Practical Blueprint for Strategic Teams
The study is organized to support cross-functional use, from procurement scenario planning to product strategy and competitive positioning. Rather than delivering a static snapshot, it assembles a multi-layered view of market mechanics that teams can translate into operating decisions. The core content architecture includes:
- A comprehensive market sizing and forecast framework that links historical revenue evolution to forward projections, giving leadership a consistent baseline for budgeting, capacity planning, and investment prioritization.
- A detailed segmentation analysis that breaks down demand structures across purity grades, product forms, application categories, and regional industrial footprints, allowing teams to identify where specification sensitivity and volume growth are converging.
- An end-use mapping that examines how niobium carbide flows into industrial and advanced manufacturing contexts, highlighting the performance requirements that shape purchasing behavior and supplier selection.
- A regulatory and policy overlay that situates the market within the broader critical-mineral and advanced-materials environment, including export-control considerations, chemical registration obligations, and defense-linked procurement dynamics that can alter sourcing feasibility.
- A competitive landscape assessment that profiles major producers and specialized material suppliers, focusing on product architectures, purity and grain-size positioning, application targeting, and the strategic implications of recent product-line expansions.
- Scenario-oriented insights that help executives evaluate alternative futures tied to feedstock availability, regional manufacturing shifts, and evolving specification requirements in high-performance sectors.
Each section is deliberately structured to be actionable. The report does not simply list market participants or restate public product claims; it interprets them through a strategic lens. It distinguishes between suppliers competing primarily on specification breadth and those building defensible positions around purity consistency, grain control, application engineering, or integrated processing routes. It also examines how recent product launches and project developments are reshaping expectations about supply security and capability depth.
For teams responsible for category strategy, the study provides a structured vocabulary for evaluating supplier qualification, dual-sourcing feasibility, and specification rationalization. For R&D and product management, it highlights where material performance thresholds are tightening and which purity or form-factor choices are becoming more commercially significant. For executives and investors, it frames the market as a network of interdependent choices around feedstock, processing capability, and application pull, rather than as a simple volume game.
The Competitive Field: Capability, Differentiation, and Strategic Positioning
The niobium carbide supply base is concentrated enough that competitive advantage is won through technical differentiation and application alignment rather than through scale alone. The study profiles a set of organizations whose product strategies illustrate the current shape of the market. These include established European powder specialists, Brazilian-based niobium resource and compound producers, large Chinese materials groups, U.S.-based advanced material suppliers, and smaller specialized manufacturers with global distribution footprints.
One recurring theme across the competitive set is the premium attached to purity and microstructural control. Several suppliers position themselves around high-purity NbC powders with tightly controlled grain characteristics, targeting applications where impurity levels, particle size distribution, and consistency influence tool performance, coating integrity, or metallurgical reliability. Others emphasize breadth of portfolio, offering mixed carbide compositions or complementary refractory-metal products that support integrated customer solutions. This bifurcation matters strategically because it implies different sourcing philosophies: some buyers will prioritize application-tuned specification matching, while others will seek suppliers capable of serving multiple performance tiers or adjacent material requirements.
The competitive analysis also captures recent activity that signals where investment and capability-building are being directed. In March 2025, a leading niobium compound producer announced a new high-purity NbC powder line oriented toward aerospace and defense usage. Moves of this kind are not merely product announcements; they are strategic signals about the expected direction of demand quality, the importance of qualification pathways, and the willingness of major suppliers to commit to higher-specification manufacturing. For downstream manufacturers and procurement teams, such developments alter the conversation around supplier suitability, especially when applications involve stringent performance, traceability, or regulatory requirements.
The study uses these profiles to draw out practical implications. It examines how differing product philosophies affect supply resilience, how qualification intensity varies across application domains, and where the market is likely to see increased competition for high-specification segments. It also considers the strategic significance of vertically oriented projects and integrated processing ambitions, which can change the long-term supply architecture by reducing reliance on fragmented midstream processing or by creating new domestic supply options in markets prioritizing material sovereignty.
Importantly, the report does not reduce competitive dynamics to a simple ranking. It recognizes that in specialty materials, positioning is multidimensional. A supplier may be highly competitive in one purity tier or form factor while less relevant in another. A company may excel at specification control but be less flexible in custom application support, or vice versa. The analysis is built to help strategists map those tradeoffs against their own technical requirements and procurement risk tolerance.
Regulatory Tailwinds and Constraints: Why Policy Is Now a Market Variable
One of the most consequential shifts for niobium carbide strategy in 2026 is the growing intersection between material commerce and policy architecture. Niobium has been designated a critical mineral by the U.S. government, a classification that carries practical consequences for exploration, processing investment, and supply-chain planning. In early 2026, Department of Defense programs continued to fund domestic exploration and processing initiatives, including projects targeting niobium-scandium-titanium resource development in Nebraska. This is not merely a geopolitical narrative; it is a tangible influence on where future processing capacity may emerge and how secure certain supply routes are expected to be.
At the same time, regulatory obligations are shaping the compliance burden for manufacturers and exporters. U.S. producers of niobium carbide products used in defense or aerospace contexts must navigate ITAR requirements, while registration under TSCA remains necessary for chemical substances produced or imported into the United States. In parallel, Canada has placed niobium carbide under its Export Control List for strategic applications, reinforcing the reality that this material is increasingly viewed through a national-security and strategic-technology lens. These controls do not halt commerce, but they do introduce friction, qualification delays, documentation requirements, and sourcing constraints that can materially affect lead times, supplier eligibility, and total cost of ownership.
For strategists, the implication is clear: policy is now a core variable in market modeling and sourcing strategy. A supplier relationship that looks attractive on price or specification may become less viable if it introduces regulatory exposure, if qualification pathways are lengthy, or if export restrictions complicate cross-border movement. Conversely, regions or companies investing in compliant, domestically integrated, or strategically aligned processing may command a premium that reflects reduced risk rather than superior unit economics alone.
The research situates these regulatory dynamics within the broader market environment rather than treating them as separate footnotes. It examines how critical-mineral designations, defense funding priorities, chemical registration rules, and export controls interact with feedstock availability and downstream demand. Niobium oxide, for instance, remains the primary feedstock for niobium carbide production, and the value and availability of upstream niobium materials influence processing economics and supply continuity. Understanding that chain relationship is essential for anticipating where cost pressure, capacity constraints, or substitution incentives may arise.
Interpreting Market Structure: Concentration, Purity, and the Shape of Demand
Market structure is a powerful indicator of how value is distributed and where strategic leverage can be created. In the niobium carbide market, concentration levels indicate that a meaningful share of revenue is held by a relatively limited set of participants, though the market also accommodates specialized suppliers serving narrow specification bands. This combination of moderate concentration and specification-driven fragmentation is typical of advanced material markets, where scale matters but differentiation often determines commercial success.
The segmentation structure examined in the study reinforces the same message from another angle. Demand is distributed across purity grades, product forms, and application categories, but not uniformly. Certain purity ranges command attention in high-performance contexts, while other grades serve more general industrial needs. Product forms show distinct demand patterns aligned with manufacturing processes and end-use requirements, and application categories differ sharply in how sensitive they are to specification, qualification, and supply reliability.
Strategically, this means that aggregate market size can be misleading if used as the only reference point. Two companies may operate in the same market and yet face very different growth prospects depending on which purity tiers, forms, and applications they serve. A supplier positioned in a fast-appreciation segment with rigid qualification requirements may experience a different competitive environment than one competing in a more price-sensitive volume segment. The report is designed to help leaders identify those structural differences and align their assumptions accordingly.
It also highlights the importance of form-factor strategy. Powder, in particular, represents a substantial share of market demand, reflecting the centrality of powdered materials in manufacturing workflows such as blending, sintering, coating, and advanced material formulation. Other forms serve more specialized roles, and the balance among them reflects how customers integrate niobium carbide into their production architectures. For procurement and product-strategy teams, understanding this mix is essential for evaluating supplier capability, inventory strategy, and technical support requirements.
How to Use This Research for 2026 Planning
The intended audience for this study is broad but specific: strategic planners, procurement leaders, materials and manufacturing executives, R&D directors, and investors seeking a rigorous foundation for decision-making. The report is not an abstract industry overview. It is structured to support concrete planning tasks, including supplier evaluation, specification strategy, market-entry scoping, and investment prioritization.
For procurement and supply-chain teams, the study provides a basis for assessing where specification requirements are escalating, where qualification risk is concentrated, and how regulatory conditions may influence supplier choice. For product and technology teams, it clarifies which purity and form combinations are gaining strategic relevance and where performance thresholds are becoming commercially decisive. For competitive strategists, it offers a framework for interpreting supplier positioning, identifying where differentiation is credible, and anticipating how recent product launches or integrated-processing projects could shift market expectations.
Most importantly, the report is built to be used as a living planning asset rather than a one-time read. Its segmentation logic, competitive interpretation, and regulatory context are designed to feed directly into scenario discussions, sourcing reviews, and strategic forecasting. By maintaining analytical discipline around which figures are surfaced broadly and which are reserved for the full dataset, the study encourages decision-makers to engage with the complete intelligence environment before committing to resource allocation or market positioning choices.
Closing Perspective: Depth That Enables Confidence, Precision That Enables Action
The niobium carbide market in 2026 is no longer a niche materials story. It is part of a broader realignment in which performance specification, regulatory architecture, feedstock continuity, and supplier capability intersect to determine competitive outcomes. The companies that navigate this environment well will be those that treat NbC not as a commodity input but as a strategically managed material with its own demand logic, qualification intensity, and supply constraints.
PW Consulting's niobium carbide market research is designed for that reality. It provides the structural clarity needed to interpret growth, the competitive insight needed to evaluate positioning, and the policy context needed to anticipate risk. It balances professional depth with deliberate restraint, offering enough analytical rigor to establish confidence while preserving the core segment-level detail for the full report. For executives preparing for 2026 and beyond, that combination is not a limitation. It is the point.
To access the complete dataset, segment-level breakdowns, competitive profiles, and forecast detail, request the full report through the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Niobium Carbide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Super Absorbent Pet Pad Market Hits $668M in 2025, Growing at 3.6% CAGR to $851M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Super Absorbent Pet Pad Market: Navigating Growth and Competition Through 2032
The global pet care industry has consistently demonstrated resilience and expansion, driven by deepening human-animal bonds and escalating standards of pet welfare. Within this broad landscape, the super absorbent pet pad segment represents a critical intersection of hygiene technology, material science, and consumer convenience. As we move further into 2026, understanding the nuanced trajectories of this market is no longer optional for stakeholders; it is a strategic imperative. Our latest research report, spanning historical analysis from 2020 through 2025 and a comprehensive forecast period extending to 2032, offers an unparalleled depth of insight designed to inform high-level decision-making.
Home Pet Deworming Medicine Market
This document serves as a strategic preview of that comprehensive study. It highlights the macro-economic currents, competitive pressures, and technological shifts defining the sector. While we outline the structural framework and operational utility of the full report below, specific quantitative data regarding regional performance tiers and segment-specific financial metrics have been reserved for the complete intelligence package available on our source webpage. This approach ensures that competitors do not gain asymmetrical access to the granular data required for precise strategic planning.
Worldwide External Bone Fixation Plate Market
Macro-Market Trajectory and Volume Dynamics
The super absorbent pet pad market has exhibited steady growth over the past half-decade, reflecting a compound annual growth rate that underscores consistent consumer demand. The market valuation in the base year of 2025 reached approximately 668.0 million USD. This figure represents a significant accumulation of value from the 2020 baseline of 550.0 million USD, indicating a robust expansion trajectory over the historical analysis window.
Organic Cane Sugar Market
Looking forward, our forecasting models project the market to attain a valuation of 686.12 million USD in 2026. The growth momentum is expected to continue, with projections suggesting a climb to 851.0 million USD by the end of the forecast period in 2032. This long-term outlook is anchored by a calculated CAGR of 3.6 percent. For strategic planners, this rate suggests a mature yet expanding market environment where volume growth is steady but requires operational efficiency and product differentiation to capture share effectively. The transition from the historical stability observed between 2023 and 2024 to the projected acceleration in the late 2020s implies shifting consumer preferences and potential saturation in standard categories, necessitating innovation in high-value segments.
It is important to note that while the aggregate market size provides a top-line view, the distribution of this value across geographic territories and specific product types varies significantly. The full report dissects these variations to reveal where concentration lies and where whitespace opportunities may exist. Access to the detailed segmentation revenue figures is essential for companies evaluating market entry or expansion strategies, as national-level aggregates can mask local volatility.
Structural Segmentation and Product Evolution
The market architecture is defined by distinct classifications that drive manufacturing strategies and retail offerings. Our analysis categorizes the landscape primarily by material technology, functional application, and geographic deployment. The technological divide is particularly pronounced, separating traditional standard polyacrylate solutions from advanced superabsorbent polymer enhanced variants and emerging biodegradable options.
The standard polyacrylate segment continues to hold substantial volume due to established supply chains and cost-effectiveness. However, the enhanced polymer variants are gaining traction among premium consumer segments seeking superior leakage protection and odor management. Meanwhile, biodegradable variants represent a high-growth potential niche, though they face specific headwinds related to raw material economics. Industry intelligence indicates that degradable super absorbent polymer alternatives to traditional sodium polyacrylate can carry unit prices 2 to 5 times higher than conventional materials. This cost differential raises overall pet pad selling prices and limits market penetration despite the environmental appeal, a dynamic that is critical for pricing strategy and portfolio mix decisions.
On the application side, the market is driven by training needs, housebreaking requirements, and specialized care scenarios. Training pads constitute the largest functional demand, reflecting the ongoing need for pet ownership onboarding solutions. Housebreaking pads follow as a secondary but consistent demand stream. A smaller but specialized segment involves whelping and incontinence pads, catering to specific veterinary and breeding use cases. The interplay between these applications influences inventory planning and marketing messaging. For instance, the performance metrics required for a whelping pad differ significantly from those of a standard training pad, impacting the specification of absorbency levels and grid technology.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, consumer behavior patterns, and distribution channel preferences. The full research study provides a deep dive into these regional nuances, identifying which markets are driving volume versus value and where import-export dynamics are shifting. Readers seeking to allocate capital or resources across borders must consult the detailed regional breakdown to avoid misallocation based on global averages.
Raw Material Economics and Supply Chain Sensitivity
Understanding the cost structure is vital for margin protection and pricing power. In the manufacturing of super absorbent pet pads, the super absorbent polymer (SAP) represents a significant portion of the input cost. Industry estimates suggest that SAP accounts for between 35 and 45 percent of total raw material costs. This makes the polymer the primary driver of product pricing and performance differentiation.
Fluctuations in SAP pricing or availability can have a disproportionate impact on profitability. Consequently, manufacturers are increasingly looking at long-term supply contracts and alternative material formulations to mitigate risk. The tension between cost efficiency and performance quality is a central theme in the operational section of our report. Companies that can optimize SAP usage without compromising absorbency ratings or tear resistance will possess a distinct competitive advantage. Furthermore, as environmental regulations and consumer awareness evolve, the cost implications of transitioning to sustainable materials remain a key risk factor that our analysis quantifies and contextualizes.
Competitive Landscape and Key Player Strategies
The market currently operates under a moderate concentration structure. The top three players hold a combined market share of approximately 41.5 percent, while the top five entities account for 52.8 percent of the total revenue. This indicates a landscape where dominant players retain significant influence, but there remains ample room for specialized manufacturers and regional leaders to compete on niche attributes such as customization, speed to market, or specific performance claims.
Several key companies define the current competitive dynamics. ElinTree, based in China, has positioned itself as a specialist in OEM and ODM customized pet training pads and underpads. Their offering emphasizes adjustable absorbency ranging from 500ml to 1200ml, coupled with odor control and eco-friendly materials. With CE, FDA compliance and ISO 9001 certification, they target clients requiring rigorous quality standards and customization capabilities.
Similarly, Hangzhou Haoyue Personal Care Co., Ltd leverages over 32 years of personal care production experience to supply high-quality disposable pet pads, including super absorbent puppy pads and custom underpads. Their longevity in the personal care sector provides a backbone of manufacturing reliability that appeals to bulk buyers and distributors.
Tianjin Yiyi Hygiene Products Co., Ltd is recognized as a leading manufacturer of disposable dog toilet pads. They operate large-scale production facilities focused on super absorbent, leak-proof training pads. Their strong OEM capabilities and significant US market presence make them a critical node in the supply chain for North American retailers and brands seeking reliable manufacturing partners.
On the retail and private-label side, Amazon Basics offers leak-proof, quick-dry super absorbent gel technology puppy and dog training pads. Their strategy emphasizes heavy-duty absorbent performance within a accessible price point, utilizing their massive distribution network to capture volume-driven market share. Glad for Pets complements this by producing activated carbon and standard super absorbent training pads with quick-drying and odor-locking features, maintaining a strong retail presence that reinforces brand visibility at the point of sale.
Recent developments highlight the dynamic nature of this competition. In January 2026, Consumer Reports conducted lab absorption and tear-resistance tests on 10 popular puppy pads, including super absorbent varieties. The testing identified distinct differences in performance without leakage, signaling to consumers that technical specifications matter and rewarding brands that can substantiate performance claims with independent data. More recently, in March 2026, HoneyCare launched a new lineup of dog training pads at the Global Pet Expo. This launch featured refreshed brand expression and showcased branded signage alongside super absorbent pet training pad products, indicating a trend toward premiumization and brand storytelling even within functional hygiene categories.
Our full report provides a detailed competitive benchmarking matrix that evaluates these players across multiple dimensions, including capacity, distribution reach, product portfolio breadth, and strategic moves. This level of detail is necessary for companies conducting competitor surveillance or evaluating potential partnership targets.
Regulatory Environment and Industry Standards
The regulatory framework governing pet products is evolving. While super absorbent training pads currently lack federal oversight equivalent to children's products under the CPSC or FDA, there is a clear industry movement toward standardization. ASTM International established a subcommittee on pet products (F15.05) in 2022, which has grown to include over 114 members from 10 countries. This body is developing voluntary safety standards for pet products, including pads.
The strategic implication of this development is significant. The subcommittee aims for major retailers to require compliance with these standards. For manufacturers and brands, this signals a future where certification may become a barrier to entry or a prerequisite for shelf space in key retail channels. Proactive engagement with these standards can mitigate future compliance risks and serve as a marketing differentiator. Our report analyzes the timeline and potential impact of these regulatory shifts, helping stakeholders prepare for a more formalized quality assurance landscape.
Operational Utility of the Full Research Report
This market research study is designed as a practical tool for strategic execution. It goes beyond high-level summaries to provide actionable intelligence across several functional areas. For strategy teams, the report offers a comprehensive market overview that contextualizes the super absorbent pet pad sector within the broader pet care economy. This includes historical data trends from 2020 to 2025 that establish baseline performance metrics, allowing for more accurate benchmarking of current operations against past performance.
The forecast section extends these insights through 2032, providing a long-term view that supports capital investment decisions, capacity planning, and R&D roadmapping. By understanding the projected growth trajectory and the associated CAGR, leaders can model different scenarios for market share acquisition and revenue growth. The segmentation analysis detailed in the full document allows for precise targeting. Whether a company is looking to expand into specific product types like biodegradable variants or focus on high-demand applications like training pads, the data provides the granularity needed to validate market size assumptions.
Furthermore, the competitive analysis section equips marketing and sales teams with the knowledge to position products effectively. Understanding the strengths and weaknesses of competitors like ElinTree, Amazon Basics, and Glad for Pets enables the development of counter-strategies. For example, if a competitor relies heavily on private-label distribution, a brand might emphasize direct-to-consumer engagement or specialized OEM partnerships to differentiate. The inclusion of recent developments, such as the Consumer Reports testing and HoneyCare's product launch, ensures that the intelligence is current and reflects the immediate market environment.
Supply chain managers will find value in the raw material cost analysis and the discussion on SAP dependency. Knowing that SAP constitutes 35 to 45 percent of costs highlights the need for procurement agility. The report discusses the implications of raw material price volatility and the potential trade-offs involved in switching to degradable polymers despite their higher unit costs. This information supports decisions regarding supplier diversification and inventory hedging.
Finally, the regulatory section provides a risk assessment framework. By outlining the activities of the ASTM subcommittee and the current lack of federal oversight, the report helps compliance officers and legal teams anticipate future requirements. Companies that align their quality control processes with emerging voluntary standards early may gain a first-mover advantage in securing retailer partnerships that mandate compliance.
Conclusion and Access to Deep Intelligence
The super absorbent pet pad market is poised for continued growth, driven by stable demand fundamentals and evolving product technologies. However, the path to capitalizing on this growth requires more than general market awareness. It demands precise data on regional performance, segment-specific revenue streams, and detailed competitive positioning. The macro indicators point to a market reaching 851.0 million USD by 2032, but the distribution of that value across the diverse segments and regions holds the key to strategic success.
This article has outlined the structural components, competitive players, and dynamic factors influencing the sector. It has highlighted the importance of SAP costs, the potential of biodegradable variants, and the emerging regulatory standards from ASTM. Yet, the specific percentages driving regional dominance, the exact revenue contributions of each product type, and the granular market share breakdowns remain part of the proprietary intelligence contained in the full report.
For executives, investors, and strategy professionals seeking to make informed decisions in 2026 and beyond, accessing the complete dataset is essential. The full research publication provides the necessary depth to validate assumptions, identify risks, and uncover opportunities that aggregate data cannot reveal. We invite you to visit the source webpage to obtain the comprehensive Super Absorbent Pet Pad Market research report, where the full spectrum of analysis, forecasts, and strategic recommendations is available for immediate application to your business planning.
For detailed analysis of this topic, please visit the official page: Super Absorbent Pet Pad Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


