



PW Consulting: Office Storage Market Hits $3.15B in 2025, Projects 7.9% CAGR to $5.34B by 2032
By PW Consulting, 2026-09-07
2026 Office Storage & Organization Market Outlook: Strategic Intelligence for Workplace Infrastructure Decisions
The office storage and organization market is entering a phase of structural realignment, driven by hybrid work permanence, rising density requirements in commercial real estate, and a renewed focus on workplace functionality. As organizations recalibrate their physical environments to support collaboration, compliance, and employee experience, the demand for intelligent storage solutions is evolving from a commodity procurement category into a strategic workplace investment. PW Consulting’s latest Office Storage & Organization Market research offers a comprehensive, decision-grade view of this transformation, equipping executives, procurement leaders, and facility planners with the analytical foundation needed to navigate 2026 and the years ahead.
Manure Agitators Market
This market research is designed as a strategic briefing rather than a static data dump. It maps the trajectory of an industry that has already demonstrated consistent expansion across the 2020–2025 period and is projected to continue its upward momentum through the 2026–2032 forecast window. The purpose of this article is to preview the depth, methodology, and strategic applicability of the full report while illustrating how its insights can be operationalized for high-impact business decisions. The complete dataset, segmentation breakdowns, competitive benchmarking matrices, and region-specific deployment scenarios are reserved for the published report, where they are presented with the granularity required for actionable planning.
Worldwide Drawer Air Fryer Market
Market Trajectory and the Strategic Implications of Sustained Growth
Over the past half-decade, the office storage and organization sector has moved through a period of measurable expansion, with revenue climbing steadily from 2020 through 2025. This trajectory reflects more than a post-pandemic recovery; it signals a broader rethinking of how physical workspace assets are designed, allocated, and utilized. As organizations consolidated remote work policies and adjusted office footprints, storage and organization products transitioned from peripheral furnishings to integral components of space management strategy. The trend has continued into 2026, where the market’s valuation reflects a maturing demand environment shaped by both commercial real estate optimization and the formalization of home-office infrastructure.
Artificial Grass Adhesive Market
Looking forward, the forecast period through 2032 indicates a continued expansion path supported by a robust compound annual growth rate. This growth is not incidental. It is anchored in several operational realities: the need to maximize usable square footage in high-cost urban markets, increasing requirements for secure and compliant document and equipment storage, and the aesthetic-functional pressure to integrate storage seamlessly into modern workplace design. For decision-makers, the implication is clear. Storage and organization spending is no longer a line item to be minimized; it is a variable that interacts with talent retention, space efficiency, regulatory compliance, and overall workplace productivity.
What makes this trajectory strategically significant is the way growth is distributed across product philosophies and deployment contexts. Rather than a uniform increase, the market is being shaped by divergent use cases that require different procurement logic, investment horizons, and evaluation criteria. Some organizations are prioritizing fixed storage architectures that anchor permanent headquarters, while others are investing in mobile and reconfigurable systems that support agile space allocation. Still others are scaling home-office and distributed-workplace setups, where storage decisions influence both functional output and employee satisfaction. Each of these pathways carries distinct cost structures, vendor ecosystems, and implementation risks, which is precisely why high-level market sizing is only the starting point for meaningful strategy.
The full research unpacks these dynamics with forward-looking projections that extend beyond aggregate revenue figures. It isolates the structural drivers that will determine which solution categories gain share, how procurement cycles are shifting, and where regional demand intensity is likely to concentrate. Decision-makers who rely solely on broad market headlines risk misallocating capital or underestimating the timing of transitions in supplier capacity, pricing behavior, and specification requirements. By contrast, the complete PW Consulting analysis is built to support scenario-based planning, allowing organizations to align procurement strategy with their own operational tempo and real estate roadmap.
Key Forces Reshaping the Competitive Landscape
The office storage and organization market is characterized by a mix of specialized manufacturers, broad-line furniture providers, and retail-oriented solution platforms. This diversity matters because it creates a competitive field in which value propositions differ substantially across customer segments. Some companies compete on modularity, speed of deployment, and catalog breadth, while others emphasize engineering durability, high-density capacity, or design-forward aesthetics. A few operators occupy niche positions that blend retail accessibility with workplace utility, broadening the range of options available to small and mid-sized enterprises as well as corporate procurement teams.
Several of the most active participants operate from distinct geographic and operational bases, which influences their supply chains, product development priorities, and market access strategies. On the North American side, firms with established showroom networks, online catalogs, and workplace-integrated system portfolios have continued to refine their storage and organization offerings to align with hybrid office needs. Meanwhile, manufacturers based in Asia have expanded their footprint by emphasizing modern cabinet design, plastic and composite container systems, and modular organizer lines that appeal to both office and home-office buyers. Large global retailers also play a role, particularly where affordability, accessibility, and branded modular systems influence purchasing decisions for smaller workplaces and remote setups.
A defining feature of the competitive landscape is the relatively fragmented concentration profile. The market does not rely on a small number of dominant incumbents to the exclusion of all others; instead, it supports a broad field of players that compete across dimensions such as price, customization, product durability, distribution reach, and specialty functionality. This fragmentation creates both opportunity and complexity. Buyers benefit from multiple sourcing pathways, but they also face the challenge of comparing solutions that may appear similar on the surface while differing sharply in load-bearing performance, mobility features, aesthetic finish, and long-term maintenance requirements.
Recent activity from several leading participants illustrates how competitive positioning is being sharpened through catalog updates, product showcases, and targeted launches. Throughout the 2025–2026 period, multiple companies have released updated product catalogs or showcased new storage and organization lines at major trade events. These moves are not merely promotional; they reflect an industry-wide effort to communicate updated design philosophies, material choices, and functional configurations that align with evolving workplace expectations. For procurement teams, such releases provide early signals about where suppliers are directing innovation investment and how product roadmaps may influence future purchasing decisions.
At the same time, competitive dynamics cannot be understood without accounting for the operational pressures affecting the supply side. Raw material cost volatility for steel, wood composites, and engineered plastics has introduced margin constraints that shape vendor pricing strategies and product mix decisions. In parallel, regulatory expectations around load-bearing performance and fire resistance are raising the baseline for what qualifies as a compliant storage solution in commercial environments. These forces interact with labor cost trends and producer price movements in the broader office furniture sector, creating a more complex decision environment for buyers who must balance specification quality, total cost of ownership, and delivery reliability.
The full report examines these competitive pressures in greater depth, mapping how major participants position themselves relative to one another and where differentiation is becoming increasingly important. It also evaluates how market concentration patterns influence negotiation leverage, supplier diversification strategy, and risk exposure for enterprise buyers. By situating company-level activity within the broader structural context, the research enables decision-makers to interpret market movements with greater precision rather than relying on surface-level brand recognition.
Strategic Dimensions for 2026 Decision-Makers
For executives planning workplace investments in 2026, the office storage and organization market presents several strategic questions that extend well beyond immediate purchasing needs. One central issue is the alignment between storage procurement and wider real estate strategy. As organizations optimize space utilization, storage systems increasingly need to support multiple functions: enabling efficient retrieval, reducing clutter that undermines productivity, facilitating secure storage for sensitive materials, and contributing to the overall visual coherence of the workplace. The right solution in one context may be inappropriate in another, which makes segmentation-aware planning essential.
Another strategic dimension involves the growing relevance of financing and investment pathways for office infrastructure. In certain markets, long-term financing mechanisms for small business infrastructure investment can influence the timing and scale of storage upgrades. When coupled with the need to manage material and labor-related cost pressures, procurement leaders must evaluate not only the sticker price of storage systems but also the financing structure, deployment timeline, and expected service life of the assets they acquire. This broadens the scope of decision-making from transactional purchasing to asset strategy.
Operational resilience is also becoming more prominent in procurement thinking. Organizations are increasingly attentive to vendor consistency, product availability, and the ability to scale orders without sacrificing specification quality. At the same time, compliance considerations remain central in commercial settings, where storage units must satisfy safety and performance standards relevant to the environment in which they are deployed. These requirements create a strong incentive to evaluate suppliers not only on aesthetics or price but also on documented performance, certification alignment, and post-sale support capacity.
The distributed workplace continues to add complexity. As remote and home office setups become a more permanent part of the work ecosystem, storage decisions must account for smaller-scale deployments, ease of assembly, aesthetic compatibility with residential environments, and the practical need to maintain organization without dedicated facilities support. This segment has distinct purchasing behaviors and specification preferences compared with large corporate headquarters, and it requires its own evaluation framework.
Taken together, these factors point to a market in which strategic value comes from matching the right solution architecture to the right operational context. That is precisely where the full PW Consulting research is intended to support executive judgment. It does so by organizing market intelligence in a way that connects demand drivers, product categories, application settings, and competitive realities to concrete planning decisions.
What the Full Report Delivers
The complete Office Storage & Organization Market research is structured to provide a practical, decision-oriented toolkit rather than a narrow statistical summary. It opens with a consolidated market overview that establishes baseline sizing and forward projections, then moves into the segmentation and demand-side analysis needed to interpret where growth is coming from and how it is likely to evolve. The report examines how different solution types are positioned across office environments, including fixed storage architectures and mobile or high-density systems that address space-constrained layouts. It also distinguishes between major deployment contexts, such as centralized corporate headquarters, remote and home office settings, and other organizational use cases, so that readers can calibrate expectations by environment rather than treating the market as a single homogeneous demand pool.
A substantial portion of the research is devoted to regional demand patterns and the operational factors that shape them. Rather than simply presenting geographic splits in isolation, the report situates regional variation within the broader context of workplace norms, procurement practices, regulatory expectations, and distribution dynamics. This allows decision-makers to understand not just where demand is occurring, but why it is occurring there and what that implies for market entry, sourcing strategy, and localization of product specifications.
The competitive section moves beyond basic company identification to analyze how leading participants differentiate themselves across product philosophy, distribution channels, and target customer profiles. It incorporates recent product catalog releases, showcase activity, and other visible indicators of strategic focus, using them to illuminate where innovation attention is being directed. By connecting company-level movement to broader market structure, the report provides a more useful competitive map than a simple roster of names and headquarters locations.
The research also integrates the operational and regulatory pressures that influence both supply and demand. Material cost volatility, producer price trends in related furniture categories, safety and compliance requirements, and financing mechanisms that affect investment timing are all addressed as part of the market environment. These elements are not treated as background noise; they are framed as decision-relevant variables that shape pricing behavior, specification choices, and procurement risk. For organizations planning multi-year workplace investments, this context is essential for building realistic cost assumptions and contingency plans.
Finally, the report is designed with an emphasis on usability. It supports read-through analysis for senior leadership while also providing the level of structural detail required by procurement, facilities, and strategic planning teams. The aim is to make the intelligence actionable: to help readers identify where to focus sourcing efforts, how to evaluate alternative solution types, which competitive signals deserve attention, and how macro-level growth translates into organization-specific opportunities.
Conclusion: Why This Research Matters Now
The office storage and organization market is not simply expanding; it is being redefined by changes in work patterns, space economics, compliance expectations, and supplier innovation. In that environment, high-level awareness of growth trends is necessary but insufficient. Decision-makers need a structured view of how demand is segmented, how competitive players are positioning themselves, and which external pressures are likely to influence cost, availability, and specification standards over the forecast period.
PW Consulting’s Office Storage & Organization Market research is built to meet that need. It translates macro growth into strategic context, connects market structure to practical procurement and workplace planning decisions, and provides the analytical depth required to move from observation to action. The full report contains the detailed segmentation data, regional intensity patterns, company-level competitive profiles, and forward-looking scenario content that executives and operational leaders need to make informed choices throughout 2026 and beyond.
For organizations seeking to align workplace storage investments with broader strategic objectives, the complete market intelligence offers a timely and practical foundation. The insights previewed here are intended to demonstrate the report’s scope and relevance; the full analysis is where the detailed numbers, segmentation logic, and competitive benchmarks are presented in the depth required for implementation-grade decision-making.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for a High-Stakes Surgical Market: Navigating the Hemostasis and Tissue Sealing Agents Landscape in 2026
The surgical theater is undergoing a quiet revolution. As procedures become increasingly minimally invasive and patient expectations for recovery times tighten, the demand for precision hemostasis and reliable tissue sealing has moved from a supportive function to a critical driver of clinical outcomes. For stakeholders in the medical technology sector, understanding the trajectory of the Hemostasis and Tissue Sealing Agents Market is no longer optional; it is a prerequisite for strategic positioning. This article serves as a strategic preview of our latest comprehensive market research, designed to equip executive leadership with the context needed to navigate the complexities of 2026 and beyond.
IMS-based Interactive Voice Response Softwares Market
Our analysis covers the historical performance from 2020 through 2025 and projects forward to 2032. The macroeconomic signals are clear. The global market size reached an estimated 7,940 million USD in the base year of 2025. Looking ahead, the trajectory indicates robust expansion, with the market projected to reach 8,363.64 million USD in 2026. This growth is not merely cyclical but structural, driven by an aging population, the rising prevalence of chronic diseases requiring surgical intervention, and continuous innovation in biomaterials. Our forecast suggests the market will continue its upward momentum, culminating in a significant valuation by 2032. The compound annual growth rate during the forecast period stands at 8.2 percent, signaling a healthy, expanding ecosystem that offers ample opportunity for players who can differentiate effectively.
Mesenchymal Stem Cell Injection Market
Competitive Dynamics in a Concentrated Arena
The Hemostasis and Tissue Sealing Agents market is characterized by a notable degree of concentration. The top three companies command a 54 percent share of the revenue, while the top five firms control 68 percent. This structure suggests that while market leadership is entrenched, there is sufficient fragmentation to allow for strategic acquisitions or disruptive product launches to shift the balance. The competitive landscape is defined by several key players who are actively shaping the future of surgical hemostasis.
Olmesartan Medoxomil Hydrochlorothiazide Tablets Market
Baxter International Inc.
Based in Deerfield, Illinois, Baxter remains a cornerstone of the market. Their portfolio is extensive, leveraging decades of expertise in fibrin sealants and hemostatic matrices. Key offerings include TISSEEL fibrin sealant, Floseal hemostatic matrix, ARTISS, COSEAL, PREVELEAK, and RECOTHROM thrombin topical. Baxter's strength lies in the versatility of these products across various surgical disciplines. Notably, their focus on absorbable hemostatic agents such as Floseal, which are fully resorbed within 24 to 48 hours by enzymatic action in vivo, addresses critical surgeon concerns regarding residue and long-term complications. This biological compatibility remains a key selling point in a market increasingly sensitive to foreign body reactions.
Johnson & Johnson
Headquartered in New Brunswick, New Jersey, Johnson & Johnson continues to expand its footprint through the Ethicon portfolio and specific innovations like VISTASEAL. In October 2024, the company announced the U.S. market availability of VISTASEAL fibrin sealant spray, marking a significant expansion of its advanced hemostatic products. This move underscores the competitive intensity in the sprayable sealant segment, where ease of application and coverage area are paramount. The Ethicon portfolio of hemostats and sealants further reinforces their position as a comprehensive solutions provider for general and specialized surgeries.
Medtronic plc
Medtronic, based in Dublin, Ireland, brings a different technological approach to the table. Their Nexpowder endoscopic hemostasis system represents the convergence of hemostasis and minimally invasive technology. As endoscopic procedures grow, solutions like Nexpowder that can be deployed through scopes are gaining traction. Medtronic's strategy highlights the shift toward devices that integrate seamlessly into existing surgical workflows, reducing friction for the surgical team.
Becton, Dickinson and Company
BD, located in Franklin Lakes, New Jersey, relies on the strength of its Avitene Microfibrillar Collagen Hemostat (MCH) family. These absorbable collagen-based hemostats have a long history of use and reliability. The market data indicates that collagen-based formulations maintain a steady demand, particularly where mechanical tamponade and biocompatibility are required. BD's focus on the MCH family demonstrates the enduring value of established material science in a market often chasing the newest innovation.
Teleflex Incorporated
Teleflex, from Wayne, Pennsylvania, has shown aggressive growth in the hemostatic device space. In April 2025, Teleflex received FDA 510(k) clearance expansion to include all grades of internal and external bleeding, from mild to life-threatening, across multiple anatomical sites for its QuikClot Control+ hemostatic device. This regulatory milestone significantly broadens the addressable market for their product, moving it beyond niche applications into broader trauma and surgical use cases. Such regulatory expansions are critical catalysts for revenue growth in the medical device sector.
Cresilon Inc.
Innovation often comes from smaller, agile entities. Cresilon, based in Brooklyn, New York, represents this dynamic. In August 2024, they received FDA 510(k) clearance for TRAUMAGEL hydrogel hemostatic gel for temporary external use in controlling moderate to severe bleeding. This product utilizes proprietary cellulose derivatives for rapid external bleeding control without animal-derived components. The material science here is notable; plant-based hydrogel agents offer an alternative to biological products, potentially reducing supply chain vulnerabilities and ethical concerns associated with animal-derived materials. Fibrin sealants such as TISSEEL and VISTASEAL carry the highest per-unit cost among topical hemostatics, often exceeding 500 USD per application, highlighting the cost pressures that alternative materials like hydrogels might alleviate in specific contexts.
Medcura Inc.
Rounding out the key competitive set is Medcura Inc., with their LifeGel absorbable hemostatic gel. As the market diversifies, solutions that offer absorbable properties with gel-based application mechanisms are finding niches, particularly where precise placement is required without the risks associated with liquid sprays or particulate powders.
Market Segmentation Trends: Product and Application Drivers
Understanding how value is distributed across product types and clinical applications is vital for resource allocation. The market is broadly divided into two major product categories: Topical Hemostats and Adhesive and Tissue Sealants. While both segments are essential, the Adhesive and Tissue Sealants segment represents a larger portion of the revenue, driven by the high value of fibrin-based products and the increasing need for watertight seals in complex surgeries. Topical Hemostats remain the workhorse of the operating room, with a diverse array of materials including collagen, gelatin, and synthetic polymers.
The application landscape is equally nuanced. General Surgery dominates the application share, reflecting the sheer volume of procedures performed globally. However, high-growth potential lies in specialized applications. Cardiovascular Surgeries, Neurosurgeries, and Orthopedic Surgeries each represent significant revenue streams. The complexity and risk profile of these procedures justify the use of premium sealing and hemostatic agents. For instance, in neurosurgery, the margin for error is infinitesimal, driving demand for agents that provide reliable hemostasis without causing tissue damage or swelling. In cardiovascular procedures, the ability to seal anastomoses and control bleeding on delicate vessels is critical. Our report dives deep into these application-specific drivers without relying on broad generalizations, offering granular insight into volume trends and procedural shifts.
Regional dynamics also play a crucial role. While specific regional percentages are proprietary to our full dataset, it is evident that North America remains a dominant force due to high healthcare spending and advanced surgical infrastructure. However, the Asia Pacific region is witnessing accelerating adoption rates, fueled by expanding healthcare access and a growing surgical volume. Europe maintains a steady presence with a focus on cost-effectiveness and standardized care protocols. Latin America and the Middle East and Africa represent emerging opportunities where infrastructure development is unlocking new demand.
Regulatory and Reimbursement Dynamics: The Hidden Drivers
Strategic decision-making cannot occur in a vacuum; it must account for the regulatory and reimbursement environment. The U.S. Food and Drug Administration maintains an active list of approved hemostatic agents under 510(k) clearance pathways, including collagen-based and hydrogel formulations. This regulatory framework means that time-to-market and clearance strategy are competitive advantages. Companies that can navigate the 510(k) process efficiently, or leverage predicate devices effectively, can capture market share faster. Teleflex and Cresilon's recent clearances exemplify how regulatory wins translate directly into commercial opportunities.
Reimbursement remains a complex layer. Hemostatic agents are typically included as integral to the surgical procedure under Medicare CPT coding and are not separately reimbursed by CMS. This structure places the burden of cost-effectiveness squarely on the hospital and the surgeon. Products must demonstrate value through reduced operative time, lower complication rates, or reduced need for transfusions to justify their cost within the bundled payment model. This reality favors products that offer tangible clinical efficiencies or reduce overall procedure costs, rather than those that simply add expense without corresponding benefit. Understanding these reimbursement nuances is essential for market access strategies.
Strategic Imperatives for 2026 Decision-Making
As we look toward 2026, several strategic imperatives emerge for companies operating in this space. First, differentiation through material science is becoming increasingly important. The shift toward non-animal-derived components, as seen with plant-based hydrogels, addresses both regulatory scrutiny and supply chain resilience. Companies investing in proprietary raw materials that offer superior performance or ethical advantages will likely command premium positioning.
Second, the integration of hemostatic agents into broader surgical ecosystems is key. Devices that complement existing energy platforms, endoscopic tools, or robotic systems will see higher adoption. Medtronic's approach with endoscopic systems is a prime example of this convergence. Compatibility and workflow integration reduce the cognitive load on surgeons and streamline procurement for hospitals.
Third, portfolio breadth versus depth is a critical strategic choice. Large players like Baxter and Johnson & Johnson benefit from the ability to offer solutions across multiple surgical specialties, providing a one-stop-shop advantage for hospital procurement. Smaller innovators must find ways to carve out defensible niches, perhaps through unique indications, superior ease of use, or superior cost profiles. The concentration data suggests that partnerships, licensing deals, or acquisitions may be necessary for smaller firms to scale effectively.
Finally, the geographic expansion strategy must be tailored. While mature markets demand innovation and cost-efficiency, emerging markets may prioritize availability and basic efficacy. Understanding the local reimbursement landscape, regulatory pathways, and surgical volume growth in each region is essential for successful international expansion. Our report provides the detailed regional breakdowns and opportunity assessments needed to prioritize these investments.
Deep Dive into the Full Research Report
This article provides a high-level strategic overview, but the complexities of the Hemostasis and Tissue Sealing Agents Market require a more detailed examination. Our full market research report offers a comprehensive quantitative and qualitative analysis designed to support board-level decision-making. The report includes detailed segmentation analysis that breaks down revenue contributions, growth rates, and volume trends across all product types, applications, and regions. While we have highlighted the macro trends here, the full report reveals the specific dynamics driving growth in each segment, allowing you to identify the most promising areas for investment or product development.
The competitive analysis section goes beyond company profiles to include strategic benchmarking, product pipeline assessments, and analysis of recent M&A activity. We examine how key players are positioning themselves for the future, what gaps exist in the market, and where the next wave of innovation is likely to emerge. The report also features a thorough examination of the regulatory environment, including a database of recently cleared devices and an outlook on potential policy changes that could impact market access.
Furthermore, the report addresses the economic aspects of the market in greater depth, including pricing trends, cost structures, and the impact of reimbursement policies on product adoption. For companies evaluating potential entry into new markets or launching new products, this information is invaluable for financial modeling and go-to-market strategy.
To access the complete dataset, including detailed forecasts, segmentation splits, and the full competitive landscape analysis, we invite you to download the full Hemostasis and Tissue Sealing Agents Market Research Report. This document is structured to provide actionable intelligence, enabling you to anticipate market shifts, identify risks, and capitalize on the significant growth opportunities projected for the 2026 to 2032 period. In a market defined by both concentration and innovation, having access to precise, up-to-date intelligence is the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Hemostasis and Tissue Sealing Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Body Composition Analyzers Market to Hit $847.35M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-07
Unlocking Strategic Value in the Body Composition Analyzers Market: Why 2026 Demand a Deeper Intelligence
The body composition analysis sector is undergoing a structural transformation that goes far beyond incremental growth. As healthcare systems shift toward preventive and personalized medicine, fitness ecosystems digitize their member journeys, and academic research demands higher reproducibility, the instruments measuring lean mass, fat distribution, and segmental composition have become strategic assets rather than isolated diagnostics. For executives planning capital allocation, product roadmaps, and market entry in 2026, surface-level reading of top-line numbers is no longer sufficient. A rigorous, data-grounded intelligence framework is required to separate durable demand drivers from transient noise.
Mica Cloth Market
Our latest market research on the Body Composition Analyzers Market is designed precisely for this decision environment. It maps the evolution of the industry from 2020 through 2025, establishes a firm base year of 2025, and projects forward across 2026 to 2032. The study translates historical revenue progression into a disciplined forecast, while deliberately preserving the analytical depth that procurement leaders, R&D directors, and venture investors need to act with confidence. This article previews the strategic architecture of the report, demonstrates how the macro trajectory informs 2026 decision-making, and explains why the full document remains an essential instrument for anyone serious about competitive positioning.
Worldwide Negatively Refractive Material Market
The market has already demonstrated a consistent upward path. From 388.32 million USD in 2020, revenue climbed to 402.92 million USD in 2021, then accelerated to 454.21 million USD in 2022 as institutional buyers restarted procurement cycles. The expansion continued through 2023 at 468.96 million USD and 2024 at 499.04 million USD, before reaching 535.64 million USD in 2025. That momentum carries into the early forecast window, with 567.17 million USD in 2026, 591.88 million USD in 2027, and 652.58 million USD in 2028. By 2030, the trajectory points to 760.16 million USD, advancing to 787.05 million USD in 2031 and 847.35 million USD in 2032. Across the full projection period, the compound annual growth rate settles at 6.98 percent, reflecting a market that is expanding at a measured but durable pace rather than relying on speculative spikes. For strategy teams, this shape matters as much as the endpoint: it signals a market where share gains, technology differentiation, and channel execution will determine winners, not merely a rising tide.
Sterile Transparent Dressing Market
What the Research Delivers: From Macro Trajectory to Actionable Architecture
A robust market study does more than report figures; it builds a decision scaffold. This report structures its intelligence so that leadership teams can connect revenue trends with operational realities. The analytical framework is built around three interdependent pillars that matter directly to 2026 planning cycles: segmentation logic that reveals where demand concentrates, competitive profiling that decodes how incumbents protect and extend their positions, and regulatory and reimbursement context that determines which solutions can scale commercially.
The segmentation architecture examines the market across multiple dimensions without reducing the story to a single axis. By mapping the landscape through product categories, application environments, and regional deployment patterns, the study shows how different buyer groups prioritize accuracy, portability, connectivity, and total cost of ownership. This matters because a device strategy that performs in one setting may misfire in another. A hospital procurement committee evaluating clinical-grade reproducibility will weigh evidence and certification differently from a wellness chain optimizing member engagement and throughput, even when both are buying body composition analyzers. The report teases these decision pathways apart so that product leaders can align feature sets, pricing, and go-to-market tactics with the realities of each buying center.
Equally important is the report’s treatment of the competitive field. The industry is not a flat landscape; it is shaped by a handful of established players whose portfolios, clearances, and channel relationships create real barriers for newcomers. The research profiles the organizations that are actively defining standards for professional use, including their distinct technological orientations and deployment strengths. Tanita Corporation has built its reputation around FDA-cleared professional multi-frequency bioelectrical impedance analyzers designed for segmental assessment in both clinical and fitness environments. InBody Co., Ltd. has expanded its footprint with a professional BIA family spanning the 270, 380, 580, 770, and 970 series, emphasizing reproducibility across hospitals, clinics, and sports applications. Hologic, Inc. anchors its offering in the Horizon DXA system, which supports whole-body composition, bone density, and lean and fat mass analysis in clinical settings. OMRON Corporation contributes Bluetooth-connected body composition monitors that apply bioelectrical impedance for segmental analysis across wellness and clinical programs. Seca GmbH & Co. KG provides medical-grade BIA devices in its mBCA series, integrating ultrasonic height measurement to support precise hospital and clinical assessment. Bodystat Ltd. focuses on portable BIS and BIA analyzers built for quick, accurate segmental and whole-body measurements in fitness and medical contexts. RJL Systems, Inc. continues to advance its Quantum series for whole-body and segmental composition analysis with a foundation in clinical validation.
These profiles are not static company summaries. They are used to illuminate how product architecture, certification status, and application focus shape market access. The study explains where each player’s differentiation creates leverage, where their coverage is strongest, and what gaps may remain for challengers or new entrants. For 2026 strategists, this is the difference between guessing which competitor might move next and understanding the structural incentives behind their likely moves.
Regulatory and Reimbursement Signals That Reshape Commercial Calculus
Technology alone does not determine adoption; the rules of the market do. One of the most valuable contributions of this research is its integration of regulatory and reimbursement context into the broader market narrative. Rather than treating compliance as an afterthought, the report uses these signals to explain where demand can legitimately scale and where friction may persist.
On the regulatory side, the United States has registered 430 body composition analyzers with the FDA, a figure that underscores both the breadth of product activity and the importance of clearance status in professional procurement. At the same time, specific devices continue to secure milestone approvals that open or reinforce market pathways. The Seca mBCA 514 body composition analyzer obtained FDA 510(k) clearance, reinforcing the viability of medical-grade bioimpedance platforms in hospital and clinic workflows. In parallel, the Hologic Horizon DXA system received CE Mark approval for body composition analysis, broadening its addressable footprint in settings that recognize European conformity standards. These approvals are not isolated accolades; they are commercial enablers that influence purchasing confidence, integration into care pathways, and acceptance by institutional buyers.
Reimbursement dynamics add another layer of strategic relevance. CPT code 0358T remains available for whole-body bioelectrical impedance analysis body composition assessment, preserving a billing pathway that can improve the economic case for clinical adoption. For healthcare providers weighing capital equipment decisions, the presence of a usable reimbursement code can shift the cost-benefit calculus and alter the speed at which a technology moves from pilot use to routine deployment. The research places these reimbursement realities in context, showing how they interact with workflow fit, evidence requirements, and purchasing cycles across care settings.
For a strategist in 2026, these dynamics are not background color. They define where the addressable opportunity is most liquid, which product characteristics are likely to be rewarded, and how quickly a new offering can gain traction. The report translates these regulatory and reimbursement signals into practical implications for market entry timing, sales enablement, and partnership choices.
Interpreting the 2026–2032 Trajectory for Strategic Planning
The forecast period is where intelligence becomes usefulness. A market growing from 567.17 million USD in 2026 toward 847.35 million USD by 2032 at a 6.98 percent compound annual growth rate is expanding steadily, but steady growth rewards disciplined strategy more than brute-force investment. The report frames this trajectory as a planning tool for capacity decisions, R&D prioritization, channel expansion, and M&A evaluation.
Several strategic questions naturally emerge when the numbers are read alongside the competitive and regulatory context. Which applications are likely to absorb new capacity fastest, and what evidence or integration capabilities will those buyers demand? Which product categories offer the clearest route to differentiation without triggering a race to the bottom on price? Where do regional procurement cultures and regulatory environments create uneven adoption curves that require localized market approaches rather than a uniform global rollout? The study addresses these questions by connecting the macro forecast to the structural factors that actually drive purchasing behavior.
The report also places market concentration in strategic context. With the top three competitors accounting for 47.8 percent of market revenue and the top five reaching 62.1 percent, the industry reflects a meaningful degree of consolidation among leading players. This concentration matters for 2026 strategy because it shapes the bargaining power of distributors, the expectations of institutional buyers, and the realistic pathways for challengers. A new entrant cannot assume that a technically competent device will automatically gain traction in a field where incumbents already command a large share of revenue and have established validation narratives, service networks, and recurring customer relationships. The research helps leaders assess whether to compete on a narrow advantage, pursue partnership-based distribution, or target underserved application environments where concentration is less protective.
Why the Full Report Is Essential for 2026 Decision-Making
An executive summary can point toward direction, but it cannot replace the granular architecture required for real commitments. The full report extends well beyond the macro outlook and company profiles previewed here. It delivers a working view of how the market segments in practice, where buyer preferences are converging or diverging, and how the competitive set is likely to evolve as clearances, reimbursement realities, and technology upgrades reshape buying criteria. It gives strategy teams a basis for scenario planning rather than a single-point guess.
For product leaders, the study supports decisions about feature emphasis, clinical validation, connectivity, and form factor by tying them to the settings where they will be evaluated. For commercial teams, it informs channel design, pricing architecture, and value proposition framing by revealing how different buyer groups justify investment. For investors and corporate development teams, it provides a structured lens on where concentration is high, where whitespace may still exist, and where regulatory momentum could accelerate adoption. For operations and supply planning, it offers a forecast shape that can be stress-tested against different assumption sets.
Crucially, the report is built to remain useful as conditions change. By grounding conclusions in historical data from 2020 to 2025 and extending them through 2032, it gives decision-makers a reference frame that can be revisited as new clearances emerge, reimbursement policies shift, and competitor moves alter the field. That continuity is what turns a market overview into a strategic asset.
How to Use This Intelligence in 2026 Planning Cycles
The most effective use of this research is not passive reading but active integration. We recommend that leadership teams approach the full document as a decision toolkit. Start by aligning the forecast with internal capacity and investment horizons, then test whether current product and channel assumptions still fit the segmentation pattern revealed in the study. Use the competitive profiles to challenge hidden assumptions about barriers, substitution risk, and the realistic scope of differentiation. Bring the regulatory and reimbursement context into procurement and clinical advocacy conversations so that product value is framed in terms that institutional buyers can act on.
The report also supports more disciplined external messaging. When speaking with partners, distributors, or prospective customers, teams can anchor claims in a coherent view of market structure rather than isolated stats. That matters because credibility in this sector depends on demonstrating that a solution fits a real adoption pathway, not merely that it exists. The more precisely a company can connect its offering to the application environment, evidence expectations, and purchasing logic described in the research, the stronger its position becomes in 2026 negotiations and pilots.
Closing Perspective
The body composition analysis market is entering a phase where durable growth and competitive separation depend on the same thing: a clear understanding of how technology, regulation, reimbursement, and buyer behavior intersect. The numbers tell part of the story, but the strategic value lies in the structure beneath them. From the 2020 baseline of 388.32 million USD through the 2025 base year of 535.64 million USD and into the 2032 projection of 847.35 million USD, the market is expanding at a pace that rewards precision over speculation. The 6.98 percent compound annual growth rate across the forecast window reinforces the need for planning discipline rather than reactive optimism.
This research is designed to give executives that discipline. It preserves the analytical depth required to guide product, commercial, and investment decisions while keeping the most actionable segmentation and competitive insights intact for the full document. For teams preparing for 2026, the opportunity is not simply to note that the market is growing, but to decide where to position, how to justify adoption, and which competitive moves are most likely to pay off. The complete report provides the intelligence needed to make those choices with confidence. To access the full dataset, segmentation logic, and executive recommendations, visit the source page and secure the complete market intelligence package.
For detailed analysis of this topic, please visit the official page: Body Composition Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Stem Cell Therapy Market Hits $232.5M in 2025, 7.05% CAGR to $375.1M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Next Frontier: Inside the Animal Stem Cell Therapy Market 2026–2032
The animal health sector is undergoing a paradigm shift. For decades, veterinary medicine relied heavily on pharmacological interventions and surgical procedures to manage chronic conditions, degenerative diseases, and complex injuries in companion and livestock animals. Today, a new therapeutic class is redefining the standard of care: stem cell therapy. What was once confined to experimental research laboratories and elite specialty clinics has matured into a structured commercial landscape, driven by advances in regenerative biology, evolving regulatory frameworks, and an expanding willingness among pet owners and producers to invest in long-term animal health outcomes.
Hot Water Heating Cable Market
PW Consulting’s latest market research report on the Animal Stem Cell Therapy Market captures this inflection point with precision. Designed for executive leadership, R&D directors, commercial strategists, and investment committees, this study maps the trajectory of a market that has moved from nascent curiosity to measurable revenue momentum. The following analysis previews the strategic lens, structural insights, and decision-making utility embedded in the full report, while preserving the granular intelligence that will be delivered in the complete publication.
Shooting Earmuff Market
A Market That Has Crossed the Proof-of-Concept Threshold
Regenerative therapies for animals are no longer a speculative storyline. The data tells a clear story of consolidation and acceleration. Between 2020 and 2025, the market expanded from a modest baseline to a multi-hundred-million-dollar revenue pool, reflecting sustained adoption across veterinary practices, specialty clinics, and emerging commercial partnerships. The trajectory has not been linear, but it has been durable. Fluctuation in early years gave way to steadier growth as clinical applications broadened, practitioner awareness deepened, and supply-side capabilities improved.
Worldwide Pipe Grouting Service Market
Looking forward, the forecast window through 2032 indicates continued expansion at a compound annual growth rate that underscores the sector’s structural momentum. This is not a bubble built on hype; it is a commercial pathway shaped by tangible therapeutic demand, incremental regulatory clarity, and a growing number of players transitioning from investigational products toward commercialized offerings. For decision-makers evaluating market entry, partnership structures, or portfolio reallocation, the growth curve offers both opportunity and timing risk. The window for strategic positioning is open, but it is narrowing as more competitors validate the commercial viability of stem cell–based veterinary solutions.
The report situates these figures within a broader narrative of adoption maturity. It examines how early clinical enthusiasm has been tempered by operational realities, how pricing models are stabilizing around practitioner workflows, and how the balance between autologous procedures and off-the-shelf allogeneic products is reshaping the economics of veterinary regenerative medicine. Readers will find that the headline growth numbers are only the starting point; the strategic value lies in understanding the forces that will determine which business models scale and which remain confined to niche applications.
Segmentation as a Strategic Compass
Understanding where demand is concentrated, and why, is essential for resource allocation. The report dissects the market across multiple axes without reducing it to static percentage tables. Instead, it examines the structural logic behind each segmentation dimension so that executives can align their go-to-market strategy with the underlying drivers of adoption.
At the application level, the therapy landscape is anchored by orthopedic and degenerative conditions, with osteoarthritis representing the dominant clinical use case. Tendon and joint disorders, wound healing, bone repair, and inflammatory conditions each contribute distinct demand profiles, while emerging applications in oncology and complex systemic diseases illustrate the long-tail potential that will shape later-stage commercialization. The report analyzes how clinical evidence maturity, practitioner familiarity, and reimbursement or out-of-pocket willingness vary across these indications, and how those variables influence volume, margin, and cycle time for therapy developers.
Animal type segmentation reveals a market that is currently anchored by companion animals but with meaningful structural relevance from livestock applications. Companion animal segments benefit from higher owner spending capacity, emotional decision-making dynamics, and direct-to-consumer awareness channels. Livestock applications, while smaller in current revenue contribution, carry different economic logic: herd-level outcomes, production efficiency, and veterinary economics that reward scalable, cost-effective regenerative interventions. The report examines how these two segments diverge in purchasing behavior, clinical workflow requirements, and commercial scaling strategies, enabling readers to identify where their capabilities best align with end-market economics.
Geographic segmentation further illuminates the commercial map. North America currently represents the largest revenue concentration, supported by established veterinary specialty networks, advanced laboratory infrastructure, and early regulatory engagement. Europe follows with its own distinct demand patterns shaped by regional practice structures and differing attitudes toward regenerative modalities. Asia Pacific reflects an emerging but accelerating footprint, driven by expanding pet ownership, growing veterinary specialization, and increasing investment in animal health innovation. Latin America and the Middle East and Africa represent additional zones of potential expansion, each with unique access, pricing, and distribution dynamics. Rather than presenting raw regional splits, the report translates these patterns into actionable intelligence about where infrastructure, partnerships, and regulatory readiness create viable entry points, and where caution is warranted.
The Competitive Arena: Differentiated Strategies in a Contested Space
The animal stem cell therapy market is not a winner-take-all environment, but it is increasingly defined by differentiated positioning. Companies are competing along multiple dimensions: product format, regulatory status, clinical indication focus, delivery logistics, and veterinarian engagement models. The report provides a structured competitive landscape analysis that goes beyond company descriptions to examine how each player’s strategic choices shape their commercial prospects.
Gallant has emerged as a notable example of a company pursuing allogeneic, ready-to-use therapies for companion animals. Its focus on refractory feline chronic gingivostomatitis and osteoarthritis reflects a strategy centered on unmet clinical need and regulatory ambition, including advancement toward FDA conditional approval. In early 2026, Gallant announced a first-of-its-kind partnership with MWI Animal Health to establish ultra-low temperature cold chain logistics for delivery of ready-to-use stem cell therapies into veterinary clinics. This move highlights a critical commercial challenge: the requirement for reliable storage and distribution at very low temperatures can become a barrier to adoption if not solved at scale. By investing in cold chain infrastructure, the company is addressing a bottleneck that affects not only its own product pathway but also signals broader operational expectations for off-the-shelf regenerative therapies in veterinary medicine.
VetStem, Inc. represents a different strategic posture, with deep experience in autologous stem cell therapies derived primarily from adipose tissue for canine osteoarthritis, equine joint disorders, and chronic pain management. At the same time, the company is expanding toward allogeneic off-the-shelf products, including precise regenerative solutions and orthopedics-focused pipelines. Additional funding secured in early 2025 is being directed toward advancing StemStat Ortho toward FDA conditional approval, signaling a dual-track strategy that pairs established practitioner relationships with next-generation product development. The report examines how VetStem’s positioning illustrates the broader industry tension between customization and standardization, and how companies are attempting to capture value across both paradigms.
Ardent Animal Health operates with a strong in-clinic autologous regenerative therapy model, offering stromal vascular fraction–based treatments and platelet-rich plasma solutions for dogs and cats with orthopedic conditions. Its approach reflects the commercial reality that many veterinary practices prefer point-of-care procedures that integrate directly into existing clinic workflows. VETherapy, with development operations spanning San Francisco and Coimbra, Portugal, emphasizes cost-effective and time-efficient regenerative solutions for complex pet diseases, underscoring the importance of operational efficiency in a market where adoption depends heavily on practitioner convenience and case throughput.
Magellan Stem Cells, based in Australia, contributes a regional perspective by supplying autologous and donor-derived mesenchymal stem cells for osteoarthritis treatment in companion animals, with clinical trial planning underway. Its presence illustrates how market activity is distributed across geographies and how companies in emerging hubs are building capabilities that may eventually intersect with larger global commercialization pathways.
The competitive analysis in the report does not treat these players as isolated profiles. It evaluates them within the context of market concentration, showing that the sector remains moderately consolidated, with a meaningful share held by a relatively small group of active commercial and development-stage companies. This concentration pattern matters for M&A strategy, partnership targeting, and barrier-to-entry assessment. It also signals that the field is still open enough for new entrants with differentiated technology or business models, but increasingly crowded enough that undifferentiated plays will face pressure on pricing, clinical differentiation, and practitioner loyalty.
Regulatory Realities and Industry Dynamics
No assessment of this market is complete without confronting the regulatory environment, which remains one of the most important variables shaping commercial timelines, risk exposure, and strategic planning. The report dedicates substantial attention to the current state of oversight, the practical implications for product developers, and the signals that indicate where the regulatory trajectory is heading.
As of early 2025, no FDA-approved animal cells, tissues, and cell- and tissue-based products were available for veterinary use in the United States. This absence is not a marginal detail; it defines the current commercial landscape. Companies are navigating a space where therapeutic promise and investigator interest are substantial, but formal approval pathways remain incomplete. That reality creates both urgency and caution. For developers, it means clinical data generation, quality systems, and regulatory engagement must be advanced with precision. For veterinary practices and distributors, it means procurement, communication, and compliance strategies must account for the distinction between approved therapeutics and investigational or unregulated offerings.
Regulatory pressure has already begun to manifest in enforcement activity. In 2025, the FDA issued warning letters to companies including Ardent Animal Health, LLC and Safari Stem Cell, LLC for marketing unapproved stem cell and regenerative products. These actions signal a more active oversight posture and highlight the compliance risks facing organizations that move faster than regulatory frameworks can accommodate. The report examines what these enforcement patterns imply for market discipline, how they may influence practitioner confidence, and why companies with robust regulatory strategies may gain competitive advantage as the field matures.
At the same time, there are signs of constructive progress. Regulatory engagement is not uniformly obstructive. For example, the FDA Center for Veterinary Medicine completed the Reasonable Expectation of Effectiveness technical section letter for Gallant’s lead feline chronic gingivostomatitis stem cell therapy candidate in September 2025, a milestone that reflects a pathway toward conditional approval and a more structured interface between innovators and regulators. VetStem’s additional funding and advancement of StemStat Ortho toward FDA conditional approval further illustrate how companies are converting regulatory engagement into forward momentum. These developments are not guarantees of success, but they provide a realistic basis for scenario planning.
Beyond regulation, the report analyzes other industry dynamics that influence commercial execution. Supply chain architecture is one critical area. The cold chain requirements for certain stem cell products, including ultra-low temperature storage and transport, create logistical complexity that affects cost, reach, and clinic-level feasibility. The recent move by Gallant to establish the first ultra-low temperature cold chain in veterinary medicine for therapies requiring -80°C storage is a tangible example of how operational innovation can become a strategic differentiator. Distribution partnerships, storage equipment availability, training requirements, and clinic workflow integration all become variables that determine whether a product is theoretically promising or practically adoptable.
The report also explores practitioner adoption patterns, clinic economics, and the role of education and professional advocacy in accelerating uptake. Stem cell therapies do not sell themselves through traditional pharmaceutical channels alone; they require engagement with veterinarians who must understand indications, collection or delivery procedures, patient selection, expected outcomes, and realistic limitations. Companies that invest in veterinary education, clinical support, and evidence dissemination are better positioned to build durable demand than those that rely solely on product availability.
What the Report Delivers for Decision-Makers
This study is designed as an operational intelligence asset rather than a high-level overview. It translates market trajectory into concrete strategic inputs across multiple functional areas. The full report includes detailed analysis and structured content intended to support planning, prioritization, and risk assessment.
- A comprehensive market sizing and forecast framework that connects historical performance with the 2026–2032 outlook, enabling readers to benchmark internal projections and test growth assumptions against sector-wide trends.
- Application-level analysis that maps demand concentration, clinical maturity, and commercial implication across major therapeutic areas, helping R&D and commercial teams align pipeline focus with adoption readiness.
- Segmentation insights across animal type and geography, presented with strategic interpretation rather than raw splits alone, so that executives can evaluate where to invest, partner, or stage market entry.
- Competitive landscape profiling that examines company strategies, product formats, regulatory posture, and operational models, providing context for partnership screening, benchmarking, and positioning decisions.
- Regulatory and compliance analysis that addresses the current absence of FDA-approved veterinary cell- and tissue-based products, recent enforcement actions, and the implications of conditional approval pathways for product planning and market timing.
- Supply chain and distribution considerations, including cold chain requirements, clinic-level logistics, and the operational prerequisites for scaling off-the-shelf regenerative therapies.
- Strategic scenario inputs that support M&A evaluation, investment prioritization, and market-entry planning by identifying where concentration, differentiation, and execution risk converge.
By integrating these elements, the report enables readers to move from general market awareness to specific decision support. It is structured to help leadership answer practical questions: Which indications and animal segments offer the strongest commercial logic for a given capability set? How should a company respond to a regulatory environment that is simultaneously restrictive and progressively clarifying? What operational capabilities must be built or sourced before a therapy can be reliably delivered at scale? Where does market concentration create both partnership opportunity and competitive vulnerability? The full publication provides the structured evidence and interpretive framework needed to address these questions with confidence.
Why 2026 Is a Strategic Inflection Point
The years ahead will reward organizations that act on informed timing rather than reactive adaptation. In 2026, the market is positioned at a point where early adoption patterns are becoming clearer, regulatory engagement is intensifying, and operational infrastructure for regenerative veterinary therapies is beginning to take shape. Companies that treat these shifts as background noise risk being outpaced by competitors who are already aligning product strategy, compliance planning, and distribution design with the market’s emerging structure.
For therapy developers, the strategic priority is to connect clinical ambition with regulatory realism and commercial feasibility. For veterinary service providers and distributors, the priority is to understand which therapies are approaching credible regulatory and operational readiness, and how to integrate them into practice workflows without overcommitting to unproven or non-compliant offerings. For investors and corporate strategists, the priority is to distinguish sustainable differentiation from short-term promotional momentum, and to assess the operational and regulatory moats that will determine long-term value creation.
PW Consulting’s Animal Stem Cell Therapy Market research is built to support these decisions with depth, discipline, and a clear line of sight from market data to strategic action. The macro trajectory, segmentation logic, competitive dynamics, and regulatory context are all essential inputs, but the real value lies in how they are synthesized into an actionable view of where the market is going and what it will take to compete successfully within it.
The full report expands on every dimension previewed here, offering the detailed segmentation intelligence, competitive benchmarking, regulatory framing, and scenario-based strategic recommendations that enterprise decision-makers require. To access the complete analysis and the proprietary data that underpin it, readers are invited to visit the source page and retrieve the full market research package. In a market defined by rapid evolution and contested positioning, comprehensive intelligence is not a luxury; it is a prerequisite for confident strategy.
For detailed analysis of this topic, please visit the official page: Animal Stem Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glucagon Market to Reach $505M by 2032, Growing at 5.25% CAGR
By PW Consulting, 2026-09-07
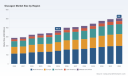
The Glucagon Market at an Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global glucagon market stands at a critical juncture where decades of steady therapeutic reliance are colliding with structural shifts in manufacturing capacity, regulatory clarity, and next-generation delivery formats. For pharmaceutical executives, investors, and healthcare strategists, the numbers alone tell only a fraction of the story. What matters now is the operational architecture behind those numbers: how concentrated supply chains are adapting, how dose-ready innovations are reshaping emergency care, and how macro policy signals are re-tuning metabolic supply networks that indirectly support glucagon diagnostics and rescue use. Our newly released Glucagon Market research report was designed to translate these layered dynamics into actionable intelligence for 2026 planning cycles and beyond.
Transparent PI Hard Coating Film Market
From a top-line perspective, the market has demonstrated resilient growth through the second half of the decade, with base-year valuation at USD 368.5 million in 2025 and a projected trajectory climbing toward USD 400.49 million in 2026. Over the historical window from 2020 to 2025, the segment moved from USD 288.5 million through a series of incremental expansions, reflecting both steady diabetes prevalence and gradual adoption of emergency hypoglycemia management tools. Looking forward, the forecast period from 2026 through 2032 maps a compound annual growth rate of 5.25 percent, with endpoint valuation approaching USD 505.0 million. These figures are not merely a backward-looking summary; they serve as the scaffold for a more granular examination of where value is being created, which product architectures are gaining share, and how regional demand curves are diverging under regulatory and reimbursement pressure. The full segmentation architecture, pricing sensitivity ranges, and regional volume splits are detailed within the report, because surface-level totals cannot reveal the operational logic decision-makers need.
Tunnel Jet Fans Market
What makes this edition distinct is its focus on decision readiness. Rather than simply charting historical trajectories, the research converts market momentum into a structured toolkit for capacity planning, portfolio prioritization, partnership evaluation, and risk calibration. Below is a preview of the analytical depth and operational content embedded in the full study.
Worldwide Silver Coated FEP Film Market
Competitive Architecture and the reshaped Supplier Landscape
The glucagon sector remains moderately concentrated, with the top three competitors accounting for roughly 55 percent of revenue and the top five capturing closer to 78 percent. That concentration is not a static relic; it reflects deliberate investments in manufacturing scale, differentiated formulation strategies, and territory-specific commercialization strengths. The report profiles the core participants shaping this environment, mapping their technical positioning, supply footprints, and recent strategic moves so that readers can assess not only who holds share today but which entities are structurally positioned to capture the next wave of demand.
Eli Lilly and Company, headquartered in Indianapolis, continues to anchor part of the emergency rescue segment through its recombinant rDNA-origin glucagon for injection, positioned both for severe hypoglycemia treatment and as a diagnostic aid to inhibit gastrointestinal motility. Its operational posture has recently been reinforced by a USD 3 billion commitment to U.S. injectable-drug manufacturing capacity for metabolic treatments, including glucagon signaling products, signaling a long-term view of domestic supply resilience and broader metabolic portfolio integration. Novo Nordisk A/S, based in Bagsværd, maintains its established position with GlucaGen rDNA glucagon injection for severe hypoglycemia in diabetes patients and diagnostic applications. The company's May 2026 announcement of a USD 4.1 billion expansion of its North Carolina manufacturing facility to boost injectable production lines, including glucagon, underscores a capacity build that extends well beyond incremental volume gains and into structural supply assurance.
Amphastar Pharmaceuticals, Inc., operating from Rancho Cucamonga, remains an active producer of generic glucagon for injection that is bioequivalent to established branded products, packaged within emergency kits for severe hypoglycemia treatment. This generic presence is strategically important because it defines the price-accessibility floor of the market and influences how branded players defend differentiation through convenience, stability, and device experience. Fresenius Kabi USA, LLC, based in Lake Zurich, continues as an active supplier of synthetic glucagon for injection for severe hypoglycemia treatment across pediatric and adult diabetes populations, reinforcing the hospital and clinical channels where reliability and compatibility with institutional procurement systems matter as much as product architecture.
The competitive frontier is increasingly defined by formulation and device innovation. Xeris Biopharma Holdings, Inc., from Austin, has built its identity around Gvoke, a ready-to-use stable liquid glucagon, alongside the Gvoke HypoPen autoinjector for severe hypoglycemia rescue in patients aged two and older. Its March 2025 FDA approval of a supplemental New Drug Application for Gvoke VialDx, expanding use as a diagnostic aid for glucagon, broadens the commercial and clinical footprint beyond rescue alone. More recently, the company's exclusive partnership with Beta Bionics to co-develop pump-ready liquid glucagon for dual-hormone artificial pancreas systems points toward an ecosystem where glucagon is no longer only an emergency fallback but an integrated component of automated metabolic management. Zealand Pharma A/S, headquartered in Copenhagen, advances the differentiated analog path with dasiglucagon under the ZEGALOGUE injection brand for severe hypoglycemia in diabetes patients. Its regulatory journey also illustrates the complexity that persistent innovation can encounter, including a second Complete Response Letter in October 2024 for pediatric congenital hyperinsulinism dosing, with data resubmission expectations by the end of 2025 for continued approval progress.
The strategic implication is that competitive advantage is migrating from pure volume toward delivery reliability, formulation stability, device usability, and ecosystem integration. The report's competitive section goes beyond biographical summaries to evaluate how these profiles interact with supply constraints, procurement cycles, and regulator-facing milestones. Readers who need to assess partnership opportunities, competitive response scenarios, or territory entry feasibility will find the comparative framework built for that purpose.
Market Dynamics: Supply Realities, Regulatory Signals, and the Stabilization Effect
A robust market view requires more than competitor mapping; it requires an honest accounting of the forces that can accelerate or disrupt the trajectory. One of the most consequential dynamics in the recent period has been the persistence of API and fill-finish supply constraints for synthetic glucagon products, driven in part by limited pre-filled syringe capacity and broader manufacturing capacity bottlenecks. These constraints are not abstract; they affect time-to-market, batch reliability, hospital stocking patterns, and the economics of emergency kit distribution. The report translates these constraints into commercial implications, distinguishing between temporary friction and structural capacity gaps, and identifies which product formats and supplier configurations are most exposed.
Regulatory stabilization in adjacent metabolic categories has also begun to re-tune the operating environment. The FDA's determination that the shortage of semaglutide injection products was resolved as of February 2025, followed by the resolution of tirzepatide injection shortages as of October 2024, has helped stabilize related metabolic supply chains. While these are GLP-1 receptor agonist products rather than glucagon therapies, the stabilization matters because it indirectly supports the broader diabetes management infrastructure within which glucagon diagnostics and emergency use operate. When surrounding supply networks are less volatile, procurement teams, distributors, and clinical protocols can plan with greater confidence, and that confidence tends to flow into more consistent demand realization for rescue and diagnostic glucagon applications.
At the same time, regulatory pathways for newer formulations remain iterative. The experience of dasiglucagon development demonstrates how promising innovation can still face gatekeeping milestones that alter commercialization timing, especially in pediatric and specialty indications. Conversely, the expansion of Gvoke VialDx into diagnostic use reflects how existing platforms can unlock additional use cases without requiring an entirely new product architecture. The dynamics section of the report traces these regulatory interactions carefully, not to predict every outcome, but to equip strategists with scenario-aware planning frameworks. In an environment where one Complete Response Letter or one supplemental approval can reshape a product's addressable market, organizations need more than a headline; they need a structured read on probability, timing, and downstream commercial impact.
Report Contents: What Decision-Makers Will Find Inside
The Glucagon Market research report is organized to support multiple workstreams simultaneously. It is not a single-view dashboard but a modular intelligence package that can be deployed for portfolio review, supply chain strategy, competitive benchmarking, investment screening, and market-entry evaluation. The following elements are developed in depth throughout the document.
- Historical performance reconstruction from 2020 through 2025, with base-year grounding and a clear explanation of the demand and supply factors that shaped year-over-year movement across the segment.
- A ten-year forecast window spanning 2026 to 2032, built around a CAGR of 5.25 percent and endpoint valuation near USD 505.0 million, with scenario sensitivity that accounts for formulation adoption, supply normalization, and regulatory pacing.
- Segment-level analysis by region, product type, and application, presented in a way that highlights structural drivers instead of isolated percentages. The full regional and format splits, including volume and value architecture, are provided in the report so teams can identify where relative opportunity is concentrating without relying on second-order estimates.
- A competitive landscape review that connects company profiles to recent operational events, including manufacturing expansions and partnership announcements, so readers can assess not only current share but forward capacity and ecosystem positioning.
- Market concentration metrics that show how the top three and top five competitors frame the pricing, supply, and innovation environment, with interpretation of what that concentration means for entry barriers, negotiation leverage, and differentiation requirements.
- Industry dynamics covering API and fill-finish constraints, pre-filled syringe capacity limitations, regulatory stabilization in adjacent metabolic supply chains, and the educational and clinical infrastructure trends that influence emergency hypoglycemia management.
- Regulatory and development milestone tracking, including diagnostic-use expansions, pediatric indication complexity, and the implications of approval timing on commercial readiness.
- Practical recommendations for capacity planning, portfolio sequencing, partnership targeting, and risk monitoring, tailored for teams that must convert market signal into operational decisions during 2026.
The report is built with an explicit understanding that different stakeholders consume intelligence differently. Commercial leaders may prioritize segment momentum and differentiation pathways; operations teams may focus on capacity constraints and supply normalization timing; investors may want the concentration structure and forward CAGR mapped against milestone risk; and market-access teams may need the regulatory and application context that shapes hospital and payer adoption. The content architecture accommodates those needs without forcing every reader into a single narrative.
Why This Research Matters for 2026 Decisions
The 2026 planning environment is defined by a tension that is familiar but unusually acute in this sector: demand fundamentals are strengthening, yet supply and regulatory complexity are preventing straightforward extrapolation. A 5.25 percent CAGR over the forecast period is meaningful, but the strategic value lies in understanding what drives that growth, which formats capture disproportionate value, how regional demand diverges under local reimbursement and clinical practice patterns, and which competitors are converting capital expenditure into durable supply advantage. Organizations that treat the forecast as a flat line will miss the operational inflection points that determine margin, reliability, and market access.
Three decision themes stand out. First, capacity is becoming a competitive variable, not just a cost variable. The recent manufacturing commitments from leading players reflect an understanding that injectable supply security, fill-finish throughput, and syringe/vial availability can determine who can reliably serve emergency and diagnostic demand. Second, formulation and device experience are increasingly the battleground for differentiation, especially where generic options establish a price floor and branded players must justify convenience, stability, and usability. Third, the regulatory environment is stabilizing in adjacent metabolic categories while remaining iterative for novel glucagon applications, creating a dual dynamic where some operational uncertainty is receding even as product-level approval pathways continue to require careful scenario planning.
For companies evaluating market entry, portfolio extension, or partnership strategy, the report's segmentation and competitive sections provide the necessary scaffold to test assumptions before committing resources. For incumbent players, the same material supports defensive planning: where concentration is high, where supply bottlenecks are most likely to affect service levels, and where adjacent use cases such as diagnostic aids can extend platform value. For investors, the research frames the market not as a single growth curve but as a set of overlapping trajectories with distinct risk and reward profiles tied to formulation maturity, regulatory status, and manufacturing scale.
How to Use the Intelligence: From Signal to Action
The most valuable market research does not simply describe what is happening; it helps teams decide what to do next. In practice, that means connecting market-wide trends to specific operational questions. For example, if a manufacturer is considering an expansion of emergency kit distribution, the report's segmentation logic helps identify which application and format dynamics are most relevant without relying on blunt aggregate figures. If a strategist is evaluating partnership opportunities around automated delivery or dual-hormone systems, the competitive and development event sections provide context on who is moving toward ecosystem integration and what recent partnerships suggest about the direction of travel. If a supply chain leader is mapping exposure to fill-finish constraints, the dynamics section helps distinguish intermittent friction from longer-term structural limits and highlights why pre-filled syringe capacity is a meaningful variable in product availability and commercialization pacing.
The report also supports more disciplined scenario planning. Because macro figures such as the 2025 base valuation, the 2026 projected size, and the 2032 endpoint are presented as part of a broader analytical framework, readers can stress-test their own assumptions against the underlying drivers rather than treating the forecast as a fixed outcome. That discipline matters in a market where regulatory milestones, manufacturing expansions, and formulation adoption can shift the timing and composition of growth even when the overall trajectory remains constructive.
Closing Perspective
The glucagon market is entering a period in which strategic advantage will be defined less by broad visibility and more by precise, actionable understanding. The top-line numbers establish that demand is expanding and that the segment is moving toward a mid-half-billion-dollar valuation by the end of the forecast window. But the operational story is richer: concentration is reshaping bargaining dynamics, manufacturing investments are altering supply assurance, formulation and device innovation are widening the definition of value, and regulatory signals in adjacent metabolic categories are stabilizing the broader infrastructure within which glucagon emergency and diagnostic use operates. Our Glucagon Market research report captures that full complexity in a form designed for 2026 decision-making. It offers the depth required to build confidence and the structure needed to convert insight into planning. For teams that need the regional splits, application and type architecture, concentration interpretation, and company-specific strategic context in detail, the complete report provides the comprehensive intelligence necessary to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Glucagon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Fountain Machines Market Hits $215M in 2025, Projects 33% Growth by 2032
By PW Consulting, 2026-09-07
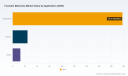
Navigating the Future of Beverage Dispensing: Strategic Insights from the 2026 Fountain Machines Market Report
A Critical Intelligence Brief for Decision-Makers in Foodservice and Equipment Manufacturing
The global beverage landscape is undergoing a subtle but profound transformation. For executives in the foodservice sector, equipment manufacturing, and supply chain management, understanding the trajectory of fountain machines is no longer optional—it is a strategic imperative. As we move through 2026, the inflection points in market volume, technological integration, and regulatory pressure are reshaping how convenience and customization intersect in commercial venues.
O-Tolidine Diisocyanate (TODI) Market
PW Consulting has completed an exhaustive analysis of the Fountain Machines Market, synthesizing historical performance from 2020 through 2025 with a detailed forecast extending to 2032. This introduction serves as a strategic primer, outlining the macro-economic realities and competitive pressures that define this sector. While we offer a high-level view of the landscape here, the granular data required to build precise business cases resides within the full report.
Worldwide Outdoor Camping Cookware Market
The objective of this briefing is to contextualize why immediate engagement with this data is vital for 2026 planning. The market is not merely growing; it is evolving in complexity. Leaders who rely on outdated assumptions about dispensing hardware risk capital misallocation and competitive obsolescence.
Worldwide Distributed Direct Acting Solenoid Valve Market
Macro Market Trajectory: Resilient Growth Amidst Economic Flux
The fountain machines market has demonstrated remarkable resilience over the past half-decade. Historical data indicates a steady climb in global revenue, reflecting the enduring demand for efficient beverage service solutions. From a baseline of approximately 163.15 Million USD in 2020, the market expanded consistently to reach an estimated 215.0 Million USD in 2025. This progression underscores a fundamental truth: despite supply chain disruptions and inflationary pressures during the early 2020s, the underlying demand for commercial dispensing infrastructure remained robust.
Looking forward, the forecast period from 2026 to 2032 suggests a continuation of this upward trend, albeit at a measured pace. The market is projected to reach approximately 237.44 Million USD in 2026, signaling a healthy start to the forecast window. By 2032, valuations are anticipated to approach 344.8 Million USD. This trajectory reflects a Compound Annual Growth Rate (CAGR) of roughly 2.6 percent over the forecast period.
While a 2.6 percent CAGR might appear moderate compared to high-growth technology sectors, it is significant within the context of mature hardware markets. It suggests steady replacement cycles, incremental upgrades, and adoption in emerging foodservice categories. For strategic planners, this stability offers a predictable environment for CAPEX planning, provided that regional and segment-specific nuances are accounted for. It is crucial to note that aggregate figures mask significant variations across geography and application, which are detailed fully in the proprietary sections of our analysis. However, the overarching message is clear: the total addressable market is expanding, creating opportunities for those positioned to capture value across the value chain.
Competitive Landscape: Innovation as the Primary Divisor
The fountain machines market is characterized by a blend of global beverage giants and specialized equipment manufacturers. Market concentration metrics indicate a moderately fragmented environment, with the top three players holding a combined share of approximately 24.6 percent and the top five reaching 26.2 percent. This structure implies that while major brands exert significant influence, there is ample room for specialized innovators to differentiate through technology and service models.
Several key companies are defining the trajectory of this sector. The Coca-Cola Company, headquartered in Atlanta, continues to leverage its Coca-Cola Freestyle platform, offering post-mix dispensing systems with extensive flavor combinations. Their recent moves highlight a shift toward connected innovations and data-driven service. Similarly, PepsiCo, based in Purchase, NY, maintains a strong presence with self-serve and manned dispensers tailored for QSR operators under their core brands.
On the manufacturing side, Lancer Worldwide in San Antonio, TX, remains a pivotal player with their Lancer CED and high-performance tower systems. Metro Fountain Service in Houston, TX, focuses on premium frozen and ice-based systems for institutional applications, while Cornelius Company supplies countertop IDC Pro dispensers with advanced touchscreen and carbonation features. In the Asia Pacific region, Tianwan (Shanghai) Intelligent Equipment Co., Ltd. is manufacturing soda fountain machines and ice-beverage combos for global brands, indicating the growing importance of cross-border equipment supply chains.
Coke Solutions (Coca-Cola Equipment) rounds out the landscape by providing a variety of counter electric, drop-in, and combo systems. The interplay between these entities creates a dynamic where hardware capability is increasingly tied to software integration and service reliability. Companies that fail to integrate with broader POS ecosystems or lack robust maintenance networks risk losing ground to more agile competitors.
Technology and Innovation: The Shift Toward Intelligence and Efficiency
The traditional view of fountain machines as static hardware is obsolete. The 2026 landscape is defined by intelligence, connectivity, and user experience. Recent developments underscore this shift. In May 2026, The Coca-Cola Company unveiled next-generation Freestyle dispensing equipment, including the Freestyle Equinox with a new user interface and the Freestyle Mini designed for compact venues. These launches emphasize real-time pour data, enabling custom drink creation and faster deployment cycles—sometimes as few as 90 days. Such innovations were showcased at the National Restaurant Show in Chicago, providing attendees with hands-on experience of the evolving interface between consumer and machine.
Beyond brand-specific launches, the industry is seeing a broader trend toward automation and integration. As of January 2026, various manufacturers introduced automated models with POS integration capable of handling cup, ice, and drink dispensing simultaneously. This convergence reduces labor friction and enhances throughput, addressing one of the critical pain points for high-volume venues.
Operational efficiency is another driving force. Technical service visits for soda fountain machines typically range from 150 to 300 USD per visit, making annual maintenance a critical factor for peak efficiency and cost control. Organizations that invest in systems with predictive maintenance capabilities or superior durability can significantly reduce total cost of ownership over the lifecycle of the equipment.
Regulatory and Environmental Dynamics
Compliance and sustainability are no longer peripheral concerns; they are central to market access and consumer perception. Regulatory frameworks are tightening around food safety and electrical standards. For instance, NSF and UL certifications are required for commercial fountain dispensers to meet these mandates. Manufacturers must ensure their equipment aligns with these standards to operate in regulated markets, adding a layer of complexity to product development and sourcing.
Hygiene protocols remain paramount. Regular nozzle and diffuser sanitization is mandated to comply with food safety standards, a practice that has been active since standards were established years ago and remains enforced today. Non-compliance can result in operational shutdowns or reputational damage, making equipment design that facilitates easy cleaning a competitive advantage.
Environmental efficiency is also reshaping procurement strategies. New environmental efficiency standards are driving adoption of energy-efficient dispensing systems, particularly in North America. This regulatory pressure aligns with broader corporate sustainability goals, pushing buyers toward solutions that minimize energy consumption without sacrificing performance. Furthermore, the use of syrup concentrates in fountain machines offers ancillary benefits, reducing single-use packaging waste and lowering beverage costs by up to 50 percent compared to pre-packaged alternatives.
Segmentation Nuances and Strategic Implications
While the macro growth figures provide a reliable baseline, the true strategic value of market intelligence lies in understanding the segmentation splits. The market is divided across distinct regions, types, and applications, each with unique growth drivers and barriers.
In terms of equipment type, tower fountain machines represent a significant portion of the market, reflecting their prevalence in large-scale foodservice operations where volume and visibility are key. Drop-in fountain machines constitute another substantial segment, often favored for their integration flexibility in existing countertops. Other types, including specialized countertop units, round out the mix. Understanding the specific demand elasticity for each type is crucial for manufacturers planning product line extensions and for buyers evaluating CAPEX portfolios.
Application-wise, restaurants dominate the consumption landscape, driven by the need for consistent, high-quality beverage service in high-traffic environments. Cinemas represent another key application, where fountain systems are integral to concession revenue models. Other applications, including institutional and corporate settings, offer niche but growing opportunities.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents distinct challenges regarding supply chain logistics, regulatory environments, and consumer preferences. For example, while North America sees push for energy efficiency, Asia Pacific may offer faster volume growth linked to expanding QSR chains. Detailed regional revenue breakdowns and growth rates are essential for determining where to allocate sales resources or manufacturing capacity, but these specifics require access to the full segmentation data to avoid strategic missteps.
Why the 2026 Report is Indispensable for Decision-Makers
In an environment where margin pressure is high and technology cycles are accelerating, generic market summaries are insufficient. The PW Consulting Fountain Machines Market Report provides the depth required to execute with confidence. The report goes beyond high-level valuations to offer operational content that directly informs business strategy.
Stakeholders will find detailed profiles of key companies, analyzing their product portfolios, strategic moves, and market positions. This includes analysis of recent developments such as product launches and trade show presence, allowing readers to anticipate competitor moves. For instance, understanding the timing of new UI launches or compact venue equipment can inform procurement timing or competitive positioning.
The report also integrates industry context noise—critical operational facts that impact profitability. Insights on labor costs associated with service visits, the cost benefits of syrup concentrates, and the specifics of NSF/UL certification requirements are woven into the analysis. This ensures that financial models built from the report data reflect real-world operational constraints rather than idealistic assumptions.
Furthermore, the forecast methodology accounts for historical volatility and future drivers, providing a range of scenarios rather than a single static number. This is vital for risk management. Whether you are a manufacturer planning capacity, a distributor evaluating inventory, or a foodservice operator budgeting for 2027 renovations, the granularity of this data supports more accurate financial modeling.
Connecting Macro Trends to Micro Actions
The convergence of stable market growth, technological innovation, and regulatory pressure creates a unique window for strategic action in 2026. Firms that act now can secure advantages in supply chain positioning, technology adoption, and market share retention.
For equipment manufacturers, the emphasis on POS integration and energy efficiency suggests a roadmap for R&D investment. Aligning product development with these trends can open doors to customers seeking compliance and operational efficiency. For distributors and service providers, understanding the maintenance costs and certification requirements allows for more competitive service contracts and value-added offerings. For end-users in restaurants and cinemas, selecting the right type of fountain machine—whether tower, drop-in, or countertop—based on specific application needs can optimize both customer experience and backend costs.
However, executing these strategies requires precise data. Knowing the overall market size is helpful, but knowing which region offers the highest ROI for a new product launch, or which application segment is most sensitive to labor cost savings, requires the detailed segmentation splits and regional analysis contained in the full study. The differences between market segments can determine the success or failure of a specific initiative.
Conclusion: Accessing the Full Intelligence Picture
The Fountain Machines Market is on a steady growth path, supported by enduring demand in foodservice and a shift toward smarter, more efficient dispensing solutions. The projected revenue growth from 237.44 Million USD in 2026 to nearly 344.8 Million USD by 2032 offers a compelling backdrop for investment and strategy. Yet, the aggregate numbers only tell part of the story.
The true competitive edge lies in the details: the specific regional dynamics, the precise application splits, the granular company profiles, and the operational cost factors that influence net profitability. The macro trends highlighted here—resilience in revenue, the rise of connected equipment, and the tightening of regulatory standards—signal a market that rewards informed, data-driven decision-making.
PW Consulting's full market research report delivers this depth. It transforms broad industry observations into actionable intelligence, enabling leaders to navigate the complexities of the fountain machines ecosystem with precision. We invite you to explore the complete analysis to unlock the specific data points, forecasts, and strategic recommendations necessary to optimize your position in this evolving market. Detailed segmentation values, regional revenue specifics, and comprehensive competitor benchmarking are available within the full report to support your 2026 and beyond planning.
For detailed analysis of this topic, please visit the official page: Fountain Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wheat Germ Oil Market Hits $649M in 2025, Poised for 5.81% CAGR Growth Through 2032
By PW Consulting, 2026-09-07
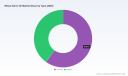
Strategic Horizons in the Global Wheat Germ Oil Market: A 2026 Leadership Brief
The global wheat germ oil market stands at a critical inflection point in 2026. What began as a niche ingredient confined largely to dietary supplements and traditional cosmetics has evolved into a multi-dimensional commodity intersecting pharmaceuticals, functional foods, premium personal care, and specialized animal nutrition. As supply chains recalibrate following years of input volatility, regulatory recalibration, and shifting consumer preferences, corporate leadership requires more than surface-level forecasts. They need a structured, granular understanding of where value is being created, which segments are expanding fastest, which manufacturers are building durable competitive moats, and how external forces such as raw material pricing and trade logistics will reshape margin profiles over the next strategic cycle.
Orange Peel Scrap Grapples Market
This market study was constructed to answer those questions with precision. Drawing on comprehensive historical tracking, forward-looking modeling, and primary-level industry intelligence, the analysis maps the trajectory of wheat germ oil from 2020 through the end of the forecast horizon in 2032. The resulting dataset is engineered not merely to describe where the market has been, but to equip executives, R&D leads, procurement directors, and strategy teams with the decision architecture needed to allocate capital, refine product portfolios, negotiate supply agreements, and anticipate regulatory shifts before they become market-wide constraints.
Worldwide Silicone Pressure Sensitive Adhesives Market
The Strategic Imperative of 2026 Market Intelligence
Corporate planning in 2026 demands a clear distinction between historical momentum and forward-looking inflection. The wheat germ oil sector has already absorbed significant volatility across its value chain, from fluctuating feedstock pricing to evolving pharmaceutical and cosmetic regulatory standards. Yet the underlying demand architecture remains resilient and structurally expanding. The broader market has demonstrated consistent upward progression, with measured scale moving from approximately $562.0 million in 2020 to a projected $665.85 million in 2026. This progression is not accidental. It reflects sustained adoption across health and wellness channels, growing integration into premium cosmetic formulations, and increasing recognition of wheat germ oil’s functional profile in specialized nutrition applications.
Worldwide Organic Preservatives Market
The forward trajectory outlined in the study projects continued expansion beyond 2026, with the market size anticipated to reach $714.04 million in 2027, $787.05 million in 2028, and $824.77 million in 2029, before advancing toward $862.83 million in 2030 and $928.68 million in 2031. By 2032, the modeled market size reaches $957.0 million. These projections are derived through a composite methodology that balances historical pattern recognition with structural demand drivers, competitive capacity shifts, and adoption curves across core usage categories. Importantly, the study does not treat these figures as static endpoints. Instead, it embeds them within scenario-aware planning frameworks that allow leadership teams to assess growth sensitivity, margin exposure, and segment reallocation under changing conditions.
The implied compound annual growth rate across the forecast period is approximately 5.81%, a pace that positions wheat germ oil as a steady, structurally supported category rather than a speculative one. For strategic planners, this level of growth carries specific implications. It suggests sustained demand pull across multiple downstream industries, but it also reinforces the necessity of supply-side discipline, ingredient traceability, and formulation differentiation. Growth at this scale does not automatically translate into margin expansion unless companies understand the underlying segmentation dynamics, regional demand intensity, and competitive density that shape pricing power and customer retention.
What This Study Reveals: Operational Intelligence Across the Value Chain
A credible market study must move beyond aggregate sizing and deliver actionable intelligence that can be operationalized within product development, procurement, sales strategy, and investor communication. This research is structured to serve each of those functions. At its foundation, the report establishes a rigorous baseline for market sizing, historical performance review, and forward modeling, but its differentiation lies in the depth of its applied analysis.
Readers will find a detailed breakdown of how the market is organized across product configurations and end-use channels. The report examines liquid oil formats alongside softgel-ready variants, mapping the distinct manufacturing requirements, formulation considerations, and downstream demand profiles associated with each. It further explores how wheat germ oil is deployed across dietary supplements, cosmetics and personal care, food and beverages, and animal feed, identifying the specific value drivers, adoption barriers, and formulation sensitivities that define each channel. Because each application area carries its own regulatory expectations, consumer perception dynamics, and purchasing behavior, the study isolates where integration is most mature and where emerging demand signals suggest opportunity for expanded penetration.
Equally important is the report’s treatment of regional demand architecture. The analysis maps how demand is distributed across major geographic corridors, highlighting where consumption intensity, manufacturing presence, import-export patterns, and formulation preferences diverge. Rather than presenting oversimplified regional snapshots, the research provides the structural logic behind regional performance, enabling companies to evaluate distribution partnerships, capacity placement, market entry sequencing, and cross-border sourcing strategies with greater confidence. This is particularly relevant in an environment where trade flows, export constraints in major wheat-producing countries, and logistics bottlenecks can materially affect ingredient availability and cost structures.
Competitive Landscape and Strategic Positioning
The wheat germ oil market is shaped by a concentration of established producers and specialized manufacturers, each pursuing distinct positioning strategies across pharmaceutical, nutraceutical, cosmetic, and functional food channels. The report provides a structured competitive assessment that examines how leading companies are aligning product grade, extraction methodology, capacity, and distribution strategy to capture share in a market where differentiation is becoming increasingly important.
Among the companies analyzed, Viobin operates as a producer of cold-processed wheat germ oil sourced from North American wheat, supplied in bulk formats and prepared for softgel integration in supplements and personal care. Connoils LLC functions as a bulk supplier and manufacturer of wheat germ oil and powders for supplement and nutraceutical applications, emphasizing scale and ingredient versatility. In Europe, Gustav Heess GmbH supplies pharmaceutical-grade wheat germ oil with specifications oriented toward purity and cross-application use in food, cosmetics, and nutraceuticals. NOW Foods manufactures cold-pressed wheat germ oil in both liquid and softgel formats, positioned around allergen-conscious consumer expectations. Henry Lamotte Oils GmbH produces high-purity wheat germ oil for pharmaceutical and cosmetic applications and has pursued recent capacity expansions to support growing demand. Th. Geyer GmbH focuses on gentle extraction processes aimed at clean-label food ingredients and organic quality options, reinforcing the importance of process transparency in premium segments. Hebei Jiafeng Plant Oils Co., Ltd. operates as a refined and odorless wheat germ oil producer serving functional foods and export markets, with a product emphasis suited to industrial formulation requirements.
The competitive structure of the market reflects meaningful concentration. The study notes that the top three firms collectively account for approximately 52.0% of market share, while the top five firms extend that concentration to roughly 65.0%. This level of concentration signals a market where scale, quality certification, and supply reliability can serve as durable advantages, but it also indicates that innovation, specification differentiation, and channel specialization remain essential for challengers seeking to expand share without engaging directly in low-margin commodity competition.
Recent Developments Reshaping Market Dynamics
Market dynamics in 2026 are being actively reshaped by operational moves, product launches, regulatory signals, and supply-side constraints. These developments are not peripheral noise; they are indicators of where strategic value is migrating. The report integrates these events into a forward-looking interpretation of market trajectory, rather than treating them as isolated headlines.
One of the most telling capacity signals comes from Henry Lamotte Oils GmbH, which expanded production capacity by 30% in September 2024 to meet growing European demand for pharmaceutical-grade wheat germ oil. This expansion underscores the premiumization trend within the sector and illustrates how quality-graded supply is becoming a strategic bottleneck for manufacturers targeting pharmaceutical and high-end cosmetic applications. In parallel, Hebei Jiafeng Plant Oils Co., Ltd. launched a refined, odorless wheat germ oil tailored for food manufacturers in November 2024, with particular relevance to Asia’s expanding functional food sector. The move highlights how formulation refinement and odor management are becoming critical enablers for broader food and beverage adoption.
Innovation in extraction technology is also reshaping competitiveness. In January 2025, Herbal Biosolutions unveiled a patented extraction technology designed to significantly improve the yield and purity of wheat germ oil for use in Ayurvedic medicine. Such technological advances can alter cost structures and specification boundaries, especially where traditional medicine and nutraceutical formulation intersect. At the same time, regulatory and quality events continue to influence market confidence. In February 2025, the USA FDA posted a voluntary nationwide recall by Brassica Pharma involving ophthalmic ointments containing wheat germ oil, including Equate Stye Lubricant Eye Ointment and CVS Health Lubricant Eye Ointment. Incidents of this nature reinforce the importance of supply chain integrity, specification control, and compliance documentation, particularly for companies operating across pharmaceutical-adjacent categories.
Beyond individual company actions, broader market dynamics are being shaped by raw material pricing, regulatory notices, and trade disruptions. In 2024, wheat germ oil export and import prices ranged from approximately $5.70 to $17.84 per kg, reflecting significant variability tied to grade, origin, and supply conditions. Meanwhile, the USDA projected the 2025/26 USA all-wheat season-average farm price at USD 4.90 per bushel, down from USD 5.52 per bushel in 2024/25, a shift with implications for feedstock cost expectations and upstream pricing leverage. Regulatory attention is also intensifying in select regions; for example, India’s CDSCO issued a public notice in February 2025 related to a soft gelatin capsule formulation containing refined wheat-germ oil BP 10 mg. More broadly, major wheat-producing countries such as India, Russia, and Ukraine continue to face export restrictions and logistical bottlenecks that affect wheat germ supply availability. These forces collectively shape procurement strategies, inventory planning, and price negotiation timelines across the value chain.
Why This Research Matters for Decision-Makers in 2026
For executives and strategy teams, the central challenge is not simply whether the market is growing, but how growth is distributed, where competitive risk is concentrated, and which operational decisions will determine margin resilience in the years ahead. This study is designed to support that decision-making process at multiple levels.
First, it provides a validated baseline for strategic forecasting. Rather than relying on heuristic assumptions or fragmented secondary indicators, the report grounds projections in a continuous historical series and a forward framework that accounts for adoption dynamics, capacity shifts, and regulatory evolution. This allows companies to benchmark internal plans against a defensible market trajectory and adjust investment timing accordingly.
Second, the report enables segment-level strategic prioritization. Because growth is not uniform across applications or product formats, companies need clarity on where specification requirements, consumer expectations, and volume potential align most favorably with their capabilities. The analysis helps identify which channels are likely to reward premium positioning, which formats are gaining manufacturing traction, and where formulation or packaging innovation may unlock additional demand.
Third, the competitive assessment supports realistic positioning strategy. In a market where top players already hold meaningful share and where capacity expansion, grade certification, and extraction quality influence customer selection, new entrants and incumbent competitors alike must define their value proposition with precision. The report helps organizations understand how peer companies are competing on purity, format readiness, organic positioning, and regional specialization, enabling more informed decisions about partnership, acquisition, capacity investment, and channel focus.
Finally, the study integrates supply-side and regulatory signals into a practical risk lens. With raw material pricing variability, evolving regulatory notices, and trade logistics constraints all capable of affecting ingredient availability and cost, procurement and supply chain leaders require early-warning context rather than retrospective data. This research surfaces those factors in a structured way so that companies can stress-test sourcing plans, assess alternative supply routes, and align product claims with compliance realities.
How to Use This Report for Planning and Execution
The research is organized to support multiple internal workflows. Product and formulation teams can use the segmentation and application analysis to evaluate where wheat germ oil can be integrated more effectively into existing portfolios or where new variants may address unmet specification needs. Procurement and supply chain teams can leverage the pricing context, regional demand patterns, and competitive capacity developments to refine sourcing strategies and anticipate timing constraints. Commercial leaders can use the competitive landscape and demand distribution analysis to sharpen positioning, prioritize geographic or channel expansion, and align marketing claims with category expectations. Executive teams can rely on the consolidated market sizing, growth trajectory, and concentration analysis to inform capital allocation, scenario planning, and investor communication.
Because the study balances breadth with depth, it can serve both high-level strategic review and more detailed operational planning. It is structured to help organizations distinguish between near-term tactical issues and longer-term structural shifts, ensuring that decisions are anchored in evidence rather than short-term market noise.
Closing Perspective: The Path Ahead
The wheat germ oil market in 2026 is not defined by a single driver, but by the interaction of demand expansion, competitive specialization, regulatory evolution, and supply-side variability. That complexity is precisely why leadership teams require a comprehensive, structured, and forward-looking research foundation. The market’s progression from a measured 2020 base toward a projected 2032 scale reflects durable interest in wheat germ oil’s functional and formulation value, but capturing the full strategic benefit of that growth will depend on how well companies understand the segment dynamics, competitive relationships, and external pressures that shape commercial outcomes.
This study offers that understanding in a form designed for action. It provides the market architecture, competitive intelligence, and contextual analysis needed to make informed decisions across product, supply, commercial, and governance functions. For organizations seeking to move beyond general market awareness into precise strategic planning, the full report delivers the deeper segmentation data, regional breakdowns, application-level analysis, and competitive benchmarking required to build a confident path forward. The complete dataset and detailed strategic assessment can be accessed through the full market research page, where the full scope of the analysis, underlying structure, and actionable detail is presented for review and planning use.
For detailed analysis of this topic, please visit the official page: Wheat Germ Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railway Equipment Market Set for 6.45% CAGR, Reaching $535.08 Million by 2032
By PW Consulting, 2026-09-07
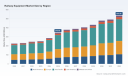
Railway Equipment Market Outlook 2026: Strategic Intelligence for Executive Decision-Making
The global railway equipment market stands at a critical inflection point in 2026. As infrastructure spending accelerates across continents and digital transformation reshapes operational paradigms, industry leaders require more than superficial trend analysis—they need precise, actionable intelligence to navigate capital allocation, regulatory compliance, and competitive positioning. This comprehensive market research publication delivers the depth required to make informed strategic decisions throughout the forecast period extending to 2032.
Worldwide Housekeeping Trolley Market
The railway sector has demonstrated remarkable resilience and growth momentum over the past half-decade. From a base of 225.0 million USD in 2020, the market has progressed through consistent expansion to reach an estimated 345.46 million USD by 2025. This trajectory reflects sustained investment in modernization programs, passenger transport demand recovery, and freight logistics optimization initiatives worldwide. Looking ahead, the market is projected to climb to 378.25 million USD in 2026, continuing its ascent toward 535.08 million USD by 2032. These figures represent more than incremental growth—they signal a structural transformation in how rail infrastructure and equipment are designed, manufactured, and integrated into broader transportation ecosystems.
Elevating Parking Robot Market
Understanding the compound annual growth rate of 6.45 percent across the forecast horizon is essential for executives evaluating long-term investment theses. This growth rate places railway equipment in a favorable position relative to broader industrial equipment categories, driven by unique tailwinds including decarbonization mandates, urbanization pressures, and government stimulus programs targeting sustainable mobility. However, capturing value in this expanding market requires nuanced understanding of segment dynamics, regional variations, and the competitive strategies employed by leading equipment manufacturers.
Worldwide Manual Tool Changer Market
Market Structure and Segment Dynamics
The railway equipment landscape encompasses multiple interconnected segments, each presenting distinct opportunities and challenges for equipment suppliers, operators, and investors. Rolling stock dominates the equipment mix, reflecting the capital-intensive nature of train manufacturing and fleet renewal programs globally. The track infrastructure segment follows, driven by network expansion, maintenance rehabilitation cycles, and safety enhancement projects. Signaling systems, while representing a smaller portion of the overall equipment expenditure, carry disproportionate strategic importance due to their role in capacity optimization, safety certification, and digital rail transformation initiatives.
Application-wise, the market divides between passenger transport and freight transport, both representing substantial and roughly comparable demand centers. This balance underscores the dual importance of commuter and intercity rail modernization alongside freight logistics efficiency improvements. Operators in both domains face common pressures: aging asset bases requiring replacement or upgrade, workforce transitions as experienced personnel retire, and the imperative to integrate digital solutions that improve asset utilization and maintenance predictability.
Regional dynamics vary considerably, with mature markets in Europe and North America focusing on replacement cycles and performance upgrades, while Asia Pacific markets exhibit stronger expansion characteristics driven by new network construction and high-speed rail deployment. Latin America and the Middle East and Africa regions present emerging opportunities tied to development finance initiatives and infrastructure modernization programs. Each regional context carries specific regulatory frameworks, procurement practices, and competitive conditions that demand localized understanding rather than generalized assumptions.
Competitive Landscape: Key Players and Strategic Positioning
The railway equipment market exhibits significant concentration, with the top three firms commanding approximately 65 percent of market share and the top five collectively representing 82.5 percent. This oligopolistic structure reflects the high barriers to entry inherent in railway equipment manufacturing: stringent certification requirements, long qualification cycles, complex supply chain integration, and the need for sustained service and maintenance relationships spanning decades. For new entrants, partnership strategies and niche specialization represent more viable pathways than broad-based market entry attempts.
Several organizations define the competitive frontier through their product portfolios, geographic reach, and strategic moves. Wabtec Corporation, headquartered in Pittsburgh, Pennsylvania, operates as a leading global supplier spanning pantographs, electronic braking systems, couplers, and digital solutions for both freight and passenger rail applications. The company has pursued an aggressive strategic agenda in early 2026, including the completed acquisition of Dellner Couplers, a Sweden-based specialist in safety-critical train connection systems for passenger rolling stock. This acquisition strengthens Wabtec's coupling technology portfolio and expands its European manufacturing footprint. Simultaneously, the company secured multiple contracts to supply over 680 pantographs for six major commuter rail and metro projects in India, demonstrating execution capability in high-volume emerging market deployments. In a significant development for freight interoperability, Wabtec collaborated with more than twenty industry partners including Siemens, Alstom, and ÖBB on joint testing of Digital Automatic Coupler technologies, validating interoperable communication protocols. The company also signed a 670 million USD deal with CSX for 100 new Evolution Series locomotives, 50 modernized units, and integrated digital solutions, reinforcing its freight locomotive market position.
Alstom SA, based in Paris, France, stands as a major provider of signaling systems, rolling stock equipment, and integrated railway solutions serving global rail operators. The company's strategic focus in 2026 includes accelerating digital rail transformation in Queensland, Australia, where its first mainline ETCS contract supports the broader "The Wave" program aligned with Brisbane 2032 Olympics infrastructure preparation. Additionally, Alstom's TGV-M high-speed train received marketing authorization from the European Union Agency for Railways, advancing the product toward passenger service deployment. These developments illustrate the company's dual emphasis on signaling technology leadership and rolling stock innovation for premium high-speed corridors.
Hitachi Rail, headquartered in Tokyo, Japan, supplies signaling, rolling stock, and smart rail solutions including ETCS systems and high-speed train components. The organization combines engineering heritage with digital capability, positioning itself across both traditional equipment categories and next-generation connected rail solutions. Siemens Mobility, based in Munich, Germany, maintains a key position in railway signaling, train control, and high-speed rail equipment, notably advancing ETCS Level 2 systems and Velaro family trains. The company's June 2026 strategic partnership with VinSpeed for comprehensive high-speed rail development in Vietnam, encompassing Velaro Novo train supply, ETCS Level 2 signaling, and electrification systems, signals continued expansion of European technology standards into Southeast Asian markets.
CRRC Corporation Limited, headquartered in Beijing, China, operates as a global manufacturer of locomotives, rolling stock, and railway equipment with particular focus on high-speed and mainline systems. The company benefits from China's extensive domestic rail construction program while pursuing international project participation. Progress Rail, based in Albertville, Alabama, provides signaling systems, locomotives, and rail infrastructure equipment tailored to North American freight and passenger operators, representing a strong regional presence with specific market knowledge. CAF, Construcciones y Auxiliar de Ferrocarriles, headquartered in Beasain, Spain, manufactures rolling stock and railway equipment including trains and maintenance systems, maintaining a strong European manufacturing base with international project execution capability.
Regulatory Dynamics and Technical Standards Evolution
The regulatory environment for railway equipment is undergoing significant updates that will influence product design, certification timelines, and competitive positioning throughout the forecast period. EN 50155:2026, which became valid on 18 May 2026, defines updated requirements for the design, manufacturing, documentation, testing, and integration of all electronic equipment installed on-board rolling stock. This standard applies comprehensively to control, regulation, protection, diagnostic, and energy supply systems, representing a substantial revision from the preceding EN 50155:2021 edition.
The updated standard covers environmental and electrical operating conditions for railway electronic equipment, with specific requirements encompassing temperature tolerance, humidity resistance, shock and vibration resilience, operating voltage parameters, and electromagnetic compatibility testing. Critically, EN 50155:2026 applies to any electronic equipment for rolling stock subsystems, including external doors and wheel slide protection mechanisms. For equipment manufacturers and system integrators, this means that product development cycles must account for revised testing protocols and documentation requirements. Suppliers who proactively adapt their engineering processes and quality management systems will secure competitive advantages in qualification speed, while those with legacy designs may face extended re-certification timelines and potential market access delays.
Beyond product-level standards, the broader regulatory landscape continues to evolve around safety certification, interoperability mandates, and environmental compliance. Operators and equipment procurement teams must navigate these requirements while balancing cost constraints and delivery schedules. The interplay between national regulatory bodies, European standardization organizations like CENELEC, and industry consortiums creates a complex compliance environment that demands specialized expertise. Market participants who invest in regulatory intelligence and maintain active engagement with standards development processes will be better positioned to anticipate changes and manage transition risks.
Strategic Implications for 2026 Decision-Makers
The convergence of market growth, competitive concentration, technological transformation, and regulatory evolution creates a decision environment where informed strategic choices carry significant long-term consequences. For equipment manufacturers, the question is not merely whether to participate in a growing market, but how to position product portfolios, geographic presence, and partnership architectures to capture disproportionate value. Key considerations include:
- Portfolio alignment with high-growth segments: Understanding which equipment categories and application domains are expanding most rapidly enables targeted R&D investment and manufacturing capacity allocation decisions.
- Geographic strategy calibration: Regional market characteristics vary substantially, requiring nuanced approaches to pricing, localization, after-sales service, and partnership models rather than uniform global strategies.
- Certification and standards readiness: Proactive adaptation to evolving technical standards like EN 50155:2026 protects market access and creates differentiation against competitors who react more slowly to regulatory change.
- M&A and partnership evaluation: The acquisition activity visible in early 2026, particularly in specialized components and digital technology domains, signals ongoing industry consolidation. Organizations must continually assess whether organic development or external acquisition offers faster path to strategic objectives.
- Digital integration capability: As signaling, train control, and operational data systems become increasingly integral to equipment value propositions, manufacturers need to demonstrate integration expertise alongside traditional hardware competencies.
For rail operators, infrastructure owners, and public sector procurement entities, the strategic calculus centers on total cost of ownership, reliability, interoperability, and alignment with long-term network plans. Equipment selection decisions made in 2026 will influence operational performance, maintenance burdens, and upgrade pathways for decades. Access to comprehensive market intelligence that illuminates supplier capabilities, technology trajectories, and pricing dynamics supports more effective procurement and partnership strategies.
For investors and financial stakeholders, understanding market concentration patterns, growth segmentation, and competitive moats informs valuation frameworks and risk assessments. The high market concentration levels suggest that established players possess durable competitive advantages, but targeted analysis of segment-level dynamics, regional exposure, and technology transition risks remains essential for accurate investment judgment.
What This Market Research Publication Delivers
This comprehensive Railway Equipment Market research report provides the analytical depth and practical content required to support confident strategic decisions through 2032 and beyond. The publication encompasses detailed segment analysis across equipment types, application domains, and geographic regions, with quantitative projections that enable scenario planning and resource allocation modeling. Readers will find:
- Historical market performance analysis covering the 2020 to 2025 period, establishing baseline trajectories and identifying inflection points that inform forward-looking assumptions.
- Forecast projections through 2032 with granular segment-level data that supports detailed business planning, capacity investment analysis, and competitive benchmarking.
- Comprehensive competitive profiling of leading market participants, including organizational capabilities, strategic positioning, recent developments, and competitive strengths and vulnerabilities.
- Regulatory and standards landscape assessment, translating technical requirements into business implications for product development, certification, and market access strategies.
- Industry dynamics analysis identifying key drivers, restraints, opportunities, and challenges that shape market evolution and create differential outcomes across participants.
- Strategic recommendation frameworks that translate analytical findings into actionable guidance for various stakeholder types, from equipment manufacturers to operators to investors.
The report draws on rigorous research methodologies, primary source analysis, and expert interpretation to deliver insights that go beyond readily available summary statistics. While public information may provide headline market size figures or broad trend descriptions, the complete publication offers the structured detail, segment breakdowns, company-level intelligence, and forward-looking analysis that executives need to move from awareness to action.
Access the Complete Strategic Intelligence
The railway equipment market presents substantial opportunity for organizations positioned to navigate its complexities effectively. Realizing this opportunity requires more than general market awareness—it demands detailed segment intelligence, competitive benchmarks, regulatory foresight, and strategic frameworks tailored to specific decision contexts. This research publication is designed to provide that comprehensive foundation.
Readers seeking the full depth of analysis, complete segment data, detailed company profiles, and actionable strategic recommendations are encouraged to access the complete report through our official publication channel. The full version delivers the quantitative detail, methodological transparency, and interpretive depth necessary to support confident decision-making across the 2026 to 2032 forecast horizon and beyond.
For detailed analysis of this topic, please visit the official page: Railway Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


