



Non-PVC IV Bag Market: Tracking the 6.98% CAGR Shift Toward Safer Solutions
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Non-PVC IV Bag Market
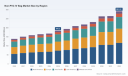
The non-PVC intravenous (IV) bag market has moved from a niche alternative to a structural imperative in clinical packaging. Driven by safety concerns, regulatory momentum, and supply chain resilience priorities, the segment is expanding at a compound annual growth rate of approximately 7.0 percent through 2032. From 2020 to 2025, market revenue grew from roughly USD 139 million to USD 184 million, with the trajectory accelerating as healthcare systems consolidate around DEHP-free and PVC-free infrastructure. Forward projections indicate revenue approaching USD 292 million by the end of the forecast period, reflecting sustained demand for infusion packaging that aligns with modern pharmacovigilance standards and procurement policies.
This expansion is not merely a volume story. It represents a shift in materials science, regulatory expectations, and manufacturing strategy that is reshaping competitive positioning across the value chain. For executives, investors, and procurement leaders, the non-PVC IV bag market offers clear signals about where capital, capability, and partnerships will be rewarded over the next several years.
Intravenous Fluid Bags Market
Market Status and Core Challenges
The market has matured rapidly over the past half-decade, but growth is uneven and constrained by structural frictions. While overall revenue is climbing steadily, participants must navigate a landscape where material performance, regulatory compliance, and capacity availability intersect in complex ways. The following challenges define the current inflection point.
Material Performance and Validation Hurdles
Non-PVC formulations must replicate or exceed the barrier properties, durability, and compatibility characteristics historically associated with PVC. Polyolefin and other alternative polymers have advanced significantly, yet scale-up validation remains costly and time-intensive. Clinical stakeholders require documented evidence on extractables, leachables, and drug-container interactions, which slows adoption for newer materials and raises the barrier for smaller entrants. This validation burden is particularly acute in multi-compartment and specialized infusion configurations, where performance requirements are more demanding.
Regional Regulatory Fragmentation
Regulatory and policy climates are diverging across jurisdictions, creating compliance complexity for manufacturers with global footprints. Some regions are moving toward explicit restrictions on phthalate-based plasticizers, while others continue to rely on broader pharmacopoeial standards. This fragmentation forces suppliers to maintain parallel product families and documentation sets, increasing operational overhead and complicating supply planning. At the same time, localized mandates and public tenders are accelerating the shift to DEHP-free and PVC-free options in specific markets, creating pockets of rapid adoption that do not always align with global rollout timelines.
Capacity Concentration and Supply Resilience
The market remains moderately fragmented at the top, with the largest three players holding just under 30 percent share and the top five reaching roughly 35 percent. While concentration is low enough to preserve competition, it also means that capacity additions and validation wins by leading suppliers can materially influence regional availability. Recent supply disruptions and drug shortage episodes have highlighted how container sourcing can become a limiting factor in critical care delivery. Procurement teams are increasingly treating container formats as part of supply resilience strategy rather than a commoditized accessory, which raises the strategic importance of reliable, qualified non-PVC capacity.
PW Consulting
Key Drivers of Market Change
Technology Innovation and Material Science Advances
Material innovation is the central engine of the transition. Polyolefin-based configurations now command the largest share of the product mix, reflecting their balance of safety profile, mechanical performance, and manufacturability. Polyester-based and ethylene vinyl acetate-based variants serve more specialized requirements, including tailored barrier properties and specific drug compatibility needs. Advances in film extrusion, multi-chamber design, and sterilization compatibility have expanded the range of therapies that can be packaged in non-PVC formats, including ready-to-use injectables and combination products. These advancements reduce the historical trade-offs between safety and performance, making non-PVC options viable across a broader set of clinical applications.
Recent product and regulatory milestones illustrate this momentum. A dual-chamber PVC-free and DEHP-free system received FDA clearance for an antibiotic combination, signaling that complex delivery formats are increasingly acceptable in non-PVC designs. In parallel, a major manufacturer coordinated with regulators to temporarily import saline in non-PVC containers to help mitigate shortages, underscoring how container qualification can directly support continuity of care. Another milestone saw an FDA-approved ready-to-use injectable in IV bags, reinforcing the broader shift toward premixed, non-PVC delivery formats that reduce handling risk and streamline clinical workflows.
Policy and Regulatory Environment
Regulatory direction is reinforcing the commercial case for non-PVC packaging. Pharmacovigilance pressures and public health policies are steadily elevating expectations around plasticizer exposure, particularly in vulnerable patient populations. In one notable example, state-level legislation has mandated that manufacturers notify customers of DEHP-free options and restrict DEHP-containing IV bags and tubing within defined timelines, setting a precedent that encourages broader adoption beyond the jurisdiction itself. These requirements are prompting healthcare systems to update procurement guidelines and push suppliers toward standardized DEHP-free portfolios.
Importantly, the regulatory environment is also enabling non-PVC containers to play a role in shortage management. FDA guidance has recognized non-PVC, DEHP-free IV bags as acceptable in drug shortage mitigation programs, including temporary import pathways for saline in non-PVC packaging. This linkage between regulatory clarity and operational resilience is a powerful catalyst: it positions non-PVC packaging not only as a safety choice but also as a contingency asset during supply stress.
Demand-Side Shifts in Clinical and Procurement Behavior
Demand is being reshaped by a combination of clinical preference, procurement policy, and therapeutic portfolio evolution. Blood and blood product transfusion remains the largest application area, reflecting the high sensitivity of these therapies to container interactions and the importance of minimizing extractables and leachables. Nutritional support and medication delivery applications continue to expand as premixed and ready-to-administer formulations gain traction, driven by goals to reduce preparation errors and improve bedside efficiency. Beyond these core uses, additional clinical applications are adding incremental demand as hospitals standardize container formats across service lines.
Procurement behavior is evolving in parallel. Group purchasing organizations and health systems are increasingly specifying DEHP-free and PVC-free options in contracts, while hospital pharmacies are favoring formats that support batch traceability, compatibility, and ease of use. This demand-side pull is amplified by manufacturers seeking to differentiate through safer packaging narratives and robust compatibility data, creating a reinforcing cycle between clinical confidence and commercial uptake.
Supply Chain and Cost Structure Dynamics
Cost structures are shifting as non-PVC materials move from specialized production to higher-volume manufacturing. Economies of scale are improving, particularly where producers have invested in dedicated eco-friendly facilities with multi-chamber capacity. Such scale advantages can compress per-unit costs over time and improve lead-time reliability, both of which matter to buyers seeking predictable supply. At the same time, raw material availability, film grade qualification, and sterilization pathway compatibility remain levers that influence margin and delivery performance.
Partnerships are becoming an important cost and capability strategy. A recent joint venture between an IV solutions manufacturer and a pharmaceutical partner was aimed at strengthening manufacturing and supply of intravenous solutions in North America, reflecting a broader tendency to align container and solution capabilities to reduce coordination risk and improve continuity. As these arrangements deepen, the market may see more integrated offerings that link bag formats, fill-finish processes, and therapeutic portfolios, changing how value is captured across the chain.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Key Players
The competitive field includes global infusion leaders, regional specialists, and material suppliers, each pursuing distinct positioning. Baxter International emphasizes a DEHP-free portfolio that includes non-PVC large-volume bags, leveraging scale and a broad infusion franchise to standardize safer container options across mainstream channels. B. Braun positions itself around a full line of DEHP-free and non-PVC IV bags and containers, differentiating on breadth of format coverage and a stated commitment to PVC- and DEHP-free offerings across drug, solution, and irrigation containers. ICU Medical focuses on an FDA-approved DEHP-free and non-PVC bag portfolio, aligning its container strategy with regulatory readiness and compatibility assurance for U.S. market access.
Regional and specialty players are carving out differentiated niches. A Korean manufacturer operates what is described as the world's largest eco-friendly non-PVC IV fluid plant with multi-chamber bag capacity, using scale and specialized format capability to serve high-volume, sustainability-aligned demand. A Spain-based supplier offers DEHP-free IV bags for pharmaceutical and medical solutions, emphasizing product-grade compatibility for pharma partners. A Germany-based producer supplies PP-based non-PVC films and tubes for IV solution packaging, positioning closer to the material and conversion layer. A Portugal-based company focuses on pharmacopoeia-compliant DEHP-free bags, appealing to buyers seeking documented compliance. A U.S.-based materials company provides high-quality non-PVC materials for infusion bags, enabling downstream converters and fillers. A UK-based materials supplier contributes polyolefin materials for IV and pharmacological bags, reinforcing the material ecosystem. A UAE-based producer operates a facility producing sterile IV bag solutions in non-PVC bags, expanding regional manufacturing optionality and localized supply.
Differentiation Levers and Competitive Dynamics
Leading players are differentiating along several axes: regulatory readiness, format breadth, material innovation, scale, and regional supply presence. Regulatory readiness is especially valuable where customers face tight compliance timelines or require documented DEHP-free options for tenders and policy mandates. Format breadth matters for health systems that want to consolidate container types across therapies and reduce training and handling variability. Scale and dedicated eco-friendly capacity help stabilize lead times and improve cost trajectories, while material and film expertise can shorten qualification cycles for new drug-container combinations. Regional manufacturing presence is increasingly important for supply resilience, local content expectations, and responsiveness to policies that encourage or require domestic sourcing.
Evolution of the Market Structure
The market is likely to evolve through a combination of consolidation among scaled players, deepening specialization among niche suppliers, and selective entry by companies that can bring compliant material platforms and regional capacity. Because concentration at the top remains moderate, there is room for multiple winners, but differentiation will depend on execution in qualification, supply reliability, and partnership ecosystems rather than on scale alone. The ongoing trend toward premixed and ready-to-use formats, together with drug shortage management needs, may encourage more integrated plays that connect bag formats with solution production and fill-finish capabilities. At the same time, suppliers that can offer standardized DEHP-free and non-PVC options with strong compatibility data will be better positioned to capture procurement mandates and public tenders as they expand.
Future Trends and Commercial Opportunities
Accelerated Standardization of DEHP-Free and Non-PVC Formats
Over the next three to five years, DEHP-free and non-PVC container formats are likely to become default expectations in an increasing number of procurement guidelines, especially where regulations and institutional policies are converging. This standardization will reduce the need for parallel inventories, simplify training, and strengthen the bargaining position of suppliers that can provide consistently qualified formats across large-volume and specialized applications. The commercial opportunity lies in offering harmonized portfolios that span blood and blood product transfusion, nutritional support, medication delivery, and other clinical uses, while maintaining documented compatibility and regional compliance. Suppliers that can demonstrate repeatable quality across these applications will be able to capture volume as health systems consolidate container specifications.
Integration of Container, Solution, and Fill-Finish Capabilities
A second trend is the deepening integration of container supply with solution manufacturing and fill-finish operations. Recent partnerships and Joint Ventures point toward closer alignment between bag formats and therapeutic availability, aiming to reduce coordination risk, improve lead times, and support continuity during shortage episodes. For market participants, this suggests value in building or partnering for end-to-end readiness, including sterilization pathways, multi-chamber capability, and validated compatibility with specific drug classes. The opportunity is not only in selling bags, but in enabling reliable, compliant delivery systems that meet hospital and pharmacy requirements for premixed and ready-to-use products. Companies that can connect material selection, format design, and fill-finish compatibility will be better positioned to compete for long-term supply agreements.
Regional Capacity Expansion and Supply Resilience as a Competitive Edge
A third trend is the expansion of regional capacity and localized supply, motivated by regulatory alignment, logistics resilience, and public procurement expectations. The emergence of large-scale eco-friendly non-PVC facilities and regional sterile manufacturing sites indicates that geography is becoming a strategic variable rather than a logistical afterthought. This creates opportunities for suppliers that can offer local content, shorter lead times, and regulatory familiarity, especially in markets where policies are accelerating the shift away from DEHP and PVC. The risk, however, is that capacity additions may outpace qualified demand in some regions or that differing pharmacopoeial standards will require duplicated validation efforts. Participants should plan for flexible capacity models and invest early in the documentation and testing needed to secure multi-market qualification.
Actionable Recommendations for Decision-Makers
For Manufacturers and Suppliers
- Prioritize standardized DEHP-free and non-PVC portfolios with documented compatibility across high-volume applications, especially where procurement mandates and tender language are tightening.
- Invest in multi-chamber and large-volume format capability, as these configurations are increasingly central to premixed and ready-to-use offerings and to shortage mitigation programs.
- Develop regional supply options and partnerships that reduce lead-time risk and align with local regulatory expectations, while maintaining the validation rigor required for multi-market access.
For Investors
- Evaluate exposure to companies with clear non-PVC material platforms, scaled eco-friendly capacity, and regulatory-ready portfolios, as these capabilities are likely to capture disproportionate share in a market that is moving from optional to standard.
- Look for value creation through partnerships that link container formats with solution production and fill-finish readiness, since integration can improve resilience and long-term contract eligibility.
- Consider the timing of regional capacity and policy catalysts, because local mandates and procurement shifts can create step-change demand that rewards companies with qualified supply already in place.
For Procurement and Clinical Operations Leaders
- Specify DEHP-free and non-PVC formats in contracts where possible, aligning container requirements with clinical safety goals and supply resilience planning, and request documented compatibility data to support adoption.
- Assess suppliers on format breadth, validation maturity, and regional availability, not just price, since container reliability and qualification status increasingly influence continuity of care.
- Coordinate across pharmacy, nursing, and supply chain functions to standardize container formats where clinically appropriate, reducing handling variability and strengthening the case for consistent non-PVC adoption.
For executives and investors seeking deeper segmentation, competitive benchmarks, and region-specific procurement dynamics, a detailed market study can translate these strategic signals into prioritization and timing decisions. A comprehensive report with granular segmentation and customized recommendations is available for teams that need to move from directional insight to execution planning.
IV Bags Market
For detailed analysis of this topic, please visit the official page: Non-PVC IV Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Tattoo Ink Market
Market Reality and Core Challenges
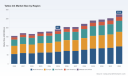
The global tattoo ink market has evolved significantly over the past five years, transitioning from a niche artistic sector into a more structured and regulated industry. Market valuation crossed the USD 190 million threshold in 2025 and is projected to reach approximately USD 275 million by 2032. This growth trajectory reflects a compound annual growth rate of 5.36 percent, indicating steady but measured expansion. The market has shown consistent upward movement since 2020, with temporary fluctuations in 2022 giving way to renewed momentum as consumer adoption broadens and manufacturing standards mature. Revenue generation continues to concentrate within a handful of established players, while the broader ecosystem accommodates a mix of regional producers, specialty formulators, and direct-to-consumer brands.
Despite this positive trajectory, the industry faces structural challenges that will shape competitive dynamics in the coming years. Safety and contamination risk remain the most pressing concerns. Historical incidents involving bacterial contamination and inconsistent sterilization practices have drawn regulatory scrutiny and heightened consumer awareness. Manufacturers must now balance artistic formulation with rigorous quality control, a shift that increases operational complexity and raises the barrier to entry for smaller producers. Supply chain volatility adds another layer of pressure. The availability of high-purity pigments, carrier solutions, and packaging materials fluctuates with broader chemical and logistics markets, affecting cost stability and product consistency. These dynamics force companies to decide between absorbing margin pressure or passing costs downstream, a decision that reverberates through pricing strategies and brand positioning.
A third challenge lies in the widening gap between artistic demand and technical standardization. Tattoo artists increasingly expect inks that deliver predictable healing, color retention, and application behavior across skin types and techniques. At the same time, end consumers are more informed, often prioritizing ingredient transparency, vegan formulations, and sterilization certifications. This dual expectation pushes manufacturers to invest in both formulation science and consumer-facing communication, a combination that not all firms can sustain. The market is therefore at a decision point: companies that treat quality and transparency as core competencies will be better positioned to retain professional clients and expand into adjacent applications, while those relying on legacy formulations risk commoditization.
Key Drivers Shaping Market Evolution
Technological Innovation and Formulation Precision
Advancements in pigment dispersion, carrier chemistry, and sterilization technology are redefining what tattoo ink can deliver. Formulators are moving toward pre-dispersed pigments and controlled particle size distributions, which improve color clarity and reduce the risk of uneven application. Sterilization processes have also matured, with manufacturers adopting validated batch-processing methods that minimize contamination risk while preserving formulation stability. These technical improvements translate directly into better healed results, a critical factor for professional artists who prioritize repeatability and client satisfaction. Innovation in this space is not only about aesthetics; it is increasingly about predictability and safety. Brands that can demonstrate consistent batch-to-batch performance and transparent ingredient profiles are gaining traction among studios that treat ink selection as a clinical and artistic decision rather than a commodity purchase.
Regulatory and Health-Safety Dynamics
Regulatory attention is intensifying, reshaping compliance expectations across the value chain. In late 2024, the U.S. Food and Drug Administration issued guidance to help manufacturers and distributors recognize and prevent contamination scenarios, signaling a shift toward proactive risk management rather than reactive recalls. Subsequent public health advisories have highlighted specific contamination concerns, including microbial risks associated with certain products, reinforcing the importance of sterile manufacturing and shelf-life control. On the research front, controlled clinical studies conducted at leading European institutions have provided new insights into how soluble ink ingredients behave in the body, generally indicating that residual levels may be lower than earlier assumptions suggested. These findings do not eliminate safety concerns, but they contribute to a more nuanced scientific dialogue that can inform labeling, formulation choices, and consumer education. For manufacturers, the practical implication is clear: compliance is no longer a checkbox exercise. It requires documented sterilization protocols, traceable ingredient sourcing, and clear communication about product handling and expiration.
Demand-Side Shifts and Application Diversification
Consumer behavior is expanding the use cases for tattoo ink beyond traditional body art. Cosmetic and medical applications continue to grow, driven by demand for semi-permanent aesthetic solutions and specialized clinical procedures. This diversification creates new revenue streams for manufacturers that can adapt formulations to different performance requirements, such as finer pigment grading for cosmetic work or specific handling characteristics for medical contexts. At the same time, mainstream tattooing is increasingly influenced by lifestyle and self-expression trends, with younger demographics and professional artists seeking inks that support complex color work, longevity, and skin-friendly profiles. The demand side is therefore not monolithic; it is splitting into segments with distinct expectations. Companies that understand these nuances can tailor product lines, branding, and education programs to match the priorities of each audience, rather than offering a single formulation strategy across all channels.
Supply Chain and Cost Structure Considerations
Cost structures in the tattoo ink market are influenced by pigment sourcing, carrier formulation, sterilization, packaging, and distribution. High-quality organic and vegan pigments often command premium pricing, while broader chemical market fluctuations can affect raw material costs and lead times. Manufacturers that maintain direct-from-manufacturer models or tightly controlled production environments can sometimes reduce intermediary costs and improve margin resilience. However, scaling these models requires investment in quality assurance, logistics, and batch documentation. The supply chain challenge is not simply about cost reduction; it is about preserving formulation integrity while managing volatility. Brands that build redundancy into sourcing, maintain rigorous in-house testing, and communicate transparently about lead times and batch availability are better equipped to sustain trust with professional buyers who depend on consistent product performance.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a concentration of revenue among a relatively small group of established manufacturers, alongside a broader field of regional and specialty brands. The market structure favors companies that combine formulation expertise, sterilization capability, and strong distribution relationships with professional studios. Several U.S.-based manufacturers illustrate different strategic approaches within this landscape. Intenze has built its positioning around professional tattoo and permanent makeup pigments manufactured domestically, emphasizing vegan and sterile formulations engineered for predictable handling, color clarity, and consistent healed results. Its direct-from-manufacturer model supports tighter control over quality and responsiveness to professional clients. Eternal Tattoo Ink and Eternal Tattoo Supply similarly emphasize certified sterilized, vegan, and cruelty-free inks produced in the United States, with a focus on advanced sterilization processes that appeal to safety-conscious buyers.
Other established players pursue differentiated value propositions that hinge on longevity, quality control, and brand trust. Dynamic Color Co. has emphasized premium manufacturing since the early 1990s, relying on pre-dispersed pigments and batch-level quality checks to maintain consistency. World Famous Tattoo Ink leverages decades of experience and a premium vegan formulation narrative to reinforce reliability in a market where artist loyalty is closely tied to performance reputation. Solid Ink focuses on high-quality organic vegan pigments, aligning with the growing demand for cleaner ingredient profiles and ethical sourcing. These strategies reveal a common theme: differentiation is increasingly tied to formulation integrity, sterilization assurance, and the ability to communicate those attributes credibly to professional buyers.
The market structure is evolving along two parallel tracks. On one hand, consolidation pressure is likely to increase as larger manufacturers seek to capture more shelf space, expand into adjacent applications, and leverage scale in quality systems and distribution. On the other hand, niche segmentation is also strengthening, with specialty brands carving out positions around vegan formulations, UV and specialty colors, cosmetic suitability, and region-specific supply relationships. New entrants face a challenging environment because trust and consistency are hard-earned in professional tattoo communities. Success typically requires more than a competitive price; it depends on documented sterilization, reliable batch performance, and strong relationships with artists and distributors who can validate product quality through repeated use. The most resilient brands are those that treat compliance, transparency, and formulation science as strategic assets rather than operational overhead.
Forward-Looking Trends and Commercial Implications
Quality Assurance as a Market Currency
Over the next three to five years, quality assurance is likely to become an even stronger differentiator. As regulatory expectations stabilize and professional buyers become more accustomed to validation practices, brands that can provide clear documentation of sterilization, batch testing, and ingredient transparency will gain an advantage in procurement decisions. This trend creates commercial opportunity for manufacturers that invest in verifiable quality systems and for distributors that prioritize compliant, well-documented products in their portfolios. It also raises the stakes for companies that rely on informal production practices, since procurement teams and studio owners increasingly weigh contamination risk and consistency alongside price and color range. The commercial implication is that reputation in this market will be increasingly tied to demonstrable process control.
Application Expansion and Cross-Use Formulation Strategy
The growth of cosmetic and medical applications suggests that formulation flexibility will be a valuable strategic capability. Inks designed for traditional body art do not always map seamlessly onto semi-permanent cosmetic procedures or clinical use cases, which may require different particle characteristics, viscosity profiles, or handling behavior. Manufacturers that develop modular formulation platforms can serve multiple segments without diluting brand focus, while also capturing higher-margin opportunities in specialized applications. This trend favors companies that can align R&D with end-use requirements and communicate those distinctions clearly to buyers. The opportunity lies in building product families that share core quality standards while meeting segment-specific performance expectations, enabling expansion without sacrificing trust in any one category.
Transparency, Ethics, and Consumer Education
Consumer-facing expectations around vegan formulations, cruelty-free production, and ingredient clarity are likely to keep rising. This is not merely a marketing preference; it influences procurement decisions among artists who want to align their studio practices with client values. Brands that integrate ethical sourcing and clear labeling into their core identity can strengthen loyalty and justify premium positioning. At the same time, consumer education becomes a competitive lever. Studios and distributors that provide accurate information about handling, aftercare, sterilization, and expiration help reduce misuse-related risks and improve outcomes, which in turn reinforces confidence in the products they stock. The broader commercial opportunity is to treat education and transparency as part of the product experience, not as an add-on. A potential risk in this area is overstatement; claims must be supported by verifiable practices, because professional buyers and informed consumers are increasingly able to distinguish between genuine compliance and surface-level branding.
Potential Risks and Uncertainties
Despite the positive outlook, several uncertainties warrant attention. Regulatory trajectories can shift as health authorities refine guidance and respond to new contamination events, which may impose additional documentation or labeling requirements. Supply chain disruptions in pigments or packaging could affect cost stability and availability, particularly for brands with limited sourcing redundancy. Scientific understanding of ink behavior in the body continues to evolve, and while recent controlled studies have provided reassuring data in certain respects, public perception and regulatory focus may still tighten around safety narratives. Finally, competitive intensification could compress margins for brands that cannot differentiate on quality, consistency, or application-specific performance. Companies that monitor these signals and maintain flexibility in formulation, compliance, and sourcing will be better prepared to navigate volatility.
Strategic Actions for Decision Makers
For manufacturers, the priority is to reinforce formulation integrity and verifiable quality as core competitive advantages. Investing in sterilization validation, batch documentation, and ingredient traceability strengthens positioning with professional buyers and prepares the organization for evolving regulatory expectations. It is equally important to develop formulation flexibility that supports adjacent applications without compromising the brand's core reputation. Companies that can align R&D, quality systems, and clear consumer-facing communication will be better equipped to retain artist loyalty and expand into higher-value segments. Pricing and distribution strategies should reflect this emphasis on reliability, since professional clients often prioritize consistent healed results and safety assurance over marginal cost differences.
PW Consulting
For investors, the market offers opportunities in brands that demonstrate defensible quality practices, transparent sourcing, and the ability to serve multiple application segments. Due diligence should focus on manufacturing controls, sterilization capability, regulatory readiness, and the credibility of product claims. Portfolio exposure to companies with direct distribution relationships and strong professional-channel reputations may offer more durable growth than exposure to undifferentiated commodity positioning. Investors should also watch for consolidation dynamics, as established players may seek to acquire specialty brands with strong ethical or technical positioning to broaden their portfolio and strengthen market access.
Ceramic Ink Market
For procurement teams and studio owners, product selection should increasingly weigh documented sterilization, batch consistency, and ingredient transparency alongside color range and price. Building supplier relationships with manufacturers that provide clear quality documentation and reliable lead times can reduce operational risk and improve client outcomes. Procurement decisions should also account for application fit, since inks intended for traditional body art may not be optimal for cosmetic or medical use. Educating staff and clients about proper handling, shelf life, and aftercare reinforces product performance and supports trust in the brand ecosystem. Building a small number of reliable, well-documented supplier relationships often proves more effective than chasing marginal price advantages across a fragmented supplier base.
Detailed segment-level data, regional breakdowns, and customized strategic scenarios can further sharpen these decisions. Readers seeking a deeper look at market sizing, competitive positioning, and application-specific opportunities can access the full research report for more granular analysis and tailored recommendations.
Tattoo Needles Market
For detailed analysis of this topic, please visit the official page: Tattoo Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pharmaceutical Grade Sodium Chloride: Asia Pacific’s 67% Share and 5.6% CAGR Reshape Growth
By PW Consulting, 2026-09-21
Pharmaceutical Grade Sodium Chloride Market: Strategic Trends and Commercial Opportunities in a Shift-Driven Landscape
Market Snapshot: Growth Trajectory and Structural Realities
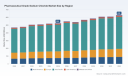
The pharmaceutical grade sodium chloride market has settled into a steady expansion phase, with revenue reaching approximately $525 million in 2025 and projected to approach $630 million by 2032. The implied compound annual growth rate of 5.6 percent reflects a market that is growing not through explosive demand surges, but through gradual capacity additions, formulation complexity, and sustained healthcare consumption across mature and emerging regions alike. Historical data from 2020 through 2025 shows a relatively smooth upward trajectory, punctuated by modest step changes rather than sharp inflection points, suggesting that core demand drivers have remained resilient even as feedstock costs, logistics, and regulatory expectations have shifted.
What makes this market structurally interesting is its concentration profile. The top three players account for roughly 28.5 percent of revenue, while the top five capture about 35.2 percent. That level of fragmentation, combined with steady growth, signals a landscape where scale advantages exist but are not insurmountable. Regional and application splits reveal clear concentration patterns: the Asia Pacific region represents the largest revenue pool, while the market is bifurcated by type between active pharmaceutical ingredient grade sodium chloride and hemodialysis grade material. On the application side, injections and hemodialysis dominate the demand base, with oral rehydration salts, osmotic agents, and other uses contributing meaningful but smaller shares. Rather than focusing on individual share percentages, the strategic takeaway is that high-value clinical applications and large-volume therapeutic uses are pulling the market in different directions, each with distinct quality, logistics, and margin expectations.
Several structural challenges and transition points are shaping how participants navigate this growth. First, regulatory scrutiny around impurity profiles, traceability, and batch documentation continues to intensify, especially for materials used in parenteral and dialysis applications where patient safety margins are narrow. Second, cost volatility in energy, purification inputs, and distribution has compressed margins for suppliers that lack integrated quality systems or flexible sourcing models. Third, regional demand growth is uneven, with mature markets facing price discipline and capacity rationalization, while high-growth regions require localized compliance readiness, consistent specification management, and stronger technical support. These dynamics mean that growth alone is not enough; suppliers must convert volume into dependable, specification-grade supply with clear quality differentiation.
Key Drivers Reshaping Demand and Competitive Positioning
Technical Innovation in Purification and Controlled Manufacturing
Advances in purification technology, crystallization control, and analytical verification are redefining what suppliers can reliably deliver at pharmaceutical grade. Improvements in trace metal control, endotoxin management, and particle size consistency have become increasingly important for injection-grade and dialysis-grade applications, where even minor deviations can affect downstream processing or clinical performance. Manufacturers that have invested in closed-loop handling, validated cleaning protocols, and robust quality documentation are better positioned to serve customers who require tight specification adherence across multiple batches. For buyers, this shift means that technical capability is increasingly evaluated not just by certificate compliance, but by the consistency of lot-to-lot performance, the transparency of testing, and the supplier’s ability to support troubleshooting when formulations are adjusted.
Worldwide Pharmaceutical Grade Calcium Hydroxide Market
The innovation curve also extends to packaging, storage, and transport conditions that preserve material integrity. Moisture control, contamination prevention, and shelf-life stability are gaining attention as supply chains become more distributed and inventory strategies more cautious. This matters because pharmaceutical grade sodium chloride is often treated as a commodity input, yet its downstream use can be highly sensitive. Suppliers that align processing improvements with practical logistics and documentation benefits are creating a more defensible value proposition than those competing purely on price.
Regulatory and Policy Environment: Stricter Expectations, Higher Barriers
Policy and regulatory expectations continue to evolve in ways that raise the quality bar and increase the cost of market entry for lower-capability players. Pharmaceutical grade materials sit at the intersection of industrial chemical production and healthcare compliance, which means they are subject to rigorous documentation, quality system expectations, and increasingly detailed impurity surveillance. In practical terms, this environment favors suppliers that can demonstrate controlled manufacturing, reliable audit readiness, and clear traceability from raw source to finished batch. It also reinforces the importance of harmonization across regions, since multinational buyers increasingly seek consistent specifications regardless of sourcing location.
The regulatory backdrop is not solely a constraint; it is also a competitive filter. As compliance expectations rise, suppliers with mature quality infrastructure and experienced regulatory support gain an advantage in securing long-term supply agreements, especially with larger pharmaceutical and dialysis operators that prioritize supply reliability over spot pricing. At the same time, buyers are becoming more discerning about vendor qualification, testing protocols, and change-control management, which raises the stakes for suppliers that treat quality systems as administrative rather than operational capabilities.
Demand-Side Evolution: Clinical Complexity, Volume Growth, and Formulation Strategy
On the demand side, the market is being shaped by a combination of steady clinical consumption and evolving formulation needs. Injections and hemodialysis applications remain central demand pillars because sodium chloride is integral to solution preparation, dilution, and dialysis fluid composition. As healthcare delivery expands and treatment volumes increase, especially in regions scaling hospital infrastructure and outpatient services, demand for dependable pharmaceutical grade material continues to grow. At the same time, formulation strategies are becoming more nuanced, with manufacturers seeking materials that integrate smoothly into multi-component preparations and meet tighter internal quality standards.
Another demand-side development is the growing emphasis on supply assurance. Buyers are less willing to accept variability in lead times, specification consistency, or documentation completeness, particularly when production downtime or batch deviation carries high cost or clinical risk. This is changing purchasing behavior: procurement teams are placing more weight on supplier reliability, technical responsiveness, and continuity planning than on headline price alone. The result is a market where differentiated service and quality assurance can support stronger commercial positioning, especially when tied to long-term supply arrangements.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure: Energy, Sourcing, and Logistics Pressure
Cost structures in this market are influenced by energy usage, purification requirements, source material variability, and distribution complexity. Because pharmaceutical grade sodium chloride requires controlled processing and verification, it is more sensitive than industrial-grade equivalents to fluctuations in operating costs and transport conditions. Suppliers that can manage energy intensity, source consistent inputs, and minimize handling risk gain a margin advantage, while those exposed to fragmented sourcing or less controlled processing face greater volatility.
Logistics further complicates the cost picture. Pharmaceutical-grade materials often require careful storage, contamination control, and documentation handoffs across borders or regions. In markets where import dependence is high or where regulatory clearance adds time and cost, lead-time reliability becomes a commercial differentiator. This environment pushes companies toward either regional sourcing strategies, integrated production and supply models, or stronger partnerships with distributors that can support compliance and traceability requirements. The broader implication is that cost competitiveness in this market is increasingly about operational discipline and supply continuity, not simply unit pricing.
Competitive Landscape: Positioning, Differentiation, and the Shape of Consolidation
Established Players and Differentiated Strategies
The competitive field includes a broad set of global and regional players with distinct strategic orientations. Large diversified chemical and salt producers bring advantages in scale, sourcing breadth, and distribution reach. Their positioning often emphasizes dependable volume supply, multi-region availability, and established quality systems that support pharmaceutical customer qualification. For these companies, the opportunity lies in converting broad salt-production expertise into a controlled pharmaceutical-grade offering that can compete on reliability as well as cost.
Alongside these broader players, specialized producers and regional manufacturers focus on tighter specification control, local compliance readiness, and closer technical engagement with buyers. Their differentiation typically comes from product consistency, responsive documentation, and the ability to serve specific customer segments such as injection preparation, hemodialysis fluids, or regional formulation needs. These companies often compete by demonstrating that they can reduce variability and support tighter integration into customer processes, which is valuable when procurement teams prioritize risk reduction over purely transactional pricing.
A third group of participants operates with a niche or application-specific orientation, serving laboratory, specialty formulation, or highly regulated use cases where documentation, purity thresholds, and batch control are paramount. Their commercial leverage often depends on technical trust, reproducibility, and the ability to maintain stringent handling standards. In a market where the top three and top five players hold only modest combined shares, these specialized positions can remain viable if they deliver clearly differentiated quality and service.
How Leading Companies Are Structuring Advantage
Across the competitive set, several strategic themes recur. One is the focus on controlled processing and quality documentation as a commercial asset. Suppliers that can show consistent impurity control, validated manufacturing practices, and complete traceability are better positioned to win and retain pharmaceutical customers who treat material qualification as a multi-year decision rather than a periodic purchase. Another theme is the alignment of product grades with end-use requirements. Because API-grade and hemodialysis-grade sodium chloride serve different functional and regulatory contexts, companies that clearly articulate grade-specific capabilities and test data can reduce friction in buyer evaluation and strengthen their positioning in targeted segments.
A third recurring strategy is the use of technical service as a differentiator. Suppliers that provide formulation support, specification clarity, troubleshooting assistance, and reliable change-control communication can create stickier customer relationships. This is especially relevant in applications where sodium chloride must integrate with other ingredients or where patient-facing formulations demand high consistency. In practice, competitive advantage is increasingly built on the combination of material quality, documentation reliability, and the supplier’s ability to reduce operational risk for the buyer.
Market Evolution: Fragmentation, Selective Consolidation, and New Entrants
The market’s concentration profile suggests ongoing fragmentation rather than dominance by a small number of incumbents. That structure creates space for both consolidation and new entry, depending on capabilities and regional positioning. Consolidation is likely to occur where scale, quality infrastructure, and regional coverage can be combined to serve multinational buyers more efficiently. In contrast, new entrants may find footholds by addressing specific quality, specification, or service gaps that larger suppliers do not fully cover, particularly in regions where localized compliance and technical support are valued.
A practical evolution to watch is the growing importance of regional supply resilience. Buyers in multiple markets are increasingly attentive to sourcing diversification and continuity risk, which can benefit suppliers that offer dependable local or near-local supply with appropriate quality credentials. At the same time, multinational procurement standards are pushing the market toward greater consistency in documentation and testing expectations, which may pressure smaller players without strong quality systems. The net effect is a landscape where competitive success depends less on claiming general market presence and more on demonstrating reliable performance in the specific grade, application, and region that matters to the customer.
Looking Ahead: Three Trends That Will Shape the Next Three to Five Years
Trend One: Quality and Traceability Become Commercial Differentiators
Over the next several years, pharmaceutical grade sodium chloride is likely to be evaluated less as a routine chemical input and more as a quality-sensitive component whose consistency, documentation, and traceability directly affect buyer risk. As regulatory and internal quality expectations rise, suppliers with stronger analytical verification, controlled handling, and transparent batch records will be better positioned to secure long-term agreements and command more stable pricing. For manufacturers and procurement teams, this trend means that supplier selection should increasingly weigh quality reliability and documentation completeness alongside cost and lead time.
Trend Two: Regional Demand Growth Will Redefine Sourcing Strategies
Demand growth will remain uneven across regions, with larger revenue pools continuing to attract attention while high-growth areas require more localized readiness. This will encourage suppliers to develop region-specific quality alignment, distribution responsiveness, and technical support capacity. For buyers, the strategic implication is that sourcing decisions may increasingly balance global consistency with regional resilience, especially where supply interruptions or specification mismatches carry high operational risk. Companies that can provide predictable supply in the right region, with appropriate pharmaceutical-grade credentials, will have an advantage in winning disciplined, long-cycle procurement relationships.
Trend Three: Capacity, Cost Discipline, and Margin Pressure Will Separate Operators
As the market grows at a moderate pace, the competitive battleground will shift toward operating efficiency and cost discipline. Energy usage, purification intensity, logistics overhead, and waste control will matter more as buyers become more price-aware and suppliers compete for share in a fragmented market. Operators that can manage cost structures without compromising pharmaceutical-grade consistency will be better positioned to protect margins, while those with weaker process control may face pressure to lower prices or lose qualification status. The risk is that cost-cutting efforts erode the very quality attributes that justify pharmaceutical-grade positioning in the first place, so the winning approach will likely combine efficiency with rigorous quality assurance rather than sacrificing one for the other.
Sodium Chloride Injection Market
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of growth. Regulatory expectations may tighten further in ways that raise compliance costs or change documentation requirements, especially for materials used in sensitive clinical applications. Cost volatility in energy and logistics could compress margins and shift sourcing preferences faster than suppliers can adapt. Demand patterns may also evolve if healthcare delivery models change, if formulation strategies shift away from certain uses, or if alternative sourcing models alter how buyers qualify and manage suppliers. Finally, regional supply disruptions or trade friction could expose vulnerabilities in concentrated sourcing strategies, making diversification and continuity planning more important than ever.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to treat pharmaceutical-grade consistency as a growth lever rather than a compliance checkbox. Investing in purification control, analytical verification, and documentation reliability can improve qualification success and support longer contract cycles. Equally important is clarifying grade-specific capabilities so that customers can quickly see which applications a supplier is best equipped to serve. Companies that align product quality, technical support, and regional availability will be better positioned to convert steady market growth into durable share gains.
For investors, the key is to distinguish between suppliers that are scaling volume and those that are building defensible pharmaceutical-grade capability. Growth in this market is real, but value creation will favor operators with strong quality systems, controlled cost structures, and the ability to retain customers through reliability rather than price alone. Investment diligence should therefore focus on manufacturing discipline, regulatory readiness, traceability, and the company’s capacity to serve high-value applications without compromising specification integrity.
For procurement and supply chain leaders, the strategic imperative is to evaluate suppliers on a broader set of criteria than unit price alone. Lead-time reliability, lot-to-lot consistency, documentation completeness, change-control responsiveness, and continuity planning all matter when sodium chloride feeds into injections, dialysis fluids, or other sensitive applications. Diversifying supply where appropriate, qualifying suppliers with strong quality systems, and maintaining clear specification expectations can reduce operational risk while preserving cost discipline.
Given the range of regional, technical, and regulatory variables shaping this market, detailed segment-level data and tailored supply-chain assessment can make a meaningful difference in planning. For decision-makers seeking deeper visibility into volume patterns, application-specific demand, grade-level positioning, and supplier qualification dynamics, a more comprehensive market review can help translate these trends into concrete sourcing, investment, and production decisions.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oligonucleotide Pool Library Market: How 12.35% CAGR & CRISPR Demand Reshape Strategy
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Oligonucleotide Pool Library Market
Market State and Core Challenges
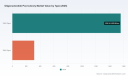
The oligonucleotide pool library market has evolved from a specialized research enabler into a strategic infrastructure layer for synthetic biology, functional genomics, and precision therapeutics. Over the past five years, the sector has demonstrated sustained momentum, with market valuation climbing from approximately $880 million in 2020 to $1.875 billion in 2025. Forward projections indicate continued expansion, reaching an estimated $4.2 billion by 2032 and reflecting a compound annual growth rate of 12.35 percent across the 2026–2032 forecast horizon. This trajectory signals a market transitioning from early adoption curves into mainstream scientific and commercial workflows, where oligonucleotide pools are no longer optional research tools but foundational inputs for discovery pipelines and manufacturing processes.
The pace of growth, however, is not uniform across the value chain. Demand is increasingly concentrated around applications that require high complexity, low error rates, and scalable production formats. Target capture workflows, CRISPR/Cas9 design libraries, and gene synthesis programs continue to absorb the largest shares of commercial activity, while library preparation and adjacent use cases are gaining relevance as sequencing and diagnostic platforms become more decentralized. The geographic distribution of activity reflects mature demand centers alongside rapidly expanding research ecosystems, creating a multi-speed environment where supply readiness, regulatory familiarity, and scientific capability vary significantly by region.
At the same time, the industry is navigating several structural challenges that will shape competitive outcomes over the next decade. First, cost volatility in core synthesis inputs remains a persistent pressure point. Phosphoramidite building blocks and related reagents have experienced recurring price fluctuations, introducing uncertainty into unit economics and forcing suppliers to balance margin protection with customer retention. Second, the market is not yet fully consolidated, with competitive intensity spread across established manufacturers and specialized entrants. A moderately fragmented landscape can drive innovation and customization, but it also creates pricing ambiguity and service inconsistency that buyers must navigate carefully. Third, the regulatory trajectory for oligonucleotides is becoming more defined, particularly as synthetic libraries move closer to diagnostic, therapeutic, and commercial applications. Evolving guidance on manufacturing practices, characterization, and quality control is raising the bar for documentation, reproducibility, and compliance, especially for organizations scaling production beyond research-grade environments.
Oligonucleotide Purification Market
These dynamics create a market that is expanding rapidly, but not without friction. The central question for industry participants is no longer whether demand will continue to grow, but how effectively they can manage input risk, align service models with emerging application requirements, and position themselves within a competitive field that is likely to become more structured over time.
Key Drivers of Market Change
Technological Innovation and Synthesis Scaling
The most direct driver of market growth is the continued refinement of oligonucleotide synthesis and library construction technologies. Chip-based and array-based synthesis approaches have expanded the practical limits of pool size, complexity, and turnaround time, enabling researchers and developers to move from small custom batches to large-scale library formats without proportionally increasing cost or lead time. At the same time, improvements in sequence design, error correction, and pool QC workflows have reduced the operational overhead associated with library deployment. This matters because the commercial value of oligonucleotide pools is increasingly tied not just to raw production capacity, but to the reliability and usability of the final product in downstream applications.
Recent industry activity reflects this technological emphasis. Twist Bioscience, for example, has built its market positioning around array-based oligonucleotide pool libraries for gene synthesis, gene editing, and synthetic biology applications, illustrating how synthesis platform differentiation can become a commercial identity. IDT has similarly expanded its relevance by offering custom DNA and RNA oligonucleotide pools tailored to library preparation, CRISPR, and multiplex sequencing workflows. These profiles are not merely product descriptions; they signal a broader shift in which suppliers are competing on application fit, throughput, and integration with customers’ experimental pipelines rather than on price alone.
PW Consulting Health Care Research Center
Regulatory Maturation and Quality Expectations
Regulatory and quality infrastructure is becoming an increasingly important market driver, particularly as oligonucleotide pools move from purely academic contexts into environments where reproducibility, traceability, and consistency carry higher stakes. The EMA’s draft guideline on the development and manufacture of oligonucleotides addressed manufacturing processes, characterization, specifications, and analytical control, signaling a more formal expectation around how oligonucleotides should be produced and documented. Although initially framed around broader development pathways, such guidance has practical implications for pool manufacturers because it raises the baseline for process discipline and quality assurance.
In parallel, regulatory attention in the United States has included focus on generic oligonucleotide challenges, such as quality assessment and immunogenicity considerations for synthetic oligos. These developments do not necessarily slow demand, but they do change the cost of entry and the value of established manufacturing practices. Organizations that can demonstrate robust QC, clear specifications, and dependable documentation are better positioned to serve customers who face increasing internal or external scrutiny. In that sense, regulatory maturation is acting as both a compliance requirement and a competitive filter.
Demand-Side Shifts in Research and Commercial Pipelines
Demand for oligonucleotide pool libraries is increasingly shaped by how scientific and commercial organizations structure their discovery and validation workflows. CRISPR/Cas9 design libraries remain a major demand anchor, reflecting continued investment in gene editing and functional genomics. At the same time, target capture and gene synthesis applications are expanding as researchers and developers seek more efficient routes to screening, validation, and construct generation. The broader trend is toward libraries that can support multiplexed, high-throughput experiments without sacrificing specificity or interpretability.
This demand evolution is also visible in pricing and product structuring. Commercial offerings increasingly reflect tiered or scale-sensitive pricing models, with costs varying substantially depending on pool size and specification. That pattern indicates a market in which buyers are not simply purchasing synthetic material; they are negotiating access to capacity, complexity, and service levels. As a result, demand-side behavior is pushing suppliers to think more carefully about portfolio design, minimum order structures, and the trade-off between flexibility and scale.
Supply Chain and Cost Structure Pressures
No discussion of market drivers is complete without acknowledging the fragile cost structure underlying oligonucleotide production. Phosphoramidite chemistry remains central to synthesis, and ongoing increases in raw material costs have introduced volatility that affects pricing, lead times, and planning assumptions. This is not a transient issue. Raw material dependencies can create exposure to broader supply chain disruptions, which in turn influence how suppliers price risk, manage inventory, and negotiate long-term agreements.
Recent pricing adjustments by service providers illustrate how these pressures translate into commercial decisions. Updates to oligonucleotide synthesis service pricing have been attributed to rising raw material costs and external factors, reinforcing the idea that input economics are actively reshaping market pricing behavior. For buyers, this means procurement strategies need to account for more than unit price; they must consider stability, forecasting alignment, and the durability of supplier relationships under cost pressure. For manufacturers, the challenge lies in balancing pass-through costs with the need to remain competitive, especially when multiple vendors are vying for the same application-driven demand.
Competitive Landscape and Leading Strategies
The competitive environment in this market is defined by a mix of established molecular biology suppliers, synthesis-focused manufacturers, and specialized library providers. Entities such as Twist Bioscience, IDT, Agilent Technologies, CustomArray, LC Sciences, Synbio Technologies, Daicel Arbor Biosciences, GenScript, Dynegene Technologies, General Biosystems, and Creative Biogene each bring distinct positioning to the market, often anchored in specific applications, formats, or workflow advantages.
A few patterns stand out. One is the emphasis on application-specific differentiation. Some suppliers position strongly around gene synthesis and synthetic biology workflows, while others focus on library preparation, CRISPR-related libraries, in-situ hybridization, or targeted sequencing support. This specialization matters because oligonucleotide pools are rarely interchangeable from the customer’s perspective; the value of a pool often depends on how well it fits the experimental design, screening format, or validation pathway.
Another pattern is the importance of scale and synthesis format. Companies leveraging chip-level or array-based synthesis often emphasize throughput and library size as core value propositions, which can be especially attractive for large-scale gene synthesis or functional genomics programs. Others compete by offering custom services, flexible ordering, or strong support for niche applications. In practice, this creates a landscape where some leaders compete on volume and process efficiency, while others compete on customization and service depth.
The market is also characterized by moderate concentration, with leadership shared across multiple firms rather than dominated by a single player. That structure has implications for strategy. For incumbents, the priority is often to deepen application relevance, improve process reliability, and protect margins in the face of input cost volatility. For newer or smaller entrants, the opportunity frequently lies in serving underserved workflows, regional demand, or specialized library formats that larger suppliers may not prioritize. For buyers, the practical takeaway is that supplier selection should be driven by workflow compatibility and service reliability as much as by headline pricing.
Market evolution is likely to proceed along two simultaneous paths: consolidation among players seeking scale, manufacturing efficiency, or broader workflow integration, and differentiation among those targeting specific application segments or technical niches. Recent licensing and technology-sharing activity, such as agreements involving exNA oligonucleotide technology and related reagents for research use, suggest that strategic partnerships and IP-enabled access are becoming more relevant alongside pure manufacturing competition. In a market where performance, quality, and cost are all contested, access to enabling technology can be as important as production capacity.
Future Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to shape the direction of the oligonucleotide pool library market and create distinct commercial opportunities.
One major trend is the continued alignment of library supply with high-value application clusters. Demand will likely remain strongest where oligonucleotide pools directly enable screening throughput, gene editing design, target validation, and construct generation at scale. Suppliers that can package synthesis capability with application-aware design support, QC consistency, and predictable turnaround will be better positioned to capture recurring demand from organizations that rely on libraries as part of standard workflows. The commercial opportunity here is not simply to sell more pools, but to become embedded in the operational rhythm of research and development teams.
A second trend is the growing importance of cost discipline and supply resilience. As raw material volatility persists and pricing becomes more sensitive to external cost pressures, both suppliers and buyers will need stronger planning frameworks. For suppliers, this may mean more structured pricing tiers, improved inventory and feedstock strategy, and clearer communication around cost drivers. For buyers, the opportunity lies in moving from transactional purchasing to more strategic sourcing, including multi-supplier planning, forecast sharing, and evaluation of total workflow cost rather than per-pool price alone. Organizations that handle this transition well can reduce exposure to price shocks while maintaining access to the library formats they need.
A third trend is the broadening of quality and regulatory readiness as commercial differentiators. As guidance continues to develop and applications become more consequential, documentation, reproducibility, and process control will carry increasing weight. Companies that invest early in quality systems, characterization rigor, and transparent specifications may gain access to more demanding customer segments and higher-value projects. Conversely, suppliers that treat quality as a secondary concern may find their addressable market narrowing as customer expectations rise.
These trends carry risk as well. Demand growth could be uneven if certain application areas mature faster than others, or if technology shifts alter the need for specific pool formats. Input cost volatility could compress margins or disrupt planning if supply chains remain vulnerable. Regulatory expectations could increase overhead for smaller operators, potentially accelerating consolidation or raising barriers for new entrants. The net effect is a market with strong upside, but one in which advantage will increasingly belong to players who can manage risk while delivering dependable, application-aligned products.
Oligosaccharide Market
Implications for Decision-Makers
Different stakeholders in this market face distinct strategic priorities, but all can benefit from a clearer view of where demand, cost, and competition are heading.
For manufacturers and service providers, the priority should be to sharpen application alignment and strengthen operational resilience. This includes evaluating which library formats and workflows offer the best combination of demand durability and margin potential, while also reassessing exposure to raw material volatility and lead-time variability. Suppliers that can offer predictable quality, transparent pricing logic, and reliable delivery will have an advantage as customers become more deliberate about vendor selection. It also means paying attention to technology access and partnerships, since differentiation may increasingly come from proprietary synthesis methods, QC capabilities, or specialized library designs rather than from scale alone.
For investors, the useful question is less about whether the market will grow than about where value will accrue within it. The strongest opportunities are likely to be found in companies that can demonstrate durable demand linkages, defensible synthesis or service advantages, and the ability to manage cost volatility without eroding competitiveness. At the same time, it is worth watching for consolidation signals, pricing behavior, and regulatory shifts that could change the relative position of incumbents and entrants. In a market with moderate concentration and strong application specialization, due diligence should focus on workflow relevance, quality infrastructure, and the sustainability of unit economics under cost pressure.
For procurement teams and research organizations, the strategic imperative is to treat oligonucleotide pool sourcing as a workflow decision rather than a commodity purchase. Evaluating suppliers should include attention to application fit, error profiles, turnaround reliability, documentation standards, and the credibility of pricing in the face of raw material volatility. Building a sourcing strategy that balances flexibility with stability can reduce the risk of disruption while improving the consistency of experimental outcomes. Where possible, organizations should also consider forecasting and planning collaboration with suppliers, since cost and capacity dynamics are increasingly intertwined with commercial pricing.
For readers seeking a more detailed view of segmentation dynamics, competitive positioning, pricing structures, and regional demand patterns, the full market research report provides a deeper evidence base and more granular scenario analysis. In a market moving this quickly, the value of detailed intelligence lies in its ability to turn broad trends into specific decisions about suppliers, investment exposure, procurement strategy, and product development priorities.
For detailed analysis of this topic, please visit the official page: Oligonucleotide Pool Library Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tonneau Covers Market: Why 5.8% CAGR and $314M Size Redefine Competition
By PW Consulting, 2026-09-21
Tonneau Covers Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The global tonneau covers market has entered a phase of steady, compounding growth, driven by durable demand for truck bed protection, utility optimization, and aesthetic customization. Measured in millions of USD, the market expanded from roughly $243.0 million in 2020 to approximately $314.99 million in 2025, reflecting a compound annual growth rate of 5.8 percent across the 2020–2025 period. The trajectory continues upward through the forecast horizon, with projected revenue reaching $460.85 million by 2032. This expansion signals more than cyclical fluctuations; it points to structural demand supported by pickup truck utilization patterns, aftermarket customization culture, and incremental upgrades in materials and locking mechanisms.
Despite the favorable growth path, the market faces a handful of inflection points that could reshape competitive dynamics and margin profiles over the next several years. These challenges are not isolated operational issues; they are systemic forces that require strategic repositioning rather than incremental adjustments.
Tariff and trade policy uncertainty represents the most immediate pressure point. A cluster of U.S.-based manufacturers filed antidumping and countervailing duty petitions against imports of truck bed covers from China, prompting federal trade investigations and raising the prospect of revised duty structures. For a market where import exposure varies across product categories and supply chains, this development introduces pricing volatility, sourcing reconfiguration costs, and potential short-term inventory tightness. Companies that rely on globally distributed components or finished-cover imports must evaluate exposure not only at the customs line but also across logistics, lead times, and customer price sensitivity.
Material cost and engineering trade-offs form a second structural challenge. Tonneau covers span a spectrum from soft roll-up designs to hard folding and retractable systems, each balancing weight, durability, ease of installation, bed accessibility, and aesthetics. Rising costs for polymers, aluminum, and specialized coatings can compress margins or force repositioning of price points. At the same time, performance expectations continue to rise: customers increasingly seek low-profile profiles, stronger locking architectures, weather sealing, and features that accommodate toolboxes or specialized bed configurations without sacrificing convenience.
Finally, channel and customer fragmentation adds complexity. Demand flows through both OEM integration and aftermarket channels, each with distinct procurement cycles, specification requirements, and margin structures. Aftermarket buyers often prioritize installation simplicity, resale value, and visible product differentiation, while OEM arrangements require reliability validation, integration timelines, and volume consistency. Managing brand positioning, inventory, and service support across these channels calls for disciplined segmentation and channel-specific value propositions.
Key Demand Drivers
Technological Innovation and Product Architecture
Product innovation continues to be a primary engine of market expansion. Advances in hard-folding mechanisms, retractable roll systems, and reinforced latch designs have broadened the functional appeal of tonneau covers beyond basic bed protection. Manufacturers are increasingly emphasizing full-bed access, low-profile contours, and heightened security features, reflecting a shift from commodity coverage to integrated utility solutions. The introduction of flip-up and trifold hard variants demonstrates how mechanical design can address contractor workflows, recreational towing setups, and daily driver convenience simultaneously. Pre-launch interest in newly presented premium models indicates that differentiated engineering can generate meaningful pull before broad retail availability, signaling that design-led innovation remains a viable path to share gains.
Policy and Regulatory Dynamics
Trade policy is emerging as a decisive factor in sourcing strategy and competitive positioning. The recent filing of antidumping and countervailing duty petitions by a coalition of domestic manufacturers has triggered federal investigations into truck bed cover imports from China. Beyond the immediate legal process, this signals a broader environment in which domestic producers are actively seeking to reshape the competitive baseline through trade remedies. For industry participants, the implications extend past headline tariff rates. Sourcing roadmaps, inventory buffers, pricing architectures, and even product mix decisions may need to adapt to a landscape where import costs, lead times, and supply continuity are less predictable. Companies with flexible manufacturing footprints and diversified supplier bases are better positioned to absorb policy shocks while preserving margin integrity.
Demand-Side Shifts in Consumer and Commercial Behavior
Demand patterns reflect evolving truck ownership use cases. For consumer buyers, tonneau covers increasingly serve as both functional equipment and visual customization elements, contributing to bed security, weather resistance, and vehicle appearance. For commercial operators and contractors, the value proposition tilts toward durability, fast access, load protection, and compatibility with work-related accessories. The durable appeal of truck platforms in North America underpins consistent aftermarket demand, while regional variations in vehicle mix and purchasing power influence product preferences. This dual demand structure supports a market where both lifestyle-oriented and work-oriented buyers contribute to growth, but it also requires clear messaging and product tiering to avoid diluting brand equity across segments.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by a combination of input price dynamics, logistics complexity, and the strategic response to trade actions. Manufacturers that can optimize material selection, streamline installation-friendly designs, and localize key production steps gain an advantage in managing volatility. At the same time, the aftermarket channel places a premium on packaging, instructions, and support assets that reduce installation friction and return rates. In this environment, operational efficiency is not only a margin safeguard but also a customer experience driver. Companies that invest in predictable fulfillment, clear compatibility information, and robust warranty support can differentiate even in a market where product forms are increasingly familiar.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established manufacturers with strong brand portfolios, multi-brand architectures, and deep aftermarket presence. Several of the leading names operate under shared corporate umbrellas, enabling portfolio breadth across folding, rolling, retractable, and hard-cover categories. This structure creates advantages in distribution reach, cross-brand merchandising, and the ability to address multiple price tiers and use cases within a single organizational framework. At the same time, other independent premium-focused manufacturers compete through design innovation, contractor-oriented feature sets, and pre-launch market engagement that builds anticipation ahead of full commercial release.
Leading players generally pursue differentiation along a few recognizable axes. One is mechanical performance and warranty assurance, where folding and retractable systems are positioned around strength, durability, and repeated-use reliability. Another is aesthetic and usability refinement, including low-profile profiles, clean bedlines, and accessories that complement toolbox installations or specialized bed layouts. A third is channel execution, where strong aftermarket distribution and installer relationships help convert product specifications into retail demand. Companies that combine product credibility with clear installation advantages and consistent availability tend to hold an edge in a market where purchase decisions are influenced by both function and convenience.
Truck Tonneau Covers Market
Market structure appears to be moving toward a blend of consolidation and specialized differentiation. Portfolio consolidation under multi-brand 소유 structures allows broader coverage of product types and customer segments, while independent premium entrants continue to pursue niche leadership through targeted launches and distinctive mechanical concepts. This duality suggests that scale and reach will remain important, but they will not automatically determine outcomes. Newer models that generate early buyer interest and articulate a clear use-case advantage can secure positioning even in a crowded category. The presence of multiple brands under common ownership also raises the importance of internal segmentation discipline, ensuring that each brand maintains a coherent identity rather than competing against itself across price points and features.
Worldwide LED Tube Covers Market
Recent developments illustrate how competitive momentum is being built. A coordinated trade case effort by a group of prominent domestic manufacturers highlights a strategic attempt to influence the import environment and protect domestic production economics. Simultaneously, premium manufacturers have used industry events and pre-order campaigns to validate demand for next-generation designs, with early interest signals suggesting that innovative trifold and flip-up concepts can attract committed buyer attention before full launch. These moves underscore two parallel strategies in the market: one focused on shaping the external competitive environment, and another focused on capturing demand through product novelty and launch execution.
Forward Outlook: Trends Shaping 2026–2032
Several trends are likely to define the market over the next three to five years. The first is continued product architectural diversification. Hard folding, retractable, and soft roll-up formats will coexist, but incremental improvements in sealing, locking, ease of operation, and bed access will matter increasingly for share shifts. Premium trifold and flip-up designs that combine strength with convenient access are poised to gain traction among buyers who need frequent bed usage without sacrificing coverage. As these designs mature, expectations for fit, finish, and compatibility across popular truck platforms will rise, rewarding manufacturers that invest in platform-specific engineering and clear fitment guidance.
The second trend is a more contested and policy-sensitive import environment. The outcome of ongoing trade investigations could alter relative cost structures and redirect sourcing strategies. Even without dramatic policy changes, the mere prospect of duties and investigations encourages buyers and sellers to reconsider exposure, buffer inventory, and evaluate domestic or near-domestic alternatives. This creates both risk and opportunity: companies with adaptable supply chains can use the transition period to strengthen carrier relationships, negotiate better terms, and reinforce brand trust through reliability, while those with concentrated import dependence may face margin and availability pressure.
The third trend is channel-specific value creation. As the market grows toward the upper range projected for the early 2030s, success will increasingly depend on how well manufacturers and distributors align product portfolios with channel realities. Aftermarket demand will reward installation-friendly designs, clear compatibility information, and strong retail visibility. OEM-adjacent opportunities will favor proven durability, integration timing, and specification consistency. In both paths, brands that articulate a crisp value proposition and support it with dependable fulfillment and service will be better positioned to convert market growth into sustained share gains.
Potential risks and uncertainties should be factored into planning. Policy outcomes remain uncertain, and the timing or scope of any duty measures could differ from current expectations. Input cost volatility may continue to pressure margins, particularly for products that rely heavily on specific metals or polymer grades. Consumer and commercial demand could also shift with broader truck sales patterns, economic conditions, and regional purchasing behavior. Finally, competitive intensity may increase as brands refine portfolios and new entrants test differentiated concepts, raising the bar for launch execution and ongoing product refresh cycles.
PW Consulting
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product architecture with clear use-case advantages while building operational flexibility. Engineering investments should target the features that most influence purchase decisions in each segment, such as full-bed access, weather sealing, locking confidence, and installation simplicity. At the same time, sourcing and inventory strategies should be reviewed for exposure to shifting trade conditions, with an emphasis on optionality, lead-time reliability, and margin resilience. Strong fitment data, installer support assets, and warranty clarity can convert product quality into channel confidence, which is especially valuable when buyers face installation or compatibility questions.
For investors, the market offers a constructive growth backdrop, but selectivity matters. Favorable expansion through the forecast period is supported by durable truck-culture demand and ongoing product innovation, yet the most attractive exposures will likely be those with defensible brand positioning, channel strength, and the ability to manage trade-related volatility. When assessing opportunities, it is useful to look beyond top-line growth potential and examine how well a company can sustain margins under changing cost structures, how diversified its product portfolio is across folding, retractable, and soft categories, and whether its launch cadence and pre-market engagement generate genuine demand pull. Early signals from new premium launches suggest that differentiated designs can create near-term momentum, but durability of that advantage will depend on execution quality and follow-through across the full product lifecycle.
For procurement teams and channel partners, the focus should be on predictability and compatibility. Evaluating suppliers on fitment reliability, installation support, and fulfillment consistency can reduce downstream friction and protect customer satisfaction. As trade dynamics evolve, maintaining visibility into sourcing origins and inventory buffers can help avoid disruption. Procurers should also consider how product choice aligns with end-customer expectations in their specific region and customer mix, since the balance between lifestyle-driven and work-driven demand can vary meaningfully across markets. Building a shortlist of suppliers that can support multiple cover types and provide clear warranty and compatibility information can improve both operational stability and sales confidence.
For organizations that need to move quickly with detailed, segment-level decision data, a comprehensive research report can provide the granularity required to translate market direction into concrete plans. Detailed breakdowns of product types, application channels, regional demand patterns, and competitive positioning enable more precise forecasting, sourcing choices, and launch prioritization. In a market where trade policy, product innovation, and channel execution are all shifting at once, timely access to structured intelligence can help teams calibrate investment, inventory, and messaging with greater confidence.
For detailed analysis of this topic, please visit the official page: Tonneau Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Glow Plugs Market: Why Diesel Demand and 4.17% CAGR Define Growth
By PW Consulting, 2026-09-21
Navigating the Automotive Glow Plugs Market: Strategic Trends and Commercial Opportunities Through 2032
1. Market Landscape and Core Challenges
The automotive glow plugs market has demonstrated steady expansion over the past half-decade, reaching an estimated 377.41 million USD in 2025. Historical trajectories from 2020 through 2025 reflect consistent volume growth, interrupted only by a brief contraction in 2022 that was quickly overcome by renewed demand recovery. Looking forward to the forecast period of 2026 through 2032, the market is projected to advance at a compound annual growth rate of 4.17 percent, culminating in a valuation of approximately 504.69 million USD by 2032. This trajectory underscores the enduring role of glow plug systems in compression-ignition engines, even as broader powertrain transformations reshape the automotive components ecosystem.
1.1 Competitive Concentration and Market Structure
The industry operates under a moderately concentrated structure, with the top three participants commanding roughly 55.4 percent of total revenue and the top five firms accounting for approximately 72.6 percent. This concentration indicates that established suppliers hold significant leverage in OEM negotiations and aftermarket channel partnerships, yet sufficient fragmentation remains to allow specialized entrants and regional players to capture meaningful niches. Market participants must therefore balance scale advantages with agility in meeting region-specific regulatory and performance requirements.
1.2 Key Challenges and Inflection Points
- Regulatory pressure on diesel combustion systems: Tightening emission frameworks, particularly the Euro 7 standard for light-duty vehicles taking effect in 2026, impose more stringent particle number limits down to 10 nm. These requirements force glow plug suppliers to support sustained low-emission combustion rather than merely enabling cold starts, elevating performance expectations and testing complexity.
- Powertrain transition uncertainty: While diesel passenger cars continue to decline in several mature markets, commercial vehicles and certain off-highway applications retain strong reliance on compression-ignition engines. This divergence creates uneven demand patterns that complicate capacity planning and inventory strategies for manufacturers operating across both segments.
- Component integration and validation costs: Advanced glow plug designs increasingly incorporate sensing and control functionalities. Transitioning from purely resistive heating elements to multi-functional modules raises development expenses and extends qualification cycles, challenging suppliers that lack robust engineering resources or dedicated validation infrastructure.
For decision-makers, these challenges translate into a need for precise demand forecasting by vehicle class and region, disciplined investment in high-value product architectures, and proactive engagement with regulatory timelines. The firms that thrive will be those treating glow plugs not as commodity components but as integrated enablers of emissions compliance and combustion optimization.
2. Key Drivers Shaping Market Dynamics
2.1 Technology Innovation and Performance Breakthroughs
Technological evolution remains the strongest catalyst for differentiation and margin preservation in the glow plugs market. Ceramic glow plug technology, pioneered and continuously refined by leading suppliers, delivers faster heat-up times while maintaining durability under high-temperature diesel combustion conditions. This performance profile is increasingly critical for modern engine management strategies that demand precise temperature control during warm-up and idle phases to minimize particulate formation. In parallel, pressure sensor glow plugs with integrated piezo-resistive sensors represent a significant step toward intelligent combustion management. By providing real-time feedback for optimized injection timing, these systems improve cold-start performance and contribute to NOx reduction, aligning component functionality with broader engine-out emissions goals.
The commercial implications are clear. Suppliers that develop and standardize advanced thermal and sensing architectures can command premium positioning in both original equipment and replacement channels. Meanwhile, conventional sheathed-element designs remain relevant for cost-sensitive applications, but their differentiation potential is narrowing as higher-performance alternatives become more accessible. Manufacturers must therefore decide where to invest in next-generation platforms and where to sustain efficient production of established designs for high-volume, price-driven segments.
2.2 Policy and Regulatory Environment
Regulatory frameworks are reshaping the functional requirements of glow plug systems. The Euro 7 emission standards for light-duty vehicles, scheduled to take effect in 2026, tighten particle number limits and require sustained low-emission combustion in compression-ignition engines. This shifts the value proposition of glow plugs from basic cold-start assistance toward active participation in emission control during the entire warm-up and operational window. Suppliers that can demonstrate measurable contributions to particle reduction and combustion stability will be better positioned to secure OEM approvals and aftermarket credentialing.
For commercial players, regulatory alignment is no longer optional. Validation programs must account for extended service life, thermal cycling under stricter operating profiles, and compatibility with after-treatment systems. Companies that anticipate these requirements and integrate them into product development cycles will reduce the risk of late-stage design changes and sourcing disruptions.
2.3 Demand-Side Shifts in Vehicle Segments and Replacement Cycles
Demand patterns are being reweighted by vehicle segment dynamics. Commercial vehicles continue to represent the larger revenue pool within the glow plugs market, reflecting the durability requirements of fleet operations and the persistent use of diesel engines in heavy-duty and medium-duty transport. Passenger cars, while smaller in aggregate, remain an important channel in regions where diesel passenger vehicles retain meaningful market share. In the aftermarket, replacement demand is driven by accumulated vehicle parc, usage intensity, and the extended service intervals that can sometimes mask component wear until performance degradation becomes noticeable.
These demand-side realities create opportunities for suppliers with strong coverage in commercial vehicle platforms and comprehensive aftermarket part number portfolios. Broad application coverage, reliable fitment data, and proactive catalog maintenance are becoming as valuable as the physical component itself. Operators that can connect product performance with accurate replacement forecasting will capture greater share of wallet in both fleet service channels and independent repair networks.
2.4 Supply Chain and Cost Structure Evolution
Cost structures in the glow plugs market are influenced by material inputs, manufacturing precision, and the growing expense of validation and certification. Ceramic formulations and sensor-integrated designs elevate raw material and processing requirements, while sheathed metal elements continue to benefit from mature production processes. Regional supply arrangements also matter: concentration of production capacity in a limited set of manufacturing hubs can create efficiency gains but also introduces exposure to logistics volatility and regional demand imbalances.
Strategic cost management therefore requires more than purchasing leverage. It depends on platform standardization, selective automation in high-volume lines, and disciplined portfolio rationalization to avoid diluting margins across excessively fragmented part numbers. Companies that achieve this balance can protect profitability even as they advance technical content and meet evolving compliance expectations.
3. Competitive Landscape and Leader Strategies
3.1 Strategic Positioning of Leading Companies
The market is anchored by a group of highly specialized suppliers that combine engineering heritage, broad application coverage, and targeted innovation. Robert Bosch GmbH maintains a central position as a leading OE and aftermarket provider, leveraging patented sheathed-element technology for faster heating and extended glow durations. Its factory-tested supply model and deep integration with European diesel platforms reinforce a reputation for reliability and compliance readiness.
PW Consulting
Denso Corporation has built a strong identity around ceramic glow plug technology, with an aftermarket portfolio that exceeds OE specifications. As one of Europe’s largest suppliers and a pioneer in ceramic formulations, Denso emphasizes thermal performance and durability as core differentiators. The recent expansion of its premium aftermarket part numbers, covering a substantial number of OE part numbers, applications, and vehicles, illustrates a deliberate push to strengthen replacement channel relevance while maintaining technical leadership.
Niterra Co., Ltd. has emerged as a significant player by combining its heritage as a global spark plug leader with an expanding glow plug footprint. Its extensive European part number coverage across vehicles in operation reflects a strategy built on broad fitment and thermal technology optimization. A recent business transfer agreement to acquire Denso’s spark plug and glow plug business operations signals a clear intent to consolidate scale, streamline production for diesel applications, and capture additional aftermarket demand.
BorgWarner Inc. occupies a more focused niche, specializing in diesel cold-start systems and pressure sensor glow plugs that integrate piezo-resistive sensing. Its value proposition centers on combustion optimization, cold-start reliability, and emissions reduction, appealing to customers seeking performance and compliance benefits rather than commodity replacement parts.
Alongside these leaders, a broad set of manufacturers in Asia and Europe supports the market through focused manufacturing capabilities, region-specific distribution, and targeted coverage for passenger cars, light trucks, and diesel engines. These participants contribute to overall supply resilience and can compete effectively in channels where cost, responsiveness, and localized service matter.
3.2 Market Structure Evolution: Consolidation, Specialization, and Entry Dynamics
The competitive landscape is evolving along multiple axes. Consolidation is gaining momentum where scale, portfolio breadth, and manufacturing optimization create advantages. The acquisition move involving Denso’s spark plug and glow plug operations demonstrates how established players can strengthen market position by integrating complementary technologies and expanding production efficiency for diesel applications. At the same time, specialization remains attractive in high-value subsegments such as sensor-integrated glow plugs and premium ceramic solutions, where performance claims and validation data justify differentiated pricing.
Worldwide Automotive Coolant Heaters Market
New entry and regional expansion also continue to shape the market. Manufacturers with strong production discipline and the ability to deliver consistent quality across passenger cars and light commercial vehicles can secure footholds in aftermarket channels and selective OEM programs. The overall effect is a market that rewards both scale and specialization, with successful players typically combining one or more of the following: broad application coverage, proven thermal or sensing technology, regulatory readiness, and reliable aftermarket service support.
4. Future Outlook: Three Strategic Trends Through the Mid-2030s
4.1 Trend 1: Glow Plugs as Active Combustion Enablers
Over the next three to five years, glow plugs will increasingly be evaluated as part of the combustion optimization chain rather than standalone cold-start components. Sensor-integrated designs and advanced ceramic formulations will become more relevant in applications where emission compliance, start reliability, and engine-out pollutant control carry heightened importance. The commercial opportunity lies in bundling performance claims with application coverage and validation support, allowing suppliers to position higher-content products as enabling technologies rather than simple replacements.
The associated risk is the potential for over-investment in high-content architectures for segments where cost sensitivity remains dominant. Companies must calibrate product roadmaps to real demand mix, ensuring that premium offerings are aligned with platform commitments and regulatory timelines rather than introduced broadly without clear adoption pathways.
Worldwide Car Bulbs Market
4.2 Trend 2: Aftermarket Demand Becomes the Stability Anchor
As vehicle parc ages in several regions and commercial fleets maintain long service lives, aftermarket demand will remain a stabilizing force for the glow plugs market. Even where new-vehicle diesel volumes fluctuate, replacement requirements persist, creating a reliable revenue base for suppliers with comprehensive part number coverage and strong distribution relationships. The opportunity is to strengthen catalog accuracy, geographic reach, and service-level consistency so that aftermarket channels can be scaled efficiently while maintaining margin integrity.
The risk in this trend is channel fragmentation and price competition. Without disciplined portfolio management and clear differentiation, aftermarket supply can drift toward commoditization. Suppliers should therefore protect value by emphasizing fitment reliability, thermal performance, and compliance-relevant testing rather than competing solely on price.
4.3 Trend 3: Portfolio Consolidation Around High-Value Platforms
Market participants are likely to consolidate resources around platforms that combine technical content, regulatory readiness, and broad coverage. This will favor suppliers that can reduce complexity through shared core designs while still meeting segment-specific requirements for passenger cars, commercial vehicles, and diesel or gasoline applications. The strategic opportunity is to allocate capital toward platforms with the strongest performance differentiation and the widest addressable vehicle base, while retiring or rationalizing low-value duplication.
The risk is execution complexity. Consolidation requires careful change management, customer communication, and transition planning to avoid disruptions in OEM programs or aftermarket availability. Firms that manage this transition with transparent roadmaps and validated alternative designs will emerge with stronger cost positions and clearer market messaging.
5. Actionable Guidance for Decision-Makers
5.1 For Manufacturers and Tier Suppliers
- Concentrate engineering investment on architectures that deliver measurable benefits in heat-up speed, combustion support, or emissions-related performance, and align product roadmaps with the 2026 Euro 7 timeline and subsequent regulatory phases.
- Rationalize part number complexity where possible without compromising application coverage, using platform sharing and modular design to reduce cost while preserving fitment breadth for both passenger cars and commercial vehicles.
- Strengthen validation and qualification capabilities to shorten cycle times for sensor-integrated and ceramic-based designs, ensuring that technical claims are backed by documentation that OEMs and fleet customers can trust.
5.2 For Investors and Strategic Allocators
- Evaluate exposure by demand driver rather than by aggregate market size: prioritize companies with durable aftermarket coverage, clear technological differentiation, and demonstrated readiness for tighter emission standards.
- Watch for consolidation signals that improve production efficiency and portfolio coherence, while remaining alert to margin pressure if integration is pursued without corresponding value enhancement or channel strength.
- Consider the divergence between commercial vehicle stability and passenger car volatility when modeling demand, and assess whether target companies have the mix flexibility to manage uneven segment trajectories.
5.3 For Procurement and Fleet Decision-Makers
- Prioritize supply partners that can provide comprehensive part number coverage, accurate fitment data, and consistent quality documentation, especially for commercial fleets where downtime costs outweigh marginal component price differences.
- Evaluate advanced glow plug technologies in the context of total operating goals, including cold-start reliability, emission compliance, and service life, rather than selecting purely on initial purchase price.
- Establish clear specifications and validation expectations early in sourcing decisions to reduce the risk of fitment issues, performance variability, and downstream service complications.
The glow plugs market is not static. It is being reshaped by emission regulation, technological content, segment-specific demand, and selective consolidation. For organizations operating in or adjacent to this market, the strategic imperative is to understand where value is migrating and to align product, sourcing, and investment decisions accordingly. Detailed segmentation data, regional demand trajectories, and customized scenario modeling can sharpen these decisions further, and the full research report provides the depth required to translate market direction into concrete planning.
For detailed analysis of this topic, please visit the official page: Automotive Glow Plugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Optical Films Market 2026: What the 7.1% CAGR and $399M Peak Really Mean
By PW Consulting, 2026-09-21
Optical Films Market: Strategic Trends and Commercial Opportunities Through 2032
The global optical films market has entered a phase of disciplined expansion, with revenue projected to grow from approximately $249.15 million in 2025 to $399.0 million by 2032, translating to a compound annual growth rate of 7.1 percent over the forecast horizon. This trajectory reflects a market that has moved past the post-pandemic normalization period and is now being reshaped by structural shifts in display design, end-user expectations, and supply chain architecture. From 2020 through 2025, annual revenue climbed steadily, crossing the $200 million threshold in 2022 and maintaining momentum through 2024 before accelerating into the 2025 baseline. The forward-looking path suggests that growth will not be linear; instead, it will be punctuated by technology adoption cycles, regional capacity realignment, and incremental premiumization in high-performance film segments.
For executives and investors, the most salient takeaway is that optical films are no longer a commodity layer in display manufacturing. They have become a functional differentiator that influences luminance efficiency, color accuracy, modular flexibility, and sustainability compliance. The market’s expansion is being underwritten by a concentrated competitive environment, with the top three players collectively holding roughly 35 percent of revenue and the top five approaching 45 percent. Such concentration does not imply stagnation; rather, it signals that scale players are leveraging capital intensity, process engineering, and application-specific customization to protect margins while smaller entrants focus on niche material science or regional distribution advantages.
Worldwide Optical Composite Film Market
Navigating the Current Inflection Points
The market is currently navigating a cluster of overlapping challenges that are redefining how optical films are developed, sourced, and deployed. First, the industry is confronting a transition from volume-driven LCD-centric demand toward mixed-display environments that include OLED, mini-LED, and emerging augmented reality interfaces. This shift places pressure on film architectures that were optimized for traditional backlighting and polarizer stacks, requiring manufacturers to reconfigure material formulations and coating processes without sacrificing throughput. Second, supply chain resilience has moved from a tactical concern to a strategic imperative. Periods of material constraints and extended lead times have forced producers to reconsider stocking strategies, dual-sourcing arrangements, and the geographic placement of conversion capacity. Third, regulatory and trade dynamics are adding new layers of cost and complexity. Tariffs and export restrictions on specialty chemicals, combined with sustainability mandates tied to recycling and material traceability, are compressing negotiable margins and rewarding companies that can internalize compliance rather than treat it as an external overhead.
These inflection points are not insurmountable barriers; they are filters. Companies that treat them as purely operational problems will see erosion in differentiation, while those that embed resilience and compliance into product architecture will find new pricing and partnership leverage.
Key Drivers Reshaping the Optical Films Landscape
Technology Innovation as a Margin and Function Catalyst
Material and process innovation remains the dominant engine of market evolution. Recent product introductions illustrate how rapidly the industry is moving toward thinner, more flexible, and higher-transmittance film architectures. In May 2025, 3M Corporation launched a new line of ultra-thin polarizing films designed for next-generation flexible OLED displays, signaling a direct response to the demand for lighter, more form-factor adaptable screens. Around the same period, LG Chem Ltd. introduced a recyclable, eco-friendly optical film portfolio aimed at reducing environmental impact across consumer electronics, demonstrating that performance and end-of-life considerations are increasingly being engineered together rather than traded off. These developments are not isolated product announcements; they reflect a broader shift in which film properties such as haze control, transmittance, mechanical durability, and recyclability are becoming explicit purchase criteria for display integrators and brand owners.
The strategic implication is straightforward: technology leadership in optical films is shifting from generic brightness enhancement or polarizer functionality toward application-specific stacks that integrate optical performance with manufacturability and environmental compliance. Manufacturers that can validate film behavior under flexible substrates, higher refresh rates, or new optical path designs will capture premium positioning and longer product cycles.
Policy, Regulation, and the Compliance Premium
Policy and regulatory pressure is accelerating a reevaluation of material inputs, production footprint, and trade routing. Increased tariffs and export restrictions on specialty chemicals used in optical film production have complicated international trade, while sustainability mandates and recycling requirements are adding further cost considerations to film pricing. These forces are particularly pronounced where optical films used in displays intersect with high-volume, tariff-sensitive trade lanes. The result is a market in which compliance is becoming a competitive variable: suppliers that can demonstrate material traceability, lower-hazard formulations, and localized production capabilities are increasingly able to secure preferred-supplier status with downstream assemblers and brands that face their own regulatory and reporting obligations.
For decision-makers, this driver reframes cost management. The cheapest input is no longer the cheapest over the product lifecycle if it introduces compliance exposure, customs uncertainty, or reputational risk. Investments in material substitution, supplier qualification, and regional manufacturing are increasingly justified by risk mitigation as much as by unit-cost savings.
Demand-Side Shifts Across Consumer and Industrial Use Cases
Demand is being reshaped by simultaneous changes in how consumers interact with displays and how enterprises deploy visual interfaces. Smartphones continue to anchor a substantial share of optical film consumption, but the character of that demand is evolving as devices prioritize thinner form factors, higher display efficiency, and adaptive optical tuning. 텔레비션 and desktop monitors and laptops contribute significant volume, yet they are being supplemented by higher-value applications where optical film performance directly influences user experience or functional reliability. Automotive display applications, although smaller in absolute scale, are growing in strategic importance as digital cockpits, heads-up displays, and integrated cabin interfaces become more sophisticated. These applications impose stricter requirements for thermal stability, durability, and optical consistency across wide temperature ranges, which in turn filters the supplier base toward manufacturers with strong process control and qualification capabilities.
The broader demand trend is a migration from uniform, mass-market film specifications toward segmented requirements that reward application engineering. Suppliers that can align film properties with the operating conditions and regulatory profiles of specific end-use categories will find more stable demand and fewer price-only competitions.
Supply Chain Reconfiguration and Cost Structure Pressures
Cost structures are under pressure from multiple directions. Fluctuations in raw material prices, particularly for polymers such as PET and TAC, directly influence film pricing, while sustainability mandates and recycling requirements add further cost considerations. In response, manufacturers have faced material shortages and extended lead times, prompting investment in localized production and strategic stockpiling to stabilize output and pricing. At the same time, the tariff environment is reshaping the economics of cross-border distribution, especially where high-value optical film families are exposed to elevated duties and trade friction. These pressures are encouraging a broader reassessment of where final film conversion should occur relative to resin supply, panel assembly, and end-market consumption.
The commercial opportunity embedded in this driver is the emergence of more regionalized, orchestration-heavy supply chains. Companies that can coordinate resin sourcing, conversion capacity, and finished-film distribution with greater granularity will be better positioned to smooth lead times, reduce exposure to tariff shocks, and offer customers more predictable delivery performance.
Competitive Landscape and Strategic Positioning
Profiles of Core Incumbents
The competitive set is anchored by companies that blend material science depth with application-specific commercialization. 3M Company continues to emphasize highly engineered optical films optimized for mobile electronics and display systems, including brightness enhancement and polarizer films, and its May 2025 product launch for flexible OLED underscores a push into next-generation form factors. LG Chem Ltd. positions itself around recyclable eco-friendly optical films and advanced photopolymer films for high-efficiency optics and displays, with its February 2025 portfolio release reinforcing a sustainability-forward narrative that aligns with brand-level compliance priorities. Samsung SDI Co., Ltd. develops and supplies optical films including polarizing and display composite films for LCD and OLED panels, linking film capability directly to panel-level integration. Zeon Corporation manufactures ZeonorFilm optical films with high transmittance and low haze for polarizer stacks and touchscreens, focusing on optical clarity attributes that matter in precision display stacks.
Toray Industries, Inc. produces plastic optical films for display and electronic applications, including specialized optical components, extending its materials breadth into tailored display roles. Eastman Chemical Company has expanded optical films manufacturing capacity for applications in displays and electronics, with its April 2025 facility expansion in South Korea highlighting a deliberate Asia-Pacific capacity build. Nitto Optical Co., Ltd. specializes in optical films for advanced display and electronic module requirements, emphasizing interface-level performance. Toyobo Co., Ltd. offers optical films and related display materials for consumer electronics and industrial use, broadening the functional scope of its material portfolio.
Strategic Differentiation and Competitive Dynamics
Across this group, differentiation is emerging along several axes rather than a single generic advantage. One axis is application engineering: suppliers that can tune optical films to specific display architectures, thermal environments, or interface requirements are creating stickier customer relationships and reducing exposure to commoditization. Another axis is sustainability and compliance: recyclable films and lower-impact material choices are increasingly relevant where downstream brands must meet environmental targets and reporting expectations. A third axis is geographic and manufacturing agility: capacity additions in Asia Pacific and localized production footprints are being used to reduce lead-time volatility and to navigate tariff exposure more effectively.
The market structure is evolving through selective integration and targeted divergence. Larger incumbents are likely to continue consolidating scale advantages in high-volume film families while investing in specialized lines for premium applications. At the same time, the environment is conducive to specialized entrants that can deliver differentiated material properties, regional service density, or compliance-ready sourcing, even if they do not compete on total volume. The most probable outcome is a layered competitive landscape in which scale players defend broad intervals and specialized players capture high-margin pockets tied to demanding applications and fast-moving display technologies.
Recent Developments as Strategic Signals
Several recent moves illustrate how incumbents are translating strategy into action. The May 2025 launch of ultra-thin polarizing films for flexible OLED displays indicates a direct bet on form-factor evolution and the accompanying optical requirements of bendable and lightweight screen designs. The April 2025 manufacturing expansion in South Korea reflects a deliberate alignment of capacity with regional demand concentration and possibly with panel-assembly geography. The early-2025 introduction of a recyclable, eco-friendly optical film portfolio signals that sustainability is being operationalized as a product attribute rather than treated as a corporate messaging layer. And partnership activity around customized optical films for heads-up displays and augmented reality applications points to the growing relevance of non-traditional display contexts, where optical films must perform under different viewing geometries, illumination conditions, and durability demands.
These developments collectively suggest that the market is moving toward tighter coupling between film properties, application requirements, and compliance expectations. Suppliers that can coordinate these dimensions within a single product strategy are likely to secure more durable positions than those competing primarily on price or generic specification.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
1. Premiumization Through Application-Specific Optical Stacks
The most durable trend is the continued shift toward optical films engineered for specific display platforms and operating environments. As flexible OLED, mini-LED, and advanced automotive displays gain wider deployment, film suppliers will face rising expectations for transmission efficiency, mechanical resilience, thickness reduction, and compatibility with new panel architectures. This trend creates commercial opportunity for manufacturers that can validate performance under application-specific conditions and offer coordinated solutions rather than standalone film reels. The risk is that premiumization can fragment demand if too many bespoke specifications dilute scale benefits, so disciplined portfolio management will be essential.
2. Regional Capacity Realignment and Supply-Chain Orchestration
Trade friction, tariff exposure, and the need for more predictable lead times are likely to accelerate regional capacity adjustments and closer integration between resin supply, film conversion, and downstream assembly. Over the next three to five years, expect more capacity located closer to key demand clusters and more deliberate buffer strategies for critical inputs. The opportunity lies in building supply networks that can absorb shocks without overcapitalizing in the wrong geographies. The uncertainty comes from the pace and direction of trade policy, which can alter the economics of regionalization faster than internal planning cycles can adapt.
Worldwide Window Films Market
3. Sustainability as a Design Variable, Not a Compliance Afterthought
Recyclable films, lower-impact polymer choices, and traceability requirements are becoming embedded in sourcing decisions, especially where downstream brands face external sustainability reporting or internal material targets. This trend opens space for suppliers that can demonstrate verifiable environmental attributes alongside consistent optical performance. The commercial upside is stronger qualification outcomes and longer-term contracts with customers that prioritize compliance and brand risk reduction. The caution is that sustainability claims must be backed by credible process controls and material documentation, because superficial positioning is unlikely to withstand scrutiny from sophisticated buyers.
PW Consulting Information & Electronics Research Center
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
Focus on application engineering and validation as a source of differentiation rather than relying solely on scale or price. Build the capability to prove film behavior in flexible, high-efficiency, and automotive-grade contexts, and align product roadmaps with the display platforms that are most likely to adopt thinner, more efficient, and more durable optical layers. Use regional capacity and sourcing choices to reduce tariff and lead-time exposure, but ensure that localization decisions are supported by data on resin availability, conversion economics, and customer geography rather than driven by short-lived policy headlines.
For Investors and Capital Allocators
Assess exposure not only to total market growth but to the mix shift toward higher-value film families and demanding applications. Track capacity additions and partnership activity as indicators of where incumbents believe demand will concentrate, and pay attention to compliance-oriented product launches as potential differentiators that can support pricing resilience. Favor business models that combine technical depth with the ability to serve application-specific requirements, because those attributes are more likely to translate into durable margins than volume-only positioning.
For Procurement and Sourcing Leaders
Treat optical film sourcing as a multi-variable decision that includes optical performance, qualification risk, tariff exposure, and environmental compliance. Diversify supply where feasible, but do so with an explicit strategy for lead-time stability and material traceability rather than simply adding nominal second sources. Where possible, engage suppliers early in display design cycles to align film selection with performance and compliance goals, because late-stage substitution often carries higher cost and risk than coordinated specification.
Where to Go Next
The optical films market is expanding at a measured but meaningful pace, and the competitive advantage will increasingly belong to organizations that can integrate material performance, application engineering, and supply-chain resilience into a coherent commercial strategy. The trends outlined here point to a market in which premiumization, regional capacity realignment, and sustainability-driven design are not peripheral themes but central drivers of value creation. For teams that need a fuller picture of segment dynamics, regional splits, application-level momentum, and detailed company benchmarking, the complete PW Consulting research report provides the deeper data set and tailored scenarios required to support concrete planning decisions.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beer Market 2026: Beyond the 4.91% CAGR Story — What’s Really Driving Growth to $1.17T
By PW Consulting, 2026-09-21
Navigating the Evolving Beer Market: Strategic Trends and Commercial Opportunities Through 2032
The global beer market is undergoing a period of structural transformation. With total market value projected to reach $1,170.34 billion by 2032, expanding at a compound annual growth rate of 4.91 percent from a 2025 base of $860.0 billion, the sector demonstrates resilient demand but faces mounting pressure on margins, shifting consumer preferences, and evolving regulatory and cost environments. The historical trajectory from 2020 through 2025 reveals a market that has absorbed pandemic-era disruptions, reconfigured distribution models, and adapted to inflationary input costs, while maintaining steady expansion. Looking ahead to the forecast period of 2026 through 2032, growth will be less about uniform volume gains and more about strategic positioning across regions, categories, packaging formats, and trade channels. For executives, investors, and procurement leaders, the imperative is to understand where value will concentrate and how to respond to structural shifts rather than cyclical noise.
Three interconnected challenges define the current inflection point. First, the market exhibits moderate concentration, with the top three players capturing approximately 46 percent of revenue and the top five holding around 58 percent. This structure provides scale advantages to incumbents but also invites regulatory scrutiny, limits pricing flexibility in certain channels, and raises the bar for new entrants seeking distribution access. Second, cost structures are under persistent strain from raw material volatility and packaging expenses. Malt represents a significant share of production inputs, and barley dominates malt usage, while packaging costs disproportionately influence total cost of goods, particularly for producers reliant on metal containers. Third, the trade channel mix is rebalancing as on-trade recovery continues and off-trade growth reflects changing consumption occasions, creating uneven margin profiles and requiring differentiated go-to-market strategies. These dynamics do not signal contraction; they signal a redefinition of where profitability is generated and how competitive advantage is sustained.
Wine Market
Key Drivers Reshaping the Market
Technological Innovation and Production Efficiency
Innovation in brewing technology is moving beyond incremental process improvements to encompass capacity optimization, ingredient efficiency, and precision formulation. Recent capital deployment illustrates how major producers are aligning investment with product strategy. One global brewer allocated substantial funding across its US operations to strengthen manufacturing jobs and expand production of light and zero-alcohol variants, while a separate investment in an Ohio brewery targeted capacity expansion and local training programs. These moves reflect a broader pattern: technology investment is increasingly tied to specific portfolio priorities, including low- and no-alcohol products, consistent quality at scale, and labor productivity. Automation, data-driven scheduling, and advanced filtration and fermentation controls are enabling producers to manage variable input costs more effectively and reduce waste. For commercial leaders, the strategic question is whether technology spending is directed toward cost reduction alone or also toward enabling new product formats and faster iteration on flavor profiles and functional attributes.
Black Beer Market
Policy and Regulatory Environment
Regulatory shifts are reshaping cost structures and market access, particularly around trade policy and packaging requirements. Tariff dynamics have introduced both risks and relief. One major importer reported that the US government removed tariffs on certain beer imports in early 2026, altering the cost calculus for cross-border supply chains. At the same time, another producer projected meaningful tariff-related expenses for the year, compressing gross margin guidance. These divergent outcomes underscore that regulatory impacts are highly portfolio- and geography-specific. Beyond trade policy, packaging-related regulation and sustainability expectations are influencing material choices and supplier negotiations. Producers are re-evaluating container formats in light of cost, recyclability, and consumer perception, with metal packaging representing a substantial portion of total packaging spend and aluminum conversion adding significant expense. The strategic implication is that regulatory monitoring must become a continuous input to sourcing, pricing, and channel planning rather than a periodic compliance exercise.
Consumer Demand and Behavioral Shifts
Demand patterns are evolving along multiple axes: moderation, premiumization, variety, and occasion-based consumption. Non-alcoholic and low-alcohol offerings continue to gain traction, with one international brewer reporting continued growth in this category alongside strength in premium segments. This trend is not limited to a single market; it reflects a broader consumer willingness to trade down on alcohol content while trading up on flavor, branding, and experience. At the same time, premiumization remains a durable force, with a meaningful share of revenue associated with higher-tier products, even as standard-tier beer continues to anchor volume in many markets. Consumers are also diversifying within traditional categories, sustaining strong preference for lager while opening space for ales, stouts, and specialty styles in specific channels and regions. For companies, the implication is that portfolio architecture must balance volume anchors with higher-margin differentiation, and that channel selection matters as much as product design because occasion and setting shape willingness to pay.
PW Consulting
Supply Chain and Cost Structure Realignment
Input cost dynamics remain a central driver of profitability. Barley and malt continue to anchor production economics, with malt accounting for a large share of raw material costs and barley comprising the majority of malt usage. This concentration makes procurement strategy, hedging, and supplier relationships critical levers. On the packaging side, metal cans represent a significant share of packaging dollars for major producers, and aluminum conversion adds a substantial premium to can expenses. Together, these factors create a cost environment where small improvements in yield, material utilization, and logistics can have outsized margin effects. Recent disclosures highlight that cans account for a significant portion of packaging costs, reinforcing the need to optimize container choice against channel requirements and consumer preferences. Companies that integrate sourcing, packaging engineering, and demand forecasting are better positioned to absorb volatility and protect gross margins without sacrificing market share.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field is anchored by globally scaled brewers and regionally focused players, each pursuing distinct strategies to defend and extend their positions. Anheuser-Busch InBev leverages a broad global brand portfolio and continues to invest in US manufacturing capacity, with capital directed toward both volume production and specific brands in the light and zero-alcohol space. Heineken N.V. has emphasized growth in non-alcoholic beer and premium segments, aligning product innovation with evolving demand while maintaining a presence across more than seventy markets. Carlsberg Group has focused on portfolio diversification and market share gains in Europe and emerging markets, using earnings guidance and annual reporting to signal disciplined expansion and category balance. Molson Coors Beverage Company combines mainstream American brands with craft and flavored offerings, using a dual structure to capture both volume and differentiation. Constellation Brands concentrates on imported beer strengths, benefiting from brand recognition and trade dynamics that favor cross-border portfolio positioning. The Boston Beer Company operates with a craft and flavored malt beverage orientation, using brand platforms and variety to compete in segments where differentiation and taste innovation matter.
These companies are not simply competing on scale; they are differentiating through portfolio mix, channel execution, and targeted investment. The leaders are aligning capacity and capital with product priorities, using financial reporting to reinforce credibility with investors, and adjusting to input and trade cost realities through sourcing and pricing discipline. The common thread is a shift from pure volume competition to a more nuanced game in which brand architecture, channel strategy, and cost control jointly determine outcomes.
Market Structure Evolution
The industry is experiencing both integration and fragmentation, depending on the segment and geography. At the top, moderate concentration suggests that scale advantages in procurement, distribution, and brand investment will persist, and that acquisitions or partnerships may be used to expand reach, add craft or specialty capabilities, or enter high-growth regions. At the same time, consumer demand for variety, local identity, and differentiated taste experiences continues to create space for smaller and mid-sized players, particularly in on-trade settings and specialty channels. New entrants and craft-oriented brands can gain traction by focusing on specific occasions, flavor innovation, and community-driven branding, but they face practical hurdles in distribution access, packaging cost efficiency, and marketing scale. The likely trajectory is a layered market in which global and regional leaders compete on breadth and efficiency, while smaller players compete on specificity and experience, with channel dynamics and local regulations shaping the boundaries of each contest.
Forward Outlook: Trends and Opportunities for 2026–2032
Premiumization and Moderation as Dual Engines
Over the next three to five years, premiumization and moderation are expected to remain intertwined growth drivers. Premium products will continue to capture disproportionate value growth, supported by consumers willing to pay more for quality, brand experience, and differentiated taste. Simultaneously, low- and no-alcohol options will expand their share in several markets, driven by health consciousness, social moderation trends, and improved product quality. The commercial opportunity lies in portfolio design that treats these as complementary rather than competing strategies. Companies that can offer credible premium choices while building distinct non-alcoholic lines, and that can position them appropriately across on-trade and off-trade channels, will be better placed to capture value across occasions. The risk is brand dilution or channel conflict if premium and moderation offerings are not clearly differentiated and supported by consistent messaging and distribution.
Packaging, Cost, and Sustainability Integration
Packaging strategy will increasingly function as a margin and positioning lever rather than a purely operational decision. Metal cans remain central to many producers, but their cost profile, including the impact of aluminum conversion, requires active management. Over the forecast period, expect more deliberate experimentation with container mixes, regional packaging preferences, and packaging efficiency initiatives that reduce waste and cost without compromising consumer experience. Sustainability expectations will further influence material choices and supplier negotiations, especially in markets where regulatory and consumer pressure is intensifying. The opportunity is to integrate packaging decisions with sourcing, channel strategy, and brand positioning so that cost, convenience, and environmental considerations reinforce rather than conflict with one another. The risk is reactive change that raises costs without delivering consumer or regulatory benefit, or over-indexing on a single format that leaves a producer exposed to input price swings.
Regional Divergence and Channel Rebalancing
Growth will not be uniform across regions. Asia Pacific, Europe, and North America represent substantial revenue bases with different consumption habits, regulatory environments, and channel structures. Latin America and the Middle East and Africa contribute meaningful value and offer varying growth paths shaped by local tastes, economic conditions, and distribution infrastructure. Within these regions, the balance between on-trade and off-trade will continue to shift as social habits, pricing, and convenience evolve. The strategic opportunity is to tailor product mix, packaging, and channel investment to regional realities rather than assuming a single global playbook. Companies that localize effectively, while maintaining core brand and quality standards, can capture disproportionate gains in markets where competitors rely too heavily on standardized approaches. The risk is underinvestment in region-specific capabilities or over-extension into markets where cost structures and channel economics do not support the intended return.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Leaders
- Align capital and capacity investments with clear portfolio priorities, ensuring that expansion supports specific brands and formats rather than diffuse volume goals.
- Integrate procurement, packaging engineering, and demand planning to manage malt and aluminum exposure, using hedging, supplier diversification, and yield improvements to protect margins.
- Design non-alcoholic and premium offerings as distinct strategic lines with dedicated positioning, channel selection, and quality standards to avoid internal competition and consumer confusion.
For Investors and Financial Stakeholders
- Evaluate companies on the coherence of their portfolio strategy, the quality of cost discipline in raw materials and packaging, and the resilience of their channel mix across on-trade and off-trade demand cycles.
- Monitor trade policy developments closely, since tariff relief and tariff exposure can shift margin trajectories quickly and asymmetrically across importers, domestic producers, and specific brand portfolios.
- Focus on the sustainability of growth by examining whether premium and moderation trends are supported by genuine product differentiation and distribution strength rather than short-term promotional activity.
For Procurement and Supply Chain Leaders
- Treat malt, barley, and aluminum container costs as interconnected levers, and build sourcing strategies that combine long-term supplier relationships, flexibility in specification, and scenario planning for price volatility.
- Coordinate packaging choices with channel and regional requirements, balancing cost efficiency against consumer expectations, sustainability goals, and regulatory considerations.
- Incorporate trade and tariff intelligence into supply chain design, including routing, inventory positioning, and contract terms, to reduce exposure to policy-driven cost shocks.
The commercial landscape ahead will reward organizations that treat market intelligence as a continuous input to strategy rather than a periodic checkpoint. Detailed segmentation data, regional breakdowns, and scenario analysis can sharpen planning around portfolio mix, pricing, channel allocation, and sourcing, especially in a market where growth is steady but value creation is increasingly selective. For leaders seeking deeper granularity on regional dynamics, category shifts, packaging economics, and competitive moves through 2032, the full research report provides the detailed framework and segmented data needed to translate these trends into concrete decisions.
For detailed analysis of this topic, please visit the official page: Beer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


