



PW Consulting: Aircraft Tractor Market to expand 5.65% CAGR, reaching USD 162.42 Million by 2032
By PW Consulting, 2026-07-23
Aircraft Tractor Market — 2026 Strategic Preview
Executive summary
As global aviation operations accelerate their recovery and transition agendas, the aircraft tractor market is poised for steady, technology-driven growth. Our analysis, anchored to a 2025 base year and spanning historical performance (2020–2025) with a forecast window to 2032, shows underlying market value expanding from roughly USD 83 million in 2020 to about USD 109 million in 2025 and further toward an estimated USD 162 million by 2032. This trajectory corresponds to a compound annual growth rate of approximately 5.65% across the forecast period — a moderate yet structurally durable expansion driven by fleet activity, emissions regulation, and the capital refresh cycle at airports and ground handlers.
Aircraft Tractor Market
Why this matters for 2026 decision-makers
-
Procurement prioritization: Capital planners at airports, ground handling companies, and airlines must sequence investments to reconcile near-term operational demands with medium-term electrification and zero-emission mandates. The market growth and replacement cycle we model indicate meaningful purchasing windows in 2026–2029 where decision timing materially affects TCO outcomes.
Aircraft Tractor Market -
Technology transition: Diesel, hybrid, and electric solutions are coexisting in the market today. Electrification is not merely a product substitution — it reshapes depot infrastructure, maintenance models, and utility load planning. For procurement and asset managers, 2026 is a pivotal year to pilot scaleable electric deployments while safeguarding legacy operations.
Aircraft Tractor Market -
Regulatory alignment: Emerging rules and advisory circulars are already influencing fleet composition and permissible operating practices. Understanding which aircraft types can be serviced today by certified electric tractors versus where towbar or towbarless approaches remain obligatory will determine near-term retrofit needs and supplier selection.
-
Competitive positioning: OEMs, integrators and service providers that can bundle hardware, charging/energy services, and aftermarket maintenance stand to capture a growing share of lifecycle spend. Investors and M&A strategists should be looking for platform plays that combine manufacturing scale with service-forward economics.
Market dynamics and regulatory drivers
The market’s growth profile reflects a confluence of demand-side and policy-side drivers. On the demand side, traffic rebound and cargo resilience create base utilization that sustains replacement cycles. On the policy side, a number of regulatory developments are actively re-shaping the addressable market and product requirements. Examples include updated FAA guidance on towbar and towbarless movement, regional airport-level zero-emission vehicle rules that mandate transition paths for new ground support equipment, and type-specific certifications for electric towbarless tractors that expand operational envelopes for narrow-body fleets.
For decision-makers, this means regulatory risk is now a price of doing business rather than a distant uncertainty. Procurement teams must incorporate certification timelines, airport rule compliance, and local electricity infrastructure readiness into capital plans. Operational leaders, meanwhile, should reassess ramp scheduling, tug allocation, and contingency planning to reflect mixed-fleet operations during transition.
Competitive landscape — strategic takeaways
The aircraft tractor supplier base combines legacy manufacturers with specialized engineering firms and GSE divisions of larger conglomerates. Market concentration metrics indicate a fragmented competitive structure, with the top three and top five suppliers together accounting for a modest share of the market — a dynamic that fosters both product innovation and price competition.
-
TLD Group (France): A well-established provider of both conventional and electric tractors, TLD’s portfolio is notable for addressing pushback and towing needs across narrow- and wide-body aircraft. Their strategic advantage lies in product breadth and existing aftermarket footprints at large hubs.
-
Goldhofer AG (Germany): Goldhofer’s PHOENIX AST-2 towbarless tractor has been positioned as a high-capability solution for a broad set of aircraft types. Recent promotional activity demonstrates their emphasis on operational versatility and lifecycle reliability — messaging that resonates with carriers and handlers seeking high-utilization assets.
-
TREPEL Airport Equipment GmbH (Germany): TREPEL offers a focused range of airport GSE, with tractors and towing solutions tailored to pushback operations. Their market posture emphasizes integration with airport handling workflows and customization for operator-specific requirements.
-
Textron GSE (United States): Leveraging hybrid-electric and electrified product lines, Textron has pursued a blend of conventional engineering and low-emission innovation. Their reach into hybrid pushback tractors positions them well for customers seeking incremental transition options.
These vendors illustrate the strategic choices available to buyers: choose mature diesel platforms with broad support, adopt electrified towbarless tractors where certifications and infrastructure permit, or pursue hybrid solutions as a bridge strategy. The competitive field remains open to entrants that can convincingly bundle hardware, charging, and aftermarket services.
Recent signals to watch
-
Product demonstrations that validate multi-aircraft operational claims can catalyze procurement waves — a recent demonstration by a leading OEM emphasized towbarless capability across high-utilization narrow- and some wide-body types.
-
Airport-level zero-emission rules and national advisory circulars continue to narrow acceptable future states for new GSE purchases. Early movers that secure compliant, certified electric assets can convert regulatory pressure into competitive advantage.
-
Certification milestones — where authorities have approved electric tractors for specific aircraft types — materially shorten adoption lead times by reducing operational friction for handlers and airlines.
What PW Consulting’s full report delivers (operationally focused)
Our full Aircraft Tractor Market study is designed as a practical playbook for executives, procurement leads, and investors taking decisions in 2026. Key deliverables include:
-
Market sizing and scenario models (2020–2032) with base-case, upside, and stress scenarios that incorporate traffic recovery and policy shock variables.
-
Investment decision frameworks and TCO calculators that compare diesel, hybrid and electric options across lifecycle metrics, energy pricing scenarios, and maintenance regimes.
-
A vendor evaluation matrix (capability, service footprint, certification readiness, total cost of ownership) and a shortlist methodology to identify suitable OEMs for different buyer archetypes.
-
Supply-chain and aftermarket mapping: supplier nodes, critical components, lead-time sensitivity, and strategic sourcing checklists to de-risk procurement.
-
Operational integration playbooks: pilot design, infrastructure scoping (charging and depot reconfiguration), operational training, and phased roll-out templates.
-
Regulatory impact assessment and engagement templates for airports and vendors to align product roadmaps with certification timelines and local rules.
-
M&A and partnership screening tools for investors seeking bolt-on acquisitions or distribution alliances in the ground support equipment ecosystem.
Strategic playbook for 2026
-
For airports and handlers: Launch tiered pilot programs that prioritize high-frequency stands with predictable duty cycles for early electric adoption. Simultaneously, prepare retrofit contracts and service-level agreements that cover mixed-fleet contingencies.
-
For OEMs and suppliers: Move beyond one-off hardware sales. Package asset-as-a-service offers that include charging infrastructure, predictive maintenance, and energy management — a model that eases buyer CAPEX constraints and locks in recurring revenues.
-
For airlines: Negotiate bundled procurement with ground handlers to secure preferential access to zero-emission ground services, and prioritize procurement clauses that specify certified compatibility for common pushback operations.
-
For investors: Target businesses that combine manufacturing scale with aftermarket platforms or digital operating tools (fleet telematics, predictive maintenance) — these assets amplify margins as electrification increases service complexity.
-
For regulators and port authorities: Continue to provide clear certification pathways and transitional compliance instruments; predictable regulatory timelines materially accelerate private sector investment.
Conclusion — how to use this preview
This preview is intended to orient 2026 strategy: the market is growing at a mid-single-digit CAGR, driven by operational demand and regulatory acceleration, while supplier fragmentation offers opportunity for consolidation and service innovation. Our full study drills into the granular segmentation drivers, executable procurement templates, TCO model inputs, and vendor scorecards that operational teams need to act decisively. We deliberately limit public disclosure here of granular regional and application splits to preserve the actionable value of our primary analysis while giving readers a clear sense of the strategic levers at play.
Next steps
If your organization is planning a 2026 procurement, technology pilot, or investment in the ground support equipment space, PW Consulting’s full Aircraft Tractor Market report provides the data, templates, and scenario models required to reduce execution risk and accelerate adoption. Access the complete analysis and supporting tools on our report page to unlock the segmented market views, detailed vendor benchmarking, and downloadable decision-support models.
For detailed analysis of this topic, please visit the official page: Aircraft Tractor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pheromones Market to Reach USD 366.2 Million by 2032 at 8.45% CAGR
By PW Consulting, 2026-07-23
Pheromones Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting releases its latest Pheromones Market research, this introduction outlines why the study is an essential planning tool for executives making strategic choices in 2026. The global pheromones market has moved from a niche tool in integrated pest management to a mainstream instrument of sustainable crop protection and precision agriculture. Between 2020 and 2025 the market expanded appreciably, and our base‑year sizing shows clear momentum: the market reached USD 208.2 Million in 2025 and, under the central scenario, is projected to approach USD 366.2 Million by 2032—a compound annual growth rate (CAGR) of 8.45% across the forecast horizon. For boards, corporate strategy teams and investors, these macro dynamics translate into a time‑sensitive window of opportunity—but also into concrete risks that must be actively managed.
Pheromones Market
Why this report matters for 2026 decision cycles
- Actionable sizing and forward visibility: The study provides a reconciled historical series (2020–2025) and an explicit forecast framework (2026–2032) that supports capex, product launch and M&A timing. The quantified baseline and growth trajectory allow finance teams to stress‑test investment cases against multiple adoption curves and regulatory scenarios.
- Risk‑first planning for supply chains: Recent policy shifts and trade volatility have already reshaped procurement economics for pheromone producers. Our research integrates these disruptions into supplier risk matrices so sourcing teams can evaluate dual‑sourcing, in‑region production, and toll‑manufacturing strategies with realistic lead‑time and cost assumptions.
- Commercial playbooks for rapid adoption: Practitioners will find channel and go‑to‑market archetypes tailored to growers (from high‑value orchards to row crop cooperatives), enabling accelerated conversions during peak rollout windows in 2026–2027.
Market dynamics that will steer boardroom choices in 2026
Three structural forces are converging to shape competitive advantage in pheromones: sustainability mandates, technological diffusion, and supply‑chain realignment. Regulatory and market pressure to reduce synthetic pesticide use is pushing growers and integrators toward semiochemical approaches; this effect underpins the steady CAGR and the consistent year‑on‑year expansion we document. Concurrently, innovations such as sprayable formulations, biodegradable dispensers and scaled biological production (e.g., fermentation routes) are expanding addressable applications beyond specialty crops into broader row‑crop contexts. Finally, geopolitical shifts and tariff regimes that affected chemical imports in 2025 have materially altered input cost structures and vendor choices—raising the value of regional production footprints and resilient supplier networks.
Pheromones Market
What recent commercial moves reveal about the competitive battlefield
- Product approvals and launches are accelerating time‑to‑market for pheromone solutions in high‑impact pests; recent regulatory clearances for crop‑targeted pheromone products demonstrate regulators’ growing receptivity—and signal faster commercialization pathways for first movers.
- Biodegradable, lower‑waste dispensers and sprayable formulations are not academic novelties: commercial launches and distribution agreements show channel partners are prioritizing these formats as the next wave of grower adoption.
- Strategic alliances—particularly between pheromone technology providers and large agricultural distributors—are scaling market access faster than organic sales channels alone. Distribution ties and co‑development pacts have become a primary route to accelerate adoption in 2026.
Competitive landscape: who matters and why
The market exhibits moderate concentration: the top three players account for a meaningful share of industry revenue, and the top five firms approach half of the market in combined scale. This structure creates two simultaneous strategic realities for market participants in 2026. Incumbents with scale can exploit distribution and production advantages to entrench leadership; smaller, specialized firms can still secure attractive niches through differentiated technologies, service‑led deployments and targeted partnerships.
Pheromones Market
- Russell IPM (UK) and Trécé (US) continue to lead on integrated monitoring and trap systems, translating decades of field data into commercial products.
- Shin‑Etsu (Japan) and specialty chemical houses provide formulation and materials expertise that matter when firms scale manufacturing or pursue novel dispenser chemistry.
- Provivi (US) and other disruptors are commercializing next‑generation mating disruption technologies, and their partnerships with local agribusinesses demonstrate an effective model for rapid regional penetration.
- Large agchem and biological players such as FMC, Koppert and ISCA are expanding pheromone offerings through R&D and M&A, accelerating industrialization—FMC’s recent product registration is a concrete example of this momentum.
Regulatory, trade and input‑cost headwinds
Decision‑makers must treat regulatory and trade developments as first‑order planning assumptions. In 2025, reciprocal tariff actions and reoriented import flows materially tightened available supply and increased landed costs for chemical intermediates used in pheromone synthesis. Historical pressure on raw material pricing—an average escalation in upstream synthesis inputs in the early 2020s—exacerbates margin sensitivity for producers who remain dependent on single‑source suppliers. In practice, this means procurement and board teams should prioritize supply diversification, localized production incentives and contract clauses that reflect commodity volatility for any 2026 rollouts.
What the report delivers (practical contents)
Our study is intentionally operational. It combines market economics with executable playbooks aimed at commercial and corporate strategy teams. Key inclusions are:
- Reconciled market sizing and growth scenarios (base year 2025; forecast 2026–2032) with sensitivity bands tied to adoption rates and regulatory outcomes.
- Supplier risk maps and mitigation blueprints (multi‑sourcing, regionalization, toll‑manufacturing checklists).
- Channel and pricing playbooks tailored to orchard, vegetable and row‑crop use cases—highlighting unit economics and farmer ROI thresholds needed to unlock broader adoption.
- Competitive profiles and partnership matrices that prioritize targets for distribution agreements, co‑development or bolt‑on acquisition.
- Regulatory tracker and scenario planning tools designed for in‑house legal and public affairs teams to model approval timelines and trade policy impact.
- A prioritized list of high‑value applications and technology bets (e.g., sprayable pheromones, biodegradable dispensers, fermentation scale‑up) with estimated commercialization timelines.
Strategic recommendations for 2026
- Prioritize supply resilience: Implement clause‑based supplier contracts, secure regional manufacturing nodes or capacity reservations, and accelerate qualification of secondary suppliers to offset tariff and raw material shocks.
- Double down on product formats that lower grower friction: Invest in biodegradable and sprayable formats and bundle pheromone solutions with monitoring services to increase growers’ willingness to pay and shorten purchase cycles.
- Use partnerships to scale distribution: Target alliances with major distributors and ag‑input integrators to access broad grower networks quickly rather than relying on organic channel development alone.
- Deploy field‑validated ROI cases: Build robust farm‑trial evidence and financial calculators that translate efficacy into net grower income to accelerate procurement approvals within cooperatives and large growers.
- Prepare M&A and licensing playbooks: With moderate concentration and accelerating innovation, 2026 is the year to either acquire niche technology for vertical differentiation or license to scale fast without heavy capital expenditure.
- Integrate digital monitoring: Combine pheromone dispensers with remote sensing and analytics to create subscription revenue streams and higher switching costs for customers.
How PW Consulting’s research supports your 2026 playbook
This study is structured to be a near‑term execution manual as much as a strategic forecast. Executives will find the quantitative base to run investment sensitivity analyses and the qualitative playbooks to operationalize supply, commercial and regulatory moves in 2026. Importantly, while the report demonstrates trends and competitive positioning in depth, it intentionally abstracts granular segmentation tables from the executive summary to preserve the commercial edge for subscribers. If your organization is preparing a go‑to‑market, sourcing or M&A decision, the full report and our bespoke advisory engagements provide the module‑level detail (regional, product and application splits, supplier contracts and deal‑ready financial models) necessary to convert strategy into results.
Closing: timing and the cost of delay
The pheromones market is at an inflection point: technological advances and shifting regulation are converting an environmental priority into a scalable commercial market. Our forecast trajectory and underlying diagnostics indicate a multi‑year window in which first movers and well‑capitalized followers can capture asymmetric returns. For corporate boards and strategy teams, the question for 2026 is not whether pheromones will matter in the future—they already do—but whether your organization will lead, follow or react. The PW Consulting report is designed to make that choice an informed and executable one.
For detailed analysis of this topic, please visit the official page: Pheromones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lab Reagents Market at USD 215.0M in 2025, 6.2% CAGR to 2032
By PW Consulting, 2026-07-23
Laboratory Chemical Reagents Market — Strategic Briefing (PW Consulting)
Executive teaser: Why this study is indispensable for 2026 strategic decisions
For executives planning capital allocation, product-roadmap prioritization, or M&A activity in 2026, the Laboratory Chemical Reagents Market is no longer a background line item — it is core to resilience and growth in life sciences, analytical services, and industrial R&D. Our PW Consulting market study synthesizes five years of historical performance (2020–2025) and a seven-year forecast (2026–2032) into a decision-grade intelligence product. The market expanded from approximately USD 162.5 million in 2020 to a reported USD 215.0 million in the base year 2025 and is forecast to grow to roughly USD 326.7 million by 2032, representing a compound annual growth rate of 6.2% across the forecast window. That macro trajectory requires different strategic responses in 2026 than those appropriate in 2022 or 2024; our study shows which responses are mission-critical.
Laboratory Chemical Reagents Market
High-level implications for 2026 corporate strategy
- Portfolio prioritization: Continued mid-single-digit CAGR at the market level validates investment in high-margin, innovation-led reagent lines (biochemical reagents, high-throughput solutions, eco-friendly chemistries). Companies that reallocate R&D and commercialization spend toward these pockets can materially outpace aggregate growth.
- Supply-chain resilience: Volatile raw-material pricing and intermittent supply disruptions are persistent. The report provides a supplier-risk matrix and hedging playbook to protect gross margins without locking companies into uncompetitive long-term contracts.
- M&A and inorganic growth: Moderate market concentration (the top three players account for roughly one-third of the market, and the top five approach mid-40s percent) creates attractive bolt-on opportunities for scale, geographic diversification, or capability fills — particularly for firms pursuing distribution network densification or specialized reagent portfolios.
- Commercial model innovation: The adoption of digital platforms and lab workflow integration is accelerating. 2026 is a pivot year for commercial experiments: subscription-based reagent supply models, reagent-as-a-service contracts for high-throughput customers, and integrated data-service bundles will separate winners from laggards.
Key market dynamics and directional evidence
- Steady, sustainable growth: The 6.2% CAGR to 2032 implies a market that rewards steady investment rather than speculative, high-risk plays. This is a structural growth market driven by ongoing investment in biotech, increased throughput in clinical and environmental testing, and renewed emphasis on supply-chain localization.
- Innovation-driven differentiation: Product launches from leading vendors in 2025—such as eco-friendly reagent lines, next-generation high-throughput biochemical reagents, and enhanced enzyme and buffer chemistries—are reshaping buyer expectations. These moves signal that product innovation, not price wars, will be the primary battlefield in 2026.
- Digitization and workflow integration: New digital platforms aimed at streamlining laboratory workflows have begun to influence procurement decisions. Buyers increasingly value reagent vendors that can reduce total cost of ownership through integrated data management, traceability, and automation-ready formulations.
- Operational and regulatory investments: New manufacturing capacity (including high-purity facilities in Asia-Pacific) and capital investments in life-science centers indicate supply-side confidence. Firms investing in localized manufacturing and regulatory compliance will have faster market access and lower freight/exposure risks.
- Input-cost sensitivity: Fluctuating raw-material prices remain a key short-term risk to margins; the report includes scenario models that quantify margin sensitivity to inputs under different sourcing strategies.
Competitive landscape — what the market moves mean for incumbents and challengers
We profile and benchmark the market’s core players across capability, channel reach, product breadth, and strategic intent. Several directional observations matter for 2026 planning:
Laboratory Chemical Reagents Market
- Established diversified players: Firms with extensive life-science footprints and broad distribution (including global catalog portfolios) continue to exercise scale advantages in procurement and channel intimacy. Recent product introductions focused on sustainability and high-throughput workflows signal a two-pronged offensive: product differentiation plus corporate responsibility positioning.
- Specialists and niche innovators: Companies investing in specialized enzyme systems, buffers optimized for drug discovery, and application-specific reagents are carving premium segments. These niches are attractive for partnership and licensing models because they combine defensibility with higher margins and lower direct competition.
- Distributor and service-led models: Global laboratory suppliers that combine distribution networks with value-added services (logistics, technical support, and custom formulation) are consolidating relationships with academic, biotech, and corporate R&D end-users. Expect more integrated commercial propositions in 2026.
Recent corporate moves and how we interpret them
- New eco-friendly reagent lines and next-generation high-throughput reagents launched in 2025: these moves reflect both regulatory and customer demand pressures. For suppliers, developing sustainable formulations is increasingly a table-stakes requirement for large institutional customers.
- Digital platform rollouts for reagent lifecycle and data management: digitization is transforming the buying process. Companies able to bundle reagent supply with laboratory informatics will improve stickiness and extract higher lifetime value per customer.
- Capital investments in regional manufacturing and life-science centers: these are strategic commitments to proximity manufacturing and expanded process capabilities. Firms that localize production in growth markets will reduce lead times and tariff exposure while addressing regulatory preferences for domestic supply.
- Acquisition activity and capability consolidations: targeted bolt-ons (instrumentation, consumables, or specialty reagent makers) remain the fastest route to fill product gaps or accelerate channel access. The report highlights categories and geographies where acquisitions are high-ROI versus where greenfield capacity is preferable.
What the PW Consulting report contains — action-oriented deliverables (practical, not academic)
- Market sizing & validated forecast (2020–2032): A transparent methodology that reconciles bottom-up product / end-user signals with top-down macro drivers. The study includes scenario ranges and sensitivity to key assumptions.
- Decision frameworks for 2026: portfolio prioritization matrices, five-year ROI models for capex vs. M&A, and a go-to-market playbook for subscription and digital bundle launches.
- Supplier and raw-material risk toolkit: supplier concentration maps, contingency procurement templates, and cost-pass-through modeling to inform pricing and hedging policy.
- Regulatory and compliance tracker: regional/regulatory change implications and a compliance readiness checklist tailored for reagent manufacturers and distributors.
- Competitor benchmarking: strategic profiles, capability heatmaps, and scenario-based reactions for major players (including their recent product and facility investments), enabling you to stress-test your strategy against likely competitive responses.
- M&A and alliance pipeline: a prioritized list of archetypal targets, valuation ranges (methodology only in this preview), and integration playbooks focused on capturing synergies in supply chain, distribution, and R&D.
- Commercial playbooks: segmented buyer-personas, pricing levers, and pilot designs for subscription-based reagent procurement and reagent-as-a-service business models.
How to use this intelligence in 2026 — a three-step decision routine
- Calibrate: Start by aligning your leadership team around the macro growth trajectory and the impact of raw-material volatility. Use our scenario projections to set realistic topline and margin targets for 2026.
- Prioritize: Apply our portfolio prioritization matrix to reallocate R&D and commercial investment toward higher-growth, higher-margin reagent classes and digital-enabled offers. Time-box pilots to the first half of 2026 to test pricing and subscription mechanics.
- Execute & hedge: Commit to at least one supply-chain resilience initiative (dual-sourcing, buffer-stock strategy, or localized manufacturing plan) and one customer-stickiness pilot (digital bundling or reagent-as-a-service) before Q3 2026. The report supplies templates and KPIs to measure outcomes.
What we intentionally do not disclose in this preview
In keeping with the “trailer” principle of this briefing, we demonstrate analytic depth and practical relevance while withholding granular segment-level revenue shares and subregional breakout figures that form the core, actionable intelligence of the full report. If you are evaluating tactical moves — a product launch, acquisition target, or a pricing experiment — those granular figures and the underlying company- and product-level datasets are essential. Our full deliverable includes those specifics plus the model files used to generate the forecast.
Laboratory Chemical Reagents Market
Next steps — how PW Consulting can accelerate your 2026 program
- Executive briefing: a 90-minute, board-level presentation that unpacks the parts of the study most relevant to your objectives and maps immediate actions for 2026.
- Custom deep-dive: targeted modeling (e.g., SKU-level margin impact, M&A target screening, or a supply-chain stress test) using your internal cost and sales data integrated with our market model.
- Implementation sprint: a 6–12 week engagement to operationalize one priority initiative (digital commercial bundle pilot, local manufacturing setup, or an M&A integration plan).
For teams that must make decisive moves in 2026, the PW Consulting Laboratory Chemical Reagents Market study is built to be more than informative — it is a practical operating manual. To access the full dataset, segment-level intelligence, and the downloadable financial forecast model, please visit the report page. Our team is ready to tailor the insights to your use case and convert them into measurable actions.
For detailed analysis of this topic, please visit the official page: Laboratory Chemical Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Protein Bars Market at USD 5,607M in 2025, growing at 6.7% CAGR to 2032
By PW Consulting, 2026-07-23
Protein Bars Market — 2026 Strategic Outlook: Why PW Consulting’s Study Is a Boardroom Imperative
As consumer demand for convenient protein-forward nutrition continues to reshape packaged foods, the global protein bars market has moved from niche sports-fuel aisles into mainstream snacking and meal-replacement occasions. Using 2025 as the base year, PW Consulting’s new study quantifies that transition: the market expanded from roughly USD 4.07 billion in 2020 to about USD 5.61 billion (USD 5,606.7 million) in 2025 and is forecast to reach approximately USD 8.78 billion (USD 8,775.5 million) by 2032, representing a compound annual growth rate of 6.7% over the forecast period. For strategy teams preparing decisions in 2026, those topline trajectories are not an abstract backdrop — they are the frame for investment sizing, product roadmaps, channel allocation, and M&A prioritization.
Protein Bars Market
Why this study matters for 2026 decision cycles
-
Portfolio prioritization under growth constraints: The market’s steady mid-single-digit CAGR signals sustained consumer adoption but also intensifying competition. Firms must choose between expanding SKU breadth to chase microsegments or doubling down on a smaller set of higher-margin, trademarkable formats.
Protein Bars Market -
CapEx and capacity planning for co-manufacturing: With leading brands increasingly outsourcing production, 2026 is a key year to lock capacity or invest in co-packer partnerships to avoid late-cycle bottlenecks as innovation pulses through the category.
Protein Bars Market -
Supply chain and ingredient strategy: The rise of plant-based proteins, specialty fibers (prebiotics), and low-sugar sweeteners creates exposure to concentrated ingredient markets. Securing supply contracts or strategic supplier relationships will materially affect margin sensitivity to raw-material swings.
-
Regulatory and reputational risk mitigation: Emerging class action activity around labeling accuracy underscores the need for robust testing, traceability, and label governance ahead of broader regulatory scrutiny or litigation costs.
Data-driven vignettes that should shape 2026 plays
-
Scale vs. specialization: The market’s growth path — a meaningful uplift from 2020 to 2025 and continued expansion into the early 2030s — favors firms that can pair scalable manufacturing models with product differentiation (texture, function, clean-label claims). The concentration profile is instructive here: the category remains moderately fragmented, leaving space for both national champions and regional or purpose-led challengers to grow.
-
Innovation velocity is high and retail windows are short: Recent launches during early 2026 highlight rapid flavor and format experimentation (multi-layer bars, prebiotic + protein combinations, candy-inspired formulations). Speed-to-shelf and e-commerce rollouts determine whether a concept becomes a platform or fades as a promotional SKU.
-
Label trust is a commercial moat: High-profile testing and litigation over labeling accuracy — including consumer-facing disputes reported in 2025–2026 — convert compliance into competitive advantage. Brands that can demonstrate third-party verification and transparent ingredient disclosure are better positioned to scale premium claims.
What PW Consulting’s report contains (practical, actionable layers)
-
Market sizing and forecast model (2020–2032) with scenario sensitivities — multiple demand curves calibrated to ingredient cost shocks, channel share shifts, and regulation scenarios.
-
Competitive benchmarking dossier — company profiles, capability maps, go-to-market plays, and a proprietary innovation scoring system that ranks product launches by consumer resonance and margin potential.
-
Channel economics deep-dive — detailed CAC/LTV proxies for e-commerce and subscription channels, retail trade-off analysis, and a retailer segmentation matrix for national and regional distribution partnerships.
-
Supply chain playbook — supplier maps for key protein and fiber inputs, cost pass-through sensitivity, recommended hedges, and a co-manufacturer capacity tracker.
-
Regulatory & litigation register — issues to monitor (labeling accuracy litigation, HS code/tariff implications for imports), plus templates for test-and-trace compliance programs.
-
M&A and partnership playbook — valuation benchmarks, earn-out structures, and a shortlist of prioritized targets and potential co-manufacturing partners keyed to strategic objectives.
Note: this public introduction intentionally omits the full, granular breakdowns by region, application, and the detailed subsegment revenue table in order to preserve the proprietary analytical models. Full segmentation and downloadable Excel models are available in the comprehensive report.
Competitive landscape — synthesis and strategic implications
-
Kellogg Company (RXBAR). Strengths: brand clarity around minimal ingredients and high-protein positioning. Strategic implication: incumbent brand equity allows premium pricing but requires continuous scrubbing of ingredient provenance claims to avoid erosion of trust.
-
Clif Bar & Company. Strengths: innovation pipeline and organic credentials. Strategic implication: flavor and format experimentation (e.g., seasonal and co-branded flavors) will continue to drive trial; partners should monitor ingredient sourcing costs tied to organic inputs.
-
ONE Brands (Hershey) & Simply Good Foods (Quest). Strengths: scale, distribution, and strong functional formulations (low sugar, high protein). Strategic implication: these players excel at translating sports-nutrition credibility to mainstream channels; expect further expansion into multi-texture bar formats and channel-exclusive SKUs.
-
Premier Nutrition, KIND, General Mills, Nestlé, Mars. Strengths: broad go-to-market footprints and cross-category marketing muscle. Strategic implication: their moves will define shelf width and trade promotional dynamics; challenger brands should focus on direct-to-consumer stories and niche differentiation.
-
Hearthside Food Solutions & Glanbia. Strengths: manufacturing scale and ingredient supply. Strategic implication: control of co-manufacturing capacity and ingredient supply is a tactical lever — securing these relationships early in 2026 mitigates time-to-market risk for new launches.
Signals from recent activity and what to watch in 2026
-
Product launches in early 2026 demonstrate a bifurcation of the market: one axis pushes indulgent, candy-inspired formats with sports-level protein counts; the other pushes functional nutrition (prebiotics, plant-based proteins, clean labels). Both trajectories will expand the overall addressable market, but they require distinct sourcing and consumer-education investments.
-
Regulatory noise such as labeling disputes has commercial consequences: brands implicated in accuracy claims face rapid retail delisting risk and class-action exposure. Incorporating third-party nutrient testing and robust label governance in 2026 is no longer optional for national brands.
-
Trade technicalities matter operationally: HS code classification continues to govern import duties and logistics cost baselines. For firms that source internationally, small differences in classification can materially change landed costs and shelf pricing strategies.
-
Packaging policy landscape is stable: our scans for 2025–2026 did not identify new, category-specific packaging taxes or labeling mandates — a near-term relief for packaging planners — though plastic reduction and recyclability remain important retailer commitments.
Prioritized 90-day playbook for 2026 (executive checklist)
-
Audit labeling and testing: commission third-party nutrient verification for flagship SKUs and update governance processes to reduce litigation exposure.
-
Lock strategic supply: execute medium-term supply agreements for high-risk ingredients and evaluate dual-sourcing for proprietary plant protein blends.
-
Run a rapid SKU profitability drill: identify the top 20% of SKUs that deliver 80% of margin and accelerate discontinuation or repricing of low-return SKUs.
-
Accelerate direct channels: pilot subscription bundles with premium formats to capture customer lifetime value and reduce reliance on promotional retail economics.
-
Map co-manufacturer capacity: secure guaranteed slots or pursue minority investments in strategic co-packers to avoid late-cycle production scarcity for holiday windows.
Closing: the strategic choice for 2026
For executives building 2026 strategies, the PW Consulting study converts a bullish but competitive growth story into discrete, actionable choices. The market’s steady CAGR and multi-billion-dollar scale create compelling incentives to invest, but the window for establishing durable differentiation (through ingredient integrity, manufacturing security, and channel economics) is limited. This is a category where agile execution — backed by validated demand models, supplier intelligence, and legal-risk mitigation — separates winners from short-lived trend-followers.
To access the full data tables, segmented forecasts, downloadable model, and the exhaustive competitive dossier that underpins these recommendations, please consult the complete PW Consulting Protein Bars Market report. The public executive summary intentionally omits the full segment-level tables to preserve the proprietary scenario models and Excel workbooks available in the main study.
For detailed analysis of this topic, please visit the official page: Protein Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Methyl Diethanolamine Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-23

Methyl Diethanolamine (MDEA) Market — Strategic Outlook for 2026 Decision-Making
Executive trailer: why PW Consulting’s MDEA study matters for boards and strategy teams in 2026
As energy markets reconfigure and industrial decarbonization accelerates, Methyl Diethanolamine (MDEA) has re-emerged as a strategic intermediate for both conventional and transition-era value chains. Our market model shows the global MDEA market expanding from approximately USD 215.0 Million in the base year 2025 to an estimated USD 234.46 Million in 2026, tracking a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast horizon and reaching roughly USD 344.8 Million by 2032. These macro dynamics deliver a clear signal: 2026 is a pivotal year for commercial positioning — firms that act now to secure cost, capacity and specialty-product routes will shape competitive economics for the remainder of the decade.
Methyl Diethanolamine Market
What this briefing delivers (and what we deliberately withhold)
-
We present a concise synthesis of the market drivers, supplier behavior, and pricing dynamics that will shape 2026 sourcing and investment decisions.
Methyl Diethanolamine Market -
The full PW Consulting report contains granular intelligence — regional and application-level demand breakdowns, supplier scorecards, price time-series, and client-ready scenario models. To preserve the actionability of that proprietary content and in keeping with the “trailer” approach, we intentionally withhold the core segmented tables and supplier share matrices here. Those datasets are included in the full deliverable and are the primary reason procurement and strategy teams subscribe.
Methyl Diethanolamine Market
Data-driven snapshot: growth trajectory and implications
Between 2020 and 2025 the market exhibited moderate cyclical behaviour before accelerating into 2025. Our forecast anticipates a continuation of that momentum into 2026 and beyond: the market increases materially in 2026 versus 2025 and follows a near-7% CAGR through 2032. For executives, the implication is twofold — near-term demand upticks require immediate mitigation of supply and price exposure, while the multi-year growth profile justifies strategic investments in capacity, specialty grades and vertical integration where economics permit.
Supply-side dynamics and pricing pressure — the short-to-medium term
Raw material availability and logistics continue to be the dominant near-term drivers. In March 2026, a leading global supplier adjusted amine pricing upwards in response to logistics and feedstock cost increases. That move crystallizes a broader market tendency: suppliers with feedstock integration or advantaged logistics are exercising pricing power when markets tighten. For buyers, this translates into higher likelihood of periodic price spikes, contract renegotiation points, and the need for hedging strategies beyond standard annual contracts.
Demand-side evolution — traditional and emergent use cases
MDEA’s role in acid gas removal and other gas-treatment applications remains the largest anchor of demand. Simultaneously, secondary industrial users — from certain chemical intermediates to process-engineering applications in refining and petrochemicals — are contributing stable baseline consumption. Looking ahead, two themes merit attention: (1) the energy transition is changing synergies between conventional gas treatment and low-carbon fuel processing, and (2) specialty MDEA grades are being developed to meet tighter performance requirements in CO2 capture and hydrogen-related processing. These trends raise product-differentiation value and create pockets of higher-margin demand.
Competitive landscape — leaders, challengers and regional suppliers
The market structure is characterized by a mix of global majors and regional producers. Global integrated chemicals companies retain advantages in scale, backward integration and international logistics; specialist chemical players differentiate on product grades and technical service. Key players referenced in our study include:
-
BASF SE (Ludwigshafen, Germany) — a leading producer of alkylethanolamines, with broad application coverage across gas treatment and petrochemicals.
-
Dow Inc. (Midland, Michigan, USA) — supplies MDEA under established brand lines and focuses on scale solutions for acid gas removal in oil & gas.
-
Huntsman Corporation (The Woodlands, Texas, USA) — offers commercial and specialty grades tailored for gas treatment performance.
-
Eastman Chemical Company (Kingsport, Tennessee, USA) — positions specialty MDEA offerings for industrial applications.
-
Advance Petrochemicals Ltd. and other regional suppliers in India, Russia and China — provide competitive regional supply and export options, often serving price-sensitive customers or niche regional demand.
For incumbents and new entrants alike, three competitive facts stand out: technical support and specialty grade portfolios drive premium placement; logistics and feedstock access determine cost competitiveness; and reputation in regulatory compliance and product stewardship reduces commercial friction, particularly for cross-border supply.
Strategic options for 2026 — what boards and procurement chiefs should consider now
-
Short-term (0–6 months): implement layered procurement strategies combining spot coverage, medium-term contracts with indexation clauses tied to feedstock indicators, and selective use of physical inventory buffers at strategic nodes—ports or inland terminals—to dampen price volatility.
-
Medium-term (6–18 months): evaluate supplier consolidation and collaborative development agreements for specialty grades; pursue long-lead-time supply agreements with performance SLAs; run reverse auctions only where service intensity is low and logistics predictable.
-
Long-term (18–36 months): consider downstream integration or minority stakes in regional producers where access to feedstock or logistics bottlenecks justify capital deployment; prioritize investments that secure specialty-product capabilities supporting low-carbon pathways (e.g., CO2 capture compatibility, hydrogen process resilience).
Operational playbook included in the full report
The full PW Consulting MDEA market study is built as a decision-support toolkit. Key operational deliverables include:
-
Proprietary demand-supply model with base-year calibration (2025) and forecast to 2032, enabling scenario runs under alternative energy and feedstock assumptions.
-
Price-formation tracker that correlates MDEA contract levels to petrochemical feedstock indices and reported logistics-cost movements — useful for contract indexation design.
-
Supplier scorecard and due-diligence framework covering capacity, feedstock integration, geographic reach, quality certifications and commercial flexibility. (Note: full scorecards and supplier share matrices are available only in the paid report.)
-
Go-to-market playbooks for producers and procurement teams: GTM for specialty grades, regional market-entry checklists, and CAPEX/OPEX benchmarks for greenfield and brownfield options.
-
Regulatory and compliance compendium covering typical registration pathways, transport classification considerations and environmental permitting risks that materially affect time-to-market.
Scenario planning — how to stress-test 2026 decisions
Our analysis recommends three practical scenarios you should use to stress-test plans:
-
Demand shock (e.g., accelerated hydrogen and CO2 capture projects): tests the ability to supply specialty grades at scale and the value of long-term collaborative development agreements.
-
Supply shock (e.g., feedstock disruption or logistics constraints): evaluates inventory policies, alternative sourcing corridors and the economic case for nearshoring or vertical integration.
-
Price escalation (e.g., sustained petrochemical cost inflation): quantifies margin erosion across contract profiles and the efficacy of different indexation and hedging structures.
Research rigour and credibility
The report is grounded in a transparent methodology: base-year 2025 calibration, historical analysis 2020–2025, and a 2026–2032 forecast window built from bottom-up demand modeling and supply-side capacity mapping. Inputs include primary interviews with producers, third-party logistics providers, and end-users; contract and tender intelligence; and triangulation against public financials and trade flows. Where supplier statements exist (for example, the March 2026 pricing move by a major supplier), we treat them as directional signals and reconcile them with market-level balances to avoid single-source bias.
Next steps — how to convert insight into action in 90 days
-
Request the full PW Consulting MDEA dataset and supplier scorecards to validate existing contracts and identify immediate supply-risk exposures.
-
Run at least two internal scenario stress-tests using the PW Consulting modeling templates: one focused on procurement/cost and one on product-development timelines for specialty grades.
-
Engage potential pipeline partners for co-development of higher-performance MDEA grades where line-of-sight demand exists in hydrogen or CCUS applications.
Conclusion — the strategic inflection in 2026
2026 represents the hinge-year where tactical procurement and strategic investment choices will compound into long-term competitive advantage. With the market already expanding into 2026 and a near-7% CAGR projected through 2032, the decisions you make this year about suppliers, contracts, and specialty-grade development will determine cost structure and market access for years. PW Consulting’s full MDEA report equips leaders with the quantitative models, supplier intelligence, and contractual playbooks necessary to convert that market growth into durable advantage. Access the complete research to unlock the segmented insights and supplier-specific recommendations that are intentionally omitted from this high-level briefing.
For detailed analysis of this topic, please visit the official page: Methyl Diethanolamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

AMOLED Market 2026: Strategic Preview
As AMOLED moves from niche premium panels to mainstream display real estate across consumer electronics, wearables and automotive cockpits, corporate strategies formed in 2026 must account for a market that is both growing rapidly and structurally changing. Our PW Consulting AMOLED Market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—shows the industry expanding at a compound annual growth rate of 9.75%. The market size crossed the USD 25 billion threshold in 2025 and is projected to rise meaningfully in 2026 and beyond. This preview explains why that trajectory matters for the decisions you will make this year, what levers truly move value, and how our full report equips decision-makers with the practical tools to act.
AMOLED Market
Why this market matters for 2026 corporate strategy
-
Acceleration into new form factors: Long-lifespan investments in foldable, flexible and automotive AMOLEDs are reshaping product roadmaps. Technology maturation is compressing the cost-per-panel curve and enabling new premium product tiers—creating both opportunity and incumbent risk for OEMs and Tier-1 suppliers.
AMOLED Market -
Profit pools are shifting: The CAGR near 10% compounds across adjacent categories (wearables, laptops, automotive), driving non-linear upside for companies who capture higher-margin design wins while maintaining supply resiliency.
AMOLED Market -
Concentration and competitive dynamics: The market exhibits significant concentration among a small group of manufacturers, making supplier strategy and partner selection central to go-to-market and cost control decisions.
What our analysis delivers (operationally focused)
The PW Consulting AMOLED Market report is intentionally practical. We translate market dynamics into actionable outputs designed for boardrooms and strategy teams preparing 2026 plans:
-
Forward-looking demand modeling calibrated to technology adoption curves and substitution dynamics across device classes. (The model uses 2020–2025 historicals and projects through 2032.)
-
Supplier risk heatmaps and a procurement playbook: scoring suppliers on capacity, technology readiness, IP exposure, geographic concentration and cost curve sensitivity.
-
CapEx prioritization toolkit for OEMs and fabs: scenario-based spend allocation that quantifies payback periods under alternative volume and price assumptions.
-
Commercial negotiation templates: term-sheet priorities, royalty versus volume tradeoffs, and clauses tailored to protect OEMs against supply shocks and raw-material price volatility.
-
M&A and partnership criteria: an integrative framework for assessing strategic acquisitions, joint ventures and minority investments—prioritizing IP, process know-how and customer pull-through.
-
Gated appendices containing granular segmentation tables, regional buildouts and unit economics; these detailed exhibits are available only in the full report to preserve competitive confidentiality.
Key narrative themes you need to embed into 2026 planning
-
From component scarcity to commodity dynamics: Select raw materials remain a differentiator. For example, OLED glass substrates are commanding a material premium versus legacy LCD substrates due to tighter surface roughness requirements—this is a structural input cost that affects margin sensitivity across the value chain.
-
IP and licensing are no longer background noise: Cross-licensing and patent access materially influence who can scale production fastest. Recent licensing developments have already altered strategic options for major Chinese producers, and IP availability will shape supplier selection and joint-development approaches in 2026.
-
Geopolitics as an operational constraint: Export controls and trade policy on high-purity precursors and advanced materials introduce non-linear supply risk that must be modeled into sourcing and contingency strategies.
-
Product differentiation versus cost economics: The premium for ultra-thin, foldable or QD-enhanced AMOLEDs is weakening as process maturity increases—this signals a window for differentiation-led revenue capture before commoditization accelerates.
Competitive landscape — what the leaders are doing (high-level synthesis)
The AMOLED value chain is dominated by a handful of deeply vertically-integrated suppliers who combine material engineering, panel fabs and advanced module assembly. Our report profiles the strategic positioning and go-to-market moves of the leading players and synthesizes implications for OEMs, investors and suppliers.
-
Samsung Display (Yongin, South Korea): The volume leader, with investments across flexible, rigid, QD-OLED and foldable panels. Recent 8.6-generation IT line activity and sample shipments for laptop-class displays underscore a push into new premium form factors. For decision-makers, Samsung’s scale means both dependable supply for high-volume programs and a benchmark for cost and performance.
-
LG Display (Seoul, South Korea): Positioned around tandem and WOLED technologies that serve TVs, auto and selected mobile segments. Its technology roadmap influences premium large-format use cases and provides a counterweight to smartphone-centric strategies.
-
BOE Technology Group (Beijing, China): Aggressively scaling flexible and foldable capacity while refining structural and material solutions for seamless form factors. BOE’s trajectory matters particularly for customers seeking alternative volume sources and for competitive pricing dynamics.
-
AUO Corporation (Hsinchu, Taiwan) and Visionox (Shenzhen, China): These players are active in consumer and automotive AMOLEDs and increasingly focused on niche differentiation (e.g., automotive-grade durability, high-resolution wearables). For OEMs, they represent potential strategic partners for localized sourcing and bespoke product development.
Our report includes a vendor scorecard that synthesizes financial metrics, technology depth, IP posture, capacity roadmaps and recent product developments; it is specifically designed for use in RFPs and supplier selection workshops.
Supply-chain and materials: practical considerations
-
Cost structure sensitivity: The cost of specialty substrates and high-purity precursors is a primary driver of margin variance between suppliers. Corning’s introduction of ultra-thin glass for foldables is an example of upstream innovation that changes the technology and cost equations.
-
Concentration risk and contingency planning: With a relatively concentrated manufacturing base among top producers, buyers should develop multi-sourcing plans, pre-qualified second-tier suppliers, and inventory buffers that are modeled against plausible export-control scenarios.
-
Negotiation levers: Long-term offtakes, technology-sharing agreements and collaborative R&D can be used to secure capacity at predictable economics. Our model quantifies the tradeoffs between price concessions and supply certainty under multiple scenarios.
Actionable frameworks in the full study
For teams executing strategic choices in 2026, the report provides several plug-and-play frameworks:
-
Scenario engine: Three pragmatic scenarios (Base, Acceleration, Disruption) that stress-test demand, price and input-cost volatility through 2032. Each scenario maps to recommended commercial, operational and investment responses.
-
Supplier scorecard and RFP template: Weighted criteria tailored to AMOLED (process maturity, qualification time, IP risk, geographic exposure, cost curve) so procurement can move beyond price-only selection.
-
CapEx decision matrix: Stepwise guidance for fab expansion versus outsourcing—incorporating payback thresholds, strategic control needs and technology obsolescence timelines.
-
M&A playbook: How to value targets with manufacturing capabilities versus pure-play IP providers, including integration risks that historically cause value leakage.
Signals to watch in 2026 (for executive dashboards)
-
Rate of adoption for laptop and automotive AMOLEDs—early design wins and announced production starts are leading indicators of mainstreaming beyond smartphones.
-
Material cost spreads—substrate and precursor price movements will flow directly into supplier margins and final product economics.
-
Patent licensing news and cross-licensing arrangements—these can reconfigure competitive advantage overnight.
-
Trade-policy developments affecting critical inputs—export controls or new tariffs materially increase the value of onshore or nearshore capacity.
Why PW Consulting’s AMOLED Market study is strategically valuable in 2026
We balance rigor with operational utility. The study couples a granular demand forecast (built from 2020–2025 historicals and projected through 2032) with a toolbox that executives can act on this year: supplier selection, capex prioritisation, M&A screening, commercial contracting and contingency planning. Importantly, the report is constructed as a decision-support package—not merely descriptive intelligence—so teams can run “what-if” analyses and convert insights into board-level choices within weeks.
Note: This preview highlights high-level findings and strategic levers. The full PW Consulting AMOLED Market report contains the detailed segmentation, region- and application-level modeling, and Excel-based scenario models that underpin the conclusions summarized here. Access to those detailed exhibits and vendor-level scorecards is available through our report portal.
Next steps
-
If you are planning product launches, supply agreements or capex commitments in 2026, schedule a briefing with our AMOLED practice to run the scenario engine against your specific P&L and product roadmap.
-
For procurement and strategy teams, request the supplier scorecard and RFP templates to accelerate a defensible, risk-aware sourcing process.
PW Consulting’s AMOLED Market study is designed to convert market intelligence into executable strategy. In an industry where material innovation, IP posture and geopolitical developments intersect, the right analysis in 2026 will distinguish winners from followers. Contact our team to unlock the full dataset, models and proprietary vendor assessments.
For detailed analysis of this topic, please visit the official page: AMOLED Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Offshore Patrol Vessels Market Poised for 4.65% CAGR, Reaching USD 304.52M by 2032 - PW Consulting
By PW Consulting, 2026-07-23

Offshore Patrol Vessels Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The Offshore Patrol Vessels (OPV) market occupies a distinct niche at the intersection of maritime security, sovereign fleet modernisation, and civil maritime services. Our latest market model — base year 2025, historical series 2020–2025, and a forward-looking forecast through 2032 — shows an established growth trajectory with a compound annual growth rate (CAGR) of approximately 4.65% in revenue terms (USD Million). PW Consulting’s topline time series frames the market from an estimated global aggregate in 2020 of USD 178.26 Million to USD 223.42 Million in 2025, with a projected climb to roughly USD 304.52 Million by 2032. These macro-dynamics reflect persistent procurement programmes, design modularity adoption, and increasing emphasis on long-endurance multi-mission platforms.
Offshore Patrol Vessels Market
Why this preview matters for 2026 decision-makers
-
Timing of procurement windows: 2026 is shaping up as a nexus year for national OPV programmes and export opportunities. With several recent launches, deliveries and contract awards validating market momentum, procurement lead-times and industrial capacity will determine winners across supply chains.
Offshore Patrol Vessels Market -
Investment prioritisation: Naval and coast guard authorities must balance capability upgrades (e.g., sensors, mission modules, aviation facilities) against lifecycle cost pressures and emissions regulations. Our analysis provides scenario-tested trade-offs that are immediately actionable for 2026 budget cycles.
Offshore Patrol Vessels Market -
Industrial strategy: Shipyards and systems integrators face a strategic choice between platform specialisation and modular, exportable families. The market’s measured growth and concentration dynamics indicate both opportunistic mid-size suppliers and a small set of scale players will shape supply-side outcomes.
What PW Consulting’s full study delivers (practical, actionable content)
This preview highlights the strategic contours; the full PW Consulting OPV Market report is structured for executives who must make 2026-capable decisions. Key actionable deliverables include:
-
Top-down valuation model and bottom-up validation: A reconciled market sizing from 2020–2032 that traces procurement pipelines, retrofit programmes and export prospects. The report exposes demand drivers and overlays scenario stress-tests for alternative geopolitical and fiscal outcomes.
-
Procurement and programme timelines: A prioritised matrix of live programmes, planned procurements and fleet replacement windows — enabling procurement offices and prime contractors to map opportunity capture strategies into 2026 funding cycles.
-
Risk-adjusted supplier scorecards: Comparative evaluations of manufacturing footprint, modular design capability, systems integration track record, and aftermarket readiness. These scorecards are calibrated for use in supplier selection and JVs.
-
Technology & regulation playbooks: Detailed guidance on integrating emissions-compliant propulsion, anti-pollution systems, aviation facilities and mission modules — with retrofit pathways and capex–opex trade-offs tailored to common OPV mission sets.
-
Commercial strategies: Pricing benchmarks, contract structure templates, and financing approaches (including export credit and offsets). The study includes negotiation levers for 2026 contract cycles to limit exposure to steel/aluminum price volatility and lead-time risk.
-
Shortlists and go-to-market pathways: Prescriptive recommendations for prime contractors, Tier-1 suppliers and regional shipbuilders on partnership models, IP strategies, and capability investments that will be rewarded in 2026 procurement rounds.
Market structure and competitive dynamics
The OPV market displays a moderate degree of concentration: our market concentration metrics indicate the top three firms account for c.45.6% of the market while the top five command approximately 68.2%. This structure creates distinctive strategic opportunities — incumbents can leverage scale, whereas well-positioned challengers can win via design specialisation, modular offerings and export-focused pricing.
-
Damen Shipyards Group (Gorinchem, Netherlands): Known for scalable OPV families — including military and coast guard variants — Damen’s strength lies in modular architecture that supports multi-mission profiles such as EEZ surveillance, SAR and fisheries protection. Strategy: pursue platform variants that reduce unit production costs while maximising export appeal.
-
Lürssen (Lemwerder, Germany): A premium naval builder with PV80-class OPVs and key naval platforms (notably variants used in Australia). Strategy: continue capturing niche high-spec contracts where sovereign requirements prioritise performance and domestic industrial offsets.
-
Fincantieri (Genoa, Italy): The PPX next-generation OPV family demonstrates integration of coastal surveillance, anti-pollution capabilities and aviation facilities aligned with contemporary regulatory expectations. Strategy: capitalise on proven naval-class launches to expand into allied export markets.
-
Austal (Fremantle, Australia): Developer of Offshore Patrol 60 derivatives and evolved Cape-class platforms; Austal’s competitive edge is aluminium construction and rapid delivery cycles. Strategy: double down on border-force and rapid-delivery contracts, and offer integrated sustainment packages.
-
Hyundai Heavy Industries (Ulsan, South Korea): Builds large OPVs optimized for long-endurance patrols; recent early deliveries highlight supply-chain execution. Strategy: translate shipyard scale into competitive delivery guarantees and modular mission-fit options for regional partners.
-
Jong Shyn Shipbuilding Company (Taiwan): Regional specialist producing coast-guard OPV classes. Strategy: exploit domestic and regional demand with cost-competitive solutions and shorter lead times.
-
OCEA (France): Supplier of bespoke OPVs to coast guard customers and smaller navies. Strategy: target niche markets requiring fast-build composite-hull solutions and integrated maritime systems.
Recent developments shaping 2026 opportunity windows
-
Austal — May 2026: Awarded contract for additional patrol boats for an Australian border agency, underscoring continued appetite for rapid-delivery, aluminium-hull solutions and border-centric mission sets.
-
Fincantieri — Feb 2026: Launched the first PPX next-generation OPV for the Italian Navy, validating design choices that integrate anti-pollution systems and helicopter facilities — features now expected in many European programmes.
-
Hyundai Heavy Industries — Feb 2026: Early delivery of a Rajah Sulayman-class OPV to a Southeast Asian navy, signalling robust project execution capabilities and reinforcing trust in large-scale, long-endurance platforms.
Dynamics and tailwinds (what’s moving the market)
-
Regulatory pressure and capability expansion: Emissions standards and coastal safety regulations are driving the adoption of cleaner propulsion solutions and integrated anti-pollution systems. OPV programmes increasingly include aviation-capable decks and mission module spaces as baseline requirements.
-
Material and design choices: Steel and aluminum remain the dominant build materials; choices here materially affect unit cost, maintenance profile and mission endurance. Aluminium designs — when coupled with simplified mission fit-outs — enable faster, lower-cost patrol fleets for perimeter security roles.
-
Sensor and mission systems convergence: Advanced acoustic detection suites and modular mission bays are enabling OPVs to undertake roles once reserved for larger surface combatants, including limited ASW and sophisticated domain awareness tasks.
-
Delivery and certification premium: Early-delivery track records increasingly factor into bid evaluations. Shipyards that can demonstrate adherence to updated maritime security certifications materially improve their selection odds.
Strategic recommendations for 2026
For public-sector buyers, shipyards and systems firms, 2026 is the year to convert planning into competitive advantage. Below are priority-focused, executable actions we recommend:
-
Close capability gaps now: Map legacy fleet gaps against the report’s mission taxonomy and commit to modular upgrades that defer platform replacement costs while enabling 2026 procurement options.
-
Lock long-lead suppliers: Steel/aluminum price volatility and electronics lead-times are non-trivial. Secure critical suppliers and long-lead items under conditional purchase agreements to protect 2026 build schedules.
-
Pursue modular IP partnerships: If you are a mid-sized shipbuilder, partner with sensor and mission-module integrators to offer certified “kit” solutions that reduce integration risk and time-to-field for buyers.
-
Use performance-based contracting: For sustaining capability within constrained budgets, structure contracts that incentivise lifecycle performance (availability, mean time between failures) rather than just unit price.
-
Resource the sustainment offer early: Aftermarket and in-theatre support increasingly determine total cost of ownership. Build credible sustainment packages into bid proposals for 2026 award competitiveness.
Conclusion — the strategic value of this research for 2026
PW Consulting’s OPV market study gives executives the quantitative market map, procurement intelligence and supplier-grade playbooks necessary to act decisively in 2026. The market’s steady CAGR, multi-year demand visibility and moderate concentration create differentiated pathways for incumbents and challengers alike. Our full report turns the previewed insights into transaction-ready recommendations, supplier shortlists, and negotiation levers designed for immediate deployment in 2026 procurement cycles.
To access the in-depth segmentation tables, proprietary programme timelines, supplier scorecards and the full set of scenario models that underpin these conclusions, please visit the PW Consulting report page and download the complete Offshore Patrol Vessels Market study.
For detailed analysis of this topic, please visit the official page: Offshore Patrol Vessels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Offshore Supply Vessel (OSV) Market — Strategic Outlook for 2026 Decision-Making
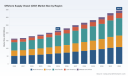
As companies prepare capital plans, charter strategies, fleet renewal programs, and M&A roadmaps for 2026, the Offshore Supply Vessel (OSV) market presents a mix of cyclical recovery, structural scarcity and regulatory disruption. PW Consulting’s latest OSV market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) synthesizes a proprietary bottom‑up dataset and scenario modelling to translate market movements into operational and transactional imperatives. The headline trajectory is clear: the OSV market is expanding from roughly USD 215.0 Million in 2025 toward an anticipated USD 344.8 Million by 2032 at a compound annual growth rate (CAGR) of approximately 6.98%. This growth profile is the backdrop against which every strategic decision in 2026 should be judged.
Offshore Supply Vessel (OSV) Market
Why this study matters to 2026 decision-makers
-
Timing capital deployment: With the market already recovering from mid‑cycle troughs observed during 2020–2023, the projected near‑term uptick in 2026 and beyond creates discrete windows for newbuilds, retrofits and second‑hand acquisitions. Our forecast, modelled through 2032, quantifies the payoff curves for different timing and specification choices.
Offshore Supply Vessel (OSV) Market -
Asset‑level value drivers: Structural supply constraints — reflected in an exceptionally light combined PSV/AHTS orderbook relative to the live fleet — combine with an ageing fleet to support asset value upside for modern, compliant vessels. Operators and investors who understand which technical attributes drive hire and utilisation premiums will gain asymmetric returns.
Offshore Supply Vessel (OSV) Market -
Regulatory and technology risk: IMO GHG guidance, national emissions mandates (notably in Norway and the UK), and updated OSV Chemical Code requirements are rapidly altering the permissible specification set for commercial operations. The study translates regulatory change into retrofit economics and operational thresholds.
-
Competitive positioning in a fragmented market: With the market concentration metrics indicating a fragmented supply base (CR3 ~24.6%; CR5 ~26.2%), there is significant room for consolidation, niche specialization and differentiated service propositions.
What the PW Consulting OSV study delivers (practical, transaction-ready deliverables)
-
Transparent market model: An unlocked Excel model covering historical 2020–2025 performance and base‑case, upside and downside forecasts for 2026–2032, with driver-level levers (dayrates, utilisation, retirement schedules, newbuild delivery phasing and fuel/regulatory cost pass‑through).
-
Scenario analysis & stress testing: Three investment scenarios calibrated to energy price regimes and offshore project activity: conservative recovery, demand acceleration (wind + subsea), and prolonged soft patch — each showing implications for asset values and charter markets.
-
Regulatory impact matrix: A practical, jurisdiction‑by‑jurisdiction assessment (including emerging rules in Norway, the UK and IMO guidance) mapping compliance triggers to retrofit timelines, projected costs and operational constraints.
-
Vessel TCO and retrofit playbooks: Total cost of ownership templates for common OSV vintages and specifications, retrofit decision trees (hybridization, scrubbers, fuel conversion, DP upgrades) and estimated payback bands under alternative employment scenarios.
-
Fleet & orderbook analytics: A dynamic registry of active fleets, age profiles, and orderbook status that identifies short‑listed acquisition targets, build capacity constraints and yard risk points (note: granular regional/type/application splits and vessel lists are reserved for the full dataset).
-
Competitive and commercial benchmark: Benchmark dayrate bands, utilization envelopes, contract structures and tender checklists to support chartering negotiations and procurement decisions.
-
M&A and JV playbook: Screens for identifying consolidation targets, partnership structures for market entry, and a valuation template tuned to OSV cash‑flow peculiarities and charters of varying tenor.
-
Decision dashboards: Executive one‑page heatmaps for board review, investor memos for fundraising rounds, and an operations checklist for yard and retrofit programs.
Market dynamics shaping 2026 choices
-
Demand drivers: The post‑2023 recovery is supported by a mix of resumed deepwater oil & gas activity, accelerated offshore wind build‑out in select geographies, and a steady slate of subsea projects. These demand streams create differentiated requirements by vessel capability (dynamic positioning, cargo capacity, chemical carriage capability), which our study maps to dayrate and utilization outcomes.
-
Supply constraints and fleet age: The combined PSV/AHTS orderbook is unusually light relative to the live fleet, creating near‑term structural scarcity. Simultaneously, major owners operate fleets that skew toward mid‑teens average ages, prompting accelerated retirements or capital‑intensive upgrades — a critical triage question for owners and financiers.
-
Regulation and emissions: Newbuilds and retrofits increasingly aim to exceed minimum compliance (OSV Chemical Code, national emissions rules), while IMO guidance on GHG reduction incentivizes hybridization and alternative fuels. Operators must weigh upfront retrofit capex against potential market access restrictions and charter premium capture.
-
Technology and specification premium: Hybrid propulsion, methanol‑capable engines, higher automation, and enhanced DP systems now command measurable commercial premiums in many contracts. The study quantifies those premiums across employment profiles and regulatory regimes.
-
Yard capacity and supply chain: Shipyard capacity for high‑spec OSVs is constrained. Recent newbuild activity and launches indicate yard activity is restarting, but lead times remain material and sensitive to commodity and steel cost cycles.
Competitive landscape — what the major players are doing and what it means
-
Edison Chouest Offshore (US): Operates one of the largest fleets of PSVs and AHTSs with high‑spec vessels supporting deepwater drilling and cargo operations. Their scale and technical depth make them a natural counterparty in long‑term charter markets and a bellwether for dayrate recovery.
-
Tidewater Inc. (US): Maintains an extensive PSV footprint across traditional basins. Tidewater’s regional diversification and platform supply expertise underscore the resilience element in charter contract design.
-
Bourbon Corporation (France): Focuses on internationally certified PSVs and AHTSs with specialization in cargo handling and offshore support — a competitive archetype for premium international contracts.
-
DOF Group (Norway): Integrates PSV/AHTS operations with subsea and EPCI services, capturing project margins across installation and support value chains; a model we flag for operators seeking to vertically integrate.
-
SEACOR Marine Holdings (US): Advancing hybrid propulsion and chemical‑capable OSV designs that exceed prevailing rules — an example of investment to pre‑empt regulatory risk and win higher specification contracts.
-
Vard Group (Norway): Ship designer/builder focusing on high‑spec solutions for the energy transition; critical partner for investors planning newbuilds with future‑proof specifications.
-
Swire Pacific Offshore (Singapore): Strong Asia‑Pacific presence and platform supply capability in E&P regions, illustrating the geographic playbook for operators balancing regional exposure.
-
Hornbeck Offshore Services (US): Gulf of Mexico and deepwater support specialist — a case study in niche focus and asset utilization optimisation.
-
Havila Shipping ASA and Siem Offshore (Norway): Emphasize safety, efficiency and subsea/platform support — positioning relevant for contracts in high‑regulation basins.
Recent newbuild announcements and launches from regional yards and operators indicate a market in selective reinvestment mode. These developments serve as both a validation of demand recovery and a reminder: newbuilds are being targeted to specific specification sets (hybridization, chemical carriage, DP) that directly influence future hireability and resale value.
Strategic implications and recommended actions for 2026
-
Undertake an immediate fleet triage: Use TCO and retrofit playbooks to classify vessels into retrofit‑worthy, trade‑sale, or recycle buckets. Prioritise conversions that unlock market access in high‑regulation basins.
-
Lock in scarce capacity selectively: Given limited newbuild supply, consider forward purchasing, strategic charters or yard options to secure future delivery slots for high‑spec units.
-
Pursue focused consolidation or JV strategies: The fragmented CR3/CR5 landscape creates pockets of opportunity for roll‑ups or strategic alliances to capture scale economics in management, crewing and procurement.
-
Embed regulatory scenario planning in bids: Tender and charter proposals should include explicit pricing for emissions and chemical compliance uplift — and contractual clauses to address future regulatory shifts.
-
Use data to de‑risk M&A: Leverage fleet age analytics, historical utilisation patterns and the report’s valuation templates to avoid common overpayments in a recovering market.
Why PW Consulting’s OSV study is the decision‑making tool for 2026
Our study blends a validated, vessel‑level universe with macro drivers and jurisdictional regulatory overlays to produce decision‑grade outputs: invest/not‑invest thresholds, retrofit payback calculators, acquisition target screens and charter negotiation playbooks. We deliberately present executive insights and directional metrics here while reserving our granular splits, vessel lists and transaction‑ready models for the full report package. This is the “preview” — enough to inform strategic intent, but intentionally a doorway to the dataset and templates that finance, operations and strategy teams will use to execute.
To convert the market’s growth profile (USD 215.0 Million in 2025 expanding toward USD 344.8 Million by 2032 at ~6.98% CAGR) into executable value requires the full dataset, tender comparisons, and our scenario models. Access to those deliverables is available through the PW Consulting report portal and will be essential for boards and executive teams finalising 2026 capital and commercial plans.
For detailed analysis of this topic, please visit the official page: Offshore Supply Vessel (OSV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


