



PW Consulting: Worldwide MMP13 Antibody Market to Grow from USD 42.5 Million in 2025 to USD 63.14 Million by 2032 at a 5.82% CAGR
By PW Consulting, 2026-07-15
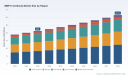
Worldwide MMP13 Antibody Market — Strategic Outlook and 2026 Playbook
PW Consulting today releases a concise executive briefing drawn from our forthcoming Worldwide MMP13 Antibody Market report (base year 2025). The briefing synthesizes what life-sciences leaders must know now to make high-conviction commercial and R&D decisions in 2026. It highlights market scale, growth trajectory, competitive dynamics and the specific, action-oriented analyses included in the full study — while deliberately withholding granular sub-segment datapoints to preserve the report’s commercial value and direct readers to the source for the complete dataset.
Worldwide MMP13 Antibody Market
Market at a Glance — Size, Momentum and Near-Term Trajectory
The global market for MMP13 antibodies has demonstrated steady expansion through the early 2020s and entered 2025 with broad-based demand across academic, biopharma and CRO laboratories. Our consolidated market sizing places the industry at USD 42.5 Million (revenue unit: Million) in 2025 (base year), rising from under USD 38 Million in 2023 and projected to reach approximately USD 44.97 Million in 2026. Over the forecast window 2026–2032, we model a compound annual growth rate (CAGR) of 5.82%, delivering a market exceeding USD 63 Million by 2032 under the base-case scenario.
Worldwide MMP13 Antibody Market
This growth is underpinned by steady investment in extracellular matrix biology, cartilage and wound-healing research, and oncology-focused studies where MMP13 is an important biomarker and research target. The trajectory reflects a blend of incremental replacement of legacy polyclonal reagents with recombinant monoclonals and higher-value validated product formats that command premium pricing.
Worldwide MMP13 Antibody Market
Why 2026 Is a Strategic Inflection Point
- Validation and reproducibility drive procurement: Laboratories and pharma sponsors are increasingly scrutinizing antibody validation. Vendors that can demonstrate orthogonal validation, batch-to-batch consistency and extensive application data will capture outsized share.
- Product differentiation matters: The shift from commoditized offerings toward recombinant and application-validated monoclonals creates margin opportunity for suppliers that invest in characterization and documentation.
- Consolidation and competition: The market shows mid-level concentration among incumbent suppliers, creating both barriers and opportunities — larger suppliers benefit from scale, while specialized players can win through niche validation claims and application-specific kits.
- Regulatory clarity for commercial strategy: All commercial MMP13 antibody products are marketed for research use only (RUO); none are approved for diagnostic or therapeutic use. That regulatory envelope frames commercial claims, labeling and customer segments for 2026 planning.
What the Report Contains — Practical, Transactional and Tactical Deliverables
PW Consulting’s full report is constructed as a practitioner’s toolkit for commercial leaders, product managers, BD teams and investors. It combines rigorous market analytics with executable recommendations, including:
- Comprehensive market sizing and forecasting (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario models (base, upside, downside) and sensitivity testing against pricing, validation uptake and research funding trends.
- End-to-end competitive landscape: vendor profiles, capability matrices, comparative validation footprints, commercial strengths and weaknesses, digital channel performance and distribution strategies.
- Product and technology assessment: monoclonal vs polyclonal economics, recombinant antibody adoption curves, validation and multiplexing opportunities, and the business case for value-added formats (e.g., conjugates, validated kits).
- Go-to-market playbooks targeted to 2026 priorities: academic channels, translational labs, pharma discovery groups and CRO partnerships — with prioritized tactical steps for each channel.
- Commercial intelligence decks: pricing benchmark database, promotional messaging frameworks, AE/clinical sales talking points tailored to RUO constraints, and channel margin modelling.
- Supply chain & manufacturing analysis: recommended sourcing strategies for recombinant production, QC throughput metrics, inventory policies and contract-manufacturing considerations.
- M&A and partnership screening: shortlists of targets and JV models, strategic rationale, and valuation sensitivities tied to market share and growth capture assumptions.
- Primary research appendices: anonymized interview excerpts with leading procurement heads, lab directors and senior R&D scientists; methodology documentation outlining bottom-up and top-down triangulation.
To preserve the commercial integrity of the full intelligence, the report does not give away granular regional or application-level revenue splits in this press release; those detailed breakdowns are available only within the paid study.
Competitive Landscape — Who Matters and Why
Our analysis synthesizes product portfolios, validation claims, distribution reach and reputational capital across leading suppliers. The competitive set includes established reagent powerhouses and specialized antibody providers. Key strategic observations:
- Large-scale reagent platforms (examples include firms with broad catalogues and multi-application listings) leverage global distribution, diverse product types and extensive application notes to win institutional contracts. These firms often lead with volume, service and integration into lab procurement systems.
- Specialist antibody houses differentiate through deep validation data, peer-cited clones and strong reputational pull in specific application areas (e.g., IHC or quantitative ELISA). Their advantage is credibility among demanding academic and translational customers.
- Recombinant antibody adopters are gaining momentum because recombinant formats reduce batch variability and support premium pricing. Vendors that accelerate recombinant development and provide raw-data validation will likely increase realized selling prices and retain customer loyalty.
Representative companies profiled in the report include Abcam, Thermo Fisher Scientific (Invitrogen), R&D Systems (Bio-Techne), Santa Cruz Biotechnology, Cell Signaling Technology, Proteintech, Sigma-Aldrich (Merck), GeneTex, Bioss and Novus Biologicals (Bio-Techne). Each vendor profile in the full report contains headquarters, online presence, signature MMP13 reagents, cited applications, and pragmatic recommendations for how competitors should respond to their strengths.
Strategic Imperatives for 2026 — Recommendations by Function
- Product Management: Prioritize a limited set of validated recombinant clones with orthogonal data across WB, IHC and ELISA. Bundle these with clear validation packages and lot-level QC documentation as a premium offering.
- Commercial & Pricing: Adopt value-based pricing for validated formats; use freemium validation data to accelerate adoption while preserving paid tiers for guaranteed-supply and lot-release documentation.
- R&D and QA: Invest in cross-platform validation and third-party reproducibility studies to reduce customer friction and claims. Create a reproducibility badge program to shorten procurement cycles.
- Supply Chain: De-risk single-source processes; evaluate contract manufacturers for recombinant expression to scale without overinvesting in fixed assets.
- Business Development: Target strategic alliances with CROs and translational centers to embed MMP13 assays into discovery workflows and early translational studies.
- M&A and Corporate Strategy: Use the market’s mid-level concentration as a rationale for tuck-in acquisitions that add validation capabilities, rabbit-to-recombinant conversion expertise, or niche application dominance.
Risk Factors and Mitigants
- Regulatory/Labeling constraints: All commercial MMP13 antibodies are designated for research use only (RUO); vendors must avoid diagnostic claims and align marketing and QC accordingly.
- Reproducibility concerns: Persistent reproducibility issues can depress demand for low-cost, poorly validated reagents. Proactive investment in validation and transparent data mitigates this risk.
- Substitution risk: As recombinant and engineered binders become cheaper, legacy polyclonal formats face erosion. A phased upgrade and trade-in program can protect installed base revenue.
- Funding volatility: Academic and public research funding fluctuations can impact demand; diversifying into CRO and pharma discovery channels cushions sensitivity.
FAQ — Regulatory and Usage Reality Checks
- Are MMP13 antibodies approved for clinical diagnostic use? No. Current commercial MMP13 antibody products are marketed for research use only (RUO) and are not approved for diagnostic or therapeutic procedures in humans.
- What applications are MMP13 antibodies used for? They are used in laboratory settings for applications such as Western blot, immunohistochemistry, ELISA and immunocytochemistry, commonly applied in extracellular matrix and related condition studies.
- Should commercial strategy assume a move into diagnostics? Any transition to diagnostic use would require substantial regulatory engagement, clinical validation and label changes. For 2026 planning we recommend a RUO-centric commercial approach while tracking translational pipelines for future opportunities.
Next Steps — How PW Consulting Can Accelerate Your 2026 Plan
PW Consulting’s full Worldwide MMP13 Antibody Market report contains the proprietary datasets, segment-level detail, vendor scorecards and downloadable financial models you need to execute in 2026. The report’s deliverables include the granular regional and application splits, product-type revenues, vendor market shares and a downloadable Excel model that allows you to run alternative scenarios and stress tests tailored to your business assumptions.
For procurement leads, product managers, BD executives and principal investors seeking to convert insight into action, the report provides both the strategic narrative and tactical playbooks required to win in a market that is growing at a mid-single-digit CAGR but rewarding for those who can prove validation and supply reliability.
Access to the full report, methodology appendix and the Excel model is available via our official publication page. PW Consulting’s advisory team is available for custom briefings and tailored scenario work to harmonize the data with your 2026 go-to-market plan.
For detailed analysis of this topic, please visit the official page: Worldwide MMP13 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Enzymes for Biofuels Market Poised for 6.51% CAGR Through 2032
By PW Consulting, 2026-07-15
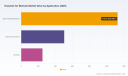
Worldwide Enzymes for Biofuels Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
As governments and corporates accelerate decarbonization objectives, enzymes remain a critical lever to improve yields, reduce costs and lower the carbon intensity of biofuels. PW Consulting’s latest market study, with base year 2025 and a forecast horizon of 2026–2032, models the enzyme market supporting biofuel production as a steadily expanding opportunity. The global market stood at approximately USD 1.89 billion in 2025 and, under our central-case assumptions, is projected to grow at a compound annual growth rate (CAGR) of 6.51% through the forecast period — reaching nearly USD 2.95 billion by 2032. That trajectory reflects both incremental adoption in conventional ethanol and accelerating penetration of enzyme-enabled cellulosic pathways.
Worldwide Enzymes for Biofuels Market
Why this report matters for 2026 strategic choices
- Timing of investment: With near-term regulatory clarifications (notably updated RFS volumes for 2026–2027) and multi-year policy pushes for higher blending of advanced biofuels, 2026 is a pivotal year for capital allocation in enzyme supply, co-location decisions, and long-term procurement contracts.
- Supply-chain exposure: Enzyme manufacturing is feedstock-sensitive — fermentation feedstocks such as glucose (derived from starch) can represent a material share of production cost. Volatility in agricultural commodity markets will influence both margins and supplier selection strategies.
- Consolidation and bargaining: The market exhibits high concentration (top-3 players control a large majority of industry revenue; top-5 players capture an even greater share), so supplier negotiation power, M&A dynamics and strategic partnerships will determine differentiation and access to next-generation biocatalysts.
Market trajectory — a data-driven view without spoilers
Our model synthesizes historical performance (2020–2025) and scenario-tested drivers for 2026–2032 to produce a revenue outlook, whose headline numbers we present here to orient decision-makers. The path to 2032 is characterized by a steady compounding effect from process intensification, incremental pricing power as advanced biofuels scale, and targeted policy support for cellulosic pathways. While we publish full-year-on-year figures and sensitivity runs in the full report, this release intentionally omits granular segment or regional allocations to preserve the commercial value of the underlying datasets.
Worldwide Enzymes for Biofuels Market
What the PW Consulting report delivers (practical, actionable content)
- Transparent methodology: detailed modeling assumptions, sensitivity matrices, and scenario variants (base, policy-accelerated, and low-demand) so executives can map funding and procurement decisions to quantified outcomes.
- Commercial playbooks: go-to-market options for enzyme vendors and biofuel producers — from long-term offtake agreements to performance-based contracting and co-development frameworks.
- Supply-chain and cost benchmarking: factory-level cost breakdowns, raw-material exposure analysis (including the 30–40% typical share of fermentation feedstock costs), and supplier risk heatmaps to support procurement hedging strategies.
- Technology and innovation roadmap: evaluation of enzyme classes (starch-active, cellulases, lipases and engineered biocatalysts), expected cost-performance curves, and time-to-scale implications for next-generation cellulolytic systems.
- Regulatory and carbon-accounting guidance: implications of changing mandates and carbon-credit mechanisms, and practical steps to align enzyme choices with low-carbon fuel standards and voluntary corporate targets.
- M&A and partnership diagnostic: decision frameworks for bolt-on vs. platform acquisitions, JV structures, and licensing models tailored to different corporate objectives (volume scale vs. technology control).
- Case studies and pilot-to-commercial checklists: lessons from operating plants, critical KPIs, and a template for enzyme supplier selection and performance verification.
Competitive landscape — who matters and why
The enzyme-for-biofuels space is dominated by a relatively small set of global specialty players, regional specialists and engineered-biocatalyst startups. Market concentration metrics indicate that incumbent leaders capture the bulk of global revenue, creating high barriers for new entrants but also openings for disruptive technologies that demonstrate step-change economics.
Worldwide Enzymes for Biofuels Market
- Novonesis (formerly Novozymes): A market leader with an end-to-end portfolio for both starch-based and fiber-based ethanol production. Their strength lies in depth of product line (liquefaction, saccharification, biomass conversion), large-scale validation and strong customer servicing capabilities that help mills and biorefineries maximize yields while lowering lifecycle emissions.
- Lallemand Biofuels & Distilled Spirits (LBDS): Expanded rapidly through inorganic growth — most notably the acquisition of BASF’s bioenergy enzymes business in mid-2024 — strengthening its grain-processing enzyme suite and market reach. This move highlights a broader industry trend: consolidation to secure technology pipelines and market access.
- DuPont (Industrial Biosciences / IFF): Focuses on both starch and lignocellulosic solutions, offering product families optimized for industrial-scale hydrolysis and existing supply-chain relationships with major grain processors and ethanol producers.
- Regional and niche specialists (AB Enzymes, DSM-Firmenich, Advanced Enzyme Technologies, Iogen, TransBioDiesel, Enzyme Supplies, Codexis, Amano, Agrivida): These players compete on localized service, specialized product blends, enzyme engineering and application-specific know-how (e.g., lipases for enzymatic biodiesel or engineered cellulases for specific biomass types).
For buyers and investors, the practical implication is clear: strategic sourcing should balance the security and reliability of incumbents with targeted risk bets on engineered or niche providers that can unlock margin or carbon-reduction advantages. The market’s current concentration level means M&A remains an effective route to quick capability acquisition; however, integration complexity and technology transfer risk must be carefully managed.
Market dynamics, risks and regulatory drivers
- Feedstock price volatility: Agricultural commodity price swings directly affect enzyme manufacturers because fermentation substrates (e.g., glucose) are a significant cost input. Producers and suppliers should model counterparty exposure across commodity and energy price scenarios.
- Policy tailwinds: Updated renewable fuel mandates (including the U.S. EPA’s RFS volumes for 2026–2027) and global blending targets materially influence demand for advanced enzymes used in cellulosic ethanol. Strategic engagement with regulators and participation in standard-setting consortia can unlock preferential pathways or credits.
- Technology disruption: Engineered enzymes and on-site enzymatic biodiesel routes (lipase-based transesterification) present alternative value chains. Adoption rates will depend on validated operating cost improvements, enzyme lifecycle economics and capital retrofit requirements.
- Consolidation and supplier power: High market concentration raises counterparty risk for large buyers and creates opportunities for smaller producers to differentiate through service models, performance guarantees and co-development agreements.
Strategic imperatives — practical recommendations for 2026
- Hedge and contract smartly: Negotiate hybrid contracts that combine fixed pricing for baseline volumes with performance-linked adjustments tied to yield improvements and feedstock indices. This mitigates both commodity and technology adoption risk.
- Prioritize piloting for cellulosic enzymes: Allocate dedicated capex for pilot and demonstration-plant runs with multiple enzyme suppliers to de-risk scale-up before committing to full commercial deployment.
- Explore partnership over ownership: For companies lacking deep enzyme R&D, structured partnerships or minority investments in engineered-enzyme specialists can secure preferential access to breakthrough IP without full-scale acquisition risk.
- Integrate carbon economics: Factor carbon intensity reductions from enzyme-enabled yield gains into commercial valuation and contract terms; these can unlock low-carbon fuel credits and improve customer economics.
- Supply-chain resilience: Build a supply-book consisting of a strategic incumbent, a regional specialist and an innovation partner to balance reliability, cost and optionality.
Conclusion and next steps
2026 represents a decision window for industrial-scale biofuel stakeholders: choose too early without adequate piloting and you risk stranded assets; choose too late and you forgo both margin and compliance advantages. PW Consulting’s Worldwide Enzymes for Biofuels Market report provides the operational blueprints, competitive intelligence and financial models required to make these calls with confidence. The summary metrics shared here outline the scale and growth momentum — our full report offers the granular segmentations, regional allocations and vendor-level dashboards that procurement teams, corporate strategists and investors will need to finalize 2026 plans.
Accessing the full intelligence
For executives ready to translate this strategic perspective into action, PW Consulting offers private briefings, customized scenario workshops and access to the complete dataset and model. Visit our report page to view the full table of contents, methodology, and to acquire the complete Worldwide Enzymes for Biofuels Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymes for Biofuels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Copaiba Essential Oil Market to Expand from USD 148.5 Million in 2025 to USD 241.6 Million by 2032 at a 7.2% CAGR
By PW Consulting, 2026-07-15
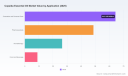
Worldwide Copaiba Essential Oil Market — 2026 Strategic Outlook (PW Consulting)
Executive teaser
PW Consulting’s new market brief, Worldwide Copaiba Essential Oil Market (base year 2025), delivers a concise but rigorous advance view of the competitive, supply-chain and sustainability dynamics that will shape executive decisions in 2026. Built on a historical dataset covering 2020–2025 and forward-looking projections across 2026–2032, the study frames actionable choices for procurement leaders, product strategists and corporate development teams. The global market is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the forecast horizon, expanding from an estimated USD 148.5 Million in 2025 to roughly USD 241.6 Million by 2032. These headline metrics hide important structural shifts; this briefing highlights the implications without revealing the granular segment tables reserved for the full report.
Worldwide Copaiba Essential Oil Market
Why this matters for 2026 planning
-
Strategic timing: 2026 will be the first full planning cycle after multiple recent supply and sustainability initiatives in the Copaiba value chain. Companies that align sourcing, R&D and regulatory readiness now will capture disproportionate share as buyers prioritize traceability and efficacy evidence.
Worldwide Copaiba Essential Oil Market -
Investment prioritization: A steady ~7.2% CAGR implies a market that rewards sustained product development, but success will depend on differentiated value propositions (clinical substantiation, certified sourcing, or formulation superiority) rather than simple volume plays.
Worldwide Copaiba Essential Oil Market -
Risk management: The oil’s Amazon-centric raw-material base creates concentrated upstream exposure. 2026 strategies should treat sourcing certification and community partnerships as operational risk mitigants, not only marketing claims.
Core market trajectory — headline numbers
Our topline model synthesizes historical performance and primary research to produce a conservative-to-moderate scenario baseline. Key snapshot figures (USD Million): 2023 — 130.15; 2024 — 139.10; 2025 (base year) — 148.50; 2026 — 159.19; 2027 — 170.65; 2028 — 182.94; 2029 — 196.11; 2030 — 210.23; 2031 — 225.37; 2032 — 241.60. The implied steady expansion reflects rising demand from personal care and wellness channels, incremental adoption in pharmaceutical applications, and an expanding ingredient role in natural formulations.
Market structure and concentration
Market concentration metrics indicate a moderately fragmented supply base: the combined share of the top three suppliers is in the low‑thirties percent range, while the top five firms account for a figure in the low‑forties percent range. In practice this means there are established global players with differentiated value chains, but meaningful room remains for regional specialists, cooperative-led suppliers and vertically integrated entrants to grow by addressing sustainability and traceability gaps.
Supply-side realities & sustainability dynamics
-
Raw material and processing: Copaiba essential oil is produced by steam distillation of oleoresin tapped from Copaifera species native to the Amazon. The oleoresin-to-oil supply chain is inherently seasonal and localized, which amplifies logistics and quality-control challenges for buyers operating at scale.
-
Sustainability and social impact: Certified and cooperative-based sourcing models have moved from optional to strategic. Recent public initiatives highlight partnerships with Amazon cooperatives, community compensation frameworks and low-impact extraction techniques. Firms that can document sociobiodiversity compliance will lower regulatory friction and unlock premium channels.
-
Regulatory context: Expect increasing scrutiny on claims, chain-of-custody documentation and biodiversity protection. Buyers and brand owners should embed compliance checks into supplier selection, especially when marketing functional or therapeutic benefits.
Competitive landscape — who to watch
The Copaiba market blends global ingredient houses, specialty essential-oil houses, and smaller organic or cooperative suppliers. The following companies are notable participants and illustrate the range of strategies currently in play:
-
doTERRA International (Pleasant Grove, Utah, USA) — Major supplier positioning Copaiba through Co-Impact sourcing partnerships with Amazon communities; product range includes Copaiba Softgels and pure essential oil with a growing emphasis on clinical research.
-
Young Living Essential Oils (Lehi, Utah, USA) — Global aromatherapy leader offering Copaiba distilled from Copaifera trees, positioned heavily for wellness and consumer aromatherapy applications.
-
Beraca (Clariant) (São Paulo, Brazil) — Brazilian origin supplier that emphasizes sustainable sourcing via partnerships with Amazon cooperatives and sociobiodiversity initiatives; focuses on formulations for cosmetics and personal care markets.
-
Berjé Inc. (Carteret, New Jersey, USA) — Specialty supplier leveraging longstanding producer relationships to serve flavor, fragrance and aromatherapy customers.
-
Bontoux S.A. (France) — International producer with capabilities across fragrances, flavors and cosmetic ingredient supply chains.
-
Elixens America / Elixens SA (France / US) — Bulk supplier offering conventional and certified-organic Copaiba oils targeted at F&F and aromatherapy segments.
-
Jedwards International, Inc. (Braintree, Massachusetts, USA) — Bulk supplier focused on natural ingredients for personal care and cosmetics formulations.
-
Kaapi Ingredients (Campinas, Brazil) — Regional producer leveraging Brazil’s biodiversity for domestic and export markets.
-
Mountain Rose Herbs (Eugene, Oregon, USA) — Organic and sustainable botanicals supplier positioned in aromatherapy and herbal product niches.
-
Edens Garden (USA) — Consumer-focused aromatherapy brand emphasizing the soothing and balancing properties of Copaiba in wellness blends.
Recent developments shaping 2026 opportunities
-
September 2025 — Beraca (Clariant) announced an expanded sustainability partnership with Amazon cooperatives, showcasing models that combine fair remuneration, low-impact extraction and community capacity building. This reinforces the commercial value of certified sourcing models when negotiating with global personal-care formulators.
-
September 2025 — doTERRA published a deep-dive human clinical study on Copaiba Softgels exploring cellular, molecular, and microbiome endpoints. Early findings bolster claims-focused product development but also raise the bar for evidence when positioning functional benefits.
What the full PW Consulting report contains (practical toolkit)
The published brief is an executive trailer. The complete Worldwide Copaiba Essential Oil Market report includes tools designed for decision makers who need to move from insight to action:
-
Forecast models (2026–2032) with scenario toggles for demand elasticity, raw-material shocks, and certification premium sensitivities.
-
Supply-chain maps highlighting origin risk, seasonality windows, and logistics choke points from Amazon extraction to global distribution hubs.
-
Regulatory and claims tracker covering biodiversity law, labeling expectations, and clinical-evidence thresholds by market.
-
Sustainability risk matrix and supplier scorecard templates to operationalize third-party audits, community-impact benchmarks and price-premium defensibility.
-
Go‑to‑market playbooks for brands and ingredient suppliers: product positioning, channel segmentation, pricing architecture and promotional evidence strategies (including clinical and consumer studies).
-
Corporate development package: M&A screen, target shortlist methodology and integrated financial models to appraise bolt-on acquisitions or strategic partnerships.
-
Commercial negotiation memo: term-sheet priorities (long-term offtake, traceability clauses, cooperative investment options) and a procurement roadmap for 12–36 month contracting cycles.
How leading firms should think about tactical moves in 2026
-
Procurement: Lock-in diversified origin sources and consider blended contracts that balance certified cooperative supply with scalable bulk channels to protect margins against seasonal shortages.
-
Product development: Prioritize formulations where Copaiba’s unique chemistry creates defensible sensory or functional differentiation; pair formulation work with targeted clinical or mechanism-of-action studies where relevant.
-
Sustainability investments: Treat community partnerships and certifications as strategic assets; they materially reduce supply risk and unlock premium distribution in personal-care and wellness retail accounts.
-
Commercial: Use a multi-tier pricing strategy that reflects certification and documentation levels — enabling both mass-market placement and premium specialty positioning.
-
M&A and partnerships: Screen for regional suppliers with strong cooperative ties or proprietary distillation/quality control capabilities that can accelerate market entry without bearing upstream community-building costs from scratch.
Limitations and where to find the full intelligence
This release intentionally frames the strategic contours, headline forecast and practical implications for 2026 without disclosing the full segmentation tables, regional breakdowns or granular application volumes — elements that are included in the complete report. Those detailed data and the supplier-level scorecards are the decisive inputs for transaction diligence, budgeting and product-line rationalization.
Next steps — how to use this insight
-
For procurement and sourcing leads: request the supplier scorecard annex and the origin-risk heatmap to begin contract restructuring before Q2 2026.
-
For R&D and regulatory teams: access the clinical-evidence appendix to align product claims and trial design with market expectations emerging from recent research initiatives.
-
For corporate development and investor teams: obtain the M&A target list and integrated financial models to fast-track valuations and approach strategies.
PW Consulting’s Worldwide Copaiba Essential Oil Market report is designed to convert market context into executable decisions. To access the full report, including detailed segmentation, supplier scorecards, and the scenario-adjustable forecast models, please visit our official report page for purchase and licensing details.
For detailed analysis of this topic, please visit the official page: Worldwide Copaiba Essential Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Predicts Worldwide Embedded Hypervisor Software Market to Grow at a 7.5% CAGR During 2026–2032
By PW Consulting, 2026-07-15
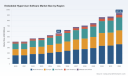
Worldwide Embedded Hypervisor Software Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As embedded systems continue to converge compute, safety, and connectivity at the network edge, the market for embedded hypervisor software is moving from a niche enabling technology to a strategic platform decision for systems architects, OEM executives, and procurement leaders. PW Consulting’s latest market study — the Worldwide Embedded Hypervisor Software Market — sets a data-grounded baseline for those decisions in 2026 and beyond. Our analysis combines historical performance, a seven-year forecast horizon, certification and compliance economics, and vendor-grade competitive intelligence to convert market signals into executable options for enterprise strategy.
Worldwide Embedded Hypervisor Software Market
Why this study matters for 2026 decisions
Two facts frame the urgency for buyers and strategic planners: first, the embedded hypervisor market has demonstrated steady expansion through 2025 and is forecast to sustain a compound annual growth rate (CAGR) of 7.5% over the 2026–2032 period; second, the accelerating regulatory and hardware constraints that govern safety-critical deployments mean that architectural choices made in 2026 will materially affect development velocity, product certification timelines, and cost of ownership through the next hardware refresh cycle.
Worldwide Embedded Hypervisor Software Market
- Market trajectory as a planning anchor: PW Consulting’s base-year assessment positions 2025 as the commercial inflection point for hypervisor adoption across automotive, aerospace, industrial automation, and medical markets; the study projects continued expansion across our 2026–2032 forecast horizon. The trajectory and growth rate serve as the quantitative backbone for five- and seven-year product roadmaps and procurement budgets.
- Certification and compute are gatekeepers: Compliance regimes (DO-178C for avionics, ISO 26262 ASIL D for automotive, IEC standards for industrial and medical) and hardware virtualization features (ARM virtualization extensions, x86 VT-x) are non-negotiable prerequisites. They define which vendors are viable partners and which architectures will dominate future ECU and edge node designs.
What the report contains — practical, executable intelligence
We designed the report for executives who must convert market insight into tactical actions within 90–180 days. Key deliverables include:
Worldwide Embedded Hypervisor Software Market
- Executive dashboards that synthesize market sizing, growth scenarios, and sensitivity analyses to commodity risk, supply constraints, and certification timelines.
- Decision frameworks for mixed-criticality system selection that map hypervisor type, host architecture, and certification path to expected time-to-market and incremental verification cost.
- Vendor evaluation matrices that go beyond capability checklists to include certification pedigree, supported processor families, real-world integration case studies, maintainability score, and ecosystem depth.
- Total cost of ownership (TCO) models that combine licensing, integration effort, certification expenditure, and lifecycle maintenance under alternative hardware and software scenarios.
- Use-case playbooks (automotive zonal ECUs, avionics line-replaceable units, industrial robotic controllers, and medical device gateways) that provide blueprints for architecture, test scope, and procurement language for RFPs.
- Risk heat maps identifying chokepoints — from silicon virtualization feature availability to region-specific certification dependencies — and mitigation options such as multi-vendor architectures and staged certification strategies.
To preserve commercial value for report subscribers, we intentionally withhold granular segment-level tables and precise regional or application dollar allocations in this briefing; the full dataset and downloadable vendor scorecards are provided in the full report package on our website.
Competitive landscape: what market leadership looks like in 2026
The embedded hypervisor market is concentrated, with leading incumbents holding a dominant slice of commercial deployments in safety-critical domains. Competitive advantage coalesces around three attributes: certification pedigree, long-term maintenance and patch pathways for safety artifacts, and deep silicon partnerships.
- Wind River (Alameda, CA) : Known for VxWorks 653, Wind River continues to anchor aerospace and defense relationships with DO-178C DAL A–grade deliveries. Recent product updates extend support to RISC-V and Armv9, signaling a strategic bet on emerging silicon families for safety-critical workloads.
- Green Hills Software (Santa Barbara, CA) : Green Hills’ INTEGRITY and μ-velOSity families emphasize real-time determinism and ARINC 653 partitioning, making them a frequent choice where avionics and industrial timing guarantees are essential. Their differentiation remains strong in deterministic scheduling and isolation assurance.
- Lynx Software Technologies (San Jose, CA) : LynxSecure’s separation-kernel approach and partnerships with silicon vendors (notably an integration push with NXP i.MX RT series) position Lynx well in industrial and edge segments that prioritize a security-first architecture.
- SYSGO (Mainz, Germany) : PikeOS’ multi-certification path across avionics, automotive, and industrial standards remains attractive to OEMs pursuing converged platforms. Recent IEC 62304 Class C certification for medical use cases broadens their addressable opportunity in regulated healthcare hardware.
- Real-Time Systems GmbH (Mittelberg, Germany) : Focused on ARM and x86 embedded virtualization with real-time partitioning, they are notable for streamlined integrations in automotive and industrial IoT projects.
- BlackBerry QNX (Ottawa, Canada) : With QNX Hypervisor’s emphasis on automotive and medical certifications, combined with optimized support for popular AI-capable platforms, QNX remains a default for OEMs seeking ISO 26262 ASIL D compliance on complex ECUs.
- Mentor Graphics / Siemens EDA and ETAS (Bosch Group) : Both bring deep automotive toolchain and AUTOSAR interoperability strengths; their hypervisor offerings are often chosen when upstream tool integration and AUTOSAR compatibility are prioritized.
Recent vendor developments illustrate the market’s technical and commercial dynamics. Notable events include Wind River’s 2025 release extending support to RISC-V and Armv9, SYSGO’s medical certification milestone in early 2025, Lynx’s strategic silicon partnership announced in late 2024, and BlackBerry QNX’s enhanced support for NVIDIA Jetson Orin in 2024 — developments that collectively signal vendor migration toward heterogeneous compute support and vertical certification expansion.
Regulatory, hardware, and standards forces shaping adoption
- Regulatory gating: Certification regimes remain the single most influential adoption factor for safety domains. Compliance with DO-178C for avionics and ISO 26262 ASIL D for automotive is not optional for primary flight or vehicle-control functions — hypervisor selection must align with an auditable certification path.
- Hardware dependencies: Practical Type 1 partitioning increasingly requires processor-level virtualization support (for example, ARM virtualization extensions or x86 VT-x). Where hardware lacks these features, integrators face costly software workarounds, degraded timing guarantees, or outright architectural rejection.
- Standards alignment: ARINC 653 partitioning and related APIs continue to standardize time and space partitioning semantics for avionics. For automotive, AUTOSAR alignment and compatibility with zonal domain controllers are becoming purchasing filters for OEMs.
- Real-time performance caveat: Conventional Type 2 hypervisors (built on general-purpose host OSes) are typically unsuitable for hard real-time embedded tasks due to host scheduling latencies that exceed sub-millisecond determinism requirements — an engineering constraint that shapes architectural choices for mixed-criticality systems.
Strategic recommendations for 2026 — three pragmatic plays
Based on market dynamics, vendor capabilities, and standards pressures, PW Consulting recommends three parallel strategic tracks for executives planning systems and portfolio moves in 2026.
- Certify defensively, choose partners offensively: Select hypervisor platforms with an established certification footprint aligned to your primary safety standard. Where possible, negotiate certification outcome sharing (e.g., leveraging vendor safety artifacts) to reduce your marginal certification expense and accelerate time-to-market.
- Design for heterogeneity: Future-proof platform choices by specifying hardware-agnostic abstraction layers and selecting hypervisors with proven multi-ISA support. Vendors that already support Armv9, RISC-V, and common AI accelerators will reduce migration risk as silicon roadmaps evolve.
- Adopt staged mixed-criticality strategies: For products with both safety and non-safety workloads, use a phased deployment model: begin with hard-partitioned architectures for the safety plane while iterating soft-isolated payload planes. This reduces certification scope for first-to-market variants and enables incremental capability expansion.
How PW Consulting supports your 2026 readiness
Our full report provides the executable artifacts procurement, systems engineering, and certification teams need to operationalize these recommendations: downloadable vendor scorecards, certification cost models, integration risk benchmarks, and templated RFP language optimized for mixed-criticality hypervisor procurements.
Importantly, while this brief highlights high-level market sizing and growth, detailed subsegment breakdowns — regional allocations, application-specific revenue splits, and the full numeric vendor scorecards — are intentionally reserved for report subscribers. Access to those granular tables will materially enhance vendor selection, contractual negotiation, and internal costing exercises.
Next steps
- Download the full report to obtain the segmented datasets, interactive TCO calculators, and vendor scorecards required to finalize 2026 procurement and architecture decisions.
- Engage PW Consulting for a tailored 90‑day assessment: we will map your product line to certification timelines, quantify incremental certification costs under alternate hypervisor scenarios, and produce an executable vendor short list aligned to your silicon roadmap.
Embedded hypervisors are no longer an implementation detail — they are a strategic choice that influences certification, supplier relationships, and product longevity. With a clear market trajectory and actionable vendor intelligence, 2026 is the year to move from ad hoc selections to platform-led strategies that protect safety, accelerate innovation, and manage cost. PW Consulting’s Worldwide Embedded Hypervisor Software Market report is built to be the playbook for that transition.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Telecom Security Software Market Hits USD 15,570 Million in 2025, Poised for 13.01% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Security Software in Telecom: Strategic Imperatives for 2026 — PW Consulting Market Brief
As telecom operators accelerate their transformation into technology-led service providers, security software has moved from a supporting utility to a strategic differentiator. PW Consulting’s latest market study, Worldwide Security Software in Telecom (base year 2025; forecast 2026–2032), synthesizes five years of historical trends and seven years of forward-looking analysis to give executives, technology strategists, and procurement leaders an operationally useful playbook for 2026. The market is projected to expand from USD 15,570 million in 2025 to roughly USD 36,653 million by 2032, representing a compound annual growth rate (CAGR) of about 13.0% across the forecast window — a clear signal that security investment will be a sustained priority as networks scale for 5G, cloud and AI workloads.
Worldwide Security Software in Telecom Market
Executive summary: Why this matters to telecom decision-makers in 2026
- Security is now inseparable from product strategy. Operators packaging cloud, connectivity, IoT and AI services must embed security capabilities to preserve trust, differentiate commercial offerings, and comply with an increasingly intricate regulatory environment.
- Investment momentum is strong. After the market nearly doubled from 2020 to 2025, forecasted growth through 2032 implies not only ongoing demand for traditional network and endpoint controls, but also rising spend on cloud-native, AI-aware, and quantum-resistant solutions.
- Consolidation and specialization coexist. The market shows moderate concentration: the leading vendors retain outsized influence, yet specialist companies continue to win targeted deployments where telecom-specific protocols and traffic patterns matter.
What the PW Consulting report delivers — operational depth without the fluff
Our objective was to build a report that answers the practical questions leaders face when making 12–36 month commitments. The document combines quantitative market sizing and scenario modeling with prescriptive guidance and tools that can be executed by network architects, security teams and procurement groups. Key deliverables include:
Worldwide Security Software in Telecom Market
- Robust market-sizing and trend analysis spanning 2020–2025 and a granular forecasting framework for 2026–2032 (CAGR ~13.0%). We model multiple adoption trajectories tied to 5G monetization, cloud migration velocity, and AI-enabled services.
- Decision frameworks for telco security architecture: migration playbooks from legacy on-premise controls to cloud-native, distributed security fabrics and SASE/SSE models; integration patterns for RAN, core, transport and edge security.
- Vendor assessment matrices and buyer scorecards that combine technology fit, roadmap alignment, integration cost, and geopolitical/regulatory risk. These are scored to support shortlists and RFPs.
- Deployment guides and runbooks that cover phased rollouts, functional validation tests, and operational KPIs to measure security efficacy and business impact.
- Regulatory impact modeling and compliance checklists tailored to prevailing regimes (including EU digital sovereignty measures and upcoming cryptography transitions), helping legal and network teams quantify remediation effort and compliance timelines.
- Commercial tools — TCO/ROI calculators, procurement templates, and risk-adjusted investment scenarios — designed to translate security decisions into board-level trade-offs between CAPEX, OPEX, service agility and revenue protection.
To preserve the integrity of competitive tendering and to encourage direct engagement, the report intentionally refrains from publishing the full segmentation tables and proprietary vendor-weighted revenue splits in this summary; those data and the underlying datasets are available in the complete study.
Worldwide Security Software in Telecom Market
Competitive landscape: strategic postures and tactical moves
The telecom security ecosystem is shaped by a combination of large, horizontal vendors with deep route-to-market strength and telecom-focused specialists that address protocol-level threats and service-provider use cases. Our analysis profiles vendors across technology capability, telco go-to-market, ecosystem partnerships, and regulatory exposure. Highlights include:
- Cisco Systems — Continues to leverage its telco-grade networking footprint and portfolio breadth (secure firewall, DNS-layer controls, network security platforms) to sell end-to-end security propositions into operators. Cisco’s advantage is integration across routing, switching and security domains, which simplifies operator operations but raises scrutiny under trusted-vendor and sovereignty policies in certain markets.
- Palo Alto Networks — Rapidly positioning itself around AI-secure frameworks and service-provider use cases. Recent partnership expansions announced in early 2026 underscore a strategy to co-package sovereign AI controls and edge-to-cloud protections with systems integrators and infrastructure vendors.
- Fortinet — With a focus on high-performance firewalls and a fabric approach, Fortinet’s recent product refresh emphasizes AI controls and flexible SASE deployments, directly addressing operators balancing throughput-intensive traffic with modern security features.
- Ericsson and Nokia — Both network equipment incumbents are embedding security controls into 5G RAN, core and transport stacks. Their value proposition is secure-by-design network elements and lifecycle management integrated with operator OSS/BSS workflows.
- Huawei — Continues to offer tightly integrated network and security stacks to operators that prioritize cost and vertical integration, while facing regulatory and supply-chain constraints in some jurisdictions.
- Check Point, Juniper, F5, Trend Micro — These established security vendors retain important roles in network perimeter, application and hybrid-cloud security. Their strength is rapid innovation across cloud-native workloads and mature threat intelligence feeds.
- Specialists (Allot, P1 Security) — Niche vendors focused on telecom protocol security, DDoS mitigation, signaling protection and mobile subscriber security are increasingly chosen for targeted projects where protocol fidelity and low-latency enforcement matter.
Our vendor scoring recognizes that winning in telecom requires more than a superior product: it demands validated interoperability, proven scale, local partner ecosystems, and an ability to adapt to jurisdictional trust frameworks. The competitive picture is dynamic — partnerships, product releases and geopolitical policy shifts in early 2026 have reshaped vendor advantage maps.
Regulation, technology and threat trends shaping 2026 decisions
- Regulatory complexity is rising. Policymakers are advancing digital sovereignty measures, data localization rules and vendor trust frameworks. Notably, Europe’s regulatory agenda in 2026 places added emphasis on secure architectures and measurable compliance outcomes, and several jurisdictions are accelerating requirements for quantum-resistant cryptography.
- AI and cloud drive architectural change. Vendors are releasing AI-aware security controls and service-provider-focused integrations (e.g., sovereign AI protections, fabric-based AI agents). Operators must decide how much to insource versus partner for AI-driven security capabilities.
- Persistent threat evolution. Independent analyses warn that sophisticated attacks targeting telecom signaling, AI supply chains and cloud orchestration layers will continue. DDoS, signaling exploit kits and supply-chain manipulations remain top risks requiring dedicated mitigations.
- Operator business model shifts. Many operators are expanding cybersecurity as a customer-facing offering. This requires productized security bundles, measurable SLAs, and billing/assurance integration to monetize security services effectively.
How senior leaders should use this report in 2026
- CEOs and CFOs: Prioritize security as a strategic investment linked to revenue protection and new-service enablement. Use the report’s ROI models to size investments against expected churn reduction and incremental B2B revenue.
- CIOs and CTOs: Adopt the migration playbooks to phase legacy decommissioning, cloud-native adoption, and traffic steering for SASE/SSE. Apply the vendor scorecards to shortlist suppliers based on integration risk and roadmap fit.
- Security and network ops: Implement the runbooks and KPIs for phased validation of controls across RAN, core, transport and edge. Use threat-model templates to prioritize mitigations aligned to specific service tiers.
- Procurement and legal: Leverage procurement templates and the regulatory impact matrix to craft contract clauses addressing data residency, supply-chain attestations, and post-quantum readiness.
Conclusion — the next 12 months are decisive
With a projected market expansion from mid-2020s levels to well over double by 2032 and a sustained CAGR of roughly 13%, security software will remain a central lever for telecom transformation. Leaders who combine pragmatic procurement, robust vendor governance, and operationalized security playbooks will be best positioned to convert risk mitigation into revenue-generating services. PW Consulting’s Worldwide Security Software in Telecom report is designed to be a practical companion for those decisions — combining quantitative foresight, tactical execution tools, and competitive intelligence tailored for 2026.
For the complete datasets, detailed segmentation, vendor-weighted models, and downloadable templates referenced throughout this brief, please access the full PW Consulting report or contact our advisory team to schedule a tailored briefing. The executive summary above intentionally omits proprietary segmentation tables to encourage direct review of the underlying models, which remain available exclusively in the full publication.
For detailed analysis of this topic, please visit the official page: Worldwide Security Software in Telecom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Broadband Data Card Market to Reach USD 2,495.03 Million by 2032 at a 2.15% CAGR (2026–2032); Asia Pacific Leads with USD 706.4MPW Consulting: Worldwide Polycarbonate Glazing Market Set for a Robust 5.19% CAGR
By PW Consulting, 2026-07-15
Worldwide Broadband Data Card Market: Strategic Outlook to 2032 — PW Consulting Release
Executive preview — what senior leaders must know as they plan for 2026
PW Consulting’s latest market intelligence brief, the Worldwide Broadband Data Card Market report (base year 2025, historical 2020–2025, forecast 2026–2032), delivers an executive-grade roadmap for technology, product and commercial decisions entering 2026. The market demonstrates modest but steady expansion with a calculated compound annual growth rate (CAGR) of 2.15% over the forecast window. Our topline model shows the market moving from roughly USD 2,150 Million in 2025 to an expected USD 2,495.03 Million by 2032 — a trajectory that masks important inflection points driven by 5G commercialization, regulatory shifts, and interplay with fixed broadband trends.
Worldwide Broadband Data Card Market
Why this report matters for 2026 strategy
-
Actionable clarity at a low-growth inflection: As growth is measured rather than explosive, executives must prioritize margin, product differentiation and lifecycle management over volume-led expansion. The report identifies where to invest selectively to preserve returns as the market expands modestly.
Worldwide Broadband Data Card Market -
Timing product refreshes: The forecast period surfaces windows where 5G-enabled modules and M.2 form-factor cards transition from early-adopter to mainstream enterprise deployment. Our timeline recommendations help program managers schedule R&D, certification and go-to-market efforts to maximize share capture with minimal inventory risk.
Worldwide Broadband Data Card Market -
Capital allocation and supply chain posture: With supply-side consolidation and continued component scarcity in adjacent ecosystems (e.g., RF front-ends, substrate supply), the research prescribes procurement hedges and contract strategies to stabilize BOM costs across the product lifecycle.
-
Regulatory readiness: Spectrum allocation, device certification cycles and data sovereignty rules are recurring variables that materially affect time-to-revenue. The report’s regulatory playbook equips legal and compliance teams to accelerate approvals or avoid costly regional missteps.
Topline market behavior — concise data-driven framing
PW Consulting’s continuous historic model (2020–2025) and our 2026–2032 baseline projection combine to show a market that has recovered from early-cycle perturbations and settled into a steady-growth mode. Our base-year calibration (2025) anchors all scenario workstreams for 2026 planning and capital budgeting. While headline growth is modest at 2.15% CAGR, the distribution of that growth is uneven — technological transitions and regulatory events create pockets of opportunity and risk within the aggregate number. The full report provides sensitivity scenarios and upside/downside cases that are essential for board-level capital allocation decisions.
Report structure — practical tools inside
-
Market sizing and forecast methodology — transparent assumptions, data sources and error-bands so CFOs and strategy leads can re-run models under alternate scenarios.
-
Commercial segmentation framework — supply-side (module, CPE, mobile hotspots), demand-side (consumer, enterprise, government) and channel dynamics; segmentation tables, adoption curves and lifecycle maps (note: detailed segment-level numeric breakdowns are reserved for the full report).
-
Vendor benchmarking and scorecards — objective assessments across product breadth, technology roadmap, go-to-market strength and supply resilience.
-
Go-to-market playbooks — distribution strategies by channel, partnership templates (MVNOs, enterprise integrators), pricing and bundling tactics that preserve ARPU in high-competition pockets.
-
Risk register and mitigation playbooks — spectrum risks, certification timelines, component obsolescence modes and recommended contractual language to shift risk back to suppliers.
-
Decision trees and investment matrices — prioritization tools for R&D, M&A screening and commercial pilots including ROI thresholds tailored to different corporate objectives.
Competitive landscape — what incumbents and challengers are doing
The competitive map shows a mix of vertically integrated OEMs, specialist module vendors and consumer-network-device brands. Market concentration is meaningful but not monopolistic: the combined share of the top three players approximates mid‑40s percent, while the top five move the needle into the high‑50s percent range. This structure creates persistent opportunities for mid-tier specialists and white‑label partners to capture niche value.
-
Huawei Technologies Co. Ltd. — continues to field portable high‑speed LTE and 5G consumer-focused hotspots and cards with competitive performance on download speeds and integration. Its broad portfolio and channel reach make it a natural anchor partner or competitor depending on commercial strategy.
-
Telit Cinterion (now under Semtech) — post-acquisition dynamics have strengthened product depth in sub‑6 GHz 5G M.2 cards designed for fixed wireless and enterprise gateways; their roadmaps signal a focus on robust GNSS and enterprise-oriented feature sets.
-
Sierra Wireless (part of Semtech dynamic) — remains differentiated by multi-network 5G solutions and automotive/vehicle connectivity platforms; consolidation has implications for module roadmaps and component availability.
-
Inseego and Netgear — represent the mini‑CPE and MiFi segment with strong OEM-to‑operator pathways; these vendors are playing to portable/fixed-blended use cases and are significant partners for carriers pursuing consumer and small-business buckets.
-
ZTE, Quectel, Fibocom — strong module and modem players with scale in manufacturing and an emphasis on enabling partners (router manufacturers, integrators) with cost‑effective 5G/LTE options.
For corporate strategists, the implication is twofold: (1) partner selection must balance short‑term distribution advantages with medium‑term supply and IP risks; (2) white-label or OEM partnerships can be lucrative but demand contractual protections for module roadmap continuity and certification support. The full vendor scorecards in our report provide the underlying evidence base for these choices.
Market dynamics, regulatory noise and infrastructure interactions
-
Regulation and net neutrality — evolving open‑internet frameworks continue to shape wholesale pricing and product design. Carriers’ service terms and data‑throttling policies can materially affect the perceived value of data cards in consumer and enterprise propositions.
-
Data sovereignty and IoT MVNO considerations — compliance burdens can influence which markets are addressable for USB modems, embedded SIM strategies and multi‑IMSI solutions. The report includes a compliance decision matrix for cloud and connectivity teams.
-
Spectrum allocation and certification — spectrum release schedules and certification timelines remain a gating factor in deployment. We quantify typical certification lead times by region and recommend program-level contingency buffers.
-
Fixed broadband evolution — FTTH adoption continues to rise globally and complements wireless data cards in hybrid access strategies. The macro interplay between fiber proliferation and wireless uptake creates differentiated service opportunities (e.g., redundancy, temporary/portable high‑speed access).
Recent sector moves that matter for 2026 planning
-
Industry roadmaps and standards progression — the World Broadband Association’s next‑generation roadmap and other sector analyses indicate evolution beyond basic 5G toward higher capacity wireless profiles; product planners should map modular upgrade paths into roadmaps now.
-
Market intelligence and rankings — independent rankings and analyst releases during 2025–2026 provide market‑perception data that influences carrier and retail partner selection; the report synthesizes these signals into vendor risk/reward exemplars.
How senior executives should use this report in 2026
-
Product leaders — use our product lifecycle and certification timelines to sequence launches and retirements so that new 5G SKUs replace legacy 4G offerings without creating inventory write‑downs.
-
Commercial teams — leverage the playbooks and channel maps to negotiate differentiated distribution terms and design bundling strategies that protect ARPU against low‑cost device entrants.
-
Finance and corporate development — apply the investment matrices and sensitivity models when sizing acquisition targets or committing to new manufacturing capacity. The report’s scenario runs make trade‑offs explicit and quantifiable.
-
Regulatory and compliance functions — operationalize the compliance decision matrix to avoid regional roll‑out stalls caused by data sovereignty and device certification mismatches.
Next steps and how to access full intelligence
This release is a strategic preview intended to equip boards and leadership teams with the reasoning and decision frameworks they need for 2026. For complete segment-level figures, regional and connectivity splits, full vendor scorecards, and downloadable financial models (including the conservative, baseline and upside scenarios used to derive the 2.15% CAGR), please consult the full PW Consulting Worldwide Broadband Data Card Market report. The full dossier contains the granular inputs and appendices required to operationalize the insights summarized here.
PW Consulting is available to present a bespoke executive briefing or to workshop the report’s scenarios with management teams preparing 2026 budgets and strategic plans.
For detailed analysis of this topic, please visit the official page: Worldwide Broadband Data Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Commercial Small Batteries Market to Grow at a 6.79% CAGR Through 2032
By PW Consulting, 2026-07-13
Commercial Small Batteries Market — Strategic Outlook for 2026 (PW Consulting Briefing)
Executive summary
PW Consulting’s Commercial Small Batteries Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) delivers a focused, decision-ready picture for executives planning capital, procurement and product strategy in 2026. The global market reached approximately USD 14,580.0 Million in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 6.79% across the 2026–2032 forecast window, reaching roughly USD 23,107.7 Million by 2032. Market concentration is moderate: the top three suppliers account for just over 42% of market value, while the top five approach a near-59% share — a structure that creates both defensive positions for incumbents and fertile ground for fast-moving challengers and niche specialists.
Commercial Small Batteries Market
Why this report matters in 2026
-
Cost pressure and raw-material volatility are driving immediate procurement and price-risk decisions across OEMs and distributors.
Commercial Small Batteries Market -
Tighter safety and labeling rules in major jurisdictions require operational changes to product design, packaging, and extended producer responsibility programs.
Commercial Small Batteries Market -
Technology choice (chemistry mix, form factors) is now a strategic lever — affecting lifetime cost, regulatory compliance and route-to-market for commercial applications such as healthcare devices, IoT endpoints and backup power.
-
Consolidation signals and targeted product innovations open discrete M&A and partnership windows for companies seeking scale or capability add-ons.
What the report contains — practical, transactionable outputs
-
Granular market-sizing and validated forecasting (2020–2032) with scenario modules that stress-test commodity price swings, regulatory shock events and adoption curves.
-
Commodity and cost model: a transparent, sensitivity-ready model linking lithium carbonate and other raw-material price paths to manufacturing cost and margin outcomes.
-
Regulatory impact playbook: compliance checklists and retrofitting guidance for new EU Batteries Regulation requirements, UL and IEC safety standards, and country-level packaging mandates.
-
Competitive benchmarking and capability maps: bespoke scorecards for manufacturers, contract manufacturers and distributors covering product breadth, manufacturing footprint, quality certifications and channel coverage.
-
Go-to-market and commercial playbooks: segmentation-led pricing strategies, route-to-market matrices for healthcare/medical, industrial IoT and other commercial verticals, and channel partnership templates.
-
M&A and partnership pipeline: screened target lists, valuation heuristics and integration risk matrices tailored to acquirers seeking fast capacity, tech IP or geographic reach.
-
Operational playbooks for procurement and inventory: hedging strategies, supplier split recommendations and contract-clauses to mitigate raw-material and logistics shocks.
-
Executive briefings, slide decks and dataset extracts optimized for board presentation and commercial planning cycles.
Competitive landscape: who matters and why
The commercial small-battery space is populated by diversified global manufacturers and focused specialists. Incumbent brand players and component specialists coexist: household names with broad portfolios compete alongside companies emphasizing micro-form factors, hearing-aid cells or sealed lead-acid backup formats. Notable firms covered in our analysis include Energizer Holdings, Duracell, Panasonic, VARTA AG, Maxell, GP Batteries, EnerSys, GS Yuasa, Power-Sonic, Murata, Renata and Toshiba. Each brings differentiated strengths — global distribution and consumer brand equity, engineering depth in coin/button cells, expertise in VRLA/backup systems, or tight vertical integration with electronics OEMs.
Key strategic notes from our benchmarking:
-
Energizer and Duracell retain strong brand and channel positions that protect premium pricing in multiple commercial segments; Duracell’s recent child-safety bitter coating innovation underscores how product-level safety features can be monetized and used defensively.
-
Japan- and Germany-headquartered suppliers (e.g., Panasonic, Murata, VARTA, Maxell) continue to invest in precision chemistries and micro-battery manufacturing excellence — a competitive advantage for medical and precision-instrument applications.
-
Specialist industrial vendors (EnerSys, Power-Sonic, GS Yuasa) dominate standby and UPS niches where form-factor and reliability are sale determinants — these firms surface as natural partners for enterprise and infrastructure OEMs.
-
Regional OEMs and Asian contract manufacturers provide low-cost scale and rapid capacity expansion, keeping margins under pressure and enabling quick response to short-term demand spikes.
Market dynamics and “noise” that will shape 2026 decisions
-
Raw-material volatility: Lithium carbonate prices rebounded markedly in 2025 and are expected to remain in a wide range through 2026. Procurement teams must assume cost swings that materially affect small lithium-cell economics and plan contracts and hedges accordingly.
-
Regulatory tightening: Newer standards and regulations — including jurisdictional implementations of the EU Batteries Regulation, UL 4200A safety guidance and updated IEC standards for button cells — are increasing compliance costs and introducing specific testing and labeling requirements. These are not merely administrative: they affect product design, packaging and field-liability exposure.
-
Product-safety focus: Ingestion and physiological-hazard risks associated with coin and button cells are driving packaging innovations and safety-treated chemistries. Expect higher compliance and product-liability visibility in commercial procurements and tender specifications.
-
Innovation and capacity shifts: Public disclosures and trade-show activity in 2025–2026 signal both new entrants and incumbents expanding into adjacent small-battery formats and HEV/pouch segments — this will alter competitive dynamics in select subsegments.
What to watch in 2026 — four near-term strategic signals
-
Supplier-level cost pass-throughs: Monitor which manufacturers absorb raw-material swings versus those who pursue pass-through clauses; this will determine short-term margin leadership.
-
Regulatory enforcement timing: Watch the rollout cadence for EU labeling rules and ingestion-safety standards; procurement cycles should include compliance verification milestones.
-
Product-safety differentiation: Safety-treated coin cells and child-safe packaging will become minimum commercial requirements in healthcare and consumer-adjacent procurements.
-
Consolidation vs. specialization: Active M&A in targeted niches (micro-batteries, medical-grade cells, backup systems) will create acquisition opportunities for buyers seeking capability rather than scale alone.
Recommended strategic actions for 2026
-
Hedge raw-material exposure: Lock in multi-supplier agreements and consider financial hedges for lithium-related inputs; test contract language for pass-through triggers and force majeure clarity.
-
Diversify chemistry and supply footprints: Where feasible, pursue multi-chemistry product strategies (primary lithium, alkaline, nickel variants) to balance cost, regulatory and lifecycle trade-offs.
-
Prioritize compliance-driven engineering: Invest early in design changes required by new safety and labeling standards to avoid rushed redesigns and costly recalls.
-
Targeted M&A and partnerships: Use the moderate top-end concentration to scout bolt-on targets that add niche technical know-how, medical certifications or regional manufacturing capacity.
-
Commercial playbook updates: Update RFP templates to include safety test evidence, labeling conformity and EPR commitments; reprice product lines to reflect embedded compliance costs.
How leading teams will use this report
-
CEOs and CPOs will use the commodity scenarios and supplier scorecards to set 12–24 month procurement strategies and contract terms.
-
Product and engineering leads will leverage regulatory impact mapping and test-plan templates to prioritize design cycles for medical and IoT product lines.
-
Corporate development teams will apply the M&A pipeline and valuation heuristics to screen tuck-in targets and prepare integration checklists.
-
Compliance and legal teams will adopt the standards matrix and labeling checklists to close gaps ahead of enforcement milestones.
Conclusion & access to the full intelligence
PW Consulting’s Commercial Small Batteries Market report is designed as a working tool for 2026 strategic planning — combining validated macro forecasts, scenario-ready cost models, and transaction-oriented competitive intelligence. This briefing surfaces the essential signals: a growth trajectory underpinned by steady demand, material-driven cost risk, tighter safety and regulatory requirements, and a competitive landscape that rewards both brand strength and engineering specialization.
To preserve the tactical value of our segmentation models, detailed regional and end-use splits, and company-level scorecards are reserved for the full report and accompanying datasets. For complete access to the segmented revenues, downloadable tables, supplier scorecards and bespoke consulting options, visit PW Consulting’s Commercial Small Batteries Market report page or contact your PW account lead to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Chromatography Columns Market to Grow at a 5.5% CAGR — Report Unveils Shifting Regional and Application Dynamics
By PW Consulting, 2026-07-13
Chromatography Columns Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
As global analytical and process-scale chromatography activity rebounds and reconfigures in the wake of supply-chain disruptions and regulatory tightening, the chromatography columns market has entered a phase where strategic timing matters as much as technical differentiation. PW Consulting’s new market study (base year 2025) positions the market at USD 3.20 billion in 2025 and forecasts a steady expansion at a 5.5% CAGR through the 2026–2032 horizon, producing meaningful upside for well-positioned suppliers, integrators and end users. This bulletin distills the report’s strategic implications for 2026 decision-makers—revealing where to prioritize investment, partnerships and operational resilience—while reserving full subsegment tables and vendor-level financials for the report landing page.
Chromatography Columns Market
Why 2026 is a pivot year
-
Regulation meets cost pressure. New regulatory actions (notably recent EU restrictions around certain silica particle sizes and updated requirements in U.S. and state-level jurisdictions) converge with rising raw material and transport costs, forcing suppliers to re-engineer formulations and supply routes.
Chromatography Columns Market -
Demand is heterogeneous but growing. Clinical, biopharma process-scale needs (including mRNA and biologics purification), environmental testing expansion, and food-safety monitoring sustain volume growth while pushing buyers toward higher-performing media and single-use options.
Chromatography Columns Market -
Consolidation dynamics continue. The market shows mid-level concentration (three-firm concentration in the mid-40s percent range and five-firm concentration approaching six-in-ten), a structure that favors both scale-focused incumbents and narrowly specialized challengers with differentiated technical IP.
Market trajectory: what the headline numbers mean for strategy
The market’s USD 3.20 billion base in 2025 and a projected 5.5% CAGR to 2032 reflect steady, technology-led expansion rather than speculative spikes. By 2032, our top-line projection reaches the mid-single-digit-billion-dollar range—sufficiently large to support both premium high-performance niches and higher-volume, cost-sensitive offerings.
For executives, this implies three strategic postures:
-
Invest in differentiated chemistries and column architectures that command margin premium and stickiness in regulated end markets.
-
Hedge raw-material and logistics exposure through supplier diversification, backward integration for critical packing materials, or long-term contracting aligned with volume forecasts.
-
Deploy commercial segmentation and channel strategies that separate process-scale and analytical customers to avoid margin erosion from cross-subsidization.
Key industry dynamics to factor into 2026 planning
-
Upstream feedstock volatility: silica gel costs have experienced notable year-on-year increases driven by supply disruptions. Margin planning must incorporate realistic raw-material elasticity scenarios and procurement hedging strategies.
-
Regulatory constraints: recent regulatory moves limit certain silica particle specifications in chromatography media and increase labeling and compliance obligations in some U.S. states. These changes affect product formulations, testing burdens and time-to-market for reformulated media.
-
Trade and transport friction: tariff adjustments on column imports and added ocean freight surcharges have materially changed landed costs for imports—customers and manufacturers will need to revisit source-country strategies and nearshoring economics.
-
Environmental and safety compliance: new listings and state-level restrictions increase compliance cost and reputational risk for vendors that rely on legacy materials; product redesign and transparent disclosure will be competitive differentiators.
Report contents — practical tools for immediate action
Beyond market sizing and trend narrative, our report is structured as a strategic playbook for 2026 execution. Key operational deliverables include:
-
A modular financial model with scenario toggles (input raw-material cost shocks, tariff changes, and demand shift scenarios) to quantify P&L sensitivity for different go-to-market choices.
-
Segment-level growth roadmaps and an eight-quadrant opportunity matrix that link product architectures to buyer archetypes—crafted to prioritize R&D and SKU rationalization over the next 18 months.
-
Supply-chain resilience toolkit: supplier risk scoring, nearshore vs offshore cost curves, and a procurement playbook for securing critical packing media under tightening regulatory regimes.
-
Regulatory impact matrix that translates recent policy moves into action items (reformulation, labeling, test protocols, and time-to-certification timelines) for product managers and compliance teams.
-
Commercial playbooks for channel segmentation, pricing, and tender defense tailored to clinical, industrial, and academic buyer segments.
-
Vendor benchmarking dashboards—covering product breadth, technical differentiators, recent launches and certification status—to support M&A screening, supplier selection and strategic partnerships.
Competitive landscape: what leading suppliers are doing
The market is shaped by a mix of large instrument-house suppliers and specialized media players. Our competitive intelligence section drills into product strategies, route-to-market choices and recent moves by the most influential firms. Highlights include:
-
Agilent Technologies is advancing UHPLC performance and bioanalytic compatibility through new guard and high-efficiency product introductions; its roadmap emphasizes integrated workflows for regulated bioanalysis applications.
-
Thermo Fisher Scientific is expanding its proteomics and high-resolution LC offerings with next-generation column chemistries designed for high-throughput omics laboratories—an approach that deepens technical lock-in with instrument ecosystems.
-
Waters Corporation continues to invest in certified portfolios for pharmacopeial compliance, reinforcing its appeal to contract labs and regulated manufacturers seeking validated supply chains.
-
Merck KGaA, Shimadzu, PerkinElmer, Restek, Phenomenex and other established suppliers are pursuing either breadth (multi-application portfolios) or depth (niche high-performance phases) depending on their strategic end-market focus.
-
Bioprocess-focused vendors such as Sartorius and Cytiva have shifted capacity and product development toward single-use and preparative-scale solutions, reflecting the accelerating demand for biologics purification media.
Recent product launches and capacity moves—from Agilent’s late-2025 UHPLC guard launches to Cytiva’s early-2025 expansion for mRNA purification capacity—underline an industry investing ahead of demand while navigating material and regulatory headwinds.
Strategic implications by function (concise playbook)
-
R&D: Prioritize formulations that reduce regulatory friction (particle-size alternatives, non-silica supports where feasible) and invest in characterization protocols that speed regulatory approvals.
-
Supply Chain: Implement dual-sourcing and long-term off-take agreements for packing materials; evaluate nearshoring to mitigate tariff and freight surcharge impacts.
-
Commercial: Differentiate through certified product lines, bundled workflows, and service-based pricing for process-scale customers.
-
M&A & Partnerships: Target tuck-ins that provide either differentiated media chemistries or vertical integration into packing-media manufacturing to control cost and compliance risk.
How executives should use this report in 2026
Leaders should treat the report as both a decision-support engine and an actionable roadmap. Use the scenario model to stress-test budget plans, the regulatory matrix to triage product portfolios for reformulation, and the supplier scorecards to prioritize procurement negotiations. For investors, the combination of stable CAGR, mid-level concentration, and continued product innovation suggests attractive opportunities in companies that control specialty chemistries or critical process-scale capabilities.
Trailer note — what’s behind the paywall
This preview frames the strategic questions and directional answers executives need in 2026. The full PW Consulting Chromatography Columns Market report provides the detailed segmentation tables, region- and application-level forecasts, granular vendor profiles with recent financial and product rollout data, and the downloadable scenario model. These elements are intentionally omitted here to preserve the report’s value as a decision-grade subscription asset.
Next steps
Contact PW Consulting for an executive briefing and access to the interactive model. Our analysts will run a tailored “what-if” session using your input assumptions (product mix, exposure to China-based suppliers, and target end markets) so you can see the P&L, balance-sheet and cash-flow implications for 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Chromatography Columns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


