



PW Consulting Report: Display Driver IC (DDIC) Wafer Foundry Services Market Set to Expand at a 6.55% CAGR During 2026–2032
By PW Consulting, 2026-07-13

Display Driver IC (DDIC) Wafer Foundry Services Market — 2026 Strategic Brief
As markets normalize after cyclical demand swings and foundry capacity rebalancing, the global DDIC wafer foundry services market is entering a phase of steady growth. Our new market model (base year 2025) anticipates a compound annual growth rate (CAGR) of approximately 6.55% over the 2026–2032 forecast horizon, lifting market value from a 2025 baseline to a materially larger addressable market by 2032. For executives making capital allocation, sourcing, and partnership decisions in 2026, the combination of predictable expansion and concentrated supplier dynamics creates both opportunity and strategic risk — and it demands disciplined, data-driven planning.
Display Driver IC (DDIC) Wafer Foundry Services Market
Why this report matters for 2026 decisions
-
Actionable supplier strategy: The report translates capacity maps, node-compatibility matrices, and vendor readiness assessments into a tactical supplier-selection playbook that procurement and operations teams can deploy immediately.
Display Driver IC (DDIC) Wafer Foundry Services Market -
Investment prioritization: For semiconductor and display OEMs deciding where to place R&D or capex bets, our scenario-driven forecasts reveal the windows of commercial viability for mature and specialty nodes used in DDICs.
Display Driver IC (DDIC) Wafer Foundry Services Market -
M&A and partnership screening: With a highly concentrated market structure at the foundry tier, we identify the value levers that make vertical partnerships, minority investments, or strategic JV structures compelling — and the conditions under which they are likely to deliver ROI.
-
Risk quantification: The analysis provides quantified downside scenarios from raw-material inflation, regional capacity shifts and export-control-induced bottlenecks — enabling board-level contingency planning.
High-level market trajectory (what the numbers tell you)
Our base-year calibration for 2025 establishes a clear starting point for strategic planning. From that baseline, the modeled 6.55% CAGR reflects a multi-year structural expansion driven by continued consumer display refresh cycles, growing large-area panel deployments, and incremental content increases in automotive and industrial displays. The pace is neither explosive nor stagnant — it is enough to justify near-term investments in qualified capacity and supplier relationships, while also favoring disciplined capital allocation that prioritizes flexibility over fixed, single-shift expansions.
Macro dynamics shaping the DDIC foundry market
-
Cost inflation across the supply chain: Since 2025, foundry and outsourced assembly/test (OSAT) cost bases have risen materially. Precious-metal price pressure for bumping and backend processes is compressing supplier margins and prompting price adjustments upstream.
-
Capacity reallocation and uneven supply distribution: Leading Taiwanese and South Korean foundries have reallocated some capacity away from large-area DDIC volumes to other high-priority segments such as PMICs. This has opened commercial opportunities for regional foundries to expand, creating a geographically uneven supply picture that buyers must navigate carefully.
-
Geopolitical and regulatory headwinds: Export controls and equipment restrictions are affecting capital expansion plans for certain Chinese foundries. These constraints change the timetable for node upgrades in specific regions and alter the risk-return calculus for long-term sourcing.
-
Pricing actions: Multiple foundries have signaled wafer price increases on mature-node processes; in some contracts and markets, clients are seeing single- to double-digit percentage uplifts. Procurement teams must treat price as a dynamic variable rather than a static input.
Competitive landscape — who moves the market (strategic implications)
The DDIC wafer foundry market exhibits high concentration at the top of the supplier pyramid. Our market-concentration metrics show that a small set of top-tier foundries capture the lion’s share of commercially available capacity, underscoring the bargaining power asymmetry with buyers. For 2026, this concentration has several pragmatic implications:
-
TSMC (Hsinchu, Taiwan): The global leader’s blend of advanced and mature-node capabilities means it remains the default choice for high-volume, mixed-node DDIC programs that require tight integration with premium mobile and large-area panel customers. Where schedule certainty and yield maturity matter most, TSMC’s scale is a decisive factor.
-
Samsung Foundry (Suwon, South Korea): Samsung’s integrated display ecosystem creates commercial advantages for partners seeking premium AMOLED and LCD driver solutions. For brands pursuing premium differentiation, Samsung’s vertically aligned offering shortens qualification cycles and can enhance co-development opportunities.
-
UMC and Vanguard: Specialty-process pure-plays retain commercial importance for high-voltage and analog-heavy DDICs. Their focus on mature-node optimization preserves competitive alternatives for buyers aiming to diversify supplier concentration risk.
-
GlobalFoundries: With proven high-voltage platforms across mature nodes, GlobalFoundries serves program teams that require production-proven platforms and predictable capacity for premium AMOLED drivers.
-
Chinese foundries (Nexchip, Hua Hong, SMIC): Regional players have stepped into gaps created by capacity reallocation in Taiwan and Korea. Nexchip’s continued growth — including recent public-market actions to fund expansion — highlights how a fast-scaling regional champion can shift the competitive topology. Buyers and investors must therefore balance short-term commercial availability with medium-term technology and geopolitical risk.
Recent corporate and market developments you need on your radar
-
Nexchip’s capital moves: A recent listing application aimed at funding large-scale fab expansion reflects a broader trend of Chinese foundries scaling mature-node capacity to capture incremental DDIC demand. For buyers, this can translate into improved commercial leverage in certain geographies, but it also raises considerations around qualification timelines and yield maturity.
-
Price adjustments across mature nodes: Several foundries announced upward price pressure in 2026 to rebalance capacity and recover margin — a signal for procurement to re-examine indexation clauses, long-term pricing collars, and hedging mechanisms for key inputs.
-
Regulatory friction affecting equipment flows: Export-control dynamics are influencing capital-expansion timetables and tech-roadmap choices for some suppliers, lengthening the timeline for node transitions in affected regions.
What the full report contains — practical, implementation-focused deliverables
To inform 2026 decisions, the full PW Consulting report is deliberately tactical. Highlights include:
-
Executive decision dashboard: One-page strategic guidance for C-suite and board use, linking market scenarios to recommended actions across sourcing, capex, and M&A.
-
Supplier heatmaps and scorecards: Multi-dimensional vendor assessments covering capacity elasticity, node maturity, yield history, geographic risk and contractual flexibility.
-
Node-level demand and capacity curves: Forward-looking node compatibility matrices and ramp schedules to support product qualification planning (note: node-by-node tables and unit-volume detail are in the full report).
-
Cost-model templates: Parametric wafer-cost models and sensitivity tools to simulate the impact of wafer price moves, OSAT fees, and precious-metal inflation on gross margins.
-
Qualification and sourcing playbooks: Standardized qualification timelines, recommended sampling volumes, and negotiation levers for securing priority allocation during tight cycles.
-
Scenario stress tests: Pre-built scenarios (e.g., capacity shock, 1–2 year price inflation, export-control escalation) with quantified P&L and supply-risk impacts for product lines.
Strategic recommendations — prioritized actions for 2026
-
Diversify supplier exposure by node and region: Reduce reliance on any single top-tier foundry for mission-critical programs; instead, structure a two-tier supply base with a primary partner for volume and a regional specialist for capacity buffering.
-
Negotiate flexible long-term frameworks: Seek multi-year collaborative agreements with contingent pricing mechanisms, capacity reservation rights, and yield-sharing clauses to align incentives while protecting against sudden price inflation.
-
Invest selectively in co-qualification: For products where differentiation depends on driver performance, co-invest in qualification activities with foundries that can accelerate time-to-qual while securing allocation priority.
-
Hedge raw-material exposure: Incorporate commodity hedges or supplier pass-through mechanisms where precious-metal and OSAT cost volatility materially affect the bill of materials.
-
Monitor regulatory signals and adapt node strategy: Maintain a regulatory watch function and tie capital-allocation triggers to observable changes in export-control trajectories and equipment shipment flows.
-
Use M&A and JV selectively: Consider regional minority investments or JV structures with fast-scaling foundries to secure capacity and gain early access to regional panels, while maintaining technical oversight via shared roadmaps.
How to deploy this intelligence in your organization
-
Immediate: Run a focused supplier-risk workshop using the executive dashboard to stress-test contracts for the next 12 months.
-
Near-term (90 days): Re-prioritize product qualification calendars based on node availability and supplier scorecards; start or expand co-development pilots with targeted foundries.
-
Medium-term (6–18 months): Execute hedging strategies and renegotiate framework agreements to incorporate dynamic pricing and allocation clauses; prepare contingency sourcing plans for critical SKUs.
This brief intentionally highlights the strategic contours of the DDIC wafer foundry market without reproducing the granular node-by-node tables, regional demand curves, vendor-level cost models and pricing trajectories contained in the full PW Consulting report. Those datasets are the basis of the tactical playbooks that procurement, product and corporate development teams will use in 2026.
For access to the complete dataset, interactive dashboards, and client-ready templates that support fast execution, please visit the PW Consulting report page or contact our industry practice to request the full report and bespoke advisory engagement.
For detailed analysis of this topic, please visit the official page: Display Driver IC (DDIC) Wafer Foundry Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Focus Ring Market Set to Expand at 8.22% CAGR Through 2032, Driving Revenues to USD 4,259.12 Million
By PW Consulting, 2026-07-13
Semiconductor Focus Ring Market: A Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our new Semiconductor Focus Ring Market research — a practical briefing designed to orient executive decision-making in 2026. The focus ring segment of the semiconductor consumables market is no longer a niche line-item for fab planners: it is a strategic lever affecting yield, tool uptime, supply resiliency and, increasingly, geopolitical risk exposure. Our study uses 2025 as the base year and models the market across 2026–2032. At the macro level, the market is on a sustained growth trajectory (CAGR 8.22% through the forecast), moving from the mid‑2020s base into materially larger absolute scale by the early 2030s. Market concentration remains meaningful (CR3 ≈ 54.2%; CR5 ≈ 68.45%), underlining the importance of supplier selection and qualification strategies.
Semiconductor Focus Ring Market
Why this market matters to corporate strategy in 2026
-
Process scaling and device complexity are elevating the strategic importance of focus rings. As etch chemistries and multilayer stacks multiply, small incremental changes in edge-ring performance translate into measurable wafer-level yield gains or losses. Procurement decisions that were once transactional now carry product roadmap and cost-of-goods implications.
Semiconductor Focus Ring Market -
Supply-chain fragility and raw-material pressures (notably for high‑purity SiC and specialty ceramics) make single‑sourced or just‑in‑time supply models riskier. Longer lead times for specialty ceramics — and the potential for export controls or mineral restrictions — require procurement and operations to build alternative qualification pipelines and buffer strategies.
Semiconductor Focus Ring Market -
Concentration among a relatively small set of technical suppliers means commercial leverage is asymmetric. Strategic sourcing, co-development agreements and multi-year qualification roadmaps are effective levers to secure supply while embedding product differentiation.
Key market signals executives must act on in 2026
-
Adopt qualification windows that align with tool OEM cadence and device development cycles. Our research shows that qualification lead-times remain a critical gating factor; compressing those windows through early technical collaboration yields outsized returns in time-to-production.
-
Build a material‑risk heat map. Focus ring performance is sensitive to material choice (e.g., silicon, CVD/solid SiC, quartz and engineered ceramics). Given rising cost and availability volatility for high‑purity SiC and specialty ceramics, manufacturers should maintain at least one validated alternate material path for each critical etch process.
-
Prioritize suppliers that offer integrated lifecycle services — design-for-etch support, on-tool tuning, failure analytics and predictable spares pipelines. Vendors that combine materials science with field service and analytical feedback reduce time-to-yield and total cost of ownership.
-
Embed export-control and trade policy scenarios into sourcing decisions. Recent measures across allied jurisdictions have demonstrated how regulation can disrupt parts supply. Scenario planning and regional dual-sourcing help avoid single-point failures in the supplier base.
Market dynamics and operational impacts
Our study synthesizes primary interviews, supplier capability audits and process‑level testing data to map the dominant forces shaping the market. Key dynamics include material migration (toward more durable SiC in high-stress etch regimes), the rising tactical importance of nitride-free designs in select nodes, and a bifurcation between high-performance/low-volume specialty rings and commoditized mass‑production variants. These drivers interact with macro inputs — raw material pricing, geopolitical tensions and tighter export controls — to increase the value of proactive supplier management.
Operationally, fabs will face three concrete impacts:
-
Qualification calendars will lengthen unless mitigated by joint-development agreements and standardized test protocols agreed with suppliers.
-
Inventory strategies will need rebalancing — a move away from pure just‑in‑time toward controlled onshore buffer stocks for critical geometries and materials.
-
R&D teams must incorporate consumable packaging and ring‑tool interactions earlier in device and process design to avoid late-stage yield cliffs.
Competitive landscape: who matters and why
The competitive map combines established global materials specialists, CVD SiC pioneers and regional high-volume producers. Suppliers differ not only by material capability (CVD SiC, solid SiC, single‑crystal silicon, engineered ceramics, quartz) but also by scale, vertical integration and service model. The market’s top tier controls a majority share, but regional and niche players are gaining relevance through product innovation and local partnerships.
-
CoorsTek (United States) — Strengths: high‑purity ceramics, deep materials science and engineered solutions for extreme etch environments. Best suited for fabs requiring bespoke, high‑reliability ceramic rings and integrated service models. URL: https://www.coorstek.com
-
Morgan Technical Ceramics (United Kingdom) — Strengths: CVD SiC and high‑purity alumina offerings, long history in high‑temperature and plasma‑resistant components. Strong R&D partnership potential for European and global OEMs. URL: https://www.morgantechnicalceramics.com
-
Tokai Carbon Co., Ltd. (Japan) — Strengths: pioneer status in solid SiC focus rings via proprietary CVD processes; recognized for durability in high-performance etch applications. High technical credibility for advanced nodes. URL: https://www.tokaicarbon.co.jp
-
BC&C (South Korea) — Strengths: mass production capability for polycrystalline silicon rings and recent commercial traction with nitride‑free poly‑Si designs; demonstrates how process innovation can unlock cost and yield advantages at scale. Recent development: order and qualification success with a North American chipmaker (product entering mass supply in early 2025), reinforcing the commercial viability of non-SiC alternatives in targeted use-cases.
-
China-based suppliers (e.g., Semicorex, Semicera, DSTC) — Strengths: rapid scale-up, competitive pricing and an expanding portfolio of CVD SiC and coated graphite solutions. These firms are increasingly relevant for regional fab projects and for buyers seeking alternative sources.
-
Other notable players (Ferrotec, Kyocera, Worldex, Kallex, Daewon, Greene Tweed, etc.) — Each brings differentiated capabilities across ceramic chemistry, silicon processing, quartz fabrications and aftermarket services; selection should be driven by process fit and long‑term supply resilience.
Report deliverables: what executives will find inside
The full research package is purpose‑built for commercial, operations and R&D leaders. It delivers:
-
Proprietary market-sizing and a validated CAGR forecast (8.22% through the 2026–2032 horizon) with scenario analyses that stress-test export control, raw‑material shock and regional capacity build-outs.
-
Supplier capability heat maps and a buyer’s playbook that ranks vendors by technical fit, qualification complexity, and supply‑risk exposure.
-
Actionable procurement frameworks: qualification timelines, test protocols, contractual clauses for supply assurance, and suggested inventory posture by process risk tier.
-
Hands‑on engineering guidance for ring‑tool interaction optimization, on-wafer performance diagnostics, and recommendations for co‑development agreements to accelerate qualification.
-
Supply‑chain risk matrices including material sourcing vulnerability analyses (notably for high‑purity SiC and specialty ceramics) and mitigation levers such as dual-sourcing, onshoring, and inventory hedging.
-
Executive decision templates: CapEx vs. OpEx tradeoffs for in‑house machining vs. outsourced supply, and a procurement scorecard aligned to TTM, yield impact and regulatory exposure.
Practical recommendations for 2026 planning cycles
-
Initiate prioritized supplier qualifications now for every critical etch family. Even when a current supplier is performing, the cost of switching later is high; parallel qualification preserves optionality.
-
Negotiate technical collaboration clauses into key supplier contracts to accelerate shared root‑cause analysis and on‑tool tuning, reducing TTM for node transitions.
-
Establish a materials contingency plan: identify at least one validated alternate material and one alternate geographic source for critical ring types within 12–18 months.
-
Make supply‑resilience a board-level KPI for fabs with advanced node exposure. Track supplier concentration, lead‑time volatility and regulatory risk as part of quarterly risk reviews.
Conclusion and next steps
The focus ring market is maturing from a technical commodity into a strategic component class that links materials science, supply-chain resilience and device economics. For 2026 planning cycles, the essential moves are clear: diversify validated sources, embed supplier partnerships early in process development, and optimize inventory and contractual structures to absorb material and regulatory shocks. Our full report contains the granular segment tables, supplier scorecards and quantitative scenario outputs that will enable executable roadmaps; this preview is intended to surface the critical strategic choices you need to make now to avoid costly delays later.
To access the complete dataset, segment-level breakdowns, supplier profiles and procurement templates, please visit the PW Consulting report page for the Semiconductor Focus Ring Market. The full study is tailored for procurement leads, process R&D managers and corporate strategy teams preparing their 2026–2028 action plans.
For detailed analysis of this topic, please visit the official page: Semiconductor Focus Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Como Catalyst Market 2026 Outlook — Strategic Briefing for Decision-Makers
Executive summary
As the downstream fuels and hydroprocessing landscape normalizes into a new mid‑cycle, the global cobalt-molybdenum (CoMo) catalyst market presents a blend of steady baseline growth, episodic raw‑material volatility and concentrated supplier power that together will shape high‑impact decisions in 2026. PW Consulting’s Como Catalyst Market (Como Catalyst Market) report uses a 2025 base year and a 2026–2032 forecast horizon to quantify a measured compound annual growth rate (CAGR) of 3.8%. Published as part of the Como Catalyst Market series, the full report combines market-size projections (USD, revenue in Million), scenario modeling, supplier benchmarking and transaction-level playbooks to support capital allocation, procurement strategy and technology roadmaps.
Como Catalyst Market
Why this matters for 2026 decisions
-
Investment timing: With moderate, predictable top‑line expansion over the forecast window, capital projects tied to hydrotreating and mid‑distillate upgrading must optimize for lifecycle returns rather than chase short, commodity‑driven spikes.
Como Catalyst Market -
Supply‑chain resilience: Raw‑material shocks in 2025 exposed supply concentration risk. Firms that reconfigure sourcing, inventory and contract terms in 2026 will avoid margin erosion and project delays.
Como Catalyst Market -
Technology differentiation: High‑activity CoMo formulations and longer‑life catalysts are proving to be a competitive lever for refiners moving to ultra‑low sulfur and renewable diesel co‑processing applications.
Market outlook — headline metrics
Using 2025 as the base year, PW Consulting’s topline forecast projects continued expansion across the 2026–2032 period at a CAGR of 3.8% (revenues reported in USD Million). The market trajectory reflects steady demand from conventional hydrotreating and selective uplift from renewable fuel processing, constrained periodically by raw‑material cycles and capacity rebalancing among suppliers. Concentration remains material: the three largest suppliers control roughly half the market, and the five largest approach two‑thirds, underscoring the strategic leverage held by tier‑one catalyst manufacturers.
Competitive landscape — what to watch in 2026
The market’s competitive architecture is characterized by a small group of global technology leaders supplying high‑value CoMo and allied formulations. Key dynamics for 2026 include product innovation, capacity adjustments and strategic portfolio reshaping.
-
Topsoe — Leveraging new product introductions and recent capacity expansions, Topsoe is positioning for demand coming from renewable diesel and next‑generation hydrotreating projects. Expect them to prioritize high‑activity, long‑life catalysts tailored for ultra‑low sulfur diesel and deep desulfurization needs.
-
BASF — With a long track record in CoMo/NiMo hydrogenation chemistry, BASF is focusing on established industrial use cases such as pygas and coke‑oven light oil hydrogenation while maintaining robust application engineering support.
-
Axens — Known for middle‑distillate and VGO hydrotreating formulations, Axens continues to compete on a combination of product breadth and process integration services for mid‑pressure units.
-
Shell Catalysts & Technologies (Criterion) — Competing via application‑specific series and global technical service footprints, Shell remains a preferred supplier for low‑pressure distillate HDS projects in large refiners.
-
Kuwait Catalyst Company (KCC) — Serving regional refining clusters with tailored desulfurization and denitrification solutions, KCC is an important option where proximity and localized support matter.
-
Ketjen (former Albemarle refining catalyst business) — Following recent corporate transactions that restructured ownership and go‑to‑market arrangements, this business will be watched closely for strategic reinvestment and potential recombination with private‑equity resources.
Across suppliers, recent public moves — capacity scale‑ups in early 2026, product launches in 2025, and corporate realignment of legacy refining catalyst businesses — signal an emphasis on supply security, product performance and balance‑sheet optimization. For 2026 sourcing decisions, counter‑party stability and service guarantees should be prioritized in tandem with price.
Raw‑material and regulatory drivers — immediate operational impacts
Three industry shocks in 2025–2026 are shaping short‑term strategy:
-
Cobalt supply tightening: Export controls and quota mechanisms implemented in 2025 materially tightened cobalt availability. The market moved from oversupply to a condition of episodic tightness, lifting spot and contract benchmarks. For catalyst formulations with cobalt content, procurement teams need contingency sourcing, hedging mechanisms and an active recycling program.
-
Molybdenum price variability: Fluctuations in molybdenum availability and pricing have introduced 5–7% swings for some producers, encouraging producers to adopt more efficient extraction and to test low‑metal formulations without sacrificing activity.
-
Technical constraints: CoMo catalysts retain a competitive edge in low‑to‑medium pressure hydrodesulfurization through higher selectivity versus NiMo formulations, but they are sensitive to carbon monoxide partial pressure in the reactor gas. Operational parameters and feed pre‑treatment thus become key levers to unlock catalyst performance and lifetime.
Practical contents of the Como Catalyst Market report
PW Consulting’s Como Catalyst Market report is structured for tactical and strategic use. Selected deliverables include:
-
Topline market model (2020–2032): historical validation, baseline forecast and three scenario variants that stress feedstock shifts and raw‑material shocks.
-
Supplier scorecards: capability maps, service proposition comparison, risk indicators and commercial negotiation guidance (terms, lead times, service SLAs).
-
Procurement playbook: contract templates, inventory buffers calibrated to service level targets, hedging and consignment options.
-
Technology and CAPEX toolkit: lifecycle cost comparisons (including catalyst replacement intervals), retrofit prioritization checklist and performance KPIs.
-
Operational diagnostic: reactor operating envelopes that maximize CoMo catalyst selectivity while mitigating CO inhibition, plus feed pre‑treatment best practices.
-
Scenario stress tests and M&A screeners: for investors and corporates evaluating acquisition or vertical integration opportunities.
Strategic recommendations for 2026
For executives making binding decisions in 2026, PW Consulting highlights six prioritized actions based on the Como Catalyst Market analysis:
-
Lock in layered supply agreements: Combine long‑term offtake with shorter spot and quota‑based purchases to balance price certainty and flexibility in volatile raw‑material markets.
-
Invest selectively in high‑activity, long‑life catalysts: A small premium for extended run length can materially reduce total cost of ownership and exposure to metal price cycles.
-
Stress test reactor operations: Revisit feed conditioning and CO management protocols to fully realize CoMo selectivity advantages; small operational changes can unlock outsized performance gains.
-
Prioritize supplier service and technical support: In a moderately concentrated market, guaranteed technical assistance and spare parts availability can be as valuable as unit price.
-
Accelerate catalyst recycling and circularity pilots: Recovering cobalt and molybdenum can dampen input-cost volatility and support sustainability targets.
-
Use M&A and JV tools tactically: Consider bolt‑on acquisitions or strategic partnerships to secure regional manufacturing capacity or to internalize critical application engineering capabilities.
Implications for stakeholders
-
Refiners and fuel producers: Optimize catalyst selection against lifecycle cost and operational fit rather than headline price; incorporate service and lifecycle assurances into procurement decisions.
-
Catalyst producers: Focus R&D on cobalt conservation, extended life chemistries and performance under variable feeds to differentiate in an oligopolistic market.
-
Investors and M&A teams: Evaluate targets for technical depth, supply‑chain resilience and aftermarket service economics; consolidation is likely to remain a theme.
-
Policy-makers: Recognize that mineral policy and export regimes have immediate downstream consequences; predictable rules improve downstream capital formation.
Conclusion — how to use this briefing
This briefing synthesizes the high‑impact insights from PW Consulting’s Como Catalyst Market report and translates them into actionable choices for 2026. The full report contains the underlying market model, supplier matrices, scenario outputs and operational templates required to implement the recommendations, while intentionally withholding detailed segmented tables within this public release to preserve the strategic value of primary data.
Next steps
For executives, procurement leads and investors seeking to operationalize these insights, PW Consulting offers tailored workshops that apply the Como Catalyst Market models directly to your asset base or portfolio. Visit the report landing page to access the full dataset, scenario models and a downloadable executive toolkit.
For detailed analysis of this topic, please visit the official page: Como Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti‑Tamper Software Market Poised to Reach USD 2,014.9 Million by 2032, Expanding at a 15% CAGR
By PW Consulting, 2026-07-13
Anti-Tamper Software Market 2026: Strategic Imperatives for Risk-Aware CIOs and Product Leaders
Executive preview
PW Consulting’s latest market study—anchored on a 2025 base year and covering historical performance (2020–2025) with a forecast window through 2032—provides a data-driven strategic compass for organizations buying, building, or investing in anti-tamper software in 2026. At the macro level, the global anti-tamper software market has accelerated from a low hundreds of USD Million in 2020 to a substantially larger base in 2025 and is projected to grow at a 15.0% compound annual growth rate (CAGR) through 2032, reaching just over USD 2.0 Billion (USD Million units). This trajectory reflects rising commercial, regulatory, and national-security drivers that make tamper-resilience a board-level priority rather than a niche engineering concern.
Anti Tamper Software Market
Why this matters for 2026 decision-making
-
Risk posture is shifting from perimeter-only defenses to application and endpoint assurance. Anti-tamper controls—ranging from code obfuscation and runtime application self-protection (RASP) to hardware-integrated sensors and cryptographic cores—are now core to preserving product integrity, monetization models, and exportability of strategic systems.
Anti Tamper Software Market -
Regulatory and procurement forces are converging with technical risk: defense directives and program protection policies, together with industry-specific compliance requirements and an expanding patchwork of state-level privacy laws, are increasing the compliance premium for demonstrable tamper protection.
Anti Tamper Software Market -
Market concentration indicates a competitive landscape where a handful of specialist vendors and broader platform providers account for a meaningful share of value—creating clear opportunities and trade-offs for buyers evaluating vendor lock-in, technical depth, and lifecycle support models.
What the report contains (practical, operational deliverables)
-
Executive decision frameworks that translate threat scenarios into procurement requirements and technical acceptance criteria—designed for CISOs, heads of product security, and procurement leads.
-
Vendor scorecards and use-case mappings that compare candidate solutions across protection techniques (obfuscation, RASP, white-box cryptography, hardware sensors), deployment models, and integration effort—presented without vendor revenue breakdowns in the public summary but fully detailed in the full report.
-
ROI and TCO modeling templates calibrated to the 2026 cost environment—covering development lift, DevSecOps upskilling, maintenance, and incident-reduction benefits.
-
Procurement and contract playbooks with model SOWs, acceptance tests, and IP/escrow clauses for both commercial and defense-context purchases.
-
Scenario-driven roadmaps for tiered adoption: protect-first (critical IP), integrate-first (DevSecOps), and platform-first (cloud-native/no-code) strategies—each with milestones, staffing, and budgetary guardrails.
-
Technical annexes detailing attack taxonomies, detection heuristics, and recommended telemetry for continuous assurance.
Competitive landscape — practical implications
The market mixes specialist application-shielding firms, platform vendors offering embedded anti-tamper as a module, and hardware-focused players providing tamper-resistant IP and cryptographic cores. Select observations with direct procurement relevance:
-
Established application-protection specialists provide deep, multi-platform protections (mobile, desktop, IoT, gaming). Their strengths lie in mature obfuscation, runtime integrity checks, and toolchains that integrate into CI/CD pipelines—reducing time-to-hardening for legacy portfolios.
-
No-code and low-code entrants have emerged as accelerants for organizations with limited native security engineering capacity. These solutions dramatically reduce integration friction for mobile and web apps, but buyers must validate long-term maintainability and licensing models in enterprise contexts.
-
Hardware and SoC-focused vendors are increasingly relevant where anti-tamper must cross the software/hardware boundary—defense, high-value IP, and safety-critical industrial systems. Their offerings are complementary to software shielding and often required to meet classified or export-controlled program protection requirements.
-
M&A and asset transactions are reshaping supplier capabilities. Recent asset sales and partnerships have consolidated mobile protection portfolios under specialist vendors, while recognition in user-review platforms is amplifying momentum for cloud-friendly, automated shielding providers. Buyers should expect continued consolidation and should include change-of-control and transition clauses in multi-year contracts.
Vendor highlights (selection)
-
Digital.ai — Broad in-app protection across mobile, IoT, web, and enterprise endpoints; suitable for organizations seeking an integrated application protection component within a broader app lifecycle suite.
-
Guardsquare — Mobile security focus with specialized tooling for Android and iOS; attractive for mobile-first product teams that require deep, platform-specific hardening.
-
Verimatrix — Provider of media and application shielding; note recent strategic asset activity that signals portfolio reshaping in the mobile protection space.
-
Appdome — No-code, automated approach with strong momentum in user reviews; a practical choice for organizations prioritizing rapid deployment and limited in-house security engineering.
-
Irdeto (Denuvo) — Recognized in gaming and media anti-piracy; relevant where runtime integrity and anti-piracy are commercial imperatives.
-
Specialist hardware/IP players (Secure-IC, Rambus, and others) — Required where anti-tamper must live inside silicon, or where side-channel resistance and trusted processing are non-negotiable.
Regulatory and procurement dynamics shaping 2026 choices
-
Defense and program protection policies increasingly mandate anti-tamper measures as part of acquisition and exportability strategies—buyers supporting defense programs should align implementation plans with current directives and program protection instructions.
-
Regulatory compliance across finance, healthcare, and public sectors is elevating the bar for demonstrable application integrity; anti-tamper controls are now often cited in audit narratives and incident post-mortems.
-
State-level privacy laws and evolving data-residency requirements increase the complexity of cloud vs on-premises deployment decisions for integrity tooling. Legal and procurement teams must coordinate early in vendor selection.
Actionable recommendations for 2026
-
Map protection needs to attacker models. Start with a prioritized asset register (IP, monetization flows, safety-critical functions), then select protection techniques proportionate to the threat and program value.
-
Adopt a layered protection architecture. Combine software shielding, runtime integrity monitoring, telemetry for anomaly detection, and hardware-level controls where required. Avoid single-point reliance on obfuscation alone.
-
Embed anti-tamper into the SDLC. Allocate budget for DevSecOps training and CI/CD integration to make protection repeatable and maintainable—this materially reduces long-term lifecycle costs versus ad-hoc hardening.
-
Negotiate continuity protections. Given recent and ongoing market consolidation, insist on transition, escrow, and step-in rights in multi-year contracts to mitigate vendor-risk.
-
Validate operational metrics. Require vendors to supply verifiable telemetry and incident-case histories, and run adversarial acceptance tests (red-team scenarios) as part of procurement acceptance criteria.
-
Plan for workforce uplift. Implementation of advanced anti-tamper and AI-enabled detection capabilities requires specialist skills; include training and third-party services in initial procurement planning.
How PW Consulting’s report adds value
-
We translate macro projections (15.0% CAGR through 2032 and an overall market scale that crosses the USD Billion threshold in our forecast) into specific procurement, architecture, and M&A decision levers for 2026.
-
Our vendor evaluations combine technical test results, customer-feedback analysis, and commercial risk scoring—producing pragmatic shortlists aligned to enterprise constraints and program-specific threat models.
-
The report’s tactical annexes include contract language templates, CI/CD integration checklists, and red-team playbooks that buyers can operationalize within 90 days.
Next steps
This article is a strategic preview. The full report contains the comprehensive regional and vertical segmentation, vendor-by-vendor financial and technical scorecards, and downloadable decision-support templates that enterprise teams and investors need to execute in 2026. To access the complete analysis—including the detailed segmentation and the proprietary vendor matrix—visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Anti Tamper Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flat Panel Loudspeaker Market Set to Grow at a 6.81% CAGR Through 2032
By PW Consulting, 2026-07-13
Flat Panel Loudspeaker Market: Strategic Intelligence to Frame 2026 Decisions
Executive summary
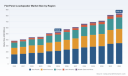
PW Consulting’s new Flat Panel Loudspeaker Market report synthesizes five years of historical performance (2020–2025) with a seven‑year forecast (2026–2032) to deliver decision-ready insight for manufacturers, systems integrators, investors and specification‑driven buyers. The market has expanded from USD 385.12 Million in 2020 to USD 529.09 Million in 2025, and our modeling shows continued expansion into the next decade — with the market projected to grow at a 6.81% CAGR over 2026–2032, approaching roughly USD 839.09 Million by 2032. This trajectory masks substantial technology- and channel‑level shifts that will determine winners and losers in 2026 and beyond.
Flat Panel Loudspeaker Market
Why this matters for 2026 planning
- Market momentum: The recent step‑change in absolute market scale between 2023 and 2025 signals a transition from early adoption to scaling commercial opportunities across select verticals. Companies planning launches, capacity investments, or strategic pivots in 2026 need demand‑validated roadmaps — not intuition.
- Technology differentiation: Multiple flat panel wave‑generation technologies (bending‑wave/DML derivatives, planar magnetic, piezo/magnetostatic variants and hybrid BMR designs) are converging in capability but diverge on manufacturability, cost‑to‑serve, and channel fit. Technology choice will be a primary determinant of margin performance and commercial traction in 2026 product portfolios.
- Concentration and opportunity: The market exhibits a moderate concentration profile (top‑3 and top‑5 firm CR metrics indicate mid‑range consolidation). This creates pockets where focused scale and distribution partnerships can unlock outsized returns without needing category‑leading share.
Market dynamics and near-term shocks
Several structural and transitory forces will shape 2026 outcomes:
Flat Panel Loudspeaker Market
- Tariff complexity: Recent U.S. tariff actions have created what industry participants describe as a "tariff inversion" — in some cases higher duties on components than on finished loudspeakers — materially affecting offshoring economics and assembly footprints. Sensitivity to tariff scenarios must be built into 2026 sourcing plans and supplier negotiations.
- Semiconductor and amplifier IC volatility: Lead‑times for DSP and Class‑D amplifier ICs have at times exceeded 26 weeks into 2025, and platform redesigns to accommodate alternative ICs have incurred development costs in the USD 50,000–200,000 range per platform, plus delayed launches up to six months. Procurement strategies and design modularity are therefore immediate priorities for 2026 roadmaps.
- Specification vs. perception: As flat panel solutions migrate from niche audiophile and museum roles into mainstream AV and automotive consideration sets, procurement teams will increasingly require third‑party verification of coverage, speech intelligibility, and distortion metrics. Vendors that codify and publish verifiable performance credentials will shorten sales cycles in 2026.
Competitive landscape — strategic takeaways
Our report profiles the vendors shaping the category and decodes practical implications for partners and competitors. Highlights:
Flat Panel Loudspeaker Market
- FlatPanel Audio (San Jose): A DML‑centric supplier positioning for professional AV installations. Their DML500 family — including weatherized and in‑ceiling/ceiling variants — is optimized for diffuse soundfields and reverberant spaces. For 2026, FlatPanel Audio’s playbook is instructive for companies targeting specification channels: marry product variants to installer workflows and complementary subwoofer/amplifier ecosystems.
- Magnepan (White Bear Lake): A high‑end planar magnetic incumbent focused on audiophile and reference‑grade deployments. Their value proposition emphasizes handcrafted quality and fidelity improvements. For businesses evaluating premium segments in 2026, Magnepan demonstrates the value of brand equity and field‑proven performance as margin protection.
- Flatt Speakers (Phoenix): Thin, durable planar transducers with strong directivity and weather resistance suited to intelligibility‑critical installs. Their MCMA technology underscores a category pathway where robustness and reduced unit counts deliver TCO advantages for system integrators.
- Tectonic Audio Labs (Woodinville): Developer of bending‑wave and BMR solutions with a broad addressable set across pro audio, consumer and automotive. Their recent product showcases illustrate how component‑level innovation (drive units, exciters) can open platform licensing and OEM supply opportunities — a potential strategic axis for 2026 revenue diversification.
- Brown Innovations & Wisdom Audio: Brown’s directional ceiling/tiling form factors and Wisdom’s high‑performance planar line‑source offerings highlight two profitable roles vendors can adopt — targeted, specification‑driven systems for museums and exhibits (Brown) versus high SPL, multi‑octave performance for premium home and commercial installs (Wisdom).
Recent product and channel movements to watch
- Tectonic’s CES 2025 showcase and new drive units signal renewed OEM interest in flat diaphragm solutions for both immersive and distributed applications; expect OEM licensing conversations and sample programs to accelerate in 2026.
- Brown Innovations’ 2025 trade show activity demonstrates the ongoing strength of the directional audio niche — companies that can pair focused hardware with installation‑grade control and accessibility options will secure repeat institutional business.
- FlatPanel Audio’s 2024 InfoComm debut is emblematic of a broader trend: vendors are increasingly selling through architect/specification channels; success demands bundled system design, training and reference builds rather than single SKU transactions.
Strategic recommendations for 2026 (what to do now)
PW Consulting recommends a three‑layer approach for executives planning 2026 moves — Protect, Pivot, and Prove.
- Protect (supply chain resilience)
- Run tariff sensitivity scenarios and re‑price BOMs under inversion stress cases. Consider near‑shoring select assembly steps where labor and tariff math justify localized integration.
- Execute dual‑sourcing for critical ICs or modularize power and DSP subassemblies to enable rapid board swaps without full‑platform redesigns.
- Pivot (portfolio and GTM)
- Identify two commercial plays to pursue in 2026: a high‑value specification channel for commercial/professional builds and a volume play for targeted consumer/automotive partnerships. Each requires distinct productization, channel incentives and returns thresholds.
- Prioritize product roadmaps that reduce total installed cost (fewer drivers per coverage area, integrated mounting, weatherization options) to expedite acceptance in AV/architectural specs.
- Prove (commercial credibility)
- Invest in third‑party acoustic validation and speech intelligibility testing to shorten procurement evaluation cycles. Publish installation case studies and verifiable performance data tied to real‑world environments.
- Where applicable, develop OEM/technology licensing offers (drive units, exciters, subwoofer pairings) to monetize IP while minimizing capital outlays for scale.
What PW Consulting’s report delivers (practical content)
This release is designed as an operational playbook, not an academic paper. Key deliverables include:
- Top‑down market sizing and CAGR forecasts with sensitivity scenarios calibrated to tariff and component‑supply volatility.
- Segmentation frameworks by region, technology and application with strategic implications and go‑to‑market maps (note: detailed numeric splits and proprietary model outputs are available in the full report).
- Vendor diligence dossiers (product roadmaps, distribution footprints, go‑to‑market strengths and weaknesses) for the major players shaping the category.
- Supply‑chain risk matrix and mitigation playbooks addressing tariffs, semiconductor lead times and alternative sourcing strategies.
- Commercial tools: market entry checklists, ROI templates for platform investments, M&A screening criteria and 12‑month tactical milestones for scaling in specification channels.
How to use the analysis in boardroom and product planning
For CEOs and product chiefs, the report turns market forecasts into prioritized decisions: where to allocate R&D, whether to pursue licensing versus direct manufacturing, and how to structure channel incentives for 2026. For CFOs and corporate development teams, the CR3/CR5 concentration context and scenario P&L models inform valuation assumptions for M&A and JV negotiations. For supply‑chain and procurement leads, the tariff and semiconductor modules provide executable contingency plans with clear cost and timing tradeoffs.
Next steps and how to get the full intelligence
PW Consulting’s executive summary above is intentionally selective: we reveal market scale and the directional forces you must plan around, while preserving the granular, model‑level outputs that clients use to operationalize strategy. Access to the full report unlocks the detailed segment matrices, regional demand projections, commercial model spreadsheets and vendor scorecards necessary to execute confidently in 2026.
- If you are evaluating portfolio moves, supply‑chain redesigns, or inorganic transactions in the flat panel loudspeaker space for 2026, PW Consulting can provide targeted briefings, scenario workshops and custom financial models derived from the full study.
- Visit the PW Consulting report page to request the full report, schedule a briefing, or commission a bespoke strategic due diligence tailored to your organization’s role in the ecosystem.
In an industry where product form factor, directivity and manufacturability now intersect with trade policy and chip scarcity, 2026 will reward companies that combine engineering clarity with pragmatic commercial design. Our analysis equips leaders to make those choices with confidence — and to act quickly while the market’s growth and disruption windows remain open.
For detailed analysis of this topic, please visit the official page: Flat Panel Loudspeaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Camouflage Netting Market to Expand at a 7.25% CAGR as Defense Demand Drives Growth
By PW Consulting, 2026-07-13
Camouflage Netting Market — Strategic Outlook for 2026: Tactical Intelligence for High‑stakes Decisions
PW Consulting’s new Camouflage Netting Market report is the definitive strategic resource for executives, procurement leads, product teams, and investors who must make decisions in 2026 with multi‑year consequences. At a market size of USD 745.2 Million in our 2025 base year and an expected expansion to approximately USD 812.6 Million in 2026, the sector is set to grow at a compound annual growth rate (CAGR) of 7.25% through 2032, when our forecast reaches roughly USD 1.22 Billion. These headline figures understate a far more important story: a market being reshaped by multispectral sensor threats, defence procurement windows, raw material volatility, and a rapidly diversifying set of commercial end‑uses. This briefing explains why those who act in 2026 will create asymmetric advantage through positioning, partnerships, and targeted capability investments.
Camouflage Netting Market
Why this report matters for 2026 decision cycles
-
Timing matters: Defence procurement cycles and a renewed emphasis on multispectral signature management are translating into near‑term demand spikes for advanced netting solutions. Companies that align production, certification and tender readiness in 2026 will capture outsized share during follow‑on contract awards.
Camouflage Netting Market -
Technology is a differentiator: Modern camouflage systems now compete on their ability to defeat visual, near‑IR, shortwave IR, thermal and radar sensors simultaneously. The winners combine materials science, modularity and platform integration rather than competing on price alone.
Camouflage Netting Market -
Supply chain sensitivity: Polyester‑based materials remain the backbone of the category because they balance strength, weight and cost. At the same time, resin price volatility materially affects margins and must be modelled into 2026 budgets and supplier agreements.
-
Sustainability and new markets: Pressure to incorporate recycled feedstocks and plant‑based fibres is growing—creating both product development risk and an opportunity to win non‑defence commercial contracts with demonstrable ESG credentials.
What the PW Consulting report delivers — practical, transaction‑grade insight
This is a hands‑on strategy product, not a high‑level summary. The report equips decision makers with:
-
Tactical procurement playbooks tailored to defence and commercial buyers, including checklist templates for testing multispectral performance, contract clauses to mitigate raw material price swings, and ramp‑up timelines to support urgent orders.
-
Supplier capability matrices and a vetted shortlist process to identify partners by technical capability, production scale, and geopolitical footprint. (Note: our public summary highlights capabilities; detailed segment‑level supplier shares and financials are available in the full dataset.)
-
Product roadmaps and R&D priorities that reconcile performance targets (e.g., thermal suppression at scale) with manufacturability and unit economics.
-
Scenario modelling (three demand/risk scenarios through 2032), plus sensitivity analyses that quantify the P&L impact of raw material price swings and procurement timing shifts.
-
An M&A and partnership playbook highlighting adjacencies (advanced textiles, sensor defeat coatings, modular concealment architectures) and valuation frameworks appropriate to this mid‑market vertical.
Competitive landscape — capabilities to watch in 2026
The market exhibits a mixed structure: concentrated technology leadership at the top and a broad base of specialized regional and niche suppliers. Our concentration metrics show that leading firms capture meaningful share, yet there remains ample room for strategic challengers and consolidators.
-
Saab (Barracuda): Global leader in multispectral systems. Saab’s Barracuda family epitomizes high‑performance, lightweight solutions designed for platform integration and broad spectrum signature management. Their strength is R&D depth and established relationships with major defence integrators.
-
Fibrotex Technologies / Fibrotex USA Inc.: A major supplier of ultra‑lightweight multispectral systems with deep engagement in modern army programs. Recent contract awards and integrations into national camouflage programs underscore their tactical positioning.
-
CamoSystems: A flexible manufacturer focused on treated/coated nets for multispectral suppression and private‑label manufacturing. Their recent product launches signal an aggressive push into IR suppression across both defence and hunting/commercial channels.
-
Camonets and J & S Franklin: Established specialty suppliers providing certified flame‑retardant and entertainment/wildlife solutions. Their niche focus preserves margins and keeps them relevant for non‑tactical market segments.
-
Seyntex, Miranda Military, Nitex and regional players such as Sterlite Camotech: These firms bring differentiated technologies (anti‑radar/3D systems, localized manufacturing footprints, competitive pricing) that matter in procurement decisions where proximity and sovereign supply are valued.
Recent market activity underscores these dynamics: major contract awards to leading multispectral manufacturers, multiple product launches focused on IR suppression, and public tenders from defence departments testing expeditionary and netting systems. For 2026 procurement strategists, monitoring supplier announcements and active tenders is operationally essential.
Market structure implications: concentration and consolidation
The market exhibits moderate concentration: a handful of firms collectively represent a significant portion of commercial activity while a larger group serves specialty and regional demand. For incumbents, this points to three realistic strategic plays: deepen technology differentiators to defend share; pursue targeted acquisitions to broaden capability; or double down on low‑cost manufacturing for volume business. New entrants should focus on narrow performance niches or high‑growth commercial adjacencies to avoid head‑on competition with entrenched multispectral incumbents.
Supply chain and raw material risk — actionable mitigation
-
Hedge and contract: Given the exposure to polyester resin and polymer price swings, buyers and manufacturers should consider multi‑year supply agreements with price bands, indexed pass‑throughs, or financial hedges where liquid instruments exist.
-
Dual sourcing and nearshoring: Where defence programmes require assured supply, build redundancy across geopolitical boundaries and qualify local suppliers for surge capacity testing.
-
Sustainable alternatives as an insurance policy: Pilot recycled and plant‑based yarns in non‑critical commercial lines first. Capture lessons on durability and sensor performance before scaling to defence applications.
A 2026 strategic playbook — four prioritized moves
-
For manufacturers: Accelerate certification paths for multispectral performance and create modular product families that can be rapidly configured for specific platform footprints. Lock in strategic raw material agreements this year to stabilize 2027 cost forecasts.
-
For defence contractors/OEMs: Integrate camouflage systems as a configurable subsystem with clear performance acceptance criteria. Pre‑qualify multiple suppliers to maintain negotiating leverage during tender awards.
-
For distributors and commercial brands: Leverage product differentiation (thermal suppression coatings, fire retardancy, private‑label flexibility) to expand into film, events and wildlife markets, where higher margins can subsidize R&D for tactical products.
-
For investors and M&A teams: Target bolt‑on acquisitions that add multispectral capability, seal supply chain risk, or provide access to defence channels. Valuations should reflect the time value of certification and procurement lead times—expect integration horizons of 12–24 months.
Risk scenarios to stress‑test 2026 plans
-
Defence surge scenario: Accelerated procurement leads to supply shortages and price inflation for raw materials—mitigate with supplier contracts and surge manufacturing plans.
-
Material shock scenario: Volatile polyester inputs compress margins—use cost sensitivity models to determine price‑pass mechanisms or product redesigns using alternative substrates.
-
Regulatory and sustainability push: Stricter environmental requirements force reformulation—accelerate laboratory testing and stagger commercial and defence roll‑outs to manage certification risk.
How to use the full PW Consulting dataset
Our public briefing demonstrates the analytical frame and tactical granularity you need, while intentionally reserving the full segment‑level breakdowns that commercial users require to execute. The complete report provides year‑by‑year market sizing, validated supplier profiles, detailed segmentation across materials and applications, and an annex with sourcing scorecards and bid response templates. If your 2026 plan requires precise allocation by material, region or application (the inputs used to build procurement commitments, inventory plans and capex), those tables and model files are available through the full report package on our website.
Concluding recommendation
2026 is a pivotal year: market growth is healthy, but the competitive landscape and supply chain realities mean that first movers with disciplined risk management and focused capability investments will outperform. PW Consulting’s Camouflage Netting Market report translates sector dynamics into executable decisions—tender readiness, supplier selection, product development prioritization and M&A targets—without sacrificing the confidentiality you need for negotiation. For teams preparing 2026 budgets and strategic plans, the question is simple: do you want directional insight, or the transaction‑grade, segment‑level intelligence required to win the next contract?
Contact PW Consulting to access the full dataset, supplier scorecards and the tactical playbooks that will convert market growth into sustainable advantage.
For detailed analysis of this topic, please visit the official page: Camouflage Netting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Mold Flux for Continuous Casting Market to Expand at a 3.85% CAGR Through 2032 as Asia‑Pacific Leads DemandPW Consulting: Laser Spectrum Analyzer Market Forecast to Hit USD 700.1 Million by 2032
By PW Consulting, 2026-07-13
Mold Flux for Continuous Casting Market — Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s new market study on Mold Flux for Continuous Casting (base year 2025, forecast 2026–2032) distills technical nuance, commercial dynamics, and competitive maneuvering into an actionable guide for executives, procurement leaders, and investors preparing for 2026 decisions. The global market — measured in Million USD — has demonstrated steady expansion through the 2020–2025 historical window and is forecast to continue growing at a compound annual growth rate (CAGR) of 3.85% over 2026–2032. Our central conclusion for 2026: this is a transition year in which raw‑material exposure, regulatory compliance, and supply‑side consolidation will determine winners and losers across the steel value chain.
Mold Flux For Continuous Casting Market
High‑level market snapshot (what the macro numbers mean for strategy)
-
Market tempo: After a recovery phase in the early 2020s, demand for mold fluxes is advancing on a moderate but resolute trajectory. The 3.85% CAGR to 2032 implies predictable unit demand growth but increasing importance of margin capture via formulation, logistics, and technical services.
Mold Flux For Continuous Casting Market -
Scale and timing: With the report’s 2025 base, our model shows the market reaching materially higher aggregate revenue through the forecast window—enough to underpin new capacity investments and M&A activity, but not so rapid as to insulate incumbents from disruption.
Mold Flux For Continuous Casting Market -
Concentration: Market concentration metrics (CR3 ~38.5%; CR5 ~52.1%) indicate a midly consolidated supplier set—large enough for leading firms to influence standards and pricing, yet porous enough for specialty entrants and regional champions to capture niches.
What the PW Consulting report delivers — practical, decision‑ready intelligence
We designed the report for executives who need to convert insight into action. Key operational and strategic tools included:
-
Scenario models (three trajectories) showing demand sensitivity to steel production mix, decarbonization timelines, and raw‑material cost shocks.
-
Supplier capability matrix — technical depth, spray‑dry capacity, R&D orientation, and aftermarket service footprint — enabling rapid shortlisting for partnerships, qualification, or competitive benchmarking.
-
Technology roadmap — mapping conventional fluorine‑rich systems, low‑fluorine and fluorine‑free alternatives, and carbon‑free powders against metallurgical performance, equipment compatibility, and compliance risk.
-
Procurement playbook — sourcing strategies (vertical integration vs. multi‑sourcing), inventory tactics for volatile minerals, and a price‑sensitivity framework for contract design.
-
Regulatory and environmental checklist — jurisdictional compliance obligations, emissions control best practices, and reformulation levers to reduce harmful constituents while preserving casting performance.
-
M&A and partnership shortlist — targets and archetypes (craft premium producers, regional capacity hubs, technical R&D studios) aligned to consolidation scenarios and margin enhancement pathways.
-
Operational protocols — quality testing thresholds, trial design templates, and troubleshooting guides for slab, billet and bloom casting environments (keeps formulation-level confidentiality while enabling practitioners to implement trials effectively).
Market dynamics shaping 2026 strategic choices
-
Raw‑material sensitivity: Mold flux formulations rely on a predictable basket of minerals (quartz, wollastonite, fluorite/CaF2, lime, silica, alumina and borates). Price and availability volatility in any of these inputs materially affect supplier margins and create procurement risk for steelmakers that lack secondary sourcing.
-
Regulatory and environmental pressure: There is a clear industry pivot toward low‑fluorine and fluorine‑free systems, and toward carbon‑free powders for ultra‑low‑carbon steels. These trends are being driven by equipment‑corrosion limits, workplace safety regulations, and broader emissions control programs. The implication for 2026 is immediate: firms that have not validated alternative chemistries risk access constraints or retrofit costs in short order.
-
Supply‑side consolidation and capability buildout: Recent moves—targeted acquisitions and greenfield investments—are concentrating technical know‑how and production capacity in strategic locations. These shifts change the bargaining dynamics between steelmakers and suppliers and create new options for localization and co‑development.
-
Specialization premium: Small‑batch, craft producers that pair high R&D intensity with flexible manufacturing (premium powders for thin slab, specialty steels, or low‑fluorine mixes) are increasingly attractive acquisition targets for larger refractory players seeking product differentiation.
Competitive landscape — signals to watch in 2026
The market includes global engineering suppliers, large refractory groups, and regional manufacturers. Notable dynamics and strategic moves observed in the last 24 months include:
-
Strategic aggregation: Shinagawa Refractories’ acquisition of a majority stake in a U.S. premium craft producer in early 2026 demonstrates a two‑pronged playbook — combine artisanal R&D capability with global distribution scale. Expect more controlled acquisitions aimed at technology access rather than pure volume.
-
Capacity and localization investments: Major suppliers are expanding footprint in high‑growth regions — a development visible through new plant inaugurations and planned hubs. These moves shorten lead times, reduce logistics risk, and position owners to capture regional content premiums.
-
Incumbent advantage with caveats: Established firms that supply integrated steel groups or long‑standing customers retain privileged access and channel stability, but they must demonstrate competence in low‑fluorine systems to retain market share as environmental limits tighten.
-
Regional champions: Several domestic producers in Asia, India, South Africa and China continue to meet cost‑sensitive demand and can rapidly scale for local mills; partnerships or licensing agreements with these players are pragmatic routes for multinationals seeking rapid market entry.
Strategic recommendations for 2026 — prioritized actions
-
For steelmakers: Execute a dual sourcing strategy that pairs a global, technically advanced supplier for critical formulations with an agile regional partner for spot volume and local compliance. Start pilot programs this year to validate fluorine‑reduced and carbon‑free powders for the most sensitive steel grades.
-
For flux producers: Prioritize R&D investments into low‑fluorine and fluorine‑free chemistries, and develop modular production lines that can switch between granular, spray‑dried, and pre‑fused formats with minimal downtime. Explore acquisitive growth focused on premium small‑batch manufacturers to accelerate capability acquisition.
-
For investors: Target mid‑tier refractories and specialty flux producers that combine technical IP with underutilized capacity in strategic geographies. Look for assets with validated pilot trials for low‑fluorine powders or with established co‑development agreements with steelmakers.
-
For procurement teams: Build an input‑price hedge playbook for volatile minerals, and include technical performance KPIs in long‑term contracts to avoid quality drift. Mandate environmental‑compliance covenants for any supplier selected in 2026.
Risk matrix — what can derail 2026 plans
-
Input shocks: Sudden spikes in fluorite, wollastonite or borates can compress margins and force reformulation under time pressure.
-
Regulatory acceleration: Faster‑than‑expected bans or equipment‑level corrosion limits on fluorides would accelerate demand for alternative chemistries and potentially strand investment in older spray‑dry assets.
-
Technical performance gaps: Reformulated fluxes that fail to match inclusion control or thermal behavior can produce costly casting defects; robust trial protocols and co‑development governance are essential mitigants.
-
M&A integration failure: Acquisitions intended to buy technology can erode value if integration neglects shop‑floor know‑how or client trust—particularly with craft producers whose value is people and tacit process knowledge.
How PW Consulting’s report helps you act in 2026
This study provides the playbook and the decision tools needed to translate macro forecasts into executable programs in 2026: from supplier selection and pilot planning to capex justification and M&A target screening. We intentionally preserve proprietary segment detail and granular regional splits within the full report to protect our modeling assumptions and to provide subscribers with exclusive diagnostic datasets and supplier scorecards.
Conclusion — the 2026 inflection
2026 will be defined less by headline demand growth and more by choices: who controls access to cleaner formulations, who secures resilient mineral supply chains, and who pairs metallurgical performance with regulatory foresight. With a predictable market growth trajectory (3.85% CAGR through 2032) and a mid‑concentrated supplier landscape, the returns to timely strategic action are significant. Firms that move early to derisk raw materials, validate low‑fluorine formulations, and build partnership ecosystems will convert modest market growth into durable competitive advantage.
To access the full set of diagnostic tools, supplier matrices, scenario models and proprietary datasets referenced here, please visit PW Consulting’s Mold Flux for Continuous Casting Market report page or contact our strategy team for a briefing and trial access to the executive dashboard.
For detailed analysis of this topic, please visit the official page: Mold Flux For Continuous Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Lead‑Based Rare Earth Alloy Market to Grow at 5.0% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
Lead-Based Rare Earth Alloy Market: Strategic Imperatives for 2026 — Preview of PW Consulting’s Market Intelligence
Executive snapshot
As PW Consulting’s lead industry strategist, I present a forward-looking synthesis of our latest Lead Based Rare Earth Alloy Market report — the one-stop strategic playbook designed to inform executive decisions in 2026. The global market has demonstrated steady expansion from our historical baseline (2020–2025) and, with a projected compound annual growth rate (CAGR) of 5.0% over the 2026–2032 forecast window, is expected to move from a 2025 base of USD 306.0 Million to a materially larger market by 2032. This preview outlines the principal dynamics that will shape near-term corporate choices, while reserving our full segment-level intelligence — pricing scenarios, regional and application splits, and detailed financial models — for the full report.
Lead Based Rare Earth Alloy Market
Why this market matters now
Lead-based rare earth alloys remain a niche but strategically important material class. They sit at the intersection of traditional heavy-industry demand (notably battery grids and radiation shielding) and emerging supply-chain sensitivities driven by rare earth feedstock availability and geopolitical shifts. For manufacturers, battery OEMs, materials traders, and private investors, the coming 24 months will be decisive: supply-side constraints, regulatory pressures, and input price volatility will determine who captures margin and who is forced into defensive positions.
Lead Based Rare Earth Alloy Market
Market trajectory and what the headline numbers mean
-
Historical momentum: The market expanded meaningfully across 2020–2025, reflecting both steady end-use demand and incremental substitution of specialty alloys in traditional applications.
Lead Based Rare Earth Alloy Market -
Base year and forecast baseline: With 2025 as our reporting base (USD 306.0 Million), our scenarios model a 5.0% CAGR across 2026–2032 under a central-case macro environment — an outcome consistent with continued industrial demand and moderate expansion of downstream capacity.
-
Strategic implication: The scale and pace of growth are sufficient to justify selective capacity additions and targeted M&A, but not to support indiscriminate expansion — firms must prioritize efficiency, input security, and product differentiation.
Dynamics shaping 2026 decisions
Several high-impact dynamics converge as companies plan capital allocation, sourcing strategies, and product roadmaps for 2026:
-
Upstream feedstock volatility — rare earth concentrate pricing has become a defining input risk. Recent industry-level benchmarks show a sharp quarter-over-quarter increase in negotiated concentrate prices in Q2 2026, reflecting tighter supply and active repositioning by major rare earth producers. That trajectory compresses gross margins for alloy makers that cannot rapidly pass costs through.
-
Policy and reshoring incentives — government financing and loan programs (notably initiatives in 2025 supporting rare earth metallization and separation) are beginning to alter the global supply chain map. These policies reduce concentration risk over the medium term but create transitional winners and losers in 2026 as new capacity and domestic processing lines come online.
-
Regulatory and sustainability pressure — lead toxicity remains a material regulatory constraint. Environmental, health, and transport regulations shape both production cost and market access. Firms that invest in cleaner processing, occupational safety, and traceable supply chains will find premium market access and lower regulatory risk.
Competitive landscape — who matters and why
The market exhibits moderate concentration (CR3 approximately 42.2%; CR5 approximately 58.4%), indicating notable incumbent scale advantages but also room for niche specialists. Our competitive assessment highlights several archetypes:
-
Integrated major producers: Large, vertically integrated firms with upstream lead and rare earth inputs command cost and security advantages. These players typically supply battery-grid markets and industrial alloys through integrated logistics and captive feedstocks.
-
Resource-backed smelters and refiners: Companies with adjacent non-ferrous metals portfolios (zinc, germanium, copper) use cross-commodity synergies to optimize yield and diversify raw material risk, often offering specialized alloy grades for industrial customers.
-
Specialist alloy fabricators: Niche manufacturers focus on higher-value forms — master alloys, wires, foils, and custom purity grades — serving customers with strict metallurgical specs. These players can command margin premiums for product breadth and technical service.
Representative firms we profile in the full report include established integrated producers and specialist fabricators, each with differentiated strengths in feedstock integration, product portfolio, and route-to-market. Our corporate scorecards evaluate capex plans, technological capabilities, balance-sheet resilience, and likely 12–24 month strategies — from capacity ramp-up to selective divestment.
Supply chain and pricing — tactical levers for 2026
Executives must treat feedstock procurement and pricing as front-line strategic issues. Our research shows that the most effective immediate actions include:
-
Negotiate multi-year offtake agreements with price collars to smooth input cost volatility;
-
Pursue vertical tie-ups or minority stakes in upstream concentrate production where feasible to secure allocation;
-
Invest in downstream product differentiation (specialty alloys and forms) to reduce pure commodity exposure and enhance margin capture;
-
Implement incremental efficiency and decarbonization projects that also mitigate regulatory risk related to lead handling.
Sector opportunities and strategic playbook
Based on scenario modeling, we identify four pragmatic strategic plays companies should evaluate in 2026:
-
Secure-to-grow: For firms with balance-sheet capacity, targeted capacity additions near stable power and logistics hubs can capture demand upside while controlling quality and emissions.
-
Niche leadership: Technical specialization (e.g., high-purity master alloys, tailored strip/foil forms) enables margin expansion without heavy capex-led exposure.
-
De-risk and hedge: Financial and physical hedging of rare earth feedstocks, plus contractual customer protections, reduce earnings volatility during input-price shocks.
-
Collaborative resilience: Strategic alliances — joint ventures for separation, recycling partnerships, and shared processing platforms — address both feedstock scarcity and regulatory compliance costs.
What PW Consulting’s full report delivers (practical, actionable assets)
Our research is built for decision-makers. The full report provides:
-
Granular market sizing and a transparent bottom-up model covering 2020–2032 (base year 2025) with scenario toggles to stress-test demand and price assumptions;
-
Segmentation matrices by region, type, and application with defensible assumptions and sensitivity analysis (note: segment tables and exact percentage splits are available in the full report);
-
Company scorecards and an M&A shortlist with an assessment of strategic fit, value creation potential, and integration risks;
-
Supply-chain maps highlighting choke points in concentrate supply, processing capacity, and logistics, plus tactical playbooks for procurement and offtake negotiations;
-
Regulatory and ESG risk register with mitigation options and costed compliance pathways;
-
Go-to-market frameworks for product differentiation, channel strategy, and customer contracting (including a 100-day rapid-response plan for price-shock events).
Risk matrix — what keeps CFOs awake
Key downside risks we model include prolonged rare earth concentrate tightness, accelerated regulatory restrictiveness on lead use, and abrupt demand erosion in legacy applications. Upside risks are faster-than-expected domestic processing capacity additions (reducing supply concentration) and technical breakthroughs that increase rare-earth utilization efficiency in alloys. Each risk is quantified in the full report and mapped to concrete mitigation steps.
Implications for boardroom decisions in 2026
For executives preparing 2026 capital and commercial plans, the strategic takeaway is straightforward: act with precision, not breadth. Prioritize actions that improve feedstock certainty, product margin, and regulatory resilience. Consider the following near-term moves:
-
Revisit capital allocation: prioritize projects with short payback that improve product mix or lower unit costs;
-
Intensify commercial contracting: renegotiate key customer and supplier agreements to include indexation and protection clauses;
-
Pursue targeted partnerships: joint ventures for separation or recycling can materially lower feedstock exposure;
-
Accelerate compliance investments: early adopters of best-practice environmental controls gain market access and avoid costly retrofits.
Final note — why PW Consulting’s intelligence is different
This report blends detailed financial modeling with on-the-ground intelligence from plant-level capacity audits, procurement channel interviews, and patent analysis. We combine quantitative forecasts (5.0% CAGR baseline, full model anchored to 2025 base-year sizing) with qualitative scenario narratives that operational teams can convert into a 90–180 day action plan. Importantly, while this preview highlights the strategic contours, the full report contains the segment-level breakouts, company profiles, and downloadable models you will need to operationalize these insights.
Call to action
Executives considering investments, partnerships, or restructuring in the lead-based rare earth alloy space should request the full PW Consulting report to access: the downloadable financial model, proprietary supply-chain maps, and our prioritized M&A shortlist. Our team is available for tailored briefings and scenario workshops to translate the research into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Lead Based Rare Earth Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


