



PW Consulting: Non-Destructive Testing Instruments Market to Reach $30.7B by 2032, 9.3% CAGR
By PW Consulting, 2026-09-16
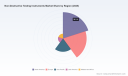
Strategic Imperatives in the Non-Destructive Testing Instruments Market: Navigating Growth Through 2032
The global landscape for non-destructive testing instruments is undergoing a profound transformation, driven by escalating safety mandates, infrastructure aging, and the rapid integration of digital technologies. As industrial sectors worldwide prioritize asset integrity and operational reliability, the demand for advanced inspection solutions has accelerated beyond historical trajectories. Our latest comprehensive analysis, Non-Destructive Testing Instruments Market, provides a critical roadmap for stakeholders aiming to align their strategies with the compounding opportunities projected through 2032. This article outlines the strategic value of this research, synthesizing macroeconomic indicators, competitive dynamics, and emerging industry shifts to underscore why informed decision-making is paramount in the current fiscal year and beyond.
For enterprise leaders, investors, and product strategists, the overarching market narrative is defined by sustained expansion and evolving technological prerequisites. Historical data reveals a consistent upward momentum, with the market valuation climbing from 11.6 billion USD in 2020 to an estimated 16.5 billion USD by 2025. This trajectory is not merely a reflection of post-pandemic recovery but indicative of a structural shift in how industries approach quality assurance and risk mitigation. The forecast period anticipates a robust compound annual growth rate of 9.3 percent, propelling the market valuation toward 18.62 billion USD in 2026 and surpassing the 30 billion USD threshold by 2032. Such figures underscore a fertile environment for capital allocation, product development, and strategic partnerships. However, realizing value within this ecosystem requires navigating a complex web of regional variances, technological bifurcation, and regulatory tightening that only deep-dive intelligence can adequately decode.
Deconstructing the Market Architecture
A superficial glance at aggregate numbers offers limited strategic utility. True competitive advantage lies in understanding the granular mechanics that drive revenue streams across different modalities, end-user sectors, and geographic territories. The research provides a multi-dimensional segmentation analysis that illuminates where growth is concentrated and which sub-markets are maturing versus those poised for disruption.
Technological Modalities and Adoption Curves
The industry is characterized by a diverse array of testing methodologies, each serving distinct operational needs and capital constraints. Ultrasonic testing continues to command significant attention, reflecting its versatility in detecting internal flaws across a wide range of materials without causing damage. Radiographic testing maintains its relevance, particularly in scenarios demanding high-resolution imaging for complex geometries. Simultaneously, magnetic particle testing, eddy current testing, and emerging alternative types cater to specialized applications where surface defects, conductivity variations, or specific material properties are the primary concern.
Non-Destructive Testing Instruments Market
The strategic nuance here is not just in identifying the dominant techniques but in understanding the shifting cost-benefit analyses that influence procurement decisions. High upfront costs associated with advanced instruments, such as phased array ultrasonic and digital radiography systems, remain a barrier for small and medium enterprises. Yet, the pressure on component and sensor pricing is reshaping the affordability landscape. Our analysis dissects these pricing dynamics, average selling price trends, and the subtle trade-offs between capital expenditure and long-term inspection efficacy, enabling organizations to forecast budget requirements and technology roadmaps with precision.
Sectoral Demand Drivers
Demand for NDT instruments is inextricably linked to the operational intensity and safety criticality of downstream industries. The oil and gas sector remains a pillar of consumption, driven by the need to monitor pipelines, refineries, and offshore structures under harsh conditions. Power generation facilities, encompassing both traditional and renewable energy assets, rely heavily on inspection technologies to ensure grid stability and prevent catastrophic failures. Aerospace applications impose the most rigorous standards, where the margin for error is non-existent and regulatory compliance is absolute. Manufacturing, as a broad category, continues to expand its footprint, integrating NDT into production lines for real-time quality control. Other applications further diversify the revenue base, capturing niche but high-growth opportunities in automotive, rail, and marine sectors.
The report delves into the specific demand catalysts within each vertical, highlighting how operational downtime costs, regulatory penalties, and the push for predictive maintenance are reshaping procurement behaviors. By mapping these application-specific drivers, decision-makers can identify high-engagement segments and tailor their value propositions accordingly.
Geographic Value Distribution
Regional dynamics play a pivotal role in shaping market opportunities. North America and Europe represent mature markets with established regulatory frameworks and high adoption rates of advanced technologies. Asia Pacific, while currently reflecting a different scale of valuation, is emerging as a critical growth engine fueled by rapid industrialization, infrastructure development, and increasing awareness of quality standards. Latin America and the Middle East and Africa contribute distinct regional profiles, often tied to resource extraction, energy projects, and localized manufacturing hubs.
The research avoids generic regional summaries, instead providing a nuanced view of how economic policies, trade dynamics, and local industrial priorities influence market penetration. Understanding these geographic nuances is essential for multinational corporations seeking to optimize their distribution networks and for regional players aiming to capture cross-border opportunities.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated structure, with a select group of leading entities commanding a significant share of total revenue. The top three competitors account for approximately 65.5 percent of the market, while the top five collectively hold around 82.2 percent. This concentration indicates the presence of established incumbents with strong technological portfolios, extensive service networks, and deep customer relationships. However, the remaining market share is distributed among a diverse array of specialized firms, creating a dynamic environment where innovation and niche expertise can disrupt traditional hierarchies.
Profiles of Key Industry Participants
The competitive arena is populated by organizations that have carved out distinct identities through technological specialization, geographic reach, and service integration. Mistras Group, Inc., headquartered in Princeton Junction, New Jersey, stands as a leading provider of NDT instruments and field inspection solutions, offering ultrasonic and advanced testing equipment tailored for industrial applications. Olympus Corporation, based in Shinjuku, Tokyo, is a major manufacturer focusing on ultrasonic phased array and thickness measurement systems, leveraging decades of imaging and sensing expertise.
Nikon Metrology NV, located in Tricht, Belgium, supplies X-ray and computed tomography instruments that cater to precision NDT applications, appealing to sectors where detailed internal visualization is paramount. Sonatest Ltd, operating from Hertfordshire, UK, produces portable ultrasonic and eddy current NDT instruments, addressing the need for field-deployable and flexible testing solutions. Acuren Corp., based in Markham, Ontario, Canada, provides advanced NDT equipment and inspection services, with a specialization in phased array and digital radiography instruments that bridge hardware and expertise.
Eddyfi Technologies, from Quebec City, Quebec, develops eddy current and remote NDT instruments specifically designed for pipeline and industrial use, emphasizing reliability in critical infrastructure monitoring. Zetec Inc., situated in San Jose, California, manufactures eddy current and magnetic particle NDT instruments, serving a broad customer base with robust and proven technologies. YXLON International GmbH, headquartered in Hamburg, Germany, produces X-ray NDT instruments and modules, contributing to the radiographic testing ecosystem with high-performance solutions. Fischer Technology Inc., located in Windsor, Connecticut, supplies coating thickness and material analyzers used in NDT contexts, addressing surface measurement and material verification needs. TWI Ltd, based in Cambridge, UK, provides advanced NDT testing instruments and systems for research and industrial use, acting as a bridge between cutting-edge development and practical deployment.
Recent Corporate Developments and M&A Activity
The competitive landscape is further shaped by a series of strategic moves that signal shifting priorities and consolidation trends. In April 2026, NDT Systems launched the BondHub Imaging Bond Tester with C-scan imaging capability, a product release that enhances composite inspection capabilities and reflects the growing emphasis on advanced imaging for non-metallic structures. This development underscores the industry's pivot toward multi-modal inspection tools that deliver actionable data faster.
Earlier in the forecast window, SGS introduced a new AI-driven inspection platform in November 2025, designed to enhance NDT accuracy through machine learning algorithms and automated defect recognition. This launch highlights the accelerating integration of artificial intelligence into inspection workflows, promising to reduce human error and increase throughput. In October 2025, Bureau Veritas executed an acquisition of a regional competitor to expand its advanced ultrasonic testing capabilities, a move that illustrates the strategic value of consolidating technological strengths and expanding service footprints.
Intertek entered a strategic partnership in September 2025 with a technology firm to develop a remote digital NDT inspection platform, signaling the industry's embrace of connectivity and remote monitoring. Such collaborations are becoming increasingly common as organizations seek to leverage external expertise and accelerate digital transformation. Additionally, Previan Technologies realigned Eddyfi Technologies and NDT Global as independent industrial-technology leaders in June 2026, a corporate restructuring that aims to sharpen focus and enhance agility within specialized segments of the market.
X-ray Non-destructive Testing Equipment Market
Industry Dynamics and Headwinds
Regulatory Evolution and Compliance Costs
Regulatory frameworks are tightening, with direct implications for both equipment suppliers and inspection service providers. The new ISO 9712-2025 standard, issued by ISO Technical Committee 135 in January 2026, increases the certification renewal frequency for NDT personnel to every three years, mandating compulsory retraining on advanced methods. This shift ensures that the workforce remains proficient with evolving technologies but also introduces recurring compliance costs and administrative burdens. Similarly, the EN 4179:2026 standard establishes updated minimum requirements for the qualification and certification of NDT personnel in aerospace applications, reinforcing the sector's demand for highly credentialed inspectors.
These regulatory changes elevate the importance of instrumentation that supports efficient training, certification, and documentation. Instruments that integrate with digital record-keeping systems or offer intuitive interfaces for complex procedures gain a competitive edge in an environment where compliance is non-negotiable. Furthermore, certification renewal changes in 2026 require more frequent retraining, driving up labor costs for qualified NDT personnel, as noted by industry sources in late 2025. This labor cost pressure incentivizes the adoption of tools that maximize inspector productivity and reduce the time required per inspection.
Cost Pressures and Adoption Barriers
Despite the favorable growth outlook, cost remains a pivotal factor influencing market penetration, particularly among smaller enterprises. The high upfront cost of advanced NDT instruments, including phased array ultrasonic and digital radiography systems, continues to limit adoption among small and medium enterprises. This barrier creates a bifurcation in the market, where large industrial players can accelerate their digital and advanced testing transformation, while smaller entities may rely on traditional methods or shared service models.
On the pricing front, averaged selling price trends for ultrasonic testing techniques showed increases through 2024, with ongoing pressure from component and sensor pricing in 2025. These dynamics suggest that manufacturers are navigating a delicate balance between maintaining margins and offering competitive pricing in a supply-constrained environment. Our analysis examines how these cost structures affect downstream pricing strategies and the total cost of ownership for end-users, providing clarity on where economies of scale can be leveraged and where value-added services can offset hardware costs.
Strategic Value of the Research for 2026 Decision-Making
In an environment defined by rapid technological change, regulatory evolution, and intense competitive maneuvering, access to granular, forward-looking intelligence is a strategic necessity. This research equips decision-makers with the analytical framework required to navigate uncertainty and capitalize on emerging opportunities.
Capital Allocation and Investment Strategy
For investors and corporate strategy teams, the forecast trajectory offers a compelling basis for portfolio decisions. The projected growth from 18.62 billion USD in 2026 to over 30 billion USD by 2032 indicates sustained demand across multiple cycles. Understanding which segments are expanding at higher rates, which technologies are gaining share, and which geographic regions are accelerating adoption allows for targeted investment in high-potential areas. The report's segmentation analysis helps identify where capital can be deployed with the highest return potential, whether in product innovation, market expansion, or strategic acquisitions.
Product Development and Technology Roadmapping
For manufacturers and technology developers, the research provides critical insights into the evolving requirements of end-users. The shift toward AI-driven platforms, remote digital inspection capabilities, and advanced imaging solutions signals where R&D efforts should be concentrated. By analyzing recent product launches and corporate realignments, organizations can benchmark their own innovation pipelines and identify gaps in the market. The discussion of cost pressures and pricing trends further informs go-to-market strategies, helping companies position their offerings to address both the premium segment seeking cutting-edge performance and the cost-conscious segment requiring accessible solutions.
Market Entry and Competitive Positioning
For companies considering market entry or expansion, the competitive landscape analysis offers a realistic assessment of the barriers and opportunities. The concentration of market share among top players highlights the importance of differentiation, whether through technological novelty, specialized application focus, or regional expertise. The profiles of key companies and recent strategic developments reveal the tactics that incumbents are employing to defend and grow their positions. Armed with this knowledge, new entrants can identify underserved niches, form strategic alliances, or develop disruptive business models that challenge the status quo.
Risk Management and Regulatory Compliance
For operators and service providers, the regulatory updates represent both a challenge and an opportunity. The increased frequency of certification renewals and the heightened requirements for advanced methods underscore the need for robust training programs and compliant instrumentation. The research integrates these regulatory dynamics into the broader market context, helping organizations anticipate compliance costs, plan workforce development, and select tools that streamline certification and documentation processes. By proactively addressing these factors, companies can mitigate operational risks and maintain their competitive standing in regulated industries.
Conclusion: The Path Forward
The Non-Destructive Testing Instruments Market is at an inflection point, where historical growth patterns are being amplified by technological innovation, regulatory tightening, and the imperatives of asset integrity across critical industries. The data landscape reveals a market on a robust growth trajectory, yet the true value for decision-makers lies in the strategic insights that connect macroeconomic trends to actionable business implications. This research serves as a comprehensive guide for navigating the complexities of the market, offering the depth and precision required to make informed investments, drive product innovation, and secure a resilient competitive position.
To fully capitalize on the opportunities outlined in this analysis, stakeholders are encouraged to access the complete report. The full study provides the detailed segmentation data, granular regional breakdowns, company-level assessments, and forward-looking scenarios that form the backbone of a winning strategy. By integrating this intelligence into your planning processes, you can transform market uncertainty into a structured pathway for sustainable growth and leadership in the years ahead.
For detailed analysis of this topic, please visit the official page: Non-Destructive Testing Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cockpit and Flight Data Recorder Market Hits $170M in 2025, 5.8% CAGR to $257M by 2032
By PW Consulting, 2026-09-16
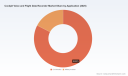
Strategic Imperatives in the Cockpit Voice and Flight Data Recorder Market: Navigating Growth and Regulatory Shifts Through 2032
The aviation safety ecosystem stands at a pivotal juncture. As aircraft design philosophies evolve and regulatory bodies tighten mandates around data retention and crashworthiness, the Cockpit Voice and Flight Data Recorder market is experiencing a structural realignment that will define procurement strategies, product development roadmaps, and competitive positioning for the next decade. Our latest market research offers a comprehensive, data-driven blueprint for executives, sourcing directors, and engineering leaders who must make capital allocation and compliance decisions in 2026 and beyond.
This publication arrives at a moment when the intersection of technological innovation and regulatory compliance is no longer a peripheral concern, but a central boardroom priority. The insights contained within are designed to transform uncertainty into actionable intelligence, enabling stakeholders to anticipate demand shifts, evaluate supplier capabilities, and align investment timing with the market’s most consequential inflection points.
Market Trajectory: A Decade of Calculated Expansion
Tracing the historical arc from 2020 through 2025 reveals a market that has consistently demonstrated resilience and steady upward momentum, even amid global supply chain disruptions and shifting fleet utilization patterns. The sector has progressed from a baseline valuation in the early 2020s to a substantially expanded footprint by 2025, reflecting sustained airframe deliveries, replacement cycles, and the gradual integration of next-generation recording architectures across both commercial and defense platforms.
Looking forward across our forecast period, the trajectory points toward continued growth, underpinned by heightened safety mandates, fleet modernization programs, and the ongoing proliferation of digital flight data streaming capabilities. The compound annual growth rate projected for this window signals a durable expansion narrative, one that will reward organizations capable of aligning their product portfolios and supply chain strategies with emerging compliance requirements. Critically, the projected valuation milestones across successive forecast years illustrate a market that is not merely expanding in nominal terms, but evolving in complexity, demanding more sophisticated integration, certification readiness, and lifecycle support capabilities from manufacturers and integrators alike.
For enterprise decision-makers, this growth profile carries strategic weight. It suggests that the market will accommodate new entrants and incumbent expansions alike, but that the distribution of opportunity will be uneven. Organizations that treat the recorder segment as a commoditized afterthought risk ceding ground to competitors who recognize it as a high-value, regulation-sensitive domain with significant barriers to entry and long-term revenue visibility.
Regulatory Catalysts Reshaping Demand Profiles
The single most potent force currently restructuring procurement pathways is the regulatory environment. Throughout 2024 and 2025, authorities across major aviation markets moved to codify extended recording durations and enhanced data accessibility standards. A landmark development in early 2026 saw the finalization of a rule mandating twenty-five-hour cockpit voice recorder retention for newly manufactured aircraft across multiple operational categories, with compliance timelines anchored to production dates in mid-2025. This ruling does not merely extend a specification; it fundamentally alters the engineering requirements for manufacturers designing for the commercial airliner, business jet, and commuter segments.
Complementary legislative actions, including provisions embedded in broader aviation reauthorization frameworks, have extended similar twenty-five-hour capability requirements to larger transport-category aircraft and established retrofit compliance horizons extending toward the end of the decade. These mandates create a dual-layer demand structure: an immediate pull from new production lines adapting to revised certification baselines, and a deferred but substantial pull from in-service fleets that must be upgraded or replaced to remain compliant. International standardization efforts have reinforced this trajectory, with global aviation bodies advancing proposals to harmonize flight recorder data download interfaces, reduce analysis friction, and improve cross-manufacturer interoperability. Such initiatives signal a longer-term shift toward data-centric safety architectures that will influence procurement criteria well beyond the current forecast horizon.
For organizations evaluating market entry, product line expansion, or supplier partnerships, the regulatory calendar is not a peripheral detail. It is a scheduling mechanism that dictates certification timelines, production slot allocation, retrofit campaign planning, and ultimately, revenue realization. The strategic implication is clear: companies that map their development cycles and capacity investments against these regulatory milestones will secure competitive advantage, while those that treat compliance as an after-the-fact engineering task will face costly redesigns and delayed market access.
Aerospace and Marine Data Recorders Market
Product Segmentation and Engineering Evolution
The market’s product architecture spans distinct recorder categories, each carrying different engineering demands, certification pathways, and end-user value propositions. Traditional flight data recording units continue to serve as the backbone of operational monitoring and accident investigation, while cockpit voice recording systems have undergone a generational leap in capacity and reliability. The emergence of combined voice and flight data recorder solutions reflects a broader industry preference for integrated, weight-optimized, and simplified installation architectures, particularly in platforms where space, power, and maintenance access are tightly constrained.
Engineering sophistication in this segment has accelerated markedly. Modern recorder families now emphasize extended recording durations, enhanced crashworthiness and fire resistance, faster data retrieval through advanced interface protocols, and optional onboard streaming or rapid-retrieval capabilities that reduce post-event analysis timelines. Ethernet-enabled download pathways, integrated rapid-retrieval information processing systems, and modular designs that accommodate multi-platform certification are increasingly becoming baseline expectations rather than premium differentiators. For integrators and airframe manufacturers, these features translate into reduced certification complexity, streamlined maintenance workflows, and improved alignment with fleet-wide data management strategies.
The implication for market participants is that product differentiation is shifting from standalone recorder specifications toward ecosystem compatibility. Suppliers that can demonstrate seamless integration with existing avionics suites, provide clear retrofit pathways, and offer lifecycle support aligned with extended operational use cases will capture disproportionate share in a market where total cost of ownership and compliance assurance weigh heavily in purchasing decisions.
Cockpit Voice and Flight Data Recorder Market
Competitive Architecture: Who Holds the Edge
The competitive landscape is defined by a concentrated group of established aerospace and defense technology firms that have invested heavily in recorder platforms, certification portfolios, and OEM relationships. Industry analysis indicates a market structure where a relatively small number of participants command a substantial share of revenue, reflecting the high technical barriers, lengthy certification cycles, and long-term supply agreements that characterize this domain. Such concentration rewards companies with proven track records in airworthiness certification, production scalability, and global aftermarket support.
Among the organizations shaping this competitive environment, several stand out for their product architectures and strategic positioning. Honeywell Aerospace has solidified its presence through combined recorder platforms engineered for commercial airliners and business jets, with certification coverage that spans multiple aircraft categories and recording durations aligned with the latest mandates. Curtiss-Wright Defense Solutions contributes through its recording technology divisions, including collaborative development of next-generation recorder series and proprietary systems designed for commercial aviation applications. Universal Avionics has advanced the segment through its fifth-generation recorder line, emphasizing combined unit configurations, Ethernet download options, and modular rapid-retrieval capabilities that align with modern fleet data management needs.
L3Harris Technologies maintains a strong footprint through its recorder and survival recorder families, including series designed for widely deployed airframes with supplemental type certificate coverage on platforms such as the Boeing 737NG and integrated rapid-retrieval systems. HENSOLDT brings European certification expertise and a portfolio spanning combined recorders, standalone flight data units, and voice recording models certified to recognized industry standards. Flight Data Systems has carved a position around lightweight combined recorder designs that meet stringent crashworthiness and fire-resistance requirements while offering optional rapid-retrieval integration. Safran extends its influence through helicopter and fixed-wing recorder solutions, reflecting the diversification of platform requirements across rotorcraft and general aviation segments. Acron Aviation has emerged as a notable player through its recorder series offering extended audio and flight data retention, alongside strategic recognition as an approved solution for major airframer programs and a platform for continuous online procurement of certified avionics components.
The strategic takeaway for procurement and planning teams is that supplier selection increasingly hinges on more than unit pricing. Certification breadth, retrofit readiness, production capacity, global support infrastructure, and alignment with forthcoming data interface standardization all factor into long-term value. Organizations that conduct structured supplier evaluations against these criteria will be better positioned to secure reliable supply, navigate certification dependencies, and capitalize on retrofit and replacement cycles.
Where 2026 Decision-Makers Must Focus
As enterprises calibrate their strategies for the current year and beyond, several priority areas demand focused attention. First, regulatory mapping must become a continuous function rather than a periodic compliance exercise. The staggered compliance dates across new production and retrofit mandates require organizations to sequence procurement, engineering, and fleet planning activities with precision. Second, product evaluation frameworks should incorporate data accessibility, interface compatibility, and aftermarket support as core criteria, reflecting the longer-term shift toward integrated safety data ecosystems.
Third, supply chain resilience warrants heightened scrutiny. The concentration of market share among a limited set of manufacturers underscores the importance of qualifying alternate sources where feasible, securing multi-year agreement structures, and stress-testing production capacity against anticipated demand surges driven by retrofit campaigns and fleet renewal programs. Fourth, forward-looking investment decisions should account for the possibility that standardization initiatives around data download interfaces and interoperability will create new value pools in software, analytics, and service delivery, extending the commercial relevance of recorder platforms beyond hardware sales.
Organizations that embed these considerations into their strategic planning will not only mitigate compliance risk but also unlock opportunities to influence specification development, secure preferred supplier status, and align product roadmaps with the market’s most consequential growth vectors.
What the Full Study Delivers
Our complete market research publication provides a granular, actionable foundation for the decisions outlined above. The report constructs a multi-year market size framework anchored to historical performance data and extended through a detailed forecast horizon, enabling precise scenario planning and investment timing analysis. It decomposes demand across major geographic markets and application segments, illuminating where growth concentration is forming and how regional aviation activity, fleet composition, and regulatory adoption patterns shape local opportunity profiles.
The study delivers deep segmentation analysis by recorder type, clarifying the relative commercial weight of flight data recorders, cockpit voice recorders, and combined systems, while mapping product architecture trends, certification requirements, and technological adoption curves across each category. Application-level examination distinguishes between civil aviation and military aviation demand drivers, including fleet renewal cycles, operational mandates, and platform-specific engineering requirements that influence procurement timing and specification preferences.
A dedicated competitive profiling section evaluates the strategic posture, product capabilities, certification footprints, and recent developments of the leading manufacturers, providing a structured basis for supplier benchmarking, partnership evaluation, and competitive positioning analysis. The report also integrates regulatory trackers, recent product launches, partnership announcements, and procurement developments, offering a continuously updated view of the forces that are actively reshaping purchasing requirements and market access conditions.
For executives seeking to validate capital allocation, guide engineering investment, or refine market entry strategies, the full study translates macro-level trends into specific, segment-level intelligence that can be operationalized across procurement, product management, and strategic planning functions. The most consequential details, including precise regional revenue distributions, application-level valuation breakdowns, and company-specific market share estimates, are reserved for the complete report to ensure that stakeholders receive unfiltered, decision-ready intelligence when they engage directly with the analysis.
The Strategic Case for Early Engagement
The Cockpit Voice and Flight Data Recorder market will not be defined solely by airframe production volumes or cyclical procurement patterns. It will be shaped by the interplay of regulatory mandates, engineering standardization, supplier concentration, and the growing expectation that safety recorders function as integral nodes within broader aviation data architectures. Organizations that act early to align their strategies with these forces will secure advantages in specification influence, supply assurance, and market positioning that will compound as the forecast period unfolds.
This research publication is designed to provide the evidentiary foundation and analytical structure necessary to make those decisions with confidence. By combining historical validation, forward-looking modeling, competitive mapping, and regulatory tracking into a single integrated framework, it equips decision-makers with the clarity required to navigate a market that rewards preparedness and penalizes ambiguity. The complete dataset, segment-level breakdowns, and detailed company assessments are available through the full report, offering the depth required to translate strategic intent into executed action.
For detailed analysis of this topic, please visit the official page: Cockpit Voice and Flight Data Recorder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
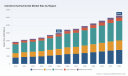
Unlocking Growth in the Cetirizine Hydrochloride Market: Strategic Insights for 2026 and Beyond
The global pharmaceutical landscape for antihistamine therapies is undergoing a significant transformation, driven by rising prevalence of allergic conditions, evolving regulatory frameworks, and shifting supply chain dynamics. For stakeholders operating within the Cetirizine Hydrochloride sector, understanding the nuanced trajectory of this market is no longer optional; it is a strategic imperative. Our latest comprehensive market research study delves deep into the operational, financial, and competitive layers of the Cetirizine Hydrochloride industry, providing a robust foundation for decision-making throughout the forecast period extending to 2032.
This article serves as a strategic overview of the key findings contained within the full report. It is designed to highlight the macroeconomic trends and competitive pressures that define the current landscape, while outlining the specific analytical depth available to subscribers who seek to leverage this intelligence for commercial advantage.
Macroeconomic Trajectory and Market Valuation
The financial outlook for the Cetirizine Hydrochloride market demonstrates sustained growth momentum, reflecting both steady demand from established markets and expanding penetration in emerging regions. Based on historical data tracking from 2020 through the base year of 2025, the market has shown a consistent upward trend in revenue generation. The valuation started at a significant baseline in 2020 and has climbed steadily, reaching an estimated 3980.0 Million USD by 2025.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is anticipated to reach approximately 4408.89 Million USD in 2026, with growth accelerating towards a valuation of 6250.0 Million USD by the end of the forecast window in 2032. This trajectory underscores a Compound Annual Growth Rate (CAGR) of 6.98 percent during the forecast period. Such growth rates indicate a healthy elasticity in demand, suggesting that despite generic competition and pricing pressures, the core utility of Cetirizine Hydrochloride in managing allergic conditions remains robust.
These figures represent more than just top-line revenue; they signal the scale of opportunity available for manufacturers, distributors, and investors. However, realizing this potential requires a granular understanding of where value is being created and eroded within the value chain, which is a core focus of our detailed analysis.
Segmentation Dynamics and Consumption Patterns
The market is fragmented across several key dimensions, each presenting unique challenges and opportunities for market participants. Our report dissects these segments to reveal shifting consumption patterns that are critical for product portfolio strategy.
Dosage Forms and Patient Preferences
The form factor in which Cetirizine Hydrochloride is delivered plays a pivotal role in market share distribution. Tablets continue to dominate the landscape, reflecting their convenience and established patient preference in adult demographics. However, the report highlights significant activity in liquid formulations, including syrups and solutions, which are essential for pediatric and geriatric populations who may have difficulty swallowing solid dosage forms. The balance between these forms influences manufacturing complexity, packaging requirements, and regulatory pathways, particularly concerning flavorings, preservatives, and sugar content in pediatric formulations.
Therapeutic Applications Driving Demand
Clinically, the demand for Cetirizine Hydrochloride is anchored primarily in the treatment of allergic conditions. Allergic Rhinitis remains the largest application segment, driven by environmental factors and increased diagnosis rates globally. Other significant applications include Allergic Conjunctivitis and Eczema, where antihistamines play a supportive role in symptom management. Understanding the specific growth rates within each therapeutic area allows companies to tailor their marketing messages and clinical support materials to the conditions with the highest unmet need or fastest growing prevalence.
Geographic Revenue Distribution
Geographically, the market exhibits a diverse revenue mix. While North America and Europe represent mature markets with established reimbursement pathways and high brand recognition, the Asia Pacific region emerges as a critical volume driver. The region's growth is supported by increasing healthcare access, rising disposable incomes, and a large patient base. Latin America and the Middle East and Africa also contribute to the global total, though often with different dynamic characteristics related to pricing regulations and import dependencies. Our analysis avoids simple regional rankings, instead focusing on the specific growth drivers and barriers within each territory to guide market entry or expansion strategies.
Competitive Landscape and Corporate Strategy
The Cetirizine Hydrochloride market is characterized by a mix of large multinational pharmaceutical corporations and specialized generic manufacturers. Market concentration data indicates a moderately consolidated environment, where a handful of key players command a significant portion of the market share. This structure creates a competitive arena where pricing power, regulatory approval speed, and supply chain reliability are key differentiators.
Key companies active in this space include major generic producers and API manufacturers such as Granules India Limited, Aurobindo Pharma Limited, Cipla Limited, and Mylan (Viatris). These entities compete not only on price but on regulatory compliance and supply consistency. For instance, Teva Pharmaceutical Industries Ltd. and Apotex Inc. maintain strong positions in finished dosage forms, leveraging long-standing FDA approvals and established distribution networks.
Recent activity among these competitors highlights the intensity of the race for market access and product differentiation. Strategic moves often involve securing new approvals to extend portfolio depth or entering specific geographic markets where demand is underserved. Our report provides detailed profiles of these key companies, analyzing their recent developments, strategic positioning, and potential impact on market pricing and availability.
Regulatory and Supply Chain Volatility
One of the most critical aspects of the current market environment is the volatility introduced by regulatory changes and supply chain constraints. These factors can materially impact profit margins and product availability, making real-time intelligence vital for risk management.
Regulatory Developments
Regulatory bodies are increasingly scrutinizing safety profiles and pricing structures. In May 2025, the FDA issued a Drug Safety Communication requiring revised labeling for cetirizine and levocetirizine products. This update warned about rare but severe pruritus upon long-term use and abrupt discontinuation. Such labeling changes can influence prescribing habits and patient adherence, requiring manufacturers to update communication strategies and potentially manage adverse event reporting more rigorously.
Furthermore, pricing regulations remain a potent force, particularly in emerging markets. In January 2026, the National Pharmaceutical Pricing Authority (NPPA) of India capped the retail price of cetirizine hydrochloride ophthalmic solution. Price controls of this nature directly affect revenue projections and require companies to adjust their cost structures or volume expectations to maintain profitability in controlled markets.
Supply Chain and Raw Material Dynamics
Supply chain resilience has become a focal point for industry participants. In March 2026, U.S. spot prices for cetirizine dihydrochloride API rose approximately 11.8 percent. This increase was attributed to constrained supply from Indian and Chinese sources, compounded by seasonal demand spikes and logistical pressures. Such fluctuations highlight the dependency on specific geographic hubs for API production. Companies that rely heavily on single-source suppliers or specific regions face heightened risk, whereas those with diversified sourcing strategies may find opportunities to capture margin improvements during periods of constrained supply.
Quality and Recall Incidents
Quality assurance remains a non-negotiable standard. In March 2025, specific lots of Cetirizine Hydrochloride Tablets were recalled due to potential manufacturing quality issues identified by the FDA. Incidents like these serve as reminders of the operational risks inherent in pharmaceutical manufacturing. They can lead to temporary supply shortages, reputational damage, and increased regulatory oversight. Our report examines these incidents not merely as news items, but as case studies for understanding systemic risks and the importance of robust quality management systems.
Recent Developments Shaping the Foreground
The period leading into 2026 has seen specific product launches and approvals that refine the competitive landscape. These developments often signal where companies are placing their bets for future growth.
Notably, Preferred Pharmaceuticals Inc. received FDA approval in March 2026 for a Cetirizine Hydrochloride Oral Solution USP specifically formulated for pediatric use. The product is sugar-free and dye-free with a grape flavor, targeting children two years and above. This move addresses a specific niche within the liquid dosage form segment, focusing on palatability and safety concerns for younger patients.
Cetirizine Hydrochloride Market
Loratadine Market
Simultaneously, Aurohealth LLC received FDA approval in February 2026 for Cetirizine Hydrochloride as an over-the-counter human drug, expanding the availability of generic OTC options. Indoco Remedies Limited also secured final USFDA approval in October 2025 for their 10 mg tablets. These sequential approvals indicate a continuous pipeline of generic entrants seeking to capture share in the OTC and prescription segments, intensifying competition but also ensuring supply stability for consumers.
The Strategic Value of Deep-Dive Intelligence
While the macroeconomic trends and competitive moves outlined above provide a high-level view, successful strategic planning requires access to granular data that lies beneath the surface. The full market research report offers actionable intelligence that goes beyond general observations.
Subscribers to the complete study gain access to detailed segmentation revenue splits, allowing for precise identification of high-growth niches within dosage forms and therapeutic applications. The report provides deep-dive profiles of key companies, including their financial health, recent strategic partnerships, and specific regional strengths. This level of detail enables competitive benchmarking and helps identify potential acquisition targets or partnership opportunities.
Furthermore, the analysis of market dynamics includes a thorough examination of raw material sourcing risks, regulatory timelines, and reimbursement trends. Understanding the interplay between API price volatility and finished product pricing strategies is essential for margin protection. The report also addresses frequently asked questions regarding market barriers, entry strategies, and the impact of recent regulatory changes on long-term profitability.
For investors and corporate strategists, the ability to model different scenarios based on accurate historical data and robust forecast methodologies is invaluable. The report provides the foundational data required to build financial models, assess risk exposure, and validate market entry assumptions. Whether the goal is to expand production capacity, launch a new formulation, or enter a new geographic region, the insights contained in this study serve as a critical decision-support tool.
Navigating the Future Landscape
As the Cetirizine Hydrochloride market moves through the forecast period towards 2032, the interplay of growth drivers, regulatory constraints, and competitive pressures will continue to evolve. The projected CAGR of 6.98 percent suggests that the market will expand significantly, but the distribution of this growth will not be uniform. Companies that can navigate supply chain complexities, adapt to regulatory labeling requirements, and differentiate their products through formulation innovation or strategic pricing will be best positioned to capture value.
The recent approvals for pediatric solutions and new OTC entrants indicate that the market remains dynamic, with room for innovation even in a mature therapeutic class. However, challenges such as API price volatility and pricing caps in key markets require vigilant management. Access to comprehensive, up-to-date intelligence is the key to turning these challenges into opportunities.
We invite industry stakeholders to explore the full findings of our Cetirizine Hydrochloride Market research. The complete report provides the detailed segmentation data, company profiles, and dynamic analysis necessary to formulate a winning strategy in this evolving landscape. Access the full intelligence to ensure your decisions are grounded in rigorous data and expert analysis.
For detailed analysis of this topic, please visit the official page: Cetirizine Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Film Dubbing Market to Hit $215M in 2025, Grow at 6% CAGR to $321.88M by 2032
By PW Consulting, 2026-09-16
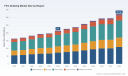
Navigating the Future of Entertainment: Strategic Insights from the 2026 Film Dubbing Market Report
The global media landscape is undergoing a tectonic shift, where the boundary between content creation and content localization has become increasingly porous. As streaming platforms expand their footprint across borders and theatrical releases demand simultaneous worldwide launches, the film dubbing sector has emerged as a critical enabler of global audience engagement. At PW Consulting, we recognize that understanding this market is no longer optional for stakeholders in media, entertainment, and technology. Our latest comprehensive study on the Film Dubbing Market offers a definitive roadmap for navigating the complexities of this evolving industry through 2032.
This article serves as a strategic prequel to our full market research publication. It outlines the macroeconomic trajectory, the competitive forces reshaping the sector, and the operational headwinds that decision-makers must anticipate in 2026. However, the true depth of our analytics, including specific regional revenue breakdowns and segmented growth vectors, is reserved for the full report. Here, we establish the framework for why this intelligence is vital for your 2026 corporate strategy.
Market Trajectory and Macro Growth Indicators
The financial architecture of the film dubbing market reveals a consistent upward trajectory, underpinned by the insatiable demand for localized content. Our analysis covers a extensive historical period from 2020 through 2025, providing a robust baseline for forecasting the future. The research indicates that the market has steadily climbed from a valuation of 163.15 million USD in 2020 to an estimated 215.0 million USD by the base year of 2025.
Looking forward, the forecast period spanning 2026 to 2032 projects sustained momentum. The market is expected to reach 226.54 million USD in 2026 and continues its growth path toward a projected peak of 321.88 million USD by 2032. This expansion is driven by a Compound Annual Growth Rate (CAGR) of approximately 6.0 percent over the forecast horizon. Such figures suggest that while the market is maturing, it retains significant elasticity fueled by technological integration and cross-border content consumption.
It is crucial for executives to understand that these aggregate numbers mask underlying complexities. The growth is not uniform across all vectors. Our full report dissects these macro figures to reveal where the true value pools are emerging, helping stakeholders avoid the trap of averaging out high-potential niches.
Segmentation Dynamics: Types and Applications
Understanding the composition of the market is essential for resource allocation. The industry is broadly categorized by film type and application, each carrying distinct implications for production workflows and cost structures. In terms of film types, the market encompasses polyolefin film, polyester film, and other types. Each material and format presents unique challenges in terms of audio synchronization and visual overlay requirements, influencing the choice of localization partners.
Similarly, the application landscape is diverse, ranging from semiconductor wafer manufacturing and IC packaging to various other niche applications. While some segments appear technical, their intersection with media content delivery systems is where the dubbing market finds its operational rhythm. For instance, the push for high-fidelity audio in specialized manufacturing interfaces often borrows technologies developed for cinematic dubbing, creating a cross-pollination of innovation.
Our detailed segmentation analysis goes beyond these high-level categories. We provide granular insights into which specific types and applications are outpacing the average CAGR. This is critical for companies deciding where to invest their R&D budgets or which service lines to prioritize in the coming fiscal year. Accessing the full intelligence allows clients to pinpoint the exact segments that align with their core competencies.
Regional Landscape and Competitive Concentration
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a distinct regulatory and cultural environment that impacts dubbing requirements. For example, specific regulatory frameworks in Europe and Asia mandate local language tracks, driving consistent demand regardless of global box office performance.
The competitive landscape is characterized by a fragmented yet evolving structure. Our market concentration analysis indicates that the top three players hold a combined market share of 24.6 percent, while the top five firms account for 26.2 percent. This suggests that while there are dominant players setting industry standards, a significant portion of the market remains open to agile competitors and specialized service providers.
Key companies shaping this landscape include BTI Studios, headquartered in Burbank, California, which focuses on AI-enhanced dubbing services with global localization and voice quality oversight. ZOO Digital Group plc, based in El Segundo, offers multilingual lip-sync dubbing and voiceover services at scale for global TV, movie, and OTT content. In the Middle East, ABC Dubbing and Subtitles Studios in Dubai specializes in Arabic-language dubbing and multilingual audio services for films and series.
European capabilities are represented by entities like Audiomaster in the United Kingdom, focusing on high-fidelity audio mastering, and Mafilm Audio, which handles professional dubbing and audio post-production. In Southeast Asia, TFC provides critical specialization in Tagalog and regional-language localization. Meanwhile, VOA Voice Studios and JBI Studios in the United States continue to serve the domestic market with robust voice-over and lip-sync capabilities. The full report profiles each of these entities, analyzing their strategic moves and market positioning in greater detail.
Closed Caption Services Market
Operational Headwinds and Industry Dynamics
Growth is not without friction. Our 2026 analysis identifies several structural challenges that are currently reshaping supply chains and production timelines. Labor dynamics remain a primary concern. Analysts insights from May 2026 highlight a shortage of approximately 26 percent of skilled native voice actors, coupled with 18 percent synchronization challenges that slow market expansion. This talent gap creates bottlenecks for studios aiming to meet simultaneous global release schedules.
Furthermore, proficiency levels among the workforce present another layer of complexity. According to the European Union's Creative Europe report, less than 25 percent of dubbing professionals are proficient in more than two languages. This linguistic limitation constrains the scalability of localization operations, particularly for studios managing pan-regional content.
Regulatory environments also dictate the pace of operations. In France, regulations administered by the Centre National du Cinéma et de l'Image Animée (CNC) mandate French-language dubbing for all theatrical films exceeding a minimum commercial threshold. Similarly, in China, the National Radio and Television Administration (NRTA) requires Mandarin-language audio tracks for all foreign content approved for broadcast or theatrical release. Compliance with these mandates requires localized infrastructure and careful planning, factors that are thoroughly quantified in our full research.
Cost structures have also been impacted by recent trade policies. In 2025, a series of newly implemented U.S. import tariffs have materially reshaped cost structures and supply chain configurations within the film dubbing sector, with baseline duties on audiovisual components ranging from 10 percent to as high as 46 percent. These tariffs influence the pricing models for equipment and post-production services, necessitating a strategic review of vendor contracts and production locations.
Recent Developments and Strategic Shifts
The industry is actively responding to these challenges through education and technology adoption. In January 2025, Dubbing School hosted professional workshops in Los Angeles focusing on film dubbing, voice-over, and ADR techniques under U.S. standards. Such initiatives indicate a industry-wide recognition of the need to upskill talent to meet higher technical standards and mitigate the shortage of skilled professionals.
Film Dubbing Market
Technology remains a wild card. The integration of AI-enhanced services, as pursued by leaders like BTI Studios, suggests a future where human creativity is augmented by machine efficiency. However, the balance between automation and artistic integrity remains a delicate negotiation. Our full report explores the adoption rates of these technologies and their impact on cost-to-serve metrics.
Strategic Value for 2026 Decision-Making
Why does this comprehensive analysis matter for your 2026 strategy? Because the difference between capturing market share and losing ground often lies in the granularity of intelligence. Knowing the total market size is a starting point; knowing which sub-segment is driving the CAGR, which regulatory change will alter compliance costs, and which competitor is consolidating a specific regional niche is where true advantage is found.
For media conglomerates, the data informs content scheduling and localization budgeting. For technology providers, it highlights where audio processing tools are most needed. For investors, the concentration metrics and growth rates offer a clear view of market stability and opportunity.
The 2026 forecast period is pivotal. With the market projected to grow from 226.54 million USD in 2026 toward nearly 322 million USD by 2032, the decisions made this year will define competitive positioning for the remainder of the decade. Ignoring the nuances of labor shortages, tariff impacts, or regional regulatory mandates could result in costly operational inefficiencies.
Conclusion and Access to Full Intelligence
The Film Dubbing Market is at an inflection point where cultural demand meets technological capability and regulatory complexity. PW Consulting's latest market research is designed to cut through the noise and provide actionable intelligence. While this overview highlights the macro trends, the competitive profiles, and the operational challenges, the full report contains the specific data tables, regional breakdowns, and strategic recommendations required to execute a winning plan.
We invite industry leaders, investors, and strategists to delve deeper into the findings. The complete analysis offers the precise segmentation splits, detailed company profiles, and risk assessments necessary to navigate the 2026 landscape with confidence. To access the full intelligence and secure your strategic advantage in the global film dubbing market, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Film Dubbing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phloroglucinol Market Sees 5.85% CAGR Toward $280.7M by 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Global Phloroglucinol Market Through 2032
The global phloroglucinol market stands at a pivotal inflection point, shaped by tightening regulatory frameworks, expanding pharmaceutical applications, and a highly concentrated supply chain. For executives, procurement leaders, and strategic planners, understanding the trajectory of this critical intermediate is no longer optional—it is a prerequisite for resilient sourcing, capacity planning, and competitive positioning. Our latest comprehensive study, spanning historical performance through 2032, delivers the structured intelligence required to transform market uncertainty into actionable strategy.
Over the past half-decade, the market has demonstrated steady expansion, reflecting sustained demand from pharmaceutical formulation and specialty chemical synthesis. Current valuations position the industry at a substantial baseline, with forward projections indicating continued value accumulation through the end of the decade. The compound annual growth rate across the forecast horizon registers at 5.85 percent, a figure that encapsulates both organic demand growth and the market's sensitivity to capacity adjustments, regulatory shifts, and pricing dynamics. This growth trajectory is neither linear nor uniformly distributed; it is mediated by regional manufacturing ecosystems, grade-specific procurement patterns, and the strategic maneuvers of a tightly knit competitive field.
At the core of this analysis lies a rigorous reconstruction of supply and demand mechanics. The report dissects historical consumption patterns, maps production capacity expansions, and evaluates the structural drivers that will dictate market behavior through 2032. Readers will find granular examinations of how pharmaceutical-grade dominance shapes overall revenue composition, how industrial and research-grade segments carve out specialized niches, and how application-level demand responds to clinical adoption, manufacturing scale-up, and downstream chemical integration. Each dimension is contextualized within pricing environments, raw material volatility, and compliance requirements that collectively determine margin profiles and sourcing feasibility.
Decoding Competitive Dynamics and Strategic Positioning
The phloroglucinol landscape is characterized by pronounced concentration. The top three players command more than half of total market share, while the top five extend their footprint to approximately two-thirds of total revenue. This concentration is not accidental; it reflects the capital intensity of pharmaceutical-grade production, the regulatory overhead required for API and injection-grade compliance, and the incremental barriers that separate bulk suppliers from high-purity specialists. The report provides a detailed competitive mapping that moves beyond simple market-share rankings to analyze operational footprints, supply reliability, quality certification pathways, and strategic alliances that define leadership positions.
Phloroglucinol Market
Worldwide P-chlorophenol Market
Among the manufacturers under scrutiny, several Chinese enterprises have built formidable positions by aligning production capabilities with domestic pharmaceutical demand and export-oriented API supply. Entities such as Taixing Yinxin Chemical, Jiangsu Dingye Pharmaceutical, Beijing Wisdom Chemicals, Hebei Jianxin Chemical, Shouguang Fukang Pharmacy, Kaifeng Mingren Pharmaceutical, Clent Chemical, and Sinopharm Guorui Pharma each occupy distinct roles within the value chain, ranging from bulk and specialty chemical supply to high-purity pharma-grade output and approved injection formulations. Their collective activities illustrate how regional manufacturing clusters are consolidating technical capability, expanding throughput, and responding to both domestic procurement cycles and international demand signals.
On the global stage, established multinational players continue to reinforce their positioning through targeted acquisitions and supply-chain integration. Merck KGaA, for instance, has moved to secure stable access to phloroglucinol API and intermediates by acquiring the pharmaceutical chemicals division of Shaanxi Sciphar HiTech Industry, a move that underscores the strategic premium placed on supply continuity and quality assurance. Meanwhile, Aarti Industries maintains a globally oriented production footprint that supports pharmaceutical customers with consistent API supply. These developments are not isolated incidents; they are symptomatic of a broader industry pattern in which leading firms prioritize upstream security, capacity alignment, and regulatory readiness as foundational elements of long-term competitiveness.
The report systematically evaluates how these competitive forces interact with pricing structures, order Book stability, and customer-switching behavior. By tracing recent operational milestones—including Sinopharm Group's strategic partnership with Nantong Acetic Acid Chemical to expand production capacity and Merck KGaA's acquisition activity in early 2025—the analysis isolates the mechanisms through which capacity adjustments and M&A transactions reshape supply availability, regional balance, and pricing expectations. Readers gain clarity on which moves represent tactical short-term optimizations and which signal structural shifts likely to influence procurement strategy over the next several years.
Market Dynamics: Regulation, Pricing, and Supply Resilience
Regulatory visibility and pricing transparency are the twin pillars upon which procurement decisions now rest. The industry operates within an environment where compliance documentation, safety reporting, and substance recognition directly affect market access and buyer confidence. Phloroglucinol's inclusion in official substance databases, its recognition through FDA UNII identifiers, and its presence in EMA periodic safety update reports for marketed medicines collectively reinforce its regulatory standing and facilitate cross-border procurement. These signals matter because they reduce ambiguity for formulators, wholesalers, and contract manufacturers seeking reliable, auditable supply sources.
Pricing dynamics remain highly sensitive to raw material cost fluctuations, production batch sizing, and grade-specific purity requirements. As of early 2026, bulk pharmaceutical-grade phloroglucinol has been observed trading within a range reflecting these pressures, with price dispersion driven by contract structures, order volume, and regional logistics costs. The report translates these observed price bands into a structured framework for scenario planning, enabling buyers and suppliers to model margin sensitivity, evaluate contract terms, and anticipate the impact of raw material volatility on overall cost of goods. This is especially critical for organizations that rely on steady API input for antispasmodic formulations, specialty synthesis pipelines, or dye manufacturing workflows where cost predictability directly affects product economics.
Regulatory developments also intersect with capacity strategy. The approval of phloroglucinol injection for marketing by Sinopharm Guorui Pharma exemplifies how product-level regulatory milestones can catalyze demand shifts, stimulate downstream procurement, and incentivize upstream capacity expansion. The report assesses how such milestones propagate through the value chain, influencing not only volume expectations but also quality-system requirements, documentation burdens, and the competitive positioning of manufacturers that can demonstrate consistent compliance. By mapping these intersections, the study equips decision-makers with the foresight needed to anticipate supply tightness, evaluate alternative sourcing options, and time procurement commitments to align with anticipated capacity releases.
Inside the Report: Tools for Decisive Action
This study is designed as an operational asset rather than a static reference. Its architecture supports a range of internal use cases, from strategic sourcing reviews and capacity-investment justification to competitive benchmarking and risk assessment. The report integrates historical reconstructions, forward-looking forecasts, and structural analysis into a cohesive decision-support toolset. Key components include:
- A comprehensive market sizing framework that traces revenue evolution across historical years and projects growth through the forecast period, providing a consistent baseline for scenario modeling and investment appraisal.
- Segment-level analysis covering type classifications, application domains, and regional distribution patterns, presented in a way that highlights relative share, growth behavior, and demand drivers without obscuring the structural relationships that underpin them.
- A competitive landscape evaluation that profiles leading manufacturers, maps their operational strengths and supply characteristics, and examines recent strategic moves that signal positioning shifts.
- An integrated assessment of regulatory developments, pricing behavior, and raw material dynamics, linked to practical frameworks for procurement planning, contract negotiation, and supply continuity management.
- Forward-looking insights that connect market concentration, capacity expansion activity, and product-level regulatory milestones to medium-term supply expectations and competitive reordination risks.
Throughout the analysis, emphasis is placed on interpretability and applicability. Data points are contextualized within operational realities, and projections are accompanied by the assumptions and sensitivities that shape them. This approach ensures that readers can translate high-level trends into specific, defensible actions—whether that means reevaluating supplier portfolios, assessing the strategic value of long-term contracts, or prioritizing internal investments in quality systems and compliance infrastructure.
Turning Intelligence into Advantage
Markets characterized by moderate growth, concentrated supply, and regulatory sensitivity reward organizations that combine analytical rigor with operational discipline. The phloroglucinol market is no exception. Its trajectory through 2032 will be shaped by the interplay of capacity expansion, compliance readiness, pricing sensitivity, and the strategic choices of a relatively small group of influential manufacturers. For executives navigating this environment, timely and well-structured intelligence is the difference between reactive adjustment and proactive positioning.
Our full report delivers the depth, granularity, and strategic framing required to make informed decisions with confidence. It provides the segmented breakdowns, competitive profiles, pricing frameworks, and forward scenarios that executives need to align sourcing strategies, evaluate investment opportunities, and anticipate the competitive moves that will define the next phase of market evolution. To access the complete analysis and integrate it into your planning cycle, visit our official report page for the full Phloroglucinol Market research.
For detailed analysis of this topic, please visit the official page: Phloroglucinol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Encryption Key Management Market Hits $3.8B in 2025, Projects 12.8% CAGR to $8.83B by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Encryption Key Management Market: A 2026 Outlook
As organizations navigate an increasingly complex data security landscape, the management of cryptographic keys has evolved from a technical afterthought to a core strategic priority. The Encryption Key Management Market stands at a pivotal inflection point in 2026, driven by converging forces: tightening regulatory frameworks, the rapid adoption of cloud-native architectures, and the looming transition toward post-quantum cryptographic standards. For enterprise decision-makers, understanding the trajectory of this market is no longer optional; it is a foundational requirement for building resilient, compliant, and future-proof data protection strategies.
Our latest comprehensive research report on the Encryption Key Management Market offers a meticulously structured analysis designed to inform high-stakes 2026 planning. Spanning historical performance from 2020 through 2025 and projecting forward to 2032, the study maps the market's evolution with precision. In 2020, the global market generated approximately 2.08 million USD in revenue. By 2025, this figure had climbed to 3.8 million USD, reflecting sustained enterprise investment in centralized cryptographic controls. Looking ahead, the forecast period from 2026 to 2032 is projected to deliver a compound annual growth rate of 12.8 percent, with market revenue expected to surpass 8.8 million USD by the end of the outlook window. These headline trajectories are more than statistical milestones; they signal a structural shift in how organizations allocate security budgets, modernize legacy infrastructure, and evaluate vendor ecosystems.
Market Dynamics Reshaping Key Management Strategies
The acceleration of the Encryption Key Management Market is being propelled by a confluence of regulatory, technological, and operational dynamics. Chief among these is the ongoing evolution of government and industry standards. In December 2025, NIST released the initial public draft of SP 800-57 Part 1 Revision 6, updating foundational recommendations for cryptographic key management. With public comment open through February 2026, this revision signals a heightened emphasis on lifecycle governance, algorithmic agility, and alignment with emerging threat models. For compliance and architecture teams, these updates will directly influence procurement criteria, audit readiness, and the design of internal key governance frameworks.
Simultaneously, the quantum computing horizon is forcing a reevaluation of long-term cryptographic investments. Utimaco's 2025 PQC Readiness Report, which surveyed more than 200 IT security professionals, underscored an urgent industry consensus: organizations must begin embedding post-quantum cryptographic capabilities into their key management roadmaps now, rather than treating them as a distant future concern. This sentiment is echoed in recent product and partnership movements. Utimaco's launch of a Post Quantum Security App Package in April 2025 and its subsequent integration into the VAST Cosmos ecosystem in March 2026 demonstrate how vendors are translating quantum readiness from theoretical discussion into deployable, infrastructure-grade solutions. The implications for enterprise architects are clear: key management platforms must already be evaluated for crypto-agility, algorithm swapping capabilities, and compatibility with external hardware security module ecosystems.
Operational complexity continues to compound these regulatory and technological pressures. As enterprises expand across hybrid and multi-cloud environments, the administrative overhead associated with fragmented key inventories, inconsistent rotation policies, and disparate access controls has become a material bottleneck. Modern key management solutions are increasingly judged not only on cryptographic robustness but also on their ability to provide unified operational visibility, automated policy enforcement, and seamless integration with existing cloud service provider toolchains. Reducing the human and procedural burden of key lifecycle management has emerged as a decisive factor in vendor selection and platform consolidation efforts.
Report Scope: Operational Content for Executive Decision-Making
The report is structured to move beyond high-level market sizing and deliver actionable intelligence that can be directly plugged into enterprise planning cycles. Readers will find a detailed examination of deployment models, procurement pathways, and integration requirements that reflect the actual operating conditions of modern security teams. The analysis breaks down the market across multiple functional dimensions, allowing decision-makers to isolate the segments most relevant to their organizational context without getting lost in undifferentiated aggregates.
Key components of the research include:
- A rigorous historical reconstruction of market performance from 2020 to 2025, establishing baseline trajectories and highlighting inflection points where investment patterns shifted in response to cloud migration, regulatory changes, and vendor consolidation.
- A forward-looking forecast model extending through 2032, built on scenario-informed assumptions that account for regulatory uptake, cloud adoption curves, and the gradual mainstreaming of advanced cryptographic capabilities.
- A structured segmentation analysis that disentangles the market by deployment type, functional application, and geographic concentration. This enables readers to identify which solution categories are absorbing the most enterprise spend, which use cases are driving platform selection, and how regional maturity profiles differ across major economic zones.
- A deep competitive landscape assessment that profiles the leading platforms, maps their strategic positioning, and evaluates how recent product launches, partnership announcements, and standards alignment are reshaping vendor differentiation.
- An integrated regulatory and standards timeline that cross-references NIST guidance, industry readiness reports, and enterprise compliance requirements, helping teams anticipate audit expectations and align procurement cycles with forthcoming guidance updates.
Throughout the document, qualitative insights are anchored to verifiable data points and recent industry events, ensuring that strategic recommendations are grounded in observable market behavior rather than speculative projections. The report is designed to serve chief information security officers, enterprise architects, procurement leaders, and risk compliance officers who need a shared, evidence-based reference point for multi-stakeholder 의사결정에.
Competitive Landscape: Leaders, Innovators, and Strategic Positioning
The Encryption Key Management Market is characterized by a pronounced concentration of enterprise revenue among a select group of platform providers, while a broader field of specialized and cloud-native players competes on integration depth, cryptographic agility, and regional compliance capabilities. Market concentration metrics highlight the dominance of established vendors, with the top three firms collectively capturing a substantial share of total revenue and the top five extending that footprint further. This consolidation reflects the enterprise preference for platforms that offer comprehensive lifecycle management, proven cloud integrations, and clear alignment with external compliance frameworks.
Among the most influential players, AWS Key Management Service continues to anchor a large portion of cloud-native deployments. Its centralized creation, storage, rotation, and access control capabilities support encryption, signing, and multi-cloud hybrid deployments, making it a default consideration for organizations already invested in Amazon's ecosystem. Recent product enhancements, such as the April 2025 integration enabling server-side encryption for Amazon S3 Tables using customer-managed keys, illustrate how platform vendors are continuously expanding the scope of managed key use cases to cover structured data workloads and analytics pipelines.
Google Cloud's Cloud Key Management Service offers a parallel trajectory, emphasizing generation, management, and external linking of keys across Google Cloud services. Its external key management support extends the platform's reach for organizations that prefer to retain certain cryptographic controls with third-party managers, a configuration that is increasingly relevant for regulated industries and sovereignty-sensitive deployments.
On the enterprise security side, Thales has reinforced its position through the CipherTrust Data Security Platform and CipherTrust Cloud Key Management, which deliver centralized lifecycle management for cloud-native, bring-your-own-key, and hold-your-own-key models across public clouds. This breadth of deployment models appeals to organizations navigating complex data residency requirements and hybrid architectures that span on-premises infrastructure and multiple cloud providers.
Utimaco has emerged as a particularly dynamic force in the market, combining hardware security module support with software-defined key management and a strong emphasis on post-quantum preparedness. Its Enterprise Secure Key Manager and Secure Server offerings provide crypto-agile key management with unified on-premises and cloud control, directly addressing the administrative consolidation needs flagged by security teams. The company's recent activity underscores a dual focus on standards alignment and ecosystem expansion: the April 2025 Post Quantum Security App Package, the March 2026 VAST Cosmos partnership for AI data infrastructure compliance, and the February 2025 PQC Readiness Report collectively position Utimaco as a vendor bridging immediate operational needs with longer-term cryptographic resilience.
Fortanix complements this landscape with a data security manager that delivers HSM-grade key management, full lifecycle controls, bring-your-own-key management capabilities, and integration for multi-cloud and hybrid environments, including support for external key management models on Google Cloud Platform. IBM continues to reinforce its enterprise data protection portfolio through key management solutions and data security services that emphasize bring-your-own-key configurations and cloud integration, catering to large organizations with stringent governance requirements.
Regional and cloud-native entrants are also shaping competitive dynamics. Alibaba Cloud's Key Management Service provides scalable, compliant key generation, storage, and envelope encryption with webhook and customer-managed key configurations, aligning with the needs of organizations operating within its cloud ecosystem. KakaoCloud's Key Management Service offers secure, systematic key management for its cloud environments with automated encryption controls, reflecting the broader trend of regional cloud providers embedding cryptographic governance directly into their service layers.
The competitive narrative in 2026 is increasingly defined not by raw feature count but by the ability to operate seamlessly across deployment boundaries, accommodate evolving cryptographic standards, and reduce the operational friction associated with key sprawl. Vendors that can demonstrate clear migration paths, transparent audit trails, and forward compatibility with emerging algorithmic requirements are gaining decisive advantage in enterprise evaluations.
Commercial Encryption Products Market
Strategic Takeaways for 2026 Enterprise Decisions
For organizations mapping their security investments in 2026, the Encryption Key Management Market presents both a consolidation opportunity and a resilience imperative. The most consequential decisions will revolve around platform selection criteria that balance immediate operational efficiency with long-term cryptographic adaptability. Enterprises that treat key management as a static compliance checkbox risk accumulating technical debt as regulatory expectations evolve and cloud architectures grow more distributed.
Several strategic priorities emerge from the current market trajectory:
Encryption Key Management Market
- Align procurement cycles with forthcoming standards updates, particularly those stemming from NIST's evolving key management guidance, to ensure that selected platforms can accommodate revised lifecycle and governance expectations without disruptive re-architecture.
- Evaluate vendor roadmaps for post-quantum readiness, including the availability of algorithm agility, hybrid cryptographic modes, and integration pathways with hardware security modules or external key management services.
- Prioritize unified operational visibility across on-premises and cloud environments, as the administrative burden of fragmented key inventories continues to be a primary driver of platform consolidation and budget reallocation.
- Assess multi-cloud and hybrid deployment compatibility early in the selection process, since environments that span multiple cloud providers or combine managed services with self-managed infrastructure increasingly require portable key management models and consistent policy enforcement.
- Consider the concentration dynamics of the vendor landscape when planning for vendor risk, support continuity, and negotiation leverage, recognizing that a small number of platforms account for a significant share of enterprise adoption while specialized providers compete on niche cryptographic and compliance capabilities.
The broader implication is that key management is becoming a strategic architecture layer rather than a discrete utility. Enterprises that embed cryptographic governance into their cloud migration, data classification, and incident response planning will be better positioned to absorb regulatory changes, operational complexity, and emerging cryptographic threats without sacrificing agility.
Conclusion: Accessing the Full Intelligence Picture
The Encryption Key Management Market is entering a phase of accelerated structural change, where growth rates, competitive positioning, and regulatory expectations intersect to reshape how organizations protect their most sensitive data assets. The headline trajectory of the market reflects sustained enterprise commitment to cryptographic governance, but the real value for decision-makers lies in understanding the segmentation patterns, vendor movement, and operational dynamics that will determine which platforms deliver durable value over the next several years.
This report provides the analytical framework needed to evaluate those dynamics with precision. By integrating historical performance, forward-looking forecasts, detailed segmentation breakdowns, and a granular competitive assessment, it equips enterprise teams with a shared reference point for budgeting, vendor evaluation, and architecture planning. The complete dataset, including the full regional, type-based, and application-level segmentation splits, as well as the in-depth competitive profiles and scenario-informed forecasts, is available through the full report. Organizations seeking to translate these market signals into concrete 2026 action plans are encouraged to access the complete study for a comprehensive view of the strategic opportunities and risks shaping the Encryption Key Management Market.
For detailed analysis of this topic, please visit the official page: Encryption Key Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Earthing Lightning Protection Market to Hit $10.61B by 2032 at 7.3% CAGR
By PW Consulting, 2026-09-16
Navigating the Surge: Strategic Intelligence for the Earthing Lightning Protection System Market in 2026
The global infrastructure landscape is undergoing a critical transformation, driven by the accelerating need for resilient electrical safety systems. As we move deeper into 2026, the Earthing Lightning Protection System Market stands at a pivotal juncture where historical growth trajectories meet new regulatory and technological realities. For industry stakeholders, investors, and strategic planners, understanding the nuances of this evolution is not merely an academic exercise—it is a fundamental requirement for risk mitigation and capital allocation.
This article serves as an executive overview of the comprehensive market research recently published by PW Consulting. Our analysis draws upon a robust dataset spanning from 2020 through 2025, offering a detailed forecast window extending to 2032. The objective is to arm decision-makers with the foresight necessary to navigate a market defined by stringent compliance standards, material innovations, and shifting geographic demands. The following insights represent the high-level strategic value embedded within our full report, highlighting why deep-dive intelligence is essential for capturing the opportunities within this sector.
Lightning Arrester Market
Market Trajectory and Financial Horizons
The financial architecture of the Earthing Lightning Protection System Market demonstrates a consistent upward trend, reflecting the global prioritization of infrastructure safety. Our research indicates that the overall market revenue has seen steady expansion over the past half-decade. Starting from a baseline in 2020, the market has cultivated substantial momentum, reaching significant valuation milestones by 2025. This historical performance sets the stage for a forecast period that analysts view with considerable optimism.
Looking toward the immediate and long-term future, the growth trajectory suggests a compound annual growth rate (CAGR) that underscores the sector's vitality. This expansion is not accidental; it is the result of compounded investments in industrial safety, renewable energy integration, and telecommunications infrastructure. However, raw numbers alone do not tell the whole story. The strategic value lies in understanding the velocity of this growth and the specific drivers that will sustain it beyond 2026. Our report dissects these financial flows to reveal where capital is concentrating and where future revenue streams are likely to emerge, providing a clear lens through which to view investment potential.
Regulatory Frameworks as Growth Engines
One of the most potent catalysts for market expansion is the evolving landscape of international safety standards. Compliance is no longer optional; it is a prerequisite for market entry and operational continuity in many regions. The industry is heavily influenced by established protocols such as the IEC 62305 series, which mandates comprehensive earthing and lightning protection systems for structures and electrical installations. Similarly, the UL 96A standard establishes rigorous requirements for the installation of lightning protection systems, including grounding electrodes, specifically targeting commercial and industrial applications.
These regulations create a structured environment where compliance drives demand. For manufacturers and service providers, alignment with standards like NFPA 780 and UL 96A is critical. Our analysis explores how these regulatory frameworks vary by region and application, creating unique barriers to entry and opportunities for specialization. Companies that can navigate this complex compliance web effectively are positioned to capture greater market share. The report details how these standards influence design choices, material specifications, and installation protocols, ensuring that stakeholders understand the operational implications of regulatory adherence.
Technological Innovations and Material Science
Beyond regulation, the market is being reshaped by advancements in material science and product design. The performance of earthing systems relies heavily on the resistivity of the ground and the conductivity of the materials used. Industry data highlights the importance of copper bonded electrodes in maintaining low resistance grounding performance, often requiring systems to achieve thresholds below 10 ohms. Furthermore, copper conductors and plates are frequently specified for earthing systems to achieve even stricter grounding resistance targets, such as below 4 ohms, in lightning protection setups.
Recent developments indicate a shift toward more application-specific solutions. For instance, recent product announcements have showcased retractable grounding assemblies for storage tanks, addressing niche requirements within oil and gas facilities. Additionally, the release of comprehensive product catalogs and design tools is streamlining the engineering process for contractors and engineers. These innovations reduce installation time and improve reliability, which in turn accelerates adoption. Our research evaluates these technological shifts to determine which innovations are likely to become industry standards and which represent transient trends. Understanding the technical specifications behind these products is crucial for procurement teams and engineering leads.
Competitive Landscape and Key Players
The market structure is characterized by a mix of established multinational corporations and specialized regional manufacturers. Our analysis identifies key companies that are defining the competitive boundaries. These entities range from manufacturers of structural lightning protection components and grounding electrodes to providers of application-specific systems and surge protection integration.
Leading players such as nVent ERICO and DEHN SE are recognized for their specialist capabilities in integrating lightning protection with surge suppression and compliance standards. Meanwhile, firms like Harger Lightning and Grounding and Lightning Eliminators focus heavily on structural components and application-specific assemblies, particularly in the North American market. Other significant contributors include Furse and LPI Group, which provide complete systems across Europe and the UAE, and regional powerhouses like Gravin Earthing & Lightning Protection System and Bahra Electric, which serve specific material and geographic needs.
The competitive dynamics are further influenced by the low market concentration, suggesting ample opportunity for new entrants or niche players who can differentiate through technology or service. Our report provides a detailed competitive benchmarking analysis, evaluating the strategic moves, product launches, and standard updates undertaken by these key entities. By understanding the strategies of these market leaders, organizations can better position themselves to compete or collaborate effectively.
Strategic Segmentation and Application Drivers
Demand for earthing and lightning protection is not uniform across all sectors. The market is segmented by type, region, and application, each with its own growth drivers. The division between Lighting Protection Systems and Earthing Systems represents a fundamental split in product focus, with both segments contributing significantly to overall revenue. However, the application side offers deeper insights into where the immediate demand lies.
Key application areas include industrial factories, solar plants, telecommunications towers, residential homes, and the oil and gas sector. Each of these verticals faces distinct risk profiles and compliance requirements. For example, solar plants require robust earthing to protect significant capital investment in photovoltaic arrays, while factories demand systems that can handle high-voltage industrial loads. Telecom towers, often located in exposed areas, rely heavily on effective lightning protection to ensure network uptime. Our report breaks down these application drivers to reveal which sectors are experiencing the highest velocity of adoption. We analyze the specific needs of each vertical without disclosing the precise revenue splits, encouraging stakeholders to consult the full dataset for actionable allocation strategies.
Earthing Lightning Protection System Market
Regional Dynamics and Growth Variations
Geography plays a crucial role in market performance. Different regions exhibit varying levels of infrastructure development, regulatory strictness, and climatic conditions that influence lightning risk. The market is distributed across major global regions, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa.
Asia Pacific, for instance, represents a significant portion of the market volume, driven by rapid industrialization and infrastructure projects. North America and Europe maintain strong demand due to mature regulatory environments and the retrofitting of existing structures. Emerging markets in Latin America and the Mideast and Africa present growth opportunities linked to energy projects and urban development. However, navigating these regions requires an understanding of local standards and supply chain logistics. Our comprehensive study maps these regional nuances, offering guidance on where to focus sales efforts and distribution networks. We highlight the macro trends in each geography while reserving specific regional revenue figures for the detailed report to ensure clients benefit from the complete intelligence package.
Market Concentration and Consolidation Trends
An important aspect of the competitive environment is the level of market concentration. Current data suggests a fragmented landscape where no single entity dominates the entire value chain. This fragmentation indicates that while large players hold significant influence, there is substantial room for competition based on quality, innovation, and regional expertise.
This structure impacts pricing power, supply chain resilience, and merger and acquisition strategies. Companies looking to expand may find opportunities to consolidate smaller regional players to gain market access. Conversely, smaller firms may seek partnerships with larger integrators to broaden their solution offerings. Our analysis examines the implications of this concentration level, providing context for strategic partnerships and M&A activities. Understanding the balance of power among the top competitors is essential for forecasting market stability and pricing trends.
In conclusion, the Earthing Lightning Protection System Market offers substantial opportunities for those equipped with the right intelligence. The convergence of regulatory pressure, technological advancement, and infrastructure development creates a fertile environment for growth. However, realizing this potential requires more than a surface-level understanding of the market. It demands a deep dive into the specific drivers, competitive maneuvers, and regional intricacies that define the landscape.
This article has provided a strategic overview of the key themes shaping the industry in 2026 and beyond. Yet, the full extent of the opportunity lies in the details. The complete PW Consulting market research report offers exhaustive data, precise segmentation analysis, and actionable forecasts that go beyond the macro trends discussed here. For enterprises ready to make informed decisions on product development, market entry, or investment, accessing the full intelligence is the critical next step. We invite you to explore the complete study to unlock the comprehensive insights necessary to lead in this evolving market.
For detailed analysis of this topic, please visit the official page: Earthing Lightning Protection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Photocatalyst Market Hits $2.2B in 2025, Forecasts 9.6% CAGR to $4.18B by 2032
By PW Consulting, 2026-09-16
The Photocatalyst Market in 2026: A Strategic Compass for Industrial Transition
The global photocatalyst market stands at a pivotal inflection point. After a decade of incremental adoption driven by niche environmental applications, the sector is now accelerating under the combined weight of regulatory pressure, urban air-quality mandates, and next-generation construction standards. Our latest market research delivers a comprehensive, forward-looking assessment of this landscape, designed specifically to equip corporate strategists, R&D directors, and investment committees with the operational intelligence needed to navigate decision-making in 2026 and beyond.
By consolidating five years of historical performance with a seven-year forecast horizon, the study maps how demand is structurally shifting across material classes, end-use sectors, and regional ecosystems. More importantly, it translates macro trajectories into actionable strategic frameworks—covering supply-chain resilience, regulatory compliance pathways, competitive positioning, and innovation roadmaps. This is not a static sizing exercise. It is a decision-support architecture for enterprises that must anticipate where capital, technology, and policy will converge over the next cycle.
A Market Accelerating Under Structural Tailwinds
Photocatalysis has evolved from a laboratory-scale environmental concept into a commercially embedded technology set. The sector’s valuation trajectory over the past half-decade reflects a clear acceleration, with revenue compounding steadily from the early 2020s through the current base year. That momentum is projected to intensify as the forecast window unfolds, supported by a compound annual growth rate that places the industry among the faster-growing segments within advanced materials and environmental technologies.
The underlying drivers are multifaceted and mutually reinforcing. Stricter indoor-air VOC and NOx emission standards worldwide are pushing facility operators, architects, and municipal authorities toward photocatalytic air-purification and self-cleaning materials. Simultaneously, the European Green Deal’s circular-economy provisions are channeling subsidies into sustainable construction materials that incorporate photocatalytic glazing and surface treatments. These policy signals are not isolated; they are compounding with corporate sustainability commitments, urbanization pressures, and a growing recognition that passive environmental remediation can deliver measurable operational savings over asset lifecycles.
Precious Metal Catalyst Market
Yet growth is not uniform, and the strategic implications vary sharply by material type, application architecture, and geographic footprint. This is precisely where high-level headlines fall short and granular, structured analysis becomes essential. Our research dissects the market’s composition without exposing the margin for guesswork, allowing leadership teams to evaluate where their portfolios align with the steepest growth vectors and where exposure to slower-moving segments requires defensive repositioning.
Photocatalyst Market
From Macro Trajectories to Operational Strategy
The study is structured to bridge the gap between top-line market direction and on-the-ground execution. Rather than presenting a single aggregate figure, the report builds a layered view of demand dynamics, pricing behavior, and technology substitution patterns across the forecast horizon. It examines how input-cost volatility—particularly within high-purity titanium dioxide feedstock supply chains, where production remains concentrated among a limited number of global suppliers—shapes margin structures and procurement strategies for downstream formulators and coating manufacturers.
Supply-chain visibility is a recurring theme. The analysis maps the sensitivity of photocatalytic product economics to upstream raw-material availability, logistics bottlenecks, and regional production capacity. It also evaluates how vertical integration moves by key feedstock and intermediate suppliers influence stability of supply and cost predictability for industrial buyers. For procurement and operations teams, these insights translate into more resilient sourcing frameworks and better-informed make-versus-buy decisions for specialty formulations.
On the demand side, the report traces how application adoption curves diverge across sectors. Air purification, water purification, and self-cleaning surfaces each follow distinct commercialization rhythms, shaped by local regulatory timelines, public-sector procurement cycles, and building-material integration requirements. Anti-fogging and anti-soiling coatings, alongside other emerging use cases, occupy a different risk-reward profile, typically requiring longer validation periods but offering higher differentiation potential once performance thresholds are met. The study outlines the commercial milestones, testing protocols, and certification pathways that govern market entry, helping R&D and product management teams sequence development pipelines against realistic adoption windows.
The forecast framework extends through the end of the decade and into the early 2030s, enabling scenario planning under varying assumptions for regulation, feedstock costs, and regional investment intensity. By modeling how different policy or cost environments could alter demand pacing, the report equips strategy teams to stress-test capital allocation, capacity expansion, and partnership choices well ahead of market inflection points.
Competitive Architecture and the Players Shaping the Next Cycle
The competitive landscape in photocatalysis is defined by a blend of material science specialists, large chemical conglomerates, and application-focused innovators. Concentration metrics indicate that the top three and top five participants command a meaningful share of commercial activity, underscoring the importance of understanding not just who leads today, but how incumbency advantages, differentiation strategies, and partnership ecosystems are evolving.
Kronos Worldwide, Inc. remains a specialist in photocatalytic titanium dioxide grades tailored for self-cleaning surfaces and building materials, positioning its portfolio around architectural and infrastructure demand. Cristal Global, operating through its CristalACTiV platform, has advanced ultrafine titanium dioxide formulations for photocatalytic coatings and NOx abatement applications, with recent product development centered on air-quality improvement use cases. TOTO Ltd. supplies photocatalytic coatings spanning self-cleaning surfaces as well as air and water purification, with a strong footprint in construction and healthcare environments. Ishihara Sangyo Kaisha, Ltd. contributes high-purity titanium dioxide photocatalysts aimed at environmental and industrial applications, while Nippon Soda Co., Ltd. develops and supplies photocatalytic formulations and binders that enable downstream integration.
On the broader materials and environmental catalysis side, BASF SE provides photocatalytic materials for air purification and environmental catalysis, leveraging its scale and cross-sector distribution capabilities. In the innovation frontier, Puralytics LLC has developed PuraMesh photocatalyst technology for advanced oxidation and water/air purification, while Nanoptek Corp. supplies visible-light titania photocatalysts and pigments that address performance limitations in lower-light conditions. Daicel Miraizu continues as a manufacturer of photocatalytic materials and coatings, and the International Photocatalyst Standards Test Centre in the UK serves as an independent testing and certification provider, underpinning market credibility through ISO-aligned evaluation protocols.
Recent corporate activity reinforces the strategic direction of the sector. In early 2026, Cristal Global advanced its CristalACTiV TiO2 products for NOx abatement applications targeting air-quality improvement, signaling continued emphasis on pollution-mitigation endpoints. Around the same period, Tronox highlighted photocatalytic applications within its specialty TiO2 products in its sustainability reporting, while also advancing vertical integration in its TiCl4 supply chain to stabilize TiO2 production. These moves illustrate a broader pattern: leading participants are aligning product development with regulatory tailwinds, while simultaneously working to insulate production from feedstock volatility.
The report examines how these competitive dynamics translate into market access barriers, partnership opportunities, and differentiation strategies. It evaluates where scale, where formulation expertise, and where application validation create durable advantages, and where new entrants or collaborative models may compress incumbency moats over the forecast period.
Why 2026 Is a Decision Window, Not Just a Forecast Year
For corporate decision-makers, 2026 functions as a strategic checkpoint. The convergence of tighter emission standards, subsidy mechanisms for sustainable construction, and evolving testing and certification expectations is reshaping the criteria by which photocatalytic products win commercial adoption. Enterprises that treat this year as a passive continuation of prior trends risk misaligning product roadmaps, sourcing strategies, and go-to-market priorities with the market’s actual direction.
Notable structural forces now shaping that direction include the ongoing influence of environmental compliance on specialty TiO2 product portfolios, with sustainability reporting and regulatory expectations encouraging broader adoption of photocatalytic NOx abatement technologies. In parallel, European frameworks are directing financial support toward circular-economy-aligned building materials, strengthening the economic case for photocatalytic glazing and surface solutions. At the same time, global indoor-air quality standards are tightening, expanding the addressable base for photocatalytic air-purification and self-cleaning materials. Regulatory approvals from bodies such as the European Chemicals Agency have also enabled the commercial launch of new photocatalytic products for air purification, widening the field for innovation-led entrants while raising the bar for compliance-ready product design.
These conditions create a market environment where strategic timing matters as much as technical capability. Companies that understand the interplay between feedstock cost dynamics, regional regulatory pacing, and application-specific certification requirements are better positioned to prioritize investments, negotiate supply agreements, and structure partnerships. The study is built to surface those interdependencies clearly, giving leadership teams a shared analytical baseline for cross-functional planning.
What the Report Delivers for Strategy, R&D, and Commercial Teams
The research is organized to support a wide range of internal use cases. For strategy and corporate development teams, it provides a market-level orientation that ties growth trajectories to competitive positioning, enabling more informed evaluation of adjacency opportunities, M&A targets, and geographic expansion priorities. For R&D and product teams, it maps technology substitution patterns, formulation considerations, and performance-testing expectations, helping calibrate development timelines against market readiness. For commercial and sales leadership, it outlines application-specific demand drivers, procurement contexts, and the regulatory and certification factors that influence buying decisions in construction, environmental services, and industrial settings.
The report also includes practical coverage of market-concentration dynamics, supply-chain sensitivity, and recent corporate developments that shape near-term competitive behavior. It integrates sector-level signals around regulation, raw-material availability, and sustainability reporting trends, translating them into implications for sourcing, pricing, and product positioning. By combining historical context, forecast direction, and qualitative intelligence on the companies and institutions actively shaping the market, the study offers a consolidated reference point for decision-making across functions.
Importantly, the analysis is designed to remain useful beyond the immediate planning cycle. Because photocatalytic adoption is influenced by long-duration assets such as buildings, infrastructure, and industrial facilities, today’s product and sourcing choices have multi-year consequences. The forecast horizon and scenario frameworks included in the research help organizations connect near-term actions to longer-term outcomes, reducing the risk of short-horizon optimization that undermines competitive positioning later in the decade.
Accessing the Full Intelligence Suite
Our Photocatalyst Market study is intended for teams that need more than directional commentary. It provides a structured, data-informed foundation for evaluating where the market is heading, which actors are shaping the pace of change, and how enterprise strategy should respond in 2026 and through the coming forecast years. The complete report includes detailed segmentation analyses, competitive profiles, regulatory and supply-chain assessments, and forecast scenarios that together form a comprehensive decision-support toolkit.
To explore the full segmentation detail, company-level positioning, regional demand architecture, and scenario-based forecasts, request access to the complete market research. The full intelligence suite is available through our official research portal, where strategy, procurement, and innovation teams can retrieve the complete dataset and analytical modules needed to ground 2026 planning in a rigorous, forward-looking view of the photocatalyst market.
For detailed analysis of this topic, please visit the official page: Photocatalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


