



PW Consulting: Grain Bins Market Hits $172.5M in 2025, Projected 5.9% CAGR Through 2032
By PW Consulting, 2026-09-16
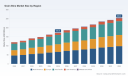
Grain Bins Market Outlook 2026: Strategic Intelligence for Agricultural Infrastructure Decision-Makers
Executive Overview
The global grain storage infrastructure sector is entering a decisive phase of maturity and innovation. As agricultural supply chains adapt to volatile commodity cycles, climate variability, and tightening food security requirements, grain bins remain the foundational asset for harvest preservation, inventory management, and post-harvest value retention. PW Consulting’s latest Grain Bins Market research delivers a rigorously constructed intelligence framework designed specifically for executives, investors, and operational leaders navigating strategic decisions in 2026 and beyond.
This analysis synthesizes historical performance, forward-looking demand signals, competitive positioning, and policy-driven funding mechanisms into a single decision-ready architecture. Rather than presenting static snapshots, the report maps the structural forces that will dictate procurement timing, capital allocation, and product roadmap prioritization across the next seven-year horizon.
Historical Trajectory and the Path to 2032
Over the 2020 to 2025 baseline period, the grain bins market demonstrated consistent expansion, scaling from approximately 120.5 million USD to 172.5 million USD. This growth trajectory reflects a combination of on-farm capacity upgrades, commercial storage expansion, and incremental modernization of aging inventory systems. The momentum has not plateaued. Projections extending through 2032 indicate the market will advance toward the 254 million USD threshold, underpinned by a compound annual growth rate of roughly 5.9%.
For corporate planners, this macro trajectory carries a clear implication: capacity demand is no longer cyclical in the traditional sense. It is being reshaped by structural substitutions, storage optimization mandates, and the gradual integration of digital monitoring into core bin operations. The report isolates the inflection factors that separate temporary procurement spikes from durable demand shifts, enabling leadership teams to time investments with greater precision.
What the Research Delivers: An Operational Blueprint
The Grain Bins Market study is structured as a working document for strategy formulation rather than a passive reference volume. It translates raw market mechanics into actionable intelligence across several interconnected layers:
Grain Combine Harvester Market
Every section is designed to answer a specific executive question. Which material and configuration choices dominate end-user preference? How do geographic procurement patterns reflect regional agricultural economics? Where do financing programs lower barrier-to-entry for new storage installation? The report addresses these questions through layered segmentation analysis, historical-to-forecast continuity checks, and competitive benchmarking that can be directly embedded into pricing, sourcing, and market-entry models.
Technology, Safety, and the Automation Inflection Point
The grain storage industry is undergoing a quiet but consequential operational transformation. Physical storage capacity remains essential, but the value proposition is increasingly defined by how bins are monitored, maintained, and integrated with broader handling systems. Recent industry activity highlights this shift. In late 2025, Ag Growth International launched a farmer-facing digital platform designed to provide real-time monitoring of grain bin conditions, signaling a market-wide move toward continuous visibility rather than periodic manual inspection. Alongside that software launch, the company introduced diesel-driven handling tools engineered for the 2026 season, reinforcing the broader trend toward field-ready, mechanized grain movement equipment.
Material and fabrication innovation is advancing in parallel. Demonstration activity surrounding advanced lamination and structural configurations has begun appearing at major agricultural equipment exchanges, indicating that durability, moisture resistance, and installation efficiency are becoming key differentiators in a crowded supplier landscape. These developments matter because they directly affect total cost of ownership, downtime risk, and long-term storage integrity.
Safety-driven policy support is also reshaping procurement economics. Regulatory and grant mechanisms at the state level have begun reimbursing a substantial share of eligible safety equipment costs for on-farm storage operations. Complementary federal financing programs have lowered upfront capital burdens for storage construction by offering favorable loan structures. Together, these mechanisms reduce friction in the adoption curve and create a more predictable demand environment for manufacturers, distributors, and capital partners. The report examines how these instruments interact with regional purchasing behavior and what they signal for near-term installation velocity.
Competitive Landscape: Orchestration, Specialization, and Regional Density
The grain bins market is characterized by a dense supplier base with pronounced specialization and meaningful concentration among leading participants. Market structure analysis indicates that the top three firms command a substantial share of total revenue, while the top five extend that footprint even further. This concentration pattern suggests that scale advantages in production, distribution, and after-sales service continue to influence customer selection, particularly for larger commercial storage projects and multi-site farm operations.
Several established manufacturers anchor the competitive field. Ag Growth International operates across multiple storage and handling product families under well-recognized brand lines, serving both farm and commercial storage requirements. Sukup Manufacturing Co. remains a prominent family-owned player with deep vertical integration across bins, drying, and handling equipment. CTB, Inc. and its grain-focused business unit provide on-farm and holding bin solutions alongside material handling systems. Superior Grain Equipment, Sioux Steel Company, and Grain Systems, Inc. each contribute distinct structural configurations and accessory ecosystems, while Behlen Manufacturing Company and Westman Manufacturing broaden the field with specialized bin and system offerings. Additional participants such as SCAFCO Grain Systems, Brock Grain Systems, and Chief Industries, Inc. reinforce the breadth of the competitive set and ensure continued pressure on design, service response, and regional availability.
Grain Bins Market
The strategic takeaway is not simply that competition is intense. It is that competition is multidimensional. Suppliers compete on structural design, handling integration, installation speed, digital compatibility, financing alignment, and safety compliance. The report evaluates how these dimensions shape share movement, customer retention, and pricing elasticity across different buyer profiles.
Regional and Application Dynamics Without the Noise
Grain storage demand does not distribute uniformly across markets or use cases. Regional procurement patterns reflect differences in farm structure, harvest logistics, storage financing access, and commercial throughput requirements. Application-side dynamics further differentiate the market, with on-farm storage representing the dominant volume driver and off-farm storage forming a strategically important complement tied to commercial aggregation, drying, and distribution networks.
The research avoids superficial regional or application breakdowns in favor of a more decision-useful approach. It examines how geographic demand nodes evolve under varying commodity price environments, how local safety and financing programs alter project economics, and where infrastructure gaps create either risk or opportunity. This enables readers to anticipate not just where volume is concentrated, but where demand is likely to strengthen, stall, or shift between installation types.
Strategic Implications for 2026 Decision-Makers
As organizations finalize capital plans, procurement cycles, and market positioning for 2026, several implications emerge from the market structure and forward outlook:
The research is built to help executives convert these implications into concrete strategies. Whether the priority is supplier diversification, geographic expansion, product line extension, or financing-aligned go-to-market design, the underlying intelligence is structured to support scenario planning and risk-adjusted investment decisions.
Conclusion: Reading the Market Before the Next Cycle Settles
Grain bins may appear to be a mature storage category, but the surrounding ecosystem is anything but static. Financing instruments, safety mandates, digital monitoring tools, material advancements, and concentrated supplier competition are recombining to create a market with sharper discontinuities and clearer strategic levers than many decision-makers currently appreciate. PW Consulting’s Grain Bins Market research is designed to give leadership teams the clarity required to act early, allocate wisely, and outmaneuver competitors who rely on outdated demand assumptions.
The full study provides detailed segmentation paths, competitive profiling, financing-program impact analysis, and forecast scaffolding that cannot be fully unpacked in a summary view. For executives who need the complete operational intelligence behind these trends, the complete report is available for direct access through our research portal.
For detailed analysis of this topic, please visit the official page: Grain Bins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Football Helmet Market Hits $209M in 2025, 5.2% CAGR to 2032
By PW Consulting, 2026-09-16
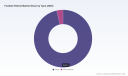
Intercepting Impact: Why the 2026 Football Helmet Market Research Report Is a Strategic Imperative for Industry Leadership
The athletic protection industry stands at a critical inflection point. Where safety once lived in the background of product design, it now sits at the center of regulatory mandates, consumer expectations, and competitive differentiation. PW Consulting’s newly published Football Helmet Market research report transforms that inflection point into a navigable strategic roadmap for executives, product leaders, and investors preparing their 2026 decision calendars. What follows is not a superficial market overview. It is a structured intelligence briefing designed to reveal the contours of opportunity, the pressure points of compliance, and the competitive rhythms that will define the sector through the end of the decade.
The Market Trajectory as a Strategic Compass
From Recovery to Sustained Expansion
The market has moved through a defined cycle over the past half-decade. After navigating a modest contraction in 2023, the sector rebounded with renewed momentum, reflecting a structural shift rather than a temporary correction. Macro-level tracking places the overall market at approximately 209.0 Million USD in 2025, with projected expansion to 224.61 Million USD in 2026. The forecast window through 2032 maps a continued upward arc, anchored by a 5.2 percent compound annual growth rate. Those headline figures are only the entry point. The real value lies in understanding the velocity, the inflection triggers, and the distribution of growth across product lifecycles, channel strategies, and regulatory timelines.
Why the 2026–2032 Window Demands Precision Planning
Growth on paper does not translate automatically into share, margin, or shelf placement. The forecast period coincides with a regulatory and operational environment that will reward organizations capable of aligning product roadmaps, aftermarket services, and channel partnerships to shifting standards. The report is built to support that alignment. It maps the trajectory from the base year of 2025 through a twelve-year horizon, giving decision-makers a framework to pressure-test capacity investments, inventory planning, and go-to-market sequencing before the next wave of compliance deadlines and product launches reshapes the competitive field.
Decoding Competitive Dynamics and Brand Architecture
A Field Shaped by Technology, Licensing, and Performance Validation
The competitive landscape is concentrated and performance-driven. Industry calculations point to a CR3 of 48.5 percent and a CR5 of 59.2 percent, signaling a market where a small cohort of established players command the bulk of revenue while leaving meaningful room for specialized challengers that win on testing credibility and design agility. The research unpacks that architecture in detail, tracing how brand equity, technology portfolios, and institutional relationships interact to create durable advantages or expose strategic vulnerabilities.
Strategic Profiles Across the Leadership Tier
Riddell anchors its position through a dual engine of professional league alignment and product breadth. Headquartered in Des Plaines, Illinois, the company continues to center its strategy on the Axiom and SpeedFlex lines for varsity and youth football, reinforced by its standing as an NFL licensee and market leader in professional play. That licensing foundation provides a durable visibility channel, while recent 2026 product activity signals ongoing investment in younger athlete segments and energy-management engineering. Schutt Sports, based in Plainfield, Indiana, competes with a focus on impact protection and fit systems across the F7 LTD, F7 UR1, and Vengeance series, positioning fit and protective performance as the core commercial message for varsity programs. LIGHT Helmets, operating from Carlsbad, California, has carved a distinct lane with ultra-lightweight Gladiator ATK and Apache varsity helmets that have earned top-tier recognition in Virginia Tech helmet testing, appealing to programs that prioritize weight reduction and independently validated performance metrics. VICIS, with U.S.-based operations, maintains a technology-first identity through the ZERO2 Trench and ZERO2 varsity lines, consistently ranked at the highest level in independent impact performance testing, a positioning that resonates with institutions seeking performance differentiation in a technology-sensitive purchasing environment. Xenith’s Orbit Pro and Shadow XR varsity helmets remain part of the broader competitive conversation as acquired assets have been integrated into the Riddell portfolio, reshaping how legacy technology, brand assets, and channel access are managed within a consolidated structure.
Helmets Market
Recent Moves That Alter the Competitive Rhythm
The competitive tempo is not static. In March 2026, Riddell introduced the ND6 youth football helmet line designed to meet the new NOCSAE ND006 youth standard, alongside the SF Echo varsity model featuring energy management liners and inflatable face frames. Developments of this kind are more than product announcements. They are signals about compliance readiness, segment prioritization, and engineering priorities that competitors must interpret and respond to. The report places such launches within a wider strategic context, helping leaders determine whether to match, differentiate, or reposition around evolving performance and regulatory expectations.
Regulatory and Lifecycle Forces That Reshape Purchasing Behavior
Youth Standards and the Compliance Horizon
Regulatory architecture is becoming a direct driver of product planning. NOCSAE finalized the first-ever performance standard for youth football helmets, ND006, on February 7, 2025, with an effective date of September 1, 2027. That timeline creates a defined window for design adjustments, validation cycles, and supply chain readiness. Rather than treating compliance as an endpoint, the report treats it as a planning variable, helping organizations understand how standards influence launch sequencing, inventory positioning, and the pace at which existing lines may require revision.
Football Helmet Market
Recertification, Warranty Validity, and the Economics of Aftermarket Service
The aftermarket dimension is no longer a secondary concern. As of October 2025, NAERA recommends that every football helmet be reconditioned and recertified annually for warranty validity, with manufacturer intervals enforced. At the same time, NOCSAE and manufacturer guidelines limit football helmet recertification to a maximum of 10 years from the manufacture date, and NAERA members no longer accept for reconditioning any football helmets more than 10 years old. These parameters reshape the economics of product ownership, influence repurchasing cycles, and elevate the strategic importance of service networks, parts availability, and lifecycle messaging. The report examines how these rules alter buyer behavior across programs, boost demand for validated reconditioning pathways, and create opportunities for organizations that can integrate protection, service, and compliance into a single customer proposition.
Licensing and Brand Visibility as Strategic Multipliers
Not all competitive advantage comes from product engineering. Riddell extended its NFL exclusive license and promotional rights for collectible helmets through the 2030 season, a move that sustains brand visibility, strengthens fan-facing engagement, and reinforces the commercial halo around core protection lines. Such licensing arrangements influence category perception, demand patterns, and the ability to command attention in crowded purchasing environments. The research evaluates how these rights interact with product strategy and channel positioning, so leaders can assess whether visibility, endorsement, and collectible extensions support or distract from core commercial objectives.
What the Report Delivers: Operative Intelligence for 2026 Planning
This publication is engineered for action. It synthesizes market sizing, growth trajectory, segmentation logic, competitive profiles, and regulatory context into a single decision-support framework. Rather than leaving readers with isolated statistics, the report connects numbers to operating choices: how to sequence product introductions, where to concentrate inventory and service capacity, how to interpret testing credibility as a commercial asset, and how to anticipate the timing of standards-driven purchasing shifts. The content is structured to support product strategy, sales planning, supply chain configuration, and investment prioritization with the level of specificity required for boardroom and planning-table use.
The segmentation analysis is designed to reveal where demand is accumulating and how different product architectures and program levels interact with purchasing behavior. By examining regional and application patterns in relation to product type and lifecycle requirements, the report helps leaders understand which environments are expanding, which are stabilizing, and where service, safety validation, and compliance readiness are becoming the dominant purchasing criteria. That perspective is essential for organizations that need more than growth rates; they need to know how demand is composed and how that composition will influence channel strategy and product mix over the forecast horizon.
Why the Full Report Is the Next Strategic Step
The headline trajectory tells us the category is expanding. The competitive and regulatory context tells us that expansion is conditional on timing, validation, compliance preparation, and service capability. What remains is the granular intelligence required to convert that knowledge into execution. The complete PW Consulting Football Helmet Market research report delivers that intelligence in a structured, decision-ready form. It provides the segment-level detail, competitive depth, and regulatory timeline mapping that executives need to calibrate product roadmaps, service networks, and commercial positioning for 2026 and the years that follow.
Organizations that enter this planning cycle with full visibility will be better positioned to align engineering investments with emerging standards, to anticipate the purchasing implications of recertification and warranty rules, and to interpret competitor launches as strategic signals rather than isolated events. Those that rely on partial information risk optimizing for yesterday’s market structure. The complete report is the instrument for navigating the next phase with precision, confidence, and strategic clarity.
For detailed analysis of this topic, please visit the official page: Football Helmet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DRM Market Hits $1,680M in 2025, Poised for 7.5% CAGR Growth to 2032
By PW Consulting, 2026-09-16
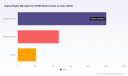
The Strategic Imperative of Digital Rights Management: Navigating the 2026 Market Shift
Executive Overview: Why DRM Intelligence Matters Now
Digital Rights Management has evolved from a niche technical safeguard into a foundational pillar of digital commerce. As content consumption models fragment across streaming, interactive entertainment, and enterprise digital workflows, organizations face mounting pressure to protect intellectual property while maintaining seamless user experiences. Our latest market research report provides a comprehensive, data-driven examination of the DRM landscape, designed specifically to equip executive leadership and strategic planning teams with the intelligence required to make confident, forward-looking decisions in 2026 and beyond.
The global DRM market has demonstrated consistent, compounding growth over the past half-decade, expanding from approximately 1,200 million USD in 2020 to 1,680 million USD in 2025. This upward trajectory reflects broader structural shifts in how media, software, and published content are monetized, distributed, and secured. Looking ahead, the market is projected to maintain a robust compound annual growth rate of 7.5 percent through the forecast period ending in 2032, reaching an estimated 2,740 million USD. These figures are not merely historical retrospectives; they serve as leading indicators of capital allocation priorities, technology investment cycles, and competitive positioning strategies that will define the next wave of digital business models.
Macro Market Trajectory and Forecast Architecture
Understanding the scale and velocity of market expansion requires more than surface-level sizing. Our research framework tracks historical performance across a six-year baseline, establishing a reliable foundation for predictive modeling. The data reveals a steady acceleration in revenue generation, driven by the proliferation of high-value digital assets and the corresponding demand for enterprise-grade protection mechanisms. Each successive year has shown measurable gains, with the transition from 2024 to 2025 marking a notable inflection point as organizations scaled their security infrastructure to match increasingly sophisticated distribution networks.
The forward-looking forecast window spans seven years, offering a structured view of how market participants can anticipate capacity requirements, partnership opportunities, and technology lifecycle transitions. Rather than presenting isolated snapshots, the report constructs a continuous growth narrative that aligns with product roadmaps, regulatory timelines, and shifting consumer behavior patterns. Decision-makers will find this temporal architecture particularly valuable when evaluating long-term technology adoption cycles, assessing infrastructure readiness, and mapping resource allocation against projected demand curves.
Key Structural Components of the Market
The DRM ecosystem is inherently multidimensional, with value creation distributed across distinct solution categories, application verticals, and geographic corridors. Our analysis dissects these layers to reveal where investment flows concentrate and how operational priorities diverge across sectors.
- Software-based protection platforms continue to represent the largest share of market activity, reflecting the industry's preference for scalable, adaptable licensing frameworks that integrate directly into digital delivery pipelines.
- Hardware-embedded security solutions maintain a substantial footprint, particularly in environments where physical media distribution, broadcast infrastructure, or specialized playback devices require dedicated encryption and access control mechanisms.
- Professional services and implementation support form a critical enabler layer, addressing the complexity of integrating rights management into legacy workflows, compliance frameworks, and multi-vendor technology stacks.
Across application landscapes, the music industry continues to drive significant adoption, followed closely by film and television production, gaming ecosystems, and digital publishing. Each vertical presents unique protection requirements, licensing models, and consumer engagement patterns that demand tailored strategic approaches. Geographic distribution further illustrates the global nature of digital content markets, with mature economies maintaining established protection infrastructures while emerging regions accelerate their adoption curves to support expanding digital distribution networks.
Competitive Landscape and Strategic Positioning
The DRM vendor ecosystem is characterized by a layered competitive structure where market concentration remains moderately high, reflecting the technical complexity, compliance requirements, and long-term partnership dynamics inherent to content security. The top three players collectively account for a substantial share of industry activity, while the top five firms extend their influence across multiple solution categories and geographic markets. This concentration pattern signals both the barriers to entry in enterprise-grade protection and the strategic importance of vendor selection for organizations building or expanding their digital distribution capabilities.
Leading Market Participants and Their Value Propositions
Verimatrix delivers multi-DRM and embedded protection architectures specifically engineered for OTT platforms and media distribution networks. Their approach emphasizes layered security models that combine encryption, forensic watermarking, and anti-piracy monitoring to protect premium video streams across diverse playback environments.
Nagra, operating through the Kudelski Group and Conax divisions, provides multi-DRM service frameworks and the Contego platform, which supports secure streaming content protection across major DRM standards. With deployment across more than fifty service providers globally, Nagra's infrastructure highlights the industry's shift toward interoperable, provider-agnostic security ecosystems that can adapt to evolving licensing agreements and device compatibility requirements.
Adobe anchors its DRM strategy in content protection for video workflows and enterprise digital asset management. Through Primetime DRM and Experience Manager Assets, the company enables rights enforcement, compliance tracking, and controlled access within complex digital production pipelines, addressing the needs of organizations that must balance creative distribution with strict licensing adherence.
Microsoft integrates DRM capabilities across both consumer media protection and enterprise information security. PlayReady DRM supports premium video licensing and playback control, while Azure Rights Management extends protection to documents, communications, and internal data flows, illustrating how digital rights concepts increasingly overlap with broader information security strategies.
Google's Widevine DRM remains a cornerstone of premium media protection, powering licensing, playback verification, and content access control across consumer devices and streaming services. Its widespread adoption underscores the importance of standardized, device-compatible protection frameworks that can scale across heterogeneous hardware and software environments.
Recent Partnership Activity and Ecosystem Integration
The competitive landscape continues to evolve through strategic alliances that expand protection capabilities and integrate DRM into new content delivery contexts. In early 2026, BuyDRM solidified its position through multiple high-profile engagements, including a partnership with Mostly Music to secure premium music experiences using forensic watermarking and advanced protection techniques, a collaboration with OneFootball to safeguard streaming channels on its digital platform, and the deployment of its MultiKey Service to power secure streaming on Telenet's TV Iconic offering. These developments illustrate how DRM providers are embedding themselves deeper into content creator and distributor workflows, moving beyond standalone licensing to become integral components of end-to-end delivery architectures.
Regulatory Foundations and Market Dynamics
The DRM market does not operate in a vacuum; it is shaped by a long-standing regulatory and standards-driven environment that defines how rights are expressed, enforced, and balanced against consumer expectations. Foundational legal frameworks, including landmark copyright legislation from the late 1990s, expanded protection to digital forms and established the legal groundwork for technology-based rights enforcement. Subsequent policy discussions and regulatory reviews have consistently highlighted the prevalence of DRM across hardware, publishing, and media sectors, reinforcing its role as a standard mechanism for controlling access and usage.
Standards organizations have further contributed to the ecosystem by emphasizing the need for interoperability with consumer electronics, blank media, and cross-device playback environments. At the same time, ongoing discourse around rights expression languages has underscored the importance of aligning DRM systems with fair use principles, privacy considerations, and public domain expectations. These dynamics create a complex operating environment where technical protection must coexist with legal compliance, user experience requirements, and evolving societal norms around digital content access.
For enterprises, this regulatory backdrop translates into several operational imperatives. Vendor selection must account for compliance readiness and adaptability to shifting legal interpretations. Product architecture should support flexible rights expression that can accommodate regional differences and emerging policy frameworks. Investment strategies must balance protection robustness with user accessibility to avoid friction that could undermine content engagement or market expansion.
Strategic Applications for 2026 Decision-Making
The insights contained in this report are designed to translate market data into actionable strategic guidance. Executive teams can leverage the findings to inform technology procurement decisions, evaluate partnership and licensing opportunities, and align internal security roadmaps with projected market growth. Procurement and IT leadership will find value in understanding how solution categories differentiate in terms of deployment complexity, integration requirements, and long-term scalability. Content executives and business development teams can use the application-level analysis to identify protection gaps, optimize licensing models, and assess how competitor strategies may influence market positioning.
The report also addresses practical implementation considerations, including integration pathways, compliance alignment, and the operational trade-offs between software-centric and hardware-centric protection approaches. By mapping these factors against historical growth patterns and forward-looking forecasts, the research provides a structured foundation for scenario planning, budget justification, and risk assessment. Organizations preparing for multi-year technology cycles will benefit from the report's emphasis on sustained growth trajectories and the structural forces that continue to drive adoption across content sectors.
Digital Rights Management (DRM) Market
Conclusion and Next Steps
Digital Rights Management is no longer a peripheral security function; it is a strategic enabler of digital monetization, compliance assurance, and content lifecycle management. As market growth accelerates and competitive dynamics intensify, organizations that invest in comprehensive, forward-looking intelligence will be better positioned to navigate technology transitions, regulatory shifts, and evolving consumer expectations. This report delivers the depth, structure, and analytical rigor required to support confident executive decision-making throughout 2026 and the broader forecast horizon.
The complete market research includes detailed segmentation profiles, granular competitive assessments, technology trend analysis, and implementation frameworks that go beyond the high-level overview presented here. To access the full dataset, methodology documentation, and executive-ready strategic recommendations, we invite you to explore the complete report and begin applying these insights to your organization's digital rights strategy.
Intellectual Property Rights Royalty Management Market
For detailed analysis of this topic, please visit the official page: Digital Rights Management (DRM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVA Medical Market Hits $118.1M in 2025, Projects 4.3% CAGR to $154.62M by 2032
By PW Consulting, 2026-09-16
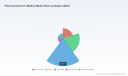
Strategic Intelligence in a Maturing Market: Why the Polyvinyl Alcohol in Medical Sector Demands Precision in 2026
The global market for polyvinyl alcohol (PVA) in medical applications has entered a phase of structured consolidation and disciplined expansion. Over the past five years, steady acceptance of PVA-based excipients, hydrogel systems, and specialty coatings has transformed what was once a niche material segment into a strategically relevant pillar of pharmaceutical and medical device value chains. For executives planning product portfolios, supply strategies, and capital allocation through the rest of the decade, understanding where this market is heading is no longer optional. It is a prerequisite for defensible growth.
This article introduces PW Consulting’s latest market research on Polyvinyl Alcohol in Medical, a study built to convert macro momentum into actionable strategic clarity. The analysis draws on a six-year historical baseline and projects trajectory through the medium term, giving decision-makers a grounded view of how demand, pricing dynamics, regulatory expectations, and competitive positioning are evolving together. The goal is simple: to help organizations move beyond broad assumptions and toward precise, evidence-based planning.
A Market Built on Sustained, Measurable Growth
The medical PVA segment has demonstrated a consistent upward arc, reflecting the material’s expanding role in core pharmaceutical formulations and targeted medical applications. Historical revenue progression shows a clear compound trajectory: from a base near 81.72 million USD in 2020, the market advanced through successive annual increments to reach 118.1 million USD in 2025. That trajectory is projected to continue through the forecast window, with sequential growth milestones mapped across each year to 2032.
For strategy teams, the macro figures are useful only when placed in context. A projected CAGR of 4.3 percent is neither explosive nor stagnant. It is the kind of rate that rewards disciplined execution: steady demand growth from established application areas, gradual adoption in higher-value medical grades, and targeted regional opportunities that reward companies with the right manufacturing footprint and compliance readiness. In this environment, growth is less about chasing volume and more about capturing recurring value through formulation performance, supply reliability, and differentiated product grades.
The market’s trajectory also signals an increasing premium on visibility. As revenues compound year over year, small differences in cost structure, yield, product specification alignment, and regional reach can translate into meaningful advantages or persistent margin pressure. That is precisely why a structured research framework matters: it helps leadership separate durable trends from cyclical noise.
What the Research Delivers: From Market Sizing to Execution-Ready Intelligence
PW Consulting’s Polyvinyl Alcohol in Medical study is designed as an operational reference rather than a static snapshot. The report combines broad market sizing with a detailed structural view of the industry, giving teams the ability to interrogate the market across the dimensions that matter most to planning and execution.
Core Coverage Areas
- Historical performance records and forecast modeling across the full analytical horizon, enabling leadership to test assumptions against observed trends and projected trajectories.
- Segment-by-segment analysis of type profiles, application demand patterns, and regional market structure, presented in a format built for scenario planning and internal alignment.
- Competitive mapping that connects company profiles, product positioning, and recent industry events to broader market dynamics.
- Regulatory and compliance contexts relevant to medical-grade use, including pharmacopoeial alignment and application-specific expectations that influence purchasing decisions and formulation approvals.
- Supply-side considerations such as feedstock dynamics, process economics, and certification pathways that shape cost behavior and product availability.
- Strategic interpretation designed to support decisions in procurement, product development, capacity planning, market entry, and competitive positioning.
The structure is intentionally practical. Rather than offering a single summary view, the research is organized so that commercial, R&D, supply chain, and regulatory stakeholders can each extract relevant insight without losing sight of the broader market logic. This integrated approach is especially valuable in a market where formulation performance, grade suitability, and supply continuity are tightly interconnected.
Why This Format Matters for 2026 Decision-Making
In a market characterized by moderate but dependable growth, the biggest strategic risks often come from misreading the drivers behind the numbers. A product may perform well in one application environment while facing different adoption dynamics in another. A region may show strong potential but require distinct compliance, distribution, or partnership strategies. Recent pricing actions and input-cost pressures further complicate planning, reinforcing the need for a research asset that connects market structure to real-world operating conditions.
The report is built to support exactly that kind of layered decision-making. It gives organizations a shared factual baseline, then adds interpretive depth so teams can evaluate where to invest, where to protect margin, and where to reposition for the next phase of market evolution.
How the Competitive Landscape Is Shaping the Market
The medical PVA space is defined by a concentrated group of capable manufacturers, each bringing distinct product families, technical heritage, and customer relationships to the table. The combined influence of leading firms is substantial, with top-three and top-five players holding a significant share of market concentration. In such an environment, competitive advantage depends not only on scale but on product specificity, regulatory readiness, and the ability to respond quickly to shifting demand and cost conditions.
Polyvinyl Alcohol in Medical Market
Several established companies anchor the competitive landscape. Kuraray Co., Ltd. produces POVAL™, ELVANOL™, EXCEVAL™, and MOWIFLEX™ medical-grade polyvinyl alcohol resins for pharmaceutical excipients, hydrogels, and coatings. Sekisui Specialty Chemicals offers Selvol™ polyvinyl alcohol for medical adhesives, hydrogels, and pharmaceutical applications with specialty medical grades. Mitsubishi Chemical Corporation manufactures GOHSENOL™ and GOHSENX™ pharmaceutical-grade polyvinyl alcohol for excipients, binders, film coatings, and ophthalmic or nasal solutions. Japan VAM & Poval Co., Ltd. supplies pharmaceutical-grade polyvinyl alcohol under brands including PE-05JPS for medical applications. Eastman Chemical Company produces polyvinyl alcohol grades for medical and pharmaceutical applications including hydrogels and coatings.
What distinguishes this group is not merely product breadth, but the way each company aligns its portfolio to medically relevant performance requirements. Pharmaceutical-grade specifications, application-specific consistency, and the ability to support technical customers are repeatedly the differentiators that matter in formulation development and procurement selection. In practical terms, the market rewards suppliers who can pair material quality with reliable compliance documentation and predictable supply behavior.
Recent Industry Movements and What They Signal
Recent developments in the sector have sharpened the importance of forward-looking intelligence. In 2026, multiple leading manufacturers announced pricing actions that reflect both input-cost realities and strategic repositioning. Kuraray Co., Ltd. announced upward price revisions for its POVAL™, ELVANOL™, EXCEVAL™, and MOWIFLEX™ polyvinyl alcohol resins, with additional adjustments communicated for North America, Central America, and South America. Sekisui Specialty Chemicals announced further price increases across several Selvol product lines, including a global increase for Selvol polyvinyl alcohol products at differentiated levels across North America, Latin America, Asia, and EMEA.
These actions should be read as more than routine cost pass-throughs. They underscore a market where feedstock cost movement, regional cost structures, and margin management are increasingly intertwined. At the same time, underlying supply-side conditions such as vinyl acetate monomer feedstock cost increases in early 2026 have placed upward pressure on polyvinyl alcohol prices in Northeast Asia and Europe. Parallel pressures from labor cost increases linked to monomer price volatility have also affected production economics for medical grades.
For buyers and competitors alike, the implication is clear: pricing discipline, grade selection, and regional sourcing strategy now carry greater strategic weight. Companies that understand the rationale behind these moves can plan more effectively for procurement timing, contract structure, and product substitution assessments.
Regulatory Alignment, Certification, and the Rise of Lower-Carbon Medical Materials
The medical PVA market does not evolve in a vacuum. It is shaped by pharmacopoeial expectations, application-specific acceptance criteria, and an increasingly important emphasis on traceability and sustainability in medical material supply chains.
Compliance readiness is a meaningful enabler of adoption. For example, GOHSENOL™ EG series polyvinyl alcohol is documented to meet European Pharmacopoeia, United States Pharmacopoeia, and Japanese Pharmaceutical Excipients standards for medical use, reinforcing the role of standardized pharmaceutical-grade materials in formulation confidence and market access. At the same time, supportive policy and research activity is helping expand the long-term relevance of PVA-based systems. The Japanese Ministry of Economy, Trade, and Industry has supported research into PVOH hydrogels for ophthalmic and regenerative medicine applications, pointing toward nearer-term process development and longer-term application expansion.
Sustainability credentials are also entering the purchasing conversation more directly. Sekisui Specialty Chemicals secured ISCC PLUS certification for Selvol polyvinyl alcohol, enabling lower-carbon traceable medical-grade materials globally. In an environment where healthcare and pharmaceutical customers increasingly scrutinize supply chain footprint alongside performance, such certifications can become a visible differentiator in evaluation processes, especially where multiple technically suitable grades are available.
Together, these developments illustrate that market success in medical PVA is increasingly multi-dimensional. Technical performance remains essential, but regulatory alignment, documentation quality, and sustainability positioning are now part of the competitive equation.
Worldwide Polyvinyl Alcohol Market
Where Strategic Attention Should Focus in 2026
As organizations plan for the remainder of the decade, several strategic questions rise to the surface. How should procurement teams balance price visibility with supply continuity in a market where leading suppliers are actively adjusting pricing? How should R&D and formulation teams evaluate PVA grades against application-specific requirements when regulatory standards and customer expectations are tightening? How should commercial teams assess regional opportunities when growth is distributed unevenly across markets and applications?
Addressing these questions requires more than a single market figure. It requires a structured view of demand by application context, an understanding of type differentiation, awareness of regional market structure, and a realistic read of competitive behavior. It also requires the discipline to recognize where general trends end and company- or segment-level choices begin.
That is why this research is built to support scenario-based planning. Executives can use it to test procurement strategies against price movement, evaluate market-entry logic against competitive concentration, and align product development priorities with demand patterns that are likely to persist through the forecast period. In a market growing at a steady but not spectacular pace, the winners are often the organizations that make fewer assumptions and more informed trade-offs.
Why PW Consulting’s Market Research Is Designed for Action
This report is not intended as a passive reference document. It is intended to help teams make better decisions faster. By combining historical performance, forecast structure, segmentation logic, competitive context, and recent industry events, the study creates a single integrated frame for evaluating the medical PVA market.
The value lies in the connections. The report links market size evolution to the forces shaping it. It connects product types and application areas to the commercial realities behind them. It places company actions within the broader dynamics of feedstock costs, compliance expectations, and supply-side economics. Most importantly, it is designed to reduce ambiguity at the moment when strategic choices must be made.
For teams responsible for pharmaceutical sourcing, medical materials strategy, product planning, or regional market development, this level of detail is essential. It offers a credible basis for internal discussion and a reliable foundation for decision-making that can withstand scrutiny from finance, R&D, quality, and supply chain stakeholders.
Next Steps: Access the Full Strategic Picture
The insights outlined here provide a high-level view of why the Polyvinyl Alcohol in Medical market deserves focused attention in 2026 and beyond. But the real strategic value lies beneath the summary layer: in the segmented structure, the detailed competitive context, the regional and application patterns, and the interpretive analysis that ties market movement to execution choices.
To support rigorous planning, PW Consulting’s full report delivers the complete dataset, the deeper segmentation view, and the applied analysis needed to turn market intelligence into business strategy. If your organization is evaluating procurement timing, product-grade selection, market-entry logic, or competitive positioning in medical-grade PVA, the full research is built to help you move from awareness to action with confidence.
For the complete forecast structure, segmentation detail, company profiles, and strategic interpretation, explore the full Polyvinyl Alcohol in Medical market research from PW Consulting.
For detailed analysis of this topic, please visit the official page: Polyvinyl Alcohol in Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Civil Helicopter MRO Market Hits $9.7B in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: The Civil Helicopter MRO Market Outlook 2026–2032
The civil helicopter maintenance, repair, and overhaul (MRO) sector stands at a pivotal inflection point as we move into 2026. Driven by accelerating fleet utilization rates, evolving regulatory frameworks, and sustained investment in rotorcraft modernization, the market has transitioned from a post-pandemic recovery phase into a period of structured, high-velocity growth. For executives, investors, and operational leaders across the aviation value chain, understanding the trajectory of this market is no longer optional. It is a strategic imperative.
This analysis serves as a strategic preview to PW Consulting's newly released Civil Helicopter MRO Market Research Report , a comprehensive intelligence asset designed to equip decision-makers with the granular insights, competitive mapping, and forward-looking projections necessary to navigate the next seven years of industry evolution. The following overview highlights the macro-scale dynamics, competitive realities, and regulatory currents shaping the landscape, while demonstrating why this research has become an essential tool for institutional strategy in 2026 and beyond.
Market Trajectory: Sustained Expansion Anchored in Historical Momentum
The civil helicopter MRO market has demonstrated remarkable resilience and consistent upward momentum over the past half-decade. Drawing on a robust historical dataset spanning 2020 through 2025, the sector has recorded steady year-over-year revenue expansion, culminating in a baseline valuation of approximately $9.7 billion in the most recent full-year cycle. This trajectory reflects not only the restoration of civil aviation activity but also the deepening integration of helicopter assets into critical infrastructure: emergency medical services, offshore energy support, law enforcement, and an expanding array of commercial passenger and cargo logistics networks.
Forecasting models projecting through 2032 indicate that this growth will not merely continue but accelerate in structural complexity. The market is anticipated to surpass the $10.2 billion threshold in 2026, with compound annual growth rates stabilizing at approximately 6.5 percent over the forecast horizon. By the close of the projection window in 2032, total market valuation is projected to approach the $15 billion mark. This sustained expansion is underpinned by several converging forces: the aging of incumbent rotorcraft fleets that demands increasingly intensive heavy maintenance cycles, the modernization of avionics and propulsion systems that introduces new service categories, and the geographical diversification of civil helicopter operations into emerging markets where aerial mobility solutions are gaining institutional adoption.
For corporate strategists, these figures represent more than macroeconomic indicators. They signal a market in which capacity planning, service-line prioritization, and regional footprint decisions will yield disproportionate competitive advantages. Organizations that align their MRO investments with the cadence of fleet age profiles and regulatory timelines will be positioned to capture disproportionate shares of high-margin maintenance cycles, while those that rely on backward-looking utilization models risk strategic misalignment.
Structural Segmentation: Where Value Is Created and Captured
The civil helicopter MRO ecosystem is not a monolith. It is a layered constellation of service categories, each with distinct demand drivers, technical requirements, and margin profiles. Market intelligence reveals that airframe heavy maintenance continues to command the largest share of industry revenue, reflecting the capital-intensive nature of structural inspections, corrosion mitigation, and comprehensive rotorcraft airframe overhauls. Engine maintenance constitutes the second-largest pillar of the market, driven by the operational imperative to sustain powerplant reliability and the growing trend of engine life-extension programs that defer prohibitive replacement costs. Component maintenance, encompassing dynamic systems, avionics, transmissions, and rotor assemblies, represents a rapidly evolving segment where precision engineering and digital diagnostics are increasingly reshaping service delivery models.
Alongside these technical divisions, the application landscape reveals a pronounced tilt toward commercial operations, which account for the dominant portion of MRO spending across the civil rotorcraft sector. Private and corporate helicopter fleets contribute a substantial secondary stream of demand, characterized by more customized service requirements, shorter turnaround expectations, and a higher willingness to invest in premium maintenance packages that preserve asset values and operational flexibility. Understanding the interplay between these service lines and application categories is critical for firms evaluating capacity allocation, pricing architecture, and partnership strategies.
The regional distribution of MRO activity further underscores the importance of geographically informed strategy. North America remains a foundational market, anchored by dense fleets, mature regulatory environments, and a robust network of certified repair stations. Europe follows as a structurally significant region, supported by stringent EASA compliance frameworks and a growing emphasis on cross-border rotorcraft operations. Asia Pacific represents an increasingly dynamic frontier, where expanding public safety mandates, resource-sector helicopter demand, and emerging commercial rotorcraft programs are catalyzing new MRO investments. Latin America and the Middle East and Africa, while currently smaller in aggregate scale, are experiencing targeted growth driven by energy-sector operations, crisis-response capabilities, and localized fleet modernization initiatives.
Military Helicopter MRO Market
A complete picture of these segmentation dynamics, however, requires more than high-level categorizations. It demands detailed breakdowns of demand elasticity, service-cycle durations, regional certification pathways, and the margin implications of each maintenance modality. This is precisely the level of granularity embedded within the full research deliverable.
Competitive Landscape: OEM Dominance, Independent Agility, and Strategic Differentiation
The civil helicopter MRO market is characterized by a moderately concentrated competitive environment, where a handful of large-scale players command meaningful market share while a diverse field of specialized independents competes on technical agility, regional proximity, and niche service capabilities. Market concentration metrics indicate that the top three participants collectively control roughly 38 percent of industry revenue, while the top five extend their combined footprint to approximately 48 percent. This structure suggests a market that rewards both scale efficiencies and specialized differentiation, with room for agile entrants to secure sustainable positions through certified capabilities, strategic partnerships, and targeted service expansions.
At the OEM tier, Airbus Helicopters maintains a formidable presence through its integrated HCare service portfolio, which spans heavy maintenance, dynamic component repair, blade restoration, avionics upgrades, and continuing airworthiness management organization (CAMO) support. Operating across more than thirty sites and ninety-three MRO centers globally, the OEM leverages its manufacturing heritage, proprietary technical data, and expansive service network to anchor long-term fleet support relationships. Its recent emphasis on preserving MRO expertise amid digital transformation signals a strategic recognition that technological modernization must be paired with the retention of high-caliber engineering and maintenance talent.
Within the independent MRO segment, several firms have established strong reputations for operational excellence and regulatory compliance. StandardAero and Heli-One, both Canadian-based specialists, deliver comprehensive airframe maintenance, repair, overhaul, and component support services for civil and commercial rotorcraft fleets worldwide. Their scale, technical certifications, and global service footprints position them as critical capacity providers for operators seeking independent, cost-competitive alternatives to OEM channels. Rotortrade, headquartered in Atlanta, has emerged as a highly adaptive independent provider, combining full-service maintenance, CAMO oversight, and FAA Part 145 certification with avionics integration capabilities, including its recognized dealership status with Garmin. Eurotech, based in Italy, operates as an EASA Part 145 certified MRO center delivering comprehensive maintenance and overhaul services for civil rotorcraft, while Saudia Technic, anchored in Riyadh, has expanded its capabilities to encompass comprehensive helicopter maintenance and overhaul services for civil and commercial aircraft, reflecting broader regional investment in aviation infrastructure.
The competitive landscape is not static. Recent developments illustrate how targeted investments and regulatory certifications are reshaping service capabilities in real time. In late 2025, Rotortrade officially launched its U.S. MRO facility, securing full FAA Part 145 certification and enabling return-to-service approvals for FAA-regulated rotorcraft—a move that materially expands its domestic service reach. The following year, in early 2026, the company's Latrobe facility was appointed an official Garmin dealership, broadening its certified avionics integration capabilities under existing FAA approvals. These developments highlight a broader industry pattern: independents are increasingly differentiating through specialized certifications, strategic technology partnerships, and facility expansions that align with regional regulatory frameworks and operator demand.
Simultaneously, the inaugural Vertical MRO Conference, held in Kelowna, British Columbia, drew over five hundred rotorcraft MRO professionals for education sessions and industry exhibitions, underscoring the growing institutional focus on knowledge exchange, technical standards, and cross-company collaboration within the rotorcraft maintenance community. For market participants, these gatherings are more than networking events; they are barometers of emerging best practices, supplier relationships, and regulatory expectations that will shape competitive dynamics in the years ahead.
Regulatory Dynamics and Industry Currents: The Compliance-Led Evolution of MRO Strategy
Regulatory evolution is one of the most powerful forces reshaping the civil helicopter MRO market. In the United States, the FAA Modernization of Special Airworthiness Certification (MOSAIC) final rule, published in mid-2025, introduced a series of phased compliance milestones that directly affect pilot training, maintenance rules, and the regulatory classification of certain aircraft categories. The staggered effective dates—spanning pilot training and maintenance rule updates in late 2025 through the removal of the light-sport aircraft definition from federal aviation regulations in mid-2026—require MRO providers and fleet operators to adapt their compliance frameworks, training pipelines, and service protocols with precision and foresight.
Parallel regulatory developments have reinforced the importance of structured safety management. U.S.-registered Part 145 repair stations that also hold EASA Part 145 certification were required to implement formal safety management systems by the end of 2025, aligning North American and European maintenance standards with increasingly rigorous risk-management expectations. More recently, the FAA has emphasized a long-term industry goal of achieving zero fatal civil helicopter accidents, publishing enhanced guidance that includes updated Airman Certification Standards for rotorcraft-helicopter series, replacing older practical test standards with more rigorous competency frameworks. These regulatory currents do not merely impose compliance obligations; they reshape the competitive landscape by rewarding organizations that invest early in proactive safety cultures, standardized training, and digitally enabled compliance tracking.
Beyond regulation, the market is responding to broader operational and technological currents. Eurotech's certification by Robinson Helicopter Company as an Authorized Robinson Helicopter Dealer for 2026 exemplifies how manufacturer-aligned authorizations are becoming strategic differentiators, validating MRO providers' adherence to specific technical standards and unlocking access to dedicated service ecosystems. Meanwhile, advances in predictive maintenance analytics, digital airworthiness documentation, and component lifecycle tracking are gradually transforming traditional MRO workflows from reactive repair models into data-informed service architectures. Organizations that integrate these capabilities into their operational models will be better positioned to reduce turnaround times, optimize parts inventory, and deliver the transparency that modern operators increasingly demand.
The Strategic Value of Comprehensive Market Intelligence in 2026
For enterprises operating in or adjacent to the civil helicopter MRO ecosystem, the complexity of the market environment in 2026 demands more than generalized industry awareness. It requires a structured, evidence-based intelligence foundation that integrates historical performance data, forward-looking projections, segmentation analysis, competitive profiling, and regulatory foresight into a single, coherent decision-support framework.
Civil Helicopter MRO Market
PW Consulting's Civil Helicopter MRO Market Research Report has been designed to meet this need. The study draws upon extensive primary and secondary research to deliver a multi-dimensional view of the market across its full forecast horizon. It provides detailed analysis of revenue trajectories, service-line dynamics, regional demand patterns, and the strategic moves of key market participants, enabling readers to benchmark their positioning, identify whitespace opportunities, and anticipate shifts in competitive intensity. The report also examines the practical implications of regulatory changes, technological adoption curves, and fleet lifecycle dynamics, translating high-level trends into actionable strategic considerations for capacity planning, partnership evaluation, and market-entry or expansion decisions.
Importantly, the intelligence contained within this research is structured to support a range of operational and strategic functions. For MRO service providers, the analysis offers a basis for calibrating investment in facility capacity, certification pathways, and specialized service lines. For OEMs and component manufacturers, it illuminates downstream demand patterns and the service-interface opportunities that accompany fleet modernization. For financial stakeholders and investors, it provides a disciplined framework for evaluating growth trajectories, margin drivers, and the competitive vulnerabilities that may influence long-term returns. For fleet operators and aviation authorities, it delivers context on service availability, regulatory alignment, and the evolving standards that shape procurement and compliance strategies.
Navigating the Next Seven Years with Confidence
The civil helicopter MRO market is entering a phase defined by sustained growth, regulatory refinement, and intensifying competitive differentiation. The macroeconomic trajectory is clear: revenue expansion will continue at a robust pace, fleet age profiles will drive increasing demand for heavy maintenance and component overhaul, and regional demand centers will continue to diversify as rotorcraft operations expand into new operational contexts. Yet the precise allocation of opportunity across service categories, geographic zones, and competitive tiers remains a question that can only be answered through detailed, research-backed analysis.
In an environment where strategic agility depends on accurate foresight, access to comprehensive market intelligence is not merely an informational advantage—it is a foundational element of operational resilience and growth planning. The full Civil Helicopter MRO Market Research Report provides the depth, structure, and analytical rigor required to make informed decisions with confidence. Readers seeking the complete segmentation breakdowns, detailed company profiles, regional demand mappings, and forward-looking scenario analysis are encouraged to access the full report through the source webpage, where the complete intelligence suite is available for institutional review and strategic application.
For detailed analysis of this topic, please visit the official page: Civil Helicopter MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: B2B E-commerce Sales Hit $32.11T in 2025, Surge to $70T by 2032 at 16.64% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the B2B E-commerce Era: Navigating the 2026 Market Landscape
The business-to-business e-commerce sector has evolved from a transactional convenience into a strategic imperative for enterprises seeking scalable, data-driven procurement and sales ecosystems. As organizations confront shifting supply chain architectures, rising digital expectations, and complex regulatory environments, decision-makers require more than surface-level market summaries. They need precise, actionable intelligence that maps technological adoption patterns, competitive positioning, and structural growth trajectories. Our latest B2B E-commerce Market study delivers exactly that: a rigorously validated analysis designed to inform capital allocation, platform selection, and long-term commercial strategy across 2026 and beyond.
This market research does not merely track headline figures. It decodes the operational and structural forces driving commercial transformation, offering executives a clear lens through which to evaluate platform investments, partnership opportunities, and market entry strategies. By synthesizing historical performance with forward-looking projections, the report equips procurement leaders, IT architects, and revenue operations teams with the clarity needed to navigate an increasingly fragmented and fast-moving commercial landscape.
A Trajectory of Sustained Expansion: Market Scale and Context
The B2B e-commerce market has demonstrated remarkable resilience and growth momentum over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward curve, reflecting accelerated digital adoption across manufacturing, wholesale distribution, and enterprise services. This trajectory has positioned the sector at a pivotal inflection point as it moves into the 2026-2032 forecast window. The projected compound annual growth rate underscores a market that is not simply recovering from post-pandemic digitization, but actively restructuring how businesses discover, evaluate, and purchase commercial goods and services.
Our analysis captures the full arc of this expansion, tracking how foundational adoption phases have given way to more sophisticated commercial architectures. Enterprises are no longer treating B2B e-commerce as an isolated sales channel. Instead, they are embedding digital procurement and wholesale ordering into broader operational frameworks, demanding platforms that can handle complex pricing structures, multi-tier account management, and integrated financial workflows. The report contextualizes these shifts within broader macroeconomic and technological trends, providing decision-makers with a grounded understanding of why growth is accelerating and where it is likely to concentrate.
What the Report Delivers: Actionable Intelligence for Executives
Market intelligence only creates value when it translates into executable strategy. This study is structured to bridge the gap between high-level market observation and on-the-ground operational planning. The report provides a comprehensive mapping of platform capabilities, procurement workflow requirements, and technological integration patterns that define modern B2B commercial environments. Readers will find detailed examinations of how leading solutions address order complexity, custom quoting, inventory synchronization, and account hierarchy management, along with practical guidance on evaluating platform fit against organizational scale and industry-specific procurement models.
- Platform evaluation frameworks that align technical architecture with commercial objectives, including headless and composable deployment models
- Workflow optimization insights covering purchase order automation, approval routing, and self-service buyer portals
- Integration readiness assessments that examine ERP connectivity, quote-to-cash processes, and cross-channel inventory visibility
- Adoption roadmaps that differentiate between rapid-deployment solutions and enterprise-grade customization requirements
- Risk and compliance considerations tied to data governance, pricing transparency, and multi-region operational constraints
Beyond platform comparisons, the report dissects the structural dynamics influencing buyer behavior and seller readiness. It examines how procurement teams are redefining vendor selection criteria, how wholesalers and distributors are balancing digital self-service with relationship-driven sales, and how technological investments are reshaping margin structures and order fulfillment timelines. Every section is designed to support concrete decision-making, whether the objective is platform migration, market expansion, or competitive repositioning.
Competitive Dynamics and Platform Evolution
The B2B e-commerce platform landscape is defined by a concentrated yet highly differentiated group of technology providers. Market concentration metrics indicate that a small cohort of dominant players controls a substantial share of enterprise deployments, yet the competitive environment remains intensely active as vendors race to capture specialized use cases and regional demand. Leading platforms have moved beyond generic storefront functionality, investing heavily in features that address the unique friction points of business procurement: tiered pricing, negotiated contracts, multi-purchaser account structures, and seamless financial reconciliation.
Shopify has expanded its B2B capabilities to support unified commerce operations, offering manufacturers, wholesalers, and distributors self-serve purchasing, volume-based pricing, and structured account management. BigCommerce has positioned its B2B Edition around headless and composable architectures, emphasizing corporate account management, advanced pricing logic, purchase order automation, and approval workflows tailored to wholesale and distribution operations. Adobe Commerce provides an optimization suite built for large enterprises, featuring personalized catalogs, hierarchical buyer accounts, multi-purchaser roles, and self-service portals that accommodate complex organizational buying structures.
commercetools has pursued a composable approach with pre-built solutions for manufacturing environments and custom purchasing journeys, leveraging API-first flexibility to support enterprise B2B sales at scale. Oracle NetSuite Commerce integrates its B2B offering directly with ERP systems, enabling business buyer sites, quote requests, account management, and invoice payment workflows within a unified financial ecosystem. OroCommerce targets distributors, wholesalers, and manufacturers with enterprise-grade functionality that supports custom pricing, high-SKU catalogs, and multi-model licensing spanning B2B, B2C, and B2B2X scenarios. NuORDER, operating under Lightspeed, delivers a closed-loop wholesale platform that connects brands and retailers through POS and e-commerce integration, real-time inventory visibility, and automated ordering. Shopware rounds out the competitive field with B2B components designed for customized commerce platforms, supporting complex workflows, B2B and direct-to-consumer unification, and automated business processes for distributors and manufacturers.
The competitive environment has also been shaped by recent strategic developments that signal where the market is heading. In mid-2026, Shopware partnered with Smart Solutions to deliver compliance, strategy, and seamless B2B/B2C e-commerce solutions for complex business models, reflecting a broader industry push toward integrated consulting and technology delivery. Earlier that year, Shopware released its B2B Ecommerce Compass 2026 whitepaper and hosted the B2B Future Forum, highlighting automation pressures and the challenges of managing complex system landscapes. In late 2025, Go Autonomous introduced Execution Fabric, an autonomous execution layer designed to unify B2B commerce channels across sales and procurement processes. Around the same period, PROS and Commerce announced a strategic partnership combining AI-powered pricing and quoting with BigCommerce's B2B digital commerce platform to accelerate intelligent B2B transactions. These developments illustrate how platform providers are responding to demand for greater automation, pricing intelligence, and cross-functional integration.
Macro Forces and Infrastructure Realities Shaping Commercial Strategy
B2B e-commerce does not operate in a vacuum. Platform decisions, deployment architectures, and growth expectations are increasingly influenced by infrastructure constraints, regulatory shifts, and operational cost dynamics. Decision-makers evaluating digital commerce investments must account for the broader environment in which these systems will run, particularly as workload intensity, data residency requirements, and integration complexity continue to rise.
B2B Debt Collection Services Market
Infrastructure cost considerations have become a central factor in platform and hosting strategy. Comparisons between colocation and public cloud environments for steady-state B2B e-commerce workloads reveal that colocation can offer meaningful total cost advantages once sustained utilization clears certain utilization thresholds. At the same time, power constraints are affecting data center expansion timelines, with a significant share of new projects facing delays as electricity availability becomes a binding constraint. These realities are prompting enterprises to reassess where and how commerce workloads are deployed, balancing performance, latency, and long-term cost predictability against flexibility and scalability expectations.
Regulatory and policy environments are also evolving in ways that affect digital commerce infrastructure and wholesale connectivity. Shifts in broadband program policy, including moves toward technology-neutral competition and open access models for wholesale providers, are reshaping how multi-service connectivity is delivered and monetized. As standardized marketplace models gain traction among major communications providers, the underlying connectivity landscape is becoming more modular and competitive. For B2B e-commerce operators, these changes influence site performance expectations, multi-region deployment strategies, and the feasibility of tightly integrated supply chain and procurement networks.
These macro forces are not abstract background conditions. They directly affect platform selection, hosting commitments, integration timelines, and the economics of scaling digital commerce operations. The report situates these dynamics within the broader market narrative, helping executives anticipate operational risks and align technology decisions with realistic infrastructure and regulatory trajectories.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a clear-eyed assessment of where B2B e-commerce is heading and what it will take to compete effectively. Organizations that treat digital procurement and wholesale commerce as strategic capabilities rather than tactical sales channels will be better positioned to manage complexity, protect margins, and accelerate buyer onboarding. This study provides the analytical foundation needed to make those judgments with confidence.
By combining validated market sizing, structural segmentation insights, competitive profiling, and infrastructure-aware context, the report enables executives to evaluate platform investments, partnership strategies, and operational roadmaps against a realistic view of market momentum. The analysis is designed to support a range of decision contexts, from enterprise platform migrations and distributor network modernization to new market entry and pricing architecture redesign. Rather than offering generic recommendations, it delivers the kind of granular, scenario-aware intelligence that procurement, IT, and commercial leadership teams can apply directly to their planning processes.
Market growth at this scale is never uniform. It is shaped by adoption readiness, technological maturity, regulatory conditions, and the competitive intensity of the platform ecosystem. Understanding those layers is essential for avoiding costly missteps and capturing the opportunities that come with digital commerce transformation. This research gives decision-makers the clarity to separate short-term noise from long-term structural shifts, ensuring that 2026 investments are aligned with where the market is actually moving.
Next Steps: Turning Insight into Execution
Comprehensive market intelligence is only as valuable as its application. Organizations ready to move from awareness to action will find this report structured to support that transition, with practical evaluation criteria, competitive context, and forward-looking market mapping that can be integrated into existing strategic planning workflows. The full study provides the depth required to validate assumptions, benchmark platform options, and strengthen commercial decision-making across the enterprise.
For executives and strategy teams seeking a complete picture of B2B e-commerce market dynamics, platform positioning, and operational implications, the full report offers the detailed data and analysis necessary to guide confident, evidence-based decisions. Accessing the complete intelligence will provide the specificity needed to translate market momentum into measurable strategic advantage throughout 2026 and the forecast period ahead.
Business-to-Business (B2B) E-commerce Market
For detailed analysis of this topic, please visit the official page: Business-to-Business (B2B) E-commerce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Products Market to Hit $66.2M by 2032, Reflecting 4.7% CAGR Amid Regional Shifts
By PW Consulting, 2026-09-16
Strategic Intelligence for Blood Products Leaders: Navigating the 2026 Market Landscape
Executive Overview
The global blood products market is entering a critical inflection point. With historical momentum carrying the industry from 38.15 billion USD in 2020 to an estimated 48.0 billion USD in 2025, and a projected trajectory toward 66.2 billion USD by 2032, the sector is poised for sustained, measured expansion. Our newly released research framework dissects this evolution with precision, delivering the analytical depth required for enterprise-level strategy, capital allocation, and competitive positioning in the coming cycle.
For executives, investors, and operational leaders, the years ahead will not be defined by simple top-line growth. Instead, success will hinge on understanding structural shifts in donor economics, reimbursement architectures, regulatory cadence, and manufacturing capacity deployment. This report is engineered to translate macro trends into actionable intelligence, allowing decision-makers to stress-test strategies against realistic demand scenarios, supply constraints, and competitive maneuvering.
The 2026–2032 Trajectory: A Market Built on Stable Demand, Shaped by Execution
The forecast window reflects a compound annual growth rate of 4.7 percent, a figure that signals resilience rather than volatility. Demand fundamentals remain anchored in clinical necessity: surgical interventions, trauma response, oncology protocols, and chronic hematologic management continue to drive consistent consumption. Yet growth is no longer a passive outcome of population aging or procedural volume alone. It is increasingly contingent on operational efficiency, fractionation throughput, cold-chain integrity, and the ability to scale plasma-derived therapies without compromising quality or compliance.
Notably, the projection curve does not follow a linear stretch. The data anticipates a period of consolidation and recalibration, where capacity investments, regulatory approvals, and donor recruitment dynamics will differentiate high-performing players from those merely riding baseline demand. Companies that align manufacturing footprints, collection networks, and product portfolios with regional healthcare financing models will capture disproportionate value. Those that rely solely on historical utilization patterns will face margin compression, supply bottlenecks, or competitive displacement.
Our analysis maps these inflection points across the full forecast horizon, isolating the operational levers that determine whether volume growth translates into sustainable profitability. The report does not stop at aggregate figures; it examines how pricing structures, procurement consolidation, and clinical adoption pathways interact to shape realizable revenue in each phase of the cycle.
Decoding the Competitive Arena: Integrated Networks, Specialized Technologies, and Strategic Capacity Plays
The competitive landscape is defined by a mix of vertically integrated plasma manufacturers, specialized technology providers, and large-scale blood services organizations. Each group occupies a distinct strategic position, and the dynamics between them are shifting as capacity investments accelerate and pathogen reduction technologies gain broader clinical adoption.
Grifols and CSL Behring continue to anchor the upper tier of plasma-derived therapies, leveraging vertically integrated collection and fractionation networks to supply hematology, critical care, and rare disease portfolios. Their scale advantages are counterbalanced by the operational complexity of maintaining donor throughput, fractionation yield, and regulatory compliance across multiple jurisdictions. Terumo Blood and Cell Technologies, meanwhile, operates at the intersection of automation and component production, providing apheresis platforms, processing systems, and storage technologies that influence how blood centers and hospitals manage collection efficiency and product consistency.
On the services and distribution side, Vitalant exemplifies the large-scale U.S. blood services model, delivering whole blood, platelets, plasma, cryoprecipitate, and specialty products across hospital networks. Its operational footprint highlights the importance of regional supply resilience, donor engagement, and logistics optimization in a market where inventory management and shelf-life constraints remain perennial challenges.
Specialized technology and plasma-focused players add another layer of strategic complexity. Cerus Corporation’s pathogen reduction systems address a persistent vulnerability in transfusion medicine, inactivating viruses and bacteria in platelets and plasma to enhance safety margins. Octapharma, Biotest, and Kedrion Biopharma each emphasize plasma-derived medicines and collection infrastructure, with product portfolios spanning coagulation factors, immunoglobulins, and therapies for rare and chronic conditions. Their strategies illustrate a broader industry pattern: differentiation is increasingly achieved through specialized protein fractionation, targeted disease areas, and ownership or control of collection assets.
Recent corporate activity reinforces the strategic stakes. Kedrion Biopharma’s allocation of substantial investment to expand production capacity in Italy signals confidence in regional plasma throughput and fractionation scale. Grifols has moved forward with new manufacturing construction in Spain, reinforcing its commitment toEuropean capacity and supply continuity. Cerus Corporation’s multi-year supply agreement with a major French blood establishment underscores the commercial traction of pathogen reduction platforms in institutional procurement. Additionally, the 2026 International Plasma Protein Congress, held with record participation, reflects intensifying industry focus on plasma protein therapeutics, regulatory alignment, and cross-border supply coordination. Together, these developments illustrate a market where capacity, safety technology, and institutional partnerships are converging as decisive competitive variables.
Operational Realities That Shape Margins: Donor Economics, Reimbursement, and Regulatory Discipline
Behind every market projection lies a set of operational realities that determine whether growth is profitable, sustainable, and defensible. Donor economics remain one of the most consequential cost drivers. In the United States and select markets, donor compensation commonly falls within a range of 50 to 100 USD per visit, and collection-related expenses can represent more than half of finished plasma-derived product costs. This structure means that collection efficiency, donor retention, center utilization, and labor deployment are not back-office concerns; they are direct determinants of cost of goods and margin resilience.
At the same time, hospital reimbursement models introduce a distinct pricing dynamic. Many healthcare systems operate under fixed bundled reimbursement rates for patient care episodes, which encompass blood products as part of hospitalization without separate product-level billing. This architecture compresses direct price visibility for manufacturers and distributors, while shifting commercial emphasis toward reliability, quality assurance, inventory availability, and total cost-of-care efficiency. For suppliers, the implication is clear: competitive advantage arises from demonstrating consistent supply, minimizing waste, and aligning product offerings with clinical pathways rather than pursuing isolated list-price leverage.
Regulatory oversight adds another layer of discipline. Blood establishments are required to register and list products under FDA frameworks, with inspections occurring at least every two years to verify compliance with collection, testing, and processing standards. Updated clinical usage guidance, such as revisions to red blood cell preparation and component handling specifications, further shapes how products are manufactured, stored, and deployed. These requirements elevate the importance of quality systems, audit readiness, and documentation rigor. In practice, they reward organizations that embed compliance into operational design rather than treating it as a periodic checkpoint.
Labor intensity compounds these factors. Plasma collection networks rely on large workforce deployments across hundreds of centers to sustain high-frequency donor operations and fractionation throughput. The operational implication is twofold: scaling capacity requires careful workforce planning, training, and center-level productivity management, while disruptions in staffing or donor availability can quickly propagate into fractionation schedules and supply continuity. The companies that manage these variables most effectively will be best positioned to convert demand into revenue without eroding margins.
Blood Plasma Derivatives Market
What’s Inside the Research: Practical Intelligence for Strategy and Execution
This report is designed as an operational companion for executive decision-making, not a static market snapshot. It integrates demand trajectories, competitive positioning, regulatory context, and cost-structure dynamics into a coherent strategic framework. The analysis spans the forecast period from 2026 through 2032 and is anchored in a historical baseline that captures the market’s evolution from 2020 to 2025.
The research delivers detailed segmentation intelligence across product categories, application areas, and regional demand patterns, allowing readers to identify where growth concentrates, where throughput constraints emerge, and where procurement behavior differs by healthcare system. It examines product-level demand drivers, including red blood cell utilization in trauma and surgical care, platelet requirements in supportive treatment protocols, and the broader category of specialty and plasma-derived components. It also maps application-level consumption patterns across trauma and surgery, cancer treatment, and blood disorders, linking clinical utilization to supply planning and commercial strategy.
Beyond volume and segmentation, the report provides actionable competitive analysis. It evaluates the strategic posture of leading manufacturers, plasma collection organizations, technology suppliers, and blood services providers, highlighting how vertical integration, automation, pathogen reduction, and capacity expansion shape market positioning. The competitive framework is paired with recent corporate developments, regulatory milestones, and industry gathering activity to show how strategic intent is translating into infrastructure investment, supply agreements, and institutional partnerships.
A distinct emphasis is placed on operational economics and market mechanics. The analysis addresses donor compensation structures, collection cost weight within finished product economics, hospital reimbursement architecture, regulatory inspection cadence, and the labor footprint required to sustain high-frequency plasma collection and fractionation. These factors are integrated into a broader assessment of margin sensitivity, supply resilience, and procurement behavior, enabling readers to evaluate not just where the market is going, but how value is created and defended along the way.
Blood Products Market
To support practical decision-making, the report also includes scenario-based interpretation tools that help leadership teams test strategic assumptions against changing demand intensity, capacity deployment timelines, and competitive response patterns. The goal is to provide clarity on priorities: where to invest, where to optimize, where to partner, and where to differentiate.
Why This Report Matters for 2026 Decision-Making
The 2026 decision environment demands more than high-level forecasts. It requires an understanding of how donor economics, reimbursement models, regulatory oversight, and capacity investments interact to shape competitive outcomes. It requires clarity on which product and application segments will absorb incremental demand, which regions will see the most pronounced shifts in procurement behavior, and which strategic moves will separate market leaders from followers.
This research is built for that purpose. It provides the structural insight needed to align product strategy, supply chain planning, and commercial positioning with realistic market conditions. It helps organizations anticipate where margin pressure may emerge, where safety technology and compliance rigor will influence purchasing decisions, and where capacity expansion will alter supply dynamics. It also serves as a reference point for investment evaluation, partnership assessment, and long-range planning in a market where execution quality increasingly determines returns.
The full report contains the detailed segmentation breakdowns, regional demand mapping, competitive profiles, operational cost analysis, and strategic scenario interpretation needed to convert market intelligence into concrete action. For teams responsible for portfolio strategy, operations, procurement, or investment planning, the complete dataset and interpretive framework are essential for building resilient 2026 and beyond strategies.
Explore the full research suite to access the complete segmentation intelligence, competitive landscape analysis, and operational dynamics assessment that underpin the findings outlined here.
For detailed analysis of this topic, please visit the official page: Blood Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Venting Membrane Market to Hit $1.46M by 2032, 4.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Industrial Venting Membrane Market: Strategic Intelligence for 2026 Decision-Makers
The industrial landscape in 2026 is defined by increasingly stringent performance requirements for enclosure protection, breathing capability, and contamination control. As equipment becomes more sophisticated and operating environments more volatile, the demand for reliable pressure compensation and moisture management solutions has accelerated. Industrial venting membranes have emerged as a critical enabler across sectors ranging from automotive and electronics to medical devices and chemical packaging. Understanding where this market is heading, which forces are shaping its trajectory, and how competitive dynamics are evolving is no longer optional for C-suite leaders, product development teams, and investment strategists.
For organizations making capital allocation, product roadmap, and supply chain decisions in 2026, access to granular, forward-looking intelligence is essential. Our newly published Industrial Venting Membrane Market research delivers exactly that: a structured, evidence-based view of market size, growth momentum, segmentation patterns, competitive positioning, and the regulatory and cost pressures that will define the next several years. This article provides a strategic preview of what the full report covers, why it matters for 2026 planning, and how decision-makers can translate these insights into actionable advantage.
Market Trajectory: What the Numbers Signal for 2026 and Beyond
The industrial venting membrane market has demonstrated a pattern of measured expansion, punctuated by periods of recalibration as end-use demand, raw material conditions, and regional adoption cycles interact. Historical data from 2020 through 2025 shows the market progressing from an estimated 0.84 million USD in 2020 to 1.06 million USD in 2025, reflecting a maturing but still growing supply-demand equilibrium. Into the forecast window of 2026 through 2032, the market is projected to continue its upward path, moving from an estimated 1.15 million USD in 2026 toward approximately 1.46 million USD by 2032, supported by a compound annual growth rate of 4.7 percent.
For strategists, the significance of this trajectory lies not only in the headline figures but in what they imply about momentum. A mid-single-digit CAGR in a specialized component market indicates steady, structural demand rather than speculative hype. The expansion from 2026 to 2032 suggests that adoption is widening across applications and geographies even as mature segments stabilize. Decision-makers should interpret this as a signal to prioritize long-term readiness: aligning product architectures with venting requirements, evaluating supplier partnerships that can scale with demand, and building regulatory compliance into design cycles before market expectations tighten further.
The full report unpacks these trends with a detailed year-by-year view, enabling readers to test assumptions about near-term demand, mid-period inflection points, and longer-term growth ceilings. Rather than relying on aggregated summaries, the analysis provides a clear temporal map of where growth is likely to concentrate and how external shocks—such as raw material price movements or regulatory shifts—could alter the pace of adoption.
Strategic Value of the Report for 2026 Enterprise Planning
Market intelligence becomes valuable only when it is directly usable. This research is designed to support multiple enterprise functions simultaneously. For product strategy teams, the report provides a structured breakdown of how venting membranes are categorized by type and applied across end-use sectors, helping teams map technical specifications to real-world demand patterns without getting lost in fragmented supplier claims. For supply chain and procurement leaders, the analysis illuminates the cost environment, including raw material dynamics that affect pricing strategies and sourcing decisions. For competitive intelligence and business development units, the report maps the participant landscape and highlights recent moves that signal where capacity, innovation, and regional focus are shifting.
Industrial Venting Membrane Market
The report also addresses the compliance dimension, which has become a decisive factor in many industrial purchasing decisions. Regulatory expectations around medical-grade applications and food-contact safety are shaping specification requirements and vendor qualification processes. By integrating these requirements into the market context, the research enables teams to anticipate qualification timelines, avoid specification mismatches, and structure product development in a way that aligns with evolving safety and performance standards.
Most importantly, the full report is built to support decision-making rather than merely describe the market. It identifies where concentration exists, where fragmentation creates opportunity, and how recent developments—such as capacity expansions and product introductions—may influence competitive intensity in specific segments. Readers can use these insights to prioritize markets, assess risk exposure, and prepare for shifts in supplier bargaining power or customer specification requirements.
Inside the Research: What the Full Report Delivers
The complete study is organized to move from macro context to operational detail, giving readers a comprehensive view while allowing them to focus on the areas most relevant to their role. The core components include:
- Historic market sizing and forecast data spanning 2020 to 2032, presented in a way that supports scenario planning and demand modeling for multiple operating assumptions.
- Segmentation analysis by region, type, and application, giving a structured picture of where usage concentrates and how different market slices are positioned relative to one another.
- Competitive landscape assessment covering leading participants, their areas of specialization, and the strategic implications of recent launches, facility investments, and product enhancements.
- Regulatory and compliance context relevant to industrial venting membranes, including considerations for medical applications, food packaging safety, and chemical packaging use, as well as the increasing importance of PFOA-free and APFO-free certifications.
- Raw material and cost environment observations, including recent pricing signals in key input markets that can affect margin planning and sourcing strategies.
- Market concentration data indicating the extent to which leading participants share the landscape, helping readers gauge competitive intensity and evaluate entry or expansion feasibility.
Each section is written with a practical lens. The segmentation analysis, for example, helps teams understand which product architectures and application contexts are driving adoption, while the competitive section supports supplier evaluation, partnership strategy, and benchmarking. The regulatory discussion is not treated as a side note; it is integrated into market dynamics so that compliance requirements can be evaluated alongside demand growth and cost pressures.
Readers who engage with the full report will also find recent developments mapped into the competitive narrative. These include capacity investments aimed at meeting demand in specific regional markets and product introductions designed to expand performance envelopes under demanding operating conditions. By placing such events in context, the research helps organizations interpret whether these moves are incremental or indicative of broader shifts in supply strategy and end-use focus.
Competitive Landscape: Leading Participants and Recent Moves
The industrial venting membrane market features a set of established participants with distinct technical emphases and geographic footprints. Several companies stand out for their focus on ePTFE and PTFE-based venting solutions, each bringing different strengths in adhesive formats, hydrophobic and oleophobic treatments, pressure compensation sealing, and integration with filtration or housing systems. GERGONNE, based in France, specializes in ePTFE adhesive venting membranes for industrial pressure compensation, moisture removal, and protection across automotive, electronics, and technical applications. Membrane Solutions LLC, headquartered in the United States, produces PTFE hydrophobic and oleophobic venting membranes used in industrial chemical packaging, electronics, and gas or vent filter housings. Porex Corporation, also U.S.-based, offers PTFE hydrophobic venting membranes and adhesive solutions for industrial enclosures, container venting, diagnostics, and medical applications. Schreiner Group, a German participant, develops waterproof venting membranes and pressure compensation seals for industrial housings, protecting against liquids and dirt while enabling air exchange.
Broader global players also shape the market. W. L. Gore & Associates, based in the United States, provides ePTFE membranes for industrial venting in automotive, electronics, and battery protection applications. Donaldson Company, Inc., another U.S. participant, supplies ePTFE membranes integrated into filtration and venting systems for industrial and off-highway applications. Saint-Gobain Performance Plastics, headquartered in France, offers advanced PTFE-based venting membranes for industrial packaging, chemical resistance, and pressure equalization. Nitto Denko Corporation, based in Japan, manufactures functional ePTFE venting membranes for industrial electronics, automotive, and process applications. Together, these participants illustrate the breadth of technical approaches and application coverage that characterize the competitive environment.
Recent developments underscore how actively the landscape is evolving. In mid-2026, a dedicated venting-membrane production line was inaugurated in Chennai, India, by Porvair Filtration Group, reflecting an expansion of capacity aimed at meeting demand for lightweight outdoor equipment venting solutions. Around the same time, GERGONNE introduced its VM16 ePTFE venting membrane with enhanced resistance to extreme hydrodynamic stresses and conditions. These moves are more than isolated news items; they signal where participants are placing bets on capacity, performance, and regional demand. For enterprises evaluating suppliers or planning product architectures, such developments provide early indicators of where supply flexibility, technical differentiation, and regional support may strengthen or weaken over the forecast period.
Market concentration data adds another layer to this picture. With a combined share held by the top three participants at approximately 25 percent and the top five at around 35 percent, the market remains relatively dispersed. This level of concentration suggests both opportunity and complexity. On one hand, no single player dominates to the point of constraining choice across all applications; on the other, competition is active enough that differentiation depends on technical performance, compliance readiness, and regional capability. The full report examines these dynamics in greater detail, helping readers interpret how concentration interacts with segment-specific demand and supplier specialization.
Market Dynamics: Regulation, Cost, and Shifting Demand Signals
Several forces are actively shaping how industrial venting membranes are specified, sourced, and priced in 2026. Regulation is one of the most consequential. For medical applications, venting membranes must align with expectations associated with ISO 13485, while food packaging safety considerations are governed by frameworks such as EU Regulation (EC) 1935/2004. These requirements influence material selection, certification pathways, and vendor qualification timelines. At the same time, chemical safety standards are becoming increasingly important across industrial packaging and enclosure applications. Membrane Solutions has emphasized APFO-free certification for its PTFE venting membranes used in industrial chemical packaging per EPA guidelines, and Porex has indicated that its Virtek PTFE membranes require PFOA-free certification to meet global chemical safety standards. Schreiner Group has incorporated oleophobic properties into its pressure compensation seals to meet industrial housing standards for liquid ingress prevention. Taken together, these compliance positions show that certification is no longer a background consideration; it is becoming a deciding factor in supplier selection and application design.
Cost dynamics also play a central role in strategic planning. Raw material conditions, particularly for PTFE, directly affect input economics and can influence pricing strategies, margin planning, and sourcing timing. Recent pricing signals have shown PTFE raw material prices in Northeast Asia at approximately 8.35 USD per kg, with a modest month-over-month increase. For procurement and product cost teams, such movements matter because they can shift the balance between alternative material choices, adhesive formats, and venting architectures. The research places these cost signals within the broader market context so that teams can assess whether pricing pressure is likely to be temporary, structural, or regionally uneven.
Demand-side dynamics continue to evolve as well. The application landscape spans electric and electronics, automotive, medical, chemical packaging, food and beverages packaging, and other uses, each with different performance priorities and compliance expectations. The type landscape includes adhesive venting formats and vent solutions without backing material, each serving different integration needs. Rather than treating these categories as isolated silos, the report evaluates how they interact with regional demand patterns and competitive positioning. This integrated approach helps readers see where specification requirements are converging, where cost sensitivity may shape adoption, and where performance differentiation will be most valuable.
PTFE Venting Membrane Market
Using the Research to Strengthen 2026 Decisions
The strategic value of this research lies in its ability to connect market structure with operational choice. For leaders planning product development, the segmentation and application analysis provides a basis for prioritizing venting requirements in next-generation designs. For procurement and sourcing teams, the combination of cost dynamics, compliance context, and competitive positioning supports more informed supplier evaluation and risk assessment. For business development and strategy teams, the concentration data and recent market moves offer a framework for evaluating entry points, partnership opportunities, and regional expansion priorities.
In a market where growth is steady but competitive intensity is real, the organizations that gain advantage will be those that act on precise, forward-looking information rather than on assumptions or fragmented inputs. The full report is built for that purpose: it provides the depth required to support decisions, while keeping the focus on implications rather than description alone.
For a complete view of market sizing, segmentation detail, competitive profiles, regulatory considerations, and the year-by-year forecast that underpins the 2026 to 2032 outlook, access the full Industrial Venting Membrane Market research. The complete study provides the data, analysis, and strategic context needed to translate market intelligence into confident decision-making throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Industrial Venting Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


