

Blogs
Worldwide Tandem Rolling Mill Market: Why 3.7% CAGR and Asia Pacific Shift Strategy
By PW Consulting, 2026-09-18
Strategic Trends & Commercial Opportunities in the Worldwide Tandem Rolling Mill Market
Market Snapshot: Scale, Structure, and Core Challenges
The global tandem rolling mill market has entered a phase of steady, structurally supported expansion. Measured in USD millions, the sector has grown from a baseline of roughly 590 million in 2020 to just over 714 million in 2025, and forward indicators point to a consistent climb through 2032. The implied compound annual growth rate sits at approximately 3.7 percent, reflecting a market that is maturing rather than exploding. This trajectory is neither a cyclical surge nor a speculative boom; it is the result of long-lived capital investments in metal processing infrastructure, where replacement cycles, capacity modernization, and incremental efficiency upgrades compound over time.
The market structure carries a distinctly concentrated character. A small cluster of global technology providers commands a majority share of high-value equipment sales, service contracts, and retrofit business. This concentration is not a barrier to entry so much as a reflection of the engineering complexity, process know-how, and after-sales ecosystem required to deliver mills that meet today's metallurgical specs. Customers are no longer purchasing standalone machinery; they are acquiring integrated process lines with embedded automation, flatness control, and energy management capabilities. As a result, the commercial value has shifted from hardware volume to performance assurance, uptime guarantees, and lifecycle optimization.
Three interlocking challenges define the current inflection point for operators, equipment builders, and investors.
- Raw material price volatility and margin pressure. Recent pricing data shows hot-rolled coil benchmarks in the U.S. Midwest reaching multi-quarter highs, while Northeast Asia spot prices have climbed on the back of automotive, shipbuilding, and construction demand. Elevated input costs compress downstream margins and force rolling mill operators to extract more throughput per unit of energy and labor. Mills that cannot deliver consistent gauge control, reduced rework, and faster line speeds face deteriorating economics, making modernization decisions less optional and more urgent.
- The precision-at-thinner-gauges dilemma. Demand for advanced high-strength steels, electrical steels, and specialty non-ferrous alloys is pushing processors toward tighter tolerances, thinner gauges, and more uniform property distribution. Traditional rolling configurations struggle to maintain shape, flatness, and thermal stability at these specifications without significant upgrades to automation, work roll selection, and closed-loop control. The challenge is technical, but the commercial consequence is clear: capacity that cannot hold spec loses premium contracts.
- Energy, emissions, and regulatory exposure. Rolling operations are energy-intensive, and the operational cost of reheating, rolling, and auxiliary systems is increasingly tied to carbon intensity and local enforcement regimes. Mills that continue to rely on legacy furnace and drive configurations face rising operating costs and potential compliance friction. Conversely, energy-efficient upgrades are moving from "nice-to-have" engineering projects to core components of plant economics and financing eligibility.
These challenges converge on a single strategic question: how to justify and sequence capital investment in a market where utilization, specification compliance, and energy cost are all moving targets. The answer increasingly lies in targeted modernization, process digitization, and selective capacity additions rather than blanket expansion.
Key Drivers Reshaping the Tandem Rolling Mill Market
The market's upward arc is not accidental; it is being pulled by a set of reinforcing drivers that reshape where value is created and how competitive advantage is earned. Four forces stand out.
1. Technology innovation shifting from mechanical throughput to process intelligence
The most consequential technical shift is the migration from mechanical stand-alone capability to integrated, closed-loop process systems. Tandem configurations are increasingly paired with advanced shape and flatness control, automated gap and tension regulation, and real-time thermal modeling. In steel, this translates into the ability to hold tighter tolerances on high-strength and thin-gauge products without sacrificing line speed. In aluminum and non-ferrous processing, it means more uniform properties across wider strips and better control of surface quality for automotive and packaging grades.
PW Consulting
Recent contract activity illustrates this direction. One global equipment supplier secured an order for a two-stand tandem cold rolling mill oriented toward automotive and can sheet production at a new facility in China, signaling that end-market specification requirements are steering equipment selection. In a separate modernization project, a major Japanese heavy section mill adopted compact cartridge mill stands and a tandem rolling mill control system for automatic gap control, an upgrade pattern that prioritizes responsiveness and precision over raw capacity addition. These are not isolated events; they reflect a broader preference for upgrades that improve controllability, reduce variability, and extend the useful life of existing assets.
2. Policy and regulatory pressure reshaping cost structures and procurement priorities
Regulatory and industrial policy environments are acting as both constraint and catalyst. On the constraint side, energy pricing, emissions expectations, and local content or sourcing requirements in certain regions are altering the economics of plant operation and equipment selection. On the catalyst side, the same pressures are accelerating demand for more efficient reheating, reduced thermal losses, and automation that lowers labor intensity and variability.
Industry reference material indicates that modern tandem rolling lines incorporating energy-efficient technologies such as regenerative burners in reheating furnaces can achieve average energy savings above 30 percent while reducing CO2 and NOx emissions. That magnitude of operational improvement changes the payback calculus for upgrades and makes energy performance a relevant criterion in vendor evaluation. In practice, this means policy and cost pressures are aligning: the mills that can demonstrate lower specific energy consumption and cleaner operation are better positioned to secure internal capital approval, favorable financing, and in some cases preferential consideration in regulated or semi-regulated procurement environments.
Worldwide Tandem Piston Compressors Market
3. Demand-side shifts toward advanced materials and application-specific specifications
On the demand side, the story is one of specialization. Steel processors are increasingly asked to deliver advanced high-strength grades, more consistent electrical steels, and narrower tolerance windows for automotive lightweighting and electrical applications. Aluminum and non-ferrous processors face similar pressure from automotive can-sheet, packaging, and specialty alloy requirements. In electrical steel applications, for instance, tandem cold rolling configurations are being specified with emphasis on high-precision automation, temperature modeling, and edge control to meet extremely thin gauges and uniform property demands.
This demand shift matters commercially because it rewards capability over capacity. A mill that can reliably deliver a premium specification earns a different revenue profile than one that competes primarily on tonnage. It also changes the upgrade logic: companies are more willing to invest in precision control, surface quality, and automation when those investments unlock access to higher-margin product mixes rather than merely increasing throughput of commoditized grades.
4. Supply chain and cost structure reconfiguration favoring selective modernization
Supply chain dynamics are reinforcing a preference for targeted investment. Steel input prices have exhibited notable swings, with U.S. Midwest hot-rolled coil benchmarks reaching levels that represent a significant year-over-year increase, while Northeast Asia prices have moved higher on demand from automotive, shipbuilding, and construction. When input costs rise, the operating leverage of a rolling operation depends heavily on yield, downtime, and energy efficiency.
That reality is pushing many operators away from greenfield expansion toward modernization that improves existing asset productivity. Retrofit programs that restore reliability, replace wear components, and upgrade control systems can deliver meaningful reductions in unplanned downtime and improve throughput consistency without the cost and lead-time burden of new greenfield capacity. A recent turnkey-style rehabilitation project in Italy, for example, focused on restoring reliability and reducing downtime in a tandem cold rolling mill by replacing key mechanical components. Projects of this nature reflect a market where extending asset life and stabilizing operations can be more commercially attractive than building new capacity from scratch.
Competitive Landscape and Leading Strategies
The competitive field is defined by a relatively small group of globally capable equipment and technology providers, each competing on a different combination of metallurgical expertise, automation depth, regional reach, and aftermarket support. Concentration in the market means that procurement decisions are often shaped by the perceived risk reduction, technical support coverage, and integration capability a vendor can offer, not only by headline equipment price.
Several strategic positioning patterns are visible among leading players.
- Integrated precision and automation as a differentiator. Some suppliers have built their reputation around continuous tandem cold mill solutions with advanced shape control, thickness uniformity, and automation systems, especially for electrical steel and high-precision applications. Their value proposition is less about brute-force capacity and more about repeatability, thin-gauge capability, and process stability. This is particularly relevant for customers whose product roadmap depends on meeting tighter specifications and accessing premium end markets.
- Broad-spectrum capability across ferrous and non-ferrous metals. Other leaders compete by offering a wide range of cold and tandem rolling solutions covering multiple strip widths, alloys, and configurations, including modular designs that combine rolling and forming units. This breadth allows them to serve diverse processor portfolios and to propose flexible equipment architectures that can adapt to changing product mixes. For customers with multi-metal operations or uncertain product strategies, that flexibility can be a decisive commercial advantage.
- Regional execution and aftermarket intensity. A further dimension of competition comes from suppliers with strong regional execution capability and deep aftermarket presence. Modernization, component replacement, and reliability-focused rehabilitation projects create recurring touchpoints with customers and build long-term service relationships. In concentrated markets, the ability to respond quickly with localized engineering support and spare-part logistics can be as important as the original equipment sale.
- Specialty configurations for demanding alloys. Some participants specialize in high-capacity, automation-driven tandem solutions with particular strengths in magnetic materials, stainless steel, and special alloys, using design choices such as small work roll diameters and large-stroke shifting to handle difficult processing requirements. This kind of specialization allows them to command position in niches where generic solutions underdeliver on metallurgy or control.
The landscape is evolving along three overlapping trends. First, differentiation is increasingly tied to digital control, energy performance, and specification compliance rather than to mechanical configuration alone. Second, the boundary between "new equipment" and "modernization" is blurring, as many contracts effectively extend the life and capability of installed bases rather than adding entirely new lines. Third, regional demand centers, especially in Asia, are generating a steady cadence of new orders and upgrade projects that reward suppliers with both global technology and local project execution. Taken together, these trends suggest a market where winners are those who can pair process technology with dependable service, and where the most attractive commercial opportunities often emerge in selective upgrades rather than indiscriminate expansion.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Looking ahead, several trends are likely to shape where growth concentrates and which capabilities command premium positioning.
- Continued selective modernization over blanket capacity addition. Given the maturity of the market and the cost of new greenfield builds, a meaningful share of investment will continue to flow toward retrofits, control-system upgrades, and reliability improvements. Expect more contracts focused on gap control, flatness optimization, automation, and component renewal. The commercial opportunity here lies in sequencing upgrades that unlock higher-margin products and reduce operating cost, rather than pursuing capacity additions that do not improve specification performance.
- Energy efficiency and emissions performance becoming procurement criteria. As energy costs and regulatory scrutiny remain salient, mills that can quantify and deliver energy savings, lower specific consumption, and reduced emissions will have an advantage in both internal approval processes and external competitiveness. Equipment and service offerings that integrate energy-efficient furnace technologies, optimized drive configurations, and process control that reduces waste are likely to see stronger demand, particularly where financing or compliance considerations are tied to efficiency outcomes.
- Premium specification capability as the route to margin differentiation. Demand for advanced high-strength steels, electrical steels, and specialty non-ferrous products is expected to keep pressure on processors to deliver thinner gauges, tighter tolerances, and more uniform properties. Providers that can demonstrate repeatable thin-gauge performance, advanced automation, and metallurgical process control will be better positioned to support customers moving up the value chain. The strategic implication is that capability upgrading and product-mix upgrading are increasingly two sides of the same investment decision.
These trends carry meaningful but manageable risks. Raw material price volatility can shift the urgency of upgrades and the affordability of capital projects. Regional demand cycles in automotive, construction, and shipbuilding can speed up or slow down order books. And the concentration of capable suppliers means that procurement negotiations often hinge on ecosystem support and integration risk, which can raise barriers for newer entrants attempting to compete on price alone. Still, the underlying direction is clear: value is migrating toward precision, efficiency, and reliability.
Strategic Implications and Action Steps for Decision-Makers
For manufacturers and processors, the near-term priority is to align capital planning with specification and efficiency outcomes rather than with tonnage targets alone. Targeted modernization that improves gauge control, reduces downtime, and lowers specific energy consumption can improve both margin resilience and access to premium product segments. Where new capacity is justified, it should be evaluated against the ability to hold tighter specs and to integrate efficiently with existing automation and material-handling systems.
For investors and strategic planners, the most durable opportunities are likely to be found in providers and projects that combine process technology with strong aftermarket and service economics. In concentrated markets, recurring service relationships, retrofit pipelines, and energy-performance-driven upgrades can offer more predictable value than pure equipment volume. It is also worth monitoring regional demand centers where new orders and modernization projects are accumulating, since execution capability and local support often determine long-term share dynamics.
Worldwide Steel Rolling Oils Market
For procurement and sourcing leaders, vendor evaluation should expand beyond baseline equipment cost to include controllability, automation depth, energy performance, and the credibility of the support ecosystem. In a market where specification risk and operating cost are both high, the cheapest initial price can be misleading if it comes with higher variability, more downtime, or weaker efficiency.
Because the market is shifting across technology, regulation, and demand simultaneously, decision-makers benefit from having detailed segmentation data, regional dynamics, and customized scenario analysis at hand before committing to capital or partnership choices. A comprehensive research report can provide the granular breakdowns, competitive benchmarking, and forward scenarios needed to translate these directional trends into concrete project prioritization and sourcing strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Tandem Rolling Mill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
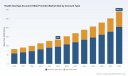
Strategic Trends & Commercial Opportunities in the Health Savings Account Provider Market
Market Overview: Scale, Trajectory, and Core Challenges
The Health Savings Account (HSA) provider market has matured into a cornerstone of the U.S. consumer-directed healthcare ecosystem, reflecting both structural shifts in insurance design and evolving consumer expectations around health financing. Measured in constant terms over a five-year baseline through 2025, the market has expanded from roughly 82.5 to 135.0 across the referenced period, with projections extending through 2032 pointing to sustained momentum. The forward trajectory implies a compound annual growth rate of approximately 11.55 percent, lifting the market size to nearly 290.1 by the end of the forecast window. This expansion is not merely a function of inflation or administrative growth; it signals a fundamental recalibration of how households and employers approach healthcare spending, savings, and investment.
Worldwide Financial Wellness Benefits Market
Beneath the headline figures, several structural realities define the current operating environment. First, account distribution is heavily weighted toward employer-sponsored arrangements, which dominate the overall composition, while individual-direct accounts represent a meaningful but smaller share. This split underscores the continued reliance on workplace channels for account origination, even as digital enrollment pathways and direct-to-consumer marketing gradually broaden the addressable base. Second, the provider landscape is fragmented across Banks and Financial Institutions, Insurance Carriers, and FinTech and Third-Party Administrators, with no single category achieving outright dominance. That fragmentation creates both distribution frictions and partnership opportunities, as each provider type brings distinct capabilities in compliance, investment access, and user experience. Third, regional concentration remains pronounced, with North America accounting for the overwhelming majority of activity and the rest of the world representing a negligible fraction, highlighting the deeply U.S.-centric nature of the current regulatory and tax framework.
The market also exhibits meaningful concentration at the top, with the largest players collectively holding roughly 48.2 percent of the landscape and the top five approaching 62.4 percent. Such concentration suggests established incumbents have secured durable advantages in employer relationships, compliance infrastructure, and asset accumulation, yet the remaining share leaves considerable room for differentiated entrants and niche platforms. The challenges ahead are equally clear. Providers must navigate the tension between scale-driven margin improvement and the growing expectation for personalized digital experiences, all while operating within a regulatory perimeter that ties account eligibility to qualifying High Deductible Health Plans. Compounding these dynamics, the shift from pure spend accounts to true investment vehicles is reshaping customer expectations, forcing providers to prove out performance, transparency, and long-term value rather than merely facilitating contributions and withdrawals.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Realities
The most visible catalyst for market expansion is the accelerating convergence of financial services and digital health platforms. Modern HSA architectures increasingly embed self-service dashboards, real-time claim adjudication, automatic investment enrollment, and integrated budgeting tools that treat health spending as part of broader household finance. These capabilities reduce administrative burden for employers and improve engagement among account holders, which in turn supports higher asset retention and deeper investment adoption. The trend toward embedding HSA functionality within broader benefits ecosystems—often layered with flexible spending arrangements, health reimbursement arrangements, and emergency savings features—has transformed the account from a standalone tax-advantaged vehicle into a multi-purpose financial hub. Recent industry reporting highlights that assets reached nearly 174 billion across 41.7 million accounts at year-end 2025, with 19 percent year-over-year asset growth and a rising share allocated to investments, signaling that users and sponsors are increasingly comfortable with longer-horizon financial behaviors.
Regulation continues to shape the speed and structure of adoption, not only by defining eligibility but by setting annual contribution limits that influence household behavior and employer design choices. For 2026, the IRS set HSA contribution limits at 4,400 for self-only coverage and 8,750 for family coverage, parameters that guide recurring contributions and encourage year-end planning. Because HSAs must be paired with a qualifying High Deductible Health Plan to preserve tax advantages, any shift in employer insurance strategy, employee cost sensitivity, or plan design directly influences account origination and asset accumulation. The regulatory backdrop also rewards providers that can demonstrate robust compliance, clean reporting, and seamless integration with plan documents and payroll workflows. In practice, the firms that most effectively translate regulatory requirements into friction-free employer onboarding and employee education capture disproportionate share of new accounts and assets.
Demand-side dynamics reinforce this trajectory. Employers are increasingly weighing total rewards packages that blend clinical coverage with financial wellness, recognizing that HSA participation can influence employee retention, productivity, and financial resilience. Individuals, meanwhile, are becoming more deliberate about health spending, investment growth, and portability as job mobility rises and traditional employer relationships become less sticky. This behavioral shift favors platforms that offer clear fee structures, intuitive investment options, and educational support that demystifies contribution strategies, catch-up provisions for older participants, and the interplay between current spending and future growth. The result is a market where user experience and transparency are no longer differentiators but baseline requirements.
Cost structures and operating models are evolving in parallel. As digital onboarding, automated compliance checks, and platform-based integrations reduce marginal handling costs, providers are gaining latitude to compete on value rather than price alone. At the same time, the economics of managing growing asset balances introduce new considerations around recordkeeping, custody, and investment administration. Companies that can align scalable technology with disciplined cost control are better positioned to sustain margins as the market expands, especially when investment assets increasingly represent a meaningful portion of total value. The strategic implication is straightforward: the winners will be those that turn cost efficiency into better user outcomes, not just internal savings.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by several well-established players, each leveraging a distinct blend of scale, integration, and product breadth. Fidelity Investments has built a reputation for fee-light HSAs paired with broad investment menus that span stocks, ETFs, and mutual funds, complemented by seamless connectivity to retirement accounts. Its positioning emphasizes low cost and investment flexibility, appealing to account holders who view their HSA as a long-term savings and investment instrument rather than a transactional spend account. HealthEquity has concentrated on employer-sponsored administration at scale, combining compliance rigor with integrated consumer-directed benefits that include FSAs and HRAs. Its strengths lie in analytics, account volume, and enterprise-grade support, and its recent financial results—record revenue of 1.31 billion, over one million new HSAs from sales, and an outlook raised for fiscal 2027 with 17.8 million total accounts and more than 36 billion in assets—illustrate how scale and disciplined execution can compound in a maturing market.
HSA Bank, operating as a division of Webster Bank, blends HSA administration with investment access through brokerage relationships and integrated benefits solutions, while also extending into adjacent pillars of employee financial wellness. Its acquisition of SecureSave to expand into employer-sponsored Emergency Savings Accounts signals a move toward broader financial resilience offerings, allowing employers to bundle health savings with emergency savings in a single wellness narrative. Lively has carved out a modern, digital-first identity with an emphasis on user-friendly tools, transparent pricing, and support for both individuals and small-to-mid employers, positioning itself as an agile alternative to more traditional administrators. Optum Bank leverages its integration within a large health benefits ecosystem to offer HSAs connected to broader care and benefits management, with investment options available through brokerage windows or managed solutions. Bank of America brings a conventional banking footprint with tiered interest rates and basic investment access, appealing to consumers who prioritize familiar banking relationships and integrated account management.
The strategic differences among these players reveal a market that is simultaneously consolidating around scale and differentiating around experience. Incumbents with deep employer relationships and robust compliance infrastructure continue to capture the bulk of new accounts, while newer platforms compete on design, fee clarity, and specialized workflows that reduce administrative overhead for smaller sponsors. The evolution is also visible in product adjacency: providers are extending beyond core HSA administration into emergency savings, wellness incentives, and integrated benefit stacks, recognizing that household financial decisions rarely occur in isolation. This blending of use cases creates opportunities for cross-selling and deeper engagement, but it also raises the bar for operational discipline, as each new feature must be supported by clear governance and reliable user communication.
Concentration patterns suggest that while the largest players enjoy meaningful advantages in distribution and asset accumulation, the market remains open to targeted innovation. The gap between top-tier scale and the long tail of smaller providers creates a natural environment for partnerships, platform integrations, and geographic or segment specialization. At the same time, the expectation for investment adoption and digital fluency is pulling even traditional providers toward more modern interfaces and transparent fee logic. The net effect is a landscape in flux: scale still matters, but differentiation through experience, ecosystem fit, and adjacent financial wellness capabilities is increasingly decisive.
Strategic Outlook: Three Trends Shaping the Next 3-5 Years
First, the HSA will continue its evolution from a spend account to a core investment vehicle within household finance. As assets grow and a larger share is allocated to investments, providers that offer well-structured investment options, clear performance reporting, and educational support will deepen engagement and retention. The commercial opportunity lies in building trust around long-term outcomes, including guidance on contribution strategies, catch-up eligibility, and the interaction between current healthcare spending and future growth. Platforms that can communicate value without complexity are likely to capture more assets and fewer lapses.
Second, financial wellness bundling will become a standard expectation rather than a differentiator. Employers and individuals increasingly view health savings alongside emergency savings, retirement readiness, and benefits transparency as part of a single financial resilience strategy. Providers that can integrate these use cases in a coherent, compliant manner will gain preference in employer selection and individual adoption. The upside is higher engagement and broader account utility; the risk is operational complexity and the potential for feature sprawl that dilutes clarity.
Third, digital experience and fee transparency will increasingly separate leaders from laggards. As account holders compare platforms on usability, investment access, and total cost, providers that invest in self-service design, proactive education, and straightforward fee logic will stand out. The uncertainty here is twofold: regulatory parameters can change with annual limits and eligibility rules, and competitive pressure may compress fee-based economics, pushing providers to rely more on scale, ecosystem partnerships, and value-added services to sustain margins.
Actionable Recommendations for Decision-Makers
For employers and plan sponsors, the priority is to treat HSA design as a strategic component of total rewards rather than an administrative checkbox. That means selecting providers based on integration quality, fee clarity, investment readiness, and employer analytics, while pairing account access with education that improves participation and asset retention. Sponsors should also evaluate adjacent financial wellness capabilities, such as emergency savings integrations, as part of a cohesive offer that supports employee resilience and engagement.
Health Products Market
For investors and market participants, the most durable opportunities lie in platforms that combine scalable compliance infrastructure with modern user experience and credible investment pathways. Attractive theses typically emphasize asset growth, investment adoption trends, and the ability to expand into adjacent wellness use cases without sacrificing operational discipline. Caution is warranted where differentiation rests primarily on marketing claims without transparent fee structures, reliable service levels, or clear employer value.
PW Consulting Information & Electronics Research Center
For technology providers and procurement teams, the mandate is to prioritize interoperability, clean data flows, and enrollment simplicity. Solutions that reduce onboarding friction, automate compliance checks, and deliver actionable reporting will earn preference in a market where scale and experience increasingly converge. Timely, granular intelligence on segment dynamics, provider positioning, and adoption patterns can sharpen procurement decisions and reduce integration risk, especially as the market continues to reward providers that align product design with real user behavior. For those seeking deeper segmentation, competitive benchmarking, and tailored strategic guidance, PW Consulting’s full research report provides detailed breakdowns and customized recommendations to support concrete next steps.
For detailed analysis of this topic, please visit the official page: Health Savings Account (HSA) Provider Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
RFI Shielded Glasses Market 2026: Why 7.82% CAGR and Healthcare Demand Reshape Growth
By PW Consulting, 2026-09-18
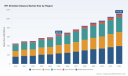
Strategic Trends and Commercial Opportunities in the RFI Shielded Glasses Market: A 2032 Outlook
The RFI shielded glasses market has matured into a specialized yet strategically vital segment within the broader electromagnetic compatibility (EMC) and protective infrastructure industry. Over the past five years, the sector has transitioned from niche compliance-driven production to value-added differentiation, driven by tighter electromagnetic standards, expanding imaging and test environments, and a growing recognition that optical clarity cannot be sacrificed for shielding performance. Historical trajectory through the early 2020s established a consistent upward path, with revenue climbing steadily as medical facilities, defense contractors, and electronic testing laboratories upgraded aging shielding infrastructure. The market reached a valuation of approximately $657.39 million in 2025, reflecting sustained investment in controlled electromagnetic environments across critical sectors. Looking ahead, the compound annual growth rate is projected at 7.82 percent, positioning the market to surpass $1.1 billion by 2032.
PW Consulting Chemical & Energy Research Center
This expansion is not uniform. Growth concentrates in applications where visibility, patient or operator safety, and electromagnetic containment intersect, creating structural demand rather than cyclical fluctuations. The market remains moderately consolidated, with a handful of established players capturing a significant share of volume, while regional distribution reflects divergent procurement cycles, regulatory maturity, and industrial base readiness. For decision-makers, this landscape signals both stability and friction: predictable baseline demand exists, but capturing incremental growth requires navigating material constraints, performance trade-offs, and shifting procurement expectations.
Three structural challenges currently define the market's inflection points. First, optical transparency and shielding attenuation remain in persistent tension. Increasing shielding effectiveness across broadband frequencies often requires thicker conductive layers or denser mesh architectures, which can compromise light transmission and introduce visual distortion. Second, supply chain volatility for raw materials and precision coating processes has tightened margins and extended lead times. Float glass substrates, conductive inks, sputtering targets, and specialized wire alloys face price fluctuations and geopolitical sourcing constraints that ripple through manufacturing schedules. Third, certification and compliance complexity continues to raise the barrier for new entrants and mid-tier manufacturers. Medical and defense applications demand reproducible testing, clean room production standards, and documented compatibility with equipment-level standards, which slows product commercialization and elevates development costs. These challenges are not insurmountable, but they reward operators with process discipline, material partnerships, and application-specific engineering capabilities.
Key Drivers Shaping Market Trajectory
Several interdependent forces are accelerating demand and reshaping product expectations across the RFI shielded glasses market. Understanding these drivers clarifies where investment, capacity expansion, and differentiation are most likely to generate durable advantage.
Technological Innovation and Performance Optimization
The most consequential driver is the pursuit of higher shielding effectiveness without degrading optical performance. Conductive film laminates, ultra-fine metal mesh architectures, and improved indium tin oxide coating processes have progressively expanded the performance envelope. Manufacturers are increasingly targeting surface resistance in the sub-ohm to low-ohm range while maintaining light transmission above seventy percent, with some solutions exceeding ninety percent in optimized configurations. This trajectory matters because end-users no longer view shielded glass as a compromise component. Instead, they expect medical visibility standards, display clarity for electronic test setups, and situational awareness in defense enclosures to remain uncompromised while electromagnetic interference is contained.
Worldwide Anti-Interference Shielding Material Market
Recent product development signals reflect this direction. Suppliers are refining micro-replicated conductive grids and woven wire mesh variants that reduce visual artifacts while preserving broadband attenuation. Others are advancing scratch resistance, chemical durability, and clean room compatibility to meet hospital and laboratory environment requirements. The cumulative effect is a shift from generic shielding solutions toward application-tuned optics, where transmission, attenuation bandwidth, mechanical robustness, and durability are engineered together rather than treated as independent specifications.
Regulatory and Standards-Driven Demand
Compliance frameworks continue to shape procurement behavior, particularly in medical and defense settings. Standards addressing electromagnetic compatibility for medical electrical equipment, including requirements for imaging environments such as MRI rooms, create recurring demand for shielding components that must be documented, tested, and installed with predictable performance. In practice, this means shielded glass is not merely a material purchase but a compliance enabler integrated into broader facility and equipment qualification processes.
Regulatory expectations also influence product design choices. RoHS-compatible materials, systematic optical quality control, and clean room manufacturing traceability are increasingly referenced in procurement specifications. For high-stakes environments, these requirements reduce acceptable supplier pools and increase switching costs, reinforcing the value of established compliance documentation and repeatable production processes. The standards environment does not just constrain the market; it filters it, favoring operators who can evidence consistent performance and transparent process control.
Demand-Side Shifts in Critical Infrastructure and Testing
Demand is being reinforced by the expansion and modernization of controlled electromagnetic environments. Medical imaging facilities continue to require visibility and protection in shielded enclosures, where openings, observation windows, and display interfaces must manage stray electromagnetic fields without obstructing clinical workflows. Defense and aerospace programs similarly depend on transparent shielding for enclosures, sensor integration, and sensitive electronics testing, particularly as systems grow more complex and frequency usage intensifies.
Electronic test laboratories represent another structural driver. As device density, wireless functionality, and sensitivity to external interference increase, laboratory environments must maintain repeatable measurement conditions. Shielded windows and display interfaces contribute to isolation without eliminating operator visibility or instrument interaction. This combination of stricter measurement reliability and broader deployment of sensitive electronics sustains demand beyond incremental replacement cycles.
Supply Chain and Cost Structure Evolution
Cost dynamics are increasingly influenced by material availability, coating process efficiency, and customization levels. Float glass remains the dominant substrate, but the value creation occurs in coating uniformity, mesh integration, lamination quality, and finishing tolerances. Manufacturers that can stabilize coating yield, reduce scrap rates, and standardize frame or enclosure integration gain meaningful cost advantages, especially when customization remains a competitive necessity. At the same time, custom sizes, special shapes, and application-specific frame options can create both premium pricing opportunities and operational complexity.
This cost structure incentivizes a strategic balance between standardization and specialization. Operators that over-index on bespoke production may face margin pressure and delivery risk, while those that over-standardize may lose specifications-driven opportunities in medical and defense procurements. The more sustainable path involves modular product architectures, repeatable coating and lamination processes, and selective customization where specifications truly justify the cost.
Competitive Landscape and Leadership Positioning
The competitive environment is characterized by a mix of established shielding specialists, materials-focused manufacturers, and application-oriented integrators. Market concentration is notable, with a core group of companies accounting for a substantial share of revenue, though fragmentation persists at the regional and application-specific level. Leadership in this market is less about scale alone and more about performance consistency, certification readiness, and the ability to match optical and shielding requirements to procurement realities.
Differentiation Through Material and Application Expertise
Leading participants distinguish themselves through clearly defined technical value propositions. Some competitors emphasize high transparency combined with broad frequency coverage, positioning their shielded glass for environments where visibility is paramount, such as medical observation windows and display interfaces. Others focus on metal mesh or ITO-based architectures that deliver strong attenuation while preserving usable light transmission across glass or polycarbonate substrates. A further group leans into mechanical durability and customization, offering laminated float glass, scratch and chemical resistance, and tailored shapes for industrial, medical, or defense installations.
These distinctions matter because procurement decisions in this market are specification-intensive. Buyers often evaluate light transmission, shielding bandwidth, surface resistance ranges, substrate type, and compatibility with enclosure or framing systems. Suppliers that can articulate performance across these dimensions, and back claims with reproducible manufacturing and testing, gain a clearer path to qualification. In contrast, generalist positioning tends to weaken in environments where compliance documentation and environmental durability are equally important as optical performance.
Strategic Positioning by Market Segment
Within the broader competitive field, several players have built reputation advantages aligned with specific application families. Medical-focused suppliers often emphasize compatibility with hospital and imaging environments, referencing standards-aligned design, clean room manufacturing, and the need to protect staff and equipment while maintaining visibility. Defense- and aerospace-oriented participants tend to highlight broadband performance, mechanical robustness, and integration into enclosures or sensitive electronic setups. Test and laboratory suppliers commonly prioritize optical clarity and repeatable shielding behavior for measurement environments. This segmentation is not absolute, but it reflects a practical reality: procurement cycles, testing expectations, and acceptance criteria differ enough that reputation and reference use cases influence shortlisting.
Geographically, the landscape reflects both maturity and growth potential. Established demand centers show deeper qualification pathways and longer replacement cycles, while emerging demand regions often combine infrastructure investment with cost sensitivity. Suppliers with strong regional service, documentation support, and adaptable product configurations tend to navigate these differences more effectively than those relying on one-size procurement models.
Market Evolution: Consolidation, Niches, and New Entries
The market is likely to see continued selective consolidation at the capability level rather than purely through M&A headlines. End-users increasingly favor suppliers who can provide consistent coating quality, shielding performance across target frequency ranges, and reliable delivery of customized dimensions. This dynamic rewards operators with integrated manufacturing and predictable process control. At the same time, niche specialists may thrive by dominating particular application requirements, such as optical-grade shielding for displays, high-transparency observation windows, or cost-optimized solutions for laboratory environments.
New entry opportunities exist, but they are conditional. The barrier is not only technical performance but also qualification burden, repeatability, and the ability to supply with consistent documentation. Entrants that can demonstrate differentiated material approaches, improved transmission-to-attenuation ratios, or streamlined integration with enclosure systems have plausible entry points. However, those entering without clear application focus or compliance readiness face a steep path to shortening procurement cycles and displacing incumbents with established reference use.
Competition is therefore shifting from pure price competition toward performance reliability, traceability, and application fit. Market participants that can balance standardized production efficiency with targeted customization are best positioned to defend margins while expanding into higher-value segments.
Future Trends and Commercial Implications (2026–2032)
Three trends are likely to define the market over the next several years. First, performance expectations will continue to tighten around the transparency-versus-shielding frontier. As imaging systems, electronic test benches, and enclosed defense systems become more sensitive, the tolerance for optical compromise will decrease. Suppliers that can deliver high transmission with effective attenuation across broader frequency ranges will capture preferential positioning, particularly in medical and high-end laboratory applications. This trend creates commercial opportunities for advanced coating processes, refined mesh architectures, and lamination techniques that preserve clarity while improving attenuation consistency.
Second, procurement will increasingly treat shielded glass as part of a system-level compliance and reliability strategy rather than an isolated component. Documentation, standards alignment, clean room production practices, and environmental durability will become stronger differentiators in bidding and qualification processes. Commercial advantage will accrue to manufacturers that can package product performance with reproducible quality control and clear application guidance. This also raises the value of trusted supplier relationships, since replacement windows, display interfaces, and enclosure openings often require long-cycle compatibility with installed infrastructure.
Worldwide Fibers and Electromagnetic Shielding Market
Third, supply and cost pressures will push the market toward smarter portfolio design. Expect greater emphasis on modular product families, reusable frame or enclosure integration approaches, and selective customization only where specifications justify it. Manufacturers that can standardize core coating and lamination processes while offering controlled variation in size, substrate, and finishing will be better equipped to manage margin and delivery risk. Over time, this may also encourage broader adoption of coated film laminate options in applications where glass is not strictly required, expanding the addressable solution set.
Risks and uncertainties remain. Raw material cost volatility, coating yield variability, and freight or sourcing disruptions can compress profitability and extend lead times. Regulatory expectations may become more prescriptive in certain regions or application areas, raising compliance burdens unevenly across suppliers. There is also the possibility of substitution pressure if alternative shielding approaches improve in transparency, cost, or ease of integration. These uncertainties do not undermine the growth trajectory, but they increase the importance of operational resilience and specification agility.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product architecture with specification reality. Build repeatable processes around coating uniformity, optical consistency, and mechanical durability, then reserve customization for applications where performance trade-offs are explicitly justified. Strengthen documentation and testing narratives that support medical, defense, and laboratory procurement requirements, since qualification speed often matters as much as nominal performance. Where possible, structure product families to balance standardization with selective variation in size, substrate, and frame compatibility so that cost and lead time remain controlled.
For investors, the commercial opportunity lies in operators with disciplined manufacturing, defensible compliance readiness, and clear positioning in high-value applications. Preference should lean toward companies that can demonstrate consistent transmission-to-attenuation performance, stable supply relationships, and evidence of repeat qualification in regulated environments. Growth potential is strongest where suppliers can expand beyond replacement demand into system-level shielding upgrades, enclosure integration, and specialized optical shielding for displays or test environments. Due diligence should examine process yield, customization cost exposure, and the ability to scale without eroding optical or shielding performance.
For procurement and engineering leaders, sourcing strategy should prioritize performance reproducibility and integration fit over headline specifications alone. Evaluate suppliers on optical clarity consistency, shielding bandwidth relevance to the operating environment, substrate durability, and the quality of compliance documentation. Where facility or equipment upgrades are planned, consider how shielded windows and display interfaces will interact with enclosure design, maintenance cycles, and future imaging or electronics requirements. Treating RFI shielded glass as a long-cycle system component rather than a commodity purchase reduces rework risk and improves lifecycle value.
Detailed segmentation data, competitive benchmarking, and region-specific procurement dynamics can materially sharpen these decisions. Access to comprehensive upstream, midstream, and downstream analysis helps identify which materials, applications, and geographies offer the most favorable risk-adjusted opportunity in the coming growth cycle.
For detailed analysis of this topic, please visit the official page: RFI Shielded Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Coffee Concentrate Juice Market: Why 6.12% CAGR Changes Everything
By PW Consulting, 2026-09-18
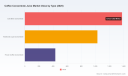
Strategic Trends and Commercial Opportunities in the Global Coffee Concentrate Market
Market Landscape and Core Challenges
The global coffee concentrate market has demonstrated consistent expansion, with revenue climbing from approximately USD 2,120.45 million in 2020 to an estimated USD 2,842.50 million in 2025. Projections indicate a compound annual growth rate of 6.12 percent through 2032, positioning the sector to reach roughly USD 4,303.18 million by the end of the forecast window. This trajectory reflects a broader reallocation of value within the beverage industry, where convenience, consistency, and scalability are increasingly dictating procurement decisions across both commercial and retail channels. The market's steady expansion suggests that concentrate formats are no longer functioning as a niche input but are becoming a structural component of modern beverage architecture.
Despite the favorable growth backdrop, the industry is navigating several structural friction points that will determine which participants capture disproportionate value in the coming years. First, raw material volatility continues to inject uncertainty into cost planning and margin management. The International Coffee Organization's Composite Indicator Price averaged 296.89 US cents per pound in January 2026, followed by a downward drift toward lows near 262 US cents per pound in February before partial stabilization in the 273–290 US cents per pound range during the spring months. This pattern underscores the sensitivity of concentrate economics to crop cycles, weather outcomes, and supply expectations. When input costs shift rapidly, manufacturers with limited hedging discipline or inflexible procurement structures face compressed profitability, while more adaptive firms can protect margins and even gain share during periods of price dislocation.
Second, regulatory architecture remains uneven and poorly synchronized across markets, creating compliance friction for global operators. Coffee and tea infusions derived from dried ingredients fall outside the scope of FDA Juice HACCP regulation, a distinction that differentiates coffee concentrates from fruit or vegetable juice concentrates intended for beverage use. At the same time, labeling rules for products purporting to contain juice require explicit juice content declarations and mandate that beverages made from concentrate include terms such as "from concentrate" or "reconstituted" where the product name appears. For coffee concentrate manufacturers operating in adjacent or hybrid categories, these overlapping and sometimes contradictory requirements increase formulation complexity, labeling costs, and the risk of misclassification. Firms that invest early in regulatory mapping and documentation discipline will face fewer costly disruptions as product portfolios expand across categories and geographies.
Third, the combination of market concentration and ongoing process innovation is raising the competitive bar. With the top three participants accounting for roughly 38.45 percent of revenue and the top five reaching approximately 52.3 percent, scale, brand equity, and distribution reach continue to confer meaningful advantages. Yet concentration also signals an opportunity for targeted differentiation. As major operators push proprietary processing technologies and customized concentrate variants, smaller or regionally focused players must avoid competing on commodity-like volumes alone. The market is bifurcating: scale players are leveraging volume and branding, while agile suppliers are carving positions through specialty origins, performance-focused processing, and tailored foodservice formats. Recognizing this divergence is essential for any operator planning capacity, partnership, or entry decisions.
Coffee Concentrates Market
Key Growth Drivers
Several interconnected forces are shaping the direction of the coffee concentrate market and creating differentiated opportunities for participants that align their capabilities with structural demand shifts.
Technological Innovation and Processing Differentiation
Process innovation remains one of the most consequential drivers of competitive advantage. Advances in cold-brew extraction, high-Brix concentration, and shelf-stable liquid formulation are enabling manufacturers to deliver concentrates with improved flavor consistency, reduced preparation complexity, and broader application compatibility. Recent product activity illustrates this trajectory clearly. In July 2025, Red Diamond Coffee & Tea introduced the Fitz Cold Brew Coffee Concentrate for foodservice operators, designed to simplify cold brew preparation by providing a ready-to-dilute format that reduces labor, variability, and equipment demands. A few months later, in April 2026, Nestlé and Starbucks unveiled the Starbucks Coffee Craft concentrate, expanding cold coffee availability through a concentrate format engineered for consistent taste and efficient deployment across foodservice and beverage manufacturing applications.
These launches are not isolated product additions; they reflect a broader shift toward concentrates that serve as operational tools rather than raw inputs. For beverage manufacturers and foodservice operators, the commercial appeal of concentrates increasingly rests on repeatability, speed of preparation, and compatibility with existing dispensing or blending infrastructure. Suppliers that can pair flavor integrity with formulation flexibility, such as customized Brix levels or origin-specific profiles, are well positioned to deepen customer relationships and move beyond transactional supply arrangements. The strategic implication is that processing capability is becoming a core differentiator, and investment in extraction, stabilization, and customization technologies is likely to separate market leaders from follow-on competitors.
Demand-Side Transformation and Channel Evolution
Consumer and enterprise behavior is reshaping where and how coffee concentrate is consumed. Cold coffee formats have moved from a seasonal novelty to a sustained category with year-round demand, and the concentrate segment is benefiting directly from this normalization. Foodservice operators are drawn to concentrate formats that reduce preparation variability and labor intensity, particularly in high-turnover environments where consistency and speed are essential. At the same time, retail and household channels are absorbing concentrates as consumers seek convenient, customizable home beverage experiences without the operational burden of brewing from scratch.
This channel divergence is producing distinct demand profiles. Foodservice demand tends to prioritize operational efficiency, portion control, and compatibility with existing equipment. Retail and household demand places greater weight on shelf stability, ease of use, and perceived premium quality. Manufacturers that design concentrate portfolios with these channel-specific requirements in mind can capture value across multiple touchpoints without forcing a single format to carry all use cases. The broader insight is that demand growth is being supported not only by total volume expansion but also by the migration of coffee consumption into formats that are inherently more concentrate-friendly.
Supply Chain Dynamics and Cost Structure Realignment
Coffee concentrate economics are being recalibrated by evolving raw material conditions and supply chain design choices. The recent softening of green coffee pricing, driven by expectations of record Brazilian harvests and broader global supply surpluses, has altered the near-term cost environment. While lower input prices can relieve margin pressure, they also introduce new considerations around procurement timing, inventory strategy, and supplier relationships. Firms that treat raw material volatility as a recurring design parameter rather than an episodic disruption are better equipped to maintain cost discipline. This includes diversifying origin exposure, structuring flexible offtake arrangements, and aligning concentrate specifications with cost-efficient processing routes where feasible.
PW Consulting
Supply chain resilience is increasingly tied to operational flexibility. Concentrate manufacturers are evaluating everything from batch sizing and packaging configurations to logistics networks and regional production footprints. In a market where foodservice and industrial processing customers demand reliable availability and predictable lead times, the ability to balance efficiency with responsiveness is becoming a differentiator. Cost structures that incorporate proactive inventory planning, multi-origin sourcing, and format optimization are more likely to sustain profitability through cycles of input price movement. The practical takeaway is that supply chain design is no longer a back-office concern; it is a strategic lever that shapes pricing power, service levels, and customer retention.
Regulatory Clarity as a Strategic Enabler
Regulatory dynamics are also functioning as a growth enabler by clarifying where concentrate products sit within existing compliance frameworks. The distinction between coffee and tea infusions from dried ingredients and juice-based concentrates under FDA Juice HACCP guidance helps reduce uncertainty for coffee-focused manufacturers, provided that labeling and category positioning are managed carefully. In parallel, customs marking exemptions for roasted and instant coffee and certain coffee preparations can simplify trade documentation and reduce administrative overhead for exporters and importers operating across jurisdictions. Where beverage products include juice claims, however, percentage declarations and from-concentrate labeling requirements still apply and must be integrated into product development and packaging processes.
These regulatory nuances are not merely compliance checkboxes; they influence product architecture, market entry sequencing, and labeling investment. Organizations that build regulatory literacy into their formulation and go-to-market planning can reduce time-to-market, avoid rework, and position products more cleanly within their intended categories. As the concentrate market expands across both coffee-centric and hybrid beverage applications, clarity on classification and labeling will increasingly separate operators that scale smoothly from those that encounter avoidable friction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global scale players, specialized concentrate suppliers, and foodservice-oriented manufacturers, each pursuing distinct value propositions. Nestlé and Starbucks exemplify a partnership-driven approach to category expansion, leveraging brand equity and distribution muscle to accelerate cold coffee availability through concentrate formats. Their focus on broad availability and recognizable branding targets mass consumption and beverage manufacturing channels where standardization and reach are paramount. This strategy underscores the continued relevance of scale, but it also highlights the importance of product relevance: even large incumbents must ensure that concentrate formats align with specific usage occasions and preparation expectations.
Finlays represents a more customization-oriented posture, supplying tailored coffee concentrates including cold brew and high-Brix variants for beverage manufacturing and ready-to-drink products. Its emphasis on multiple origins and certifications signals a strategy built on formulation flexibility and sourcing credibility. For industrial and beverage manufacturing customers, this profile can translate into stronger partnership potential, particularly where product differentiation depends on origin selection, processing nuance, or certification requirements. In a market where generic concentrate offerings are increasingly commoditized, the ability to adapt specifications to customer needs becomes a meaningful differentiator.
U.S.-based manufacturers such as Westrock Coffee Company, The J.M. Smucker Company, Keurig Dr Pepper, All American Coffee LLC, Red Diamond Coffee & Tea, Chameleon Cold-Brew, CoolBrew, and Jedwards International illustrate the breadth of domestic concentration activity across private label, retail, and foodservice applications. Some participants emphasize proprietary processing for customized formats, while others focus on convenience-driven foodservice concentrates or organic retail-oriented cold brew products. Red Diamond's Fitz Cold Brew launch, for example, reflects a practical service logic: enabling foodservice operators to deliver premium cold brew with simplified preparation. CoolBrew's proprietary cold-drip process and Chameleon's organic positioning point to differentiation through process identity and category authenticity. These approaches demonstrate that U.S. players are competing not only on volume but also on format design, brand narrative, and channel fit.
International and specialty-oriented operators add further texture to the landscape. Jake-Frut & Jake-Café provides custom branding solutions for concentrated juices and liquid coffee, targeting customers that value packaging and brand integration. Cafeahaus AG DEK specializes in soluble coffees and liquid coffee extracts for food industry and vending applications, an area where compatibility, dosing reliability, and machine-friendly formats matter. Batavia Cold Drip Coffee, with operations spanning the Netherlands and Indonesia, offers bulk liquid cold drip concentrates with customizable recipes and packaging options, an appealing profile for buyers seeking scale without sacrificing formulation input. Together, these companies show that the market is not a simple hierarchy of global giants versus niche suppliers; it is a layered ecosystem where competitive advantage can be built through provenance, customization, service model, or application expertise.
The competitive trajectory appears to be moving toward selective consolidation and simultaneous niche differentiation. Scale players will continue to consolidate advantageous distribution, brand recognition, and processing capacity, especially in broad consumer and foodservice segments. At the same time, new entrants and focused incumbents will likely find room by addressing underserved applications, origin narratives, organic or specialty certifications, and operational pain points such as preparation complexity or format incompatibility. The most durable strategies will be those that combine credible processing capability with clear customer value, whether that value is operational efficiency, flavor consistency, customization, or category positioning. A market with this level of strategic diversity rewards companies that define their positioning precisely rather than attempting to compete across every dimension at once.
Future Outlook: Three Signals to Watch
Looking ahead to the 2026–2032 window, several signals point to where strategic attention should be concentrated.
First, cold coffee adoption will continue to anchor concentrate demand, but the growth logic will increasingly shift from novelty to operational integration. As foodservice and beverage manufacturing customers mature in their use of concentrate formats, the value proposition will depend less on introducing cold coffee and more on improving preparation efficiency, consistency, and scalability. Manufacturers that align concentrate specifications with real-world workflow requirements, including dilution ratios, dispensing compatibility, and batch-to-batch stability, are likely to secure stickier customer relationships. The related opportunity is to design concentrate portfolios for repeatable deployment rather than one-off product launches.
Second, a period of lower input prices can reshape competitive behavior if it leads to complacency in cost management or procurement discipline. Lower green coffee pricing may temporarily ease margin pressure, but it can also obscure the need for robust hedging, origin diversification, and specification-to-cost alignment. Operators that use favorable pricing windows to strengthen supply chain resilience and lock in flexible sourcing arrangements will be better positioned when prices cycle back. The risk is that temporary cost relief encourages volume-driven competition without corresponding value or efficiency gains, which can erode profitability over time.
Third, category boundaries will continue to test labeling and regulatory clarity, especially as beverage concepts blur the line between coffee, juice-adjacent, and hybrid formats. Products that incorporate juice claims, from-concentrate language, or multi-ingredient formulations will face tighter scrutiny on declaration accuracy and consumer communication. This creates both a compliance challenge and an opportunity: companies that develop clean, category-appropriate labeling and transparent product narratives can reduce friction and build trust, while those that treat labeling as an afterthought risk rework, market delays, or consumer confusion. The strategic opportunity lies in treating regulatory and labeling design as part of product architecture rather than a downstream task.
Strategic Recommendations for Decision-Makers
For manufacturers, the immediate priority is to align concentrate development with application-specific value. This means prioritizing processing consistency, customization capability, and preparation simplicity where customer workflows demand it. Investment should be directed toward formats and specifications that reduce customer friction, whether that friction is operational, sensory, or regulatory. In parallel, supply chain strategy should incorporate flexible sourcing and inventory planning so that margin protection is not dependent on any single price environment.
Worldwide Citrus Concentrate Market
For investors, the most relevant question is not whether the market is expanding, but which business models are best configured to capture durable margin and share. Comparative evaluation should focus on processing differentiation, channel fit, customer retention logic, and exposure to raw material cycles. Companies that can demonstrate repeatable concentrate performance, clear application relevance, and disciplined cost management are more likely to translate market growth into sustained profitability. Due diligence should also assess regulatory readiness, especially for products operating near category boundaries or with multi-ingredient formulations.
For procurement and sourcing teams, concentrate selection should be evaluated on total operational impact rather than unit price alone. Dilution performance, shelf stability, equipment compatibility, lead-time reliability, and documentation clarity all influence total cost of ownership. Where feasible, buyers should seek suppliers with proven customization capacity and transparent compliance practices, particularly if product portfolios are expected to expand into hybrid or multi-format use cases. Strategic sourcing relationships, rather than transactional purchasing, will increasingly determine how smoothly concentrate programs scale.
Market-level growth is only one part of the story. The more consequential question is which participants will convert that growth into defensible advantage through better processing, smarter sourcing, and sharper category positioning. Detailed segmentation, regional dynamics, and application-level cost structures provide the granularity needed to make those judgments with confidence. Readers seeking a deeper view of segment performance, competitive benchmarking, and forward scenarios can consult the full PW Consulting report on the worldwide coffee concentrate market for more detailed data and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Coffee Concentrate Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Con las olas de calor cada vez más frecuentes en el sur de Europa, la camisa masculina ha dejado de ser una prenda meramente formal para convertirse en un auténtico sistema de ventilación y estilo. La tendencia actual se aleja de la clásica camisa blanca de oficina y apuesta por cortes frescos, tejidos sostenibles y patrones con identidad propia.
Si es la primera vez que diseñas una prenda masculina a medida, esta guía paso a paso te ayudará a elegir el corte, los tejidos y los detalles adecuados para conseguir una pieza impecable.
Paso 1: Elegir el corte y el tejido según el destinatario
El corte determina la comodidad de la prenda, especialmente en los meses de mayor temperatura:
* **El cuello cubano (*Cuban Collar*):** Su apertura en V favorece la circulación del aire y aporta un aire retro y relajado. Es la elección perfecta para escapadas a Mallorca, veladas en terrazas mediterráneas o festivales de música al aire libre.
* **Tejidos transpirables y sostenibles:** La producción bajo demanda permite elegir fibras respetuosas con el medio ambiente, como el Tencel o el lino ligero. Estos materiales facilitan la transpiración natural, caen con soltura sobre el cuerpo y reducen el impacto ambiental frente a la moda rápida convencional.
La combinación de estas siluetas con estampados exclusivos da como resultado camisas personalizadas que aúnan frescura y distinción sin caer en la monotonía de las prendas en serie.
Paso 2: Diseñar el estampado con fotos o motivos visuales
Al personalizar visualmente una camisa para hombre, el enfoque debe inclinarse hacia la estética editorial antes que hacia la broma efímera:
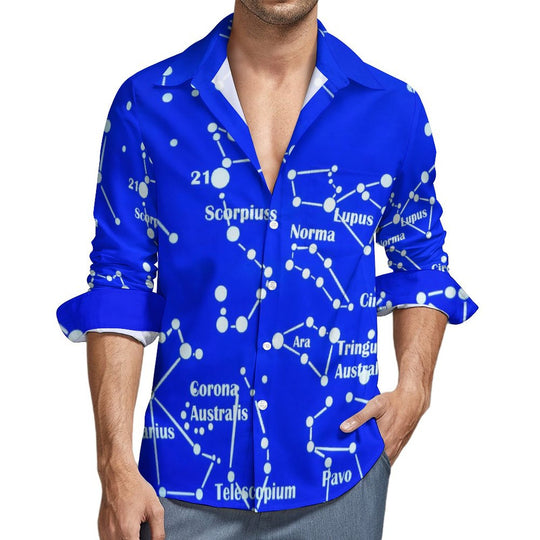
* **Qué contenidos funcionan mejor:** Evita las fotografías de retrato directo, ya que las costuras y los pliegues del tejido deforman las caras. Funcionan de maravilla los patrones botánicos, las texturas abstractas de vegetación tropical o los mosaicos geométricos de inspiración mediterránea generados a partir de fotografías de viajes o herramientas de diseño digital.
* **Composición equilibrada:** Los patrones continuos (*all-over print*) con una paleta de dos o tres tonos neutros o tierra (arena, verde salvia, azul marino) garantizan que la camisa se pueda combinar fácilmente con bermudas de lino o vaqueros claros.
Paso 3: Incorporar texto o nombres con discreción
Si el objetivo es marcar una fecha importante o convertir la pieza en un regalo inolvidable, el texto debe integrarse con sutileza.
Al confeccionar una prenda de la gama de camisas personalizada , el minimalismo marca la pauta:
* **Detalles íntimos:** Unas iniciales bordadas en tono sobre tono en el dobladillo inferior, una fecha señalada en el interior del cuello o las coordenadas de un viaje memorable en el reverso de la botonadura.
* **Tipografías limpias:** Huye de las fuentes excesivamente recargadas; las tipografías rectas de estilo contemporáneo aportan sofisticación y mantienen la elegancia de la prenda.
Paso 4: Equilibrar recuerdo y uso cotidiano
El éxito de una camisa a medida reside en su versatilidad. Una prenda con valor sentimental no debe quedarse guardada en el armario tras una celebración especial; debe ser lo bastante cómoda y ponible como para acompañar al homenajeado durante toda la temporada estival.
Continúa descubriendo más sobre diseño textil
¿Te interesa conocer qué gramaje de lino es el más adecuado según el clima o cómo cuidar el tejido Tencel para prolongar su suavidad?
Viele Autofahrer verbringen wöchentlich viele Stunden im Fahrzeug – auf dem Weg zur Arbeit, bei Erledigungen oder auf längeren Urlaubsfahrten. Mit der Zeit wirkt das gewohnte Cockpit jedoch oft etwas eintönig oder zeigt erste Gebrauchsspuren. Um den täglichen Fahrkomfort spürbar zu steigern und dem Fahrzeug wieder eine frische Optik zu verleihen, ist kein teurer Werkstattbesuch nötig. Bereits mit wenigen, durchdachten Zubehörteilen lässt sich der Innenraum funktional und optisch aufwerten.
5 praktische Upgrades für ein besseres Raumgefühl
Kleine Anpassungen erzielen oft die größte Wirkung. Wer Wert auf Ergonomie, Ordnung und Atmosphäre legt, profitiert von folgenden Ausstattungs-Highlights:
1. **Ergonomisches Lendenkissen:** Unterstützt die natürliche Haltung der Wirbelsäule und beugt Verspannungen auf langen Strecken effektiv vor.
2. **LED-Ambientebeleuchtung:** Schafft bei Dämmerung und Dunkelheit eine angenehme, blendfreie Lichtstimmung im Fußraum oder an der Mittelkonsole.
3. **Universeller Handyhalter mit Qi-Ladefunktion:** Hält das Smartphone stets sicher im Sichtfeld für die Navigation und lädt den Akku kabellos während der Fahrt.
4. **Allwetter-Fußmatten:** Schützen den Fahrzeugteppich zuverlässig vor Nässe, Matsch sowie Schmutz und lassen sich mühelos reinigen.
5. **Individueller Sitzschutz:** Bewahrt die Polster vor Abnutzung und bildet das optische Herzstück eines modernisierten Interieurs.
Der Blickfang im Cockpit: Autositzbezüge selbst gestalten
Unter den vorgestellten Möglichkeiten sticht der Sitzschutz besonders hervor. Sitze beanspruchen die größte Fläche im Innenraum; ihr Zustand prägt den Gesamteindruck des Autos maßgeblich. Anstelle einheitlicher Standardware aus dem Baumarkt entscheiden sich immer mehr Fahrzeughalter dafür, Autositzbezüge Selbst Gestalten zu wollen.
Über benutzerfreundliche Konfiguratoren lässt sich das Design exakt an den eigenen Geschmack anpassen. Elastische, formbeständige Textilfasern wie Polyester gewährleisten dabei eine saubere Passform auf den meisten Fahrzeugsitzen. Gleichzeitig bleibt der Originalstoff der Sitze vor Flecken, UV-Einstrahlung und Abrieb geschützt – ein relevanter Faktor für den Werterhalt des Fahrzeugs.
Für wen lohnt sich die Personalisierung?
Ein individuell gestalteter Sitzbezug vereint praktischen Nutzen mit einer persönlichen Komponente, ohne kitschig zu wirken:
* **Tierhalter:** Besonders beliebt sind autositzbezüge mit foto des eigenen Hundes oder der Katze. Sie schützen die Polster vor Tierhaaren und Schmutzpfoten, während das eigene Tier symbolisch immer mit an Bord ist.
* **Pendler und Vielfahrer:** Dezente Muster, beruhigende Farbverläufe oder Initialen verwandeln eine funktionale Fahrerkabine in eine vertraute Umgebung, in der man gern Zeit verbringt.
* **Familien:** Wo Kinder mitfahren, passieren kleine Missgeschicke. Individuelle Schonbezüge fangen Krümel und Flecken ab, lassen sich leicht abnehmen und schonen die Nerven der Eltern.
* **Beschenkte:** Ein solches Zubehör eignet sich hervorragend als durchdachtes Geschenk zum Neuwagen oder bestandenen Führerschein.

Funktional, strapazierfähig und alltagstauglich
Ein ansprechendes Äußeres darf nicht zu Lasten der Praxistauglichkeit gehen. Wer Autositzbezüge Personalisiert auswählt, profitiert von pflegeleichten Materialien: Die elastischen Stoffe sind atmungsaktiv, lassen sich unkompliziert abziehen und in der Waschmaschine reinigen. Dadurch bleibt das Cockpit nicht nur optisch ein Unikat, sondern auch langfristig hygienisch sauber.
Fazit: Das Auto mit wenigen Handgriffen individualisieren
Die Kombination aus ergonomischen Helfern und maßgeschneidertem Sitzschutz macht jede Fahrt spürbar entspannter. Sie werten Ihr Fahrzeug optisch auf, schützen die Polster vor dem Alltag und setzen zugleich einen diskreten, ganz persönlichen Akzent.
Modulari e sostenibili: la nuova architettura a incastro
Il panorama dei dispositivi ad alta autonomia sta vivendo una trasformazione evidente, orientandosi verso soluzioni più responsabili e meno dispersive. In questo scenario si distingue la Vozol Star 50k, una proposta che ridefinisce il concetto di monouso attraverso una struttura modulare a innesto rapido. Il corpo macchina separa la cartuccia precaricata da 25 ml dalla base operativa con batteria ricaricabile da 1000 mAh. Con un semplice clic, il serbatoio si aggancia al modulo principale: una volta esaurito il liquido, non occorre smaltire l'intero blocco elettronico ma è sufficiente sostituire la ricarica aromatica, preservando la base per utilizzi successivi. Questa soluzione riduce l'impatto dei rifiuti elettronici e assicura un sensibile risparmio sui costi nel tempo.
Personalizzazione aromatica: doppia mesh e regolazione della freschezza
Oltre alla sua architettura a pod, il sistema offre un livello di controllo avanzato raramente riscontrabile nei formati ad altissima capienza. Grazie al circuito di vaporizzazione con tecnologia Dual Mesh e al display intelligente di monitoraggio, l'erogazione si adatta alle preferenze individuali tramite un pratico tasto multifunzione. Si può passare con un tocco da un profilo standard calibrato per raggiungere fino a 50.000 boccate a una modalità più energica da 35.000 tiri, ideale per chi cerca una densità di vapore più calda e corposa. A completare l'interazione interviene la gestione dedicata dell'effetto freddo (Ice Control), che permette di modulare l'intensità balsamica delle ricette fruttate in base al momento della giornata.
A chi si rivolge e come integrarla nella routine quotidiana
Per la sua natura a metà strada tra usa e getta e pod mod, la Vozol Star 50k si rivela indicata per gli utenti adulti che cercano la comodità immediata senza rinunciare alla flessibilità di una base riutilizzabile. Il design solido e privo di spigoli rende il dispositivo facile da portare con sé tra ufficio, tempo libero e viaggi, senza il timore di restare a secco o di dover maneggiare flaconi di ricarica. Inoltre, la possibilità di alternare gusti differenti semplicemente staccando e riagganciando cartucce diverse amplifica la versatilità quotidiana.
Vuoi conoscere da vicino tutte le specifiche tecniche e scoprire la gamma completa di profili aromatici disponibili? Visita le altre sezioni informative del nostro sito per leggere di più.
Prodotti che potrebbero interessarti:
Fumot 50k
Vozol Vape 50000
Nexa 50000
Große Einweg-E-Zigaretten mit hohen Zugzahlen versprechen langanhaltenden Dampfgenuss ohne ständiges Nachkaufen. Auf vielen Verpackungen prangt heute die Angabe von 20.000 Zügen. Für erwachsene Dampfer stellt sich dabei vor allem eine praktische Frage: Wie lange hält ein solches Gerät im Alltag tatsächlich durch? Die deklarierte Zugzahl basiert in der Regel auf standardisierten, sehr kurzen Laborzügen. Entscheidend für die reale Ausdauer ist jedoch nicht allein das Marketing, sondern das tatsächliche Füllvolumen an E-Liquid, das bei gängigen Modellen dieser Klasse meist zwischen 20 und 24 ml liegt.
Reale Nutzungsdauer: Was bedeuten 20 bis 24 ml Liquid?
Da das individuelle Dampfverhalten stark variiert, lässt sich die Haltbarkeit am besten über den täglichen Liquidverbrauch abschätzen. Je nach Zugtiefe und Häufigkeit reicht eine Füllung von über 20 ml für mehrere Wochen aus:
Nutzerprofil
Geschätzter Tagesverbrauch
Reale Nutzungsdauer
Gelegenheitsdampfer (moderate Züge)
ca. 1,0 ml pro Tag
etwa 20 bis 25 Tage (~ 3 Wochen)
Intensivnutzer (tiefere Lungenzüge)
ca. 1,5 bis 2,0+ ml pro Tag
etwa 10 bis 15 Tage (~ 2 Wochen)
Einfluss von Gerätemodi und Luftführung
Neben der Zugfrequenz spielt auch die verbaute Technik eine erhebliche Rolle beim Liquidverbrauch. Moderne Geräte bieten häufig unterschiedliche Betriebsmodi oder verstellbare Luftströme, um das Dampferlebnis anzupassen. Wer beispielsweise bei Modellen wie der Vozol Star 20k eine integrierte Leistungssteigerung (Power-Modus) aktiviert, erhält spürbar intensiveren Dampf, verbraucht das Liquidreservoir jedoch fast doppelt so schnell. Ähnlich verhält es sich bei Konstruktionen mit breiter Airflow: Eine offene Luftzufuhr, wie man sie bei der Fumot Tornado 20k findet, erzeugt zwar dichte Dampfwolken, beschleunigt jedoch gleichzeitig die Entleerung des Tanks.
Aromenvielfalt und Zugstil im Alltag
Ein zentraler Vorteil dieser Geräteklasse liegt in der Kombination aus kompakter Bauweise und großer Geschmacksauswahl. Für unterwegs entfällt das Mitführen separater Liquidflaschen. Allerdings beeinflusst auch das Aroma das Dampfmuster: Fruchtige Shisha-Geschmacksrichtungen, für die etwa die Adalya 20000 puffs vape bekannt ist, verleiten viele Nutzer zu längeren, tieferen Zügen. Ein solcher Konsumstil verkürzt die Gesamtzahl der Züge im Vergleich zu kurzen Mund-zu-Lunge-Zügen spürbar, liefert dafür aber ein gleichmäßig kräftiges Geschmacksprofil über die gesamte Nutzungszeit.
Fazit: Worauf es beim Kauf ankommt
Die Angabe von 20.000 Puffs dient primär als Orientierungswert. Wer eine zuverlässige Vape für Reisen, Freizeit oder den Arbeitsalltag sucht, sollte vor allem auf ein transparent angegebenes Liquidvolumen von mindestens 20 ml und einen wiederaufladbaren Akku achten. Möchten Sie mehr über die technischen Unterschiede moderner E-Zigaretten erfahren? Lesen Sie in unseren weiteren Ratgebern mehr zu aktuellen Modellen, Akkulaufzeiten und Aromenprofilen.
Sie könnten auch Folgendes mögen:
Al Fakher Crown Bar 15k Ice Adjust
JNR 18k
Shopee Live(虾皮直播)如今已经成为卖家进行商品展示、即时互动和促进成交的重要工具。相比传统商品页面,直播能够让消费者更直观地了解产品,同时结合限时优惠、优惠券、虾币奖励以及实时问答,提高用户停留与下单意愿。因此,直播间的观看人数、在线热度、互动频率和整体人气,也逐渐成为卖家衡量直播表现的重要参考。
不过,随着越来越多商家投入Shopee直播,想要在开播初期快速获得足够曝光已经不容易。即使提前准备好商品、价格优惠、直播脚本和场景布置,新账号或新店铺依然可能遇到在线人数偏低、互动不足、直播间缺乏热度等问题。尤其在刚开始经营时,如果直播间长期保持低人气,也可能降低新观众继续停留和参与互动的意愿。
因此,除了持续优化选品、优惠力度、直播节奏与开播时间之外,一些卖家也会关注 虾皮直播人数购买推荐 ,希望更快建立直播间的基础观看人数与社交证明。不过,Shopee直播增加人数并不是单纯追求数字越高越好,更应该关注观看质量、增长速度、稳定性以及服务可靠性。只有把基础人气与真正有吸引力的商品、优惠活动和直播内容结合起来,才能进一步提升互动表现与实际成交转化。

虾皮直播没人看, 购买 线上观看人数有用吗?
1.购买虾皮直播人数有用吗?
虾皮买直播人数当然有用,你今天来到虾皮直播卖商品,如果你的直播总是没人看,大家买你的东西一定会担心害怕;此时如果你购买一些线上观众,除了可以提升品牌形象,还能增加客人购买当下的信任度,所以买直播观看人数当然会有一定帮助,取决你怎么去使用它来对你的Shopee直播加分。
2.直播观看人数会激发更多价值
在这个时代流量为王道的时代,大量的直播观看人数可以说是最宝贵的资源。对于个人生活分享者而言,意味著自己与粉丝的黏著度很高,还能得到了更多人的关注;对于直播主、网红KOL而言,除了卖东西增加收入外,你还能得到更多的合作案以及流量;所以虾皮直播人数的多寡,更能决定你的网路影响力。
3.虾皮买直播观众会有被锁帐号的风险吗?
大部分买直播人数或是粉丝是不会被锁的,会被锁帐号通常是因为你的直播影片违反虾皮规则,才会可能被Ban的风险,因此你可以安心购买观看人数。
但是买虾皮直播人数最重要的是平台的品质,如果你买的观众总是容易掉线,那也会连带影响到你的品牌信誉,因此选择高品质的直播加人数平台,才能让你的直播人数稳定之外,还能得到更多客户的品牌信任度喔。
如果您对Instagram加观众有兴趣,可以参考这篇: 最新IG直播人数购买推荐全攻略

买Shopee冲直播观看人数会被发现吗?
1.如何有技巧地购买虾皮直播观众
虾皮直播人数大家只看的到有多少人,并不会看到观看直播的总共有哪些人,因此你可以放心地购买直播观众,人数越多,对于你的整场直播的帮助才会越大。
你可以选择在直播一开始,就马上增加自己的直播,这样5-20分钟内就能达到你期望的观看人数,一开始炒热气氛以及人气后,就能开始你的直播卖货重头戏啦!
2.选择高品质的直播加人数平台
很多厂商为了吸引客人,都是采取低价劣等直播服务来贩售,如果买了低端观众总是让你大掉粉的直播人数,对于你的帐号负面影响力是更大的,所以说选择稳定高质量的加观众平台非常重要!
比如说像粉丝王Fansking这个网站为华人最强大的虾皮加直播人数网站推荐,粉丝王只做高品质的直播观众及快速提升流量的服务,不管是增加Shopee直播人数、提升观看流量等,你都能以最优惠的价格,得到你想要的网路人气。
如果您对Youtube加观众有兴趣,可以参考这篇: 最新YT直播人数购买推荐全攻略

虾皮买直播人数的好处有哪些?
1.直播有人潮才会有钱潮
我们都知道人潮等于钱潮,当直播有一定的观看人数,除了代表直播主很有人气以外,当粉丝或网友看到你的大量直播观众,也会增加他们来看直播的意愿;而如果是卖东西的直播主就更明显了,越多的线上直播人数,越能增加你的人气,更能增加销售商品的转换率。
当大家都在卖货,剩下的真的就是看谁的虾皮直播观看人数多,越有人气的直播台,越能抢占先机,得到最多的流量以及业绩喔。
2.重点还是需要用心经营
短期内适当的加直播人数也许可以达到有效曝光,但是如果长期利用买观众而非优质内容去吸引更多的粉丝,那么将不利于该直播台的长期发展;最好的方式还是经营品牌的同时搭配加直播人数、观众流量等服务,才能让你的虾皮直播影响力事半功倍喔。
如果您对Facebook加观众有兴趣,可以参考这篇: 最新FB直播人数购买推荐全攻略

虾皮直播观众人数越多,会吸引更多人来观看吗?
1.直播人数越多,大幅增加曝光度
虾皮演算法会根据热门的直播,来让它进入为您推荐的品牌直播影片;如果直播人数很多,也会提升机率让你虾皮直播排在更前面,来让更多人看到你的直播,当你得到这些曝光,将能得到更多的自然流量,进而达到更多人来你的直播观看并购买。
2.Shopee线上直播观众数,决定你的成败
虽然说直播人数不是万能,但现在每天这么多直播台的竞争中,要快速地吸引粉丝观众,直播观看人数已经成为一个标配的数字了;如果今天你的直播台总是没什么人气,即使你再认真的做好直播,可能最终的结果也不符合你的预期。
因此你还是能专注做好你的直播,只要在每场直播的过程中,适度的搭配快速稳定的虾皮加直播人数平台,将会让你的直播更容易脱颖而出,进而达到事半功倍的 Fans 效果。
如果您对Twitch加观众有兴趣,可以参考这篇: 最新图奇直播人数购买推荐全攻略

虾皮直播人数如何快速增加,有推荐的加观众平台吗?
那么,什么才是Shopee直播人数购买的最好方法呢?粉丝王可以说是一个最好的解决方案。作为亚洲最大的买粉丝源头,Fansking可以提供虾皮冲直播人气、提升影片流量等多项精选服务,让客人能够以最优惠的价格取得最优质的服务,同时还能依据使用者的实际情况,客制化专属的社群服务 Line 。
快去使用 粉丝王加粉平台 ,24小时全年无休,随时随地都能都能增加你的虾皮直播人数、提升社群流量等,轻松掌握自己的网路直播影响力吧。
如果您对Tiktok加观众有兴趣,可以参考这篇: 最新抖音直播人数购买推荐全攻略

Twitch(图奇)作为全球知名的直播与游戏内容平台,已经从传统游戏实况逐步扩展到聊天、音乐、电竞、户外以及各种实时互动内容。对于主播和内容创作者来说,频道关注人数、平均观看人数、直播互动以及整体活跃度,都会影响新用户对频道人气与专业度的第一印象,也关系到后续的曝光与商业合作空间。
不过,随着Twitch主播数量持续增加,新频道想在前期快速获得关注并不容易。即使固定开播、提升画面与声音质量、认真与观众互动,如果缺少基础粉丝和观看人气,频道依然可能面临曝光不足、关注增长缓慢以及新观众留存困难等问题。尤其在竞争较高的游戏或热门直播分类中,如何建立初期人气基础,往往成为很多新主播最先需要解决的问题。
因此,除了持续优化直播内容、固定开播时间、经营Discord或其他社交平台之外,一些创作者也会关注 Twitch买粉丝人数推荐 ,希望更快建立频道的基础关注规模与社交证明。不过,图奇增加粉丝并不是单纯追求人数越多越好,更应该关注粉丝质量、增长速度、留存情况、账号稳定性以及后续真实互动。只有将基础人数增长与优质直播内容、稳定更新和长期社群运营结合起来,才能让Twitch频道获得更持续的发展。

Twitch买粉丝有用? 图奇买观众会有被锁的风险吗?
1.Twitch买粉丝人数有用吗?
买粉丝追随当然有用,如果你今天开台了,大家看到你的粉丝只有少少几个,一定会觉得你只是新手,可能不太值得追踪订阅;此时如果你购买一些粉丝人数,除了可以提升品牌形象,还能增加客人观看您直播实况的信任度,所以买订阅人数绝对有一定的帮助,取决你怎么去使用它来对你的图奇频道大大加分。
2.频道粉丝人数会激发更多价值
在这个时代流量为王道的时代,大量稳定的图奇粉丝数可以说是最宝贵的资源。一个好的Twitch频道,如果人数够多,绝对可以增加大家加入的意愿; 而且当游戏业者或者是业配厂商看到你拥有大量的粉丝族群,也会大大的提升你的接案机率。
3.图奇买直播观看人数会有被锁帐号的风险吗?
大部分买直播观众跟观看流量是不会被锁的,会被锁帐号通常是因为你的直播违反社群守则,才会可能被Ban的风险,因此你可以安心购买观众和流量。
一个频道最重要的就是粉丝追随者以及直播观众人数,拥有高品质的观众与流量,也会同更有机率让你的直播触及给更多人看到;因此选择快速稳定的Twitch加粉丝平台,更可以让你在经营频道的同时,大大的增加粉丝以及直播观看人数喔。
如果您对IG加粉丝有兴趣,可以参考这篇: 最新Instagram买粉丝推荐懒人包

Twitch买粉丝人数会被发现吗?
1.如何有技巧地购买图奇频道追随者
Twitch频道粉丝有哪些人,只有你自己看的到,一般网友只能看到你有多少粉丝数,所以你可以放心地加入你想要的追踪人数;而当你开直播的时候,购买适度的观看人数,也可以更有机会得让更多人看到你的实况喔。
2.选择高品质的加粉平台
很多厂商为了吸引客人,都是采取低价劣等机器人及流量来贩售,但买了低端服务很容易掉粉丝和观众,对于你的频道负面影响力是更大的,所以说选择稳定高质量的加粉平台非常重要!
比如说像粉丝王这个网站为华人最强大的加粉丝及观众人数推荐 网站 , Fansking 只做高品质的粉丝以及快速提升流量的服务,不管是增加Twitch粉丝追随者、 直播观看人数 等,你都能以最优惠的价格,得到你想要的网路人气。
如果您对推特加粉丝有兴趣,可以参考这篇: 最新Twitter买粉丝推荐懒人包

Twitch买追随者及直播观看优缺点大整理
1.增加品牌口碑与流量价值
随著Twitch频道粉丝的增长,在一定程度上可以很好地提升品牌的口碑,从而吸引更多真实的粉丝来订阅,有利于为建立稳定的追随者打下良好基础。如果属于业务拓展型使用者,那优势则更加明显,因为数字依旧可以作为考量网红影响力的重要指标,这样可以吸引到更多有价值的业配以及合作来洽谈。
拥有一定的图奇粉丝人数及直播观看流量,对于你在异业合作或者是接案业配,都能拥有更好的合作以及信任度,更能让你的业绩以及收入蒸蒸日上喔。
2.重点还是需要用心经营
短期内适当的买粉丝和流量行为也许可以达到有效曝光,但是如果长期利用买粉而非优质内容去吸引更多的粉丝,那么将不利于该频道的长期发展;最好的方式还是经营内容的同时搭配加粉丝追踪、直播观众等服务,才能让你的Twitch品牌 Fans 影响力事半功倍喔。
如果您对DC加群组人数有兴趣,可以参考这篇: 最新Discord购买伺服器成员推荐懒人包

到底要怎么买Twitch人数,有推荐的加粉丝平台吗?
那么,什么才是购买图奇频道粉丝的最好方法呢?粉丝王可以说是一个最好的解决方案。作为亚洲最大的买粉丝源头,Fansking可以提供Twitch频道粉丝追随者、直播观众人数、以及影片观看流量等多项服务购买,让客人能够以最优惠的价格取得最优质的服务,同时还能依据使用者的实际情况,客制化专属的社群服务 Line 。
快去使用 粉丝王加粉平台 ,24小时全年无休,随时随地都能都能增加你的Twitch粉丝数、直播观重及影片流量,赶快轻松掌握自己的网路社群影响力吧。
如果您对抖音加流量有兴趣,可以参考这篇: 最新Tiktok购买观看次数推荐懒人包

原文连结: 最强Twitch买追随人数推荐,图奇快速增加直播机器人观众优惠懒人包!
本篇所有内容皆由Fansking粉丝王团队原创文章,仅供学习社群行销资讯参考,未经许可不得转载,翻印必究。