

Blogs
Polymer Capacitor Market at 8.2% CAGR: What 2032 Growth and Consumer Electronics Demand Really Signal
By PW Consulting, 2026-09-21
The Polymer Capacitor Market: Strategic Trends and Commercial Opportunities Through 2032
The global polymer capacitor market stands at a pivotal inflection point. From 2020 to 2025, total market revenue expanded from approximately 163.15 million to 215.0 million, reflecting steady growth across multiple end-use sectors. Looking ahead, the trajectory accelerates, with the market projected to reach 344.8 million by 2032, delivering a compound annual growth rate of 8.2 percent over the 2026 to 2032 forecast period. These numbers signal more than incremental expansion; they reflect a structural shift in how electronics manufacturers, automotive system designers, and industrial equipment engineers approach power management and signal integrity.
Beneath the headline figures lies a fragmented yet increasingly strategic competitive arena. The top three players collectively account for 24.6 percent of market revenue, while the top five capture 26.2 percent. This moderate concentration suggests room for differentiation, regional specialization, and technology-led positioning rather than pure scale dominance. For executives and investors evaluating the space, the question is no longer whether polymer capacitors will grow, but which sub-segments, applications, and supply chain strategies will capture disproportionate value as the market matures.
Market Dynamics and Structural Challenges
The polymer capacitor sector operates within a broader passive component ecosystem that is simultaneously experiencing demand surges, material constraints, and tightening qualification standards. Three interconnected challenges define the current landscape and will shape competitive outcomes over the next several years.
Balancing Miniaturization With Reliability Expectations
Design engineers across consumer electronics, automotive, and industrial applications continue pushing for smaller form factors while demanding higher ripple current tolerance, lower ESR, and extended operational lifespans. Polymer capacitors inherently address many of these requirements through conductive polymer electrolyte technology, but the pressure to reduce profile dimensions without compromising thermal stability or moisture resistance creates genuine engineering tension. Manufacturers that can deliver low-profile solutions while maintaining certification-ready performance metrics gain a clear advantage in qualification cycles and design-in opportunities.
PW Consulting Information & Electronics Research Center
Material Cost Volatility and Pricing Pressures
Cost structures across the passive component supply chain have faced sustained upward pressure, particularly in tantalum-based polymer lines. Industry pricing adjustments took effect in mid-2024 as manufacturers cited rising material input costs, and those dynamics have persisted into subsequent quarters. For product planners and procurement teams, this translates into longer hedging windows, tighter inventory buffers, and increased sensitivity to raw material availability. Suppliers with vertically integrated material strategies or diversified polymer formulations are better positioned to manage margin erosion while maintaining competitive pricing.
Qualification Rigor and Customer-Specific Validation Cycles
Automotive and high-reliability industrial applications now require stricter validation protocols. Compliance with AEC-Q200 qualification remains a baseline expectation for automotive polymer capacitors, ensuring consistent performance in electric vehicle power systems and related subsystems. Beyond automotive, industrial-grade polymer products increasingly face moisture-resistance benchmarking at elevated temperature and humidity conditions over extended durations. These qualification thresholds extend time-to-market for new part numbers and raise the barrier for generic commodity players. Companies that invest early in robust qualification dossiers and maintain transparent reliability data shorten customer design cycles and strengthen long-term supply agreements.
Supply chain timing further complicates planning. Across all capacitor technologies, average lead times have hovered around 19 weeks as of late 2025, reinforcing the importance of stable production scheduling and proactive capacity alignment. For buyers, this means demand forecasting and supplier diversification are no longer optional procurement best practices; they are operational necessities.
Core Drivers Shaping Market Trajectory
Several overlapping forces explain why polymer capacitors are capturing growing share across multiple end markets. Understanding these drivers helps decision-makers distinguish structural growth from cyclical demand swings.
Technology Innovation and Form-Factor Engineering
The most visible product-level evolution centers on profile reduction, thermal endurance, and ripple current performance. Recent commercial introductions illustrate how manufacturers are aligning advanced materials with application-specific constraints. In late 2025, Panasonic Industry began commercial production of conductive polymer tantalum solid capacitors with an industry-leading 3 mm profile, targeting USB Type-C power delivery architectures where space and current handling are equally critical. Around the same period, Taiyo Yuden commercialized hybrid aluminum electrolytic capacitor series engineered for higher rated ripple current and reduced profile, specifically addressing automotive ADAS and power steering applications. These launches reflect a broader pattern: manufacturers are not simply scaling existing designs, they are engineering product families around real-world system constraints such as board space, thermal environment, and power delivery topology.
Nichicon’s recent activity reinforces this trend from a thermal-reliability angle. The company introduced a highly heat-resistant conductive polymer hybrid aluminum electrolytic series capable of sustaining 4000 hours at 135°C, alongside automotive-rated hybrid capacitor series distributed across EMEA channels. High-temperature endurance directly supports automotive under-hood and near-power-electronics placements, where long-term degradation profiles determine component selection. Similarly, Nichicon’s broader portfolio emphasis on conductive polymer hybrid aluminum electrolytic and solid capacitors with elevated temperature ratings signals a strategy centered on reliability differentiation rather than cost-only competition.
Application-Side Demand Transformation
Consumer electronics remain the largest application anchor for polymer capacitors, driven by compact power systems, wireless charging, high-density motherboard designs, and ever-increasing power conversion requirements in portable devices. However, the most strategically significant demand shift is occurring in automotive electrification and advanced driver-assistance architectures. As vehicle power systems become more complex and electronics content per platform rises, polymer capacitors are increasingly integrated into DC-DC conversion stages, noise filtering networks, and decoupling arrangements that must tolerate fluctuating thermal and vibration environments.
Industrial automation, renewable energy inverters, and high-reliability infrastructure equipment also contribute to demand diversification. These sectors prioritize long service life, stability under continuous load, and qualification documentation over lowest-unit-cost sourcing. The result is a demand landscape that rewards suppliers capable of matching application-specific performance profiles, not merely volume capacity.
Regulatory, Qualification, and Standardization Pressure
Qualification frameworks and environmental reliability benchmarks increasingly shape purchasing decisions. AEC-Q200 continues to serve as the foundational reliability standard for automotive-grade polymer capacitors, while industrial product expectations have evolved toward stricter moisture and thermal endurance testing. These standards create a two-tier market dynamic: commodity-grade applications tolerate broader performance variance, while automotive and industrial buyers reward proven qualification records and traceable reliability data.
Standardization also influences supply chain behavior. When qualification requirements become more uniform across tier customers, manufacturers with established validation infrastructure gain efficiencies in documentation, testing throughput, and customer onboarding. Those without dedicated qualification capabilities face longer approval timelines and higher rejection risk, particularly in safety-related or mission-critical subsystems.
Supply Chain Resilience and Material Strategy
Recent pricing actions across tantalum-based polymer capacitors underscore the importance of material resilience. Rising input costs have prompted manufacturers to reassess sourcing strategies, formulation alternatives, and inventory positioning. At the same time, lead time elongation across capacitor technologies has reinforced the value of multi-source arrangements and forecast-aligned production planning.
For incumbent suppliers, the response has included hybrid capacitor architectures that combine conductive polymer benefits with aluminum electrolytic structural familiarity, offering a balance of performance and manufacturability. For buyers, this environment emphasizes the need to evaluate not only unit price but also manufacturing continuity, qualification coverage, and the supplier’s ability to sustain availability through cost cycles.
Competitive Landscape and Strategic Positioning
The polymer capacitor market features a mix of established Japanese manufacturers, U.S.-based specialty players, European component specialists, and Taiwan-based producers with regional manufacturing advantages. Despite moderate top-tier concentration, competitive differentiation is increasingly driven by product architecture, application targeting, and qualification readiness rather than broad commoditization.
KYOCERA AVX Components Corporation has positioned itself around conductive polymer solid electrolytic capacitors with notable attention to automotive and high-reliability segments. Its portfolio includes TCO and TCQ automotive series, high-reliability hermetically sealed polymers, and COTS+ military-grade tantalum polymer lines. This mix suggests a strategy that leans into reliability-grade differentiation and application-specific series development rather than volume-only competition.
Panasonic Industry Co., Ltd. maintains a broad polymer capacitor portfolio spanning conductive polymer aluminum electrolytic, tantalum solid, aluminum solid, and hybrid aluminum electrolytic capacitors. Its recent product activity emphasizes profile reduction for power delivery applications, aligning with consumer and computing trends that prize compact form factors without sacrificing current-handling capability.
Murata Manufacturing Co., Ltd. continues to leverage its broader passive component ecosystem, offering conductive polymer aluminum electrolytic and solid capacitors for automotive, industrial, and high-reliability applications. The company’s positioning benefits from integration with adjacent component categories and a strong design-in support structure across multiple end markets.
Nippon Chemi-Con Corporation has expanded its polymer capacitor emphasis through high-voltage series, liquid immersion cooling-oriented series, and hybrid models. The inclusion of high-voltage and cooling-specific product lines indicates attention to power electronics and industrial applications where voltage stress and thermal management are key selection criteria.
Nichicon Corporation has pursued a reliability-led strategy, highlighting conductive polymer hybrid aluminum electrolytic and solid capacitors with high-temperature ratings. Its recent automotive-rated series and heat-resistant product introductions reinforce a focus on application-grade durability, particularly relevant for automotive and industrial environments with sustained thermal exposure.
Rubycon Corporation and Lelon Electronics Corp. provide conductive polymer aluminum electrolytic solutions for general and automotive use. Their market roles illustrate how regional and mid-tier manufacturers compete by combining cost-competitiveness with targeted application support, rather than attempting to match the broadest portfolio breadth of larger incumbents.
Vishay Intertechnology, Inc. extends its presence through polymer tantalum and aluminum solid electrolytic capacitors for industrial, automotive, and aerospace applications. Its positioning reflects the demands of sectors where qualification rigor, material traceability, and reliability documentation carry significant commercial weight.
Würth Elektronik GmbH & Co. KG competes with aluminum polymer electrolytic capacitors and radial series, aligning with the broader European component distribution and design ecosystem. ROHM Co., Ltd. rounds out the competitive field with polymer tantalum and aluminum solid electrolytic capacitors following integration of related business assets, indicating continued consolidation and portfolio rationalization across the sector.
Several competitive themes emerge from this landscape. First, differentiation is shifting from generic capacitance ranges toward application-optimized families with defined thermal, profile, and ripple current characteristics. Second, hybrid architectures are gaining prominence because they combine polymer-level ESR and ripple performance with structural and manufacturing familiarity. Third, the market is unlikely to consolidate rapidly into a single dominant structure; instead, it will likely evolve into a tiered ecosystem where automotive and high-reliability applications favor qualified incumbents, while consumer and general-purpose segments remain more price-sensitive and accessible to multiple suppliers.
Recent product introductions also suggest that regional channel strategies matter. Automotive-rated series launched across EMEA channels highlight the importance of localized qualification support, distribution partnerships, and application engineering availability. Suppliers that can demonstrate consistent technical support across geographies are better positioned to secure design wins in regions where automotive and industrial sourcing decisions are highly relationship and qualification driven.
Forward Outlook: Trends and Opportunities Through 2032
Extrapolating current growth dynamics, qualification momentum, and product innovation patterns points to several interrelated trends that will shape commercial opportunities over the next three to five years.
Trend 1: Application-Specific Polymer Capacitor Families Will Displace One-Size-Fits-All Sourcing
As system designers face tighter thermal envelopes, higher power densities, and more demanding reliability thresholds, generic capacitor specifications will become less persuasive. Buyers will increasingly evaluate parts against application-level benchmarks such as thermal endurance, ripple current capability, profile constraints, and qualification documentation. Suppliers that publish clear application 매핑 and maintain robust reliability data will capture more design-ins, particularly in automotive and industrial segments where failure cost is high.
Commercial opportunity: Companies that invest in application engineering, reference designs, and qualification-ready documentation can shorten customer evaluation cycles and build longer-term supply relationships. This creates a defensible position even in a moderately concentrated market.
Trend 2: Hybrid and Advanced Polymer Formulations Will Broaden Performance Windows
Hybrid aluminum electrolytic structures and advanced conductive polymer formulations will continue to expand the balance between ESR reduction, temperature stability, and manufacturability. These architectures are particularly relevant where designers need polymer-level electrical performance without abandoning aluminum-based mechanical or cost advantages. The ongoing appearance of hybrid-oriented product launches supports the view that this direction is not a niche experiment but a mainstream performance strategy.
Commercial opportunity: Product planners should monitor hybrid and advanced polymer lines as potential candidates for next-generation power delivery, noise filtering, and decoupling designs. Early engagement with suppliers offering these architectures can provide first-mover advantages in demanding applications.
Trend 3: Automotive Electrification and High-Reliability Industrial Demand Will Drive Sustained Volume Growth, With Qualification as the Gatekeeper
Conductive Polymer Aluminum Solid Capacitors Market
The 8.2 percent CAGR projected through 2032 reflects more than cyclical replacement demand; it reflects a structural increase in electronics content across vehicles, industrial equipment, and energy-related infrastructure. Automotive platforms in particular will continue placing higher capacitor content per vehicle as power management architectures grow more decentralized and more performance-critical. At the same time, qualification requirements will remain the commercial gatekeeper, meaning that volume growth will disproportionately flow to suppliers with credible reliability records and efficient validation processes.
Commercial opportunity: Suppliers that build automotive and industrial qualification capabilities early can secure longer design cycles and multi-program visibility. For buyers, prioritizing qualification readiness and supply continuity over short-term unit cost can reduce downstream risk in safety-related or mission-critical designs.
Vacuum Capacitor Market
Risk and Uncertainty Considerations
Several uncertainties could alter this trajectory. Material cost volatility may persist, affecting tantalum-based and other polymer lines unevenly. Lead time normalization is not guaranteed; supply disruptions, capacity constraints, or sudden demand shifts could reintroduce planning friction. Qualification expectations may continue to tighten, compressing timelines for new entrants and rewarding incumbents with established testing infrastructure. Finally, competitive overcapacity in certain commodity-grade segments could pressure pricing, even as qualified automotive and industrial segments remain more resilient. Decision-makers should therefore treat the polymer capacitor market as a portfolio of differentiated sub-segments rather than a single homogeneous opportunity.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities in this environment. The following actions are designed to translate market dynamics into executable planning.
For Manufacturers and Component Suppliers
- Prioritize application-specific product families that address profile, thermal endurance, and ripple current requirements simultaneously rather than competing solely on capacitance range or unit cost.
- Strengthen qualification documentation and reliability data packages, especially for automotive and industrial customers where AEC-Q200 and extended environmental testing are baseline expectations.
- Evaluate hybrid and advanced polymer formulations as a way to expand performance differentiation while maintaining manufacturability and cost discipline.
- Align production planning and inventory strategy with current lead-time realities, and consider multi-source options where qualification and performance allow.
For Investors and Strategic Allocators
- Focus due diligence on suppliers with credible automotive and high-reliability qualification footprints, because those segments are likely to capture disproportionate value even in a moderately concentrated market.
- Assess exposure to material cost sensitivity and pricing actions across tantalum and aluminum polymer lines, and weigh vertical integration or formulation diversification as risk-mitigation indicators.
- Watch for portfolio consolidation and asset integration activity that may reshape competitive positioning, especially where adjacent business assets are combined to strengthen polymer capacitor capabilities.
For Procurement, Engineering, and Supply Chain Leaders
- Treat qualification status, thermal performance, profile constraints, and supply continuity as core evaluation criteria alongside price, particularly for automotive and industrial designs.
- Diversify approved sources where application requirements permit, while maintaining clear qualification thresholds to avoid fragmented validation burden.
- Engage suppliers early in the design phase to align on reliability testing, documentation, and lead-time expectations, reducing the risk of late-stage redesign or sourcing disruption.
The polymer capacitor market is expanding with clarity in direction but complexity in execution. Growth will continue toward 344.8 million by 2032, but the value capture will depend on how well companies align product engineering, qualification readiness, and supply resilience with the application needs that matter most. For organizations seeking deeper segmentation data, regional positioning detail, and tailored strategy recommendations, the full PW Consulting research report provides the granular breakdown and scenario analysis needed to convert these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Textile Chemicals Market 2026: Beyond the 4.8% CAGR and Asia Pacific’s $15.4B Pull
By PW Consulting, 2026-09-21
The Textile Chemicals Market: Strategic Shifts and Commercial Opportunities Through 2032
The textile chemicals sector has entered a phase of structural recalibration. After a decade of steady volume growth underpinned by expanding apparel production and industrial fabric consumption, the market is now being reshaped by tighter environmental mandates, evolving consumer expectations, and technological breakthroughs that are redefining how fibers are treated, dyed, and finished. For executives, investors, and procurement leaders, the central question is no longer whether demand will grow, but where value will concentrate and which capabilities will separate winners from laggards in the coming years.
The global market for textile chemicals has reached a valuation of approximately 30 billion USD in 2025, representing a measured acceleration from roughly 21.5 billion USD in 2020. Over the 2020 to 2025 period, revenue expanded at a compound trajectory that reflects both post-pandemic recovery and the steady integration of chemical solutions across garment, home textile, and technical fabric supply chains. Looking ahead to 2032, the market is projected to surpass 41 billion USD, driven by a compound annual growth rate averaging 4.8 percent. While this growth rate signals resilience, it also indicates that the era of unconstrained volume expansion is giving way to a more selective, regulation-aware, and performance-driven landscape. Value creation will increasingly depend on how effectively companies navigate compliance complexity, capture premium segments, and align product portfolios with sustainability and circularity mandates.
Market Reality and Critical Inflection Points
The headline growth figures mask underlying tensions that are already reshaping competitive dynamics. Three interlocking challenges define the current inflection point for the sector.
First, regulatory intensity is shifting from voluntary best practices to enforceable, auditable standards. Chemical input approval criteria, substance restriction lists, and wastewater discharge targets are no longer confined to niche certifications. They are cascading through procurement contracts, brand compliance programs, and regional market access requirements. Companies that treat compliance as a retrospective documentation exercise are finding themselves locked out of premium accounts or forced into costly reformulation cycles. The regulatory wave is compressing margins for undifferentiated products while rewarding firms that have built formulation transparency and substitution capability into their R&D workflows.
Second, the cost and availability of conventional chemical building blocks remain structurally uncertain. Feedstock volatility, energy price swings, and shifting trade flows have disrupted the predictability that many formulators relied on for cost planning. At the same time, the transition toward lower-impact and bio-based alternatives introduces new input economics that can be higher in the short term. The practical consequence is that pricing strategies based solely on historical material costs are increasingly brittle. Businesses that succeed are those that combine multi-source sourcing, formulation flexibility, and service-level agreements that share risk more intelligently across the value chain.
Textile Dyes Market
Third, customer expectations are bifurcating the market. Mass-market segments continue to pressure suppliers for cost efficiency and reliable delivery, while premium and performance-oriented segments demand demonstrable environmental attributes, functional performance in demanding applications, and traceability. This polarization makes portfolio strategy decisive. Suppliers that attempt to serve all segments with a uniform offering risk being commoditized in the low end while failing to capture the margin in the high end. Those that can clearly segment their value proposition, back claims with verified data, and align service models accordingly are better positioned to defend pricing and deepen customer relationships.
Key Drivers Reshaping the Landscape
Understanding where growth and margin will concentrate requires looking past top-line volume to the forces that are changing how textile chemicals are developed, approved, and deployed.
Technological innovation and formulation breakthroughs. Advances in low-temperature dyeing, enzyme-assisted pretreatment, waterless or reduced-water finishing, and digital color matching are steadily reducing resource intensity while improving reproducibility. Digital tools are also enabling faster formula optimization and more precise dosing, which directly lowers wastewater load and chemical waste. These innovations matter commercially because they translate environmental performance into operational savings that customers can verify. Suppliers that embed these capabilities into ready-to-adopt process packages, rather than offering only raw ingredients, are building stickier relationships and gaining pricing power.
Policy and regulatory environment. The regulatory framework is tightening across multiple jurisdictions, with substance restrictions, organic textile chemical criteria, and endocrine disruptor limits all moving toward stricter thresholds and broader coverage. Recent updates to major standards have introduced lower limits for certain substances, expanded the list of regulated compounds, and added mandatory due diligence expectations for chemicals used in organic fiber production. In parallel, regional legislation targeting specific chemical families in textiles, clothing, footwear, and waterproofing agents has moved into force or toward implementation, with exemptions limited to specific recycled or industrial use cases. For suppliers, the strategic implication is clear: product stewardship is now a market-access requirement. Formulation roadmaps must anticipate substitution needs, documentation must meet audit expectations, and technical support must help customers navigate compliance without disrupting production.
Demand-side behavior. Brands and manufacturers are increasingly tying procurement decisions to measurable sustainability outcomes and risk reduction. Consumer-facing claims are being scrutinized more closely, which pushes upstream suppliers to provide credible, standardized evidence rather than marketing narratives. At the same time, the rise of technical textiles and high-performance applications is expanding demand for chemicals that deliver specific functionalities such as durability, moisture management, antimicrobial action, or flame resistance, often with tighter environmental profiles. This dual pressure rewards suppliers that can combine performance with verifiable attributes and that can support customers in meeting both internal targets and external claims.
Supply chain and cost structure realignment. Geographic concentration of production, logistics bottlenecks, and evolving trade dynamics have encouraged buyers to diversify sources and favor suppliers with regional presence or strong distribution networks. Distributors and integrated suppliers that can guarantee continuity, offer technical troubleshooting, and consolidate multiple chemical needs into a single interface are gaining importance, particularly for smaller and mid-sized processors. The cost structure is also being reshaped by the premium attached to compliant, lower-impact chemistries and by the operational savings that come from more efficient application processes. Businesses that can articulate total cost of ownership rather than unit price are better equipped to navigate these shifts.
The Competitive Field: Positioning, Differentiation, and Evolution
The market remains moderately concentrated, with the largest players holding a meaningful share of total revenue while significant space remains for specialized and regional players. This structure favors a dual strategy: scale players compete on broad portfolios, global reach, and technical service infrastructure, while specialists compete on deep application knowledge, niche performance attributes, and agility in formulation.
Fine Chemicals Market
Archroma occupies a prominent position as a global provider of sustainable dyes, colorants, and performance chemicals tailored to dyeing, finishing, and printing applications. Its differentiation rests on a strong sustainability narrative backed by product development focused on reduced environmental impact and process efficiency, combined with the ability to serve large, multi-site customers with consistent standards.
Huntsman Textile Effects, with operations spanning Switzerland and Germany, focuses on functional dyes, finishing chemicals, and performance solutions. Its strength lies in blending application expertise with high-performance outcomes, allowing it to address demanding end-use requirements while supporting customers in meeting quality and compliance expectations.
CHT Group, based in Germany, specializes in textile chemicals, auxiliaries, and dyeing solutions for printing, finishing, and processing. Its positioning emphasizes depth in application know-how and a focused specialty portfolio, which enables close collaboration with processors seeking tailored solutions rather than broad commodity offerings.
Azelis operates as a distributor and integrated supplier across dyes, bleaching agents, pretreatment chemicals, and finishing solutions. Its competitive advantage comes from network reach, inventory continuity, and the ability to bundle technical support with supply reliability, an increasingly valuable proposition for customers managing complex compliance and sourcing requirements.
On the Asia-centric side, NICCA Chemical stands as Japan's leading developer and manufacturer of scouring, dyeing, and finishing chemicals, leveraging strong process expertise and a reputation for quality and reliability. Sarex Chemicals and Fineotex Chemical, both based in India, contribute specialist coverage across auxiliaries, pretreatment, dyeing, printing, and finishing. Their relevance lies in serving full value-chain needs with regional cost structures, local technical presence, and the ability to support high-volume production environments that demand consistent availability and practical process support.
The competitive landscape is evolving along three trajectories. Consolidation continues to favor larger players that can integrate R&D, compliance documentation, and global service delivery, particularly as customers seek fewer, more accountable partners. At the same time, fragmentation remains viable for specialists that can dominate specific application niches, offer differentiated performance, or provide rapid regional responsiveness. A third dynamic is the growing role of events and platforms that concentrate the industry's attention on chemicals and dyes. The launch of a dedicated Textile Chemicals and Dyes product segment at a major international trade fair, featuring more than 30 exhibitors across dyes, auxiliaries, functional finishes, and polymer technologies, signals that chemical solutions are being elevated from supporting inputs to strategic showcase categories. Early booking windows and confirmed participation from established players further indicate that the segment is becoming a focal point for partnership formation, product launches, and market signaling. Regional expos centered on textile chemicals and auxiliaries continue to reinforce the importance of Asia as both a manufacturing base and a sourcing hub, where proximity, cost, and technical support intersect.
Forward Outlook: Three Trends Shaping 2026 to 2032
The combination of regulation, technology, and demand evolution points to a set of trends that will define commercial opportunities over the next several years.
Compliance-driven reformulation will become a recurring revenue stream rather than a one-time project. As substance restrictions tighten, due diligence expectations expand, and wastewater guidelines grow more prescriptive, processors will need ongoing support to maintain market access. This creates sustained demand for alternative chemistries, testing support, documentation services, and process adjustments. The commercial opportunity lies not only in new molecules but in service architectures that help customers stay ahead of change. Suppliers that anticipate regulatory trajectories and pre-develop substitute portfolios will capture switching demand before competitors react. The risk is that compliance becomes a reactive cost center if firms lack foresight, leading to rushed substitutions, production disruptions, and eroded trust.
Performance and sustainability will increasingly converge in premium segments. Functional finishes, durable properties, and reduced-impact processing are moving from separate considerations to combined requirements. Customers want chemicals that deliver specific end-use performance without undermining environmental targets, and they expect evidence that can satisfy both internal procurement criteria and external claims. This convergence favors suppliers that can bundle functional chemistry with application engineering and verified attribute data. The upside is margin expansion in segments where differentiation is defensible. The uncertainty is that verification standards and claim scrutiny will continue to rise, which raises the bar for substantiation and can slow adoption if proof points are weak.
Regional service models and distribution strength will matter as much as product formulations. As procurement teams diversify sourcing and tighten continuity requirements, the ability to deliver reliably, troubleshoot locally, and consolidate multiple needs into a coherent package becomes a differentiator. Distributors and integrated suppliers with strong regional footprints can reduce risk for processors that cannot manage complex multi-supplier relationships across borders. This trend supports growth for players that invest in local technical presence, inventory resilience, and responsive service. The downside is that building and maintaining such networks requires capital and operational discipline, and players that over-extend geographically without adequate support infrastructure may struggle to convert reach into profitable relationships.
Strategic Imperatives for Decision-Makers
The choices made over the next twelve to twenty-four months will shape competitiveness through the end of the decade. The following actions are most relevant across the main stakeholder groups.
PW Consulting Information & Electronics Research Center
For manufacturers and formulators. Build a reformulation pipeline that maps current product portfolios against anticipated regulatory thresholds and customer sustainability expectations. Prioritize formulations that lower water, energy, and waste intensity while maintaining or improving performance, because these solutions convert environmental goals into operational savings that customers can measure. Strengthen documentation, testing, and traceability so that claims can withstand audit scrutiny. Segment the portfolio clearly between cost-competitive essentials and premium performance or sustainability-led offerings, and align sales and technical service teams accordingly so that each segment is supported with the right value narrative and service model.
For investors. Favor business models with defensible differentiation: proprietary formulations paired with verified attributes, strong compliance capability, and regional service reach. Assess exposure to regulatory risk by examining how dependent revenue is on substances likely to face tighter limits, and evaluate whether the company has substitution roadmaps and credible alternatives. Look for evidence that environmental performance is being integrated into product design rather than treated as a separate initiative, since this integration increasingly determines access to premium accounts. Monitor distribution partnerships and technical service capacity, because continuity and support can be the deciding factor in procurement decisions for processors facing compliance and sourcing complexity.
For procurement and buying organizations. Treat chemical selection as a risk-management and total-cost decision rather than a unit-price exercise. Evaluate suppliers on formulation transparency, compliance readiness, substitution capability, and the ability to support process efficiency improvements that reduce resource use and waste. Encourage multi-year collaboration with key suppliers so that reformulation, testing, and documentation can be planned in advance rather than triggered by emergency compliance events. Prioritize suppliers that can provide standardized evidence packages aligned with the certifications and standards relevant to your markets, because this reduces downstream verification friction and strengthens your own claims.
Timely, granular intelligence is essential for executing these actions with precision. Market-level growth rates and segment sizes provide useful context, but the decisions that determine competitive advantage depend on how specific regulations will affect product lines, where substitution demand is emerging earliest, which applications are capturing premium margins, and how distribution and service models are shifting in key regions. A complete research report offers the detailed segmentation, company benchmarking, regulatory mapping, and scenario-based forecasts needed to translate these dynamics into concrete plans. It also provides the granular data and customized recommendations that allow decision-makers to prioritize initiatives, assess risk exposure, and identify the most actionable opportunities for their specific portfolio and geography.
For detailed analysis of this topic, please visit the official page: Textile Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nel mercato attuale dei dispositivi monouso a grande autonomia, la soglia delle decine di migliaia di boccate è diventata il nuovo standard per gli utenti che cercano praticità e lunga durata. Tuttavia, quando si parla di cifre elevate come le 60.000 boccate pubblicizzate, è utile comprendere che tali stime si basano generalmente su modalità di utilizzo a basso consumo energetico. Due dei modelli più discussi in questa categoria offrono prestazioni e filosofie costruttive profondamente differenti, pensate per soddisfare aspettative e stili di svapo del tutto peculiari.
Da un lato, il modello Vozol Neon 60k punta con decisione sull'equilibrio tra autonomia energetica e controllo del liquido. Grazie a una batteria capiente da 1100mAh e a un serbatoio fisico trasparente che permette di tenere sempre sotto controllo il livello residuo, questo dispositivo assicura una gestione molto regolare. L'integrazione di tre livelli di regolazione e di una doppia bobina a rete intelligente consente di passare facilmente da uno stile di tiro più chiuso a uno più aperto, ottimizzando i consumi e avvicinando l'esperienza complessiva al limite massimo dichiarato.
Dall'altro lato, Al Fakher Crown Bar 60k adotta un approccio orientato alla potenza e alla tradizione del fumo denso. Equipaggiato con una batteria da 850mAh compatibile con la ricarica rapida e un sistema progettato per offrire un tiro polmonare diretto in stile narghilè, questo dispositivo privilegia l'intensità aromatica e la corposità del vapore. La struttura a bassissima resistenza assicura una resa eccezionale in termini di sapore, sebbene l'uso continuo di svapo profondo possa incidere in modo più marcato sulla durata effettiva complessiva rispetto a un profilo più moderato.
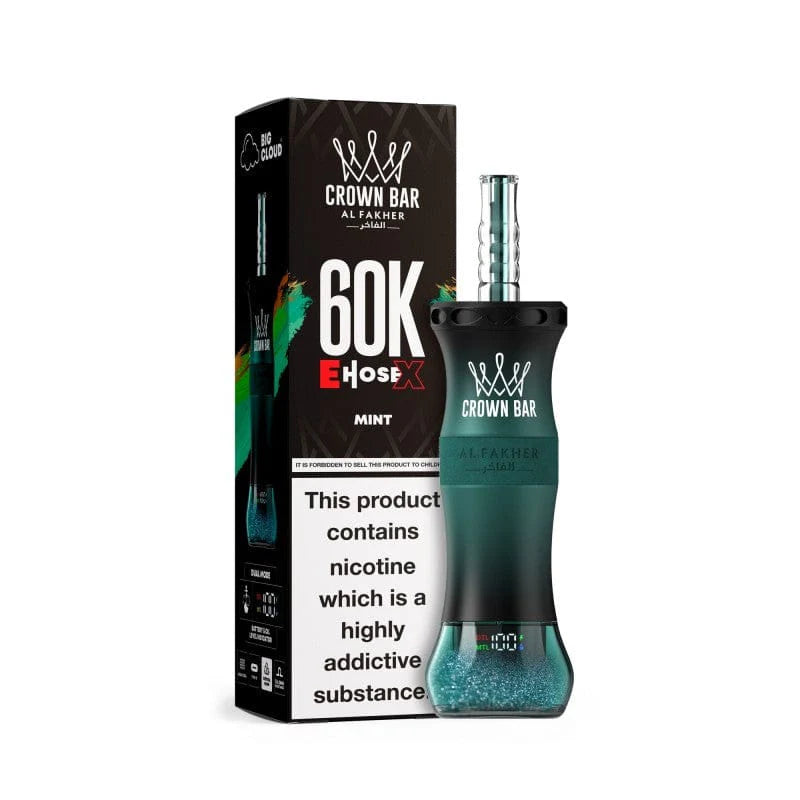
La scelta tra questi due giganti dipende interamente dalle abitudini personali: chi predilige la durata prolungata della batteria e un controllo visivo costante troverà nel primo un ottimo compagno quotidiano, mentre chi cerca densità di vapore e richiami al gusto tradizionale preferirà la spinta del secondo. Per valutare nel dettaglio quale soluzione si adatti meglio alle tue esigenze di portabilità e selezione dei gusti, ti invitiamo a scoprire di più sulle schede tecniche dei prodotti. Leggi di più sui test di autonomia e sulle caratteristiche delle novità del settore.
Mit Kapazitäten von bis zu 50.000 Zügen erreichen moderne Einweg-E-Zigaretten eine neue Dimension der Langlebigkeit. Für erwachsene Nutzer bringt diese enorme Ausdauer jedoch oft eine praktische Herausforderung mit sich: die sogenannte Geschmacksmüdigkeit, wenn wochenlang dasselbe Aroma gedampft wird. Genau hier setzt die Vozol Gear Ice & Sweet 50k an. Das kompakte Gerät richtet sich an Dampfer, die im Alltag und auf Reisen nicht auf Portabilität verzichten möchten, aber gleichzeitig hohe Ansprüche an geschmackliche Flexibilität stellen.
Individuelle Aromen dank Dual-Achsen-Steuerung
Das herausragendste Merkmal dieses Modells ist das innovative Anpassungssystem für den Geschmack. Nutzer können über eine einfache Mechanik am Gerät zwischen vier verschiedenen Frische-Stufen (Ice) und zwei Süße-Graden (Sweet) wählen. Durch diese clevere Kombination ergeben sich acht völlig unterschiedliche Geschmacksprofile aus ein und demselben Liquid-Tank. So lässt sich das Dampferlebnis je nach Stimmung oder Tageszeit individuell anpassen, wodurch selbst bei einer extrem langen Nutzungsdauer keine Langeweile aufkommt.
Triple-Mesh und smarte Anzeige-Technologie
Im Inneren überzeugt das Gerät durch fortschrittliche Technik, die auf Langlebigkeit ausgelegt ist. Die verbaute Triple-Mesh-Technologie mit spezieller Geschmacksversiegelung verteilt die thermische Belastung gleichmäßig auf drei Spulen. Das schützt effektiv vor unangenehmem Kokeln (Dry Hits) und sorgt für einen beständigen Geschmack vom ersten bis zum letzten Zug. Zudem liefert ein modernes 3D-Curved-Display jederzeit klare Echtzeitdaten zum aktuellen Akkustand sowie zur gewählten Frische und Süße. Für die nötige Leistung sorgt eine großzügige 1100-mAh-Batterie, die zwei wählbare Ausgabemodi (Regular und Surge) zuverlässig mit Energie versorgt.

Robustes Design für den Alltag
Neben der starken technischen Ausstattung punktet die Vozol Gear Ice & Sweet 50k durch ihr äußerst robustes Gehäuse. Ganz in der Tradition der bekannten Gear-Serie verfügt auch dieses Modell über eine praktische Staubschutzkappe für das Mundstück sowie eine widerstandsfähige Außenhülle. Diese Eigenschaften machen die E-Zigarette zu einem idealen Begleiter für Outdoor-Aktivitäten oder längere Ausflüge. Eine stufenlos verstellbare Luftzufuhr (Airflow) an der Unterseite rundet das nutzerfreundliche Gesamtpaket ab.
Zusammenfassend kombiniert dieses Modell eine außergewöhnliche Kapazität mit einer nie dagewesenen geschmacklichen Anpassungsfähigkeit in einem äußerst tragbaren Format. Es löst das Problem eintöniger Aromen auf clevere Weise und bietet ein langanhaltendes Premium-Erlebnis. Möchten Sie mehr über die neuesten E-Zigaretten-Trends, innovative Features und praktische Tipps für Ihren Alltag erfahren? Entdecken Sie jetzt weitere spannende Beiträge in unserem Blog und lesen Sie mehr!
Sie könnten auch Folgendes mögen:
Vozol Star 50k
Nexa Vape 50000
Fumot 50k
Wet Flue Gas Desulfurization Systems Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-19
Wet Flue Gas Desulfurization Systems Market
Overview
The Wet Flue Gas Desulfurization Systems Market encompasses advanced pollution control technologies designed to remove sulfur dioxide (SO₂) from industrial exhaust gases. These systems are vital for reducing environmental emissions, ensuring compliance with stringent regulations, and supporting sustainable industrial operations. Core functionalities include the absorption of SO₂ using a liquid scrubbing process, typically involving limestone or lime slurry, which converts sulfur compounds into by-products like gypsum.
The market plays a crucial role in supporting modern industries such as power generation, cement manufacturing, and chemical processing. The Wet Flue Gas Desulfurization Systems Market is central to mitigating air pollution and minimizing environmental impact, making it indispensable for industries aiming to meet environmental standards and enhance operational sustainability.
Market Size and Growth
The current market value for Wet Flue Gas Desulfurization Systems is estimated at approximately USD 8 billion. It is projected to grow to around USD 15 billion by 2030, reflecting a compound annual growth rate (CAGR) of roughly 7%. Factors driving this growth include stricter emission regulations, increasing adoption of clean coal technologies, and expanding industrial infrastructure in emerging economies.
The ongoing demand for effective sulfur oxide removal solutions sustains steady market expansion, with technological innovations further boosting adoption rates across various sectors. As environmental policies tighten globally, the market for wet flue gas desulfurization systems is expected to maintain a robust growth trajectory over the next decade.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2082
Key Drivers
• Stringent environmental regulations and emission standards
• Rising demand for clean coal and fossil fuel power plants
• Increasing industrialization in emerging markets
• Technological advancements improving system efficiency
• Growing environmental awareness and corporate sustainability commitments
Restraints
• High capital and operational costs of systems
• Technical complexity and maintenance requirements
• Regulatory delays and compliance uncertainties
• Limited availability of suitable raw materials in some regions
• Operational challenges in retrofitting existing plants
Segmentation
• By Type: Wet scrubbers, spray tower systems, venturi scrubbers
• By Deployment: In-situ, modular, mobile units
• By Enterprise Size: Large enterprises, SMEs, government agencies
• By End User: Power plants, cement plants, chemical industries, refineries
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits mature adoption driven by stringent environmental policies and technological innovation. Europe’s market growth is fueled by strong regulatory frameworks and industrial modernization efforts. In the Asia-Pacific region, rapid industrial growth and urbanization are key factors, with China and India leading demand. Latin America shows emerging opportunities as industries upgrade pollution control systems. The Middle East & Africa are gradually adopting these systems to comply with environmental standards amid expanding energy sectors.
Opportunities
• Expansion in emerging markets such as India and Southeast Asia
• Adoption of hybrid systems integrating wet and dry technologies
• Innovation in membrane and filtration technologies
• Increasing use of automation and IoT for system monitoring
• Growing demand from renewable energy and decarbonization initiatives
Key Companies
Babcock & Wilcox Enterprises, GE Power, Mitsubishi Power, ANDRITZ, FLSmidth, Thermax Limited, Hamon Group, Doosan Group, Hitachi Zosen Inova, Sulzer, Veolia, Alstom
Conclusion
The overall outlook for the Wet Flue Gas Desulfurization Systems Market remains positive, driven by evolving environmental regulations and industrial modernization. With long-term growth potential, the market is strategically important for industries seeking sustainable emission control solutions. As global emphasis on air quality intensifies, the market for wet flue gas desulfurization systems is poised for continued expansion and technological innovation.
Related Reports
Industrial Drone Technology Market , Size Share and Analysis | Report 2033
Automatic Degas And Sealing Machine Market , Size Share and Analysis | Report 2033
Fiber Fineness Tester Market , Size Share and Analysis | Report 2033
Iot Industrial Controller Market , Size Share and Analysis | Report 2033
Mobile Apple Cabin House Market , Size Share and Analysis | Report 2033
Vertical Stack Fan Coil Market , Size Share and Analysis | Report 2033
Dome Star Rooms Market , Size Share and Analysis | Report 2033
High Purity Germanium Gamma Spectrometer Market , Size Share and Analysis | Report 2033
Rtk Survey Systems Market , Size Share and Analysis | Report 2033
Flat Membrane Pressure Sensor Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Wave Buoy Market
Overview
The Wave Buoy Market encompasses the development and deployment of advanced wave measurement devices designed to monitor oceanic and sea conditions. These buoys serve critical functions such as measuring wave height, frequency, and direction, providing essential data for maritime navigation, coastal management, and renewable energy projects. Their core functionalities support industries that rely on accurate oceanic data, including offshore drilling, shipping, and wave energy generation.
The importance of the Wave Buoy Market lies in its ability to facilitate safer maritime operations and optimize renewable energy extraction. As the demand for sustainable energy sources grows, wave energy conversion becomes increasingly vital. The market for wave buoys is central to these efforts, enabling precise data collection to support innovative technological solutions and industry growth. The Wave Buoy Market is thus integral to advancing ocean-based industries and environmental monitoring systems.
Market Size and Growth
The current value of the Wave Buoy Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 3.5 billion, reflecting a compound annual growth rate (CAGR) of approximately 11%. Growth is driven by rising investments in renewable energy, increased maritime safety regulations, and expanded offshore infrastructure. Technological advancements in buoy design and data analytics further propel market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2120
Key Drivers
- Increasing demand for renewable wave energy solutions
- Growing maritime safety and navigation requirements
- Expansion of offshore oil and gas exploration
- Technological innovations in buoy sensors and data transmission
- Government incentives for sustainable energy projects
Restraints
- High operational and maintenance costs
- Technical challenges in harsh ocean environments
- Regulatory hurdles and compliance complexities
- Limited standardization across different regions
- Environmental impact concerns and ecological restrictions
Segmentation
• By Type: Fixed, moored, drifting
• By Deployment: Coastal, deep-sea, offshore
• By Enterprise Size: Large corporations, SMEs
• By End User: Marine research, energy, defense, shipping, government agencies
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market benefits from extensive offshore energy projects and advanced maritime infrastructure, fostering steady demand. Europe’s focus on renewable energy and stringent safety standards drive adoption, especially in the North Sea. Asia-Pacific shows rapid growth due to expanding offshore exploration and emerging wave energy initiatives. Latin America’s market remains emerging, with increasing interest in coastal management. The Middle East & Africa are gradually adopting wave buoy technology, primarily for offshore oil and renewable projects.
Opportunities
- High-growth potential in offshore renewable energy sectors
- Adoption of IoT and AI for real-time ocean monitoring
- Innovation in durable, cost-effective buoy designs
- Expanding applications in climate change research and disaster prevention
- Strategic partnerships between technology providers and energy companies
Key Companies
ABB, Teledyne Marine, Oceanographic Instruments, Kongsberg Maritime, Datawell, Fugro, RBR, Nortek, Xylem, McMurdo, NOAA, Sea & Land Technologies
Conclusion
The overall outlook for the Wave Buoy Market remains optimistic, with long-term growth driven by the global shift toward sustainable energy and enhanced maritime safety. As industries increasingly rely on precise oceanic data, the market’s strategic importance will continue to rise. The Wave Buoy Market offers substantial potential for innovation and expansion, making it a vital component in future ocean and energy infrastructure development.
Related Reports
Candy Pouring Mold Market , Size Share and Analysis | Report 2033
Fully Automatic Lithium Battery Pressing Machine Market , Size Share and Analysis | Report 2033
Cordless Mitre Saw Market , Size Share and Analysis | Report 2033
Molded Transformers Market , Size Share and Analysis | Report 2033
Soft Candy Boiling Machine Market , Size Share and Analysis | Report 2033
Cassette Membrane Ultrafiltration System Market , Size Share and Analysis | Report 2033
Hybrid Aircraft Propulsion Propeller Market , Size Share and Analysis | Report 2033
Open Cycle Aero Engine Market , Size Share and Analysis | Report 2033
Dark Box Uv Analyzer Market , Size Share and Analysis | Report 2033
Multi Stage Ultrasonic Cleaners Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Water Toxicity Tester Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-19
Water Toxicity Tester Market
Overview
The Water Toxicity Tester Market encompasses advanced analytical devices designed to detect and quantify toxic substances in water sources. These testers are crucial for ensuring water safety, compliance with environmental regulations, and safeguarding public health. They typically employ chemical, biological, or physical methods to assess water quality, supporting industries such as water treatment, environmental monitoring, and manufacturing. The core functionalities include rapid detection, high sensitivity, and data accuracy, which are vital for operational decision-making in modern industries.
The Water Toxicity Tester Market plays a vital role in maintaining water quality standards across various sectors. Its purpose is to enable real-time monitoring and early detection of contaminants, thereby preventing environmental and health hazards. As water quality concerns grow globally, the market supports technological advancements and industry compliance efforts. The market size and growth are driven by increasing regulatory pressures and the rising awareness of water pollution issues.
Market Size and Growth
The market value for the Water Toxicity Tester Market is estimated at approximately USD 1.8 billion in the current year. It is projected to reach around USD 4.5 billion by the end of the next decade, reflecting a compound annual growth rate (CAGR) of about 10%. This growth is fueled by stringent environmental regulations, technological innovations, and expanding industrial applications. The rising need for accurate, fast, and portable testing solutions further accelerates market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2172
Key Drivers
- Increasing water pollution and regulatory compliance needs
- Growing industrialization and urbanization
- Technological advancements in testing devices
- Rising awareness of water safety and health risks
- Expansion of water treatment infrastructure
Restraints
- High costs of advanced testing equipment
- Operational complexity and need for skilled personnel
- Regulatory delays and inconsistent standards
- Technical challenges in detecting emerging contaminants
- Limited access in remote or underdeveloped regions
Segmentation
• By Type: Portable, Benchtop, Online
• By Deployment: In-situ, Laboratory-based
• By Enterprise Size: Small, Medium, Large
• By End User: Municipalities, Industrial facilities, Commercial entities, Research institutions
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits high adoption rates driven by stringent regulations and technological innovation. The U.S. leads in integrating advanced toxicity testing solutions across municipal and industrial sectors.
Europe’s demand is bolstered by robust environmental policies and a focus on sustainable water management. Countries like Germany and France are investing heavily in water quality monitoring infrastructure.
In the Asia-Pacific region, rapid industrial growth and urbanization are fueling demand for water toxicity testing. Emerging markets such as China and India are witnessing increased adoption of portable and cost-effective solutions.
Latin America shows steady growth, primarily driven by expanding water treatment projects and regulatory enforcement in Brazil and Mexico.
Middle East & Africa are gradually adopting water toxicity testers, mainly in oil-rich and industrial regions, with growth prospects tied to infrastructure development.
Opportunities
- Expanding use of real-time monitoring technologies
- Integration of IoT and AI in testing devices
- Focus on affordable, portable solutions for emerging markets
- Development of multi-parameter testing systems
- Increasing adoption in wastewater and industrial effluent management
Key Companies
Hach Company, Thermo Fisher Scientific, Merck KGaA, IDEXX Laboratories, Hach Lange, Lovibond, Palintest, Hach Lange, Hanna Instruments, YSI Inc., Drägerwerk AG & Co. KGaA, LaMotte Company
Conclusion
The overall outlook for the Water Toxicity Tester Market remains positive, with long-term growth potential driven by environmental concerns and technological progress. As industries and governments prioritize water safety, the market’s strategic importance will continue to grow. The market size and demand for reliable testing solutions are expected to expand significantly, making it a key component of sustainable water management strategies worldwide.
Related Reports
Industrial Fluid Chillers Market , Size Share and Analysis | Report 2033
Ai Powered Surgical Assistance Market , Size Share and Analysis | Report 2033
Laboratory Thermal Imagers Market , Size Share and Analysis | Report 2033
Liquid Cooling Heat Rejection Units Market , Size Share and Analysis | Report 2033
Intelligent Edge Banding Machine Market , Size Share and Analysis | Report 2033
Portable Desiccant Dryer Market , Size Share and Analysis | Report 2033
Particle Beam Accelerator Market , Size Share and Analysis | Report 2033
Hollow Cathode Ion Sources Market , Size Share and Analysis | Report 2033
Coating Machine For Fuel Cell Experiments Market , Size Share and Analysis | Report 2033
Three Way Agv Forklift Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Vertical Unpacking Machines Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-19
Vertical Unpacking Machines Market
Overview
The Vertical Unpacking Machines Market encompasses equipment designed to automate the process of unpacking products from cartons, trays, or containers in various industrial settings. These machines enhance efficiency by reducing manual labor, increasing throughput, and ensuring product integrity during handling. Their core functionalities include precise product separation, orientation, and placement, supporting industries such as food processing, pharmaceuticals, and consumer goods.
The market plays a vital role in modern manufacturing and logistics operations where speed and accuracy are critical. Vertical Unpacking Machines support the automation of supply chains, contributing to streamlined workflows and improved safety standards. The importance of these machines in supporting high-volume, fast-paced environments underscores their strategic relevance in the evolving landscape of industrial automation.
Market Size and Growth
The current value of the Vertical Unpacking Machines Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 2.4 billion, reflecting a compound annual growth rate (CAGR) of about 8%. This growth is driven by increasing automation in manufacturing, rising demand for efficient packaging solutions, and advancements in machine technology.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2142
Key Drivers
• Rising demand for automation in manufacturing processes
• Growing focus on operational efficiency and productivity
• Technological advancements in machine design and control systems
• Expansion of e-commerce and retail distribution networks
• Increasing regulatory standards for safety and hygiene
Restraints
• High initial investment costs for advanced machinery
• Technical complexity requiring specialized maintenance
• Regulatory hurdles in certain regions
• Limited flexibility for small-scale or customized operations
Segmentation
• By Type: Fully automatic, semi-automatic
• By Deployment: New installations, retrofit/upgrades
• By Enterprise Size: Small, medium, large enterprises
• By End User: Food & beverage, pharmaceuticals, consumer goods, logistics
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, demand for Vertical Unpacking Machines is driven by high automation adoption and stringent safety standards. Europe shows steady growth due to its mature manufacturing sector and focus on efficiency improvements. Asia-Pacific is experiencing rapid expansion, fueled by manufacturing growth and rising industrialization. Latin America’s adoption is increasing, particularly in food and beverage sectors, while the Middle East & Africa are gradually integrating these solutions as part of broader industrial upgrades.
Opportunities
• Expansion into emerging markets with growing manufacturing bases
• Integration of smart sensors and IoT for predictive maintenance
• Development of versatile, adaptable unpacking solutions for diverse product types
• Adoption in e-commerce fulfillment centers and logistics hubs
• Innovation in energy-efficient and space-saving machine designs
Key Companies
Bosch Packaging Technology, Marchesini Group, IMA Group, Omori Machinery, Fhope Packaging Machinery, Ulma Packaging, Tetra Pak, Sealed Air, Ishida, Multivac, Fuji Machinery, Aksu Machinery
Conclusion
The overall outlook for the Vertical Unpacking Machines Market remains positive, with long-term growth potential driven by ongoing automation trends across industries. As industries seek to optimize operational efficiency and meet increasing demand for high-speed packaging, the strategic importance of these machines will continue to grow. The market’s expansion will be pivotal in shaping the future of industrial automation, making the Vertical Unpacking Machines Market a critical component of modern manufacturing ecosystems.
Related Reports
Steam Quality Monitoring Machine Market , Size Share and Analysis | Report 2033
Fine Classifier Market , Size Share and Analysis | Report 2033
Eb Generator Market , Size Share and Analysis | Report 2033
Automobile Oil Management Module Market , Size Share and Analysis | Report 2033
Electro Hydraulic Servo Fatigue Testing Machine Market , Size Share and Analysis | Report 2033
Vehicle Spark Eliminator Market , Size Share and Analysis | Report 2033
Vehicle Exhaust Extraction Machine Market , Size Share and Analysis | Report 2033
Dram Testers Market , Size Share and Analysis | Report 2033
Roof Bolters For Coal Market , Size Share and Analysis | Report 2033
Three Primary Fluorescent Light Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Vertical Storing Mechanical Dock Leveler Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-19
Overview
The Vertical Storing Mechanical Dock Leveler Market Market encompasses advanced loading dock solutions designed to optimize material handling efficiency. These systems facilitate seamless loading and unloading operations by bridging the gap between trucks and warehouses, ensuring safety and productivity. As industries increasingly prioritize automation and streamlined logistics, vertical storing mechanical dock levelers have become integral to modern supply chain infrastructure.
The market is driven by the need for durable, space-efficient, and reliable dock levelers that support high-volume operations. Vertical storing mechanical dock leveler market players focus on innovations that enhance safety features, load capacity, and operational speed. These systems play a crucial role in supporting industries such as retail, manufacturing, and logistics, where quick turnaround times and operational flexibility are essential.
Market Size and Growth
The current market value of the Vertical Storing Mechanical Dock Leveler Market Market is estimated at approximately USD 1.2 billion. Over the next 7–10 years, it is projected to reach around USD 2.4 billion, reflecting a compound annual growth rate (CAGR) of roughly 8%. The growth is fueled by expanding e-commerce activities, increased automation in warehouses, and rising infrastructure investments worldwide.
Factors such as rising demand for efficient loading solutions, technological advancements, and stricter safety regulations are key drivers. Additionally, the growth of logistics hubs and urban distribution centers is further propelling market expansion, making vertical storing mechanical dock levelers essential for modern enterprise operations.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2077
Key Drivers
• Increasing automation in logistics and warehousing
• Rising demand for space-efficient dock solutions
• Growing e-commerce sector and supply chain complexity
• Technological innovations enhancing safety and load capacity
• Infrastructure development in emerging markets
Restraints
• High initial capital investment requirements
• Technical complexities in installation and maintenance
• Regulatory compliance challenges across regions
• Operational disruptions during upgrades or repairs
Segmentation
• By Type: Fixed, Adjustable, Vertical Storing
• By Deployment: Indoor, Outdoor
• By Enterprise Size: Small, Medium, Large
• By End User: Retail, Manufacturing, Logistics, Food & Beverage, Others
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong demand driven by technological adoption and logistics infrastructure modernization. The region’s focus on safety standards and automation further supports market growth.
Europe’s market growth is propelled by stringent safety regulations and a high level of industrial automation, especially in Germany, France, and the UK.
In Asia-Pacific, rapid industrialization, urbanization, and e-commerce expansion are driving significant adoption of vertical storing mechanical dock levelers, particularly in China, India, and Southeast Asia.
Latin America’s growth is linked to infrastructure development and increasing foreign investments in manufacturing and logistics sectors.
The Middle East & Africa are witnessing emerging demand, primarily in logistics hubs and industrial parks, with growth expected to accelerate as regional economies diversify.
Opportunities
• Adoption of smart, IoT-enabled dock levelers for real-time monitoring
• Integration with automated guided vehicles (AGVs) and robotics
• Expansion in emerging markets with growing industrial bases
• Development of modular and customizable systems for diverse industries
• Focus on sustainable and energy-efficient dock solutions
Key Companies
Jungheinrich, Blue Giant, Rite-Hite, Nordock, Serco, Eoslift, Poweramp, Stertil-Koni, Kelley, JLG, Aventure, Tieman
Conclusion
The overall outlook for the Vertical Storing Mechanical Dock Leveler Market Market remains positive, with long-term growth driven by technological innovation and expanding logistics networks. As industries seek more efficient, safe, and space-saving loading solutions, this market is poised for sustained expansion. The strategic importance of vertical storing mechanical dock levelers underscores their role in modern enterprise operations and supply chain resilience.
Related Reports
Intelligent Cheese Cutting Equipment Market , Size Share and Analysis | Report 2033
Slip Rings With Through Bores Market , Size Share and Analysis | Report 2033
Cheese Press Machines Market , Size Share and Analysis | Report 2033
Rubber Screw Extruder Market , Size Share and Analysis | Report 2033
Ceramic Anilox Rolls Sleeves Market , Size Share and Analysis | Report 2033
Backpack Gas Leaf Blower Market , Size Share and Analysis | Report 2033
Fire Extinguisher Filling Machines Market , Size Share and Analysis | Report 2033
Mobile Impact Crushing Station Market , Size Share and Analysis | Report 2033
Fully Automatic Vacuum Battery Filling Machines Market , Size Share and Analysis | Report 2033
Mesh Belt Type Spring Tempering Furnace Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Vertical Glass Production Line Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-19
Overview
The Vertical Glass Production Line Market encompasses the equipment and systems used to manufacture flat and specialty glass products through vertical processing methods. This market is integral to industries such as construction, automotive, electronics, and consumer goods, where high-quality glass components are essential. Its core functionalities include precise temperature control, automated cutting, shaping, and coating processes that ensure efficiency and consistency in glass production.
The market's significance lies in its ability to support modern technological advancements and manufacturing standards. The Vertical Glass Production Line Market plays a critical role in enabling scalable, high-speed production of glass panels with minimal defects, aligning with the demands of rapid urbanization and technological integration across industries.
Market Size and Growth
The current market value of the Vertical Glass Production Line Market is estimated at around USD 2.5 billion. Over the next decade, it is projected to reach approximately USD 4.8 billion, reflecting a compound annual growth rate (CAGR) of about 8.3%. Growth drivers include increasing demand for energy-efficient windows, the expansion of automotive glass applications, and ongoing innovations in automated manufacturing processes.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2159
Key Drivers
- Rising infrastructure development and urbanization
- Growing demand for energy-efficient and smart glass products
- Technological advancements in automation and robotics
- Expansion of automotive and electronics industries
- Increasing focus on sustainable manufacturing practices
Restraints
- High capital investment requirements
- Technical complexity in integrating new systems
- Regulatory compliance and safety standards
- Fluctuations in raw material costs
- Operational challenges in maintenance and upgrades
Segmentation
• By Type
- Flat Glass Lines
- Specialty Glass Lines
• By Deployment
- Fully Automated
- Semi-Automated
• By Enterprise Size
- Large Enterprises
- SMEs
• By End User
- Construction & Architectural
- Automotive
- Electronics & Appliances
- Consumer Goods
• By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Insights
North America exhibits steady demand driven by renovation projects and technological upgrades in manufacturing facilities. The U.S. and Canada focus on energy-efficient and smart glass solutions, fostering growth in the Vertical Glass Production Line Market.
Europe’s market growth is propelled by stringent energy regulations and a strong automotive sector. Countries like Germany, France, and Italy are investing in advanced production lines to meet sustainability standards.
In Asia-Pacific, rapid industrialization and urban development fuel demand. China, India, and Japan are key markets, with a focus on high-volume, cost-effective glass manufacturing.
Latin America shows emerging opportunities, particularly in construction and automotive sectors. Growth is tied to infrastructural investments and market modernization efforts.
Middle East & Africa are gradually adopting advanced glass production technologies, driven by infrastructural expansion and increasing industrialization.
Opportunities
- Expansion into smart and energy-efficient glass segments
- Adoption of Industry 4.0 and automation technologies
- Development of lightweight, high-strength glass products
- Investment in sustainable manufacturing practices
- Growing demand in emerging markets for customized glass solutions
Key Companies
ASAHI GLASS CO., LTD.
Saint-Gobain
NSG Group
Guardian Industries
Fuyao Glass Industry Group Co., Ltd.
Yingli Green Energy Holding Company Limited
Central Glass Co., Ltd.
Kuraray Co., Ltd.
Vitro, S.A.B. de C.V.
Xinyi Glass Holdings Limited
AGC Inc.
Schott AG
Conclusion
The overall outlook for the Vertical Glass Production Line Market remains positive, with long-term growth potential driven by technological innovation and expanding end-user industries. As demand for high-quality, sustainable glass products continues to rise globally, the market's strategic importance will increase, fostering continued investment and development in vertical glass manufacturing solutions.
Related Reports
In Row Coolers Market , Size Share and Analysis | Report 2033
Gas Chromatography Sensors Market , Size Share and Analysis | Report 2033
Electronic Heat Sinks Market , Size Share and Analysis | Report 2033
Fully Automatic Ton Bag Unpacking Machines Market , Size Share and Analysis | Report 2033
Industrial Vacuum Rental Market , Size Share and Analysis | Report 2033
Missile Servo Market , Size Share and Analysis | Report 2033
Pipe Rotator For Welding Market , Size Share and Analysis | Report 2033
Fluid Dispensing Consumables Market , Size Share and Analysis | Report 2033
H Beam Straightening Machine Market , Size Share and Analysis | Report 2033
Single Column Hydraulic Straightening Machine Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher