

Blogs
Worldwide Dryer Refurbishment Repair Service Market: Why 4.6% CAGR Redefines Value
By PW Consulting, 2026-09-18
Worldwide Dryer Refurbishment & Repair Service Market: Strategic Shifts and Commercial Opportunities (2026–2032)
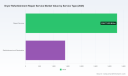
The dryer refurbishment and repair service market has matured into a resilient, operationally critical segment of the broader industrial and commercial equipment lifecycle ecosystem. Valued at 4.68 billion USD in 2025, the market has expanded from 3.75 billion in 2020, reflecting a compound annual growth rate of 4.6 percent through the 2026–2032 forecast horizon. This trajectory underscores a structural shift: organizations are increasingly optimizing existing assets rather than pursuing full capital replacement. The market is projected to approach 6.41 billion by 2032, driven by aging equipment fleets, supply chain recalibrations, and a growing preference for service-led value retention. Yet this expansion is neither automatic nor uniform. The sector stands at an inflection point where operational efficiency, regulatory compliance, and service model innovation will determine which players capture margin and scale.
Three structural challenges are reshaping competitive dynamics. First, the talent constraint in specialized field service has intensified cost pressures and limited deployment flexibility, particularly for complex rotary and industrial dryer systems requiring certified technicians. Second, fragmented service standards and varying regional compliance requirements create operational friction, especially for multinational operators seeking consistent quality across jurisdictions. Third, the procurement mindset is shifting from reactive breakdown maintenance to predictive, outcome-based service contracts, forcing traditional repair providers to rethink pricing, capability deployment, and customer engagement. These pressures are not merely operational; they are redefining value capture across the service chain.
For decision-makers, the implication is clear. The refurbishment and repair space is no longer a peripheral support function but a strategic lever for total cost of ownership optimization, uptime assurance, and sustainability alignment. Organizations that recognize this transition and align their service strategies accordingly will be better positioned to navigate the next five years of market evolution.
Market Drivers: Technology, Regulation, Demand, and Cost Architecture
Technology Innovation and Predictive Service Integration
Digital diagnostics, remote monitoring, and modular repair frameworks are redefining what refurbishment and repair can deliver. Advanced sensor integration and condition-based monitoring allow service teams to identify wear patterns, thermal inefficiencies, and mechanical degradation before failure occurs. This shift is particularly evident in rotary dryer applications, where alignment, seal integrity, trunnion wear, and drum shell deformation directly influence throughput and energy consumption. Providers that combine field diagnostics with engineering-grade retrofits are converting episodic repairs into lifecycle optimization engagements. The result is a more predictable service cadence, reduced unplanned downtime, and a stronger value proposition for operators managing high-utilization assets.
Technology also enables more precise parts matching and refurbishment sequencing. Reconditioned components, when validated through standardized testing and quality protocols, can extend asset life without compromising performance. This capability matters as original equipment availability becomes less predictable in certain categories, and as operators seek to balance lead-time risk against capital expenditure. Service providers that invest in machining, shell repair, and precision realignment capabilities are increasingly positioned as de facto lifecycle partners rather than break-fix vendors.
Policy and Regulatory Pressure as a Service Catalyst
Regulatory expectations around safety, emissions, and operational compliance are accelerating demand for certified refurbishment and repair practices. Industrial environments, in particular, require field teams to operate under stringent safety frameworks and documented procedures. Certified alignment, seal replacement, gear and trunnion work, and drum shell repairs are no longer optional best practices; they are increasingly tied to operational licensure, insurance expectations, and corporate risk management. In parallel, the broader push toward resource efficiency and asset circularity is reinforcing the economic case for refurbishment over replacement, especially when refurbished units carry warranty coverage that mitigates performance risk.
Compliance-oriented service models also create differentiation. Providers that maintain documented repair procedures, standardized quality checks, and certified field teams can serve regulated sectors more effectively and command premium positioning. As safety and quality expectations rise across industrial and commercial applications, procedural rigor becomes a competitive moat.
Demand-Side Behavior: From Ownership to Outcome
Customer behavior is moving toward service models that prioritize uptime, predictability, and cost control over isolated repair transactions. In commercial laundry and institutional settings, operators are managing high-cycle equipment where malfunction directly affects throughput, customer experience, and revenue continuity. This reality is driving demand for preventive maintenance, rapid response networks, and genuine parts supply chains that reduce variability in repair outcomes. Brand-agnostic service coverage is gaining relevance because many facilities operate mixed equipment fleets and value single-point accountability over manufacturer-restricted service paths.
Residential and light commercial segments exhibit a similar pattern, albeit at a different scale and complexity. Consumers and property operators increasingly expect reliable, transparent service with clear parts replacement protocols and consistent quality. The emphasis is shifting from lowest initial cost to long-term dependability, particularly in multi-unit residential, hospitality, and laundromat environments where repeat failures carry high operational and reputational costs.
Supply Chain and Cost Structure Realignment
Labor intensity remains a defining feature of the dryer repair and refurbishment sector. On-site diagnostics, machining, component reconditioning, and field installation rely heavily on skilled human execution, which keeps labor economics at the center of margin structure. At the same time, material availability, reconditioning throughput, and logistics for specialized parts influence service response times and cost consistency. Providers are responding by standardizing procedures, expanding localized service presence, and investing in training pipelines that reduce dependency on scarce specialized talent.
Cost architecture is also being reshaped by warranty-backed refurbishment and reconditioning models. When an upgraded or restored unit is delivered with a new-machine warranty, the service transaction shifts from uncertainty to risk-managed performance. This structure supports higher customer confidence and can justify more comprehensive service bundles, but it also requires disciplined quality control and parts traceability. Organizations that can align labor efficiency, component quality, and warranty assurance will capture stronger retention and more stable revenue streams.
PW Consulting
Competitive Landscape and Leading Strategies
The market remains relatively fragmented at the top, with a limited concentration of share among leading providers. This fragmentation reflects the diversity of dryer types, application contexts, and regional service requirements. Yet the leaders share a common strategic thread: they extend beyond transactional repair into capability-rich service ecosystems that combine field execution, parts availability, technical training, and standardized quality administration.
FEECO International exemplifies a capability-focused positioning centered on rotary dryer support across multiple industries. Its service scope spans preventive maintenance, repair, rebuilds, retrofits, and replacement parts, with specialized field work such as alignment, seal replacement, gear and trunnion service, and drum shell repairs. The emphasis on certified field teams and cross-industry applicability signals a strategy built on technical breadth and regulatory-aware execution. In practical terms, this approach allows the provider to serve operations where dryer performance directly affects processing continuity and safety compliance.
Industrial Kiln & Dryer Group has cultivated a leadership position by combining field service with engineering support and training. Its offering includes installation, alignment, emergency and planned repair, maintenance, and new or reconditioned parts for rotary dryers and kilns, with support for all OEM brands. The integration of 3D modeling, specialized tooling, and structured training programs suggests a differentiation strategy rooted in precision, repeatability, and capability transfer. By investing in know-how dissemination, the organization builds long-term customer reliance rather than one-off service events.
Prime Field Service Corp has pursued a globally deployable model with localized execution. Its service portfolio covers repair, rebuild, installation, retrofitting, and maintenance for rotary kilns and dryers, supported by machining capabilities and ISO-qualified procedures. The combination of global reach, machining depth, and standardized process control is strategically important for multinational operators that need consistent service quality across sites. This model aligns well with customers seeking scalable support without sacrificing procedural rigor.
Semiconductor Part Refurbishment Repairs Market
In the commercial laundry space, Consolidated Laundry Machinery and Alliance Laundry Systems illustrate divergent but complementary pathways. CLM focuses on industrial tumbler dryers with on-site and in-plant upgrading and refurbishing services, emphasizing downtime reduction and warranty-backed completion. This positions the company as an asset-upgrade partner where customers value performance restoration and risk mitigation in a single engagement. Alliance Laundry Systems, through its distribution network, emphasizes brand-agnostic repair, installation, preventive maintenance, and genuine parts supported by a sizable technician network and worldwide distributors. Its recent service network update reinforced the importance of factory-trained support and rapid parts-backed response. Both models highlight a shared reality: service credibility increasingly depends on trained personnel, parts authenticity, and consistent field execution.
Residential and multi-site commercial players such as Mr. Appliance and Whirlpool Corporation’s authorized service network demonstrate the importance of scale, brand alignment, and parts supply reliability. Their service models center on replacing critical components such as thermostats, belts, and coils, with broad coverage across electric and gas dryer types. For laundromats, hotels, and residential operators, the value proposition rests on dependable response, recognizable service standards, and streamlined parts replacement. These players benefit from established franchise or authorized provider structures that support geographic coverage and customer trust.
Taken together, the competitive landscape is evolving along three axes. One is integration, as providers combine repair, refurbishment, training, and digital or engineering support to deepen customer relationships. A second is specialization, where companies build advantage around certified safety practices, machining capability, or application-specific expertise. A third is network expansion, with service organizations extending local presence and technician capacity to reduce response times and improve coverage reliability. New entrants face meaningful barriers in specialized field service, particularly where certification, parts access, and technical reputation are prerequisites for trust. At the same time, consolidation remains plausible in regions where fragmented providers can be combined into broader coverage platforms with stronger logistics and training backbones.
Future Outlook: Three Trends Shaping the Next Three to Five Years
The first trend is the continued migration from reactive repair to predictive and preventive service architectures. As condition monitoring becomes more accessible and service teams accumulate diagnostic data, providers will be able to anticipate failure modes earlier and structure maintenance around usage patterns rather than breakdowns. This creates opportunities for subscription-style service contracts, tiered coverage, and performance-linked pricing, especially in commercial and industrial settings where uptime is directly tied to revenue.
The second trend is the growing importance of warranty-backed refurbishment as a commercial differentiator. Customers are increasingly willing to commit to upgraded or reconditioned equipment when the service provider assumes performance risk through a new-machine-style warranty. This model encourages deeper refurbishment engagements and can support premium pricing, but it also demands disciplined quality assurance, traceable parts sourcing, and consistent field execution. Providers that can operationalize this risk transfer will stand out in a market where trust and reliability are central purchase criteria.
The third trend is geographic and capability rebalancing. As organizations seek faster response and more predictable service costs, local or regional service presence will become more valuable, particularly where specialized labor and parts logistics have historically constrained performance. This may encourage network expansion by established providers and selective partnerships by manufacturers seeking broader coverage. At the same time, labor availability and certification requirements will remain a binding constraint, making training pipelines and workforce development strategically important rather than merely operational concerns.
Worldwide Electrical Transformer Repair Market
Potential risks should not be underestimated. Cost volatility in skilled labor, uneven regulatory expectations across regions, and variability in parts quality can erode margin and service consistency. Macroeconomic pressure may also shift procurement toward the lowest short-term cost, delaying investment in preventive or warranty-backed service models. Providers and buyers alike will need to manage these uncertainties through standardized procedures, clear service-level definitions, and disciplined capacity planning.
Actionable Recommendations for Decision-Makers
For Manufacturers and Equipment Owners
Treat dryer service strategy as a lifecycle decision rather than a maintenance afterthought. Prioritize providers that combine certified field expertise, standardized repair procedures, and clear warranty or performance assurance for refurbishment work. Where equipment fleets are mixed, evaluate brand-agnostic service coverage and rapid-response capabilities to reduce downtime risk across asset types.
For Investors and Strategic Buyers
Focus on service organizations with defensible capabilities: certified technical teams, machining and reconditioning depth, training infrastructure, and documented quality processes. Business models that can convert episodic repairs into recurring service relationships, or that can support warranty-backed refurbishment with disciplined quality control, are better positioned for durable margin expansion. Geographic coverage, technician scalability, and parts supply reliability should be assessed as core value drivers.
For Procurement and Operations Leaders
Shift evaluation criteria from unit cost to total cost of ownership, response reliability, and performance assurance. Ask for documented repair procedures, parts traceability, and clear warranties on refurbished or upgraded units. Where possible, consolidate service relationships to improve accountability, reduce coordination overhead, and strengthen negotiating leverage around response times and preventive maintenance scheduling.
The market’s trajectory will reward organizations that act on these structural shifts early. For those seeking deeper segmentation data, regional dynamics, and customized strategic pathways, the full PW Consulting report provides a more granular view of the commercial landscape and the service models likely to outperform over the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Dryer Refurbishment Repair Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Titrator Market: by Type (Potentiometric, Karl Fischer, Coulometric, Thermometric, Precipitation, Others), Application (Pharmaceuticals, Food & Beverages, Water & Wastewater, Environmental Testing, Chemicals, Oil & Gas), Distribution Channels (Direct Sales, Distributors/Wholesalers, Online, Specialty Stores, Value-Added Resellers, Others), Technology (Automatic, Manual, Semi-Automatic, Smart/IoT-Enabled, Digital, Analog), Organization Size (Small, Medium, Large) and By Global Historical & Forecast Period (2020-2035) Comprehensive Study 2025
Read More - https://bussinessinsights.com/research-report/global-titrator
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-titrator
Frequently Asked Questions
Who are the key players in Global Titrator industry?
The top five players in the Global Titrator market include Metrohm AG, Mettler Toledo, Hanna Instruments, Xylem Inc., and Hiranuma Sangyo Co. These companies are leaders in chemical analysis solutions, offering advanced titration equipment and technologies, extensive global distribution networks, and innovative research and development capabilities.
What is the Global Titrator growth?
The Global Titrator market is experiencing steady growth due to rising demand in pharmaceutical and food industries. Recently, Mettler Toledo reported a significant increase in analytical instrument sales, driven by quality control needs and automation trends boosting precision and efficiency in laboratory testing.
Which segment accounted for the largest Global Titrator share?
The pharmaceutical industry segment accounted for the largest share of the Global Titrator market. Titrators are widely used for quality control, purity analysis, and compound quantification in drug manufacturing processes, ensuring adherence to regulatory standards and safety, thereby driving segment dominance.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Titanium Anodizing Machines Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-18
The market has shown steady growth from 2020, reaching a projected USD 478.5 Million in 2025. Fueled by expanding adoption and technological advances, revenue is expected to rise consistently, surpassing USD 1,112.7 Million by 2035. The compound annual growth rate accelerates after 2025, reflecting increasing investments in high-precision and automated anodizing equipment. Industrial modernization and the expanding presence of titanium applications in key verticals like aerospace and medical will continue to drive robust revenue gains over the forecast period.
Read More - https://bussinessinsights.com/research-report/global-titanium-anodizing-machines
Aerospace dominates the global titanium anodizing machines market, holding a 32% share in 2025, due to rigorous requirements for corrosion resistance and structural integrity. The medical segment follows at 24%, propelled by the growing adoption of titanium implants and surgical devices. Automotive applications account for 18% as lightweight, durable materials become integral to modern vehicle design. Electronics, industrial, and jewelry together contribute 26%, with increased demand for wear-resistant and decorative finishes. The focus on high-performance end-use sectors underscores titanium anodizing’s role in advancing components where durability and reliability are paramount.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-titanium-anodizing-machines
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Markets Beyond CAC 728.31: Strategic Shifts Driving 5.15% Emamectin Benzoate Growth
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Emamectin Benzoate Market
Market Overview and Core Challenges
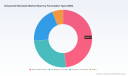
The global market for emamectin benzoate has demonstrated consistent expansion over the past half-decade, establishing itself as a critical component within the broader crop protection landscape. From a base valuation of approximately 395.2 million USD in 2020, the market has progressed through a period of accelerated growth, reaching 481.93 million USD by 2023. Although 2024 saw a temporary contraction to 454.47 million USD, the trajectory rebounded strongly, with 2025 valuations climbing to 512.45 million USD. This pattern indicates a market that is resilient despite short-term volatility, driven by fundamental agricultural needs. Looking ahead, the forecast period from 2026 to 2032 suggests a steady upward path, with valuations projected to move from 533.7 million USD in 2026 to 728.31 million USD by 2032. This growth trajectory implies a compound annual growth rate of 5.15 percent, signaling a mature yet expanding market phase where incremental gains are driven by efficiency and regional demand rather than purely novel adoption.
Despite the positive revenue outlook, the industry stands at a critical juncture defined by environmental scrutiny and supply chain volatility. One of the most significant challenges is the tightening regulatory framework surrounding environmental safety, particularly in aquaculture-intensive regions. Recent implementations of Environmental Quality Standards (EQS) in sediment, such as those introduced in Scotland, highlight a growing regulatory focus on protecting benthic populations from agricultural discharges. This shift forces manufacturers and formulators to reconsider application methods and runoff management, potentially increasing compliance costs and limiting certain use cases in sensitive areas.
A second major challenge involves price instability linked to upstream raw material availability and inventory levels. The technical grade material, synthesized primarily from abamectin B1a/B1b, has experienced notable price fluctuations. For instance, domestic prices in China saw a significant recovery in 2024, rising by over 24 percent among top insecticides, driven by reduced inventories against ongoing demand. However, retail prices monitored in early 2026 showed a decrease from higher peaks, indicating a market sensitive to inventory corrections and regional supply dynamics. This volatility complicates budgeting for agricultural distributors and farmers, creating uncertainty in procurement planning.
The third key challenge is the concentration of market power among a limited number of key players. With a CR3 concentration ratio of 42.5 percent and a CR5 of 61.8 percent, the market is moderately consolidated. While this suggests stability among leading incumbents, it also raises barriers to entry for new manufacturers and places pressure on smaller formulating companies to differentiate through niche applications or specific regional partnerships. Navigating this concentration requires strategic alignment with either major integrated players or specialized technical producers to secure reliable supply chains.
Key Drivers of Market Change
Technological Innovation and Formulation Advancements
Innovation in formulation technology remains a primary driver for market value retention and growth. The shift towards user-friendly and environmentally safer delivery systems is evident in the market mix. Water soluble granules currently represent the largest share of formulation types, capturing significant value due to their ease of handling and reduced exposure risks compared to older solvent-based formats. However, emulsifiable concentrates and suspension concentrates continue to hold substantial market share, catering to specific application equipment and crop requirements. The development of dual-action products that combine rapid knockdown with residual control is a notable technological leap. Companies are increasingly focusing on integrating emamectin benzoate into broader portfolios that address resistance management, ensuring that the active ingredient remains effective against lepidopteran pests over time. This focus on performance longevity extends the commercial lifecycle of products containing the active ingredient.
Policy and Regulatory Environment
The regulatory landscape is acting as both a constraint and a driver for differentiation. While environmental standards in regions like Scotland and Norway are tightening regarding sediment quality and aquaculture discharges, other regions are focusing on registration efficiency and residue limits for food crops. In major agricultural economies across Asia Pacific and Latin America, regulatory frameworks often support the continued use of effective biologicals and chemistries against resistant pest populations. The divergence in regulatory strictness creates a complex compliance map. For global manufacturers, this means that regulatory expertise is a competitive advantage. Companies that can navigate varying environmental quality standards while maintaining efficacy are better positioned to capture value in high-growth regions. Furthermore, regulations pushing for lower application rates due to higher potency formulations can drive demand for premium-priced, high-purity technical materials.
PW Consulting
Demand-Side Shifts in Agriculture
On the demand side, the pressure to secure global food supplies against pest infestation continues to underpin volume requirements. Vegetables and field crops remain the primary application areas, reflecting the need for robust protection in high-value edible crops. Fruit cultivation also represents a significant demand node, where quality standards for export dictate strict pest control measures. Consumer behavior is indirectly influencing this sector; as demand for residue-free produce grows, there is a corresponding need for chemistries that offer high efficacy at low dosage rates, reducing the chemical load on the final product. Emamectin benzoate fits this profile when used according to integrated pest management protocols. Additionally, the ornamental plant sector, while smaller in volume, drives demand for aesthetic quality, sustaining usage in niche markets where visible pest damage is unacceptable.
Supply Chain and Cost Structure Dynamics
Supply chain resilience has become a critical differentiator following recent global disruptions. The synthesis of emamectin benzoate relies on specific upstream starting materials, and any bottleneck in the production of abamectin derivatives can ripple through the entire value chain. Recent data points indicate that China remains a pivotal hub for technical material production, with domestic pricing serving as a bellwether for global cost structures. The recovery of technical prices in 2024 due to reduced inventories suggests that supply tightness can quickly reverse cost advantages. For downstream formulators, securing long-term supply agreements or diversifying sourcing from multiple technical manufacturers is becoming a standard risk mitigation strategy. Cost structures are further influenced by logistics and raw material energy costs, making operational efficiency in manufacturing a key determinant of margin preservation.
Worldwide Insect Growth Regulators Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large multinational corporations and specialized chemical manufacturers. Major global players such as Syngenta AG and FMC Corporation maintain strong positions through integrated agricultural solutions portfolios. Syngenta, headquartered in Basel, leverages its global registration network and integrated formulation offerings to control lepidopteran pests across diverse crop systems. FMC Corporation, based in Philadelphia, competes by emphasizing dual-action products that provide both rapid knockdown and residual control, appealing to farmers seeking immediate and lasting protection. BASF SE contributes to the landscape by supplying technical material and formulated insecticides focused on broad-spectrum control, utilizing its extensive R&D infrastructure to optimize product performance.
On the other side of the landscape, Chinese manufacturers play a crucial role in the supply of technical concentrate and formulations. Companies like Hebei Veyong Bio-Chemical, Zhejiang Hisun Chemical, and Hailir Pesticides and Chemicals Group are active producers with capacities supporting global distribution. Shandong Qilu King-Phar Pharmaceutical and Awiner Biotech also contribute to the technical material pool, often focusing on quality certifications required for international supply. POMAIS, operating as Shanghai AgroRiver Chemical Co., Ltd., distinguishes itself by offering specific formulations like 5% WDG with ISO 9001 certification and customized packaging for export. ADAMA Agricultural Solutions Ltd., based in Israel, rounds out the competitive field by offering emamectin benzoate-containing products tailored for tough pests, leveraging its regional expertise in agricultural solutions.
The strategic positioning of leaders varies significantly. Multinationals tend to focus on brand equity, comprehensive pest management solutions, and regulatory stewardship in regulated markets. In contrast, technical manufacturers often compete on cost efficiency, production capacity, and the ability to customize formulations for specific regional needs. This bifurcation creates a dynamic where value capture is split between those controlling the end-product market and those controlling the technical supply. Recent developments highlight this dynamic; for example, industry data from early 2025 noted a price recovery in China driven by inventory reductions, benefiting technical suppliers. Simultaneously, ADAMA highlighted product performance in full-year results, emphasizing the value of efficacy in maintaining market share for formulators.
Market evolution suggests a trend towards further consolidation among formulators who need to secure supply, while technical manufacturers may face pressure to differentiate through purity and consistency rather than price alone. New entrants face high barriers due to regulatory registration costs and the established relationships between key suppliers and global distributors. However, opportunities exist for companies that can bridge the gap between technical production and specific regional formulation needs, particularly in high-growth areas where local registration support is valuable. The concentration ratios indicate that while the top five players hold a majority share, there is enough fragmentation in the remaining market to allow for strategic niche positioning by agile manufacturers.
Future Trends and Predictions
Looking toward the 2027 to 2031 window, several key trends are likely to shape the commercial landscape. First, environmental compliance will increasingly dictate market access. As sediment quality standards and aquaculture discharge regulations mature in Europe and potentially influence standards in other regions, products and formulations that minimize environmental runoff will gain preference. This could drive innovation in formulation types that reduce leaching, potentially shifting value towards suspension concentrates or specialized granules in regulated zones. Companies that proactively adapt to these standards will secure a competitive advantage in premium markets.
Second, price volatility is expected to remain a feature of the market, driven by the cyclical nature of technical material inventories and raw material availability. The observed swing from technical price recoveries to retail price adjustments suggests that market participants must remain agile. Forecasting models indicate continued growth in market size, but the path will not be linear. Suppliers who can offer stability through long-term contracts or stock buffering will be valued highly by downstream customers facing their own margin pressures. The divergence between technical costs and retail pricing offers opportunities for arbitrage and strategic inventory management.
Third, the demand structure will likely continue to favor high-value crops. While field crops provide volume, vegetables and fruits offer higher margin potential for pesticide suppliers. The growth in these segments will be supported by the need for quality assurance in global food trade. However, uncertainty remains regarding the pace of regulatory tightening in key export markets. If residue limits become stricter or specific environmental restrictions expand, certain applications could face headwinds. Nevertheless, the fundamental need for lepidopteran control in major staple and cash crops provides a solid floor for demand, ensuring that the market continues to expand even as the mix of applications evolves.
Strategic Recommendations for Decision Makers
For manufacturers and suppliers, the priority should be securing supply chain resilience while investing in formulation differentiation. Given the concentration of key players and the volatility in technical pricing, diversifying sourcing options and maintaining strategic inventory levels can mitigate risk. Manufacturers should also evaluate opportunities to align with regulatory trends, such as developing formulations that meet emerging environmental standards in aquaculture and sensitive ecological zones. This proactive stance can open doors to markets where competitors are slowed by compliance hurdles.
Investors assessing this sector should focus on companies with strong technical production capabilities in key regions like China, as well as formulators with robust distribution networks in high-growth areas such as Asia Pacific and Latin America. The moderate market concentration suggests that while leaders are secure, there is room for value creation in specialized segments. Monitoring price trends and inventory levels in the upstream technical market will provide early signals of margin shifts for downstream entities. Understanding the regulatory trajectory in regions like Europe and North America is also essential for evaluating long-term risk exposure.
For procurement teams and agricultural buyers, the focus should be on total cost of ownership rather than just unit price. With price fluctuations observed in both technical and retail markets, locking in supply through partnerships or contracts during stable periods can protect against volatility. Evaluating products based on efficacy, resistance management profiles, and environmental compliance will ensure sustainable operations. Accessing detailed market intelligence on regional pricing, regulatory changes, and competitor activity is crucial for making informed procurement decisions. Comprehensive data sets and customized analysis allow stakeholders to navigate these complexities with greater confidence.
Deltamethrin Market
For detailed analysis of this topic, please visit the official page: Worldwide Emamectin Benzoate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global tool rolls market revenue demonstrates consistent growth from 2020 to 2035. Valued at $1,267 million in 2025, the market is projected to reach $1,803 million by 2030 and $2,273 million by 2035. Growth is driven by rising demand in industrial, automotive, and construction sectors, supported by the proliferation of e-commerce sales. Industry players are innovating in sustainable material use and advanced manufacturing processes to capture further value, while regional diversification increasingly strengthens overall market resilience.
Read More - https://bussinessinsights.com/research-report/global-tool-rolls
The automotive sector leads in tool rolls market application share for 2025, driven by the need for organized tool storage in vehicle repair and maintenance. Industrial use closely follows, as manufacturing and field service professionals significantly rely on tool rolls for portability and protection of specialized equipment. Household and construction applications also contribute robustly, with growing uptake in DIY projects and on-site job requirements. Electrical applications and others complete the segmentation, collectively reflecting increasing tool usage across sectors.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-rolls
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Household Automatic Soap Dispenser Market: Why 8.84% CAGR Changes Everything
By PW Consulting, 2026-09-18
The Worldwide Household Automatic Soap Dispenser Market: Strategic Trends and Commercial Opportunities Through 2032
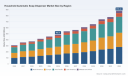
The global household automatic soap dispenser market has transitioned from a pandemic-driven novelty to a structural fixture in modern home hygiene infrastructure. With a base year valuation of 2025 establishing a robust revenue foundation and projections extending through 2032, the sector demonstrates sustained expansion momentum. Historical performance from 2020 through 2025 reflects a consistent upward trajectory, driven by accelerated adoption cycles and evolving consumer expectations around contactless sanitation. Forecasts indicate the market will continue scaling at a compound annual growth rate of 8.84%, translating into billions of dollars in cumulative revenue across the forecast horizon. This growth is not merely a rebound effect but rather the result of entrenched behavioral shifts, product maturation, and broader integration into residential design standards.
Despite the positive momentum, the industry navigates several structural inflection points. First, price sensitivity continues to pressure manufacturers as premium pricing strategies encounter resistance in cost-conscious segments, forcing companies to balance innovation investments with accessible tiered pricing models. Second, the category faces functional saturation in baseline sensor-driven dispensing, where incremental hardware improvements yield diminishing differentiation unless paired with meaningful user experience enhancements. Third, regulatory and classification frameworks are tightening around electronic consumer goods, influencing import procedures, material compliance, and end-of-life considerations. These dynamics create both friction and opportunity: firms that navigate compliance efficiently while embedding sustainable and convenient features into core product architecture are positioned to capture disproportionate share as the market expands. Understanding how these forces interact is essential for stakeholders evaluating entry points, expansion strategies, or portfolio reallocation within the broader home hygiene ecosystem.
Key Drivers Shaping Market Evolution
Technology Innovation and Product Refinement
The transition from basic infrared detection to refined sensing algorithms, improved battery management, and modular refill systems represents a meaningful shift in product value propositions. Recent product cycles reflect a clear emphasis on usability and durability, with multiple 2026 model upgrades introducing USB charging, adjustable dispensing levels, and enhanced waterproofing for both countertop and wall-mounted configurations. These improvements address long-standing consumer friction points around maintenance, battery replacement, and inconsistent flow control. Independent evaluations have further validated the importance of design integration, with rechargeable sensor pump dispensers ranking prominently in household use assessments based on aesthetic coherence, operational reliability, and battery efficiency. For manufacturers, the strategic implication is clear: hardware differentiation increasingly depends on subsystem performance and user experience refinement rather than stand-alone sensor presence. Companies that invest in feedback loops connecting consumer usage patterns with iterative design adjustments can reduce return rates, enhance satisfaction, and reinforce repeat purchase cycles across refill and accessory categories.
Policy, Regulatory Environment, and Classification Dynamics
Regulatory classification and trade policy continue to shape go-to-market pathways, particularly for electronically powered hygiene appliances. Customs rulings have classified battery-operated automatic soap dispensers under established mechanical appliance categories for liquid dispersion, a designation that influences tariff treatment, documentation requirements, and cross-border logistics planning. While classification clarity can streamline compliance, it also underscores the need for manufacturers and distributors to maintain accurate product specifications, material declarations, and technical documentation aligned with jurisdictional expectations. Beyond trade mechanics, sustainability expectations are increasingly embedded in procurement criteria and consumer preferences, prompting a shift toward recycled plastics and eco-friendly material inputs in dispenser construction. Firms that proactively align product architecture with environmental sourcing standards and transparent compliance practices reduce exposure to regulatory scrutiny while strengthening brand positioning in markets where sustainability has become a baseline purchase consideration rather than a peripheral feature.
Demand-Side Shifts in Household Hygiene Behavior
Demand patterns illustrate a durable preference for touchless hygiene solutions in bathroom and kitchen environments, where infrared sensors and adjustable volume controls have become expected rather than exceptional. This behavior is reinforced by heightened awareness of surface contact transmission and a broader cultural emphasis on convenience-oriented sanitation routines. Households increasingly view automatic dispensers as integrated components of vanity and kitchen organization, favoring products that combine discreet aesthetics with reliable operation. The demand environment also favors multi-use flexibility, with consumers evaluating dispensers based on compatibility with different soap formulations, ease of refilling, and suitability for family-scale usage. Manufacturers responding to these preferences are expanding product lines that balance tactile design with functional adaptability, recognizing that the purchase decision is increasingly influenced by how seamlessly the device integrates into daily routines rather than by standalone hygiene messaging. This evolving demand profile rewards product ecosystems that reduce friction across the ownership lifecycle.
Supply Chain and Cost Structure Pressures
Cost dynamics remain a central consideration as materials, electronics, and logistics inputs fluctuate across regions. Manufacturers are increasingly incorporating recycled plastics and alternative material blends to mitigate raw material volatility while aligning with sustainability expectations. At the same time, the proliferation of USB charging and enhanced waterproofing features introduces new component requirements that can affect bill-of-materials complexity. Supply chain resilience has therefore become a strategic differentiator: companies that diversify sourcing, standardize modular components, and optimize assembly workflows can maintain margin stability while adapting to regional demand shifts. Distribution pathways are also evolving, with online retail channels capturing a dominant share of household purchases and amplifying the importance of packaging efficiency, direct-to-consumer fulfillment, and reliable inventory turnover. In this environment, cost leadership alone is insufficient; sustained advantage depends on balancing input efficiency with product reliability and channel responsiveness.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a fragmented but increasingly specialized participant base, with firms pursuing distinct positioning strategies across design, durability, sustainability, and distribution. Stern Engineering Ltd. has built a reputation around premium touchless dispensers for residential and commercial settings, emphasizing sensor innovation and durable hands-free sanitary products. Hokwang Industries Co., Ltd. operates as an ISO-certified manufacturer offering automatic dispensers alongside complementary bathroom fixtures, with export reach across numerous countries and a focus on high-quality touchless models for household and commercial use. GOJO Industries, Inc. continues to leverage its hygiene brand equity through touch-free dispenser lines that highlight sustainable design elements for household and institutional applications, reinforcing a long-term sustainability narrative. Simplehuman, LLC occupies a high-end household niche with rechargeable sensor dispensers that emphasize aesthetics, battery efficiency, and touchless operation for kitchen and bathroom environments. Other participants, including Bradley Corporation, American Specialties, Inc., Bobrick Washroom Equipment, Inc., Sloan Valve Company, Ningbo Power (Joro), AIKE, and Hsumao Industrial Co., Ltd., extend the competitive field across commercial-grade durability, multi-feed systems, integrated plumbing compatibility, hospitality customization, and value-oriented household offerings.
PW Consulting
Several strategic patterns emerge across this landscape. First, premium design-oriented players are using independent validation and product testing visibility to reinforce credibility, as seen in recent rankings that highlight aesthetic and reliability performance for household models. Second, sustainability-oriented positioning is becoming a recurring theme, with manufacturers promoting enhanced eco-friendly design features and recycled material usage to differentiate beyond baseline functionality. Third, product cycle acceleration is evident, with multiple upgrades in early 2026 emphasizing USB charging, adjustable dispensing, and improved waterproofing, signaling a market that rewards rapid iteration and responsiveness to consumer feedback. These dynamics suggest a competitive environment where advantage is increasingly defined by the integration of design, compliance, and user experience rather than by category ownership alone.
The market structure is also showing signs of both consolidation pressure and segmental divergence. Larger hygiene and bathroom fixture players benefit from broader distribution, cross-selling opportunities, and institutional relationships, while specialized designers and regional manufacturers compete through targeted value propositions and customization flexibility. New entrants and private-label activity continue to intensify price competition in mainstream segments, yet they also expand total category availability and normalize touchless hygiene as a standard household expectation. Over time, this pattern is likely to encourage selective consolidation among mid-tier manufacturers while enabling niche leaders to maintain differentiation through design, sustainability, and service integration. For stakeholders, the strategic question is less about who leads today and more about which capability sets will determine resilience as the category matures.
Forward-Looking Trends and Strategic Implications
Looking ahead to the next three to five years, the household automatic soap dispenser market is likely to be shaped by three interlocking trends. First, product ecosystems will increasingly favor smart-adjacent features that enhance usability without overcomplicating the core experience. Adjustable dispensing, improved battery architectures, and better water resistance are early indicators of a trajectory in which users expect tighter control, longer service intervals, and more consistent performance across environments. Commercial opportunity lies in modular designs that allow incremental feature upgrades while preserving baseline reliability, enabling manufacturers to serve both entry-level and premium segments with shared platforms.
Second, sustainability and material transparency will move from differentiator to baseline expectation. As recycled plastics and eco-friendly construction become more prevalent, procurement decisions in both retail and institutional settings will increasingly weigh environmental sourcing alongside price and performance. This creates opportunities for brands that can substantiate material claims, streamline compliance documentation, and align product design with longer-term circular economy considerations. Firms that treat sustainability as an integrated design parameter rather than a surface-level feature will be better positioned to retain trust and defend margins.
Dispenser Pump Market
Third, channel dynamics will continue to reward manufacturers that can synchronize product availability with digital purchasing behavior while maintaining strong retail partnerships. Online channels already account for a substantial share of household purchases, and this distribution emphasis places a premium on packaging efficiency, predictable inventory flow, and clear product specifications that reduce return risk. At the same time, specialty stores and hypermarkets remain relevant for trial, comparison, and immediate availability in certain regions. The most resilient players will likely be those that can manage omnichannel consistency without overinvesting in redundant go-to-market structures. These trends carry inherent uncertainty, including potential shifts in material costs, regulatory classification updates, and varying regional adoption rates. Companies that monitor these variables closely and maintain flexible product roadmaps will be better equipped to adapt without sacrificing strategic focus.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the capabilities that matter most in a maturing category: reliable sensor performance, improved battery and charging architectures, adjustable dispensing, and material choices that support sustainability claims without compromising durability. Developing modular platforms can reduce time-to-market for incremental upgrades while preserving margin discipline. Emphasizing clear documentation for classification and material compliance will also strengthen supply chain predictability and reduce friction in cross-border distribution.
For investors, the most relevant signals are not simply top-line growth but the underlying drivers of share shifts: design credibility, sustainability positioning, channel execution, and the ability to iterate quickly without eroding quality. Companies that demonstrate consistent product validation, disciplined cost management, and coherent brand differentiation are better positioned to capture value as the market broadens. Portfolio evaluation should account for segmentation nuance, since countertop and wall-mounted formats, as well as foaming, liquid, and spray variants, serve distinct usage contexts and purchasing motivations.
For procurement and retail stakeholders, selection criteria should extend beyond unit price to include refill compatibility, maintenance burden, waterproofing and battery reliability, and alignment with consumer preferences for touchless hygiene in kitchen and bathroom settings. Structured evaluation frameworks that weigh total cost of ownership and user satisfaction can reduce downstream returns and strengthen category trust. As the market continues to evolve, timely access to detailed segmentation data, competitive tracking, and customized scenario planning becomes increasingly valuable for converting category momentum into measurable business outcomes.
Automatic Hand Dryers Market
For detailed analysis of this topic, please visit the official page: Worldwide Household Automatic Soap Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Tool Presetter Market: by Type (Manual Tool Presetter, Semi-Automatic Tool Presetter, Automatic Tool Presetter), Application (Automotive, Aerospace, Metalworking, Electronics, Medical, Others), Distribution Channels (Direct, Distributors, Online, Retail, VARs, Others), Technology (Optical, Contact, Laser, Digital, Magnetic, Others), Organization Size (Small, Medium, Large) and By Global Historical & Forecast Period (2020-2035) Comprehensive Study 2025
Read More - https://bussinessinsights.com/research-report/global-tool-presetter
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-presetter
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Market revenue for tool turrets is projected to grow steadily from 2020 to 2035, rising from $1,120 million in 2020 to an estimated $3,450 million by 2035. This trajectory highlights the sector's resilience and increased capital expenditure in automation solutions. The upward curve indicates robust demand, particularly in fast-growing manufacturing geographies and industries prioritizing digitalization, smart machining, and enhanced operational efficiency.
Read More - https://bussinessinsights.com/research-report/global-tool-turrets
The application landscape in 2025 sees automotive as the dominant sector for tool turret adoption because of high-volume and precision requirements, followed closely by aerospace and industrial machinery, driven by demand for quality, flexibility, and productivity in component manufacturing. Electronics and medical devices also represent significant market segments as micro-machining and precision finishing needs rise. Other sectors, including general engineering, contribute a smaller but steady share.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-turrets
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global tool sharpener market revenue is set to surge from $2,100 million in 2025 to approximately $3,590 million by 2035, reflecting robust CAGR fueled by increased demand for automated sharpening solutions and recurring investment from emerging markets. Notably, the acceleration post-2027 is marked by rapid industrial adoption and new product launches in IoT-enabled and CNC-based technologies. The industry’s revenue trajectory signals sustained momentum, anchored by strong end-user adoption and continuous innovation.
Read More - https://bussinessinsights.com/research-report/global-tool-sharpener
The Industrial segment dominates the application landscape for tool sharpeners in 2025, accounting for the highest market share due to widespread usage in manufacturing and heavy-duty maintenance. Residential applications also capture a significant share, underscored by DIY culture and increased home improvement activities. Commercial and Educational Institute applications continue to grow, supported by expanding technical curriculum and training programs. Workshops and other specialized environments add further diversity to the market, underlining the universal need for sharp, efficient tools across sectors.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-sharpener
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Wireless Communication Intelligent Module Market: Why 13.5% CAGR Reshapes Strategy
By PW Consulting, 2026-09-18
The Wireless Communication Intelligent Module Market: Navigating the Next Wave of Connectivity Growth
1. Market Landscape and Core Challenges
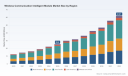
The wireless communication intelligent module market has entered a phase of sustained, high-velocity expansion. From 2020 through 2025, the sector compounded at a steady pace, crossing the twenty-five billion dollar threshold in the base year before accelerating into the forecast window. The growth trajectory points toward a double-digit compound annual growth rate through 2032, with revenue projections approaching sixty-two billion dollars by the end of the decade. This expansion reflects a structural shift rather than a cyclical upturn: intelligent modules are transitioning from peripheral connectivity components to core architectural elements in connected products across multiple verticals.
Geographic distribution of revenue reveals a market that is simultaneously mature in developed economies and rapidly scaling in emerging regions. Asia Pacific continues to generate the largest share of global revenue, driven by manufacturing density, consumer electronics demand, and accelerated industrial automation. North America and Europe maintain substantial, stable contributions, supported by automotive adoption, enterprise IoT deployments, and regulated connectivity standards. Latin America and the Middle East and Africa, while smaller in absolute terms, are expanding as infrastructure investment and digital transformation initiatives create new monetization pathways for wireless intelligent modules.
Technology segmentation further illustrates where value is concentrating. Cellular IoT dominates the technology mix, reflecting the broad applicability of licensed-band connectivity for mission-critical, mobility-heavy, and long-range deployments. Wi-Fi and Bluetooth remain essential for short-range, high-throughput, and cost-sensitive applications, particularly in consumer and enterprise environments. Low-power wide-area networks and satellite or ultra-wideband technologies occupy smaller but strategically important positions, enabling niche use cases in remote monitoring, asset tracking, and specialized positioning scenarios. On the application side, automotive and transportation represent the largest demand pool, followed by industrial IoT and consumer electronics. Smart city and utilities, along with healthcare, contribute meaningful but comparatively narrower revenue streams, each with distinct regulatory, reliability, and integration requirements.
Several structural challenges are shaping the market's inflection points. First, the competitive landscape is moderately concentrated, with a small group of established players accounting for the majority of global revenue. This concentration creates both pricing discipline and barriers for newcomers, while also intensifying pressure on incumbents to differentiate through performance, certification breadth, and application-specific optimization. Second, the industry is navigating a transition from volume-driven growth to value-driven design. Customers increasingly demand modules that integrate processing capability, edge intelligence, security features, and multi-standard interoperability rather than standalone connectivity silicon. This shift requires deeper engineering collaboration, longer qualification cycles, and more sophisticated lifecycle management. Third, supply chain and infrastructure dynamics are introducing new cost and timing variables. Rising material and deployment costs in adjacent infrastructure segments, including fiber and broadband construction, indirectly influence the economics of network-dependent modules by shaping rollout timelines and total cost of ownership for end customers.
These pressures do not diminish the market's growth potential; rather, they redefine where competitive advantage will be earned. Companies that align product roadmaps with regulatory momentum, application-specific reliability needs, and cost-aware design will be better positioned to capture share as the market matures. Understanding these inflection points is essential for any organization evaluating product strategy, procurement planning, or investment allocation in the wireless intelligent module space.
2. Key Drivers Shaping Market Trajectory
The market's expansion is not being pulled by a single force. Instead, several interlocking drivers are reinforcing each other, creating a compounding effect on demand, product evolution, and competitive behavior.
PW Consulting Information & Electronics Research Center
Technical innovation remains the most visible driver. Intelligent modules are increasingly defined by their ability to combine connectivity with on-device processing, improved power efficiency, and multi-protocol support. The emergence of reduced-capability cellular variants, such as RedCap, illustrates how the industry is expanding the addressable design space between full-featured 5G modules and low-bandwidth alternatives. These intermediate solutions enable manufacturers to deploy richer sensing, telemetry, and edge-computing functions without the cost and power profiles of flagship cellular platforms. Similarly, the integration of positioning, short-range radios, and cellular capabilities into unified intelligent module architectures is reducing integration complexity for OEMs and system integrators. The practical effect is faster time to market for connected products and a broader set of applications that can justify wireless connectivity in previously cost-sensitive or power-constrained contexts.
Regulatory and spectrum policy dynamics are another powerful catalyst. Authorities in key markets are altering the operating environment in ways that directly affect module demand and design choices. Recent rule changes aimed at easing technology transitions from legacy networks to IP-based infrastructure are reducing friction for operators and enterprises preparing for next-generation connectivity. Parallel efforts to expand the commercial spectrum pipeline create longer-term optimism around capacity, coverage, and new service models that can rely on wireless intelligent modules as enabling hardware. In specific regions, certification pathways and regulatory approvals are also becoming more structured, which helps module suppliers plan product lifecycles and gives end customers greater confidence in long-term support. At the same time, ongoing work to modernize spectrum sharing and allocate mid-band spectrum for advanced wireless services is shaping which standards and frequency bands module developers prioritize in their roadmaps.
Demand-side behavior is evolving as enterprises and consumers reassess what connected products must deliver. Purchasing decisions are increasingly influenced by total cost of ownership, reliability under real operating conditions, and the ability to support future feature upgrades without hardware replacement. In automotive and transportation, connectivity is no longer limited to infotainment or basic telemetry; it is becoming integral to fleet optimization, safety-related communications, and infrastructure interaction. In industrial IoT, the emphasis is shifting toward modules that can withstand harsh environments, maintain secure and deterministic communication, and support integration with analytics and automation workflows. Consumer electronics demand continues to reward compact, energy-efficient, and multi-standard solutions that can serve diverse usage scenarios without fragmenting bill-of-materials complexity. These preferences are pushing module suppliers to offer more application-tailored configurations, reference designs, and certification packages rather than generic connectivity components.
Supply chain and cost structure changes are adding both friction and opportunity. On one hand, input cost volatility and infrastructure deployment pressures in adjacent segments can complicate planning for network-dependent products. Rising material and labor costs in broadband and fiber deployment, for example, can influence rollout pace and indirectly affect the timing of demand for certain connectivity modules. On the other hand, these pressures are encouraging more disciplined design practices, including greater use of standardized form factors, platform-based development, and supplier partnerships that can share qualification risk. Companies that can stabilize lead times, manage component sourcing across regions, and provide clear migration paths between technology generations are gaining trust in segments where downtime or redesign cost is unacceptable.
Taken together, these drivers point to a market in which product excellence, regulatory awareness, and application-specific value creation matter as much as raw connectivity performance. Players that treat intelligent modules as part of a broader system solution, rather than as commoditized radio components, are likely to capture disproportionate value as demand broadens and matures.
3. Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of global specialists, region-rooted scale players, and operator-affiliated or diversified technology firms. The leading companies share a common strategic imperative: build credible application coverage while differentiating on reliability, certification depth, platform integration, and lifecycle support.
Worldwide Wireless Communication Systems Market
Several established players have anchored their positions through broad cellular IoT portfolios and extensive certification footprints. These companies typically compete on the strength of their product breadth across 5G, LTE, low-power wide-area, and positioning technologies, as well as their ability to support automotive, industrial, and enterprise use cases with pre-validated designs. Their advantage often lies in offering customers a predictable migration path across generations, reducing qualification risk, and maintaining long-term availability for deployed systems. In practice, this means leading module suppliers are investing not only in silicon selection but also in firmware support, security frameworks, and regional compliance packages that make it easier for OEMs to scale across markets.
Other strong competitors have built differentiation through specialization. Some focus on high-reliability and security-oriented modules for industries where failure is not an option, emphasizing robust architectures, traceability, and certification for demanding environments. Others concentrate on cost-effective cellular and wireless solutions that address price-sensitive IoT, machine-to-machine, and smart applications, using lean product structures and efficient manufacturing to compete on value. A further group emphasizes embedded wireless modules for consumer electronics, industrial equipment, and automotive applications, leveraging integration expertise and compact form factors to serve design-constrained products. Operator-affiliated providers add yet another angle, drawing on network relationships and shipment scale in cellular IoT to support integrated connectivity solutions.
Recent product and market activity underscores how competition is evolving from catalog expansion to targeted, application-driven launches. In early 2026, multiple companies introduced or expanded 5G-capable modules and platform integrations designed for specific deployment contexts. New 5G NR sub-6 module series with platform-based architectures and railway-ready variants signaled growing attention to mobility, public-transport, and specialized communication standards. Parallel expansions in reduced-capability 5G portfolios reflected efforts to capture mid-tier use cases that need more capability than legacy low-power options but do not require full flagship performance. At the same time, flagship fixed-wireless and CPE-oriented solutions combining advanced 5G modules with high-performance processor platforms showed how module suppliers are increasingly positioning themselves within broader system-level solutions rather than selling connectivity in isolation.
Certification and market-access moves are equally important. Securing regional approvals for LTE Cat 1 bis and similar efficiency-focused modules illustrates how suppliers are building out addressable markets in geographies where cost, power, and coverage trade-offs favor leaner cellular options. Trade show showcases featuring next-generation IoT modules, AI-oriented platforms, and advanced 5G connectivity further highlight the industry's emphasis on embedding intelligence and future-proofing designs for evolving workloads. Collectively, these developments suggest a market where competitive advantage is being earned through a combination of technical readiness, regional compliance, and the ability to align module capabilities with application roadmaps.
Looking at the broader structure, the market appears to be moving toward selective consolidation in certain segments and continued fragmentation in others. In high-volume, standardized segments, scale, cost efficiency, and certification breadth will reward larger, well-resourced players. In specialized or vertically demanding applications, differentiation through reliability, integration, and domain expertise can sustain smaller or more focused competitors. New entrants face a real barrier in certification lead times, supply chain credibility, and the need to demonstrate long-term support, but targeted opportunities remain in emerging applications, region-specific requirements, and architectures that combine connectivity with edge intelligence in novel ways. The most resilient strategies are likely those that balance scale with specialization, allowing companies to serve broad demand while retaining the flexibility to win in higher-value niches.
4. Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market will likely be shaped by three interlocking trends. First, intelligent modules will increasingly be evaluated as integrated system enablers rather than radio components. Buyers will expect stronger combinations of connectivity, processing efficiency, security, and application-specific certification in a single design path. This trend favors suppliers that can offer cohesive platforms and reference architectures, and it raises the importance of firmware, lifecycle management, and migration planning.
Second, the spectrum and regulatory environment will continue to influence product priorities. Policy moves that ease network modernization and expand commercial spectrum access should support long-term demand for advanced wireless modules, while regional certification and sharing rules will keep shaping which standards and bands receive the most engineering focus. Companies that monitor regulatory timelines and align product roadmaps accordingly will be better positioned to capture emerging opportunities without costly redesigns.
Third, application demand will keep diversifying in ways that reward tailored solutions. Automotive and transportation, industrial IoT, and consumer electronics will remain core growth engines, but the most interesting margin opportunities may come from specialized deployments where reliability, power constraints, or integration complexity create room for higher-value module designs. Smart city, utilities, and healthcare will contribute incremental but strategically meaningful demand, especially where secure, dependable connectivity is non-negotiable.
These trends carry both opportunity and risk. On the opportunity side, broader intelligent module adoption opens the door to platform-based revenue models, longer customer relationships, and cross-selling into security, positioning, and edge-processing add-ons. On the risk side, input cost volatility, infrastructure deployment delays, certification bottlenecks, and the ongoing concentration of share among leading players can compress margins and raise entry barriers. Organizations that plan for these dynamics by diversifying supply, prioritizing application-relevant differentiation, and investing in regulatory readiness will be better prepared to convert market growth into durable commercial advantage.
5. Strategic Implications for Decision-Makers
For manufacturers and product leaders, the near-term priority is to align module selection with application realities rather than treating connectivity as a commodity input. The most effective strategies typically combine platform-based development, proactive certification planning, and clear migration paths across technology generations. Where possible, companies should evaluate suppliers not only on unit cost but also on qualification support, regional compliance coverage, power-performance balance, and the ability to support future feature upgrades without full hardware redesign.
For investors, the market offers a nuanced picture. Growth is robust, but value creation is increasingly concentrated in players that can combine scale with application-specific differentiation and disciplined lifecycle management. Due diligence should focus on product roadmaps, certification momentum, supply chain resilience, and exposure to both high-volume standards and specialized high-reliability segments. Companies that can demonstrate repeatable wins in demanding applications while maintaining cost competitiveness are likely to command more durable positioning than those competing primarily on price in commoditizing segments.
WiFi Modules Market
For procurement and procurement-led organizations, the strategic task is to balance cost, availability, and long-term support risk. Multi-source strategies, clear technical requirements for security and reliability, and early engagement with suppliers on regional certifications can reduce exposure to lead-time shocks and redesign costs. Establishing performance and compliance criteria before specification freezes helps ensure that module choices support both immediate deployment goals and future scalability.
Given the pace of product launches, regulatory activity, and application expansion, staying current with detailed segment data, competitive moves, and region-specific requirements is increasingly important. Deeper analysis of subsegments, technology transitions, and supplier-by-supplier positioning can help decision-makers refine product roadmaps, investment theses, and sourcing strategies with greater precision. For those seeking a fuller picture of market sizing by segment, competitive dynamics, and scenario-based guidance, the complete PW Consulting report provides the structured detail needed to support more granular planning decisions.
For detailed analysis of this topic, please visit the official page: Wireless Communication Intelligent Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com