

Blogs
PW Consulting: Global Smart Carry-on Bags Market Hits $1.45B in 2025 with 13.42% CAGR to 2032
By PW Consulting, 2026-09-17
Global Smart Carry-on Bags Market: Strategic Intelligence for 2026 and Beyond
The global travel accessories industry is undergoing a profound technological transformation, driven by the convergence of mobility, connectivity, and stringent safety regulations. At the forefront of this evolution is the smart carry-on bag segment, a category that has rapidly shifted from a niche novelty to a mainstream necessity for the modern traveler. As businesses navigate an increasingly complex landscape defined by fluctuating consumer preferences, evolving aviation safety standards, and intense competitive pressure, access to precise, forward-looking market intelligence is no longer optional—it is a strategic imperative.
PW Consulting is pleased to introduce our comprehensive Worldwide Smart Carry-on Bags Market research report, a definitive resource designed to equip executives, product strategists, and investors with the actionable insights needed to capitalize on the opportunities emerging in 2026 and throughout the forecast period ending in 2032. This article serves as a strategic preview of the report's depth, outlining the macroeconomic trajectory, competitive dynamics, and regulatory forces shaping this high-growth market.
Macroeconomic Trajectory: Sustained Expansion Through 2032
The smart carry-on bags market has demonstrated remarkable resilience and growth acceleration over the past half-decade. Our analysis tracks historical performance from 2020 through the base year of 2025, revealing a consistent upward trajectory that underscores the segment's maturation. Market revenue has expanded substantially over this period, reflecting the broader integration of technology into travel goods and the rising disposable income of frequent flyers worldwide.
Looking ahead, the market is projected to maintain robust momentum. The compound annual growth rate (CAGR) for the forecast period spanning 2026 to 2032 is estimated at 13.42%, signaling a period of sustained double-digit expansion. This growth rate is supported by multiple reinforcing factors, including the post-pandemic recovery of business and leisure travel, the increasing sophistication of smart hardware, and the growing consumer willingness to pay a premium for convenience-centric travel solutions. Revenue valuations across the forecast horizon indicate a clear pathway toward significant market valuation by the early 2030s, presenting a compelling window for stakeholders to position themselves advantageously.
Worldwide Smart Carry-on Bags Market
However, raw growth figures only tell part of the story. The true strategic value lies in understanding the underlying drivers, the shifts in regional demand patterns, and the technological adoption curves that will dictate market share distribution. Our report deconstructs these macro trends with granular precision, offering a roadmap that aligns corporate strategy with foreseeable market realities.
Report Contents: A Framework for Actionable Decision-Making
The Worldwide Smart Carry-on Bags Market report is structured to provide a holistic yet focused analysis of the industry ecosystem. Beyond high-level sizing, the study delivers a multi-dimensional perspective that addresses the critical variables influencing commercial success. Readers will gain access to detailed segmentation analysis that dissects the market across key dimensions, including technology integration, sales channel performance, and regional demand characteristics.
The technology landscape within smart carry-on bags is particularly dynamic. Our report evaluates the adoption and commercial impact of features such as GPS and Bluetooth tracking, USB charging capabilities coupled with integrated power bank pockets, digital weight sensors, and advanced biometric or remote locking systems. Understanding the relative market penetration and consumer valuation of each technology cluster is essential for product development teams prioritizing feature roadmaps and for marketing divisions crafting value propositions. The report further examines how these technologies interplay with airline compliance requirements, a critical consideration that directly affects product design and market accessibility.
In addition to technological segmentation, the study provides an in-depth assessment of sales channel dynamics. The shift toward online e-commerce platforms has reshaped how smart luggage is distributed and discovered, yet specialty stores and duty-free retail environments continue to play strategic roles in specific consumer segments. By analyzing the revenue contributions and growth trajectories associated with each channel, the report enables stakeholders to optimize their go-to-market strategies and allocate resources toward the most effective distribution pathways.
Geographically, the report offers a nuanced view of regional market landscapes, highlighting the distinct growth rates, consumer behaviors, and competitive intensities that characterize different territories. This regional granularity allows multinational corporations to tailor their market entry or expansion strategies with precision, while regional players can benchmark their performance against global trends.
Competitive Landscape: Navigating an Evolving Roster of Innovators
The smart carry-on bags market is characterized by a diverse array of established luggage manufacturers, premium lifestyle brands, and technology-forward startups, each pursuing distinct value propositions and business models. Our report provides detailed company profiles and competitive assessments for key industry participants, offering stakeholders a clear view of the strategic positioning and product innovations that define the current market phase.
Leading the premium segment are firms such as Samsonite International S.A. and TUMI Holdings, Inc., which have leveraged their brand heritage to introduce smart lines that blend connectivity, security, and durability. Samsonite's EVOA TECH series, for example, integrates built-in weighing scales, fingerprint TSA locks, Bluetooth proximity trackers, and USB charging capabilities, reflecting a comprehensive approach to traveler convenience. TUMI continues to target the business traveler demographic with offerings that emphasize connectivity and charging functionality within a sophisticated design language.
Direct-to-consumer and premium lifestyle brands have also made significant inroads. Away Travel Inc. has built a strong market presence through durable polycarbonate designs and smart features like removable batteries for USB charging, coupled with an organized interior ecosystem that appeals to both functionality and aesthetics. Similarly, Arlo Skye Inc. and Delsey Paris have focused on delivering airline-compliant smart carry-ons, with Delsey notably expanding into lithium-free connected options such as its Pluggage line, a strategic response to tightening battery regulations.
Other notable players include Travelpro International, Inc., whose Platinum Elite series features external USB A and C fast-charging ports and dedicated patent-pending battery compartments designed for FAA compliance, and Heys, which markets its SmartLuggage series of hardside spinner carry-ons with integrated smart features tailored to airline-approved travel. European innovation is represented by Horizn Studios GmbH and Rimowa, the latter combining high-end aluminum construction with integrated smart elements that cater to the luxury segment. Meanwhile, Samsara Luggage, Inc. specializes in aluminum smart suitcases with app-based connectivity features, including movement alerts and opening notifications, appealing to security-conscious consumers.
At the intersection of mobility and luggage, Airwheel Holding Ltd. has pursued a differentiated path by developing rideable and motorized smart carry-on suitcases that incorporate smart mobility features, pushing the boundaries of what a carry-on can achieve. This diversity of approaches underscores the importance of strategic clarity: companies must decide whether to compete on premium luxury, technological integration, regulatory compliance, affordability, or mobility innovation, and our report provides the analytical framework to evaluate these strategic choices against market realities.
Industry Dynamics: Regulation, Innovation, and the Road Ahead
The smart carry-on bags market does not operate in a vacuum; it is deeply influenced by regulatory environments, industry events, and shifting safety protocols. One of the most critical dynamic factors shaping product design and market viability is the regulatory treatment of lithium-ion batteries. Guidelines from the International Air Transport Association (IATA) and various aviation authorities mandate that lithium-ion batteries in smart luggage must be removable for checked baggage acceptance. Non-removable batteries restrict bags to carry-on only, with capacity limits typically capped at 100 Wh. These requirements have compelled manufacturers to engineer battery compartments and connectivity solutions that align with safety standards without compromising user experience.
These regulatory pressures intensified further with effective updates to dangerous goods regulations in 2026, which tightened rules for lithium batteries and power banks in smart luggage across multiple aviation authorities. In parallel, individual carriers have moved to enforce stricter policies; airlines such as Frontier and Spirit have explicitly prohibited smart luggage with non-removable lithium batteries as either carry-on or checked baggage due to safety risks. These regulatory developments have direct implications for product portfolios, requiring ongoing compliance monitoring and, in some cases, product redesigns or the introduction of alternative battery chemistries.
Beyond regulation, industry events continue to signal the pace of innovation. The 2025 Travel Goods Show, organized by the Travel Goods Association, featured record-breaking new product launches and innovations from luggage brands, with a notable emphasis on smart and tech-enabled carry-ons. Such gatherings highlight the industry's commitment to pushing technological boundaries while responding to consumer demand for smarter, more secure, and more convenient travel gear.
Consumer media and review platforms also play a vital role in shaping market perception and purchasing decisions. In March 2026, Travel & Leisure published updated testing and recommendations for smart luggage pieces, highlighting products such as the Heys SmartLuggage, the Aotos L2 rideable suitcase, and the July Carry On with CaseSafe. These independent evaluations help refine consumer expectations and influence brand visibility, making real-time awareness of media narratives an important component of market strategy.
Strategic Imperatives for 2026 and the Forecast Horizon
As the market moves through its forecast period spanning 2026 to 2032, executives and strategists must address several foundational questions. How will regulatory evolution reshape the competitive balance between brands that have already embraced removable battery architectures and those that lag? Which technology features will deliver the strongest return on investment as consumers become more discerning about their smart luggage purchases? How will channel strategies adapt as e-commerce continues to capture share while specialty and duty-free retail maintain relevance in specific contexts? And how should companies position themselves regionally to maximize growth in markets with differing travel behaviors and purchasing power?
The Worldwide Smart Carry-on Bags Market report is designed to answer these questions with rigor and clarity. It provides the data-driven foundation necessary to evaluate investment priorities, align product development with emerging standards, and anticipate shifts in competitive dynamics before they become apparent in public market signals. The study also examines market concentration metrics, offering context on the degree of consolidation and the strategic implications of competitive density within the industry.
Luggage Bags Market
Market leaders and challengers alike will find value in the report's structured approach to forecasting, segmentation, and competitive benchmarking. Whether the objective is to identify white-space opportunities, refine pricing and feature strategies, optimize distribution networks, or assess the viability of new market entries, the intelligence contained within this study is calibrated to support decisive action.
Access the Complete Intelligence
This overview provides a high-level perspective on the growth trajectory, competitive dynamics, and regulatory forces defining the worldwide smart carry-on bags market. However, the full strategic value of this research lies in its detailed segmentation analysis, proprietary forecasts, regional breakdowns, and in-depth company evaluations—elements that are essential for translating market awareness into executable strategy.
We invite industry executives, product leaders, investors, and analysts to access the complete report for a comprehensive exploration of the data, insights, and recommendations that will shape decision-making throughout 2026 and the forecast period extending to 2032. PW Consulting remains committed to delivering the analytical precision and strategic clarity necessary to navigate complex markets with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Carry-on Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FPSO Market to Hit $21.1B by 2032, Powered by 7.34% CAGR and Deepwater Growth
By PW Consulting, 2026-09-17
Strategic Imperatives in the Global FPSO Market: Navigating Growth Through 2032
The global offshore energy landscape is undergoing a structural transformation, driven by the interplay of deepwater resource development, evolving service delivery models, and shifting macroeconomic conditions. As operators seek to maximize asset utilization while managing capital expenditure, Floating Production Storage and Offloading (FPSO) equipment has emerged as a critical enabler of offshore field development. The Worldwide Floating Production Storage and Offloading Equipment Market study provides a comprehensive lens into this evolving ecosystem, offering decision-makers the analytical rigor required to navigate the forecast period from 2026 through 2032.
Our latest market research captures the momentum building across the sector. The overall market valuation expanded from approximately US$9.0 billion in 2020 to an estimated US$12.9 billion in 2025, reflecting sustained demand across multiple offshore basins. Looking ahead, the market is projected to follow a compound annual growth rate of 7.34 percent, reaching a substantial valuation by the end of the forecast window. This trajectory underscores a sector that is not merely recovering from cyclical downturns but is being reshaped by structural demand drivers, technological standardization, and changing commercial arrangements.
The strategic value of this analysis lies in its ability to translate macroeconomic and project-level signals into actionable intelligence. For executives evaluating capacity allocation, supply chain partnerships, or fleet expansion strategies, the report delineates where value pools are forming, which commercial models are gaining traction, and how competitive dynamics are consolidating around a set of capable, globally positioned players. Rather than offering static snapshots, the study maps the interplay between equipment categories, water depth classifications, and regional project pipelines, enabling stakeholders to anticipate shifts in procurement timing, scope definition, and risk allocation.
Market Trajectory and Core Dynamics
The growth path reflected in the data is neither linear nor uniform. Market expansion between 2020 and 2025 was characterized by incremental gains punctuated by project sequencing decisions, contract negotiation cycles, and the influence of input cost dynamics. Going forward, the forecast period reveals a more pronounced acceleration, with yearly valuations climbing steadily as project awards translate into fabrication, conversion, and installation activity. This pattern highlights the importance of understanding lead-time sensitivity and the cascading effects of final investment decisions on equipment demand.
Worldwide Floating Production Storage and Offloading Equipment Market
Several structural dynamics are reshaping how FPSO projects are conceived and executed. Lease-and-operate contracts have gained considerable share in recent award cycles, reflecting a broader industry preference for models that reduce upfront operator capital exposure while transferring operational responsibility to specialized providers. This shift toward turn-key, lease-based arrangements is altering the risk-reward calculus for both operators and equipment suppliers, favoring entities with strong execution track records, financial flexibility, and the ability to manage long-duration charters.
Regional content requirements and local supply chain development continue to influence project economics in key basins. In certain jurisdictions, regulatory frameworks designed to foster domestic industrial capacity can increase project budgets while simultaneously expanding the pool of trained personnel and supporting suppliers. Understanding these trade-offs is essential for bidders and investors evaluating entry strategies, as compliance costs and schedule implications can materially affect bid competitiveness and margin structures.
Macro energy pricing and supply environment conditions further modulate investment decisions. Variations in benchmark crude pricing and gas market dynamics influence the economic viability of offshore development schemes, particularly for projects with higher breakeven thresholds. At the same time, the push toward decarbonized operations is starting to inform equipment specification decisions, with operators increasingly favoring concepts that reduce greenhouse gas emissions intensity through electrification, process optimization, and integrated subsea-to-topsides design. These considerations are becoming embedded in procurement criteria and are reshaping the competitive differentiation of equipment and service providers.
Equipment Segmentation, Water Depth, and Geographic Distribution
The FPSO equipment market is inherently multi-dimensional, spanning process equipment, mooring and marine systems, power generation and distribution, and safety and control systems. Each category carries distinct technology requirements, supply chain dependencies, and margin profiles. Process equipment typically anchors the scope definition of an FPSO, reflecting the central role of separation, treatment, and process control in field development plans. Mooring and marine systems remain critical to station-keeping reliability and operational safety, particularly in exposed environments and ultra-deepwater settings. Power generation and distribution systems, alongside safety and control architectures, are increasingly scrutinized for their contribution to overall energy efficiency and compliance with evolving operational standards.
Water depth classification further differentiates demand patterns and engineering complexity. Shallow water projects continue to support a meaningful share of activity, often leveraging mature designs and established fabrication pathways. Deepwater deployments represent the largest demand concentration, reflecting the migration of development activity into more challenging environments where FPSO flexibility offers distinct logistical and economic advantages. Ultra-deepwater applications, while smaller in relative terms, are characterized by higher technical barriers, customized engineering, and longer execution cycles, making them focal points for specialized contractors and technology leaders.
Geographic distribution of demand is similarly varied, with activity concentrated across multiple offshore basins. Latin America remains a dominant demand center, supported by extensive pre-salt programs and ongoing fleet expansion. Asia Pacific continues to contribute a significant share, driven by regional field developments and conversion activity. Africa maintains a steady presence as operators advance new projects and extend the life of existing facilities. Europe and the Middle East and North America region also represent relevant demand pockets, often associated with specific field developments, conversion opportunities, and technology demonstration projects. Importantly, the relative weight of these regions is not static; it evolves with the timing of final investment decisions, the pace of regulatory approvals, and the competitive dynamics of local content and supply chain readiness.
Worldwide Subsea Well Access And BOP System Market
Commercial Models and Project Delivery Evolution
The way FPSO capacity is procured and operated has become as strategically important as the equipment itself. Operators are increasingly evaluating total cost of ownership, schedule certainty, and operational flexibility when selecting between newbuilds, conversions, and lease-based arrangements. Conversion programs offer potential schedule and cost advantages by repurposing existing hull structures, while newbuilds provide design freedom andthe ability to incorporate latest-generation process and decarbonization features. The choice between these pathways often hinges on fleet availability, yard capacity, hull integrity assessments, and the specific production profile of the target field.
Standardization initiatives are beginning to influence procurement efficiency. The emergence of standardized hull concepts and modular delivery approaches is reducing engineering redundancy, compressing cycle times, and improving predictability for repeated project types. For suppliers and operators alike, standardization can unlock economies of repetition, simplify spare parts management, and enhance the bankability of lease-and-operate structures by reducing performance uncertainty across multiple units.
At the same time, the industry is witnessing the continued maturation of integrated delivery models. Engineering, procurement, construction, installation, and commissioning scope is increasingly bundled across multiple disciplines, including subsea systems, topsides, hull fabrication, and marine operations. Such integration can reduce interface risk, improve schedule alignment, and facilitate single-point accountability, but it also demands robust project controls, supply chain coordination, and commercial structuring. Stakeholders evaluating partnership strategies should assess not only technical capability but also the commercial architecture through which risks and rewards are shared across the project lifecycle.
Competitive Landscape and Key Players
The FPSO market is defined by a mix of specialized offshore service companies, major shipbuilders, and operator-driven project constituencies. A consolidated set of firms commands a significant share of activity, with the top three participants accounting for roughly 38.4 percent of market revenue and the top five reaching approximately 52.15 percent. This concentration reflects the capital intensity, technical complexity, and execution risk associated with FPSO projects, which tend to favor organizations with established fleet management capabilities, strong balance sheets, and long-term operator relationships.
SBM Offshore stands out for its global leadership in FPSO design, engineering, construction, installation, and lease/operate models, supported by standardized hull concepts and a substantial backlog anchored in deepwater projects across Guyana and Brazil. MODEC has built a strong reputation in EPCI and charter/operate arrangements, particularly for ultra-deepwater and harsh environment applications, with multiple active units and recent contract wins in Brazil pre-salt and Guyana. BW Offshore continues to provide FPSO ownership, leasing, and operations, with an active footprint across Brazil, Africa, and advancing projects such as Bay du Nord, while Yinson Holdings has expanded its leasing and operations portfolio with recent Brazilian deployments including Anna Nery and Maria Quiteria units.
Bumi Armada contributes design, construction, and operations capabilities with a focus on Southeast Asia and international markets, and Bluewater Energy Services delivers specialized turret mooring systems and FPSO/FSO units with expertise in harsh environments and marginal field developments. On the engineering and integration side, Saipem offers integrated EPCI services spanning subsea and topsides across multiple offshore basins, while TechnipFMC provides subsea and topside integration often in partnership with hull specialists. Keppel Offshore & Marine and Samsung Heavy Industries represent major shipyard capabilities in FPSO construction and conversions, supporting Asian and global projects, and HD Hyundai Heavy Industries adds significant capacity for deepwater hull and topsides fabrication.
The operator side is equally influential. Petrobras remains a major charterer and operator of FPSOs in Brazil's pre-salt fields, with an extensive fleet and an ongoing newbuild program, including recent final investment decisions on SEAP-scheme units awarded to SBM Offshore under build-operate-transfer arrangements. ExxonMobil continues to drive significant demand through multiple FPSO developments in the Guyana Stabroek block. These operator-led programs not only shape demand volumes but also influence technology specifications, procurement timing, and the competitive positioning of equipment and service providers.
Recent Project Developments and Demand Signals
Recent milestones illustrate the pace and direction of market activity. In early 2026, Petrobras reached a final investment decision on the SEAP scheme, awarding SBM Offshore the P-81 and P-87 FPSOs under a build-operate-transfer model, reinforcing the continued expansion of Brazil's pre-salt fleet and the preference for collaborative delivery structures. Around the same time, Hunting secured a significant equipment supply contract for an FPSO offshore Guyana, highlighting the breadth of demand across different equipment categories and the continued inflow of fabrication and supply awards tied to major operator programs.
In the second half of 2025, MODEC received an award for the FPSO Hammerhead for ExxonMobil in Guyana, contributing to a notable surge in order activity and underscoring the strength of ultra-deepwater demand in the region. BW Offshore advanced its Bay du Nord FPSO project with Equinor, completing pre-FEED activities and initiating long-lead equipment ordering, a signal that new project fronts are moving into execution-ready phases. Separately, the BW Opal FPSO arrived at the Barossa gas field and progressed through hookup and final commissioning activities ahead of first gas, demonstrating the operational transition from construction to production that characterizes mature project cycles.
Collectively, these developments point to a market where demand is being driven by multiple concurrent programs, with Brazil and Guyana acting as focal points, while additional basins contribute incremental but strategically relevant activity. For market participants, the implication is clear: visibility into award timing, scope composition, and delivery sequencing is essential for aligning capacity, securing contracts, and managing cycle-time risk.
Strategic Takeaways for 2026 Decision-Making
As organizations formulate their strategies for the 2026 to 2032 horizon, several priorities emerge. First, demand visibility should be anchored in a disciplined view of final investment decision timing, project award cycles, and the lag between contract execution and equipment fabrication. Second, commercial model selection is increasingly consequential, with lease-and-operate structures reshaping capital allocation and risk transfer; stakeholders should evaluate the implications for balance sheet exposure, operational control, and long-term profitability. Third, supply chain resilience and yard capacity must be assessed against the backdrop of concentrated demand in specific regions and water-depth segments, where competition for engineering talent, hull slots, and long-lead equipment can create bottlenecks.
Fourth, technological differentiation is becoming a decisive competitive factor. Standardization, electrification concepts, process efficiency improvements, and integrated subsea-to-topsides design are not merely engineering optimizations; they are becoming commercial differentiators that influence operator preferences and lease economics. Fifth, regulatory and local content environments require careful navigation, particularly in markets where compliance costs and domestic supply chain development intersect with project economics and schedule risk.
Finally, the concentration of market revenue among a limited set of players suggests that partnership strategy matters. Whether through joint ventures, EPCI alliances, charter structures, or technology partnerships, the ability to assemble credible, execution-ready consortia will be central to securing a position in a market where trust, track record, and financial strength are heavily weighted in award decisions.
The Worldwide Floating Production Storage and Offloading Equipment Market report is designed to provide the analytical foundation for these decisions. It integrates macro market size and growth trajectory with granular segmentation, competitive profiling, recent project developments, and sector-specific dynamics, enabling stakeholders to move from high-level awareness to targeted strategic action. By mapping where demand is forming, how it is being structured, and which organizations are positioned to capture it, the study equips executives, investors, and project planners with the intelligence needed to allocate resources, shape partnerships, and anticipate the next wave of market opportunity.
For detailed analysis of this topic, please visit the official page: Worldwide Floating Production Storage and Offloading Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trading to $2.3B by 2032: PW Consulting Notes 6.92% CAGR in Global Topical Dispenser Market
By PW Consulting, 2026-09-17
Strategic Intelligence for the Global Topical Dispenser Market: Navigating Growth and Precision in 2026 and Beyond
The worldwide topical dispenser market stands at a critical inflection point. As healthcare systems increasingly prioritize precise drug delivery, infection control, and patient-centric formulation design, the mechanisms that govern how creams, gels, lotions, and topical adhesives reach their intended site of action have evolved from simple packaging components into indispensable clinical enablers. For executives, procurement leaders, and R&D strategists operating across pharmaceutical, dermatology, cosmetics, and personal care value chains, understanding the structural forces shaping this segment is no longer optional. It is a core determinant of competitive positioning, supply chain resilience, and regulatory readiness through the end of the decade.
This article outlines the strategic rationale behind PW Consulting’s latest worldwide topical dispenser market study, a comprehensive intelligence framework designed specifically to equip decision-makers with actionable clarity for 2026 planning. Rather than offering static snapshots, the research maps the interplay of demand fragmentation, manufacturing precision, regulatory scrutiny, and competitive consolidation that will define the next seven years of market evolution.
The Macro Trajectory: Mapping a Seven-Year Expansion Cycle
Over the historical window from 2020 through 2025, the topical dispenser market demonstrated consistent upward momentum, reflecting cumulative shifts in compounding pharmacy workflows, hospital formulary modernization, and consumer-facing skincare innovation. That trajectory sets the stage for the forecast period spanning 2026 to 2032, during which the global market is projected to expand at a compound annual growth rate of 6.92 percent. By the close of the forecast horizon, total revenue is expected to surpass the two-billion-dollar threshold in USD terms, underscoring a market that has matured beyond niche clinical applications into a broadly integrated distribution ecosystem.
For strategic planners, the significance of these headline figures lies not in the numbers themselves but in what they reveal about underlying demand elasticity. Growth is being distributed across multiple innovation vectors: the continued adoption of airless pump architectures that protect sensitive active ingredients from oxidation and microbial contamination, the steady utilization of metered-dose tubes and click-dosing mechanisms that standardize compound preparation, and the expanding role of dual-chamber systems that maintain ingredient separation until point-of-use. Jar dispensers, droppers, and ancillary accessories continue to serve specialized workflows, but the center of gravity is clearly shifting toward dispensing technologies that deliver repeatable, dose-controlled output across varied base formulations.
The forecast window also exposes the market’s structural sensitivity to broader healthcare and industrial trends. Supply chain localization efforts, evolving pharmacopeial expectations for dose uniformity, and the growing intersection of human and veterinary compounding are all reshaping procurement calendars, manufacturing scale-up timelines, and regional distribution footprints. A rigorously segmented view of these dynamics is essential for distinguishing transient demand spikes from durable shifts in application mix, and for forecasting capital allocation with greater precision.
From Volume to Value: Why Strategic Precision Matters in 2026
Leadership teams operating in this space are increasingly asked to reconcile two competing imperatives: capturing volume growth while defending margin integrity through higher-value dispensing architectures. The transition is not merely technological; it is commercial, regulatory, and operational. As formulators and compounding organizations demand greater consistency in active-ingredient delivery, the economic premium associated with precision dispensing mechanisms becomes more pronounced. Simultaneously, the cost of non-compliance—whether through dose variability, inadequate sterile-barrier performance, or misalignment with quality management expectations—continues to rise.
A research framework built for 2026 decision-making must therefore move beyond aggregate sizing. It needs to isolate the operational drivers that determine which dispensing platforms gain traction in institutional versus decentralized compounding environments, how reimbursement structures influence formulary inclusion of topical agents paired with specific applicators, and which geographic corridors are experiencing the fastest reconfiguration of supply and demand balances. The strategic value lies in mapping the trigger points where product design, regulatory classification, and procurement economics intersect.
In practice, this means equipping regional managers with the context needed to evaluate whether a shift toward metered-dose or airless architectures aligns with local clinical workflows and sterilization capacity, helping product developers anticipate which formulation characteristics will require dispenser redesign, and enabling sourcing leaders to stress-test supplier qualification pipelines against evolving quality-system expectations. Without a clear view of these intersections, organizations risk over-indexing on legacy container strategies or underinvesting in the precision components that will define competitive differentiation as the market matures.
Inside the Research: Operational Intelligence for Cross-Functional Teams
The newly released PW Consulting study is structured to convert macro trends into practical decision support across multiple functional domains. Rather than functioning as a single-volume market summary, the report is designed as an operational intelligence toolkit that can be deployed by commercial, R&D, regulatory, and supply chain teams in parallel.
At its core, the research provides a detailed breakdown of the global market across its primary segmentation axes, mapping revenue distribution by geographic corridor and by dispensing technology category. The regional view captures divergent adoption patterns, procurement maturity, and the varying intensity of institutional demand, while the technology-level analysis isolates the relative positioning of airless pump dispensers, metered-dose tubes, dual-chamber systems, jar dispensers, and dropper-based accessories. This dual-lens approach enables readers to cross-reference where specific dispensing formats are gaining structural advantage and how regional demand profiles influence product-mix planning.
A parallel segmentation by end-use application situates the compounding and healthcare context within the broader commercial landscape. Pharmaceutical and dermatology applications, cosmetics and skincare workflows, and personal care utilization all draw on the same underlying dispensing infrastructure, yet they impose distinct requirements on dose accuracy, barrier performance, manufacturability, and end-user experience. Clarifying how these segments interact with the overall revenue base allows organizations to anticipate cross-segment demand spillover, identify adjacent market entry opportunities, and calibrate investment priorities with a realistic view of where growth is being generated and where it is merely ornamental.
The study also integrates a dedicated competitive landscape analysis, profiling organizations that are actively shaping product architecture, manufacturing capability, and go-to-market positioning. These profiles are paired with a chronological account of recent corporate developments, including new product introductions and regulatory milestones that signal shifts in the competitive baseline. For strategists evaluating partnership opportunities, supplier transitions, or competitive response scenarios, this timeline provides the context needed to distinguish one-off announcements from sustained positioning moves.
To support scenario planning, the research addresses the regulatory and reimbursement environment with applied granularity. Coverage spans device classification expectations for topical applicators and skin adhesives, quality management standards relevant to design and production, and the practical implications of dose-uniformity evaluations for dispenser selection in compounding workflows. Reimbursement considerations are also mapped, particularly where topical agents and associated applicators intersect with coverage policies that affect downstream demand. These elements are presented as decision variables rather than background noise, enabling teams to factor compliance and coverage risk directly into product and market strategy.
Finally, the report is built to support executive-level synthesis. It provides the connective tissue needed to translate data points into actionable conclusions: where concentration dynamics suggest platform-level competition, where regional variance indicates the need for localized supply strategies, and where technological differentiation is likely to become a determinant of customer retention and pricing power.
Competitive Architecture: Incumbents, Specialists, and the Push Toward Precision Manufacturing
The competitive landscape in the topical dispenser market is defined by a blend of established packaging and dispensing specialists, medical-device-oriented manufacturers, and niche players concentrated on compounding and clinical workflow optimization. This mix creates a market structure in which scale advantages in component supply and global distribution coexist with highly differentiated clinical engineering capabilities. Understanding how these tiers interact is essential for anticipating pricing behavior, partnership structures, and technology adoption cycles.
Among the profiled organizations, several illustrate the market’s direction of travel. Companies developing metered dosing applicators for creams, gels, and lotions are increasingly emphasizing dose uniformity and workflow integration for both human and veterinary compounding pharmacy applications. The focus on pharmacist and patient experience signals a broader shift from purely mechanical dispensing toward solutions that reduce preparation variability and streamline operational throughput. In parallel, suppliers of airless and semi-solid dispensing systems continue to highlight product protection, hygiene, and metered output as core value propositions for pharmaceutical skin treatments, reinforcing the clinical premium attached to containers that preserve formulation integrity.
The competitive field also includes providers of click-dosing and metered pump dispensers designed for both non-sterile and sterile compounded preparations, alongside manufacturers supplying airless metered dose pumps and lidded applicators tailored to compounding workflows. These product lines reflect the market’s sensitivity to dosing accuracy across different cream bases and the growing expectation that dispensing hardware should be evaluated for consistency rather than convenience alone. Supporting this ecosystem are porous plastic and fiber component manufacturers that engineer drug delivery reservoirs and applicator components for medical device integration, as well as organizations developing precision healthcare dispensing solutions for dermal applications and controlled-dosing devices for topical gels and creams.
Dispenser Pump Market
Contract manufacturing capability further shapes the landscape. FDA-registered, ISO 13485-certified manufacturers of injection-molded pharmaceutical and medical applicators provide the production discipline required to support Class I and Class II device supply chains. Their presence underscores the market’s dependence on quality-system maturity as a competitive differentiator, particularly as demand for precision applicators grows across regulated healthcare channels.
Worldwide Topical Dispenser Market
Recent corporate activity reinforces these structural themes. A notable product launch introduced a metered-dose topical applicator optimized for in-container automated compounding, with design choices explicitly oriented toward improving pharmacist workflow and patient experience. In parallel, regulatory activity surrounding topical skin adhesives—classified as Class II medical devices requiring premarket notification—illustrates the broader device-ecosystem context within which topical dispensers and applicators operate. These developments are more than isolated milestones; they indicate how product architecture, regulatory expectations, and workflow efficiency are converging into a new competitive baseline.
Concentration dynamics within the market suggest a landscape that is neither fully fragmented nor tightly consolidated. A meaningful share of revenue is captured by a defined tier of leading participants, while substantial remaining share is distributed across specialists and regional suppliers. For strategy teams, this implies that competitive advantage will increasingly depend on the ability to combine component reliability, dosing precision, and workflow compatibility, rather than competing on container cost alone.
Regulatory and Reimbursement Fault Lines as Strategic Variables
As the topical dispenser market matures, regulatory and reimbursement variables are moving from peripheral considerations to central strategic inputs. Device classification frameworks, quality management requirements, and dose-uniformity expectations directly influence which dispensing architectures can scale efficiently and which require additional validation investment. At the same time, reimbursement treatment for certain topical agents and their associated application methods can shape formulary decisions, compounding volume, and downstream demand for specific applicator types.
For manufacturers and distributors, the implication is clear: product strategy cannot be decoupled from compliance strategy. ISO-aligned quality systems, documentation discipline, and design controls are increasingly treated as market-access prerequisites rather than operational overhead. Similarly, understanding dose-accuracy performance across formulation types is becoming relevant not only for clinical outcomes but also for procurement justification in regulated environments. The market’s most agile participants are those that integrate regulatory foresight into product roadmaps early, allowing them to align dispensing capabilities with evolving expectations before compliance gaps become market barriers.
2026 Positioning: How to Use This Intelligence
The strategic utility of this research lies in its ability to convert a rapidly evolving market into a structured set of decision levers. For commercial leaders, the segmentation views clarify where demand is concentrated and where regional variance calls for differentiated go-to-market models. For R&D and product management teams, the technology- and application-level analysis identifies the performance attributes that will command premium positioning as compounding and clinical workflows demand greater consistency. For supply chain and procurement functions, the competitive profiles and manufacturing context support more disciplined supplier evaluation and risk allocation. For regulatory and market-access teams, the coverage of device classification, quality standards, and reimbursement dynamics provides the context needed to anticipate friction points before they affect launch timing or adoption.
To move from overview to operational advantage, organizations need the full analytical layer behind these themes: the detailed segmentation splits, the regional revenue architecture, the application-level demand mapping, and the competitive-event timeline that together form the study’s core intelligence spine. These components transform strategic narrative into precise planning inputs, allowing leadership teams to size opportunity, calibrate investment, and stress-test assumptions with confidence.
Access the Full Strategic Framework
The complete PW Consulting Worldwide Topical Dispenser Market study provides the detailed data architecture and cross-segment analysis required to translate market direction into executable strategy. For decision-makers responsible for portfolio planning, supply chain positioning, competitive benchmarking, and regulatory readiness through 2032, the full report delivers the granularity needed to move from observation to action. Readers seeking the precise segmentation values, regional revenue distributions, application-level demand breakdowns, and extended competitive intelligence should consult the full research release, where the underlying dataset and analyst commentary are available in complete form.
For detailed analysis of this topic, please visit the official page: Worldwide Topical Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Occlusion Spray Sales Hit USD 115.45M in 2025, Projected 5.28% CAGR Till 2032
By PW Consulting, 2026-09-17
Unlocking Precision: Strategic Intelligence for the Worldwide Occlusion Spray Market (2026-2032)
In the rapidly evolving landscape of digital dentistry and industrial 3D scanning, occlusion sprays have transitioned from simple diagnostic aids to critical enablers of precision manufacturing and clinical accuracy. As we step into 2026, the Worldwide Occlusion Spray Market stands at a pivotal juncture, characterized by steady growth, evolving regulatory standards, and a competitive landscape dominated by specialized dental innovation leaders. Our latest comprehensive market research study, "Worldwide Occlusion Spray Market," offers stakeholders a granular view of the opportunities, challenges, and strategic imperatives defining this sector over the forecast period from 2026 to 2032.
Worldwide Occlusion Spray Market
This article serves as a strategic preview, outlining the macroeconomic trajectory, competitive contours, and the actionable intelligence embedded within our full report. We invite industry executives, investors, and procurement leaders to explore how this analysis can sharpen decision-making in an environment where precision, compliance, and cost-efficiency are paramount.
Market Trajectory: Steady Expansion Driven by Clinical and Industrial Demand
The occlusion spray market has demonstrated resilient growth over the past five years, and our analysis projects this momentum to continue through the end of the decade. Valued at approximately 115.45 million USD in 2025, the market is poised to reach 121.57 million USD in 2026, reflecting a consistent upward curve. Over the full forecast window, the market is expected to expand at a Compound Annual Growth Rate (CAGR) of 5.28 percent, culminating in a projected revenue of 165.72 million USD by 2032.
This growth is underpinned by a confluence of factors. The global shift toward digital dentistry, including CAD/CAM workflows and intraoral scanning, demands highly accurate marking and scanning aids that reduce errors in prosthetic fabrication. Simultaneously, the industrial 3D scanning segment is increasingly adopting occlusion spray technologies for enhanced surface contrast and measurement precision. While the market base remains rooted in dental applications, the diversification of use cases and the ongoing modernization of dental laboratory and clinical workflows provide a robust foundation for sustained expansion.
It is important to note that while the headline growth figures are compelling, the true strategic value for decision-makers lies in understanding the velocity of growth across different operational contexts, the nuances of regional demand dynamics, and the shifting preferences in product specifications. Our full report dissects these layers, providing a roadmap for capitalizing on high-growth vectors without exposing the organization to unquantified risks.
Strategic Segments and Application Dynamics: Where Value Is Concentrated
Occlusion sprays are not a monolithic category. The market is segmented by type, application, and region, each with distinct performance characteristics and demand drivers. Our research identifies clear patterns in how these segments perform relative to one another, offering insights into where competitive advantages can be cultivated.
From a product type perspective, certain color variants have established dominant positions, reflecting their alignment with specific clinical and scanning requirements. Green-color sprays, for instance, have captured a significant share of the market, driven by their high visibility and widespread acceptance in both dental and scanning workflows. Red-color sprays follow closely, offering complementary contrast properties. White scanning sprays represent a specialized but growing niche, particularly relevant for digital surface preparation. Other color variants and specialized formulations continue to address niche performance needs, allowing manufacturers to differentiate through formulation innovation and packaging flexibility.
In terms of end-use applications, the market is primarily anchored in dental laboratories, which account for the largest share of demand. This dominance reflects the intensive use of occlusion sprays in the evaluation, adjustment, and finishing of crowns, bridges, dentures, and other restorations. Dental clinics represent a substantial secondary segment, where rapid in-office marking and occlusal verification drive consistent consumption. Meanwhile, the industrial 3D scanning application segment, though smaller in relative terms, is emerging as a strategic growth area, reflecting the crossover of dental-grade marking technologies into broader precision scanning environments.
Regional demand patterns further illustrate the market's structural characteristics. Europe currently commands the largest share of global revenue, supported by a mature dental infrastructure, stringent quality standards, and a strong presence of established manufacturers. North America follows, driven by high adoption rates of digital dentistry and a competitive procurement environment. The Asia Pacific region presents a dynamic growth story, with expanding healthcare access, increasing dental tourism, and growing investments in dental technology infrastructure. LAMEA markets, while smaller in absolute terms, offer long-term potential as awareness of advanced dental diagnostics and scanning aids increases.
The detailed segmentation analysis in our report goes beyond identifying who leads and who follows. It explores the interplay between product attributes, application requirements, and regional procurement behaviors, enabling stakeholders to pinpoint the most attractive entry points, expansion strategies, and product positioning tactics. However, the precise numerical allocations and region-specific revenue contributions are reserved for the full dataset, where stakeholders can conduct tailored scenario modeling and sensitivity analysis.
Competitive Landscape: A Concentrated Arena of Specialized Innovators
The occlusion spray market exhibits a moderately concentrated competitive structure, with the top three players collectively holding a significant share of total market revenue. The top five companies extend this influence further, underscoring the importance of brand reputation, product quality, and regulatory compliance in capturing and retaining market share. This concentration does not imply stagnation; rather, it reflects a market where incumbents have built strong technical moats through formulation expertise, clinical validation, and distribution partnerships. At the same time, the presence of multiple credible players creates opportunities for differentiation through innovation, customer service, and value-added solutions.
Among the leading companies, Pascal International, Inc. has established itself as a trusted provider of occlusion sprays designed for precise occlusal contact marking across a range of restorative applications. Its aerosol indicator marking spray is approved for intra-oral use, a critical credential in a market where safety and regulatory alignment are non-negotiable. The company's focus on both wet and dry field applicability demonstrates an understanding of the practical demands faced by dental professionals.
Bausch (Dr. Jean Bausch GmbH & Co. KG) brings a strong European heritage to the market, with its Arti-Spray occlusion articulating spray available in multiple colors and formulated to leave a thin, removable film. The product's compliance with the European Council Directive 93/42/EEC for medical devices, along with its use of physiologically safe ingredients and environmentally neutral propellants, positions it favorably in markets where sustainability and regulatory rigor are increasingly valued. This alignment with environmental and safety standards is not merely a compliance checkbox; it is a strategic asset that resonates with procurement teams and clinical stakeholders alike.
Renfert GmbH contributes to the competitive mix with its Occlutec occlusion spray, offered in green and red variants for clear, detailed marking of high spots and trouble areas on model castings, crowns, and bridges. The emphasis on clarity and diagnostic precision aligns with the needs of dental technicians and laboratory professionals who rely on consistent, interpretable markings to refine prosthetic fit. YETI Dentalprodukte GmbH complements this offering with its intense occlusal spray, which is water-soluble and adheres to a variety of surfaces, providing versatility in both clinical and laboratory settings.
DFS Diamon GmbH differentiates itself with Okklean occlusion spray, which is formulated to mark contact points without discoloring plaster models and without dissolving in water or alcohol. This characteristic addresses a specific pain point in dental laboratory workflows, where model integrity and long-term usability are critical. Vacalon, operating in the USA market, provides Quickcheck indicating spray that serves dual purposes: detecting high spots and evaluating contacts, while also functioning as a digital scan spray. This hybrid functionality reflects the broader industry trend toward multi-purpose solutions that streamline procurement and reduce workflow complexity. Indenco Dental Products rounds out the competitive field with contact-indicating occlusal sprays available in multiple colors and sizes, catering to the need for flexibility in marking high spots and occlusal contacts across diverse practice settings.
The competitive dynamics in this market are shaped not only by product performance but also by the ability to navigate regulatory frameworks, maintain supply chain reliability, and respond to shifting user preferences. Our report provides a deep-dive analysis of each key player's positioning, product portfolio breadth, and strategic moves, enabling stakeholders to benchmark their own capabilities and identify potential partnership or acquisition opportunities. The full competitive intelligence section includes proprietary assessments and strategic groupings that are not disclosed in this preview.
Regulatory and Market Dynamics: Navigating Compliance as a Competitive Advantage
Regulatory compliance is a defining feature of the occlusion spray market, particularly given the intra-oral application of many products. In the United States, occlusion spray products such as Reveal Occlusion Spray are permitted for intra-oral use under FDA guidelines for dental articulating materials, establishing a clear regulatory pathway for manufacturers seeking to serve the US market. This framework emphasizes safety, biocompatibility, and appropriate labeling, setting a baseline that all credible entrants must meet.
In Europe, the regulatory landscape adds an additional layer of scrutiny. Arti-Spray occlusion spray, for example, meets the requirements of the European Council Directive 93/42/EEC for medical devices and utilizes physiologically safe ingredients with environmentally neutral propellants. This compliance is a strategic differentiator, as European procurement decisions increasingly factor in environmental impact and ingredient safety alongside clinical performance. The trend toward greener propellants and non-toxic formulations is not confined to Europe; it is emerging as a global expectation, particularly among forward-looking dental laboratories and clinics that prioritize sustainability in their supply chains.
Beyond regulatory compliance, market dynamics are influenced by packaging norms and user preferences. Occlusion sprays are typically packaged in 75 ml aerosol cans, with some variants available in 23 g or 200 ml sizes. The availability of multiple sizes allows manufacturers to serve both high-volume laboratory users and smaller clinic-based consumers, while the range of colors green, red, blue, and white ensures that professionals can select the visibility profile that best matches their diagnostic or scanning needs. These seemingly granular details have strategic implications for inventory planning, distribution design, and product line optimization, all of which are addressed in the operational recommendations section of our report.
Report Capabilities: Actionable Intelligence for 2026 Decision-Making
Our Worldwide Occlusion Spray Market research is designed to be more than a static data repository. It is a decision-support tool that translates market complexity into actionable strategy. The full report includes a comprehensive suite of analyses and datasets, structured to support a wide range of strategic planning activities.
- Historical and forecast revenue data spanning 2020 through 2032, enabling robust trend analysis and forward-looking scenario modeling. The data is presented in a consistent currency framework and revenue unit structure, facilitating accurate aggregation and comparison across segments and regions.
- Deep-dive segmentation analysis by region, type, and application, with methodological rigor that allows stakeholders to evaluate growth drivers, demand elasticity, and competitive intensity within each segment. While this preview highlights directional trends, the complete dataset contains the precise numerical breakdowns necessary for financial planning and market entry assessments.
- Competitive landscape profiling of key companies, including headquarters location, product portfolio summaries, and strategic positioning insights. This section is structured to support benchmarking, partnership evaluation, and competitive response planning.
- Regulatory and compliance review, mapping FDA and European directive requirements to product attributes and market access implications. This component helps stakeholders assess regulatory risk and align product development or procurement strategies with evolving standards.
- Packaging, formulation, and application detail analysis, drawing on manufacturer catalogs and industry documentation to inform product specification decisions and user preference alignment.
- Strategic implications and recommendations tailored to different stakeholder roles, including market incumbents, new entrants, investors, and procurement leaders.
The report also incorporates a structured approach to market concentration analysis, providing context on how revenue is distributed among leading players and what this means for competitive strategy. By combining quantitative data with qualitative industry insights, the study offers a holistic view of the market that supports both operational planning and long-term strategic positioning.
Looking Ahead: Precision, Compliance, and Growth in the Occlusion Spray Market
As the Worldwide Occlusion Spray Market moves through the 2026-2032 forecast period, stakeholders face a landscape defined by steady expansion, regulatory sophistication, and a competitive environment that rewards precision and compliance. The projected growth trajectory, supported by a CAGR of 5.28 percent and a market size expected to exceed 165 million USD by 2032, signals that occlusion sprays will remain an essential component of dental and scanning workflows. However, realizing value in this market requires more than awareness of aggregate trends. It demands a nuanced understanding of segment performance, regional dynamics, competitive positioning, and the operational implications of regulatory and packaging norms.
Our full market research study provides the depth, structure, and actionable insight necessary to navigate this complexity. For executives evaluating market entry, product portfolio adjustments, or partnership strategies, the report offers a rigorous foundation for decision-making. For procurement leaders and clinical stakeholders, it delivers clarity on the product attributes and compliance credentials that matter most in a competitive bidding environment. And for investors seeking to understand the growth vectors and concentration risks within the sector, the study presents a comprehensive analytical framework.
Worldwide Micro Spray System Market
The occlusion spray market is not a commodity space. It is a specialized domain where formulation quality, regulatory alignment, and user-centric design determine long-term success. Our research is built to help stakeholders distinguish between incremental trends and transformative opportunities, ensuring that strategic decisions in 2026 and beyond are grounded in reliable, detailed, and forward-looking intelligence.
To access the complete dataset, segment-level analysis, competitive profiles, and strategic recommendations, we invite you to explore the full Worldwide Occlusion Spray Market report. The detailed intelligence within is designed to support confident, informed action in a market where precision is not just a product feature but a business imperative.
For detailed analysis of this topic, please visit the official page: Worldwide Occlusion Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RF Chip Inductors Market Hits $1.79B in 2025, 7.5% CAGR to 2032
By PW Consulting, 2026-09-17
Navigating the RF Chip Inductors Landscape: Strategic Intelligence for the 2026–2032 Cycle
Executive Perspective
The RF chip inductor market is entering a phase of disciplined expansion where volume growth, technological specificity, and supply chain resilience must be managed simultaneously. Based on our Worldwide RF Chip Inductors Market research, the sector is projected to move from approximately USD 1,794.5 million in 2025 to around USD 2,977.2 million by 2032, reflecting a compound annual growth rate of 7.5 percent. This trajectory is not merely a function of broader electronics demand. It is being redefined by high-frequency communication architectures, vehicle intelligence mandates, and the material and geopolitical pressures that now shape component sourcing decisions.
For senior leaders, procurement heads, product strategists, and investors, the market story is no longer about whether RF chip inductors matter. The question is where value will concentrate, how competitive positioning will shift, and which decisions made in 2026 will determine margin and optionality through the end of the decade. This article previews the strategic logic behind our latest study and explains how its structure supports high-stakes planning without exposing the granular intelligence that gives competitive advantage to paying stakeholders.
Why 2026 Is a Defining Planning Year
A Market Framework Built for Decision-Making
Any useful market study for 2026 must do more than present a forward revenue curve. It needs to connect historical behavior, structural demand drivers, and near-term market friction into a single operational lens. Our research framework was designed with that intent. The historical base from 2020 through 2025 provides a migration path that shows how the RF chip inductor market has consistently expanded across technology cycles, product generations, and regional manufacturing shifts. That history is valuable precisely because it exposes the pattern of acceleration and consolidation that often repeats in passive component markets when new communications standards and automotive electronics requirements converge.
From a planning perspective, the forecast window from 2026 through 2032 is where early decisions compound. Because the sector is moving toward roughly a USD 2.98 billion revenue envelope by 2032, even modest changes in sourcing strategy, qualification lead times, or technology mix can translate into meaningfully different cost positions and time-to-market outcomes. Our report translates that macro path into a structured environment where leadership teams can test assumptions around demand timing, component allocation, and portfolio prioritization rather than reacting to market signals after they have already reshaped the supply base.
Importantly, this study is built to support decisions at multiple levels of granularity. Executives can use it to validate top-down market direction, while operations and engineering teams can use its segmentation logic to think through technology choice, application exposure, and regional sourcing implications. The objective is not simply to describe the market, but to provide a reusable analytical scaffold that can inform product roadmaps, supplier negotiations, and capital allocation conversations throughout the forecast period.
What the Study Covers: From Market Structure to Execution
Segmentation Logic That Maps to Operational Reality
The research is organized around the dimensions that matter most to actual sourcing, design, and commercialization decisions. Rather than offering a single aggregate narrative, the report breaks the market into type, application, and region in a way that reflects how buyers evaluate trade-offs among performance, form factor, qualification burden, and cost.
On the product side, the study examines how wire-wound, multilayer, and thin-film chip inductor technologies differ in the contexts where they are most relevant. Each technology pathway carries distinct implications for high-frequency performance, miniaturization, manufacturing complexity, and qualification requirements. Instead of treating these categories as static labels, the report ties them to application needs and supply characteristics so that engineering and procurement teams can interpret them as strategic choices rather than catalog options.
The application perspective is equally practical. Communication-related devices, automotive electronics, industrial and IoT systems, and consumer electronics plus other end-use contexts each place different demands on RF chip inductors. Some prioritize high-frequency stability and noise management, others prioritize durability under vehicle-grade qualification regimes, and still others depend on cost-compressed volume delivery. By analyzing the market through application lenses, the study helps readers understand where demand intensity is structurally stronger and what that means for capacity planning, supplier dependencies, and launch timing.
RF Inductors Market
Regional analysis completes the picture by linking market size distribution to sourcing architecture and manufacturing footprint considerations. In practice, geography is inseparable from risk, lead time, logistics, and qualification strategy. The report situates regional dynamics within the broader supply chain environment so that decision-makers can assess not just where demand is concentrated, but where production, trade exposure, and input vulnerabilities intersect.
Competitive Positioning and the Shape of the Supply Base
Concentration, Differentiation, and the Players That Matter
Market structure is one of the most actionable elements of the study because it reveals where bargaining power, innovation tempo, and qualification advantage tend to reside. The RF chip inductor sector is characterized by a moderately concentrated competitive field, with the top five participants accounting for a substantial share of activity and the top three representing nearly half of the market. That level of concentration is significant. It suggests that while multiple suppliers remain available, strategic relationships, technical differentiation, and reliability credentials increasingly shape sourcing outcomes.
The report profiles a broad set of established and region-specific participants whose product footprints illustrate the competitive logic of the market. Japanese manufacturers such as Murata Manufacturing, TDK Corporation, and Taiyo Yuden continue to occupy prominent positions in multilayer and high-frequency RF inductor offerings, with product development emphasis on high-Q performance, miniaturization, and communication- and vehicle-relevant use cases. Murata, for example, commercialized its LQP02HQ_Z2 high-Q RF chip inductor series in a very compact form factor for in-vehicle communication devices, bringing AEC-Q200 qualification into mass production.
In the United States, suppliers including Bourns, Coilcraft, Vishay Intertechnology, Gowanda Electronics, and API Delevan illustrate the range of specialization available in the market. Bourns has advanced multiple multilayer chip inductor series built around advanced multilayer technology and monolithic construction, targeting high-frequency performance, compact size, and strong self-resonant frequency characteristics for RF and mobile applications. Coilcraft contributes high-performance RF inductor and magnetic component expertise oriented toward RF, microwave, and high-frequency signal processing environments. Vishay and Gowanda extend the competitive field with multilayer and wire-wound approaches as well as ceramic core solutions aimed at demanding RF, power, military, and medical requirements. API Delevan rounds out this group with RF inductors tuned for high-frequency analog circuits, signal processing, RFID, GPS, and radar applications, including qualified and custom options.
Worldwide RF Chip Inductors Market
European participation is represented by Würth Elektronik, whose RF inductor and passive component portfolio supports signal and communications applications across high-frequency chip inductor designs. Meanwhile, Taiwan-based suppliers such as Walsin Technology, ABC ATEC, and Chilisin Electronics, along with Shenzhen Sunlord Electronics in China, reflect the increasingly important role of regional manufacturers in RF inductor supply, spanning wire-wound ceramic chips, multilayer RF inductors, LTCC-based products, and broader communications-related components.
These company profiles are not included as marketing directories. They are used to show how product strategy, application targeting, and technology selection differentiate suppliers in a market where specifications, qualification records, and delivery reliability often matter as much as headline price. The report also tracks recent company-level moves so readers can connect competitor actions to broader market momentum. The recent product launches and commercialization milestones captured in the study demonstrate how the competitive field is actively responding to miniaturization, high-frequency performance, and automotive-grade requirements in parallel.
Market Dynamics: Materials, Regulation, and Risk Asymmetry
Why Structural Pressures Are Now Central to Strategy
No market study for 2026 can treat pricing and supply as background variables. In the RF chip inductor space, raw material behavior and regulatory direction are becoming core drivers of cost structure and availability. Early 2026 has already seen rising silver and copper costs interacting with strong AI, electric vehicle, and industrial demand, producing structural price adjustments across multilayer chip inductors and related passive components. Copper price movement on the London Metal Exchange has moved materially above late-2025 averages, feeding directly into inductor production economics. At the same time, ferrite core supply has tightened, extending delivery cycles for certain models and slowing inductive component production in some contexts.
These pressures create a risk asymmetry that decision-makers cannot afford to overlook. When input costs rise and lead times elongate, the cost of late planning increases as well. Buyers that rely on reactive sourcing are more exposed to allocation constraints, spot pricing, and qualification delays. Organizations that anticipate these dynamics can protect margins through design flexibility, dual qualification, inventory policy adjustment, and more deliberate supplier coordination. The report integrates these material and supply dynamics so that procurement and engineering teams can evaluate not only what the market size trajectory implies, but also what it will cost to access supply reliably.
Regulatory direction adds another layer of strategic relevance. EU RoHS and WEEE directives continue to influence the adoption of recyclable and low-toxicity materials in chip inductor production, reinforcing the idea that compliance is increasingly tied to material selection and manufacturing process choices. At a geopolitical level, Europe’s dependence on China for rare earth elements and high-purity ferrites remains a critical vulnerability, with export controls on materials such as gallium and certain rare earths classified as high supply risk. This context matters for any organization evaluating regional sourcing strategies or long-term supply resilience because it shows that component availability is no longer determined by factory output alone. It is also shaped by trade policy, material concentration, and the broader regulatory environment.
Strategic Applications of the Research for 2026 Decision-Making
From Intelligence to Action
The real value of this study lies in the decisions it helps organizations make more confidently. The report is intended to support:
- Portfolio and technology roadmapping decisions by linking RF chip inductor types to application requirements and future demand trajectories
- Sourcing and supplier strategy by clarifying where competitive concentration, specialization, and regional dynamics shape access and negotiation leverage
- Cost and risk planning by incorporating material price behavior, supply tightness, and regulatory shifts into scenario-based thinking
- Market entry, expansion, or partnership evaluation by identifying where demand intensity and technology needs are most pronounced
- Investment and capability prioritization by showing how market growth is distributed across application and technology pathways rather than treating growth as a monolith
In practice, these applications often converge. A product team may need to decide whether a design should emphasize one inductor technology over another; a sourcing leader may need to assess whether current supplier coverage is sufficient under tightening material availability; and a strategy group may need to evaluate whether regional exposure creates unacceptable risk in the context of trade and material controls. The study is structured to support all three discussions with a consistent evidence base.
How to Use This Intelligence Without Guesswork
Accessing the Full Analytical Depth
The preview above reflects the strategic architecture of the report, but many of the most useful analytical outputs are designed for users who need full segmentation context, competitive benchmarking, and forward-looking scenario support. The complete study goes beyond narrative to provide the structured detail that teams require for supplier scoring, demand modeling, risk assessment, and executive alignment.
Because the RF chip inductor market is being shaped simultaneously by technology differentiation, application growth, material cost pressure, and geopolitical supply exposure, the margin between good planning and reactive planning is widening. Organizations that understand the direction of travel early can align product development, procurement, and investment decisions before the market redistributes advantage.
To benefit from the complete assessment, including the detailed segmentation findings, company-level competitive analysis, and forecast-supported planning tools, we invite you to access the full Worldwide RF Chip Inductors Market research. The published report is designed to give leadership teams the depth they need to act with precision in 2026 and to build resilience through the 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide RF Chip Inductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Freight Forwarding Market to Hit $200M in 2025, Grow at 4.55% CAGR to 2032
By PW Consulting, 2026-09-17
Navigating the Global Freight Forwarding Landscape: Strategic Intelligence for 2026 and Beyond
The international freight forwarding industry stands at a critical inflection point. As supply chains adapt to geopolitical shifts, regulatory pressures, and rapid technological transformation, organizations require more than surface-level market data to navigate the coming years with confidence. This comprehensive market research study delivers a rigorous, data-driven analysis of the Worldwide International Freight Forwarding Services Market, offering executives and strategy teams the actionable intelligence needed to make informed decisions across 2026 and the forecast horizon through 2032.
Drawing on historical performance data from 2020 through 2025 and projecting forward across a seven-year forecast period, this report captures both the cyclical volatility and the structural growth trajectories that define modern logistics ecosystems. The base year analysis establishes a clear foundation, while forward-looking projections equip decision-makers with the planning parameters necessary for capacity allocation, partnership strategies, and technology investment roadmaps.
Market Size Evolution and Growth Trajectory
The global freight forwarding market has demonstrated remarkable resilience despite confronting unprecedented disruptions over the past half-decade. Historical revenue figures reveal a market that weathered pronounced fluctuations before stabilizing and returning to a sustainable growth path. After reaching a valuation exceeding 174,000 million USD in 2020, the sector experienced a pronounced surge through 2022, driven by pandemic-era demand restructuring and inventory restocking cycles. The subsequent correction in 2023 and 2024 reflected normalization patterns as freight rates adjusted and consumer spending patterns shifted, yet the underlying demand fundamentals remained intact.
By the 2025 base year, the market had recovered to approximately 200,000 million USD, establishing a solid platform for forward expansion. The forecast period from 2026 through 2032 charts a steady upward trajectory, with projected revenues expanding from roughly 203,300 million USD in 2026 to over 273,000 million USD by 2032. This growth reflects a compound annual growth rate of 4.55 percent, a figure that underscores the sector's capacity to generate consistent value even amid fluctuating macroeconomic conditions. For enterprise planners, this growth rate provides a reliable benchmark for modeling revenue expectations, evaluating market entry opportunities, and calibrating long-term investment commitments.
Structural Segmentation: Where Value Is Created
Understanding the multidimensional structure of the freight forwarding market is essential for targeting the right opportunities and mitigating concentration risks. This report dissects the market across three critical analytical dimensions: geographic regions, transport modes, and end-use industries. Rather than presenting opaque aggregates, the analysis isolates the revenue contributions and growth characteristics of each segment, enabling stakeholders to identify high-potential corridors and service lines.
The geographic breakdown reveals distinct regional dynamics shaped by trade policy, infrastructure readiness, and industrial composition. Asia Pacific commands the largest revenue share, driven by manufacturing exports, intra-regional trade intensification, and expanding port infrastructure. Europe maintains a substantial position, supported by integrated multimodal networks and stringent regulatory frameworks that drive demand for compliance-forward logistics solutions. North America represents a mature but evolving market where e-commerce acceleration and nearshoring trends are reshaping forwarding volumes. Latin America and the Middle East and Africa, while smaller in absolute terms, present high-growth opportunities tied to emerging market industrialization, resource-sector logistics, and corridor development initiatives.
On the service mode front, the analysis differentiates between ocean freight, air freight, road and rail transport, and specialized other services. Ocean freight remains the dominant revenue contributor, reflecting the continued centrality of maritime shipping to global trade. Air freight sustains a significant share, buoyed by time-critical shipments, high-value goods, and resilience-driven routing decisions. Road and rail transport segments demonstrate steady demand, particularly in intra-continental corridors where multimodal integration offers cost and efficiency advantages. Complementary service lines, including customs brokerage, warehousing integration, and value-added logistics, represent differentiated niches where forwarders can capture margin premium.
End-use industry segmentation further clarifies where forwarding demand originates. Manufacturing remains the largest consumer of freight forwarding services, reflecting complex global sourcing networks and just-in-time production requirements. Retail and e-commerce continue to expand their logistics footprint, driven by consumer expectations for faster delivery and the proliferation of cross-border online commerce. Consumer goods, healthcare, and automotive and energy sectors each present distinct forwarding requirements shaped by regulatory standards, temperature control needs, hazardous materials handling, and project logistics complexity. By mapping forwarding demand to these end-use verticals, the report provides a practical lens for aligning service portfolios with sector-specific growth cycles.
Competitive Landscape and Market Concentration
The freight forwarding industry operates within a fragmented yet consolidating competitive environment. The analysis indicates a moderate level of market concentration, with the top three players collectively accounting for approximately 12.4 percent of total market revenue and the top five firms representing roughly 18.25 percent. This concentration profile suggests ample room for both established incumbents and specialized challengers to compete on service differentiation, digital capabilities, and regional expertise.
Several globally recognized enterprises define the competitive frontier, each pursuing distinct strategic positions. Kuehne + Nagel has reinforced its position as a leader across sea, air, and road forwarding by integrating digital platforms such as myKN to deliver end-to-end visibility and streamlined transaction workflows. DSV has expanded its comprehensive forwarding capabilities across all major transport modes while building distinctive strength in project logistics, culminating in a landmark acquisition of DB Schenker in September 2025 that created the world's largest freight forwarder by revenue. DB Schenker itself has built a strong reputation for ocean, air, and land forwarding with particular emphasis on automotive and healthcare verticals.
DHL Global Forwarding continues to lead in time-critical air freight and ocean forwarding, leveraging resilience capabilities such as resilience360 to provide supply chain visibility and risk mitigation. Expeditors International has differentiated itself through technology-driven operations, proprietary EDI systems, and a focus on air, ocean, and ground services that emphasize operational precision and client responsiveness. CEVA Logistics offers full-service forwarding integrated with contract logistics, targeting automotive and consumer sectors with coordinated supply chain solutions. UPS Supply Chain Solutions and FedEx Trade Networks bring the advantage of integrated global networks, with UPS emphasizing Quantum View tracking and FedEx specializing in customs brokerage alongside its air and ocean forwarding capabilities.
Regional and specialized players further enrich the competitive landscape. Nippon Express anchors strong Asia-Pacific trade lane expertise across air, sea, and rail services. Sinotrans provides integrated sea, air, and rail forwarding from a Chinese base with global reach. C.H. Robinson has scaled a digital freight forwarding platform through Navisphere, enabling ocean, air, and truck services with a technology-first operating model. Hellmann Worldwide Logistics, as a family-owned forwarder, combines air, sea, and contract logistics with cloud-based track and trace functionality. Geodis delivers multi-modal forwarding with notable strength in e-commerce and healthcare supply chains. Bolloré Logistics focuses on Africa and energy sector logistics via air and sea networks, while Agility Global Integrated Logistics targets emerging markets and provides integrated warehousing and forwarding services through its GWC operations.
Industry Dynamics Shaping Strategic Decisions
Market size and participant profiles alone do not capture the forces that will determine competitive outcomes in 2026 and beyond. A suite of operational, regulatory, and geopolitical dynamics exerts direct influence on forwarding costs, service reliability, and routing strategies. Understanding these forces is indispensable for scenario planning and risk management.
Fuel cost volatility remains a persistent pressure point. Ocean freight bunker fuel prices averaged approximately 650 USD per metric ton in the fourth quarter of 2025, representing a year-over-year increase of 15 percent driven in part by compliance costs associated with IMO 2020 sulfur regulations. For forwarding providers and their clients, fuel cost fluctuations translate directly into freight rate variability and require proactive hedging and pricing strategies.
Regulatory developments are adding new layers of compliance complexity and cost. The European Union Emissions Trading System was extended to shipping in 2025, imposing carbon-related costs on a portion of emissions for intra-EU voyages. This regulatory shift incentivizes carbon-efficient routing, modal optimization, and investment in greener equipment, while simultaneously affecting cost structures for European-facing trade lanes. Labor cost escalation represents another structural headwind. Global logistics labor costs rose by approximately 8 percent in 2025, propelled by port worker shortages across the United States and Europe. This tightening labor market pressures throughput capacity at key nodes and elevates the value of automation and workforce productivity initiatives.
Worldwide Freight Forwarding Service Provider Services Market
Trade policy and geopolitical events continue to reshape freight flows in ways that forwarding strategies must accommodate. Tariff actions, including the imposition of 25 percent tariffs on Chinese steel imports by the United States effective March 2025, have influenced forwarding volumes and routing decisions by altering the economics of specific trade corridors. Geopolitical disruptions have similarly forced adaptive responses. Red Sea disruptions rerouted a significant share of Asia-Europe container traffic via the Cape of Good Hope in early 2025, increasing transit times and fuel consumption while testing the resilience of forwarding networks. These events highlight the importance of diversified routing options, scenario-aware contingency planning, and real-time visibility capabilities that enable rapid response to unfolding disruptions.
Worldwide International Freight Forwarding Services Market
What This Research Delivers for Strategic Decision-Makers
This market research study is designed to translate complex market data into clear strategic guidance. The full report provides an extensive toolkit for executives, business development leaders, investors, and operations strategists. Key deliverables include:
- Detailed historical market sizing and forward projections segmented by region, transport mode, and end-use industry, enabling precise demand forecasting and market opportunity quantification.
- Competitive benchmarking across leading global forwarders, with analysis of strategic positioning, service portfolios, digital capabilities, and recent corporate developments such as acquisitions, platform launches, partnership initiatives, and major client engagements.
- Assessment of market concentration trends and their implications for pricing power, partnership dynamics, and competitive strategy.
- Analysis of the operational and regulatory forces affecting cost structures, route viability, and service reliability, including fuel cost patterns, emissions regulations, labor market conditions, tariff impacts, and geopolitical disruption scenarios.
- Strategic recommendations for aligning service offerings, technology investments, and regional expansion plans with the most promising growth vectors identified in the data.
By integrating quantitative market sizing with qualitative assessments of competitive and operational dynamics, the report equips organizations to move beyond reactive adjustments and toward proactive, evidence-based strategy formulation.
Why This Research Matters for 2026 Planning
The freight forwarding market of 2026 will be defined by organizations that can balance growth ambition with operational adaptability. The 4.55 percent compound annual growth rate projected through 2032 signals a market that continues to expand, but the path of that expansion will be uneven across regions, modes, and industries. Companies that understand where demand is concentrating, which competitors are capturing share, and how regulatory and cost pressures are evolving will be best positioned to allocate resources efficiently and capture disproportionate value.
Digital transformation remains a decisive competitive differentiator. Recent moves by leading forwarders, including AI-driven rate management platform updates, partnerships focused on supply chain resilience, and proprietary technology systems that enhance tracking and transaction efficiency, demonstrate that technology investment is no longer optional. Similarly, corporate consolidation events underscore the importance of scale, network reach, and integrated service capabilities in a market where clients increasingly demand end-to-end solutions.
For enterprises evaluating market entry, service expansion, partnership formation, or investment targeting, the granular insights contained in this report reduce uncertainty and sharpen strategic focus. The segmentation data clarifies which corridors and verticals offer the most attractive risk-adjusted returns. The competitive analysis identifies where incumbents are strengthening their positions and where gaps may exist for differentiated service models. The dynamics assessment provides the context needed to design cost structures, pricing frameworks, and contingency plans that withstand volatility.
Next Steps for Intelligence-Driven Strategy
Accessing the complete dataset, segmentation breakdowns, and competitive profiles allows decision-makers to move from high-level awareness to specific, actionable planning. The full version of this market research includes detailed revenue projections, mode-level and region-level performance analysis, end-use industry demand drivers, company-specific strategic profiles, and a comprehensive overview of the industry events and regulatory developments shaping near-term market behavior.
For organizations seeking to strengthen their positioning in the global freight forwarding market, this research provides the evidence base required to make confident strategic choices in 2026 and beyond. Explore the complete market intelligence to uncover the segmentation insights, competitive benchmarks, and forward projections that will inform your next round of strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide International Freight Forwarding Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Power CW Laser Market Surges to $3.4B in 2025, Projected to $6.02B by 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the High-Power CW Laser Era: Why 2026 Demands Precision Market Intelligence
The industrial landscape of 2026 is defined by an uncompromising demand for precision, throughput, and energy efficiency. At the heart of this transformation lies the continuous-wave (CW) high-power laser sector—a market that has evolved from a niche manufacturing enabler into a critical infrastructure component for global production ecosystems. As automation accelerates and material processing requirements grow increasingly complex, decision-makers across industrial manufacturing, semiconductor packaging, and emerging technology sectors face a critical imperative: move beyond superficial trend tracking and ground capital allocation, R&D roadmaps, and supply chain strategies in rigorously validated market intelligence.
Our recently published Worldwide High Power CW Laser Market research delivers exactly that foundation. Spanning a comprehensive historical baseline from 2020 through 2025 and extending a structured forecast horizon to 2032, this study transforms fragmented industry signals into a cohesive strategic narrative. For executives, investors, and engineering leaders navigating the 2026 operating environment, the report serves not as a static reference document, but as a dynamic decision-support framework calibrated to the velocity of technological adoption and competitive realignment.
The Macro Trajectory: Sustained Expansion Anchored in Industrial Realities
Market momentum in the high-power CW laser space is no longer speculative; it is quantifiable, structural, and increasingly non-linear. Drawing on validated historical revenue tracking and forward-looking econometric modeling, the research documents a clear trajectory of expansion. Starting from an established base in 2020, the market has consistently advanced through 2025, crossing significant descriptive milestones that reflect both capacity expansion and deepening application penetration. Looking ahead, the forecast window through 2032 projects a sustained compound annual growth rate of 8.5 percent, measured in USD millions. This growth rate is not an artifact of optimistic modeling; it is anchored in observable adoption curves across metal fabrication, battery manufacturing, additive processes, and precision industrial marking.
For strategic planners, the implication is straightforward: the high-power CW laser market is entering a phase where scale advantages, technological differentiation, and regional supply chain positioning will dictate competitive outcomes. The forecast horizon to 2032 provides a multi-year lens that aligns with typical capital equipment procurement cycles, facility expansion timelines, and technology refresh schedules. Executives who integrate this trajectory into their 2026 planning will be better positioned to time capacity investments, negotiate long-term supply agreements, and anticipate shifts in customer demand before they become visible in quarterly order books.
Worldwide High Power CW Laser Market
Navigating Market Concentration and Competitive Realignment
Scale alone does not guarantee strategic advantage in a market characterized by concentrated leadership and rapidly evolving technological boundaries. The research captures a highly structured competitive environment, with the top three participants commanding a combined share of approximately 56.4 percent and the top five collectively representing over 72 percent of total market revenue. This concentration signals mature competitive dynamics, where incumbents leverage manufacturing scale, application engineering depth, and system-level integration to defend positioning, while challengers and regional specialists pursue targeted differentiation in cost structure, beam quality, or application-specific optimization.
Understanding these dynamics requires more than a leaderboard view. The report dissects how established players balance diversified product portfolios with focused high-margin offerings, how regional manufacturing footprints influence cost competitiveness and logistics resilience, and how strategic partnerships, channel relationships, and vertical integration shape go-to-market effectiveness. For 2026 decision-making, this competitive intelligence translates directly into actionable planning: it informs benchmarking exercises, identifies potential partnership or acquisition targets, highlights whitespace opportunities in underserved application segments, and clarifies where pricing pressure is likely to intensify versus where technology premium positioning remains defensible.
CW DFB Laser Diode Market
Structural Partitioning: Technology, Application, and Regional Interplay
A market of this scale cannot be understood through aggregate figures alone. The research maps the underlying structural partitions that drive demand creation, pricing behavior, and technology roadmapping. Across the laser technology spectrum, the study differentiates performance trajectories, cost curves, and adoption velocity among fiber-based architectures, CO2 platforms, solid-state and disk configurations, and direct diode solutions. Each architecture carries distinct implications for beam delivery, thermal management, maintenance complexity, and end-use suitability, and the report translates these technical attributes into commercial relevance for procurement teams, systems integrators, and technology planners.
On the application side, the analysis isolates the demand drivers that are reshaping purchasing priorities. Cutting processes continue to anchor a substantial portion of high-power CW laser deployment, reflecting their centrality to metal fabrication, sheet processing, and high-volume manufacturing. Welding and brazing applications represent a parallel growth axis, increasingly influenced by battery assembly requirements, automotive lightweighting initiatives, and aerospace structural joining demands. Additive manufacturing, marking and engraving, and surface treatment applications each contribute distinct volumes and margin profiles, and the report delineates how these segments interact with regional industrial policies, automation investment cycles, and quality-certification requirements.
Regional demand distribution further complicates the strategic picture. The research examines how manufacturing capacity, local automation adoption rates, industrial policy incentives, and supply chain regionalization influence market pull across major geographic corridors. Rather than presenting static share tables, the report contextualizes regional behavior within broader macroeconomic and industrial transformation trends, enabling readers to assess where localized production strategies, export-oriented supply positioning, or regional partnership models will yield the strongest return on commercial engagement in 2026 and beyond.
Tactical Intelligence for 2026 Decision-Making
High-level trajectory and structural analysis are necessary, but rarely sufficient for operational planning. The report is engineered to bridge strategic overview and tactical execution. It provides procurement and engineering leaders with framework-level insights into technology selection criteria, including guidance on when fiber-based solutions dominate, where diode or solid-state alternatives offer compelling tradeoffs, and how beam quality, power stability, and back-reflection resilience influence application suitability for reflective or thermally sensitive materials.
For supply chain and operations executives, the study addresses material dependency considerations and production scalability constraints. It traces how specialized semiconductor and optical raw material dynamics, including regional supply concentration and spot price volatility observed in recent periods, intersect with manufacturing continuity planning. The report also incorporates regulatory and safety compliance requirements that shape design, qualification, and maintenance processes for high-power systems, emphasizing that thermal management complexity and non-linear optical effects demand specialized engineering expertise and rigorous process controls. These factors directly influence total cost of ownership, service network requirements, and vendor evaluation criteria.
Commercial and go-to-market teams will find actionable frameworks for positioning, segmentation, and partnership strategy. The research outlines how application-specific value propositions differ across cutting, welding, additive, and surface treatment contexts, and how system-level integration, service availability, and performance guarantees influence buyer decision-making. By aligning market structure with commercial execution pathways, the report equips teams to refine pricing architectures, prioritize addressable segments, and design channel strategies that match the realities of regional demand and competitive intensity.
Recent Developments Reshaping the Competitive Frontier
The 2026 operating environment is being actively reshaped by product launches, sampling programs, and recognition events that signal where technology leadership is concentrating. Recent industry activity underscores this momentum. In early 2026, leading fiber laser developers showcased compact high-power single-mode sources with tightly controlled beam quality metrics, earning industry recognition for packaging efficiency and industrial usability. These exhibitions and awards are not merely ceremonial; they signal commercial readiness, validate performance claims, and often precede accelerated adoption in precision cutting and welding workflows where beam consistency directly impacts process yield.
Simultaneously, adjacent high-power CW developments are expanding the addressable context beyond traditional industrial processing. Sampling programs for high-power CW sources targeting AI datacenter and co-packaged optics applications indicate a broadening demand ecosystem, where optical power requirements, linewidth control, and fabrication scalability on advanced substrate lines are becoming commercially relevant. Early-stage production timelines and initial revenue expectations tied to these initiatives illustrate how high-power laser technology is feeding into next-generation infrastructure and photonics architectures, creating cross-sector demand linkages that traditional industrial laser markets did not previously capture.
Additional recent introductions in high-efficiency CW sources with stringent linewidth and wall-plug efficiency targets further reflect the industry-wide push toward energy optimization and integration compatibility. Together, these developments demonstrate that the high-power CW laser market is not a closed industrial loop; it is a convergent technology platform where manufacturing, photonics, and infrastructure demands increasingly interact. The report synthesizes these signals into a coherent view of where near-term commercial activity is likely to concentrate and which performance benchmarks are becoming table stakes for competitive participation.
Why This Research Matters for 2026 Strategy
The strategic value of this market research lies in its integration of macro trajectory, structural partitioning, competitive positioning, and near-term industry signals into a single, decision-ready framework. For 2026, that integration matters because the cost of misreading market direction is rising. Capital deployed into misaligned technology platforms, capacity added without clear regional demand justification, or supply agreements negotiated without visibility into concentration dynamics and raw material risk can quickly erode competitive positioning. Conversely, organizations that anchor their planning in validated market structure, realistic growth trajectories, and application-specific demand drivers can time investments more effectively, negotiate from a position of informed confidence, and identify differentiation pathways before competitors lock them in.
The report is designed to support precisely that informed confidence. It equips leadership teams with the context needed to evaluate technology roadmaps against realistic adoption curves, to assess competitive vulnerability and opportunity across regions and applications, and to align procurement, manufacturing, and commercial strategies with the structural realities of a high-growth, technically demanding market. It also provides the analytical discipline required to separate transient market noise from durable demand shifts, a distinction that becomes increasingly critical as automation, electric vehicle manufacturing, aerospace additive requirements, and emerging photonics applications collectively reshape purchasing priorities.
Direction for Deeper Engagement
This overview establishes the analytical foundation and strategic relevance of the study, but the full market intelligence required for definitive 2026 planning resides in the complete research deliverable. The underlying segmentation detail, regional demand mapping, application-specific volume and revenue context, technology performance comparisons, and company-level profiling are structured to support granular scenario modeling, vendor evaluation, and investment prioritization. Accessing the complete report enables decision-makers to move from directional understanding to precise, actionable intelligence tailored to their operational footprint, technology roadmap, and commercial objectives.
For executives and strategy teams seeking to align 2026 capital allocation, product positioning, and supply chain planning with the trajectory of the worldwide high-power CW laser market, the full research offers the depth, structure, and forward visibility required to act with confidence. The market is expanding, concentrating, and converging across industrial and infrastructure applications; the organizations that navigate this environment successfully will be those that replace assumption with evidence, and direction with detail.
For detailed analysis of this topic, please visit the official page: Worldwide High Power CW Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Solar Urban Equipment Market Hits $1.14B in 2025, 15.02% CAGR to 2032
By PW Consulting, 2026-09-17
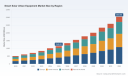
The Urban Energy Transformation: Strategic Insights into the Worldwide Smart Solar Urban Equipment Market (2026-2032)
The global urban landscape is undergoing a profound metamorphosis, driven by the urgent need for sustainable infrastructure and the integration of intelligent technologies into public spaces. At the forefront of this transformation is the smart solar urban equipment sector, a niche yet rapidly expanding market that merges renewable energy generation with IoT-enabled urban furniture. As municipalities and commercial developers seek to reduce carbon footprints while enhancing citizen engagement, the demand for autonomous, connected solar solutions is reshaping procurement strategies and urban planning paradigms. This article serves as a strategic primer to our latest comprehensive study, the Worldwide Smart Solar Urban Equipment Market Research, designed to equip industry leaders with the critical intelligence needed to navigate the opportunities and complexities of the 2026-2032 forecast period.
Executive Market Overview: Trajectory of Exponential Growth
The market for smart solar urban equipment has demonstrated robust momentum over the past half-decade, evolving from a novelty into a staple of modern smart city initiatives. Our analysis captures a market that has steadily accelerated, reflecting the compounding effects of policy support, technological maturity, and the economic imperative for off-grid resilience. In the base year of 2025, the global revenue associated with this sector reached approximately $1,142.83 million. This figure represents a substantial escalation from the $510.45 million recorded in 2020, underscoring a consistent double-digit expansion trajectory that has outpaced many broader infrastructure segments.
Looking ahead to the forecast window ending in 2032, the market is projected to surge past the $3 billion mark, reaching an estimated $3,043.66 million in revenue. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 15.02 percent. Such a rate signals not merely incremental adoption but a structural shift in how urban assets are powered and managed. The period from 2026 through 2032 is poised to be defined by scaling infrastructure projects, increased investment in public-private partnerships, and the maturation of the product ecosystem. For decision-makers, understanding this velocity is paramount; it indicates a window of opportunity where early movers can secure market share and establish technological standards before the market reaches saturation.
The Role of Data-Driven Insights in 2026 Decision-Making
In an environment characterized by rapid technological iteration and shifting regulatory frameworks, decisions based on intuition or outdated benchmarks carry significant risk. The strategic value of a dedicated market research report lies in its ability to distill complex macroeconomic signals into actionable intelligence. For 2026, stakeholders face a unique inflection point. Costs for core components, such as photovoltaic modules, have seen volatility and downward pressure in global spot markets, yet regulatory dynamics, including trade duties on specific cell types and modules, introduce new variables into supply chain planning. Furthermore, incentive structures at the state and municipal levels are evolving, creating pockets of high ROI that require precise identification.
Our research report goes beyond top-line projections to unpack the drivers and restraints influencing these numbers. It provides a granular examination of how cost structures, installation efficiencies, and capacity-weighted averages impact total cost of ownership for urban deployments. By analyzing the interplay between raw material pricing trends and equipment performance metrics, the report enables procurement managers and strategic planners to model sensitivity scenarios. Whether evaluating the financial viability of a fleet of smart solar benches for a public park or assessing the long-term maintenance costs of solar street lighting in municipal infrastructure, access to accurate, forward-looking data is the difference between a speculative venture and a calculated investment.
Product and Application Landscape: Where Value is Being Created
The market is not monolithic; it is a mosaic of distinct product categories and application verticals, each with its own adoption curve and value proposition. The research delves deeply into the segmentation of the market, revealing which equipment types are capturing the lion's share of revenue and why. The analysis covers a spectrum of solutions, including smart solar benches that serve as community hubs with integrated connectivity and charging, solar smart waste bins that optimize municipal collection routes through sensor data, solar street lighting that eliminates trenching and grid reliance, and solar kiosks and signage that provide interactive information in off-grid locations.
Each of these categories addresses specific pain points for urban operators. For instance, smart benches and kiosks are increasingly viewed as assets for public engagement and digital inclusion, while solar waste bins offer tangible operational cost savings through compaction and fill-level monitoring. The report provides a comparative assessment of these segments, highlighting the relative market valuation of each and the growth drivers specific to their use cases. Readers will gain clarity on which product types are resonating most strongly with current procurement trends and where the innovation pipeline is likely to disrupt existing categories.
Worldwide Smart Solar Urban Equipment Market
Similarly, the application landscape is dissected to reveal the end-use environments driving demand. Public parks and plazas represent a significant focal point for smart urban furniture, leveraging solar solutions to create sustainable, functional gathering spaces without the burden of extensive grid infrastructure. Municipal infrastructure projects are deploying these technologies to modernize street lighting and waste management, often driven by sustainability mandates and budget constraints. Commercial real estate developers are integrating solar equipment to enhance property amenities and meet green building certifications, while transportation hubs are utilizing these assets to support transit users with lighting and connectivity. The report quantifies the revenue allocation across these applications and identifies the key performance indicators that influence purchasing decisions in each vertical.
Geographic Dynamics and Market Concentration
Regional variations play a critical role in the deployment and adoption of smart solar urban equipment. The research provides a detailed breakdown of market performance by region, highlighting the distinct characteristics and growth trajectories of key geographies. Europe continues to demonstrate strong leadership, underpinned by aggressive sustainability targets, supportive regulatory environments, and a mature ecosystem of smart city initiatives. North America remains a potent market, fueled by substantial public infrastructure spending, a focus on energy independence, and the rapid adoption of off-grid solutions in diverse climates. Asia Pacific is characterized by rapid urbanization and large-scale smart city projects, offering immense volume potential, while the Rest of the World segment is emerging with niche opportunities driven by specific regional needs and development programs.
Beyond regional splits, the report examines the competitive structure of the market. Analysis of market concentration reveals that the sector is relatively fragmented, with the top three companies commanding a combined market share of 21.4 percent and the top five holding 32.65 percent. This level of concentration suggests a market that is still open to new entrants and consolidation, where competitive advantages are derived not just from scale but from technological differentiation, service models, and regional expertise. Understanding this landscape is essential for companies evaluating partnership opportunities, acquisition targets, or positioning strategies.
Competitive Intelligence: Navigating a Dynamic Player Ecosystem
The smart solar urban equipment space is populated by a diverse array of companies, ranging from specialized hardware manufacturers to integrated solution providers. Our research includes comprehensive profiles of key market participants, offering insights into their product portfolios, strategic focus, and recent activities. These profiles are designed to provide a 360-degree view of the competitive landscape, enabling clients to benchmark their offerings and identify potential collaborators or rivals.
EnGoPlanet Energy Solutions LLC, based in New York, exemplifies the trend toward multi-functional urban assets. Their portfolio encompasses smart solar street lights with IoT connectivity, Wi-Fi hotspots, security cameras, and environmental sensors, alongside smart solar benches and a subscription-based solar lighting-as-a-service model. This service-oriented approach addresses the budget constraints of municipalities by shifting capex to opex, a strategy that is gaining traction. EnGoPlanet has also been active in high-visibility projects, with developments noted in early 2024 regarding major installations in Texas, and ongoing thought leadership on solar integration in urban contexts.
SOLTECH LLC, headquartered in Emeryville, California, focuses on high-efficacy commercial solar LED lighting systems. Their offerings include street lights, pathway lights, bollards, flood lights, and mobile solar light towers, with an emphasis on off-grid reliability capable of sustaining illumination for extended periods. Recently, SOLTECH has highlighted performance capabilities suitable for demanding applications, including Olympic-grade standards, and promoted fast-deploy solutions that avoid the need for trenching or wiring, a significant advantage for event infrastructure and rapid urbanization projects.
Archasol operates as a global supplier of solar-powered urban furniture, providing smart benches with phone charging and lighting, solar charging stations, pathway lighting, and sign lighting. Their value proposition centers on delivering functional public space enhancements without the requirement for mains power connections, making them relevant for parks, pedestrian zones, and areas where grid extension is cost-prohibitive.
SEEDiA, based in Poland, develops smart solar benches equipped with USB and inductive charging, LED lighting, and sensors, managed through the InCity.io platform. Their ecosystem extends to solar bus shelters, info kiosks, and e-scooter chargers, positioning them as a comprehensive provider for smart urban mobility and public interaction nodes. The integration of remote management platforms is a recurring theme among leading players, emphasizing the shift from passive hardware to actively managed data-generating assets.
Sunna Design, a pioneer with operations in France and North America, specializes in autonomous solar street lighting and energy management systems. Their connected, off-grid solutions are tailored for both urban and rural smart city applications, leveraging robust lighting control algorithms to optimize energy usage. Strawberry Energy, based in Serbia, offers highly customizable smart solar benches with WiFi, charging, LED lighting, and IoT features, allowing municipalities to tailor solutions to specific aesthetic and functional requirements. Finbin, from Finland, addresses the waste management dimension with CitySolar smart solar-powered compacting waste bins that utilize sensors to improve collection efficiency. These profiles, and others detailed in the report, illustrate the breadth of innovation and the varying approaches competitors are taking to capture market value.
Industry Dynamics, Trends, and Strategic Implications
The market does not operate in a vacuum; it is influenced by a complex web of industry dynamics, including raw material pricing, regulatory changes, and incentive structures. Our report synthesizes these external factors to provide a holistic view of the operating environment. For example, the analysis incorporates data on global PV module spot prices and installed costs of utility-scale PV systems, providing context for the cost structures of smaller urban-scale deployments. While utility-scale metrics differ from urban equipment economics, they signal broader trends in the solar supply chain that affect component availability and pricing power.
Regulatory developments are another critical focus. The report addresses relevant trade policies, such as additional duties on solar cells and modules imposed in key markets, which can impact procurement costs and supply chain strategies. Simultaneously, the research highlights positive regulatory tailwinds, such as local solar access funds and grant programs that provide financial support for community solar projects. These incentives can significantly alter the project economics for municipalities and developers, and the report identifies where and how such mechanisms can be leveraged. Furthermore, the broader context of global solar PV additions and the dominance of certain regions in manufacturing and deployment sets the stage for understanding supply-demand balances and innovation flows.
Why This Report is Essential for 2026 Planning
As we enter 2026, the stakes for strategic decision-making in the smart solar urban equipment market have never been higher. The convergence of sustainability mandates, technological advancements, and economic pressures is creating a fertile ground for growth, but also a landscape filled with potential pitfalls. Companies that rely on fragmented data or lagging indicators risk misallocating resources, entering the wrong segments, or failing to capitalize on emerging trends.
Our Worldwide Smart Solar Urban Equipment Market Report is designed to be the definitive resource for navigating this landscape. It offers a depth of analysis that goes beyond surface-level summaries, providing the granular insights necessary to formulate robust strategies. Whether you are a manufacturer looking to expand your product line, a distributor seeking high-growth regions, a municipality planning a smart city initiative, or an investor evaluating opportunities, this report delivers the intelligence you need. It combines quantitative rigor with qualitative context, offering a clear view of the market's past performance and future potential.
The market is on a trajectory to triple in size over the forecast period, driven by a CAGR of over 15 percent. The competitive landscape is evolving, with players differentiating through technology, service models, and regional focus. The product and application segments are maturing, revealing clear winners and value drivers. The industry dynamics are shifting, demanding agile responses to pricing, regulation, and incentives. To make sense of it all and to position your organization for success, you need the comprehensive, authoritative analysis that only this report provides.
Secure your copy of the Worldwide Smart Solar Urban Equipment Market Research today and gain the strategic edge required to lead in the urban energy transformation. Access the full dataset, detailed segmentation analysis, competitive profiles, and forward-looking insights that will empower your 2026 and beyond decision-making.
Solar Mobile Light Tower Market
For detailed analysis of this topic, please visit the official page: Worldwide Smart Solar Urban Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reusable Food Wrap Market Hits $245M in 2025, Projects 7.15% CAGR to 2032
By PW Consulting, 2026-09-17
The Reusable Food Wrap Revolution: Strategic Insights for Navigating Market Growth Through 2032
A PW Consulting Executive Preview
The global transition away from single-use plastics has moved from a niche consumer preference to a mainstream operational imperative. For businesses operating in the food storage, packaging, and sustainable goods sectors, the reusable food wrap market represents one of the most dynamic growth vectors of the decade. Our latest comprehensive study, Worldwide Reusable Food Wrap Market, offers a granular, data-driven roadmap for navigating this evolving landscape. This article serves as a strategic preview, outlining the macro-trajectory, the competitive architecture, and the regulatory catalysts that will define market winners between 2026 and 2032.
The Macro Trajectory: From Recovery to Accelerating Expansion
Over the past half-decade, the worldwide reusable food wrap market has demonstrated a robust recovery and expansion phase. Historical revenue data from 2020 through 2025 illustrates a clear upward trajectory, with the market size climbing from 173.46 million USD to a projected 245.0 million USD. This growth reflects not only the post-pandemic normalization of supply chains but also a structural shift in consumer purchasing behavior. As households and commercial kitchens increasingly prioritize waste reduction, demand for breathable, plastic-free alternatives has cemented itself as a recurring revenue stream rather than a transient trend.
Looking forward to the forecast period spanning 2026 to 2032, the market is positioned for sustained expansion. The projected compound annual growth rate of 7.15 percent signals that the sector will outperform many traditional consumer goods categories. By 2032, the overall market revenue is expected to reach 397.3 million USD. For corporate strategists, this CAGR implies a compounding opportunity: early movers who establish distribution networks, brand loyalty, and regulatory compliance frameworks today will capture disproportionate market share as the total addressable market expands. The forecast also highlights year-over-year inflection points, such as the jump toward 315.56 million USD in 2028, suggesting that regulatory deadlines and commercial adoption curves will likely accelerate demand velocity in the latter half of the forecast window.
It is crucial for decision-makers to understand that these macro figures represent the aggregate of distinct regional performances, product typologies, and end-use applications. Our full report unpacks these layers systematically, providing the precise volume and value breakdowns required for regional go-to-market planning, product portfolio optimization, and capacity allocation. However, the headline trend is unambiguous: the market is scaling, and the pace of scaling is tightening around a consistent mid-single-digit growth rate that rewards strategic foresight over reactive positioning.
Decoding the Competitive Architecture
The reusable food wrap sector is characterized by a moderately fragmented but strategically consolidating competitive landscape. Market concentration metrics indicate that the top three players command approximately 28.5 percent of total revenue, while the top five hold around 36.2 percent. This distribution suggests that while no single entity dominates the global stage, established brands with strong product differentiation, ethical sourcing narratives, and supply chain resilience are capturing meaningful pockets of influence. The remaining market share is distributed among a vibrant ecosystem of specialized manufacturers, regional producers, and emerging direct-to-consumer brands, creating a highly dynamic environment for both competition and partnership.
Key incumbents exemplify the strategic pillars driving success in this space. Bee's Wrap, LLC, headquartered in Vermont, has positioned itself as a pioneering brand by offering reusable beeswax food wraps crafted from GOTS-certified organic cotton, ethically sourced beeswax, jojoba oil, and tree resin. Their emphasis on breathable, plastic-free alternatives across various sizes and patterns demonstrates how product variety and material transparency can build enduring consumer trust. Similarly, Abeego Designs Inc. from Canada has capitalized on the original beeswax food storage wrap concept, designing products that allow food to breathe while protecting it. Their focus on extending the freshness of produce, cheese, and bread aligns tightly with the narrative of reducing household food waste, a powerful purchase driver.
Reusable Water Bottle Market
The competitive field also includes Etee, another Canadian player providing organic reusable food wraps and zero-waste products that serve as sustainable alternatives to single-use plastics. LilyBee Wrap targets eco-conscious consumers with organic cotton beeswax wrappers featuring diverse designs, highlighting the importance of aesthetic differentiation alongside functional sustainability. The Beeswax Wrap Company Ltd operates as a manufacturer and supplier focused on reusable, biodegradable options for household food preservation, illustrating the role of dedicated B2B and wholesale channels in scaling distribution. Keep Leaf integrates reusable food wraps into a broader sustainable kitchen product line, emphasizing eco-friendly materials that resonate with lifestyle-focused retail assortments.
Further down the value chain, U-KONSERVE offers reusable food storage solutions including wraps that prioritize durable, sustainable alternatives to disposable plastics. Khala & Company provides beeswax wraps and related eco-products with an emphasis on natural and ethical sourcing, reinforcing how supply chain integrity has become a competitive differentiator. SuperBee supplies beeswax wraps and eco-friendly products compliant with various dietary and manufacturing standards, targeting sustainable food storage with a framework that appeals to regulated and quality-conscious markets. Honeywrap and Apiwraps both offer beeswax-based reusable food wraps for everyday kitchen use, representing the steady demand from brands that focus on everyday utility and repeatable purchase cycles.
On the manufacturing and export frontier, Henan Green Wrap Products Co., Ltd in China operates as a large-scale manufacturer of beeswax wraps, vegan wraps, and related products compliant with LFGB, REACH, and FDA standards, while offering OEM/ODM services. This profile underscores the strategic importance of regulatory compliance and flexible manufacturing partnerships for brands seeking to scale internationally or launch private-label offerings. Green Wrap, also based in China, positions itself as an experienced manufacturer of reusable beeswax food wraps and bags, emphasizing stable quality and efficient production. Together, these manufacturers illustrate how production capacity, certification portfolios, and service models are reshaping the competitive dynamics beyond consumer-facing brands.
For executives, the central insight is that competition in this market is multidimensional. It is not merely a price war; it is a contest over material credibility, product performance, regulatory readiness, and supply chain agility. Our full report provides detailed comparative assessments that help brands identify white-space opportunities, benchmark against incumbents, and evaluate potential acquisition or partnership targets within this ecosystem.
Regulatory Catalysts and Raw Material Realities Shaping the Demand Curve
Market growth in the reusable food wrap sector cannot be understood in isolation from the regulatory environment. Policy interventions across multiple jurisdictions are actively reshaping end-user demand and creating compliance-driven purchasing behavior. In the United States, California's SB 54 mandates that 100 percent of single-use packaging and food service ware sold in the state must be recyclable or compostable by 2032. This legislative trajectory is a powerful demand catalyst for reusable alternatives, as food service operators and packaging suppliers seek compliant, scalable solutions that can meet both environmental targets and operational practicality. The regulation effectively expands the commercial addressable market by forcing a structural shift in procurement priorities.
Beyond California, a cascade of state-level actions is tightening the regulatory perimeter around single-use plastics. New Jersey's law prohibits food service businesses from providing single-use utensils and condiments under certain conditions, effective August 1, 2026. Georgia has implemented a ban on single-use plastic food packaging and foodware for food service establishments, effective July 1, 2026. These measures, documented by CalRecycle and the New Jersey Department of Environmental Protection, among other sources, signal a clear policy direction: single-use disposables are increasingly constrained, and reusable, durable alternatives are moving from optional sustainability enhancements to baseline compliance requirements. For commercial end-users and the brands that supply them, this regulatory cadence creates both urgency and a multi-year window to align product portfolios with evolving mandates.
At the same time, raw material dynamics introduce both opportunity and risk. Beeswax, a foundational input for many reusable wrap products, has experienced notable price volatility. In late 2025, visible trade data indicated that US beeswax transaction prices reached approximately 18.29 USD per kilogram. Meanwhile, the global average beeswax export price in 2024 was recorded at 6,311 USD per ton. These figures highlight the importance of input cost monitoring, supplier diversification, and formulation strategies that can buffer margin pressure. Brands that rely heavily on beeswax must navigate geographic sourcing variations, certification requirements, and seasonal supply fluctuations, while manufacturers of vegan or alternative-material wraps must track the cost and performance trajectories of their own material substitutes. Our research integrates these raw material realities into the broader demand forecast, enabling clients to model sensitivity scenarios and make informed sourcing decisions.
Inside the Report: Practical Intelligence for Strategic Execution
The Worldwide Reusable Food Wrap Market study is designed as an operational decision-support tool, not merely a high-level overview. It provides a structured exploration of the market's foundational drivers, restraints, and enabling factors, connecting macro forces to actionable business implications. Readers gain access to a detailed segmentation analysis that dissects the market by region, by product type, and by application, allowing stakeholders to pinpoint where growth is concentrating and where competitive intensity is rising. This multi-dimensional segmentation is essential for companies evaluating market entry, expansion, or portfolio rebalancing, as it reveals the relative weight of household versus commercial demand and clarifies how product categories perform across different economic and regulatory contexts.
The report also includes comprehensive profiles of the key companies shaping the competitive landscape. Each profile examines brand positioning, material and sourcing strategies, product range breadth, compliance frameworks, and distribution approaches. By mapping these profiles against market share and concentration metrics, the study helps clients identify competitive gaps, evaluate benchmarking targets, and anticipate likely strategic moves from both established players and agile challengers. For investors and corporate development teams, this company-level intelligence supports due diligence, partnership screening, and market positioning exercises with a clear view of who is leading in which segment and why.
Worldwide Reusable Food Wrap Market
Beyond segmentation and company analysis, the study embeds the regulatory and raw material context directly into the market narrative. This integration ensures that forecasts are not developed in a vacuum; instead, they reflect the combined influence of legislation, material pricing, consumer behavior shifts, and supply chain capacity. The forecast period through 2032 is treated as a sequence of decision-relevant milestones, allowing clients to align product launches, capacity investments, and geographic prioritization with the most probable market inflection points. The result is a research asset that supports scenario planning, pricing strategy, channel mix optimization, and risk assessment within a single coherent framework.
Translating Insight into 2026 Decision-Making
As organizations move into 2026, the strategic imperative is to convert market awareness into structured action. The reusable food wrap market is large enough to reward focused investment, yet dynamic enough to penalize delayed or uninformed decisions. Companies that act early can secure distribution relationships, align product specifications with emerging regulatory expectations, and build brand equity around material transparency and performance reliability. Those that wait risk entering a market where compliance costs are higher, consumer expectations are more entrenched, and competitive positions are already defended by brands with multi-year head starts.
For consumer brands, the priority is to determine which product types and application segments offer the most defensible growth profile, then to calibrate pricing, packaging, and marketing around the value propositions that resonate with target buyers. For manufacturers and suppliers, the focus should be on certification readiness, production efficiency, and the ability to support OEM/ODM demand from brands seeking to scale quickly while maintaining quality and compliance. For investors and corporate strategists, the opportunity lies in identifying which companies possess the combination of material expertise, regulatory agility, and market reach needed to compound value as the forecast period unfolds.
The macro figures point to a market moving from 245.0 million USD in 2025 toward 397.3 million USD in 2032, with a CAGR of 7.15 percent anchoring a credible growth narrative. Yet the real strategic advantage comes from understanding the distribution of that growth: which regions are expanding fastest, which product types are gaining share, which applications are shifting from early adoption to mainstream procurement, and how regulatory timelines will compress decision windows. Those details are the difference between a general sense of optimism and a precise execution plan.
Access the Full Intelligence
This preview has outlined the structural forces, competitive architecture, and regulatory momentum defining the reusable food wrap market through 2032. To move from directional confidence to decision-ready precision, stakeholders need the complete dataset, segmentation matrices, company benchmarking, and forecast sensitivities contained in the full study. The detailed breakdown of regional performance, product-type dynamics, household versus commercial application splits, and raw material scenario modeling is available in the comprehensive Worldwide Reusable Food Wrap Market report. We invite executives, strategists, and investment teams to access the full research asset and equip their 2026 planning with the depth required to act decisively in a market that is scaling quickly and rewarding informed positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Zero-Point Clamping Market Hits $633.19M in 2025, To Hit $987.21M by 2032
By PW Consulting, 2026-09-17
Unlocking Precision and Speed: Strategic Insights into the Global Zero-Point Clamping System Market 2026–2032
In the high-stakes environment of modern manufacturing, the margin between profitability and obsolescence often comes down to seconds. Every minute spent on machine setup is a minute of lost capacity. As we move deeper into 2026, the imperative for high-mix, low-volume production environments has never been more critical. The global Zero-point Clamping System market stands at the forefront of this operational shift, offering the technological backbone required for rapid changeovers, lights-out production, and uncompromising precision. Our latest Worldwide Zero-point Clamping System Market study is not merely a collection of statistics; it is a strategic compass designed to navigate the complex interplay of technological innovation, regional dynamics, and competitive intensity that defines this sector through 2032.
The Macro Economic Trajectory: A Decade of Sustained Growth
Understanding the broader market trajectory is the first step in strategic planning. The data reveals a robust growth story that extends well beyond temporary fluctuations. In our base year of 2025, the global market for zero-point clamping systems established a significant revenue baseline. Looking forward, the forecast period from 2026 to 2032 projects a steady and compelling compound annual growth rate (CAGR). This growth is not accidental; it is the direct result of manufacturing industries prioritizing efficiency metrics that were previously secondary to raw output.
Historical analysis covering the period from 2020 to 2025 shows a consistent upward trend in revenue valuation, measured in millions of USD. This historical resilience sets the stage for the future. The market size is expected to expand significantly by the end of the forecast period in 2032. For enterprise strategists, this indicates a healthy ecosystem where investment in clamping technology is viewed as a capital expenditure with demonstrable returns in operational throughput. The shift from manual intervention to automated, repeatable clamping solutions is becoming a standard rather than a luxury. However, the aggregate numbers only tell part of the story. The true value for decision-makers lies in understanding the velocity of adoption across different actuation technologies, the specific demands of key application verticals, and the uneven distribution of market revenue across global regions. These nuanced layers of data are essential for identifying where the next pockets of growth will emerge.
Industry Dynamics: The Drivers of Change in 2026
Several macro trends are converging to accelerate the adoption of zero-point clamping technology. The primary driver remains the urgent need to reduce setup times. In high-mix production environments, traditional workholding methods often create bottlenecks. Industry leaders highlight that implementing zero-point systems can reduce setup times by up to 90%. This efficiency gain directly translates to increased machine capacity, allowing manufacturers to run more batches or dedicate more time to actual cutting operations.
Furthermore, the integration of these systems into the broader Industry 4.0 framework is a critical dynamic. Zero-point clamping systems provide standardized, repeatable interfaces that are essential for CNC and robotic handling. This standardization enables lights-out production scenarios where machines operate autonomously overnight or during weekends. For corporations aiming to reduce labor dependency and mitigate supply chain volatility, the ability to run unmanned shifts is a strategic advantage that hinges on reliable workholding technology.
Precision and repeatability are also key factors capping the ceiling of market growth. Modern systems are engineered to compensate for thermal expansion with symmetrical fixed zero points and clearance-free fits. Achievement of repeat accuracy below 2.5 micrometers allows for tighter tolerances in finished parts, which is particularly vital in sectors where component failure is not an option. Additionally, the materials used in these systems are critical. High-strength hardened alloy steel components, often treated to approximately 57 HRC, ensure durability and precision under heavy loads. This material specification underscores the engineering rigor required to maintain system integrity over thousands of clamping cycles.
Report Scope and Operational Content
Our comprehensive study is structured to provide actionable intelligence rather than abstract theory. The report delves into the segmentation of the market by actuation type, covering pneumatic, hydraulic, and manual mechanical clamping solutions. Each actuation type offers distinct advantages regarding speed, force, and integration complexity. The analysis extends to the application landscape, dissecting demand across automotive manufacturing, aerospace and defense, medical device manufacturing, and general machinery and tooling. Each vertical presents unique challenges regarding vibration resistance, clamping force requirements, and cycle times.
Regional analysis is another cornerstone of this research. We examine the market concentration across Europe, Asia Pacific, North America, and the Rest of World. Understanding the regional distribution of revenue is vital for supply chain planning and market entry strategies. The report also scrutinizes the competitive landscape, analyzing market concentration metrics to understand the balance between dominant incumbents and emerging challengers. This includes an assessment of the top players who command significant market share, providing insight into pricing power and consolidation trends.
- Segmentation Analysis: Deep dives into actuation types and application verticals to identify high-growth niches.
- Regional Breakdown: Country and region-specific revenue trends to support geographic expansion or sourcing decisions.
- Competitive Intelligence: Profiles of key industry players, including their strategic moves, product launches, and exhibition activities.
- Investment Viability: Identification of high-value segments where capital deployment yields the highest return on investment.
Key Enterprise Profiles and Strategic Moves
The competitive arena is populated by specialized manufacturers who have anchored their reputations on precision and reliability. STARK Spannsysteme GmbH, part of the ROEMHELD Group, continues to pioneer zero-point clamping technology. Their solutions focus on fast, precise workpiece and fixture clamping in CNC machining, optimizing setup time across milling, turning, and automation. Similarly, LANG Technik GmbH offers the Quick•Point® system, known for modular 52 mm and 96 mm grids that emphasize versatility and retrofitting capabilities on various CNC machines.
The Zimmer Group provides modular systems suitable for milling, turning, EDM, and grinding, emphasizing error reduction. HAINBUCH GmbH offers the DockLock system for stationary applications, enabling quick change-over of clamping devices in under two minutes with form-fit clamping. SMW-AUTOBLOK supplies systems including APS series modules with turbo functions for enhanced pull-down force and sealed designs. EROWA AG specializes in systems optimized for automated CNC manufacturing and lights-out production, integrating loading units with platforms for EDM, milling, and measurement.
In the Americas, Jergens Inc. supplies a Zero Point System that combines fixing, positioning, and clamping in one step, reducing setup times by up to 90%. SCHUNK GmbH & Co. KG provides Vero-S and other solutions widely referenced for precision workholding. NIKKEN Kosakusho Works Ltd., operating in Japan and the USA, develops integrated technology directly into rotary tables to maintain machine rigidity without additional stack height.
Recent activity indicates a vibrant pipeline of innovation. Gressel AG released new plate modules for their gre4doc system in early 2025. The ROEMHELD Group and Gressel both showcased their technologies at EMO Hannover 2025. NIKKEN highlighted integrated zero-point clamping in their 5AX-201 rotary table in March 2025. AMF Andreas Maier GmbH & Co. KG published a comprehensive catalog covering mechanical, hydraulic, and pneumatic modules. These developments signal that the industry is not static; product lifecycles are active, and competition is fierce.
Competitive Landscape and Market Concentration
The market structure is characterized by a concentration of revenue among a core group of established players. Analysis of market concentration reveals that a significant portion of the total revenue is held by the top companies. This concentration suggests strong brand loyalty, high barriers to entry regarding precision engineering certifications, and the importance of existing customer relationships in CNC machining networks. However, the presence of specialized manufacturers, such as ZeroClamp GmbH and Suzhou SET Industrial Equipment System Co., Ltd., indicates niche opportunities where specific value propositions like extreme repeat accuracy or custom high-precision solutions can carve out market share.
Worldwide Zero-point Clamping System Market
Strategic decisions for 2026 must account for this landscape. Whether a company is looking to source clamping technology to improve internal operations or considering market entry, understanding the capabilities of competitors like STARK, LANG, and EROWA is essential. These companies are not just selling hardware; they are selling uptime and precision. Their recent trade show exhibitions and catalog releases demonstrate a commitment to continuous improvement and adaptation to new machining requirements, such as additive manufacturing compatibility seen in recent presentations by companies like LEHMANN.
Magnetic Clamping Technology Market
Strategic Recommendations for 2026 Decision Makers
As we navigate 2026, the integration of zero-point clamping systems should be viewed through the lens of total cost of ownership rather than just initial procurement cost. The reduction in setup time allows for quicker changeovers, which is critical for the demand for customization in automotive and medical sectors. In aerospace and defense, the emphasis on error reduction and material durability aligns with the stringent quality standards required.
For manufacturers, the first step is evaluating current bottlenecks. If setup times are consuming significant machine availability, the ROI on zero-point systems is likely clear. For investors and analysts, the growth trajectory suggests that companies enabling high-mix, low-volume production will continue to see favorable conditions. The technology supports the macro trend of reducing labor intensity while increasing output quality. Supply chain managers should also note the importance of material specifications, such as the hardness of steel components, which impacts longevity and maintenance schedules.
The data presented in this overview serves as a foundation. The specific percentages of regional revenue splits, the exact valuation of each actuation segment, and the detailed share percentages of the top five competitors require a deeper dive into the full analysis. These granular details are necessary for precise budgeting and strategic targeting. For example, while the broad strokes show strong growth, the specific disparity between pneumatic and hydraulic adoption rates in specific regions can dictate sourcing strategies.
Conclusion: Accessing the Full Intelligence
The Worldwide Zero-point Clamping System Market is evolving from a niche component supply chain to a critical enabler of modern manufacturing efficiency. The projected growth through 2032 reflects a structural shift in how workpieces are held, positioned, and changed. The competitive landscape is dynamic, with established German and Swiss engineering prowess coexisting with innovative solutions from Japan and emerging players in China. Recent product launches and trade show demonstrations confirm that innovation is accelerating, particularly in areas related to automation integration and thermal management.
While this article provides a strategic overview of market dynamics, segmentation drivers, and competitive profiles, it is designed as a preview of the comprehensive intelligence available in our full study. The aggregate figures and qualitative trends serve to establish context, but the detailed breakdown of market sizes, regional revenue splits, and compound growth rates for each sub-segment holds the specific data required for immediate tactical execution. To access the complete dataset, including the precise market valuation for each region and application, and to leverage the full competitive benchmarking, we invite you to explore the full Worldwide Zero-point Clamping System Market report. This resource is designed to equip stakeholders with the granular intelligence necessary to secure a competitive advantage in the precision engineering sector.
For detailed analysis of this topic, please visit the official page: Worldwide Zero-point Clamping System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com