

Blogs
The China AI camera market is set for dynamic growth, with revenue increasing from $3,800 million in 2021 to $16,500 million by 2035. Factors driving this upward trajectory include expansive adoption in public security, automotive safety, telemedicine, and retail analytics. Consistent investments by government and enterprise users, coupled with rapid consumer device innovation, underpin sustained double-digit growth rates throughout the forecast period. By 2035, the market is projected to be more than four times its size in 2021, reflecting the critical role of AI in modern imaging.
Read More - https://bussinessinsights.com/research-report/china-artificial-intelligence-(ai)-camera-market
Security & surveillance applications account for the largest share of China's AI camera market in 2025, a trend driven by expansive smart city deployments and regulatory mandates. Consumer electronics, primarily smartphones and smart devices, follow closely behind, benefiting from mass-market adoption and continuous innovation. Automotive and healthcare sectors are rising in importance, propelled by advanced safety requirements and medical imaging advancements, respectively. This growing application diversity supports the market’s rapid expansion and cross-sector innovation.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-artificial-intelligence-(ai)-camera-market
Frequently Asked Questions
Who are the key players in China Artificial Intelligence (AI) Camera Market industry?
The top 5 players in the China AI Camera Market include Hikvision, Dahua Technology, Huawei, Xiaomi, and SenseTime. Hikvision and Dahua are industry leaders in surveillance solutions, while Huawei and Xiaomi leverage AI for smartphone cameras. SenseTime is known for advanced AI image processing and facial recognition technologies.
What is the China Artificial Intelligence (AI) Camera Market growth?
The China AI Camera Market is witnessing rapid growth, driven by government investment in smart city initiatives and public safety. For example, Hikvision reported a significant increase in AI camera sales in 2023, underlining accelerated demand for intelligent surveillance and automation across urban and enterprise sectors.
Which segment accounted for the largest China Artificial Intelligence (AI) Camera Market share?
The security and surveillance application segment holds the largest market share in China’s AI camera market. This is due to widespread adoption by government and commercial sectors for facial recognition and real-time monitoring, with companies like Dahua Technology at the forefront of AI-powered security solutions.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: RFID Smart Cabinet Market to Hit $1.18B by 2032, 9.5% CAGR
By PW Consulting, 2026-09-16
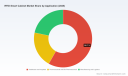
Navigating the RFID Smart Cabinet Revolution: Strategic Intelligence for 2026 Enterprise Decision-Making
Executive Overview
The enterprise landscape is undergoing a profound transformation driven by the need for real-time visibility, operational efficiency, and stringent regulatory compliance. At the forefront of this shift is the RFID Smart Cabinet market, a specialized yet rapidly expanding sector within the broader Internet of Things (IoT) and asset tracking ecosystem. As organizations across healthcare, manufacturing, and logistics strive to eliminate inventory blind spots, smart cabinets equipped with Radio Frequency Identification (RFID) technology have emerged as a critical infrastructure component.
This article serves as a strategic primer for executives and industry analysts evaluating the RFID Smart Cabinet market. It synthesizes key macro-economic trends, competitive dynamics, and regulatory drivers that define the current landscape. While this overview provides a high-level perspective on market momentum and structural forces, a comprehensive understanding of specific growth vectors, regional nuances, and detailed segment analysis requires access to the full proprietary research dataset. The following insights are designed to highlight the strategic imperative for action in 2026 while underscoring the depth of intelligence available through our complete market study.
Macro Market Trajectory: From Recovery to Accelerated Expansion
The trajectory of the RFID Smart Cabinet market over the past half-decade illustrates a robust recovery and acceleration pattern. Historical data from 2020 through 2025 demonstrates a consistent upward trend in revenue generation, reflecting increasing enterprise adoption rates and the maturation of RFID technology. The market has moved beyond early adoption phases into a period of scaled deployment, where the value proposition of automated inventory management is now widely recognized across multiple verticals.
Looking forward, the forecast period spanning 2026 to 2032 indicates a continued period of significant growth. Market projections suggest that the industry is poised to reach new revenue milestones, driven by the integration of advanced IoT capabilities and the pressing need for supply chain digitization. The compound annual growth rate (CAGR) during this forecast window remains a key indicator of market health, signaling sustained investor confidence and technological innovation. This growth is not merely linear; it represents a structural shift in how high-value assets are managed, tracked, and secured within enterprise environments.
For strategic planners, these macro trends suggest that delaying investment in smart cabinet infrastructure could result in competitive obsolescence. The momentum is clear: the market is expanding, and the baseline for operational efficiency is being raised by early adopters who are leveraging real-time data to optimize workflows. However, navigating this expansion requires more than just recognizing the growth trend; it demands a granular understanding of where value is being created and how market share is distributed among key players.
Key Industry Dynamics and Regulatory Drivers
The expansion of the RFID Smart Cabinet market is not happening in a vacuum. It is heavily influenced by a confluence of regulatory mandates, technological cost reductions, and operational necessities. Understanding these dynamics is essential for assessing risk and opportunity in the current investment cycle.
- Healthcare Compliance Mandates: The healthcare sector remains a primary driver of demand. Regulatory frameworks such as the U.S. FDA Unique Device Identification (UDI) mandate enforce strict requirements for medical device tracking. This directly increases the demand for RFID smart cabinets in hospital inventory compliance, ensuring that supplies are not only tracked but also auditable in real-time. Furthermore, Joint Commission standards require real-time inventory tracking for high-value medical assets, driving adoption of RFID smart cabinets in U.S. hospitals. These compliance pressures transform smart cabinets from a luxury into a necessity for risk management.
- Cost-Effectiveness and Scalability: A critical enabler of widespread deployment is the cost structure of underlying RFID components. Passive UHF RFID tag costs are projected to range from $0.05 to $0.15 per unit in high volume for 2026. This reduction in unit cost enables scalable smart cabinet deployments, allowing organizations to tag individual items within cabinets without prohibitive expense. This economic shift lowers the barrier to entry for smaller facilities while enhancing the ROI for large-scale health systems.
- Standardization and Interoperability: Reliable tracking relies on adherence to global standards. ISO 18000-63 and EPCglobal Gen2 protocols govern RFID smart cabinet operations in industrial and healthcare environments. Compliance with these standards ensures that hardware and software from different vendors can interoperate, reducing vendor lock-in risks and facilitating smoother integration into existing enterprise resource planning (ERP) and supply chain systems.
- Supply Chain Digitization: Broader initiatives by the FDA and Joint Commission compliance mandates for supply chain digitization accelerate RFID smart cabinet installations in healthcare facilities. The push for end-to-end visibility means that point solutions are no longer sufficient; cabinets must communicate seamlessly with broader logistics networks, creating a demand for connectors and APIs that enhance system integration.
These dynamics create a complex operating environment. While regulatory pressure pushes adoption, the ability to scale efficiently depends on technology costs and interoperability. A deep dive into the specific impact of these factors across different regions and application verticals is necessary to formulate a targeted entry or expansion strategy. The full market report provides a detailed breakdown of how these dynamics interact to shape revenue potential in specific contexts.
Segmentation Landscape: Beyond the Aggregate Numbers
While the overall market size tells a story of growth, the true strategic value lies in understanding the segmentation splits that define revenue distribution. The market is primarily segmented by region and application, each presenting unique opportunities and challenges.
In terms of application, the Healthcare and Hospitals sector represents a dominant share of the market revenue, reflecting the high value of medical supplies and the strict regulatory environment. However, Pharmaceutical and Bio-Pharmaceutical applications, as well as Manufacturing and Logistics, constitute significant and growing portions of the ecosystem. Each segment has distinct requirements regarding temperature sensitivity, asset value, and workflow integration. For instance, pharmaceutical storage demands rigorous environmental monitoring alongside inventory tracking, whereas manufacturing logistics may prioritize tool control and access management. Recognizing which segment aligns with an organization's core competencies or target customer base is a critical step in strategic positioning.
Geographically, the market exhibits varying levels of maturity and opportunity. North America currently holds a substantial portion of market revenue, driven by advanced healthcare infrastructure and early adoption of compliance technologies. Europe follows as a significant market, with increasing regulatory alignment and industrial IoT adoption. The Asia Pacific region presents a dynamic growth environment, characterized by rapid industrialization and expanding healthcare facilities. Latin America and the Middle East and Africa, while currently smaller in absolute revenue terms, offer emerging opportunities as digitization efforts gain traction in these regions.
It is important to note that while the aggregate revenue figures provide a sense of scale, the specific percentage contributions and dollar values for each region and application segment are subject to complex variables including local regulatory frameworks, infrastructure readiness, and competitive intensity. Accessing the detailed segmentation data within the full report allows stakeholders to identify high-growth pockets that may not be visible from top-level aggregates.
Competitive Landscape: Innovation and Consolidation
The competitive environment in the RFID Smart Cabinet market is characterized by a mix of specialized solution providers, large-scale technology integrators, and component manufacturers. The market concentration indicates a moderately fragmented landscape, where innovation and niche specialization often drive success alongside broader ecosystem plays.
Several key companies define the current competitive benchmarks. Terso Solutions, Inc. specializes in RAIN RFID-enabled smart cabinets and enclosures for real-time inventory tracking of high-value medical supplies, pharmaceuticals, and temperature-sensitive assets. Similarly, IDENTI Medical develops patent-protected RFID smart cabinets with UHF RFID, cloud integration, and business intelligence software for hospital inventory management and supply chain visibility. These players focus heavily on the healthcare vertical, leveraging compliance needs as a lever for adoption.
In the industrial and manufacturing space, companies like Nexess Solutions offer IoT and RFID smart cabinets such as the NexCap XL for automated tool control, asset tracking, inventory management, and access control in industrial, aerospace, and pharmaceutical environments. CribMaster and Snap-On Incorporated also compete in this space, with CribMaster manufacturing AccuCab automated RFID-enabled tool cabinets for industrial and MRO inventory control, and Snap-On offering AutoCab FX and AutoLocker FX RFID smart cabinets for tool and equipment management.
Component and technology providers play a crucial role in enabling these solutions. Impinj, Inc. supplies RAIN RFID chips, readers, and solutions optimized for smart cabinet applications in enterprise inventory and asset tracking. Alien Technology, LLC manufactures RFID tags and systems that integrate into smart cabinet platforms for real-time tracking. Avery Dennison Corporation provides RFID tags and printers for labeling and integration into smart cabinets, forming the backbone of the tagging infrastructure.
Recent developments highlight the pace of innovation. In early 2026, Terso Solutions launched a new generation of RFID smart cabinets specifically for automated tracking of medical supplies and temperature-sensitive high-value assets. Impinj introduced next-generation RAIN RFID chips and readers optimized for smart cabinet applications, enabling higher read accuracy and faster inventory processing. Avery Dennison expanded RFID-enabled inventory management solutions for healthcare and industrial environments, enhancing smart cabinet integrations with real-time asset tracking and cloud analytics. Furthermore, strategic partnerships are reshaping the landscape; a notable example includes a high-level strategic partnership announced between Zebra Technologies and SATO Holdings to co-develop next-generation RFID-enabled smart cabinet solutions.
Other notable participants include LogiTag Systems, which provides RFID smart cabinets and medical supply management solutions for automated inventory control, charge capture, and compliance in healthcare facilities. Mobile Aspects manufactures RFID-enabled smart cabinets for surgical supplies, high-value device tracking, and clinician workflow automation in hospitals. Invengo Technology supplies RFID smart cabinet systems with tags, readers, and software platforms for asset management and inventory in healthcare and industrial applications. TAGSYS RFID develops RFID solutions including smart cabinets and readers for inventory tracking and access control. SATO Holdings Corporation provides RFID-enabled smart cabinet solutions integrated with printers and readers for retail and healthcare inventory management. Stanley Healthcare offers RFID smart cabinet systems for healthcare inventory and supply chain management. Techcode manufactures metal RFID smart cabinets with advanced UHF RFID integration for furniture and storage solutions. Grifols integrates RFID smart cabinets into plasma and medical supply inventory systems.
Understanding the specific strengths, partnerships, and product roadmaps of these competitors is vital for positioning. The full research report offers a detailed competitive analysis, including market share estimates and strategic profiling, which is essential for competitive intelligence and partnership evaluation.
Server Cabinet Market
Strategic Implications for 2026 Decision-Makers
As enterprises plan their capital expenditures and technology roadmaps for 2026 and beyond, the RFID Smart Cabinet market presents both opportunities and complexities. The convergence of regulatory pressure, cost reductions, and technological maturity creates a favorable environment for deployment. However, success depends on selecting the right partners, understanding the specific needs of the target segment, and ensuring integration with broader digital ecosystems.
Decision-makers must look beyond the initial hardware cost and consider the total value of ownership, including software analytics, cloud integration, and long-term support. The ongoing product launches and partnerships indicate that the technology is evolving rapidly, offering higher accuracy and better connectivity. Staying informed about these developments through continuous market intelligence is crucial for maintaining a competitive edge.
RFID Smart Cabinet Market
The strategic value of this market research lies in its ability to convert raw data into actionable insights. By understanding the macroeconomic trends, the specific drivers in healthcare and industrial segments, and the competitive moves of key players, organizations can make informed decisions about investment, expansion, and innovation.
Conclusion
The RFID Smart Cabinet market is at an inflection point, driven by essential compliance needs and the broader shift towards Industry 4.0 and connected healthcare. The projection of significant market growth through 2032 underscores the long-term viability of this technology sector. However, navigating this landscape requires more than general awareness; it demands precise data and deep analytical context.
This overview has highlighted the key growth drivers, regulatory influences, and competitive forces shaping the industry. To transform these insights into a concrete strategy, stakeholders are encouraged to access the full market research report. The complete study provides the detailed segmentation data, regional analysis, and comprehensive competitor profiles necessary to validate assumptions and identify specific growth opportunities. In a market moving at this pace, having access to the most current and granular intelligence is the most valuable asset an organization can possess.
For detailed analysis of this topic, please visit the official page: RFID Smart Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Padlock Market Reaches $2B in 2025, 5.9% CAGR ≈ $3.1B by 2032
By PW Consulting, 2026-09-16
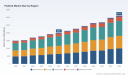
Strategic Insights: The Padlock Market Trajectory and Decision Framework for 2026
The global security hardware landscape is undergoing a structural transformation, and nowhere is this more evident than in the padlock market. As organizations recalibrate their physical security postures in response to evolving regulatory environments, supply chain volatility, and rising threat vectors, the padlock sector has emerged as a critical barometer of industrial resilience and commercial confidence. This article serves as a strategic preview of our latest comprehensive market research, designed to equip executives, procurement leaders, and security architects with the analytical rigor required to navigate the forecast period from 2026 through 2032.
Over the past half-decade, the market has demonstrated a consistent upward trajectory, recovering from the contractionary pressures of the early 2020s and establishing a robust growth foundation. Total market revenue reached approximately USD 2.137 billion in 2026, reflecting a compound annual growth rate of 5.9 percent across the forecast horizon. This expansion is not merely a function of post-pandemic normalization; it is driven by foundational shifts in how businesses and institutions approach asset protection, regulatory compliance, and operational continuity. Understanding these underlying currents is essential for any organization seeking to optimize capital allocation, mitigate supply chain exposure, and align security procurement with long-term strategic objectives.
Macroeconomic Foundations and Growth Catalysts
The revenue progression from 2020 through 2025 tells a story of adaptive resilience. After starting at roughly USD 1.502 billion in 2020, the market expanded steadily, surpassing the USD 2.0 billion threshold by 2025. This growth has been underpinned by sustained demand across commercial security deployments, residential protection upgrades, and industrial applications where lockout/tagout protocols and heavy-duty access control remain non-negotiable. The forecast period extending to 2032 projects a market valuation approaching USD 3.116 billion, signaling that the sector has moved beyond cyclical recovery into a phase of structural expansion.
Padlock Market
Several interlocking factors are accelerating this trajectory. First, the modernization of physical security infrastructure in mid-market commercial real estate and logistics facilities is creating consistent replacement and upgrade cycles. Second, residential security spending has matured beyond basic deterrent models toward integrated, higher-tolerance hardware that complements smart home ecosystems. Third, industrial and institutional buyers are increasingly standardizing on certified, auditable locking solutions that satisfy insurance requirements and occupational safety mandates. These demand drivers are compounding, and they interact with macroeconomic variables that our research quantifies through scenario-based modeling and sensitivity analysis.
Regulatory and Supply Chain Dynamics Shaping Procurement Strategy
The padlock market does not operate in a vacuum. Recent regulatory interventions have introduced new cost structures and compliance considerations that directly influence manufacturing economics and downstream pricing. The Department of Commerce initiated the Section 232 Steel and Aluminum Inclusions Process in April 2025, with determinations issued within a 60-day window. This action has had immediate implications for raw material inputs, particularly for steel-bodied and laminated padlocks prevalent in construction, industrial, and municipal applications. Subsequent expansions to the tariff list in August 2025 added hundreds of product categories to the steel and aluminum duty framework, raising component costs and reinforcing the need for strategic sourcing flexibility.
Lock Market
Simultaneously, the Harmonized Tariff Schedule underwent revision in 2026, with updated classifications for imported padlocks affecting duty calculations for manufacturers supplying North American and broader US channels. These classification adjustments require procurement teams to reassess landed cost models, evaluate alternative supplier geographies, and consider inventory timing strategies that account for duty volatility. Our research maps these regulatory touchpoints against pricing elasticity and supply chain reconfiguration scenarios, providing decision-makers with a structured view of how policy shifts translate into operational risk and opportunity.
On the standards side, the CEN classification framework continues to serve as the authoritative reference for security ratings across global markets. Manufacturers such as ABUS maintain active alignment with BS EN12320 testing protocols, which define low, medium, and high security tiers. Commercial insurers, facility managers, and government procurement offices increasingly reference these ratings during vendor selection, making certification status a strategic differentiator rather than a passive compliance checkbox. Understanding which manufacturers have sustained validated ratings, and how those ratings map to end-use risk profiles, is a recurring theme throughout our analysis.
Competitive Architecture: incumbents, specialists, and the certification moat
The competitive landscape is characterized by a mix of globally scaled manufacturers, family-owned specialists, and regional players that compete on distinct value propositions. Concentration metrics indicate that the top three firms command approximately 55 percent of market revenue, while the top five collectively hold around 62 percent. This level of concentration suggests that scale advantages in distribution, certification portfolios, and OEM integration are meaningful, yet ample room remains for differentiated players to capture niche demand through specialized product architectures and relationship-driven channels.
Within this architecture, several manufacturers have established recognizable positions. Master Lock Company LLC operates a broad portfolio spanning combination, laminated, high-security, lockout/tagout, and smart-connected models, serving home, commercial, and industrial channels with a globally recognized distribution footprint. Wilson Bohannan Lock Company LLC, a seventh-generation family enterprise, has built its reputation on solid brass construction, high-security interchangeable core designs, and door-key compatible configurations tailored for utility, industrial, military, and government deployments. ABUS August Bremicker Söhne KG maintains a strong European and global presence in premium padlock segments, with particular relevance in commercial, industrial, and safety applications where certified security ratings carry weight.
In the North American manufacturing base, Pacific Lock Company has drawn attention through its focus on government-standard field service hardware and medium-to-low security padlocks for military and Department of Defense applications. Its recent achievement of Department of Defense approval for the PL951 high-security padlock, following successful certification under MIL-DTL-43607J, positioned it as the first and only US manufacturer certified to all three military padlock grades. This milestone illustrates how certification depth can function as a competitive moat, particularly in segments where procurement specifications are stringent and substitution is limited. Wilson Bohannan and other US-based specialists similarly emphasize interchangeable cores, custom OEM solutions, and utility-grade durability, expanding the menu of options available to buyers who require traceable supply chains and configurable hardware.
Asian manufacturers contribute additional capacity and product diversity. SINOX, for example, produces heavy-duty key and combination padlocks targeting school, gym, toolbox, club, and industrial locker environments, with resettable and key override features that address practical operational needs. Federal Lock Company and other regional producers supply padlocks tailored to security and industrial requirements, broadening the supplier base for cost-sensitive and application-specific deployments. Meanwhile, Brady Corporation reinforces the lockout/tagout safety segment, providing safety padlocks and employee protection solutions that intersect physical security with occupational health compliance. These varied profiles underscore a market where segmentation by material, mechanism, security tier, and end-use application creates multiple distinct playing fields rather than a single commoditized arena.
Report Scope: Operational Intelligence for Procurement and Strategy Teams
Our research is structured to move beyond headline figures and deliver actionable intelligence across the dimensions that matter most to enterprise decision-making. The report opens with a detailed market sizing framework that traces historical revenue performance and projects forward through the forecast period, enabling readers to benchmark their own growth assumptions and identify divergence points between macro trends and segment-level behavior. Revenue models are expressed in millions of USD and are accompanied by scenario analysis that accounts for regulatory cost impacts, material price volatility, and demand elasticity across application categories.
A central component of the study is the segmentation architecture, which disaggregates revenue by type, application, and geographic region. This framework is designed to help procurement and product strategy teams understand where value concentrates, which sub-segments exhibit higher growth momentum, and how regional demand patterns interact with manufacturing and logistics footprints. The analysis also examines material composition trends, including the relative positioning of steel, brass, and other body constructions, alongside mechanism differentiation that ranges from traditional keyed systems to rotating disc cylinder technologies and smart-connected variants. These structural insights are paired with qualitative assessment of how certification status, insurance alignment, and OEM integration influence share dynamics.
The competitive profiling section extends beyond descriptive summaries. Each key enterprise is evaluated across manufacturing capability, certification portfolios, channel reach, and recent strategic moves that signal shifting priorities. The report captures notable developments such as military-grade certification achievements, trade show participation that signals market expansion intent, and product-line extensions that address emerging use cases. By contextualizing these events within broader industry cycles, the analysis helps readers distinguish between one-off announcements and structural shifts that warrant attention in sourcing and partnership decisions.
In addition, the study integrates a regulatory and standards watch module that tracks tariff classifications, trade policy adjustments, and testing standards that affect compliance and cost. This module is intended for teams that need to anticipate changes before they impact landed costs or vendor eligibility. The report also includes a framework for evaluating supplier risk, covering concentration exposure, geographic dependency, and the implications of raw material tariff regimes for steel and aluminum-intensive product lines. Together, these components form a decision-support toolkit rather than a static market snapshot.
Strategic Implications for 2026 and Beyond
For executives navigating 2026, the padlock market presents a clear mandate: treat physical security hardware as a strategic input rather than a commoditized purchase. Several implications follow directly from the data and dynamics outlined in our research.
- Certification alignment is a procurement accelerator. Buyers whose specifications reference recognized security ratings and military or industrial certifications can streamline vendor qualification, reduce substitution risk, and strengthen audit readiness. Manufacturers with validated certifications across multiple tiers are better positioned to support regulated environments and insurance-driven compliance requirements.
- Material cost volatility demands sourcing diversification. Recent tariff developments around steel and aluminum content have reshaped cost structures for laminated and steel-bodied padlocks. Organizations should evaluate multi-source strategies, alternative material configurations where operationally acceptable, and inventory planning that accounts for duty cycles and classification updates.
- Segment strategy should match risk profile to product architecture. Commercial security, residential protection, and industrial applications each impose distinct performance, durability, and compliance expectations. A portfolio approach that aligns product selection with end-use risk, rather than defaulting to uniform specifications, yields better total cost of ownership and fewer downstream failures.
- Competitive concentration creates both stability and opportunity. While a concentrated top tier provides established distribution and certification depth, specialized manufacturers continue to compete effectively through customization, OEM integration, and niche certification portfolios. Evaluating both scale players and specialists enables buyers to balance reliability with flexibility.
- Standards and classification monitoring should be institutionalized. Changes to tariff schedules, testing standards, and security rating frameworks can alter vendor eligibility and landed costs. Embedding regulatory surveillance into procurement workflows reduces surprise and supports more resilient contracting terms.
The market is not merely growing; it is evolving in ways that reward organizations who can read the interplay between regulation, material economics, certification, and application-specific demand. Our research is designed to make that interplay legible, providing the analytical scaffolding needed to convert market intelligence into procurement strategy, capital planning, and risk mitigation.
Accessing the Full Intelligence Package
This article has outlined the strategic contours of the padlock market and highlighted the decision frameworks that our latest research brings into focus. The complete study goes further, delivering the granular segmentation detail, competitive benchmarking, scenario models, and regulatory tracking that enterprise teams require to move from awareness to action. Core figures, segment-level revenue splits, regional demand patterns, and application-specific growth breakdowns are available in the full report, alongside detailed profiles of the manufacturers shaping the competitive landscape and an expanded view of the regulatory developments influencing cost and compliance.
For decision-makers ready to translate market dynamics into concrete sourcing, pricing, and portfolio choices, the full research package provides the depth and specificity needed to sharpen strategy across the 2026 to 2032 horizon. We invite you to access the complete report to explore the segmentation architecture, competitive analysis, and scenario frameworks that underpin the insights summarized here.
For detailed analysis of this topic, please visit the official page: Padlock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dipropylene Glycol Market Hits USD 4.9B in 2025, Projects 4.14% CAGR Through 2030
By PW Consulting, 2026-09-16
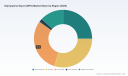
Strategic Intelligence in the Dipropylene Glycol (DPG) Market: Navigating the 2026-2032 Forecast Period
The global Dipropylene Glycol (DPG) market stands at a critical inflection point as we move deeper into 2026. For procurement leaders, supply chain strategists, and market expansion teams, understanding the trajectory of this essential chemical intermediate is no longer just a matter of cost optimization; it is a strategic imperative. The DPG market, valued at 4.9 billion USD in the base year of 2025 and projected to reach 6.51 billion USD by 2032, presents a complex landscape shaped by feedstock volatility, evolving regulatory frameworks, and shifting end-user demand. This comprehensive market research study offers the granular intelligence required to make informed decisions in this dynamic environment.
Our latest report provides a deep dive into the historical performance and future outlook of the DPG sector. With a historical review spanning 2020 to 2025 and a detailed forecast period extending from 2026 to 2032, the study is designed to equip stakeholders with the foresight necessary to mitigate risk and capitalize on emerging opportunities. The compound annual growth rate (CAGR) of 4.14 percent underscore a steady, yet nuanced, expansion trajectory. However, headline figures only tell part of the story. To truly navigate the market, one must understand the underlying forces driving these numbers, from regional supply dynamics to grade-specific demand shifts.
Market Trajectory and Growth Dynamics
Analyzing the historical data reveals a resilient market foundation. After reaching 4.0 billion USD in 2020, the market witnessed a consistent upward trend, accelerating to 4.63 billion USD by 2024 and settling at 4.9 billion USD in 2025. This growth reflects the compound's versatility across diverse industrial applications. Looking ahead, the forecast period suggests continued expansion, with market size anticipated to hit 5.28 billion USD in 2026. However, astute analysis reveals that growth is not always linear. Strategic fluctuations noted in the forecast data highlight the sensitivity of the market to external pressures such as raw material costs and production scheduling, making real-time intelligence crucial for capacity planning and procurement timing.
The projected growth to 6.51 billion USD by 2032 indicates a robust long-term outlook. Yet, the path to this figure is influenced by several macroeconomic and microeconomic variables. Our research dissects these variables to provide a clear view of where value is being created and where margins might be under pressure. Understanding the interplay between supply chain constraints and demand generation is key to leveraging these forecasts effectively.
Supply Chain Pressures and Raw Material Dynamics
One of the most significant factors influencing the DPG market in 2026 is the cost of raw materials, specifically propylene oxide. As a co-product of monopropylene glycol production, DPG manufacturing is intrinsically linked to the availability and pricing of upstream feedstocks. Recent data indicates that propylene oxide prices in North America rose 7.5 percent quarter-over-quarter to 1.14 USD/KG by March 2026. This upward pressure on feedstock costs directly impacts DPG manufacturing economics, prompting strategic adjustments across the value chain.
These cost pressures have already manifested in market behavior. In April 2026, Industry leaders Dow Chemical and Monument Chemical announced price increases on Dipropylene Glycol and related glycol products. Dow Chemical specifically targeted DPG LO+ and related glycol products, citing exposure to propylene oxide feedstock pressures. Such moves signal a tightening margin environment that buyers must anticipate. Our report provides detailed analysis on how these cost pass-through mechanisms affect different regions and application sectors, enabling buyers to negotiate from a position of strength.
Technological Innovation and Sustainability Trends
Sustainability is no longer a peripheral concern in the DPG market; it is becoming a core driver of procurement decisions. Leading producers are increasingly integrating bio-based and recycled feedstocks into their portfolios to meet the growing demand for sustainable chemicals. Dow Inc.'s marketing of Dipropylene Glycol-REN LO+ with at least 50 percent ISCC PLUS certified bio-based material via the Ecolibrium mass-balance approach serves as a prime example. This innovation allows customers in personal care and industrial applications to reduce their carbon footprint without compromising product performance.
Such developments require buyers to evaluate not just the chemical properties but also the lifecycle credentials of the DPG they source. Our research assesses the availability and scalability of these sustainable grades against traditional petrochemical routes. We examine how mass-balance certification and bio-circular feedstocks are reshaping the competitive landscape and influencing customer preferences, particularly in regions with stringent environmental regulations.
Regional and Segment Growth Opportunities
The Asia Pacific region continues to command a significant share of global DPG consumption, reflecting the broader growth of chemical-intensive industries in the region. Similarly, North America and Europe remain substantial demand centers, driven by established industrial bases and high standards for product quality and safety. Our report breaks down market dynamics across these key geographies, analyzing how local production capacities, import-export balances, and regional regulatory environments shape supply availability and pricing structures. By understanding regional nuances, stakeholders can optimize their sourcing strategies and identify untapped markets or underserved segments.
Beyond geography, the composition of the DPG market by type and application reveals critical growth vectors. Technical grades hold a prominent position, catering to broad industrial needs such as solvents and coupling agents. Pharmaceutical and electronics grades also command significant value, driven by stricter purity requirements and niche applications. The analysis covers Functional Fluids, Polyurethane and Polyester Resins, and Personal Care and Pharmaceuticals, highlighting how demand patterns differ across these verticals. For instance, while functional fluids represent a large volume segment, the personal care sector drives demand for high-purity, low-odor variants. Understanding these segmentation dynamics allows companies to tailor their product development and marketing strategies to the most lucrative opportunities.
Competitive Landscape and Industry Consolidation
The DPG market is characterized by a moderately concentrated competitive structure. Our analysis identifies a CR3 of 51.0 percent and a CR5 of 62.0 percent, indicating that the top five players hold a substantial portion of the market. This concentration suggests that major producers have significant influence over pricing, supply stability, and innovation directions. Key companies profiled in the research include Dow Inc., BASF SE, LyondellBasell Industries, Shell Chemicals, and ExxonMobil Chemical.
Each of these players brings distinct capabilities and strategic focuses to the market. Dow Inc., based in Midland, Michigan, is a primary producer of DPG Regular Grade and specialized grades such as DPG-CIR LO+, DPG-REN LO+, as well as DPG LO+ and DPG JSQI variants. Dow supplies fragrance-grade, industrial-grade, and sustainable options, leveraging its co-product status from monopropylene glycol production to offer a wide array of solutions for solvents, coupling agents, and personal care. BASF SE, headquartered in Ludwigshafen, Germany, offers DPG as a by-product of monopropylene glycol production and provides grades for use as solvents in fragrances, inks, semiconductors, leather, and hydraulic fluids, along with Care-grade humectant and solubilizer formulations.
Propylene Glycol (PG) Market
LyondellBasell Industries, with its operations in Houston, Texas, manufactures both industrial grade and fragrance-grade DPG, supplying the polyester synthesis, urethane, personal care, and industrial sectors. Shell Chemicals, based in London, United Kingdom, focuses on supplying DPG LO (low-odor) and standard grades for perfumery, cosmetics, and industrial solvents, supported by comprehensive product stewardship summaries. ExxonMobil Chemical, located in Spring, Texas, produces and supplies DPG as part of its broader glycol portfolio, serving chemical intermediates, coatings, and personal care applications. The report provides in-depth competitive profiling, examining each company's product portfolio, regional footprint, and strategic moves to help clients benchmark their position and identify partnership or acquisition opportunities.
Regulatory Compliance and Operational Safety
Operating in the DPG market requires strict adherence to regulatory standards and product stewardship protocols. Dipropylene Glycol production is a by-product of monopropylene glycol manufacturing, subjecting it to specific regulatory oversight. For instance, strict REACH registration requirements govern the safety data sheets and handling of DPG in European markets. Additionally, industrial grade DPG requires compliance with the Globally Harmonized System for transport and handling, as outlined in stewardship bulletins from major producers like LyondellBasell. These regulatory frameworks impact not only the cost of compliance but also the flow of goods across borders and the ability to enter certain markets. Our report details the regulatory landscape, providing guidance on how to navigate these requirements efficiently while maintaining operational continuity.
Executive Takeaways and Strategic Recommendations
For executives and decision-makers, the insights contained in this report translate into actionable strategies. The 4.14 percent CAGR and the projected market size of 6.51 billion USD by 2032 suggest ample opportunity, but realizing this value requires precise navigation of the complexities outlined above. Procurement teams should consider locking in supply agreements or diversifying sources in light of the April 2026 price increases and ongoing feedstock volatility. R&D and product development units can leverage the growth in sustainable grades and specialty applications to differentiate offerings. Furthermore, understanding the competitive concentration and the specific capabilities of key players like Dow, BASF, and LyondellBasell can inform partnership strategies and market entry plans.
Dipropylene Glycol (DPG) Market
The DPG market is evolving. The transition from high-volume industrial consumption to more specialized, value-driven applications, coupled with the push for sustainability and the realities of raw material cost fluctuations, demands a sophisticated approach to market intelligence. This study is designed to be that compass, offering the depth and breadth of analysis needed to thrive in the 2026-2032 period. By illuminating the hidden drivers of market performance and forecasting, we empower our clients to move beyond reactive adjustments and toward proactive, strategic growth. To access the full scope of data, detailed segmentation breakdowns, and comprehensive company profiles, we invite you to explore the complete market research report.
For detailed analysis of this topic, please visit the official page: Dipropylene Glycol (DPG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulphur Bentonite Market Hits $178.1M in 2025, Projects 4.7% CAGR to 2032
By PW Consulting, 2026-09-16
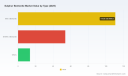
Strategic Intelligence for the Sulphur Bentonite Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
The Sulphur Bentonite Market stands at a critical inflection point. As agricultural demand intensifies and regulatory frameworks evolve across key producing and consuming regions, manufacturers, investors, and supply chain strategists require more than surface-level projections. PW Consulting’s latest market research delivers a comprehensive, forward-looking assessment designed to equip decision-makers with actionable intelligence for the 2026–2032 horizon. This report does not merely chart historical trajectories; it decodes the structural forces shaping value creation, margin dynamics, and competitive positioning in a market experiencing steady, technology-driven expansion.
Market Trajectory: A Data-Backed Foundation for Strategic Planning
Building on a clear historical baseline, the Sulphur Bentonite Market has demonstrated consistent upward momentum across the 2020–2025 evaluation window. Total market valuation climbed from approximately 140.5 million USD in 2020 to an estimated 178.1 million USD by 2025, reflecting sustained adoption of bentonite-sulphur formulations across agricultural and industrial applications. This trajectory is projected to accelerate into the forecast period, with the market anticipated to reach 184.9 million USD in 2026 and expand further to 242.72 million USD by 2032. The compound annual growth rate of 4.7 percent throughout the 2026–2032 forecast window underscores a market characterized by moderate but reliable expansion, driven by soil health initiatives, micronutrient integration requirements, and evolving fertilizer blend architectures.
Revenue streams have consistently been denominated in USD million, providing a standardized metric for cross-regional benchmarking and investment allocation. Rather than relying on static snapshots, this research maps the inflection points where capacity expansions, raw material price realignments, and policy-driven demand shifts converge. For executives calibrating production schedules, pricing architectures, or geographic market entries, these projections establish a disciplined foundation for scenario modeling and resource deployment.
Report Scope and Operational Content: What Decision-Makers Will Gain
PW Consulting’s Sulphur Bentonite Market study is structured to translate macro-level indicators into operational clarity. The report opens with a rigorous segmentation analysis that isolates demand patterns by product specifications, regional consumption profiles, and end-use applications. Each segment is evaluated through the lens of volume drivers, substitution risks, and pricing elasticity, enabling readers to identify where margin expansion is structurally achievable versus where competitive intensity will compress returns.
Sulphur Bentonite Market
Beyond segmentation, the research delivers a granular competitive landscape assessment. It maps enterprise positioning, manufacturing footprints, product portfolio strategies, and recent capacity deployment initiatives. The analysis goes further by integrating supply chain vulnerability mapping, evaluating how molten sulphur feedstock availability, energy cost fluctuations, and logistics constraints influence production economics. Regulatory and environmental compliance requirements are also examined in depth, particularly their impact on dust control protocols, emission standards, and plant-level operating expenditures.
To ensure strategic relevance, the report incorporates a comprehensive dashboard of recent industry developments. These timelines capture manufacturing expansions, facility inaugurations, product line extensions, and regional demand interventions that have already altered market dynamics. By contextualizing these events within broader pricing cycles and policy trajectories, the research provides a working framework for forecasting near-term supply responses and identifying windows of competitive advantage.
Competitive Landscape: Key Players and Strategic Positioning
The Sulphur Bentonite sector exhibits a moderately consolidated structure, with the top three firms commanding approximately 48.0 percent of market share and the top five reaching 58.0 percent. This concentration level suggests that scale, distribution networks, and formulation expertise remain decisive competitive moats. Yet the market continues to attract targeted expansions from both established producers and regional specialists, indicating room for differentiation through product customization, organic certification, and micronutrient integration.
Among the leading participants, several enterprises illustrate distinct strategic orientations. In Gujarat, India, Maruti Corporation has positioned itself as an active manufacturer and exporter of 90 percent sulphur bentonite, alongside micronutrient-enhanced variants incorporating zinc and copper. Its export-oriented model and focus on blended formulations reflect a strategy aimed at capturing emerging market demand for customized nutrient delivery. In Edmonton, Alberta, Keg River has built a reputation around premium bentonite sulphur fertilizers, including its Keg90S and Keg 85S lines, with particular emphasis on pastille form factors and dust mitigation. The company’s OMRI-listed organic offerings further signal a strategic pivot toward compliance-driven and sustainability-conscious buyer segments.
Globally, Tiger-Sul operates as a recognized leader in sulphur bentonite production, maintaining a broad footprint across multiple regions and emphasizing micronutrient-enhanced sulphur products. Its scale and distributionreach provide a benchmark for market positioning. In the Middle East, the National Sulphur Fertilizer Company, based in Qatar’s Messaied Industrial Area, has structured its core plant nutrient offering around high-quality sulphur bentonite, targeting substantial production capacity as part of its regional supply strategy. Meanwhile, Istanbul-based Sulfert Chemical has carved a specialized role in organic bentonite sulphur manufacturing, aligning product development with regulatory and certification preferences in export markets.
India’s Coromandel International Limited continues to expand its dedicated bentonite sulphur fertilizer manufacturing footprint, reinforcing its position within a market increasingly shaped by domestic soil health programs and import demand dynamics. In Dubai, Amarak Chemicals has advanced its portfolio beyond standard formulations to include zincated and boronated sulphur bentonite variants, recently launching a fully automated production facility designed to enhance throughput and consistency. These company profiles collectively illustrate a market where product engineering, certification pathways, and capacity agility are becoming as important as baseline volume output.
Recent Developments and Structural Industry Shifts
Several high-impact developments since early 2025 have already begun reshaping capacity allocation and regional supply balances. In March 2025, Coromandel International Limited inaugurated a second sulphur manufacturing plant at its Visakhapatnam facility, effectively doubling its bentonite sulphur capacity to 50,000 tonnes per annum. This expansion directly addresses rising domestic and export demand, while also signaling India’s broader push toward self-sufficiency in sulphur-based fertilizer inputs.
By February 2026, Amarak Chemicals commenced operations at a fully automated sulphur bentonite facility within the Jebel Ali Free Zone in Dubai, with a 60,000 tonnes per annum capacity target. The launch underscores accelerating investment in Middle Eastern production hubs, where logistics advantages and export-oriented infrastructure are being leveraged to serve both regional agricultural demand and overseas distribution channels. These capacity additions arrive against a backdrop of fluctuating molten sulphur feedstock availability, where refinery maintenance schedules and export restrictions in key producing regions have periodically constrained supply for bentonite sulphur producers.
Simultaneously, raw material pricing dynamics have introduced meaningful volatility into production economics. Average global sulphur prices have fluctuated between roughly 70 and 130 USD per metric ton through mid-2025, compelling manufacturers to recalibrate hedging strategies, inventory buffers, and pass-through pricing mechanisms. Energy cost variability and input price swings have further pressured production economics in key manufacturing zones, particularly in India and China, where cost structures are highly sensitive to feedstock and utility pricing.
Environmental and regulatory developments are equally consequential. Stricter emissions standards and dust control requirements during bentonite sulphur fertilizer production have elevated operational expenditures for manufacturers, prompting investments in closed-system processing, dust suppression technologies, and compliance-driven process upgrades. In India, government-backed fertilizer support programs and widespread soil health card distribution have amplified sulphur bentonite import volumes and domestic demand, creating an additional growth catalyst that interacts with global supply reallocations and pricing cycles.
Strategic Implications for 2026 and Beyond
For executives operating in or adjacent to the Sulphur Bentonite Market, the convergence of steady top-line growth, moderate competitive concentration, and evolving input cost dynamics demands a disciplined strategic posture. The 4.7 percent CAGR through 2032 suggests that broad market expansion will continue, but revenue capture will increasingly depend on segment selection, formulation differentiation, and supply chain resilience. Companies that can align capacity deployment with regional demand signals, manage sulphur feedstock exposure through contractual and inventory strategies, and navigate environmental compliance without sacrificing throughput will be best positioned to defend margins.
Sulphur Recovery Market
The competitive landscape also indicates that scale alone is no longer a sufficient differentiator. Enterprise strategies that incorporate micronutrient enhancement, organic certification readiness, dust control advantages, and automation-driven consistency are emerging as meaningful value drivers. Regional dynamics further complicate the equation: policy interventions in key agricultural markets, refinery-driven sulphur supply constraints, and logistics infrastructure variations require firms to maintain flexible sourcing architectures and scenario-aware production planning. In this environment, intelligence that connects macro forecasts with segment-level demand behavior, competitor capacity moves, and regulatory cost trajectories becomes a critical asset rather than a supplementary report.
How to Access the Complete Intelligence Package
This overview provides a structured preview of the market forces, competitive dynamics, and developmental milestones shaping the Sulphur Bentonite Market through 2032. However, the full research deliverable extends significantly beyond these highlights. Readers seeking detailed segment-level valuations, regional consumption mappings, pricing scenario models, competitive share analyses, and operational benchmarking frameworks will find the complete PW Consulting market study designed specifically for strategic planning, investment evaluation, and supply chain optimization. To access the full dataset, granular forecasts, and executive decision matrices, visit the official market research page and secure the complete intelligence package built for 2026-facing strategy teams.
For detailed analysis of this topic, please visit the official page: Sulphur Bentonite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 4K Ultra HD TV Market Hits $118.85M in 2025, Projected 24.38% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Horizon: Navigating the 4K Ultra HD TV Market in 2026 and Beyond
The 4K Ultra HD television market stands at a critical inflection point as of 2026. Driven by an accelerating compound annual growth rate of 24.38 percent, the sector has transformed from a mature consumer electronics category into a high-velocity growth arena fueled by display innovation, smart ecosystem integration, and shifting viewer behaviors. Our latest 4K Ultra HD TVs Market study compresses the historical trajectory of 2020 through 2025 and extends a disciplined forecast window to 2032, delivering the analytical architecture executives need to calibrate capital allocation, product roadmaps, and supply chain resilience in an increasingly volatile landscape.
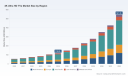
For strategic decision-makers, the overarching narrative is clear: market revenue has climbed from 56.22 million USD in 2020 to an estimated 118.85 million USD in 2025, positioning the base year as a springboard for exponential expansion. Looking forward, the forecast period maps a steep upward curve, projecting revenue to reach 147.92 million USD in 2026, 178.42 million USD in 2027, and accelerating toward 541.36 million USD by 2032. This trajectory is not merely a statistical projection; it is a structural signal that the next wave of growth will be captured by organizations that align product strategy with regional demand patterns, display technology adoption, and application-driven usage models. The purpose of this preview is to illuminate the analytical depth awaiting buyers of the full study, while deliberately withholding the granular breakdowns that only the complete report can provide.
Decoding the Growth Trajectory: From Recovery to Accelerated Expansion
The historical window of 2020 to 2025 reveals a market that has consistently outgrown the broader consumer electronics average. Revenue climbed to 64.76 million USD in 2021, advanced to 76.68 million USD in 2022, and held steady growth at 86.68 million USD in 2023. The acceleration became more pronounced in 2024, when revenue reached 105.39 million USD, before culminating in the 2025 base-year figure of 118.85 million USD. This progression underscores a market that has successfully navigated post-pandemic demand normalization, channel rebalancing, and the early adoption of premium display technologies.
The forecast window from 2026 through 2032 is where strategic planning becomes decisive. Starting at 147.92 million USD in 2026, the market is projected to scale to 228.87 million USD by 2028, then 351.99 million USD by 2030, and ultimately 541.36 million USD by 2032. This stepped expansion signals a market in which technological differentiation, smart-platform monetization, and regional penetration rates will increasingly determine competitive positioning. Executing on this opportunity requires more than a top-line growth assumption; it demands a comprehensive understanding of how product segmentation, regional dynamics, and end-use applications interact over time. The full study unpacks these interactions with a level of granularity that enables scenario planning, market-entry prioritization, and investment sequencing.
Segmentation Architecture: Where Growth Will Concentrate
A market moving at this pace cannot be managed through aggregate figures alone. The report disaggregates the landscape across three critical dimensions, each carrying distinct strategic implications for product planning, pricing architecture, and channel strategy. Understanding how display types compete, how applications evolve, and how regional markets behave is essential for translating a 24.38 percent CAGR into actionable forecasts.
Display Technology Dynamics
The competitive battleground for 4K Ultra HD televisions is increasingly defined by the interplay of advanced display technologies. The study examines OLED, QLED, and LED architectures as distinct value pools, mapping their adoption curves, pricing tiers, and performance positioning. Each technology offers a different value proposition, from premium contrast and color performance to cost-efficient scalability and smart-feature enablement. The analytical framework inside the full report isolates the demand drivers that will determine which technology segments capture share, how pricing pressure evolves, and where manufacturers can secure margin resilience. Because these technology shares are shifting rapidly with new panel supply and consumer preference, the detailed splits and growth trajectories are disclosed only within the complete study.
Application-Driven Demand
Modern 4K Ultra HD TVs are no longer passive display devices; they are content hubs, gaming platforms, and smart-ecosystem endpoints. The report evaluates application categories including Smart TV and Gaming TV environments, alongside other specialized use cases. This segmentation is vital because application mix directly influences feature requirements, connectivity expectations, and retail positioning. Smart TVs, for instance, require deep integration with operating systems, streaming partnerships, and AI-driven user experiences, while gaming-focused models emphasize refresh rates, low latency, and HDR alignment. The study maps demand intensity and growth prospects across these applications, equipping product teams with a demand-side blueprint. Specific proportion breakdowns and revenue attribution by application are reserved for the full report to preserve the precision of the underlying model.
Regional Growth Profiles
Geographic demand is unevenly distributed and increasingly shaped by regulatory conditions, infrastructure readiness, and local pricing dynamics. The research partitions the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each presenting a distinct value-creation path. Asia Pacific represents the largest value concentration, reflecting scale demand and rapid technology adoption, while North America and Europe contribute structurally significant volumes with higher average unit pricing in premium segments. Latin America and the Middle East and Africa present growth opportunities tied to infrastructure expansion, digital content availability, and evolving retail ecosystems. The complete study provides a region-by-region examination of market size trajectories, demand catalysts, and competitive intensity without publishing the detailed regional percentages here, so decision-makers are encouraged to consult the full report for the exact geographic splits required to build accurate regional plans.
Competitive Landscape: Strategic Positioning and Innovation Pressure
The 4K Ultra HD TV market is defined by a dense field of global manufacturers, each pursuing differentiated strategies in display technology, smart-platform integration, and pricing architecture. The report profiles leading enterprises including Samsung Electronics, LG Electronics, Sony Corporation, Hisense, TCL Corporation, Panasonic Corporation, VIZIO, and Skyworth. These companies anchor the market through distinct value propositions: Samsung and LG leverage advanced QLED, OLED, and AI-enhanced smart features; Sony competes on premium picture quality and BRAVIA platform integration; Hisense and TCL push Mini-LED and QD-Mini LED architectures into broader consumer segments with Google TV and smart ecosystem alignment; Panasonic combines OLED and 4K LCD panels with Fire TV integration; VIZIO focuses on accessible 4K UHD smart TVs with Dolby Vision and HDR support; and Skyworth delivers HDR-enabled 4K UHD models targeting value-conscious segments.
Beyond the established incumbents, market dynamics are being reshaped by new entrants and platform-driven expansion. Notably, Amazon announced the W70B Series Smart TV as a core 4K UHD model, emphasizing sleek design and immersive viewing, signaling how platform players are entering the hardware space to deepen ecosystem lock-in. This kind of product launch matters strategically because it intensifies competition for share of attention, smart-services revenue, and retail shelf presence. The full study goes beyond company profiles to map competitive interaction patterns, including how brand portfolios are structured, where pricing pressure is building, and which segments are most vulnerable to disruption. Given the consolidated nature of the industry, competitive analysis must also consider market concentration, and the complete research provides the exact concentration metrics needed to assess barrier-to-entry conditions and pricing power.
Industry Dynamics: Supply Chain Constraints, Regulatory Headwinds, and Cost Volatility
No strategic assessment of the 4K Ultra HD TV market is complete without confronting the operational and regulatory pressures that shape cost structures and supply continuity. As of April 2025, China placed export restrictions on seven categories of medium and heavy rare earths, including dysprosium, samarium, and terbium, which are essential for permanent magnets used in 4K TV displays and components. These restrictions were part of a broader response to tariff escalations and have introduced material price volatility and supply chain uncertainty across electronics production. Further analysis from early 2026 indicates that these controls will continue to affect component availability and cost planning, with additional foreign direct product rule extensions shaping procurement strategies.
The practical implication for manufacturers and channel partners is that cost forecasting can no longer rely solely on historical component pricing. Rare earth constraints and raw material volatility have become structural variables in the cost stack, influencing margin planning, sourcing diversification, and manufacturing geography. The report integrates these dynamics into a broader sustainability and supply chain risk framework, helping executives anticipate where bottlenecks may emerge, how pricing architectures may need to adapt, and which product tiers are most exposed to input-cost fluctuations. Because the precise impact varies by component, component substitution pathways, supplier diversification options, and regional sourcing implications differ across product segments, the complete study supplies the operational detail necessary to translate these macro risks into procurement and product decisions.
Inside the Report: Operational Content Built for Executive Action
This market study is designed to move beyond descriptive trends and deliver decision-grade intelligence. The full version includes product and technology assessments, application-level demand analysis, regional market mapping, and competitive positioning evaluations. It is structured to support multiple functional needs: product managers can use it to prioritize feature roadmaps and display mix decisions; sales and commercial teams can align go-to-market plans with regional demand signals; supply chain and sourcing leaders can evaluate material exposure and supplier diversification paths; and strategy teams can build investment scenarios grounded in forecast-period growth paths.
In addition to the core segmentation and forecast content, the study synthesizes recent industry developments and regulatory milestones, including export control actions and platform-driven product launches, into a practical context for near-term planning. The report is built for readers who need a single analytical reference that connects market size, growth trajectory, competitive intensity, and supply-side risk into one consistent framework. Readers seeking exact regional percentages, application splits, type-based revenue shares, and company-level concentration figures will find those details only in the full release, which is why this preview deliberately highlights the architecture and advisory value without disclosing the embedded figures.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a market view that is simultaneously optimistic about growth and disciplined about risk. A compound annual growth rate of 24.38 percent over the forecast period signals an exceptional opportunity, but capturing that opportunity requires a precise understanding of where growth is concentrated, how competitive pressures are evolving, and which external shocks can alter cost and availability assumptions. The 4K Ultra HD TVs Market study provides that integrated view, linking historical momentum, forecast expansion, segmentation dynamics, and competitive context into a single strategic frame. It is intended to help leadership teams answer the practical questions that shape capital allocation, product portfolio strategy, regional prioritization, and risk mitigation in the year ahead.
For organizations building their 2026 plans, the full report offers the depth required to convert a high-level growth story into actionable strategy. The preview above demonstrates the analytical approach, the scope of coverage, and the strategic context embedded in the research, while preserving the segmented data and competitive metrics for the complete edition. To access the full market size progression by year, the detailed segmentation splits, the comprehensive company profiles, and the operational dynamics analysis, readers are encouraged to obtain the full study from the source page, where the complete intelligence package is available for decision-making across product, commercial, and supply chain functions.
4K Ultra HD TVs Market
UHD TV Market
For detailed analysis of this topic, please visit the official page: 4K Ultra HD TVs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Corporate Travel Insurance Drives 14.75% CAGR in $648.4M Market
By PW Consulting, 2026-09-16
Strategic Imperatives in the Business Travel Insurance Market: A 2026 Outlook
Introduction: The New Risk Landscape for Corporate Travel
Corporate travel has fundamentally transformed over the past half-decade. As organizations navigate a complex environment defined by geopolitical volatility, evolving regulatory frameworks, and heightened duty of care obligations, the business travel insurance market has emerged as a critical component of enterprise risk management strategies. Our latest comprehensive market research provides decision-makers with the intelligence needed to navigate this rapidly expanding landscape through 2032.
The base year analysis (2025) reveals a market that has demonstrated remarkable resilience and growth momentum. Historical data from 2020 through 2025 illustrates consistent upward trajectory, with revenues expanding from 129.74 million USD to 249.8 million USD—a reflection of both increased travel volumes and heightened awareness of comprehensive coverage needs. This growth pattern establishes a robust foundation for the forecast period extending through 2032, where compound annual growth rates are projected at 14.75 percent.
Market Trajectory and Growth Catalysts
The forecast period from 2026 to 2032 presents compelling expansion opportunities that warrant immediate strategic attention. Market valuations are expected to progress from approximately 285.26 million USD in 2026 to reach 648.4 million USD by 2032. This trajectory underscores the accelerating demand for specialized coverage solutions as corporations reassess their travel risk postures in an uncertain global environment.
Structural Market Dynamics and Segment Evolution
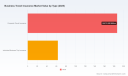
Understanding which coverage categories command the largest share of corporate spending provides essential insight for product development teams and procurement strategists. Within the type-based segmentation, Corporate Travel Insurance represents the dominant category, valued at 186.73 million USD, while Individual Business Trip Insurance accounts for 63.07 million USD. This distribution highlights the strong preference among enterprises for comprehensive group-based solutions that streamline administration and ensure consistent protection across teams.
The application-based analysis further illuminates corporate priorities. Medical and Health Coverage stands at 95.62 million USD, Accident and Liability at 92.19 million USD, and Trip Cancellation and Delay at 61.99 million USD. These figures affirm that health protection and liability management remain paramount concerns for risk managers, while trip disruption coverage continues to gain prominence as travel schedules become increasingly complex and subject to interruption.
Regional deployment patterns reveal distinct maturity profiles across global markets. North America leads with 100.35 million USD in market value, followed by Europe at 74.6 million USD and Asia Pacific at 62.42 million USD. Latin America contributes 12.43 million USD, while the Mideast and Africa region represents an emerging frontier with significant growth potential. These regional distributions correspond closely with corporate travel volumes and maturity of local insurance infrastructure.
Market concentration data indicates that the top three players command 55.2 percent of total market share, while the top five firms control 68.4 percent. This concentrated structure suggests both competitive intensity among established leaders and opportunities for specialized providers to differentiate through niche capabilities, digital innovation, or tailored service models.
Regulatory Environment and Compliance Imperatives
Regulatory considerations increasingly shape procurement decisions within the business travel insurance sector. No federal statute mandates business travel insurance in the United States; however, employers maintain a duty of care obligation under OSHA Section 5(a)(1), creating a compliance-driven rationale for maintaining adequate coverage programs. This obligation extends to organizations operating internationally, where local labor laws and host-country requirements may impose additional expectations.
The ISO 31030:2021 standard for travel risk management provides a framework that requires organizations to document insurance as one control within their broader risk management architecture. Corporations seeking to demonstrate mature risk governance increasingly reference this standard when evaluating provider offerings and structuring their travel protection programs. Adoption of such frameworks correlates strongly with the purchasing patterns observed in larger enterprises.
Evolving data privacy requirements under GDPR and related regulations compel providers to enhance cybersecurity protocols for policyholder data embedded within corporate plans. Organizations must evaluate vendor capabilities not only on coverage breadth and pricing but also on data handling maturity, particularly when policies encompass multinational travel across jurisdictions with divergent privacy expectations. Specialized human labor for claims processing and risk advisory services represents a primary operational cost for business travel insurance providers, a factor that influences both pricing structures and service quality differentiation across the competitive landscape.
Competitive Landscape and Strategic Positioning
The competitive arena features established multinational insurers and specialized providers, each pursuing differentiated value propositions. Allianz, headquartered in Munich, Germany, specializes in Allianz Travel and Allianz Global Assistance business travel insurance plans with digital app-based claims processing, emergency assistance, and corporate/group programs. AXA, based in Paris, France, provides AXA Assistance corporate and digital business travel insurance platforms with multi-trip coverage and real-time traveler support features, emphasizing technology-enabled service delivery.
Travel Insured International, located in Morristown, New Jersey, USA, offers specialized business travel insurance solutions with coverage for trip cancellation, interruption, medical emergencies, and business equipment protection—catering to organizations with diverse asset protection needs. Seven Corners, headquartered in Bloomington, Minnesota, USA, delivers annual multi-trip business travel insurance plans with high limits and features tailored for frequent business travelers and corporate groups, addressing the segment of employees with elevated travel frequency.
International Business Travel Insurance Plans Market
HTH Worldwide, based in Scottsdale, Arizona, USA, provides corporate business travel insurance with long-term and international coverage options for business travelers, serving organizations with extended-duration assignments. Zurich Insurance Group, headquartered in Zurich, Switzerland, offers Zurich Business Travel Solution and Zurich Travel Assist for group business travel insurance with dedicated account management and global claims processing, emphasizing relationship-driven service for complex corporate accounts.
Chubb, also based in Zurich, Switzerland, supplies Chubb Business Travel Insurance plans with group coverage, target market determinations, and integration with corporate risk management—appealing to organizations seeking seamless alignment between travel insurance and broader enterprise risk frameworks. Marsh, headquartered in New York, USA, delivers business travel insurance solutions as part of its risk advisory services, including group plans and corporate risk management integration, positioning insurance within a holistic advisory context.
Aon, based in London, UK, provides Aon Business Travel Insurance solutions with focus on corporate travel programs and integrated risk management services, leveraging its global advisory platform. Berkshire Hathaway Travel Protection, located in Fairfield, Connecticut, USA, specializes in business travel insurance with robust coverage for corporate travelers and group programs, drawing on the financial strength and reputation of its parent organization.
Recent industry developments underscore the evolving governance landscape. In March 2026, the US Travel Insurance Association named a new president to guide the association focused on travel insurance standards, signaling heightened attention to industry self-regulation and best practice dissemination. In February 2026, USTIA released updated resources on why 2026 is the year to travel smart, reinforcing the strategic emphasis on informed coverage decisions as travel activity accelerates.
Report Framework and Analytical Depth
Our market research delivers actionable intelligence across multiple analytical dimensions designed to support evidence-based decision-making. The report structure encompasses comprehensive market sizing with historical baselines and forward-looking projections, segmentation analysis across type, application, and regional dimensions, and granular competitive profiling of key market participants.
Operational cost analysis examines the role of specialized human labor in claims processing and risk advisory services, illuminating cost structures that influence pricing strategies and margin profiles. Coverage architecture assessments evaluate how medical, liability, and trip disruption protections are bundled and priced across different corporate segments, revealing optimization opportunities for procurement teams seeking to align coverage with actual risk exposure.
Business Travel Insurance Market
Technology adoption trends are explored in the context of digital claims processing, real-time traveler support platforms, and integrated risk management dashboards that connect travel insurance data with broader corporate risk ecosystems. The analysis of regulatory developments—including OSHA duty of care obligations, ISO 31030:2021 framework expectations, and GDPR-driven cybersecurity requirements—provides compliance leaders with structured guidance for vendor evaluation and policy design.
The report also incorporates scenario analysis that enables organizations to stress-test their coverage strategies against potential disruptions, from geopolitical events to public health crises and natural disasters. By mapping coverage gaps against plausible disruption scenarios, risk managers can prioritize enhancements that deliver the greatest resilience improvement relative to incremental cost.
Strategic Recommendations for 2026 Decision-Makers
Organizations approaching business travel insurance procurement in 2026 should prioritize several strategic actions. First, assess current coverage alignment with duty of care obligations and ISO 31030:2021 documentation requirements, ensuring that policy structures satisfy both legal expectations and internal governance standards. Second, evaluate provider capabilities in digital claims processing and real-time traveler support, as these service dimensions increasingly differentiate vendor value propositions and influence employee experience during incidents.
Third, consider the integration potential between travel insurance platforms and existing corporate risk management systems, recognizing that seamless data flow enhances both operational efficiency and risk visibility. Fourth, examine regional coverage adequacy in light of expanding travel footprints, particularly as organizations increase engagement with Asia Pacific and Latin American markets where insurance infrastructure continues to mature.
Fifth, benchmark pricing and coverage structures against the competitive landscape, leveraging the detailed vendor analysis provided in this report to identify opportunities for renegotiation or provider diversification. The market concentration data indicates that while large players dominate, specialized providers offer differentiated features that may better suit specific organizational profiles, travel patterns, or risk appetites.
Conclusion: Accessing Comprehensive Market Intelligence
The business travel insurance market stands at an inflection point where growth, regulation, and technology converge to reshape enterprise risk management practices. Our full market research report provides the detailed quantitative analysis, competitive assessments, and strategic recommendations necessary for informed decision-making throughout the 2026–2032 forecast horizon. The insights presented here represent a curated preview of the comprehensive analysis available in the complete study.
Decision-makers seeking granular segmentation data, detailed vendor benchmarking matrices, scenario modeling outputs, and region-specific procurement guidance are invited to access the full report through our platform. The complete intelligence package delivers the depth required to construct resilient, cost-effective, and compliant business travel insurance strategies aligned with organizational objectives.
As corporate travel continues its recovery and expansion trajectory, the organizations that invest in sophisticated risk management frameworks—supported by comprehensive insurance coverage and informed by rigorous market intelligence—will be best positioned to navigate uncertainty while enabling their teams to travel with confidence. We invite you to explore the full research to strengthen your strategic positioning in this dynamic market.
For detailed analysis of this topic, please visit the official page: Business Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: High-Speed Centrifugal Blower Market at $633M in 2025, Forecast 2.9% CAGR to 2032
By PW Consulting, 2026-09-16
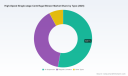
Navigating the High-Speed Single-stage Centrifugal Blower Market: Strategic Intelligence for 2026 Decision Makers
The industrial air and gas handling sector stands at a critical inflection point. As manufacturing processes become increasingly energy-intensive and environmental regulations tighten globally, the demand for efficient, reliable, and high-performance fluid movement solutions has never been more pronounced. At the heart of this transformation lies the High-Speed Single-stage Centrifugal Blower Market, a specialized segment that serves as a critical enabler for wastewater treatment, industrial gas processing, and emerging clean energy applications.
For executives, investors, and strategic planners operating in 2026, understanding the nuances of this market is no longer optional—it is a prerequisite for sustainable growth. This article serves as a strategic primer, drawing from our comprehensive market research report to illuminate the key dynamics, competitive forces, and growth trajectories that will define the sector through 2032. While we outline the broader landscape here, the full depth of our quantitative analysis and granular segmentation remains a vital resource for those seeking to secure a competitive advantage in this evolving industry.
Market Trajectory and Macroeconomic Context
The High-Speed Single-stage Centrifugal Blower Market has demonstrated resilience and steady expansion over the past half-decade. Analyzing the historical performance from 2020 to 2025 provides a robust baseline for forecasting future demand. The market revenue, denominated in USD Million, has shown a consistent upward trend, reflecting the underlying growth in industrial infrastructure and environmental compliance requirements across key global regions.
Looking forward, the forecast period spanning 2026 to 2032 suggests a continued progression. The compound annual growth rate (CAGR) indicated for this forecast window points to a moderate yet steady expansion. This growth is not merely a function of volume but is increasingly driven by the replacement of older, less efficient technologies with high-speed single-stage solutions that offer superior aerodynamic performance and lower lifecycle costs. For stakeholders, this trajectory implies a market that is mature enough to offer stability but dynamic enough to reward those who can navigate technological shifts and regional demand variations effectively.
Technology Drivers and Application Dynamics
The core value proposition of high-speed single-stage centrifugal blowers lies in their ability to deliver high flows at precise pressures with minimal energy consumption. This capability is essential across several key verticals. In the realm of sewage treatment, these blowers are indispensable for aeration processes, where energy efficiency directly correlates with operational expenditure. Similarly, in off-gas desulfuration and other industrial gas handling applications, the ability to manage variable flow requirements while maintaining system integrity is paramount.
Recent developments in the sector highlight a clear industry focus on efficiency and integration. For instance, major players have launched new ranges specifically targeting energy reduction in wastewater applications, aligning with stricter EU energy efficiency standards. These regulatory pressures are not just constraints; they are catalysts for innovation, forcing manufacturers to refine impeller designs, bearing technologies, and control systems. The integration of magnetic levitation and air-foil bearings represents a significant technological leap, reducing maintenance needs and enhancing reliability in continuous operation environments.
However, the market is not without its headwinds. Sector analysis indicates that material costs, particularly for aluminum and steel, alongside skilled labor shortages for high-speed impeller manufacturing, continue to influence overall blower pricing and availability. Supply chain resilience and local manufacturing capabilities are becoming strategic differentiators. Companies that can balance cost efficiency with quality certification, such as ISO 9001 and API standards, are better positioned to capture market share in a regulated environment.
Competitive Landscape and Strategic Positioning
The competitive arena for high-speed single-stage centrifugal blowers is characterized by a mix of established global industrial giants and specialized manufacturers with deep technical expertise. The market concentration, as reflected by CR3 and CR5 metrics, suggests a fragmented yet competitive landscape where differentiation is key. No single entity dominates completely, allowing for niche players to thrive by focusing on specific applications or regional strengths.
High-Speed Single-stage Centrifugal Blower Market
Leading companies such as Howden (Chart Industries) and Gardner Denver continue to set benchmarks with integrally geared turbo blowers and magnetic-bearing models optimized for large turndown ranges. Their recent product launches and partnerships underscore a commitment to R&D and geographic expansion. For example, Howden's launch of high-efficiency centrifugal blower ranges targeting energy reduction demonstrates the industry's response to regulatory and operational pressures. Similarly, expansions by companies like Greenheck into new corporate campuses signal long-term confidence in market growth.
On the other hand, manufacturers based in China, such as Shandong Zhangqiu Blower and Shenyang Blower Works Group Corporation, leverage lower labor and material costs to offer competitive solutions for wastewater treatment and industrial gas handling. Their export capabilities and domestic-leading designs present both a challenge and an opportunity for global incumbents. Meanwhile, specialized firms like APG-Neuros and Hoffman & Lamson focus on delivering energy savings through advanced air-bearing technologies and plug-and-play installations, catering to customers who prioritize ease of integration and operational savings.
Strategic partnerships are also reshaping the landscape. Recent collaborations aimed at strengthening distribution networks, such as those seen in the Mid-Atlantic region, highlight the importance of local presence and service support. Acquisitions of manufacturing facilities to expand production capacity further indicate that supply security is a top priority for companies aiming to meet rising demand without compromising on lead times.
Regional Perspectives and Growth Opportunities
While global demand is rising, the distribution of market value varies significantly by region. North America and Asia Pacific represent substantial portions of the market revenue, driven by robust industrial activity and infrastructure investments. Europe, while a mature market, remains critical due to stringent environmental regulations that accelerate the replacement of legacy systems. Latin America and the Middle East & Africa, though smaller in relative terms, offer emerging opportunities as industrial capacities expand in these regions.
Understanding the specific demand drivers in each region is essential for tailoring go-to-market strategies. In developed markets, the focus is often on retrofitting and upgrading existing installations to meet energy standards. In developing markets, new infrastructure projects and capacity expansions drive initial equipment sales. Our detailed analysis delves into these regional nuances, providing actionable intelligence on where to allocate resources for maximum impact.
Why This Report Matters for 2026 Strategy
In an environment defined by rapid technological change and regulatory complexity, generic industry overviews are insufficient. Decision-makers need access to precise data on market size, segmentation trends, and competitive movements to formulate effective strategies. This report is designed to bridge the gap between high-level market knowledge and actionable strategic insight.
- Comprehensive Segmentation Analysis: Gain clarity on how revenue is distributed across different blower types, applications, and regions without getting lost in aggregated data.
- Competitive Intelligence: Understand the product portfolios, recent developments, and strategic moves of key players to identify gaps and opportunities in the market.
- Risk and Opportunity Assessment: Evaluate the impact of raw material costs, labor availability, and regulatory standards on pricing and supply chain stability.
- Forecasting Accuracy: Utilize our detailed forecast data from 2026 to 2032 to plan capacity, investment, and R&D initiatives with greater confidence.
The insights contained within this research are tailored for stakeholders who require more than just headline numbers. Whether you are evaluating market entry, assessing competitor threats, or optimizing your product roadmap, the granular data provided in the full report is essential for validating assumptions and mitigating risks.
Conclusion: Empowering Decision-Making in a Dynamic Market
The High-Speed Single-stage Centrifugal Blower Market is poised for continued evolution, driven by the dual engines of industrial efficiency demands and environmental compliance. For organizations operating in this space, staying informed is the first step toward staying ahead. While the overview presented here highlights the critical themes and trends shaping the sector, the full extent of our analysis offers the depth required for precise strategic planning.
Centrifugal Compressors Market
We invite you to explore the complete market intelligence provided in our full report. By accessing the detailed segmentation data, comprehensive company profiles, and forward-looking forecasts, you can equip your team with the knowledge needed to navigate the complexities of 2026 and beyond. The investment in accurate, timely market intelligence is an investment in your organization's ability to thrive in a competitive global landscape.
For detailed analysis of this topic, please visit the official page: High-Speed Single-stage Centrifugal Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pallet Rack Market Hits $11.7B in 2025 with 6.7% CAGR to $18.26B by 2032
By PW Consulting, 2026-09-16
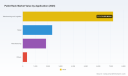
Strategic Intelligence for the Modern Warehouse: Navigating the Pallet Rack Market Outlook 2026–2032
In an era defined by volatile supply chains, accelerating e-commerce penetration, and relentless pressure on warehouse throughput, the pallet racking infrastructure is no longer a passive storage utility. It is a strategic asset that dictates inventory velocity, space utilization, and long-term operational scalability. PW Consulting’s newly published Pallet Rack Market research report transforms fragmented industry signals into a structured intelligence framework, equipping executive teams, procurement leaders, and supply chain architects with the analytical rigor required to make confident capital allocation decisions in 2026 and beyond. The report does not merely track historical inventory movements; it maps the structural inflection points that will separate cost-advantaged operators from those burdened by legacy spatial constraints and unpredictable capex cycles.
Pallet Rack Market
The Macro Trajectory: Translating Historical Momentum Into Forward Visibility
Drawing on a comprehensive historical window spanning 2020 through 2025, the research establishes a clear baseline of market resilience and expansion. Over this period, total industry revenue climbed from approximately 8,500 million USD to 11,700 million USD, reflecting sustained demand across both retrofitting initiatives and ground-up facility builds. More importantly, the forward projection window extends through 2032, anchored by a compound annual growth rate of 6.7 percent. This growth trajectory translates the market from a 12.8 billion USD base in 2026 toward an estimated 18.3 billion USD by 2032, signaling a structurally expanding addressable market rather than a cyclical upturn.
For enterprise decision-makers, this macro arc carries immediate strategic implications. First, it underscores that pallet racking procurement can no longer be treated as a commodity purchasing exercise; the scale of projected expansion means capacity planning must account for multi-year infrastructure commitments. Second, the steady CAGR indicates that demand drivers are becoming entrenched in operational realities rather than temporary inventory bulges. The report contextualizes this trajectory by mapping underlying consumption behaviors, durability requirements, and regional deployment rhythms, giving leadership teams a reliable baseline against which to calibrate budgeting, vendor negotiations, and facility expansion timelines.
Decoding the Segment Architecture: Where Capital Meets Operational Leverage
Market growth does not distribute evenly across product configurations or application environments. The research dissects the pallet rack ecosystem across dimensional axes, revealing how structural design choices and operational use cases converge to shape procurement priorities. On the product architecture side, the analysis examines how conventional selective systems continue to anchor baseline storage requirements, while high-density alternatives—driven by space-constrained urban facilities and labor optimization mandates—are reshaping engineering specifications. The report also evaluates secondary configurations that serve specialized throughput profiles, helping procurement teams align rack geometry with actual pallet flow patterns rather than defaulting to historically familiar layouts.
From an application perspective, the study maps demand intensity across warehousing and logistics hubs, retail distribution networks, manufacturing floor environments, and adjacent operational verticals. Rather than presenting static share figures, the report emphasizes how end-use characteristics influence load capacity requirements, seismic and compliance considerations, and lifecycle maintenance expectations. This application-layer analysis is particularly valuable for organizations operating multi-site networks, as it clarifies which facility types are experiencing the most aggressive storage density upgrades and which are prioritizing reconfigurability over maximum vertical utilization. By understanding how segment dynamics interact, executives can anticipate whether their procurement strategy should lean toward standardization, customization, or hybrid deployment models.
Competitive Dynamics and Strategic Positioning in a Consolidating Landscape
The pallet rack manufacturing and distribution ecosystem is characterized by a meaningful degree of concentration, with the top three players accounting for roughly 48.5 percent of market revenue and the top five firms extending that footprint to approximately 62.8 percent. This concentration does not imply a monolithic market; rather, it highlights the importance of differentiating vendor evaluation criteria beyond unit pricing. The research profiles leading operators whose product portfolios and service architectures set the competitive tempo. Steel King Industries, headquartered in Stevens Point, Wisconsin, continues to anchor its market presence through engineered offerings such as the SK2000 boltless tubular pallet rack and the SK3000 structural pallet rack system, emphasizing modular adaptability and load integrity. Ridg-U-Rak, based in North East, Pennsylvania, competes across a broader configuration spectrum, with teardrop and slotted pallet racking complemented by high-density systems including drive-in, push-back, gravity flow, and pick modules. Interlake Mecalux, operating from Chicago, Illinois, pushes integration further by pairing selective and high-density racking platforms with automated warehouse solutions. Nucor Warehouse Systems, headquartered in Monroe, Georgia, contributes patented engineering approaches through its TubeRack platform alongside structural, roll-formed, cantilever, pushback, and drive-in pallet racking systems.
Evaluating these players requires more than a feature-comparison matrix. The report examines how product engineering philosophies, regional service networks, lead-time reliability, and aftermarket support shape total cost of ownership. Because the market exhibits concentrated revenue shares at the top, enterprise buyers must treat vendor selection as a risk-mitigation exercise as much as a procurement decision. The analysis highlights how manufacturers are differentiating through certification alignment, fabrication standards, and installation ecosystems, allowing organizations to align supplier partnerships with their own operational risk tolerances and quality assurance mandates.
Market Dynamics and External Pressures Shaping Procurement Timelines
Structural growth does not occur in a vacuum. The research integrates real-time industry context to show how external pressures are altering quoting behavior, compliance requirements, and deployment urgency. On the material side, steel tariffs and import duties have introduced significant pricing unpredictability into new racking procurement. Recent market observations indicate that quotes can swing by 10 to 20 percent within a matter of weeks, forcing procurement teams to reconsider fixed-budget assumptions and just-in-time purchasing models. This volatility reinforces the report’s emphasis on scenario planning, long-lead negotiations, and inventory buffering strategies for critical structural components.
Regulatory and standards compliance has simultaneously become a more visible differentiator. Recent certification milestones, including fusion welding certifications aligned with CSA Standard W47.1 and the achievement of RMI R-Mark Certifications for manufacturer, system, and installation compliance, illustrate how quality assurance frameworks are reshaping buyer expectations. These developments matter because they influence not only installation safety and load reliability but also insurance considerations, audit readiness, and cross-jurisdiction operational continuity. Companies that require standardized, certifiable supply chains are increasingly factoring compliance credentials into vendor shortlists, and the report maps how these credentials are distributed across the competitive landscape.
Data Center Rack Market
Demand-side momentum is equally pronounced. E-commerce volume expansion and the continued growth of third-party logistics networks are intensifying requirements for heavy-duty pallet racking across the United States, with heavy-duty pallet rack demand alone reaching an estimated 182.40 million USD in 2025. This signal aligns with broader operational trends: faster order cycles, higher throughput expectations, and the need for racking systems that tolerate heavier pallet loads without compromising reconfiguration flexibility. The report synthesizes these dynamics into actionable observations on where procurement urgency is intensifying and which facility typologies are most exposed to capacity constraints.
Recent Industry Movements Signaling 2026 Deployment Priorities
Recent corporate developments provide additional texture for anticipating near-term market behavior. At MODEX 2026, Nucor Warehouse Systems announced a new facility in Monroe, Georgia, signaling expanded manufacturing or service capacity aimed at strengthening regional delivery and installation support. Around the same event window, multiple industry participants, including AR Racking and Frazier Industrial Company, showcased their latest racking technologies and system configurations in Atlanta, highlighting continued investment in product visibility and customer engagement at major trade platforms. Earlier in the year, AR Racking also participated in LogiMAT 2026, presenting galvanized system options that reflect ongoing attention to corrosion resistance and environmental durability.
These movements are not isolated publicity events. They indicate where manufacturers are placing capital, which geographies are receiving infrastructure attention, and how product features such as galvanization, high-density modularity, and automated integration are being positioned for commercial uptake. The report distills these signals into deployment-oriented insights, helping organizations understand whether nearby manufacturing or distribution expansions may improve lead times, whether trade-show announcements foreshadow broader product-line shifts, and how service network density is evolving in regions critical to their operations.
What the Report Delivers: Operational Content for Executive Decision-Making
PW Consulting’s Pallet Rack Market research is structured to move quickly from macro context to decision-ready detail. The report opens with baseline sizing and forward projections that frame the scale of the opportunity and the tempo of expected growth. From there, it transitions into segmentation analysis that clarifies how product configurations and application environments drive divergent procurement requirements. Competitive profiling goes beyond corporate summaries to examine how leading manufacturers differentiate through product engineering, certification alignment, and service ecosystem depth. The dynamics section integrates material pricing volatility, regulatory certification trends, and demand-side momentum from e-commerce and 3PL expansion into a cohesive narrative on procurement risk and timing.
Operational appendices and analytical supplements provide additional leverage for planning teams. These include technology adoption considerations, installation and maintenance lifecycle observations, and scenario-based guidance that helps organizations align rack system selection with throughput projections, space constraints, and compliance expectations. The report is designed to support multiple internal audiences simultaneously: procurement teams can use the competitive and pricing dynamics sections to structure negotiations; operations leaders can reference segmentation and application analysis to refine facility layout decisions; and strategy executives can draw on the macro trajectory and competitive concentration data to evaluate multi-year capital commitments and vendor partnership strategies.
Strategic Imperatives for 2026 and the Years Ahead
The pallet rack market is entering a period where growth is supported by durable operational shifts rather than temporary inventory accumulation. For organizations planning facility upgrades, network expansions, or large-scale racking replacement programs, the strategic question is no longer whether demand will persist, but how to structure procurement, vendor selection, and capacity planning in an environment marked by pricing volatility, concentrated supplier influence, and rising performance expectations. The research underscores several decision-making priorities: aligning rack configuration choices with actual material flow and density requirements rather than historical precedent; evaluating suppliers on total cost of ownership, certification credibility, and service network reliability; and building procurement timelines that account for material price swings and installation lead times.
Organizations that treat racking infrastructure as a long-horizon operational lever will be better positioned to convert space constraints into throughput advantages. Those that continue to approach procurement as a transactional purchasing event risk facing mounting inefficiencies as facility density requirements intensify and compliance expectations rise. The report provides the analytical scaffolding needed to move from reactive purchasing to proactive infrastructure strategy.
Access the Full Intelligence Framework
This article provides a high-level orientation to the trajectory, competitive structure, and operational dynamics shaping the pallet racking sector through 2032. The complete PW Consulting Pallet Rack Market research report extends far beyond these thematic outlines, delivering granular segmentation breakdowns, detailed competitive positioning analyses, scenario-informed procurement guidance, and region-specific deployment insights that enable precise capital planning. To access the full dataset, vendor evaluations, and strategic recommendations that support decisive 2026 action, request the complete report and integrated market intelligence package through our official research portal.
For detailed analysis of this topic, please visit the official page: Pallet Rack Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Functional Cooking Food Processors Hit $3.38B in 2025, 5.88% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Multi-Functional Cooking Food Processors Market: Strategic Insights for 2026 Decision-Making
The modern kitchen has evolved from a simple preparation space into a hub of technological integration, where efficiency, versatility, and smart functionality converge. As household consumers and commercial operators alike seek to streamline food preparation workflows, the multi-functional cooking food processor segment has emerged as a critical battleground for appliance manufacturers. This article serves as a strategic preview of the latest PW Consulting market study, designed to equip executives, product managers, and investment analysts with the analytical frameworks needed to navigate the 2026–2032 forecast period. While this overview establishes the macro trajectories and competitive undercurrents shaping the sector, the complete intelligence—including granular segmentation breakdowns, pricing elasticity models, and supplier-tier mapping—resides within the full report.
The Macro Trajectory: A Decade of Measured Expansion
The multi-functional cooking food processor market has demonstrated consistent, compounding growth over the past five years, reflecting a structural shift rather than a transient consumer trend. Historical revenue data from 2020 through 2025 reveals a steady upward curve, as the global market expanded from approximately 2,538 million USD to a projected 3,378 million USD at the close of the base year. This trajectory has been underpinned by broadening appliance adoption, rising disposable incomes in emerging economies, and an increasing consumer preference for space-efficient, multi-tasking kitchen equipment.
Looking forward, the forecast period extending through 2032 indicates sustained momentum. The market is projected to breach the 3,500 million USD threshold in 2026 and accelerate toward the 5,000 million USD mark by the end of the decade. This expansion is anchored by a forecast compound annual growth rate of 5.88 percent, a figure that signals healthy, above-inflation demand across both mature and developing regions. For corporate strategists, this CAGR is not merely a statistical projection; it represents a window of opportunity for product portfolio optimization, supply chain reconfiguration, and targeted geographic penetration. The years ahead will reward firms that can balance volume growth with margin preservation, particularly as input costs and regulatory compliance requirements continue to reshape manufacturing economics.
Market Architecture and Structural Dynamics
Understanding the architecture of this market requires moving beyond headline revenue figures and examining the underlying demand drivers. The industry is characterized by a moderate degree of concentration, with the top three participants collectively commanding roughly 48.5 percent of total industry revenue, while the top five firms extend their combined share to approximately 52.0 percent. This concentration profile suggests a market that is neither fragmented nor monopolistic, but rather one where established incumbents maintain strong brand equity while leaving ample room for niche innovators and regional specialists to capture value through differentiated features or localized distribution networks.
Product design philosophy has increasingly shifted toward all-in-one functionality. The integration of guided smart cooking, precision blending, automated chopping, steaming, and slow-cooking capabilities into single units has fundamentally altered purchasing behavior. Industry utilization data indicates that multi-functional processors achieve an average household utilization rate exceeding 65 percent, a metric that underscores the tangible value proposition of consolidated appliance ecosystems. Consumers are no longer buying isolated tools; they are investing in kitchen workstations that reduce countertop clutter, minimize accessory swaps, and streamline recipe execution. This behavioral shift has direct implications for product engineering roadmaps, warranty cost structures, and after-sales service expectations.
Capacity segmentation remains a critical dimension of consumer and commercial decision-making. The market accommodates a spectrum of volume requirements, ranging from compact units designed for everyday household chopping and mixing, to mid-tier configurations that balance batch flexibility with storage footprint, and finally to larger-capacity systems tailored for high-volume meal preparation. Each tier serves distinct use cases, and the strategic allocation of research and development resources across these capacity bands will determine which manufacturers can effectively capture cross-segment demand without diluting brand positioning.
Strategic Imperatives for 2026 Enterprise Decision-Making
As organizations plan their 2026 product launches, capacity expansions, and market-entry initiatives, several strategic imperatives emerge from the broader market context. First, the convergence of hardware engineering and software-guided culinary workflows demands cross-functional collaboration between mechanical design teams, embedded systems developers, and recipe content creators. Firms that treat smart cooking guidance as a premium differentiator rather than a marketing afterthought will likely secure stronger customer retention and higher average selling prices.
Second, pricing architecture must be calibrated against evolving consumer willingness to pay. Premium multi-functional processors from leading innovators command retail prices that sit 40 to 50 percent above basic models, a premium justified by integrated electronics, precision engineering, and extended functionality. However, this pricing gap also creates a two-tier market dynamic. Mass-market consumers continue to seek reliable, compact units that deliver core chopping, shredding, and mixing capabilities at accessible price points, while enthusiast and premium segments prioritize advanced dicing meshes, wider feed chutes, and guided programming. Successful portfolio strategies will require clear tiering, distinct feature roadmaps, and disciplined channel management to prevent cannibalization.
Multi-Functional Cooking Food Processors Market
Third, compliance and certification have transitioned from back-office obligations to competitive advantages. In the European Union, mandatory CE marking verification remains a prerequisite for retail listing, and leading manufacturers have aligned their products with EU Low Voltage and EMC directives to ensure consumer safety and electromagnetic compatibility. Simultaneously, household kitchen appliances in key export markets are increasingly evaluated against NSF International food-contact material standards. Companies that proactively embed compliance into their design cycles reduce time-to-market friction, minimize regulatory risk, and strengthen retailer confidence. For 2026 planning, compliance readiness should be treated as a strategic enabler rather than a procedural checkpoint.
Competitive Landscape: Incumbents, Innovation Pace, and Differentiators
The competitive field is anchored by a diverse set of multinational appliance manufacturers, each leveraging distinct brand heritage, engineering philosophies, and distribution strengths. Vorwerk, headquartered in Germany, continues to lead the premium segment with its Thermomix lineage, including the TM6 and the recently introduced TM7. The TM7's global rollout in early 2025 reinforced Vorwerk's emphasis on guided smart cooking, blending, chopping, steaming, and slow-cooking within a single integrated device. This holistic approach has cultivated a dedicated user base and positioned the brand as a reference point for smart culinary ecosystems.
Cuisinart, based in the United States, maintains a strong presence through customizable capacity options, including the Custom 14-Cup and Pro Classic 7-Cup configurations. Its product architecture emphasizes chopping, slicing, shredding, and mixing versatility, appealing to consumers who value modular flexibility and recognizable brand reliability. Breville, an Australian manufacturer, has pursued a performance-oriented strategy with its Sous Chef 16 and Sous Chef 9 lines, and in mid-2026 expanded its lineup with the Paradice 9 and Paradice 16 models. These updates introduced wide dicing meshes and extended feed chutes, reflecting a continued focus on precision dicing and throughput efficiency.
KitchenAid contributes to the competitive mosaic through its KFP series, which targets versatile chopping, mixing, and food preparation tasks with a strong emphasis on brand familiarity and kitchen integration. Ninja, also American, has capitalized on everyday utility with its Professional Plus and related models, emphasizing accessible chopping, shredding, and mixing performance for routine household use. Magimix, from France, caters to users seeking professional-grade chopping, slicing, and dough handling, often positioning its 14-Cup configurations as durable, high-performance workhorses. Hamilton Beach addresses the value-conscious segment with compact, easy-assembly designs such as its 12-Cup Stack & Snap line, prioritizing daily food prep convenience and straightforward operation. TAURUS Group, headquartered in Spain, extends its reach through versatile attachments that serve both household and light commercial applications, while Tefal rounds out the competitive field with processors that support chopping, mixing, and general preparation functions.
This competitive diversity creates both opportunities and risks. On one hand, the breadth of design philosophies allows consumers to align purchases with specific kitchen constraints, culinary habits, and budget parameters. On the other hand, it intensifies the need for clear value communication, consistent quality control, and differentiated after-sales support. Firms that invest in user education, recipe ecosystems, and service network reliability will be better positioned to defend market share as feature parity increases across mid-tier segments.
Regulatory, Labor, and Consumer Habit Pressures Shaping the Next Cycle
Beyond product design and competitive positioning, several macro-level pressures will influence market behavior throughout the forecast period. Regulatory compliance remains a persistent operational consideration, particularly for manufacturers exporting across multiple jurisdictions. The requirement for CE marking verification prior to retail listing in the EU, coupled with NSF International food-contact material certifications for household kitchen appliances, establishes a baseline of safety and material integrity that retailers and consumers increasingly expect. Companies that treat these standards as strategic safeguards rather than administrative hurdles will experience fewer supply chain disruptions and faster market access.
Labor cost dynamics and premium pricing structures also warrant attention. As integrated electronics, precision engineering, and smart cooking guidance become more prevalent in premium models, manufacturing complexity rises. This complexity is reflected in retail pricing, with premium units commanding a significant premium over basic alternatives. For 2026 planning, manufacturers must evaluate whether the cost of advanced feature integration can be offset by higher margin capture, reduced return rates, or expanded service revenue streams. Simultaneously, mass-market segments will continue to pressure supply chain efficiency, requiring leaner component sourcing and more scalable assembly processes.
Consumer habit data further reinforces the strategic importance of utilization and satisfaction. The observed average household utilization rate above 65 percent indicates that multi-functional processors are not merely occasional-use gadgets but central components of daily kitchen routines. This pattern suggests that product reliability, ease of cleaning, attachment durability, and software consistency will heavily influence repeat purchase behavior and word-of-mouth advocacy. Brands that prioritize post-purchase experience—through intuitive interfaces, clear maintenance guidance, and responsive warranty support—will likely see stronger lifetime value metrics.
Inside the PW Consulting Market Study: What Decision-Makers Will Find
The complete PW Consulting Multi-Functional Cooking Food Processors Market study is structured to translate macro trends into actionable intelligence. The report opens with a detailed historical reconstruction covering the 2020–2025 period, establishing baseline demand patterns, regional growth rhythms, and capacity-tier performance. From there, the analysis extends through the full 2026–2032 forecast horizon, providing forward-looking revenue trajectories, structural inflection points, and scenario-based sensitivity considerations.
The segmentation framework examines market behavior across multiple dimensions without reducing complexity to oversimplified ratios. Readers will find granular analysis of regional demand characteristics, product capacity preferences, and application-driven usage patterns, all contextualized within broader macroeconomic and consumer behavior trends. The competitive landscape section goes beyond company profiling to evaluate strategic positioning, feature differentiation, pricing architecture, and recent product launch cadence. Regulatory and compliance dynamics are mapped to specific market entry requirements, while labor cost and premium pricing pressures are analyzed in relation to margin sustainability and portfolio tiering.
Importantly, the study integrates real-world product development milestones, including recent launch activity and model updates, to illustrate how incumbents are adapting to shifting consumer expectations. These case-level observations are paired with industry habit data, utilization patterns, and certification requirements to create a multidimensional view of market evolution. The report also provides strategic recommendations for product planning, channel optimization, compliance readiness, and competitive response, enabling executives to align 2026 initiatives with measurable market opportunities.
Kitchen Food Garbage Processors Market
Conclusion: Turning Market Intelligence into 2026 Advantage
The multi-functional cooking food processor market is entering a phase where growth is no longer guaranteed by broad appliance adoption alone. Sustained expansion will depend on product differentiation, compliance agility, pricing discipline, and a deep understanding of how consumers actually use these devices in daily routines. The forecast CAGR of 5.88 percent and the projected revenue progression toward 5,039 million USD by 2032 outline a promising trajectory, but capturing share within that trajectory requires more than top-line optimism.
This article has outlined the strategic contours of the market: the concentration dynamics, the premium-versus-mass segmentation tension, the regulatory and certification expectations, and the competitive diversity that defines the sector. Yet the full depth of the analysis—segment-level revenue splits, application-specific demand drivers, regional growth nuances, and detailed competitor benchmarking—remains within the complete PW Consulting report. For executives preparing 2026 product launches, supply chain adjustments, or market-entry strategies, the full study provides the structured intelligence needed to move from awareness to action. The next step is to access the complete market intelligence and translate these macro insights into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Multi-Functional Cooking Food Processors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com