

Blogs
PW Consulting: Railroad Tie Market Hits $488.65M in 2025, Poised to Reach $655.95M by 2032 at 4.23% CAGR
By PW Consulting, 2026-09-16
Navigating the 2026 Railroad Tie Landscape: Strategic Intelligence for Infrastructure Leaders
The global railroad infrastructure sector stands at a critical inflection point as we enter 2026. Operators, suppliers, and investors alike are confronted with a complex matrix of aging assets, evolving environmental regulations, and shifting material preferences that will define capital allocation decisions for the next decade. Understanding the underlying market mechanics is no longer a passive exercise—it is a strategic imperative. Our latest comprehensive study on the Railroad Tie Market delivers the granular intelligence required to navigate this terrain with confidence.
Worldwide Composite Railroad Tie Market
This report is designed not merely as a statistical overview, but as a decision-support framework for executives who must balance operational reliability with long-term sustainability. By synthesizing historical performance data with forward-looking projections, the analysis equips stakeholders with the clarity needed to anticipate supply chain disruptions, evaluate competitive positioning, and align procurement strategies with emerging regulatory mandates. The insights presented here are drawn from rigorous primary research and validated industry datasets, ensuring that every recommendation rests on a foundation of verifiable market reality.
Macro Market Trajectory: Growth Anchored in Infrastructure Renewal
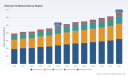
The railroad tie market has demonstrated consistent resilience over the past half-decade, driven by sustained capital expenditure on rail network maintenance and expansion. From a baseline valuation of approximately USD 392 million in 2020, the sector has advanced through a series of incremental yet meaningful increments, reaching an estimated USD 458 million by 2024 and climbing to roughly USD 489 million in 2025. This trajectory reflects a compound annual growth rate of 4.23 percent across the forecast horizon extending through 2032, positioning the market to surpass the USD 655 million threshold by the end of the projection period.
Such growth is not accidental. It is intrinsically linked to the ongoing modernization of rail infrastructure across multiple geographies, where aging wooden sleepers are gradually being replaced or supplemented by longer-lasting alternatives. The steady upward curve underscores a market that is maturing rather than experiencing volatile spikes, offering planners a predictable environment for budgetary forecasting. However, the aggregate figures only tell part of the story. Beneath the headline numbers lie nuanced shifts in material adoption, regional procurement patterns, and application-specific demand drivers that require deeper excavation to inform precise strategic moves.
Decoding Market Structure: Segment Dynamics and Material Shifts
Material Preferences in Transition
The composition of the railroad tie market reveals a clear hierarchy of material adoption, yet the edges of this hierarchy are where the most strategic opportunities reside. Traditional wooden ties continue to command a substantial share of overall revenue, reflecting their entrenched role in legacy networks and the sheer scale of ongoing replacement cycles. Concrete alternatives have carved out a significant and growing footprint, particularly in heavy-haul and high-speed corridors where durability and load-bearing capacity are non-negotiable. Steel and emerging composite solutions occupy more specialized niches, but their relevance is expanding as operators seek to mitigate decay-related maintenance costs and comply with increasingly stringent environmental standards.
What makes this material landscape particularly compelling for 2026 decision-makers is the pace at which performance expectations are evolving. Field data and industry benchmarks indicate that conventional wooden crossties typically deliver between eight and twelve years of service life in high-decay environments. By contrast, advanced composite formulations are now demonstrating operational lifespans exceeding fifty years under comparable conditions. This differential is not merely a technical footnote—it translates directly into total cost of ownership, track availability metrics, and long-term asset planning. Procurement teams that understand the cost-benefit calculus across these material categories will be better positioned to negotiate favorable terms and justify capital expenditures to internal stakeholders.
Application and Regional Nuances
Demand generation within the railroad tie ecosystem is heavily influenced by the operational profile of the end-user. Mainline passenger and freight train operations remain the dominant application driver, absorbing the bulk of annual production output. Subway and urban transit networks represent a secondary but strategically important demand channel, where space constraints, noise considerations, and rapid deployment requirements shape material selection. Beyond these core segments, specialized industrial and temporary track applications contribute incremental volume while introducing distinct specification requirements.
Geographically, the market exhibits pronounced concentration patterns that reflect historical infrastructure investment cycles, regulatory environments, and local sourcing capabilities. North America continues to represent the largest revenue contributor, underpinned by extensive Class I railroad networks and ongoing maintenance programs. Europe follows as a mature market with strong emphasis on high-speed rail modernization and environmental compliance. The Asia Pacific region, while currently smaller in absolute terms, presents dynamic growth potential tied to expanding rail corridors and urban transit development. Latin America and the Middle East/Africa markets, though more modest in scale, offer targeted opportunities for suppliers that can navigate localized logistics and specification requirements. Detailed regional and application breakdowns are mapped comprehensively within the full report to enable precise market-entry and expansion planning.
Competitive Landscape: Incumbents, Innovators, and Strategic Moves
Established Players and Supply Chain Anchors
The competitive architecture of the railroad tie market is characterized by a mix of large-scale manufacturers, specialized treatment providers, and national distributors. Firms such as Koppers Inc. and Stella-Jones Inc. have long anchored the North American supply chain, leveraging extensive sawmill sourcing networks and pressure-treatment capabilities to serve Class I, regional, and short-line railroads. Their scale and established relationships provide a baseline of supply reliability that network operators depend upon for routine replacement programs.
On the concrete and composite side, Vossloh AG has built a global reputation for prestressed concrete ties and synthetic sleepers tailored to heavy-haul and high-speed applications. L.B. Foster Company, through its concrete product subsidiary, holds a significant share of the North American concrete tie supply, reinforcing the material's growing relevance in mainline infrastructure. Gross & Janes Corporation and Nisus Corporation contribute specialized pressure-treated wood solutions, with the latter emphasizing copper naphthenate formulations designed to extend service life in demanding field conditions. These companies illustrate how incumbent players are adapting their portfolios to address both traditional performance expectations and emerging longevity requirements.
Innovation Entrants and Sustainability-Driven Investment
A distinct cohort of composite-focused manufacturers is reshaping the competitive perimeter by targeting the intersection of durability and environmental stewardship. TieTek LLC, operating under Axion International, specializes in composite ties manufactured from recycled materials, offering sustainable alternatives that reduce reliance on virgin timber and creosote-based treatments. Evertrak has similarly positioned itself in the recycled-plastic and fiberglass composite space, with its flagship models engineered for extended lifespans in high-decay zones. IntegriCo Composites Inc. expands this segment further by producing composite railroad ties from recycled feedstocks across dedicated manufacturing facilities.
Railroad Tie Market
Strategic capital flows are reinforcing this innovation axis. In early 2025, Sumitomo Corporation of Americas announced a strategic investment and formalized partnership with Evertrak to support production scalability and expand sustainable composite tie manufacturing for North American railroads. Such moves signal growing institutional confidence in composite technologies and suggest that financing environments are increasingly favorable for manufacturers that can demonstrate both performance superiority and circular-economy alignment. Additionally, broad-line suppliers such as A&K Railroad Materials, Inc. and POHL Railroad Materials Corporation LLC continue to play essential roles in distribution and sourcing, maintaining comprehensive catalogs of new and used ties that support diverse procurement needs across the network.
Market Concentration and Competitive Implications
The competitive dynamics of the railroad tie market are further contextualized by its concentration profile. With the top three firms accounting for approximately 21.5 percent of market revenue and the top five reaching roughly 24.8 percent, the sector exhibits a moderately fragmented structure. This configuration carries strategic implications: while no single entity dominates outright, established players benefit from scale advantages in treatment capacity, distribution networks, and long-term contracting leverage. Meanwhile, niche innovators can pursue differentiation through material performance, sustainability credentials, and specialized application targeting. For buyers, this balance means that supplier diversification, qualification processes, and performance benchmarking are essential to securing both cost competitiveness and supply resilience.
Regulatory and Operational Currents Shaping 2026 Strategy
Performance Standards and Environmental Compliance
Regulatory evolution is becoming a decisive force in material specification and disposal practices. In August 2025, the U.S. Federal Railroad Administration developed performance-based specifications for concrete railroad tie freeze-thaw durability, a move designed to ensure track longevity and tighten manufacturing process control. This specification framework directly influences procurement standards, quality assurance protocols, and supplier qualification criteria for concrete tie programs across North American networks.
Environmental considerations are simultaneously reshaping the end-of-life landscape for treated wood ties. The U.S. Department of Transportation's Federal Railroad Administration issued a request for information in 2023 examining potential uses and options for the disposal or repurposing of used creosote-treated railroad ties, reflecting broader concerns about hazardous substance management. At the state level, New Hampshire's Department of Environmental Services implemented requirements in September 2025 mandating proper disposal options for creosote-treated ties to prevent environmental release. These regulatory threads collectively push operators and suppliers toward more transparent disposal pathways, extended service life solutions, and alternative materials that reduce long-term environmental liability.
Raw Material Capacity and Supply Realism
On the supply side, industry capacity data provides important context for procurement planning. Railroad crossties account for the majority of North American wood tie production capacity, which exceeds 24 million units annually, while current industry output stands at just over 19 million ties. This gap between nameplate capacity and realized output highlights both latent production potential and the operational constraints—labor availability, raw material logistics, treatment facility throughput—that influence actual delivery timelines. For network planners, understanding this capacity dynamic is essential when forecasting replacement schedules, negotiating supply agreements, and modeling cost trajectories under varying operational scenarios.
Strategic Takeaways for 2026 Decision-Makers
The railroad tie market in 2026 rewards organizations that approach procurement and investment through a multi-dimensional lens. Several strategic priorities emerge from the current landscape:
- Align material selection with total cost of ownership rather than upfront unit pricing, factoring in service life differentials, maintenance frequency, and disposal compliance costs.
- Evaluate supplier portfolios for both scale reliability and innovation capability, recognizing that established treatment and manufacturing networks remain critical while composite and sustainability-focused entrants are gaining traction.
- Incorporate regulatory developments into specification frameworks early, particularly performance-based durability standards and environmental disposal mandates that will influence eligibility, reporting, and liability exposure.
- Monitor capacity utilization and regional sourcing dynamics to anticipate lead-time variability and identify opportunities for dual-sourcing or localized supply partnerships.
- Leverage strategic investment activity as a signal of where institutional capital is converging, using partnership and funding announcements to inform competitive benchmarking and technology adoption roadmaps.
These considerations are not isolated tactics; they form an integrated approach to navigating a market where material performance, regulatory pressure, and supply chain realism intersect. Organizations that embed these priorities into their planning cycles will be better equipped to manage risk, capture efficiency gains, and position their rail infrastructure assets for long-term operational excellence.
Accessing the Full Strategic Intelligence
The insights summarized here represent a high-level orientation to the railroad tie market's structure, dynamics, and strategic levers. Yet the depth required for enterprise-level decision-making extends well beyond aggregate trends. The complete report delivers detailed segment-level revenue trajectories, application-specific demand breakdowns, regional procurement analyses, and granular competitive profiling that enable precise market-entry assessments, supplier negotiations, and capital planning. It also maps the interplay between regulatory timelines and material adoption curves, offering scenario-based frameworks that help leaders stress-test procurement strategies against evolving compliance requirements and performance expectations.
For executives and strategy teams preparing for 2026 and the forecast window through 2032, the full study provides the empirical foundation necessary to convert market awareness into actionable advantage. To access the complete dataset, competitive deep-dives, and operational recommendation frameworks, we invite you to explore the full report through our official publication channel. There, you will find the detailed tables, methodology notes, and scenario analyses that transform these strategic themes into executable intelligence tailored to your organization's specific rail infrastructure objectives.
For detailed analysis of this topic, please visit the official page: Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CTBN Market Reaches $70M in 2025, Projected 4.98% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the CTBN Market: Navigating Growth, Competition, and Material Innovation in 2026
The specialty chemicals landscape is undergoing a structural recalibration. Among the most consequential segments for advanced manufacturing, the Carboxyl-Terminated Butadiene-Nitrile (CTBN) market is entering a decisive inflection point. Over the past half-decade, demand trajectories have been shaped by automotive lightweighting mandates, adhesive formulation shifts, and the expanding reliance on polymer-modified epoxy systems across industrial and aerospace applications. As we move through 2026, enterprise decision-makers face a more complex calculus: balancing cost-efficient sourcing against performance-grade material specifications, anticipating regional supply chain realignments, and positioning product pipelines ahead of tightening regulatory and sustainability expectations. Our newly released CTBN Market research report has been designed specifically to convert this complexity into actionable intelligence.
The foundational narrative of this market is one of measured but persistent expansion. Historical consumption patterns from 2020 through 2025 reveal a consistent upward arc, with aggregate revenue climbing from 55.2 million USD to 70.0 million USD. Looking forward across the 2026 to 2032 forecast horizon, the sector is projected to continue its growth path, reaching an estimated 97.86 million USD by the terminal year of the analysis window. This progression translates to a compound annual growth rate of 4.98 percent, a pace that underscores durable industrial demand rather than speculative optimism. The implied trajectory signals steady capacity utilization, incremental formulation upgrades, and sustained procurement activity across mature and emerging applications alike. For procurement leaders and R&D directors, these macro indicators are not merely background statistics; they represent the scaffolding upon which sourcing strategies, capacity planning, and product roadmaps must be constructed.
Why This CTBN Market Research Matters for 2026 Enterprise Decisions
Corporate strategy in specialty chemicals rarely succeeds on intuition alone. It requires a granular understanding of where value is created, where margins compress, and where competitive friction is intensifying. The CTBN Market study is built to address precisely these operational and strategic questions. Rather than offering a static snapshot, the report functions as a decision-support instrument calibrated for the realities of 2026 procurement cycles, technology adoption timelines, and regional market access strategies.
Several structural dynamics make this publication particularly timely:
- The CTBN value chain is no longer driven solely by volume expansion; formulation differentiation, reactive toughening performance, and compatibility with advanced resin systems increasingly determine commercial advantage.
- Supply-side geography is evolving in response to logistics costs, raw material availability, and localized regulatory frameworks, forcing manufacturers to weigh concentration risk against cost efficiency.
- Downstream applications are diverging in their technical requirements. Epoxy modification for adhesives and sealants, composite toughening for automotive and industrial assemblies, and polyurethane precursor performance all impose distinct specification thresholds that influence supplier selection.
- Pricing and contractual frameworks are being reshaped by capacity investments, feedstock variability, and the growing premium attached to consistent batch quality and technical service support.
By mapping these forces into a structured analytical framework, the report enables leaders to test assumptions before they commit capital. Whether the objective is to optimize distributor relationships, evaluate a new plant footprint, refine a product-grade strategy, or identify whitespace in a particular application vertical, the research supplies the evidentiary base needed to reduce uncertainty and accelerate approval cycles.
TCB Bonder Market
What the Report Delivers: Analytical Depth and Actionable Frameworks
To support rigorous planning, the CTBN Market report integrates multiple analytical layers that bridge high-level market sizing with granular commercial insight. The structure is designed to serve both strategic and tactical teams, from executive committees to technical sourcing managers. Core deliverables include:
Market Sizing, Historical Baselines, and Forward Estimates
The analysis begins with a comprehensive historical reconstruction covering the 2020 to 2025 period, establishing a defensible baseline against which growth assumptions can be stress-tested. From that foundation, the forecast window extends through 2032, allowing planners to model revenue trajectories, capacity utilization patterns, and demand timing across multiple planning horizons. Every projection is anchored to observable market behavior rather than abstracted trends, ensuring that downstream decisions rest on plausible, internally consistent assumptions.
Segmentation Architecture for Application and Type Dynamics
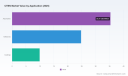
Because CTBN chemistry is deployed across distinct end-use environments, the report disaggregates demand by type and application to expose where performance requirements and consumption intensity diverge. This segmentation supports more precise portfolio decisions, including whether to prioritize low-acrylonitrile or high-acrylonitrile grades, how to align formulation capabilities with adhesive and sealant markets versus coatings and composite toughening, and where automotive-linked specifications create durable demand pull.
Regional Market Structure and Access Considerations
Geographic distribution is analyzed to clarify where demand concentration creates scale advantages, where regulatory or logistics conditions influence cost structures, and where localized supply capabilities alter competitive positioning. The regional view does not simply rank territories; it helps organizations evaluate import-export exposure, assess nearshoring and regionalization scenarios, and determine which markets warrant dedicated commercial resources versus selective distribution models.
Competitive Benchmarking and Supplier Intelligence
The report profiles the principal participants shaping the CTBN competitive landscape, with attention to product architecture, application focus, and commercial strategy. Featured companies include:
- Emerald Performance Materials , whose Hypro CTBN carboxyl-terminated butadiene-acrylonitrile copolymer is positioned as a reactive toughener in epoxy resins, adhesives, sealants, and composites for aerospace, automotive, and industrial applications.
- Tanyun Aerospace Materials (Yingkou) Technology Co. , which produces carboxy-terminated butadiene-acrylonitrile rubber as an additive for epoxy resins and thermoset polymers, emphasizing toughness, flexibility, and impact resistance in aerospace composites and structural applications.
- Shandong Qilong Chemical Co., Ltd. , a manufacturer of end-carboxyl-terminated butadiene-nitrile rubber liquid rubber and related functional elastomers for adhesives, sealants, and polymer modification.
- Shanghai Theorem Chemical Technology Co., Ltd. , which exports and supplies CTBN as a high-performance polyurethane precursor and toughener in resins for adhesives, sealants, and advanced composites.
Beyond company-level profiles, the research incorporates concentration metrics that illuminate market structure. With a CR3 of 35.2 percent and a CR5 of 52.8 percent, the landscape reflects a competitive environment in which leading suppliers command meaningful share while still leaving substantial room for specialized players and regional specialists. This structure has direct implications for pricing power, negotiation leverage, and supplier diversification strategy.
Strategic Scenario Tools for 2026 and Beyond
The report closes the gap between descriptive analysis and decision execution by providing scenario-oriented tools. These include demand sensitivity frameworks tied to application growth, type-mix shifts, and regional procurement behavior; competitive response simulations that help anticipate supplier pricing or capacity moves; and sourcing risk assessments that connect material performance requirements to supply continuity considerations. The intent is to enable organizations to model alternative pathways rather than rely on a single forecast.
Competitive Positioning in a Fragmented but Concentrating Landscape
A defining feature of the CTBN market is its blend of technical specialization and commercial contestability. The presence of well-established suppliers with distinct formulation capabilities coexists with regional manufacturers that compete on cost, responsiveness, and application-specific service. For enterprises buying or producing CTBN-based systems, this means supplier evaluation cannot be reduced to unit price alone. Performance consistency, technical assistance, regulatory documentation, and compatibility with downstream processing equipment all influence total cost of ownership.
The competitive analysis in the report is structured to help buyers and producers interpret this environment with precision. Rather than treating market share as a static hierarchy, the study examines how supplier positioning varies by application pressure, type-grade specialization, and geographic access. This approach is particularly relevant in 2026, as firms reassess supplier portfolios in response to changing procurement policies, resilience requirements, and formulation roadmaps. Organizations that understand where concentration creates negotiation constraints and where fragmentation creates alternatives will be better equipped to structure contracts, qualify second sources, and manage supply continuity without overpaying for unnecessary redundancy.
Market Dynamics, Demand Drivers, and the Regulatory-Economic Backdrop
CTBN demand is linked to broader trends in advanced materials, structural performance requirements, and formulation evolution. Automotive programs continue to pursue weight reduction and damage-tolerant composite assemblies. Adhesive and sealant formulators are seeking tougher, more flexible polymer modifications that preserve bond integrity under mechanical stress. Coatings and industrial resin systems increasingly depend on reactive tougheners to balance mechanical performance with processing practicality. These application-level drivers are not uniform; they differ by region, by product class, and by the technical maturity of the end market.
At the same time, market participants are operating within a broader industrial and regulatory environment that continues to reshape infrastructure investment, spectrum access frameworks, and connectivity requirements in adjacent sectors. While these dynamics belong to the wider advanced-technology ecosystem, they indirectly influence the operating context for specialized material supply chains by affecting logistics planning, industrial capacity deployment, and the cadence of capital investment across technology-intensive industries. Regulatory coordination in spectrum and network access, neutrality principles, and efforts to streamline cross-border policy burdens all contribute to the background conditions under which industrial procurement and infrastructure programs advance. Public and private investment in network build-out and shared-access frameworks has expanded materially, with operator spending on spectrum and small-cell deployment reaching substantial levels and annual investment in related radio access and transport infrastructure projected to grow at a double-digit pace through the near term. These conditions do not define CTBN chemistry directly, but they shape the industrial tempo, risk appetite, and capital environment in which specialty chemical suppliers and their customers operate.
For CTBN market participants, the practical implication is clear: demand planning must account for both application-specific technical drivers and the wider industrial environment in which capacity, logistics, and compliance costs evolve. The report integrates these considerations into its forward analysis so that strategic assumptions are grounded in current operating reality rather than historical convenience.
How to Use This Research for 2026 Planning Cycles
The report is constructed for multiple internal audiences and planning workflows. Procurement teams can use the segmentation and supplier profiles to refine grade selection and qualification strategies. Commercial leaders can apply the competitive structure and regional analysis to prioritize market access and partnership models. R&D and product management teams can align formulation direction with the most consequential application and type-grade dynamics. Executive planners can rely on the consolidated market sizing and scenario tools to test growth assumptions and capital allocation priorities.
To support this range of use cases, the study is organized around questions that recur in 2026 decision-making:
- Which demand pools are expanding fastest in specification intensity rather than merely in volume?
- Where do type-grade distinctions create sustainable differentiation versus commoditization risk?
- How should supplier portfolios be structured to balance performance assurance with cost competitiveness?
- Which regional markets warrant closer commercial engagement given concentration, logistics, and regulatory conditions?
- What scenario ranges should be assumed for the 2026 to 2032 period when modeling capacity, sourcing, and product strategy?
Answering these questions requires more than summary data. It requires an evidence base that connects market size, segmentation behavior, supplier positioning, and dynamic operating conditions into a single coherent framework. That is the core function of this publication.
Conclusion: Converting Market Uncertainty into Strategic Advantage
The CTBN market is not defined by abrupt disruption; it is defined by cumulative technical demand, evolving supplier capabilities, and a competitive structure that rewards precision in formulation, sourcing, and market selection. The 2026 to 2032 outlook reinforces the case for disciplined strategic planning. With aggregate revenue projected to advance from 75.38 million USD in 2026 toward nearly 98 million USD by 2032 at a CAGR of 4.98 percent, the opportunity lies not simply in participating in growth, but in shaping how a company captures it. That requires clarity on type-grade positioning, application relevance, geographic exposure, and competitive leverage.
The CTBN Market report is designed to provide that clarity. It offers the analytical depth needed to justify decisions internally, the segmentation discipline required to avoid oversimplification, and the competitive context necessary to anticipate supplier and customer behavior. The full research contains detailed segmentation performance, regional market structures, application-level breakdowns, and extended company profiles that cannot be fully reproduced here. To access the complete dataset, scenario tools, and competitive intelligence, visit the official report page and retrieve the full CTBN Market study.
CTBN Market
For organizations preparing for 2026 sourcing cycles, product commitments, and long-range capacity evaluation, the difference between informed positioning and reactive adjustment will come down to the quality of the underlying intelligence. This research is built to supply precisely that advantage.
For detailed analysis of this topic, please visit the official page: CTBN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Auto Repair Market Hits $779.3M in 2025, Projected 5.7% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Automotive Repair and Maintenance Services Market in 2026
The automotive service industry stands at a critical inflection point. As vehicle technologies evolve and consumer expectations shift, the Automotive Repair and Maintenance Services Market requires rigorous analysis to support strategic decision-making in 2026 and beyond. PW Consulting's latest market research delivers a comprehensive examination of this dynamic landscape, offering enterprise leaders the intelligence needed to navigate growth, competition, and transformation.
This market study tracks historical performance from 2020 through 2025, establishing a robust baseline against which future projections can be measured. The global market reached approximately 779.3 million USD in 2025, reflecting steady expansion driven by increasing vehicle parc, aging fleets, and rising consumer awareness of preventive maintenance. Looking ahead, the forecast period spanning 2026 to 2032 projects the market to reach 1,148.76 million USD by the terminal year, representing a compound annual growth rate of 5.7 percent. These macro-level indicators signal sustained demand, but the true strategic value lies in understanding the underlying forces shaping this trajectory.
Why This Research Matters for Enterprise Strategy
Market intelligence is only valuable when it translates into actionable insight. This report is designed for executives, investors, and operational leaders who need to make informed decisions about capacity planning, service portfolio optimization, geographic expansion, and competitive positioning. The analysis goes beyond surface-level metrics to examine the structural dynamics that will define winners and laggards in the coming years.
Several macro trends converge to create both opportunity and disruption. Vehicle ages continue to rise in many developed markets, extending the repair lifecycle and sustaining demand for mechanical and electrical services. Simultaneously, the transition toward electrification introduces new service categories while rendering certain traditional skill sets obsolete. Regulatory developments around data access and repair rights reshape the competitive balance between dealerships, independent shops, and aftermarket suppliers. Labor markets present their own challenges, with technician shortages and wage inflation pressuring margins across the value chain.
Worldwide Car Body Repair Market
This research contextualizes these forces within a rigorous analytical framework. It provides clients with the clarity needed to allocate capital efficiently, identify adjacent growth opportunities, and mitigate risks stemming from technological or regulatory shifts.
Report Scope and Practical Components
The study delivers a multi-dimensional view of the market, structured to support diverse use cases across strategy, finance, and operations. Key components include:
Automotive Repair and Maintenance Services Market
- Historical and Forecast Modeling: Detailed year-over-year projections from 2026 through 2032, enabling scenario planning and sensitivity analysis for revenue forecasting and investment appraisal.
- Segmentation Analysis: Breakdowns across service types, vehicle categories, end-user profiles, and regional dimensions to pinpoint where growth concentrates and which subsegments warrant dedicated resources.
- Competitive Landscape Mapping: Profiles of leading operators, examination of market concentration metrics, and assessment of consolidation trends that influence pricing power and market access.
- Industry Dynamics and Structural Shifts: Evaluation of workforce development, certification trends, regulatory initiatives, and supply chain factors that alter operating economics.
- Strategic Recommendations: Actionable guidance for service providers, investors, and suppliers seeking to optimize portfolios, enter new geographies, or pivot toward emerging service categories.
Each section is designed to stand alone for targeted deep dives while contributing to a cohesive narrative about where the market is headed and how stakeholders should respond.
Dynamic Market Forces Shaping 2026
No market analysis is complete without acknowledging the rapidly evolving environment in which companies operate. Several developments in early 2026 illustrate the pace of change and the need for agile strategy.
Regulatory and Policy Evolution
The U.S. House Energy and Commerce Committee passed the Motor Vehicle Modernization Act of 2026, a legislative milestone that modernizes vehicle data access and repair rights. This act carries significant implications for independent repair shops, dealerships, and aftermarket suppliers, as it redefines who can access diagnostic data and under what conditions. Around the same time, the Auto Care Association launched a member-exclusive Auto Parts Tariff Calculator and hosted a webinar addressing the 2026 policy landscape, including Right to Repair considerations and vehicle data governance. These initiatives underscore the growing importance of regulatory fluency as a competitive differentiator.
Workforce and Certification Transformation
The National Institute for Automotive Service Excellence announced a major training expansion, with total nationwide technicians holding L3 Electric Vehicle Safety certifications surpassing 25,000. This milestone reflects the industry's urgent response to electrification, as high-voltage systems demand specialized knowledge and safety protocols. Concurrently, labor economics remain a persistent concern. Automotive repair labor rates average 110 USD per hour in Mississippi and approach 175 USD per hour in California, illustrating the regional variability that complicates standardized service pricing and margin management. Companies must balance wage pressures with throughput efficiency and service mix optimization.
Corporate M&A and Strategic Positioning
Consolidation continues to reshape the competitive field. Valvoline Inc. completed its acquisition of Breeze Autocare from Greenbriar Equity Group in December 2025, integrating over 200 geographic locations into its retail infrastructure. This move expands Valvoline's service footprint and reinforces its emphasis on preventive maintenance and quick-lube convenience. In parallel, Bosch Car Service issued a global opportunity statement to experts for the development of EV repair and maintenance aspects, signaling supplier-side investment in capability building. These actions highlight how incumbents and adjacent players are repositioning to capture value in a transitioning market.
Competitive Landscape and Market Concentration
The market exhibits moderate concentration, with the top three firms accounting for approximately 35 percent of revenue and the top five reaching roughly 42 percent. This structure suggests room for both scaled operators and regional specialists to compete effectively, though scale advantages in procurement, brand recognition, and service network density remain influential.
Several established players illustrate the diversity of strategic approaches within the sector:
- Monro, Inc. operates a family of 16 brands including Mr. Tire, Mr. Lube, and Mr. Muffler, delivering complete under-car care, oil changes, brakes, shocks, struts, exhaust systems, and state inspections across 1,115 service locations in 32 states. Its multi-brand architecture enables targeted positioning across price points and service specialties.
- Jiffy Lube International provides quick-lube and full-service offerings spanning oil changes, tires, brakes, batteries, fluids, and vehicle inspections at over 2,000 service centers coast to coast. Its emphasis on speed, convenience, and consistency aligns with consumer demand for low-friction maintenance experiences.
- Valvoline Inc. manages Valvoline Instant Oil Change and allied brands, delivering preventive maintenance, oil changes, tire services, and general repairs through approximately 2,400 franchised and company-operated centers in the U.S. and Canada. Its hybrid franchise and corporate model supports rapid scaling while maintaining service quality standards.
- Mavis Tire Express Services Corp. offers tires, oil changes, brakes, alignments, and general automotive repair at over 2,100 service centers across 36 states. Its broad geographic coverage and integrated service menu position it to capture share in tire-centric and general repair demand.
These companies demonstrate that differentiation can emerge from brand architecture, service mix, operational model, or geographic density. The report analyzes how each player navigates margin pressures, regulatory shifts, and technology transitions, providing benchmarks for peers evaluating their own strategic direction.
Segmentation Considerations Without Losing Sight of the Whole
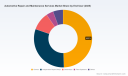
While aggregate growth figures provide orientation, the real strategic insight emerges from understanding how demand distributes across service categories, vehicle types, and end users. For instance, mechanical services and electrical services collectively represent a substantial share of market activity, reflecting both traditional repair needs and the growing complexity of vehicle electronics. Body repair services and tire services constitute additional meaningful pillars, each with distinct demand drivers tied to accident rates, seasonal usage patterns, and vehicle age profiles. Preventive maintenance remains a critical lever for customer retention and lifetime value, particularly as fleets and individual owners seek to extend vehicle lifecycles amid rising replacement costs.
On the vehicle side, passenger cars drive the largest portion of service volume, yet light and heavy commercial vehicles contribute materially to overall revenue, especially in regions with strong logistics and construction activity. Motorcycles and other niche categories add incremental but strategically relevant demand, particularly where two-wheeler penetration is high. End-user dynamics further complicate the picture: owners represent the largest customer base, while independent repair shops, dealerships, fleet operators, and other channels each exhibit unique purchasing behaviors, margin structures, and service expectations.
Rather than presenting static splits that quickly become outdated, the research emphasizes the relationships between these segments and the forces that shift their relative importance over time. This approach equips clients to anticipate which subsegments will accelerate, which will face headwinds, and where cross-segment synergies can be captured.
Regional Dynamics and Geographic Strategy
Geographic variation in demand, labor economics, regulatory environment, and competitive intensity requires tailored strategy. North America and Asia Pacific represent large and evolving market centers, each with distinct growth drivers and operational considerations. Europe maintains a mature service ecosystem shaped by stringent vehicle standards and strong independent repair traditions. Latin America and the Middle East and Africa present smaller but potentially high-growth opportunities, often contingent on infrastructure development, vehicle parc expansion, and formalization of service channels.
The report examines regional trends without reducing them to simplistic rankings. It explores how local labor markets influence service pricing, how regulatory frameworks affect aftermarket access, and how consumer preferences shape service mix. This nuanced perspective enables clients to prioritize markets based on their risk appetite, operational capabilities, and strategic objectives rather than chasing aggregate size alone.
Cost Structures and Economic Realities
Margin management sits at the heart of service business performance. Recent industry analysis indicates that average vehicle maintenance and repair cost per mile reached 9.83 cents in the most recent AAA assessment, a figure that encapsulates parts, labor, and overhead across a broad vehicle population. For service providers, this benchmark contextualizes the value proposition offered to consumers and fleet operators alike. It also highlights the sensitivity of demand to economic cycles, fuel prices, and vehicle reliability trends.
Labor remains the most variable and strategically significant cost component. Regional disparities in wage rates, combined with technician availability and certification requirements, create a complex operating environment. Companies that invest in training pathways, workflow optimization, and service scheduling technology can partially offset wage inflation while improving throughput and customer satisfaction. The research integrates these economic realities into its forward outlook, helping clients stress-test their assumptions about pricing, staffing, and capacity.
Strategic Implications for 2026 Decision-Makers
Leaders evaluating this market in 2026 should focus on several interconnected priorities:
- Service Portfolio Rebalancing: Assess exposure to traditional mechanical and body repair demand while building capability in electrical diagnostics, battery-related services, and preventive maintenance programs that align with evolving vehicle fleets.
- Workforce Strategy: Develop recruitment, training, and retention programs that address technician shortages and support certification pathways, particularly for high-voltage and EV-related competencies.
- Regulatory Readiness: Monitor data access rules, tariff implications, and Right to Repair developments that influence aftermarket participation, supplier relationships, and service delivery models.
- Scale and Network Optimization: Evaluate whether organic growth, acquisition, or partnership models best fit target geographies and customer segments, considering the concentration dynamics and competitive intensity present in each market.
- Technology and Equipment Investment: Align tooling, diagnostic systems, and service management platforms with the mix of conventional and electrified vehicles expected to enter the service pipeline over the forecast period.
These priorities are not isolated; they interact in ways that reward integrated strategy. A workforce initiative supports service quality, which strengthens customer retention, which improves the economics of preventive maintenance, which in turn reduces reliance on higher-cost reactive repairs. The report provides the analytical foundation to design and sequence such initiatives coherently.
Access the Full Intelligence
This overview highlights the strategic dimensions and market momentum captured in PW Consulting's Automotive Repair and Maintenance Services Market research. It demonstrates the breadth of analysis available, from historical baselines and multi-year forecasts to competitive profiling, regulatory context, and operational economics. Yet the full value of the study lies in its detailed breakouts, scenario frameworks, and segment-specific guidance, which are essential for precise planning and execution.
Enterprise leaders seeking to translate market awareness into decisive action are encouraged to access the complete report. The full analysis provides the granular insight required to validate assumptions, benchmark performance, and model strategic options with confidence. In a market defined by technological change, regulatory flux, and competitive realignment, comprehensive intelligence is not a luxury—it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Automotive Repair and Maintenance Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zinc Selenide Market Hits $170M in 2025, 4.8% CAGR Outlook to 2032
By PW Consulting, 2026-09-16
Zinc Selenide Market Outlook: Strategic Imperatives for Decision-Makers in 2026 and Beyond
As industrial systems increasingly demand precision infrared optics, zinc selenide (ZnSe) has moved from a niche specialty material to a strategically important component across laser processing, thermal imaging, and spectroscopic instrumentation. The transition is not merely a story of improved device performance. It reflects deeper shifts in supply chain resilience, regulatory scrutiny on critical raw materials, and the competitive dynamics of a concentrated but globally distributed manufacturer base. For executives navigating capital allocation, product roadmaps, and sourcing strategies, the market warrants a structured and evidence-based reading.
Zinc Sulfide Market
This article previews the strategic logic behind our latest Zinc Selenide Market research. It outlines the macro trajectory, the structural forces shaping demand, the competitive landscape, and the operational variables that matter most in planning windows through 2032. The objective is to give leadership teams a credible foundation for decision-making while signaling where deeper, granular intelligence can sharpen execution.
Why the ZnSe Market Matters Now
ZnSe occupies a distinct position in the infrared optics value chain because it combines broad transmissivity in the mid-wave and long-wave infrared with practical manufacturability for components that must withstand high-power laser environments. That combination has made it especially relevant for CO2 laser optics, thermal imaging platforms, and spectroscopy systems used across industrial, medical, and defense-adjacent applications. The material is not a commodity in the traditional sense; it is a performance-critical input where purity, homogeneity, and coatings directly influence end-device reliability.
At the same time, ZnSe markets are shaped by upstream constraints. Seaborne selenium supply, refinery output dynamics, and price volatility in key sourcing regions all feed into production economics for substrates and optical components. Downstream, the growth of infrared-enabled technologies across automation, sensing, and advanced manufacturing continues to expand the addressable space for ZnSe, even as buyers become more selective about quality consistency and supply continuity.
Macro Trajectory: Resilience With Steady Expansion
The market has demonstrated a measured but persistent growth path over the recent historical period, with revenue expanding from 144.0 million USD in 2020 to approximately 170.0 million USD in 2025. That progression reflects more than incremental demand. It indicates a market that is consolidating its role within higher-value optical systems while adapting to fluctuating input costs and shifting regional manufacturing footprints.
Looking forward, the forecast period suggests continued expansion, with the market moving from about 175.5 million USD in 2026 toward roughly 235.0 million USD by 2032. The implied compound annual growth rate of 4.8 percent is not explosive, but it is meaningful in a materials market where scale is often constrained by specialized production capacity, qualified supply chains, and application-specific qualification cycles. For planners, the key takeaway is that ZnSe growth is likely to be durable rather than episodic, with the most significant opportunities accruing to participants who can align product portfolios with higher-growth end-use segments and secure reliable material access.
Because this is a concentrated sector, strategic planning also requires attention to structure. The market is not fragmented in a way that makes pricing or availability purely transactional. Positionality matters, and the firms that can combine material expertise with component-level fabrication, coating capability, and customer-specific qualification support are better placed to capture value beyond base material sales.
Structural Forces Shaping 2026–2032
The forward trajectory is best understood as the interaction of several forces rather than a single demand driver.
Raw material backdrop and cost sensitivity
Selenium availability and pricing remain central to ZnSe production economics. Recent reporting points to reduced domestic output of crude selenium and selenium-bearing copper anode slimes in the United States, alongside price increases in both U.S. and European warehouse markets. Even where percentage changes appear moderate, the practical impact on producers can be outsized because ZnSe manufacturing depends on controlled reaction environments and high-purity precursors. In this context, procurement strategy, inventory design, and supplier qualification are not back-office tasks; they are strategic levers.
Regulatory and safety considerations
ZnSe is treated with caution in handling and environmental compliance. Classifications associated with acute toxicity risks through ingestion and inhalation, as well as toxicity to aquatic life with long-lasting effects, mean that responsible suppliers and end users must manage documentation, containment, and disposal practices with rigor. At the same time, certain regulatory exemptions can be relevant to registration obligations. This dual reality, genuine safety management requirements combined with specific regulatory treatment, makes compliance literacy a differentiator. Companies that can demonstrate controlled handling, transparent documentation, and consistent quality systems may gain an edge in qualified supply chains where auditability matters.
Application pull from infrared-intensive industries
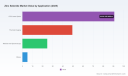
Demand is being reinforced by applications that rely on stable infrared transmission and robust mechanical performance. CO2 laser optics remain a central use case, where ZnSe components are expected to function under sustained power and thermal loading. Thermal imaging and medical or spectroscopy-related systems add further breadth, creating a demand mix that is diversified but still anchored by a few high-impact segments. Organizations planning product investments should treat this as a cue to evaluate where their own roadmaps intersect with infrared optics bottlenecks, particularly in environments where alternative materials may not match ZnSe’s balance of transmission and manufacturability.
Competitive Landscape: Concentrated Expertise, Diverse Footprint
The ZnSe market is best characterized as a specialized arena where competitive advantage stems from material know-how, production consistency, and the ability to deliver finished or semi-finished optics rather than raw crystals alone. The participating firms span multiple geographies and business models, from vertically integrated producers to specialist component suppliers and regional materials experts.
Several firms illustrate the range of strategic positions in the market. Coherent Corp. represents a vertically integrated approach, with capabilities that extend from ZnSe substrates and bulk optical materials through fabrication into lenses, windows, output couplers, beamsplitters, and other infrared optics. This integration can reduce handoff risk between material production and component realization, an important consideration for customers seeking qualified supply for demanding laser and IR systems.
Crystran Ltd. and KORTH Kristalle GmbH reflect deep specialization in polycrystalline ZnSe and high-power laser-grade components. Their emphasis on CVD-based production and controlled homogeneity for 10.6 µm applications underscores how material processing precision directly enables performance in CO2 laser contexts. In practical terms, the ability to supply thicker plates or large-area substrates with consistent optical properties is not a minor detail; it determines whether a component can meet the requirements of high-stress optical assemblies.
Edmund Optics Inc. demonstrates the importance of the distribution and customization layer. By supplying both standard and custom ZnSe components, such firms bridge the gap between material supply and end-application integration, providing optics that are immediately usable in a range of IR setups. For buyers, this model can reduce lead-time risk and simplify procurement for non-custom or lower-volume needs.
Alkor Technologies and Crystaltechno Ltd. illustrate the role of high-purity CVD production and broader II-VI material expertise in the market, including advanced coating capabilities. Meanwhile, Vital Materials Co., Ltd. and R'AIN Group highlight the expanding presence of suppliers aligned to infrared optics, semiconductor lasers, thermal imaging, and advanced detector-related uses. Together, these players point to a landscape where regional presence, material purity, and coating or fabrication support all contribute to market positioning.
Strategic implication: competitive advantage in this market is often cumulative. The strongest positions tend to emerge where suppliers combine material reliability, qualified fabrication, and the ability to support customers through specification, testing, and volume scaling. For buyers and investors alike, understanding these capabilities at the firm level is more useful than treating ZnSe as a uniform commodity.
What the Research Delivers: An Executive-Focused Toolkit
Our Zinc Selenide Market study is designed to support operational and strategic decisions rather than to offer only top-line figures. The report maps the market across type, application, and region, while embedding the macro trajectory within a framing that helps executives interpret risk, opportunity, and timing. It is structured to answer practical questions that arise in sourcing, product planning, and competitive positioning.
The analysis includes:
- A historical and forecast view of market scale and growth dynamics, anchored in a base year of 2025 and extended through the forecast period to 2032, with an emphasis on interpreting trend direction rather than treating numbers in isolation.
- Segmentation that distinguishes among major product types and application contexts, helping teams identify where ZnSe demand is most concentrated and where differentiation is most achievable.
- Regional context that situates demand and supply patterns across key markets, without reducing the story to a single geography, since the material’s supply chain and end-use base are internationally distributed.
- Competitive profiling that goes beyond corporate descriptions to explore the strategic significance of vertical integration, material purity, CVD expertise, component fabrication, and coating capability.
- Regulatory and safety context, including handling considerations and compliance-relevant details that can influence procurement choices, qualification requirements, and supply chain design.
- Upstream factors such as selenium supply and pricing dynamics, integrated into the broader interpretation of cost structure, margin sensitivity, and sourcing resilience.
In short, the report is intended to support decisions about where to participate, how to source, which applications to prioritize, and how to assess competitors not just by scale but by technical and operational credibility.
Decision Themes for 2026 Planning
For leadership teams planning around 2026, several practical themes emerge.
First, treat ZnSe as a performance enabler with supply-chain stickiness. Where end systems depend on dependable infrared transmission and component durability, switching costs and qualification cycles can be significant. That makes supplier reliability and documentation quality strategically valuable, not merely operational.
Zinc Selenide Market
Second, integrate raw-material awareness into procurement and capacity planning. Selenium market conditions, refinery output, and regional price movements can affect cost structures and availability. Even when the market expands steadily, the ability to manage input volatility can determine whether a participant captures margin or merely maintains volume.
Third, evaluate competitive differentiation through capability rather than headline presence. Vertical integration, substrate-to-component control, high-purity CVD production, and coating or customization capacity can matter more than simple product listings. In interviews, sourcing reviews, and partnership decisions, these capabilities should be assessed against the specific requirements of the target application.
Fourth, align product and investment planning with the application mix that most strongly benefits from ZnSe’s properties. CO2 laser optics, thermal imaging, and spectroscopy-related uses are not interchangeable from a materials standpoint. Mapping internal roadmaps to the segments where ZnSe provides the most credible advantage can improve capital efficiency and reduce design risk.
Fifth, incorporate compliance and handling discipline into supplier evaluation. In markets with acute toxicity and environmental sensitivity concerns, robust MSDS practices, auditable handling procedures, and clear regulatory positioning are part of the commercial value proposition. They can influence qualification speed, risk exposure, and long-term partnership stability.
What Is Held Back: Why the Full Intelligence Matters
This preview establishes the strategic frame and the macro logic, but the market’s actionable detail is more granular than any summary can responsibly convey. Segment-level revenue splits, regional breakdowns, application-level allocations, and firm-specific positioning nuances all require careful presentation because they directly affect sourcing choices, investment timing, and competitive benchmarking. Publishing those specifics here would reduce the value of the underlying analysis and, more importantly, could mislead planning if taken out of context.
The full research provides that depth in a structured, decision-ready form, allowing teams to compare opportunities across type, application, and region while interpreting them against the competitive and regulatory environment. It also connects the numbers to the operational realities that determine whether a market trajectory can actually be captured.
How to Use This Insight
The value of this market research is not limited to understanding where the ZnSe market is going. It is most useful when it helps organizations decide what to do next. Procurement teams can use it to refine supplier qualification criteria and scenario planning around input volatility. R&D and product leaders can use it to validate application priorities and material choices. Strategy and corporate development teams can use it to assess where vertical integration, partnerships, or geographic coverage would create durable advantage.
For executives who need to justify resource allocation in 2026, the strongest use of this intelligence is to connect market direction with internal capability gaps and sourcing exposure. That is where the report moves from description to delivery: it is built to support concrete actions, not just narrative awareness.
To access the complete segmentation, competitive assessment, regional interpretation, and operational context, readers are encouraged to explore the full study on the source page. There, the detail is presented in a way that allows teams to integrate it directly into planning workflows, sourcing reviews, and investment discussions.
For detailed analysis of this topic, please visit the official page: Zinc Selenide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Helicopter MRO Market to Hit $215M in 2025, Set for 2.32% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Resilience of Military Helicopter MRO: Strategic Intelligence for 2026 and Beyond
Executive Summary
The military helicopter maintenance, repair, and overhaul (MRO) sector stands at a critical inflection point as defense organizations worldwide navigate evolving operational demands, aging fleet sustainment requirements, and supply chain modernization imperatives. This comprehensive market research study provides enterprise decision-makers with actionable intelligence to navigate the complexities of this specialized defense logistics domain through 2032.
Drawing on extensive primary research, proprietary modeling, and rigorous analysis of procurement patterns across major defense ministries, this report delivers a structured examination of market trajectories, competitive positioning, and investment opportunities. The analysis spans the full MRO value chain—from engine overhaul services to component modification programs—while tracking regional demand patterns, platform-specific utilization trends, and the strategic maneuvers of established industry participants.
For strategic planners, procurement executives, and investment committees evaluating positioning in the defense aerospace sector, this research provides the analytical foundation necessary to allocate capital efficiently and anticipate shifts in government contracting priorities through the forecast period.
Market Structure and Growth Trajectory
The global military helicopter MRO market has demonstrated remarkable resilience through a period of geopolitical volatility and defense budget recalibrations. Following a steady expansion phase from 2020 through 2025, the sector reached an estimated valuation of USD 215.0 million in the base year, reflecting sustained demand for lifecycle support services across active-duty rotary-wing fleets. The ongoing forecast window projects continued expansion, with the market expected to reach approximately USD 220.57 million in 2026 before advancing toward a projected valuation of USD 252.76 million by the terminal forecast year.
This growth trajectory, characterized by a compound annual growth rate reflecting steady mid-single-digit momentum, underscores the structural reliance of modern defense organizations on specialized MRO ecosystems. Several macro factors contribute to this persistent demand profile: the gradual aging of legacy helicopter platforms necessitating more intensive maintenance interventions, increasing operational tempo requirements across multiple theaters of engagement, and procurement strategies that increasingly favor sustained lifecycle support contracts over one-time acquisition events.
The market architecture reveals distinct service category demands, with engine MRO representing the largest share of expenditure, followed by component and modification services, airframe maintenance, and field-level support operations. Platform-level analysis indicates that utility helicopters drive the predominant share of MRO activity, with attack, transport, reconnaissance, and maritime platforms comprising the balance. Regional demand distribution highlights significant concentration in established defense industrial bases, while emerging procurement patterns in Asia Pacific and select emerging markets suggest gradual diversification of the customer base.
Market concentration metrics indicate a fragmented but evolving competitive environment, with the top three participants capturing approximately 24.6 percent of total market revenue and the top five firms extending this footprint to roughly 26.2 percent. This concentration profile suggests that while established incumbents maintain meaningful market presence, substantial opportunity remains for specialized providers and new entrants capable of delivering differentiated service capabilities.
Comprehensive Report Coverage and Methodology
This research publication delivers a multi-dimensional analysis designed to support strategic planning across diverse organizational functions. The study architecture encompasses several integrated components that collectively provide a comprehensive view of market dynamics, competitive forces, and forward-looking indicators relevant to enterprise decision-making.
Market Sizing and Forecasting Framework: Detailed quantitative modeling covers historical performance from 2020 through the 2025 base year, with extended projections spanning the 2026 through 2032 forecast horizon. The forecasting methodology incorporates multiple demand drivers including fleet size trajectories, operational utilization rates, maintenance interval requirements, and government budget allocations across major defense markets. Sensitivity analysis scenarios examine potential variations under different geopolitical and budgetary conditions.
Military Helicopter MRO Market
Segmentation Analytics: The research decomposes market activity across three primary analytical dimensions. Service-type analysis differentiates expenditure patterns among engine overhaul, component modification, airframe maintenance, and field support categories. Platform-level examination tracks demand distribution across utility, attack, transport, reconnaissance, and maritime helicopter classifications. Geographic assessment evaluates regional concentration patterns and identifies emerging demand centers with actionable growth potential.
Competitive Landscape Assessment: Comprehensive profiles of leading market participants provide detailed examination of corporate capabilities, service portfolios, facility infrastructure, and strategic positioning. The analysis incorporates recent acquisition activity, contract awards, facility expansions, and partnership developments that signal competitive trajectory. Market share evolution tracking enables readers to assess momentum shifts among incumbent providers and evaluate the positioning of emerging competitors.
Regulatory and Procurement Intelligence: The study incorporates analysis of defense procurement patterns, contract vehicle structures, and regulatory developments that shape MRO service delivery frameworks. Examination of Department of Defense contracting trends, defense logistics agency procurement programs, and allied nation acquisition practices provides context for understanding evolving customer requirements and contract opportunities.
Strategic Implications and Scenario Analysis: Forward-looking sections translate quantitative findings into actionable strategic recommendations, addressing questions of capacity investment, service portfolio optimization, geographic expansion priorities, and partnership strategy. Scenario modeling examines potential market evolution paths under varying assumptions regarding defense budget trajectories, technological modernization programs, and supply chain restructuring initiatives.
Competitive Landscape Dynamics
The military helicopter MRO competitive environment features a cohort of established providers with deep institutional relationships, specialized technical capabilities, and long-standing government contracting credentials. These participants operate across multiple service categories and platform types, leveraging diverse operational footprints to address varying customer requirements.
AAR Corp maintains an active presence as a comprehensive provider of airframe and component MRO services, parts supply, and government sustainment programs specifically targeting military rotary-wing fleets including UH-60 Black Hawk, CH-47 Chinook, and AH-64 Apache platforms. The organization's integrated service model positions it to capture demand across multiple MRO categories while benefiting from established defense customer relationships.
TIGHITCO Inc operates as a specialized aerospace MRO provider with particular expertise in overhaul support services for exhaust ducts, spindles, swashplates, and structural components on UH-60 Black Hawk and CH-47 Chinook military helicopters. The company's focused technical specialization enables it to address complex component-level maintenance requirements that demand particular engineering expertise and precision manufacturing capabilities.
SOC USA functions as a provider of tactical vehicle and aircraft MRO services, delivering organizational, intermediate, and depot-level maintenance for U.S. Army rotary-wing platforms such as UH-60 Black Hawk, CH-47 Chinook, and AH-64 Apache. The organization's multi-echelon maintenance capabilities support requirements across different operational readiness levels and maintenance tier structures.
Amentum provides rotary-wing helicopter maintenance, sustainment, and life-cycle services for U.S. Army and Air Force platforms including UH-60 Black Hawk, CH-47 Chinook, and Apache fleets. The company's comprehensive life-cycle service approach enables engagement across the full spectrum of maintenance requirements, from routine operational support through major overhaul and upgrade programs.
Lockheed Martin , through its Sikorsky division, maintains an active role as a provider of MRO and sustainment services for military helicopters, including the UH-60 Black Hawk fleet with modernization, engineering, and support contracts. The organization's platform manufacturer perspective provides unique insight into design-intent maintenance requirements and facilitates integration of modernization initiatives with ongoing support programs.
Recent activity across this competitive cohort illustrates the dynamic nature of the MRO contracting environment. In December 2025, TIGHITCO secured a five-year indefinite-delivery/indefinite-quantity contract from the U.S. Army for left- and right-hand exhaust duct overhaul and repair on UH-60 Black Hawk helicopters, reinforcing the company's specialized component maintenance positioning. Earlier that year, in August 2025, Lockheed Martin's Sikorsky division received a 43 million dollar U.S. Army contract for Black Hawk UH-60 modernization engineering encompassing airframe enhancements and digital backbone development for unmanned aerial system integration.
Facility investment activity further signals competitive momentum, with TIGHITCO expanding MRO capabilities in May 2025 through new service center enhancements targeting complex aerospace components on military helicopters. In April 2025, SOC USA secured a 3.5 million dollar contract to supply custom maintenance platforms for UH-60 Black Hawk helicopters to the U.S. Army National Guard, demonstrating ongoing demand for specialized support equipment and tooling solutions.
Industry Dynamics and Procurement Environment
The military helicopter MRO sector operates within a dynamic procurement environment shaped by evolving defense priorities, supply chain considerations, and regulatory frameworks. Recent developments across contracting activity, logistics infrastructure, and platform sustainment programs illustrate the multifaceted forces influencing market direction.
Defense contracting patterns demonstrate sustained government commitment to fleet sustainment infrastructure. In December 2025, the U.S. Army awarded a 19.47 million dollar contract for UH-60 Black Hawk exhaust duct overhaul services, reflecting continued investment in component-level maintenance programs for high-utilization platforms. The Defense Logistics Agency moved forward with a substantial 270 million dollar 10-year Industrial Product-Support Vendor Gen II contract awarded to Boeing Distribution Services Defense in February 2026, covering over 9,300 repair parts supporting Army helicopters—an initiative that underscores the strategic importance of supply chain resilience and parts availability for sustained operational readiness.
Platform-level sustainment programs continue to attract significant resource allocation. The U.S. Department of Defense announced a contract modification valued at approximately 115 million dollars in June 2024 covering MH-47G Chinook rotary-wing aircraft production and sustainment, highlighting the intersection of procurement and lifecycle support activities that characterize modern defense rotary-wing programs.
These procurement developments reflect broader trends toward long-term contracting relationships, emphasis on supply chain reliability, and increasing integration of sustainment planning with platform acquisition and modernization initiatives. Organizations operating in the MRO space must navigate evolving contract vehicle structures, performance metric expectations, and compliance requirements that shape competitive participation in government procurement programs.
Strategic Considerations for 2026 Decision-Making
Enterprise leaders evaluating engagement in the military helicopter MRO sector face a complex set of strategic considerations that demand careful analysis of market structure, competitive dynamics, and forward-looking risk factors. The insights provided through this research publication support structured evaluation across several planning dimensions.
Capacity and Investment Alignment: Understanding the trajectory of demand across service categories, platforms, and geographic regions enables organizations to align capital allocation decisions with projected market opportunities. The concentration patterns observed in the current market environment suggest that targeted investment in specialized capabilities may offer competitive differentiation opportunities, while broader service portfolio strategies require careful assessment of capital requirements and execution complexity.
Contract Strategy and Relationship Management: The predominance of long-term government contracting mechanisms in the MRO sector places premium value on established relationships, proven performance records, and capability certifications. Organizations must develop strategies that balance pursuit of near-term contract opportunities with investment in capabilities that position them for sustained engagement as fleet compositions and maintenance requirements evolve.
Supply Chain and Logistics Positioning: Recent large-scale logistics contracts and emphasis on parts availability highlight the strategic significance of supply chain capabilities within the MRO value chain. Providers that can demonstrate robust logistics infrastructure, reliable parts sourcing, and efficient inventory management offer differentiated value propositions in an environment where operational readiness depends critically on maintenance component availability.
Civil Helicopter MRO Market
Technological Integration and Modernization: Platform modernization programs increasingly incorporate digital infrastructure, advanced materials, and enhanced avionics that affect maintenance requirements and service delivery models. MRO providers must assess the implications of these technological shifts for technical capability requirements, workforce development, and service portfolio adaptation.
Geopolitical and Budgetary Risk Assessment: Defense budget trajectories, alliance commitments, and regional security considerations influence demand patterns across markets and platforms. Scenario-based analysis enables organizations to evaluate potential impacts of varying geopolitical conditions on MRO market evolution and to develop contingency strategies that maintain organizational resilience across different operating environments.
Conclusion: The Value of Authoritative Market Intelligence
The military helicopter MRO market represents a specialized but strategically significant segment of the broader defense aerospace industry, characterized by sustained demand fundamentals, complex technical requirements, and evolving competitive dynamics. Organizations seeking to navigate this environment effectively require access to rigorous, forward-looking market intelligence that transcends surface-level observation and provides actionable strategic guidance.
This comprehensive research publication delivers the analytical depth and structural clarity necessary to support informed decision-making across multiple organizational functions. By integrating quantitative market analysis, competitive landscape assessment, regulatory context, and scenario-based strategic evaluation, the study provides enterprise leaders with a coherent framework for evaluating opportunities, anticipating challenges, and positioning for sustained success through the forecast horizon.
Access the complete Military Helicopter MRO Market research report for detailed segmentation data, full competitive profiling, regional market breakdowns, and comprehensive forecasting models that support strategic planning initiatives through 2032.
For detailed analysis of this topic, please visit the official page: Military Helicopter MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grain Bins Market Hits $172.5M in 2025, Projected 5.9% CAGR Through 2032
By PW Consulting, 2026-09-16
Grain Bins Market Outlook 2026: Strategic Intelligence for Agricultural Infrastructure Decision-Makers
Executive Overview
The global grain storage infrastructure sector is entering a decisive phase of maturity and innovation. As agricultural supply chains adapt to volatile commodity cycles, climate variability, and tightening food security requirements, grain bins remain the foundational asset for harvest preservation, inventory management, and post-harvest value retention. PW Consulting’s latest Grain Bins Market research delivers a rigorously constructed intelligence framework designed specifically for executives, investors, and operational leaders navigating strategic decisions in 2026 and beyond.
This analysis synthesizes historical performance, forward-looking demand signals, competitive positioning, and policy-driven funding mechanisms into a single decision-ready architecture. Rather than presenting static snapshots, the report maps the structural forces that will dictate procurement timing, capital allocation, and product roadmap prioritization across the next seven-year horizon.
Historical Trajectory and the Path to 2032
Over the 2020 to 2025 baseline period, the grain bins market demonstrated consistent expansion, scaling from approximately 120.5 million USD to 172.5 million USD. This growth trajectory reflects a combination of on-farm capacity upgrades, commercial storage expansion, and incremental modernization of aging inventory systems. The momentum has not plateaued. Projections extending through 2032 indicate the market will advance toward the 254 million USD threshold, underpinned by a compound annual growth rate of roughly 5.9%.
For corporate planners, this macro trajectory carries a clear implication: capacity demand is no longer cyclical in the traditional sense. It is being reshaped by structural substitutions, storage optimization mandates, and the gradual integration of digital monitoring into core bin operations. The report isolates the inflection factors that separate temporary procurement spikes from durable demand shifts, enabling leadership teams to time investments with greater precision.
What the Research Delivers: An Operational Blueprint
The Grain Bins Market study is structured as a working document for strategy formulation rather than a passive reference volume. It translates raw market mechanics into actionable intelligence across several interconnected layers:
Grain Combine Harvester Market
Every section is designed to answer a specific executive question. Which material and configuration choices dominate end-user preference? How do geographic procurement patterns reflect regional agricultural economics? Where do financing programs lower barrier-to-entry for new storage installation? The report addresses these questions through layered segmentation analysis, historical-to-forecast continuity checks, and competitive benchmarking that can be directly embedded into pricing, sourcing, and market-entry models.
Technology, Safety, and the Automation Inflection Point
The grain storage industry is undergoing a quiet but consequential operational transformation. Physical storage capacity remains essential, but the value proposition is increasingly defined by how bins are monitored, maintained, and integrated with broader handling systems. Recent industry activity highlights this shift. In late 2025, Ag Growth International launched a farmer-facing digital platform designed to provide real-time monitoring of grain bin conditions, signaling a market-wide move toward continuous visibility rather than periodic manual inspection. Alongside that software launch, the company introduced diesel-driven handling tools engineered for the 2026 season, reinforcing the broader trend toward field-ready, mechanized grain movement equipment.
Material and fabrication innovation is advancing in parallel. Demonstration activity surrounding advanced lamination and structural configurations has begun appearing at major agricultural equipment exchanges, indicating that durability, moisture resistance, and installation efficiency are becoming key differentiators in a crowded supplier landscape. These developments matter because they directly affect total cost of ownership, downtime risk, and long-term storage integrity.
Safety-driven policy support is also reshaping procurement economics. Regulatory and grant mechanisms at the state level have begun reimbursing a substantial share of eligible safety equipment costs for on-farm storage operations. Complementary federal financing programs have lowered upfront capital burdens for storage construction by offering favorable loan structures. Together, these mechanisms reduce friction in the adoption curve and create a more predictable demand environment for manufacturers, distributors, and capital partners. The report examines how these instruments interact with regional purchasing behavior and what they signal for near-term installation velocity.
Competitive Landscape: Orchestration, Specialization, and Regional Density
The grain bins market is characterized by a dense supplier base with pronounced specialization and meaningful concentration among leading participants. Market structure analysis indicates that the top three firms command a substantial share of total revenue, while the top five extend that footprint even further. This concentration pattern suggests that scale advantages in production, distribution, and after-sales service continue to influence customer selection, particularly for larger commercial storage projects and multi-site farm operations.
Several established manufacturers anchor the competitive field. Ag Growth International operates across multiple storage and handling product families under well-recognized brand lines, serving both farm and commercial storage requirements. Sukup Manufacturing Co. remains a prominent family-owned player with deep vertical integration across bins, drying, and handling equipment. CTB, Inc. and its grain-focused business unit provide on-farm and holding bin solutions alongside material handling systems. Superior Grain Equipment, Sioux Steel Company, and Grain Systems, Inc. each contribute distinct structural configurations and accessory ecosystems, while Behlen Manufacturing Company and Westman Manufacturing broaden the field with specialized bin and system offerings. Additional participants such as SCAFCO Grain Systems, Brock Grain Systems, and Chief Industries, Inc. reinforce the breadth of the competitive set and ensure continued pressure on design, service response, and regional availability.
Grain Bins Market
The strategic takeaway is not simply that competition is intense. It is that competition is multidimensional. Suppliers compete on structural design, handling integration, installation speed, digital compatibility, financing alignment, and safety compliance. The report evaluates how these dimensions shape share movement, customer retention, and pricing elasticity across different buyer profiles.
Regional and Application Dynamics Without the Noise
Grain storage demand does not distribute uniformly across markets or use cases. Regional procurement patterns reflect differences in farm structure, harvest logistics, storage financing access, and commercial throughput requirements. Application-side dynamics further differentiate the market, with on-farm storage representing the dominant volume driver and off-farm storage forming a strategically important complement tied to commercial aggregation, drying, and distribution networks.
The research avoids superficial regional or application breakdowns in favor of a more decision-useful approach. It examines how geographic demand nodes evolve under varying commodity price environments, how local safety and financing programs alter project economics, and where infrastructure gaps create either risk or opportunity. This enables readers to anticipate not just where volume is concentrated, but where demand is likely to strengthen, stall, or shift between installation types.
Strategic Implications for 2026 Decision-Makers
As organizations finalize capital plans, procurement cycles, and market positioning for 2026, several implications emerge from the market structure and forward outlook:
The research is built to help executives convert these implications into concrete strategies. Whether the priority is supplier diversification, geographic expansion, product line extension, or financing-aligned go-to-market design, the underlying intelligence is structured to support scenario planning and risk-adjusted investment decisions.
Conclusion: Reading the Market Before the Next Cycle Settles
Grain bins may appear to be a mature storage category, but the surrounding ecosystem is anything but static. Financing instruments, safety mandates, digital monitoring tools, material advancements, and concentrated supplier competition are recombining to create a market with sharper discontinuities and clearer strategic levers than many decision-makers currently appreciate. PW Consulting’s Grain Bins Market research is designed to give leadership teams the clarity required to act early, allocate wisely, and outmaneuver competitors who rely on outdated demand assumptions.
The full study provides detailed segmentation paths, competitive profiling, financing-program impact analysis, and forecast scaffolding that cannot be fully unpacked in a summary view. For executives who need the complete operational intelligence behind these trends, the complete report is available for direct access through our research portal.
For detailed analysis of this topic, please visit the official page: Grain Bins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Football Helmet Market Hits $209M in 2025, 5.2% CAGR to 2032
By PW Consulting, 2026-09-16
Intercepting Impact: Why the 2026 Football Helmet Market Research Report Is a Strategic Imperative for Industry Leadership
The athletic protection industry stands at a critical inflection point. Where safety once lived in the background of product design, it now sits at the center of regulatory mandates, consumer expectations, and competitive differentiation. PW Consulting’s newly published Football Helmet Market research report transforms that inflection point into a navigable strategic roadmap for executives, product leaders, and investors preparing their 2026 decision calendars. What follows is not a superficial market overview. It is a structured intelligence briefing designed to reveal the contours of opportunity, the pressure points of compliance, and the competitive rhythms that will define the sector through the end of the decade.
The Market Trajectory as a Strategic Compass
From Recovery to Sustained Expansion
The market has moved through a defined cycle over the past half-decade. After navigating a modest contraction in 2023, the sector rebounded with renewed momentum, reflecting a structural shift rather than a temporary correction. Macro-level tracking places the overall market at approximately 209.0 Million USD in 2025, with projected expansion to 224.61 Million USD in 2026. The forecast window through 2032 maps a continued upward arc, anchored by a 5.2 percent compound annual growth rate. Those headline figures are only the entry point. The real value lies in understanding the velocity, the inflection triggers, and the distribution of growth across product lifecycles, channel strategies, and regulatory timelines.
Why the 2026–2032 Window Demands Precision Planning
Growth on paper does not translate automatically into share, margin, or shelf placement. The forecast period coincides with a regulatory and operational environment that will reward organizations capable of aligning product roadmaps, aftermarket services, and channel partnerships to shifting standards. The report is built to support that alignment. It maps the trajectory from the base year of 2025 through a twelve-year horizon, giving decision-makers a framework to pressure-test capacity investments, inventory planning, and go-to-market sequencing before the next wave of compliance deadlines and product launches reshapes the competitive field.
Decoding Competitive Dynamics and Brand Architecture
A Field Shaped by Technology, Licensing, and Performance Validation
The competitive landscape is concentrated and performance-driven. Industry calculations point to a CR3 of 48.5 percent and a CR5 of 59.2 percent, signaling a market where a small cohort of established players command the bulk of revenue while leaving meaningful room for specialized challengers that win on testing credibility and design agility. The research unpacks that architecture in detail, tracing how brand equity, technology portfolios, and institutional relationships interact to create durable advantages or expose strategic vulnerabilities.
Strategic Profiles Across the Leadership Tier
Riddell anchors its position through a dual engine of professional league alignment and product breadth. Headquartered in Des Plaines, Illinois, the company continues to center its strategy on the Axiom and SpeedFlex lines for varsity and youth football, reinforced by its standing as an NFL licensee and market leader in professional play. That licensing foundation provides a durable visibility channel, while recent 2026 product activity signals ongoing investment in younger athlete segments and energy-management engineering. Schutt Sports, based in Plainfield, Indiana, competes with a focus on impact protection and fit systems across the F7 LTD, F7 UR1, and Vengeance series, positioning fit and protective performance as the core commercial message for varsity programs. LIGHT Helmets, operating from Carlsbad, California, has carved a distinct lane with ultra-lightweight Gladiator ATK and Apache varsity helmets that have earned top-tier recognition in Virginia Tech helmet testing, appealing to programs that prioritize weight reduction and independently validated performance metrics. VICIS, with U.S.-based operations, maintains a technology-first identity through the ZERO2 Trench and ZERO2 varsity lines, consistently ranked at the highest level in independent impact performance testing, a positioning that resonates with institutions seeking performance differentiation in a technology-sensitive purchasing environment. Xenith’s Orbit Pro and Shadow XR varsity helmets remain part of the broader competitive conversation as acquired assets have been integrated into the Riddell portfolio, reshaping how legacy technology, brand assets, and channel access are managed within a consolidated structure.
Helmets Market
Recent Moves That Alter the Competitive Rhythm
The competitive tempo is not static. In March 2026, Riddell introduced the ND6 youth football helmet line designed to meet the new NOCSAE ND006 youth standard, alongside the SF Echo varsity model featuring energy management liners and inflatable face frames. Developments of this kind are more than product announcements. They are signals about compliance readiness, segment prioritization, and engineering priorities that competitors must interpret and respond to. The report places such launches within a wider strategic context, helping leaders determine whether to match, differentiate, or reposition around evolving performance and regulatory expectations.
Regulatory and Lifecycle Forces That Reshape Purchasing Behavior
Youth Standards and the Compliance Horizon
Regulatory architecture is becoming a direct driver of product planning. NOCSAE finalized the first-ever performance standard for youth football helmets, ND006, on February 7, 2025, with an effective date of September 1, 2027. That timeline creates a defined window for design adjustments, validation cycles, and supply chain readiness. Rather than treating compliance as an endpoint, the report treats it as a planning variable, helping organizations understand how standards influence launch sequencing, inventory positioning, and the pace at which existing lines may require revision.
Football Helmet Market
Recertification, Warranty Validity, and the Economics of Aftermarket Service
The aftermarket dimension is no longer a secondary concern. As of October 2025, NAERA recommends that every football helmet be reconditioned and recertified annually for warranty validity, with manufacturer intervals enforced. At the same time, NOCSAE and manufacturer guidelines limit football helmet recertification to a maximum of 10 years from the manufacture date, and NAERA members no longer accept for reconditioning any football helmets more than 10 years old. These parameters reshape the economics of product ownership, influence repurchasing cycles, and elevate the strategic importance of service networks, parts availability, and lifecycle messaging. The report examines how these rules alter buyer behavior across programs, boost demand for validated reconditioning pathways, and create opportunities for organizations that can integrate protection, service, and compliance into a single customer proposition.
Licensing and Brand Visibility as Strategic Multipliers
Not all competitive advantage comes from product engineering. Riddell extended its NFL exclusive license and promotional rights for collectible helmets through the 2030 season, a move that sustains brand visibility, strengthens fan-facing engagement, and reinforces the commercial halo around core protection lines. Such licensing arrangements influence category perception, demand patterns, and the ability to command attention in crowded purchasing environments. The research evaluates how these rights interact with product strategy and channel positioning, so leaders can assess whether visibility, endorsement, and collectible extensions support or distract from core commercial objectives.
What the Report Delivers: Operative Intelligence for 2026 Planning
This publication is engineered for action. It synthesizes market sizing, growth trajectory, segmentation logic, competitive profiles, and regulatory context into a single decision-support framework. Rather than leaving readers with isolated statistics, the report connects numbers to operating choices: how to sequence product introductions, where to concentrate inventory and service capacity, how to interpret testing credibility as a commercial asset, and how to anticipate the timing of standards-driven purchasing shifts. The content is structured to support product strategy, sales planning, supply chain configuration, and investment prioritization with the level of specificity required for boardroom and planning-table use.
The segmentation analysis is designed to reveal where demand is accumulating and how different product architectures and program levels interact with purchasing behavior. By examining regional and application patterns in relation to product type and lifecycle requirements, the report helps leaders understand which environments are expanding, which are stabilizing, and where service, safety validation, and compliance readiness are becoming the dominant purchasing criteria. That perspective is essential for organizations that need more than growth rates; they need to know how demand is composed and how that composition will influence channel strategy and product mix over the forecast horizon.
Why the Full Report Is the Next Strategic Step
The headline trajectory tells us the category is expanding. The competitive and regulatory context tells us that expansion is conditional on timing, validation, compliance preparation, and service capability. What remains is the granular intelligence required to convert that knowledge into execution. The complete PW Consulting Football Helmet Market research report delivers that intelligence in a structured, decision-ready form. It provides the segment-level detail, competitive depth, and regulatory timeline mapping that executives need to calibrate product roadmaps, service networks, and commercial positioning for 2026 and the years that follow.
Organizations that enter this planning cycle with full visibility will be better positioned to align engineering investments with emerging standards, to anticipate the purchasing implications of recertification and warranty rules, and to interpret competitor launches as strategic signals rather than isolated events. Those that rely on partial information risk optimizing for yesterday’s market structure. The complete report is the instrument for navigating the next phase with precision, confidence, and strategic clarity.
For detailed analysis of this topic, please visit the official page: Football Helmet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DRM Market Hits $1,680M in 2025, Poised for 7.5% CAGR Growth to 2032
By PW Consulting, 2026-09-16
The Strategic Imperative of Digital Rights Management: Navigating the 2026 Market Shift
Executive Overview: Why DRM Intelligence Matters Now
Digital Rights Management has evolved from a niche technical safeguard into a foundational pillar of digital commerce. As content consumption models fragment across streaming, interactive entertainment, and enterprise digital workflows, organizations face mounting pressure to protect intellectual property while maintaining seamless user experiences. Our latest market research report provides a comprehensive, data-driven examination of the DRM landscape, designed specifically to equip executive leadership and strategic planning teams with the intelligence required to make confident, forward-looking decisions in 2026 and beyond.
The global DRM market has demonstrated consistent, compounding growth over the past half-decade, expanding from approximately 1,200 million USD in 2020 to 1,680 million USD in 2025. This upward trajectory reflects broader structural shifts in how media, software, and published content are monetized, distributed, and secured. Looking ahead, the market is projected to maintain a robust compound annual growth rate of 7.5 percent through the forecast period ending in 2032, reaching an estimated 2,740 million USD. These figures are not merely historical retrospectives; they serve as leading indicators of capital allocation priorities, technology investment cycles, and competitive positioning strategies that will define the next wave of digital business models.
Macro Market Trajectory and Forecast Architecture
Understanding the scale and velocity of market expansion requires more than surface-level sizing. Our research framework tracks historical performance across a six-year baseline, establishing a reliable foundation for predictive modeling. The data reveals a steady acceleration in revenue generation, driven by the proliferation of high-value digital assets and the corresponding demand for enterprise-grade protection mechanisms. Each successive year has shown measurable gains, with the transition from 2024 to 2025 marking a notable inflection point as organizations scaled their security infrastructure to match increasingly sophisticated distribution networks.
The forward-looking forecast window spans seven years, offering a structured view of how market participants can anticipate capacity requirements, partnership opportunities, and technology lifecycle transitions. Rather than presenting isolated snapshots, the report constructs a continuous growth narrative that aligns with product roadmaps, regulatory timelines, and shifting consumer behavior patterns. Decision-makers will find this temporal architecture particularly valuable when evaluating long-term technology adoption cycles, assessing infrastructure readiness, and mapping resource allocation against projected demand curves.
Key Structural Components of the Market
The DRM ecosystem is inherently multidimensional, with value creation distributed across distinct solution categories, application verticals, and geographic corridors. Our analysis dissects these layers to reveal where investment flows concentrate and how operational priorities diverge across sectors.
- Software-based protection platforms continue to represent the largest share of market activity, reflecting the industry's preference for scalable, adaptable licensing frameworks that integrate directly into digital delivery pipelines.
- Hardware-embedded security solutions maintain a substantial footprint, particularly in environments where physical media distribution, broadcast infrastructure, or specialized playback devices require dedicated encryption and access control mechanisms.
- Professional services and implementation support form a critical enabler layer, addressing the complexity of integrating rights management into legacy workflows, compliance frameworks, and multi-vendor technology stacks.
Across application landscapes, the music industry continues to drive significant adoption, followed closely by film and television production, gaming ecosystems, and digital publishing. Each vertical presents unique protection requirements, licensing models, and consumer engagement patterns that demand tailored strategic approaches. Geographic distribution further illustrates the global nature of digital content markets, with mature economies maintaining established protection infrastructures while emerging regions accelerate their adoption curves to support expanding digital distribution networks.
Competitive Landscape and Strategic Positioning
The DRM vendor ecosystem is characterized by a layered competitive structure where market concentration remains moderately high, reflecting the technical complexity, compliance requirements, and long-term partnership dynamics inherent to content security. The top three players collectively account for a substantial share of industry activity, while the top five firms extend their influence across multiple solution categories and geographic markets. This concentration pattern signals both the barriers to entry in enterprise-grade protection and the strategic importance of vendor selection for organizations building or expanding their digital distribution capabilities.
Leading Market Participants and Their Value Propositions
Verimatrix delivers multi-DRM and embedded protection architectures specifically engineered for OTT platforms and media distribution networks. Their approach emphasizes layered security models that combine encryption, forensic watermarking, and anti-piracy monitoring to protect premium video streams across diverse playback environments.
Nagra, operating through the Kudelski Group and Conax divisions, provides multi-DRM service frameworks and the Contego platform, which supports secure streaming content protection across major DRM standards. With deployment across more than fifty service providers globally, Nagra's infrastructure highlights the industry's shift toward interoperable, provider-agnostic security ecosystems that can adapt to evolving licensing agreements and device compatibility requirements.
Adobe anchors its DRM strategy in content protection for video workflows and enterprise digital asset management. Through Primetime DRM and Experience Manager Assets, the company enables rights enforcement, compliance tracking, and controlled access within complex digital production pipelines, addressing the needs of organizations that must balance creative distribution with strict licensing adherence.
Microsoft integrates DRM capabilities across both consumer media protection and enterprise information security. PlayReady DRM supports premium video licensing and playback control, while Azure Rights Management extends protection to documents, communications, and internal data flows, illustrating how digital rights concepts increasingly overlap with broader information security strategies.
Google's Widevine DRM remains a cornerstone of premium media protection, powering licensing, playback verification, and content access control across consumer devices and streaming services. Its widespread adoption underscores the importance of standardized, device-compatible protection frameworks that can scale across heterogeneous hardware and software environments.
Recent Partnership Activity and Ecosystem Integration
The competitive landscape continues to evolve through strategic alliances that expand protection capabilities and integrate DRM into new content delivery contexts. In early 2026, BuyDRM solidified its position through multiple high-profile engagements, including a partnership with Mostly Music to secure premium music experiences using forensic watermarking and advanced protection techniques, a collaboration with OneFootball to safeguard streaming channels on its digital platform, and the deployment of its MultiKey Service to power secure streaming on Telenet's TV Iconic offering. These developments illustrate how DRM providers are embedding themselves deeper into content creator and distributor workflows, moving beyond standalone licensing to become integral components of end-to-end delivery architectures.
Regulatory Foundations and Market Dynamics
The DRM market does not operate in a vacuum; it is shaped by a long-standing regulatory and standards-driven environment that defines how rights are expressed, enforced, and balanced against consumer expectations. Foundational legal frameworks, including landmark copyright legislation from the late 1990s, expanded protection to digital forms and established the legal groundwork for technology-based rights enforcement. Subsequent policy discussions and regulatory reviews have consistently highlighted the prevalence of DRM across hardware, publishing, and media sectors, reinforcing its role as a standard mechanism for controlling access and usage.
Standards organizations have further contributed to the ecosystem by emphasizing the need for interoperability with consumer electronics, blank media, and cross-device playback environments. At the same time, ongoing discourse around rights expression languages has underscored the importance of aligning DRM systems with fair use principles, privacy considerations, and public domain expectations. These dynamics create a complex operating environment where technical protection must coexist with legal compliance, user experience requirements, and evolving societal norms around digital content access.
For enterprises, this regulatory backdrop translates into several operational imperatives. Vendor selection must account for compliance readiness and adaptability to shifting legal interpretations. Product architecture should support flexible rights expression that can accommodate regional differences and emerging policy frameworks. Investment strategies must balance protection robustness with user accessibility to avoid friction that could undermine content engagement or market expansion.
Strategic Applications for 2026 Decision-Making
The insights contained in this report are designed to translate market data into actionable strategic guidance. Executive teams can leverage the findings to inform technology procurement decisions, evaluate partnership and licensing opportunities, and align internal security roadmaps with projected market growth. Procurement and IT leadership will find value in understanding how solution categories differentiate in terms of deployment complexity, integration requirements, and long-term scalability. Content executives and business development teams can use the application-level analysis to identify protection gaps, optimize licensing models, and assess how competitor strategies may influence market positioning.
The report also addresses practical implementation considerations, including integration pathways, compliance alignment, and the operational trade-offs between software-centric and hardware-centric protection approaches. By mapping these factors against historical growth patterns and forward-looking forecasts, the research provides a structured foundation for scenario planning, budget justification, and risk assessment. Organizations preparing for multi-year technology cycles will benefit from the report's emphasis on sustained growth trajectories and the structural forces that continue to drive adoption across content sectors.
Digital Rights Management (DRM) Market
Conclusion and Next Steps
Digital Rights Management is no longer a peripheral security function; it is a strategic enabler of digital monetization, compliance assurance, and content lifecycle management. As market growth accelerates and competitive dynamics intensify, organizations that invest in comprehensive, forward-looking intelligence will be better positioned to navigate technology transitions, regulatory shifts, and evolving consumer expectations. This report delivers the depth, structure, and analytical rigor required to support confident executive decision-making throughout 2026 and the broader forecast horizon.
The complete market research includes detailed segmentation profiles, granular competitive assessments, technology trend analysis, and implementation frameworks that go beyond the high-level overview presented here. To access the full dataset, methodology documentation, and executive-ready strategic recommendations, we invite you to explore the complete report and begin applying these insights to your organization's digital rights strategy.
Intellectual Property Rights Royalty Management Market
For detailed analysis of this topic, please visit the official page: Digital Rights Management (DRM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVA Medical Market Hits $118.1M in 2025, Projects 4.3% CAGR to $154.62M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in a Maturing Market: Why the Polyvinyl Alcohol in Medical Sector Demands Precision in 2026
The global market for polyvinyl alcohol (PVA) in medical applications has entered a phase of structured consolidation and disciplined expansion. Over the past five years, steady acceptance of PVA-based excipients, hydrogel systems, and specialty coatings has transformed what was once a niche material segment into a strategically relevant pillar of pharmaceutical and medical device value chains. For executives planning product portfolios, supply strategies, and capital allocation through the rest of the decade, understanding where this market is heading is no longer optional. It is a prerequisite for defensible growth.
This article introduces PW Consulting’s latest market research on Polyvinyl Alcohol in Medical, a study built to convert macro momentum into actionable strategic clarity. The analysis draws on a six-year historical baseline and projects trajectory through the medium term, giving decision-makers a grounded view of how demand, pricing dynamics, regulatory expectations, and competitive positioning are evolving together. The goal is simple: to help organizations move beyond broad assumptions and toward precise, evidence-based planning.
A Market Built on Sustained, Measurable Growth
The medical PVA segment has demonstrated a consistent upward arc, reflecting the material’s expanding role in core pharmaceutical formulations and targeted medical applications. Historical revenue progression shows a clear compound trajectory: from a base near 81.72 million USD in 2020, the market advanced through successive annual increments to reach 118.1 million USD in 2025. That trajectory is projected to continue through the forecast window, with sequential growth milestones mapped across each year to 2032.
For strategy teams, the macro figures are useful only when placed in context. A projected CAGR of 4.3 percent is neither explosive nor stagnant. It is the kind of rate that rewards disciplined execution: steady demand growth from established application areas, gradual adoption in higher-value medical grades, and targeted regional opportunities that reward companies with the right manufacturing footprint and compliance readiness. In this environment, growth is less about chasing volume and more about capturing recurring value through formulation performance, supply reliability, and differentiated product grades.
The market’s trajectory also signals an increasing premium on visibility. As revenues compound year over year, small differences in cost structure, yield, product specification alignment, and regional reach can translate into meaningful advantages or persistent margin pressure. That is precisely why a structured research framework matters: it helps leadership separate durable trends from cyclical noise.
What the Research Delivers: From Market Sizing to Execution-Ready Intelligence
PW Consulting’s Polyvinyl Alcohol in Medical study is designed as an operational reference rather than a static snapshot. The report combines broad market sizing with a detailed structural view of the industry, giving teams the ability to interrogate the market across the dimensions that matter most to planning and execution.
Core Coverage Areas
- Historical performance records and forecast modeling across the full analytical horizon, enabling leadership to test assumptions against observed trends and projected trajectories.
- Segment-by-segment analysis of type profiles, application demand patterns, and regional market structure, presented in a format built for scenario planning and internal alignment.
- Competitive mapping that connects company profiles, product positioning, and recent industry events to broader market dynamics.
- Regulatory and compliance contexts relevant to medical-grade use, including pharmacopoeial alignment and application-specific expectations that influence purchasing decisions and formulation approvals.
- Supply-side considerations such as feedstock dynamics, process economics, and certification pathways that shape cost behavior and product availability.
- Strategic interpretation designed to support decisions in procurement, product development, capacity planning, market entry, and competitive positioning.
The structure is intentionally practical. Rather than offering a single summary view, the research is organized so that commercial, R&D, supply chain, and regulatory stakeholders can each extract relevant insight without losing sight of the broader market logic. This integrated approach is especially valuable in a market where formulation performance, grade suitability, and supply continuity are tightly interconnected.
Why This Format Matters for 2026 Decision-Making
In a market characterized by moderate but dependable growth, the biggest strategic risks often come from misreading the drivers behind the numbers. A product may perform well in one application environment while facing different adoption dynamics in another. A region may show strong potential but require distinct compliance, distribution, or partnership strategies. Recent pricing actions and input-cost pressures further complicate planning, reinforcing the need for a research asset that connects market structure to real-world operating conditions.
The report is built to support exactly that kind of layered decision-making. It gives organizations a shared factual baseline, then adds interpretive depth so teams can evaluate where to invest, where to protect margin, and where to reposition for the next phase of market evolution.
How the Competitive Landscape Is Shaping the Market
The medical PVA space is defined by a concentrated group of capable manufacturers, each bringing distinct product families, technical heritage, and customer relationships to the table. The combined influence of leading firms is substantial, with top-three and top-five players holding a significant share of market concentration. In such an environment, competitive advantage depends not only on scale but on product specificity, regulatory readiness, and the ability to respond quickly to shifting demand and cost conditions.
Polyvinyl Alcohol in Medical Market
Several established companies anchor the competitive landscape. Kuraray Co., Ltd. produces POVAL™, ELVANOL™, EXCEVAL™, and MOWIFLEX™ medical-grade polyvinyl alcohol resins for pharmaceutical excipients, hydrogels, and coatings. Sekisui Specialty Chemicals offers Selvol™ polyvinyl alcohol for medical adhesives, hydrogels, and pharmaceutical applications with specialty medical grades. Mitsubishi Chemical Corporation manufactures GOHSENOL™ and GOHSENX™ pharmaceutical-grade polyvinyl alcohol for excipients, binders, film coatings, and ophthalmic or nasal solutions. Japan VAM & Poval Co., Ltd. supplies pharmaceutical-grade polyvinyl alcohol under brands including PE-05JPS for medical applications. Eastman Chemical Company produces polyvinyl alcohol grades for medical and pharmaceutical applications including hydrogels and coatings.
What distinguishes this group is not merely product breadth, but the way each company aligns its portfolio to medically relevant performance requirements. Pharmaceutical-grade specifications, application-specific consistency, and the ability to support technical customers are repeatedly the differentiators that matter in formulation development and procurement selection. In practical terms, the market rewards suppliers who can pair material quality with reliable compliance documentation and predictable supply behavior.
Recent Industry Movements and What They Signal
Recent developments in the sector have sharpened the importance of forward-looking intelligence. In 2026, multiple leading manufacturers announced pricing actions that reflect both input-cost realities and strategic repositioning. Kuraray Co., Ltd. announced upward price revisions for its POVAL™, ELVANOL™, EXCEVAL™, and MOWIFLEX™ polyvinyl alcohol resins, with additional adjustments communicated for North America, Central America, and South America. Sekisui Specialty Chemicals announced further price increases across several Selvol product lines, including a global increase for Selvol polyvinyl alcohol products at differentiated levels across North America, Latin America, Asia, and EMEA.
These actions should be read as more than routine cost pass-throughs. They underscore a market where feedstock cost movement, regional cost structures, and margin management are increasingly intertwined. At the same time, underlying supply-side conditions such as vinyl acetate monomer feedstock cost increases in early 2026 have placed upward pressure on polyvinyl alcohol prices in Northeast Asia and Europe. Parallel pressures from labor cost increases linked to monomer price volatility have also affected production economics for medical grades.
For buyers and competitors alike, the implication is clear: pricing discipline, grade selection, and regional sourcing strategy now carry greater strategic weight. Companies that understand the rationale behind these moves can plan more effectively for procurement timing, contract structure, and product substitution assessments.
Regulatory Alignment, Certification, and the Rise of Lower-Carbon Medical Materials
The medical PVA market does not evolve in a vacuum. It is shaped by pharmacopoeial expectations, application-specific acceptance criteria, and an increasingly important emphasis on traceability and sustainability in medical material supply chains.
Compliance readiness is a meaningful enabler of adoption. For example, GOHSENOL™ EG series polyvinyl alcohol is documented to meet European Pharmacopoeia, United States Pharmacopoeia, and Japanese Pharmaceutical Excipients standards for medical use, reinforcing the role of standardized pharmaceutical-grade materials in formulation confidence and market access. At the same time, supportive policy and research activity is helping expand the long-term relevance of PVA-based systems. The Japanese Ministry of Economy, Trade, and Industry has supported research into PVOH hydrogels for ophthalmic and regenerative medicine applications, pointing toward nearer-term process development and longer-term application expansion.
Sustainability credentials are also entering the purchasing conversation more directly. Sekisui Specialty Chemicals secured ISCC PLUS certification for Selvol polyvinyl alcohol, enabling lower-carbon traceable medical-grade materials globally. In an environment where healthcare and pharmaceutical customers increasingly scrutinize supply chain footprint alongside performance, such certifications can become a visible differentiator in evaluation processes, especially where multiple technically suitable grades are available.
Together, these developments illustrate that market success in medical PVA is increasingly multi-dimensional. Technical performance remains essential, but regulatory alignment, documentation quality, and sustainability positioning are now part of the competitive equation.
Worldwide Polyvinyl Alcohol Market
Where Strategic Attention Should Focus in 2026
As organizations plan for the remainder of the decade, several strategic questions rise to the surface. How should procurement teams balance price visibility with supply continuity in a market where leading suppliers are actively adjusting pricing? How should R&D and formulation teams evaluate PVA grades against application-specific requirements when regulatory standards and customer expectations are tightening? How should commercial teams assess regional opportunities when growth is distributed unevenly across markets and applications?
Addressing these questions requires more than a single market figure. It requires a structured view of demand by application context, an understanding of type differentiation, awareness of regional market structure, and a realistic read of competitive behavior. It also requires the discipline to recognize where general trends end and company- or segment-level choices begin.
That is why this research is built to support scenario-based planning. Executives can use it to test procurement strategies against price movement, evaluate market-entry logic against competitive concentration, and align product development priorities with demand patterns that are likely to persist through the forecast period. In a market growing at a steady but not spectacular pace, the winners are often the organizations that make fewer assumptions and more informed trade-offs.
Why PW Consulting’s Market Research Is Designed for Action
This report is not intended as a passive reference document. It is intended to help teams make better decisions faster. By combining historical performance, forecast structure, segmentation logic, competitive context, and recent industry events, the study creates a single integrated frame for evaluating the medical PVA market.
The value lies in the connections. The report links market size evolution to the forces shaping it. It connects product types and application areas to the commercial realities behind them. It places company actions within the broader dynamics of feedstock costs, compliance expectations, and supply-side economics. Most importantly, it is designed to reduce ambiguity at the moment when strategic choices must be made.
For teams responsible for pharmaceutical sourcing, medical materials strategy, product planning, or regional market development, this level of detail is essential. It offers a credible basis for internal discussion and a reliable foundation for decision-making that can withstand scrutiny from finance, R&D, quality, and supply chain stakeholders.
Next Steps: Access the Full Strategic Picture
The insights outlined here provide a high-level view of why the Polyvinyl Alcohol in Medical market deserves focused attention in 2026 and beyond. But the real strategic value lies beneath the summary layer: in the segmented structure, the detailed competitive context, the regional and application patterns, and the interpretive analysis that ties market movement to execution choices.
To support rigorous planning, PW Consulting’s full report delivers the complete dataset, the deeper segmentation view, and the applied analysis needed to turn market intelligence into business strategy. If your organization is evaluating procurement timing, product-grade selection, market-entry logic, or competitive positioning in medical-grade PVA, the full research is built to help you move from awareness to action with confidence.
For the complete forecast structure, segmentation detail, company profiles, and strategic interpretation, explore the full Polyvinyl Alcohol in Medical market research from PW Consulting.
For detailed analysis of this topic, please visit the official page: Polyvinyl Alcohol in Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Civil Helicopter MRO Market Hits $9.7B in 2025, Projects 6.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: The Civil Helicopter MRO Market Outlook 2026–2032
The civil helicopter maintenance, repair, and overhaul (MRO) sector stands at a pivotal inflection point as we move into 2026. Driven by accelerating fleet utilization rates, evolving regulatory frameworks, and sustained investment in rotorcraft modernization, the market has transitioned from a post-pandemic recovery phase into a period of structured, high-velocity growth. For executives, investors, and operational leaders across the aviation value chain, understanding the trajectory of this market is no longer optional. It is a strategic imperative.
This analysis serves as a strategic preview to PW Consulting's newly released Civil Helicopter MRO Market Research Report , a comprehensive intelligence asset designed to equip decision-makers with the granular insights, competitive mapping, and forward-looking projections necessary to navigate the next seven years of industry evolution. The following overview highlights the macro-scale dynamics, competitive realities, and regulatory currents shaping the landscape, while demonstrating why this research has become an essential tool for institutional strategy in 2026 and beyond.
Market Trajectory: Sustained Expansion Anchored in Historical Momentum
The civil helicopter MRO market has demonstrated remarkable resilience and consistent upward momentum over the past half-decade. Drawing on a robust historical dataset spanning 2020 through 2025, the sector has recorded steady year-over-year revenue expansion, culminating in a baseline valuation of approximately $9.7 billion in the most recent full-year cycle. This trajectory reflects not only the restoration of civil aviation activity but also the deepening integration of helicopter assets into critical infrastructure: emergency medical services, offshore energy support, law enforcement, and an expanding array of commercial passenger and cargo logistics networks.
Forecasting models projecting through 2032 indicate that this growth will not merely continue but accelerate in structural complexity. The market is anticipated to surpass the $10.2 billion threshold in 2026, with compound annual growth rates stabilizing at approximately 6.5 percent over the forecast horizon. By the close of the projection window in 2032, total market valuation is projected to approach the $15 billion mark. This sustained expansion is underpinned by several converging forces: the aging of incumbent rotorcraft fleets that demands increasingly intensive heavy maintenance cycles, the modernization of avionics and propulsion systems that introduces new service categories, and the geographical diversification of civil helicopter operations into emerging markets where aerial mobility solutions are gaining institutional adoption.
For corporate strategists, these figures represent more than macroeconomic indicators. They signal a market in which capacity planning, service-line prioritization, and regional footprint decisions will yield disproportionate competitive advantages. Organizations that align their MRO investments with the cadence of fleet age profiles and regulatory timelines will be positioned to capture disproportionate shares of high-margin maintenance cycles, while those that rely on backward-looking utilization models risk strategic misalignment.
Structural Segmentation: Where Value Is Created and Captured
The civil helicopter MRO ecosystem is not a monolith. It is a layered constellation of service categories, each with distinct demand drivers, technical requirements, and margin profiles. Market intelligence reveals that airframe heavy maintenance continues to command the largest share of industry revenue, reflecting the capital-intensive nature of structural inspections, corrosion mitigation, and comprehensive rotorcraft airframe overhauls. Engine maintenance constitutes the second-largest pillar of the market, driven by the operational imperative to sustain powerplant reliability and the growing trend of engine life-extension programs that defer prohibitive replacement costs. Component maintenance, encompassing dynamic systems, avionics, transmissions, and rotor assemblies, represents a rapidly evolving segment where precision engineering and digital diagnostics are increasingly reshaping service delivery models.
Alongside these technical divisions, the application landscape reveals a pronounced tilt toward commercial operations, which account for the dominant portion of MRO spending across the civil rotorcraft sector. Private and corporate helicopter fleets contribute a substantial secondary stream of demand, characterized by more customized service requirements, shorter turnaround expectations, and a higher willingness to invest in premium maintenance packages that preserve asset values and operational flexibility. Understanding the interplay between these service lines and application categories is critical for firms evaluating capacity allocation, pricing architecture, and partnership strategies.
The regional distribution of MRO activity further underscores the importance of geographically informed strategy. North America remains a foundational market, anchored by dense fleets, mature regulatory environments, and a robust network of certified repair stations. Europe follows as a structurally significant region, supported by stringent EASA compliance frameworks and a growing emphasis on cross-border rotorcraft operations. Asia Pacific represents an increasingly dynamic frontier, where expanding public safety mandates, resource-sector helicopter demand, and emerging commercial rotorcraft programs are catalyzing new MRO investments. Latin America and the Middle East and Africa, while currently smaller in aggregate scale, are experiencing targeted growth driven by energy-sector operations, crisis-response capabilities, and localized fleet modernization initiatives.
Military Helicopter MRO Market
A complete picture of these segmentation dynamics, however, requires more than high-level categorizations. It demands detailed breakdowns of demand elasticity, service-cycle durations, regional certification pathways, and the margin implications of each maintenance modality. This is precisely the level of granularity embedded within the full research deliverable.
Competitive Landscape: OEM Dominance, Independent Agility, and Strategic Differentiation
The civil helicopter MRO market is characterized by a moderately concentrated competitive environment, where a handful of large-scale players command meaningful market share while a diverse field of specialized independents competes on technical agility, regional proximity, and niche service capabilities. Market concentration metrics indicate that the top three participants collectively control roughly 38 percent of industry revenue, while the top five extend their combined footprint to approximately 48 percent. This structure suggests a market that rewards both scale efficiencies and specialized differentiation, with room for agile entrants to secure sustainable positions through certified capabilities, strategic partnerships, and targeted service expansions.
At the OEM tier, Airbus Helicopters maintains a formidable presence through its integrated HCare service portfolio, which spans heavy maintenance, dynamic component repair, blade restoration, avionics upgrades, and continuing airworthiness management organization (CAMO) support. Operating across more than thirty sites and ninety-three MRO centers globally, the OEM leverages its manufacturing heritage, proprietary technical data, and expansive service network to anchor long-term fleet support relationships. Its recent emphasis on preserving MRO expertise amid digital transformation signals a strategic recognition that technological modernization must be paired with the retention of high-caliber engineering and maintenance talent.
Within the independent MRO segment, several firms have established strong reputations for operational excellence and regulatory compliance. StandardAero and Heli-One, both Canadian-based specialists, deliver comprehensive airframe maintenance, repair, overhaul, and component support services for civil and commercial rotorcraft fleets worldwide. Their scale, technical certifications, and global service footprints position them as critical capacity providers for operators seeking independent, cost-competitive alternatives to OEM channels. Rotortrade, headquartered in Atlanta, has emerged as a highly adaptive independent provider, combining full-service maintenance, CAMO oversight, and FAA Part 145 certification with avionics integration capabilities, including its recognized dealership status with Garmin. Eurotech, based in Italy, operates as an EASA Part 145 certified MRO center delivering comprehensive maintenance and overhaul services for civil rotorcraft, while Saudia Technic, anchored in Riyadh, has expanded its capabilities to encompass comprehensive helicopter maintenance and overhaul services for civil and commercial aircraft, reflecting broader regional investment in aviation infrastructure.
The competitive landscape is not static. Recent developments illustrate how targeted investments and regulatory certifications are reshaping service capabilities in real time. In late 2025, Rotortrade officially launched its U.S. MRO facility, securing full FAA Part 145 certification and enabling return-to-service approvals for FAA-regulated rotorcraft—a move that materially expands its domestic service reach. The following year, in early 2026, the company's Latrobe facility was appointed an official Garmin dealership, broadening its certified avionics integration capabilities under existing FAA approvals. These developments highlight a broader industry pattern: independents are increasingly differentiating through specialized certifications, strategic technology partnerships, and facility expansions that align with regional regulatory frameworks and operator demand.
Simultaneously, the inaugural Vertical MRO Conference, held in Kelowna, British Columbia, drew over five hundred rotorcraft MRO professionals for education sessions and industry exhibitions, underscoring the growing institutional focus on knowledge exchange, technical standards, and cross-company collaboration within the rotorcraft maintenance community. For market participants, these gatherings are more than networking events; they are barometers of emerging best practices, supplier relationships, and regulatory expectations that will shape competitive dynamics in the years ahead.
Regulatory Dynamics and Industry Currents: The Compliance-Led Evolution of MRO Strategy
Regulatory evolution is one of the most powerful forces reshaping the civil helicopter MRO market. In the United States, the FAA Modernization of Special Airworthiness Certification (MOSAIC) final rule, published in mid-2025, introduced a series of phased compliance milestones that directly affect pilot training, maintenance rules, and the regulatory classification of certain aircraft categories. The staggered effective dates—spanning pilot training and maintenance rule updates in late 2025 through the removal of the light-sport aircraft definition from federal aviation regulations in mid-2026—require MRO providers and fleet operators to adapt their compliance frameworks, training pipelines, and service protocols with precision and foresight.
Parallel regulatory developments have reinforced the importance of structured safety management. U.S.-registered Part 145 repair stations that also hold EASA Part 145 certification were required to implement formal safety management systems by the end of 2025, aligning North American and European maintenance standards with increasingly rigorous risk-management expectations. More recently, the FAA has emphasized a long-term industry goal of achieving zero fatal civil helicopter accidents, publishing enhanced guidance that includes updated Airman Certification Standards for rotorcraft-helicopter series, replacing older practical test standards with more rigorous competency frameworks. These regulatory currents do not merely impose compliance obligations; they reshape the competitive landscape by rewarding organizations that invest early in proactive safety cultures, standardized training, and digitally enabled compliance tracking.
Beyond regulation, the market is responding to broader operational and technological currents. Eurotech's certification by Robinson Helicopter Company as an Authorized Robinson Helicopter Dealer for 2026 exemplifies how manufacturer-aligned authorizations are becoming strategic differentiators, validating MRO providers' adherence to specific technical standards and unlocking access to dedicated service ecosystems. Meanwhile, advances in predictive maintenance analytics, digital airworthiness documentation, and component lifecycle tracking are gradually transforming traditional MRO workflows from reactive repair models into data-informed service architectures. Organizations that integrate these capabilities into their operational models will be better positioned to reduce turnaround times, optimize parts inventory, and deliver the transparency that modern operators increasingly demand.
The Strategic Value of Comprehensive Market Intelligence in 2026
For enterprises operating in or adjacent to the civil helicopter MRO ecosystem, the complexity of the market environment in 2026 demands more than generalized industry awareness. It requires a structured, evidence-based intelligence foundation that integrates historical performance data, forward-looking projections, segmentation analysis, competitive profiling, and regulatory foresight into a single, coherent decision-support framework.
Civil Helicopter MRO Market
PW Consulting's Civil Helicopter MRO Market Research Report has been designed to meet this need. The study draws upon extensive primary and secondary research to deliver a multi-dimensional view of the market across its full forecast horizon. It provides detailed analysis of revenue trajectories, service-line dynamics, regional demand patterns, and the strategic moves of key market participants, enabling readers to benchmark their positioning, identify whitespace opportunities, and anticipate shifts in competitive intensity. The report also examines the practical implications of regulatory changes, technological adoption curves, and fleet lifecycle dynamics, translating high-level trends into actionable strategic considerations for capacity planning, partnership evaluation, and market-entry or expansion decisions.
Importantly, the intelligence contained within this research is structured to support a range of operational and strategic functions. For MRO service providers, the analysis offers a basis for calibrating investment in facility capacity, certification pathways, and specialized service lines. For OEMs and component manufacturers, it illuminates downstream demand patterns and the service-interface opportunities that accompany fleet modernization. For financial stakeholders and investors, it provides a disciplined framework for evaluating growth trajectories, margin drivers, and the competitive vulnerabilities that may influence long-term returns. For fleet operators and aviation authorities, it delivers context on service availability, regulatory alignment, and the evolving standards that shape procurement and compliance strategies.
Navigating the Next Seven Years with Confidence
The civil helicopter MRO market is entering a phase defined by sustained growth, regulatory refinement, and intensifying competitive differentiation. The macroeconomic trajectory is clear: revenue expansion will continue at a robust pace, fleet age profiles will drive increasing demand for heavy maintenance and component overhaul, and regional demand centers will continue to diversify as rotorcraft operations expand into new operational contexts. Yet the precise allocation of opportunity across service categories, geographic zones, and competitive tiers remains a question that can only be answered through detailed, research-backed analysis.
In an environment where strategic agility depends on accurate foresight, access to comprehensive market intelligence is not merely an informational advantage—it is a foundational element of operational resilience and growth planning. The full Civil Helicopter MRO Market Research Report provides the depth, structure, and analytical rigor required to make informed decisions with confidence. Readers seeking the complete segmentation breakdowns, detailed company profiles, regional demand mappings, and forward-looking scenario analysis are encouraged to access the full report through the source webpage, where the complete intelligence suite is available for institutional review and strategic application.
For detailed analysis of this topic, please visit the official page: Civil Helicopter MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com