

Blogs
Navigating the Microbial Identification Market: Strategic Trends and Commercial Opportunities Through 2032
The microbial identification market has entered a decisive growth phase, transitioning from a specialized laboratory tool to an essential operational capability across healthcare, pharmaceutical quality control, food safety, and environmental monitoring. Valued at USD 212.0 million in 2020, the market expanded steadily to USD 327.2 million by 2025, reflecting a compound annual growth rate of 9.07 percent projected through 2032. At that trajectory, revenue is expected to surpass the USD 600 million threshold by the end of the forecast window. This expansion is not merely a function of incremental laboratory adoption; it signals a structural shift in how organizations detect, classify, and respond to microbial threats and quality deviations.
The momentum is sustained by converging pressures. Rising antimicrobial resistance, tightening regulatory expectations for contamination control, and the growing economic cost of delayed or inaccurate identification have elevated microbial identification from a discretionary upgrade to a core compliance and risk-mitigation function. At the same time, the market remains relatively fragmented. The top three players account for approximately 24.6 percent of total revenue, while the top five hold 26.2 percent, indicating that scale advantages exist but have not yet produced a consolidated oligopoly. This concentration profile leaves meaningful room for differentiated positioning, regional expansion, and technology-led disruption.
Key Challenges and Inflection Points
Despite the clear growth trajectory, several structural challenges are reshaping how participants compete and how end users evaluate solutions. The first challenge lies in the widening performance gap between centralized reference laboratories and decentralized point-of-need settings. Traditional identification workflows still struggle with turnaround time, sample preparation complexity, and database limitations when confronting rare, fastidious, or rapidly evolving pathogens. Organizations that require same-day decisions in clinical, manufacturing, or field environments are increasingly unwilling to accept multi-day turnaround cycles, forcing vendors to balance analytical depth with operational simplicity.
A second inflection point centers on regulatory and reimbursement alignment. Regulatory clearance, quality management certification, and coding mechanisms for test reimbursement are no longer peripheral compliance issues; they directly shape market access, purchasing confidence, and the economic viability of new systems. As diagnostic and quality-control workflows become more automated and integrated, ambiguous reimbursement pathways or inconsistent certification expectations can slow adoption, even when the underlying technology is mature. Participants that treat regulatory strategy as an afterthought risk losing momentum to competitors who design clearance, documentation, and billing alignment into their product roadmaps from the outset.
A third challenge emerges from data usability and workflow integration. Identification is only valuable when it feeds timely decisions. Laboratories and production environments increasingly expect systems that not only classify organisms but also connect results to downstream actions, such as antibiotic stewardship decisions, batch release judgments, or environmental corrective measures. Vendors that deliver isolated identification outputs without interoperable software, standardized reporting, or scalable database updates are seeing their solutions marginalized in consolidated laboratory ecosystems. The market is therefore moving from a hardware-centric evaluation toward a total-workflow assessment.
Key Drivers of Market Change
Technological Innovation and Analytical Performance
Technology advancement remains the most visible driver of adoption. Modern identification platforms are increasingly judged on speed, accuracy across difficult organism classes, and the ability to scale database coverage without sacrificing reproducibility. In clinical and industrial settings, this means systems must handle gram-positive and gram-negative bacteria, anaerobes, yeasts, mycobacteria, molds, and resistant pathogens with consistent confidence. The competitive edge is shifting toward solutions that combine reliable spectral or molecular discrimination with streamlined sample handling and high-throughput software workflows.
Recent product developments illustrate this direction. In March 2025, bioMérieux received FDA 510(k) clearance for its VITEK COMPACT PRO ID/AST system, designed to support rapid microorganism identification and antibiotic susceptibility testing in clinical and industrial laboratories. The launch reflects a broader push toward integrated identification and susceptibility workflows that compress turnaround time while preserving interpretive value for treatment and quality decisions. Later in the year, Bruker expanded its FDA-cleared portfolio by securing clearance for additional claims on the MALDI Biotyper CA System, extending the cleared reference library to 549 species and introducing workflow-oriented software and shuttle capabilities intended to improve laboratory throughput. These developments matter because they show two distinct but converging strategies: one emphasizing integrated ID/AST utility for routine lab operations, the other expanding organism coverage and workflow efficiency for high-volume identification environments.
Pathogen Detection Market
Regulatory and Policy Environment
The regulatory landscape is becoming a defining commercial variable. In the United States, FDA 510(k) clearance for microbial identification tests has growing practical significance because it can enable reimbursement pathways through CPT codes, directly affecting the economics of test adoption in clinical settings. This linkage between clearance and reimbursement is changing how laboratories evaluate new systems. A technically capable platform that lacks clear regulatory status or documented quality-system certification may face longer procurement cycles, more conservative pilot decisions, or limited budget allocation.
Beyond clearance, quality management expectations continue to shape procurement in medical-grade applications. ISO 13485 certification has become a baseline expectation for systems intended for medical use, influencing buyer confidence in consistency, risk management, and post-market support. At the same time, regulatory momentum around antimicrobial stewardship is reinforcing demand for faster and more reliable identification in clinical environments, where earlier organism characterization can support more targeted therapy and reduce unnecessary broad-spectrum use. For manufacturers, this means regulatory strategy is no longer a documentation exercise; it is a market-access lever that affects sales cycles, customer confidence, and the speed at which new features can be commercialized.
Demand-Side Shifts Across End-Use Segments
Demand is expanding beyond traditional diagnostic laboratories. Pharmaceutical manufacturing quality control continues to drive consistent adoption, as contamination events carry steep consequences in terms of batch loss, investigation cost, and regulatory exposure. In this environment, identification is not simply a scientific exercise; it is part of a containment and root-cause workflow that must be fast, traceable, and repeatable. Food safety and environmental monitoring represent additional demand centers, where organizations increasingly need to detect and identify contaminants before they escalate into recalls, site closures, or compliance breaches.
Behaviorally, purchasers are shifting from isolated instrument evaluation toward workflow-level purchasing. Laboratories and quality teams want systems that fit existing staffing models, reduce manual touchpoints, and produce results that integrate with laboratory information systems or quality management processes. This is especially relevant in settings where skilled microbiologists are in short supply or where throughput demands exceed the practical capacity of legacy methods. As a result, adoption decisions increasingly weigh database breadth, software usability, and the ability to standardize identification across multiple sites or shifts.
Supply Chain and Cost Structure Dynamics
Cost structures are being reconsidered across the value chain. The operational burden of microbial identification is no longer limited to instrument acquisition; it includes consumables, database access, calibration and maintenance, training, and the hidden cost of delayed results. In many organizations, the true cost comparison between methods depends on total turnaround time, error rates, and the downstream impact of misidentification or inconclusive results. This has increased interest in platforms that reduce hands-on time and minimize repeat testing, even when upfront instrument economics appear less advantageous.
Supply chain resilience is also influencing procurement strategy. Organizations operating across multiple geographies or managing critical production processes are more cautious about dependence on single-source consumables or proprietary workflows that are difficult to scale during disruptions. That caution is encouraging interest in systems with robust support networks, predictable consumables availability, and software architectures that can be updated without repeated hardware replacement. For vendors, this environment rewards transparent total-cost narratives and dependable service models as much as it rewards analytical performance.
Competitive Landscape and Leading Strategies
The competitive landscape reflects a market where performance, regulatory readiness, and workflow design are being used to carve out defensible positions rather than compete solely on price. Bruker Corporation, based in Billerica, Massachusetts, has emphasized the MALDI Biotyper CA System as a focused offering for microbial identification, with FDA-cleared MALDI-TOF mass spectrometry intended to support rapid identification of gram-positive and gram-negative bacteria, anaerobes, and yeasts from cultured isolates. Its associated MBT Compass HT CA software is positioned to improve workflow efficiency, an increasingly important consideration for laboratories handling high sample volumes or seeking to reduce manual bottlenecks. Bruker’s recent expansion of cleared claims and reference library coverage suggests a strategy centered on broadening organism coverage and strengthening the practical usability of the system in cleared-use settings.
bioMérieux, headquartered in Marcy-l’Étoile, France, has taken a different but complementary approach, emphasizing integrated identification and susceptibility testing through its VITEK MS PRIME and VITEK COMPACT PRO systems. Its FDA 510(k)-cleared MALDI-TOF and automated ID/AST offerings are designed for both clinical and industrial microbial identification, with expanded databases that address mycobacteria, molds, and resistant pathogens. The company’s emphasis on combined ID/AST functionality reflects a strategy aimed at environments where identification is only one step in a broader decision chain, particularly where antibiotic stewardship, infection control, or quality release decisions depend on timely susceptibility information alongside organism identification.
Microbial Air Samplers Market
The strategic differentiation between these leaders is instructive. One approach prioritizes broad organism coverage and workflow efficiency for identification-intensive operations. The other emphasizes integrated clinical and industrial utility, linking identification more tightly to downstream interpretation and action. Both strategies address real buyer priorities, but they appeal to different purchasing rationales. In practice, this means competition is increasingly segment-specific: laboratory types, throughput profiles, organism mix, and regulatory requirements all influence which value proposition is more compelling.
PW Consulting
Market Structure and Evolution
Market concentration remains moderate, leaving the industry in a phase where scale matters but does not yet dictate outcomes. That structure favors companies that can combine credible technology, clear regulatory positioning, and strong application-specific messaging. It also leaves space for regional players and niche entrants that can serve localized demand, specialized organism panels, or specific compliance environments more flexibly than larger platforms. Over time, the market is likely to move toward selective consolidation, but not uniformly. Consolidation will probably be driven by workflow integration, database stewardship, and service-network economics rather than by instrument pricing alone.
New entrants and technology shifts will continue to test incumbents, especially where identification can be embedded into broader diagnostic, quality, or environmental monitoring ecosystems. However, entry barriers remain meaningful because practical adoption depends on more than analytical promise. Buyers look for cleared or certified status where applicable, established database maintenance, predictable consumables supply, and integration with existing laboratory or manufacturing workflows. As a result, the most durable competitive advantage will belong to organizations that treat identification as an end-to-end capability rather than a standalone instrument sale.
Forward Outlook: Trends Shaping the Next Three to Five Years
One of the most consequential trends is the continued compression of identification workflows into faster, more decision-ready formats. Laboratories and quality teams are unlikely to accept longer turnaround times simply because a method is familiar. The demand for same-day or near-real-time identification will keep pushing platforms toward higher throughput, simpler sample handling, and software that reduces interpretation burden. Commercially, this trend favors vendors that can demonstrate measurable workflow gains, not just incremental accuracy improvements.
A second trend is the growing importance of database depth and updateability as a competitive asset. As pathogen populations evolve and industrial contamination profiles become more diverse, static identification libraries will become less valuable than actively maintained, expandable databases. Organizations will increasingly evaluate whether a vendor can sustain coverage for emerging or less common organisms, support regional variation in microbial profiles, and deliver updates without disrupting operations. This shifts competitive advantage toward companies with strong bioinformatics, curation processes, and customer-support infrastructure.
A third trend is the alignment of identification solutions with stewardship and risk-management objectives. In clinical settings, faster identification supports antimicrobial stewardship by enabling more informed therapy decisions earlier in the care pathway. In pharmaceutical, food, and environmental contexts, identification increasingly supports contamination response, root-cause analysis, and compliance documentation. Solutions that connect identification results to actionable downstream workflows are likely to gain preferential consideration because they reduce the operational gap between result generation and decision implementation.
These trends create tangible commercial opportunities. Vendors can capture share by packaging identification with workflow software, database services, and support models that reduce total operating burden. Procurement teams can lower risk by prioritizing systems that align with their organism mix, throughput needs, and regulatory context rather than choosing on instrument specifications alone. Investors and strategic partners should pay attention to companies that demonstrate not only technical credibility but also the ability to navigate clearance, certification, reimbursement alignment, and multi-site deployment. At the same time, uncertainty remains. Reimbursement pathways can shift, regulatory expectations can tighten, and adoption can slow if workflow integration proves more difficult than anticipated. Database maintenance costs, training demands, and consumables availability may also influence the realized pace of growth, especially in cost-sensitive or resource-constrained environments.
Strategic Implications for Decision Makers
For Manufacturers and Solution Providers
Product strategy should be built around total workflow value rather than identification performance in isolation. That means prioritizing database curation, software usability, service reliability, and regulatory readiness as core commercial assets. Where applicable, clearance and certification should be treated as enablers of market access and purchasing confidence, not as optional compliance milestones. Companies should also define their positioning by application context, since clinical, pharmaceutical, food safety, and environmental buyers evaluate risk, turnaround, and integration needs differently.
Go-to-market execution should emphasize predictable operating economics and demonstrable time-to-result benefits. In fragmented markets, regionalized support, site-level deployment expertise, and clear documentation can be as influential as product features. Manufacturers that can show how identification reduces repeat testing, shortens investigation cycles, or supports stewardship and quality decisions will have stronger leverage in competitive evaluations.
For Investors and Strategic Partners
Investment theses in this space should account for more than top-line growth rates. Sustainable value creation depends on regulatory positioning, database and software stewardship, service economics, and the ability to serve multiple end-use segments without diluting focus. Because market concentration is moderate, there is room for both scaled incumbents and specialized players, but long-term winners are likely to be those that can convert technological capability into repeatable deployment and customer retention.
Partners should also monitor where identification is becoming embedded into broader workflows. Opportunities may arise not only in instrumentation but also in middleware, data interpretation, quality documentation, and support services that make identification results more actionable. Conversely, exposure to segments with unclear reimbursement, weak service infrastructure, or limited regulatory alignment may carry higher execution risk.
For Procurement, Laboratory, and Quality Leaders
Purchasing decisions should begin with the operational problem rather than the instrument category. Define the required organism coverage, acceptable turnaround time, staffing constraints, and integration needs before evaluating vendors. In many cases, the more relevant comparison is not instrument price but total workflow impact, including hands-on time, repeat testing, database relevance, and the reliability of ongoing support.
Where regulatory compliance and reimbursement affect adoption, confirm clearance status, certification expectations, and coding implications early in the evaluation process. Also assess whether the solution can be deployed consistently across multiple sites or shifts, since standardization often determines whether identification capabilities deliver enterprise value or remain confined to a single high-performing unit.
Conclusion
The microbial identification market is expanding under the influence of clearer regulatory expectations, stronger demand for faster and more actionable results, and a competitive field that is increasingly rewarding workflow-integrated solutions. Growth to the USD 600 million range by 2032 is plausible, but the commercial winners will be determined by how effectively organizations translate analytical capability into reliable, compliant, and decision-ready operations. For executives, investors, and procurement leaders, the strategic priority is to look beyond specifications and evaluate how identification solutions fit into the broader economics of risk reduction, throughput, and stewardship. For those seeking a more detailed view of segment-level demand, regional dynamics, and vendor-specific positioning, the full market research report provides the deeper breakdown needed to shape execution plans with greater confidence.
For detailed analysis of this topic, please visit the official page: Microbial Identification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Strategic Shift Reshaping the PCB Design Software Market
The electronic design automation landscape supporting printed circuit board development has entered a period of accelerated structural change. Between 2020 and 2032, the global market for PCB design software is projected to expand from roughly $2.17 billion to $10.11 billion, reflecting a compound annual growth rate of 13.7 percent. This trajectory rests on more than steady hardware shipment growth. It signals a fundamental recalibration of how electronic systems are conceived, simulated, validated, and handed off to manufacturing. Market participants that treat PCB design tools as generic utility licenses are misreading the market. The value is shifting toward integrated workflows, simulation depth, ecosystem interoperability, and the ability to compress design cycles without sacrificing signal integrity or compliance readiness.
Two inflection points define the current moment. First, design complexity is outrunning legacy toolchains. Modern PCBs routinely combine multi-layer stacks, high-speed serial interfaces, power delivery networks, and embedded sensing functions. Engineers increasingly need a single environment where schematic capture, layout, 3D mechanical clearance, and electromagnetic or thermal simulation can be iterated without file translation loss or versioning friction. Second, the gap between premium enterprise platforms and accessible open-source or entry-tier tools is widening in capability, but narrowing in expectation. Free and community-driven suites have matured enough to influence feature roadmaps and pricing expectations, forcing commercial vendors to justify their cost through workflow efficiency, collaboration, and verification depth rather than basic drafting functions.
The markets leadership structure remains moderately fragmented, with the top five vendors collectively accounting for less than 30 percent of revenue and the top three below a quarter. That fragmentation is both a symptom and an opportunity. It reflects diverse end-market needs, differing regional procurement models, and the persistence of specialized tools for enterprise, mid-market, and hobbyist or startup use cases. It also suggests that consolidation will not arrive through blunt acquisition alone. Value creation will increasingly come from platform breadth, data continuity across design phases, and the capacity to serve regulated industries without forcing every customer into the same deployment model.
Key Drivers Redefining Growth
Technical Innovation Is Moving From Drawing Boards to Verified Systems
The most consequential driver is the migration from drafting-centric workflows to verification-aware design. Tools that bundle schematic, layout, and simulation into integrated suites reduce the rework spiral that historically drained engineering time. In practical terms, earlier signal integrity checks, power distribution analysis, and 3D mechanical co-design shorten feedback loops between electrical, thermal, and mechanical teams. Recent product updates from established vendors have focused on parallel library management, AI-assisted routing aids, and strengthened collaboration features. These improvements are not cosmetic. They address the real bottleneck in modern electronics development: the handoff between design intent and physical realization. When a design team can maintain a synchronized library, run targeted simulations earlier, and resolve clearance or routing conflicts before fabrication, the total engineering cost drops and time-to-market compresses.
At the same time, openness is reshaping expectations. The continued release cadence of mature open-source PCB design suites keeps raising the floor for usability, community libraries, and cross-platform accessibility. That matters commercially because it pressures proprietary vendors to differentiate on integration depth, support, and enterprise-grade assurance rather than on feature availability alone. The presence of capable free or low-cost tools does not eliminate the premium segment; it clarifies it. Buyers who can tolerate more manual coordination may choose accessible suites, while those facing complex signal integrity, large team collaboration, or strict manufacturing data handoffs are willing to invest in environments that reduce coordination risk.
Regulatory And Compliance Pressure Is Becoming A Design Requirement
Regulatory change is no longer a downstream concern. It is influencing how PCB design workflows are configured from the outset. The U.S. Quality Management System Regulation, aligned with ISO 13485:2026, imposes mandatory risk-based design controls, traceability, and documentation requirements on medical device PCB design processes. Effective February 2026, that framework increases the cost of informal or poorly documented design practices in regulated hardware. For software providers, this creates a growing preference for tools that support design traceability, version control, validation records, and audit-ready outputs. The commercial implication is straightforward: electronics entering regulated segments increasingly need design environments that can demonstrate not just what was built, but how decisions were captured and verified.
On the cybersecurity side, the EU Cyber Resilience Act introduces obligations for digital products, including software used in the design and maintenance of connected systems, to address vulnerability handling and security maintenance. Reporting duties for actively exploited vulnerabilities begin in September 2026. For PCB design software vendors and their customers, the practical effect is heightened attention to update cycles, dependency management, and secure handling of proprietary design assets, especially when cloud-linked collaboration or third-party libraries are involved. Compliance is becoming a procurement criterion, not just a legal checkbox.
Demand-Side Shifts Are Accelerating Iteration Cycles
End-market demand is pushing design teams toward faster, more iterative development. In consumer and computing electronics, product refresh cycles and feature differentiation continue to reward designs that can integrate new components while preserving board real estate and thermal margins. In telecommunications, higher bandwidth and denser subsystems raise the stakes for routing discipline and simulation accuracy. Medical devices combine miniaturization with stricter documentation and risk management expectations. Industrial and automotive applications introduce harsh-environment reliability, long product lifecycles, and increasing electronic content per unit. Across these segments, the common thread is the need to reduce late-stage design changes. When design software supports earlier validation and clearer collaboration, engineering teams can absorb more complexity without paying for schedule slip.
Cost Structures And Deployment Preferences Are Shaping Adoption
Cost dynamics are influencing who buys what, and how. Premium enterprise PCB design software subscriptions for leading integrated tools begin at roughly $4,235 per user per year, before training, configuration, and hardware considerations. Advanced design work also depends on capable workstations and experienced engineers, which increases total cost of ownership for smaller organizations and can slow adoption of premium suites. That economic reality reinforces a bifurcated market: enterprise and complex-project users invest in high-capability environments to protect schedule and quality, while smaller teams often blend accessible tools, in-house expertise, and selective simulation or verification services.
PW Consulting
Deployment models remain shaped by data sensitivity. On-premise deployment continues to dominate for PCB design software in aerospace, defense, and automotive sectors because those segments require strict data security and intellectual property protection. This is a durable advantage for vendors that can offer secure, locally controlled workflows with the same feature depth as cloud-enabled alternatives. At the same time, collaboration features and library synchronization are becoming more attractive in less constrained industries, creating a tension that vendors must manage: flexibility versus control, and shared workflow efficiency versus data isolation. The winners will be those that can offer both paths without fragmenting the user experience.
Competitive Positioning And Market Evolution
The competitive landscape is defined less by raw market share than by workflow philosophy and target segment clarity. Altium has maintained a strong identity around an integrated PCB design environment that combines schematic capture, layout, simulation, and collaboration in a single workflow. Its value proposition centers on reducing tool-switching friction and making mid-to-enterprise engineering teams more self-sufficient. Zuken operates with a more tiered platform logic, pairing enterprise-grade solutions for complex subsystem and 3D layout with mainstream PCB design tools and electrical design platforms. That structure lets it serve organizations with varied complexity levels while keeping a hand in both high-end and broader market needs. Siemens EDA brings a portfolio spanning PCB design, layout, simulation, analysis, and verification, aligning naturally with customers who want continuity across design and verification stages and who already value industrial-scale process discipline. Cadence has been advancing AI-enabled PCB design, layout, and analysis through its OrCAD X platform, leaning into the expectation that intelligent assistance can reduce routine load and improve decision quality in complex layouts.
Below the commercial leaders, the market includes open-source and accessible EDA offerings that exert influence through reach, community contributions, and baseline usability. These tools matter strategically because they shape training pipelines, attract new designers, and pressure commercial vendors to justify premium pricing through measurable efficiency gains. They also illustrate that entry barriers in basic PCB design are lower than ever, while barriers in high-performance, high-reliability, and highly regulated design remain substantial. Industry groups are recognizing the skills gap as well. A global electronics association launched an introductory PCB design course in early 2026 focused on layout and schematic skills using EDA tools, signaling that workforce readiness is becoming part of the ecosystem conversation. The practical outcome is a market where capability, training, and certification are increasingly linked, especially for organizations trying to expand design capacity without sacrificing quality.
Electrical Design Software Market
The market structure is evolving along three axes. Integration is deepening where customers face complexity and coordination overhead. Differentiation is sharpening where vendors compete on simulation fidelity, library management, collaboration, and compliance support rather than on feature counts. And new entry pressure persists from open and accessible tools, especially at the lower end of the market and in education and startup segments. Consolidation is possible, but it will likely be selective. Buyers in regulated and high-complexity segments value continuity and support more than brand aggregation. Mid-market and cost-sensitive buyers value flexibility and practical learning curves. The most resilient strategies will be those that align product architecture with actual workflow pain points rather than with headline feature announcements.
Forward Outlook: Three Trends To Watch
The next three to five years are likely to be shaped by three interlocking trends. First, simulation and verification will move earlier and deeper into the design flow. As boards carry more high-speed interfaces, denser power networks, and tighter mechanical constraints, the cost of discovering problems late will keep rising. Tools that enable targeted simulation, earlier signal and power integrity checks, and smoother mechanical co-design will become core purchasing criteria, especially in telecommunications, computing, medical, and automotive-adjacent applications. The commercial opportunity here is not only in selling licenses but in reducing downstream engineering and rework costs. Vendors and service providers that can demonstrate measurable reductions in iteration cycles will have stronger positioning.
Printed Circuit Board Market
Second, compliance readiness will become a more explicit part of tool selection. Regulatory expectations around risk-based design controls, traceability, and documentation in medical devices, along with cybersecurity obligations for digital products and vulnerability reporting, raise the stakes for design environments that support auditable processes and disciplined data handling. Organizations that adopt design workflows with better record-keeping, version discipline, and secure asset handling will be better positioned for regulated market access. Vendors that help customers map tool capabilities to compliance workflows can turn regulatory pressure into a differentiator. The risk, however, is that compliance requirements could slow adoption if tools are perceived as cumbersome or if update and vulnerability management processes are weak.
Third, the market will continue to segment by deployment model and total cost of ownership. On-premise control will remain important in defense, aerospace, and automotive contexts, while cloud-linked collaboration and library synchronization will gain ground where data isolation is less critical and team coordination matters more. At the same time, premium subscription economics will keep challenging smaller firms, reinforcing demand for flexible purchasing, scalable training, and selective use of high-end tools only where complexity justifies them. A third risk lies in the skills pipeline. Advanced tools require capable engineers and adequate hardware. If organizations invest in software but underinvest in training and workstation readiness, adoption will underperform and the perceived value of premium suites will erode.
What Decision-Makers Should Do Now
For hardware manufacturers and design organizations, the strategic priority is to align tool selection with actual complexity and risk rather than with generic feature lists. If a team regularly handles high-speed signals, dense layouts, or regulated documentation, the payoff from integrated design, earlier simulation, and stronger library and collaboration control tends to be higher. If the work is more standard in scope, accessible or mid-tier tools may deliver more efficient use of budget, especially when combined with targeted external verification or training. In either case, it is worth auditing the total cost of ownership: subscription cost, training time, workstation requirements, data security constraints, and the cost of late-stage design changes. Treat software choice as a workflow decision, not a licensing event.
For investors and strategic partners, the opportunity lies in identifying vendors and platform plays that convert workflow friction into measurable efficiency. The most durable value is likely to come from tools and ecosystems that reduce rework, improve traceability, and support both secure and collaborative deployment depending on customer need. Watch for differentiation that is tied to real engineering outcomes: faster convergence, better signal and power integrity handling, smoother handoffs to manufacturing, and clearer compliance support. Be cautious of offerings that compete mainly on price without addressing the coordination and verification gaps that drive cost in complex electronics development. Also monitor the training and workforce dimension, since design tool value is realized only when engineers can use advanced capabilities effectively.
For procurement and technology buyers, the practical move is to evaluate tools against the organization’s regulated exposure, collaboration needs, and internal skill level. Where medical, automotive, or cyber-relevant considerations apply, prioritize environments that can support documentation discipline, traceability, and secure handling of proprietary design data. Where teams are smaller or budget-constrained, test whether a lower-cost toolchain can meet current needs and where its limits will appear as complexity grows. Clarify whether the organization requires on-premise control or can benefit from shared collaboration, and ensure that procurement includes training, deployment configuration, and hardware readiness rather than license cost alone. Detailed segmentation data, vendor-by-vendor capability comparisons, and deployment economics can materially improve these decisions, which is why deeper research and tailored assessments remain valuable for organizations making near-term platform commitments.
For detailed analysis of this topic, please visit the official page: PCB Design Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thionyl Chloride Market $935M by 2032: Why 4.8% CAGR Signals a Strategic Shift
By PW Consulting, 2026-09-21
Thionyl Chloride Market Outlook 2026-2032: Strategic Shifts and Commercial Opportunities
Market Context and Core Challenges
The thionyl chloride market enters the 2026-2032 forecast period from a foundation of steady expansion. Recorded revenue progressed from USD 531.23 million in 2020 to USD 679.8 million in 2025, reflecting consistent demand accumulation across multiple end-use sectors. The forward trajectory points toward USD 695.83 million in 2026, climbing to USD 935.1 million by 2032, with a compound annual growth rate of 4.8 percent over the forecast horizon. This baseline growth establishes a recognizable macro pattern, but the market structure beneath these figures is undergoing meaningful recalibration that warrants closer attention.
One defining challenge is the uneven maturity of application segments. Industrial synthesis, pharmaceutical intermediates, and electrolyte-related uses do not expand at the same pace or respond to the same cost drivers. Buyers in mature segments increasingly demand consistency, purity, and supply reliability, while growth-oriented segments push for volume access and price stability. Suppliers must reconcile these divergent expectations within a single production and distribution framework, which places pressure on specification management, inventory planning, and customer segmentation.
PW Consulting
A second challenge arises from regulatory fluidity. Chemical handling, transport classification, and cross-border trade documentation remain subject to periodic adjustments that can alter lead times, compliance costs, and regional sourcing strategies overnight. The market has seen targeted updates that change the administrative burden around specific battery-related uses, and such changes can redirect procurement flows between jurisdictions without any underlying shift in chemical demand. Organizations that treat regulation as a static compliance checklist rather than an active market variable risk missing sourcing opportunities or overestimating friction in certain corridors.
A third challenge is feedstock linkage and cost predictability. Thionyl chloride production depends on the reaction of sulfur trioxide with sulfur dichloride, making the availability and price behavior of sulfur dichloride a central input risk. Because this feedstock is tied to refining and chlorination byproduct streams, supply can be influenced by upstream plant turnarounds, regional capacity dynamics, and energy cost movement. In a market expanding at a mid-single-digit rate, input volatility can compress margins more quickly than end-market demand can offset them, especially for producers with limited feedstock flexibility.
Strategic Implications of the Current Landscape
The combination of polarized application growth, regulatory variability, and feedstock sensitivity means that aggregate market size alone is an insufficient planning tool. Executives need to understand where growth is concentrating, which supply routes are becoming more or less friction-prone, and how specification requirements differ across customer types. The next phase of advantage will belong to firms that can align product grade, logistics, and compliance posture with the specific end-use profile they serve, rather than competing primarily on broad availability.
Key Drivers Shaping Market Direction
Technology and Application Innovation
Innovation in downstream applications is one of the most important demand-side forces in this market. In battery-related uses, thionyl chloride functions as a key electrolyte component in lithium thionyl chloride cells, where long service life and stable performance under demanding conditions support adoption in industrial, utility, and specialized remote deployments. Improvements in cell design, energy density, and operational reliability expand the addressable base for these batteries and, in turn, reinforce demand for high-purity electrolyte-grade material. For manufacturers, the strategic implication is clear: application-level performance gains can create durable demand pull, but they also raise expectations for consistency and traceability in the chemical input stream.
Beyond batteries, refinement in organic synthesis and specialty intermediate production continues to broaden the use of thionyl chloride as a chlorinating and synthesizing agent. Process optimization in pharmaceuticals and fine chemicals increasingly emphasizes yield, impurity control, and reproducibility, which favors suppliers able to support tighter specifications and dependable batch quality. Where customers integrate thionyl chloride into multi-step synthesis routes, delivery reliability and documentation quality can become as commercially significant as unit pricing.
Policy and Regulatory Environment
Policy developments are actively reshaping trade conditions in specific segments. Recent guidance from Chinese authorities optimized import and export measures for lithium thionyl chloride batteries containing no more than 1 kg of the chemical, removing licensing requirements from January 1, 2026. This adjustment reduces administrative friction for smaller-format cells and related components moving through China’s trade channels, and it can improve speed-to-market for products that rely on cross-border sourcing of battery-grade material. The broader lesson is that regulatory recalibration does not always function as a barrier; in some cases it realigns cost and timing dynamics in ways that benefit well-positioned supply chains.
At the same time, chemical regulation remains fragmented across regions. Handling standards, transport classification, workplace exposure oversight, and import documentation all vary, and the cumulative compliance burden can influence where production is sited, how inventory is buffered, and which customer segments are most attractive. Market participants that proactively monitor regulatory calendars and map them against their sourcing and distribution footprint can convert policy visibility into a planning advantage rather than reacting after changes take effect.
Demand-Side Shifts in End-Use Behavior
Demand patterns are being shaped by a combination of industrial electrification, specialty chemical expansion, and more selective procurement behavior. Battery-linked applications continue to benefit from the broader push toward long-duration and maintenance-light power solutions, particularly where stability and shelf life matter more than rechargeability. In parallel, pharmaceutical and agrochemical manufacturers are under pressure to improve process efficiency and reduce variability, which increases the value of predictable reagent supply and consistent grade quality.
Procurement teams are also behaving differently. Rather than treating thionyl chloride as a commodity bought primarily on spot price, many buyers now weigh total cost of ownership, including quality risk, lead-time variability, and compliance assurance. This shift favors suppliers that can demonstrate dependable specification control and transparent logistics, and it can create a divergence between customers who prioritize cost above all and those who prioritize supply integrity. Understanding which buyer archetype dominates a given region or application is essential for positioning product offerings and service levels appropriately.
Supply Chain and Cost Structure Dynamics
Cost structure remains tightly connected to feedstock behavior and production efficiency. With sulfur dichloride as the core feedstock for thionyl chloride synthesis, availability is supported by refining byproducts, but that linkage also means supply can be sensitive to changes in upstream operations and regional chlorination capacity. When feedstock conditions tighten, producers with integrated sourcing options or diversified input relationships can better protect margins and maintain delivery continuity.
Worldwide Lithium Thionyl Chloride Cell Market
Logistics and safety requirements add another layer to the cost structure. Because thionyl chloride must be handled and transported under appropriate controls, regional transport conditions, packaging standards, and intermodal coordination can materially affect landed cost and service reliability. In a market where multiple application segments depend on timely delivery, firms that optimize packaging, routing, and inventory positioning can differentiate on reliability even when base pricing remains competitive. The strategic opportunity lies in treating logistics and feedstock coordination as part of the core value proposition, not as a back-office function.
Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with the top three players accounting for roughly 29.4 percent of market revenue and the top five combining for about 39.0 percent. This concentration indicates that leading firms hold meaningful share, but it also suggests substantial room for regional specialists, niche-grade suppliers, and application-focused entrants. The market is not dominated by a single universal model; instead, competitiveness depends heavily on grade focus, geography, and the ability to serve specific end-use requirements with reliable quality and documentation.
Large diversified chemical and specialty material firms are positioned around scale, brand trust, and broad application coverage. Companies such as LANXESS AG maintain a presence that spans high-purity chlorinating agent supply and electrolyte-related uses for long-life lithium thionyl chloride batteries, alongside pharmaceutical, agrochemical, and specialty synthesis demand. Merck KGaA, including its reagent-grade offerings through Sigma-Aldrich Co. LLC, serves laboratory and specialty synthesis customers with a focus on specification clarity and research-grade consistency. These positions are strongest where customers value recognized quality, technical support, and predictable supply over lowest-cost volume purchasing.
Worldwide Titanium Chloride Market
Regional and application-focused producers create value through proximity, responsiveness, and targeted product families. In China, Jiangxi Selon Industrial Co. Ltd. and Shandong Kaisheng New Materials Co. Ltd. participate in fine chemical and specialty materials supply for pharmaceutical, agrochemical, and organic synthesis uses, where local manufacturing and distribution can reduce lead times and improve service continuity. In India, Transpek Industries Ltd. and Bodal Chemicals Ltd. supply thionyl chloride for pesticides, pharmaceuticals, and fine chemical intermediates, aligning production with regional demand clusters in agrochemical and specialty intermediate markets. CABB Group adds another European-oriented presence with chlorinating agent supply for industrial and agrochemical applications.
Differentiation Paths in Practice
The market is shaping up around several identifiable differentiation strategies:
- Grade specialization, where suppliers build reputation and pricing power around technical-grade consistency or pharmaceutical/reagent-grade purity, depending on their target customer base.
- Application alignment, where firms tailor inventory, packaging, and technical support to battery electrolyte needs, organic synthesis workflows, or agrochemical and pharmaceutical intermediate production.
- Regional service depth, where local production, distribution, and compliance knowledge reduce lead-time risk and improve responsiveness for nearby customer clusters.
- Supply resilience, where feedstock coordination, multi-site capability, or inventory positioning is used to protect continuity during upstream disruption or demand surges.
These strategies are not mutually exclusive, but they tend to define distinct competitive identities. A supplier that attempts to compete on every axis at once may dilute focus; one that chooses a defensible specialty and executes it consistently can command stronger customer loyalty and more stable margins.
Market Evolution Trends
Several directional patterns are visible in the competitive landscape. First, the market is likely to see continued differentiation rather than full consolidation into a small number of universal suppliers. Application specificity and regional service needs favor a mixed structure in which global or multinational players coexist with regional specialists and grade-focused niche suppliers. Second, new entrants and expanding local producers are most likely to succeed where they can reduce lead-time risk, match specification expectations, or serve fast-growing application pockets that larger players serve less intensively. Third, customer purchasing behavior is increasingly segmented, which means competitive pressure is not uniform: some segments will remain price-sensitive, while others will reward reliability, documentation quality, and technical support. The firms that understand this segmentation and do not treat the market as a single battlefield will be better positioned to protect share and margin.
Future Trends for 2026-2032
Trend 1: Application-Linked Demand Becomes the Main Growth Engine
Over the next several years, aggregate growth is expected to remain positive, but the more important story is where that growth concentrates. Battery-related electrolyte demand, specialty synthesis, and pharmaceutical and agrochemical intermediates are likely to be among the more influential pockets, each with different specification and supply requirements. The commercial opportunity is to align product offerings, inventory depth, and service models with the application segments that offer the best combination of growth and margin resilience, rather than spreading resources evenly across all uses.
Trend 2: Regulatory Visibility Turns Into a Sourcing Advantage
As trade and handling rules continue to evolve in targeted ways, the ability to anticipate and adapt to regulatory changes will become a stronger differentiator. Adjustments that reduce licensing or administrative burden for specific battery formats can improve trade flow and open short-term pricing or sourcing windows. More broadly, suppliers and buyers that maintain forward visibility into regulatory calendars and regional compliance expectations will be better able to secure inventory, select routes, and negotiate terms from an informed position. The risk is complacency: organizations that wait for disruption to settle before adjusting their plans may leave value on the table or face avoidable friction.
Trend 3: Feedstock and Cost Discipline Shape Margin Outcomes
Because feedstock availability and input cost behavior remain central to production economics, firms that invest in feedstock coordination, procurement diversification, and process efficiency are likely to manage the middle of the market more effectively than those that rely on spot exposure alone. In a 4.8 percent CAGR environment, margin protection depends on more than selling into growth; it also depends on controlling input variability and avoiding reactive purchasing. The opportunity here is operational: companies that treat feedstock strategy and logistics design as strategic levers can improve resilience without needing to win on price alone.
Risks and Uncertainties
Several factors could alter this trajectory. Regulatory adjustments may move faster than anticipated in some regions or stall in others, changing the relative attractiveness of different sourcing corridors. Feedstock conditions could tighten if refining or chlorination byproduct streams are disrupted, pressuring margins for less flexible producers. Demand growth may also become uneven if downstream adoption in batteries or specialty synthesis slows in certain markets, leaving supply better balanced in some segments than others. Finally, competition from regional producers could intensify where local service advantages or cost positions improve, putting pressure on incumbents that depend primarily on scale and brand recognition.
Strategic Actions for Decision Makers
For Manufacturers and Suppliers
Position the portfolio around defensible grade and application profiles rather than treating all demand as interchangeable. Where high-purity or reagent-grade consistency is the main buyer concern, invest in specification control, documentation, and technical support. Where volume and reliability matter more, focus on feedstock coordination, production stability, and logistics design that protects delivery continuity. It is also worth examining whether regulatory changes affecting specific battery-related flows can be used to strengthen regional service advantages or streamline cross-border supply in selected segments.
For Investors and Strategic Buyers
Evaluate opportunities with an application-segment lens. The most compelling cases are likely to combine steady demand characteristics with manageable compliance and feedstock risk, rather than relying on scale alone. When assessing entrants or expansion projects, pay attention to regional service positioning, feedstock relationships, and the ability to serve a specific segment with consistent quality. In a moderately concentrated market with clear niche opportunities, value creation often comes from focusing on the right segment and executing supply reliability well, not from broad horizontal growth.
For Procurement and Supply Chain Leaders
Treat thionyl chloride sourcing as a total-cost and continuity decision, not solely a spot-price exercise. Map the trade and regulatory environment for each corridor you use, especially where battery-related or cross-border flows are involved, so that changes can be anticipated rather than absorbed. Diversify where possible across grade-qualified sources and regions to reduce exposure to localized feedstock or logistics disruption, and align supplier evaluation criteria with the quality and reliability expectations of your end-use application. Buying decisions that reflect specification needs, lead-time risk, and compliance visibility will usually outperform decisions based on headline price alone.
Where to Go Next
The thionyl chloride market is moving through a phase in which aggregate growth is important, but segmentation, regulatory dynamics, and feedstock discipline matter more for business outcomes. Leaders who understand which application pockets are expanding, how trade conditions are shifting, and where supply resilience will be tested are better placed to prioritize investment, sourcing, and competitive positioning. For organizations that need detailed segmentation data, regional breakdowns, grade-level demand patterns, and tailored strategic scenarios, the full PW Consulting research report provides the deeper structure required to move from market-level insight to company-specific action.
For detailed analysis of this topic, please visit the official page: Thionyl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vitamin C Market: Why Asia Pacific's 76.88M Scale and 5.35% CAGR Redefine Growth
By PW Consulting, 2026-09-21
The Vitamin C (Ascorbic Acid) Market: Strategic Trends & Commercial Opportunities Through 2032
1. Market Overview & Core Challenges
The global ascorbic acid market has demonstrated resilient expansion over the past five years, with revenues rising from approximately USD 147.2 million in 2020 to an estimated USD 186.7 million in 2025. The trajectory points toward continued growth through the forecast window, with the market projected to exceed USD 267.2 million by 2032. This expansion reflects a compound annual growth rate of 5.35 percent, signaling steady but not explosive demand appreciation across downstream sectors. The pace of growth suggests a maturing commodity that is simultaneously undergoing structural repositioning rather than experiencing pure volume-driven expansion.
PW Consulting
A defining characteristic of the current market structure is its moderate concentration. The three largest firms account for roughly 54.7 percent of total revenue, while the top five players capture approximately 68.5 percent. This distribution indicates a landscape where dominant incumbents hold meaningful pricing and supply influence, yet substantial room remains for specialized producers, regional suppliers, and application-focused innovators to compete on differentiation rather than scale alone.
Key Challenges and Inflection Points
Several structural tensions are reshaping how value is created and captured in this market. Understanding these inflection points is essential for any executive evaluating capital allocation, sourcing strategy, or product development roadmaps.
First, the pricing environment has become more normalized but remains sensitive to regional trade dynamics. After a period of pronounced volatility across global supply chains, benchmark pricing settled into a more stable band through early 2026, with market indicators pointing to levels around USD 2.95 per kilogram compared to approximately USD 3.58 per kilogram in the prior year period. This decline reflects Chinese supply normalization and softer near-term demand pull, but it also introduces a strategic dilemma for producers who must balance margin defense with customer retention. Price stability should not be mistaken for pricing power; companies that rely purely on volume without application-specific value addition face renewed compression risk.
Second, trade policy uncertainty continues to create asymmetric opportunities across geographies. Import flows from China into the United States are subject to a 30 percent tariff rate following the expiration of a temporary truce in August 2024. This structural cost element reshapes competitive dynamics for formulators and distributors sourcing from East Asian production hubs, pushing some procurement strategies toward alternative sourcing corridors or prompting reformulation efforts that reduce exposure to tariff-sensitive supply lines. Executives who treat tariff exposure as a static risk rather than a dynamic sourcing variable may find their cost assumptions drifting as trade frameworks evolve.
Third, the raw material cost cycle is introducing both margin relief and planning complexity. In the first quarter of 2026, upstream glucose feedstock prices declined, reducing manufacturing input costs at major ascorbic acid production sites. While lower feedstock costs improve near-term operating economics, they also compress the cost advantage that some producers previously leveraged during periods of input inflation. Companies that use cost tailwinds to invest in capacity upgrades, application development, or sustainability programs will be better positioned than those that simply pass through temporary savings without strengthening structural competitiveness.
2. Key Drivers of Market Change
The market’s direction is being shaped by a combination of technological, regulatory, demand-side, and supply chain forces. These drivers interact in ways that reward firms capable of aligning production strategy with downstream application requirements.
Technological Innovation and Product Differentiation
Innovation in ascorbic acid is increasingly focused on stability, bioavailability, and formulation compatibility rather than pure commodity volume. The launch of premium stabilized forms, such as gold-stabilized ascorbic acid variants introduced for high-performance cosmetics, illustrates how technical differentiation can command higher value in application segments where shelf life, sensory performance, and active efficacy matter. Parallel developments in plant-derived and sustainably positioned ingredients reflect a broader industry push toward cleaner labels and traceable sourcing narratives. These innovations are not marginal; they are reshaping the value hierarchy within the market, separating commoditized bulk supply from specialty grades that justify tighter margins and longer customer relationships.
For producers, the strategic implication is clear: incremental R&D investment in stabilized forms, derivative variants, and application-tailored grades can unlock revenue pools that are less correlated with bulk commodity cycles. For buyers, the implication is equally important: specification decisions increasingly involve performance trade-offs, compatibility with formulation systems, and total cost of ownership rather than price-per-kilogram alone.
Policy and Regulatory Environment
Regulatory developments are acting as both a constraint and an enabler. Compliance requirements around purity, documentation, and application-grade certification continue to raise the bar for suppliers serving pharmaceutical and food sectors, reinforcing the advantage of producers with mature quality systems and audit-ready operations. At the same time, regulatory recognition of sustainability practices is beginning to influence procurement decisions. The awarding of high-quality development benchmark status to a producer’s pilot project on comprehensive waste utilization from vitamin C fermentation signals that environmental efficiency is moving from a supporting initiative to a qualification criterion in certain markets and customer conversations.
Policy-induced cost elements, including tariffs and trade-flow changes, also influence where value is created. Firms that can anticipate regulatory shifts and adjust supply routing, certification positioning, or regional manufacturing footprints gain a planning edge. Rather than reacting to compliance or trade changes after they affect quoting cycles, companies that build scenario planning into sourcing and capacity decisions can protect margin and customer confidence more effectively.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand patterns are being shaped by three overlapping currents. In personal care and cosmetics, there is sustained interest in vitamin C as an active ingredient associated with visible skin benefits, which supports demand for grades with enhanced stability and compatibility in complex formulations. In food and beverages, fortification and clean-label positioning continue to drive usage, though formulation constraints and label expectations requiregrades that integrate cleanly into varied processing conditions. In pharmaceuticals, demand remains tied to both established therapeutic applications and broader nutraceutical trends, with buyers placing a premium on consistency, documentation, and supply reliability.
Vitamin A Market
Across these segments, the common thread is a shift from transactional purchasing toward specification-driven partnerships. Customers are increasingly willing to pay for performance assurance, batch-to-batch consistency, and responsive technical support when those attributes reduce downstream risk. This behavior shift benefits suppliers who can demonstrate application competence, not merely capacity availability.
Supply Chain and Cost Structure Evolution
The supply side is undergoing a gradual rebalancing. Chinese producers, which represent a significant share of global output, are increasingly emphasizing value-over-volume approaches, with pricing stabilization and modest upward movement observed after an extended period of volatility. This recalibration suggests that the market is moving away from pure capacity-led competition toward a more nuanced environment where grade differentiation, sustainability performance, and supply reliability contribute to competitive positioning.
Cost structure dynamics also reflect feedstock movements, logistics considerations, and regional production economics. The decline in glucose feedstock costs provides temporary margin support, but the longer-term question is whether producers will convert that support into durable advantages through process improvements, byproduct utilization, and energy efficiency. Firms that treat input cost fluctuations as an opportunity to fund structural upgrades will build more resilient operating models than those that treat lower costs as a transient reprieve.
3. Competitive Landscape and Leading Strategies
The competitive field features a mix of globally positioned specialty players and large-scale producers with strong regional footprints. The strategic contrast among them highlights different pathways to value capture in a market where concentration is meaningful but not absolute.
Strategic Positioning Among Leading Companies
Dsms-firmenich has concentrated its ascorbic acid offering around a high-purity, pharmaceutical-grade positioning linked to a dedicated production site in Scotland, positioning itself as a Western-manufactured source for customers prioritizing traceability and grade consistency. This specialization reflects a deliberate choice to compete on quality assurance and application credibility rather than on sheer bulk volume.
BASF SE combines bio-based and standard ascorbic acid production through China-based facilities with collaborative development activity targeting nutraceutical and sustainable applications. Its approach blends scale with applied development, using partnerships and formulation-oriented innovation to expand relevance beyond conventional bulk supply.
Chinese producers such as CSPC Pharmaceutical Group, Northeast Pharmaceutical Group, Zhejiang NHU, Shandong Luwei Pharmaceutical, and North China Pharmaceutical Group illustrate a range of scale and application orientations. Several of these firms emphasize bulk and derivative production across pharmaceutical and food-grade standards, while others integrate ascorbic acid output with broader active pharmaceutical ingredient or peptide lines. One notable operational signal is the focus on waste recycling and comprehensive utilization in fermentation processes, a theme that aligns with both cost efficiency and sustainability positioning.
Evonik Operations GmbH has leaned into premium stabilized forms for cosmetics, targeting high-performance applications where enhanced stability and bioavailability justify a differentiated value proposition. This strategy demonstrates how a firm can compete in a mature market by building a specialty-grade identity rather than competing primarily on commodity pricing.
Differentiation Advantages and Competitive Evolution
The landscape is evolving along several axes. One is the divergence between bulk-oriented suppliers and specialty-grade innovators. Bulk producers compete on capacity, cost discipline, and reliability of large-volume supply, while specialty players differentiate through grade design, formulation support, and compliance narratives. Both models can be viable, but they require distinct operating postures, sales approaches, and capital priorities.
A second axis is regional repositioning. Trade policy and tariff exposure are encouraging some buyers to diversify sourcing and some producers to consider how manufacturing location affects customer affordability and supply continuity. This does not necessarily mean a wholesale exit from any one geography, but it does increase the value of flexible supply arrangements and transparent cost explanations.
A third axis is sustainability and process efficiency as competitive attributes. Waste utilization, energy efficiency, and feedstock optimization are moving from back-office improvements to elements of customer-facing storytelling and qualification. In a market where multiple suppliers can meet baseline purity requirements, process credibility and sustainability performance can become meaningful selection criteria.
New entrants and smaller specialists are unlikely to displace the largest incumbents through scale alone, but they can gain footholds by targeting underserved application niches, offering superior technical service, or introducing stabilized and derivative forms that address specific formulation pain points. The more probable trajectory is continued differentiation layered onto a concentrated base, with competitive advantage flowing to firms that match grade portfolio, supply reliability, and application expertise to the right customer segments.
3-O-Ethyl-L-Ascorbic Acid Market
4. Future Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape the market’s evolution and create actionable opportunities for firms that prepare early.
Trend 1: Continued Shift from Commodity Pricing to Application-Based Value
As stabilized forms, derivative variants, and grade-specific certifications become more established, a larger share of revenue is likely to migrate toward product categories where performance attributes matter more than bulk cost. This creates opportunities for producers to expand margins through specification-led offerings and for buyers to reduce downstream formulation risk by selecting grades that align with their processing and shelf-life requirements. Companies that invest early in application testing, technical documentation, and customer co-development will be better positioned to capture this shift than those that continue to compete mainly on tonnage and headline price.
Trend 2: Supply Chain Realignment Around Resilience and Sourcing Flexibility
Tariff exposure, regional cost differences, and customer sensitivity to supply continuity are likely to keep sourcing diversification on the agenda for formulators and distributors. Over the next few years, this should encourage more dual-sourcing architectures, greater attention to lead-time reliability, and more explicit conversations about total landed cost rather than ex-works price alone. For manufacturers, the opportunity lies in providing predictable supply, transparent cost logic, and the ability to serve multiple grade requirements from a coherent operational base. For procurement teams, the opportunity is to structure supplier relationships that balance cost efficiency with resilience, rather than optimizing narrowly for the lowest unit price.
Trend 3: Sustainability and Process Efficiency as Procurement Criteria
Waste utilization, feedstock efficiency, and energy-conscious manufacturing are expected to become more prominent in supplier evaluation, especially where customers face their own sustainability reporting obligations or where regulatory and consumer expectations reward cleaner production narratives. Producers that can demonstrate measurable efficiency gains and credible environmental practices may find these attributes translating into preferred-supplier status in certain segments. The risk for lagging firms is not immediate disqualification, but gradual erosion of relevance as sustainability becomes a tie-breaker in multi-supplier selection processes.
Risks and Uncertainties
Several factors could alter this trajectory. Continued trade-policy changes could reintroduce cost volatility in specific corridors, particularly where tariff exposure remains significant. Demand softness in one or more application segments could pressure utilization and reassert price competition, especially if feedstock cost relief encourages a return to volume-focused behavior. Regulatory tightening around documentation, purity, or environmental performance could raise compliance costs for less-prepared operators. Finally, innovation adoption may be uneven; if stabilized or specialty grades fail to achieve broad formulation acceptance, the anticipated value migration could stall, leaving bulk pricing dynamics more influential than expected.
5. Strategic Recommendations for Decision-Makers
Different roles face different priorities, but several strategic actions are broadly relevant across the industry.
For Manufacturers and Producers
- Align product portfolios with application value rather than aggregate tonnage. Invest in stabilized and derivative grades, technical documentation, and formulation support where customers are most likely to pay for performance assurance.
- Use feedstock cost relief and operational improvements to fund process efficiency, waste utilization, and energy optimization. These investments strengthen margin durability and build credible sustainability positioning that can support customer qualification.
- Build sourcing and supply flexibility into customer engagements. Transparent cost logic, reliable lead times, and the ability to serve multiple grade requirements can differentiate a supplier even in a concentrated market.
For Investors
- Evaluate exposure along the value gradient. Companies with specialty-grade portfolios, strong quality systems, and application-oriented customer relationships typically have more resilient margin profiles than pure bulk players in a normalizing price environment.
- Monitor regional risk factors, including tariff exposure and supply re-routing dynamics, as part of valuation assumptions. Cost structures that appear favorable in one trade scenario may shift materially if sourcing patterns change.
- Track sustainability and process-efficiency milestones as indicators of competitive positioning. In a market where baseline purity is increasingly table stakes, operational credibility can be a meaningful differentiator in customer retention and premium segment access.
For Procurement and Sourcing Leaders
- Shift evaluation frameworks toward total cost of ownership and supply reliability. Price-per-kilogram remains relevant, but grade compatibility, batch consistency, lead-time predictability, and documentation quality can have a larger impact on downstream outcomes.
- Consider diversified sourcing architectures that balance cost efficiency with resilience, especially where tariff exposure or single-region dependence creates hidden vulnerability.
- Engage suppliers early on specification needs and application constraints. Earlier collaboration can reduce reformulation risk and improve the fit between grade selection and end-product performance requirements.
The vitamin C market is not simply expanding; it is recalibrating around grade differentiation, supply resilience, and application-driven value. For executives navigating this environment, the most useful next step is a detailed look at segment-specific dynamics, regional cost and tariff exposure, and the competitive positioning of individual suppliers relative to end-use requirements. A comprehensive industry report can provide the deeper segmentation detail, competitive profiling, and scenario context needed to translate these strategic themes into concrete sourcing, investment, and product-development decisions.
The evolving balance between bulk supply and specialty-grade value, the impact of trade and feedstock dynamics, and the growing role of sustainability in supplier evaluation all point to the same conclusion: informed, segment-level intelligence will matter more over the coming years than broad market summaries. Decision-makers who secure access to detailed market data and tailored strategic guidance will be better equipped to act before structural changes become obvious to the entire industry.
For detailed analysis of this topic, please visit the official page: Vitamin C (Ascorbic Acid) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cable Glands Market: Why 6.5% CAGR and $2.78B Scale Redefine 2032 Strategy
By PW Consulting, 2026-09-21
Cable Glands Market: Strategic Trends and Commercial Opportunities (2025–2032)
The cable glands market has entered a phase of structural expansion, driven by renewed investment in industrial infrastructure, energy transition projects, and stricter safety compliance requirements across hazardous and non-hazardous environments. With historical revenue progressing from approximately 1.5 billion in 2020 to 1.8 billion in 2025, the market is positioned to reach roughly 2.78 billion by 2032, reflecting a compound annual growth rate of 6.5 percent. This trajectory signals more than cyclical recovery; it indicates a broader realignment of how industrial, utility, and construction sectors approach cable entry protection, environmental sealing, and hazardous-area compliance. For executives and investors, the opportunity lies not in treating cable glands as commoditized accessories, but in recognizing them as critical components within larger system reliability, asset protection, and regulatory compliance strategies.
The growth pattern observed between 2020 and 2025 demonstrates steady momentum with a notable acceleration toward the end of the period. Revenue levels held firm through 2024 before expanding more sharply in 2025, suggesting that procurement cycles, project backlogs, and compliance-driven replacements began converging at scale. The forecast window through 2032 points to continued expansion, with mid-term projections crossing the 2 billion threshold around 2026 and maintaining upward momentum thereafter. This environment rewards firms that can align product portfolios with application-specific demands, certification pathways, and regional deployment patterns while managing input cost volatility and supply chain complexity.
Market Landscape and Core Challenges
Concentrated Competitive Field With Diverging Growth Vectors
The market operates within a moderately concentrated structure, where a small group of established manufacturers commands a substantial share of revenue and distribution. This concentration creates a dual dynamic: incumbents benefit from brand trust, certification portfolios, and long-standing channel relationships, while smaller and regionally focused players gain traction through specialized materials, price agility, and localized service models. For decision-makers, this landscape means sourcing strategies must balance reliability and compliance assurance against cost, lead-time flexibility, and application-specific performance. The presence of strong European, North American, Asian, and South African manufacturers also indicates that regional preferences, certification regimes, and project types continue to shape purchasing behavior, rather than a single global standard dominating every segment.
Key Challenges and Inflection Points
Several structural pressures are redefining how the market evolves. First, hazardous-area compliance is becoming more rigorous and fragmented across jurisdictions. Cable entry equipment used in explosive atmospheres must satisfy an expanding set of certification expectations, and projects increasingly require documentation that satisfies multiple approval bodies simultaneously. This raises the bar for product design, testing, and time-to-market, particularly for manufacturers serving cross-border industrial customers.
Second, raw material cost fluctuation remains a persistent operational challenge. Brass, stainless steel, aluminum, and engineered plastics form the backbone of cable gland production, and global pricing movements directly affect margin stability and pricing strategy. Suppliers that depend heavily on a narrow set of input materials can experience cost shocks that propagate quickly through contract renewals and tender pricing. This has pushed many manufacturers to revisit material mix decisions, supplier diversification, and product standardization.
Third, the market is facing a subtle but meaningful shift in buyer expectations around performance beyond basic sealing. Industrial customers now evaluate cable glands as part of broader cable management systems, considering strain relief, electromagnetic compatibility, environmental durability, and ease of installation. This expands the evaluation criteria and rewards suppliers that can deliver integrated solutions rather than isolated hardware. At the same time, it pressures manufacturers to avoid over-engineering products where simpler, cost-effective designs would satisfy the application.
Key Demand Drivers
Technical Innovation and Materials Advancement
Product development is increasingly oriented toward versatility, protection performance, and installation efficiency. Manufacturers are expanding families of cable glands that accommodate multiple cable diameters, reduce part complexity, and maintain protection ratings across varied environments. Lamellar and adaptive sealing approaches, for example, have gained attention because they allow a single gland design to serve a broader range of cable sizes while preserving sealing integrity. This kind of design flexibility matters in the field because it lowers inventory complexity for distributors and contractors while reducing the risk of mismatches during installation.
Material choices are also evolving in response to application demands. Brass continues to serve as a widely used baseline for durability and conductivity, but stainless steel and engineered plastics are gaining prominence where corrosion resistance, weight, or chemical exposure becomes decisive. The coexistence of these material pathways indicates that the market is not moving toward a single superior material; rather, it is becoming more application-sensitive. Winners in this environment are those that match material selection to operational conditions, provide clear guidance on suitability, and avoid one-size-fits-all positioning.
Worldwide Connector Backshells Market
Regulatory and Certification Pressure as a Deployment Catalyst
Regulatory requirements are a central force shaping demand, particularly in hazardous locations and utility environments. Cable glands intended for explosive atmospheres must meet recognized standards and obtain relevant certifications, while external connection solutions in defined hazardous zones increasingly require documented compliance. This regulatory backdrop does more than constrain product design; it actively stimulates replacement cycles, upgrade programs, and new project inclusions. When safety and compliance expectations rise, engineering teams specify cable entry hardware more deliberately, and operators often choose certified solutions to reduce liability, streamline audits, and maintain operational continuity.
PW Consulting
Certification complexity also affects commercial dynamics. Products that carry multiple recognized approvals can gain preference in multinational projects, especially where engineers must satisfy overlapping regional requirements. Conversely, manufacturers that can only meet a narrow set of approvals may find their addressable market limited to domestic or lower-risk applications. This dynamic reinforces the strategic importance of certification portfolios as a commercial asset, not merely a technical checkbox.
Demand-Side Shifts in Industrial and Infrastructure Spending
Demand is being supported by broad industrial activity across energy, utilities, manufacturing, and construction. Oil and gas operations continue to require reliable cable entry for instrumentation, control, and power applications, particularly where environmental and explosion-risk conditions are present. Power and utilities projects contribute steady demand as grid infrastructure, substation work, and industrial power distribution expand or modernize. Manufacturing and process industries add further volume through automation upgrades, equipment refreshes, and facility expansions that rely on durable cable connections.
A notable shift on the demand side is the growing emphasis on operational resilience. Procurement teams are increasingly willing to prioritize solutions that reduce maintenance exposure, improve sealing reliability, and support faster installation, even when this means moving beyond lowest-unit-price selection. This does not eliminate cost sensitivity, but it changes the decision calculus: total cost of ownership, downtime risk, and compliance confidence now weigh more heavily in many bids. As a result, suppliers that can articulate performance benefits in operational terms often gain an advantage over those competing solely on specification sheets.
Supply Chain and Cost Structure Evolution
Supply chain conditions continue to influence both pricing and availability. Global trade dynamics, import-export policies, and input material availability interact to shape manufacturing costs and delivery reliability. In this environment, regional production footprints and diversified supplier networks can become strategic advantages, especially for customers who require predictable lead times and stable pricing. Manufacturers that can localize certain production steps or maintain flexible sourcing arrangements are better positioned to absorb external shocks and maintain commercial credibility during procurement cycles.
Tubular Cable Lugs Market
Cost structure pressure is also encouraging product rationalization. Rather than maintaining excessive SKU proliferation, some suppliers are narrowing ranges to high-use configurations, improving production efficiency, and reducing overhead complexity. This approach can simultaneously support margin defense and improve customer experience by making specification and ordering more straightforward. At the same time, differentiation remains essential, because overly simplified portfolios may fail to meet the needs of specialized hazardous-area or high-corrosion applications.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
Leading manufacturers are competing on a combination of certification breadth, application coverage, material expertise, and brand trust. Some firms have built strong identities around hazardous-location solutions, where Ex-certified cable glands and explosion protection expertise form the core of their value proposition. Others differentiate through wide industrial portfolios, emphasizing durable seals, strain relief, and compatibility across multiple cable types. A further group focuses on material-grade specialization, offering brass, stainless steel, or plastic nylon options tailored to corrosion, weight, or cost priorities.
Geographic origin and distribution footprint also influence positioning. European manufacturers often lean on engineering heritage, broad certification portfolios, and established industrial relationships. North American and Asian players may gain ground through application breadth, production scale, or targeted product technologies such as multi-diameter sealing systems. South African and Indian manufacturers can compete effectively by combining regional presence, cost competitiveness, and experience in weatherproof, flameproof, and EMC-relevant applications. The result is a market where no single formula dominates; instead, advantage tends to come from aligning product strength with the customer's primary risk profile and purchasing environment.
Strategic Behavior Reflected in Recent Market Activity
Recent supplier activity highlights a shared emphasis on visibility, application demonstration, and relationship development. Multiple manufacturers have participated in major trade events to present cable gland portfolios, industrial wire protection solutions, and related product lines. This pattern suggests that face-to-face engagement remains important in a market where specification decisions often involve engineers, procurement teams, and project stakeholders who value direct product explanation and technical reassurance. Trade presence also serves as a channel for showcasing new designs, reinforcing certification claims, and positioning suppliers within broader industrial ecosystems.
At the same time, regulatory developments continue to reinforce the importance of compliant, well-documented products. Certifications and safety approvals for hazardous locations are increasingly treated as baseline expectations rather than differentiators alone, which pushes competitors to distinguish themselves through reliability, ease of specification, material suitability, and service support. Companies that can integrate compliance credibility with practical installation benefits are better placed to convert interest into long-term contracts.
Market Evolution: Consolidation, Specialization, and New Entrants
The competitive field appears likely to evolve along multiple paths. Consolidation may continue where larger players seek to broaden regional coverage, strengthen certification portfolios, or acquire specialized capabilities. At the same time, specialization will remain attractive for firms that can serve distinct niches, such as polyamide-based designs, high-temperature applications, railway and new-energy fittings, or locally customized hazardous-area solutions. New entrants can still gain relevance if they bring clear technical differentiation, competitive cost structures, or strong regional channel access.
For buyers and investors, this mixed evolution means the market is not simply becoming more concentrated or more fragmented; it is becoming more segmented by use case and compliance profile. That segmentation creates opportunities for targeted growth, but it also raises the importance of understanding which applications and regions offer the most reliable demand signals. Broad positioning without application clarity is increasingly risky, while focused strategies built around specific industries, materials, or certification regimes can generate more predictable returns.
Future Trends and Commercial Implications
Trend 1: Compliance-First Specification Will Become Standard Practice
Over the next several years, hazardous-area compliance and multi-certification readiness will likely become default considerations in more procurement processes. As safety scrutiny persists and project documentation requirements deepen, engineers will favor products that simplify approval verification and reduce the risk of non-conformance. The commercial implication is clear: manufacturers with strong certification coverage and transparent documentation will have an easier path to specification, while those with limited approval footprints may be restricted to lower-risk segments. For investors, compliance readiness should be viewed as a durability factor, because it affects both revenue stability and the ability to enter demanding project pipelines.
Trend 2: Material and Design Choices Will Become More Application-Specific
The market is moving toward more deliberate matching of materials and gland architectures to operating conditions. Stainless steel will continue to gain relevance where corrosion or chemical exposure is a concern; brass will remain important where durability and cost balance matter; engineered plastics will hold value in lighter-weight or cost-sensitive applications. Simultaneously, designs that reduce SKU complexity while retaining performance flexibility will be favored by distributors and installers. The opportunity here lies in helping customers specify correctly the first time. Suppliers that provide clear application guidance, compatible accessory ecosystems, and reliable protection ratings can reduce friction in the buying process and strengthen repeat business.
Trend 3: Industrial Modernization and Infrastructure Renewal Will Sustain Demand
Demand is expected to remain supported by ongoing modernization across power systems, process manufacturing, energy operations, and construction activity. Many of these projects require cable entry hardware that can withstand environmental stress, support safe electrical connections, and meet project-specific regulatory expectations. Because such work often unfolds over multi-year cycles, demand is likely to be less volatile than in discretionary consumer markets. The commercial opportunity is to align product availability, lead times, and technical support with the pacing of large industrial programs, rather than treating each order as an isolated transaction. Firms that can serve as dependable partners in long-duration projects may benefit from stronger retention and more predictable order flow.
Risks and Uncertainties
Despite the positive trajectory, several uncertainties deserve attention. Raw material price swings can compress margins if pricing mechanisms lag cost increases. Regulatory expectations may tighten further or diverge across regions, complicating product planning and certification maintenance. Project delays in energy, utilities, or construction can affect order timing even when underlying demand remains intact. In addition, competition from lower-cost suppliers may intensify in non-hazardous and standard industrial applications, pressuring incumbents to defend value through service, certification, and performance credibility rather than price alone. These risks do not negate the growth outlook, but they highlight the need for disciplined portfolio management and scenario-aware sourcing strategies.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Focus portfolio strategy on application clarity rather than broad volume claims. Identify the highest-value use cases where certification, material durability, and sealing reliability directly influence buying decisions, and align product development, documentation, and channel messaging accordingly. Evaluate SKU complexity with an eye toward both cost efficiency and field usability; reducing unnecessary variants can improve production stability while preserving the configurations that matter most to key segments. Strengthen certification and approval readiness as a commercial capability, not just a technical requirement, because it influences specification speed, project eligibility, and buyer confidence.
For Investors and Strategic planners
Assess companies through the lens of application exposure, compliance breadth, and supply chain resilience. Revenue tied to industries with sustained modernization cycles and hazardous-area requirements may offer more durable growth characteristics than exposure concentrated in highly price-sensitive segments. Pay attention to material mix, production flexibility, and regional distribution strength, since these factors shape margin stability and responsiveness to cost fluctuations. Where possible, prioritize businesses that can demonstrate a clear link between product differentiation and operational value for end users, because that link typically supports pricing discipline and customer retention.
For Procurement and Engineering Teams
Treat cable gland selection as a system-level decision with implications for safety, maintenance, and installation efficiency. Standardize where possible to reduce complexity, but preserve material and certification options for environments that demand them. Evaluate suppliers not only on unit price, but also on approval documentation, compatibility with cable types, protection ratings, and field service support. Where projects span multiple regions or regulatory regimes, prioritize products that simplify compliance verification and reduce the administrative burden of multi-approval procurement.
For organizations that need a deeper, segment-level view of revenue splits, regional dynamics, material trends, and competitive positioning, broader market research can provide the additional granularity required for detailed planning and custom go-to-market decisions. A structured research deep-dive can help translate these strategic themes into specific product priorities, sourcing strategies, and investment screens tailored to the relevant industry and geography.
For detailed analysis of this topic, please visit the official page: Cable Glands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Gel Batteries Market: Strategic Trends and Commercial Opportunities Through 2032
The global gel batteries market has transitioned from a niche energy storage solution to a foundational component of modern infrastructure. With a base-year valuation of $2.49 billion in 2025 and a projected expansion to $4.04 billion by 2032, the sector is consolidating its position at a compound annual growth rate of 7.2 percent. This trajectory reflects a market that has moved beyond early-adopter status and is now embedding itself into telecommunications networks, renewable energy installations, and motive power applications. The growth profile signals maturity, but maturity does not equate to stagnation. Instead, it indicates a phase where strategic positioning, technological differentiation, and supply chain resilience will separate winners from followers.
Behind the headline numbers lies a complex operating environment. Gel batteries, particularly valve-regulated lead-acid variants, offer distinct advantages in safety, maintenance reduction, and thermal stability compared to traditional flooded designs. These attributes have made them attractive for stationary deployments where reliability outweighs the pursuit of maximum energy density. Yet the market is not operating in a vacuum. Technological competition, shifting regulatory frameworks, and evolving end-user expectations are reshaping how value is created and captured. Organizations that understand the structural forces driving demand will be better equipped to allocate capital, design product roadmaps, and mitigate exposure to cyclical or regulatory disruptions.
Tubular GEL Battery Market
The following analysis examines the market's current reality, the forces accelerating change, the competitive dynamics defining the landscape, and the strategic implications for decision-makers navigating the next five to seven years.
Market Snapshot: Scale, Growth, and Structural Reality
The gel batteries market has demonstrated consistent expansion over the past half-decade, growing from approximately $1.0 billion in 2020 to $2.49 billion in 2025. The forecast horizon through 2032 points to a market crossing the $4 billion threshold, with annual growth stabilizing at a mid-single-digit rate. This progression suggests a market that has escaped the volatility of early-stage adoption and entered a phase where incremental demand from infrastructure projects, energy transition initiatives, and mobility applications compounds year over year.
PW Consulting
Regional distribution reveals a balanced but uneven landscape. Asia Pacific commands the largest share of total market value, reflecting rapid deployment of renewable energy systems, expanding telecommunications networks, and growing industrial activity across multiple economies. Europe and North America follow as significant contributors, each anchored by mature industrial bases and policy-driven energy storage mandates. Latin America and the Middle East and Africa represent smaller but strategically important niches, often characterized by off-grid and remote power requirements where gel batteries' durability and low maintenance profiles align with local operating conditions.
In terms of application segmentation, stationary use cases represent the dominant share of market activity, encompassing telecom backup power, renewable integration, and utility-scale storage deployments. Motive applications, including material handling, marine operations, and commercial fleet electrification, form a substantial secondary segment that is gaining momentum as operators seek safer, longer-life alternatives to conventional battery chemistries. Across both categories, the underlying pattern is consistent: gel batteries are being specified not as the cheapest option, but as the most reliable fit for environments where downtime, safety, and lifecycle costs carry significant operational and financial weight.
Polymer Gel Market
The Key Challenges Shaping the Market's Next Phase
Three structural challenges define the current inflection point for gel batteries. The first is the intensifying competition from alternative energy storage chemistries. Lithium-based systems, sodium-ion developments, and emerging solid-state prototypes continue to capture attention in applications where energy density, rapid charge cycles, or space constraints dominate decision-making. While gel batteries hold strong advantages in safety, cost predictability, and proven reliability, they are not immune to substitution pressure. The challenge for incumbents is not to outperform every alternative in every metric, but to sharpen the value proposition in applications where gel technology's specific attributes deliver unambiguous total-cost-of-ownership benefits.
The second challenge lies in navigating evolving regulatory and compliance expectations. Industry-wide adoption of valve-regulated lead-acid gel technology is increasingly tied to carbon tax policies, emission reduction goals, and energy storage standards that vary across jurisdictions. At the same time, quality and environmental management frameworks such as ISO 9001 and ISO 14001 have become baseline requirements for production facilities, raising the operational bar for manufacturers seeking to enter or expand within regulated markets. These standards create a higher threshold for market participation, which can protect established players from low-quality entrants but also adds cost and complexity for organizations scaling production or entering new regions.
The third challenge involves supply chain continuity and critical mineral dynamics. Lead remains the core material underpinning gel battery construction, and its availability, pricing, and recycling infrastructure directly influence manufacturing economics and margin stability. While ongoing mining and recycling efforts by major producers support supply chain stability, the market remains sensitive to geopolitical disruptions, environmental permitting timelines, and shifts in raw material trade flows. Companies that treat lead sourcing and recycling as strategic capabilities rather than back-office procurement tasks will be better positioned to manage cost volatility and maintain production continuity.
Drivers Accelerating Market Evolution
Technology innovation continues to be a primary catalyst. Advances in gel electrolyte formulation, plate design, and valve-regulated architecture have improved deep-cycle performance, extended service life, and enhanced thermal resilience. These improvements are particularly relevant for renewable energy storage and telecom backup, where batteries must withstand frequent charge-discharge cycles and operate reliably in challenging environmental conditions. Recent product introductions illustrate how manufacturers are translating technical progress into commercially relevant outcomes. For example, new high-capacity gel battery designs targeted at grid storage and renewable integration projects have expanded the usable performance envelope for stationary deployments, while modular gel systems for commercial electric vehicle fleets have emphasized safety and lifecycle durability in motive applications.
Policy and regulatory frameworks are reinforcing demand in specific sectors. Targeted renewable energy subsidies, grid code updates, and utility-scale storage mandates continue to support deployment of gel battery systems where long-duration reliability and safety certifications matter. Carbon-related policies and emission reduction goals in multiple regions also favor valve-regulated lead-acid gel technology as part of broader decarbonization strategies. These policy signals do not guarantee uniform growth, but they do create predictable pockets of demand that manufacturers and investors can plan around, provided they align product specifications and compliance documentation with local requirements.
Demand-side behavior is shifting as end-users increasingly prioritize lifecycle economics over upfront price. Telecommunications operators, renewable energy developers, and industrial facilities are evaluating storage solutions through the lens of maintenance burden, failure risk, replacement frequency, and safety compliance. Gel batteries' sealed design, reduced gassing, and lower maintenance requirements resonate with operators managing distributed assets across wide geographies or constrained access conditions. In motive applications, fleet operators exploring commercial electrification are weighing gel-based options for their safety profile and deep-cycle capability, particularly in environments where thermal runaways or hazardous incidents carry unacceptable operational or reputational costs.
Supply chain and cost structure dynamics are also reshaping competitive positions. Manufacturing capacity expansions, investments in process optimization, and the formalization of recycling loops are influencing both cost efficiency and supply resilience. Recent capacity-related investments signal that leading manufacturers are positioning for sustained demand rather than treating current orders as temporary spikes. At the same time, the emphasis on certified production environments and documented quality systems adds a layer of operational discipline that favors organizations with established management systems and supply chain transparency.
Competitive Landscape: Positioning, Strategy, and Evolution
The gel batteries market is characterized by a concentrated but diversified competitive field. A handful of large, internationally active manufacturers account for a substantial share of total market value, while a broader set of regional and application-focused players compete on specialization, service, and local market knowledge. This concentration creates a landscape where scale, technical credibility, and application expertise all matter, and where the distance between leaders and followers is defined less by raw production volume than by the ability to match technology to end-user requirements.
Several companies illustrate the strategic diversity within the market. Exide Technologies has emphasized patented gel valve-regulated lead-acid technology for deep-cycle applications spanning marine, equipment, renewable energy storage, and industrial uses, and has signaled capacity expansion to serve renewable energy and telecommunications demand. Trojan Battery Company has built a reputation around deep-cycle gel batteries for solar, marine, and off-grid renewable energy systems, positioning its products for environments where cycle life and field reliability are paramount. East Penn Manufacturing's Deka Ready Power gel line targets motive power and renewable applications, reflecting a strategy that bridges industrial mobility and stationary storage. GS Yuasa Corporation focuses on gel lead-acid batteries for industrial, renewable, and telecom energy storage, leveraging its broader industrial battery heritage. Amara Raja Batteries has concentrated on gel solutions for industrial and renewable energy storage, aligning with regional demand patterns in its home market and adjacent export opportunities. Sonnenschein Batteries, operating within the Exide Group framework, has highlighted high-capacity gel batteries for grid storage and renewable integration, reinforcing the stationary storage emphasis. Enersys addresses both motive and stationary energy storage through gel technology, while Banner Batteries serves industrial and renewable energy use cases with a focus on application-specific performance.
The strategic positioning of these players reveals several common themes. First, application specialization is a recurring differentiator. Rather than competing solely on volume, many leading manufacturers build credibility by optimizing gel formulations, terminal designs, and housing configurations for specific duty cycles and environmental conditions. Second, product architecture is evolving toward modularity and integration-friendly designs, especially in stationary and fleet applications where scalability, serviceability, and system-level compatibility reduce deployment friction. Third, investment in manufacturing capacity and research infrastructure indicates a forward-looking posture. Recent developments, such as dedicated R&D centers focused on next-generation gel chemistry and manufacturing processes, alongside capacity expansions and new product launches for grid storage and commercial fleet use, suggest that incumbents are preparing for sustained demand rather than short-lived cycles.
The market structure appears likely to evolve along two parallel paths. Consolidation may continue as larger manufacturers acquire complementary technologies, regional distribution capabilities, or application-specific product lines to strengthen their positions in high-growth segments. At the same time, differentiation and fragmentation may persist in niche application areas where specialized formulations, local service networks, or compliance expertise create defensible positions. New entrants face a challenging environment because quality certification, supply chain credibility, and application testing create meaningful barriers, but targeted innovation in electrolyte chemistry, manufacturing efficiency, or system integration can still open focused opportunities.
Looking Ahead: Three Trends to Watch and the Opportunities They Create
The first trend is the deepening integration of gel batteries into renewable energy and grid-support infrastructure. As utilities, independent power producers, and commercial energy consumers expand storage portfolios, gel batteries are well positioned for applications that value safety, predictable performance, and lower maintenance overhead. The opportunity here lies not in claiming superiority over every alternative chemistry, but in designing system-level solutions that combine gel storage with appropriate inverters, monitoring, and thermal management to deliver reliable, compliant installations. Organizations that can package storage capability as a complete, configurable solution rather than a standalone component will capture more value and reduce deployment risk for end-users.
The second trend is the growing relevance of gel batteries in motive and commercial fleet applications. Modular gel systems designed for commercial electric vehicle fleets reflect an emerging recognition that safety, cycle life, and operational robustness can outweigh pure energy density considerations in certain duty cycles. This creates opportunities for manufacturers and integrators to develop application-specific packs, charging protocols, and service models that address fleet operators' practical concerns. The commercial prize is likely to accrue to players who can demonstrate verified lifecycle performance, predictable replacement intervals, and integration with fleet management systems, rather than those who compete only on specification sheets.
The third trend is the strengthening of standards, certification, and sustainability expectations as market norms. As quality and environmental management requirements become embedded in procurement decisions, and as energy storage standards continue to mature, compliance capability will increasingly function as a competitive asset. This favors organizations that can document manufacturing consistency, environmental responsibility, and product traceability with credibility. It also creates a subtle but important opportunity: in markets where procurement teams face reputational, regulatory, or safety scrutiny, the ability to provide clear certification and lifecycle documentation can influence specifications as much as price or performance.
These trends carry inherent uncertainties. Substitution from emerging chemistries could accelerate in applications where weight, footprint, or charging speed dominate. Regulatory frameworks may shift in ways that alter subsidy structures, grid interconnection rules, or compliance burdens, changing the economics of deployment in specific regions. Raw material dynamics, including lead availability and recycling efficiency, will continue to influence cost stability and margin resilience. The commercial implication is not to assume linear growth, but to build flexibility into product planning, supply chain design, and geographic prioritization so that strategy can adapt as conditions evolve.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to sharpen application-specific value propositions while strengthening the operational foundations that support scale. This means investing in product architectures that align with the duty cycles and environmental conditions of target segments, expanding capacity and process efficiency where demand signals are durable, and treating quality certification and supply chain transparency as strategic capabilities rather than administrative tasks. Companies should also evaluate where modular, integration-friendly designs can reduce customer deployment friction and create more defensible positions in stationary and motive applications. Where feasible, partnerships with system integrators, renewable energy developers, or fleet operators can translate product strength into installed-base advantage.
For investors, the market presents a profile that rewards disciplined segmentation and operational due diligence. The broad growth trajectory is attractive, but value creation will likely concentrate in companies that combine credible technology, certified production, and application-focused go-to-market strategies. Due diligence should examine not only top-line momentum but also the specificity of product offerings, the strength of manufacturing and recycling capabilities, the clarity of compliance documentation, and the durability of demand in targeted end markets. Portfolios that distinguish between generalized battery producers and organizations with clear gel-specific differentiation are more likely to capture the market's structural upside while limiting exposure to broader chemistry competition.
For procurement and operational decision-makers, gel batteries should be evaluated through a total-cost-of-ownership lens that accounts for maintenance burden, safety requirements, lifecycle expectancy, and compliance risk. In environments where downtime, hazardous incident risk, or maintenance access constraints carry significant cost, gel-based solutions may justify their selection even when alternative chemistries appear competitive on initial price or energy density. Procurement teams should request application-relevant performance data, certification documentation, and lifecycle service expectations, and should align specifications with the operational realities of deployment rather than generic benchmark comparisons. Where projects involve grid integration, telecom backup, or fleet usage, working with suppliers who can provide configurable, documented, and service-ready solutions will reduce downstream risk.
The strategic value of detailed intelligence in this market is substantial. Market growth, competitive moves, policy shifts, and technology developments are unfolding at a pace that makes broad generalizations insufficient for planning. Organizations that need granular segmentation data, company-level benchmarking, regional demand filters, or scenario-based forecasting will benefit from structured research that connects macro trends to specific operational decisions. For those evaluating market entry, capacity planning, partnership opportunities, or procurement specifications, a comprehensive report can provide the detail necessary to move from directional confidence to precise execution.
For detailed analysis of this topic, please visit the official page: Gel Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
$125B Regenerative Medicine Market: Why 22.5% CAGR and Oncology Demand Redefine Growth
By PW Consulting, 2026-09-21
Regenerative Medicine Market: Strategic Shifts and Commercial Opportunities in a High-Growth Sector
Market Landscape and Core Challenges
The regenerative medicine market has entered a phase of accelerated expansion defined by sustained capital deployment, expanding clinical applications, and maturing development pathways. Valued at $30.0 billion in 2025, the market has grown at a rapid pace over the past five years and is projected to reach $125.0 billion by 2032, reflecting a compound annual growth rate of 22.5 percent over the forecast period. This trajectory reflects more than incremental adoption; it signals a structural shift in how biopharma developers, medical device companies, and healthcare systems approach tissue repair, disease modification, and personalized intervention.
Behind the headline numbers, the competitive landscape remains moderately concentrated. The top three players command roughly 45 percent of market revenue, while the top five account for approximately 62 percent. This concentration points to a sector where scale, manufacturing capability, and regulatory experience still confer meaningful advantages. Yet the same dynamics leave substantial room for disciplined new entrants and specialized innovators, particularly in indications where clinical differentiation and manufacturing execution can outweigh raw market share.
Three challenges are shaping the sector’s near-term inflection points:
Stem Cells Market
- Manufacturing complexity and cost variability. Cell and gene therapies continue to rely on highly specialized, often labor-intensive production processes. Batch-level manufacturing economics vary widely depending on modality, starting material sourcing, and scale, making cost predictability a persistent operational hurdle.
- Reimbursement inconsistency and access barriers. High therapy prices, combined with uneven reimbursement frameworks across markets and indications, constrain commercial uptake. The challenge is especially pronounced for therapies requiring advanced manufacturing infrastructure, cold-chain logistics, and patient-specific workflows.
- Regulatory pathways in transition. Agencies are creating faster routes for serious conditions, but these pathways demand rigorous evidence packages, clear development strategies, and nimble responses to evolving expectations. Sponsors that can align clinical design, manufacturing strategy, and regulatory engagement early gain a distinct advantage.
For enterprise leaders, these challenges are not merely operational friction. They influence capital allocation, partnership structures, geographic rollout decisions, and the pace at which innovation can be converted into sustainable revenue.
Key Drivers Shaping the Market
The regenerative medicine market is being propelled by several interrelated forces that go beyond general industry momentum. Understanding how these drivers interact is essential for identifying where value is created and where execution risk concentrates.
Technological Innovation and Clinical Breakthroughs
Innovation is expanding both the therapeutic envelope and the operational playbook. Advances in cell engineering, gene delivery, scaffold design, and manufacturing science are enabling more targeted interventions across oncology, musculoskeletal repair, wound care, and rare disease. Importantly, the strongest commercial momentum often comes from therapies that combine a credible mechanism with a feasible manufacturing strategy and a clear patient-selection approach.
Recent developments illustrate this dynamic. In late 2025, the FDA issued draft guidance on expedited programs for regenerative medicine therapies for serious conditions, reinforcing the relevance of RMAT designations and accelerated approval pathways. That regulatory signal is not just procedural; it shapes how developers prioritize indications, design evidence packages, and sequence development steps. At the same time, high-profile approvals continue to validate the model. In early 2026, regulatory milestones included expanded-use decisions for gene therapy in spinal muscular atrophy and the first taxpayer-funded therapy developed through a state-backed research program, demonstrating how public funding, nonprofit leadership, and commercial manufacturing can intersect in modern development models.
Regulatory and Policy Environment
Policy is increasingly a competitive variable rather than a back-end compliance issue. Regulators are signaling greater flexibility in select areas while maintaining high expectations for safety and product characterization. In January 2026, for example, the FDA announced increased flexibility on CMC requirements for cell and gene therapies, including more permissive release criteria in investigational applications and reduced comparability data expectations in certain scenarios.
This evolution creates opportunity for sponsors that can build regulatory strategy into their development thesis from the outset. It also raises the stakes for organizations that treat CMC, release testing, and comparability as afterthoughts. Faster pathways can shorten time-to-market, but they still require disciplined evidence generation, robust manufacturing controls, and careful post-approval planning.
Demand-Side Shifts and Unmet Clinical Need
Demand is being reinforced by genuine clinical gaps across multiple indications. Musculoskeletal regeneration, oncology, and wound management continue to represent substantial areas of opportunity, each with distinct patient populations, treatment pathways, and reimbursement dynamics. Across these applications, the commercial pull is strongest where regenerative approaches can offer durable benefit, reduced downstream care burden, or alternatives where existing options are limited.
At the same time, adoption depends on more than clinical promise. Providers and payers weigh operational feasibility, treatment logistics, and total cost of care. Therapies that can demonstrate not only efficacy but also manageable delivery requirements and predictable patient access are more likely to scale in real-world settings.
Supply Chain Constraints and Cost Structure Pressures
The sector’s growth is also being shaped by supply-side realities. A significant share of manufacturers relies on imported key starting materials, and the patient-specific nature of many therapies compresses the window between collection, manufacturing, and delivery. These factors increase vulnerability to disruption and make resilience a strategic priority rather than a procurement afterthought.
Cost pressure is equally important. Manufacturing economics remain highly variable across modalities and batch sizes, with labor intensity, specialized expertise, and limited scalability for smaller patient populations all contributing to wide cost ranges. This does not mean the sector is inherently unprofitable, but it does mean that margins and long-term viability depend heavily on process design, standardization, and the ability to scale selectively without sacrificing quality or speed.
Competitive Landscape and Leading Strategies
The competitive field spans global biopharma, specialized cell and gene therapy developers, tissue-engineering companies, and innovators in advanced wound and musculoskeletal care. The result is a market that combines deep breadth with sharp differentiation. Not all participants are competing on the same axis, and the winners are increasingly defined by clear strategic positioning rather than broad presence alone.
Several patterns stand out among leading organizations:
- Scaling established modalities with strong clinical franchises. Large global players continue to build on platforms in cell therapy and gene therapy where they already have clinical data, commercial infrastructure, and regulatory familiarity. Their advantage often lies in combining product depth with the ability to support manufacturing, market access, and global rollout.
- Focusing on indication-specific differentiation. Some companies compete by narrowing their footprint to areas where they can build a strong technical and clinical narrative. Tissue-engineered products, scaffolds, and regenerative matrices are natural examples, where surgical workflow integration, product reliability, and clinical evidence can drive adoption in specific procedural settings.
- Pursuing platform and manufacturing leverage. Other organizations emphasize process capability, allogeneic approaches, or manufacturing efficiency as the basis for long-term competitiveness. In a sector where production constraints can limit reach, an organization’s ability to standardize, scale selectively, and reduce cost variability can become a durable moat.
- Expanding through partnership and targeted progression. High-impact submissions and prioritized regulatory reviews show that late-stage execution still matters enormously. A successful resubmission, prioritized review, or expansion into a broader patient population can reset a company’s commercial trajectory quickly, especially when paired with operational readiness.
The field is also changing shape. Consolidation pressures are building where scale, manufacturing sovereignty, and market access capabilities matter most. At the same time, fragmentation persists in niche modalities and specialized applications, allowing smaller innovators to compete through superior product design, focused clinical positioning, or differentiated manufacturing approaches. New entrants that can bring credible science alongside operational discipline remain viable, but the bar for execution is rising.
For decision-makers watching this landscape, the key question is not simply who is largest, but who is best positioned to capture value in a given segment. Competitive advantage is increasingly a function of three things: therapeutic differentiation that holds up in clinical and real-world use, manufacturing reliability that supports consistent supply and acceptable unit economics, and commercial infrastructure that can convert approval into durable adoption.
Future Outlook and Strategic Implications
Over the next three to five years, the regenerative medicine market is likely to be defined less by aggregate growth alone and more by the maturation of its internal structure. Three trends are especially relevant for strategic planning.
Trend 1: Scaling Will Depend on Manufacturing Discipline More Than Ever
As the market grows, the organizations that convert innovation into durable revenue will be those that can make sophisticated therapies reproducible, timely, and economically viable. That means tighter control over starting materials, improved process standardization, and more deliberate choices about allogeneic versus autologous approaches where appropriate. Companies that can reduce variability and improve throughput without compromising quality will be better positioned to expand indications, manage demand volatility, and support broader access.
Commercial opportunity: There is meaningful value in process innovation, supply resilience, and manufacturing partnerships. Enterprises that treat manufacturing as a strategic differentiator rather than an operational cost center are likely to gain optionality in both organic growth and external deal-making.
Trend 2: Regulatory Acceleration and Evidence Expectations Will Co-Evolve
Faster pathways for serious conditions will continue to attract development activity, but they will also intensify scrutiny around the quality of the evidence package and post-approval readiness. The expectation is not simply to reach approval faster, but to reach approval with a credible plan for characterization, manufacturing consistency, and real-world follow-through. Sponsors that align clinical design, regulatory strategy, and CMC early will have an advantage in both speed and durability.
Commercial opportunity: Regulatory strategy is becoming a gating factor for portfolio value. Early alignment with evolving agency expectations can reduce late-stage rework, improve the probability of successful progression, and strengthen positioning in negotiations with partners and access stakeholders.
Trend 3: Access, Reimbursement, and Health System Adoption Will Increasingly Shape Commercial Outcomes
Even compelling therapies face real-world friction if access is uncertain or delivery is operationally burdensome. As the field expands, health systems and payers will place greater weight on total cost implications, care pathways, and practical feasibility. That will reward therapies and commercialization models that account for patient selection, site readiness, logistics, and downstream care burden.
Commercial opportunity: Companies that design for access from the beginning, including site support, evidence generation for economic evaluation, and operational simplicity where possible, will have a better chance of translating clinical success into sustained adoption.
Stem Cell Therapy Market
These trends carry risk as well. Supply concentration, cost volatility, and uneven reimbursement can slow momentum even for clinically strong products. In addition, competitive intensity may rise in segments where early movers have already established familiarity and referral pathways. Organizations should therefore weigh not only therapeutic potential, but also the durability of their manufacturing, regulatory, and commercial positioning under stress.
Actionable Takeaways for Decision-Makers
The regenerative medicine market is expanding quickly, but the distribution of value will depend on execution quality across several fronts. Different stakeholders should emphasize different priorities.
For Manufacturers and Developers
- Build manufacturing resilience into your development thesis. Starting material sourcing, batch consistency, and release strategy should be treated as strategic variables, not just technical tasks.
- Choose indications and modalities with an eye toward feasible scale, patient selection, and evidence efficiency. A narrower, better-supported path can outperform an ambitious but fragile one.
- Align regulatory engagement with product strategy early, especially where flexibility is increasing but expectations remain high. Early clarity reduces costly rework later.
For Investors
- Evaluate not only the science, but also the path to reliable supply and acceptable unit economics. Manufacturing and CMC readiness can be decisive in late-stage value creation.
- Differentiate between therapies with strong clinical narratives and those with credible operational scalability. The two do not always overlap.
- Watch for regulatory momentum that affects development sequencing, but also monitor reimbursement and access dynamics that determine whether commercial potential becomes realized revenue.
For Procurement and Health System Leaders
- Assess regenerative therapies with a broader lens that includes site readiness, logistics, training, and downstream care implications, not just product efficacy.
- Prioritize suppliers and partners that demonstrate supply continuity, quality systems, and realistic delivery expectations, especially for patient-specific or temperature-sensitive products.
- Use evidence packages that account for total cost of care where possible, to support more informed adoption and contracting decisions.
The next phase of growth in regenerative medicine will reward organizations that can combine scientific ambition with operational discipline. Detailed segmentation data, company-level benchmarks, and indication-specific analysis can sharpen these decisions considerably, particularly for teams evaluating market entry, partnership strategy, or portfolio prioritization. For that level of granularity, the full PW Consulting research report provides expanded breakdowns and tailored recommendations designed for direct application in planning discussions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Regenerative Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GaN on Diamond Semiconductor Substrates Market 2026: 17% CAGR and Strategic Shifts Redefining RF Power Leadership
By PW Consulting, 2026-09-21
GaN on Diamond Semiconductor Substrates: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The GaN on Diamond semiconductor substrates market has entered a phase of accelerated expansion, driven by the compounding demands of high-frequency communications, defense electronics, and next-generation power systems. Measured in millions of U.S. dollars across a 2020 through 2032 horizon, the sector has moved from niche experimentation to commercial validation. Revenue grew steadily through the early 2020s as proof-of-concept devices gave way to production-grade architectures, and the pace quickened materially once supply ecosystems matured and end-users began certifying GaN-on-diamond components in operational systems. Forward projections indicate continued double-digit compound growth, with the market expected to cross the 90-dollar threshold by the early 2030s as edge deployments scale and thermal management requirements tighten across RF, microwave, and power applications.
This trajectory, however, is not uniform across value chains or geographies. The segment remains concentrated among a small group of established players who have invested early in substrate development, epitaxy compatibility, and bonding processes. Such concentration creates both momentum and friction: incumbents benefit from process know-how and early customer relationships, while the broader industry faces structural bottlenecks that complicate rapid scaling. Production of high-quality diamond wafers, particularly single-crystal variants, demands specialized chemical vapor deposition capabilities, stringent quality control, and capital-intensive cleanroom environments. Bonding GaN layers to diamond substrates without introducing defects or interfacial thermal resistance remains a disciplined engineering challenge, and yield optimization is still a differentiating factor rather than a commodity.
Three structural challenges now define the inflection point for this market. First, the thermal and electrical performance advantages of diamond substrates are well understood, but translating those advantages into repeatable, cost-effective manufacturing at volume remains uneven. Process variability, wafer-scale uniformity, and the economics of bonding and testing constrain the speed at which commercial programs can ramp. Second, demand is fragmenting across application profiles with different performance priorities. Some users prioritize maximum power density and thermal conductivity, while others require reliability at moderate performance levels with lower cost thresholds. This divergence complicates standardization and slows the emergence of common substrate specifications that could accelerate adoption. Third, supply resilience has become a strategic variable. The industry depends on a limited number of specialized synthesis and wafer processing nodes, which intensifies exposure to equipment availability, raw material readiness, and regional logistics dynamics. When those nodes face disruptions, even strong end-demand can be delayed by substrate availability rather than component design.
Taken together, the market is characterized by strong technological pull and uneven commercial readiness. The opportunity lies not only in demonstrating performance but in aligning substrate supply, bonding reliability, and application-specific design to create repeatable value chains.
Key Drivers Shaping the Market
The growth path for GaN on Diamond substrates is anchored in a combination of technical breakthroughs, regulatory momentum, demand-side evolution, and supply-side restructuring. Each driver reinforces the others, but not uniformly, and the interplay between them determines which segments scale first.
Technical innovation remains the primary catalyst. Advances in chemical vapor deposition have improved the purity, grain structure, and thermal conductivity of diamond substrates, which directly supports higher power density and lower junction temperatures in GaN devices. Alongside substrate improvements, progress in wafer bonding, interface engineering, and epi-layer compatibility has reduced the risk of performance degradation at the GaN-to-diamond interface. These advances matter because the value proposition of diamond is not just thermal conductivity in isolation; it is the ability to transport heat away from active regions under high-duty-cycle conditions without compromising RF performance or long-term reliability. Recent product launches and platform demonstrations reflect this trajectory, including new single-crystal wafers optimized for RF and power device applications, and power amplifier unveilings that emphasize reduced thermal resistance for satellite communications. The cumulative effect is closing the gap between laboratory potential and fielded hardware.
Policy and procurement dynamics are adding a second layer of support. Government programs and defense procurement pathways increasingly favor substrate and packaging technologies that extend performance envelopes in latency-sensitive, thermally constrained environments. Contracts and funding initiatives have reinforced interest in GaN-on-diamond integration for defense, radar, and hypersonic-related applications where thermal and power density requirements are explicit. This is not simply a question of subsidies; it shapes demand visibility, encourages investment in domestic capability, and signals long-term procurement preferences. In parallel, broader semiconductor support measures have influenced funding availability for satellite communications and advanced RF ecosystems, helping de-risk early-stage commercialization for companies pursuing diamond-cooling approaches. The practical impact is stronger demand forecasting and a higher tolerance for early-stage supply investment where the end-use case is strategically prioritized.
On the demand side, application behavior is changing in ways that favor higher-performance substrates. Satellite communications is expanding the need for compact, efficient RF front ends that can operate reliably under continuous load and in constrained thermal environments. Radar and millimeter-wave sensing systems increasingly require wideband performance and stable gain under temperature extremes, which makes thermal management a design driver rather than an afterthought. In commercial RF deployment, the push toward higher throughput and denser arrays also raises the thermal bar, encouraging component designs that would be difficult to sustain on conventional substrates alone. These shifts are not abstract; they translate into product roadmaps where substrate selection becomes part of system optimization, not a discrete component choice.
Single Crystal Diamond Market
Supply-side and cost dynamics complete the picture. Fabrication and bonding economics still place a premium on diamond wafer production, and the costs associated with CVD processes and bonding steps influence overall substrate pricing. At the same time, supply chain bottlenecks in diamond wafer production and high production costs constrain commercial scaling unless capacity and process maturity improve together. Regional imbalances in substrate availability have also emerged from geopolitical pressures and logistics disruption, which has prompted customers and manufacturers alike to consider diversification, near-shoring, and vertical integration strategies. These pressures are reshaping how companies plan capacity, qualification, and customer commitments. Notably, consolidation and partnership activity is increasing as firms seek to improve control over critical steps in the value chain, while consortium-based regional facilities are being advanced to support supply resilience.
Worldwide Synthetic Single Crystal Diamond Market
Competitive Landscape and Leading Strategies
The competitive field is defined by a handful of companies that have moved beyond material research into concrete product routes and targeted applications. The differences among them are less about whether GaN-on-diamond is promising and more about where each player chooses to compete: substrate supply, device integration, application focus, or vertical integration.
Element Six has built a reputation around synthetic diamond substrates and GaN-on-diamond technology for high-thermal-conductivity applications in RF, power, and defense electronics. Its strategic positioning leans on deep material expertise and controlled substrate quality, which supports customers seeking consistent performance in demanding environments. By launching ultra-high-purity single-crystal diamond wafers optimized for RF and power device applications, the company has reinforced its emphasis on material-grade differentiation as a foundation for downstream device performance.
Akash Systems has targeted satellite communications technology and related substrates, with a clear link between diamond-cooling concepts and space-grade or satellite RF performance. Securing funding tied to CHIPS Act support to advance diamond-cooling GaN-on-diamond satellite technology indicates a strategy aligned with public-sector programs and long-cycle satellite roadmaps. This positions the company where performance, thermal management, and mission-critical reliability intersect, rather than competing broadly across all RF applications.
Qorvo operates as both a components producer and an integrator in the RF and satellite space, manufacturing GaN-on-diamond transistors and power amplifiers. Its product unveiling of a GaN-on-diamond power amplifier for satellite communications that reduces thermal resistance reflects a device-level strategy: rather than selling substrate capability in isolation, it demonstrates how the substrate improves end-device performance metrics that matter directly to system designers. That route can shorten the adoption cycle because it ties substrate benefits to amplifier behavior customers can measure and specify.
RFHIC Corporation has focused on GaN-on-diamond epi wafers and technology for radar, microwave, and satellite uses. Its profile suggests a strategy oriented toward enabling partners and programs that require tailored epi and substrate combinations for high-frequency applications, including defense and satellite domains. This support-layer positioning can be strategically valuable when customers need integration flexibility or customized device structures rather than standard catalog products alone.
Coherent Corp. has moved into offering GaN-on-diamond wafers scaled for commercial RF applications, which points to a strategy centered on broader commercialization and volume orientation. Scaling for commercial RF implies a different balancing act between performance and cost compared with niche or defense-first approaches, and it suggests attention to process throughput, wafer consistency, and application breadth.
Blue Wave Semiconductor has commercialized GaN-on-diamond substrates for high-power RF and defense electronics, which places it in a space where thermal performance and power handling are central. Its commercial focus aligns with programs that need robust substrate performance under sustained high-power operation, again linking substrate choice to application risk management.
PW Consulting Information & Electronics Research Center
The landscape is evolving along several axes. Vertical integration is becoming more visible, as illustrated by an acquisition in the diamond synthesis space intended to strengthen control over upstream capability for GaN-on-diamond products. That move signals a recognition that substrate and material readiness can be a strategic bottleneck, not just a component specification. At the same time, consortium-based regional facilities are emerging to support supply chain resilience, reflecting a broader shift toward diversified capacity and regional redundancy. These developments suggest the market will likely see further consolidation where material control matters, while also encouraging new regional players or partnerships aimed at reducing dependency on limited supply nodes. Differentiation will increasingly come from application-tailored solutions, process maturity, and the ability to reduce thermal and reliability risk in real systems rather than from substrate claims alone.
Future Outlook and Strategic Opportunities
Looking ahead three to five years, the market is likely to move along a path shaped by scale, specialization, and supply-chain reorganization. The most consequential trend is the gradual shift from performance demonstration to production repeatability. As bonding yields, wafer uniformity, and qualifying standards improve, GaN-on-diamond will become less of an exceptional choice and more of a standard option in selected high-performance RF and power portfolios. That transition creates commercial opportunity for companies that can offer predictable supply, documented reliability, and design support that reduces integration risk for system manufacturers.
A second trend is the deepening linkage between substrate selection and application-specific program requirements. Defense, radar, satellite, and high-end communications will continue to push toward higher power density and thermal resilience, but they will not all value the same trade-offs. Some programs will prioritize maximum performance and tolerate complex supply or cost structures, while others will seek a balanced combination of performance, reliability, and cost. This divergence opens space for tiered offerings, application-focused qualification paths, and partnerships that align substrate supply with end-use certification timelines.
A third trend concerns supply resilience and regionalization. Given the concentration of specialized diamond wafer capability and the exposure created by logistics and geopolitical pressures, more customers and manufacturers are expected to prioritize regional availability, diversified sourcing, and tighter integration across material and device stages. Where that occurs, it creates opportunities for regional capacity initiatives, strategic partnerships, and vertically coordinated offerings that can promise steadier delivery and lower program risk.
These trends carry commercial upside, but they also include uncertainty. Yield and process consistency remain central risks, especially for single-crystal paths where scale-up is technically demanding. Cost structures may persist at elevated levels for advanced substrates, which can slow adoption in price-sensitive branches of the market. Demand timing can also diverge from supply readiness when procurement cycles, qualification requirements, or regional availability issues extend program schedules. The businesses that navigate this period most effectively will be those that treat thermal performance as a system-level advantage while building credible supply and qualification pathways around it.
Actionable Guidance for Decision-Makers
For manufacturers and device developers, the priority is to align substrate strategy with realistic production and qualification pathways rather than with performance claims alone. That means investing early in bonding reliability, thermal interface engineering, and application-specific testing that mirrors field conditions. It also means evaluating whether the target application truly requires the upper end of diamond thermal performance or whether a balanced substrate approach can meet requirements at better cost and availability. The most defensible strategies will connect device architecture, substrate selection, and supply readiness into one plan, so that performance gains do not stall at the interface between design and manufacturing.
For investors, the value lies in distinguishing between material promise and commercial readiness. Platforms with clear application anchors, credible supply strategies, and demonstrable progress in yield or integration tend to offer stronger strategic positioning than those relying on performance narrative alone. Attention should also be paid to consolidation patterns and regional capacity initiatives, since these can reshape competitive advantage by changing who controls critical nodes in the value chain. The key judgment is whether a company is building durable differentiation through process maturity and customer alignment, or whether its position depends on assumptions that have not yet been validated at scale.
For procurement and program leaders, the focus should be on supply risk, qualification timelines, and design support as much as on nominal performance. In applications where thermal limits shape system architecture, substrate availability and reliability can be as decisive as device specs. Evaluating suppliers in terms of consistency, capacity visibility, and integration assistance can reduce later schedule exposure and improve total system outcomes. Where programs span multiple regions or rely on constrained supply nodes, diversification and redundancy planning should be treated as part of the technical decision, not as a separate procurement exercise.
For decision-makers seeking a fuller picture of end-use segmentation, regional dynamics, competitive positioning, and scenario-based projections, a dedicated, detailed research view can provide the granularity needed for planning. In markets moving this quickly, detailed segmentation data and customized strategic interpretation are often what separate reactive positioning from proactive advantage.
For detailed analysis of this topic, please visit the official page: GaN on Diamond Semiconductor Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Embedded Non-volatile Memory Market: Why 11.54% CAGR and Automotive Demand Redefine Industry Growth
By PW Consulting, 2026-09-21
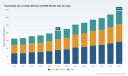
The Embedded Non-Volatile Memory Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The embedded non-volatile memory market has entered a phase of sustained expansion, underpinned by a compound annual growth rate of 11.54 percent across the forecast horizon. Revenue trajectories from 2020 through 2025 reflect steady acceleration, with the market advancing from approximately 163 million units of currency to 215 million. Forward projections extend this climb, reaching roughly 226 million in 2026 and surpassing 344 million by 2032. This growth is not merely cyclical; it represents a structural realignment in how semiconductor architectures handle persistent data storage, security, and in-field programmability.
Automotive Embedded Storage (eMMC and UFS) Market
Several interconnected challenges are reshaping the competitive baseline. First, the integration of advanced eNVM variants into next-generation system-on-chip designs introduces substantial layout complexity and extended verification cycles. Embedding memory requires additional intellectual property blocks, specialized design rules, and rigorous testing protocols that lengthen development timelines and increase engineering overhead. This friction disproportionately affects fabless design teams and smaller manufacturers that lack established process integration expertise.
PW Consulting
Second, manufacturing economics remain a persistent constraint. High-cost fabrication equipment and process steps that diverge from standard CMOS pathways create integration bottlenecks. Many foundries must adapt existing lines or invest in specialized modules, which raises capital expenditure and narrows the margin window for volume products. As a result, cost-per-bit advantages can be delayed until design maturity and factory yield optimization converge.
Third, reliability and qualification requirements are intensifying across safety-critical verticals. Automotive and industrial eNVM products must satisfy stringent temperature ranges, long-term data retention targets, and grade-level certifications that validate performance under extreme operating conditions. These demands favor mature or thoroughly validated memory technologies, yet simultaneously create barriers for emerging solutions seeking rapid adoption in high-trust segments.
Key Drivers Shaping Market Dynamics
Technological innovation in memory physics and integration methodologies is accelerating the shift toward alternative eNVM types. Resistive, magnetic, and ferroelectric approaches are gaining traction where conventional flash encounters scaling limits or endurance constraints. Demonstrations of embedded ReRAM integrated into mature BCD processes for mixed-signal and high-voltage applications illustrate how non-traditional nodes can host advanced memory for power management, analog-intensive, and high-reliability designs. Similarly, MRAM and RRAM integration into FinFET and FD-SOI platforms shows that memory types once reserved for niche use cases are becoming credible candidates for mainstream microcontroller and SoC implementations.
Regulatory and certification pressures are reinforcing demand for resilient storage in mission-critical applications. Automotive and industrial programs increasingly require qualification frameworks that guarantee operation across wide temperature envelopes and sustained data integrity over extended service life. In parallel, specialized material platforms and testing protocols are gaining attention for aerospace-grade and radiation-tolerant deployments, where memory must withstand environmental stressors that conventional solutions cannot reliably tolerate. These requirements do not simply raise the compliance bar; they reshape procurement priorities and elevate the strategic value of memory suppliers with proven qualification track records.
Demand-side shifts are also redefining the addressable market. The proliferation of connected devices, edge intelligence, and vehicle electrification is expanding the installed base of microcontrollers and processors that require on-chip persistent storage for configuration, firmware updates, cryptographic keys, and calibration data. Consumers and enterprises alike are expecting systems that can be securely updated in the field and that retain essential state information across power cycles. This behavior creates recurring pull for embedded memory that balances performance, endurance, and security without relying on external storage components that add board space, cost, and failure modes.
Supply-chain and cost-structure dynamics are influencing where and how eNVM is adopted. Foundry strategies that embed MRAM and ReRAM directly into advanced and mid-range process nodes are reducing design fragmentation and enabling more efficient IP reuse across product families. At the same time, geopolitical factors continue to diversify sourcing options, with multiple foundry ecosystems offering embedded memory capabilities to global manufacturers. This broadening of supply choices can improve resilience and pricing competitiveness, but it also requires buyers to evaluate process maturity, qualification status, and long-term roadmaps rather than assuming uniformity across vendors.
Competitive Landscape and Leading Strategies
The market features a diverse mix of semiconductor manufacturers, memory specialists, and foundry platforms, each pursuing distinct value-creation strategies. Samsung Electronics continues to develop embedded STT-MRAM and flash eNVM solutions for microcontrollers, systems-on-chip, and high-performance applications, leveraging scale and process expertise to integrate memory across multiple product tiers. STMicroelectronics has focused on embedding PCM and RRAM into FD-SOI microcontrollers for automotive and industrial use cases, emphasizing platform-level integration that aligns memory choice with architecture-level efficiency. Infineon Technologies combines embedded FRAM and RRAM within automotive AURIX controllers and edge ML microprocessors, targeting applications where reliability and real-time processing intersect.
NXP Semiconductors delivers embedded MRAM in automotive microcontrollers built on advanced FinFET processes in collaboration with leading foundries, reinforcing its position in safety-critical vehicle systems. Renesas Electronics offers embedded STT-MRAM and flash for industrial and IoT microcontrollers, aligning memory selection with broad vertical coverage and long product lifecycles. Texas Instruments supplies ferroelectric and flash-based embedded memory across microcontrollers and processors, reflecting a balanced approach that spans mature and emerging technologies. Microchip Technology manufactures embedded flash and NOR eNVM for embedded systems and microcontrollers, maintaining emphasis on broad deployability and design familiarity.
On the IP and specialized memory side, Weebit Nano licenses embedded ReRAM IP for integration into foundry platforms, with recent demonstrations and qualifications spanning multiple process nodes and design environments. Everspin Technologies supplies embedded and standalone MRAM for automotive, aerospace, and industrial applications, and has expanded its high-reliability portfolio to address extended temperature and endurance requirements. TSMC embeds MRAM and ReRAM directly into advanced FinFET processes for microcontrollers and systems-on-chip, enabling designers to access memory capabilities within leading-edge node offerings. GlobalFoundries integrates embedded MRAM and ReRAM into mature and specialized platforms for high-reliability designs, providing an alternative path for applications that prioritize robustness and customization over aggressive scaling.
Leading strategies converge around three themes. The first is platform-level integration, where memory is treated as an intrinsic capability of the process and device family rather than an afterthought, reducing integration risk and enabling repeatable product derivatives. The second is qualification and reliability leadership, particularly in automotive and industrial segments where certifications and long-term retention claims are decisive procurement criteria. The third is ecosystem expansion through licensing and multi-foundry enablement, which broadens adoption by allowing design teams to deploy a consistent memory IP across different manufacturing partners and node options.
The competitive landscape is evolving through a combination of consolidation among integrated suppliers and new entry via IP licensing and specialty memory providers. Established manufacturers continue to strengthen their process roadmaps and portfolio breadth, while memory-technology specialists are expanding the set of supported nodes and design environments. This dual dynamic creates both pressure and opportunity: incumbents must defend their integration advantages and qualification portfolios, while newer entrants can gain relevance by demonstrating multi-platform compatibility, cost-effective integration, and strong technical support. Over time, the market is likely to fragment by application requirements and process node strategy rather than converge into a single dominant memory type.
Outlook for the Next Three to Five Years
One clear trend is the broadening adoption of non-flash embedded memory types in mainstream microcontroller and SoC designs. As MRAM, ReRAM, FRAM, and related technologies demonstrate improved integration maturity and cross-platform compatibility, they are expected to capture additional share in applications that demand higher endurance, lower power during write operations, or enhanced security features. The commercial opportunity lies in enabling product families that can address multiple verticals from a common architecture, reducing time-to-market and simplifying lifecycle management for manufacturers.
A second trend is the deepening of qualification-led competition in automotive and industrial segments. Requirements for wide temperature operation, long data retention, and robust reliability will continue to favor suppliers that can document consistent performance and provide transparent qualification data. This creates an opportunity for differentiated positioning through documented reliability, application-specific reference designs, and support for in-field update and secure-boot scenarios. The risk is that qualification lead times and testing costs may slow adoption of newer memory types in the highest-tier safety applications, creating a bifurcated market where mature technologies retain a multi-year advantage in the most demanding tiers.
A third trend is the increasing strategic importance of foundry and process choice. As multiple ecosystems offer embedded MRAM and ReRAM capabilities, design teams will evaluate memory integration alongside node selection, power targets, and supply resilience. This trend favors suppliers that can provide predictable integration paths, multi-node availability, and clear migration options. The uncertainty arises from the uneven pace of process optimization across foundries and the potential for cost pressures if specialized equipment or steps remain difficult to scale economically. Buyers should therefore treat memory adoption as a joint decision with process strategy rather than a standalone component selection.
Strategic Recommendations for Decision Makers
For semiconductor manufacturers and design-house leaders, the priority is to align memory selection with architecture strategy and process roadmap. Embedding eNVM early in the design cycle can reduce integration complexity later, but only if the chosen memory type has a credible path to the target node and a clear qualification trajectory for the intended applications. Companies should map memory options against product-tier requirements, plan for extended verification where necessary, and invest in reference designs that demonstrate security, endurance, and in-field update capabilities. A disciplined approach that balances emerging memory benefits with proven reliability will improve competitiveness in automotive, industrial, and connected-device markets.
For investors and strategic analysts, the value lies in tracking differentiation signals rather than headline revenue alone. Indicators such as multi-node IP enablement, qualification progress in safety-critical segments, foundry partnerships, and portfolio expansion into high-reliability products provide early insight into which players are building durable advantage. Attention should also be paid to cost dynamics and integration complexity trends, since manufacturing economics can determine whether a promising memory technology achieves volume adoption or remains confined to premium niches. Monitoring these signals helps differentiate cyclical growth from structurally advantaged positions.
Worldwide eMMC Flash Chip Market
For procurement and product-planning teams, the practical move is to evaluate embedded memory as part of a broader system strategy that includes supply resilience, certification status, and lifecycle planning. Given the range of available technologies and node options, buyers should request detailed integration specifications, qualification documentation, and roadmap alignment before committing to a memory choice for long-lifecycle programs. Detailed, segment-level intelligence is essential for comparing alternatives across applications, regions, and process technologies without relying on assumptions that may obscure important differences in cost, reliability, and availability.
Timely access to granular market data, segmentation detail, and company-specific developments can materially improve planning accuracy and reduce execution risk. Comprehensive research that covers segmentation breakdowns, regional dynamics, and recent product and partnership activity provides the context needed to translate broad market growth into specific action plans. For teams evaluating entry, expansion, or sourcing decisions, a full structured study offers the depth required to assess opportunities with greater confidence and to align technology choices with commercial objectives.
For detailed analysis of this topic, please visit the official page: Embedded Non-volatile Memory (eNVM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nitrogen Gas Springs Market: Why the 5.7% CAGR and 657M Outlook Redefine Strategy
By PW Consulting, 2026-09-21
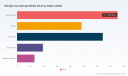
The Nitrogen Gas Springs Market: Strategic Shifts and Commercial Opportunities Through 2032
The nitrogen gas springs market has entered a phase of steady, structurally driven expansion. Valued at approximately 442.3 million USD in 2025, the market is projected to reach 657.3 million USD by 2032, reflecting a compound annual growth rate of 5.7 percent. This trajectory does not represent a cyclical rebound but rather a fundamental realignment of how downstream industries consume, specify, and integrate gas spring technologies. The historical volatility of the early 2020s has given way to a more predictable upward slope, yet the pace and composition of growth are being reshaped by digitalization, regulatory standardization, and shifting end-use demand profiles. For executives and investors navigating this space, the central question is no longer whether the market will expand, but how value will be captured across different segments, geographies, and technology tiers.
At the operational level, nitrogen gas springs have transitioned from commoditized tooling components to integrated elements within broader manufacturing and assembly ecosystems. Their role in metal stamping, injection molding, die making, and industrial machinery has been steadily reinforced by pressures for faster cycle times, higher precision, and safer tool handling. The market structure reflects this maturation, with a moderate concentration that leaves room for differentiated positioning. The top three players account for roughly 38 percent of revenue, while the top five collectively represent about 48 percent. This distribution indicates a landscape where scale matters, but technical specialization, regional proximity, and application-specific engineering remain decisive competitive levers.
Market Landscape and Core Challenges
The current market environment is defined by a tension between steady demand growth and structural friction points that constrain margin expansion and operational predictability. Three challenges stand out as particularly consequential for manufacturers, distributors, and downstream buyers.
First, the standardization framework is simultaneously a stabilizer and a constraint. Global specifications such as ISO 11901 govern dimensions, force ratings, and safety instructions for press tools and dies, while European deployments must align with PED 2014/68/EU compliance requirements. Additional mounting and interchangeability conventions, including VDI 3003 and CNOMO standards, further shape procurement and engineering workflows. These frameworks reduce integration risk and accelerate design cycles, but they also compress differentiation opportunities for suppliers that rely solely on mechanical performance. Companies that cannot embed compliance into their design and documentation processes face increasing friction in multi-region sourcing, while buyers must navigate a landscape where interchangeability is expected but not uniformly achieved across vendors.
Second, input cost volatility continues to pressure production economics. Steel prices fluctuate in response to supply chain disruptions, geopolitical tensions, and shifting demand patterns, and these movements translate directly into manufacturing cost variability for gas springs. Because many components rely on precision steel geometries, valve assemblies, and sealing systems, manufacturers operate in an environment where raw material exposure must be managed through hedging, supplier diversification, or engineered redesigns. The challenge is not simply higher prices, but the unpredictability that complicates long-term pricing commitments, inventory planning, and margin forecasting.
Third, the market is experiencing a functional shift from passive component supply to active performance monitoring and lifecycle management. Industry 4.0 initiatives in die tooling and stamping operations are driving interest in pressure and temperature telemetry, condition tracking, and predictive maintenance signals. This shift creates a transition cost for incumbents that lack digital integration capabilities, while also raising the bar for downstream adoption. Buyers increasingly expect components that can be monitored, serviced, and replaced with minimal downtime, which means the value proposition is expanding beyond force delivery to include reliability data, serviceability, and integration readiness.
Together, these challenges point to a market in which compliance, cost resilience, and digital capability are becoming baseline expectations rather than optional enhancements. Suppliers that treat these as separate initiatives will struggle to keep pace; those that integrate them into product architecture and commercial models will be better positioned to defend margins and capture share.
Key Drivers Reshaping the Market
The expansion path of the nitrogen gas springs market is being propelled by overlapping forces that influence both supply-side capabilities and demand-side behavior. Four drivers are particularly relevant for strategic planning.
Technological innovation and miniaturization pathways are expanding the functional envelope of gas springs. Standard nitrogen gas springs remain the volume backbone of the market, but compact, super compact, and micro variants are gaining relevance in applications where space constraints, weight sensitivity, and higher precision are critical. This is not merely a sizing trend; it reflects broader engineering demands in automotive tooling, aerospace assemblies, and advanced industrial machinery, where component packaging and force consistency must be optimized simultaneously. Manufacturers that can deliver reliable performance at smaller footprints, while maintaining safety and interchangeability, are able to enter design cycles earlier and secure specification preference.
Regulatory and standards-driven adoption is reinforcing demand in established industrial regions while also shaping entry barriers. Compliance with ISO 11901-5:2021, which specifies that only nitrogen in commercial-grade purity class 5.0 should be used to charge gas springs for stamping dies, provides a clear technical baseline and reduces ambiguity in procurement. PED 2014/68/EU requirements add another layer of assurance for European machinery and tooling applications. For suppliers, these standards create a credible quality narrative and reduce the risk of non-conforming installations. For buyers, they simplify specification and reduce integration risk. The net effect is a market where conformance becomes a competitive asset, particularly in sectors where safety, repeatability, and auditability are non-negotiable.
Demand-side shifts in automotive and aerospace tooling are reshaping application priorities. Automotive remains the largest application segment, reflecting the continued intensity of stamping, forming, and mold-based production across vehicle platforms. Aerospace continues to contribute a meaningful share of demand, driven by precision components, stricter performance tolerances, and higher lifecycle expectations. These sectors are not simply buying more gas springs; they are specifying them with greater attention to contamination resistance, slow-return behavior, high-temperature capability, and long-term reliability. As vehicle architectures evolve and aerospace programs demand more consistent tooling performance, gas springs are increasingly evaluated as part of a broader system-level reliability strategy rather than as isolated consumables.
Air Springs Market
Supply chain reconfiguration and cost structure adaptation are altering how manufacturers compete on availability, lead time, and total cost of ownership. In a market where steel price volatility and logistics uncertainty can erode planned margins, suppliers are responding with tighter inventory models, regional warehousing, and broader standard catalogs that enable faster fulfillment. The ability to offer steel and stainless steel variants, standardized mounting dimensions, and interchangeable designs is becoming a practical differentiator for procurement teams seeking to reduce downtime and simplify spare-part management. At the same time, manufacturers are re-examining BOM sensitivity, sealing technologies, and cylinder protection features to reduce vulnerability to contamination and premature wear, which lowers total maintenance burden over the life of the tool.
These drivers interact in practical ways. A compact or micro spring that meets ISO dimensions and is designed for contamination-resistant operation can unlock adoption in tighter industrial layouts. A product line that pairs compliance with stainless or steel variants and rapid fulfillment can reduce procurement risk in regions exposed to input cost swings. A digitally enabled series with integrated monitoring can align gas springs with broader Industry 4.0 tooling strategies. The strategic implication is that competitive advantage is increasingly cumulative: performance, compliance, availability, and intelligence must reinforce one another.
Competitive Landscape and Leadership Strategies
The competitive field is anchored by a mix of specialized manufacturers with strong regional footprints and global reach. Several companies illustrate the strategic directions currently shaping the market.
DADCO has built a broad portfolio spanning micro to very high-force nitrogen gas springs for stamping, injection molding, and tooling, with ISO-compliant series and a strong automotive OEM supply presence. Its recent move into IoT-enabled springs with integrated pressure and temperature monitoring reflects a push toward die tooling solutions aligned with Industry 4.0. The strategic logic is clear: by combining scale, specification breadth, and telemetry, the company positions itself not only as a component supplier but also as a partner in process visibility and tool management.
Special Springs has emphasized in-house manufacturing, safety-oriented designs such as OSAS, OPAS, and SKUDO, and interchangeable replacement capability for heavy-duty industrial and stamping applications. Recent updates include the Skudo-Flex accessory to extend cylinder life, a new US Series catalog, and improved reducer options for contaminated environments. The company is also actively supporting trade exhibitions with dedicated event kits. This approach underscores a strategy centered on durability, serviceability, and market engagement, with particular attention to environments where contamination and heavy-duty cycling raise failure risk.
Gas Spring Market
Hyson Products provides a full line of nitrogen gas springs for metal stamping dies, injection molds, and custom machines, including high-force, slow-return, and contamination-resistant models. Its breadth of force and functional variants suggests a focus on application flexibility and process-specific performance, which is valuable in shops where tooling requirements vary widely across jobs and material types.
Pascal Engineering Corporation supports manufacturers with nitrogen and mini gas springs for stamping dies and injection molding, emphasizing high-quality components that contribute to safety and productivity. Its positioning is aligned with manufacturers seeking dependable, application-focused components in precision workflows.
KALLER offers high-performance nitrogen gas springs for tool and die applications, including high-temperature variants capable of operating up to 250°C for hot stamping. This capability addresses a niche but strategically important requirement in processes where thermal exposure would limit conventional components.
Bordignon, with a history dating back to 1958, is known for longevity, reliability, and innovation in stamping and forming, reinforcing a value proposition built on proven performance and incremental improvement over time.
Isotech, Gemini Gas Springs, AZOLGAS, and FIBRO each contribute distinct angles to the market. Isotech emphasizes complete gas spring lines in steel and stainless steel variants for industrial applications. Gemini focuses on in-house manufactured lift supports and dampers meeting high industrial standards. AZOLGAS provides extensive catalogs and safety-compliant designs for metal stamping and multi-technology applications. FIBRO distinguishes itself through a large standard catalog and same-day delivery from a central European warehouse, which directly addresses availability and lead-time sensitivity.
Taken together, the competitive landscape reveals several differentiation pathways. One is application breadth and force range, where suppliers aim to cover everything from micro springs to very high-force units and thereby become a default specification source across multiple tooling contexts. Another is durability and safety engineering, where cylinder protection, contamination resistance, and interchangeable designs reduce downtime and simplify maintenance. A third is digital and lifecycle integration, where monitoring and telemetry align gas springs with modern tooling and maintenance strategies. A fourth is availability and fulfillment speed, where large standard catalogs, regional warehousing, and same-day delivery reduce procurement friction for time-sensitive production environments.
The market structure suggests a moderate trend toward consolidation at the top, but also continued room for differentiation among specialized players. Larger, broadly positioned suppliers can leverage scale, multi-region presence, and digital features to capture share in standardized, high-volume applications. Specialized manufacturers can compete on heavy-duty reliability, temperature resilience, contamination handling, and custom solutions in niche or demanding contexts. New entrants face a meaningful bar because compliance, interchangeability expectations, and established supplier relationships raise switching costs. At the same time, the growing emphasis on monitoring, safety, and lifecycle service creates openings for companies that can bundle component performance with operational intelligence or service support.
Forward-Looking Trends and Commercial Implications
Looking ahead to 2032, three trends are likely to shape how the nitrogen gas springs market evolves and where commercial opportunities emerge.
Trend one: digital integration will move from pilot adoption to procurement expectation in advanced tooling environments. As stamping and molding operations pursue traceability, condition monitoring, and predictive maintenance, gas springs equipped with pressure and temperature monitoring will become more relevant in high-value tooling programs. The commercial opportunity lies not only in selling smart components, but in linking component data to tool management workflows, service scheduling, and downtime reduction. Suppliers that can demonstrate measurable reliability benefits and seamless integration with existing tooling systems are likely to secure stronger specification preference in automotive, aerospace, and advanced industrial applications. The risk is that digital features may be over-specified in contexts where basic mechanical performance and compliance already suffice, creating cost and complexity without proportional return.
Trend two: high-temperature, contamination-resistant, and compact designs will capture incremental share in demanding applications. Hot stamping, harsh environments, and space-constrained tooling layouts will continue to reward designs that balance force delivery with environmental resilience and packaging efficiency. High-temperature variants, slow-return models, and contamination-resistant configurations are positioned to benefit as manufacturers seek to extend tool life and reduce failure-driven interruptions. The commercial opportunity here is application-led differentiation: suppliers that can validate performance in specific process conditions and offer interchangeable or protective accessories can build sticky relationships with tooling engineers and maintenance teams. The uncertainty lies in how quickly these features become standard expectations versus remaining specialized upgrades, which will affect pricing power and margin trajectories.
Trend three: availability, standardization, and material-cost resilience will become central to competitive positioning. With steel price volatility and supply chain disruption remaining part of the operating environment, the ability to provide steel and stainless variants, standardized dimensions, and fast fulfillment will matter increasingly to procurement teams. Large standard catalogs, regional inventory, and interchangeability aligned with recognized mounting conventions can reduce total sourcing risk and simplify spare-part management. The commercial opportunity is to compete on total cost of ownership rather than unit price alone, especially for buyers managing multiple plants, diverse tooling portfolios, and tight production schedules. The risk is that aggressive standardization may pressure margins if not paired with volume scale, efficient logistics, or value-added services that distinguish one supplier from another.
These trends point to a market where growth is likely to be underpinned by reliability, compliance, and integration rather than by volume expansion alone. The most durable opportunities will be those that align technical features with real operational outcomes: less downtime, safer tool handling, better condition visibility, and lower lifecycle maintenance burden.
Strategic Guidance for Decision Makers
For manufacturers and suppliers, the priority is to align product architecture with the converging demands of compliance, environmental resilience, and digital readiness. Rather than treating ISO conformance, contamination handling, high-temperature capability, and monitoring as separate product lines, companies should design families that can be configured around real application conditions. This includes offering interchangeable designs, protective accessories, and material variants that reduce total maintenance exposure. Equally important is the commercial narrative: positioning gas springs as part of a tool reliability and process visibility strategy can support stronger specification lock-in, especially in automotive and aerospace tooling where downtime and consistency are closely scrutinized.
PW Consulting
For investors, the market offers exposure to a steady-growth industrial component sector, but differentiation in risk-adjusted returns will depend on which business models capture compounding value. Companies with broad catalogs, reliable fulfillment, and credible digital or lifecycle features are better positioned to defend margins in an environment of input cost volatility. Investors should also monitor the pace at which smart monitoring transitions from premium option to standard expectation, since that shift will influence both pricing dynamics and the value of existing product portfolios. Exposure to heavy-duty, high-temperature, and contamination-resistant niches may provide resilience if demand in those areas continues to outpace broader commoditization.
For procurement and engineering leaders, the strategic emphasis should be on specification criteria that reduce total cost of ownership rather than focusing narrowly on upfront price. Interchangeability, compliance documentation, contamination resistance, slow-return options, and availability all contribute to lower downtime and simpler spare-part management. Where tooling environments are complex or multi-site, standardized dimensions and recognized mounting conventions can significantly reduce integration risk. Evaluating suppliers on lifecycle performance, service support, and condition-monitoring readiness can yield more durable value than selecting on unit cost alone.
Given the pace of product updates, regulatory alignment, and application-specific innovation, decision makers benefit from access to detailed segmentation data, regional demand patterns, and company-level benchmarking that go beyond headline market size. A comprehensive research view can help translate these dynamics into segment-level priorities, identify where compliance and digital readiness are becoming table stakes, and map out which supplier profiles are best aligned with specific application portfolios. For teams preparing capacity plans, sourcing strategies, or investment theses, that level of granularity is essential for moving from market awareness to actionable execution.
For detailed analysis of this topic, please visit the official page: Nitrogen Gas Springs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com