



PW Consulting: Halogen-Free Flame Retardant Market to Hit $3.45B by 2032 at 4.9% CAGR

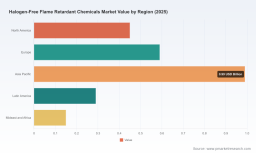
Strategizing Through the Halogen-Free Transition: A 2026 Decision Framework for Flame Retardant Markets
The global shift away from halogenated chemistry is no longer a peripheral sustainability narrative; it is a core procurement and product architecture imperative. As regulatory frameworks tighten and downstream OEMs recalibrate material specifications, the halogen-free flame retardant chemicals market has entered a phase of structural expansion that rewards early strategic positioning. Our latest market research publication maps this transition with the granularity required for 2026 capital allocation, supply chain redesign, and competitive differentiation. This briefing outlines the analytical architecture of the study and demonstrates how its insights translate into executable corporate strategy.
High-Speed Smart Egg Grading Machines Market
Market Trajectory: What the Numbers Reveal for 2026 Planning
Historical tracking from 2020 through 2025 demonstrates a consistent upward arc, with the sector moving from approximately 1.96 billion USD to 2.47 billion USD over that window. The forecast horizon extending to 2032 projects a compound annual growth rate of 4.9 percent, culminating in a market valuation of 3.45 billion USD. These revised growth rates signal a market maturing beyond cyclical volatility into a durable expansion cycle driven by regulatory mandates, electrification trends, and construction fire-safety upgrades.
Mushroom Picking Robot Market
For corporate strategists, the critical implication is not the headline figure but the velocity of change relative to capital deployment cycles. A near-five-percent annualized expansion creates a moving target for capacity planning, inventory strategy, and regional sourcing commitments. Companies that treat the halogen-free transition as a static compliance checkpoint risk underinvesting in formulation pipelines or overcommitting to legacy supply arrangements that face mounting regulatory headwinds. Our study isolates the inflection points where growth accelerates, allowing decision-makers to time investments without relying on aggregated industry narratives.
Wafer Grade Micro Lens Array (MLA) Market
Competitive Architecture: Concentration, Capability, and the New Battleground
The market exhibits measurable consolidation, with the top three players holding approximately 48.5 percent of revenue share and the top five commanding 54.2 percent. This concentration masks a highly segmented competitive field where technological differentiation, feedstock control, and regional compliance expertise determine positioning more than scale alone. The study dissects how leading organizations are converting specialty chemistry portfolios into defensible market positions.
European and North American incumbents have strengthened their formulations through targeted capacity additions and next-generation product architectures. Clariant AG has expanded its Exolit OP phosphorus-based portfolio through a major capacity investment in Daya Bay, creating additional throughput for engineering plastics, e-mobility, and consumer electronics applications while positioning the product line as an environmentally improved alternative to legacy brominated systems. Lanxess AG continues to supply halogen-free additives and polymer solutions tailored to electronics, automotive, and construction specifications, reflecting a strategy anchored in application-specific performance rather than commodity volume. Huber Advanced Materials reinforces its role as a key supplier of aluminum trihydrate and magnesium hydroxide-based formulations, alongside smoke suppressants, giving it a structural presence in polymer compounding workflows. RTP Company operates on the compounded materials side, supplying non-halogenated flame retardant compounds for plastics and resins, an important bridge between raw chemistry and end-use performance validation. In the emerging supply base, Oceanchem Group and SK Minerals & Additives Limited are advancing sustainable and indigenous formulation strategies; notably, SK Minerals & Additives recently launched Hofnil as an India-origin halogen-free additive targeting electrical insulation, automotive, and cable applications, signaling how regional self-sufficiency agendas are reshaping competitive entry points.
The strategic question for 2026 is not simply who holds the largest share, but which capability sets are becoming rate-limiting for downstream adoption. The report maps these capability clusters and identifies where partnership, acquisition, or internal development offers the highest payoff.
Regulatory and Raw Material Dynamics: How External Pressures Redefine Value
Halogen-free adoption is being accelerated by tightening fire-safety mandates across construction and electronics, reinforced by REACH and RoHS compliance expectations. The study examines how these directives do not merely restrict hazardous substances but actively incentivize reformulation roadmaps that have multi-year engineering consequences. Companies that align product development with evolving compliance expectations secure longer qualification cycles with OEMs and reduce the risk of late-cycle specification changes.
At the same time, raw material dynamics introduce a layer of volatility that many strategic plans underestimate. Magnesium hydroxide pricing in North America has already experienced measurable upward pressure in early 2026, driven by freight costs and feedstock inflation. Because brucite ore serves as the primary natural feedstock for magnesium hydroxide-based halogen-free retardants, production remains exposed to regions facing geopolitical supply risks. These dynamics make feedstock strategy a board-level consideration rather than a procurement footnote. The report quantifies where price sensitivity concentrates, which formulations offer greater cost resilience, and how regional sourcing patterns influence margin stability.
A related strategic development is the growing preference for solutions designed to sidestep antimony market volatility while supporting compliant polymer formulations. This trend illustrates how regulatory clarity and raw material risk are converging to reshape procurement preferences. Our analysis connects these supply-side realities to downstream adoption patterns, helping organizations separate short-term price fluctuations from structural shifts in preferred chemistry platforms.
What the Report Delivers: Operational Intelligence for 2026 Decision-Making
This study is designed as a working asset for strategy, procurement, R&D, and investor relations teams. Beyond macroeconomic sizing, it provides an operational lens on how the market is segmented and where value is being created. The research framework examines chemistry types, application verticals, and regional demand patterns, but its real strength lies in linking those segments to decision-relevant variables: qualification timelines, formulation trade-offs, supply concentration risks, and regulatory exposure by end-use market.
Readers will encounter a structured assessment of the competitive field, including recent capacity actions, product introductions, and positioning shifts that signal where the market is heading rather than where it has been. The report also integrates raw material and regulatory context into a single analytical narrative, allowing teams to evaluate whether proposed sourcing strategies, capacity investments, or product launches remain robust under different regulatory and input-cost scenarios. Importantly, the study deliberately avoids static percentage breakdowns for individual regions, applications, or chemistry types inside the public preview. That design choice reflects a core principle of actionable intelligence: the highest-value segmentation detail is preserved for the full dataset so that clients can benchmark without recycling the same broad aggregates available elsewhere.
Strategic Playbook: Translating Insight into 2026 Action
For executives planning the next fiscal cycle, the halogen-free flame retardant market demands a move from reactive compliance to proactive portfolio design. The study identifies several strategic priorities that consistently separate organizations capturing value from those merely absorbing cost pressure.
- Map formulation roadmaps to the regulatory calendars most relevant to your end markets, especially where construction fire-safety mandates and electronics compliance directives are converging on shorter approval windows.
- Evaluate feedstock exposure as a strategic variable, not just a purchasing metric, because magnesium hydroxide and aluminum trihydrate supply paths can materially affect margin stability and continuity of supply.
- Treat compounded and specialty formulations as differentiation platforms, since performance validation in e-mobility, electrical insulation, and construction applications often determines long-term specification status more than base chemistry alone.
- Watch regional self-sufficiency movements, particularly in fast-growing production hubs, as indigenous product introductions can reshape local supply economics and create new partnership or competitive pressures.
- Use concentration data to stress-test dependency risk; a market where a small number of players hold a majority of share can offer both reliability and vulnerability depending on your position in the value chain.
Closing Perspective: Why the Full Dataset Matters
The halogen-free flame retardant chemicals market is expanding with enough velocity to reward prepared players and penalize reactive ones. A 4.9 percent CAGR through 2032, combined with tightening compliance expectations and raw material volatility, means that decision quality in 2026 will influence competitive positioning well into the next decade. The executive overview above establishes the strategic terrain, but the detailed segmentation, scenario analysis, and competitor movement tracking inside our full report provide the operational precision required for confident commitments.
Organizations that rely on broad market narratives risk missing where growth concentrates, which formulations gain specification advantage, and how regional supply shifts alter sourcing economics. The complete study preserves that granularity while maintaining a clear line of sight from market data to decision action. For teams preparing capacity plans, reformulation budgets, or partnership evaluations this year, the full intelligence package offers the structured evidence base needed to move beyond directional confidence into executable strategy.
For detailed analysis of this topic, please visit the official page: Halogen-Free Flame Retardant Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


