



PW Consulting: Cotton Pads Market Hits $175M in 2025, Projects 5.97% CAGR Through 2032

The Quiet Evolution of Soft Consumption: Strategic Intelligence for the Cotton Pads Market in 2026 and Beyond
In the landscape of personal care and medical hygiene, few categories embody the paradox of simplicity and complexity quite like cotton pads. On the surface, they are disposable, commoditized tools—soft, absorbent, and ubiquitous. Yet, beneath this unassuming exterior lies a market undergoing a sophisticated transformation driven by material science, regulatory tightening, and shifting consumer ethics. As we navigate the fiscal year 2026, the Cotton Pads Market is no longer just about volume; it is about value, compliance, and strategic positioning within a fragmented competitive ecosystem.
Lenalidomide Capsule Market
For enterprise decision-makers, investors, and supply chain strategists, understanding the trajectory of this market is critical. The transition from basic hygiene products to specialized skincare interfaces requires a nuanced grasp of market dynamics that go beyond surface-level observations. This article serves as a strategic primer, distilling the macro-economic indicators and competitive realities that define the sector today, while highlighting the depth of intelligence required to navigate the forecast period through 2032.
Multi-function Seat Switches for Automotive Market
Market Trajectory: From Steady Growth to Structured Expansion
The historical performance of the cotton pads market between 2020 and 2025 sets a robust foundation for future projections. Over this five-year historical window, the industry demonstrated resilience despite global supply chain disruptions and fluctuating raw material costs. The market revenue climbed steadily, reflecting consistent demand across both cosmetic and medical verticals. As we close the base year of 2025, the total market valuation has established a significant foothold, signaling a mature yet expanding industry.
Fast Cure Adhesive for PV Junction Box Market
Looking toward the forecast period spanning 2026 to 2032, the growth trajectory remains positive. The Compound Annual Growth Rate (CAGR) is projected at 5.97 percent, indicating a steady, reliable expansion rather than volatile spikes. This rate suggests that while the market is not experiencing explosive disruption, it is benefiting from underlying demographic and lifestyle shifts that sustain demand. By the end of the forecast period in 2032, the market revenue is expected to reach substantial levels, driven by incremental adoption in developing regions and premiumization in established markets.
Strategic Implication: For stakeholders, a 5.97 percent CAGR implies that organic growth alone may not be sufficient to capture significant market share. Consolidation, product differentiation, and regulatory compliance will likely be the primary levers for outperformance. The revenue units, denominated in USD Millions, reflect a globalized supply chain where currency fluctuations and sourcing costs in key manufacturing hubs play a pivotal role in margin preservation.
Segmentation Dynamics: Type, Application, and Regional Nuances
The structure of the cotton pads market is defined by distinct segmentation splits that dictate product strategy and inventory planning. Understanding the interplay between product types, application verticals, and regional demand is essential for optimizing portfolio mix.
Product Typology and Consumer Preference
The market is categorized by shape and design, with round, square, oval, and other variants available. Each shape serves specific application needs, from full-face cleansing to targeted toner application. The dominance of certain shapes often correlates with regional beauty rituals and packaging efficiencies. For instance, round pads are traditionally associated with general cosmetic removal, while square variants may offer packaging density advantages. The availability of oval and specialty shapes indicates a market responding to niche skincare routines and aesthetic packaging demands.
Supply chain managers must note that inventory complexity increases with shape variety. The decision to stock multiple formats versus focusing on high-volume standards depends heavily on the target consumer segment and distribution channel.
Application Verticals: Cosmetic vs. Medical
The demand side is primarily split between cosmetic use, medical use, and other applications. Cosmetic use remains the largest driver, fueled by daily skincare routines, makeup removal, and the rising popularity of at-home beauty treatments. However, the medical segment holds significant strategic weight due to higher compliance barriers and stable demand cycles. Medical cotton pads require sterile manufacturing environments and specific certifications, creating a higher entry barrier that protects incumbent players.
The "Others" category often encompasses industrial or specialized hygiene applications, which, while smaller in volume, can provide diversified revenue streams during periods of cosmetic market saturation.
Regional Distribution
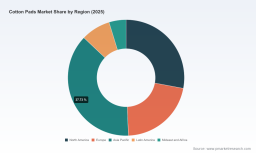
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. The Asia Pacific region represents a massive volume center, driven by population density and growing personal care awareness. North America and Europe remain high-value markets where premiumization and regulatory compliance are key differentiators. Latin America and the Mideast and Africa offer growth potential, often linked to urbanization rates and healthcare infrastructure development.
Distribution strategies must be tailored to these regions. In mature markets, the focus is on brand equity and sustainability credentials. In emerging markets, accessibility, price sensitivity, and distribution network reach are paramount.
Competitive Landscape: Fragmentation and Strategic Positioning
The market concentration metrics reveal a moderately fragmented landscape. The CR3 (Concentration Ratio of the top three players) stands at 29.8 percent, and the CR5 reaches 35.2 percent. This indicates that while there are dominant players, no single entity controls the market entirely. This fragmentation creates opportunities for niche players to thrive but also intensifies competition on price and innovation.
Several key companies define the current competitive architecture, each bringing distinct strengths to the table:
- Shiseido Company Limited (Tokyo, Japan): A leader in skincare technology, Shiseido leverages its brand equity to offer premium cotton pads. Their focus on 100 percent natural super-soft cotton with long and medium-long fibers targets moisture retention and skincare efficacy, positioning their pads as part of the beauty regimen rather than just a disposable tool.
- Unicharm Corporation (Tokyo, Japan): With a broad portfolio in personal care and hygiene, Unicharm integrates cotton pads into a larger ecosystem of health and wellness products, benefiting from cross-category distribution strength.
- Groupe Lemoine (France): Offering a wide variety of shapes such as round, square, oval, crimped, and embossed pads, Groupe Lemoine addresses diverse application needs including baby care. Their inclusion of biodegradable variants highlights the market's shift toward environmental responsibility.
- Sanitars S.p.A. (Italy): Focusing on high-quality personal care, Sanitars emphasizes 100 percent pure cotton, appealing to consumers seeking purity and comfort in personal hygiene products.
- PT Cottonindo Ariesta TBK (Indonesia): As a key player in the Asia Pacific manufacturing hub, Cottonindo serves cosmetic and medical sectors, capitalizing on regional production capabilities for cost-effective supply.
- Winner Medical Group (China): Specializing in medical-grade options, Winner Medical offers private-label and OEM solutions with ultra-sterile specifications, catering to healthcare providers and branded partners seeking compliance-ready products.
- Suzuran Medical Inc. (Japan): One of the largest suppliers in Japan, Suzuran Medical handles high-volume production for both cosmetic and medical needs, demonstrating scale advantages in manufacturing efficiency.
- A.S. Watson Group (Hong Kong): Through its retail network, A.S. Watson distributes both private-label and branded organic options, bridging the gap between mass-market availability and premium consumer preferences.
- MUJI (Japan): Distinctive for its sustainability angle, MUJI offers reusable and washable cotton pads designed to last up to 100 uses, challenging the single-use paradigm and targeting environmentally conscious consumers.
- CMC Consumer Medical Care GmbH (Germany): Serving both medical and consumer use markets, CMC focuses on reliability and compliance, aligning with European standards for health-related products.
- TZMO S.A. (Poland): With their Bella Cotton brand, TZMO focuses on personal care pads, leveraging European manufacturing heritage to meet regional quality expectations.
Recent Developments and Innovation Signals
Innovation remains a critical battleground. For example, in May 2026, Shiseido Company Limited released updated Facial Cotton pads emphasizing 100 percent natural super-soft cotton with long and medium-long fibers for superior moisture release during skincare application. This move underscores a broader industry trend where comfort and skincare efficacy are becoming key differentiators. Competitors are likely watching such launches closely to gauge consumer response to fiber technology and material sourcing claims.
Industry Dynamics and Cost Pressures
Navigating the cotton pads market in 2026 requires a clear understanding of the cost structures and regulatory environments that shape profitability. Several critical factors are currently influencing the industry dynamics:
Raw Material Sourcing
The shift toward organic cotton sourced for GOTS-certified pads incurs elevated material costs compared to conventional cotton. As consumers become more label-conscious, the demand for certified organic inputs is rising. However, this transition affects the cost base significantly. Companies must decide whether to absorb these costs to maintain premium positioning or pass them on to price-sensitive consumers, risking volume erosion.
Labor and Manufacturing Costs
Higher wages in Asian manufacturing hubs for sterile cotton pad production contribute to 10-15 percent cost inflation. As the region dominates production capacity, labor rate increases directly impact the global supply chain. Manufacturers are forced to optimize production processes, automate where possible, or explore alternative sourcing locations to mitigate margin compression.
Regulatory Compliance
Regulation is a double-edged sword: it ensures safety but adds expense. FDA and CE certifications required for medical cotton pads impose additional compliance and testing expenses. For companies operating in the medical vertical, these costs are non-negotiable barriers to entry that protect incumbents but strain R&D budgets.
Simultaneously, EU REACH restrictions on chemical processing of cotton pads for cosmetic use require updated safety data. This regulatory environment necessitates ongoing monitoring and adaptation of manufacturing processes to ensure that no restricted substances are present in the final product. Failure to comply can result in market access loss, particularly in the stringent European market.
The 2026 Decision Framework: Why Deep Intelligence Matters
Given the complex interplay of growth rates, segmentation nuances, competitive pressures, and cost drivers, high-level summaries are insufficient for strategic planning. The Cotton Pads Market Research report provides the granular data and analytical rigor necessary to make informed decisions in this environment.
What the Full Report Delivers
To truly capitalize on the opportunities outlined by the 5.97 percent CAGR and the shifting market dynamics, stakeholders need access to detailed segmentation analysis, supply chain mapping, and competitive benchmarking. The comprehensive study goes beyond macro trends to offer:
- Detailed Segmentation Revenue and Volume Data: While macro trends indicate growth, understanding the specific revenue and volume contributions of each product type, application, and region is vital for inventory and capacity planning. The full report breaks down these splits without aggregating data into vague averages, allowing for precise market sizing.
- Competitive profiling and Strategy Analysis: Beyond company names, the report evaluates market share estimates, product positioning, and strategic moves by key players. This helps identify white spaces and potential partnership opportunities.
- Regulatory Roadmaps: Detailed analysis of compliance requirements across different regions helps companies anticipate costs and timeline adjustments for market entry or expansion.
- Consumer Trend Insights: Understanding the shift toward sustainability, organic materials, and reusable options requires deep consumer sentiment data, which is integrated into the forecast models.
- Supply Chain Risk Assessment: With labor cost inflation and raw material volatility, the report assesses potential bottlenecks and sourcing alternatives to safeguard operations.
Strategic Use Cases for the Data
Access to this level of detail enables several high-value strategic actions:
- Portfolio Optimization: Determine which product shapes and applications offer the best margin potential in specific regions, allowing for targeted SKU rationalization or expansion.
- Pricing Strategy: Factor in raw material and labor cost trends to develop pricing models that protect margins without sacrificing volume, especially in price-sensitive segments.
- Market Entry and Expansion: Evaluate the feasibility of entering specific regional markets by analyzing local demand drivers, competitor presence, and regulatory hurdles.
- M&A and Partnership Identification: In a fragmented market with a CR5 of 35.2 percent, acquisition targets or strategic partnerships can accelerate scale and capability building. The report highlights potential candidates based on market position and strategic fit.
- Sustainability Roadmapping: Assess the ROI of transitioning to organic or biodegradable materials against consumer willingness to pay and regulatory timelines.
Conclusion: Positioning for the Next Cycle
The Cotton Pads Market is at a inflection point where traditional growth drivers are being reinforced by new demands for quality, safety, and sustainability. The projected growth to 2032 offers ample opportunity, but realizing this potential requires more than passive observation. It demands a proactive strategy informed by precise data and a deep understanding of the competitive and regulatory landscape.
The macro indicators suggest a healthy market, but the devil lies in the details of segmentation, cost structures, and competitor moves. As raw material costs rise and regulations tighten, the margin for error shrinks. Enterprises that equip themselves with comprehensive market intelligence will be better positioned to navigate these challenges, optimize their operations, and capture value in a market that is becoming increasingly sophisticated.
For leaders ready to move beyond estimates and into actionable strategy, the full market research provides the necessary foundation. The data is structured to support rigorous analysis, enabling stakeholders to model scenarios, assess risks, and identify high-return opportunities with confidence.
Discover the complete market intelligence, detailed segmentation data, and strategic forecasts by accessing the full report.
For detailed analysis of this topic, please visit the official page: Cotton Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


