



PW Consulting: Piperylene Market to Hit $1,231M by 2032, 6.9% CAGR from $780M in 2025

Piperylene Market Outlook 2026 Strategic Intelligence for Chemical Industry Leaders
The global piperylene market stands at a pivotal inflection point as we move through 2026. For executives, procurement strategists, and long-range planners operating across the chemical value chain, understanding where this market is heading is no longer a matter of speculative forecasting. It is a direct requirement for capital allocation, supply chain resilience, and competitive positioning. Our newly released Piperylene Market research study provides a rigorous, data-grounded examination of the structural forces shaping the sector over the next seven years. The report is engineered to translate macro-level trajectory shifts into actionable commercial intelligence, enabling leadership teams to calibrate pricing negotiations, capacity commissioning decisions, and strategic partnerships with precision.
Cognition-Enhancing Drugs Market
Market Trajectory and the 2026 Decision Horizon
The piperylene sector has demonstrated consistent expansion over the past half-decade, driven by recovering downstream manufacturing activity, sustained demand from polymer and resin applications, and supply chain recalibration following recent logistical disruptions. Historical data from 2020 through 2025 reveals a market that has systematically climbed from approximately 598.5 million USD to 780.0 million USD, reflecting compound annual growth that underscores the building block role piperylene plays across industrial chemistry portfolios. As we enter the forecast window spanning 2026 through 2032, the trajectory points toward sustained expansion, with the overall market size projected to reach roughly 812.11 million USD in the immediate 2026 horizon and continuing upward toward 1.23 billion USD by 2032.
Worldwide Marine Annunciator Panels Market
The compound annual growth rate across the forecast period is estimated at 6.9 percent, a figure that should be interpreted not as a simple growth headline but as a structural signal. A rate at this level indicates that demand pull from end-use industries is out-pacing the incremental capacity additions from C5 fractionation and steam-cracking streams, while simultaneously highlighting the importance of feedstock reliability and regional supply balancing. For corporate planners, this growth cadence carries several immediate implications. Budget cycles for 2026 and 2027 must account for pricing volatility that accompanies steady demand expansion, particularly as fewer new entrants can rapidly scale to capture margin share. Procurement teams should begin modeling scenario-based supply contracts that reflect tightening availability in high-purity segments, while capacity expansion teams need to weigh the timing of specialty-grade investments against the risk of premium compression if competing producers bring additional fractionation capacity online in synchronized windows. The forecast period is constructed precisely to give leadership teams the visibility required to make these timing decisions with confidence rather than reactive guesswork.
Worldwide Airport Scrubber Dryers Market
Segment Architecture and Commercial Leverage Points
A market of this scale and growth complexity cannot be navigated with aggregate figures alone. The strategic value of any forecasting exercise lies in its ability to reveal how value is distributed across product specifications, application verticals, and geographic supply nodes. This study segments the piperylene market across multiple operational dimensions, providing a layered view of where margin concentration, demand intensity, and supply bottlenecks are forming.
Product Grade Dynamics
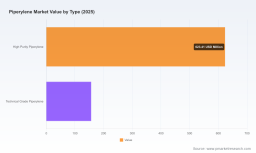
The market structure reflects a clear dominance of high-purity piperylene, which accounts for the substantial majority of reported revenue, with technical-grade material representing a smaller but commercially meaningful residual share. For downstream users, the divergence between these grades is not merely a purity specification. It translates directly into processing flexibility, resin performance characteristics, and suitability for high-value elastomer and adhesive formulations. High-purity streams command pricing premiums and require tighter fractionation control, while technical-grade material is frequently directed toward less performance-sensitive applications where cost optimization is prioritized. Understanding the relative growth velocity of each grade, and how supply availability shifts as cracking yields and separation technologies evolve, enables procurement and R&D teams to align material specifications with total cost of ownership rather than sticker price alone. Our report isolates the drivers behind grade-level demand shifts and maps the implications for sourcing strategies across both high-purity and technical-grade categories.
Application-Level Demand Architecture
Piperylene demand is distributed across several core industrial applications, each with distinct consumption profiles, price sensitivity, and growth catalysts. The largest application segment centers on resins, where piperylene serves as a foundational building block for hydrocarbon resins used in adhesives, coatings, and rubber compounding formulations. This segment carries substantial volume and is particularly sensitive to automotive, packaging, and construction sector activity. The rubber segment represents a second major consumption pillar, with piperylene incorporated into synthetic rubber streams and specialty elastomer formulations that support tire manufacturing, industrial hose production, and vibration-damping components. Adhesives and coatings form additional downstream demand nodes, each with their own regulatory, performance, and reformulation trajectories.
Because these application verticals do not expand uniformly, aggregate market growth can obscure meaningful divergence beneath the surface. A resin-focused producer may experience materially different demand signals than a coatings supplier, even within the same calendar year. The report dissects these application-level consumption patterns to help clients identify where demand is structurally expanding, where substitution risk is rising, and where downstream innovation is likely to alter piperylene uptake over the 2026 to 2032 window. By mapping revenue concentration by application without exposing the underlying granular percentages, the study preserves the directional intelligence leadership teams need while maintaining competitive confidentiality and prompting deeper consultation for precise allocation planning.
Regional Supply and Demand Architecture
Geographic segmentation is equally critical for strategic planning. Piperylene supply is inherently tied to steam-cracking and C5 fractionation networks, meaning regional capacity geography shapes both pricing dynamics and logistics costs. The market shows pronounced activity across major industrial regions, with Asia Pacific reflecting the largest aggregate market size, North America and Europe maintaining substantial mature demand bases, and Latin America and the Middle East and Africa representing growing but comparatively smaller consumption nodes.
Regional analysis in this study is structured to reveal where supply tightness may emerge, where import dependency is likely to increase, and where localized fractionation capacity could reshape trade flows. For multinational chemical groups, this geographic lens is indispensable for evaluating sourcing diversification, evaluating freight and inventory exposure, and anticipating regulatory or tariff shifts that could alter regional cost baselines. The report maps these regional dynamics to support decisions around distribution hub placement, contract structuring with domestic versus imported sources, and long-term capacity partnerships in high-growth corridors.
Competitive Landscape and Strategic Positioning
The piperylene market is characterized by a concentrated supplier base, with the top three firms accounting for approximately 68.5 percent of market share and the top five firms reaching roughly 85.2 percent. This level of concentration signals an industry where scale, integration, and feedstock reliability create durable competitive advantages. It also means that pricing frameworks, availability windows, and long-term contract terms are heavily influenced by the strategic behavior of a relatively small number of major producers.
Our research profiles a comprehensive set of key industry participants, offering detailed assessments of each company's operational footprint, feedstock positioning, and downstream market orientation.
LyondellBasell Industries N.V., headquartered in Rotterdam, operates as a global producer of piperylene as a key olefinic building block extracted from steam-cracked C5 fractions, with integrated manufacturing and supply to downstream chemical and rubber industries. ExxonMobil Chemical, based in Irving, Texas, stands as a major producer and supplier of piperylene through its petrochemical operations, with a focus on high-purity olefins for industrial applications. Chevron Phillips Chemical Company LLC, located in The Woodlands, Texas, is an active manufacturer of piperylene derived from C5 fractions, serving olefins and aromatics markets globally. Zeon Corporation, based in Tokyo, is a specialized producer extracting piperylene from C5 fractions for use in petroleum resins, synthetic rubbers, and specialty chemicals. LOTTE Chemical Corporation, headquartered in Seoul, functions as a key supplier of piperylene as a C5 by-product for industrial chemical synthesis and elastomers. Eastman Chemical Company, with operations in Kingsport, Tennessee, produces piperylene within its olefin and aromatics portfolio for downstream applications in resins and coatings.
Shell Chemicals, headquartered in The Hague, provides an integrated supply of piperylene from steam cracking operations for global chemical markets. Sinopec, based in Beijing, is a major Chinese petrochemical producer of piperylene from C5 fractions with extensive export capabilities. Formosa Chemicals & Fibre Corporation, operating out of Taipei, is an active manufacturer of piperylene for the industrial chemical sector. Mitsui Chemicals, Inc., headquartered in Tokyo, supplies and produces piperylene as part of its C5 chemical offerings.
The competitive analysis in this study extends beyond company profiles to evaluate strategic behavior, capacity positioning, integration advantages, and likely responses to market expansion. For clients evaluating partnership opportunities, supplier diversification, or competitive benchmarking, these profiles provide an essential reference point for understanding which producers are best positioned to supply high-purity streams, which firms are expanding export reach, and where supply concentration may translate into negotiating leverage.
Regulatory and Structural Dynamics Shaping the Market Environment
The piperylene market does not operate in isolation from broader regulatory and policy shifts affecting industrial chemicals and downstream manufacturing standards. While many regulatory developments directly target pharmaceutical or biologic pathways, the broader signal they send regarding review timelines, evidence requirements, and accelerated approval frameworks influences how industrial supply chains evaluate compliance posture, quality assurance, and change-management risk. Recent policy updates from U.S. regulatory bodies highlight a broader administrative emphasis on streamlined decision-making and efficiency in approval processes, including the establishment of new default standards that require a single robust pivotal study plus confirmatory evidence to reduce review timelines, as well as the implementation of accelerated approval pathway updates and real-time trial capabilities to enhance efficiency in development reviews.
For chemical market participants, the relevance of these developments lies less in direct pharmaceutical overlap and more in the structural direction they reveal. An environment oriented toward faster review cycles, clarified evidentiary expectations, and reduced procedural lag tends to indirectly favor sectors that can demonstrate consistent quality, traceable sourcing, and reliable product performance. Companies that maintain rigorous specification control, robust documentation, and predictable supply continuity are better positioned to adapt to evolving downstream expectations across multiple regulated end-use sectors. The report incorporates these structural dynamics to help clients assess how administrative and compliance momentum may influence purchasing criteria, supplier qualification processes, and entry requirements in sensitive downstream markets.
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 forecast period is not merely a statistical exercise. It is the operational window in which capacity commitments, long-term supply contracts, geographic sourcing strategies, and application development roadmaps will be locked in. A market growing at the projected pace with concentrated supplier control and divergent application-level demand creates a decision environment where generalized market awareness is insufficient. Leadership teams need segmented visibility into where value is accruing, which grade and application combinations are expanding fastest, how regional supply balances are shifting, and which competitive players are most likely to influence availability and pricing over the next several years.
This Piperylene Market study is designed to provide exactly that layered intelligence. It synthesizes historical trajectory, forecast growth, segmentation architecture, competitive positioning, and structural market dynamics into a single coherent framework. The result is a decision-support tool that can be applied across procurement, operations, corporate development, and market strategy functions. By presenting the macro contours and segmentation logic in depth while reserving the full granularity of regional and application-level figures for the complete report, the study establishes analytical credibility and signals the richness of the underlying data without prematurely disclosing the operational detail that would otherwise reduce the incentive to engage with the full intelligence package.
What the Report Delivers
The complete market research package is structured to support a wide range of internal strategic processes. Clients receive detailed segmentation analysis that breaks down market size and growth by product grade, application, and region over both historical and forecast windows. The study includes competitive profiling of major producers and an assessment of concentration dynamics that shape pricing influence and supply reliability. It also provides contextual analysis of the regulatory and structural developments that influence downstream procurement expectations and industry-wide compliance posture.
In addition to core sizing and segmentation, the report examines demand catalysts by application vertical, maps the implications of regional supply geography for sourcing and logistics, and evaluates competitive positioning across integrated producers and specialized fractionators. Methodology transparency is maintained throughout, allowing clients to understand the assumptions, data treatment, and forecast framework underpinning the projections. This combination of macro trajectory, segmentation intelligence, competitive context, and structural analysis is intended to serve as a foundational reference for 2026 planning cycles and multi-year capital and commercial strategy development.
Strategic Takeaway for Leadership Teams
The piperylene market is expanding along a steadily upward path, shaped by concentrated supply, application-specific demand growth, and regional supply geography that will increasingly influence cost and availability. For organizations operating in or adjacent to this market, the strategic imperative is clear: aggregate awareness is no longer enough. The decisions that will determine competitive advantage in 2026 and beyond depend on a more granular understanding of grade-level dynamics, application-level demand divergence, regional supply positioning, and the strategic behavior of the dominant producers that shape market conditions.
This Piperylene Market research report is built to provide that understanding in a format calibrated for executive use. It offers the analytical depth required to build trust in the forecast framework while preserving the full operational detail for the complete release. For teams preparing sourcing strategies, capacity evaluations, competitive benchmarking, and multi-year growth planning, the report provides a structured foundation for informed, forward-looking decision-making in a market where timing, specification alignment, and supply reliability will increasingly determine commercial outcomes.
For detailed analysis of this topic, please visit the official page: Piperylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


