



PW Consulting Forecasts Microcrystalline Wax Market to Hit $1.93B by 2032 at 4.15% CAGR

Navigating the Next Wave: Strategic Imperatives in the Global Microcrystalline Wax Market (2026–2032)
The global microcrystalline wax sector is entering a phase of recalibration. As industries from personal care to industrial adhesives demand more specialized, sustainable, and supply-chain-resilient materials, stakeholders must look beyond headline figures to understand the structural forces shaping value creation over the coming decade. Our latest Microcrystalline Wax Market research study delivers the analytical rigor required to position portfolios, pricing strategies, and sourcing models ahead of the curve.
This article previews the strategic architecture of that study, outlining how macro-trajectory data, competitive positioning, and regulatory fault lines intersect to form a decision framework for enterprise leaders in 2026 and beyond. Detailed segment-level figures, regional revenue breakdowns, and granular application splits are reserved for the full report, where they can be evaluated alongside scenario models and actionable benchmarks.
A Decade of Measured Expansion: What the Trajectory Tells Us
The microcrystalline wax market has demonstrated consistent growth across the reference period, expanding from a baseline valuation of approximately USD 1,134 million in 2020 to an estimated USD 1,425 million in 2025. That progression reflects underlying demand diversification rather than a single dominant catalyst. Over the forecast window spanning 2026 through 2032, the market is projected to advance at a compound annual growth rate of 4.15%, translating into a forward valuation trajectory that reaches upward of USD 1.9 billion by the close of the period.
These headline metrics serve as orientation points rather than endpoints. The real strategic value lies in unpacking what drives variance around the trend line: feedstock cost dynamics, cross-application substitution patterns, regional trade rerouting, and the pace at which sustainability mandates reshape procurement specifications. The study maps these forces into a unified analytical model, enabling clients to test how changes in one variable—say, crude oil benchmark movement or a new import restriction—cascade through volume assumptions, margin structures, and sourcing priorities.
Importantly, the growth path is not uniformly linear. The forecast period captures intervals of recalibration where supply-side constraints and regulatory interventions temporarily alter the pace of expansion. Understanding where those inflection points occur, and how incumbents versus challengers respond, is central to building resilient operating strategies in 2026.
Report Architecture: From Macro Context to Execution-Ready Intelligence
The research is designed as a practical decision-support instrument rather than a static data compendium. It combines market sizing, structural segmentation, competitive intelligence, and regulatory tracking into a single navigable framework. The following components illustrate the scope and operational orientation of the study:
- Market Sizing and Forward Modeling: Historical performance from 2020 through 2025 is reconstructed to establish a defensible baseline, then extended through 2032 using scenario-conditioned projections. The modeling approach isolates sensitivity to feedstock pricing, demand elasticity across application families, and trade-flow adjustments, giving users a basis for internal forecasting rather than reliance on a single point estimate.
- Structural Segmentation Analysis: The study disaggregates the market across type, application, and region to expose where volume and value concentrate, where growth rates diverge, and where substitution risk is most pronounced. Rather than presenting percentages in isolation, the analysis pairs each segmentation dimension with qualitative drivers—performance requirements, regulatory exposure, formulation trends, and procurement norms—so that readers can interpret shifts within a commercial context.
- Competitive Landscape and Strategic Profiles: Eight core enterprise profiles are developed with attention to product architecture, capacity orientation, application coverage, and recent commercial moves. Each profile highlights how a player positions itself within the value chain and where it is investing to capture differentiated demand.
- Regulatory and Trade Dynamics Tracking: Because mineral waxes sit at the intersection of commodity sourcing and cross-border compliance, the report integrates an active watchlist of policy developments. Coverage extends from targeted import restrictions and forced-labor enforcement actions to tariff subheadings and carbon-footprint disclosures, each mapped to potential procurement and routing implications.
- Cost and Feedstock Context: The analysis embeds raw-material dynamics—including refinery throughput constraints, crude benchmark movement, and derivative price volatility—into the demand-and-supply narrative. This linkage helps explain why price trends in specific quarters diverge from the broader growth trajectory and how that divergence affects negotiation leverage, inventory strategy, and contract design.
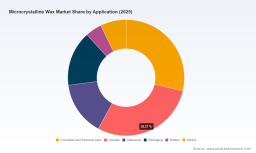
- Application-Level Demand Interpretation: Cosmetics and personal care, candles, adhesives, packaging, rubber, and other end-use segments are examined through the lens of formulation requirements, quality standards, and purchasing cycles. The goal is to show where microcrystalline wax functions as a performance-critical input versus a commoditized additive, and how that distinction shapes pricing power and switching behavior.
By integrating these layers, the study moves beyond descriptive market snapshots to provide a structured basis for capacity planning, product-mix decisions, supplier diversification, and market-entry evaluation.
Competitive Landscape: Positioning Among Established Players and Emerging Pressures
The market exhibits meaningful concentration, with the top three firms collectively representing a substantial share of revenue and the top five extending that footprint further. Such concentration does not imply homogeneity, however. Incumbents differentiate through grade specialization, compliance certification, geographic coverage, and the ability to supply customized physical forms and purity levels. The report profiles a cross-section of leading participants to illustrate how strategy diverges even within a consolidated field.
ExxonMobil Corporation anchors its microcrystalline wax offering around the Prowaxx™ family, spanning fully refined, semi-refined, and slack grades directed at packaging, adhesives, construction, personal care, and rubber applications. The breadth of grade availability supports customers who require consistent performance across varied melting ranges and oil-content specifications. Recent 2025 activity, including the launch of a high-purity microcrystalline wax line for specialty plastics and coatings, signals continued investment in higher-specification segments where formulation precision and surface-protection performance carry premium value.
Sasol Limited has emphasized differentiated, lower-impact materials through its SASOLWAX LC Spray portfolio, including micronized grades designed for coatings, inks, plastics, and specialty manufacturing. The introduction of grades featuring a notably reduced product carbon footprint aligns with buyer requirements in markets where sustainability documentation increasingly influences specification decisions. This positions Sasol at the intersection of performance consistency and environmental reporting, a combination that is gaining relevance in procurement cycles across Europe and other regulated import markets.
Calumet Specialty Products Partners L.P. maintains a strong orientation toward intermediate and microcrystalline waxes, with a significant proportion of capacity oriented toward hard grades used in industrial adhesives, packaging, and consumer products. The emphasis on hard-grade capacity is strategically meaningful because it addresses applications where hardness, brittleness resistance, and adhesion characteristics are central to product performance. Calumet’s profile illustrates how capacity allocation decisions can reinforce a company’s relevance in specific end-use clusters.
Sonneborn LLC leverages its Multiwax™ line, including U.S. FDA-compliant grades, to serve personal care, topical formulations, food packaging, and hot melt adhesives. Compliance readiness and grade consistency are central value propositions in categories where regulatory documentation and batch-to-batch repeatability are non-negotiable. In personal care and food-adjacent applications, such attributes often function as gatekeeping requirements before price or logistical considerations come into play.
The International Group, Inc. (IGI Wax) differentiates through dedicated microcrystalline wax production and blending flexibility, offering bulk liquid, granule, pellet, or slab forms for cosmetics, food-grade, industrial, and coatings applications. Form-factor versatility supports customers who integrate wax into diverse manufacturing workflows and require tailored handling characteristics. This operational flexibility can reduce friction in sourcing relationships where application engineers value supply consistency and specification tuning.
Sinopec Corporation brings substantial production and supply capability, including downstream distribution and small-package delivery to markets such as Europe. Its scale and integrated posture enable it to act across multiple points in the value chain, supporting both industrial users and distributors seeking reliable volume and geographic reach. In an environment where trade restrictions and routing complexity are increasing, the ability to manage cross-border logistics and package sizing can be a meaningful differentiator.
Paramelt B.V. positions its microcrystalline waxes around sustainability and bio-based alternatives in coatings, adhesives, and plastics. This orientation reflects a broader industry shift in which buyers evaluate not only functional performance but also the environmental narrative of material inputs. Paramelt’s focus suggests a strategic bet on the accelerating relevance of sustainable specification language in downstream formulation decisions.
Kahlwax GmbH concentrates on industrial-grade microcrystalline wax for plastics, rubber, and specialty manufacturing. Its profile highlights the importance of application-tailored industrial grades where processing conditions, thermal behavior, and compatibility with polymer matrices drive selection. In such contexts, technical support and grade consistency often weigh as heavily as unit pricing.
Together, these profiles reveal a competitive environment in which scale, grade breadth, compliance readiness, sustainability positioning, and form-factor flexibility all serve as potential sources of advantage. The full report assesses how these attributes map to market share dynamics, regional presence, and responsiveness to recent commercial developments.
Regulatory Fault Lines and Feedstock Volatility: The 2026 Operating Environment
Strategic planning in 2026 must account for an unusually active policy and cost environment. Several developments have begun to reshape the risk calculus for microcrystalline wax procurement, distribution, and formulation.
Trade Restrictions and Enforcement Scope
Regulatory measures in key import markets have expanded the scope of scrutiny applied to mineral waxes. Amendments associated with Canada’s Special Economic Measures Act, effective from mid-2025, explicitly bring paraffin wax, micro-crystalline petroleum wax, and slack wax within the scope of targeted import and trade restrictions. For organizations with North American supply chains or customer bases, this introduces additional compliance mapping and potential rerouting considerations that can affect lead times, documentation burdens, and supplier eligibility.
In parallel, enforcement actions in the United States have extended to mineral waxes within proposed duty frameworks and forced-labor-related import measures. Tariff subheadings covering other mineral waxes, including microcrystalline wax, carry specified duty rates that feed directly into landed-cost calculations. Proposed additional ad valorem rates associated with enforcement actions further complicate procurement modeling, especially for buyers sourcing from regions exposed to trade scrutiny. These measures do not necessarily change underlying demand, but they alter the cost and feasibility of particular sourcing paths.
Feedstock Pressure and Price Trend Dynamics
On the cost side, rising crude oil benchmarks and refinery constraints have placed upward pressure on microcrystalline wax pricing. In the first quarter of 2026, average prices increased across global markets as feedstock expenses climbed, illustrating how quickly margin and pricing assumptions can shift when upstream conditions tighten. This type of movement matters not only for cost accounting but also for contract structuring, inventory timing, and the negotiation of pass-through mechanisms.
Compounding this dynamic, broader geopolitical disruption in the Middle East has affected chemical feedstock flows, contributing to price volatility in naphtha, LPG, and natural gas derivatives. Because these inputs influence wax production costs and related derivative markets, the effect can ripple through the value chain in uneven ways, creating pockets of pressure that differ by region, grade, and supply route.
Why These Dynamics Matter Strategically
Regulatory and cost developments rarely operate in isolation. A tariff adjustment can change the relative attractiveness of one sourcing corridor; a feedstock surge can accelerate the search for alternative grades or formulation adjustments; a compliance expansion can narrow the pool of eligible suppliers in a given market. Our research integrates these threads into a coherent operating-risk map so that clients can anticipate interactions rather than react to them sequentially.
Strategic Takeaways for 2026 Decision-Makers
The convergence of steady long-term demand growth, concentrated competition, and a volatile regulatory and feedstock environment creates a clear mandate for structured intelligence. Several strategic priorities emerge from the study’s analytical design:
Micronized Wax Market
- Stress-test sourcing assumptions against policy exposure. Trade restrictions, duty structures, and enforcement actions can change the effective cost and availability of specific grades from specific origins. Scenario analysis should incorporate compliance mapping as a core variable rather than a peripheral legal issue.
- Align grade strategy with application criticality. In segments where microcrystalline wax functions as a performance enabler—adhesives, personal care, food-adjacent packaging, specialty coatings—grade consistency, purity, and compliance documentation can outweigh narrow price comparisons. In more commoditized uses, procurement leverage and logistics efficiency may dominate. Understanding this distinction helps prioritize where to defend specifications and where to optimize cost.
- Evaluate sustainability positioning as a procurement input. Lower-carbon-footprint grades and bio-based alternatives are increasingly relevant in buyer evaluations. Even where regulatory mandates are not yet universal, sustainability documentation can influence supplier selection, especially in export-oriented and compliance-intensive markets.
- Build flexibility into inventory and contract design. Feedstock-driven price movement and trade-related supply disruption argue for a deliberate approach to inventory buffers, contract terms, and supplier diversification. Flexibility is particularly valuable when price spikes are associated with temporary constraints rather than permanent structural shifts.
- Track capacity orientation, not just revenue. Competitors’ capacity allocation choices—such as emphasis on hard grades, micronized formats, or FDA-compliant lines—signal where they intend to compete and where they may be less responsive to certain customer needs. These structural signals can inform supplier selection and competitive positioning.
What the Full Study Provides
This overview establishes the strategic frame; the complete Microcrystalline Wax Market report delivers the underlying detail required to operationalize it. The full study includes comprehensive sizing and forecast modeling, segmentation analysis across type, application, and region, extended competitive profiles with recent development tracking, regulatory and trade mappings tied to commercial impact, and cost-context analysis that connects feedstock dynamics to pricing behavior.
Importantly, the complete report preserves analytical integrity by presenting segmentation detail—regional contributions, application-level valuations, and type-level splits—within interpretive context rather than as isolated figures. That approach allows decision-makers to see not only where value sits today, but how shifts in formulation, regulation, and sourcing economics are likely to redistribute it through 2032.
For enterprise leaders responsible for sourcing strategy, product development, capacity planning, or market-entry evaluation, the study offers a structured path from macro trajectory to actionable insight. The market is expanding, but the value of that expansion will accrue to organizations that can interpret its drivers with precision and act on them before the next round of policy or cost shocks changes the landscape.
Microcrystalline Wax Market
For detailed analysis of this topic, please visit the official page: Microcrystalline Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


