



PW Consulting: Spunbond Nonwoven Market to Reach $26.58 Billion by 2032, 6.1% CAGR

Strategic Intelligence for the Spunbond Nonwoven Fabrics Market: Navigating Growth Amid Regulatory and Supply Chain Shifts in 2026
Executive Overview
The spunbond nonwoven fabrics sector is entering a defining growth phase, driven by sustained demand across hygiene, medical, automotive, filtration, and industrial applications. As manufacturers and converters plan for 2026 and beyond, the market is characterized by a resilient demand trajectory, evolving material economics, and a rapidly tightening regulatory horizon. This introduction outlines the strategic rationale behind our latest market research, demonstrating how a granular, forward-looking analysis can convert macro trends into executable decisions for sourcing, capacity investment, compliance planning, and competitive positioning.
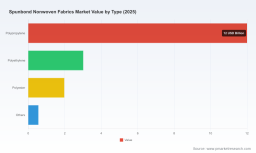
Over the past six years, the industry has expanded from a baseline of approximately 13.06 billion USD in 2020 to 17.56 billion USD in 2025, reflecting a compound annual growth rate of 6.1 percent through the 2026-2032 forecast horizon. In 2026, the market is projected to reach 18.22 billion USD, with expansion continuing toward 26.58 billion USD by 2032. These headline figures underscore a market that is not merely growing, but transforming in terms of product portfolios, regional dynamics, and value chain complexity. The question for decision makers is no longer whether the spunbond nonwoven fabrics market will expand, but how to capture share, manage cost volatility, and align operations with regulatory and sustainability mandates that are reshaping competitive rules.
Our newly released market research is designed to answer that question. It provides an integrated view of demand drivers, segment trends, regional momentum, competitive strategies, and the regulatory and raw material variables that will influence margins and availability in 2026 and beyond. The report functions as both a market map and an operating playbook, enabling executive teams to stress test assumptions, prioritize investments, and anticipate inflection points before they become industry consensus.
Market Trajectory and Structural Signals
The historical evolution of the spunbond nonwoven fabrics market reveals a steady, broad-based expansion rather than a single-cycle surge. From 2020 through 2025, growth was supported by robust post-pandemic hygiene demand, continued medical and filtration applications, and the gradual penetration of spunbond materials into automotive interiors, geotextiles, and agricultural uses. The forecast period extends this narrative, projecting acceleration in select end-use categories while challenging players to manage input cost exposure and regional competitiveness.
Several structural signals are particularly relevant for 2026 planning. First, demand is increasingly bifurcated by performance and sustainability requirements. High-loft and specialized spunbond grades are gaining traction where lightweighting, breathability, and filtration efficiency matter, while conventional commodity volumes remain critical for hygiene and base medical applications. Second, regional growth patterns are diverging as regional demand bases, trade policy, and local capacity build-out alter relative competitiveness. Third, raw material dynamics are reshaping cost structures: polypropylene feedstock prices rose 25.74 percent year-over-year by March 2026, reflecting petroleum market dynamics that directly affect spunbond nonwoven production costs and converter margins.
These forces require a decision framework that goes beyond top-line growth estimates. Companies must evaluate where demand is structurally durable versus cyclically sensitive, how regional capacity additions will affect supply availability and pricing, and which material and regulatory variables will most impact unit economics. The research provides these answers through demand-side segmentation, supply-side capacity analysis, and scenario-based considerations that link macro trajectory to operational choices.
Meltblown PP Nonwoven Fabric Market
What the Research Delivers
This report is built for practitioners who need actionable intelligence rather than generic market commentary. It combines a comprehensive market assessment with operational depth, allowing teams to translate industry-wide momentum into segment, regional, and application-specific strategies. Key content areas include:
- A detailed market sizing and forecast framework spanning historical performance and a multi-year outlook, enabling leaders to benchmark internal plans against industry trajectory and evaluate the timing of capacity or product launches.
- Segment-level analysis across material types and application categories, with a focus on the drivers of demand intensity, substitution risk, and pricing dynamics that differentiate commodity and specialty spunbond nonwoven fabrics.
- A regional perspective that maps growth momentum, supply conditions, and competitive intensity across major markets, helping firms assess where to expand, source, or reposition their commercial footprint.
- Competitive landscape profiling of leading manufacturers and suppliers, including strategic focus areas, application strengths, and recent capacity and investment activity that influence market balance.
- Market structure indicators that illuminate concentration and the degree of fragmentation or consolidation, supporting channel strategy, negotiation leverage, and partnership decisions.
- Regulatory and sustainability analysis covering carbon-related mechanisms, product stewardship rules, chemical compliance expectations, and recycled content pressures that are reshaping material choices and import competitiveness.
- Supply chain and cost considerations, including raw material price behavior, tariff exposure, and conversion constraints, with implications for sourcing strategy and margin protection.
Throughout the report, findings are presented in a way that supports scenario planning. Readers can assess how changes in feedstock costs, regulatory timelines, or regional capacity additions might alter demand distribution, competitive positioning, and return profiles. This approach is particularly valuable for 2026 decisions, where the combination of strong demand and heightened external uncertainty rewards preparation over reaction.
Competitive Landscape: Strategic Focus Across Leading Players
The spunbond nonwoven fabrics market is shaped by a mix of global integrators and specialized manufacturers, each pursuing distinct application strengths and regional priorities. The report profiles leading companies whose activities illustrate the strategic diversity now defining the sector.
Berry Global Group, Inc., headquartered in Evansville, Indiana, USA, operates as a major producer and supplier of spunbond nonwoven fabrics primarily for hygiene, medical, and industrial applications. Its scale and broad application footprint make it a central reference point for understanding how integrated players manage volume demand while developing specialized grades. Freudenberg Performance Materials SE, based in Weinheim, Germany, is a leading manufacturer focused on filtration, automotive, and industrial markets, reflecting the importance of performance-grade spunbond materials in technical applications where functional differentiation matters more than pure cost competition.
Spunbond Nonwoven Fabrics Market
Kimberly-Clark Corporation, headquartered in Irving, Texas, USA, is a key producer for hygiene and consumer products, with a strong presence in end-markets where brand strength, consistent quality, and supply reliability are critical. Ahlstrom-Munksjö Oyj, based in Helsinki, Finland, manufactures sustainable spunbond nonwoven fabrics for medical and hygiene applications, positioning sustainability attributes as part of product value rather than a separate compliance exercise. Mogul Nonwovens, in Gaziantep, Turkey, produces spunbond nonwoven fabrics for automotive, filtration, and hygiene markets, illustrating how regional manufacturers can serve diversified demand while remaining responsive to regional cost and sourcing conditions.
Toray Industries, Inc., in Tokyo, Japan, supplies high-performance spunbond nonwoven fabrics for automotive interiors and filtration, reinforcing the role of advanced material engineering in premium applications. Fitesa S.A., headquartered in Simpsonville, South Carolina, USA, is a global manufacturer serving hygiene, medical, and industrial uses, with an emphasis on scale and breadth of application coverage. Sandler AG, in Halberstadt, Germany, produces spunbond nonwoven fabrics for filtration and technical textiles, aligning with the growing demand for engineered nonwovens in specialized end-uses.
Asahi Kasei Corporation, also based in Tokyo, Japan, provides spunbond nonwoven fabrics for hygiene, medical, and filtration applications, combining material expertise with demand across both consumer-facing and technical markets. PFNonwovens Holding s.r.o., in Prague, Czech Republic, focuses on hygiene and medical products, highlighting how regional players can build defensible positions in high-consistency end-markets. Together, these companies demonstrate that competitive advantage in spunbond nonwoven fabrics is increasingly defined by application specialization, regional responsiveness, sustainability credentials, and the ability to manage capacity and input-cost volatility.
Recent Developments and Capacity Dynamics
Capacity expansion and capital deployment are central themes in the current market environment, and several recent moves illustrate how competitors are positioning for the forecast period. In February 2025, Avgol Nonwovens unveiled a new high-speed, high-capacity flexible multiple beam spunbond production line at its Mocksville, NC facility following a 100 million USD investment, delivering additional spunbond nonwoven capacity and high-loft products. This move signals not only volume expansion but also a focus on differentiated, higher-value structures.
In May 2025, Kimberly-Clark Corporation announced a 2 billion USD investment over five years in its North America business, including major expansion for polypropylene spunbond nonwoven fabric production with a 50 percent capacity increase. This is a strong indicator of confidence in sustained demand and an emphasis on securing supply for key end-markets. Also in May 2025, Spunweb Group acquired two advanced polypropylene spunbond production lines, increasing capacity by approximately 53 percent, from 12,240 MTPA to 18,740 MTPA. The transaction underscores how consolidation of production capability can rapidly alter regional supply dynamics and competitive standing.
These developments matter for 2026 planning because capacity additions do not simply shift volume; they reshape lead times, regional availability, and pricing leverage across segments. Where new capacity is directed toward high-loft or specialized grades, it may ease bottlenecks in premium applications while intensifying competition in standard grades. Where expansion is concentrated in particular regions, it can alter relative import dependence and shift the economics of local conversion versus imported material. The report analyzes these dynamics in greater detail, helping firms anticipate where competitive pressure will intensify and where supply security will become a strategic differentiator.
Regulatory and Supply Chain Forces Reshaping the Market
Market growth alone does not determine profitability or strategic success; the regulatory and supply chain backdrop is equally important. Several developments are recalibrating competitiveness and material strategy in the spunbond nonwoven fabrics sector. On the regulatory front, the EU Carbon Border Adjustment Mechanism and Packaging and Packaging Waste Regulation are recalibrating import competitiveness for polypropylene nonwoven fabrics in Europe. At the same time, REACH and SVHC compliance requirements for polypropylene resins are driving development of sustainable and bio-based alternatives in spunbond nonwoven manufacturing. In parallel, European Union and North American environmental regulations on plastic waste are compelling a shift toward recycled content in spunbond nonwoven fabrics.
Trade policy is also introducing uncertainty. Section 122 tariffs on polypropylene imports create uncertainty for North American converters in the spunbond nonwoven market, adding a variable that can affect landed costs and sourcing flexibility. Combined with the 25.74 percent year-over-year rise in polypropylene feedstock prices by March 2026, these factors place renewed importance on procurement strategy, formulation alternatives, and product design choices that can reduce exposure to input volatility.
Why This Research Matters for 2026 Decisions
In a market expanding toward 26.58 billion USD by 2032 with a 6.1 percent CAGR across the forecast period, the margin between participation and leadership will be defined by how well companies align strategy with the forces shaping supply, demand, and regulation. The spunbond nonwoven fabrics market is not simply getting larger; it is becoming more segmented, more policy-sensitive, and more dependent on operational agility. Companies that can match capacity decisions to durable end-use demand, manage raw material exposure, and anticipate regulatory change will be better positioned to protect margins and capture share.
This research provides the structure needed to make those choices with confidence. It synthesizes market sizing, segment behavior, competitive moves, and external pressures into a coherent decision framework, allowing leadership teams to evaluate where to invest, where to consolidate, where to differentiate, and where to hedge. Given the pace of recent capacity expansion and the evolving regulatory landscape, 2026 is a pivotal year for establishing a durable competitive position. The full report delivers the detailed segmentation, regional momentum, application trends, and competitive intelligence necessary to turn market growth into strategic advantage.
To access the complete analysis and the specific data behind these market-wide trends, please visit the source page for the full publication and supporting materials.
For detailed analysis of this topic, please visit the official page: Spunbond Nonwoven Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


