



PW Consulting: Holographic Anti-Counterfeiting Market to Reach $985M by 2032, Growing at 4.0% CAGR

Illuminating the Path to Authenticity: Strategic Insights into the Holographic Anti-Counterfeiting Marks Market 2026–2032
In an era where counterfeit goods erode brand equity, compromise consumer safety, and violate global trade compliance, holographic anti-counterfeiting marks have evolved from decorative finishes into mission-critical security infrastructure. As regulatory scrutiny intensifies and supply chain vulnerabilities expose high-value products to sophisticated forgery, the demand for optically secure, tamper-evident, and instantly verifiable markings has never been more indispensable. At PW Consulting, we have authored a comprehensive market study that cuts through surface-level industry narratives to deliver an actionable, forward-looking intelligence framework. This article serves as a strategic preview of our latest research, outlining how the holographic anti-counterfeiting marks sector is positioned for measurable expansion, how structural market forces are reshaping competitive boundaries, and why procurement leaders, brand protection officers, and investors require granular, data-backed intelligence to navigate the 2026–2032 horizon.
Market Trajectory and the Strategic Imperative for 2026 Planning
Over the historical review window of 2020 through 2025, the global market for holographic anti-counterfeiting marks demonstrated consistent upward momentum, reflecting a structural shift from reactive anti-fraud measures to proactive, integrated authentication strategies. From a baseline of USD 620.0 million in 2020, market revenue progressed steadily to USD 754.0 million by 2025, signaling that optical security has transitioned from a niche compliance requirement to a mainstream operational priority across multiple product categories. This growth trajectory was not accidental; it reflects sustained industry investment in higher-fidelity optical features, broader deployment of tamper-evident overlays, and increasing reliance on holographic verification as a first-line defense against product duplication.
Looking ahead through the 2026–2032 forecast horizon, the expansion narrative continues with disciplined, compounding growth. The market is projected to advance from approximately USD 770.5 million in 2026 to USD 985.0 million by 2032, underpinned by a forecast period CAGR of 4.0 percent. This trajectory underscores a critical strategic reality for decision-makers: growth will not be driven by volume saturation alone, but by deepening penetration in regulated categories, rising demand for multi-layered authentication architectures, and geographic expansion in regions where enforcement frameworks are maturing. For enterprises mapping procurement budgets, supply chain security investments, and brand protection roadmaps in 2026, understanding how this growth distributes across technology formats, end-use categories, and regional enforcement climates is essential to avoiding misaligned capital allocation.
Our study is engineered specifically to address that planning gap. Instead of presenting a static snapshot, it contextualizes revenue progression within the operational factors that truly shape procurement and investment decisions: the pace of regulatory adoption, the evolution of optical master origination capabilities, the shift toward integrated security supply chains, and the competitive responses of established manufacturers and emerging innovators. By linking historical performance to forward-looking market engineering, the report provides a reliable compass for stakeholders who must translate market size into sourcing strategy, risk mitigation, and growth positioning.
The 2026 Landscape: Regulation, Standards, and Structural Demand Drivers
The current market environment is being redefined by a convergence of policy mandates, standardization initiatives, and technological maturity. One of the most consequential forces shaping demand is the tightening of regulatory frameworks that require visible, easily verifiable security features on high-risk consumer and industrial products. In regulated sectors, the presence of holographic seals is increasingly less about brand aesthetics and more about compliance feasibility, inspection efficiency, and liability management. As authorities enforce tamper-proof visual indicators and authentication protocols, organizations that delay integration of robust optical security face not only legal exposure but also the operational burden of retroactive packaging redesigns and supply chain disruptions.
Parallel to regulatory pressure, standardization efforts are elevating the technical expectations for optical security solutions. Industry bodies are reinforcing guidelines that help organizations verify authenticity, assess performance, and reduce ambiguity in supplier selection. The growing emphasis on documented verification methodologies and structured authentication standards means that procurement teams can no longer evaluate holographic marks solely on visual appearance or unit cost. They must assess durability, replication resistance, integration compatibility, and conformity with recognized authentication frameworks. This shift favors suppliers that can demonstrate technical rigor, repeatable production quality, and alignment with internationally acknowledged verification principles.
On the production side, the technical foundation of high-security holographic marks remains anchored in master origination. The creation of precise optical masters represents the most crucial step in manufacturing secure anti-counterfeiting features, because the fidelity of the final output is directly tied to the quality of the original recording process. Advanced laser-based photoresist recording and specialized origination systems are now essential for producing marks that withstand scrutiny from both end users and counterfeiters attempting replication. As a result, the market is gradually rewarding manufacturers that control or closely integrate master origination capabilities, rather than relying exclusively on commodity-style reprographic workflows.
These dynamics create a dual strategic implication for 2026. First, demand is becoming more specification-driven, with procurement decisions increasingly anchored in performance criteria, regulatory fit, and verification reliability. Second, competitive advantage is shifting toward firms that can offer end-to-end optical security engineering, from master creation to final label or film deployment, while maintaining traceability and consistency across production runs. Understanding how these forces interact across market segments is central to the analytical framework presented in our full study.
Market Architecture: Formats, Applications, and Regional Dynamics Without the Noise
A central challenge for market participants is navigating structural segmentation without losing sight of total-market opportunities. Holographic anti-counterfeiting marks are delivered through multiple physical formats, each with distinct production considerations, integration requirements, and end-use suitability. Broadly, the market is anchored by holographic film-based solutions and holographic paper-based solutions, with film continuing to command the larger revenue share due to its broader adaptability in high-durability packaging, secure labeling, and multi-layer authentication architectures. Paper-based formats remain strategically relevant in applications where cost efficiency, print compatibility, and rapid deployment are prioritized. However, the operational choice between formats rarely hinges on substrate preference alone; it is increasingly defined by the required level of optical complexity, the environment in which the mark must survive, and the verification methods used by downstream inspectors and consumers.
On the application side, demand is dispersed across diverse end-use sectors, with particularly notable reliance in categories where product authenticity carries direct economic and safety implications. Tobacco products continue to represent a substantial share of deployment, driven by regulatory mandates for authentication marks and prominent health-warning compliance. Food and drink applications follow as another major demand channel, where brand trust, supply chain integrity, and consumer safety converge. The cosmetic sector also contributes meaningful volume, reflecting the premium-brand imperative to prevent counterfeiting and protect consumer confidence in high-margin personal care products. Beyond these core verticals, a broad residual category of applications spans documents, pharmaceuticals-adjacent packaging, luxury goods, and industrial components, reinforcing that holographic anti-counterfeiting marks are not confined to a single industry narrative but are becoming a cross-sector authentication layer.
Holographic Anti-counterfeiting Marks Market
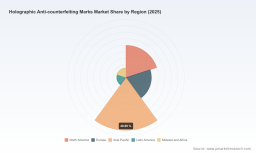
Regionally, market distribution reflects the interplay of manufacturing capacity, enforcement maturity, and end-market density. Asia Pacific stands out as a significant revenue region, consistent with its scale in packaging production, industrial manufacturing, and fast-moving consumer goods ecosystems. North America and Europe remain influential demand centers, shaped by stringent regulatory expectations, strong brand-protection cultures, and well-established authentication practices. Latin America and the Middle East and Africa collectively represent meaningful but comparatively smaller revenue pools, with growth potential tied to improving compliance enforcement, expanding export-oriented production, and increasing adoption of standardized security marking practices.
Rather than fragmenting the analysis into isolated percentage breakdowns, our study interprets these structural patterns as interacting forces. It examines where format preferences align with application requirements, where regional enforcement frameworks accelerate adoption, and where supply-side capabilities are redefining market access. This integrated perspective allows readers to see not just where revenue is generated, but why it is generated there and how that positioning is likely to shift through 2032.
Competitive Dynamics: Consolidation, Capability, and the New Innovation Perimeter
The competitive landscape for holographic anti-counterfeiting marks is characterized by a blend of established multinational suppliers, specialized regional manufacturers, and technology-focused entrants expanding the innovation perimeter. Market concentration data indicates a moderately consolidated structure, with the top three players collectively accounting for approximately 45.0 percent of market revenue and the top five reaching around 55.0 percent. This concentration suggests that while scale and integrated capabilities provide meaningful advantages, there remains sufficient space for differentiated specialists to compete on technical novelty, regional responsiveness, and application-specific engineering.
Leading participants illustrate the breadth of strategic postures now shaping the sector. Suzhou Image Technology Co., Ltd. has built a long-standing presence in optical security production, offering custom holographic security labels, hologram stickers, laminate overlays, and anti-counterfeiting solutions with more than two decades of experience in the field. Its recent 20th anniversary celebration in April 2026 reinforced continuity in its security hologram focus, even as the broader market demands more sophisticated integration and verification support. In India, Holographic Security Marking Systems P. Ltd. has positioned itself as a pioneer in holographic security tapes, tamper-evident labels, hologram stickers, and void security seals, reflecting the rising regional importance of practical, enforcement-friendly authentication tools.
Everest Holovisions Limited contributes to the competitive mix through metalized holographic films and security holographic labels designed for enhanced product security, while AFC Hologram specializes in security holograms, holographic registered packaging, lens films, and 3D micro-nano relief structures that push the boundaries of replication difficulty. Shenzhen Holoart High Technology Company Limited and Light Logics Holography and Optics Pvt Ltd further expand the supply base with advanced holographic security features and optical security labels targeting packaging and consumer product authentication. In the flexible packaging and hybrid security domain, Uflex Limited has developed integrated solutions including holographic seals for brand authentication, demonstrating how packaging manufacturers can embed optical security directly into broader product protection strategies.
In Europe, Kurz has long been recognized for holographic security foils, labels, and anti-counterfeiting packaging solutions developed in collaboration with technology partners, highlighting the importance of cross-industry cooperation in maintaining high optical standards. In the United States, Crane Authentication Solutions provides advanced holographic and optical security markings for currency, documents, and products, while in the United Kingdom, De La Rue has advanced optical security through platforms such as OPTILIGHT™, extending holographic applications into high-security environments. HUECK FOLIEN GmbH adds further depth in Europe as a manufacturer of holographic security foils and labels for brand protection and anti-counterfeiting packaging. Kumbhat Holographics rounds out the competitive field as a specialist in holographic security markings and anti-counterfeiting solutions, reinforcing the continued presence of focused, application-oriented suppliers across multiple markets.
Recent industry developments underscore that competition is increasingly defined by collaboration, standardization, and ecosystem expansion as much as by product specifications. In May 2026, IOTA expanded its global anti-counterfeiting dialogue to include banknotes, brand protection, and secure documents, strengthening collaboration with member companies. Earlier in the year, IOTA launched a new membership category for optical security start-ups to foster innovation in anti-counterfeiting technologies, alongside the introduction of the DocCheck Analysts Insights tool to support document verification and authentication for members. These moves matter because they indicate a market in which technology validation, shared verification practices, and access to emerging innovators are becoming integral to competitive resilience.
For enterprise decision-makers, this dynamic environment carries a clear message: sourcing strategy cannot assume static supplier capabilities. Instead, organizations must assess manufacturers not only on current output but on their ability to evolve with regulatory expectations, integrate master origination and replication expertise, participate in authentication ecosystems, and adapt to new verification tools. The full report provides a structured competitive assessment that connects company profiles, strategic focus areas, and recent developments to the practical questions procurement and brand-protection teams face when selecting long-term security partners.
What the Study Delivers: From Macro Signals to Operational Decisions
PW Consulting’s Holographic Anti-Counterfeiting Marks Market study is built to bridge the gap between high-level market awareness and operational decision-making. The report combines long-term market sizing, segmentation interpretation, competitive profiling, and regulatory analysis into a single intelligence framework designed for action. Rather than presenting numbers in isolation, it situates them within the business context that determines their relevance: procurement planning, compliance readiness, technology selection, supplier evaluation, and long-range investment prioritization.
readers can expect detailed coverage of market evolution across the historical and forecast periods, with analysis of how revenue trends reflect shifting demand drivers, format preferences, and application adoption patterns. The study examines the structural logic behind segmentation, helping users understand where holographic film and holographic paper solutions are gaining traction, how application-specific requirements shape deployment strategies, and where regional enforcement and manufacturing dynamics influence market access. It also contextualizes competitive behavior by linking company capabilities and recent milestones to broader market forces, enabling more informed benchmarking and risk assessment.
Equally important is the report’s emphasis on practical interpretation. It addresses the operational significance of optical master origination, the role of specialized production equipment in maintaining high-security standards, and the implications of regulatory frameworks that mandate tamper-proof visual indicators and authentication features. By integrating these elements, the study helps organizations move beyond generic market descriptions and toward precise procurement and strategy decisions. For executives preparing 2026 budgets and three-to-five-year security roadmaps, that interpretive depth is essential. Core quantitative breakdowns, scenario-based sensitivity insights, and vendor-specific benchmarking detail are reserved for the full report, where they can be examined with the precision required for confident decision-making.
Why This Intelligence Matters for 2026 Strategic Planning
The 2026–2032 period will not simply be defined by continued market growth; it will be defined by how effectively organizations translate that growth into defensive advantage and commercial resilience. Holographic anti-counterfeiting marks are increasingly embedded in regulatory compliance, brand protection, and supply chain integrity strategies, which means the cost of incomplete market intelligence is rising. Companies that rely on fragmented data or surface-level market descriptions risk under-investing in the wrong formats, selecting suppliers misaligned with future authentication expectations, or misreading regional demand shifts that affect sourcing and product rollout timing.
This study is designed to reduce those risks. It helps procurement leaders evaluate format and application fit with greater confidence, enables brand-protection teams to align security investments with enforcement trends and verification standards, and supports executives in understanding where competitive concentration creates stability and where emerging innovators may reshape the value chain. With a forecast CAGR of 4.0 percent and revenue projected to approach USD 985.0 million by 2032, the market is large enough to matter and dynamic enough to reward those who plan with precision. The question is no longer whether optical security will continue to grow, but how organizations will position themselves to capture the right opportunities within that growth.
Access the Full Intelligence Framework
This preview has outlined the strategic logic behind the market’s trajectory, the forces reshaping competition, and the operational considerations that should guide 2026 decision-making. It has intentionally avoided presenting the full set of segmented revenue breakdowns, region-by-region percentage distributions, and application-level market shares that form the analytical backbone of the complete study. Those details are essential for precise planning, and they are available in the full report, where each figure is supported by methodological context, competitive interpretation, and implementation relevance.
Holographic Anti-Counterfeiting Trademark Market
For organizations that need to move from market awareness to actionable strategy, the complete PW Consulting Holographic Anti-Counterfeiting Marks Market study offers the depth, structure, and forward-looking perspective required to make informed choices in a rapidly evolving security landscape. To access the full dataset, segmentation analysis, competitive profiling, and forecast decomposition, please visit the source page for the complete market research.
For detailed analysis of this topic, please visit the official page: Holographic Anti-counterfeiting Marks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


