



PW Consulting: Solid-State Battery Market Hits $160M in 2025, Projected 36.78% CAGR to $1.43B by 2032

Navigating the Solid-State Revolution: Strategic Imperatives for 2026 and Beyond
The global energy storage landscape is undergoing a paradigm shift. As lithium-ion technology approaches its theoretical limits, solid-state batteries (SSBs) have emerged as the definitive next-generation solution, promising unprecedented energy density, enhanced safety, and faster charging capabilities. However, the transition from laboratory breakthrough to commercial scale is fraught with complex supply chain dynamics, regulatory hurdles, and intense competitive maneuvering. For industry leaders navigating the 2026 fiscal year, understanding the nuances of this market is not merely an option—it is a strategic necessity.
Solid State Chip Battery Market
Our latest comprehensive market research, Solid State Batteries Market: Global Industry Outlook 2026-2032 , provides a granular dissection of this rapidly evolving sector. This article serves as a strategic preview, highlighting the critical macro-trends and competitive forces that will define investment decisions and R&D roadmaps in the immediate future.
The Trajectory of Growth: A Macro Perspective
The momentum behind solid-state technology is no longer theoretical; it is reflected in hard financial data. The market has demonstrated explosive growth over the past half-decade, signaling a tipping point in commercial viability. Based on our analysis of historical performance and projected trajectories, the sector has moved from nascent experimentation to tangible revenue generation.
In 2020, the global market valuation stood at approximately 39.45 million USD. By 2025, this figure has surged to 160.0 million USD, reflecting a compound annual growth rate that underscores the accelerating adoption rates across key verticals. Looking ahead, the forecast period from 2026 to 2032 indicates continued aggressive expansion. We project the market size to reach 222.25 million USD in 2026, climbing steadily to exceed 1.4 billion USD by 2032. This growth trajectory is underpinned by a CAGR of 36.78 percent, highlighting the robust demand drivers emanating from both the automotive and consumer electronics sectors.
For stakeholders, these numbers represent more than just market size; they indicate the velocity at which capital is flowing into the ecosystem. The jump from 2025 to 2026 alone suggests that initial commercialization phases are successfully translating into scalable revenue streams. However, volume alone does not guarantee success. The distribution of this value across technologies, applications, and geographies reveals a fragmented landscape where strategic positioning is critical.
Competitive Landscape: The Race for Commercialization
The SSB market is characterized by a diverse array of players, ranging from established automotive giants to specialized technology startups. Our report profiles key companies that are actively shaping the industry standard. The competitive dynamics are not just about who has the best chemistry, but who can secure supply chains, meet regulatory certifications, and achieve mass-production timelines.
Automotive Leaders and Battery Specialists
Traditional automotive powerhouses are leveraging their vertical integration to accelerate SSB deployment. Toyota Motor Corporation, based in Tokyo, remains a leading developer of sulfide-based all-solid-state batteries. Their recent achievement of Japan METI certification for automotive-grade solid-state battery cells from Prime Planet Energy & Solutions in February 2026 validates thermal runaway resistance, a critical milestone for mass production targeting EVs by 2027-2028. Similarly, Panasonic Holdings Corporation in Osaka is collaborating with Toyota to enhance safety and energy density in EVs, reinforcing the Japan-centric push toward sulfide electrolytes.
In China, CATL Co., Ltd. continues to assert its position as a global leader in battery technology, advancing solid-state and semi-solid solutions for higher energy density and safety. Meanwhile, ProLogium Technology Co., Ltd. in Hsinchu, Taiwan, is targeting GWh-scale production capacity for automotive and industrial applications.
South Korea remains a critical hub for battery innovation. Samsung SDI Co., Ltd., headquartered in Suwon, is developing pouch-type all-solid-state batteries for physical AI and automotive applications, targeting mass production in 2027 with advanced safety and power output. LG Energy Solution, based in Seoul, is concurrently developing solid-state battery technologies for automotive and energy storage applications.
North American innovators are also making significant strides. QuantumScape Corporation in San Jose is developing ceramic-separator lithium-metal solid-state batteries, with QSE-5 cells validated for Volkswagen BEV platforms and 1,000-cycle testing. Solid Power, Inc., based in Louisville, is partnering with BMW, Ford, and Samsung SDI for next-generation EV and other markets.
Niche Innovators and Industrial Applications
Beyond the automotive heavyweights, specialized firms are carving out niches. Blue Solutions SAS in Clermont-Ferrand, France, produces solid-state batteries for industrial and transport applications, holding IATF 16949 certification and delivering joint development agreements and A-samples. Donut Lab in Finland has announced the world's first all-solid-state battery ready for commercial OEM production, with initial deployment slated for Verge Motorcycles in Q1 2026.
Solid State Batteries Market
These developments illustrate a market that is branching out. While EVs remain the primary volume driver, industrial transport and specialized AI hardware are becoming viable early-adopter segments.
Recent Developments and Strategic Timelines
The pace of recent announcements underscores the urgency for market participants. In March 2026, Samsung SDI unveiled its first public pouch-type all-solid-state battery sample at InterBattery 2026 for physical AI applications, targeting mass production in the second half of 2027. This follows Donut Lab's February 2026 announcement regarding commercial OEM readiness.
These timelines are critical for procurement and partnership strategies. Companies aiming to integrate SSB technology into product lines for the 2027-2028 model years must engage with suppliers now. The gap between sample validation and mass production is narrowing, but capacity constraints remain a significant risk factor.
Supply Chain Vulnerability and Regulatory Headwinds
While the growth projections are optimistic, the path to 2032 is lined with geopolitical and operational complexities. Our research highlights several structural friction points that could alter cost structures and availability.
Raw Material Constraints
The chemistry of solid-state batteries dictates specific supply chain dependencies. Sulfide solid electrolytes, a leading candidate for high-performance applications, use lithium sulfide as a key component. Prices for these materials remain elevated due to limited global supply and specialty chemical production requirements. Furthermore, manufacturing solid-state batteries often requires inert-atmosphere processing for sulfide electrolytes. Our analysis estimates this increases production costs by 15-20 percent compared to liquid-electrolyte systems, creating a higher barrier to entry for cost-sensitive applications.
Geopolitical and Regulatory Pressures
National security and sustainability concerns are reshaping trade flows. China's export controls on battery materials, including those relevant to solid-state battery electrolytes, took effect in November 2025. This regulation directly impacts the availability of critical inputs for manufacturers outside of China.
In Europe, the Battery Directive and related critical raw materials regulations emphasize sustainability and reduced dependence on concentrated supply chains for solid-state technologies. Compliance with these directives will require transparency and potentially localized sourcing strategies.
In the United States, tariffs on Chinese lithium-ion battery components and imports, including those affecting solid-state supply chains, reached up to 156 percent composite rates as of April 2025. These tariffs fundamentally alter the economics of cross-border supply chains, potentially encouraging near-shoring or friend-shoring of production capabilities.
Market Concentration and Fragmentation
Despite the long list of active participants, the market remains relatively fragmented. Our data indicates a CR3 of 18.7 percent and a CR5 of 23.5 percent. This low concentration suggests that no single entity currently dominates the value chain, offering opportunities for new entrants or specialized partners to capture niche value. However, it also implies that consolidation may be on the horizon as economies of scale become paramount to meet the cost targets required for mass adoption.
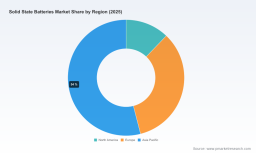
The segmentation data reveals where the current value is being generated. In terms of technology, Thin Film Battery technology currently commands a significant share of the revenue mix compared to Portable Battery solutions, reflecting the maturity of certain solid-state applications in niche electronics versus broader power storage. Regarding applications, Consumer & Portable Electronics currently account for a larger portion of market revenue than Electric Vehicles, although the latter is expected to drive the majority of volume growth in the latter half of the forecast period. Geographically, the Asia Pacific region continues to lead in revenue contribution, followed by Europe and North America, aligning with the location of key manufacturing hubs and demand centers.
Why This Report Matters for 2026 Decision-Making
In a market moving at this velocity, general industry knowledge is insufficient. Strategic decisions regarding capital allocation, supplier partnerships, and R&D focus require precise, validated data. The Solid State Batteries Market: Global Industry Outlook 2026-2032 report is designed to provide that clarity.
Our research goes beyond surface-level trends. It offers a deep dive into the operational realities of the supply chain, the specific technical milestones achieved by key players, and the regulatory frameworks that will govern market access. By analyzing the interplay between raw material costs, manufacturing complexities, and geopolitical tariffs, we provide a risk-adjusted view of the market potential.
For automotive OEMs, the report details the readiness levels of various suppliers and the implications of certification timelines. For investors, it maps the competitive landscape to identify consolidation opportunities and technology winners. For policy makers and industry associations, it clarifies the supply chain vulnerabilities exposed by recent export controls and tariff adjustments.
Accessing the Full Intelligence
The solid-state battery market is poised to redefine energy storage over the next decade. The window to establish competitive advantage is open, but it is closing faster than anticipated. Companies that delay their strategic planning risk being locked out of supply chains or forced to adopt inferior technologies due to capacity constraints.
This article has outlined the macro trajectory, the key players, and the external pressures facing the industry. However, the specific segmentation data, detailed regional analysis, and granular forecasts contained in our full study are essential for building a robust business case. The complete report provides the detailed breakdowns of revenue splits, specific growth drivers per segment, and comprehensive company profiles that are necessary for actionable strategy.
To secure your organization's position in this evolving landscape, we invite you to access the full Solid State Batteries Market research publication. Download the complete report to gain the competitive edge required for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Solid State Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


