



PW Consulting: Biosurfactant Sales Hit $9.02B in 2025, Forecast to $16.93B by 2032 at 9.41% CAGR

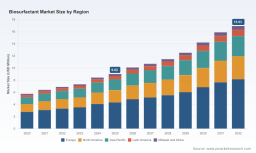
Biosurfactants Market 2026: Strategic Intelligence for the Green Chemistry Transition
The global chemical landscape is undergoing a paradigm shift, driven by stringent environmental regulations, consumer demand for sustainable products, and the urgent need to reduce reliance on petrochemical derivatives. At the forefront of this transition lies the biosurfactant sector. For strategic decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise but a critical component of supply chain resilience and product portfolio optimization. PW Consulting's latest market research provides a comprehensive roadmap for navigating these complexities, offering data-driven insights that extend beyond surface-level trends to uncover underlying structural shifts.
This analysis serves as a strategic overview of the biosurfactant landscape, synthesizing historical performance, growth projections, and competitive dynamics. It is designed to equip industry leaders with the context necessary to make informed capital allocation and product development decisions in a rapidly evolving environment.
Market Trajectory and Growth Momentum
The biosurfactant market has demonstrated consistent resilience and expansion over the past half-decade. Historical data from 2020 through 2025 indicates a steady upward climb in revenue, reflecting the gradual but firm integration of bio-based solutions into mainstream industrial and consumer applications. The market valuation has grown from approximately $5.75 billion in 2020 to an estimated $9.02 billion by 2025. This historical performance lays the groundwork for an aggressive forecast period extending through 2032.
Looking ahead to the 2026-2032 forecast period, the trajectory suggests an acceleration in adoption rates. The market is projected to reach $10.1 billion in 2026, growing to nearly $16.93 billion by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of 9.41 percent. Such growth rates indicate that biosurfactants are moving from niche applications to mainstream commoditization in specific high-value segments. For stakeholders, this implies that the window for establishing early-mover advantages in supply chain partnerships and proprietary formulation technologies is narrowing.
It is crucial to note that this growth is not uniform across all vectors. While the aggregate numbers paint a picture of robust health, the underlying distribution of revenue across regions and applications reveals strategic opportunities that remain partially obscured without granular analysis. The overall market size figures provide a macro foundation, but the real strategic value lies in understanding where the marginal growth dollars are originating and which segments are driving the CAGR.
Industry Dynamics and Regulatory Tailwinds
The acceleration of the biosurfactant market is inextricably linked to a confluence of regulatory pressures and raw material innovations. Several key dynamics are reshaping the cost structures and compliancerequirements for manufacturers, creating both headwinds for traditional petrochemical surfactants and tailwinds for bio-based alternatives.
Regulatory frameworks in major markets have tightened significantly. In Europe, the EU REACH regulations have imposed stricter rules on poorly biodegradable surfactants, prompting a rapid substitution effect. Companies utilizing traditional surfactants face increasing compliance costs and reputational risks, driving them to seek biodegradable alternatives. Furthermore, the EU Industrial Emissions Directive and REACH Annex XVII have introduced new benchmarks requiring biodegradable surfactant alternatives in various industrial processes. These regulatory shifts are not merely compliance checkboxes but are fundamentally altering the addressable market for biosurfactants.
On the policy front, the EU Renewable Energy Directive III has designated glycerol-based biosurfactant products as advanced bio-based chemicals. This designation unlocks carbon credits, improving the economic viability of production and incentivizing investment in glycerol-based pathways. Similarly, in the United States, the EPA Safer Choice program has expanded its listings of green surfactants, enabling biosurfactants like rhamnolipids to serve as compliant alternatives for manufacturers seeking eco-labels.
Raw material dynamics are also playing a pivotal role. A significant development in fermentation economics involves the substitution of crude glycerol from biodiesel production for refined vegetable oils in rhamnolipid fermentation. This shift cuts feed costs substantially, resulting in lower biosurfactant ex-factory prices. This cost optimization enhances the competitiveness of biosurfactants against their synthetic counterparts, removing one of the primary barriers to adoption in price-sensitive applications.
Competitive Landscape and Strategic Positioning
The competitive environment in the biosurfactant market is characterized by a mix of established chemical giants and specialized biotechnology firms. Concentration metrics indicate a consolidated landscape where a small number of players hold significant sway. The CR3 and CR5 concentration ratios both stand at 40.7 percent, suggesting that while the top tier is influential, there is substantial room for mid-tier and niche players to capture value through specialization and regional focus.
Leading incumbents are leveraging their scale and technical expertise to secure market share. Evonik Industries AG, headquartered in Essen, Germany, focuses on producing high-purity rhamnolipids and sophorolipids from renewable corn feedstocks via industrial-scale fermentation at its Slovak plant. This capability allows them to supply consistent, high-quality volumes to demanding sectors. Similarly, Solvay S.A. in Brussels provides biosurfactants and bio-based chemical solutions for both industrial and consumer markets, integrating these products into broader sustainable portfolios. Croda International Plc, based in the UK, produces glycolipid biosurfactants and offers technical support specifically for detergent and personal care uses, highlighting the importance of application-specific know-how.
In personal care and premium applications, Kaneka Corporation and Givaudan SA are prominent. Kaneka manufactures high-purity biosurfactants for premium cosmetic applications, while Givaudan provides biosurfactants for premium personal care and clean-label products, leveraging their fragrance and flavor dominance to cross-sell sustainable ingredients. Stepan Company, operating out of Northfield, Illinois, offers rhamnolipid biosurfactants derived from renewable feedstocks targeted at detergents and personal care, aligning their portfolio with high-volume consumer goods.
Specialized producers are also making significant moves. Jeneil Biotech Inc. and Biotensidon GmbH focus on rhamnolipid and microbial biosurfactants respectively, catering to eco-friendly formulations and eco-labeled detergents. AGAE Technologies, LLC has been particularly active in capacity expansion. In early 2025, they inaugurated the largest retrofitted manufacturing plant in Asia with annual capacity exceeding 1,000 metric tons of rhamnolipid biosurfactants. They subsequently opened a new 3,800 m² plant in Asia with similar capacity and announced US facility plans. Dispersa Inc. in Canada transitioned from pilot reactors to a 50,000 L commercial-scale system targeting 100 metric tons per year of sophorolipids. These capacity expansions signal a shift from R&D curiosity to commercial readiness.
Regional players are also strengthening their positions. Saraya Co., Ltd. and Allied Carbon Solutions Co., Ltd. in Japan specialize in MES and other biosurfactants for industrial cleaning and detergent formulations. Shaanxi Deguan Biotechnology Co., Ltd. in China produces sophorolipid biosurfactants for industrial and personal care markets. Holiferm Ltd. in the UK specializes in sophorolipid production for mass-market eco-friendly surfactants. Locus Fermentation Solutions in the USA develops EPA-approved biosurfactants for personal care and industrial applications. These diverse geographic footprints suggest that supply chain localization is becoming a strategic priority for end-users seeking to mitigate logistics risks.
Report Scope and Methodology
To navigate this complex ecosystem, comprehensive intelligence is required. The PW Consulting Biosurfactant Market research report is structured to provide actionable intelligence across multiple dimensions. The analysis covers a detailed historical review from 2020 to 2025, establishing a baseline for performance evaluation. This historical context is critical for validating growth models and understanding the impact of recent regulatory changes on market uptake.
The forecast period extends from 2026 through 2032, allowing stakeholders to model long-term investment returns and capacity planning. The report dissects the market across key segmentation vectors including region, type, and application. While aggregate growth is positive, understanding the split between Glycolipids, Lipopeptides, and Phospholipids is essential for R&D focus. Similarly, analyzing demand drivers across Detergents, Personal Care, Food Processing, and Oil & Petroleum sectors reveals where margin opportunities are most pronounced. Geographic analysis covers Europe, North America, Asia Pacific, Latin America, and the Mideast and Africa, highlighting regional regulatory nuances and supply chain dynamics.
Microbial Biosurfactants Market
Beyond market sizing, the report includes detailed profiles of key companies, assessing their strategic moves, capacity expansions, and product offerings. Recent developments such as joint ventures, new plant inaugurations, and technology transitions are tracked to provide real-time intelligence on competitive momentum. The analysis also incorporates qualitative dynamics regarding raw material sourcing, regulatory impacts, and technological shifts that quantitative data alone cannot capture.
Biosurfactant Market
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in 2026, the biosurfactant market presents a clear imperative: sustainability is no longer optional, and bio-based chemistry is becoming economically viable. The convergence of regulatory pressure, cost optimization through raw material substitution, and capacity expansion by key players creates a inflection point. Companies that hesitate to integrate biosurfactants risk facing higher compliance costs and supply chain vulnerabilities as petrochemical alternatives face stricter scrutiny.
However, the market is not monolithic. The presence of specialized players alongside giants suggests that partnership strategies will be crucial. A detergent manufacturer may not need to become a fermentation expert but can leverage partnerships with firms like Jeneil Biotech or AGAE Technologies to secure supply. Conversely, ingredient suppliers must navigate the varying requirements of personal care versus industrial cleaning applications, as purity and performance specifications differ significantly.
The data suggests that Asia Pacific and Europe remain critical theaters for growth, driven by both consumption patterns and regulatory leadership. Yet, detailed regional splits and application-specific penetration rates contain the nuanced intelligence required to prioritize specific markets. Access to the full dataset is necessary to identify the specific high-growth pockets within the broader $16.93 billion endpoint.
Investment in capacity, whether through CAPEX or joint ventures, must be timed against the demand curve. The recent capacity expansions by AGAE, Dispersa, and Croda indicate that the supply side is preparing for the forecasted demand. Decision-makers must assess whether their own demand projections align with this incoming supply to avoid market saturation in specific niches or, conversely, to secure offtake agreements before capacity tightens.
Accessing Complete Intelligence
While this overview highlights the macroeconomic trends and competitive dynamics, the full strategic value of the market research lies in the granular data. Detailed segmentation splits, specific regional revenue contributions, and application-level growth rates are essential for building precise financial models and go-to-market strategies. The top-line figures provide confidence in the sector's direction, but the bottom-line details drive allocation decisions.
PW Consulting's comprehensive Biosurfactant Market report offers the depth required to move from general awareness to specific action. It provides the segmentation data, company profiles, and dynamic analysis needed to outperform competitors who rely on aggregate industry knowledge. For organizations seeking to capitalize on the 9.41 percent growth trajectory and navigate the regulatory landscape effectively, acquiring the full intelligence suite is the logical next step. The window to secure strategic positioning in this green chemistry transition is open, but it requires data-backed conviction to act decisively.
For detailed analysis of this topic, please visit the official page: Biosurfactant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


