



PW Consulting: AMI Market to Hit $53.69B by 2032, 11.6% CAGR from 2025

Navigating the AMI Inflection Point: Strategic Intelligence for 2026 and Beyond
The Advanced Metering Infrastructure (AMI) landscape is undergoing a structural transformation that demands more than cursory market awareness. As utilities, technology providers, and infrastructure investors calibrate their roadmaps for 2026, the difference between reactive adaptation and proactive market capture hinges on decision-grade intelligence. Our latest market research synthesizes historical trajectories, forward-looking revenue projections, competitive signaling, and regulatory momentum into a single evaluative framework. This article outlines the strategic contours of that research and explains why granular, forward-looking AMI intelligence has become a non-negotiable input for enterprise decision-making in 2026.
The Scale and Trajectory of the AMI Market
Over the historical window from 2020 through 2025, the global AMI market expanded from approximately 11.28 billion USD to 25.06 billion USD. That near-doubling of reported revenue in five years signals more than cyclical upturn; it reflects a foundational re-architecture of how utilities measure, communicate, and manage consumption data across electricity, water, and gas networks. The momentum does not plateau after the base year. Forecasts extending through 2032 project the market climbing to roughly 53.69 billion USD, sustained by a compound annual growth rate of 11.6 percent. This trajectory places AMI squarely among the infrastructure technologies where capital allocation, partner selection, and product positioning carry long-tail consequences.
Several dynamics explain why this expansion is structurally durable. Meter replacement cycles are accelerating in legacy networks where analog or early-generation digital devices can no longer support real-time outage detection, demand response integration, or consumer-facing analytics. At the same time, grid-edge intelligence is shifting metering from a passive billing endpoint to an active node within distribution automation and distributed energy resource management. The revenue trajectory, when read alongside evolving technical standards and cybersecurity expectations, indicates that spending is migrating from hardware-only procurements toward integrated communication layers, data management platforms, and services that sustain network reliability over multi-decade asset lives.
For executives, the strategic implication is straightforward: AMI is no longer a procurement category evaluated solely on unit cost and certification compliance. It is a platform investment whose value compounds through data accessibility, interoperability, and the ability to scale post-deployment. Market-level projections provide context, but the operational questions that determine outcomes—where to deploy first, which communication architectures to standardize, how to sequence software and services spend—are resolved only through segmented analysis that maps growth pools to specific utility requirements and regional regulatory environments. That level of resolution is the core deliverable of our full study, available through the source page, where detailed breakdowns replace headline figures with decision-ready granularity.
Advanced Metering Infrastructure (AMI) Market
Competitive Architecture and Strategic Positioning
The AMI supplier landscape is characterized by a concentrated core of incumbents complemented by specialized players who compete on regional reach, communication technology, or vertical-specific functionality. The market reveals meaningful concentration at the top, with the three largest firms collectively accounting for a substantial share of industry revenue, while the broader top five maintains equivalent aggregate positioning. This concentration signals that scale advantages in manufacturing, network operations, and data platform development continue to matter. Yet concentration at the top does not imply uniformity of strategy. The competitive field is differentiated by how companies sequence hardware, communication infrastructure, software, and services, and by the extent to which they align their portfolios to utility modernization roadmaps.
Itron continues to anchor its AMI positioning around smart residential and commercial metering solutions built for two-way communication, remote upgradeability, interval data storage, and consumer engagement. Its AMI 2.0 orientation and grid-edge intelligence emphasis illustrate a broader industry shift from closed metering appliances to extensible endpoints that can evolve with distribution system needs. Landis+Gyr has focused its offering on next-generation AMI systems that deliver real-time data visibility, edge-level analytics, and intelligent metering across electric, gas, and water applications. That posture reflects the growing utility expectation that meter networks should contribute directly to grid modernization rather than serve as isolated data collectors. Aclara, operating within a broader network technology context, emphasizes smart metering for electric, gas, and water utilities with enhanced grid reliability and customer interaction enabled by two-way AMI networks.
European and globally operating players add distinct value propositions. Sagemcom has expanded its AMI footprint through the SICONIA AMI 2.0 electricity meter family and end-to-end solutions for energy and water, supported by ANSI certification and advanced communication terminals. Honeywell brings its Alpha 4 series into the residential, commercial, and industrial AMI space, emphasizing two-way communication, tamper detection, and integration into smart grid networks. Kamstrup differentiates through advanced metering solutions for water that incorporate embedded acoustic leak detection, flexible RF and AMI networks, and software designed to improve operational efficiency—a clear example of how metering portfolios are extending beyond measurement into loss reduction and asset management.
Asia-linked and internationally active suppliers further broaden the competitive field. Wasion promotes cellular-based AMI solutions and comprehensive smart metering for electricity, water, gas, and heat, leveraging IoT technology and scalable head-end systems that appeal to utilities seeking deployment flexibility and remote scalability. Iskraemeco contributes with residential smart energy meters and eIoT meter series designed for modular communication, smart grid integration, and optimized energy management.
These company-level orientations matter because procurement decisions in AMI are increasingly portfolio decisions. Utilities and large end-users weigh not only device compliance and price but also the resilience of communication pathways, the extensibility of data management capabilities, and the vendor’s ability to support longitudinal service relationships. Recent project activity reinforces this pattern. In December 2025, Itron and the City of Tucson commissioned a new AMI project for water conservation using cellular-based AMI Essentials, deploying 250,000 smart water communication modules alongside a Network-as-a-Service model. In August 2025, Siemens and TRC Companies collaborated with the Salt River Project to upgrade to Gridscale X MDMS, enhancing scalability and data insights for AMI 2.0 readiness. By April 2026, the Jurupa Community Services District reported 50 percent completion of its systemwide AMI project for water meters since September 2025, enabling real-time monitoring through the EyeOnWater application, while the City of Corona Utilities reached 50 percent of installations in its water AMI project that began in summer 2025 using Professional Meters, Inc. as installer.
These developments are not isolated milestones; together, they show how rapidly utilities are moving from planning to partial deployment and how communication architecture, software integration, and service delivery models are becoming integral to project success. Our full report examines the competitive field in greater depth, mapping product and service positioning, recent project activity, and strategic implications for buyers and suppliers. The source page provides the detailed company analyses, cross-referenced developments, and actionable takeaways that headline summaries cannot capture.
Worldwide Distribution Meter Market
Regulatory Signals and Supply Chain Realities
Regulatory developments in 2025 and early 2026 are reshaping how AMI deployments are justified, communicated, and recovered. In the United States, the Colorado governor signed legislation in May 2025 requiring utilities to notify residential customers before installing AMI and to explain their right to refuse installation, a measure that elevates customer transparency and consent into the deployment process. In July 2025, the Kentucky Public Service Commission granted Kentucky Power’s application for a certificate of public convenience and necessity for AMI deployment and regulatory asset recovery of costs, reinforcing the principle that well-structured AMI investments can be recovered when tied to clearly defined public convenience objectives. At the transmission-system level, Texas legislation signed in June 2025 directed ERCOT to develop a demand management service for mandatory curtailment of large loads, effective on or after January 1, 2026, deepening the connection between metering infrastructure and demand-side flexibility.
Outside the United States, the Energy Regulatory Commission of the Philippines approved amended rules to govern AMI implementation by distribution utilities in November 2025, updating 2016 guidelines with technical standards, cybersecurity protocols, and consumer data privacy safeguards. This regulatory evolution illustrates a broader pattern: jurisdictions are moving from permissive AMI frameworks toward more prescriptive expectations around technical performance, data protection, and consumer rights. For utilities and suppliers, that shift means compliance is no longer a static checklist. It is a moving target that must be managed across device certification, communication security, data governance, and customer communication strategies.
On the supply side, AMI hardware relies on widely used semiconductor technologies, including system-on-chip processors and communications chipsets. The supply chain risk profile is therefore aligned with broader electronics and battery supply chains rather than concentrated around rare earth elements. This reality carries two strategic implications. First, component availability and lead-time dynamics can influence deployment pacing and pricing, especially when large municipal or utility-scale procurements coincide with electronics market tightness. Second, product architectures that reduce exposure to single-source dependencies or that emphasize software-defined upgradability can offer more resilient operating economics over the asset life. Our research connects these supply chain considerations to procurement sequencing, vendor selection, and total-cost-of-ownership modeling, issues that require detailed, segment-level evaluation rather than aggregate market figures.
What the Full Study Delivers
The complete market research translates these macro trends and event-level signals into a structured intelligence toolkit designed for 2026 decision-making. Rather than stopping at headline revenue and growth rates, the study builds a practical anatomy of the AMI market across multiple lenses that matter to strategy, procurement, and investment teams. The report is organized to help readers move from awareness to action.
Within the study, readers will find:
- A comprehensive market size and forecast framework that traces revenue trajectories across the historical period and extends through the 2026 to 2032 horizon, with context on the pace and shape of growth.
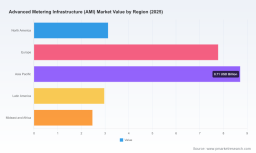
- Segment-level analysis that disaggregates the market by region, by type, and by application, enabling readers to understand where value is concentrating and how different deployment categories compare in scale and growth behavior.
- Competitive profiling of leading AMI participants, including corporate positioning, offering focus, and the strategic implications of recent projects and technology directions.
- A curated synthesis of recent project milestones, technology integrations, and commissioning activity that shows how AMI initiatives are progressing on the ground and what deployment models are gaining traction.
- Regulatory and reimbursement analysis that connects policy developments, certification expectations, data privacy requirements, and cost recovery mechanisms to planning and procurement risk.
- Supply chain and component considerations that frame semiconductor dependence, communication technology choices, and resilience strategies in the context of multi-year deployment planning.
Crucially, the study maintains a decision-oriented editorial standard. Where aggregate figures establish the strategic stakes, the segmented and company-level analysis provides the resolution needed to evaluate market entry timing, partnership strategy, product roadmap alignment, and procurement prioritization. The detailed regional, type-based, and application-based revenue structures, along with the deeper company and project analyses, are presented in full within the source report so that teams can benchmark assumptions, pressure-test forecasts, and align internal planning with the latest available evidence.
Why This Research Matters for 2026 Decisions
The 2026 planning cycle arrives at a moment when AMI investments intersect directly with grid modernization, customer communication obligations, water loss management, demand flexibility, and data-enabled operational efficiency. Utilities must decide not only whether to deploy AMI but how to sequence technologies, which communication and data architectures to standardize, and how to structure contracts that align vendor incentives with long-term service performance. Suppliers and technology partners must determine where to concentrate product development, which geographies and utility segments to prioritize, and how to differentiate beyond device compliance. Investors and market analysts need to distinguish durable growth drivers from short-term procurement timing effects.
In that environment, strategic advantage comes from information that is both comprehensive and precisely segmented. Aggregate market expansion confirms that the opportunity is large and growing; it does not, by itself, reveal which segments are accelerating fastest, where regulatory frameworks are most supportive or most restrictive, how competitive positioning differs across regions and applications, or how recent project experience is reshaping procurement expectations. Those are the questions that determine execution quality in 2026 and beyond.
Our full AMI market research is designed to answer those questions with the analytical depth and operational relevance that enterprise decisions require. The complete regional, type, and application breakdowns, together with the extended competitive and project-level analyses, are available through the source page. Teams that need to translate market momentum into concrete planning choices will find the detailed intelligence essential for framing scenarios, validating assumptions, and aligning strategy with the most current evidence base.
For detailed analysis of this topic, please visit the official page: Advanced Metering Infrastructure (AMI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


