



PW Consulting: Refractory Metals Market Hits $7.0 Billion in 2025, Projected to Reach $8.39 Billion by 2032

Securing Critical Edges: Strategic Intelligence for the Refractory Metals Market Through 2032
Refractory metals form the backbone of high-performance engineering, enabling capabilities in aerospace, electronics, and industrial manufacturing that no other material class can match. As geopolitical tensions reshape supply chains and advanced manufacturing drives new demand vectors, understanding the trajectory of this specialized market has become a strategic imperative for executives, investors, and procurement leaders. The latest market research from PW Consulting delivers a comprehensive, data-driven assessment of the global refractory metals landscape, projecting market evolution from the base year of 2025 through the forecast horizon of 2032. This article previews the strategic insights contained within the full report, highlighting the structural dynamics, competitive forces, and regulatory headwinds that will define decision-making in the years ahead.
Market Architecture: Growth Trajectory and Structural Foundations
The global refractory metals market has demonstrated steady expansion over the historical period from 2020 to 2025, progressing from a revenue base of 5.8 billion USD to a projected 7.0 billion USD by 2025. This growth reflects sustained demand from high-value end-use sectors alongside incremental capacity additions and evolving material specifications. Looking forward, the forecast period spanning 2026 to 2032 indicates continued market development, with overall revenue projected to advance toward 8.39 billion USD by the terminal forecast year. The compound annual growth rate across the forecast window registers at 2.7 percent, representing a measured but resilient expansion profile characteristic of a mature, capital-intensive materials sector.
This growth trajectory is neither uniform nor guaranteed. It reflects the interplay of structural demand drivers, supply-side constraints, pricing dynamics, and regional trade policy shifts. The report dissects these layers systematically, providing decision-makers with a framework to evaluate where value will concentrate, which segments will outperform, and how external shocks may alter baseline projections. Rather than offering a static snapshot, the analysis maps the conditional pathways that market participants are likely to navigate, emphasizing the importance of scenario planning and supply chain flexibility.
Refractory Metals Market
Segmentation Dynamics: Where Value Is Created and Competitive Pressure Intensifies
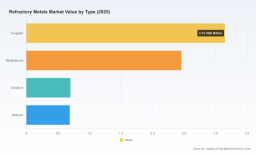
The market segmentation architecture examined in the research reveals several structural characteristics that are critical for strategic positioning. By material type, the market is anchored by tungsten and molybdenum, which together dominate revenue share and underpin the majority of industrial and advanced manufacturing applications. Tantalum and niobium represent smaller but strategically vital subsegments, often serving niche, high-specification roles in electronics, aerospace, and specialty alloys. The report details how these material categories differ not only in absolute scale but in pricing sensitivity, supply concentration, technological substitution risk, and end-market growth profiles.
From an application perspective, aerospace and defense, alongside electronics and semiconductors, constitute the primary demand engines for refractory metals. These sectors demand high purity, consistent quality, and certified supply chains, creating premium positioning for suppliers who can meet stringent qualification requirements. The steel industry remains a meaningful consumption channel, though its growth dynamics are more closely tied to broader industrial cycles and infrastructure investment patterns. The full report breaks down these application profiles with granular attention to demand drivers, material specifications, and the competitive implications of shifting procurement strategies across each vertical.
Regionally, the analysis captures a globally distributed market with meaningful participation across North America, Europe, and Asia Pacific, alongside smaller but strategically relevant activity in Latin America and the Middle East and Africa. The geographic distribution of production capacity, processing infrastructure, and end-market consumption shapes trade flows, tariff exposure, and competitive dynamics in ways that the report examines in depth. Readers of the full publication will find a detailed mapping of regional supply-demand balances, import dependency trends, and the localized effects of trade policy actions that are already altering market behavior.
Competitive Landscape: Concentration, Vertical Integration, and Strategic Maneuvering
Market concentration in the refractory metals sector registers at a CR3 of 38 percent and a CR5 of 45 percent, indicating a moderately consolidated landscape where a handful of large, globally integrated players command significant share, while a broad base of regional specialists, niche processors, and recyclers compete on service, quality, and application expertise. The competitive environment is further shaped by the presence of major primary producers, sophisticated downstream fabricators, and an active secondary processing and recycling ecosystem that is increasingly relevant as supply security and sustainability considerations intensify.
The research provides detailed company profiles and strategic assessments for a comprehensive set of participants spanning North America, Europe, China, Brazil, and Chile. Key North American entities include established producers and fabricators such as Cleveland Tungsten, Inc., Cronimet Specialty Metals USA, Inc., Elmet Technologies LLC, Global Tungsten & Powders LLC, Hyperion Materials & Technologies, Innovative Carbide LLC, Kennametal Inc., Lineage Metallurgical, Molymet Corporation, Niagara Refining LLC, PLANSEE USA LLC, Rhenium Alloys Inc., Thomas & Skinner, Inc., Umicore Canada Inc., and Vista Metals. These organizations represent a cross-section of the industry's capabilities, from primary production and powder metallurgy to specialty alloys, carbide products, and secondary recovery.
On the global stage, the competitive field includes significant primary producers and material specialists such as Jinduicheng Molybdenum Co., Ltd. and Xiamen Tungsten Industry Co., Ltd. in China, CBMM in Brazil as a leading niobium producer, Molymet in Chile, the Plansee Group in Austria, Treibacher Industrie AG, ATI, H.C. Starck Tungsten GmbH in Germany, Ningxia Orient Tantalum Industry, and Climax Molybdenum in the United States. The full report evaluates these players across dimensions including capacity positioning, product breadth, technological capabilities, geographic reach, and strategic responsiveness to supply chain and regulatory shifts.
Recent corporate activity underscores the dynamic nature of this competitive environment. In August 2025, Molymet incorporated Molymet Alloys, LLC in Delaware to advance higher value-added products and related activities, signaling a deliberate move up the value chain. In October 2025, Molymet completed the acquisition of all rights and shares of Rhenium Alloys, Inc., expanding its footprint across molybdenum, tungsten, rhenium, and semiconductor-related product lines. These moves illustrate how established players are consolidating capabilities to capture margin, broaden application coverage, and strengthen supply chain control. The report analyzes such developments not as isolated events but as indicators of broader strategic themes reshaping industry structure.
Market Dynamics: Regulation, Trade Policy, and Supply Chain Realignment
The refractory metals market is operating in an environment where regulatory frameworks, trade policy actions, and raw material pricing dynamics are exerting increasingly direct influence on competitive outcomes. Several developments captured in the research illustrate the nature and pace of these shifts. As of November 2025, the average monthly price for tantalum ore stood at 180 USD per kilogram of Ta2O5 content, reflecting the premium attached to secure, qualified supply in a market with concentrated production and growing demand from electronics and defense applications. In 2025, U.S. tantalum apparent consumption increased 58 percent to 890 tons, accompanied by corresponding rises in imports, highlighting the sensitivity of domestic demand to supply availability and pricing.
Trade policy actions are introducing new volatility and cost structures into the market. In February 2025, China implemented new export controls on selected tungsten items, contributing to sharp price rises for tungsten concentrates and reinforcing concerns about supply concentration for a material that is central to multiple high-value applications. Concurrently, U.S. Section 301 tariffs on tungsten products from China increased to 25 percent effective January 1, 2025, altering the cost calculus for importers and incentivizing efforts to diversify sourcing or develop domestic and allied-supply alternatives. The research also notes that U.S. imports for tungsten concentrates showed increased reliance on China, with data from 2021 to 2024 indicating a 26 percent share amid ongoing supply constraints, underscoring the persistence of dependency even as policy and strategic efforts push toward greater supply autonomy.
These dynamics are not merely background conditions; they are actively reshaping procurement strategies, capacity investment decisions, and competitive positioning. The report integrates these factors into its market assessment, providing a structured evaluation of how regulatory and trade developments influence price formation, supply security, regional competitiveness, and the strategic calculus of major buyers and producers alike. Decision-makers relying on the full publication will find these insights contextualized within scenario frameworks that account for the range of plausible policy and supply outcomes over the forecast period.
Strategic Developments: Capacity, Recycling, and Defense-Driven Demand
Recent activity across the industry points to a clear strategic thrust toward capacity enhancement, supply chain domestication, and the valorization of secondary materials. In November 2025, 6K Additive received a 1.95 million USD Phase II government contract to produce certified tungsten, niobium, and other refractory metal powders from domestic military scrap for defense applications, illustrating the growing intersection of advanced manufacturing, recycling, and national security priorities. Also in November 2025, the U.S. Defense Logistics Agency awarded an 8.6 million USD delivery order for tantalum ingots and secured up to 100 million USD for domestic tantalum processing from ore, reinforcing the strategic importance of tantalum for defense and aerospace applications and signaling sustained government commitment to building resilient domestic supply capabilities.
Further reflecting the push toward supply chain resilience and circular material flows, Plansee Group announced and advanced a U.S. capacity expansion project in February 2026 focused on tungsten recycling and refractory metals production. This development, alongside the broader activity in secondary processing and recycling among firms such as Lineage Metallurgical, Niagara Refining LLC, and Vista Metals, indicates that recycling and material recovery are moving from peripheral considerations to central components of supply strategy. The full report assesses these developments within the context of long-term market evolution, examining how capacity additions, recycling scale-up, and defense-driven procurement intersect with commercial demand growth and competitive dynamics.
Why This Research Matters for 2026 Decision-Making
The refractory metals market presents a distinctive strategic challenge: it is simultaneously a mature, structurally stable materials sector and a rapidly evolving environment shaped by trade policy, supply concentration, technological demand shifts, and heightened attention to supply security. Navigating this landscape requires more than high-level market sizing or generic demand narratives. It demands a precise understanding of segment-level growth drivers, competitive positioning, pricing and cost dynamics, regulatory exposure, and the strategic implications of recent corporate and policy developments.
Refractories Market
The PW Consulting Refractory Metals Market research is designed to meet that need. It combines rigorous historical analysis, a structured forecast framework extending to 2032, detailed segmentation and regional assessment, comprehensive competitive profiling, and integrated analysis of the regulatory and trade dynamics that are actively reshaping the market. The full report goes beyond the macro trajectory to provide actionable intelligence on where value is being created, which competitive moves are reshaping industry structure, and how buyers, producers, and investors can position themselves to manage risk and capture opportunity.
For executives and strategists operating in 2026, the difference between reactive positioning and proactive advantage lies in the quality of intelligence available. The insights previewed here are drawn from a broader body of analysis that drills into the specifics of material-level demand profiles, application-driven pricing dynamics, regional supply-demand balances, competitive capabilities, and the strategic significance of recent contract awards, capacity expansions, acquisitions, and regulatory actions. To access the complete dataset, segmentation detail, competitive assessment, and scenario-based forecasts that underpin these conclusions, we invite you to explore the full report through the source webpage. The comprehensive intelligence contained within is intended to serve as a foundational reference for strategic planning, procurement strategy, investment evaluation, and competitive positioning across the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Refractory Metals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


