



PW Consulting: Ferrisil Nickel Market hits $187.5M in 2025, projected 5.15% CAGR to $265.5M by 2032

Navigating the Ferronickel Market in 2026: Strategic Intelligence for Forward-Looking Enterprises
The global ferronickel industry stands at a critical inflection point. As of the 2025 base year, the total market valuation across the period from 2020 to 2025 reflects a landscape defined by shifting supply chains, evolving regulatory frameworks, and changing demand dynamics driven by stainless steel and alloy manufacturing. Looking ahead, the market is projected to expand from an estimated 197.49 million USD in 2026 to 265.5 million USD by 2032, representing a compound annual growth rate of approximately 5.15 percent. These figures underscore a steady, predictable expansion trajectory, yet beneath the headline numbers lies a complex web of operational decisions, policy interventions, and competitive maneuvers that will determine market winners and laggards over the next seven years.
For procurement leaders, supply chain strategists, and executive decision-makers, understanding these layered dynamics is no longer optional. Early 2026 has already witnessed notable operational catalysts, including the commencement of bulk carrier shipments from newly activated mining operations and the anticipated restart of legacy ferronickel plants following favorable price rallies. At the same time, regulatory shifts such as Indonesia’s differentiated export treatment for ferronickel versus nickel pig iron, coupled with the European Union’s carbon border adjustment data collection mandates, are reshaping trade flows and cost structures. This report has been designed to translate these macro-level signals into actionable, granular intelligence that can be integrated directly into corporate strategy, risk management, and investment planning frameworks.
Unpacking the Ferronickel Market Research: Core Components and Analytical Scope
Our comprehensive Ferronickel Market study is structured to serve as both a diagnostic tool and a forward-looking planning instrument. Drawing on historical data spanning 2020 through 2025, the analysis establishes a robust baseline against which near-term projections and long-range forecasts can be evaluated. The research methodology incorporates multi-source data triangulation, primary industry interviews, and cross-referenced supply-demand modeling to ensure accuracy and relevance for executive audiences.
Key deliverables within the report include:
- Historical Baseline and Trajectory Modeling: A detailed review of market performance from 2020 to 2025, charting revenue movements across multiple operational cycles and identifying the structural drivers behind observed trends.
- Forward-Looking Forecast Framework (2026-2032): A scenario-based projection model that maps expected market evolution under baseline conditions, with explicit consideration of supply-side constraints, demand elasticity, and policy variables.
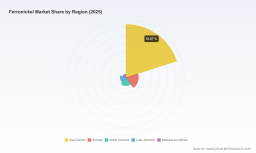
- Segment-Level Deep Dives: Granular analysis across product classifications and downstream applications, revealing cost structures, substitution dynamics, and demand sensitivity without exposing the proprietary percentage splits and revenue allocations reserved for full-report subscribers.
- Regional Market Architecture: A comparative assessment of geographic demand centers and supply corridors, highlighting infrastructure bottlenecks, trade route efficiencies, and localized regulatory environments that influence pricing and availability.
- Competitive Intelligence dossier: Strategic profiles of leading producers, including operational footprints, capacity investments, partnership networks, and recent corporate developments that signal positioning for the 2026-2032 cycle.
- Regulatory and Raw Material Risk Mapping: An integrated review of export quota adjustments, carbon compliance requirements, ore supply constraints, and pricing transmission mechanisms that directly impact production economics.
The report’s architecture is deliberately designed for operational utility. Each section connects market-level observations to decisions that procurement teams, plant managers, and investment committees face on a weekly basis. Rather than offering abstract market commentary, the analysis prioritizes questions that matter: Where are supply bottlenecks likely to emerge? Which product grades will command premium pricing under tightening ore quotas? How should firms structure procurement contracts to hedge against volatility in raw material delivery and carbon compliance costs?
Structural Dynamics Shaping the 2026 Market Environment
Several interconnected forces are actively reshaping the ferronickel supply-demand equilibrium entering 2026. On the supply side, raw material availability has become a central constraint. Recent industry analysis indicates that major lateritic ore operations in Indonesia have adjusted their 2026 mining quotas significantly below prior-year levels, tightening available feedstock for ferronickel and nickel pig iron production. This quota compression has already translated into elevated delivered pricing for key input materials, with regional nickel pig iron benchmarks reaching levels that reflect both scarcity and logistical delivery costs. Firms that rely on long-term ore supply agreements are now re-evaluating contract terms, while spot-market purchasers face heightened exposure to price volatility.
Simultaneously, operational ramp-ups and restarts are altering the supply narrative. One Philippine-listed producer has initiated bulk carrier shipments from its Surigao operations, targeting multi-million metric ton annual volumes, while a second mine site within the same portfolio began its 2026 mining season with initial shipments directed toward Chinese buyers. In parallel, a European-linked operating group has announced plans to restart both mine and ferronickel plant operations in the first half of 2026, capitalizing on recently improved price conditions. These activity shifts demonstrate that the market is not merely reacting to constraints but actively reconfiguring production capacity in response to price signals and strategic timing.
Regulatory developments add another layer of complexity. Indonesia’s decision to exempt nickel pig iron from a planned centralized export policy while classifying ferronickel differently due to its iron content creates a differentiated export landscape that will influence trade routing and competitive positioning between neighboring producing nations. Meanwhile, downstream importers into the European Union must now navigate data collection and reporting requirements associated with carbon border adjustment mechanisms, applying to both ferronickel and nickel pig iron as of 2025. For companies with significant EU exposure, compliance planning and emissions documentation are transitioning from peripheral concerns to core operational prerequisites.
Ferronickel Market
Worldwide Ferro Titanium Market
Together, these dynamics create a market environment where cost transparency, supply security, and regulatory readiness are decisive competitive advantages. The ability to anticipate quota adjustments, model price transmission through the value chain, and align procurement strategy with evolving compliance obligations will separate agile market participants from those forced into reactive positioning.
Competitive Landscape: Strategic Positioning of Key Industry Players
The ferronickel competitive landscape is characterized by a mix of large-scale diversified miners, regionally focused producers, and specialized alloy manufacturers. Market concentration metrics indicate a moderately consolidated environment, with a handful of leading firms commanding substantial share while a broader tier of regional operators competes on cost efficiency, local integration, and product specialization. Understanding the strategic posture of key competitors is essential for forecasting supply behavior, anticipating pricing pressure, and identifying potential partnership or acquisition opportunities.
Among the most prominent operators, Tsingshan Holding Group has established a significant presence through Indonesian smelter partnerships and integrated laterite ore processing, with a clear strategic emphasis on cost-efficient production for stainless steel applications. Its operational model reflects the broader industry trend toward vertically aligned supply chains that span mining, smelting, and downstream alloy fulfillment. Similarly, Eramet continues to leverage its foothold in New Caledonia and Indonesia, maintaining production of higher nickel-content grades while executing structural balance sheet initiatives designed to preserve operational continuity amid fluctuating commodity cycles.
Vale’s diversified footprint across Indonesia, the Philippines, and New Caledonia underscores the strategic value of geographic diversification in managing ore supply risk and optimizing logistics. PT Antam, as an Indonesian state-owned producer, occupies a distinct position shaped by national industrial policy objectives and domestic downstream processing priorities. Koniambo Nickel’s operations in New Caledonia highlight the continued relevance of lateritic ore processing in established mining jurisdictions, while Anglo American and South32 maintain their own integrated pathways into ferronickel and ferroalloy output through varied asset portfolios.
On the regional manufacturing side, several Chinese and Southeast Asian producers play critical roles in satisfying domestic alloy and stainless steel feedstock demand. Jiangsu Delong Nickel Industry, Shandong Xinhai Technology, Shengyang Group, Linyi Yichen Alloy, SNNC, Pacific Steel Mfg, and Sumitomo Metal Mining each contribute to the broader competitive fabric through specialized production lines, regional distribution networks, and integrated smelting capabilities. European producers such as Larco and Precomprimido further diversify the geographic supply base, catering to regional alloy and foundry requirements while navigating evolving compliance environments.
Recent corporate developments provide tangible signals of how these players are adapting to current conditions. The commencement of mining operations and initial bulk shipments from a Philippine-listed producer illustrates the pace at which new output capacity can enter the market when financing, permitting, and logistical readiness align. Similarly, the operational restart efforts undertaken by a European-linked group in early 2026 demonstrate how price rallies can act as catalysts for reengaging dormant assets. These movements are not isolated events; they reflect a broader industry rhythm in which capacity deployment, quota constraints, and commodity pricing continuously reshape competitive positioning.
What the Full Report Delivers: Decision-Ready Intelligence for 2026 Planning
While the high-level market trajectory and competitive landscape provide essential context, the full Ferronickel Market research report delivers the detailed, decision-ready intelligence that operational leaders require to move from awareness to action. The study goes beyond aggregate sizing to map the specific segments, regional corridors, and application categories that drive revenue concentration and cost variability. Readers seeking complete visibility into how product grade demand intersects with regional supply capacity, or how application-level consumption patterns respond to downstream manufacturing cycles, will find those analyses comprehensively developed within the full report.
The competitive profiling section extends beyond corporate summaries to include strategic capability assessments, investment signals, partnership dynamics, and operational risk exposures that influence each major player’s likely behavior over the forecast horizon. By connecting corporate strategy to market-level outcomes, the report enables readers to anticipate supply responses, evaluate potential disruptions, and model scenarios that factor in competitor decision-making.
Additionally, the regulatory and raw material analysis integrates recent operational disclosures and policy announcements into a structured framework that highlights their direct implications for procurement planning, contract structuring, and cost forecasting. This includes coverage of export quota adjustments, ore supply constraints, carbon compliance data requirements, and pricing transmission trends that affect delivered material costs across multiple jurisdictions. For firms managing cross-border supply chains, these insights provide the foundation for more resilient sourcing strategies and more accurate total cost of ownership calculations.
The report is built for immediate application. Strategic planners can use the segmentation and regional analysis to align inventory targets with anticipated supply availability. Finance and procurement teams can incorporate the cost and pricing dynamics into contract negotiations and hedging frameworks. Executive leadership can leverage the competitive intelligence and regulatory mapping to evaluate market entry, partnership, or capacity investment opportunities with greater confidence.
Conclusion: Act on Intelligence, Not Assumptions
The ferronickel market’s projected expansion over the 2026-2032 period reflects durable demand foundations, but that growth will be distributed unevenly across regions, product types, and applications. Firms that enter this cycle armed only with aggregate market numbers risk missing the structural nuances that determine pricing leverage, supply reliability, and competitive positioning. The strategic value of comprehensive market research lies precisely in its ability to transform broad trends into specific, actionable insights that inform procurement strategy, capacity planning, and risk mitigation.
Our full Ferronickel Market report provides the depth, granularity, and forward-looking analytical frameworks required to make informed decisions in a market defined by quota shifts, operational restarts, carbon compliance demands, and evolving competitive dynamics. For organizations that require complete segmentation data, regional and application-level revenue allocations, detailed competitor capability assessments, and scenario-based forecasting models, the complete study offers a comprehensive intelligence foundation tailored to 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Ferronickel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


