



PW Consulting: MIBC Market to Reach $309.17M by 2032, Driven by 4.8% CAGR Through 2032

Strategic Intelligence in the Methyl Isobutyl Carbinol (MIBC) Market: Navigating Growth and Complexity Through 2032
The global chemical landscape is undergoing a period of structural recalibration, where specialty intermediates like Methyl Isobutyl Carbinol (MIBC) serve as quiet but critical enablers of industrial productivity. From froth flotation in extractive operations to formulation chemistry in coatings and pharmaceutical processes, MIBC occupies a nuanced position in the value chain. Yet, despite its widespread utility, strategic decision-makers often lack a consolidated view of how capacity shifts, regulatory pressures, feedstock volatility, and regional demand patterns converge to shape long-term market trajectories.
This is the explicit purpose behind PW Consulting's latest market research on the Methyl Isobutyl Carbinol (MIBC) Market. Designed as a decision-grade intelligence asset, the report translates years of historical performance, current market architecture, and forward-looking scenario modeling into a coherent strategic narrative. Drawing on a rigorous base year of 2025 and an extensive historical window spanning 2020 through 2025, the study charts a detailed forecast horizon from 2026 to 2032, enabling executives to move beyond reactive planning and toward anticipatory positioning.
The analysis projects the overall MIBC market to expand steadily through the end of the decade, supported by a compound annual growth rate of 4.8 percent measured in U.S. dollars across the forecast window. Historical revenue progression establishes a clear baseline of resilience and incremental expansion, with market valuations building consistently from early-2020s levels and advancing toward a measured trajectory into the late 2020s and early 2030s. This sustained upward path is not merely a function of baseline industrial activity; it reflects the interplay of capacity investments, evolving end-use requirements, and the market's ability to adapt to shifting regulatory and supply-chain conditions. By anchoring the forecast in this historical continuum, the study provides a defensible framework for capital allocation, sourcing strategy, and competitive positioning.
Decoding the Architecture of the MIBC Market
The MIBC market is defined less by a single growth driver than by a mosaic of interdependent demand streams, production grades, and regional dynamics. Understanding how these elements interact is essential for any organization seeking to anticipate shifts in pricing behavior, supply availability, or competitive intensity. The report structures this complexity through a multi-dimensional lens that captures the major demand verticals, the differentiated grade landscape, and the geographic distribution of consumption without reducing the picture to oversimplified aggregates.
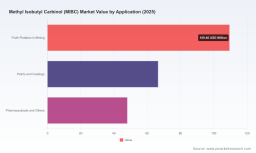
On the application side, industry demand spans a broad spectrum of industrial and specialty uses. The analysis explores how flotation-related requirements in mining operations anchor a significant share of consumption, reflecting MIBC's established role as a froth modifier and process aid. At the same time, the study spends considerable attention on the coatings and paints sector, where MIBC functions as a solvent and performance modifier, and on pharmaceuticals and other specialized applications that demand consistent purity and reliability. Each end-use channel carries its own sensitivity to macroeconomic cycles, regulatory scrutiny, and formulation trends. Rather than presenting static allocations, the research examines how these application domains evolve in response to operational demands, substitution pressures, and downstream innovation.
The grade dimension introduces an additional layer of strategic nuance. Technical-grade and industrial-grade MIBC serve distinct customer priorities and market expectations, and their relative positioning shapes pricing behavior, supply-chain requirements, and product development roadmaps. The report maps these grade-level dynamics to help stakeholders understand where value is created, where margin structures diverge, and how quality specifications influence procurement decisions across different buyer segments.
Methyl Isobutyl Carbinol (MIBC) Market
Geographically, the market exhibits a broad but uneven footprint. Demand concentrations reflect long-standing industrial infrastructure, mining activity clusters, coatings and manufacturing ecosystems, and the gradual maturation of regional supply networks. The research provides a structured regional framework that highlights where consumption is most established, where growth momentum is building, and how local production capabilities interact with cross-border trade flows. Importantly, the analysis connects these regional patterns to practical implications for sourcing diversification, market entry timing, and competitive exposure, enabling readers to see geography not as a static map but as a dynamic variable in strategic planning.
Competitive Landscape and Strategic Positioning
The MIBC market is characterized by a relatively concentrated corporate architecture, where a limited set of major producers holds substantial influence over capacity, pricing norms, and innovation directions. This concentration creates both opportunities and constraints for market participants, making competitive intelligence a central pillar of effective strategy. The report delivers a detailed evaluation of the core companies shaping the sector, examining their production footprints, technological capabilities, and recent strategic moves.
European and North American multinationals continue to anchor a significant portion of global capacity. BASF SE, operating from its Ludwigshafen site, has pursued capacity expansions that reinforce its ability to serve downstream demand across flotation frothers, lubricants, and coatings applications. Eastman Chemical Company has taken a distinctly process-oriented approach, integrating real-time monitoring and sustainability enhancements into its MIBC manufacturing to strengthen operational efficiency and support solvent applications in coatings and related fields. Dow Chemical Company maintains MIBC as part of a broader chemical portfolio, leveraging integration pathways that connect production with mining and industrial solvent use cases. Celanese Corporation produces MIBC through established acetone and MIBK routes, supported by a global distribution network that feeds flotation and specialty markets. AkzoNobel N.V. contributes a wide manufacturing footprint focused on coatings, lubricants, and industrial processes, while Solvay S.A. emphasizes high-purity grades for specialty applications spanning mining, pharmaceuticals, and chemical production. Arkema Group and Evonik Industries AG further round out the multinational field, each bringing integrated production capabilities and specialized application focus to their MIBC offerings.
Alongside these established players, regional producers have increasingly asserted themselves through targeted capacity investments and quality-focused supply strategies. In China, Zibo Nalcohol Chemical Co., Ltd. expanded MIBC production capacity by 20 percent with a new production line in early 2024, strengthening its supply position for industrial solvents and frother applications. Shenyang East Chemical Science-Tech Co., Ltd. has built a reputation for consistent-quality MIBC serving mining, coatings, lubricants, and chemical manufacturing, underpinned by stringent quality control practices. These developments illustrate how regional capacity additions can alter supply balances, create new bargaining dynamics, and influence pricing expectations across specific market segments.
The report further contextualizes these company profiles within the broader competitive structure by examining market concentration indicators. With the three largest firms accounting for a substantial share of market revenue and the top five collectively representing an even greater proportion, the industry exhibits a clear hierarchy that shapes competitive behavior. Understanding this concentration is critical for buyers evaluating supplier dependency, for producers assessing the risk of reactive pricing, and for new entrants gauging the barriers associated with scale, integration, and established customer relationships.
Market Dynamics: Feedstock, Regulation, and Geopolitical Pressure
No strategic assessment of the MIBC market is complete without a rigorous examination of the external forces that can accelerate, constrain, or redirect growth. The report devotes substantial attention to the operational and regulatory dynamics that influence both supply-side economics and end-use demand patterns, recognizing that these factors often determine the difference between nominal growth and commercially meaningful expansion.
Feedstock economics form one of the most immediate pressure points. Acetone serves as the primary upstream feedstock for MIBC production, and the trajectory of acetone pricing exerts a direct influence on manufacturing cost structures. The analysis incorporates this relationship into its forward-looking framework, demonstrating how feedstock volatility can compress margins, alter supply-chain behavior, and affect the commercial viability of capacity expansions. By connecting acetone market conditions to MIBC production economics, the study helps stakeholders anticipate cost-driven adjustments in pricing, procurement timing, and inventory strategy.
Regulatory developments introduce an equally important layer of complexity. The European Union's REACH framework, including ECHA's CoRAP evaluation processes, alongside the U.S. EPA's TSCA risk evaluation, has the potential to impose restrictions on MIBC concentrations in solvent applications. These regulatory tracks can reshape formulation requirements, influence product substitution decisions, and alter the competitive balance between grades and applications. Compounding this dynamic, stricter VOC emission standards under the EU Paints Directive and U.S. EPA NESHAP are pressuring coatings formulators to reduce MIBC use in certain contexts. The report examines how these regulatory currents create both compliance demands and innovation incentives, particularly as producers and formulators explore environmentally friendlier alternatives and adjusted formulation architectures.
Geopolitical and supply-chain disruptions further complicate the operating environment. A notable example emerged in April 2026, when U.S. acetone supply tightened sharply due to Middle East shipping disruptions, raising domestic MIBC feedstock costs. Such events underscore the vulnerability of chemical supply chains to logistics bottlenecks, regional instability, and sudden shifts in freight and sourcing conditions. The research integrates these types of disruption scenarios into its strategic analysis, helping organizations assess exposure, evaluate contingency planning, and determine where supply diversification or inventory buffering may deliver tangible resilience benefits.
Taken together, these dynamics illustrate that the MIBC market cannot be evaluated through price and volume alone. Strategic success increasingly depends on anticipating regulatory trajectory, managing feedstock exposure, and building operational flexibility in the face of external shocks.
What the Report Delivers: Operational Depth for Strategic Decisions
The value of this study lies not only in its market sizing and forecasting but in the breadth of operational insight it provides to practitioners. The report is structured to support a wide range of strategic use cases, from executive-level market evaluation to procurement planning, product portfolio assessment, and competitive benchmarking. It combines top-level market architecture with granular analytical modules designed to translate data into action.
Readers gain access to a comprehensive segmentation framework that examines demand by region, type, and application. Rather than simply reporting splits, the analysis interprets what these divisions mean for growth momentum, pricing behavior, and competitive exposure. This approach allows stakeholders to identify which segments are most sensitive to regulatory change, which are best positioned to absorb feedstock cost pressure, and where capacity additions are most likely to alter market balance.
The competitive analysis section delivers company-level profiles that go beyond descriptive summaries. For each major player, the report evaluates production orientation, recent strategic developments, product and application emphasis, and the implications of those moves for broader market dynamics. Recent developments are woven directly into the narrative to show how individual corporate actions—such as capacity expansions, process optimization initiatives, sustainability program launches, and monitoring system deployments—contribute to shifting supply conditions and competitive expectations.
The study also integrates industry-context analysis across feedstock relationships, regulatory trajectories, and geopolitical supply risks. By mapping these themes to specific sections of the market structure, the report helps readers connect external conditions to internal decision points. This includes evaluating the extent to which acetone price movements may affect manufacturing economics, understanding how evolving REACH and TSCA processes could influence solvent-based applications, and assessing the implications of VOC-driven formulation pressure for coatings-related demand.
Throughout, the research maintains a practical orientation. It is designed to answer the questions that matter most to executives and operational leaders: where is demand structurally supported, where is growth more conditional, which competitive moves are likely to reshape supply availability, and what external risks should be priced into planning assumptions. The synthesis of these elements creates a decision-making foundation that can be applied across strategy, sourcing, product development, and risk management functions.
Why the 2026 Outlook Demands a Disciplined Intelligence Edge
As organizations move deeper into the 2026 planning cycle, the MIBC market presents a case study in how specialty chemical sectors reward foresight. The combination of steady long-term growth, concentrated competition, feedstock sensitivity, and regulatory evolution creates an environment where generic assumptions are quickly exposed. Companies that rely on fragmented data sources or outdated market impressions risk misjudging cost trends, overcommitting to vulnerable supply relationships, or overlooking shifts in application-level demand.
This research is built to reduce that uncertainty. By contextualizing historical performance within a disciplined forecast framework and layering in competitive, regulatory, and supply-chain analysis, the report equips decision-makers with a more complete picture of the forces shaping the market through 2032. It highlights not only where growth is likely to materialize but also where strategic caution is warranted, enabling a more balanced approach to investment, procurement, and market positioning.
At the same time, the breadth of this analysis is intentionally supported by detailed segment-level intelligence that goes beyond the scope of this overview. The full report contains the depth of segmentation data, regional demand interpretation, grade-specific dynamics, and company-level strategic evaluation needed to convert high-level insight into precise operational decisions. Accessing the complete study allows readers to move from directional understanding to actionable precision, with the analytical rigor required to support board-level discussion and cross-functional execution.
A Strategic Lens for the Decade Ahead
The Methyl Isobutyl Carbinol (MIBC) Market is not defined by dramatic discontinuities, but by the accumulation of supply-side investments, demand-side pressures, regulatory evolution, and external shocks that gradually reshape competitive conditions. For organizations operating in or adjacent to this market, the strategic imperative is clear: understanding the direction of travel is necessary, but understanding the mechanics behind that direction is what separates reactive participants from proactive strategists.
PW Consulting's market research on MIBC provides that mechanics-focused perspective. It offers a structured, evidence-based view of market size, growth trajectory, segmentation behavior, competitive positioning, and the dynamic forces that will influence outcomes across the 2026 to 2032 horizon. By combining macro-level forecasting with detailed operational analysis, the study is designed to serve as a durable reference point for strategic planning in a market where informed anticipation is a genuine competitive advantage.
Acetyl Tributyl Citrate (ATBC) Market
For detailed analysis of this topic, please visit the official page: Methyl Isobutyl Carbinol (MIBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


