



PW Consulting: Chemical Catalyst Market to Reach $511.9 Million by 2032, Growing at 4.48% CAGR

Strategic Imperatives in the Global Chemical Catalyst Market: A 2026 Outlook
The chemical catalyst market stands at a critical inflection point in 2026. As industries navigate the dual pressures of decarbonization mandates and supply chain volatility, catalysts have evolved from mere process enablers to strategic assets that dictate operational efficiency, regulatory compliance, and long-term competitiveness. For executives steering portfolio strategy, capital allocation, and R&D roadmaps, understanding the trajectory of this market is no longer optional—it is foundational.
Precious Metal Catalyst Market
Our latest comprehensive market research report on the chemical catalyst sector provides executives with a rigorous, data-grounded framework to navigate the coming years. Spanning historical performance from 2020 through 2025 and projecting forward to 2032, this analysis captures the structural shifts, competitive maneuvers, and demand-side transformations that will define the industry landscape. Below, we preview the strategic dimensions of this research and articulate why it constitutes an indispensable decision-support tool for 2026 and beyond.
The Macro Trajectory: Sustained Growth Anchored in Industrial Demand
The global chemical catalyst market has demonstrated remarkable resilience and expansion over the past half-decade. Valued at approximately 298.15 million USD in 2020, the sector climbed steadily to reach 375.4 million USD by 2025. This upward trajectory reflects the compounding effect of industrial digitization, expanding petrochemical capacity in emerging economies, and the accelerating deployment of catalysts in environmental and sustainability-driven applications.
Chemical Catalyst Market
Looking ahead, the market is projected to maintain a compound annual growth rate of 4.48 percent through 2032, translating into a valuation of roughly 511.9 million USD by the end of the forecast horizon. This growth is not uniform; it is being shaped by divergent regional industrialization rates, shifting feedstock economics, and deliberate capacity investments by leading manufacturers. For corporate strategists, the implication is clear: the next seven years will reward organizations that align their catalyst procurement, R&D partnerships, and geographic exposure with the underlying demand vectors rather than reacting to short-term price fluctuations.
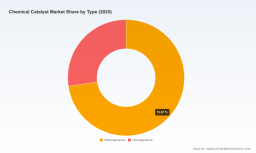
The report provides a granular breakdown of how these growth dynamics unfold across heterogeneous and homogeneous catalyst categories, as well as across application verticals ranging from petrochemical processing to polymerization, chemical synthesis, and environmental remediation. Rather than presenting static market shares, the analysis maps the interaction between technology readiness, regulatory timelines, and end-user procurement cycles—offering a dynamic view of where value creation is concentrating and where margin compression looms.
Structural Shifts Shaping the 2026 Competitive Landscape
The catalyst industry in 2026 is characterized by a blend of maturity and disruption. On one hand, the market exhibits moderate concentration, with the top three players accounting for approximately 35.5 percent of revenue and the top five commanding 42.0 percent. This concentration reflects the high barriers to entry associated with catalyst development, including proprietary formulation expertise, stringent performance validation, and long qualification cycles in downstream industries. On the other hand, the landscape is being reshaped by technological breakthroughs, evolving environmental regulations, and raw material cost volatility that are altering competitive moats.
Technology and Material Innovation as Differentiators
Recent product launches and capacity expansions underscore how leading firms are leveraging innovation to defend and expand their positions. BASF SE has been particularly active, inaugurating the world's first production facility for 3D-printed sulfuric acid catalysts—a development that signals a broader industry pivot toward advanced manufacturing techniques that enable customized catalyst geometries, improved mass transfer, and reduced waste. Concurrently, the German giant has opened a state-of-the-art R&D center for refinery catalysts co-located with its largest global production site, reinforcing the strategic linkage between research velocity and manufacturing scale. Earlier innovations, such as the SYNSPIRE G1-110 catalyst deployed at Nan Ya Plastics' 2-EH plant, have already demonstrated measurable operational benefits, including annual steam savings and significant CO2 reductions, highlighting how catalyst performance directly translates into sustainability metrics that matter to both regulators and end customers.
Clariant AG has similarly pursued a sustainability-forward product strategy, introducing titanium-based AddWorks catalyst solutions for polyester polymerization as a greener alternative to traditional antimony catalysts. This launch, alongside the earlier deployment of MegaMax 900 methanol synthesis catalysts at European Energy's e-methanol facility in Denmark, illustrates a broader industry trend: catalysts are increasingly being engineered not only for reactivity and selectivity but also for reduced toxicity, lower environmental footprints, and compatibility with renewable feedstock pathways.
Regulatory Pressures and Compliance as Strategic Filters
Regulatory frameworks are exerting an ever-stronger influence on catalyst development, procurement, and market access. Catalyst manufacturers operating in or exporting to European markets must comply with REACH regulations governing substance registration, safety data sheet preparation, and exposure monitoring. For global buyers and suppliers alike, these requirements introduce additional layers of due diligence, documentation, and lifecycle management. Companies that have invested early in compliant formulations, transparent supply chain tracing, and integrated safety protocols are positioned to shorten qualification timelines and reduce regulatory friction. Those lagging behind face the risk of market exclusion or costly remediation. The report examines how REACH compliance and analogous regulatory regimes in other jurisdictions are shaping product portfolios, R&D priorities, and regional market entry strategies.
Feedstock Economics and Raw Material Dynamics
Raw material cost volatility represents another critical variable for 2026 planning. Sulfuric acid, a foundational catalyst precursor and process chemical, has experienced notable price movements driven by shifts in elemental sulfur availability and broader commodity market dynamics. In April 2026, sulfuric acid prices reached approximately 280.80 USD per metric ton in China and 367.80 USD per metric ton in the United States, with upward pressure stemming from reduced byproduct output from copper and zinc smelting operations and volatility in crude oil markets that influence refining activity. For catalyst producers, these feedstock cost fluctuations directly affect margin structures and pricing strategies. For downstream users, they introduce uncertainty into total cost of ownership calculations and underscore the importance of long-term supply agreements, alternative feedstock strategies, and catalyst formulations that optimize material efficiency.
Competitive Intelligence: Navigating a Crowded and Evolving Field
The chemical catalyst market features a diverse set of global players, each with distinct technological competencies, geographic footprints, and strategic priorities. BASF SE, headquartered in Ludwigshafen, Germany, remains a dominant force, particularly in sulfuric acid catalysts, FCC catalysts, and industrial adsorbents. Its recent capacity expansions and R&D investments signal a clear commitment to securing leadership in both traditional and next-generation catalyst applications. Johnson Matthey PLC, based in London, continues to leverage its expertise in precious metal and PGM catalysts to serve chemical and petrochemical end markets, with a particular strength in high-value, performance-critical applications.
Clariant AG, from its Muttenz, Switzerland base, has carved out a strong position in catalysts for propylene, ethylene, and syngas processes, while increasingly differentiating through sustainable formulations. W.R. Grace & Co., operating from Columbia, Maryland, maintains a focused presence in FCC and hydroprocessing catalysts for refining and petrochemical industries, where process reliability and catalyst longevity are paramount. Albemarle Corporation, headquartered in Charlotte, North Carolina, brings its refining and petrochemical catalyst expertise—including its well-known Ketjen brand solutions—to a competitive field where incremental performance gains can yield substantial operational savings.
Haldor Topsoe A/S, based in Lyngby, Denmark, specializes in hydroprocessing and syngas catalysts for chemical synthesis, positioning itself at the intersection of traditional refining and emerging energy transition pathways. Umicore SA, from Brussels, Belgium, brings deep expertise in automotive and industrial precious metal catalysts, leveraging its materials science capabilities across multiple verticals. Evonik Industries AG, headquartered in Essen, Germany, develops specialty catalysts and adsorbents that address niche but high-value chemical applications, often in partnership with downstream innovators. Axens, from Rueil-Malmaison, France, provides catalyst technologies tailored to oil refining and petrochemical processes, with an emphasis on integrated solution delivery. Finally, Sinopec Catalyst Co., Ltd., based in Beijing, China, stands as a major producer of refinery and petrochemical catalysts, reflecting the broader rise of Chinese manufacturers in global supply chains and their increasing capability in both volume production and technology development.
The report provides detailed profiles of these and other key players, analyzing their strategic moves, capacity investments, product launches, and partnership ecosystems. By mapping competitive dynamics against market segmentation and regional demand patterns, the analysis equips executives with the intelligence needed to anticipate competitor behavior, identify partnership opportunities, and assess threats to existing supplier relationships.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Makers
Beyond macro trends and competitive snapshots, this market research report is structured to support concrete business decisions across multiple functional areas. The following elements represent the core operational value provided to subscribers:
- Segmentation Analysis Across Type and Application: The report dissects the market by heterogeneous and homogeneous catalyst types, as well as by application verticals including petrochemicals, polymerization, chemical synthesis, and environmental uses. Each segment is evaluated through the lens of growth drivers, technology maturity, pricing dynamics, and end-user procurement behavior, enabling readers to identify high-opportunity niches and assess the strategic fit of their product or procurement portfolios.
- Regional Demand Mapping and Trade Flow Insights: While the global market is projected to grow steadily, regional trajectories diverge significantly based on industrialization pace, regulatory environment, feedstock availability, and local manufacturing capacity. The analysis provides a nuanced view of demand concentration and growth momentum across key geographies, helping executives calibrate market entry strategies, supply chain configurations, and investment prioritization.
- Competitive Landscape and Strategic Group Mapping: Detailed assessments of leading companies—including their technological capabilities, recent developments, and strategic positioning—allow readers to benchmark their own organizations, identify potential collaborators or acquisition targets, and anticipate shifts in market share and pricing power. The report's coverage of recent capacity expansions, product launches, and R&D investments provides a real-time window into how competitors are shaping the future market structure.
- Regulatory and Compliance Roadmap: With REACH and analogous regulations increasingly influencing catalyst development and market access, the report offers a structured overview of compliance requirements, documentation expectations, and best practices for managing regulatory risk across jurisdictions. This section is designed to support procurement, legal, and R&D teams in aligning their processes with evolving standards.
- Raw Material and Feedstock Risk Assessment: Given the sensitivity of catalyst economics to raw material costs—particularly elemental sulfur, precious metals, and specialty precursors—the report includes an analysis of price trends, supply constraints, and mitigation strategies. This intelligence supports procurement planning, cost modeling, and supplier negotiation strategies in an environment of persistent commodity volatility.
- Forecast Scenarios and Strategic Planning Tools: The 2026–2032 forecast framework is built to support scenario planning, allowing readers to test assumptions around growth rates, segment shifts, and regional demand under different macroeconomic, regulatory, and technology adoption pathways. This flexible structure ensures that the analysis remains relevant even as external conditions evolve.
Strategic Value for 2026 Executive Decision-Making
In an environment where catalyst performance directly influences process efficiency, emissions profiles, and total operating costs, the ability to anticipate market shifts is a decisive competitive advantage. The insights contained in this report are designed to support decision-making across several critical dimensions:
- Portfolio Strategy and R&D Prioritization: By identifying which catalyst types and application segments are experiencing the strongest demand momentum and technological innovation, executives can align R&D budgets, partnership investments, and product development roadmaps with the highest-value opportunities. The analysis of recent product launches and capacity expansions provides a concrete reference point for evaluating where the industry is heading and where white space may exist.
- Procurement and Supply Chain Optimization: For downstream users and industrial buyers, the report's segmentation and regional analysis supports more informed supplier selection, contract structuring, and inventory strategies. Understanding where supply is concentrated, which technologies are gaining traction, and how raw material costs are evolving enables procurement teams to negotiate from a position of knowledge rather than reacting to spot market fluctuations.
- M&A and Partnership Evaluation: The competitive landscape section, combined with the market concentration data and segment growth profiles, provides a structured basis for evaluating potential acquisitions, joint ventures, or technology licensing arrangements. Executives can assess which capabilities are most strategically valuable, which players are strengthening their positions, and where consolidation dynamics may create openings.
- Risk Management and Regulatory Preparedness: With REACH compliance, feedstock volatility, and sustainability expectations all exerting pressure on catalyst markets, the report's coverage of regulatory requirements, raw material trends, and compliance best practices helps organizations anticipate disruptions and build resilience into their operations and supplier relationships.
- Capital Allocation and Geographic Strategy: The regional and segment forecasts support more disciplined capital allocation decisions, whether for new production capacity, R&D facilities, sales and distribution investments, or market entry initiatives. By understanding where demand is growing and which regions present the most favorable regulatory and economic conditions, executives can prioritize investments with greater confidence.
Conclusion: Turning Market Intelligence into Strategic Advantage
The chemical catalyst market is entering a phase where technological innovation, regulatory evolution, and raw material dynamics will increasingly determine which companies capture value and which face margin erosion or strategic obsolescence. The data presented in this research—spanning historical performance, current competitive dynamics, and forward-looking forecasts through 2032—provides a comprehensive foundation for navigating this complexity.
The trajectory from 375.4 million USD in 2025 to an estimated 511.9 million USD by 2032, supported by a 4.48 percent CAGR, reflects more than aggregate growth. It reflects a market being reshaped by deliberate investments in advanced manufacturing, sustainable catalyst formulations, and integrated solution delivery. Companies that understand these shifts at a granular level will be better positioned to optimize procurement, direct R&D investments, manage regulatory risk, and forge strategic partnerships that compound advantage over time.
This report is designed to serve as a strategic reference point for executives across the chemical, petrochemical, refining, environmental, and advanced materials sectors. It combines rigorous quantitative analysis with qualitative insights into competitor behavior, technology trends, and regulatory developments, all structured to support actionable decision-making in 2026 and the years ahead.
To access the full segmentation breakdowns, detailed company profiles, regional demand maps, regulatory compliance frameworks, and scenario-based forecasts, we invite you to visit the source page and explore the complete research deliverables. The depth of intelligence contained in the full report is built to support precise, confident decisions in a market where foresight is the ultimate differentiator.
For detailed analysis of this topic, please visit the official page: Chemical Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


