



PW Consulting: Polycaprolactone Market to Reach $849.17M by 2032 at 8.85% CAGR

Navigating the Polycaprolactone Landscape: Strategic Intelligence for 2026 and Beyond
As industries pivot toward sustainable, high-performance polymers, polycaprolactone (PCL) has emerged as a critical enabler across biomedical, additive manufacturing, and industrial applications. Our newly released Polycaprolactone Market research report delivers the analytical depth required for enterprise leaders navigating 2026 decision cycles. This introductory article outlines the strategic value embedded within the full study, demonstrating how our methodology transforms macro trends and granular competitive intelligence into actionable corporate strategy.
Market Trajectory: From Historical Consolidation to Structural Expansion
The polycaprolactone market has demonstrated consistent capital allocation and demand acceleration over the past half-decade. Between 2020 and 2025, global revenue expanded from approximately 340.45 million to 470.12 million, reflecting a compound trajectory that outpaces many conventional specialty polymers. Moving forward, our forecast modeling projects sustained momentum through 2032, with market valuation expected to reach nearly 849.17 million by the terminal forecast year. This expansion is anchored by a projected CAGR of 8.85 percent across the 2026-2032 window, signaling durable structural demand rather than cyclical fluctuation.
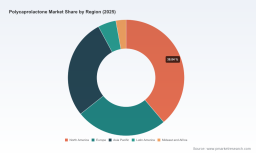
For executive teams evaluating capacity investments, M&A targets, or supply chain reconfiguration, these macro indicators serve as directional compass points. The full report dissects the inflection points, pricing elasticity thresholds, and demand-generation vectors that will dictate market velocity. We deliberately reserve the granular segmentation breakdowns for the complete intelligence package, ensuring that commercial leaders engage with the comprehensive dataset required for precise scenario planning and risk-adjusted capital deployment.
Inside the Report: Operational Intelligence for Commercial Execution
Beyond headline figures, the study functions as an operational playbook designed for cross-functional decision-making. Our research architecture integrates demand-side pull factors, feedstock volatility tracking, regulatory horizon scanning, and competitive benchmarking into a unified analytical framework. The deliverable is structured to answer the questions that matter most to product strategy, procurement, and corporate development teams.
- Application and Demand Mapping: We isolate the performance drivers across high-growth verticals, tracking how material specifications, regulatory approvals, and end-user adoption cycles shape consumption patterns. The report quantifies how emerging use cases intersect with established commercial pathways, providing a clear view of where volume will concentrate and how substitution risks will evolve.
- Supply Chain and Feedstock Dynamics: Raw material cost structures, regional availability constraints, and manufacturing footprint decisions are analyzed with a focus on margin sensitivity. The study evaluates how feedstock pricing fluctuations, logistics bottlenecks, and capacity utilization trends will influence supplier competitiveness and contract negotiation leverage over the forecast horizon.
- Competitive Benchmarking and Strategic Positioning: Company-level assessments cover product architecture, commercial reach, R&D orientation, and partnership activity. By mapping technical differentiation against commercial execution, the report highlights which players are positioned to capture premium segments and which are optimizing for volume or regional penetration.
- Scenario Planning and Risk Modeling: Sensitivity analyses incorporate regulatory shifts, tariff exposure, and regional trade dynamics. These modules are designed to help leaders stress-test investment assumptions, identify contingency pathways, and align procurement timing with expected policy and pricing inflection points.
Each section is built to support direct translation into operating decisions. The full report extends these frameworks with detailed segmentation architecture, regional demand dispersion, type-level performance comparisons, and application-specific volume trajectories. This granularity allows commercial, R&D, and finance teams to align on a single evidence base rather than relying on fragmented industry commentary.
Competitive Landscape: The Players Shaping the Next Cycle
Market concentration underscores the strategic importance of incumbent positioning. With a CR3 of 62.8 percent and a CR5 of 78.4 percent, the polycaprolactone ecosystem exhibits meaningful consolidation among established manufacturers and specialized material suppliers. This concentration does not imply stagnation; rather, it highlights how differentiated technology platforms, distribution networks, and application-specific formulations create durable competitive advantages.
Polycaprolactone Market
Several key organizations anchor the market structure. BASF SE continues to advance Capromer polycaprolactone polyols and resins, reinforcing its presence in high-performance polyurethane elastomers, thermoplastic polyurethanes, and coatings. Daicel Corporation maintains a focused portfolio through PLACCEL diols, triols, and thermoplastic grades, emphasizing adhesives, coatings, and advanced polyurethane systems. Corbion's PURASORB PC grades demonstrate the ongoing relevance of PCL-based resorbable polymers in biomedical and drug delivery contexts, where regulatory compliance and material reliability drive commercial selection.
Across the broader value chain, Shenzhen Esun Industrial Co., Ltd. has expanded its footprint in medical-grade and standard polycaprolactone materials and filaments, aligning with the accelerating integration of biodegradable polymers into 3D printing and tissue engineering workflows. Haihang Industry Co., Ltd. complements this landscape by producing polycaprolactone pellets, diols, and specialty grades for polymer modification and industrial applications, reflecting the diversification of demand beyond biomedical endpoints.
Competitive advantage in this environment increasingly depends on the ability to synchronize product development with commercial channel strategy. Our full report assesses how each organization's technical roadmap, partnership networks, and regional execution capabilities position them relative to shifting demand patterns. We map these dynamics without reducing the analysis to static market-share tables, because in concentrated specialty markets, strategic relevance is defined more by application access, formulation leadership, and distribution agility than by headline volume alone.
Recent Developments: Signals of Accelerating Commercial Activity
The competitive environment has been further shaped by a series of recent commercial moves that illustrate how the market is evolving in real time. In May 2025, Amerigo Scientific introduced 3D electrospun polycaprolactone scaffolds specifically designed for 3D cell culture applications, highlighting the ongoing expansion of advanced research and biomedical use cases. In June 2025, Polymer Source announced a strategic distribution agreement with Indorama Ventures to expand access to high-performance specialty polyesters, including PCL-block copolymers, signaling tighter integration between specialty material producers and broader polymer supply networks. In July 2025, Evonik Industries entered a strategic distribution agreement with IMCD covering the EEA, UK, Switzerland, Turkey, and the Balkans for polycaprolactone-related products, reinforcing the importance of regional distribution architecture in specialty chemical markets.
These developments are valuable not because they represent isolated events, but because they reveal the operational logic of the market. Product introductions point toward where application innovation is gaining traction. Distribution agreements reflect where access, coverage, and channel control are being prioritized. The full report integrates these moves into a forward-looking competitive narrative, connecting near-term activity with medium-term structural implications.
Market Dynamics: Feedstock Volatility, Regulatory Shifts, and Trade Policy Exposure
The operating environment for polycaprolactone is influenced by intersecting macro forces that can alter cost structures, demand timing, and regional competitiveness. Feedstock conditions remain a central sensitivity. Cyclohexanone prices, as the primary feedstock for ε-caprolactone, fluctuated with regional increases ranging from 0.8 percent to 5.1 percent in May 2026, with North America at roughly US$2.6/kg, Europe at US$1.58/kg, and Northeast Asia at US$1.4/kg. Such dispersion directly affects conversion economics and can shift regional cost advantages in ways that influence sourcing strategies and inventory planning.
Regulatory and policy dynamics add further complexity. China's 2025 tariff reductions on competing polyolefins have pressured polycaprolactone pricing in Asia-Pacific coatings and automotive sectors, demonstrating how external trade actions can reshape relative material economics even when the polymer in focus is not the direct target of policy change. In the United States, the EPA is on schedule to propose amendments to TSCA's PFAS reporting rules that would roll back the requirement for manufacturers of PFAS or PFAS-containing materials to disclose use, production, disposal, and exposures by October 2026. At the same time, the EPA is proposing a rule to provide additional time for public water systems to come into compliance with maximum contaminant levels for PFOA and PFOS in drinking water, with finalization targeted for April 2026.
Trade policy exposure remains another critical variable. In April 2026, the US government imposed a 10 percent tariff on goods from all countries under Section 122 of the Trade Act of 1974, with plans to increase the rate to 15 percent. For globally integrated polymer supply chains, this introduces additional layers of cost uncertainty and regional routing considerations. These dynamics are often underappreciated in high-level market summaries, yet they materially affect margin planning, supplier selection, and geographic expansion timing. Our report embeds these forces within the broader analytical model so that decision-makers can assess them as interacting variables rather than isolated news items.
Why the Full Report Is Essential for 2026 Decision-Making
The macro trends outlined here confirm that polycaprolactone continues to occupy an increasingly strategic position within the broader specialty polymer landscape. However, strategic confidence requires more than directional awareness. It requires segmentation clarity, competitive differentiation mapping, regional cost sensitivity analysis, and application-specific demand forecasting that can be directly linked to investment, procurement, and product roadmap decisions.
The complete Polycaprolactone Market research study is designed to provide that linkage. It offers the detailed segmentation architecture needed to distinguish where growth will accrue, the competitive assessments required to identify viable partnership and positioning strategies, and the dynamic modeling necessary to evaluate how feedstock, regulatory, and trade developments will affect commercial outcomes. In a market where concentration, application performance, and policy exposure all influence risk-adjusted returns, access to integrated intelligence reduces the cost of uncertainty.
For leaders preparing for the 2026 operating environment and the forecast window through 2032, the full report serves as a practical foundation for scenario-based planning. It enables commercial teams to align on demand assumptions, supply chain teams to prepare for regional cost and availability variability, and strategy teams to evaluate where to allocate resources for maximum defensibility and growth capture.
Conclusion: Strategic Readiness Starts with Integrated Intelligence
Polycaprolactone's trajectory reflects broader shifts toward materials that combine biodegradability, processing flexibility, and performance reliability across demanding applications. The market's historical expansion, projected growth rate, and concentrated competitive structure all point to an environment where informed positioning matters increasingly. Recent product launches, distribution agreements, and policy developments further emphasize that the market is being shaped by active commercial maneuvering as much as by underlying demand fundamentals.
The full research report provides the detailed evidence base required to convert these observations into executable strategy. By integrating macro trajectory, segmentation depth, competitive analysis, and dynamic market forces into a single framework, it equips organizations to make 2026 decisions with greater precision and confidence. For teams seeking to move beyond surface-level trends and into the operational details that determine commercial outcomes, the complete study offers the strategic architecture needed to act decisively.
Caprolactone Market
For detailed analysis of this topic, please visit the official page: Polycaprolactone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


