



获取PW Consulting报告:微电子镀层市场2025年达19.1亿美元,2032年以8.15% CAGR增长

Strategic Imperatives in Microelectronics Plating: Navigating the 2026 Industrial Landscape
The microelectronics manufacturing sector stands at a critical inflection point where material precision dictates device performance. As semiconductor architectures shrink and packaging complexity increases, the role of advanced plating technologies has evolved from a secondary finishing step to a fundamental enabler of electrical connectivity and thermal management. For executives and strategy teams operating in this space, understanding the trajectory of the plating for microelectronics market is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and competitive positioning. PW Consulting's latest market research release provides a comprehensive lens into this evolving landscape, offering the analytical depth required to make informed decisions throughout the 2026 to 2032 forecast period.
Plating for Microelectronics Market
This industry has demonstrated consistent growth over the past half-decade, reflecting the broader expansion of electronic device adoption and the ongoing miniaturization of components. Historical data from 2020 through 2025 reveals a steady upward trajectory in market valuation. Starting from approximately 1.35 billion USD in 2020, the sector climbed incrementally each year, reaching nearly 1.91 billion USD by the base year of 2025. This growth underscores the entrenched demand for high-reliability metallization solutions across multiple manufacturing nodes. Looking forward, the forecast period projects continued expansion, with the market anticipated to surpass the 2 billion USD threshold in 2026 and accelerate toward nearly 3.3 billion USD by 2032. These macro-level indicators suggest that the fundamental drivers of demand remain robust, even as companies navigate shifting regulatory environments and raw material volatility.
However, raw top-line numbers only tell part of the story. The strategic value of modern market intelligence lies in understanding the underlying mechanics of growth, the competitive tensions shaping supplier relationships, and the operational risks that can erode margins. The following analysis outlines the key themes covered in the full research report, highlighting why this intelligence is essential for stakeholders planning their roadmap for the remainder of the decade.
Market Dynamics and the Cost of Compliance
The operational environment for plating suppliers is defined by a complex interplay of technological demand and regulatory pressure. While end-user sectors continue to drive volume, the cost structure of delivering plating solutions is undergoing significant change. Environmental regulations are tightening globally, directly impacting the economics of chemical usage and waste management. In the United States, strict Environmental Protection Agency discharge limits for copper-based effluents have forced facilities to invest heavily in treatment infrastructure. These compliance costs are not static; they represent a growing line item in operational budgets that must be accounted for in pricing strategies and capacity planning.
Plating Equipment Market
Similarly, the European market faces rising compliance burdens. Data indicates that the cost of chemical treatment and disposal for copper salts used in electroplating has risen substantially since 2021, driven by rigorous enforcement from regulatory bodies. This trend suggests that manufacturers located in or serving European jurisdictions must factor higher environmental overhead into their long-term financial models. Meanwhile, trade policy introduces another layer of uncertainty. Recent executive orders affecting import tariffs on raw materials such as copper sulfate and related compounds have altered the cost baseline for key inputs. These policy shifts can disrupt supply continuity and force rapid adjustments in sourcing strategies.
Raw material volatility further complicates the landscape. Price fluctuations in critical inputs like nickel sulfate have been observed tracking sensitivities in regional markets. For instance, recent assessments showed price movements in Chinese markets during the latter months of 2025, reflecting ongoing demand volatility. For plating service providers and chemistry suppliers, hedging against these fluctuations requires sophisticated supply chain oversight. The full report dives deeper into how these cost pressures vary across different process types and how leading firms are mitigating risk through vertical integration or long-term supply agreements.
Competitive Landscape and Strategic Consolidation
The market structure for microelectronics plating is moderately concentrated, with the top players holding a significant share of influence. Analysis of the competitive environment shows that the top three firms control a substantial portion of the market landscape, while the top five expand that reach even further. This concentration implies that pricing power and technology standards are often set by a handful of dominant entities. For new entrants or smaller specialized shops, the barrier to entry is not just technical capability but also the scale required to meet the stringent qualification processes of major semiconductor manufacturers.
Several key companies define the current boundaries of competition. MacDermid Alpha Electronics Solutions, based in the United States, continues to push the envelope in precious metal plating and copper pillar solutions specifically tailored for wafer-level packaging and compound semiconductor fabrication. Their focus on direct metallization chemistries for TSVs and RDLs positions them as a critical partner for advanced node development. In Europe, MKS Atotech leverages proprietary chemistries like Spherolyte and Xenolyte to serve advanced packaging and power semiconductor markets, with a strong emphasis on pad metallization and dual damascene processes.
Technic Inc. represents another major force, offering a broad suite of copper, nickel, tin, and precious metal plating chemistries alongside associated equipment. Their recent activity highlights the intensity of competition. In late 2025, Technic secured a major contract to supply high-purity platinum plating services for titanium diffusion barrier components, a move that solidifies their position in advanced packaging supply chains. This victory was complemented by a strategic partnership formed earlier that year with Oerlikon Balzers Coating. The collaboration aims to jointly develop and commercialize platinum-group metal plating solutions, signaling a trend where competitors collaborate on specific technology hurdles while competing elsewhere.
Specialized equipment manufacturers are also reshaping the landscape. ClassOne Technology introduced a 300mm Solstice Max platform in late 2025, integrating plating, photoresist strip, and wet etch capabilities. This kind of single-wafer solution addresses the need for flexibility and precision in high-reliability microelectronics. Meanwhile, Sharretts Plating Company announced strategic expansions in 2026 to advance wafer-level metallization capabilities, indicating that capacity investment remains a priority despite economic headwinds. Other players like Singulus Technologies focus on roll-to-roll electroplating equipment, catering to thin-film metallization needs that differ from traditional batch processing.
Consolidation is another theme gaining traction. Industry activity in 2025 saw acquisitions aimed at expanding specific capability sets, such as platinum plating for titanium components. These moves suggest that companies are seeking to broaden their portfolios to capture more value within the semiconductor packaging workflow. Understanding who owns which technology stream is vital for procurement teams evaluating supplier stability and for investors assessing the long-term viability of niche players. The full report provides detailed profiles on these key companies, tracking their recent developments, capacity changes, and partnership networks to help stakeholders map the competitive terrain.
Technology Drivers and Application Growth
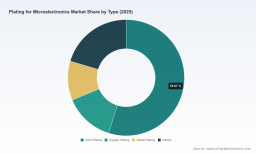
The demand for plating services is inextricably linked to the evolution of semiconductor packaging and device architecture. As components become smaller and more densely packed, the requirements for interfacial connectivity become more stringent. Gold plating remains a dominant segment within the market, driven by its superior conductivity and resistance to corrosion, which is essential for high-reliability applications. However, the cost of gold necessitates precise application techniques, pushing innovation toward thinner, more controlled layers.
Copper plating continues to be a workhorse for broader interconnects, balancing conductivity with cost efficiency. Nickel plating serves critical roles in barrier layers and surface hardness, ensuring durability in harsh operating environments. The diversity of material requirements means that suppliers must maintain a versatile chemistry portfolio. The market research breaks down the revenue contributions across these different material types, offering insights into which chemistries are seeing the strongest growth momentum. This segmentation is crucial for chemical manufacturers deciding where to invest R&D resources.
On the application side, the Printed Circuit Board sector remains a primary driver of volume. As PCBs become more complex to support higher data rates and power delivery, the quality of plating directly impacts signal integrity and thermal performance. Integrated Circuits also represent a significant demand center, particularly as wafer-level packaging and advanced interposers require precise metallization. The rise of Microelectromechanical Systems adds another dimension, where plating must meet precise dimensional tolerances and material properties for moving parts and sensors.
The report examines how these application segments are evolving relative to one another. While some areas may see steady mature growth, others linked to emerging technologies could experience accelerated expansion. For example, the push toward advanced packaging solutions like chiplets and 3D integration places new demands on plating processes that traditional methods may not satisfy. Stakeholders need to understand which application areas offer the best return on investment for capacity expansion or technology upgrades. The full analysis provides the granular breakdown necessary to identify these opportunities without relying on broad generalizations.
Why This Research Matters for 2026 Decision-Making
In a market characterized by technological rapid change and regulatory flux, intuition is insufficient. Decision-makers need data that connects market size projections to operational realities. This research is designed to bridge that gap. It moves beyond simple forecasts to explain the forces driving the numbers. By integrating historical performance from 2020 to 2025 with a detailed forecast through 2032, the report establishes a reliable baseline for scenario planning.
The strategic value extends to several key areas of corporate planning. For supply chain managers, the analysis of raw material trends and regulatory impacts helps in building resilient sourcing strategies that can withstand tariff changes and price volatility. For product developers, the segmentation data highlights where the demand is growing, allowing for prioritized development of chemistries or equipment that align with market needs. For competitive intelligence teams, the profiles of key companies and their recent developments offer early warnings of market shifts, such as capacity expansions or strategic partnerships that could alter supply dynamics.
Furthermore, the report addresses the concentration of the market. Knowing that the industry is dominated by a few large players changes how smaller firms approach partnership and acquisition strategies. It also informs large players about the risks of complacency and the need to continuously innovate to maintain their position. The inclusion of recent events, such as major contract wins and technology launches in 2025 and 2026, ensures that the analysis reflects the current state of play rather than outdated assumptions.
The forecast period from 2026 to 2032 is long enough to require serious investment planning but short enough to be actionable. Companies that base their capital expenditure decisions on rigorous market intelligence are better positioned to capture growth when it materializes. Those that rely on fragmented data or anecdotal evidence risk misallocating resources to declining segments or missing emerging opportunities in high-growth niches like advanced packaging metallization.
Conclusion
The plating for microelectronics market is poised for significant expansion over the coming years, driven by the relentless demand for more powerful and reliable electronic devices. However, realizing value in this environment requires more than just observing growth trends. It demands a deep understanding of the competitive dynamics, regulatory constraints, and technological shifts that define the industry. PW Consulting's latest market research provides the comprehensive intelligence needed to navigate this complexity.
The full report contains detailed segmentation data, rigorous company profiles, and specific forecasts that go beyond the overview presented here. It is an essential tool for executives, analysts, and investors who need to make precise, data-backed decisions in 2026 and beyond. To access the complete data sets, regional breakdowns, and proprietary insights, readers are encouraged to visit the source webpage and download the full study. The cost of uncertainty in this sector is high; the right intelligence is the best hedge against it.
For detailed analysis of this topic, please visit the official page: Plating for Microelectronics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


