



PW Consulting: Plastic Bonded Magnets Market to Hit $905M by 2032, 5.46% CAGR

Navigating Strategic Opportunities in the Plastic Bonded Magnets Market Through 2032
The global landscape for plastic bonded magnets is entering a phase of mature yet dynamic expansion. As industries ranging from automotive to advanced medical devices increasingly rely on compact, complex magnetic solutions, the demand for polymer-bonded magnetic materials has become a critical focal point for strategic planners. PW Consulting's latest market research report provides a comprehensive lens into this evolving sector, offering decision-makers the intelligence required to navigate supply chain complexities, regulatory shifts, and competitive pressures through the forecast period ending in 2032.
For organizations operating in or entering this space, the difference between reactive management and proactive strategy lies in the granularity of available data. This report moves beyond surface-level estimates to deliver actionable insights derived from rigorous analysis of historical performance and forward-looking indicators. By understanding the trajectory of the market, stakeholders can align their investment portfolios, manufacturing capabilities, and sourcing strategies with the realities of the coming strategic period.
Market Trajectory and Macroeconomic Indicators
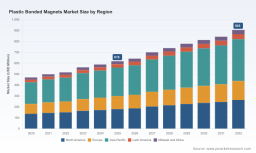
The historical data from 2020 through 2025 establishes a clear baseline for market resilience and growth. Over this six-year period, the market valuation demonstrated consistent upward momentum, reflecting steady adoption rates across key industrial verticals. This historical performance sets the stage for the forecast period extending from 2026 to 2032. Projections indicate that the global market revenue is expected to reach approximately 641.68 USD Million in 2026, continuing a steady climb to reach 905.0 USD Million by the end of the forecast horizon in 2032.
This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 5.46 percent throughout the forecast period. While this rate suggests stable growth rather than explosive disruption, it highlights the sector's role as a reliable component of broader industrial and technological supply chains. The consistency of this growth trajectory implies that demand drivers are structural rather than cyclical, rooted in the ongoing miniaturization of electronic components and the electrification of transport systems. Strategic planners must interpret this CAGR not merely as a financial metric but as an indicator of sustained capital investment opportunities within production capacity and research and development.
Segmentation Dynamics and Value Distribution
Understanding where value is generated within the plastic bonded magnets market is essential for resource allocation. The market is segmented by region, type, and application, each presenting distinct risk and reward profiles. The Asia Pacific region currently stands as the dominant revenue contributor, reflecting its position as both a major manufacturing hub and a center for high-tech electronics consumption. North America follows as a significant market, driven by strong industrial and medical device sectors, while Europe maintains a steady presence supported by automotive manufacturing and engineering excellence. Emerging regions such as Latin America and the Middle East and Africa represent smaller but potentially growing avenues for diversification.
When analyzing the market by type, injection molded magnets account for the largest share of revenue. This preference is driven by the ability to produce complex geometries with high precision, which aligns with the needs of modern sensor and motor applications. Compression molded magnets constitute the second largest segment, offering advantages in specific performance characteristics where isotropy is required. Other types, while representing a smaller portion of the total revenue mix, cater to niche applications that require specialized material properties.
In terms of application, the automotive sector is the primary driver of demand. The shift toward electric vehicles and the proliferation of advanced driver-assistance systems have intensified the need for reliable magnetic components that can withstand harsh operational environments. The electronics industry follows closely, fueled by the continuous demand for consumer gadgets, telecommunications infrastructure, and computing hardware. Medical devices, industrial equipment, and other applications round out the demand profile, each contributing to the overall health of the market in ways that are critical for specialized suppliers.
Competitive Landscape and Strategic Positioning
The market structure indicates a moderate level of concentration, with the top three companies accounting for approximately 42 percent of total market share and the top five firms holding around 48 percent. This concentration suggests that while established players hold significant influence, there remains sufficient fragmentation to allow for strategic entry or expansion by agile competitors. The competitive environment is defined by a mix of global technology giants and specialized manufacturers, each leveraging distinct capabilities to capture value.
Switzerland-based Bomatec AG remains a key player, focusing on injected and pressed plastic-bonded NdFeB magnets using binders such as polyamide 11, 12, or PPS. Their ability to offer complete assemblies provides a competitive edge in delivering turnkey solutions. Similarly, GMB Deutsche Magnetwerke GmbH in Germany specializes in custom-designed injection-molded components using NdFeB, SmCo, or ferrite powders in polyamide or epoxy resin matrices. Their focus on customization allows them to serve clients with highly specific technical requirements.
In the United States, Arnold Magnetic Technologies continues to expand its footprint by offering injection-molded and compression-bonded magnetic components for automotive, industrial, and medical markets. Their recent launch of a new line of high-temperature plastic-bonded magnets designed for aerospace applications in August 2024 demonstrates a commitment to pushing performance boundaries in demanding sectors. Bunting Magnetics Co. and Dexter Magnetic Technologies also maintain strong positions, with Bunting focusing on vertically integrated production including compound preparation, and Dexter specializing in custom assemblies for medical devices, sensors, and aerospace applications.
Asian manufacturers are equally pivotal. Daido Electronics Co., Ltd. in Japan produces isotropic polymer-bonded Nd-Fe-B magnets and radially oriented anisotropic ring magnets with ISO 9001:2015 certification, emphasizing quality and consistency. TDK Corporation leverages its broader electronics portfolio to produce bonded magnets for automotive and electronics applications. In China, Ningbo Yunsheng and DMEGC Magnetics manufacture bonded magnets with emphasis on plastic-bonded types for industrial use, capitalizing on regional supply chain efficiencies. Evitron in Poland and Nichia Corporation, which showcased advancements in bonded SmFeN magnets at MDSM 2025, further illustrate the global reach and technical diversity of the supplier base.
Industry Dynamics and Risk Factors
Strategic planning in this sector must account for significant external pressures that could alter market trajectories. One of the most pressing concerns involves the supply chain security of rare-earth elements. According to data from the U.S. Geological Survey, China accounts for over 60 percent of global rare earth production. This concentration creates inherent supply risks for manufacturers dependent on these materials. In April 2025, China tightened its export controls on rare-earth elements, adding restrictions on exports of products containing even trace amounts of Chinese content. This was followed by more stringent controls imposed in September 2025, which resulted in exports of bonded magnets declining 6.1 percent month-over-month.
These regulatory shifts underscore the vulnerability of global supply chains and highlight the importance of diversification strategies. Companies that rely heavily on single-source sourcing for critical raw materials face increased exposure to geopolitical tension and trade policy volatility. Conversely, the U.S. Department of Defense has committed funding under the Defense Production Act to develop domestic rare earth processing and magnet manufacturing capabilities. This initiative supports local production of plastic bonded magnets and may offer opportunities for suppliers aligned with domestic manufacturing incentives.
Environmental regulations also present a evolving challenge. The European Chemicals Agency (ECHA) has progressively expanded its REACH regulation scope, scrutinizing thermoplastic and thermoset binder systems used in plastic bonded magnets for environmental persistence. As compliance requirements tighten, manufacturers may need to invest in alternative binder technologies or process adjustments to maintain market access in Europe. These regulatory dynamics add a layer of complexity to product development and lifecycle management that must be factored into long-term strategic roadmaps.
Core Content and Analytical Framework of the Report
To support leaders in navigating these complexities, the report provides a multi-faceted analytical framework. It begins with a detailed executive summary that distills key findings and strategic implications for immediate decision-making. The market overview section contextualizes the industry within the broader macroeconomic environment, examining factors such as industrial production rates, automotive sales trends, and electronics consumption patterns that drive demand.
The segmentation analysis offers a granular view of revenue distribution across regions, types, and applications. Rather than simply presenting static numbers, the report examines the growth drivers and constraints within each segment. This approach helps identify which sub-markets offer the highest potential for expansion and which may face headwinds due to technological substitution or regulatory hurdles. The forecast section projects market size and growth rates through 2032, providing baseline scenarios that can be stress-tested against internal planning assumptions.
A significant portion of the report is dedicated to the competitive landscape. It profiles key companies, analyzing their product portfolios, manufacturing capabilities, and recent strategic moves. This includes an assessment of recent developments such as new product launches and expansions that signal shifting priorities among market leaders. By understanding the moves of competitors, organizations can anticipate market reactions and identify gaps in the current supply offering.
Worldwide Flexible NdFeB Market
Furthermore, the report delves into supply chain dynamics, raw material availability, and regulatory impacts. It evaluates the implications of export controls, environmental regulations, and government funding initiatives on cost structures and supply security. This section is critical for operations managers and procurement specialists tasked with mitigating risk in an unstable geopolitical environment. The synthesis of these factors provides a holistic view of the market that goes beyond simple revenue projections.
Strategic Imperatives for Decision Makers
The insights contained in this research are designed to empower specific strategic actions. For manufacturing firms, the data supports decisions regarding capacity expansion, technology investment, and geographic footprint optimization. Understanding the relative performance of injection molded versus compression molded segments can guide capital expenditure toward the production methods most aligned with future demand shifts. Similarly, recognizing the dominance of the automotive and electronics applications helps prioritize resource allocation toward the sectors with the strongest growth signals.
For investors and financial analysts, the report offers a foundation for valuation models and risk assessment. The market concentration data and competitive profiling assist in evaluating the sustainability of market shares and the potential for disruption. The identification of regulatory and supply chain risks allows for a more accurate pricing of risk in investment portfolios. For procurement and supply chain professionals, the analysis of raw material risks and regulatory changes provides the intelligence needed to diversify sourcing strategies and secure long-term contracts that protect against volatility.
The period from 2026 to 2032 will be defined by how well organizations adapt to these interconnected forces. The market is large enough to support multiple winners but competitive enough to reward efficiency and innovation. Companies that leverage the detailed intelligence in this report will be better positioned to optimize their operations, mitigate supply chain risks, and capture value in the high-growth segments of the plastic bonded magnets industry.
Plastic Bonded Magnets Market
Access to the full dataset and detailed interpretive commentary is available through the complete PW Consulting report. By leveraging this comprehensive intelligence, stakeholders can transform uncertainty into a structured plan for growth and resilience in the years ahead.
For detailed analysis of this topic, please visit the official page: Plastic Bonded Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


