



PW Consulting: Vacuum Interrupter Market Hits 2.78B in 2025, Driven by 4.16% CAGR to 3.7B by 2032

Navigating the Vacuum Interrupter Market: Strategic Intelligence for 2026 and Beyond
The global vacuum interrupter market stands at a critical inflection point. As grid modernization accelerates and renewable energy integration reshapes medium-voltage infrastructure, equipment manufacturers, utility planners, and investment committees require more than surface-level forecasts. They need defensible, scenario-ready intelligence that connects macroeconomic tailwinds to operational decision-making. Our latest Vacuum Interrupter Market research report delivers exactly that—a structured, data-grounded framework designed to guide capital allocation, product roadmapping, and competitive positioning through 2032.
This article previews the analytical architecture of the study, outlines the operational insights embedded within, and clarifies why 2026 represents a make-or-break window for stakeholders operating across the medium-voltage switching ecosystem. Core granular data points remain intentionally reserved for the full report, ensuring that procurement leaders, product managers, and strategy directors receive a verified signal before committing to deep-dive purchasing decisions.
Market Trajectory: Reading the Curve Beyond Headline Numbers
Historical tracking from 2020 through the base year of 2025 reveals a market that has matured through cycles of infrastructure investment, supply chain recalibration, and shifting deployment priorities. The trajectory shows consistent expansion, with measured annual valuations progressing from early-2020s baselines toward a 2025 footing in the high two-billion-dollar range. Looking forward, the forecasting window spans 2026 to 2032, during which the market is projected to advance toward a valuation approaching the mid-three-billion-dollar threshold.
The implied compound annual growth rate across the forecast horizon sits at 4.16 percent, a pace that signals steadiness rather than explosive disruption. For strategic planners, this profile matters because moderate, predictable expansion typically rewards players who optimize supply reliability, certification readiness, and regional service coverage over those chasing speculative volume spikes. The growth curve also underscores a structural reality: vacuum interrupter demand is increasingly tied to upgrade cycles in existing substations, expansion of ring-main networks, and the replacement of aging switching components in distribution networks.
Vacuum Isolators Market
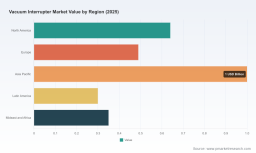
Readers should note that overall market sizing tells only part of the story. The full report decomposes this trajectory across multiple analytical dimensions, allowing decision-makers to isolate the segments most relevant to their portfolios. Those granular breakdowns—by geography, application, and voltage class—are deliberately withheld here to preserve the integrity of the paid intelligence and to encourage a targeted evaluation of the complete dataset.
Structural Dynamics Shaping Demand and Supply
Several interlocking forces are redefining the operating environment for vacuum interrupter manufacturers and buyers. First, grid modernization initiatives continue to accelerate across mature and emerging power networks alike. As utilities replace legacy air-insulated and oil-based switching equipment, vacuum interrupters have emerged as a preferred solution for their sealed architecture, reduced maintenance burden, and compatibility with compact substation footprints.
Second, the integration of renewable generation is creating new switching node requirements. Distributed solar, wind aggregation points, and hybrid grid-edge installations demand interruption technology that can handle frequent cycling, maintain dielectric recovery, and align with modern protection schemes. These trends are pushing medium-voltage switchgear manufacturers to reevaluate component specifications, particularly for applications where operational reliability must be maintained under variable load profiles and fault conditions.
Third, regulatory and standards-driven compliance remains a non-negotiable gatekeeper. Vacuum interrupters are certified according to IEC, ANSI, and GB standards for reliable operation in medium-voltage applications, while product specifications must meet or exceed IEEE, UL/CSA, IEC, JEC, and GB/DL expectations, supported by ISO 9001 and ISO 14001 certification in many 조달 environments. Independent verification also plays a central role: IEC 62271-100 type test reports from accredited laboratories verify vacuum interrupter performance for fault currents up to 40 kA. For procurement teams, this means that supplier evaluation is as much about documentation and test evidence as it is about quoted unit economics.
On the supply side, material costs introduce a persistent constraint. The high cost of copper chromium alloy contacts in vacuum interrupters for high-voltage applications serves as a primary restraining factor on market expansion, influencing both pricing strategy and margin management for OEMs and component suppliers. This cost dynamic interacts with production scale, metallurgy capabilities, and yield discipline, making process optimization a strategic differentiator rather than a back-office concern.
Competitive Landscape: Scale, Specialization, and Geographic Footprints
The competitive set in this market spans global electrical conglomerates, regional switchgear specialists, and component-focused manufacturers. The report provides a structured competitive scan that goes beyond simple company listings, examining how each player positions itself across voltage classes, end-use applications, and certification frameworks. Market concentration metrics underscore the importance of incumbency: the top three firms account for roughly 50 percent of market share, while the top five collectively represent about 65 percent, indicating a landscape where established players retain substantial influence but where focused niche competitors can still secure defensible positions.
A representative cross-section of the competitive field illustrates the breadth of strategic postures currently in play. ABB produces vacuum interrupters and embedded poles for medium-voltage applications up to 40.5 kV, drawing on over 40 years of experience with certifications aligned to IEC, ANSI, and GB standards. Eaton offers custom vacuum interrupter solutions for circuit breakers and switchgear, meeting IEEE, IEC, and GB/DL requirements with a heritage rooted in electrical circuit protection. Siemens develops proprietary vacuum interrupters optimized for medium-voltage components, engineered as hermetically sealed units for reliable switching in grid applications.
In Asia, Mitsubishi Electric manufactures vacuum interrupters ranging from 1.5 kV to 84 kV for vacuum circuit breakers, load switches, and contactors, with total production exceeding 3.5 million units. Meidensha has operated as a pioneer since 1965, producing vacuum interrupters from 3.3 kV to 145 kV with long operating life up to 250,000 cycles and IEC/ANSI/GB certifications. Schneider Electric provides vacuum interrupters in medium-voltage switchgear, including Shunt Vacuum Interrupter technology for grid modernization and renewable integration. Toshiba operates advanced vacuum metallurgy facilities supporting vacuum interrupters used in railway traction and high-cycle industrial switching applications.
Further broadening the field, CG Power and Industrial Solutions supplies vacuum interrupters within its medium-voltage electrical equipment portfolio for power distribution and industrial uses. LS Electric manufactures vacuum interrupters integrated into switchgear systems for medium-voltage applications. Fuji Electric produces vacuum interrupters for circuit breakers and contactors certified to international standards. At the regional and specialized end of the spectrum, Shone Vacuum Electrical Apparatus focuses on high-quality vacuum interrupter production and sales with R&D emphasis on advanced materials and strict quality control for domestic and export markets. Xi'an XD High Voltage Apparatus develops and manufactures high-voltage apparatus including vacuum interrupters for power transmission and distribution. Changshu Switchgear Manufacturing produces switchgear components including vacuum interrupters for electrical equipment applications. Beijing Beiyi Electric concentrates on research and production of vacuum interrupters with advanced processes for power plants and substations. GLVAC offers vacuum interrupters as core components for vacuum switches in power equipment systems.
This competitive diversity matters because procurement strategies increasingly depend on application fit, certification alignment, and supply continuity rather than price alone. The full report maps these profiles against segment relevance, enabling readers to benchmark supplier options against their specific voltage, cycling, and compliance requirements.
Recent Developments Signaling the Pace of Change
Market movement is not abstract; it is visible in product releases, production milestones, and partnership activity. In the first quarter of 2026, Schneider Electric launched the Ringmaster AirSeT medium-voltage switchgear featuring a Shunt Vacuum Interrupter mechanism with three-position ring operation, SCADA connectivity, and a 30-year design life. This launch reflects a clear industry push toward longer service life, smarter connectivity, and modular substation architectures.
On the production and scale side, ABB reached a cumulative delivery milestone of 7 million vacuum interrupters from its factory in Ratingen, Germany, underscoring the importance of manufacturing credibility and long-running process maturity in a market where reliability is a core selling point. Meanwhile, in mid-2025, General Electric entered a strategic partnership with a leading renewable energy developer for co-development of advanced vacuum interrupter technologies, signaling how incumbents are beginning to align R&D directly with the needs of renewable-heavy grid environments.
Vacuum Interrupter Market
These events are not isolated headlines; they are indicators of where capability investments are flowing. The report situates such developments within a broader trend analysis, helping readers separate marketing momentum from structural adoption signals.
What the Report Delivers: An Operational Toolkit for 2026 Decisions
The study is structured to support concrete decisions rather than general orientation. It combines market sizing, forecast modeling, segmentation analysis, competitive profiling, and regulatory context into a single decision-support framework. Key components include:
- Macro market sizing and forecast pathways anchored to a defined historical window and a forward outlook through 2032, expressed in USD billion terms.
- Segment-level analysis across regional demand patterns, application categories, and voltage-class distributions, designed to help readers identify where growth is concentrated and where substitution risk may arise.
- Competitive profiling of major manufacturers, including headquarters, product scope, certification posture, and operational scale indicators.
- Regulatory and standards context covering IEC, ANSI, GB, IEEE, UL/CSA, JEC, and GB/DL expectations, alongside ISO certification relevance and type-test verification for fault current performance.
- Supply-side constraints and enablers, including material cost dynamics, metallurgy considerations, and production scale implications for margin and availability.
- Recent corporate developments—product launches, milestones, and partnerships—that illustrate how incumbents and challengers are repositioning for medium-voltage grid modernization.
Importantly, the report is built for scenario use. Readers can isolate the segments that match their product lines, regional targets, or procurement programs and then stress-test assumptions around growth pace, competitive pressure, and compliance requirements. This modularity is particularly valuable for teams building multi-year capacity plans or evaluating entry and expansion opportunities in medium-voltage switchgear and protection equipment markets.
Why 2026 Is a Decision Pivot
The forecast period begins in 2026, and that timing is strategically meaningful. At a projected 2026 valuation approaching 2.95 billion USD, the market is moving from a phase of steady historical growth into a period where policy-driven infrastructure spending, renewable integration mandates, and substation upgrade cycles begin to compound. For manufacturers, this is the moment to align production capacity, certification portfolios, and regional distribution with the segments most likely to absorb incremental volume. For distributors and system integrators, it is the moment to secure supply commitments and differentiate on service reliability rather than commodity pricing. For investors and corporate strategy teams, it is the moment to separate durable growth narratives from short-term procurement timing effects.
The market’s moderate CAGR suggests that winners will not be determined by speculative overbuild, but by precision: the ability to match voltage-class coverage, application-specific performance, and standards compliance to the right geographies and customer programs. The full report provides the segmentation granularity required to make those matches with confidence.
Reserved Intelligence and How to Use It
In keeping with the analytical purpose of this preview, detailed regional splits, application-level values, and voltage-class proportions are not disclosed here. These figures are central to the report’s commercial value because they enable tailored planning for specific product lines and market-entry strategies. The full study makes those breakdowns available in a structured format, allowing stakeholders to benchmark against their own pipeline assumptions and to refine procurement or production plans accordingly.
Leaders evaluating this market for 2026 planning should treat the preview as a confidence check. If the macro trajectory, competitive breadth, standards environment, and recent product and partnership signals align with your internal assumptions, the full report offers the precise segment intelligence needed to convert strategy into execution. If gaps remain, the complete dataset provides the reference points required to recalibrate.
Closing Perspective
The vacuum interrupter market is not experiencing a sudden rupture; it is undergoing a calculated evolution shaped by grid modernization, renewable integration, compliance rigor, and material-cost discipline. That evolution favors organizations that can read the market at the segment level, match technology capability to application need, and build supply credibility over time. The full Vacuum Interrupter Market research report is designed to support exactly that posture, offering a comprehensive, forecast-anchored, and competitively detailed foundation for 2026 decision-making.
For strategic teams ready to move from directional understanding to actionable planning, the complete report provides the reserved segmentation, competitive depth, and scenario-ready structure necessary to make informed commitments in a market where reliability, certification, and timing increasingly determine outcomes.
For detailed analysis of this topic, please visit the official page: Vacuum Interrupter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


