



PW Consulting: Zinc Selenide Market Hits $170M in 2025, 4.8% CAGR Outlook to 2032

Zinc Selenide Market Outlook: Strategic Imperatives for Decision-Makers in 2026 and Beyond
As industrial systems increasingly demand precision infrared optics, zinc selenide (ZnSe) has moved from a niche specialty material to a strategically important component across laser processing, thermal imaging, and spectroscopic instrumentation. The transition is not merely a story of improved device performance. It reflects deeper shifts in supply chain resilience, regulatory scrutiny on critical raw materials, and the competitive dynamics of a concentrated but globally distributed manufacturer base. For executives navigating capital allocation, product roadmaps, and sourcing strategies, the market warrants a structured and evidence-based reading.
Zinc Sulfide Market
This article previews the strategic logic behind our latest Zinc Selenide Market research. It outlines the macro trajectory, the structural forces shaping demand, the competitive landscape, and the operational variables that matter most in planning windows through 2032. The objective is to give leadership teams a credible foundation for decision-making while signaling where deeper, granular intelligence can sharpen execution.
Why the ZnSe Market Matters Now
ZnSe occupies a distinct position in the infrared optics value chain because it combines broad transmissivity in the mid-wave and long-wave infrared with practical manufacturability for components that must withstand high-power laser environments. That combination has made it especially relevant for CO2 laser optics, thermal imaging platforms, and spectroscopy systems used across industrial, medical, and defense-adjacent applications. The material is not a commodity in the traditional sense; it is a performance-critical input where purity, homogeneity, and coatings directly influence end-device reliability.
At the same time, ZnSe markets are shaped by upstream constraints. Seaborne selenium supply, refinery output dynamics, and price volatility in key sourcing regions all feed into production economics for substrates and optical components. Downstream, the growth of infrared-enabled technologies across automation, sensing, and advanced manufacturing continues to expand the addressable space for ZnSe, even as buyers become more selective about quality consistency and supply continuity.
Macro Trajectory: Resilience With Steady Expansion
The market has demonstrated a measured but persistent growth path over the recent historical period, with revenue expanding from 144.0 million USD in 2020 to approximately 170.0 million USD in 2025. That progression reflects more than incremental demand. It indicates a market that is consolidating its role within higher-value optical systems while adapting to fluctuating input costs and shifting regional manufacturing footprints.
Looking forward, the forecast period suggests continued expansion, with the market moving from about 175.5 million USD in 2026 toward roughly 235.0 million USD by 2032. The implied compound annual growth rate of 4.8 percent is not explosive, but it is meaningful in a materials market where scale is often constrained by specialized production capacity, qualified supply chains, and application-specific qualification cycles. For planners, the key takeaway is that ZnSe growth is likely to be durable rather than episodic, with the most significant opportunities accruing to participants who can align product portfolios with higher-growth end-use segments and secure reliable material access.
Because this is a concentrated sector, strategic planning also requires attention to structure. The market is not fragmented in a way that makes pricing or availability purely transactional. Positionality matters, and the firms that can combine material expertise with component-level fabrication, coating capability, and customer-specific qualification support are better placed to capture value beyond base material sales.
Structural Forces Shaping 2026–2032
The forward trajectory is best understood as the interaction of several forces rather than a single demand driver.
Raw material backdrop and cost sensitivity
Selenium availability and pricing remain central to ZnSe production economics. Recent reporting points to reduced domestic output of crude selenium and selenium-bearing copper anode slimes in the United States, alongside price increases in both U.S. and European warehouse markets. Even where percentage changes appear moderate, the practical impact on producers can be outsized because ZnSe manufacturing depends on controlled reaction environments and high-purity precursors. In this context, procurement strategy, inventory design, and supplier qualification are not back-office tasks; they are strategic levers.
Regulatory and safety considerations
ZnSe is treated with caution in handling and environmental compliance. Classifications associated with acute toxicity risks through ingestion and inhalation, as well as toxicity to aquatic life with long-lasting effects, mean that responsible suppliers and end users must manage documentation, containment, and disposal practices with rigor. At the same time, certain regulatory exemptions can be relevant to registration obligations. This dual reality, genuine safety management requirements combined with specific regulatory treatment, makes compliance literacy a differentiator. Companies that can demonstrate controlled handling, transparent documentation, and consistent quality systems may gain an edge in qualified supply chains where auditability matters.
Application pull from infrared-intensive industries
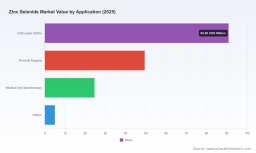
Demand is being reinforced by applications that rely on stable infrared transmission and robust mechanical performance. CO2 laser optics remain a central use case, where ZnSe components are expected to function under sustained power and thermal loading. Thermal imaging and medical or spectroscopy-related systems add further breadth, creating a demand mix that is diversified but still anchored by a few high-impact segments. Organizations planning product investments should treat this as a cue to evaluate where their own roadmaps intersect with infrared optics bottlenecks, particularly in environments where alternative materials may not match ZnSe’s balance of transmission and manufacturability.
Competitive Landscape: Concentrated Expertise, Diverse Footprint
The ZnSe market is best characterized as a specialized arena where competitive advantage stems from material know-how, production consistency, and the ability to deliver finished or semi-finished optics rather than raw crystals alone. The participating firms span multiple geographies and business models, from vertically integrated producers to specialist component suppliers and regional materials experts.
Several firms illustrate the range of strategic positions in the market. Coherent Corp. represents a vertically integrated approach, with capabilities that extend from ZnSe substrates and bulk optical materials through fabrication into lenses, windows, output couplers, beamsplitters, and other infrared optics. This integration can reduce handoff risk between material production and component realization, an important consideration for customers seeking qualified supply for demanding laser and IR systems.
Crystran Ltd. and KORTH Kristalle GmbH reflect deep specialization in polycrystalline ZnSe and high-power laser-grade components. Their emphasis on CVD-based production and controlled homogeneity for 10.6 µm applications underscores how material processing precision directly enables performance in CO2 laser contexts. In practical terms, the ability to supply thicker plates or large-area substrates with consistent optical properties is not a minor detail; it determines whether a component can meet the requirements of high-stress optical assemblies.
Edmund Optics Inc. demonstrates the importance of the distribution and customization layer. By supplying both standard and custom ZnSe components, such firms bridge the gap between material supply and end-application integration, providing optics that are immediately usable in a range of IR setups. For buyers, this model can reduce lead-time risk and simplify procurement for non-custom or lower-volume needs.
Alkor Technologies and Crystaltechno Ltd. illustrate the role of high-purity CVD production and broader II-VI material expertise in the market, including advanced coating capabilities. Meanwhile, Vital Materials Co., Ltd. and R'AIN Group highlight the expanding presence of suppliers aligned to infrared optics, semiconductor lasers, thermal imaging, and advanced detector-related uses. Together, these players point to a landscape where regional presence, material purity, and coating or fabrication support all contribute to market positioning.
Strategic implication: competitive advantage in this market is often cumulative. The strongest positions tend to emerge where suppliers combine material reliability, qualified fabrication, and the ability to support customers through specification, testing, and volume scaling. For buyers and investors alike, understanding these capabilities at the firm level is more useful than treating ZnSe as a uniform commodity.
What the Research Delivers: An Executive-Focused Toolkit
Our Zinc Selenide Market study is designed to support operational and strategic decisions rather than to offer only top-line figures. The report maps the market across type, application, and region, while embedding the macro trajectory within a framing that helps executives interpret risk, opportunity, and timing. It is structured to answer practical questions that arise in sourcing, product planning, and competitive positioning.
The analysis includes:
- A historical and forecast view of market scale and growth dynamics, anchored in a base year of 2025 and extended through the forecast period to 2032, with an emphasis on interpreting trend direction rather than treating numbers in isolation.
- Segmentation that distinguishes among major product types and application contexts, helping teams identify where ZnSe demand is most concentrated and where differentiation is most achievable.
- Regional context that situates demand and supply patterns across key markets, without reducing the story to a single geography, since the material’s supply chain and end-use base are internationally distributed.
- Competitive profiling that goes beyond corporate descriptions to explore the strategic significance of vertical integration, material purity, CVD expertise, component fabrication, and coating capability.
- Regulatory and safety context, including handling considerations and compliance-relevant details that can influence procurement choices, qualification requirements, and supply chain design.
- Upstream factors such as selenium supply and pricing dynamics, integrated into the broader interpretation of cost structure, margin sensitivity, and sourcing resilience.
In short, the report is intended to support decisions about where to participate, how to source, which applications to prioritize, and how to assess competitors not just by scale but by technical and operational credibility.
Decision Themes for 2026 Planning
For leadership teams planning around 2026, several practical themes emerge.
First, treat ZnSe as a performance enabler with supply-chain stickiness. Where end systems depend on dependable infrared transmission and component durability, switching costs and qualification cycles can be significant. That makes supplier reliability and documentation quality strategically valuable, not merely operational.
Zinc Selenide Market
Second, integrate raw-material awareness into procurement and capacity planning. Selenium market conditions, refinery output, and regional price movements can affect cost structures and availability. Even when the market expands steadily, the ability to manage input volatility can determine whether a participant captures margin or merely maintains volume.
Third, evaluate competitive differentiation through capability rather than headline presence. Vertical integration, substrate-to-component control, high-purity CVD production, and coating or customization capacity can matter more than simple product listings. In interviews, sourcing reviews, and partnership decisions, these capabilities should be assessed against the specific requirements of the target application.
Fourth, align product and investment planning with the application mix that most strongly benefits from ZnSe’s properties. CO2 laser optics, thermal imaging, and spectroscopy-related uses are not interchangeable from a materials standpoint. Mapping internal roadmaps to the segments where ZnSe provides the most credible advantage can improve capital efficiency and reduce design risk.
Fifth, incorporate compliance and handling discipline into supplier evaluation. In markets with acute toxicity and environmental sensitivity concerns, robust MSDS practices, auditable handling procedures, and clear regulatory positioning are part of the commercial value proposition. They can influence qualification speed, risk exposure, and long-term partnership stability.
What Is Held Back: Why the Full Intelligence Matters
This preview establishes the strategic frame and the macro logic, but the market’s actionable detail is more granular than any summary can responsibly convey. Segment-level revenue splits, regional breakdowns, application-level allocations, and firm-specific positioning nuances all require careful presentation because they directly affect sourcing choices, investment timing, and competitive benchmarking. Publishing those specifics here would reduce the value of the underlying analysis and, more importantly, could mislead planning if taken out of context.
The full research provides that depth in a structured, decision-ready form, allowing teams to compare opportunities across type, application, and region while interpreting them against the competitive and regulatory environment. It also connects the numbers to the operational realities that determine whether a market trajectory can actually be captured.
How to Use This Insight
The value of this market research is not limited to understanding where the ZnSe market is going. It is most useful when it helps organizations decide what to do next. Procurement teams can use it to refine supplier qualification criteria and scenario planning around input volatility. R&D and product leaders can use it to validate application priorities and material choices. Strategy and corporate development teams can use it to assess where vertical integration, partnerships, or geographic coverage would create durable advantage.
For executives who need to justify resource allocation in 2026, the strongest use of this intelligence is to connect market direction with internal capability gaps and sourcing exposure. That is where the report moves from description to delivery: it is built to support concrete actions, not just narrative awareness.
To access the complete segmentation, competitive assessment, regional interpretation, and operational context, readers are encouraged to explore the full study on the source page. There, the detail is presented in a way that allows teams to integrate it directly into planning workflows, sourcing reviews, and investment discussions.
For detailed analysis of this topic, please visit the official page: Zinc Selenide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


