



PW Consulting: PPS Resin Market to Hit $3.47B by 2032, Driven by 7.8% CAGR

Navigating the Polyphenylene Sulfide Landscape: Strategic Imperatives for 2026 and Beyond
In an era defined by accelerated material innovation, supply chain volatility, and stringent sustainability mandates, the global Polyphenylene Sulfide (PPS) resin market stands at a critical inflection point. For corporate strategists, procurement leaders, and R&D directors across high-performance engineering sectors, the ability to anticipate demand trajectories, identify emerging capacity shifts, and decode competitive positioning is no longer a luxury. It is a prerequisite for sustained market share and margin protection. Our newly released PPS Resin Market Research Report delivers exactly that: a rigorously validated, forward-looking intelligence framework calibrated to guide executive decision-making through 2032 and beyond.
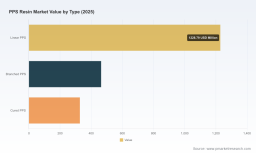
The macro trajectory tells a compelling story. From a baseline of USD 1,450.0 Million in 2020, the market has consistently compounded upward, reaching USD 2,020.0 Million in 2025. Our baseline forecast projects the sector will exceed USD 2,143.6 Million in 2026 and continue its upward march to USD 3,470.0 Million by 2032. Anchored by a robust compound annual growth rate of 7.8 percent, the expansion is neither accidental nor cyclical. It reflects structural demand drivers, evolving material substitution patterns, and deliberate capacity reallocation by Tier-1 producers who are actively reshaping the competitive architecture. Yet, headline figures only scratch the surface. The real strategic value lies in understanding the mechanics beneath the aggregate numbers: how demand is being reallocated across value chains, where production bottlenecks are forming, and which players are positioning themselves to capture disproportionate share in high-margin end-use segments.
This intelligence brief serves as a strategic preview. It outlines the core analytical pillars embedded in our full study, highlights the competitive dynamics currently redrawing the market map, and demonstrates how procurement and product development teams can leverage granular, actionable data to optimize sourcing strategies, de-risk supply chains, and accelerate time-to-market for next-generation engineered components.
Polysulfone Resin Market
Decoding the Report Architecture: What Decision-Makers Will Gain
Our research methodology is built on a multi-layered analytical framework that moves far beyond top-line market sizing. The full report synthesizes historical trajectory data, forward-looking demand modeling, supply-side capacity mapping, and application-specific consumption patterns into a unified decision-support toolkit. Rather than presenting static snapshots, we track momentum. The historical period from 2020 to 2025 establishes the baseline behavior of the market across economic cycles, raw material fluctuations, and regional demand shocks. The forecast window from 2026 through 2032 extends that modeling into scenario-weighted projections that account for macroeconomic variables, technological adoption curves, and regulatory inflection points.
Throughout the document, readers will encounter structured analytical modules designed for direct operational translation. These include demand-side consumption mapping across major end-use verticals, supply-side capacity and utilization tracking by manufacturing geography, and segmentation analysis that isolates growth vectors within resin type categories and application clusters. Each module is cross-referenced with pricing sensitivity indicators, feedstock dependency assessments, and sustainability compliance tracking. The goal is to equip strategists with a complete operational lens: one that connects macroeconomic demand signals to plant-level capacity decisions, and links regulatory developments to formulation and sourcing strategies.
Crucially, the report is structured to support iterative decision-making. Executives can use it to stress-test procurement portfolios, identify long-term supply continuity risks, evaluate joint-venture or contract-manufacturing opportunities, and benchmark internal performance against industry growth curves. R&D and product development teams will find targeted insights into grade differentiation, thermal and chemical resistance requirements, flow characteristics for high-volume injection molding, and the growing importance of recycled-content variants in meeting corporate sustainability targets.
Competitive Recon: Mapping the Architecture of Market Leadership
Market concentration in the global PPS resin sector remains pronounced, with the top three producers collectively accounting for approximately 65 percent of total revenue and the top five controlling roughly 80 percent. This concentration does not imply stagnation. On the contrary, it reflects deliberate capital allocation, technological specialization, and strategic geographic positioning by a tightly aligned group of performance-material manufacturers who are competing on grade formulation, regulatory certification, recycling capability, and application-specific value engineering.
At the heart of this competitive ecosystem sits Celanese Corporation, whose Fortron® PPS resin portfolio has long been associated with high thermal stability, chemical resistance, and consistent performance in automotive and industrial injection molding applications. Operating from Dallas, Texas, Celanese continues to reinforce its position through grade optimization, processing reliability, and deep integration into Tier-1 supply chains. Across the Atlantic, Solvay S.A. has built a formidable presence through its Ryton® PPS brand and Supreme series grades, targeting high-voltage electrical applications, high-flow engineering requirements, and increasingly, sustainability-certified production pathways. The company's ongoing pursuit of mass-balance certification and its footprint across Texas and Belgium underscore a dual focus on performance and compliance-driven market access.
The Asian manufacturing corridor continues to exert structural influence. Toray Industries, Inc. has systematically expanded its Torelina® PPS resin portfolio to serve high-performance automotive and electronics applications, recently completing a second production line expansion at its Gunsan plant in Korea to reinforce regional capacity resilience. DIC Corporation and Kureha Corporation have maintained steady positioning in industrial and automotive segments, with Kureha placing particular emphasis on high-temperature and flame-resistant grades that align with stringent safety specifications in electrical and transport equipment. Tosoh Corporation serves as a specialized supplier across electrical and high-performance engineering applications, while Polyplastics Co., Ltd. has carved a distinct niche through its DURAFIDE® PPS grades, recently advancing into mechanically recycled-content formulations that respond directly to corporate sustainability mandates and circular-economy procurement standards. Rounding out the competitive matrix, Ensinger GmbH provides compounded PPS materials and precision-machining-ready resin solutions for industrial components, reinforcing Europe's role as a hub for specialized, high-value-added formulations.
Recent operational moves by key players confirm that the competitive landscape is actively recalibration. In May 2025, Syensqo announced a capital investment to expand PPS compounding capability at its Augusta, Georgia manufacturing site for Ryton-branded compounds, signaling a strategic push into North American downstream processing and localized supply chain responsiveness. Later in the year, Toray Industries completed the expansion of its second PPS production line at its Gunsan facility in Korea, reinforcing its capacity footprint and regional supply agility. In January 2026, Polyplastics Co., Ltd. launched two new DURAFIDE® PPS grades made from mechanically recycled content, a move that directly intersects with the growing procurement preference for sustainable resin inputs and circular material sourcing.
These developments are not isolated corporate announcements. They are indicators of structural realignment: capacity is being deliberately placed closer to key demand clusters, compounding and formulation capabilities are being expanded to capture higher-margin downstream value, and sustainability certification is transitioning from a compliance checkbox to a competitive differentiator. Understanding who is expanding, where, and why is essential for any organization seeking to optimize long-term sourcing strategy or position new products in high-growth application corridors.
Structural Dynamics Shaping the 2026 Horizon
The trajectory of the PPS resin market is being shaped by an interlocking set of technical, economic, and regulatory forces. At the raw material level, PPS production relies on the polymerization of dichlorobenzene and sodium sulfide as foundational feedstocks. Pricing and supply continuity for these commodity inputs remain highly sensitive to broader chemical market dynamics, and procurement teams must track these dependencies closely as they translate into resin cost structures and margin variability. In the third quarter of 2025, North American PPS prices rose to approximately USD 11,250 per metric ton, driven by intensified demand pull from the automotive and electronics sectors. This price behavior is not an isolated event; it reflects how demand acceleration in high-value applications can rapidly transmit through regional pricing structures, particularly when capacity expansion timelines lag behind consumption growth.
Regulatory and sustainability frameworks are equally influential. The attainment of ISCC PLUS 2 mass-balance certification for PPS production facilities in Texas and Belgium demonstrates how major producers are institutionalizing sustainable manufacturing pathways. As downstream OEMs and Tier-1 suppliers face mounting corporate sustainability targets and customer-facing carbon disclosure requirements, certified sustainable resin inputs are evolving from a niche preference to a qualifying factor in procurement evaluations. The strategic implication is clear: organizations that embed sustainability compliance into sourcing criteria will not only mitigate reputational and regulatory risk but will also gain preferential access to supply from producers who have already navigated the certification pathway.
On the technology and application side, continuous advancements in resin formulation are expanding the boundaries of where PPS can be deployed. Enhancements in thermal stability, chemical resistance, flow characteristics, and flame-retardant performance are enabling deeper penetration into demanding engineering applications where traditional thermoplastics and lower-performance engineering resins fall short. Simultaneously, the rise of recycled-content grades is creating new procurement dynamics. As mechanically recycled PPS formulations gain commercial traction, buyers are confronted with a more complex sourcing landscape that requires evaluation of material consistency, processing compatibility, certification alignment, and total cost of ownership rather than simple price-per-kilogram comparisons.
Strategic Positioning for 2026 and the Road to 2032
As the market moves from baseline recovery and consolidation into an accelerated growth phase, several strategic imperatives are coming into sharp focus for organizations operating in or adjacent to the PPS value chain. First, supply chain resilience must be treated as a structural capability rather than a short-term risk mitigation exercise. The concentration of capacity among a small group of large-scale producers, combined with regional price sensitivity and feedstock dependency, means that diversification of sourcing relationships, forward contracting strategies, and awareness of capacity expansion timelines are essential to maintaining continuity and cost predictability.
Second, application-specific demand mapping should inform both procurement and product development roadmaps. As automotive electrification, high-performance electronics, aerospace component requirements, and industrial precision-machining demand continue to shape consumption patterns, organizations that understand which end-use verticals are accelerating, which are stabilizing, and which are emerging will be better positioned to align capacity acquisition, inventory planning, and new product introductions.
Third, sustainability is becoming a procurement qualifier, not an aspirational add-on. Certified sustainable production pathways, recycled-content grades, and compliance with evolving regulatory expectations are increasingly influencing supplier selection. Organizations that proactively embed these criteria into supplier qualification, technical evaluation, and contract negotiation will reduce exposure to future compliance shocks while strengthening alignment with downstream customer expectations.
Finally, competitive intelligence must be continuous. The recent capacity expansions, grade launches, and certification milestones among leading producers confirm that the market is structurally dynamic. Tracking these moves, understanding the geographic and application logic behind them, and anticipating their downstream impact on pricing, availability, and formulation options will be a decisive factor in maintaining competitive advantage over the next planning cycle and beyond.
PPS Resin Market
Closing the Intelligence Gap
Headline growth rates and aggregate market sizes provide orientation, but they rarely provide direction. Real strategic advantage comes from understanding the mechanics beneath the numbers: how capacity is being reallocated, how grade differentiation is reshaping application eligibility, how sustainability certification is filtering supplier pools, and how pricing behavior reflects demand shifts in high-value end-use sectors. Our full PPS Resin Market Research Report is designed to close that intelligence gap. It translates historical trajectory, forward-looking modeling, competitive mapping, and structural dynamics into a decision-ready framework that procurement, strategy, and engineering teams can apply directly to sourcing plans, capacity negotiations, product roadmaps, and market-entry evaluations.
For organizations preparing for the 2026 decision cycle, the window to build a comprehensive, evidence-backed view of the PPS resin market is open now. The full report provides the granular segmentation detail, regional and application-level consumption trajectories, pricing sensitivity modeling, competitive positioning analysis, and scenario-weighted forecasts needed to move from reactive monitoring to proactive strategy. We invite you to access the complete study on our website, where you will find the full data architecture, detailed segmentation contours, and executive-ready synthesis required to navigate the next phase of market expansion with confidence.
For detailed analysis of this topic, please visit the official page: PPS Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


