



PW Consulting: Tall Oil Derivative Market Hits $2,650 Million in 2025, Poised to Reach $3,439 Million by 2032

Strategic Intel for 2026: Navigating Growth and Volatility in the Crude Tall Oil Derivative Market
As industrial demand shifts toward biobased inputs and regulatory frameworks tighten around renewable feedstocks, the crude tall oil derivative market stands at a critical inflection point. For executives, procurement leaders, and strategy teams planning the 2026 cycle, isolated data points will not suffice. Decision-making requires a clear line of sight into structural supply dynamics, competitive realignments, and the pricing mechanisms that will shape margins across the value chain. Our latest research on the Crude Tall Oil Derivative Market delivers that visibility.
Recent headlines have touched on price actions and asset transactions across the sector, but the underlying forces are far more structural. Trade policy adjustments, biofuel mandates, and biomass regulation are simultaneously reshaping feedstock availability and end-use demand. In this environment, a disciplined, evidence-based view of the market is no longer optional. It is the foundation for capital allocation, product portfolio design, and risk management.
Why 2026 Demands a Deeper Read on Tall Oil Derivatives
The market has expanded steadily over the past half-decade, and the trajectory through the end of the decade points to continued, albeit measured, growth. From a base year perspective anchored in 2025, the industry has moved from a 2020 starting point near 2.18 billion USD to an estimated 2.65 billion USD in 2025. Looking ahead, the forecast period from 2026 through 2032 signals a steady climb, with the market projected to exceed 3.4 billion USD by 2032. This path implies a compound annual growth rate of approximately 3.88 percent, a pace that reflects durable demand from adhesives, coatings, and surfactant applications alongside emerging pull from renewable fuel streams.
Crude Tall Oil Derivative Market
Growth at this pace is not uniform. It is being filtered through a set of intersecting pressures: tightening pulp capacity in certain North American corridors due to lumber tariff effects, supply-side yield improvements at mills in Europe driven by biomass restriction rules, and demand-side substitution dynamics created by duties on alternative feedstocks. For firms that depend on tall oil fatty acids, rosin derivatives, or tall oil pitch, these forces translate into a nonlinear pricing and availability environment. The strategic question for 2026 is not whether the market is growing, but where margins will crystallize and how to secure position before structural advantages harden.
Crude Tall Oil (CTO) Market
Our analysis is built to answer that question. Rather than offering surface-level trend statements, the report maps the causal chain from regulation to mill yield, from trade policy to regional supply balance, and from competitive transactions to pricing power. This approach gives leaders a practical framework for scenario planning and for identifying where to invest, where to hedge, and where to reposition.
What the Report Delivers: An Executable View of the Value Chain
The research is designed around operational usefulness. It combines macro market sizing with a structured examination of the segments that matter most to commercial decisions, while preserving enough granularity to support product-level and application-level planning. The report content is organized to help teams move quickly from insight to action.
- Market sizing and forward outlook anchored to a 2025 base year, with a forecast window spanning 2026 through 2032, enabling multi-year budgeting, capacity planning, and long-cycle procurement strategy.
- Product-level decomposition across fatty acids, rosin derivatives, and tall oil pitch, with context on how each stream is positioned relative to demand from industrial formulations and biobased applications.
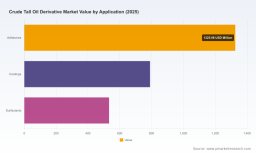
- Application-driven insights covering adhesives, coatings, and surfactants, including the demand drivers, formulation shifts, and substitution dynamics that are reshaping consumption patterns.
- Regional framing that situates North American, European, Asian Pacific, Latin American, and Middle East and Africa markets within the broader supply and demand architecture, with attention to trade flows, feedstock availability, and regulatory exposure.
- Competitive landscape assessment that profiles the leading producers, refiners, and biorefiners shaping price formation, capacity additions, and market access.
- Event-driven updates that connect recent pricing actions and asset transactions to the broader strategic narrative, helping readers interpret what is signal and what is noise.
Each section is written for application, not just observation. The goal is to give strategy, finance, and commercial teams a shared vocabulary and a consistent evidence base for cross-functional decisions. By integrating market structure with company-level developments and regulatory context, the report supports decisions about vendor selection, long-term supply agreements, product mix adjustments, and regional prioritization.
Competitive Landscape: Consolidation, Capacity, and Pricing Power
The crude tall oil derivative market is characterized by a concentrated set of active producers and refiners, with a meaningful share of revenue held by a relatively small group of companies. This concentration matters because it shapes how quickly pricing adjusts, how capacity constraints propagate, and how new supply enters the system. The leading participants span biorefining, distillation, and downstream formulation, with strong positions in fatty acids and a growing presence in renewable fuel pathways.
Several firms define the strategic center of gravity. In the United States, Kraton Corporation operates a biorefinery focused on converting crude tall oil into tall oil fatty acids and other pine-based derivatives, and it has a visible footprint as a supplier of biobased specialty chemicals and resins. Eastman Chemical Company also contributes to the market through refining and supply of tall oil fatty acids and pine chemicals for coatings, adhesives, and industrial applications. In Europe, UPM-Kymmene Oyj and Stora Enso Oyj both play foundational roles: UPM produces crude tall oil at its Lappeenranta biorefinery for conversion into renewable fuels and tall oil fatty acids, while Stora Enso extracts and supplies crude tall oil from Nordic softwood kraft pulping as a renewable feedstock for pine-based derivatives. Forchem Oyj and Fintoil Oy round out the Nordic processing landscape, with Forchem specializing in distillation and processing of crude tall oil into tall oil fatty acids and other biobased derivatives, and Fintoil operating a large-capacity biorefinery producing tall oil fatty acids and distilled tall oils for industrial use.
Outside this core cluster, the market includes additional regional specialists and integrated players. Ilim Group JSC produces and supplies crude tall oil from its Russian mills and refines it into tall oil fatty acids, adding capacity and supply reach in its operating footprint. Harima Chemicals Group, Inc. distills crude tall oil into tall oil fatty acids, rosin, and other pine-based derivatives, serving paper chemicals and electronics end markets in Japan. SunPine AB extends the value chain into raw tall diesel and other crude tall oil-derived bio-based products, linking the feedstock to renewable diesel and heating oil applications. Together, these participants illustrate the breadth of the market and the variety of routes through which crude tall oil is converted into commercial value.
Recent activity underscores how dynamic this landscape has become. Over the past year, there have been notable pricing actions and asset transactions that signal both supply tightening and portfolio realignment. In late 2025, Kraton Corporation announced a general price increase of 10 percent or higher on tall oil fatty acid products in the EMEA region. That move was followed in early 2026 by a broader global price increase of 10 to 20 percent across its crude tall oil refinery and derivatives portfolio. These adjustments reflect the interplay of demand strength, feedstock conditions, and the pricing latitude that comes with a concentrated supply base.
On the asset side, Ingevity Corporation moved to reshape its portfolio. In September 2025, it signed an agreement to sell its North Charleston crude tall oil refinery and the majority of its industrial specialties product line. The transaction was completed in January 2026, with the assets transferring to Mainstream Pine Products, LLC. This type of transaction matters because it repositions capacity and changes the competitive map, particularly in regions where refinery access and logistical reach influence commercial outcomes. For buyers and competitors alike, such moves alter availability, potential supply routes, and the negotiation dynamics that govern long-term contracts.
These developments are not isolated events. They are symptoms of a market in which access to consistent feedstock, processing capacity, and downstream market access can create durable advantages. Understanding who holds those advantages, and how they are changing, is essential for any firm that depends on tall oil derivatives as a raw material or a growth platform.
Market Dynamics: Regulation, Trade, and Feedstock Realignments
The backdrop for 2026 is defined by regulatory and trade forces that are simultaneously shaping demand and constraining or expanding supply. These dynamics do not operate in isolation; they interact, and their combined effect is what leaders need to anticipate.
On the demand side, the U.S. policy environment has introduced a notable pull factor. An EPA proposal to increase the biodiesel mandate by 56 percent for 2026 would accelerate crude tall oil consumption in U.S. biofuel blends. If implemented, this type of mandate expands the addressable market for tall oil-derived inputs and increases competition for available feedstock. At the same time, trade policy is influencing where demand migrates. EU anti-dumping duties on Chinese biodiesel, set in a range of 23.7 to 36.4 percent, have increased demand for crude tall oil as an alternative feedstock. This substitution effect redirects flows and can raise utilization at producers positioned to serve European buyers.
On the supply side, the picture is equally active. Lumber tariffs of 25 percent applied in U.S.-Canada and U.S.-Mexico trade contexts have reduced North American pulp production capacity in certain corridors, tightening crude tall oil supply where pulp operations are a primary source of the feedstock. This tightening does not simply raise prices; it changes the calculus for long-term supply agreements and for product planning in regions that depend on North American volumes. In parallel, EU RED III biomass restrictions have forced a reduction in pulp industry biomass burning, which has increased crude tall oil yields by an estimated 8 to 12 percent at mills. This yield effect partially offsets supply pressure by improving the amount of tall oil recovered per unit of pulp output, but its benefits are uneven across regions and operating models.
The strategic implication is that 2026 is a year of dual movement: demand is being amplified by biofuel policy and trade-driven substitution, while supply is being reshaped by tariffs and yield changes that are themselves policy-driven. Navigating this environment requires more than a snapshot of current pricing. It requires a forward-looking view of how mandates, duties, and biomass rules will interact with mill economics, refinery throughput, and downstream formulation needs. The report provides that view by connecting each dynamic to likely commercial outcomes and by identifying the regions and product streams where these forces will be felt first and most intensely.
Using This Research to Frame 2026 Decisions
For executives and analysts, the value of the report lies in its ability to convert complex, moving parts into a coherent decision framework. The research supports several practical uses. It can inform sourcing strategy by clarifying where feedstock availability is likely to tighten and where yield improvements or alternative supply routes may provide relief. It can guide portfolio planning by highlighting how demand is shifting across adhesives, coatings, and surfactants, and by indicating where renewable fuel pathways may create additional pull. It can support pricing strategy by contextualizing recent increases within the broader competitive and regulatory environment, helping teams distinguish structural pricing power from temporary adjustments. It can also inform capital and M&A thinking by mapping where capacity is being repositioned and where consolidation may continue.
Importantly, the report is structured to preserve analytical precision without overwhelming the reader with a wall of figures. High-level market size, growth trajectory, and concentration metrics are presented to frame the landscape, while the deeper segmentation detail is reserved for the full study. This design reflects how senior teams actually work: they need the strategic picture first, then the granular data to support specific plans. The complete research delivers that depth, including regional and application-level breakdowns, product-level context, and company profiles that together form a comprehensive intelligence package.
What the Full Study Unlocks
The summary view presented here establishes the strategic terrain, but the complete Crude Tall Oil Derivative Market research goes further. It provides the segmentation detail needed to translate market direction into product and regional plans, the competitive context needed to interpret pricing and capacity moves, and the dynamic analysis needed to anticipate the next shift in policy or trade. For teams preparing for 2026, that combination is what turns uncertainty into a manageable set of choices.
If your organization is evaluating supply commitments, product positioning, regional exposure, or investment in biobased chemical value chains, the full report offers the structured evidence required to move with confidence. The market is expanding, but expansion is being routed through a narrow set of competitive and regulatory choke points. Understanding those choke points is the difference between reacting to change and shaping your position ahead of it.
To access the complete market sizing, segmentation analysis, competitive profiles, and dynamic scenario guidance, explore the full research on the source page. The detailed intelligence there is designed to support concrete 2026 planning across commercial, procurement, and strategy functions.
For detailed analysis of this topic, please visit the official page: Crude Tall Oil Derivative Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


