



PW Consulting HDH Titanium Powder Report: Market Hits $524.5M in 2025, Projected 7.2% CAGR to 2032

Strategic Imperatives in the HDH Titanium Powder Market: Navigating Growth and Supply Chain Complexity Through 2032
The global landscape for hydrogenated-dehydrogenated (HDH) titanium powder is undergoing a profound transformation, driven by the simultaneous demands of aerospace defense, medical implant innovation, and the rapid adoption of metal additive manufacturing. For senior leadership and strategic planners, the period between 2026 and 2032 represents a critical window where capacity allocation, supply chain resilience, and purity standardization will dictate market share and profitability. PW Consulting has released a comprehensive market intelligence study designed to equip stakeholders with the actionable foresight required to navigate this high-velocity environment. This analysis serves as an executive overview of the strategic value embedded within our latest HDH Titanium Powder Market research, highlighting the macro-economic trajectories and competitive shifts that will shape decision-making in the coming years.
Macro-Economic Trajectory and Demand Forecasting
Our longitudinal analysis covers historical performance from 2020 through the base year of 2025, with an extensive forecast period extending to 2032. This 13-year view allows us to isolate structural growth trends from short-term volatility. The market demonstrated robust expansion throughout the historical review period, recovering from global logistical disruptions and accelerating as industrial production normalized. By 2025, the total market revenue had firmly established a trajectory that suggests sustained upward momentum.
Looking forward, the forecast model projects a Compound Annual Growth Rate (CAGR) of 7.2 percent across the valuation period. This growth rate is not merely a numerical projection but a reflection of widening application scopes and the substitution of traditional wrought materials in specific high-value sectors. Revenue is expected to climb from approximately 556 million USD in 2026 to over 853 million USD by 2032. For procurement directors and investment committees, this trajectory implies that locking in supply agreements early or investing in capacity expansion before the peak of the growth curve could yield significant competitive advantages. The scale of this expansion suggests that HDH titanium powder is transitioning from a niche material to a strategic commodity essential for advanced manufacturing resilience.
HDH Titanium Powder Market
Segmentation Dynamics and Application Diversification
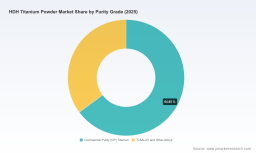
The demand landscape is fragmented across multiple purity grades and application verticals, each with distinct technical requirements and pricing sensitivities. The market is primarily divided between Commercial Purity (CP) Titanium and Ti-6Al-4V and other alloy grades. While CP titanium continues to hold a substantial share due to its utility in chemical processing and general industrial applications, the alloy segment is witnessing intensified interest from high-performance sectors where mechanical strength and corrosion resistance are paramount.
On the application front, the divergence in usage patterns highlights the versatility of the HDH process. Powder Metallurgy Components remain a traditional stronghold, leveraging the cost-effectiveness of irregular particle shapes. However, Metal Injection Molding (MIM) represents a high-growth vector, driven by the need for complex geometries in medical and consumer goods that traditional machining cannot economically achieve. Industrial additives and chemical applications provide a stable baseline demand, while Surface Coating and Thermal Spray applications offer specialized opportunities for wear resistance and component extension.
It is crucial for strategists to understand that these segments do not grow in isolation. Cross-segment competition for high-purity supplies is intensifying. For instance, the medical sector's requirement for low-oxygen and low-impurity profiles often competes directly with aerospace specifications. Our report details the specific volume flows and value drivers within each segment without exposing the proprietary granularity that would compromise client confidentiality, providing instead the relative weight and growth potential of each vertical to inform portfolio strategy.
Competitive Landscape and Corporate Consolidation
The industry structure is characterized by a moderate concentration, with the top three players controlling approximately 42.5 percent of the market and the top five commanding roughly 58.3 percent. This concentration indicates that while there is room for specialized entrants, scale and integrated supply chains remain powerful moats. The competitive field is globally distributed, with significant hubs in Asia Pacific, North America, and Europe, though Asia dominates in terms of total market revenue contribution.
Key Strategic Players and Operational Focus
Several key enterprises define the current competitive boundaries, each employing distinct strategies to secure market position:
Titanium Powder Market
- Toho Titanium Co., Ltd. and OSAKA Titanium Technologies Co., Ltd. represent the Japanese high-quality heritage, focusing on low impurity levels suitable for sputtering targets, getters, and high-grade powder metallurgy. Toho Titanium's recent corporate integration with JX Advanced Metals Corporation, effective June 2026 following a share exchange agreement, signals a move toward consolidated resource management and potentially expanded R&D capabilities under a larger corporate umbrella.
- Kymera International and ATI Inc. anchor the North American supply chain with a focus on customizable particle size distributions down to 45 microns. ATI Inc.'s expanded long-term agreement with Boeing in July 2025 reinforces the critical link between powder suppliers and major aerospace primes, ensuring steady demand for high-performance grades.
- Chinese manufacturers, including Lasting Titanium Industry Co., Ltd., AEM Metal, Baoji Titanium Industry Co., Ltd., and MTCO, form a significant production bloc. Lasting Titanium, for example, has historically accounted for a vast majority of China's titanium powder exports, leveraging proprietary hydride-dehydride processes to serve global aerospace and medical markets. Their ability to offer wide PSD options and competitive pricing pressures margins across the global supply chain.
- VSMPO-AVISMA Corporation and Höganäs AB round out the global presence, with VSMPO supplying aerospace-grade powders compliant with international standards and Höganäs offering broad application support for additive manufacturing and coatings.
Recent certification updates, such as North Titanium Industry Co., Ltd.'s ISO Quality Management System achievement in January 2025 for high-purity HDH powder, underscore the industry-wide shift toward rigorous quality assurance as a differentiator. Understanding the specific capacity constraints, geographical footprints, and strategic partnerships of these players is essential for supply chain risk assessment.
Supply Chain Vulnerabilities and Regulatory Pressures
Beyond the pure market dynamics, external factors exert substantial pressure on pricing and availability. The HDH production process relies heavily on titanium sponge feedstock, which is converted via hydrogenation to embrittle, crushed, and subsequently dehydrogenated. This technical pathway enables the production of low-cost irregular powders suitable for powder metallurgy and thermal spraying, but it also ties the powder market directly to the volatility of the sponge market.
Geopolitics and Raw Material Security
A critical strategic consideration is the geography of raw material origin. China controls approximately 65 percent of global titanium sponge capacity. This dominance creates inherent supply chain vulnerabilities for HDH powder production, particularly for North American and European manufacturers reliant on imported feedstock. The potential for export controls or tariffs on titanium materials introduces a risk premium that must be factored into long-term budgeting and sourcing strategies.
Furthermore, national security concerns regarding titanium supply have been highlighted in regulatory contexts. The U.S. Department of Commerce Section 232 investigation noted that reliance on foreign titanium sponge imports threatens national security, especially given the lack of domestic commercial production since 2020. These geopolitical undercurrents suggest that future policy interventions could reshape trade flows, incentivizing domestic capacity development or friend-shoring arrangements.
Cost Structures and Regulatory Compliance
Pricing dynamics also play a pivotal role in market adoption. HDH titanium powders typically offer a more cost-competitive alternative compared to gas-atomized spherical powders, with price points varying based on grade, purity, and particle size. This cost advantage drives adoption in powder metallurgy and thermal spray applications where spherical morphology is not strictly required. However, as specifications tighten for medical and aerospace uses, the cost differential may narrow.
Regulatory compliance adds another layer of complexity. For medical implants, HDH titanium powder must comply with standards such as ISO 23301 for sintered titanium materials and products for surgical implants, alongside ASTM specifications for powder metallurgy shapes. Adherence to these standards is not optional but a prerequisite for market entry in high-value segments. Our report analyzes how compliance costs are distributed across the value chain and which regions are most susceptible to regulatory shifts.
Strategic Value of the 2026 Analysis
In an environment defined by volatility and rapid technological iteration, generic market data is insufficient for strategic planning. The PW Consulting HDH Titanium Powder Market report provides the depth required to make informed decisions regarding capacity investment, supplier qualification, and market entry. We have synthesized historical performance, forward-looking forecasts, and competitive intelligence into a cohesive narrative that addresses the specific pain points of procurement, strategy, and R&D leadership.
The analysis avoids superficial aggregation, instead offering a nuanced view of how segmentation splits interact with regional dynamics and regulatory frameworks. We examine how the concentration of market power among key players influences negotiation leverage and how recent corporate developments, such as the integration of major Japanese producers or contract expansions with aerospace primes, signal shifts in supply stability.
Furthermore, the report contextualizes the 7.2 percent CAGR not just as a growth statistic but as a series of milestones that require proactive management. Stakeholders will gain insights into when specific application segments are projected to accelerate, allowing for targeted marketing and production planning. The interplay between raw material costs, geopolitical risks, and technical standards is mapped to help organizations build resilient supply chains that can withstand external shocks.
Conclusion: Positioning for the Next Cycle
The HDH titanium powder market is poised for significant evolution over the next decade. The convergence of aerospace demand, medical innovation, and the cost efficiencies of powder metallurgy creates a fertile ground for growth, but this growth is contingent on navigating complex supply chains and regulatory landscapes. The 2026 baseline represents a pivotal moment where early movers can secure advantages in sourcing and technology partnerships.
PW Consulting's comprehensive study is designed to be the cornerstone of this strategic planning process. By revealing the underlying currents of market concentration, regional dependencies, and application-specific growth vectors, we empower organizations to move beyond reactive decision-making. The full intelligence contained within the report provides the granular detail necessary to refine forecasts and validate assumptions against the latest industry developments.
For leaders committed to securing a competitive position in the titanium value chain, the time to act on these insights is now. We invite you to explore the full depth of our findings to understand how the 2026-2032 trajectory aligns with your specific organizational goals and risk tolerance. The complete market intelligence is available through our secure release portal.
For detailed analysis of this topic, please visit the official page: HDH Titanium Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


