



RFI Shielded Glasses Market 2026: Why 7.82% CAGR and Healthcare Demand Reshape Growth

Strategic Trends and Commercial Opportunities in the RFI Shielded Glasses Market: A 2032 Outlook
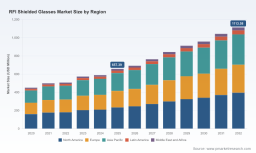
The RFI shielded glasses market has matured into a specialized yet strategically vital segment within the broader electromagnetic compatibility (EMC) and protective infrastructure industry. Over the past five years, the sector has transitioned from niche compliance-driven production to value-added differentiation, driven by tighter electromagnetic standards, expanding imaging and test environments, and a growing recognition that optical clarity cannot be sacrificed for shielding performance. Historical trajectory through the early 2020s established a consistent upward path, with revenue climbing steadily as medical facilities, defense contractors, and electronic testing laboratories upgraded aging shielding infrastructure. The market reached a valuation of approximately $657.39 million in 2025, reflecting sustained investment in controlled electromagnetic environments across critical sectors. Looking ahead, the compound annual growth rate is projected at 7.82 percent, positioning the market to surpass $1.1 billion by 2032.
PW Consulting Chemical & Energy Research Center
This expansion is not uniform. Growth concentrates in applications where visibility, patient or operator safety, and electromagnetic containment intersect, creating structural demand rather than cyclical fluctuations. The market remains moderately consolidated, with a handful of established players capturing a significant share of volume, while regional distribution reflects divergent procurement cycles, regulatory maturity, and industrial base readiness. For decision-makers, this landscape signals both stability and friction: predictable baseline demand exists, but capturing incremental growth requires navigating material constraints, performance trade-offs, and shifting procurement expectations.
Three structural challenges currently define the market's inflection points. First, optical transparency and shielding attenuation remain in persistent tension. Increasing shielding effectiveness across broadband frequencies often requires thicker conductive layers or denser mesh architectures, which can compromise light transmission and introduce visual distortion. Second, supply chain volatility for raw materials and precision coating processes has tightened margins and extended lead times. Float glass substrates, conductive inks, sputtering targets, and specialized wire alloys face price fluctuations and geopolitical sourcing constraints that ripple through manufacturing schedules. Third, certification and compliance complexity continues to raise the barrier for new entrants and mid-tier manufacturers. Medical and defense applications demand reproducible testing, clean room production standards, and documented compatibility with equipment-level standards, which slows product commercialization and elevates development costs. These challenges are not insurmountable, but they reward operators with process discipline, material partnerships, and application-specific engineering capabilities.
Key Drivers Shaping Market Trajectory
Several interdependent forces are accelerating demand and reshaping product expectations across the RFI shielded glasses market. Understanding these drivers clarifies where investment, capacity expansion, and differentiation are most likely to generate durable advantage.
Technological Innovation and Performance Optimization
The most consequential driver is the pursuit of higher shielding effectiveness without degrading optical performance. Conductive film laminates, ultra-fine metal mesh architectures, and improved indium tin oxide coating processes have progressively expanded the performance envelope. Manufacturers are increasingly targeting surface resistance in the sub-ohm to low-ohm range while maintaining light transmission above seventy percent, with some solutions exceeding ninety percent in optimized configurations. This trajectory matters because end-users no longer view shielded glass as a compromise component. Instead, they expect medical visibility standards, display clarity for electronic test setups, and situational awareness in defense enclosures to remain uncompromised while electromagnetic interference is contained.
Worldwide Anti-Interference Shielding Material Market
Recent product development signals reflect this direction. Suppliers are refining micro-replicated conductive grids and woven wire mesh variants that reduce visual artifacts while preserving broadband attenuation. Others are advancing scratch resistance, chemical durability, and clean room compatibility to meet hospital and laboratory environment requirements. The cumulative effect is a shift from generic shielding solutions toward application-tuned optics, where transmission, attenuation bandwidth, mechanical robustness, and durability are engineered together rather than treated as independent specifications.
Regulatory and Standards-Driven Demand
Compliance frameworks continue to shape procurement behavior, particularly in medical and defense settings. Standards addressing electromagnetic compatibility for medical electrical equipment, including requirements for imaging environments such as MRI rooms, create recurring demand for shielding components that must be documented, tested, and installed with predictable performance. In practice, this means shielded glass is not merely a material purchase but a compliance enabler integrated into broader facility and equipment qualification processes.
Regulatory expectations also influence product design choices. RoHS-compatible materials, systematic optical quality control, and clean room manufacturing traceability are increasingly referenced in procurement specifications. For high-stakes environments, these requirements reduce acceptable supplier pools and increase switching costs, reinforcing the value of established compliance documentation and repeatable production processes. The standards environment does not just constrain the market; it filters it, favoring operators who can evidence consistent performance and transparent process control.
Demand-Side Shifts in Critical Infrastructure and Testing
Demand is being reinforced by the expansion and modernization of controlled electromagnetic environments. Medical imaging facilities continue to require visibility and protection in shielded enclosures, where openings, observation windows, and display interfaces must manage stray electromagnetic fields without obstructing clinical workflows. Defense and aerospace programs similarly depend on transparent shielding for enclosures, sensor integration, and sensitive electronics testing, particularly as systems grow more complex and frequency usage intensifies.
Electronic test laboratories represent another structural driver. As device density, wireless functionality, and sensitivity to external interference increase, laboratory environments must maintain repeatable measurement conditions. Shielded windows and display interfaces contribute to isolation without eliminating operator visibility or instrument interaction. This combination of stricter measurement reliability and broader deployment of sensitive electronics sustains demand beyond incremental replacement cycles.
Supply Chain and Cost Structure Evolution
Cost dynamics are increasingly influenced by material availability, coating process efficiency, and customization levels. Float glass remains the dominant substrate, but the value creation occurs in coating uniformity, mesh integration, lamination quality, and finishing tolerances. Manufacturers that can stabilize coating yield, reduce scrap rates, and standardize frame or enclosure integration gain meaningful cost advantages, especially when customization remains a competitive necessity. At the same time, custom sizes, special shapes, and application-specific frame options can create both premium pricing opportunities and operational complexity.
This cost structure incentivizes a strategic balance between standardization and specialization. Operators that over-index on bespoke production may face margin pressure and delivery risk, while those that over-standardize may lose specifications-driven opportunities in medical and defense procurements. The more sustainable path involves modular product architectures, repeatable coating and lamination processes, and selective customization where specifications truly justify the cost.
Competitive Landscape and Leadership Positioning
The competitive environment is characterized by a mix of established shielding specialists, materials-focused manufacturers, and application-oriented integrators. Market concentration is notable, with a core group of companies accounting for a substantial share of revenue, though fragmentation persists at the regional and application-specific level. Leadership in this market is less about scale alone and more about performance consistency, certification readiness, and the ability to match optical and shielding requirements to procurement realities.
Differentiation Through Material and Application Expertise
Leading participants distinguish themselves through clearly defined technical value propositions. Some competitors emphasize high transparency combined with broad frequency coverage, positioning their shielded glass for environments where visibility is paramount, such as medical observation windows and display interfaces. Others focus on metal mesh or ITO-based architectures that deliver strong attenuation while preserving usable light transmission across glass or polycarbonate substrates. A further group leans into mechanical durability and customization, offering laminated float glass, scratch and chemical resistance, and tailored shapes for industrial, medical, or defense installations.
These distinctions matter because procurement decisions in this market are specification-intensive. Buyers often evaluate light transmission, shielding bandwidth, surface resistance ranges, substrate type, and compatibility with enclosure or framing systems. Suppliers that can articulate performance across these dimensions, and back claims with reproducible manufacturing and testing, gain a clearer path to qualification. In contrast, generalist positioning tends to weaken in environments where compliance documentation and environmental durability are equally important as optical performance.
Strategic Positioning by Market Segment
Within the broader competitive field, several players have built reputation advantages aligned with specific application families. Medical-focused suppliers often emphasize compatibility with hospital and imaging environments, referencing standards-aligned design, clean room manufacturing, and the need to protect staff and equipment while maintaining visibility. Defense- and aerospace-oriented participants tend to highlight broadband performance, mechanical robustness, and integration into enclosures or sensitive electronic setups. Test and laboratory suppliers commonly prioritize optical clarity and repeatable shielding behavior for measurement environments. This segmentation is not absolute, but it reflects a practical reality: procurement cycles, testing expectations, and acceptance criteria differ enough that reputation and reference use cases influence shortlisting.
Geographically, the landscape reflects both maturity and growth potential. Established demand centers show deeper qualification pathways and longer replacement cycles, while emerging demand regions often combine infrastructure investment with cost sensitivity. Suppliers with strong regional service, documentation support, and adaptable product configurations tend to navigate these differences more effectively than those relying on one-size procurement models.
Market Evolution: Consolidation, Niches, and New Entries
The market is likely to see continued selective consolidation at the capability level rather than purely through M&A headlines. End-users increasingly favor suppliers who can provide consistent coating quality, shielding performance across target frequency ranges, and reliable delivery of customized dimensions. This dynamic rewards operators with integrated manufacturing and predictable process control. At the same time, niche specialists may thrive by dominating particular application requirements, such as optical-grade shielding for displays, high-transparency observation windows, or cost-optimized solutions for laboratory environments.
New entry opportunities exist, but they are conditional. The barrier is not only technical performance but also qualification burden, repeatability, and the ability to supply with consistent documentation. Entrants that can demonstrate differentiated material approaches, improved transmission-to-attenuation ratios, or streamlined integration with enclosure systems have plausible entry points. However, those entering without clear application focus or compliance readiness face a steep path to shortening procurement cycles and displacing incumbents with established reference use.
Competition is therefore shifting from pure price competition toward performance reliability, traceability, and application fit. Market participants that can balance standardized production efficiency with targeted customization are best positioned to defend margins while expanding into higher-value segments.
Future Trends and Commercial Implications (2026–2032)
Three trends are likely to define the market over the next several years. First, performance expectations will continue to tighten around the transparency-versus-shielding frontier. As imaging systems, electronic test benches, and enclosed defense systems become more sensitive, the tolerance for optical compromise will decrease. Suppliers that can deliver high transmission with effective attenuation across broader frequency ranges will capture preferential positioning, particularly in medical and high-end laboratory applications. This trend creates commercial opportunities for advanced coating processes, refined mesh architectures, and lamination techniques that preserve clarity while improving attenuation consistency.
Second, procurement will increasingly treat shielded glass as part of a system-level compliance and reliability strategy rather than an isolated component. Documentation, standards alignment, clean room production practices, and environmental durability will become stronger differentiators in bidding and qualification processes. Commercial advantage will accrue to manufacturers that can package product performance with reproducible quality control and clear application guidance. This also raises the value of trusted supplier relationships, since replacement windows, display interfaces, and enclosure openings often require long-cycle compatibility with installed infrastructure.
Worldwide Fibers and Electromagnetic Shielding Market
Third, supply and cost pressures will push the market toward smarter portfolio design. Expect greater emphasis on modular product families, reusable frame or enclosure integration approaches, and selective customization only where specifications justify it. Manufacturers that can standardize core coating and lamination processes while offering controlled variation in size, substrate, and finishing will be better equipped to manage margin and delivery risk. Over time, this may also encourage broader adoption of coated film laminate options in applications where glass is not strictly required, expanding the addressable solution set.
Risks and uncertainties remain. Raw material cost volatility, coating yield variability, and freight or sourcing disruptions can compress profitability and extend lead times. Regulatory expectations may become more prescriptive in certain regions or application areas, raising compliance burdens unevenly across suppliers. There is also the possibility of substitution pressure if alternative shielding approaches improve in transparency, cost, or ease of integration. These uncertainties do not undermine the growth trajectory, but they increase the importance of operational resilience and specification agility.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product architecture with specification reality. Build repeatable processes around coating uniformity, optical consistency, and mechanical durability, then reserve customization for applications where performance trade-offs are explicitly justified. Strengthen documentation and testing narratives that support medical, defense, and laboratory procurement requirements, since qualification speed often matters as much as nominal performance. Where possible, structure product families to balance standardization with selective variation in size, substrate, and frame compatibility so that cost and lead time remain controlled.
For investors, the commercial opportunity lies in operators with disciplined manufacturing, defensible compliance readiness, and clear positioning in high-value applications. Preference should lean toward companies that can demonstrate consistent transmission-to-attenuation performance, stable supply relationships, and evidence of repeat qualification in regulated environments. Growth potential is strongest where suppliers can expand beyond replacement demand into system-level shielding upgrades, enclosure integration, and specialized optical shielding for displays or test environments. Due diligence should examine process yield, customization cost exposure, and the ability to scale without eroding optical or shielding performance.
For procurement and engineering leaders, sourcing strategy should prioritize performance reproducibility and integration fit over headline specifications alone. Evaluate suppliers on optical clarity consistency, shielding bandwidth relevance to the operating environment, substrate durability, and the quality of compliance documentation. Where facility or equipment upgrades are planned, consider how shielded windows and display interfaces will interact with enclosure design, maintenance cycles, and future imaging or electronics requirements. Treating RFI shielded glass as a long-cycle system component rather than a commodity purchase reduces rework risk and improves lifecycle value.
Detailed segmentation data, competitive benchmarking, and region-specific procurement dynamics can materially sharpen these decisions. Access to comprehensive upstream, midstream, and downstream analysis helps identify which materials, applications, and geographies offer the most favorable risk-adjusted opportunity in the coming growth cycle.
For detailed analysis of this topic, please visit the official page: RFI Shielded Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


