



Single-Crystal Turbine Blade Market: Why 8.5% CAGR Reshapes Aviation Strategy

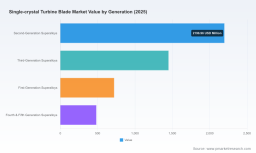
The Single-Crystal Turbine Blade Market: Strategic Crossroads in a High-Temperature Economy
Market Landscape and Defining Challenges
The global market for single-crystal turbine blades has entered a decisive phase of expansion, driven by the relentless pursuit of thermal efficiency in aerospace propulsion and power generation. From 2020 through 2025, the market grew from approximately $3.1 billion to $4.85 billion in annual revenue, reflecting a compound annual growth rate of 8.5 percent when projecting forward to 2032. This trajectory is not merely cyclical; it represents a structural shift in how engines and turbines are engineered under increasingly stringent performance and emissions constraints. By 2032, annual revenue is expected to approach $8.6 billion, underscoring the material's transition from a premium differentiator to a baseline engineering requirement across high-performance rotating machinery.
Yet this growth is unfolding within a landscape marked by acute supply-side friction and demand-side complexity. The production of single-crystal blades depends heavily on high-purity nickel, cobalt, and trace but critical elements such as rhenium. The global nickel-based superalloy sector, valued at roughly $16.8 billion in 2024, is navigating structural oversupply conditions in raw nickel, which has introduced volatile pricing dynamics for downstream alloy-makers and casting houses. Compounding this is the steep cost of rhenium-bearing formulations, where such alloys can push material expenditures upward by approximately 35 percent relative to conventional superalloys. These pressures are reshaping margin structures across the value chain.
A second defining challenge lies in the reconfiguration of procurement networks following trade policy shifts. In early 2025, the United States imposed tariffs on imported high-grade superalloys, prompting manufacturers and engine OEMs to rethink sourcing strategies. The resulting adjustments favor regional suppliers and vertically integrated partners, narrowing the pool of cost-competitive raw material access and accelerating consolidation among qualified casting suppliers. A third challenge is the widening capability gap between established aero-engine producers and emerging regional players seeking to localize high-temperature component manufacture. While directional solidification and single-crystal technologies now appear in more than 78 percent of modern gas turbines and new jet engines, the precision required in grain-boundary control, thermal barrier coating integration, and post-cast finishing means that scale alone does not guarantee competitiveness. Organizations that fail to align casting expertise with tight tolerances for internal cooling passages and surface treatments will find themselves excluded from the next wave of engine and turbine programs.
Core Drivers Reshaping the Market
Technology breakthroughs in single-crystal casting and thermal management are the most direct catalysts for market expansion. The ability of single-crystal nickel-based superalloys to sustain tensile strength above 900 MPa at 1,000°C has made them the dominant choice in roughly 85 percent of turbine blade applications. This performance envelope is no longer a constraint in theory; it is a design baseline. The real lever is manufacturing precision. Recent capability expansions have demonstrated that single-crystal and directionally solidified blades and vanes with complex internal hollow cooling passages can now be produced in facilities previously focused on equiaxed or standard investment casting. The successful establishment of such capability in India in mid-2024 marked the first instance of this technology being operationalized domestically for aero-engine and industrial gas turbine components, signaling that high-precision casting is diffusing beyond a narrow set of incumbent geographies.
Single Crystal Diamond Market
On the demand side, the structural pull from commercial aviation continues to outpace other segments. New jet engine architectures prioritize higher thrust-specific fuel consumption improvements, and single-crystal blade integration directly supports higher turbine inlet temperatures without compromising creep life. Military aviation adds a parallel demand stream where extreme operating envelopes and accelerated replacement cycles sustain steady offtake of advanced airfoils. Industrial gas turbines are also adopting high-temperature blade technologies at scale, particularly in the 10-to-40 MW range, where efficiency gains translate into tangible operational savings and lower emissions intensity. Across these applications, the overarching trend is clear: more than 78 percent of new engine and turbine builds now rely on directional solidification or single-crystal technologies, embedding the segment into long-term program pipelines.
Regulatory and policy dynamics are reshaping the operating environment as much as engineering requirements. Environmental mandates on aviation and power generation are pushing OEMs toward architectures that extract more work per unit of fuel, indirectly favoring components that withstand higher thermal loading. At the same time, early 2025 tariffs on imported high-grade superalloys have raised the cost of cross-border raw material flows. This has forced procurement teams to reassess supplier bases, with a noticeable tilt toward regional and vertically integrated partners. For manufacturers, the implication is that strategic sourcing is increasingly a function of jurisdiction, alloy certification, and process control rather than price alone.
Worldwide Gas Turbine Turbine Blades Market
Cost structure evolution ties these threads together. Material volatility is being addressed through alloy design choices, recycling of precious alloying elements, and tighter process yields in casting facilities. Where rhenium content increases costs materially, engineering teams are increasingly exploring optimized grain-boundary engineering and coating strategies to extract more life from lower-cost formulation windows. Simultaneously, post-cast value addition is becoming a competitive differentiator. A recent order secured for post-cast operations covering machining, grinding, brazing, vacuum heat treatment, thermal barrier coating, and powder vapour deposition on single-crystal ready-to-fit turbine blades illustrates how the market is moving from casting alone toward full-component readiness. This shift lengthens the value chain, improves engine integration timelines, and raises switching costs for engine OEMs that rely on end-to-end capability.
PW Consulting Chemical & Energy Research Center
Competitive Positioning and the Shape of the Market
The competitive field is anchored by a small group of firms that combine casting heritage, process control, and engine integration relationships. A market concentration metric shows that the top three participants account for roughly 58 percent of revenue, while the top five reach about 72 percent. This level of concentration reflects the high barriers associated with single-crystal growth processes, quality certification for flight-critical hardware, and long lead times for qualification. Within this landscape, strategic positioning diverges along several axes.
Howmet Aerospace has built a reputation around investment casting of single-crystal turbine airfoils using advanced techniques tailored for aero engines, emphasizing higher temperature capability and extended blade life through refined growth processes. Rolls-Royce operates an advanced blade casting facility in the UK for single-crystal blades in civil aerospace engines, leveraging in-house expertise in investment casting of nickel-based superalloys for jet engines. Pratt & Whitney, recognized as a pioneer in single-crystal turbine blade technology since the 1960s, produces blades for both commercial and military aero engines and is acknowledged for its historical mechanical engineering contributions. PCC Airfoils leads in complex investment castings including single-crystal blades and airfoils across aerospace and industrial gas turbine applications. GF Casting Solutions produces single-crystal blades via investment casting using alloys such as CMSX-4 for industrial gas turbines in the 10-to-40 MW range, while Doncasters manufactures investment cast turbine airfoils spanning equiaxed, directionally solidified, and single-crystal components in nickel and cobalt base superalloys for industrial gas turbines. On the emerging side, PTC Industries has developed single-crystal and directionally solidified casting technology for aero-engine and industrial gas turbine blades and vanes and has secured order activity for post-cast operations on single-crystal ready-to-fit turbine blades. TEI is advancing advanced manufacturing technologies for nickel-based superalloy single-crystal turbine blades under a dedicated project aimed at extreme operating conditions, and Qingdao O.B.T provides customized single-crystal turbine blades and components based on customer drawings for gas turbine applications.
The differentiation advantage among leaders is increasingly tied to process versatility and supply chain integration rather than casting volume alone. Incumbents that can combine grain-structure control with robust thermal barrier coating and post-cast finishing reduce time-to-integration for engine OEMs and improve qualification certainty. This matters because single-crystal components are not interchangeable; they must meet application-specific temperature, stress, and cooling-path requirements. Companies with strong in-house capability across multiple process steps are better positioned to absorb raw material volatility and tariff-related sourcing shifts without compromising delivery timelines.
Market structure is evolving through both consolidation and new entry. The concentrated top-tier cohort suggests a willingness to maintain scale and qualification advantages, while regional capability build-out is creating targeted opportunities for localized supply. Notably, the establishment of single-crystal and directionally solidified casting with complex internal hollow cooling passages in a new geography in 2024 illustrates that technology diffusion is occurring, but the presence of the capability does not automatically translate into program wins. Qualification, volume ramp, and engine OEM trust remain gating factors. As a result, the near-term trend is toward selective partnerships: large engine programs favor established suppliers with proven flight heritage, while industrial and regional engine programs provide incremental entry points for new players with demonstrated process control and cost discipline. The net effect is a market that is simultaneously concentrated and diversifying in application-specific niches.
Forward Outlook: Trends and Commercial Implications
Looking ahead three to five years, the most consequential trend is the deepening integration of single-crystal technology into the commercial mainstream, particularly as new engine family launches and industrial gas turbine upgrades extend the performance envelope. Because more than 78 percent of modern gas turbines and new jet engines already incorporate directional solidification or single-crystal technologies, the addressable base is no longer a niche; it is the core of high-temperature component demand. This creates a durable revenue base for capable suppliers, assuming raw material access and process yields remain stable.
A second trend is the material-cost optimization tug-of-war. With nickel oversupply creating pricing pressure on base metals and rhenium-containing formulations adding roughly 35 percent to material costs, suppliers and engine OEMs will increasingly co-engineer around alloy selection, recycling of critical elements, and coating and cooling-path efficiency. Expect incremental gains from grain-boundary engineering, improved yield in casting, and more selective use of high-cost alloying elements in non-critical regions of the blade. This trend rewards organizations that can balance thermal performance with cost-aware design.
A third trend is the geographic rebalancing of supply. Early 2025 tariffs on imported high-grade superalloys are likely to persist as a structural factor, nudging procurement toward regional and vertically integrated suppliers and encouraging localized casting and post-cast capabilities where demand is strong. This creates opportunity for suppliers that can localize high-value steps while preserving quality and certification standards. For buyers, the opportunity is to secure supply resilience and reduce tariff exposure; for manufacturers, the opportunity is to align capacity with regional program pipelines.
These trends carry clear commercial upside but also uncertainties. Trade and tariff policy can shift sourcing cost structures rapidly; raw material pricing for superalloys can remain volatile; and qualification timelines for new blade designs can delay revenue realization. Still, the direction is clear: single-crystal blade demand is anchored by engine architectures that require higher temperature capability, and the value chain is moving toward integrated, certified, region-aware supply.
Actionable Guidance for Decision-Makers
For manufacturers and casting suppliers, the priority is to extend capability beyond casting volume into post-cast readiness and alloy-process optimization. Investments in thermal barrier coating, vacuum heat treatment, and precision finishing improve time-to-integration for engine OEMs and reduce exposure to raw material cost swings through better yields and more selective alloying. Where possible, regional sourcing alignment can mitigate tariff-driven cost escalation and strengthen long-term supply relationships.
For investors, the market rewards firms with proven single-crystal process control, diversified application exposure across aviation and industrial turbines, and vertically aligned supply strategies. Concentration among the top participants suggests margins for leaders, but value creation will increasingly accrue to companies that can demonstrate qualification certainty, cost-aware alloy strategies, and localized capability in high-demand regions. Due diligence should examine process yield trends, rhenium and nickel cost management, and post-cast value capture rather than casting capacity alone.
For procurement and engineering teams at engine OEMs and turbine operators, the strategic imperative is supply resilience and technology alignment. Diversifying qualified suppliers, locking in regional or vertically integrated partners for high-grade superalloy inputs, and aligning blade design with cooling-path and coating advancements can reduce program risk. Understanding where single-crystal integration is mandatory versus where alternative microstructures can meet performance targets will improve cost-to-performance trade-offs and protect program economics.
Detailed segmentation data, regional demand flows, and firm-level benchmarking are essential to translate these trends into program-specific decisions. Comprehensive analysis covering historical revenue, forecast trajectories through 2032, and supplier-level capability mapping is available in the full market study, providing the granularity needed to refine sourcing strategies, investment theses, and product-development roadmaps in this high-temperature segment.
For detailed analysis of this topic, please visit the official page: Single-crystal Turbine Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


