



HUD Film Market: Why 15.25% CAGR and Asia-Pacific Surge Reshape 2026 Strategy

The HUD Film Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The head-up display (HUD) film market has entered a period of aggressive expansion, driven by the convergence of automotive digitalization and advanced optical materials. Valued at approximately $1.45 billion in 2025, the market has grown consistently from around $645 million in 2020. Projections indicate the sector will reach roughly $3.92 billion by 2032, representing a compound annual growth rate of 15.25 percent over the forecast period. This trajectory reflects a structural shift rather than a cyclical upturn. Vehicle manufacturers are increasingly treating HUD systems not as premium add-ons but as core components of the digital driver interface, particularly in adaptive driving display and augmented reality implementations. The growth is broad-based across vehicle segments, with passenger cars accounting for the majority of volume and commercial vehicles representing a smaller but steadily expanding application area.
Despite the strong upward momentum, the market faces several structural inflection points that will define competitive outcomes over the next several years. The first challenge centers on optical performance versus manufacturing complexity. HUD films must simultaneously manage light projection, eliminate ghosting and reflections, and maintain structural integrity under automotive safety and environmental standards. As HUD systems evolve from combiner reflections to windshield-embedded and large-field-of-view augmented reality configurations, the tolerance for optical distortion and thermal deviation narrows dramatically. Material producers are therefore pushed to deliver films with tighter birefringence control, higher thermal stability, and more precise wedge geometries, all while preserving processing ease for glass laminators.
A second challenge lies in navigating the tension between standardization and customization. The industry has seen a dominant concentration among a small group of suppliers, which reflects the specialized know-how required for HUD-grade interlayers and cover lens films. At the same time, automakers and tier-one suppliers are demanding region-specific adaptations, varying field-of-view requirements, and acoustic or thermal enhancements tailored to specific vehicle architectures. Managing this balance without fragmenting production economics is a persistent operational challenge for both material vendors and integration partners.
A third inflection point involves the pace of technology transitions. Holographic and in-plane transparent display concepts are moving from proof-of-concept stages toward potential commercialization, and large-field-of-view augmented reality HUDs are gaining traction in premium segments. These shifts create a moving target for film suppliers, who must anticipate which optical architectures will scale and which will remain niche. The risk of investing in film formulations or coating processes for architectures that do not achieve volume production is real, especially when automotive development cycles extend across multiple years. The market's trajectory will therefore be shaped not only by demand growth but by how efficiently participants align material innovation with architectural consolidation.
Key Drivers of Market Change
Several interconnected forces are accelerating the HUD film market and reshaping its value chain. Understanding these drivers is essential for mapping where growth will concentrate and which capabilities will command premium positioning.
Technology Innovation and Optical Performance Breakthroughs
Technological advancement remains the primary engine of market expansion. The core function of HUD films has evolved from passive light transmission to active optical management. Wedge-shaped interlayer films are now engineered to minimize ghosting across standard, augmented reality, and dual-plane HUD configurations, enabling cleaner projection without compromising the safety and bonding properties required in laminated windshields. In parallel, cover lens films are gaining sophistication through birefringence control, chatter mark mitigation, and UV resistance, allowing brighter and more stable imagery in high-temperature and high-humidity environments. These material improvements directly support the migration toward larger fields of view and more immersive digital overlays, which consumers and manufacturers increasingly expect from modern cockpit designs.
Light Control Film Market
A notable development in this space is the progress around holographic in-plane transparent display technology. Recent collaborations have focused on laminated hologram solutions that can host multiple transparent HUDs on a single windshield, using photopolymer films paired with specialized interlayer structures and replication processes. Proof-of-concept demonstrations have highlighted the possibility of separate display zones within one windshield, which would allow different information layers to be presented without splitting the driver's attention. While commercialization timing remains contingent on cost, yield, and automaker adoption, the underlying technology illustrates how film and interlayer materials are becoming integral to system architecture rather than mere components.
Policy and Regulatory Environment
Regulatory frameworks and automotive safety standards are both enabling and constraining market dynamics. HUD windshield interlayers must satisfy established automotive glass and safety requirements while delivering optical clarity and impact performance. Compliance with recognized safety specifications ensures that HUD-enabled windshields can be integrated into vehicle type approvals without compromising occupant protection. At the same time, regulatory expectations around driver distraction, visibility, and electronic display placement are influencing how and where HUDs are deployed. As augmented reality and large-field-of-view systems become more prominent, regulators and industry bodies are likely to scrutinize information density, projection alignment, and cognitive load. These considerations do not stifle innovation, but they raise the bar for materials that must perform reliably across a wider set of operating conditions and usage scenarios.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand patterns are being reshaped by the premiumization of digital cockpits and the electrification of vehicle fleets. Consumers are increasingly accustomed to connected, software-defined interfaces, and HUDs fit naturally into that expectation by projecting navigation, safety alerts, and vehicle status information into the driver's line of sight. For automakers, HUDs offer a way to differentiate cockpit experiences while reducing reliance on traditional instrument clusters. The push is especially pronounced in electric vehicles, where packaging flexibility and the emphasis on advanced digital features create additional room for HUD integration.
Commercial vehicle applications, while smaller in volume, are also gaining relevance. Fleet operators and commercial OEMs are exploring HUDs for safety enhancement, navigation support, and driver assistance integration, particularly where visibility and workload management are critical. This broadening demand base helps diversify the market beyond passenger car premium segments and provides a pathway for incremental volume growth in segments that were previously conservative in adopting optical display technologies.
Supply Chain and Cost Structure Dynamics
The cost and supply side of the market is evolving as volume scales and material specifications become more demanding. Established suppliers have been expanding production footprints and refining pricing structures to capture growing orders, particularly in regions with strong automotive manufacturing activity. Recent contract updates have signaled more structured volume-based pricing in response to rising demand, which reflects both increased confidence in order pipelines and the need to remain competitive in price-sensitive segments. At the same time, the shift toward more advanced film grades and cover lens solutions introduces cost pressure, since tighter optical tolerances, specialized coatings, and higher durability requirements can raise material and processing expenses.
Supply chain resilience is also becoming a strategic consideration. As HUD film demand expands across multiple regions, suppliers and glass integrators must coordinate capacity, logistics, and quality consistency across dispersed manufacturing sites. The concentration of specialized expertise among a limited number of players makes it important for buying organizations to secure long-term alignment with partners who can scale while maintaining optical and safety performance. This dynamic reinforces the value of partnerships that combine material know-how with regional production capability and responsive technical support.
Competitive Landscape and Leading Strategies
The competitive environment in the HUD film market is defined by a small group of highly specialized material companies that have built long-standing relationships with automotive glass manufacturers and system integrators. Market concentration is high, reflecting the technical barriers to producing HUD-grade interlayers and cover lens films that meet optical, thermal, and safety requirements at scale. Within this landscape, leading participants are differentiating not just on material performance but on ecosystem positioning, geographic reach, and integration with next-generation display architectures.
Strategic Positioning and Differentiation
Several core strategies are visible among the leading suppliers:
-
Wedge interlayer specialization for ghost reduction. One Japanese chemical company has built a recognizable position around wedge-shaped PVB interlayer films designed to eliminate ghosting across standard, augmented reality, and dual-plane HUD systems. Its strategy combines global production presence with broad application coverage, enabling supply across Europe, North America, China, and Japan.
-
Expanded HUD and acoustic interlayer portfolios. A US-based materials company offers wedge PVB interlayers with variant series targeting acoustic performance and large field-of-view augmented reality applications. It has also pursued partnerships that link its interlayer technology with holographic display concepts, positioning itself at the intersection of optical interlayer performance and advanced display integration.
-
Long-established interlayer supply with safety and process focus. A Japanese specialty materials company emphasizes wedge monolayer and acoustic PVB solutions that prevent ghosting while preserving safety, acoustic quality, and processing ease. Its multi-decade track record with automotive glass makers provides a credibility advantage in an industry where qualification cycles are long and performance consistency matters.
-
Cover lens films for display optics and durability. A German polymer company has focused on polycarbonate film grades for HUD cover lenses, emphasizing birefringence control, UV resistance, and durability under demanding environmental conditions. Its strategy includes mass production partnerships with automakers in China, particularly for electric vehicle applications, highlighting a regional acceleration of advanced optical film adoption.
-
Optical and thermal management films for projection systems. A US conglomerate supplies cold mirror and visible-light reflective films used in HUD projection units and assemblies, addressing brightness and thermal management. This capability extends the company's role beyond windshield interlayers into the optics and thermal control layer of HUD hardware.
Market Evolution and Competitive Dynamics
The market structure is evolving along several axes. One is the deepening integration between material suppliers and display technology partners. Recent partnership activity around holographic in-plane transparent display concepts illustrates how interlayer and photopolymer film capabilities are being combined to unlock multi-HUD windshield architectures. This suggests a trajectory in which film suppliers participate earlier in system design, co-developing solutions that span optical film, interlayer performance, and replication or display integration.
A second dynamic is regional competition and capacity deployment. Strong demand growth in Asia-Pacific, especially within China's automotive manufacturing ecosystem, is prompting suppliers to adjust pricing, expand volumes, and prioritize local order fulfillment. Recent contract and production updates underscore the strategic importance of securing share in fast-growing regional markets while maintaining global supply credibility. As electric vehicle adoption and cockpit digitalization continue to rise in these markets, regional scale is likely to become an increasingly important competitive advantage.
PW Consulting Chemical & Energy Research Center
A third dynamic is the tension between consolidation and entry. High market concentration reflects the specialized nature of HUD film technology, but it also creates incentives for partnership, licensing, and targeted entry in adjacent optical film segments. While full-scale disruption is unlikely in the near term given qualification and performance requirements, incremental new entries may emerge through niche film technologies, regional production partnerships, or specialized optical coatings that address particular HUD architectures. The likely outcome is not a fragmented free-for-all but a layered competitive field in which established leaders defend core interlayer and cover lens positions while collaborating on advanced display concepts.
Future Outlook and Strategic Implications
Looking ahead to the 2026 through 2032 window, three trends are likely to shape commercial outcomes and investment decisions.
Automotive Head-up Display (HUD) Market
The first trend is the continued shift from basic HUD implementations toward large-field-of-view and augmented reality configurations in premium and increasingly mainstream segments. As optical requirements become more demanding, films that deliver cleaner projection, improved thermal stability, and stronger durability will capture disproportionate value. Manufacturers that can supply these advanced grades at scale, while maintaining consistent quality across regions, are positioned to benefit from the premiumization of digital cockpits.
The second trend is the gradual maturation of multi-HUD and holographic display concepts. Whether through holographic in-plane transparent displays or other laminated optical approaches, the possibility of hosting multiple transparent display zones on a single windshield creates a strategic opening for suppliers that can combine interlayer performance, photopolymer film capability, and replication know-how. The transition from proof-of-concept to volume production will depend on cost, manufacturability, and automaker commitment, but the direction of travel points toward richer optical integration and new material requirements.
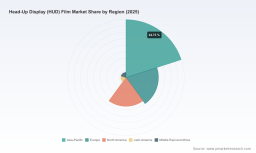
The third trend is regional realignment of demand and production. Asia-Pacific is expected to remain the largest revenue region, reflecting both vehicle production scale and rapid adoption of advanced cockpit features, especially in electric vehicles. Europe and North America will continue as significant markets, but competitive intensity may increase as suppliers expand capacity and pricing structures adapt to volume growth. For companies operating in this space, regional demand patterns will influence not only revenue potential but also the pace of qualification, production localization, and partnership strategies.
These trends carry both opportunity and uncertainty. The upside lies in capturing growth from digital cockpit expansion, electric vehicle adoption, and advanced optical architectures. The risk lies in overcommitting to film configurations or display concepts that do not achieve scale, or in underestimating the cost and yield challenges associated with higher-performance HUD films and multi-HUD systems. Market participants will need to balance innovation investment with disciplined product roadmapping and close alignment to automotive OEM development timelines.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align material and optical strategies with the HUD architectures most likely to scale. Investing in wedge interlayer precision, cover lens durability, and thermal management capabilities will be increasingly important as field-of-view and augmented reality applications expand. Equally important is securing supply commitments and technical collaboration with glass integrators and display partners who can translate film performance into reliable system outcomes.
For investors, the market offers exposure to a high-growth materials segment tied to digital cockpit adoption, but selection matters. The strongest competitive positions are likely to belong to suppliers with proven qualification credibility, diversified regional production, and participation in next-generation optical integration. Monitoring partnership activity around multi-HUD and holographic concepts can provide early signals of where value may migrate beyond conventional interlayer and cover lens products.
For procurement and sourcing leaders, the focus should be on building resilient relationships with suppliers capable of consistent performance at scale. Given the concentration of specialized expertise, long-term alignment, clear quality expectations, and regional capacity planning are critical. Evaluating suppliers on the basis of optical performance, safety compliance, process ease, and ability to support evolving HUD specifications will help reduce qualification risk and support smoother scale-up.
For organizations seeking to translate these trends into detailed segment data, regional volume estimates, pricing dynamics, and tailored sourcing or investment scenarios, a full market research report can provide the deeper granularity needed for planning. Accessing that level of detail enables more precise benchmarking, scenario modeling, and prioritization of the opportunities that best fit a company's capabilities and risk appetite.
For detailed analysis of this topic, please visit the official page: Head-Up Display (HUD) Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


