



HYW Self-Adhesive Tape Market: Why 6.12% CAGR Reshapes Regional Dynamics

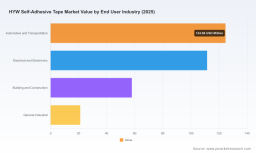
The HYW Self-Adhesive Tape Market: Strategic Trends and Commercial Opportunities Through 2032
The global HYW self-adhesive tape market has entered a phase of steady, structurally supported expansion, with total revenue projected to climb from approximately USD 315.4 million in 2025 to USD 478.02 million by 2032. This trajectory reflects a compound annual growth rate of 6.12 percent over the 2026–2032 forecast horizon, building on a consistent upward path from the 2020 baseline of USD 231.5 million. The growth is not merely cyclical but rooted in enduring shifts in packaging logistics, industrial assembly methods, and material performance expectations. Self-adhesive tapes have transitioned from auxiliary sealing commodities to engineered components that influence supply chain efficiency, product safety, and environmental compliance. As end-user industries recalibrate their material specifications and regulatory frameworks tighten around packaging waste, the tape segment is experiencing both demand acceleration and formulation pressure.
Despite the favorable macro trajectory, three structural challenges are reshaping how participants navigate the market. First, raw material cost volatility, particularly in polymer backings and adhesive resins, is compressing margins and forcing continuous price–performance recalibration. Second, the regulatory environment is shifting from voluntary sustainability commitments to enforceable recycled-content and recyclability mandates, requiring reformulation, supply chain transparency, and compliance verification that many mid-tier producers are still building capacity to absorb. Third, the market is exhibiting moderate concentration, with the top three players collectively accounting for just over 42 percent of revenue and the top five reaching approximately 58 percent, leaving substantial room for specialized, regional, and application-focused entrants but also raising the bar for scale, technical service, and compliance infrastructure. These dynamics mean that growth alone is no longer a sufficient strategic narrative; differentiation in material engineering, regulatory readiness, and value-chain integration is becoming the primary determinant of durable competitiveness.
Key Drivers Reshaping the HYW Self-Adhesive Tape Landscape
Material Innovation and Performance Differentiation
The chemistry mix continues to pivot toward adhesives that balance bonding strength, temperature tolerance, and environmental resistance while meeting downstream recyclability expectations. Acrylic-based formulations remain dominant in value terms, reflecting their broad compatibility with automated dispensing, consistent tack profiles, and suitability for high-speed carton sealing and industrial bonding. Rubber-based adhesives maintain a strong position where cost efficiency and initial tack are prioritized, particularly in medium-weight packaging and general industrial applications. Silicone adhesives, while smaller in absolute terms, are gaining traction in specialized contexts requiring extreme temperature stability, clean removal, or compatibility with sensitive substrates. The strategic implication is that tape performance is increasingly evaluated not just on holding force but on process integration, substrate compatibility, and end-of-life behavior, pushing R&D teams to optimize formulations for both manufacturing throughput and compliance footprints.
Regulatory Pressure as a Catalyst for Product Redesign
Policy frameworks are no longer peripheral considerations; they are actively reshaping formulation roadmaps and procurement specifications. Jurisdictions are moving toward explicit recycled-content minimums, recyclability requirements, and producer responsibility obligations that affect both the adhesive layer and the backing film. In India, regulatory requirements have driven early compliance-oriented product updates, with recycled-content BOPP tapes entering the market to align with national plastic waste management mandates. In Europe, packaging regulations are setting recyclability and recycled-content expectations that cascade into tape specifications used on or as part of packaging systems. The strategic signal is clear: compliance is becoming a design parameter rather than a post-production check, and manufacturers that embed regulatory readiness into their development cycles are better positioned to retain spec-in decisions and avoid reformulation scrambles.
Demand-Side Shifts in Packaging and Industrial Assembly
End-user behavior is changing on two fronts: volume and specification. E-commerce and logistics intensification continue to increase the frequency of carton sealing, reinforcing demand for reliable, high-speed compatible packaging tapes. At the same time, industrial and electronics assembly is placing greater emphasis on tapes that support clean processing, substrate safety, and consistent performance under variable environmental conditions. These use cases favor solutions that reduce line stoppages, minimize waste from misapplication, and align with broader sustainability targets in the purchasing organization. The result is a demand profile that rewards suppliers capable of pairing product performance with application engineering, testing support, and documentation that helps buyers justify material choices internally.
Airtight Tapes Market
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by regional divergence in polymer pricing and by the operational implications of sustainability mandates. Backing materials such as BOPP film exhibit meaningful price differences across major markets, influencing where production is routed and how cost-advantaged formulations are sourced. At the same time, polypropylene-linked cost indicators remain elevated, reinforcing the importance of yield optimization, scrap reduction, and adhesive efficiency. Companies are increasingly evaluating not just per-unit material cost but total cost of compliance, including certification, recycled feedstock availability, and the operational burden of managing multiple formulation grades. This broader cost lens is accelerating consolidation of SKUs around platforms that can serve multiple applications while still meeting regional regulatory thresholds.
Competitive Positioning and Market Evolution
The competitive field is anchored by a mix of global scale players and specialized manufacturers, each pursuing distinct strategic positioning. Large diversified companies leverage broad adhesive science capabilities, integrated film and coating operations, and global distribution networks to serve cross-industry demand. Their advantage lies in 일관된 성능 기준, 응용 엔지니어링 지원, 그리고 규모 기반 공급망 복원력입니다. 유럽 기반의 한 주요 업체는 재활용 PET 캐리어와 친환경 포장 테이프 라인을 강조하며 규제 대응형 제품 아키텍처를 구축하고 있으며, 이는 구매팀이 지속 가능성 목표와 성능 요구사항을 동시에 충족하도록 돕는 포지셔닝입니다. 북미와 아시아 지역의 다른 선도 기업들은 이커머스 포장, 중형·중량 박스 실링, 자동화 라인 호환성에 초점을 맞춘 핫멜트 및 아크릴 기반 솔루션을 강화하며 처리 속도와 공정 안정성을 핵심 차별점으로 삼고 있습니다.
PW Consulting Chemical & Energy Research Center
지역 및 니치 플레이어의 전략은 규모 경쟁보다 규제 적합성, 소재 혁신, 비용 효율적 재활용 함량 활용에 기울어져 있습니다. 예를 들어 인도 시장의 한 제조업체는 현지 EPR 요건에 대응하기 위해 재활용 함량 BOPP 테이프 라인을 확대하며 지역 규정 친화적 포트폴리오를 구축하고 있습니다. 이러한 움직임은 규제 민감도가 높은 시장에서 빠른 대응력과 지역 공급망 접근성이 경쟁 우위로 전환될 수 있음을 보여줍니다. 동시에 일본의 소재 및 테이프 전문 기업들은 BOPP와 특수 필름 기반의 포장·산업 용도를 포괄하며, 기판 호환성과 필름 설계 역량에서 차별화를 모색하고 있습니다.
시장 구조의 진화 방향은 수평적 통합과 수직적 전문화가 동시에 진행되는 양상입니다. 상위권 기업들은 제품 플랫폼을 확장해 여러 응용 분야를 커버하고, 지역별 규제 요건에 맞춰 변형 가능한 공통 기반을 구축하며 포트폴리오 복잡도를 관리하는 경향을 보입니다. 반면 중소형 참여자들은 특정 화학군, 특정 지역 규제 시장, 또는 특정 최종 사용 산업의 기술 요구에 집중해 대체 불가능한 포지셔닝을 확보하려는 움직임을 보입니다. 신규 진입의 문은 여전히 열려 있으나, 성공을 위해서는 단순한 가격 경쟁력이 아니라 시험 데이터, 규제 문서, 일관된 품질 관리, 그리고 구매팀의 내부 검토를 통과할 수 있는 기술 신뢰도가 함께 요구됩니다. 이 환경에서 경쟁 우위는 제품 자체의 성능뿐 아니라 구매 여정 전체를 얼마나 매끄럽게 지원하느냐에 의해 점차 결정되고 있습니다.
Forward Outlook: Trends Shaping the Next Three to Five Years
여러 동인이 겹치면서 향후 3~5년 동안 산업 방향을 규정할 몇 가지 흐름이 뚜렷해지고 있습니다. 첫째, 재활용 함량과 재활용 가능성은 선택적 마케팅 요소가 아니라 제품 설계의 기본 조건으로 자리 잡을 것입니다. 구매 조직은 사양서에 규제 적합 증거를 포함하고, 공급업체는 공통 플랫폼에서 지역 변형을 효율적으로 관리할 수 있는 구조를 갖추게 될 것입니다. 이는 준수형 등급과 고성능 등급 사이의 경계가 더 유연하게 연결되는 제품군으로 이어질 가능성이 높습니다.
Seam Sealer Tape Market
둘째, 응용 공학이 상업적 차별화의 중심축으로 부상할 것입니다. 자동화 라인 호환성, 도포 일관성, 기판 손상 최소화, 환경 조건에서의 접착 신뢰성 같은 요소가 구매 결정의 전면에 나서면서, 단순 가격 비교보다 총 공정 비용과 품질 일관성이 더 큰 비중을 차지하게 됩니다. 이 흐름은 기술 지원, 테스트 데이터, 현장 문제 해결 능력을 갖춘 공급업체에 유리하게 작용할 것입니다.
셋째, 비용 구조와 원료 조달의 지역적 분화가 심화되면서 공급망 설계가 제품 전략과 분리될 수 없게 될 것입니다. 폴리오레핀 계열 재료의 지역별 가격 차이와 재활용 원료의 가용성 변동은 생산 거점, 배합 전략, SKU 관리 방식에 직접 영향을 미칠 것입니다. 기업들은 표준화와 현지화 사이의 균형을 더 정교하게 맞추어야 하며, 그렇지 않을 경우 규제 대응과 원가 경쟁력 사이에서 동시에 압박을 받게 됩니다.
이러한 추세 아래에는 불확실성이 남아 있습니다. 규제 시행 시기와 세부 요건은 지역별로 차이가 있을 수 있고, 재활용 원료의 품질 일관성과 공급 안정성은 조성 전환을늦출 수 있으며, 경기 변동은 포장 및 산업 수요 모두에 영향을 줄 수 있습니다. 그럼에도 기본적인 방향은 명확합니다. 성능, 준수, 공정 통합이 함께 평가되는 시장에서 운영 속도와 데이터 투명성을 갖춘 참여자가 유리한 위치를 점할 가능성이 높습니다.
Strategic Implications for Decision-Makers
제조업체에게는 규제 적합성을 사후 조치가 아니라 제품 플랫폼 설계의 입력 변수로 다루는 것이 중요합니다. 공통 베이스를 중심으로 지역별 변형을 관리할 수 있는 구조를 갖추면 복잡도와 준수 리스크를 동시에 줄일 수 있으며, 응용 지원과 테스트 문서를 강화하면 사양 채택 가능성을 높일 수 있습니다. 또한 원료 가격 변동과 재활용 원료 조달 환경을 고려한 배합 및 재고 전략이 마진 방어에 직접적인 영향을 미칩니다.
투자자에게는 왜곡된 성장 수치보다 플랫폼 확장 능력, 규제 대응 속도, 지역 가격 구조를 흡수할 수 있는 운영 역량이 장기 가치 창출의 핵심이라는 점이 중요합니다. 화학군별 수요 강도, 지역 규제 일정, 원재료 조달의 지역적 차이, 그리고 경쟁사가 제품 플랫폼을 어떻게 단순화하고 있는지는 포트폴리오 판단과 진입 시점 평가에 유용한 기준입니다. 빠른 규제 대응이 가능한 지역 강자와, 글로벌 규모에서 성능 일관성을 확보한 기업 사이의 역할 분리가 심화될 가능성을 주목할 필요가 있습니다.
조달 담당자와 구매 리더에게는 총소유비용 관점으로 전환할 때 더 나은 의사결정이 가능합니다. 도포 효율성, 라인 중단 위험, 규격 변경 시 검증 부담, 그리고 문서화된 준수 증거는 가격표 이상의 가치를 만듭니다. 또한 단일 공급원에 대한 의존도를 낮추면서도 사양 일관성을 유지하려면, 동등한 성능 기준을 충족하는 대체 후보군과 검증된 시험 데이터를 사전에 확보하는 것이 유리합니다.
시장 구조와 규제 환경이 빠르게 재조정되는 상황에서는 세분화된 수요 강도, 지역별 규제 이행 일정, 원재료 가격 경로, 주요 기업의 제품 플랫폼 변화에 대한 최신 정보가 의사결정의 질을 좌우합니다. 이러한 세부 데이터는 단기 조달 전략부터 중장기 포트폴리오 재편까지 연결되므로, 지속적인 모니터링과 적용 가능한 형태의 인사이트 확보가 필수적입니다. 보다 상세한 세분화 데이터, 지역별 규제 이행 타임라인, 기업별 제품 전략과 경쟁 포지셔닝에 대한 심층 분석은 전체 연구 보고서에서 확인할 수 있습니다.
For detailed analysis of this topic, please visit the official page: HYW Self-Adhesive Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


