



Steel Grating Market at $227M: What the 3.61% CAGR Really Means for 2026-2032

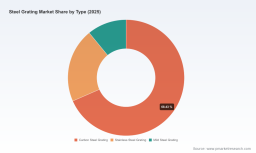
Strategic Shifts and Commercial Opportunities in the Steel Grating Market
Market Landscape and Structural Challenges
The steel grating market has demonstrated consistent expansion over the past five years, with total market revenue growing from approximately 183.8 million USD in 2020 to 227.0 million USD in 2025. The trajectory continued into 2026, reaching 230.47 million USD, and forward projections indicate a climb to 289.39 million USD by 2032. This represents a compound annual growth rate of 3.61 percent across the forecast horizon. While the absolute growth rate may appear measured, the underlying composition reveals a market undergoing meaningful recalibration. Demand is no longer driven purely by replacement cycles or basic infrastructure spend. Instead, the market is being shaped by shifts in safety compliance, industrial modernization, and regional capacity realignments.
At the same time, the industry is navigating a set of structural challenges that will define competitive positioning over the next several years. One of the most pressing is the tension between raw material price volatility and margin preservation. Steel and aluminum input costs have experienced sharp fluctuations, with carbon steel price hikes placing direct pressure on manufacturing economics. These swings are not isolated events. They compound with rising non-raw material input costs, including labor and freight, which continue to escalate beyond initial commodity-driven increases. Producers that rely on static pricing models or long-term fixed contracts without effective pass-through mechanisms are being squeezed from both sides of the cost structure.
A second challenge lies in the evolving regulatory perimeter. Trade oversight has intensified, particularly regarding imported grating products. The United States International Trade Commission instituted five-year reviews for steel grating from China to assess whether continued dumping or subsidization warrants duty extensions. This development signals that trade policy will remain an active variable rather than a settled backdrop. Companies with heavy exposure to cross-border sourcing or those that have built cost advantages on imported feedstock must now factor in the possibility of renewed duties, supply route adjustments, and administrative review cycles. Regulatory shifts of this nature do not merely alter pricing. They reshape sourcing strategies, lead times, and risk allocation across the value chain.
The third challenge is operational and strategic rather than purely financial. Market concentration data indicates that the top three players hold approximately 35.0 percent of total revenue, while the top five capture around 55.0 percent. This level of consolidation suggests a market where scale, brand equity, and distribution reach matter significantly. Yet concentration also creates friction for mid-tier and regional manufacturers that must differentiate without competing purely on volume. The industry is not fragmented in a way that allows easy entry. It rewards producers that can combine reliable capacity, specification flexibility, and application-specific engineering. Firms that remain positioned as generic commodity suppliers face a narrowing path to sustainable margins.
Key Drivers Reshaping Market Dynamics
Technological Advancement and Material Innovation
Product engineering has moved from a secondary concern to a core competitive lever. Grating manufacturers are increasingly differentiating through fabrication precision, load-specific designs, and surface treatments that extend service life in demanding environments. Pressed and electro-forged gratings, for example, allow tighter tolerances and more consistent anti-slip performance, which matters in walkway and platform applications where safety and durability intersect. Manufacturers that integrate custom fabrication into their core operations are better positioned to serve industrial customers with non-standard dimensions, specialized coatings, or elevated corrosion resistance requirements. This shift toward engineered solutions raises the barrier to entry and rewards capability depth over pure volume production.
In parallel, the industry is seeing gradual adoption of improved surface refinement and finishing processes. Pickling and controlled surface treatment are becoming more relevant for stainless and specialized carbon steel applications where appearance, cleanliness, and long-term corrosion control influence procurement decisions. These technical upgrades are not cosmetic. They translate into lower maintenance intervals, better compliance with hygiene or environmental specifications, and stronger positioning in applications where downtime is costly. The broader implication is that value in the steel grating market is migrating toward specification accuracy, finish quality, and application engineering, rather than remaining anchored solely to base metal weight and standard profiles.
Policy Frameworks and Trade Oversight
Policy and trade dynamics are actively shaping cost structures and sourcing decisions. The May 2026 decision by the United States International Trade Commission to open five-year reviews for Chinese steel grating imports underscores the continued scrutiny of cross-border competition. For domestic producers, this environment can reinforce the case for localized capacity and established supply relationships. For buyers and distributors, it introduces both risk and opportunity, depending on how procurement portfolios are structured. Where reliance on low-cost imports has been a primary margin strategy, renewed duty exposure can compress flexibility and force rapid renegotiation of supply terms.
Environmental regulation is also influencing upstream conditions. The finalization of amendments to National Emission Standards for Hazardous Air Pollutants related to taconite iron ore processing in March 2024 affects the feedstock environment for steel production. While the direct impact reaches further up the value chain, the downstream consequence is a regulatory landscape that can influence iron ore processing economics and, indirectly, the stability of input costs for steel-intensive products. Producers and procurement teams that monitor these regulatory milestones can anticipate shifts in feedstock cost structures earlier and adjust hedging, inventory, or supplier diversification strategies accordingly.
Demand-Side Evolution in Industrial and Infrastructure Applications
Demand patterns are shifting as end users prioritize safety, asset longevity, and functional integration. Walkways remain a significant application area, reflecting ongoing needs in industrial facilities, utilities, and commercial infrastructure where safe pedestrian access must be maintained under heavy use or harsh conditions. Platforms represent another substantial demand center, particularly in processing plants, energy operations, and manufacturing environments where equipment access, inspection routes, and worker safety zones must be structurally reliable. Stair treads continue to draw consistent demand due to their dual role in functionality and code-driven safety requirements.
Beyond these core uses, security fencing, drainage covers, and trench covers illustrate how steel grating is increasingly specified as part of broader infrastructure and site-management solutions. Procurement teams are no longer buying grating simply as an isolated metal component. They are integrating it into facility design, drainage planning, perimeter security, and load-bearing access systems. This application-level thinking increases the importance of product consistency, lead-time reliability, and technical support. Buyers are more likely to consolidate suppliers that can deliver across multiple application needs, which in turn rewards manufacturers with broader catalogs and stronger service capabilities.
Supply Chain Cost Architecture and Operational Pressure
The cost environment is being reshaped by more than commodity price movement alone. Labor costs and freight expenses continue to rise, adding pressure that extends well beyond initial steel price fluctuations. This broader cost architecture means that manufacturers must manage a wider set of margin variables simultaneously. Efficient production scheduling, regional distribution logic, and freight-sensitive order optimization are becoming part of the competitive formula. Producers that can align capacity with demand geography, reduce unnecessary handling, and maintain consistent order fulfillment gain an advantage that is not always visible in raw material benchmarks alone.
At the same time, carbon steel price volatility remains a persistent feature of the landscape. The impact is felt not only in direct input costs but also in the predictability of quoting, contracting, and inventory planning. In a market where customers increasingly value reliability and specification accuracy, the ability to manage price variability without sacrificing responsiveness is a meaningful operational capability. This is one reason why strategic sourcing, forward purchasing discipline, and transparent price communication are becoming central topics in buyer-supplier negotiations.
Competitive Positioning and Market Structure
The competitive landscape is anchored by manufacturers that combine production scale, application breadth, and regional footprint. Nucor Corporation operates steel bar grating through its Vulcraft and Verco divisions, with annual capacity around 50,000 tons and a product range that spans standard, heavy-duty, and custom-fabricated offerings. This positions the company within a broader structural steel ecosystem where grating is integrated with complementary metal products and distributed through established industrial channels. Its scale and divisional integration provide a strong foundation for serving large-volume and specification-driven buyers.
IKG has built a recognized position in pressure-locked bar grating and safety flooring, supported by more than 100 years of expertise across the United States and Mexico. Its full product line includes pressure-locked and anti-slip solutions, which align closely with demand in access infrastructure and safety-critical applications. Ohio Gratings stands out as the largest privately-owned industrial and commercial grating provider in the United States, with specialization in design, manufacturing, and custom fabrication using carbon steel, stainless steel, and aluminum. That combination of private ownership and broad material capability allows a high degree of flexibility in custom work and customer-specific engineering.
AMICO continues to emphasize domestically produced bar grating for industrial applications, expanding its range to include common bar grating items. This focus on U.S.-based production appeals to buyers prioritizing supply continuity, domestic sourcing expectations, and shorter lead times for standard products. On the international side, JK TECHNIC in France manufactures pressed gratings, electro-forged grating, and solutions for stair treads, platforms, and industrial applications, while Meiser in Germany focuses on high-grade products and surface refinement, including pickling, and maintains a U.S. subsidiary through Meiser Gratings Inc. These European manufacturers illustrate how specialized finishing capability and engineered product lines can support cross-border positioning, particularly where surface quality and specification precision are valued.
A defining recent development is the February 2026 acquisition of IKG by a joint venture of Meiser and Dutco from KPS Capital Partners. The transaction is notable because it combines brands and capacity to form what is described as the world's largest grating manufacturer. This kind of consolidation signals a market trajectory toward greater scale integration, shared technical resources, and broader geographic coverage. For the competitive field, it raises the strategic stakes around capacity alignment, brand portfolio strength, and the ability to serve multi-region demand without losing application-specific expertise. Consolidation of this nature can improve purchasing leverage and production efficiency, but it also places pressure on remaining independent players to clarify their differentiation, whether through custom fabrication speed, regional service density, or niche material expertise.
Market evolution is therefore shaped by both integration and specialization. Large-scale combinations can capture efficiencies and widen distribution reach, while privately-held and regionally anchored manufacturers can compete by offering faster custom turnaround, closer customer collaboration, and material-specific proficiency. New entrants face a challenging environment given the concentrated revenue structure and the importance of established production capability. As a result, the most viable path for expansion is often through targeted capability building, strategic partnerships, or acquisition of specialized assets rather than attempting to compete purely on price in standard product categories.
PW Consulting Chemical & Energy Research Center
Forward Outlook and Emerging Opportunities
Consolidation as a Strategic Accelerator
Over the next three to five years, further consolidation is likely to remain a central theme, particularly where combined capacity can strengthen supply reliability and broaden application coverage. The recent move to unite major brands and production resources illustrates how scale can be leveraged not only for cost efficiency but also for a wider product and service footprint. For customers, this can translate into simpler sourcing across multiple grating types and faster access to engineered solutions. For competitors, the strategic response will involve deciding whether to pursue scale through partnership or acquisition, or to double down on differentiation through customization, regional responsiveness, and specialized material performance.
Regulatory Continuity and Sourcing Realignment
Trade oversight and environmental regulation are expected to continue influencing sourcing strategies. The review of duties on Chinese steel grating and the broader regulatory environment around steel production feedstock suggest that supply chain design will remain dynamic. In practical terms, this creates opportunities for producers with stable domestic or near-shore capacity, as well as for procurement teams that build flexibility into supplier portfolios. Companies that preempt regulatory review cycles by diversifying sources, strengthening quality documentation, and aligning lead times with trade uncertainty will be better positioned to maintain continuity when policy conditions shift.
Engineered, Application-Specific Solutions as a Growth Axis
A third forward trend is the increasing premium on application-tailored grating products. As end users integrate grating into safety systems, drainage infrastructure, security setups, and industrial access platforms, the specification process becomes more nuanced. This favors manufacturers that can support custom dimensions, refined surface finishes, anti-slip performance, and consistent load-bearing characteristics. The commercial opportunity lies in moving up the value chain from commodity supply toward solution provision. Suppliers that invest in engineering support, responsive fabrication, and application knowledge can capture higher-margin work and build stickier customer relationships.
Steel Roofing Market
These trends also carry risk. Over-reliance on any single region, feedstock channel, or pricing model can become exposed if trade conditions change, raw material volatility intensifies, or labor and freight costs continue to rise. Additionally, if consolidation proceeds too aggressively without preserving local service quality or customization capacity, some customers may seek alternatives that can offer more direct engagement and faster adaptation to project-specific requirements. The balance between scale and responsiveness will therefore remain a critical strategic tension.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to strengthen the operational and technical foundations that support margin resilience and customer retention. This includes tightening cost pass-through mechanisms, investing in custom fabrication capability, and clarifying material specialization where it creates genuine differentiation. Producers should also evaluate whether their distribution and service models align with application-driven buying behavior. Where customers increasingly seek integrated solutions across walkways, platforms, stair treads, and covers, manufacturers that can respond with consistent quality and specification support will have a stronger competitive position. In an environment shaped by consolidation, clearly defined differentiation is not optional. It is the basis for defending share without engaging in unsustainable price competition.
For investors, the market presents a landscape where scale, integration, and application capability matter more than ever. The recent formation of a combined global-scale manufacturer highlights the value created through strategic consolidation, but it also underscores the need to assess whether scale translates into durable margins, better customer coverage, and operational flexibility. Investment decisions should account for exposure to trade review cycles, raw material volatility, and the extent to which a company's portfolio is tied to standard commodity products versus engineered, specification-sensitive solutions. Companies that can demonstrate both capacity reliability and the ability to serve higher-value application segments are better positioned for long-term relevance.
For procurement and supply chain leaders, the key is to move beyond price-only evaluation and build sourcing strategies that account for regulatory continuity, lead-time stability, and specification performance. Diversifying suppliers across regions and product types can reduce vulnerability to duty reviews or feedstock disruptions. At the same time, developing clearer technical requirements around load capacity, surface treatment, anti-slip performance, and corrosion resistance can improve long-term total cost outcomes by reducing maintenance, downtime, and replacement frequency. Procurement teams that engage earlier with manufacturers on application needs and lead-time planning are more likely to secure consistent supply and avoid reactive purchasing when market conditions tighten.
Structural Steel Market
Across all of these perspectives, the strategic value of detailed, segment-level intelligence is clear. Broad market direction provides context, but the decisions that shape outcomes sit in the specifics: how demand is distributed across applications, which material types are gaining or losing relative share, where regional capacity is expanding or constrained, and how competitive consolidation is altering supply dynamics. A more comprehensive view of these elements supports sharper planning, more disciplined sourcing, and better-timed investment choices. For organizations that need granular segment data, competitive tracking, and tailored scenario analysis, the full research report offers a deeper breakdown of market structure and forward options.
For detailed analysis of this topic, please visit the official page: Steel Grating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


